Small Cap Value Report (Tues 27 Oct 2020) - BMY, AA., HTG, QUIZ, RBG

Good morning, it's Paul here with the SCVR for Tuesday.
Reader comments - can I echo a repeated request here from other readers. If you're going to comment on any company, please include the ticker, or company name, in every post. Otherwise some readers won't know which company you're talking about, hence your comment is pointless to many readers. It depends which version of the site & comments layout people are using.
I've started a bit late today, so am aiming for a 3pm finish time. The first couple of sections should be up before midday. Update at 16:51 - today's report is now finished.
Agenda - this is what has caught my eye today, and taking into account reader requests too (which I try to do where time permits);
Bloomsbury Publishing (LON:BMY) - Interim results
Aa (LON:AA.) - Extension of deadline re takeover bid(s)
Hunting (LON:HTG) - Q3 Trading update
Quiz (LON:QUIZ) - (I hold) - Results FY 03/2020
Revolution Bars (LON:RBG) - Launch of CVA in subsidiary entity
.
Bloomsbury Publishing (LON:BMY)
Share price: 243.5p (up 16% at 11:10)
No. shares: 84.1m
Market cap: £204.8m
As usual, my first step when looking at all companies, is to review my previous notes. In this case, I reported here on 21 July 2020, when BMY issued a positive AGM trading update. This said Mar-June trading had been strong, with sales up 18%, ahead of expectations. Liquidity was strong. It reminded us that trading is H2 weighted, and the outlook was uncertain.
Moving on to today’s interim results;
Bloomsbury, the leading independent publisher, today announces unaudited results for the six months ended 31 August 2020.
It looks good, here is the CEO’s summary;
"Bloomsbury experienced excellent trading in the first half with year-on-year profit growth of 60% to £4.0 million. This has delivered our highest first half earnings since 2008 and exceeded the Board's expectations.
Obviously this is good, but we should bear in mind that the full year needs to be a lot higher than H1, to meet expectations. For context, full year adj PBT was £15.7m last year, so a £4.0m profit in H1 this year is still quite modest. Hence I’m more interested in the full year outlook comments.
We have continued to trade well during the first six weeks of the second half. In previous years, our revenue and earnings have been weighted towards the second half, with sales of trade titles rising for Christmas and sales of academic titles being strongest at the beginning of the academic year in the Autumn.
We are confident about the future of publishing. The short-term is difficult to predict because of the pandemic.
The commentary lists the new release schedule for H2, which sounds promising, including a J K Rowling book, which has been a big contributor to profitability for many years.
Acquisitions - “actively considering” opportunities.
Balance sheet - is fantastic, amazingly strong. Note that the very high receivables figures includes advances to authors. The cash pile is over £44m now, so it has plenty of ammunition to bolt on acquisitions, and now might be a good time to do so, with all the covid uncertainty.
Dividends - good to see these resuming, with a modest interim divi, flat vs last year, at 1.28p
As you can see below, there has been a lovely, long-term progression in the divis. The short bars are the interim divis, with the tall bars being the much larger final divis.

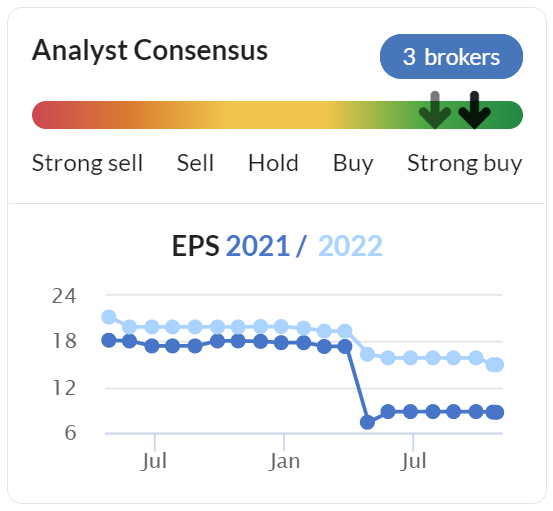
My opinion - the broker consensus forecasts (see graph below) are looking too pessimistic, although we won’t know until the Xmas trade is in the bag. Reduced orders from retailers possibly, but increased orders online? That would be my guess.
Overall, I think this looks a decent company, with a good long term track record, a fantastic balance sheet, and priced reasonably. Therefore it gets a thumbs up from me, as worthy of deeper research.
.
.
Aa (LON:AA.)
Share price: 23.3p (down 2%, at 12:05)
No. shares: 622.3m
Market cap: £145.0m
Here are my notes from 4 Aug 2020, when the AA announced it was in takeover talks, considering an equity raise, because it has £913m of debt falling due in the next 2 years. That is part of its ludicrously high £2.65bn debt mountain.
It sounds as if there’s still the possibility of a takeover bid;
On 24 September 2020, AA announced that it had consented to a request from TowerBrook Capital Partners (U.K.) LLP and Warburg Pincus International LLC (together the "Consortium") to explore the possibility of a consortium offer for the entire issued and to be issued share capital of the Company.
Commercial discussions and due diligence are progressing with the Consortium….
The Takeover Panel has granted an extension of the deadline from 27 Oct to 24 Nov 2020.
So it’s still a live situation.
My opinion - for me, the risks are far too high to want to punt on this. The AA’s balance sheet is shot to bits, with equity being little more than a call option on a good outcome. Why would a bidder be generous to equity holders, when it’s the bondholders who matter?
There’s a range of possible outcomes, from a generous bid for the shares (seems unlikely to me, but who can say?) to a wipe out for shareholders if the bidders do a deal with bondholders. Anything could happen.
With such a wide range of possible outcomes, and a dangerously over-leveraged balance sheet, I cannot see the attraction of risking my money on this. It's an interesting situation though, so the outcome will be good to watch (from a safe distance).
Market sentiment, as measured by the share price, seems to be pointing towards a poor outcome, as you can see below - terrible value destruction from its balance sheet being wrecked by financial engineers. For a while this was a sister company of Saga (LON:SAGA) (which I hold), but their balance sheets are poles apart. Saga has recently refinanced, and looks secure for now. Once its cruise ships can sail again, there's scope for a serious re-rating of in my view. Whereas the AA is in serious financial distress in my view, with insurmountable debt. Hence I wouldn't touch AA shares, far too risky.
.
Hunting (LON:HTG)
Share price: 134.5p (down 4% today, at 12:50)
No. shares: 164.9m
Market cap: £221.8m
I don’t seem to have covered this company for 5 years, probably because the market cap was too high, but it’s fallen into my remit again, as the share price chart demonstrates;
.

.
Hunting PLC (LSE : HTG), the international energy services group, today issues a Q3 2020 trading update.
It’s not clear to me whether the trading update below is for Q3 in isolation, or Q3 YTD. (although this is clarified further down, see below)
"In the most challenging environment ever faced in our industry decisive actions to resize the Group have been successful leading to a broadly break-even EBITDA result, a continued strengthening of our balance sheet, and an ongoing commitment to deliver industry leading service and technology to our customers.
Outlook for Q4;
Given the prevailing levels of activity, management believe that the revenue run rate for Q4 may be slightly lower than Q3 due to the usual seasonal slowdown.
Cost-cutting - has been deep;
"Our efforts to resize the Group in response to prevailing market conditions have resulted in annualised cash savings totalling c.$74m, with the global workforce reducing by c.30% from the 2019 year-end.
Balance sheet & possible acquisitions;
"Our strong balance sheet and improved net cash position also allows the Group optionality to explore further bolt-on acquisition opportunities. The growth of our subsea segment over the past 14 months demonstrates the success and rationale of this strategy.
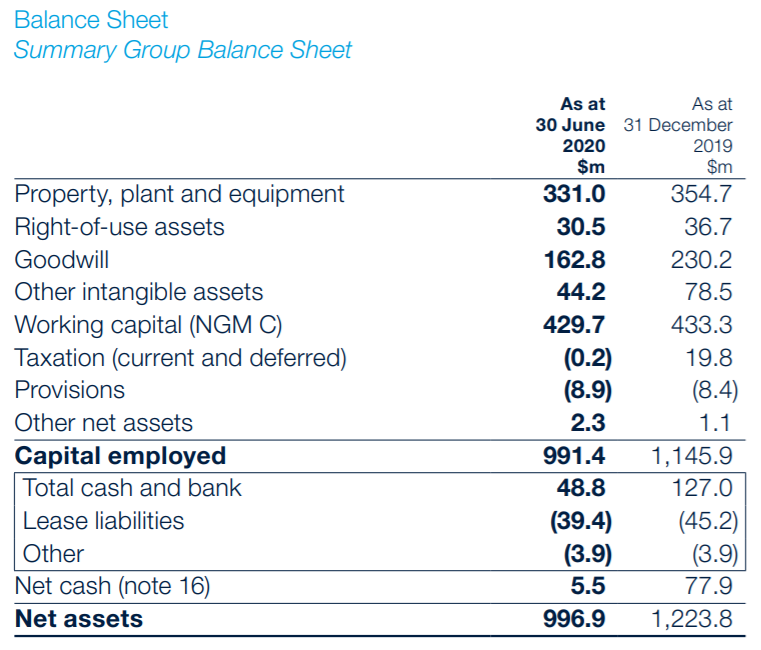
I’ll check out the last published balance sheet now. This is from the interim results to 30 June 2020;
.
.
As you can see, goodwill & intangibles have been reduced this year, so I’ll write them off completely. That gives us NTAV of $789.9m - that’s a lot, for a company currently valued by the market at £221.8m.
Therefore a key feature of this share, is that it’s trading at a deep discount to NTAV. That’s the market telling us that it doesn’t think the assets have much productive value. On the upside, it means the shares look solidly underpinned, and there could be hidden value here.
Look at the $429.7m positive working capital position - that’s huge. It does make me wonder whether it might be a breakup situation possibly - i.e. to wind down operations, turn the assets into cash, and liquidate the group, or parts of it? Maybe the shares could reach a low point where asset strippers, or takeover bids from competitors, might appear?
Outlook - very dependent on demand for oil;
"Client activity should improve during 2021, but a sustained recovery in the market will be a function of the decline in COVID 19 driving positive global economic activity. The effects of the pandemic continue to depress demand and weigh heavily on oil price sentiment."
Trading year to date -
In the year to date, Group EBITDA has been c.$28m, with Q3 2020 EBITDA showing a broadly break-even result. The Group continues to report a strong cash position of c.$69m, before lease liabilities, as at 30 September 2020, as working capital improvements continue to generate cash.
Dividends are still being paid -
On 23 October 2020, $3.3m was absorbed following payment of the second interim dividend in 2020, which totalled 2.0 cents per share.
My opinion - I’ve only scratched the surface of this, to get an initial idea of whether it’s worth doing more work on this. There’s more info in the RNS.
It does look interesting actually. I love the deep discount to NTAV, and the strong balance sheet. It’s struggling re trading, being in a very difficult sector, but has down-sized already, and is not bleeding cash.
I think this looks a potentially interesting special situation. Like it or not, the world still needs oil & gas. Therefore, it’s likely that demand could rise again, and if the oil price rises, then producers might want to buy more stuff from Hunting, possibly?
.
Quiz (LON:QUIZ)
Share price: 7.5p (up 4% today, at 14:46)
No. shares: 124.2m
Market cap: £9.3m
(I hold)
QUIZ, the omni-channel fashion brand, announces its unaudited preliminary results for the year ended 31 March 2020 ("FY 2020").
This is a special situation, because the company did a pre-pack administration of its 80 standalone stores, which I reported on here on 10 June 2020. It is crucial to understand how the pre-pack worked, to understand where things are now.
Therefore the historic results for FY 03/2020 are now irrelevant, because the company has dramatically changed - the loss-making shops are gone, and the remaining stores have been renegotiated onto turnover rents. Turnover rents are an absolute dream for a retailer, as it largely de-risks the store portfolio. Rent is paid at typically c.8-12% of turnover, monthly, and flexes up & down according to how the store is trading (subject to a base rent, usually set quite low). In this way, all the remaining shops should now be profitable, or at least close to it. That’s a game-changer for future financial performance, hence why the historic numbers are now not relevant.
Quiz has done a pre-pack administration before, in the 2008-9 Great Financial Crisis. Wind forward to 2017, and that business was floated on AIM at a valuation of £200m! The founding family took out £92.1m as part of the float - not a bad return from a business that had gone bust just 9 years earlier. It’s a good demonstration of how a pre-pack administration can lay the groundwork for a highly successful business in future, unburdened with loss-making sites, and with freshly renegotiated low rents. It’s worked once, I reckon is likely to work again.
Therefore focusing on the historic poor performance is missing the point completely. This is a turnaround, with a clean sheet, and lowered rents. Plus of course it has a decently successful online business. Once growth returns there (if it does), that could be another trigger for a re-rating.
Quiz focused on special occasion wear, which is a great pity, and unlucky, given that special occasions have largely stopped this year. Accordingly, the company has pivoted more towards casualwear this year, but performance is bound to have suffered if your key specialism suddenly becomes unnecessary for customers.
Sales since the year end are heavily down, because that covers the lockdown period, and also because only about three quarters of shops were re-opened. So we’re not comparing like with like here. Even so, this is an awful number below, so the company clearly isn’t out of the woods yet. Although the cost base is drastically lower now,with rents slashed, stores closed, and no business rates to pay;
As a result, the Group's total sales in the six months to 30 September 2020 amounted to £17.2m, a 73% decline on the £63.3m revenues generated in the previous year.
Outlook comments are all-important here;
· Despite very challenging trading conditions during the current financial year to date, the Group has taken multiple actions to preserve liquidity and at 26 October 2020 has £4.8m of cash and £3.5m of undrawn banking facilities.
· As a result of the store restructuring undertaken by the Group following the period end, the Board believes that QUIZ has a more flexible and economically viable store portfolio moving forward with an average lease term of 24 months and a significantly lower cost base.
· The Board continues to believe that the QUIZ brand has strong customer appeal and that the Group's omni-channel business model remains relevant and key to our long-term success….
We are confident that the actions we have taken to preserve liquidity and reduce our cost base while continuing to invest in the brand mean that the Group can return to profitable growth as market conditions improve.
Cash - this is all I’m interested in at this stage. Recovering from a pre-pack administration takes time, and is painful. Supplier confidence takes time to rebuild, and often involves having to pay up-front for new inventories, until suppliers gradually regain confidence in the solvency of newco.
As you can see above, Quiz is still sitting on a decent-sized cash pile of £4.8m (down from £6.9m at 31 Mar 2020), plus has unutilised bank facilities (with no covenants) of £3.5m, hence liquidity looks fine for now. That cash pile buys time to see the stores & online trading recover, hopefully. Remember these are experienced rag traders, who know what to do, and have been doing it for a long time - very successfully in the good times, but clearly not successfully when the economy dives.
Rent reductions - this shows just how deeply the rental costs have been cut, giving a very good starting point for rebuilding the business;
With our new store portfolio structure, on the basis of revenues being at similar levels to revenues in the year ended 31 March 2020, the rent payable would be approximately halved on a like for like basis.
My opinion - I’m encouraged by the cash pile & borrowing availability mean that Quiz is very much still in the game, and stands a good chance of being able to rebuild. My main worry was, would they run out of cash? There’s still plenty available, so that point remains OK.
Only time will tell if management is able to rebuild the business, I don’t know for sure what is likely to happen, nobody does. But Quiz is certainly now in a much better position than many of its competitors. All its problem leases are gone, and the stores are now trading on cheap turnover rents.
The market cap is under £10m, and I feel there’s good potential upside on that, once (if!) the business recovers on its new super-low cost base. Experienced management have done it before, so I think the odds of this recovering are more than 50%. The upside could be substantial, I’ve got a rough idea in my head that this could be a 5-bagger, taking a 2-3 year view, if trading moves back into profit. The downside case is that recovery doesn't happen, and the business gradually runs out of cash, and goes bust. I think we would see that coming, hence could exit at maybe half the current share price.
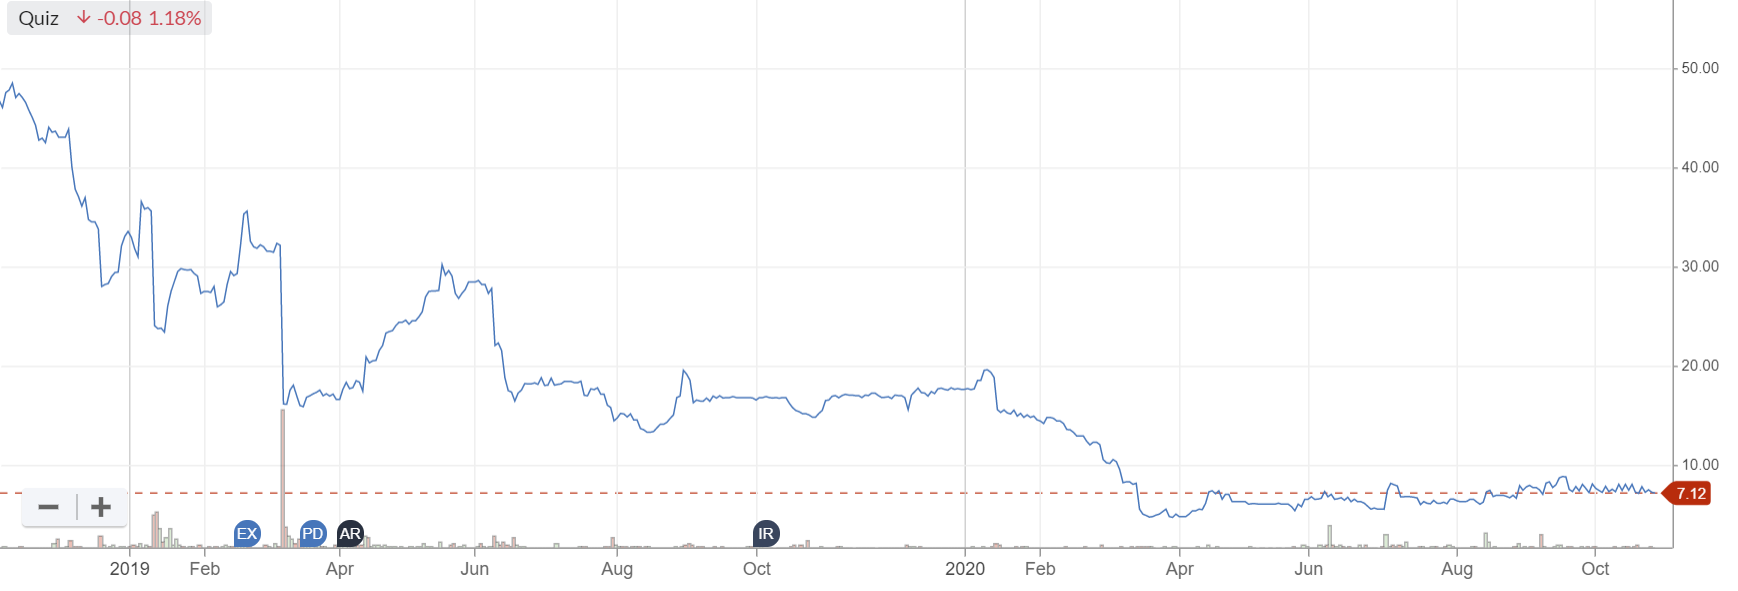
Looking at the chart, it does seem to be forming a base at around 7p perhaps?
.
.
Revolution Bars (LON:RBG)
Share price: 9.65p (down 2.5% today, at 16:14)
No. shares: 125.0m
Market cap: £12.1m
(I hold)
Launch of CVA in subsidiary entity
We knew this was coming, see my article here on 25 Sept 2020, when the company indicated it was looking at options, including a possible CVA.
CVAs are coming thick & fast in the hospitality & retailing sectors, to a point where companies that don’t restructure their leases through a CVA would be at a big disadvantage.
I’m very pleased RBG has decided to do this CVA, as it will;
- Permanently get rid of loss-making, uneconomic sites,
- Reduce rents on viable, but over-rented sites
- Reduce balance sheet lease liabilities
- Increase profitability & reduce cash burn
Hence a very positive development.
These arrangements do not apply to the entire group, but the largest trading subsidiary;
The Group's Revolucion de Cuba branded bars and four Revolution branded bars operated by other entities in the Group are unaffected by the proposal. Furthermore, there is no impact on RBG with respect to its AIM listed status.
Landlords have already been flexible & helpful it seems;
...a sharing of the rental burden has been agreed by approximately two thirds of landlords for which the Board is very grateful. These arrangements cover a wide spectrum, but many comprise lease extensions or the removal of tenant break options in return for short term rent relief.
Current trading - has been clobbered by the 10pm curfew & local shutdowns;
The Group has reported previously that *comparable venue sales in the 8 weeks from when it commenced the reopening of its bars on 4 July 2020 through to 29 August 2020 were 72.5% of last year, ahead of the level anticipated by the Board at the time of the announcement of its equity fundraising. In the subsequent three weeks, *comparable venue sales remained buoyant at 77.8% of last year, but in the last five weeks to 24 October 2020 have reduced to 49.4% due to the imposition of the 10pm curfew and more recently localised lockdowns, with more severe operating restrictions now affecting many of the Group's reopened bars.
With revenues down by half, the company must be at a point where it would make sense to re-close some of its sites, back into mothball state where cash burn would probably be lower than continuing to trade?
Outlook - as we all know, it’s looking difficult for bars, especially late night operators like RBG, so nothing new here;
Given the latest Government restrictions under which the Group is operating, the Group's trading outlook is uncertain and based on all the information and commentary available, the Board now anticipates that the important Christmas trading period will be severely compromised and any return to near normal levels will not be possible before next Spring at the very earliest.
Paradoxically, that helps make a CVA more likely to be supported by landlords, since they can see how bad the outlook is.
This looks a rather mild CVA, far less drastic than others I’ve seen;
· RBL expects to exit six bars and obtain materially improved rental terms on seven others. Where, improved rental terms are being sought, landlords will have the option to terminate the lease at various junctures over the next two years;
· The remaining 37 bars in the RBL portfolio will not be materially affected. These bars either benefit from Group guarantees, are considered strategic to the brand, and/or rental mitigation has been agreed with landlords in recent months;
Benefit of the CVA - is about £2m p.a. - worth having;
If the CVA proposals are accepted, the Group estimates that its annual cash flows (before one-off costs of implementing the CVA) will improve over the next two years by approximately £2.0m per annum. The CVA will not affect the ordinary course operations of the rest of the Group, which continues to trade as a going concern.
Banking arrangements - the bank is supportive, but monitoring things closely. Remember that the bank has a Govt guarantee over a big chunk of RBG’s facilities, so the facilities should be secure to get the company through to the other side of covid restrictions, I hope (but nobody knows the timings for sure). When things do return to normal, there’s likely to be a lot less competition, so expect an absolute bonanza for RBG at some point in 2021, if it survives.
My opinion - clearly this is now a special situation, which is all about survival until social distancing & other restrictions are lifted. I think that’s visible on the horizon, as quick/cheap testing should be available within months, and vaccines are also apparently close to early stage launch.
After extending the bank facilities, and the equity fundraising, my understanding is that RBG has plenty of liquidity to take it well into 2021.
What would this business be worth, once trading conditions have returned to normal? I reckon 3-5 times the current valuation is about right. It would be able to repay debt fairly quickly, because in normal circumstances, this is a highly cash generative business. Even more so in restructured form, with all the loss-making sites gone. Plus it might have opportunities to snap up bust competitor sites for a song.
At this stage, I think risk:reward is good. Obviously it’s been a disastrous investment so far, because of covid, but that’s irrelevant in terms of making an investment decision to buy/hold/sell today. All that matters is what the future holds. I see favourable risk:reward, because I think the group can get through to a covid recovery world before it runs out of cash, especially given that the rents are now coming down for problem sites with this CVA. This business should be making £15m+ p.a. EBITDA once it can trade normally, in my view. That’s what makes it so interesting. Its customers are young, and want to party. Therefore demand is like a coiled spring, that’s going to be released at some point, we just don’t know when.
.
No chart here, as I can't bear to look at it!!
All done for today. See you tomorrow!
Regards, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

80 comments
For those exploring bottomfishing with Hunting (LON:HTG) - the company is heavily reliant on the US O and G industry. Now with blue wave no more - o and g industry can sigh with relief. Also, Hunting (LON:HTG) has extended life once US o and g industry picks up.
Not really sure how far it affects Hunting (LON:HTG) , but I think you'll find that the blue wave was in the post.
Looks like there is even a chance that the Democrats get both houses Hasn't happened for a while and I'm not where that breaks if the president has both houses. Despite all of the rhetoric, if that does transpire we'll be glad that Biden is a moderate.
Thanks Paul, another brilliant report. Regards, Andrew
Revolution Bars (LON:RBG) (I hold)
Does anyone know:
a) why 4 more bars would be opened yesterday (why so late and with all the new lockdowns?) and,
b) whether the openings (yesterday) might have been timed with today's announcement? If yes, would there be any specific rationale for this?
Announcement of 4 more openings can be found here:
https://twitter.com/Revolution...
I'm pretty sure a) is a question make for all of us, but maybe someone has insights into b) ?
Cheers
A
Revolution Bars (LON:RBG)
I'm pretty sure a) is a question make for all of us, but maybe someone has insights into b) ?
Its tricky to be sure but it kind of makes sense that it may of partly been a ploy to get better rent discounts or it wasn’t worth the COVID related kit out costs if there was doubt that they may close outlets so now deal is done time to ge5 up and running.
iI would Guess the wind down of the furlough may also have something to do with it if they now have to partly fund wages might as well make em work.Not sure if they need to be open to get the new local council assistance for tier 2+ sites and Finally I would also guess that sites may materially dilapidate over the winter if left closed and are cold and damp. So plenty of reasons to get back up and running meethinks.
Finally I would also guess that sites may materially dilapidate over the winter if left closed and are cold and damp.
The longer a bar remains closed the higher the reopening costs are so there is always an imperative to get them running again. Mainly the costs is in machinery breakdown (ventilation systems, refrigeration etc) but also stuff you don’t think about - for example, we had to do a full legionella work up (which was expensive) after the last lockdown. I heard about a competitor who had a whole rat infestation, which cost thousands...
As far as RBG is concerned I think unless the government has the courage to admit their sunk cost fallacy issues they will continue to try and restrict the sector. I found this video interviewing Nick Hudson from Pandata19 compelling https://pandata19.org/coronavi...
The government has to return agency to the hospitality and retail sector and admit they got it wrong.
Nick Hudson did a brilliant interview on “state of the market” last week - definitely worth listening to
The Quiz (LON:QUIZ) update today was not very helpful IMO!
What's the latest month's YoY comparison? What is the current cash burn? What about scenarios (low, mid, high) for the next few months in terms of cash?
The fact that there was no mention of Positive monthly EBITDA, positive cash flow, positive any metric in the recent month(s) can only mean they're still heavily cash burning.
They do state current net cash of £4m+ but this could be from stretching creditors, definitely stretching VAT/HMRC payments, etc that is all going to come home to roost in the next few months. Therefore I see the £3m+ banking facility as not enough, as working capital will be required to build up stock levels again, through own stores and franchises.
I agree that the current valuation is cheap vs the brand equity, current net cash. But can Quiz ever recover? It wasn't a strong brand to begin with. Their existing customers - having spent 6-12 months not buying any dresses/partywear from them - will they go back to Quiz, or be tempted to try other brands?
Some fair points there, I agree Quiz (LON:QUIZ) are not being fully transparent about current trading.
As regards inventories, they're already trading, so they have inventories, and bought all the stock in the pre-pack. I reckon the stores will need about £30k at cost inventories. So 60 stores, that's only about £1.8m in inventories, plus some more for the concessions (less, about £5-10k per site), and some Head Office stock for online sales. Therefore I estimate the (now smaller) business could probably run on about £4-5m inventories (it had £9.6m at end March, before the restructuring).
Backed-up creditors? I imagine you're right on that point, but the company isn't telling us if, or how much.
Overall, I think you're right, we're only being given incomplete information. I think the cash headroom is probably enough though, including the bank facility. But until we get interim results, we won't know for sure.
Regards, Paul.
Somebody the other day was aking about finding risers and fallers of the day... I just came across this Google Sheet to the top risers + other useful variations on the same theme:
https://docs.google.com/spreadsheets/d/e/2PACX-1vR8x-34i2j-974-ughIQB8x3xyv2a0DdWUFyfQKbyZQIgUcP8rIpnWdDwt3IHgE5rRiu_pglkNKGCrn/pubhtml#
Ref: QUIZ (LON:QUIZ)
If a retailer negotiates a rent based on turnover, how does the landlord verify the turnover so that the correct rent can be charged ?
The accounts are presumably only required to show the turnover for the entire company, including all stores, on line etc, so this would be of little use.
There's a requirement in the lease to produce an audited statement annually for the landlord, to verify revenues. That was about 20 years ago, when I managed about 50 turnover rent sites. These days I imagine landlords might have software to link into the EPoS system - do any readers have any more up-to-date experience of this?
An extra issue now is how to account for online sales - how much do they benefit from the store presence, what about click and collect from store, returns via store etc.
Some scrappy notes below on Bloomsbury Publishing (LON:BMY) for anyone interested (apologies for the Adrian Mole-esque digital scribbles).
FWIW, I like the cash generation and will hold for now, but I was put off by the underlying weakness in the last 2 months of the period (which the company did NOT highlight) - it makes we wary that this negative trend will continue for the rest of the year:
Results were okay, but there was a BIG slowdown over the summer.
Print Revenues actually decreased YOY in P5-P6:
Academic GM actually decreased. This is strange given acceleration in digital sales. Implies digital margins are actually lower than print - this is implied in commentary, so the company isn't lying to us, assumed the positive side is that revenues are just more predictable due to the Saas nature of this stream:
Why do you no longer list all the companies you review in the right hand margin - it was very convenient?
Why do you no longer list all the companies you review in the right hand margin - it was very convenient?
That's an automatic thing that the website does, not something I do. It's showing as usual on my screen. Maybe raise a green ticket to query it with Stocko HQ?
It just worked for me kendal, arrows down opens the chart? - Silver
It’s a device issue for me - works about half the time on my iPad (today list isn’t visible there), always works on my PC (today’s list is visible there)
The Ftse100 continued its drift down today; nearing 5750 at the lows. I wonder if investors are simply taking money out of the market? I know I am albeit slowly. Worries about Covid of course but this weekend sees the end of a lot of various government schemes. Not just furlough but interest free overdrafts, automatic mortgage deferrals and so on. A neighbor is surprisingly selling personal possessions; she is usually a spender but admits money is getting very tight. Worries that lockdowns may continue for many months is affecting a lot of my friends and family; this may lead to a skinny Xmas and a dire January and February next year.
The Dow fell 650 points at the close yesterday and opened flat today. There seems little doubt that investors are very nervous at the moment; perhaps a good time to buy heavily? Not quite yet I sense.
Or shift focus to overseas markets, particularly SE Asia Japan and China. Aberdeen Emerging Markets Investment (LON:AEMC) is on a nice discount.
FTSE 100 is still full of banks, insurance and oil.
Re Barnpeter Ftse100 down.
Its been an ugly day on the market: I am seeing my massive International Personal Finance (LON:IPF) holding down 7.69% so far.
However, it can just as quickly bounce back on a Brexit deal, US stimulus package, Trump victory, and COVID-hysteria vaccine.
... at least I don't live in Wales under that frightened parish councillor dictator.
Of course.....at some stage it will be right to buy trackers or large cap investment trusts. Buying in March this year was the right thing to do and we might go close to those lows in the months ahead.
"More than 95 per cent of London businesses have cancelled bookings for traditional office parties this Christmas".....this is a key time for a lot of small business and I doubt many will survive. But others will take their place by next year.
Plus500 (LON:PLUS)
To my regret, I sold my holdings @1375p a few months back, trousering a nice profit.
The trouble with PLUS500, is that when it falls, it falls quite wildly and one can have a long wait for the next good news.
I got caught in the February 2019 "miss" when the share collapsed and I chased it down to get my money back.
Playing with (Israeli) fire with this stock. I sleep better out rather than in!
If it heads <£13 or <£12, I'll be back.
Re Plus500 (LON:PLUS), and quite a lot of other stocks, I see what I would describe as quite a lot of profit taking today. Novacyt Sa (LON:NCYT) is another. Where stocks have gone from nothing to a lot in a short space of time, naturally people will top slice and then the fall can turn into a rout.
On another matter, I would welcome some advice from contributors on FX charges and those trading sites which offer a better deal on foreign shares, in my case European shares in particular. I remember some helpful discussion here recently, but I didn't make a note of them. Any help gratefully received. HL and iii charge a lot IMHO, which they obviously feel is fair, but if it can be safely reduced elsewhere it is worth knowing. Thank you in anticipation.
Fully agree. At the risk of stating the obvious, Threaded view makes sense at some times - eg viewing after a some hours away when there maybe 50+ new posts - but for incremental viewing, after just a dozen new posts, then Unthreaded is more convenient. If I can't readily tell what stock is being talked about I tend to ignore the post.......or even Thumbs-down if really grumpy!
Revolution Bars (LON:RBG)
The CVA is good news. But this part was not
"but in the last five weeks to 24 October 2020 have reduced to 49.4% due to the imposition of the 10pm curfew and more recently localised lockdowns, with more severe operating restrictions now affecting many of the Group's reopened bars"
So it's back to a Covid viewpoint, RBG needs the lockdowns to ease.
Paul may have a view as to their cash buffers and runway length.
Runway length...... crash landing? Sorry about this, I can't help seeing a funny side to £RGB
what is going on with AXS today ? any ideas ?
Hi Shrubby,
It's a quite illiquid stock, price jumps can be quite sharp when the selling stops.
BSV
Hi Shrubby - Well its good news for me - but Yes - whats going on.? Maybe progress at the new Hull facility - or a trade agreement with new partner in USA - any number of things... I'm no expert but it does seem there have been a lot of trades today - more than usual. Of course with such a small MktCap I dont suppose it takes much to chase the price up or down. Its also a very 'green' company and with all these ESG funds chasing for new opportunities...!
re Accsys Technologies (LON:AXS), I suspect read across from good news coming out of suppliers into the home maintenance/improvement market. Very thin market in my experience.
Re Quiz (LON:QUIZ) RNS - Results for Y/e 31st March 2020 out (!!) but with commentary on this year. Steps taken include CVA, closure of stores internationally (a few may come back in Eire), various cost saving measures and withdrawal from some 3rd party websites where margin was too low. It also reports online sales through its own Quiz websites held up and became more profitable, largely from cutting marketing costs (all not quantified) Still has cash and liquidity (and a belief in an omni-channel approach!) and now has a more focused, more online business
However, 2 major Marketing concerns for me . First, with COVID ongoing, QUIZ recognises "Our ranges have traditionally been based upon providing options for socialising from going to lunch with friends to attending weddings." and so is switching range from glamourwear to include casual wear - this makes sense but means a move to an area where it has no brand or design heritage. Secondly, it continues to promote Sam Faiers as its lead celeb. Perhaps this makes sense short term if they are milking the existing customer base (ie all Marketing spend is on emails /social media to existing contacts/customers) but she is old news as far as the young are concerned. TOWIE just did its 10th anniverasry I think.
Net, I think could be a good private business here long term but no need to list (where it gets tied up in spillover from BOO related ethical issues). The owner made a fortune listing it at 190p (I recall). Now at 8p I am hoping he buys it back at 20p. It will be a long wait for a return otherwise.
Please will posters say which company they are talking about - it only takes 3 or 4 extra characters £xxx
There are 3 ways of reading this - old site (which is earliest first), new site unthreaded and new site threaded. So Neil W Jeffvshepherd and ThumbsUp (most recent but there are dozens of others) - only those on the threaded version have any clue as to what you are writing about.
Annoyingly, the £ function doesn't work (at least for me) on mobile. I've edited the post on PC now so it includes the Plus500 tag.
Yes, sorry. We were talking about Plus500 (LON:PLUS)
No doubt Paul is writing a more penetrating analysis of £RBG 's announcement in an RNS of a CVA covering its RBL subsidiary containing 50 Revolutions (the historically more successful, newer format Rev de Cuba;s are unaffected) but to kick off the inevitable debate on this site, this seems like mixed news to me.
On the +ve, IF it can survive, closing 6 of the weakest Revolutions and getting "materially" better rent on 7 more what is left (especially after the previous round of closures) should mean what's left are structurally profitable ones, excluding the impact of COVID. If next spring the sun is shining and every young vaccinated person is out drinking with relief, cash flow and recovery should be rapid.
However, on the -ve, with the big 2020 Christmas earning period already screwed and the Board believing "any return to near normal levels will not be possible before next Spring at the very earliest", the risk of complete default or, more likely, further equity raise in Spring (if vaccines/treatments are then in view) seems very high.
At least the bank still seem supportive - perhaps in the same way a 2nd mountaineer is to the lead climber when sharing a rope.
Anyway, an accounting query,:as part of the proposals, "the Group will write-off 50% of the £30.9m debt owed by RBL to RBG, which will materially strengthen RBL's balance sheet." Will this lead to a carry forward loss and thus low tax burden for years to come. Come to think of it, will this be true for all company's reporting thumping losses this year.
FWIW I hold (& probably will all the way to until oblivion is inevitable or major recovery )
Revolution Bars (LON:RBG)
At least the bank still seem supportive - perhaps in the same way a 2nd mountaineer is to the lead climber when sharing a rope.
I think the government should take the credit for the ongoing support here - the CLBILS loan of £16.5 million is specifically what will be keeping the lights on at present. I would be pretty certain that extra cash would not have been handed out had it not been for the governmnet backing.
Living in tier 2 area it is not surprising that trading numbers are so dire - having to go against official advise and sitting outside to meet friend aint much fun - ok one can probably game the system somewhat and sit apart inside (technically on ones own) but that isn't practical in all pubs and i would guess is somewhat frowned upon in most pubs (not had enough inside pub drinking experience recently to comment in how it works inside pubs at present :()
hi zipmanpeter - I think you are being overly pessimistic. The board seem to be taking the right steps to ensuring the business survives without taking on too much additional debt with a view to recovery next year. Whilst business is clearly very challenging the new employee support packages for the hospitality sector means the company should now have decent flexibility over its cost base. With reduced rents, no rates, the £2m annual saving from the CVA plus the new govt wage support and some cost cutting I would envisage the business should be able to get to broadly b/e and minimise cash burn on 50% revenues. Far from ideal obviously but that should allow them to survive if my calcs are broadly correct. I would prefer management to give us that b/e information though else we are a little blind.
Assuming life gets back to normal at some point in the next 6 months they should then be relatively well placed to be strongly profitable. I think the big risk to the business is if things aren't back to normal by mid next year as support measures drop off. My base case is that they will be but obviously that is no more than an educated guess.
Zipmanpeter - I am afraid there is no tax relief for the loss on a loan to a subsidiary. If the holding company were allowed a taxable loss the subsidiary would have an equivalent taxable profit on the amount foregone. In any event the subsidiary must presumably already have incurred trading losses in order to be in a position where it cannot repay the loan. It will have obtained tax relief on these losses and will no doubt have surrendered them to the holding company which may well now have significant losses to carry forward. To give tax relief on the loss on the loan would then be to give tax relief twice.
Doublelutz Thanks for education - makes sense as well .
This is not one for Paul, but for you very knowledgeable people out there. On the face of it Plus500 (LON:PLUS) appears to have had an amazing trading statement - revenues up by nearly 100% for Q3, however, there is a big share price drop this morning. What are the reasons for such a drop? Are better results expected or is it a case of profit taking?
Already an interesting discussion on value has started this morning as to why value is performing poorly - I mention this because PLUS 500 has a value rating of 81 on Stockopedia. I get the feeling that PLUS500 is very much a marmite type investment........
I was thinking the same thing. Anyone know why market has reacted badly to the statement?
Hi Neil W - Re Plus500 (LON:PLUS) - Proposed Australian Regulatory tightening?
Plus500 (LON:PLUS) The Australian Reg stuff has been known for a little while. I expect it's a mixture of the paragraph Jeff highlighted below, and also that the market was probably hoping for an earnings upgrades vs consensus.
Hi Thumbsup re your comments on £PLUS. I am sure you are correct.
Amazing how often language like hope, wish etc creep into our reasoned and logical investing decisions, then affect the market on actual news!
I'm something of a contrarian ezlifeme so for the first time I have bought a few Plus500 (LON:PLUS) shares today.
Silver
Hi Silver Moon - Re Plus500 (LON:PLUS), ATVB with your investment (I Know how many on here hate acronyms) All The Very Best
Cheers ezilifeme, yesterday I finally disposed of Abcam (LON:ABC) at a small profit and planned on spreading the returns on Polymetal International (LON:POLY), Hochschild Mining (LON:HOC), Trans-siberian Gold (LON:TSG), and K3 Capital (LON:K3C), saw the dip in Plus500 (LON:PLUS) and incorporated that into the plan as well. I will sleep better now.
Silver
My wild guess is that the share was flying on the 2020E prospects. If you look at 2021E net profit - it's significantly lower. Given the interim results today were roughly in-line with expectations and lower than Q2 results, it makes sense that 2021E number started weighing in as it might be coming earlier than expected.
The platform itself is for casual investors (high costs of using) which have high churn and will come at times like Covid and fly away in stable times. Hence the volatility of this stock in general.
I sold Plus500 (LON:PLUS) at 1500p at 3% loss today.
This paragraph in the trading update stands out to me,
Customer Income during the quarter was the second highest quarterly level of Customer Income in Plus500's history, although reduced from the record peak levels achieved in Q2 2020. This gradual reduction from peak levels has continued into Q4 2020.
Hi Letap73 (disclosure: I hold)
Plus500 (LON:PLUS) has dropped back to 1520 this morning - that’s basically the level it has been trading at for past couple of months. The shares had rallied to a new high over the past week of about 1650 based on massive expectations/ possibility of a blockbuster results set and decent news about toothless reforms in Aus. The reality was a good set of results (business as usual) rather than that over prediction. Personally I had hoped for a special dividend here - the company is sitting on a massive amount of cash but looks like they have chosen not to do that.
Agree it is marmite (lots of people don’t like hedging policy and Israeli ownership, both of which do add some measure of risk). But for me, this is getting to silly levels now with this share. Even if we accept FY2020 is artificially inflated due to market conditions, the growth is huge and now in place (ie those customers are recruited and somewhat sticky), ROCE is at 119% and they are sitting on a cash pile well over a 1/3 of market cap (and growing). Yet it is on a PE of less than 9. At some point this share is going to boom.
I can’t help thinking that the company is actively keeping the price down until buy back scheme gets closer to finishing in February. Maybe that’s just my wishful thinking...
Phuntt
Plus500 (LON:PLUS) is not a stock I own or know at all well - but I was tempted to look at the numbers today and admit I might have misunderstood things. But one thing that struck me was that active users in Q3 were 197,976 down from 264,557 in Q2 - despite there being 46,238 new customers in the quarter. Therefore presumably 112,819 (42.6%) of active users in Q2 were not active in Q3. So I presume there is question about the stickiness of customers?
Plus500 (LON:PLUS)
Yes there definitely is, Wimbledonsprinter. It helps me to think of companies like this (actually a lot of tech companies) like customer farmers - they grow them then they eat them so they have to grow more...
It’s the biggest concern for me with £PLUS. Notice I said “somewhat sticky” above. The facts are that 80%ish of their customers lose money so every quarter they are losing accounts either because they get blown up or people realise this isn’t for them. They are also a “gateway company” - they spend a lot of money recruiting people compared to competitors but their spreads are large and the smarter players will migrate to other companies naturally.
Their churn rate was 43% in Q3 2020 versus the more normal 20% rate in the equivalent previous year’s quarter so a lot of the bonus customers picked up earlier in the year have fallen away again. But I say they are somewhat sticky because they are left with the residue of these customers (whatever that is) - I’d also note they didn’t “pay” for these customers, they came for free because of financial turbulence and their recruitment costs have gone back up to more normal levels now.
I think about it like this:
Customer recruitment cost roughly $1,000
Revenue per active customer per quarter roughly $1,000
Churn rate of 20% per quarter means median customer stays for 2.5 quarters
So each new customer is worth $1,500 profit to PLUS
However if that churn rate stays at 43% then median customer stays for 1.16 quarters so each new customer is now only worth $160 profit to PLUS (basically recruitment break even which is death).
So I say “somewhat sticky” until I see evidence in the next results that this has returned to normal. It should I think and I’ll add I think this company has a chance to do really well overall out of CV19 (couldn’t help myself - bought more on the dip this morning)
I think there is a fear of valn on these companies where Covid has clearly helped them. Novacyt is off too. How do you value one off (or maybe longer but perhaps not permanent) situations? Will the Company do good things with the money? In particular here are the regulators going to wake up to how they run their businesses? What will happen when the Democrats come in? Basically my feel is uncertainty is rising.
But is it one off for the likes of Novacyt Sa (LON:NCYT) and Open Orphan (LON:ORPH)? There is a strong chance of government (and therefore biotech) spending shifting a little in favour of virology/epidemiology (which seeemed to me poor relations in healthcare until Jan this year) from other areas such as oncology.
Sorry if this is obvious but I think sentiment plays a big part too when investors who might well have stretched their liquidity to buy Novacyt Sa (LON:NCYT) view their big blue figure decreasing rapidly and all those gains start to evaporate., so they sell before they disappear entirely. Depends what price they bought at I suppose. I for one am certainly holding my breath this morning as well as my nerve. If I was really courageous I suppose I would be bravely buying.
It seems likely that by June 2021, Governments everywhere will be offering mass vaccination programmes for Covid 19. Perhaps there will be work on improved vaccines for another couple of years. But wouldn't the demand for testing people and vaccines fall away to what is was before over the following years?
Given the report today on BBC website "scientists find antibodies decline fast after Covid infection" I think testing is going to be around long term.
Plus500 (LON:PLUS) I suspect that the drop today is just a reaction to the large uplifts over the last couple of weeks........the price now is roughly back to Aug/Sept levels.
The most impressive part of the results today for me was the cash they now have (>$700M) with one quarter to go. I was a little surprised they did not announce a special dividend.
You say 'amazing trading statement' but the market will focus on the outlook. I tend to read these statements from the bottom up, 'EBITDA in line with analysts expectations' for a stock that has blown the doors off several times put me on guard immediately - that seems to imply a slow down later in the year. I like to focus on the rate of change of key metrics rather than the change (i.e. the first derivative). Markets are forward looking. Sometimes it is better to travel than arrive.
Plus500 (LON:PLUS)
What are the reasons for such a drop? Are better results expected or is it a case of profit taking?
The main summary is that the company is only in line with previous expectations with regard to expected year end numbers - in some respects that means if q3 numbers were better than would have previously been expected then q4 is likely to be worse than previous expectations all other things being equal.
Note ytd EBITDA 9 months is $496 mill - and they are only expecting $520 year end - so huge drop expected q4 compared to prior periods - so this does suggest the good times may be over with regard to next 15 months or so.
Also next year numbers per stocky show expected profit drop in earnings of over 50%+ compared to this year.
So i can see why there is a sell of if the company is flagging up that they expect to go into reverse for next 15 months. Perhaps bods were expecting upgrades today.
I suspect due to the volatility of income the company are just being sensible with future forecasts (rightly so) - as the tone seems positive overall - however sustainable growth and 50%+ expected drop in profits are slightly at odds with each other. We all know the market doesn't like uncertainty and i suspect this company is given very little benefit of the doubt in that regard! - ref reugulatory issues - its not clear if they are obfuscating here or not but they have confirmed the Aussie changes are already factored into 2021 number - i somewhat wander here if they may be strealing slightly from the pot of safety elsewhere in that regard? - ie if forecasts are now slightly less conservative than they otherwise would have been?
(Disclosure: I hold)
Or is it that the brokers consensus estimates (and therefore Stocko data!) are just plain wrong?
Liberum have admitted this morning Plus500 (LON:PLUS) have already exceeded their previous FY20 estimates. They also acknowledge that 3Q20 Revenues were 133% ahead of expectations. It's not exactly a picture of accuracy.
In acknowledging this, they also admit that despite likely increases in earning potential, they will not increase FY21/22 estimates.
This leaves just $49m of Revenue and $24m of EBITDA in Q4 to hit consensus results. (EDIT to add: average monthly run is $86.7m Rev and $55m EBITDA)
According to Plus500, Q4 thus far only represents a "gradual reduction from peak levels"... not exactly falling off the cliff to validate the consensus is it?
There's being conservative and then there's just being plain wrong...
Plus500 (LON:PLUS), one can only imagine the conservative news is to beat expectations for the full year. The key number to observe is the Number of Active Customers, as this is the best indicator of long term revenues. This is up 116% YTD, if Plus500 (LON:PLUS) can hang on to these clients revenues could be sustained for longer.
BSV
Wh Ireland (LON:WHI) H1 20 results overview by Phillip Wale, CEO. (Following results released yesterday).
WHI achieved a H1 profit for the first time in 5 years. Revenue up 15%. Cash £5.85m. For the outlook, Phillip says, 'I believe the momentum we have seen in the first half, alongside a robust capital and cash position, gives us a strong platform for the second half.'
Video or Podcast.
"Covid condemns value investing to worst run in two centuries" - FT
"Value stocks have performed dismally since the 2008-09 financial crisis and this year the drought has worsened dramatically, making the degree of underperformance relative to racier growth stocks even more extreme than at the peak of the dotcom bubble."
https://www.ft.com/content/fc7ce313-92f8-4f51-902b-f883afc1e035
Hi Mr Contrarian
I haven't read the FT article, but I suppose it depends on what one considers to be value stocks. I would expect the market to react positively to Bloomsbury Publishing (LON:BMY) results this morning which are in my view impressive. Bloomsbury Publishing (LON:BMY) might within reason be considered a value stock in 'normal' circumstances. Reasonable PE, good dividend yield and plenty of cash on the balance sheet.
I heard yesterday that a large value orientated American investment fund had thrown in the towel due to its poor continuing performance, which may well be the topic of the FT article. This thought came to mind while re-reading Peter Lynch's 'One up on Wall Street', in particular the chapter on 'Stocks I'd Avoid'. These he describes as the 'hottest stocks in the hottest industry, the one that gets the most favourable publicity, the one that every investor hears about..'
Tesla, Novacyt, Netflix all came to mind. If one can time ones entry and exit points with such stocks then you will no doubt make a fortune, but buying at or close to the top? As has often been said 'it will be different this time', perhaps but perhaps not?
Anyway please excuse my musings. I am now off to read the FT article.
All the best
Re Novacyt - Stockos earnings figures are hopelessly out of date. Barclays stock factsheet has it on a PE of 4.5 for 2020 and 4.0 for 2021. It is highly profitable and cash generative with a v. Large net cash balance sheet. To me - despite the very large profits shareholders have made it represents very good value - to bracket it with Tesla doesn’t quite seem right
I read the same
"Value" has many definitions but the article refers to price to book value.
Issue here is stocks on low price to book ratios, like banks, oil, insurance are ex-growth and risky in the sense their industries are in sunset or at least perceived to be.
It's better to pay a premium for a quality growth stock although some of the US tech stocks have orbital valuations now.
Interesting comment jwebster , it puts me in mind of an article I wrote just last week over at cube.investments looking at the Piotroski F-score. Generally regarded as a Quality metric it was actually designed (and tested) as a tool to improve returns on low price to book value investments; essentially by picking the ones that recover from their "distress".
I have tended to be very sceptical of F-Score because in general it provides a lot of false negatives and positives (imho), but taken in the specific context for which it was designed I can more clearly see the merits.
The trouble however at this current time is that given the F-Score's reliance on latest year outurn and latest year vs previous year, you have a lot of work to do to unravel the "pandemic effect".
This is of course based on the S&P500, like most such articles. It's the same for other factors. Lots of analysis for the US market, but very little elsewhere.
Try and find recent analysis for other markets, such as the UK and as far as I can see, nothing is published. With some work, it's possible to download index data from the MSCI site and make comparisons based on their indices, but of course only as far back as the MSCI index goes.
My morning smallcap tweet: Reveloution puts landlords up against the wall.
Hunting (LON:HTG) Gresham Technologies (LON:GHT) Wisdomtree Zinc ETC (LON:ZINC) Angle (LON:AGL) Revolution Bars (LON:RBG) Coral Products (LON:CRU) AA (LON:AA.) Fusion Antibodies (LON:FAB) ECSC (LON:ECSC) QUIZ (LON:QUIZ)
Hunting (HTG) Q3 results reflect the low levels of activity caused by covid. No rev fig! Broadly break-even EBITDA. Expects Q4 rev slightly lower than Q3 due to the usual seasonal slowdown. ""Client activity should improve during 2021, but a sustained recovery in the market will be a function of the decline in covid." [SP=141 Cap=233m]
Gresham Technologies (GHT) guides FY(Dec) in line. Contracted revenue for FY21 £22.5m of which £14.9m is Clareti. "We expect to further strengthen forward-looking Clareti ARR in the remaining weeks of the year and are encouraged by a growing pipeline for 2021." [SP=113 Cap=79m]
Zinc Media (ZINC) £4m placing at 60p, a 1.6% disc, to keep the lights on and £0.5m for talent acquisition. Trading: rev down 50%. Expects run rate to rise to 21% down. "The pipeline for 2021 looks strong, with £4.1 million of commissions booked and a further £23.4 million of commissions at an advanced stage or in engaged discussion." Admits making a £15k director loan in March w/o shareholder approval. Loan has been repaid. [SP=7.97 Cap=4369m]
Angle (AGL) £20m placing at 46p, a 5% disc, for ongoing operations commercial expansion and R&D. [SP=48.75 Cap=84m]
Revolution Bars (RBG) starts CVA for subsidiary owning 50 out of 73 bars. "The trading outlook is uncertain and based on all the information and commentary available, the Board now anticipates that the important Christmas trading period will be severely compromised and any return to near normal levels will not be possible before next Spring at the very earliest...If CVA proposals are accepted...estimates cash flows (before one-off costs of implementing the CVA) will improve over the next two years by approximately £2m." [SP=9.9 Cap=12m]. I hold.
Coral Products (CRU) trading in line. Delays final to Jan at the latest. [SP=5 Cap=4m]
AA (AA.) PUSU deadline extended to 24 Nov. [SP=24 Cap=149m]
Fusion Antibodies (FAB) get grant of £188k to support mammalian antibody Library R&D. [SP=156.75 Cap=40m]
ECSC (ECSC) two significant contracts worth £580k over an initial 3 years in Managed Detection and Response division. [SP=60.1 Cap=6m]
Quiz (QUIZ) FY(Mar) U/L pretax -£3.7m (+£0.6m) on rev down 10%. Trading: H1(Sept) rev down 73%. "With our new store portfolio structure, on the basis of revenues being at similar levels to revenues in the year ended 31 March 2020, the rent payable would be approximately halved on a like for like basis." [SP=7.71 Cap=10m]. I hold.
Paul,
I would second the request for comment on £BMY please.
Cracking results!
In addition, what do you think about the announcement of a large purchase of £BOO shares from a US fund? Is there anything to read into this (apart from them seeing an highly undervalued growth share)?
Thanks as always
Morning Paul. Would love to know your thoughts on the interim results for £BMY.
Look pretty outstanding to me.
They were very good I thought and indeed some of the books mentioned have been very good - HumanKind & just starting on The New Silk Roads.
Problem with it is that there half year results are kind of meaningless given they generate some 80% of their profits in H2. That said, they are making the right noises and investing in strategy - quite frankly I am surprised this has not shown up on the private equity radar - debt free/stable cash flow.
Also, they adjusted PY EPS to account for bonus share issue. Is this the done thing? - flatters EPS growth.
Great business at fair price - not the worse thing you can be doing according to some old guy who has lost it!
Re: Inserting ticker codes
In another post (I think it was you), you said the ticker-code link insertion doesn't work on your version of the mobile app.
The ticker-code link won't work in any version if the code (of the type £XXX) is immediately followed by any character (such as a full stop).
Instead, you need to leave a space or carriage return.
Regards,
Ed Miller
Good morning! Below covers todays regulatory and potentially price-sensitive announcements.