Small Cap Value Report (Tues 28 Nov 2023) - JNEO, MRL, IGR, TET

Good morning from Paul & Graham!
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. OR it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Summaries
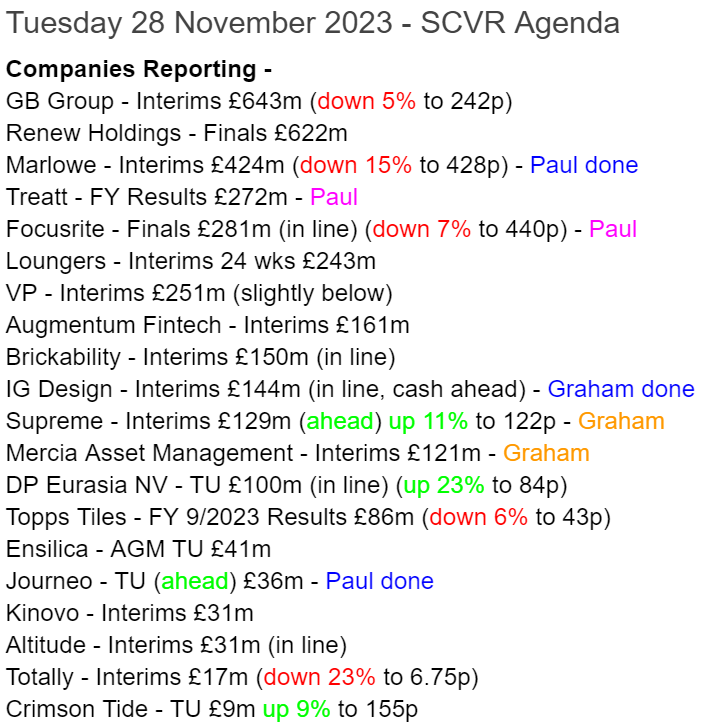
Journeo (LON:JNEO) - 216p (pre-market) £36m - Trading Update (ahead) - Paul - GREEN
Another good trading update, with profit guidance raised about 5%. Positive outlook comments for 2024. This looks a decent growth business, still priced reasonably, so I like it - providing growth can be maintained, and the orders aren't one-offs.
Marlowe (LON:MRL) - down 17% to 417p (£405m) - Interim Results - Paul - AMBER/RED
The market doesn't seem to like these numbers - operating profit looks resilient, and is up, but higher finance charges from the excessive debt pile, and higher corporation tax, cause EPS to fall. The horrible balance sheet is a deal-breaker for me. It's now doing a strategic review, after making 36 acquisitions in under 3 years! All a bit extreme if you ask me.
IG Design (LON:IGR) - up 2% to 150p (£147m/$186m) - Interim Results (outlook in line with Board expectations) - Graham - GREEN
The bull thesis is playing out with much-improved cash generation, a year-on-year reduction in net debt, and no change to the company’s target for pre-Covid profit margins. I continue to view this one as too cheap relative to its prospects. Crucial Christmas period is coming up.
Paul’s section:
Journeo (LON:JNEO)
216p (pre-market) £36m - Trading Update - Paul - GREEN
Journeo plc (AIM: JNEO), a leading provider of information systems and technical services to transport operators and local authorities, is pleased to report an update on trading for the year ending 31 December 2023 ("FY 2023").
Strong H2, revenue now expected to be £46m for FY 12/2023, ahead mkt exps.
Order intake strong, and up on £27m last year - so good visibility into FY 12/2024.
Recent acquisitions (Infotec & MultiQ) trading in line with exps.
Sales mix - more lower margin products.
Adj PBT guidance is now £3.9m, ahead of mkt exps (by about 5%).
Balance sheet - nothing is said today, but at 30 June 2023 the balance sheet looked OK, with £5.3m NTAV. Note that the cash pile of £11.3m on that date had come from customer up-front payments, which might not necessarily always be the case, so I'd be careful about reading too much into the favourable cash position in the interims, as it might unwind possibly? I'll ask management about that at Mello. They should have updated on the current cash position in today's update, but didn't.
Outlook for 2024 sounds good -
Strong sales order intake in Journeo's core Fleet Operator Systems and Passenger Information Systems businesses continues and has surpassed the £27m achieved for FY 2022 giving good forward earnings visibility into FY 2024…
Margins are expected to increase in FY 2024 as the effect of component shortages in supply chains improves, delivery of delayed rail contracts and associated SaaS revenues commence, and the overall business mix changes as the Group's integration programme starts to deliver consolidated products design, unified software and integrated services to its growing international marketplace…
We have an increasingly compelling offering, which combined with continued government support and investment in the sector is delivering our growth plans together with ever more advanced solutions for our customers."
Broker update - Cavendish ups its FY 12/2023 forecast profit by 5% to £3.9m (previously £3.7m). This is 20.6p adj EPS, a PER of only 10.5x, which seems modest, assuming this level of profitability can be maintained, and orders are not one-offs.
Forecast for FY 12/2024 is also increased a little, 4% upgrade to £4.4m adj PBT, or 23.1p adj EPS, a PER of 9.4x - I’d say there’s probably upside on that PER multiple.
Paul’s opinion - this company really seems to be on a roll. The improvement in performance in 2023 is really striking, with revenues more than doubling, and profitability making a step change upwards from the many years of rather lacklustre performance in the past. This was driven by what seems a transformational acquisition.
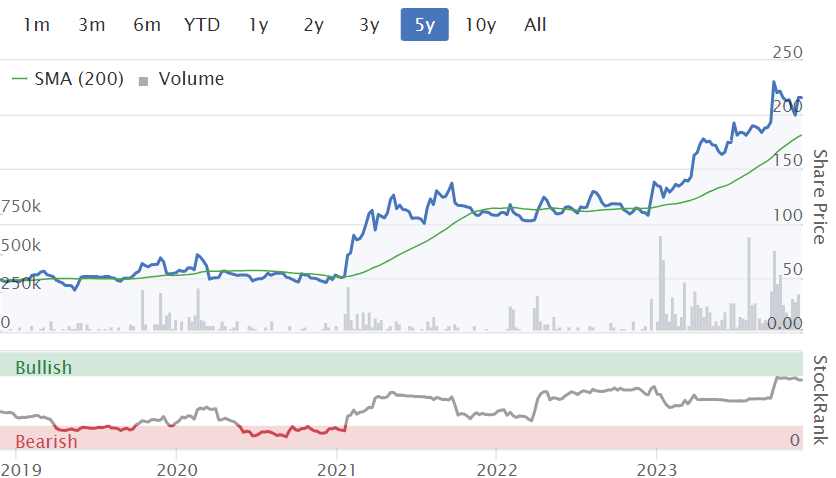
This has already been rewarded with a more than 4x increase in share price, but looking at these numbers, I wouldn’t be surprised to see this share continue its up-trend.
Management are presenting at Mello Chiswick tomorrow, so I’ll try to have a chat with them to discuss the impressive performance.
My view, has got to be GREEN, since performance and outlook are strong, and the shares still look good value.
Marlowe (LON:MRL)
Down 17% to 417p (£405m) - Interim Results - Paul - AMBER/RED
Marlowe plc ("Marlowe", the "Group" or the "Company"), the leader in business-critical services and software which assure safety and regulatory compliance, announces its unaudited results for the six-month period ended 30 September 2023 ("HY24").
I’ll keep this brief, as Marlowe fails my balance sheet testing. When last reviewing it, my summary notes were -
28/3/2023 - Marlowe - down 4% to 480p (£460m) - In line exps TU FY 3/2023. Positive tone. But Paul dislikes overly indebted, weak balance sheet. Too many acquisitions done.
H1 key numbers -
Revenue up 13% to £251m
Adj PBT down 9% to £24.1m
Operating profit is up 9%, so it looks as if finance costs must have shot up - yes they’ve more than doubled to £8.9m cost in H1 (H1 LY: £4.0m)
Statutory loss before tax is £(8.9)m. Lots of adjustments, restructuring, etc. No wonder, as they’ve done a ludicrous 36 acquisitions since April 2021.
Net debt excl leases is up 23% to £192.7m - too high, and expensive now.
Strategic review - they’ve bought a load of businesses now they want to sell some, is how I read this - failed strategy maybe? Or bank putting them under pressure to reduce debt possibly? Placing maybe? -
The outcome of this review may or may not lead to the Board deciding to undertake a managed separation of certain Group businesses with a view to optimising the Group's organisational and capital structure…
This may be via a divestment in the form of a sale, a spin off or a public listing of certain Group assets. Such an action, if pursued, could potentially provide an optimised organisational and capital structure, growth capital for certain Group businesses whilst also enabling a potential significant return of capital to shareholders in the future.
Outlook - sounds mixed to me -
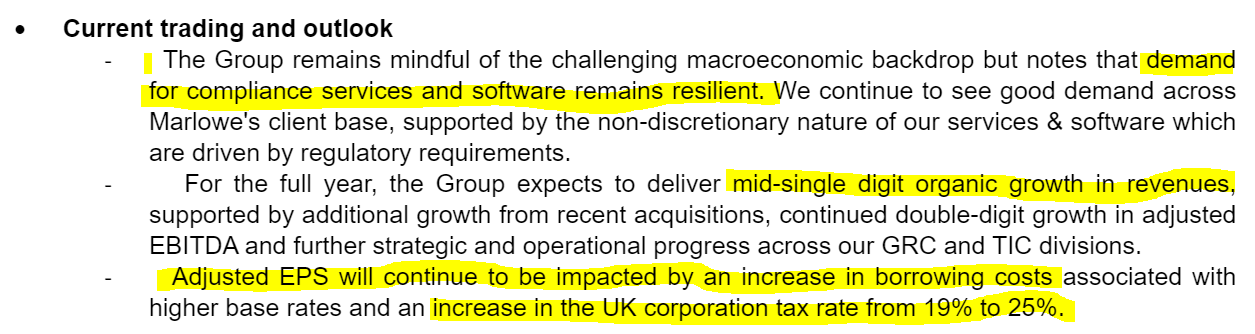
Going concern statement gives itself a clean bill of health.
Balance sheet - they seem to think it’s OK -
The Group looks to maintain a strong balance sheet that is commensurate with the high levels of recurring revenues associated with the business model.
But it’s not OK at all. NAV of £438m contains £667m goodwill & similar. So NTAV is nastily negative, at £(229)m. Being kind, we could eliminate £(55)m in deferred tax (usually related to goodwill), which leaves us with NTAV negative £(174)m.
This means there’s a nasty hole in MRL’s balance sheet, which is plugged by hefty bank borrowings of £193m (net of cash).
It’s true that recurring revenues software businesses can manage on a tight balance sheet, but even so, MRL takes it too far. That rules it out for me as a possible investment.
Cashflow statement - it’s not generating much cash, none in H1 actually, and not a lot last full year. The cash was mainly absorbed by restructuring costs and capex (including intangibles). There are no divis, and the mania for acquisitions is being funded by running up more debt each year.
Paul’s opinion - I really don’t like these numbers, so I’m shifting from amber to AMBER/RED. It strikes me that management might have created something of a mess here, with acquisitions fuelled by too much debt, which is now costing a lot more in finance charges, and there’s no evidence of much cash generation from the enlarged group.
It looks cheap on a PER c.10x, but bear in mind the debt pile is about half the market cap, so simplistically adjusting for debt would push the PER up into the mid-teens.
More restructuring is now on the cards, so who knows what the outcome of that will be? Maybe there are some nice parts within this sprawling group of companies?
Software companies can command high valuations, so this could go either way. Anyway, it’s not of interest to me.
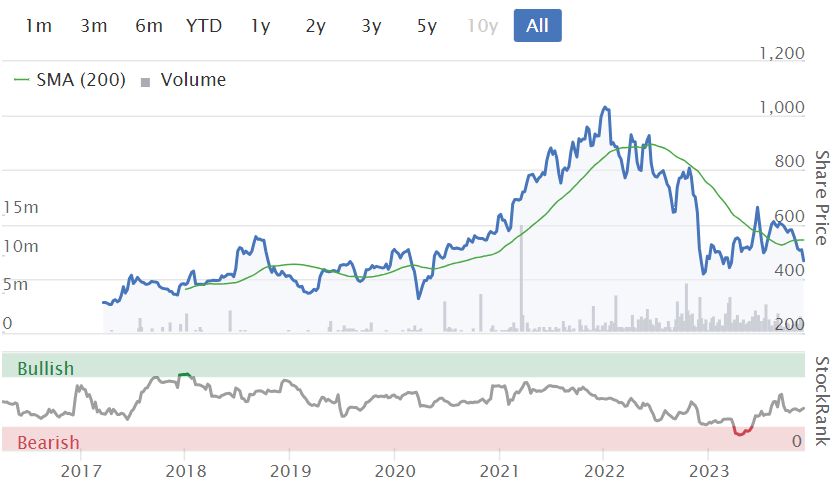
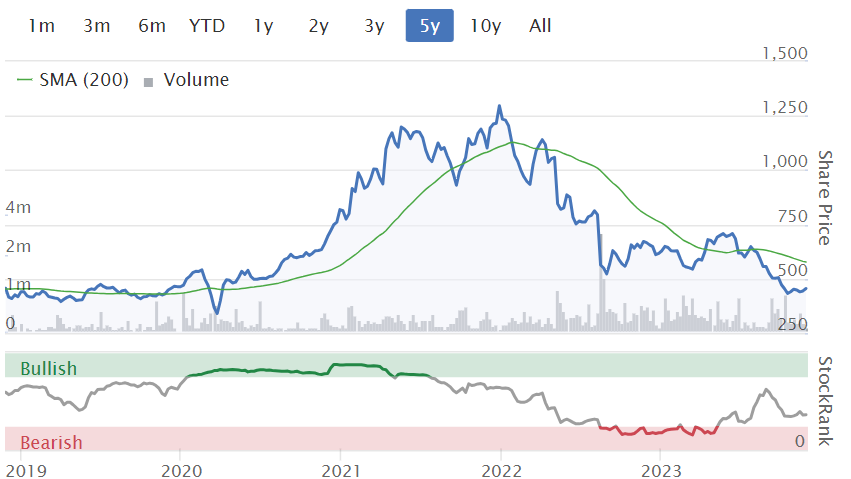
The chart shows the market has fallen out of love with Marlowe - company-specific, or just the general market malaise?
Treatt (LON:TET)
Up 1% to 456p (£275m) - FY 9/2023 Results - Paul - GREEN
Treatt, the manufacturer and supplier of a diverse and sustainable portfolio of natural extracts and ingredients for the beverage, flavour and fragrance industries, announces today its audited results for the financial year ended 30 September 2023.
Pretty good figures here -
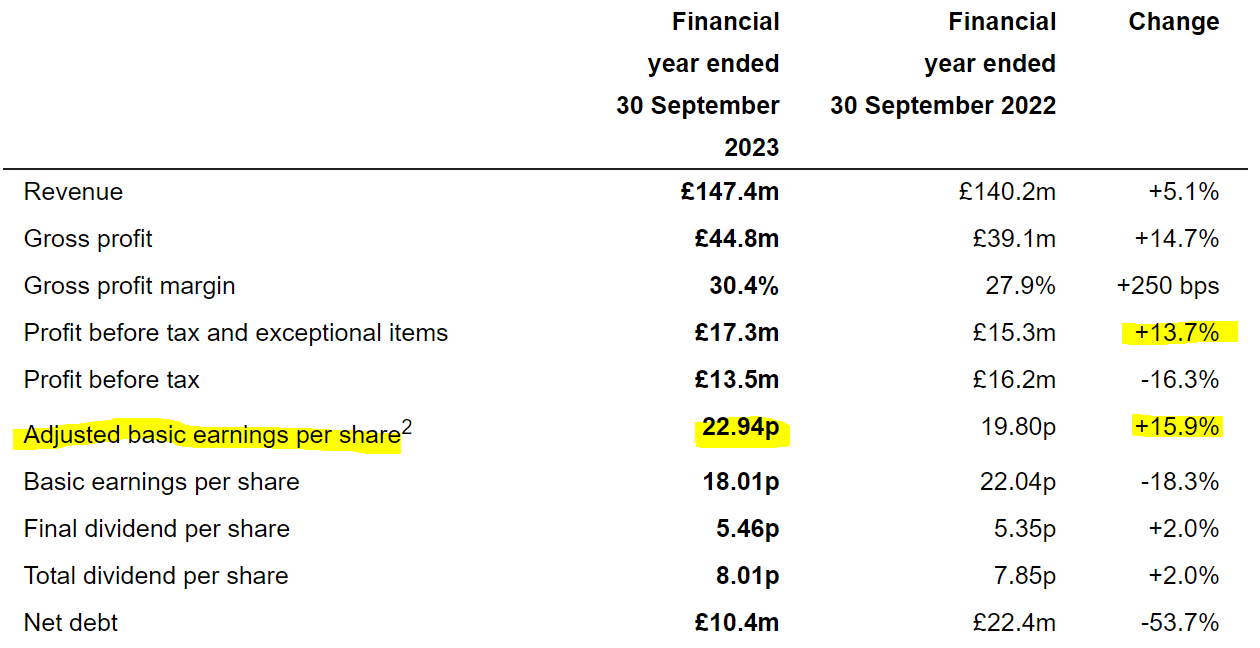
Profit is in line with management expectations, it says.
Adjustments to profit are larger this year, relating to the factory relocation & restructuring, which fair enough is a one-off.
That’s a PER of 19.9x
Dividend yield 1.8%
Net debt now modest.
Outlook - the new factory is now running, and provides a -
...strong platform to drive growth and efficiencies in the year ahead and beyond…
Having made significant investments in our infrastructure in recent years, we now have the opportunity to deliver improved operational leverage and gain further efficiencies from our modern facilities, and from our supply chain and procurement as the business continues to grow, utilising new capacity.While we remain cognisant of ongoing macroeconomic headwinds, we are confident in our strategy and in the strength of our teams and their expertise to deliver this…
Thanks to the drive and dedication of colleagues, the business is well-positioned to capitalise on its future opportunities. We have honed our cost base appropriately for the growth we expect in the next few years, and there are further operational efficiencies to be derived as volumes grow, which we expect to come from multiple categories and regions. Our core areas of expertise align with macro trends. Citrus remains a strong suit, with one in four new beverages globally based on those flavours, and we have some exciting new offerings coming to market across our portfolio. We are seeing signs of a return to growth in our largest geographical markets and are continuing to invest in China, where our burgeoning relationships and new business wins bode well for a healthy order book. By continuing to nurture what makes Treatt special, I am confident in the ability of our team to achieve our objectives for the years ahead.
Balance sheet - is excellent, very strong. NTAV is £134m. My main quibble is that inventories are way too high, at £62.4m. That compares very unfavourably with a whole year’s cost of sales of £103m on the P&L. So this balance sheet is tying up far too much in inventories, and excessive inventories can often be a lurking ground for problems. So this needs querying if anyone talks to management. Why aren’t they doing more just in time production? I would have expected inventories to be c.£20-30m tops, so £62.4m is way, way too high.
Cashflow statement - looks healthy. Note that there was a big jump in inventories last year, which has not significantly unwound this year. There’s a lot cash tied up in those inventories, so this is again my main query on the numbers. It makes sense that inventories might have been built up during the factory relocation, and during supply chain disruption, but why isn’t it now normalising?
Paul’s opinion - this story is developing nicely. I think the valuation still looks a little high, but that can be justified given the growth potential in both revenues and margins, provided by the new factory.
I’ve been following TET for years, and always complained that the share price was much too pricey for what was on offer. However, today I think risk:reward looks better than it has done for a long time. So this could be a reasonably good time to consider picking up a few of these shares, if your own research backs up my opinion.
I’ll go with GREEN this time, as things seem to be nicely lining up.
The hope is obviously that growth and margins might accelerate more than forecast, now the spangly new factory is operating.
Graham’s section:
IG Design (LON:IGR)
Share price: 150p (+2%)
Market cap: £147m ($186m)
IG Design Group plc, one of the world's leading designers, innovators and manufacturers of Gift Packaging, Celebrations, Craft & Creative Play, Stationery, Gifting and related product categories announces its unaudited results for the six months ended 30 September 2023….
We’ve been following this potential recovery story for some time, and I’m pleased to see signs that the bull thesis may be playing out. We last commented on it in October.
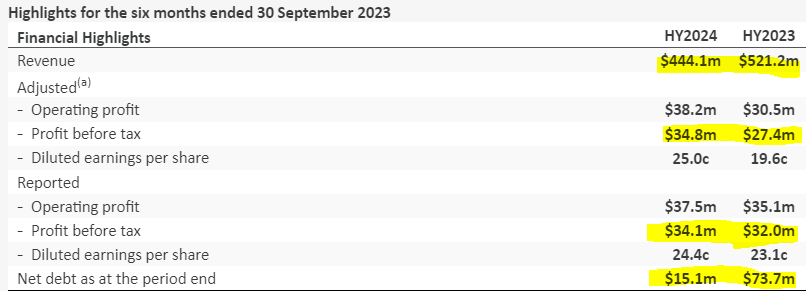
I’ve highlighted the key features above: revenues down but profits up, and there is a huge reduction in net debt.
IGR say that the profit and margin recovery in H1 has been “ahead of the Board’s expectations for the period”. However, they leave full-year profit and margins expectations unchanged.
The large fall in revenues, as previously explained, is exacerbated by the fact that last year saw H2 revenues getting pulled into H1 by supply chain concerns.
This year, a more normal H2-weighted seasonality is expected, which means that H1 is weaker.
Outlook
On top of that, there is “continued uncertainty over consumer demand, and therefore ordering by our customers, given the current economic climate”.
The orderbook is weaker, a sign that “the retail environment continues to be challenging”.
So it is understandable that despite a strong H1 result, the company is not raising full-year profit expectations.
Here’s the really good news from the outlook statement:
Cash delivery over the year is expected to be above Board expectations
Remain on track for aspiration of pre-Covid-19 operating profit margin recovery by 31 March 2025
These are the key points of the investment thesis with this stock: that the company will deleverage and that it will return to pre-Covid performance levels.
The pre-Covid operating margin at IGR did fluctuate but was somewhere in the region of 5%.
The operating margin according to today’s statements is over 8%, but the company will need to follow that up with a robust performance in the seasonally crucial H2.
The cash flow performance is also remarkable.
Last year, the company suffered a $104m outflow in H1.
This year, the company has only suffered a $66m outflow in H1, i.e. there is an improvement of nearly $40m in the H1 performance this year.
That sets it up for an excellent full-year cash performance.
Estimates
Progressive Research have made some changes to their estimates this morning, which I find puzzling as the RNS from the company states that profits and margins for the current year will be in line with Board expectations. Perhaps the analysts are catching up with the changing views of the Board?
In any case, the new estimates from Progressive suggest revenues for the current financial year (FY March 2024) of $801m (estimate lowered by 3%) and adjusted PBT of $21.5m (estimate raised by 20%).
Year-end net cash is seen at $75m (estimated raised from $60m).
Given the hoped-for improvement in profit margins, adjusted PBT is seen rising to $37m in FY March 2025.
Graham’s view
I have no reason to change my positive stance on this one, as IGR keeps moving in the right direction operationally and financially.
The share price does not agree yet:
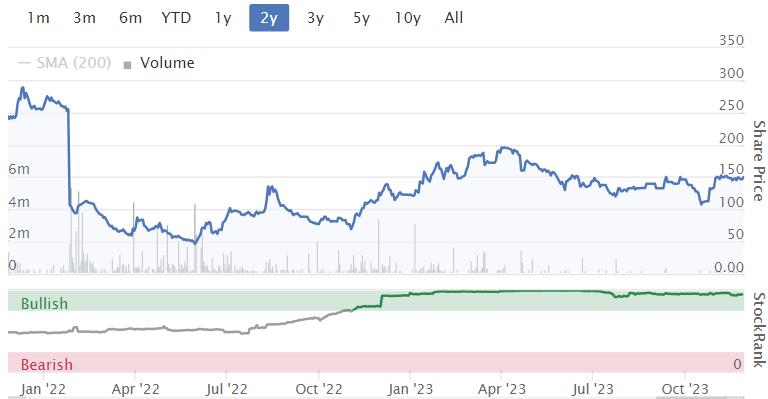
Converted to dollars, the market cap is $186m. If the company finishes the current financial year with $75m of net cash - admittedly this is a seasonal high - and if the adj. PBT estimate of $37m still seems reasonable for FY March 2025, then I see a lot of upside here.
Against that, investors need to weigh IGR’s vulnerability to consumer sentiment and economic conditions. And many of the companies we cover here can generate operating margins higher than IGR’s, so this is not a “quality” stock. But it might still be too cheap.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

92 comments
I'm going to Mello...might see some of you there.
I'm tall, grey and probably in a colourful shirt. I probably look less friendly than I am....honest
It’s “tiddlers day”today for me with my five top gainers being EnSilica (LON:ENSI) ,Crimson Tide (LON:TIDE) ,Good Energy (LON:GOOD) ,Thruvision (LON:THRU) ,Sondrel (Holdings) (LON:SND) . The total market cap of all five is under £150mm.
I put this down to some pre-Christmas spirit but it is still welcome. These micro caps are of course dangerously volatile, but it is part of stock picking to juice up returns by trying to get the risk /reward right.
Just a reminder...
MelloLondon will take place tomorrow Wednesday 29th and Thursday 30th November 2023 at the Clayton Hotel and Conference Centre in Chiswick, West London.
The full two day programme is now on the event webpage…As ever there is the usual mix of fantastic Keynote Speakers including Christopher Mills for the first time, 50 quality growth companies, Investment Trusts & Funds, Fund Managers, panel sessions and much more! To find out more information, click here: https://melloevents.com/mltickets/
The ticket options are as follows:
One day: £99 (Either Wednesday or Thursday) Stocko price £49.50
Both days: £159 also reduced to £79.50
However for all Stockopedia subscribers we offer everyone the opportunity to get half price tickets if when purchasing a ticket you apply the code; Stocko50
You will enjoy networking and meeting a lot of Stockopedia posters and friends plus lots of great speakers and interesting companies with mainly very good Stockranks
Supreme (LON:SUP)
I have just watched the H1 2024 Supreme webcast.
Although Sandy Chadha is not as eloquent as some I see him as very smart and knowing 'his' business inside out, as does CFO Suzanne Smith who has really impressed me on a couple of these webcasts now. They both lack bull and although there must be concerns over any Government ruling re rules on disposable vapes I think they are pretty clear that with adult vapers then switching to refillable vapes, where Supreme have a larger margin, I feel the risk is small. The other parts of their business seem healthy and I am happy to hold.
Also happy to invest in a company selling vapes, without which I may still have been a smoker. I gave up smoking 9 years ago after 3 months vaping.
DP Eurasia NV
https://www.londonstockexchang...
Supreme (LON:SUP) completely uninvestable for me due to peddling Vaping Products causing unimaginable harm to the young.
That's 100% your call but I can't see that it is relevant to the investment case.
I’m with Portugal
Investing in companies (owning them) is not simply about “investment case” Stats and numbers .
For some it is
For some it isn’t .
Suprene will probably always exclude a lot of fund managers etc as hard to pass their ESG guidelines .
But good company with good management in a very hot sector with good growth , just unfortunate part of that growth is just bad news for us as a society .
Supreme (LON:SUP) I decided to sell my holding. Mainly because I think the health impact of vaping isn't really known yet and I was worried about something nasty rasing it's head in the future which could bomb the price; which it couldn't recover from.
I’ve been vaping for over 10 years now, was a chronic smoker. My health has drastically improved thanks to my switch to vaping, used to struggle getting up the stairs, now ride 6 miles a day to and from work, a 40+ mile cycle on a Sunday and weight training minimum twice a week (49 y o male) Happy to hold Supreme (LON:SUP) very impressed by their budget liquids and health / wellbeing products.
I see alcohol as being much more dangerous (then vape products) it’s responsible for far more carnage to our society.
In my view this is very true. It's just that alcohol is so prevalent and pervasive that we are hardly able to stand back far enough to be able to see. ...
Yet you are happy to buy Gambling companies Portugull ?
Have you looked at Supreme (LON:SUP) history and how their products came about, the level of testing they do on every single batch, the acknowledgement that teen vaping isn’t good and how they are trying to manage this (miles ahead of the industry).
In reality vaping, like tobacco or drinking or drugs is another thing that teenagers (and adults) will do. Imagine now that you make it illegal - what happens? The black market springs up, sells outside school gates or other hangouts. But now fewer people do it but with much more severe consequence - why, because batches have no safety standards, are not tested, will almost certainly be tainted etc etc………..
So this simply isn’t as black and white, good and evil as anyone on here makes out with their moralistic judgement, whilst merrily supporting other industries accused of worse social harm.
Being very cynical, could we reasonably compare the unsold stock situation at Treatt (LON:TET) with that at Naked Wines (LON:WINE) . How much of this stock might be written off in due course?
Treatt TET the annual report today mentions inventory
'Inventory held at the year-end was GBP62.4m (2022: GBP68.4m), a decrease of GBP6.0m. This decrease was driven by a significant reduction in inventory volume, offset with higher raw material costs. One factor in the success of the business is our management of risks, such as geographic, political and climatic, to
ensure continuity of supply for our customers. Consequently, the overall level of inventory held by the Group is highly significant in cash terms.'
Nevertheless, and thanks for spotting this, the inventory valuation looks very high against revenues and looking back pre-pandemic the increase in inventory/revenue ratio is even more striking. There will be some contributing factors perhaps - diversifying supply, the very slow pace of production mentioned in the comments and responsible for low fuel input costs, the shift to new premises, destocking by end clients (which may be easing a little). But for me - and the reason I have held on despite a poor share price performance - was that I expected the massive investment in new facilities to be followed by a big pick-up in sales. This doesn't seem to have happened at all yet. I am a little concerned also that the fad for flavoured tonics and liquors may be on the wane. But at least the massive borrowings have plummeted and the US business is doing very well. It s now >40% of total sales and China was bigger then the UK last year. I think we should also note that the long-term CEO has now given up his mantle and we have a new person at the helm.
Hello All,
Trading update Thursday for £MEGP. Price action is dreadful past few months. Looks like an insti or someone selling out/down to me. Thoughts anyone?
£PHTM
Don't know why ticker hasn't worked!
No such ticker do you mean ME International (LON:MEGP) you shoukd use @ not £ now.
Similar to many shares although some have bounced in the last 2 weeks.
Try an @ before the ticker John.
ME International (LON:MEGP) and no thoughts. There has been no news so we will see what tomorrow brings.
EDIT, a couple of thoughts :-))
The H1 23 numbers in July were very good and the main driver of profits Photo Me was doing very well and I assume the increase in demand for travel etc this summer will have been a tailwind so unless something else has gone wrong I am looking forward to a positive RNS.
Also I am looking for a significant increase in the Wash Me revenue.
ME International (LON:MEGP) . I took the oppotunity of price weakness to top up yesterday. I expect their mix of small ticket sales to hold up relatively well during times of economis weakness. Thursday will reveal whether I bought the dip or caught a falling knife!
Richard
Not a small-cap, but maybe Safestore Holdings (LON:SAFE) worth a mention since it's one of the ten-baggers that Ed mentioned in his webinar?
I bought Augmentum Fintech (LON:AUGM) at 89p today after their very encouraging results.
https://www.stockopedia.com/sh...
Since IPO in 2018 AUGM has had an unbroken run of NAV increases, though the latest increase to 160p is small. Yet the share price has gone from the biggest premium of any Investment Trust at one point to a now big 41% discount! And if stripping out the £58 million cash the Discount is 51%. So while NAV has gone up consistently the share price has gone down consistently.
Note that AUGM have £58 million in cash and no debt. Their top 3 holdings, TIDE, GROVER and ZOPA and the cash are above the current AUGM market cap, with no value at all attributed to their £125 million of other investments.
So far AUGM have had 5 realisations since IPO and all were above the holding value.
They have been buying back shares to try and reduce the discount. They can’t issue new shares while AUGM is at a discount but the bought back shares will be held in treasury to potentially be reissued if AUGM goes to a premium again. NO chance of that for a good while but very good chance of the discount narrowing from current undeserved extreme level.
This is yet another example of Investment Trusts being SO out of favour with discounts at near record levels. The tide will turn at some point, and AUGM looks yet another oversold Investment Trust worth checking out.
Augmentum Fintech (LON:AUGM) I was having a look at the this on ii and it comes up with some warning documents about penalties if you exit early (this seems odd to me if I am just buying and selling at the market price on any given day). It also says there is an annual charge of 1.9%. So just to be clear - this is not an investment in the management fees part of the business but instead is an investment in their (partially closed ended - penalties attached) portfolio? If someone could clarify that would be great...many thanks in advance.
You are buying the Investment fund. Not sure what "Penaly Fees" refers to. Augmentum Fintech (LON:AUGM) is a PLC whose business is investing in Financial companies. I Hold.
MetalMaid
These warnings on ii and Hargreaves before we can buy an Investment Trust are relatively new, and very annoying and unnecessary imo. The same applies to the often useless and misleading KID documents. I never bother reading the KID documents and it has not hindered my success.
I’ve been investing in Investment Trusts (and when they existed the often big winning Investment Trust warrants and subscription shares) since the 1980s and can’t recall a single occasion when I couldn’t buy or sell immediately. An exception could be if trying to sell large stakes in one of the less liquid Trusts. A way round that is to sell in stages as long (as they are with cheap online Brokers) the dealing charges are modest. It’s much easier for us to sell large stakes than it is for Open ended Funds wanting to sell.
Another idiotic thing is that there are no such off putting warnings if we want to buy a share getting a red rating here and with the added warning from Paul that there’s a high chance that share is going bust. So why on earth these nonsense warnings for Investment Trusts?
Investment Trusts are traded exactly the same way as shares, and can be bought or sold in seconds. As with small company shares some Trusts have a too wide spread, but then it’s often possible to buy and sell well within thst spread. A lot of Trusts have very narrow spreads and note that some like City of London Investment Trust (LON:CTY) have been in existence since the 18th Century too.
NOTE!
There are NO penalties when selling. Just buy and sell the same as with shares.
When buying an Investment Trust we are buying their portfolio. Many consist almost entirely of shares, and those Trusts update NAV every day. Others like Augmentum Fintech (LON:AUGM) invest in riskier early stage and often unquoted Companies. Those Trusts don’t update NAV regularly but instead as with AUGM today, they update when issuing Results. And for unquoted Companies we do have to take more on Trust about accurate NAV. But AUGM have an impressive record of realisations well above the price they paid for them. That’s one of the reasons, along with the very positive update today, along with big discount to NAV, that I bought and posted on AUGM today.
As for charges. They vary from Trust to Trust. I use AIC website (AIC is the official trade body for Investment Trusts) and never the likes of ii for accurate info on charges. Ii are sometimes confusing or wrong or both!
Clearly the lower the charges the better but unless charges are extortionate I don’t factor them in to my investment buy or not decision.
The charges are just taken out of the share price so we don’t notice them. It’s not much different to shares where Director bonus pay or loads of new shares awarded if reaching easy performance targets are reached, or even £millions when dismissal for incompetence happens. Those too afaiaa just come out of the share price as do the often more transparent Investment Trust charges.
A key point with Augmentum Fintech (LON:AUGM) is that while the share price has fallen from nearly £1.70 to 92p today, all the while NAV was rising while the share price was falling, and NAV performance has been impressive.
It might take time, but surely in time AUGM and many other oversold Investment Trusts now trading on exceptionally high (and even the highest ever) discounts to NAV will eventually recover strongly.
Hope that answers your questions.
Many thanks Ken for your detailed and considered response. I have had little experience with investment trusts - this has certainly helped my understanding. I think the document I read must have been a general one for investment trusts, ii can be rather confusing at times. Especially when I looked up a couple of others - it had no warnings at all for Frontier IP, and no annual fees shown. When I looked up Vietnam Holding it said I would have to fill out an additional form as it regarded it as a 'complex investment'. Not sure why they have to make it so convoluted, probably a lot of box ticking for the regulator. Many thanks again Ken,
cheers
Matt
Thanks Matt.
VietNam Holding (LON:VNH) is not a complex investment. It’s a standard Investment Trust investing in a portfolio of Vietnam shares. And it has a great long term record too. I’ve held both VietNam Holding (LON:VNH) and VinaCapital Vietnam Opportunity Fund (LON:VOF) for most of this Century and both have been very successful investments.
It’s SO annoying that the likes of ii are complicating such straightforward Investment Trusts as it’s a disincentive to invest in them. Well worth checking them out on aic here:-
https://www.theaic.co.uk/aic/f...
Just click on the red Trust headings for loads of info, including portfolio, announcements etc
Both update every month with excellent factsheets.
I was intrigued by the suggestion of warnings for Investment Trusts. I just pulled up a quote on HL for Merchants Trust (LON:MRCH) and no warning box came up?
I would guess that HL have warnings for some ITs which they consider iliquid . This might be a good idea as a final check for some investors?
HL have a platform fee of 0.45 %. As far a s I am aware it is uniform irrespective of the type of investment held. Yes - its a bit steep.
Lots of basic stuff ii find complex. Take reporting no price change on my Home Reit (LON:HOME) holding, and only 10 alerts per user for starters. Can't understand why they threw out all the useful dealing/stops tools from the Share.com take-over.
It is uniform but there is a very low cap on fees in ISA (£45pa) for shares/ITs/ETFs. HL sting you on OEICs etc. where there is no cap. Non-ISA there's no holding charge at all for shares/ITs/ETFs
Ok - I must have checked the SIPP by accident. Cheers
I too hold Augmentum Fintech (LON:AUGM) across number of accounts and like the discount currently - getting in at this price should give a double uplift in the future as the discount closes and the NAV continues to increase - assuming it does???
Talking of ridiculous warnings HL refused to allow me to trade in my wife's ISA today when trying to buy Rockwood Strategic (LON:RKW) unless I went into her account directly and filled in the paperwork declaring I/she is a sophisticated investor.......what a load of rubbish. I have loads more holdings that are far more complex/risky than this. Pointless BS. They never gave anyone a warning that invested in Woodfords fund that they were investing in highly-illiquid unlisted securities and were likely to lose a lot of money!!!!
The consolidation of investment trusts continues. I've never seen this level of activity; its quite unprecedented. Merge or die seems to be the mantra!
Today its a merger of the two Troy trusts, both of which I hold: Sts Global Income & Growth Trust (LON:STS) with Troy Income & Growth Trust (LON:TIGT) with a possible 100% cash exit. Both are good trusts, but stronger together! I will take the shares not the cash exit as Troy are a very good manager.
Also today Fidelity are taking over a struggling abrdn China trust. Again, I hold both and Fidelity China Special Situations (LON:FCSS) is the standout China trust which is gobbling up the relatively poor abrdn China Investment (LON:ACIC). Tempted to take the 33% cash exit on the small residual position I have in the abrdn trust which I had mostly sold down.
In small-caps, about a week ago Jpmorgan UK Smaller Companies Investment Trust (LON:JMI) announced a merger with JPMorgan Mid Cap Investment Trust (LON:JMF) - to double the size of their small and mid-cap proposition as they are managed by the same person. I hold both of these as well, but will continue to hold.
None of this is showing that the LSE is in good health.
Abrdn (LON:ABDN) trusts are disappearing at a frantic rate!
Re Abrdn
The head of Investment Trusts is leaving and the stated policy is that of consolidation. They are also closing its IT savings plans. All a bit negative in my view.
Strategic review seems to be the favourite phrase in Investment Trust land! Three of my IT holdings seem to be in that camp with abrdn European Logistics Income (LON:ASLI) and Digital 9 Infrastructure (LON:DGI9) the latest. As you say Abrdn seem to be getting out of ITs as a corporate strategy. Digital 9 Infrastructure (LON:DGI9) announced sale of holding in Verne data centre for $575m and share price fell by 9% today. Yesterday abrdn European Logistics Income (LON:ASLI) put the whole lot up for sale and share price went up c.7%. The third reprobate is the still suspended Asian Energy Impact Trust which looks likely to return to the market at a much reduced valuation. All were IPOs in the last 5/6 in sectors which should be attractive propositions. Never again will I participate in an Investment Trust IPO!! Risky small caps might have been a better bet though come to think of it…
On the back of Supreme (LON:SUP) numbers earlier, just a reminder that we are hosting at 2pm today an Investor Presentation and Q&A with the CEO and CFO - you can register here: https://www.equitydevelopment....
I'm really impressed with IG Design (LON:IGR) interims this morning.
The progress on net debt, the improving margins/profits on a lower revenue base- a very smooth turnaround so far since Paul Bal took the reigns.
Is it now starting to look quite cheap? The clean numbers (statutory) look a decent uptick from interims last year when you exclude a couple of non recurring items and presumably the finance expenses will be much reduced going forward? A lot of the hard work now appears to have been done
Any thoughts?
I agree with you. I got lucky and bought end of 2022 when price was lower but was a far riskier investment. New management have done a great job so far but i think the market remains sceptical for now and is focussing on the revenue miss. I'm going to continue to hold and see how it pans out but surely it will re-rate in the future if they can carry on moving towards their target of "Remain on track for aspiration of pre-Covid-19 operating profit margin recovery by 31 March 2025". Thats not too far away.
I see Singers have a price target of 235p and Canaccord a target of 275p so they're believers.
Crucial Xmas trading to come. One more decent update and the market will start believing?
I think I agree with you. I used to own this and did quite well so I might try and watch the presentation. US Christmas is I believe key but so far macro US retail still doing well according to recent reports - much better than the UK. This is the presentation link
https://www.thedesigngroup.com...
Paul H talks to Supreme (LON:SUP) CEO and CFO
Why does the SCVR not appear, at the top of all discussions anymore, even if it is the latest post?
Is it something you did as I cannot see a problem.
Supreme (LON:SUP) - "Strong H1 results raise full year outlook" (new research report here: https://www.equitydevelopment....)
The H1 outcome was as indicated in the recent (18 October) Trading Update. Group guidance for the full year is now raised: from revenue of £195m - 205m to £210m - £220m (ED estimate was £204.2m); (adj.) EBITDA from £28m - £30m to £32m - £35m (ED estimate was £29.0m). From incremental EBITDA of c.£4.5m, c.£1.5m arises from core operations and c.£3.5m from the Elf distribution agreement, which supplies retailers including Tesco, Morrisons, One Stop and WHSmith.
A series of initiatives – branding and pod vape developments in particular – mean that the Group can demonstrate a realistic strategy for the potential changes in the vaping market. Supreme also reports completion of its supply and distribution centre (the ‘Ark’), noting its capacity to support both organic growth and potential M&A opportunities, with £35.3m of borrowing facilities available.
Following the Group’s increased FY24 guidance (revenue raised 7%, and (adj.) EBITDA by 14% -17%), we have raised our outlook to revenue of £221.2m, +8%, and (adj.) EBITDA of £33.5m, +16%. We expect a FY24 total dividend of c.£5.1m, with £1.7m paid at the Interim. Our Fair Value is raised to 225p/share.
Suprene
There’s a whole lot of vaping going on.
Not investable for me
Moral compass question and the growth in vaping is not something to support especially with the huge amount of vaping in schools as any parent of teenagers knows all too well .
Can try and hide behind the “helping smoking quit” argument but that’s way overshadowed by the getting teenagers hooked growth story .
Anyway I guess it’s a binary decision.
Growth market gives growth .
Think people have a moral compass when it suits them Planetx.
oil, tobacco, alcohol, gambling, drug companies blah blah. That before we get into the threat some IT companies generate etc. They’ve all generated more harm than vaping but I guess this a moral bandwagon some investors want to jump on if it’s closer to home. I suppose you’d prefer a black market for vaping where products are tainted (rather than fully tested)? I’m sure that would assuage your conscience.
These things just aren’t binary I’m afraid.
Supreme (LON:SUP) have consistently asked for regulated markets, have done a whole load of measures voluntarily like changing packaging and flavours etc and had started some of the measures way before this little villager and pitchforks crusade. They are materially ahead of the industry and government for that matter in trying to restrict use.
If you set aside the vaping the company is generating lots of profits from lighting, sports nutrition and batteries. The former two generating greater %age growth than vaping interestingly.
Anyway just a different point of view
Isn't the issue more about the environmental damage done by single use disposable vapes that Supreme sells, rather than reusable ones? I agree with Supreme that a responsible government would step in to lay down the ground rules and to enforce them - that's what's missing. (Otherwise if Supreme moved entirely to reusable vapes, others would step in to fill the vacuum left behind.)
A responsible government might consider a ban on vaping apart from for those trying to give up cigarettes?
Some countries already ban vaping but I think that is more to do with tax revenue than anything. I thought vaping was a good thing as got some people off smoking but now I have gone right off it.
I retired as an education worker a couple of years ago and vaping was the biggest health and discpline issue we had to deal with. I cannot invest in Supreme (LON:SUP) as I've seen too many young people get hooked on vapes....
I retired as an education worker a couple of years ago and vaping was the biggest health and discpline issue we had to deal with. I cannot invest in Supreme (LON:SUP) as I've seen too many young people get hooked on vapes....
And if they didn't get hooked on vapes, what would they get hooked on instead? The problem is lack of education and self control, not their addiction product of choice. This is a behavioural problem. I agree they should be banned but absolving all responsibility from the individual is wrong. I'm getting tired of this blame culture. Those who get addicted to anything should look in the mirror, get help and stop whingeing. The parents need to bear a large part of the responsibility.
Suprene
There’s a whole lot of vaping going on.
Not investable for me
Moral compass question and the growth in vaping is not something to support especially with the huge amount of vaping in schools as any parent of teenagers knows all too well .
Can try and hide behind the “helping smoking quit” argument but that’s way overshadowed by the getting teenagers hooked growth story .
Anyway I guess it’s a binary decision.
Growth market gives growth .
Hope everyone enjoys Mello - as seems to be usual for me I am abroad for it again!!!!! Really wanted to makE it this year too!!
Anyway would be very interested in peoples thoughts from the Journeo (LON:JNEO) meeting if anyone cares to post for me. Thank you in advance.
Apologies for correcting Paul but do not want readers to buy a ticket for Wednesday if wanting to see Journeo in particular. They are there all day on the Thursday and doing at least two presentations but may be able to do a third if very popular and rooms full
28 November 2023
Journeo plc
("Journeo, the "Company" or the "Group")
MelloLondon Investor Conference
Journeo plc (AIM: JNEO), a leading provider of information systems and technical services to transport operators and local authorities, is pleased to announce that the Company will be presenting and exhibiting at the MelloLondon investor conference on Thursday 30(th) November 2023, to be held at the Clayton Hotel Chiswick, Chiswick High Road, London, W4 5RY.
Russ Singleton, CEO and Nick Lowe, CFO will give two presentations, one at 11.00 a.m. and another at 2.55 p.m. each followed by a Q&A session for attendees. The Company will also be hosting a stand to meet investors.
For further information and tickets (use code SHML60 for 60% off ticket price) for the MelloLondon conference, please visit the event website at https://melloevents.com/mltick... .
Journeo (LON:JNEO) another set of superb results. I was expecting them to be ahead to be fair but a bit better than my elevated expectations.
In answer to Paul’s question they had around £6m net cash (not upfront payments) from memory.
This business now it is growing globally feels like it has the hallmarks of a multi bagger. It’s still on a very low multiple and can easily double again from here in my view. Patience will be required but very happy to hold this well run business now becoming a credible global player.
Journeo thankfully good, could be very good. Any views Davidjhill on WISE and YU.?
I liked Yu (LON:YU.) a lot at 365p Alison but failed to convince myself to buy (idiot - me!). I also liked Good Energy (LON:GOOD) in same vein at 230p and missed that one as well…..doh! I think with both of these my fundamental scepticism of sustainability of business model kept my finger away from any buy buttons. Short term definitely wrong but I still haven’t quite managed to convince myself there isn’t a fall coming. Don’t want to get involved on a FOMO move either. Not much help there I’m afraid.
On Wise (LON:WISE) I’m a bit ‘meh’ as well - think there is better stuff out there personally
Altitude (LON:ALT) more growth (a lot!), less cash...I wonder if a 'growth raise' is on the cards? Near all of the growth comes from low margin more working capital intense/negative 'merchanting' (ie being a facilitator between end users and suppliers of promotional gear)....but the valuation implies higher margin software services (growing much more modestly and maybe cash consumptive given on going capitalisation of development spend)...
...this stock always seems to be going somewhere...but never quite arriving?
To be fair Mojo they did have a number of launches in the last period so that has had an effect. They do need to start demonstrating cash conversion though I agree.
Altitude (LON:ALT) (I Hold)
Two statistics that stand out for me are a 10% forecast div (from 0%) and a PEG of 0.5.
If that dividend is to be paid it will require about another £3,000,000 of cash. Based on the growth currently forecast that should be do-able, just, maybe - particularly if they can reduce inventory from the current £1M to the March 23 year end's £361K. If they do achieve it then point proven and a major re-rating is on the cards.
What I actually expect is a position about half way there, which would bode well for future growth but not blow the doors off.
I might have missed it...or maybe I need some of your smokes...but I don't see where Altitude (LON:ALT) are forecasting a near 10% dividend payout fy24 (on current sp)? Given their cash and investment dynamics (be that working capital or intangibles) plus sales 'investment' to grow both sides of business (its not magic...and they don't exactly have a lot of presence) I don't see it as feasible they can pay out cash...in fact, I stick to the view that a 'growth raise' is a possibility
They will not even generate 500K pa until FY26!
They will not be paying a dividend , never mind a 10% one.
#IGR IG Design Group H1 webinar at 1.30 today. Register here. Outlook: FY profits and margins in line. Cash at year end expected ahead of expectations.
Saga (LON:SAGA) CEO Euan Sutherland leaves. He tends not to stay anywhere long: AS Watson 4 yrs, Kingfisher (LON:KGF) 5, CoOp 1, Superdry (LON:SDRY) 5, and now 4 at Saga. TSR at SAGA about -84% during his tenure!
Saga (LON:SAGA) Yes, not a"lucky general" as Napoleon would have said! Looks like he's be fired to me.
Saga (LON:SAGA) - and another example of the need to DYOR - How can Stocko give this share a score of 80 - crazy, but thats algorithms for you
Hi all, ive been listening to Pauls podcast now for some time - how do we identify the mystery shares each week? Looking through the past SCVR i can only see one mention of a mystery share I think in 19th nov. Thanks
Paul will either point to them in the podcast ie. Tuesdays first commentary by Paul. Or he will update the SCVR for the day and/or the Friday/Monday one and state which Co. it is.
I don't think there were any this week, which isn't uncommon.
You could use simple mathematics:
Contents of daily small cap report - Companies mentioned in podcast = mystery share.
True but that only works if i go back and listen to every podcast again as i didnt take a note of which day the mystery share was or the other ones he discussed :)
I take it that the mystery shares are the ones Paul is most keen on (like a 'double green') so it makes sense for me to check and research those first.
Perhaps it's possible for Paul to flag them on the spreadsheet?
I suggest a different colour, on the spreadsheet, for mystery shares.
I would suggest he is unemployable but no doubt he will pop up somewhere.
Apart from what has already been answered about the podcast mystery shares I think the most likely indicator is that a share is green. It's about highlighting the best stocks to the paying members I believe.
Good Energy (LON:GOOD) ahead of expectations, with forecast full year PBT at £4m versus £2.5m previous.
Renew Holdings (LON:RNWH) - Good final results with +ve outlook although ,margins have slipped a bit and they weren't that high to begin with
Financial Highlights
Year ended 30 September 2023 FY2023 FY2022 Change Group revenue(1) GBP960.9m GBP849.0m +13.2% ---------- ---------- ------- Adjusted operating profit(1) GBP63.6m GBP58.8m +8.2% ---------- ---------- ------- Operating profit GBP59.0m GBP50.0m +18.0% ---------- ---------- ------- Adjusted operating margin(1) 6.6% 6.9% -31bps ---------- ---------- ------- Profit before tax GBP58.1m GBP49.5m +17.4% ---------- ---------- ------- Adjusted earnings per share(1) 63.5p 59.5p +6.7% ---------- ---------- ------- Full year dividend 18.0p 17.0p +5.8%Fantastic results from Supreme (LON:SUP) this morning. The magic "significantly ahead" words in the outlook as well.
Like or loath (I hold) the owner is a smart dude !
Good Energy (LON:GOOD) ahead:
"Following a strong first half of the year, the Company's trading to the end of October has been ahead of expectations. If seasonal normal weather and stable commodity market conditions continue for the remainder of the year, Good Energy expects to deliver earnings ahead of the Board's expectations for the full year seeing a profit before tax of at least GBP4m."
StockRank 99, mkt cap £57m
Good Energy (LON:GOOD) was included in the 12 oversold/bargain shares I posted about at 306p on Friday, and at lower prices previously. . Good to see a better than expected update today and share up 20p just now to 360p. So many bargains to choose from that we’re spoilt for choice. Perhaps the best of the GOOD gains have been had for now after the fast run up from about 180p, but well worth monitoring for a buy the dip opportunity.
I agree. As a holder of Good Energy (LON:GOOD) it was great to hear today’s ‘ahead of expectations’ trading update.
Mild weather and stable energy prices were given as the key drivers. It would be good to understand how different commodity price levels affect profitability, ideally for me, in a similar format to how some oil and gas companies project estimates of how oil prices affect profits and dividends. This would give investors better insight into risk and return.
On the other hand, the Government’s £7,500 grants for heat pumps brings the cost of heat pumps more in line with the cost of traditional gas boiler replacement. From personal experience I know Octopus has a 3 to 4 month waiting list for a heat pump survey (that’s after customer screening) and another 6 month waiting for installation.
It would be helpful to understand how Good Energy (LON:GOOD) new heat pump installation business is developing and what its contribution to profitability will look like this year and going forward.
With a rock solid balance sheet I think Good Energy (LON:GOOD) offers great potential for stock pickers looking for returns from the UK’s green transition (that we all appear to be subsidising
My morning smallcap tweet: Wading through the overflow of announcements
Journeo (LON:JNEO) Crossword Cybersecurity (LON:CCS) Clean Power Hydrogen (LON:CPH2) Good Energy (LON:GOOD) Atome Energy (LON:ATOM) Fusion Antibodies (LON:FAB) Crimson Tide (LON:TIDE) Home Reit (LON:HOME) Sopheon (LON:SPE) Augmentum Fintech (LON:AUGM) VP (LON:VP.) Topps Tiles (LON:TPT) Supreme (LON:SUP), EnSilica (LON:ENSI), DP Eurasia NV (LON:DPEU), IG Design (LON:IGR), Kinovo (LON:KINO), Brickability (LON:BRCK), Focusrite (LON:TUNE)
◄Journeo (JNEO)► guides FY-Dec rev c.£46m, ahead of market expectations due to strong Fleet Operator Systems and Passenger Information Systems businesses. Expects adj pretax £3.9m, ahead of exp. [SP=217 Cap=36m]
◄Crossword Cybersecurity (CCS)► warns FY-Dec rev £4.1-£4.3, cf £6m guided. Blames delayed contracts. Pretax loss broadly in line due to cost control. Cuts FY24 rev guidance to £7m from £8m. [SP=9.67 Cap=9m]
◄Clean Power Hydrogen (CPH2)► terminates contract with ATOME Energy for a single 1MW MFE220 electrolyser placed in March 2022. Co to focus "its engineering and installation resources in ensuring roll out MFEs with current partners Fabrum Solutions Limited, KCA Deutag and their longstanding customer, Northern Ireland Water". [SP=13.47 Cap=36m]
◄Good Energy (GOOD)► guides FY-Dec pretax £4m+, ahead of mgmt exp due to strong trading. [SP=342 Cap=58m]
◄ATOME Energy (ATOM)► see CPH2 news. "The former mobility project is now seen as a diversion from ATOME's core focus on delivering industrial scale green fertiliser." [SP=74.8 Cap=30m]
◄Fusion Antibodies (FAB)► collaboration agreement with the National Cancer Institute for the use of OptiMAL in the discovery of novel antibodies against targets. [SP=3.4 Cap=2m]
◄Crimson Tide (TIDE)► guides FY-Dec rev in line but EBITDA £0.4m+ significantly ahead of mgmt expectation. Pretax loss £0.7m. Market exp is rev £6.2m and adj EBITDA £0.2m. [SP=142 Cap=9m]
◄Home REIT (HOME)► agreement with Eden Safe for the surrender of its leases on 38 properties. HOME has had no rent since Oct 22. [SP=38.05 Cap=301m]
◄Sopheon (SPE)► PUSU deadline extended to 26 Dec. [SP=893 Cap=95m]
◄Augmentum Fintech (AUGM)► H1-Sept NAV/sh after performance fee up 0.8% to 160.2p over the half. Chmn whines that the "share price does not reflect the tangible value creation we have seen across our top 10 investments and their potential for further growth." [SP=84.53 Cap=144m]
◄Vp (VP.)► H1-Sep. Guides FY broadly in line with market expectations. [SP=649.55 Cap=261m]
◄Topps Tiles (TPT)► FY-Sep. Outlook - "Softer build into the seasonal peak trading period. Sales down 3% in first eight weeks and Topps Tiles LFL down 6.1%. Strong growth continuing in Pro Tiler Tools. [SP=46.02 Cap=90m]
◄Supreme (SUP)► H1-Sep. Hikes FY rev guidance to £210 - 225m (previously guided £195 - 205m) and adj EBITDA c.£32 - 35m, £4.5m ahead of guidance. [SP=110 Cap=129m]
In line: ENSI, DPEU, IGR, KINO, BRCK, TUNE
Supreme (LON:SUP) has supreme numbers, fasten your seat belts, plus huge upgrades again for the full year:
· Revenue growth of 63% to £105.1 million (H1 2023: 64.6 million)
· Adjusted EBITDA up 88% to £15.2 million (H1 2023: £8.1 million)
· Pre-tax profit up 179% to £12.3 million (H1 2023: £4.4 million)
· Adjusted net debt (i.e. excluding IFRS 16 leases)4 of £4.8 million (H1 2023: £12.9 million), representing less than 0.2x adjusted LTM EBITDA, with unutilised borrowing facilities of £35 million
· Interim dividend of 1.5 pence per share declared (H1 2023: 0.8 pence)
Supreme (LON:SUP) - very strong results this morning with profit guidance for the full year lifted by about 15%. The numbers were boosted by the Elfbar distribution agreement but also have strong organic growth:
Its way to cheap once all the hot air departs this will motor on, cigarettes are a dead duck, SUP are leading the way politically, you can imagine the CEO assisting Gov policy (I hold)
Journeo (LON:JNEO) has an 'ahead of expectations' trading statement this morning. A note out from Cavendish lifts profit forecasts by 5% this year and 4% next and moves PT from 338 to 385p.
Journeo (LON:JNEO) is also currently appearing on the Jim Slater Zulu Principle Screen
It has been on there a while I think. It is also on the CANSLIM guru screen. These 2 are among the best performing UK guru screens.
VP (LON:VP.) - Delivering growth in uncertain markets (new research report here: https://www.equitydevelopment....)
Vp’s interims confirm another solid performance and continued growth despite the challenging backdrop. Revenue increased by 2.4% to £190.9m and adjusted PBT by 1.9% to £21.9m. This is >50% of our full year forecast (trimmed by c.4% to bring us in line with consensus).
Infrastructure demand has driven a positive H1 performance for Vp’s Groundforce, Torrent and TPA businesses. Vp’s experience is consistent with the latest construction industry data, which showsinfrastructure demand offsetting weakness in general construction and housebuilding. Vp is well positioned to benefit when these softer markets return to growth.
The period was notable for the change in leadership with Anna Bielby succeeding Neil Stothard as Group Chief Executive. Keith Winstanley has been appointed Group CFO and joins the Group in January 2024. We expect the refreshed management team to build on the Group’s strong foundations, with Digital innovation and ESG commitment at the forefront of Group strategy.
Following recent share price moves, Vp still trades at a marked discount to its immediate peers and its historic average rating. Over the long term, Vp has traded on a P/E rating of c.12x and the valuation at today’s share price represents a 30% discount to this level. We maintain our Fair Value estimate of £10.90 per share.
Quick look at easyJet (LON:EZJ) and they look regat to me, (probably missing something)
One for my SIPP
Headlines:
Record H2'23 financial performance with a positive outlook for FY24
· Record H2 profit before tax despite challenging external operating environment
- FY23 headline profit before tax of £455 million (£633 million year on year improvement)
- easyJet holidays profits grew 221%, delivering £122 million profit before tax
· Positive outlook for FY24
- October RPS +12% (Q1 RPS expected to be ahead YoY despite being impacted by Middle East conflict)
- Q2 to Q4 RPS all ahead YoY
- H1 CPS ex fuel to be broadly flat YoY
- easyJet holidays expected to grow >35% in FY24 with ASP up high single digits
· Remain on track to deliver disciplined growth of c.9% in FY24
- H1'24 c. 42m seats, +11% YoY
- H2'24 c. 59m seats, +8% YoY
· Financial strength
- £41 million net cash with £4.7 billion liquidity
- BBB/Baa3 credit ratings, both with positive outlook
· Dividends reinstated
- 4.5p per share payable in early 2024
- Expect pay out to increase to 20% of headline PAT on FY24's result
- Potential to increase level of future returns to be assessed over the coming years
Apart from this bit..
Easy Jet
Numbers are all good. It is the geopolitics that troubles them. The war in Middle East (flights to Egypt, Jordan and Israel) has been suspended. Fear of future terrorist attacks in in their mind too which easily affects the sentiment of travelling. This will impact next year numbers significantly. This maybe a high risk high reward share for me.
There will always be something in travel.
Thy can move capacity round pretty easily to support strong routes
Travelers have the memory of a goldfish. When then ME conflict drops out of the news cycle, demand will rebound quickly. Maybe not to Israel, Jordan, Egypt.... but definitely the European destinations where Travelers have held off, given news of protests and anti-Semitism.