Small Cap Value Report - Tuesday 11 October 2022 - BKS, IGP, IOM, QUIZ, RCH, SUR

Good morning from Paul & Graham!
Today's report is now finished, as we've covered 6 companies, and don't want to overwhelm you. However, we've not forgotten about several other items, which we'll cover tomorrow.
Agenda
Paul's Section:
Beeks Financial Cloud (LON:BKS) (I hold) - written up last night, I review the contract wins announcement (helpful but not massive), and more importantly, the FY 6/2022 results. This share is all about very rapid organic growth (revenues up 57%), mostly recurring. It's modestly profitable, but share option costs consume most of the underlying profits. Balance sheet is strong, after a £15m fundraise in April 2022. Outlook comments confirm confidence in achieving FY 6/2023 market expectations, although additional growth beyond that might take time to nail the contracts. Overall, I like it a lot for the potential, and think that the current valuation seems about right.
Intercede (LON:IGP) - also from yesterday, there's an interesting acquisition - a tiny business called Authlogics, which is said to have specialist IP which will enable IGP to increase its addressable market by tenfold, filling a gap in the product suite. Sounds very interesting! Also there's a positive-sounding trading update, with H1 in line with mgt exps, but well over half the full year forecast revenues are now in the bag, so looks like a beat against forecasts could be in the pipeline for FY 3/2023. Cash has continued rising, hitting £10m. All looks most encouraging. [I don't hold this share any more, by the way, but am keeping it on my watch list as something I'd like to return to].
Quiz (LON:QUIZ) - a smashing trading update from yesterday. This share looks incredibly cheap, largely backed by net cash, and trading encouragingly well, with its multi-channel glamorous but cheap product offering, which achieves high gross margins. Online is growing nicely, in fact all channels are, but growth has slowed in recent months, as I would expect. Broker forecasts have been raised several times. The shares look stunningly cheap to me, pity I wasn't able to hang on to mine. They tend to drift back down gradually, after spikes up in price, so probably no immediate rush to buy back in.
Graham's Section:
iomart (LON:IOM) (£161m) - a profit warning here as the current financial year is likely to come in “at the lower end of the Board’s original expectations”. A cloud computing and IT managed services provider, this business has seen some good revenue growth over the years, and expects revenue growth in H2. The difficulty is with margins and profitability: they don’t seem to keep up with revenue growth. I believe this reflects the nature of the business: high labour intensity and limited pricing power. However, I’m no longer bearish on the stock as it has been drifting lower for five years and, I believe, reached a point where profitability and cash generation can start to support it.
Reach (LON:RCH) (£240m) - this share has been an unpleasant rollercoaster for investors and the news today isn’t great: revenue trends in Q3 are only “broadly as anticipated”. The underlying revenue trend is a slow decline: excluding September, Q3’s trend was minus 0.5%. The company appears highly profitable but the market seems to think that by 2027, there won’t be much left of value. 2027 is the year when the very large payments to the company’s pension scheme are currently scheduled to cease. The UK 10-year yield is currently almost 4.5%, versus just 1.1% a year ago, i.e. the pension scheme should be able to generate much higher returns now than it did previously. So I’m wondering if we might get some good news from this scheme in the years ahead, assuming that they survive the drawdown in asset values?
Sureserve (LON:SUR) (£128m) (-4%) [no section below] - this is a “Social Housing Energy Services Group”, formerly known as Lakehouse. Today it reports that FY September 2022 is in line with expectations, on the back of “solid operational performance”. The order book is up 16% year-on-year to £585m, and the company reports a net cash balance of £23m. Two of its subsidiaries are currently up for sale. This one gets a huge StockRank of 93, i.e. it’s a Super Stock, and it also passes two bullish screens. The operating margin is 5% - 6%, reflecting that it’s a contractor that provides building services. I am open to listening to any arguments as to why this particular contractor will have an advantage in this highly competitive, low-margin, accident-prone sector. [no section below]
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul’s Section:
Beeks Financial Cloud (LON:BKS) (I hold)
148p (down 5% at 09:33)
Market cap £96m
There were two announcements yesterday, firstly -
Beeks Financial Cloud Group plc (AIM: BKS), a cloud computing and connectivity provider for financial markets, is pleased to announce the signing of two multi-year Private Cloud contracts with global Asset Management firms. The contracts, worth c.$2 million in aggregate over three years, were secured via a partner for deployments across US, APAC and EMEA.
Quite small contracts on an annual basis, but nice to have -
The contracts help to further underpin the Group's FY23 expectations.
It’s a June year end, so the current year is FY 6/2023.
The CEO sounds upbeat about the outlook -
"We continue to see positive sales momentum across our range of cloud computing offerings and are delighted that our partnerships go from strength to strength, supporting our direct sales activities. A substantial pipeline continues to build across our Private Cloud, Proximity Cloud and Exchange Cloud offerings, and we are confident in our ability to further increase our market share of the growing cloud computing market."
Moving on to the more important announcement -
Beeks Financial Cloud Group plc (AIM: BKS), a cloud computing and connectivity provider for financial markets, is pleased to announce its final results for the year ended 30 June 2022.
Revenues up 57% to £18.3m
Annualised recurring revenues hit £19.3m at year end (+40% on LY) - a useful metric, which effectively gives us the base line for next year (FY 6/2023) revenues, before any new contract wins. Hence the broker forecast (Progressive) for £24.5m revenues (+34% forecast growth) in FY 6/2023 doesn’t look demanding, given the remarkable growth rate last year of +57%, and £19.3m of it is already in the bag from recurring revenues.
Underlying EBITDA is up 52% to £6.3m, but to my mind, this is not a useful measure, given that capex has been heavy, so we can’t just ignore capex and depreciation (£3.2m).
Underlying PBT is up 28% to £2.06m, but statutory PBT is much lower, at £0.66m in the commentary, but only £66k further down in a reconciliation. So it looks like the £0.66m could be a typo, and should say £0.066m? The main difference is the £1.66m share based payments, which consumes 81% of the underlying profit. Hmmmm.
Balance sheet - has been transformed for the better with a £15m fundraise (at 165p per share) in April 2022. NAV is very sound now, at £30.8m, less intangibles of £6.7m = NTAV £24.1m, which is plenty for the size of company. Although it does need sound finances, as the business model involves up-front capex, to drive expansion in revenues.
Net cash is fine, at £7.9m.
I was a bit concerned that physical capex of £9.6m (source: cashflow statement) looked heavy, but note 10 shows this included a £3.0m freehold property purchase, and £2.0m addition to leasehold assets (right of use assets). Excluding these as one-offs and discretionary investments, then what I would see as regular capex (mainly computer equipment) was £5.2m - that’s OK I think.
Intangibles - £2.6m of internal development costs were capitalised, partly offset by £0.4m of grant funding received. This by-passes EBITDA remember, hence why I don’t regard EBITDA as a meaningful measure here (as with many IT companies that are capitalising some of their payroll costs into intangible assets). Personally I think it’s best to adjust the accounts to expense all development spending, because it’s never-ending, and is just part of the normal operating costs of any IT business. Without dev spend, the business would gradually wither away.
Note that inventories went from nothing LY, to £1.8m this time. This was due to forward purchasing of computer equipment, so that supply chain bottlenecks of IT equipment would not prevent new contracts going live. Seems very sensible, and I recall the company previously mentioning this as being a planned strategy.
Note that of the £5.6m receivables, only £1.0m is trade receivables, very low because customers tend to pay up-front, or monthly recurring revenues. Although there is a further £2.3m contract assets (see note 13) which is effectively receivables which have not yet been billed. It's all fine basically, I just like to check everything.
Remuneration for Directors could arguably be seen as too low, with the highest paid Director on £109k, which does of course flatter profits, compared with if they were paid full market salaries.
Although a reader has flagged the £1.66m share options charge this year seems out of kilter with profitability (i.e. seemingly too generous maybe?)
Corporation tax - is favourable, due to the super deductions on capex (a new Govt scheme to incentivise investment), which has resulted in a negative tax charge of £760k (also helped by deferred tax adjustments). This flatters EPS, so be aware of that when calculating the PER.
Outlook - the all-important part, especially for growth companies.
This section reads positively to me - in particular (my summary) -
Good reputation established & big name reference clients. That should drive future growth.
“...considerable opportunity” re cloud - sector tailwind.
Strong product offerings.
“...confident in achieving results for FY23 in line with market expectations…”
“... with the potential for considerable additional growth given the size of the pipeline for Exchange Cloud. These types of discussions however will naturally take time to flow through into contracts and revenues”.
I suspect that last bit about taking time for contracts, might have spooked a few people. But the way I read it, that part refers to “additional growth”, over and above the current market forecasts. Therefore it doesn’t sound like a concern, or a profit warning. The existing forecasts look achievable, and management confirm they are confident of achieving them, so panic over I think.
Continuing spend on product development, and sales & marketing. I see this as code for - don’t expect exponential profits, because the company is still in the rapid growth phase, which involves additional costs to make it happen - e.g. headcount has risen from 73 to 89 this year under review.
Broker forecasts - slightly tweaked, but nothing significant. See Research Tree, where Canaccord (many thanks) and Progressive (commissioned) have useful notes available.
Valuation - as mentioned before, this is tricky. I see BKS as having a unique growth opportunity, so personally I’m comfortable with a market cap around £100m currently. That feels about right to me.
Conceptually, I see it as similar to Eagle Eye Solutions (LON:EYE) - different activities, but a similar model of building recurring revenues, sticky clients, quite rapid organic growth, in a specialist niche, and EYE is valued at £150m currently. In comparison, BKS looks priced about right.
I don’t find PER useful for valuation with very high organic growth companies, because just a few years’ strong growth can utterly transform profitability. Although costs often also tend to rise rapidly too.
My opinion - Beeks strikes me as unique, and I could see this becoming a much larger business in time. It’s got a big market opportunity, and the growth rate has really accelerated in the last year, as you can see from the Stockopedia graphs -
.

.
For now, I think Beeks shares look priced about right. It’s the longer term upside which does get me excited.
My interview with Beeks - I’m delighted the CEO has agreed to my request for an interview this Thursday, and thanks for your ideas for questions in the reader comments yesterday. My interviews tend to be typically 30 minutes, and overview in nature. So there isn’t really scope to get stuck into minor details. Hopefully though it should be useful in us learning more about the company.
Also note that Beeks is doing an IMC webinar at 13:00 this Thursday, 13 October. I’m doing my interview immediately afterwards, so I’ll watch the webinar first, and make sure I don’t duplicate the questions! Should be interesting.
By the way, it’s fine to post bearish views on Beeks (or any company), if you feel that way, if you explain your reasoning with facts & figures, and don't become abusive. I fully understand that BKS won’t appeal to value investors right now, as it’s a rapid growth company, work in progress essentially. So we’re more than happy to hear contrarian opinions, indeed we want to hear opposing views, then we all make better decisions I think, if we consider the downside too. So do post away! There’s no groupthink here - maybe we’ve fallen into that trap in the past, but we learn from our mistakes hopefully.
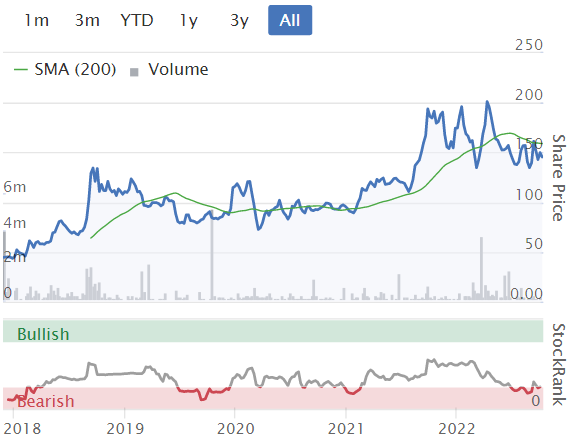
Looking at the chart below, since BKS listed 5 years ago, all the gains were really made in the first few months, and since then it's zig-zagged around, but largely flat overall. That's despite the business having made great strides in that time. The share count has risen from 49m back in 2016, to 65m now - remarkably little dilution for a growth company, which has almost all happened in the most recent £15m fundraise. I think it shows the benefit of having the founder as a major shareholder, still with 38% of the company - the "owner's eye" as they say, reluctant to dilute without good reason.
.
Intercede (LON:IGP)
54.5p (up 43% yesterday)
Market cap £32m
This is a very small business acquired, called Authlogics Ltd (founded in 2015), but the rationale sounds sensible - it has valuable IP, but lacks the funding to sell it.
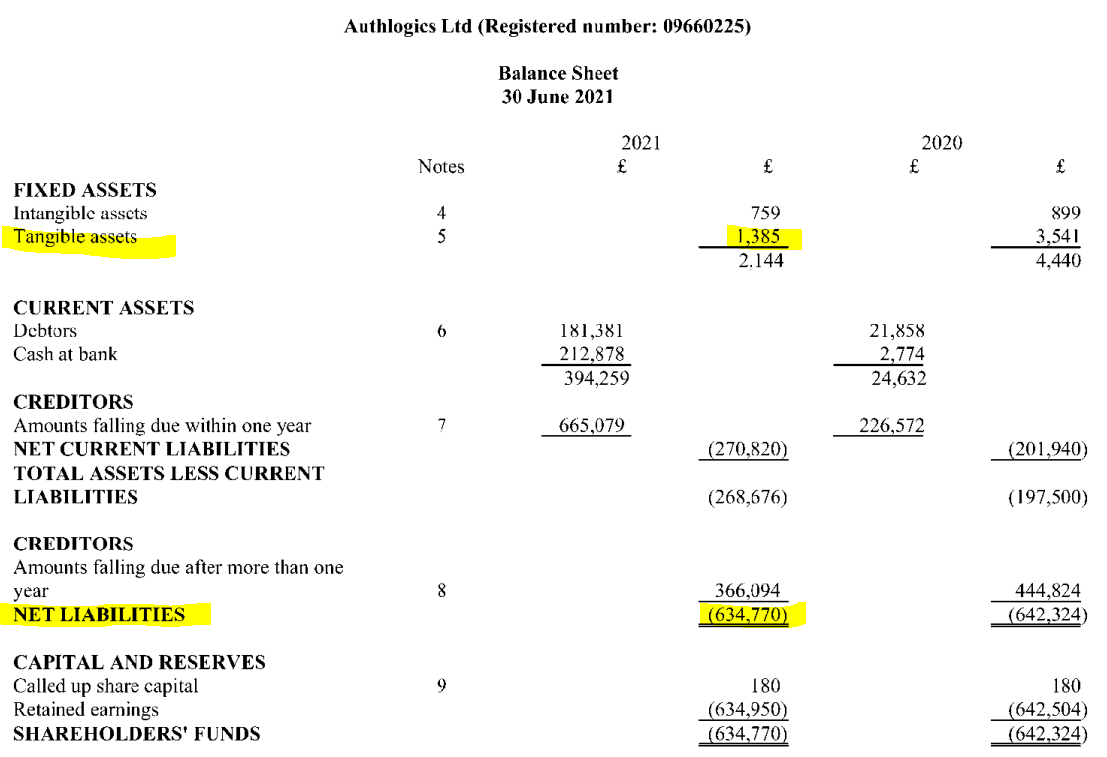
I’ve looked at Authlogics last accounts filed at Companies House, for its FY 6/2021, and it’s really, really tiny! 4 people, and fixed assets of £1,385, which looks like a desk, a couple of laptops, and a stapler! I’m being silly there, but you get the gist. Its balance sheet looks stretched, with £(635)k negative NTAV, with funding propped up with related party loans, and what looks like a big up-front payment from a customer (reflected in a big jump in deferred income).
This is not to disparage Authlogics at all, but more to say it’s clear that the company looks too small, and doesn’t have the funding, to go it alone. Hence an acquisition, with an earn-out, by Intercede could make sense.
.
Authlogics looks to have traded around breakeven for FY 6/2021. The smallest companies don’t need to file a P&L, but you can compare the change in net assets or liabilities year-on-year, which tells you (providing share capital hasn’t gone up) what the after-tax profit/loss is. In this case, it made a profit after tax of £7,554 in FY 6/2021. This is confirmed in the RNS from Intercede.
Intercede is paying £2.5m for it, so the IP must be good. Of that, £0.5m looks to be paying off Authlogics’ debt. Plus there’s another potential £3m of staged earn-out payments. I like earn-outs, as they are usually structured to be self-funding, and to keep the key people motivated in the acquired business.
As outsiders, I don’t think we can judge yet if this is a good deal or not, we have to just take it on trust. I see IGP management as safe hands, so they wouldn’t be doing the deal unless it made sense, and it’s easily funded from existing cash, so no apparent risk.
This is the most striking sentence in the acquisition announcement -
This enlarges our addressable market more than 10-fold, and these markets are predicated to grow significantly over the next three years.
Intercede is a cybersecurity company specialising in digital identities, derived credentials and access control, enabling digital trust in a mobile world.
Intercede revenues for the six months ended 30 September 2022 totalling £6.1m are approximately 23% higher than last year on a constant currency basis and 24% higher on a reported basis (2021: £4.9m on a reported basis). This is in line with management expectations.
The Group had cash reserves of £10.0m as at 30 September 2022 compared to £7.8m as at 31 March 2022 reflecting positive operating cash flow and continued tight cost control as budgeted for FY23.
Following payment of approximately £2.0m initial consideration, after net debt and working capital adjustments, relating to the acquisition of Authlogics Ltd announced today, the Group had cash reserves of £7.9m and has no debt.
My opinion - thanks to Finncap for an update note yesterday. This has £11.1m revenue pencilled in. So with £6.1m of that in the bag from H1, that only leaves £5.0m to be achieved in H2. Therefore it’s looking as if IGP is more likely than not to be heading for a full year beat at the revenue line. With a largely fixed cost base, profitability is highly operationally geared, so the £0.1m adj PBT forecast for FY 3/2023 could be beaten. Although bear in mind that staff costs are rising quite heavily at IT companies.
This all looks pleasing, and interesting. I’m not currently holding IGP, but I still like the company. A strong current trading update shows that progress is being made, and this small acquisition sounds intriguing.
The StockRank looks very mean, considering IGP is profitable again now, and has repaired its balance sheet, which is now strong.
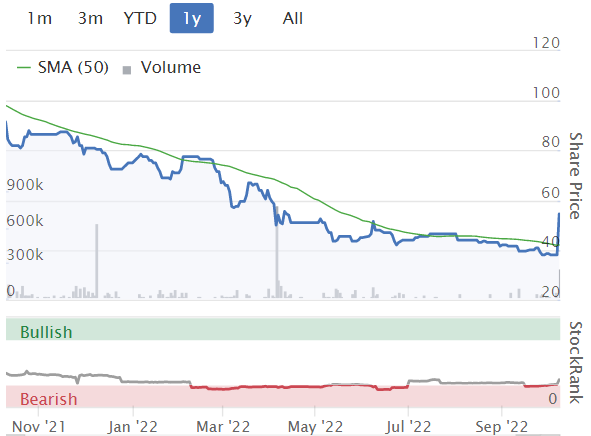
It's interesting to see that 6-months of share price losses were erased yesterday. So there's obviously pent-up buying interest, with people wanting to see evidence of good trading, before rushing in at once.
.
Quiz (LON:QUIZ)
10.4p
Market cap £13m
QUIZ, the omni-channel fashion brand, announces a Trading Update for the period from 1 April 2022 to 30 September 2022 ("the Period").
Positive trading across all channels
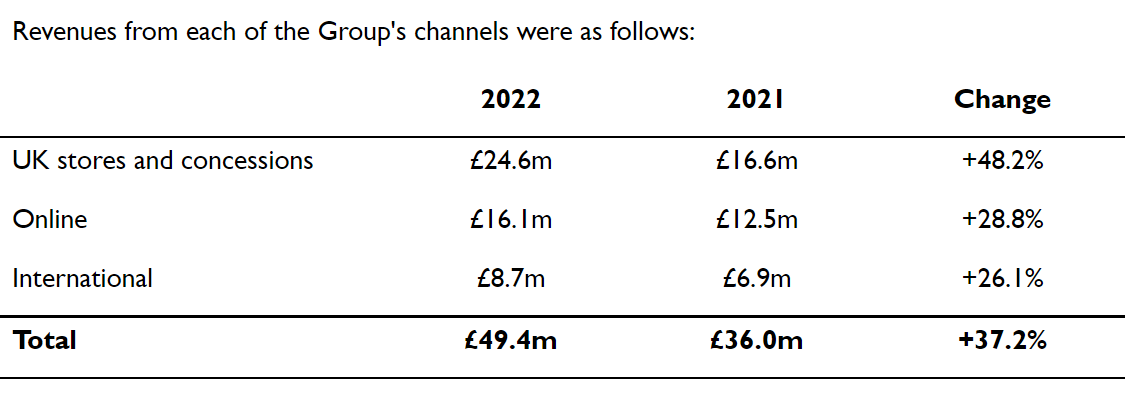
H1 revenues £49.4m, up 37% vs H1 LY, and “marginally ahead” of what mgt was expecting.
Growth rate “moderated” in Aug & Sept, which it blames on consumer confidence declining.
Gross margin has improved (but no figures provided) - demonstrating ability to pass on higher prices, which I think is impressive. It's been very high in the past.
All sales channels are up, and I think the online growth is particularly impressive, as plenty of other fashion retailers are struggling to achieve any online growth against tough 2021 comps (pandemic boosted) -
.
UK stores - LFL revenues now “consistently higher” than pre-pandemic. That’s good, but they need to be higher, to absorb cost increases like wages & utilities.
Stores are trading well in the UK, benefiting from the restructuring in 2020, which lowered rents, and I think nearly all the stores are now on turnover rents (which are marvellous, they work a treat, because rents flex up & down with revenues, largely de-risking most sites).
Concessions (which are stores within a larger store, e.g. Dept Stores) - QUIZ has 62 sites in the UK, nothing said about trading, but says they are “flexible and low-cost route to market”.
Online - good growth, and average transaction value has risen, but returns rate has worsened (something that other online fashion companies are also moaning about).
International - is the Ireland stores/concessions, plus franchise revenues elsewhere. Confident in further growth opportunities.
Cash - good grief, it’s got £9.2m cash in the bank! (the market cap is only £13m). Plus an unused £3.5m bank facility (expires June 2023, but it’s not really needed now I’d say).
Outlook - this is reassuring I think -
The Group's full year results to 31 March 2023 which will, as always, be in part dependent on trading during the key Christmas period, are expected to be in line with market expectations.
The Board is pleased with the strong growth recorded across all channels during the Period which supports the Group's omni-channel business model. It remains confident that the brand will continue to increase its appeal and looks forward to achieving continued profitable revenue growth.
Valuation - it’s a pity that QUIZ didn’t provide a footnote to explain what market expectations are, which is best practice these days, so a bit of an obvious omission. This is not helped by the lack of broker research available to us (nothing on Research Tree).
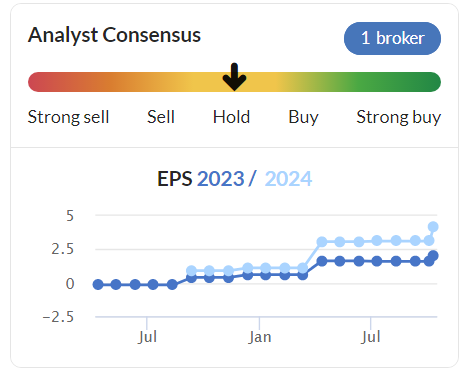
However, the Stockopedia data provider has picked up on one broker forecast, and as you can see, it’s in a nicely rising trend, not something we’re seeing with many other (if any!) retailers -
My opinion - this is going really well. I think the share price seems woefully inadequate, and in more normal markets would probably be double (or more) the current valuation.
In tight consumer conditions, I think it’s generally best to avoid the middle market, and instead focus on value, or top end retailers. QUIZ offers “glamorous looks at value prices” - I think that’s ideal for current conditions.
Lack of physical competition is also a bonus, as QUIZ is one of the few High Street retailers still going, with so many competitors having disappeared. Its shops are all (or nearly all) on cheap turnover rents, so it has an enduring competitive advantage there, and can just walk away (from short leases) if the landlord wants to raise the rent on expiry.
There’s been no dilution since it listed in 2017, with the share count remaining static at 124m.
The founding family seem intent on rebuilding the business, and I’m told are highly committed workaholics! Surely if they intended to take it private on the cheap, they would have done it by now?
There doesn’t seem any stock market interest in the shares right now, but weighing up all the facts & figures, I think this share is as close as we can get right now, to a no-brainer. But you might have to be patient. What a pity I wasn’t able to hang on to my previously big holding here. Spilt milk and all that.
.
.
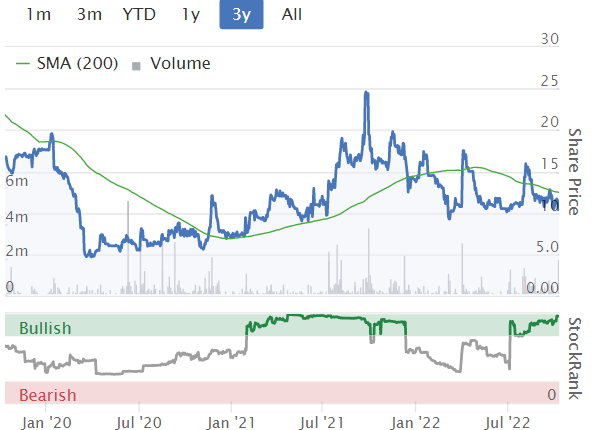
Note the almost perfect StockRank too - so the house computers agree that QUIZ looks good.
Graham’s Section:
iomart (LON:IOM)
Share price: 146.7p (-7%)
Market cap: £161m
This is a cloud computing and IT managed services group, rarely covered in the SCVR (the last time was in 2017).
Over the years, I’ve developed a sceptical attitude to IT managed services. My heuristic process is to classify it with recruitment companies and others that I consider to be “people businesses”.
This is a category that I’ve gradually stopped investing in, as I came to the conclusion that (in general, there are rare exceptions) they had trouble building and maintaining long-term competitive advantages.
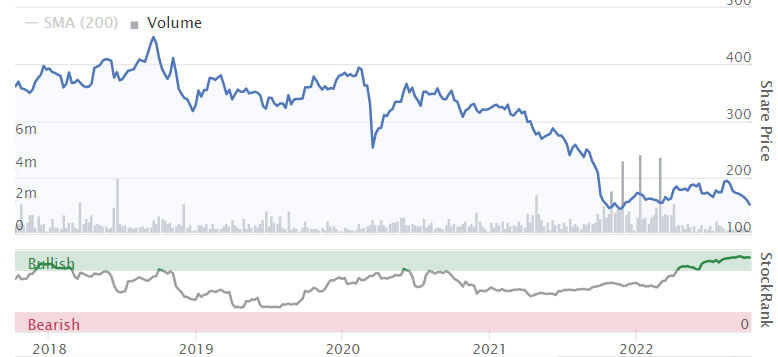
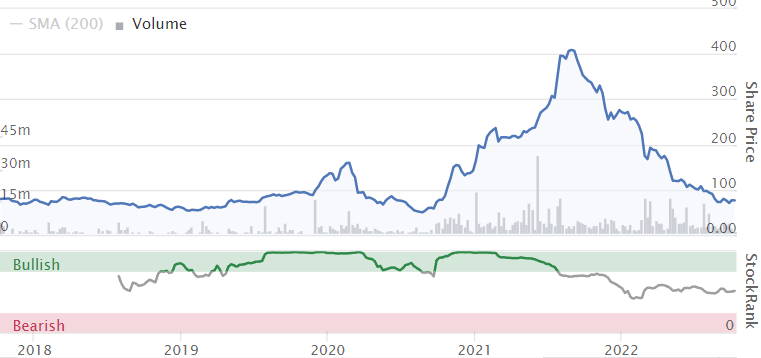
Iomart’s share price trajectory over the past five years has been unpleasant, so I’m relieved that I was writing sceptically about it all those years ago:
There was a point when any business which had the word “cloud” attached to it could receive a premium rating.
But that bubble is now a shadow of its former self. The NASDAQ, for example, is currently down by 34% versus the peak it reached last November.
Let’s dig into Iomart’s H1 trading update:
- “Performed well… with strong cash conversion, improved customer renewal levels, and continued momentum across all strategic areas, including the completion of our first acquisition…”
- Customer renewals plus recurring revenue provide visibility over full year financial targets.
- Revenue ahead of prior period (£52.5m vs. £51.9m), adjusted EBITDA lower (£17.8m vs. £19.6m), adjusted PBT lower (£7.3m vs. £9.1m).
- Lower profitability “reflects both the revenue mix in the period and our continued investment in the skills and capabilities of our workforce”.
This reference to investing in the workforce - as a drag on profitability - is indicative that this is a labour intensive type of business.
Acquisition - there is a £10.5m acquisition that “allows Iomart to broaden our market and customer reach whilst enhancing our product expertise within the data management service layer.” Another £4m is payable in deferred consideration.
Outlook - Iomart can “flex pricing” in response to energy costs and the inflationary environment.
H2 should be better than H1 but:
“...in the face of potential economic headwinds, it is not expected that margins will fully recover and that profit for the full year is therefore likely to be at the lower end of the Board’s original expectations”.
My view
Despite the profit warning and my negative attitude towards this sector, I’m actually going to take a more positive view on this share than I did five years ago.
Why? Valuation:
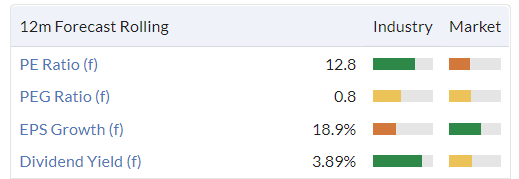
It turns out that if you have a weak share price for five years, but you broadly maintain your profitability, you can end up offering decent value!
Profits have been just about maintained over the years, despite rising revenues:
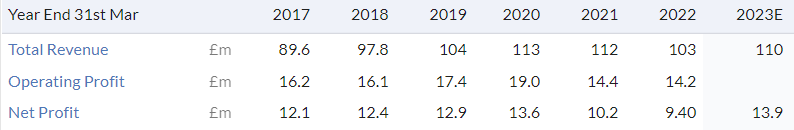
Indeed, the company announces today that H2 revenues will again be higher than H1, but that margins won’t recover. It looks like we can’t expect much margin improvement here in the long run. But given the lower valuation, maybe there will be some value investors who spot an opportunity at current levels..
The Stockopedia computers have noticed something. IOM shares pass the free cash flow screen, as the company has been generating very decent cash returns.
Last year it did exceptionally well: £35m was generated from operations, while only £10m was spent due to lower capex and no M&A.
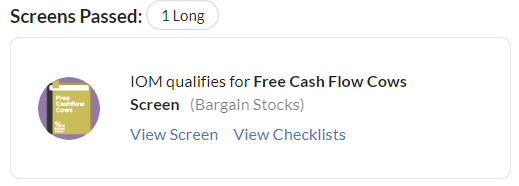
The company is carrying some net debt (£41m in March 2022). If it keeps up the good cash conversion, this shouldn’t be a problem.
So I’m no longer bearish on this stock. I wouldn’t go so far as to say I’m bullish, but I think there’s enough here to justify this market cap.
.
Reach (LON:RCH)
Share price: 75.9p (-1.5%)
Market cap: £240m
This share saw some optimism post-Covid, but then drifted lower once again:
Let’s see what the newspaper group formerly known as Trinity Mirror has to say in its Q3 update.

“Improved year on year group revenue trajectory versus Q2 driven by both print and digital”
This is a reference to the second derivative of revenue. The first derivative (in the table above) is not overly flattering.
Q3 and September revenue performance distorted by impact of the passing of HM The Queen which benefited circulation but significantly reduced advertising due to the blackout during national mourning
We can use the July & August column in the table to see a “normal” trading performance, i.e. print revenue down 2.8%, digital revenue +5.9% and total revenue down 0.5%.
Inflation - there has been “more stability in the cost of newsprint during the period”. Measures have been taken to offset the inflationary pressure.
Outlook
Although the unusual period of trading during September impacted revenue and profit, underlying revenue trends during Q3 were broadly as anticipated heading into Q4, historically the strongest period for advertising. We expect circulation revenue to be supported by increased cover prices, while advertising revenue should benefit from seasonally stronger yields, particularly around Black Friday and Christmas and from the football World Cup which starts in November.
My view
Paul has already done the donkey work here, in July, of going through the pension scheme disclosures. According to Paul, the annual payments due to the pension scheme, from 2022 to 2027, are £52m p.a.
Here are some very rough-and-ready ideas that might help someone to come up with a valuation for Reach.
Take the c. £90m in net profit that the company appears to be making currently. Deduct £52m. Use the result (£38m) as current profitability for shareholders, and apply a multiple to this figure. Under this approach, we are pessimistically assuming that the payments to the pension scheme last forever.
For example, suppose we applied a 7.5x PE since we believe that Reach is a low-quality business with a poor long-term outlook, and we only want to pay a single-digit multiple.
That gives a valuation of £285m.
On the recent interim balance sheet, current assets matched current liabilities so we could assume they don’t require any adjustments to the valuation.
However, there are long-term provisions of £40m so let’s deduct them from the £285m valuation.
This gives £245m, i.e. about the same as the current market cap.
The good news is that the payments to the pension scheme will end, some day.
The other point is that changes to inflation and interest rates can have strange effects on pension schemes.
For one thing, my understanding is that most defined benefit pension schemes, even if they are indexed to inflation, have a cap, e.g. 5%. This means that when inflation is higher than 5%, the pensioners are poorer in real terms because their payments can only rise at the rate of 5%. But it limits the risk to the pension scheme, of having to match runaway inflation.
The other point is that with higher interest rates, pension schemes can earn vastly higher returns on new investments (e.g. when reinvesting portfolio income or deploying fresh money from company contributions). This is of course offset by lower asset values, but in the long run it is excellent news for pension schemes. The era of low interest rates is, after all, what probably made defined benefit pension schemes unsustainable in the first place.
Therefore, while I can’t say this with certainty, I think there’s a possibility that the pension scheme here could prove to be less expensive than feared.
This share has never appealed to me in the past but as a risky gamble, I’m starting to get interested.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

99 comments
I wrote a longer comment about Intercede (LON:IGP) yesterday, so won't rehash - but if you thought the FY revenues are already in the bag given H1, I think there is much surprise to the upside available due to FX. Majority of Intercede revenues are in USD while their cost base (staff) are mainly in GBP. So H2 should see 10-15% more GBP reported revenue from their high recurring revenue base. Which more or less falls to the bottom line.
(I hold in the Boon Fund)
Hi Boon,
Yes I was thinking along those lines too with Intercede (LON:IGP) H1 results, and the forex benefit. However, what confused me is that there was hardly any difference between the sterling, and the constant currency figures in the headlines. that did confuse me a bit, and there wasn't time to investigate more thoroughly. Any ideas?
Regards, Paul.
Yes, that confused me too. But when I go back to the FY Mar22 results for Intercede (LON:IGP) there is this statement:
And if you look at LinkedIn, 78 out of 101 employees are in the UK.
So I really can't see why the CCY and Reported numbers are not more different in H1. Maybe they started to hedge FX in H1? Just at the wrong time to do so?
I am feeling downbeat at the minute regarding equities, almost daily seeing my small holdings that are left dripping down. There are lots of shares looking great value, but what really is great value in a bear market?!
I keep reminding myself to hang on in there as it will turn at some point, stay positive and do the work now for the next bull market.
This is my first experience of a bear market, and i hope i will have learnt a lot for when the next one comes!
It's when the night is darkest where the best opportunities are!
I've been in buying mode. Just picked up some LPA (LON:LPA) yesterday and Metro Bank (LON:MTRO) today.
You could say both are risky bets; one is an AIM tiddler and the other is a basket-case bank who hasn't been able to turn a profit and has taken the "branches are good" strategy.
In the case of LPA, my investment thesis is that they have a hidden asset - their DB Pension Fund. Which was already in acturial surplus, and in Dec they had switched out of "risky" assets to safe assets. No idea if LDI is impacting them, but they have been planning to sell it for a while, and with the rising gilt yields, they could probably get a good windfall from selling it now.
In the case of Metro Bank, its whole future hinges on rising Net Interest Margin (the difference between cost of funds and what it charges on loans). The surge in borrowing costs is a bonanza for them. They were targeting only Q1 2023 for profitability, but I reckon they can now achieve it in Q4. They have the benefit of a huge current account funding base, where they pay close to 0% interest. Currently trading at a P/B ratio of 0.15x, whilst the bigger banks are at 0.5x+, I reckon they could easily double, and will still be undervalued at 0.3x P/B.
(I hold in the Boon Fund)
Hi JohnDoe
I wrote a longer piece earlier, and since had more things go through the capital sell criteria, obviously being nearly 7pm too late to do anything today.
There is no easy answer, but have a set of rules, follow those rules and learn how to switch off the phone/tablet/pc and do something outside, or sleep, or spend time with loved ones.
It is always hard when you think it has taken my xyz months to save what I have lost in capital value this day, week, month or year. But one hand takes, the other as Boon identifies creates the opportunity for tomorrow.
Long term I am up, though not as much as I used to be. But if I step back still a lot better than putting in the Skipton Building Society (or savings provider of your choice). The best example is just to look at my main pension and what 25 years of investment has given me versus contributions, yes this last 12 months looks a car crash (like how many years contribution???) but then what is the worth compared with how many years worth of contributions!!!
Make your plan, stick to your plan, know that there is pain in a Bear Market, and even more in a Bull Market (FOMO).
But make sure you are here tomorrow, next week and next year as you will succeed.
Tommy
Thanks for your wise words Tommy! Just re reading Minervini's "Trade like a Wizard" for a bit of perspective and inspiration
Paul, Graham:
'Today's report is now finished, as we've covered 6 companies, and don't want to overwhelm you.'
Never mind about overwhelming us, what about you? Thanks for all you do.
You're welcome! G
For one thing, my understanding is that most defined benefit pension schemes, even if they are indexed to inflation, have a cap, e.g. 5%.
You would need to check that for Reach's scheme, Graham. An increasing number do have caps, but they don't all, or not for older members
Some db pension companies such as Wood Group pay increases “at the company’s discretion” which means, in practice, never. Shamefully, some Wood pensioners have seen their pensions lose 50% in value over the last 20 years.
Agreed- need to check to the Scheme report which will set out their payments policy.
Sanderson Design (LON:SDG)
I am not calling the state of the market in any way but the reaction to the Sanderson Design (LON:SDG) interims is what usually happens at the end of a bear market and the beginning of a bull, i.e. no sellers, they all went ages ago, so any demand creates a sharp rise in the SP.
Although Sandersons are catering for the better off who are less likely to be affected by inflation etc when i read the RNS I did not expect such a positive reaction.
My thoughts as well, I hold and was expecting a fall in price this morning.
Interesting. I personally use the coppock indicator which as far as I can see is no where near signalling the start of a bull market yet...hope you're right though !
Hi I keep my own Coppock data so am interested to know if there is an online source so I don't have to. I could never find one other than on (25 years ago anyway) the back of the Investors' Chronicle. Where do you get yours from please?
For an honest day, just logged in and checked where todays flow of red is
Sold Natwest (LON:NWG) Legal & General (LON:LGEN) and Belvoir (LON:BLV) for hitting a capital protection buffer, manual ~20% down. All good companies, all I would buy again but applying the lessons I kind of learnt from 2020, don't let things keep drifting down with a hope that Mx Market is wrong and tomorrow everyone is suddenly going to think the same as you and it will go back to your entry point and more!
I would say this is a simple sleep at night strategy for me as there are a lot of positions in the red overall, and some large moves in the last few days on Mum's Pension (ISA) on the renewables front, obviously following the financials downwards.
I know that I do not know what the longer term is, I am overall positive, but I want to be in the position that I still have accounts left for all the folks, and whilst there is inflation, it is about being in the game to win longer term, hence the sleep at night. This is not money that is needed today or tomorrow, we all have the ability to "tighten the purse strings" in the short term. I spent the first two days of freedom (unemployment) putting another 200mm of insulation in the loft.
Never an easy day doing this and realising an actual loss, but at the same point I think that it is important to know what your own rules are, what is your plan, and to stick to it, no matter how hard it feels when you press the "sell" button, or how much against the grain that it feels.
To be honest there is a big part thinking buy more as these are smaller stakes currently (no holding >3% portfolio value) as they are bargains. Maybe tomorrow they will bounce and I will find the nearest wall to try and manually adjust my rear view mirror, or they will be even bigger bargains.
Good Luck
Tommy
Hi Tommy
Stick to your guns, limit losses, build fire power for when the market turns seems like you have a good plan to me...Good luck mate.
Paul
Thanks Paul
Morning guys! Expected Paul to comment on QUIZ yesterday, any chance of having a look today if time permits? I can't find any notes on RT but the EPS upgrades reflected on Stocko this morning stand out - Assume QUIZ advised brokers yesterday so should carry some weight - A PER of 3 if they meet them, a PER of 6 if they come in half way even!
Morning matylda!
I've just published a review of QUIZ above.
It looks astonishingly cheap to me.
Regards, Paul.
Curious that QUIZ don't really say very much about costs pressures. They say generally that they "have been subject to inflationary pressures through the Period" but that demand for product has meant less discounting which has helped offset and that's about it. Majority of profit still comes from physical stores which has to mean increased costs for power and staff etc. - all currently inflating at an alarming rate. I would have felt reassured if they had mentioned this in more detail (ideally saying something about each cost element) and either said how it was being handled or just given it a nod that it will affect margins (or even better that price increases are being pushed through to compensate) - we are instead left in the dark a bit on this - feels like the elephant in the room and it's odd to have largely sidestepped it (or maybe its not odd as companies don;t like to dwell on the negatives...). Makes me fear them painting a slightly rosy picture?
I see they operate a lot of concessions - does anyone know how these typically work re. power usage? i.e. is is a just fixed lease cost for the concession area all-inclusive of rates, utilities etc. or is there a separate element made up of a percentage contribution for electricity etc.?
Incidentally 'elephant in the room' strikes me as an odd phrase to describe something unsaid. If I saw an elephant in a room I would mention it almost immediately... :-)
BIACS. I think the point of "Elephant in the room" is that, although it is obviously there and everyone can see it - no one has actually mentioned it, for whatever reason (embarrassing, controversial etc).
Glaringly obvious but not requiring a serious mention - a bit like a silly joke in a smallcap shares post you might say.
Me too - And I thank you for that Paul - Much appreciated - Jon
So there appears to be a continued grind down in share prices since last Monday / Tuesday's mini bounce. I was holding out for a dead cat bounce, but that looks a way away, with the Fed and the BOE likely to continue to apply large interest rate hikes over the coming weeks.
My watch list gets bigger and my shares smaller as I head back into the relative safety of cash, as shares break through to new lows, with Sureserve (LON:SUR) being todays victim. The problem with these companies is, when they break through is its hard to know where they might end up, and a 2% percent loss can quickly turn into a 8-10% loss as the sells continue. From there another leg down could come with losses becoming unsustainable.
My gut feeling is we will have to wait until after Christmas for any small shoots of recovery as inflation appears to continue its relentless climb and unemployment both sides of the Atlantic remains stubbornly low, and coupled with an ugly escalation in the war in Ukraine, black clouds will continue to linger for some time.
Cash with all it's negative drawbacks does feel like a safe place to be in right now as the bear seems to be growing in strength.
Any opinions on Foresight group (LON:FSG) - seem to be performing very well and another positive update this morning.
Foresight Solar Fund (LON:FSFL) was something I added to yesterday, the dividend seems to me to match the low share price.
Not the same company Solar Moon. I was commenting on Foresight group (LON:FSG) - sorry for any confusion. I’ve never seen Foresight group (LON:FSG) mentioned on here before. Good trading update this morning, and a company that seems well diversified and thriving.
Different companies although Foresight group (LON:FSG) manage Foresight Solar Fund (LON:FSFL)
I add to this fund too surely too big a drop
I hold Foresight group (LON:FSG) and think looks very interesting although seems to be really under the radar so not expecting much to happen any time soon. Nevertheless, as an alternative asset manager focused on areas such as renewables and infrastructure, looks well placed and very modestly valued. Continues to see strong inflows and clients tend to be sticky (unlike traditional asset managers which usually see a flood of outflows when markets sell off). Gresham House (LON:GHE) is another one with similar qualities.
FW Thorpe (LON:TFW) I have been a holder in Thorpe for many years and have high regard for the management. Annual results today show good growth (both organic and some through acquisition) despite issues with component shortages. Bullet proof balance sheet and interesting future prospects from Ratio Electric and recently acquired SchalLED. Historically highly rated, but has fallen back with everything else I hold this year. Any views from Paul/Graham appreciated.
Hi stuartb58,
Thanks for the synopsis on FW Thorpe (LON:TFW) - I like the company, but its shares have always seemed too expensive. It's on the list for us to look at today, but not sure we'll have time, as so many other companies reporting too.
Regards, Paul.
Thanks Paul
Sureserve
Nothing surprises in this market but Sureserve good update , spitting out cash , huge order book, great sector , profits in line , cash pile getting hammered .
Dropped 6% .
Shares look to be “on sale” and as Warren Buffet says “we love it when our shares go down in price so we can buy more .”
Not sure I “love it” but it’s a core holding and looks very compelling long term value at these levels .
Looking forward to the day I can buy one of £BRK.A $BRK.A shares. Hopefully when their VR is at 50.
Sorry just realised where I was - not bad to diversify, have some big boats in amongst the dinghies.
Beeks Financial Cloud (LON:BKS) Beeks Financial. Has a stock rank of 27. Obviously, this is based on past numbers, but it is not commented on very often on why you would override this red flag.
Do leopards really change their spots so easily?
Well I think the StockRanks are generally very sceptical about smaller growth companies. Here is the StockRank for Beeks Financial Cloud (LON:BKS) (I hold) -
As you can see, the major factor is the very low value score of 6. That's fine, because it's not a value share, and as I comment in the article, it's difficult to value. Rapid growth companies usually look expensive during the growth period, but people are looking forwards to much stronger profits once it's say double or triple the current size. The big risk is if growth stalls, then valuations have a long way to fall.
Quality & momentum scores are middling.
So overall, the StockRank actually fits quite well with my view of the figures. Why over-ride it then, to directly respond to your question. The main reasons for me are -
Set against that, the more negative aspects are that it required up-front expenditure on capex (although as pointed out in the main article, half the capex was one-offs - e.g. buying a freehold, and leases), so growth can be seen as quite cash-hungry initially. The big share options package is a negative too I think. Plus there's a risk that growth might slow due to macro conditions, but that's already factored in to more modest growth forecast.
So BKS is definitely not a value share at this stage, which is why the StockRank is low. I find the StockRank system a really good sense check. There needs to be a very good reason(s) for me to buy a share with a low StockRank, and I generally don't want too many of them in my portfolio.
Regards, Paul.
Thnx
BKS
"Beeks Financial. Has a stock rank of 27"
The stock ranks are only one tool - i suspect very few fast growing companies will generally show up well on the stock ranks - therefore they are not really an negative indication here as we would expect the best companies to have a poor rating. Obviously the number does its job if you dont want to pay "jam tomorow" prices today these are the kind of companies are nicely flaged up by the stockrank. To be fair to this company it looks like its already decently profitible on an underlying basis(i will admit not too great if all those profits handed out in shares) - and sales are growing ata great lick. In some respects the fgactbten number is not worse than 27 is probably a hint that there is something here potentially. I am pretty sure doug would not be impressed must admit (I miss Doug)
Good points, thanks rmillaree.
(I miss Doug)
I don't! He was what they call a PITA. And I'm not talking about bread!
To be fair to Doug he did highlight some companies that had decent metrics on his system and he did flag up the numbers his metric system produced for various companies . Obviously most here may not have agreed with his regimented system - i think nearly everyone other than doug would agree some companies simply dont show upo well on certain tests. I dont think anyone can argue with his results and that companies that he did flag up that passed his test probably had very good quality metrics. Generally it takes two to cause an argument - so i dont blame Doug for sticking to his (presumed) guns ref his system when poked by others :)
Doug's system was interesting. It was just his style of commenting that I disliked - very arrogant & abrasive. We can do without that.
Morning Paul, would you be happy to report your views on the Annual Results from SCS (LON:SCS) please, announced this morning?
The clearly did pretty well in the year just ended, and have managed to clear down a lot of the order book which had built up at the end of FY21. They report EPS of 36 p, and announce a 2 p increase to the final dividend of 9 p today. I would say they have the capacity to maintain the dividend at around 13 p, leaving us with a 10% yield at present.
The new CEO reports subdued trading since 1/8/22 with order book intake down 14.4% on last year. I wonder what impact that will have on earnings in FY2023? They do appear to have some flexibility in cost base, especially around marketing and a strong balance sheet to help survival.
For those who are happy to look through the current markets, the company seems to have a number of interesting initiatives under way to improve customer experience (in store and digital) and invest in people at all levels.
Yes, SCS (LON:SCS) is on my list, leave it with me!
Looking where I can get my leather sofa seat bit replaced - the rest is in good nick and I like it. Probably a more expensive route than a new one - but will 'mend and make do' for now. But they could be one of the 'last persons standing'. More home grown trade/artisan than container from China in the future maybe.
Re Beeks Financial Cloud (LON:BKS) my main concern is the need for another fundraise. In April 22 they raised £15m and 6 months later this is down to £7.9m. The probability of another fundraise within 6 to 12 months looks very high imo and given the state of the market (materially worse in past 6 months) this could well be at a significant discount. Throw in the huge share payments to management wiping out almost all the profits, gives me 2 major concerns. In a bull market the impressive revenue growth may well negate these factors but, sadly, we're not in a bull market..
Kouremenous35 minutes ago
Re Beeks Financial Cloud (LON:BKS) my main concern is the need for another fundraise. In April 22 they raised £15m and 6 months later this is down to £7.9m. The probability of another fundraise within 6 to 12 months looks very high imo
I think you're being too cautious there. Net cash of £7.9m looks ample to me, and I'd say the risk of another fundraising is very small, not very high! That's fine though, people interpret numbers differently. The balance sheet overall is strikingly good now, so I don't see any risk of a fundraising actually - unless they want to raise cash for say a really big contract, to accelerate growth further.
The founder doesn't like dilution, and there hasn't been much, for this type of company (up from 49m to 65m shares in issue, in the 5 years that it's been listed, when revenues have grown from just £4m (FY 6/2017) to a current run rate of over £20m.
Remember also that it chose to spend £3m on a freehold property last year, so that wasn't cash burn, it was the purchase of a valuable asset, which it could borrow against (or even sell) if necessary.
Management has also indicated in the past that they might consider different contracts with clients, which involve some up-front cash, so I'll ask the CEO about this when I interview him on Thursday.
As regards share options - I agree, these look excessive, so I'll quiz him on that too. It's actually quite helpful when readers raise concerns, because it allows me to ask management difficult questions that you have raised! ;-) (rather than making me look hostile, if the questions come from me).
Good to have your input, thanks.
Regards, Paul.
Thanks for your reply Paul. I agree that if they could secure sales with significant cash up front to fund the capex, then that would be a game changer as the cash burn would drop dramatically. However, as a customer, wouldn't you then lose out on one of the main benefits of switching to Beeks? Likely lead to a drop in winning new business . Be great if you could ask why they aren't doing this now if the customers were willing to pay upfront?
Regarding the freehold property I don't think the picture is quite as rosy as it first appears;
"During the year we took on additional borrowings of £1.5m against the £2.1 purchase of our new Head Office facilities in Glasgow"
Thanks again, David
Hi David,
Just to come back to you on one point, you said;
Regarding the freehold property I don't think the picture is quite as rosy as it first appears;
"During the year we took on additional borrowings of £1.5m against the £2.1 purchase of our new Head Office facilities in Glasgow"
Remember that the new borrowings are already taken into account in the net cash figure of £7.9m, which is cash of £10.16m, less borrowings of (1320+978k) = £2.3m = £7.86m net cash. Hence the £7.9m net cash figure effectively assumes the mortgage on the freehold is going to be paid off, which it won't be.
Therefore I'd say the gross cash figure of £10.16m is the real-world cash figure to lock onto. Thinking about it, I think the lease liabilities might be IT equipment, rather than property? Actually no, I was wrong, note 18 shows that the lease liabilities (and RoU assets) relate to space rented in data centres (and possibly in the exchanges themselves?).
The total lease IFRS 16 entries are:
Right of Use Asset (RoUA) £3.37m (within the PPE total of £16.27m)
Lease liabilities (current) £1.28m
Lease liabilities (long-term) £2.3m
That nets off to a £0.21m deficit, so negligible really. Hence it doesn't look like the company has any significant onerous lease liabilities.
We're probably over-analysing the figures. All that matters for the share price, is that rapid growth continues. Then the share price is likely to look after itself!
Regards, Paul.
Yes , Beeks Financial Cloud are just not generating any cash. Sooner or later shareholders will pay the price ( as it’s always the case ).
Yes , Beeks Financial Cloud are just not generating any cash. Sooner or later shareholders will pay the price ( as it’s always the case ).
It's not always the case at all, that's just a factually wrong sweeping statement! If you'd said "sometimes the case" I would agree, but "always the case" is incorrect, that's the specific & only bit I'm disputing, as I don't want to trigger another slanging match ;-)
Many, even most growth companies consume cash early on, and the successful ones then go on to generate cash (often huge amounts of it) once they reach scale.
Beeks chose to accelerate growth, hence the £15m fundraising, and it's building sticky, recurring revenues as a result, which delights me as a shareholder in it. There's a big opportunity, and I want the company to go for it, not obsess over cashflow when it should be maximising growth. Far too many UK companies stumble & fail to reach international scale for precisely this reason - investors are too focused on short term cashflow & profits, stifling growth. Whereas our American cousins take a much more aggressive approach, hence why so many of the world's top companies are in America (they tolerate failure much better than we do too).
I think we need to distinguish between 2 types of companies -
1) Perennial cash-burning, jam tomorrow or blue sky companies, where I agree with you that cash is often just going down the drain to fund operational losses.
2) Genuine growth companies, which are rapidly building recurring revenues, but that requires up-front spending on product development, sales & marketing, and capex etc.
The tricky bit for us, is distinguishing between the two types of companies! (not always easy when they're in the loss-making, growth phase).
To me, BKS seems to be growing so fast, in a potentially huge market, that this overrides any issues about cash (it's got plenty in the bank anyway). But I do appreciate that others have a different view on this, and are not convinced, which is fine - it's what makes a market, and I'm enjoying the discussion of it!
Regards, Paul.
On the face of it £:ETP seems to be in a great place growing revenues strongly in the hot sectors of water efficiency and green energy. Its Jan FY24 revenue target has increased 14% to £80.1m and it’s building a track record of meeting and beating revenue targets.
That said it does seem to be working through some growing pains.
Operating margins have shrunk to 12% from 23%. Large supplier payments at the start of Jan FY23 and a tripling of debtors has resulted in an operating cash outflow of £2m. ETP warn of further H2 outflows due to end of year increased receivables and inventory purchases for JanFY24 projects.
Given the large scale nature of the projects I hope all the receivables are recoverable.
Paying interest at 3.45% to 3.5% above base rates means the cost of the £6.7m of gross borrowings and funding further working capital out flows is going to increase with BoE rate increases.
In addition, given the apparent strength of its core UK offering I fear that it is being distracted by subscale initiatives such as the Indian business and the acquisition of Mathewson.
That said I’m looking forward to watching ETP on PIWorld today.
I think CEO comes across as both knowledgeable and capable but it will be interesting to hear his prospective on the value of target markets, profit margins, cash flow and demand from an increasingly under pressure property sector.
Super presentation and Q&A organised by the PIWorld team.
I am concerned that as investors we are observing all these companies reporting on the whole reasonable interims/full year numbers that were based in another time (that of low interest rates). I have noted in previous slumps analysts forecast on a straight line basis and I would caution myself and anyone out there trying to read too much into these numbers. Just my view.
Hi Camtab,
I am concerned that as investors we are observing all these companies reporting on the whole reasonable interims/full year numbers that were based in another time (that of low interest rates). I have noted in previous slumps analysts forecast on a straight line basis and I would caution myself and anyone out there trying to read too much into these numbers. Just my view.
Yes, I very much agree. It's vital to look at the broker consensus chart on every share, to make sure that broker forecasts have been reduced. In many cases, for small caps, they haven't been reduced yet, despite sectors being under pressure. That's where the profit warnings are likely to come from.
So I totally agree with you. For me, any new purchase would only make sense if the forecasts are already soft, and the company is likely to beat them (fairly easy to ascertain, as indeed we report on here when trading updates come out - a key question for me is always "how realistic are the broker forecasts"?)
Great point, thanks for reinforcing it.
Although the other aspect is that higher interest rates could only be temporary. As I suspected would be the case, the Bank of England has already had to resume QE, to stop Gilt yields going too high. The Fed seems hell-bent on causing a recession, to snuff out inflation that is largely due to supply shocks, not excessive demand. Hence the seeds have been sown for interest rates & treasury yields to be slashed again maybe next year, once action is needed to address a recession, and inflation should by then be falling (it's possibly already peaked in the US).
For these reasons, I could turn out to be very wrong, to just assume that interest rates are now normalising to historic levels. I think the world is addicted to, completely dependent on low interest rates & QE. Current policy of a rapid return to historic levels, strikes me as suicidal, hence likely to be reversed, after it's caused another financial crisis and a recession.
Cheerful thought for the day! ;-)
Regards, Paul.
Long guilts would suggest we are not going back to 17% land or zero/negative land - until we do of course.
I gave a monkeys for bonds/gilts till about two weeks ago - until discovered my pension fund is the next big financial crisis. Wondering what is a safe investment nowadays.
As referred to below, competent and given the economic headwinds pleasing interims form £SDG. Lisa Montagu and her team are doing a fabulous job of monetising the company's unique archive of brands. Paul/Graham any thoughts, time permitting would be appreciated.
Also what appears to be a well considered acquistion by K3 Capital (LON:K3C) in the insolvency space. Additionally, I very much like the company's decision to pay outstanding considerations in cash rather than equity as it considers that the market currently undervalues its equity. Mangement hold some 17% of the company with John Rigby, CEO holding 10% or thereabouts.
I hold both
Yes, Sanderson Design (LON:SDG) is on the list!
In my haste to put in a note regarding the interims by Eneraqua Technologies (LON:ETP I did not notice that they issued a second RNS at 7.01 confirming that they were entering the BTC market based on the following :
"The water neutrality pilots were to demonstrate how Control Flow HL2024 installed in existing homes can save water to offset the demand of new homes in the area. This would allow Control Flow HL2024 to be used in unlocking some of the estimated 120,000 new build homes across the UK currently stuck in planning due to water and nitrate concerns.
By eliminating water flow fluctuations, Control Flow HL2024 reduces water wastage and improves the performance of hot water systems. The pilots involved 100 homes and found that the Control Flow HL2024 system reduced the household daily energy and water bills equivalent to an average saving of c.£360 a year. The analysis, which was carried out jointly by Eneraqua and local authority staff, was based on actual gas and water meter data, taking before and after meter readings to determine the change in daily consumption, which is then multiplied by the current energy and water prices."
If this isn't a sweetspot I don't know what is !!!!
With the business rates revaluation in April next year what are peoples thoughts on which sectors will do well and which will do badly with the changes? Last time around saw a lot of hospitality businesses and retailers do badly with big increases in business rates payments. This time will be interesting to see what the government do.
Paul had a look at Eneraqua Technologies (LON:ETP) following their finals back in June and I quote " Its results out today look superb, with a huge rise in revenue & profit, beating very ambitious-looking forecasts" The iterims today are notable for not only delivering on all fronts but they have incresed their forecast for the FYJan24 .
"Having reviewed the performance to date, the Board has evaluated prospects for FYJan24 and increased its revenue target by 14% to £80 .1m, materially ahead of prior management expectations.
- This increased FYJan24 revenue target is already 72% covered by the order book2 (82% based on prior FYJan24 revenue target)."
Adding a little icing to the cake they are launching a water efficiency product direct to the consumer which has proven to reduce domestic water and energy consumption and utility bills . As you said it appears to be operating a sweetspot for heat pump installations -worth a look .
Also PI World presentation today at 12 noon. Register here https://bit.ly/ETP_H123_webinar
Morning Paul,
You mentioned yesterday about your interviews, one of which is with XP Factory. One quite general question I have for them is regarding the "replayability" of their escape rooms over the long term and any data they may have collated on this. I have been to two different sites and after that my friends and I agreed we had been there done that and I never really felt the need to keep going back. Whilst the second room looked different, the skillset needed to be successful and escape seemed very similar. My concern with that side of the company is that despite the high review scores it might be a bit of a novelty experience.
On a separate note - still loving the podcast, like many others have mentioned, it certainly improves my Monday drive to work!
Ben
Thanks Ben! Re Escape Hunt (part of XP Factory (LON:XPF) ) I also had reservations about how repeatable the customers would be, for the reasons you indicate. But the CEO said each site has about 6 different rooms, so people come back to do the other rooms. Although you make a very good point, that skillset/strategy to escape is the same, then each room could be less enthralling than the first one. I've added that to my list of questions, so will push him on that point. Excellent question, many thanks for raising it :-)
Regards, Paul.
The VR rooms are great and they can get really creative with these. I'd definitely recommend giving one a go.
Thanks Paul,
Really appreciate your response and will be looking forward to the podcast, especially as I have XP factory on the watchlist. Like the majority I haven't bought too much in recent weeks but did open a small position in SThree after listening to the podcast with management.
In challenging times such as these it would be easy for the message board to become an unpleasant place, particularly for less experienced investors such as myself. The captain steers the ship though, and the highly knowledgeable community here has remained positive and supportive throughout under your watch. Thanks for all you are doing and to all the other experienced investors who take time to share their expertise.
No better place to learn my craft than in a bear market and that first bull run will certainly feel all the better for it!
Ben
Eneraqua Technologies (LON:ETP) interim results today. These look strong to me and they are paddling with strong tail winds in water and energy markets,
“We are pleased to have increased revenue visibility through our order book(2), with the current financial year remaining fully covered. We have increased the revenue target for FYJan24 to £80.1m, materially ahead of prior management expectations, and have 72% of this already covered.”
( I hold)
Beeks
Jam today share ? Or Jam tomorrow ??
Depends if you are management or shareholders .
Huge red flag hoisted above this now as the seeming total evaporation of profits into options charges just signals self serving mindset .
I have found the most alarming thing about small cap investment is the propensity for businesses to be run for the benefit of management not the actual business owners (ie shareholders)
Nowadays it’s the biggest turn off on the market, interest rates , Putin , Covid etc can cope with all those but not jam today management .
The founder of Beeks Financial Cloud (LON:BKS) still has a substantial shareholding and I don't think he's benefitting directly from what you call jam-today management. I presume he's the highest paid director so we know what his salary is. Do you seriously think that with his combination of skills he couldn't walk into a much higher paid job tomorrow? Much more likely he is using options to recruit and retain key people who could also do the same.
Beeks's key strength is their moat around the technology they've developed and the doors that they managed to get their foot into. Doors that don't normally open easily. Cloud adoption has to be managed very carefully when you're moving systems whose failure could get you a slot on the evening news when things go wrong.
I hold.
I’d be pretty certain the founder couldn’t “walk” into a much higher paid job yes .
Not to mention he would destroy his shareholder value and breach a non compete and his market value is higher at Beeks.
Point is in small caps we are at the mercy of management to play fast and loose and to enrich themselves and staff , That’s the point of the red flag raising .
I agree with your point that there are lifestyle companies out there, but Beeks are not one of them.
My point which you neatly side-stepped is he's paying himself a salary well below the market rate for his skill set. Of course I'm pretty sure he wouldn't want to move on as he's put all this effort into building a business. And yes of course he'd benefit if his business was bought out, but this is not a lifestyle company.
Thanks planetx,
I was planning on asking the CEO about the big share options, which have consumed about 80% of the profit (as I said in the main report above). But given your outrage, I will press harder on this point, as if it's putting off investors, then mgt need to be told.
I'll ask the CEO to explain the rationale, and who the options are going to - there is a lot to be said for recruiting & retaining key people using share options, as you can lock them in for several years that way. The risk is, as you suggest, that top management use it as a way to line their own pockets, on top of vast salaries.
Although at BKS, the Directors are paid very low salaries. The CEO in particular will be looking for a major payday when the business is sold, with him owning 37%, that's going to be a whopper probably, so that's where the motivation comes from, not from options, I would suggest.
Thanks for your input, very helpful.
Regards, Paul.
Paul
Thanks for the reply .
I’m not “outraged” but I have hundreds of companies to invest in and I am not going to invest in any company where I am not convinced by management and its motivations .
RBG was another that issued a huge amount of free shares to the FD for just turning up to work .
We naively accept “it’s just the way it is “ which is lazy on our part .
I’m holding a very small selection of stocks now in a much more concentrated portfolio and I think there is a lot of abuse of AIM and smaller companies shareholders but in my few years of investing I now believe it is a very pivotal point .
So it’s an avoid red flag not an outrage red flag .
Dave
Dave,
I fully understand your concerns regarding the substantial erosion of profits at Beeks Financial Cloud (LON:BKS) (I hold) through the issue of stock options to directors/employees. I was very surprised to see the extent of this. The CEO and major shareholder has always seemed to me to be very down to earth and clearly focused, and not one to slip into allowing Beeks to be run as a lifestyle business.
Perhaps an effort is being made to align the interests of key staff (notably recent recruits?) more closely with those of shareholders ... including Gordon McArthur. That might make good business sense ... as long as it does not become entrenched as an annual leaching of shareholder value. We just don't know and, as holders (actual or prospective), we deserve an explanation.
It's not a red flag for me just yet ... but it could soon become one if a convincing justification is not provided.
David.
Beeks Financial Cloud (LON:BKS) - thoroughly informative debate, thank you. I'm a floundering chartist so believe 120 is support/resistance and if can break 190 and hold then maybe start loading up the boat. Me like simples - the SP tells the story - reinforced by the ubiquitous DYOR and the discussion here.
I did log previous buy and sell on stock Folio which is a good historical reference for how I felt a year ago (and kept some notes). Have not kept up the 'work' my bad. Bud have a day job and this game is full time, and I don't mean sitting on the beach with a laptop as youtube adverts would expound, although that would be nice - its a hard grind with a big screen.
Current hot themes are - commodities, energy, defence and mining.
Although UK energy about to be battered by another U turn on windfall taxes. Shell/BP etc are multinational - what are you taxing - getting resources out of a very hard dangerous and expensive place - so the small guys trying to extract from dead finds.
Apparently the Netherlands marshlands has enough gas to replace the Russian supply (hence attack on pipelines I suspect - voldamort is quite clever). But tremors, green lobby, windfarms etc halted such evaporative gold. Sorry strayed off - time to put the wine away.
Something ought to be done about this concern.
Marks Electrical (LON:MRK) - market share gains drive strong sales growth in H1 (new research note from Equity Development) - link to full report here: https://www.equitydevelopment....
Continued and sizeable market share gains drove a 15.1% increase in first half sales for Marks Electrical Group (MRK), particularly impressive in a market that was contracting overall. The company made gains in both Major Domestic Appliances (MDAs) and Consumer Electronics (CE), despite both categories being weak for online business in the period. Moreover, the MRK cash position remains strong, outperforming expectations. These inherent business qualities are not captured in the current share price, in our view, and we reiterate a 150p fair value. MRK is not only comfortably delivering double-digit sales growth but also enjoys significant geographic and category headroom for further expansion. In addition, it operates on a cash positive basis which implies scope for incremental dividend growth as earnings advance. We base our fair value on 1.7x FY2023 sales revenue and 21.5x FY2023 EV/EBITDA.
Morning,
Looks like a good acquisition from K3 Capital (LON:K3C) thus morning, payable from cash and immediately earnings enhancing.
RE K3 Capital (LON:K3C) yes, agreed. I watched the presentation on PiWorld recently and continue to be impressed. They are acquisitive but they also seem to be careful with their acquisitions insofar as they fill gaps in their ambitions and seem to be integrated quickly. A no-nonsense company, as they have to be dealing in the SME territory. No huge budgets there.
There is a positive, though not stunning, update from Sanderson Design (LON:SDG) this morning. Surely this does not justify the large recent fall in the share price.
Sanderson yes rock solid .
Nothing moving up these days but super solid update .
License revenue still strong and licences renewed .
Cash and profits solid
Dollar earner on top .
Sometimes no need to knock it out the park and consistent solid results needed in the next couple years .
"Clotted-cream from the corporate cows". Would that some would choke on it but there you go Mr Contrarian.
Sureserve (LON:SUR), Post Year-End Trading Update in line and looking solid. Shore Capital issued a 11-page doc. on SUR, calling the valuation "compelling" on a P/E for the current year of 8.8. And in the mini budget up to £1.5bn to improve the energy efficiency of around 130,000 social housing and low-income properties in England will help here.
Good Morning Paul,
just wanted to say thank you very much for this in-depth analysis of the Beeks Financial Cloud (LON:BKS) final results. Really appreciated!
Thanks welwichia, I see your post is in line with your user name!! ;-)
Here goes then.... I appreciate many here don't believe in technical analysis but as someone who does, I'd be looking for a better entry price on this one before taking a position, Beeks Financial Cloud (LON:BKS) has recently rejected the 200MA twice. I'd personally be looking for an entry nearer the 90p area.
Can you explain has recently rejected the 200MA twice.What does it really mean? Thank you
I'm no chartist Sady, but 200MA is a line on a share price graph showing the average price over the previous 200 days.
I believe " has recently rejected the 200MA twice" means that the share price has twice failed to break through that line (or if it did it didn't stay above it). If it does break through that would be a good sign to a chartist.
Alternative to watching 'candles', lines, dots etc etc then Stocko does show on the Momentum on the Stockreport.
I don't use this - prefer witchcraft to accountancy - but it should tell the same story.
Price vs.... is all green - which seems to debunk my theory. Let the games begin.
Indeed. Sorry to be Frosty again but I'm not sure that GarryC's style of posting below is doing anything to aid others here into thinking there is merit in TA, however everyone has their own approach to trading / investing and I wish them well.
As I see it, BKS needs to hold the range breakout at the 127p level or further downside is more likely, I personally would be looking for an entry at either of the demand lines shown in chart below, this share appears to have a high Beta as there is significant price volatility so in current market conditions the more conservative entry off the lower demand line would be preferable, which is around the 90p area as stated in initial post.
Apologies for the late response to the posts replying to my initial one - night shift worker here...
You've opened pandoras box asking such mysterious esoteric question.
Stocko has daily weekly monthly options for viewing moving average trends.
This is my daily
The Japanese rice traders would day 'three mountain top' with a 'neckline' about where we are today.
I like round numbers so 175p then DYOR and if happy buy a small position. Maybe load up at 190 if dealing fees ok.
If breaks and holds above 200 then back up the Santa Maria. This is good - it failed to break 200 three times and has settled (support) around 150. This reflects market conditions for growth tech cos.
In this market I 'suggest' the 200ma is too long a timeframe - nobody thinks next week let alone next year.
April 22 the 'third mountain' said the market was done - and so it proved (with history/hindsight - hence the snake oil).
The Big Question is - is there another downgrade from here - apparently the UK market is cheap with the Eagles swooping then leaves the lame ducks for finding food/credit in a future harsh world.
Beeks Financial Cloud (LON:BKS) is not a lame duck and if has good legs then will get snapped up at some point.
But my coffee can is overflowing with such opportunities - hence will put an alert on the 190 through Stocko and if gets hit then revisit and the old DYOR.
@Forsby I can't reproduce that. My go-to charts are Stockcharts.com (I pay a subscription) but they don't cover £BKS. I tried the Stocko charting but it refuses to draw a 200DMA for any sensible length of time, see image below. Putting that to one side, Stocko is showing the price consistently above the 200DMA, so it's support not resistance, which sounds the opposite to what you are saying. Is that right?
Looking at the mobile version of Stockopedia it shows Beeks Financial Cloud (LON:BKS) share price is below the 200MA as Forbsy has stated.
Your chart is showing a 200 week moving average.
Thanks. I am having real trouble getting the Stocko charts to show what I want.
Stocko. charts do show the 200DMA, Beeks Financial Cloud (LON:BKS) is currently below it.