Small Cap Value Report (Wed 10 June 2020) - PMP, QUIZ, RTN, EAH, FLO, CGS, VP, PHTM

Good morning, it's Paul here with the SCVR for Weds. Please see the header above, for the list of companies that I intend to cover today.
Estimated timings - there's loads of interesting news for me to cover today, so I've started at 7am, and will just keep going for as long as needed. There should be plenty of material in this report by the official finish time of 1pm.
Edit at 13:01 - I have to stop now, for an appointment, and to fetch some groceries for Mum. If I manage to finish off the last 3 sections later, then will ask Graham to flag it in tomorrow's report.
.
Portmeirion (LON:PMP)
Share price: 385p
No. shares: 10.64m + x new shares TBC
Market cap: £41.0m (before placing)
Proposed Placing, Subscription & Open Offer
Portmeirion Group PLC, the designer, manufacturer and worldwide distributor of high quality homewares under the Portmeirion, Spode, Royal Worcester, Pimpernel, Wax Lyrical and Nambé brands...
Another day, another fundraising! It's an accelerated book build, which tend to complete very quickly - because the deal is largely done behind closed doors, by the time the announcement comes out. I'll update this section later with the precise details, when the second announcement is published, probably later today.
Key features;
Placing size - raising £10m, so that looks to be about a 25% increase in issued shares.
Price - "not less than 375p" - which is a modest discount, therefore existing shareholders have nothing to complain about.
Subscription - this looks like an additional subscription for new shares, small at £0.66m
Open Offer shares - only £2.0m, which is too small at just 20% of the placing. I think companies should offer more than this, ideally 50%+ of the number of placing shares. I say this because PMP shares are so illiquid, that it would be difficult for anyone but the smallest shareholders to buy more in the open market. More attention needs to be paid to looking after the interests of smaller shareholders. A good recent example of this was Revolution Bars (LON:RBG) (I hold), which did an open offer of 67% of the size of the placing, in order to look after its private investors.
Background - this is a turnaround under new management. Obviously it has suffered reduced sales due to covid, but new management also want to expand the business. In particular, they see opportunities to substantially grow online sales, which I like. See the RNS for more details of growth plans.
My opinion - I used to be keen on this share when it was growing profits, and paying good divis. Performance has waned in recent years, so I'm not madly enthusiastic about it any more. That said, the specific problems which hit recent profits (grey market sales undermining its South Korean market, and manufacturing inefficiencies for new ranges) seem to have been resolved.
FY 12/2020 results are obviously going to be poor, due to covid. It should be able to get back on track in 2021. The move to more online sales is ideal, and a good opportunity - especially if we have a second wave of covid.
This fundraising means that the group is more securely financed. It wasn't bad in the first place, especially as it owns freeholds to its factory and warehouse. Collecting in receivables from retailers and distributors could prove challenging, especially if any of them go bust. This is a generic issue that we should watch out for at many companies.
I saw a presentation from management recently, and my impression is that they're more ambitious for the group, wanting to expand product ranges, sell more online, improve performance in specific countries (e.g. Canada) where there is more opportunity, and develop 3 more major international markets (currently these are UK, USA, and S.Korea).
I don't see this share being a multibagger, but if new mgt execute well, it has the scope to possibly double in price over say 2-3 years, in my opinion. Plus it should be fairly secure, as best selling lines such as Christmas Tree, and Botanic Garden, provide ongoing & reliable sales.
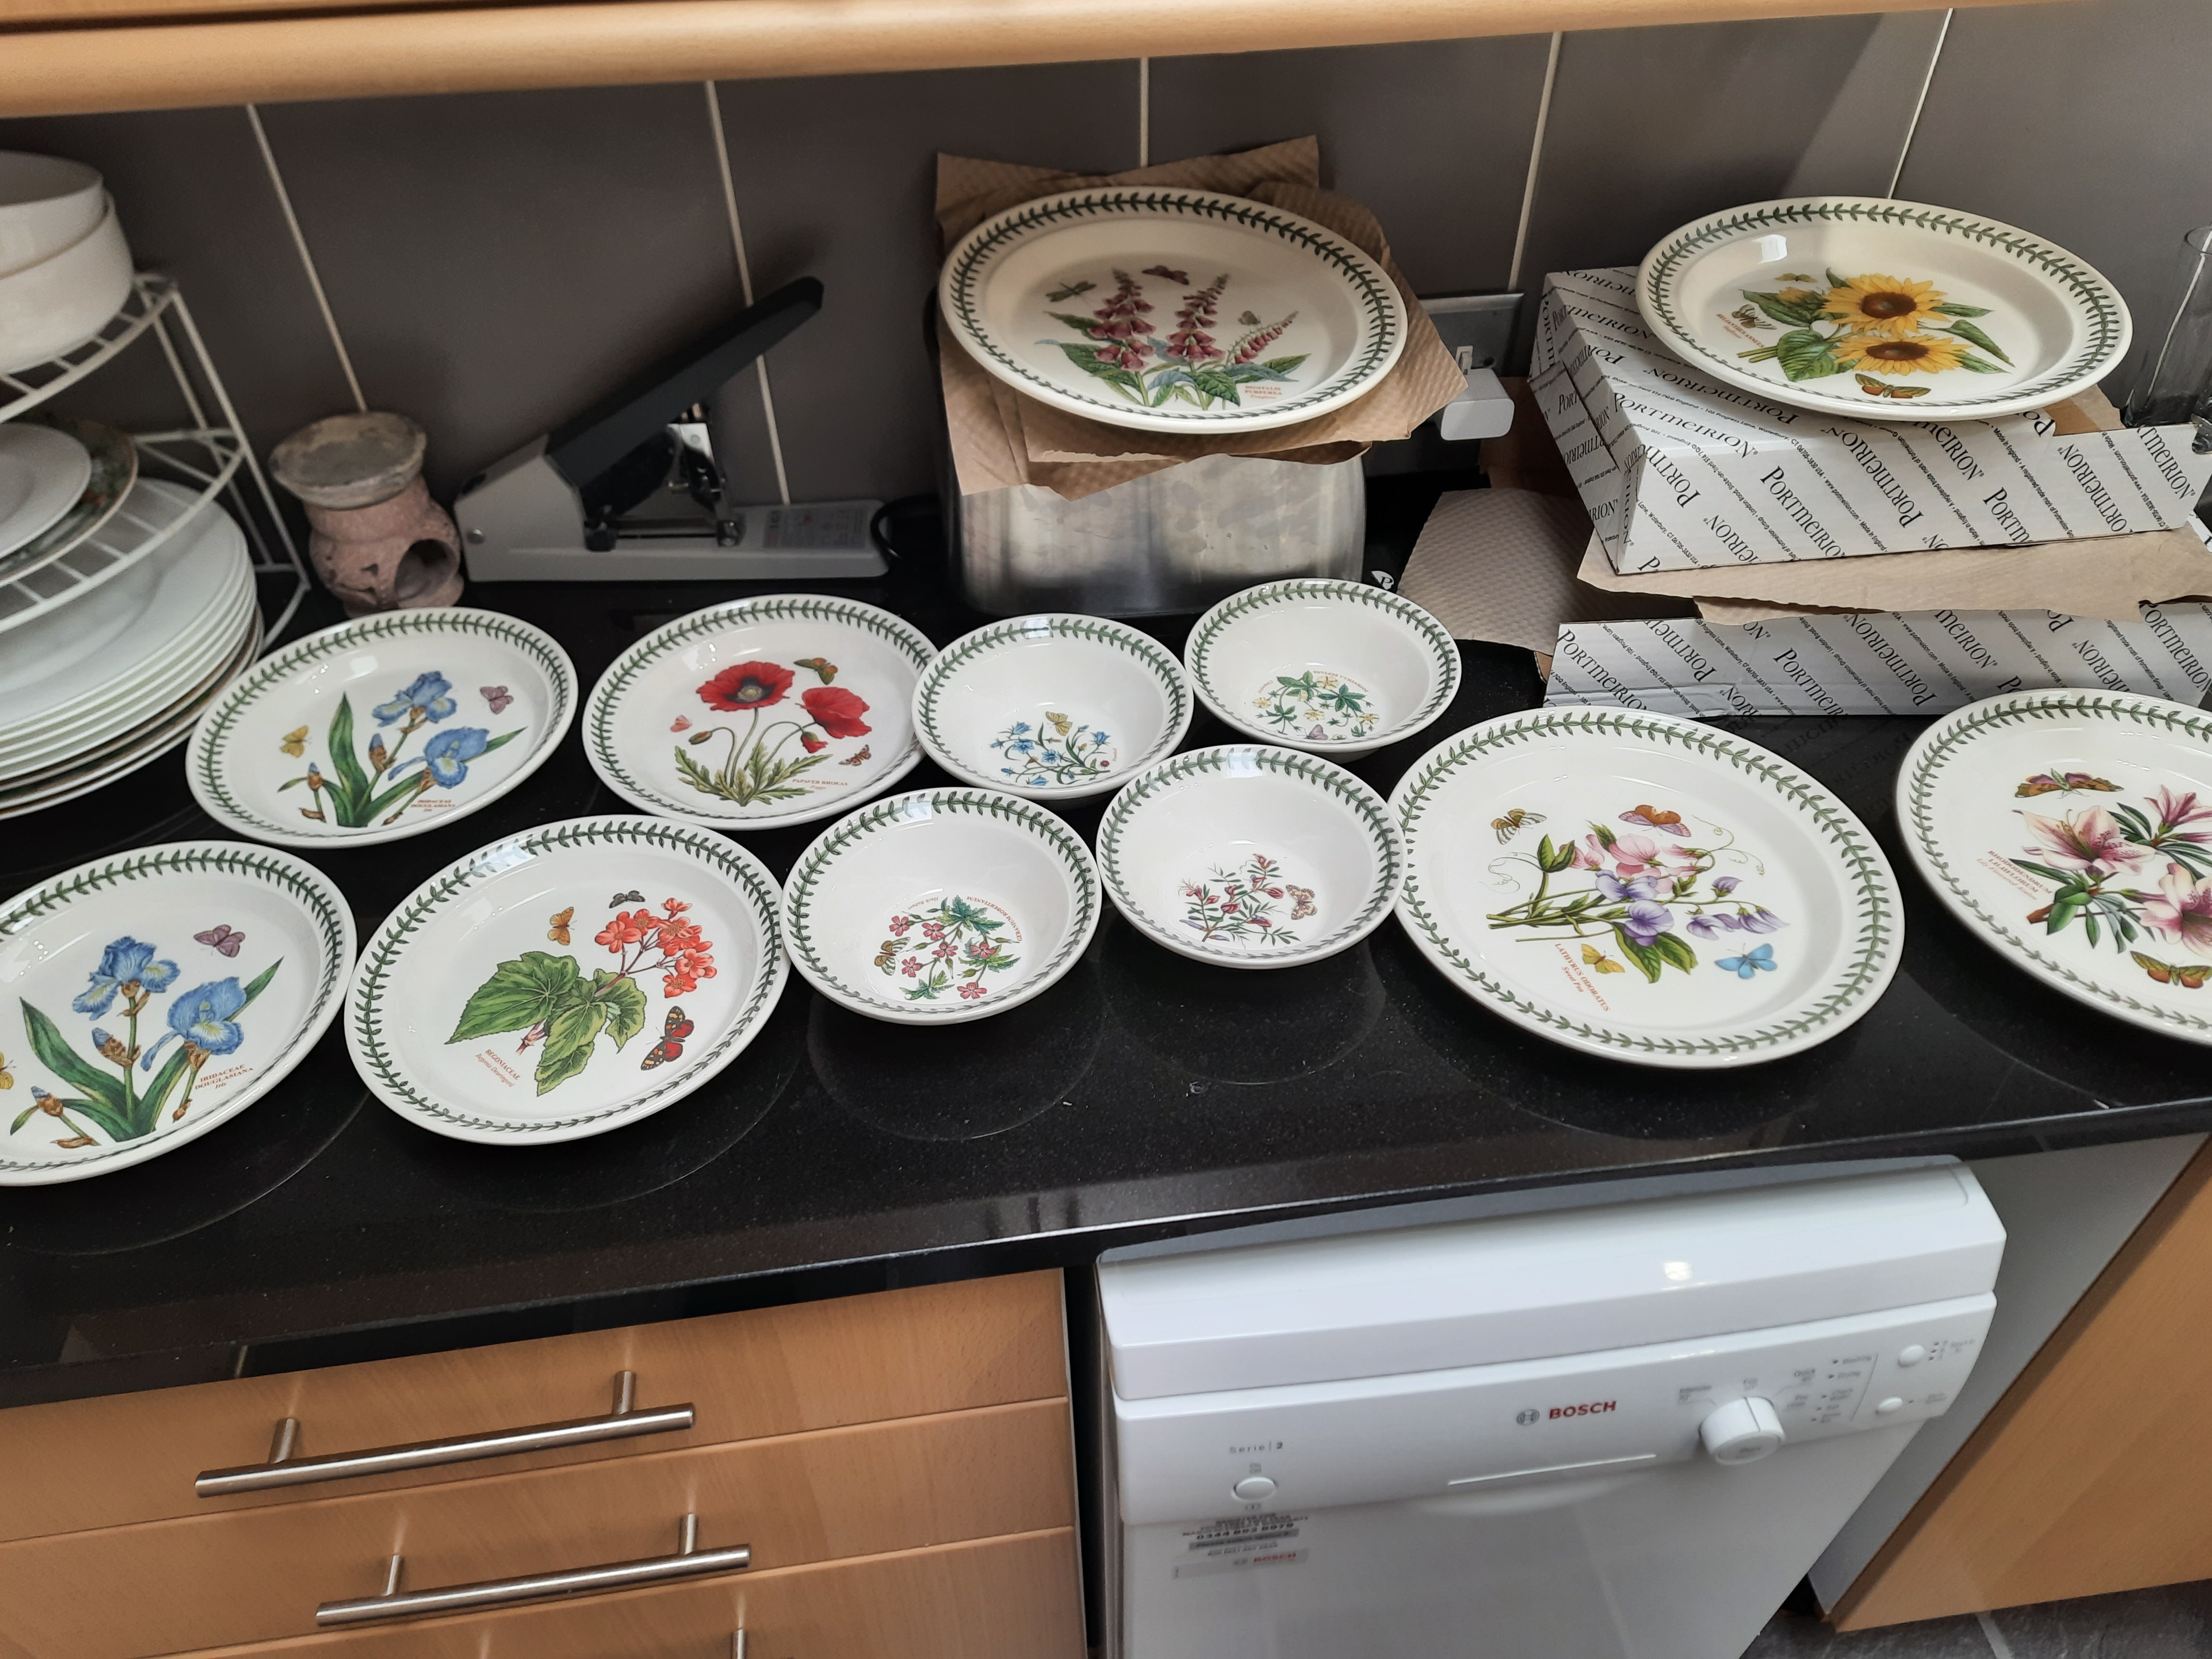
Incidentally, I decided to try out Portmeirion's online offering, and bought a set of Botanic Garden crockery, which arrived earlier this week (see pic below). It's a lot heavier than I imagined - had been expecting a more delicate porcelain type of product, but it's actually quite heavy duty, and looks absolutely lovely. This set cost about £70 all-in, which struck me as good value for a classic, made in England product. Service was excellent - good communications, a quality courier used (DPD) which texted me to give a 1-hour slot for arrival of package, and all was well packed and undamaged on arrival.
With us not being able to dine out, home cooking is back in fashion, so maybe there's an opportunity for PMP to crank up its digital marketing and sell more product online through e.g. Facebook & Instagram ads. I think that's the plan, and it should work in my view. Digital marketing was very much neglected in the past, so there's a wide open goal in that space.
Overall then, I think this is looking an interesting opportunity at 375p per share.
.
Spectra Systems (LON:SPSY)
(I hold)
A quick comment on a disappointing announcement today. A competitor has undercut SPSY on price, for one of its sales pipeline projects, for an Asian central bank.
The share was marked down heavily by the market makers, but is recovering now. A note came out from WH Ireland, saying that this contract was not in the forecasts, which remain unchanged. It also flags >$100m of other pipeline projects, with unquantified additional opportunities building.
Therefore, I'm fairly relaxed about this, and happy to continue holding. The last results were very good, and are worth a look.
.
Quiz (LON:QUIZ)
Share price: 8.4p (up c.30% today, at 08:40)
No. shares: 124.2m
Market cap: £10.4m
Proposed restructuring of standalone retail store portfolio (pre-pack administration)
In order to protect the future for QUIZ, the omni-channel fast-fashion brand, the Board of the Company announces that it is proposing to restructure its standalone retail store portfolio.
This is an important announcement, and I suspect we'll see lots of retailers & leisure companies use the pre-pack administration or CVA insolvency processes to restructure, and ditch their over-rented sites. There's a CVA announced today from RTN - which I'll cover below later.
Quiz has 82 standalone stores, which are loss-making. Using a controversial (and surprisingly, it's legal) process, the subsidiary company which operates the stores is being put into administration. Shortly afterwards, the parent company buys up the assets (but none of the liabilities) for a price of £1.3m that has been agreed with the administrator. The creditors are shafted, and all the property leases terminate.
Quiz is then free to cherry pick the sites it wants to keep open (only the profitable ones), and can re-negotiate property terms with all the landlords. In the current situation, landlords don't want empty units, so they're likely to agree to any reasonable terms. This very much puts Quiz in the driving seat, and enables it to eliminate all loss-making shops, plus slash the rent bills on any shops it wants to keep. It very much gives Quiz an unfair advantage over other retailers that are soldiering on paying unaffordable rents.
I don't see any alternative to many other companies following suit with pre-pack administrations. Trade creditors and landlords bear the pain, as they end up with bad debts. On the upside, pre-packs are effective at preserving the maximum number of jobs. In this case it sounds like most employees (822 out of 915) are being retained. This implies that Quiz thinks it can do deals with landlords of most of the shops. I reckon it could even end up trading rent-free from some of them - after all, for the landlord the alternative is an empty unit.
It sounds as if the 3 Spanish stores are being ditched too.
Financial position - after this deal is done, Quiz will still have £5.9m cash, plus (unused) bank facility of £1.75m. It is in talks to arrange a longer term bank facility (currently expires 31 July 2020). Therefore it looks to have enough cash to be able to re-open and continue trading. Although getting supplies in will be a challenge, having just stuffed its suppliers with bad debts.
Outlook - sounds alright;
The Board believes that the proposed restructuring announced today will enable the Group to operate an economically viable store portfolio alongside its online, UK concession and international channels which are unaffected by today's announcement. The Group continues to believe that stores, with appropriate property costs and flexible lease terms, can be a relevant pillar in QUIZ's omni-channel model moving forward.
My opinion - this is a game-changer. By ditching loss-making stores, and renegotiating rents on every shop, Quiz should be able to move into profits again, once stores re-open. Moreover, I imagine mgt is likely to focus on only signing short term lease deals, push for turnover rents, and long rent-free periods. This is the ideal time to do such a pre-pack administration. It leaves behind a trail of destruction, with landlords & suppliers stuffed with bad debts.
For shareholders however, this is excellent news, and opens the door to a much more profitable company emerging. For that reason, I think Quiz is worth a fresh look after this key news. Risk:reward has just drastically improved for shareholders. That said, it wasn't a very good business to start with, and this is the second time it's had to go through insolvency procedures. In both cases this was caused by uneconomic leases.
.
Restaurant (LON:RTN)
Share price: 70p (down 1% today, at 10:09)
No. shares: 589.8m
Market cap: £412.9m
Launch of the CVA for the Leisure estate
This is a large restaurant chain, including Frankie & Bennys, and it recently bought Wagamama.
We already knew a restructuring was on the cards. On Monday this week, the company said;
In order to meet both the immediate challenges and to build a post-lockdown business with a sustainable future, we are in discussions with our landlords regarding potential restructuring options for our Leisure estate. Our Wagamama, Airport Concessions and Pub operations are not affected by these discussions. [from RNS dated 8 June 2020]
Today it announces a CVA - a form of insolvency where only landlords take a hit, but on an agreed basis (they negotiate, then vote on it). Other creditors are unaffected, and the business continues trading.
My summary of main points;
- Sites affected are mainly Frankie & Benny's format
- Closing 125 sites, with 160 sites remaining - hence a big reduction, of 44% in site numbers
- Improved rental terms on 85 sites of remaining estate
- Exit from lease liabilities of 25 previously closed sites
- Other creditors (e.g. trade creditors, HMRC, and employees) not affected
- Chance of success probably boosted by consultation with British Property Federation
My opinion - no particular view either way. If the CVA is agreed by landlords, then it gives RTN a springboard to operate profitably in future, if covid is brought under control, and we get back to something like normality.
My main concern is that the Frankie & Benny's format is pretty rubbish really. We've been discussing that here for years - it's a tired format, even before covid struck. The fact that so many sites are being closed, instead of having a rent reduction, reinforces my view that this is a brand that has had its day.
Often a drastic CVA like this provides temporary breathing space, but companies often end up in trouble again, further down the road. It doesn't interest me at 70p, when we still have substantial uncertainty about what the future holds. I want really bombed out valuations, with multibagger potential upside, to take this level of risk.
.
Eco Animal Health (LON:EAH)
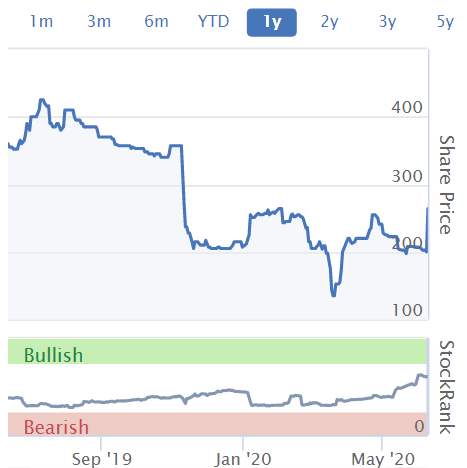
Share price: 254p (up 27% today, at 10:26)
No. shares: 67.5m
Market cap: £171.5m
This company sells pharmaceutical products for animals.
I can't remember much about it. Although I did buy a few for my portfolio at some point last year, on recovery hopes, but must have chucked them out at some point. Today's update reads very well, hence the 27% share price rise.
Key points;
- Strong performance for FY 03/2020 - revenues & EBITDA "significantly ahead" of mkt exps.
- Strong sales & higher margins in H2
- Covid - limited impact to date
- Strong start to FY 03/2021, esp USA & China
- Conserving cash - due to "considerable uncertainty" in macro picture, hence divi suspended
- Ongoing product development, but reduced R&D in H1
- Order book - "good support" for H1 revenues
- Net cash £9.9m at 31 Mar 2020 (note that more than half is held in China)
Valuation - I can't find any broker notes. Stockopedia shows broker consensus of 6.2p EPS for FY 03/2020. Assuming that the "significantly ahead" EBITDA flows through to EPS, then what does that mean? Maybe 7-8p EPS at a guess? At 254p, the PER woulkd then be 32-36 - hardly a bargain. Although that year does include the H1 impact from Asian Swine Flu. Previous years seem to show EPS in the teens. A return to that, would bring the PER down to a more reasonable level.
My opinion - no particular view either way. It's good to see guidance from the company (about an improving H2) come true. Therefore management credibility is high.
.
.
Flowtech Fluidpower (LON:FLO)
Share price: 76.5p (up c.3% today, at 11:47)
No. shares: 61.5m
Market cap: £47.0m
Trading update (AGM)
Flowtech Fluidpower plc (AIM: FLO), the leading specialist supplier of technical fluid power components and services, releases the following statement ahead of its Annual General Meeting....
This is a perfect announcement! All completely self-explanatory, as follows;
Prior to the impact of Covid-19 the business had been performing marginally ahead of our expectations in 2020.
The last part of March and the whole of April saw our Revenues reduce by approximately 40%.
The impact was approximately 30% in May and we are confident this improving trend will continue.
The cost reduction measures we had already taken, and those we took due to the outbreak, have led to an approximate adjusted EBITDA breakeven position in April and May.
We now look forward to a return to profitable trading as conditions improve. Our cash position remains good; we continue to operate with significant headroom to our aggregate £25m banking facilities.
.
My opinion - very well done to FLO and its advisers, for providing us with clear information about how the company is actually trading. EBITDA breakeven in the bad times, means it should be fine, and able to move back into profit once recovery is more underway. Remember the housebuilders ceased operations for a brief period, and are now cranking back up again, as are other sectors.
Overall, there's probably medium-term upside on the share price, although it's not really something I'd particularly want to own.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

35 comments
Re: Eco Animal Health (LON:EAH)
Bought some recently after spotting it on a value screen. It’s core product is an advanced antibiotic for use in pigs and poultry. It has a very wide moat in a similar way to a blockbuster human drug with a massive addressable market. The SP has been hammered due to epidemics of African Swine Flu but I believed its sales would recover because globally people will still find a way to raise and eat similar quantities of pork & chicken.
The company’s main weakness is the over reliance on one product (which may be superseded by a rival alternative one day). It is trying to develop animal vaccines to widen the product range but success not guaranteed at present. Sales of the antibiotic are growing as it continues to win regulatory approvals in new countries.
Another odd aspect of the antibiotic sales is that the pricing (and therefore profit margin) varies according to meat prices. The company’s performance is geared to pork and poultry prices.
Re: Portmeirion (LON:PMP)
Placing size - raising £10m, so that looks to be about a 25% increase in issued shares.
Price - "not less than 375p" - which is a modest discount, therefore existing shareholders have nothing to complain about.
Subscription - this looks like an additional subscription for new shares, small at £0.66m
Open Offer shares - only £2.0m, which is too small at just 20% of the placing.
So it turns out the placing price was 380p and the open offer is 2 shares for every 41 held.
https://www.investegate.co.uk/portmeirion-group--pmp-/rns/results-of-placing-and-notice-of-general-meeting/202006101334515664P/
I agree with Paul. A 2 for 41 offer is a complete joke and almost a case of why bother - come results you'll likely be able to add below the 380p placing price.
Personally, I am more interested in the situation at Churchill China (LON:CHH) which is a higher quality operator but with high exposure to the hospitality industry. Rock solid balance sheet and good management but obviously a highly contrarian idea...
All the best, Si
Hello Si,
Thanks for filling in the gaps re the Portmeirion (LON:PMP) placing. I've been out all afternoon, so away from my screen & keyboard.
I think Churchill China (LON:CHH) and Portmeirion (LON:PMP) are very different businesses. CHH is focused on supplying restaurants & hotels with crockery. Whereas PMP is mainly about collectable, semi-ornamental special occasion crockery (plus diversification into candles, etc.
In the current situation, I'd rather back PMP's prospects, than CHH. Because PMP doesn't depend on the hospitality sector to buy its products, whereas CHH very much does.
Regards, Paul.
In the current situation, I'd rather back PMP's prospects, than CHH. Because PMP doesn't depend on the hospitality sector to buy its products, whereas CHH very much does.
Yes, and Portmeirion (LON:PMP) has an on-line retail presence which Churchill China (LON:CHH) does not if you are looking only at the short-term. I am just looking at a potential longer term holding, although Churchill China (LON:CHH) is more exposed to Europe, so a potential no deal Brexit is still a consideration. It's not cheap enough yet but is on my watchlist of beaten down quality companies. Let's see what they have to say in the AGM statement tomorrow.
All the best, Si
I recently mentioned Metro Bank (LON:MTRO) as a short squeeze with 9 per cent short holding. Up today on heavy volume. Bid rumours are never far away from this challenger bank. Maybe of some interest on what seems to be a rather quiet day (disclosure; I hold).
Agreed MTRO does look v interesting (As far as banks go) I bought a good few after they collapsed to 70p a month or two ago. thinking risk/reward looked good.
Not that this needs to be said -but enjoy your birthday when it comes along Paul
Tr Property Investment Trust (LON:TRY) video or podcast of yesterday's excellent presentation (piworld webinar) by Marcus Phayre-Mudge. Marcus gives a good overview of the fund. (4% yield. 9% discount to NAV.) Further, an insight to commercial property during CV19. Recommended listening.
Separately, don't miss Robin Griffiths, guest on tomorrow's piworld Thursday webinar, 11.6.20, 1pm. Robin will give his macro overview, and what that means for markets. Get Robin's view on where best to invest. Robin's highly experienced, bio on link, he uses technical analysis, economic modelling and algorithms, to reach interesting conclusions, published in an (expensive) newsletter. Glean a lot of his thinking, for free, tomorrow. Register here.
Happy birthday for tomorrow Paul
Thanks Tony! One year closer to death!!!
In a way, not really. As you've managed to get this far your remaining life expectancy increases a little each year (if that makes any sense).
So at 51 you "should" live to 81.25 years whereas at 52 you should live an "extra" 36 days"
Keep going and you could cheat it until you're well past 100.
Scary isn't it?
Have a good one Paul - unfortunately there are no hostelries open in this country in which to celebrate.
Lifestyle factors probably more of an issue. e.g. more than 21 units of alcohol a week
"Lifestyle factors probably more of an issue. e.g. more than 21 units of alcohol a week"
What are you trying to say?? ;)
Re: Spectra Systems
The share was marked down heavily by the market makers, but is recovering now.
I laughed and cried in equal measure watching the open today. Whoever hadn't done their homework and panicked got a rotten deal. Properly ripped off. I hope it wasn't anyone here.
Though obviously disappointing to lose the bid I was actually impressed with the decision by management. I know how this feels because I work in a similar line of business and where someone is totally price driven (almost always the case in my experience with Asian based customers) rather than quality driven, and where you clearly have the best technical solution, you have to maintain price discipline and margins. It could also be that the other bidder is desperate for the work and doing it at, or below, cost. In these cases it's best to just move on - good luck to them!
All the best, Si
Indeed, Si! As John Ruskin never wrote:
There is almost nothing in the world that some man cannot make a little worse and sell a little more cheaply - and those who consider price alone are this man's lawful prey.
Jack Brumby has just posted an excellent article on gold miners.
I think an ETF like I shares gold producers is simplest, cheapest way to do this. Interesting podcast by Preston Pysh - We study billionaires - says that in Gold terms the US market is down 16% this year.
Restaurant (LON:RTN)
In general I agree, we have seen it a good few times before.
However in this case (assuming one trusts the management's competence) I think there is reason to believe this is not the case.
They are closing over half of their F&B's that's a pretty major axing. It would surely have been much simpler (and 'cheaper'?) to have closed the whole brand, therefore you would assume that they have done some pretty rigorous work to ensure the remaining branches are viable.
Like Paul though I am not interested in doing any more research at the current price.
Just from an overly simplistic relative valuation perspective the share price is only c. 50% below it's pre crisis levels :
I might be interested in looking if the price were somewhat more bombed out or at a similar price a few months out when the outlook will perhaps be clearer.
Moodys downgrade or about to, Wagamama. About the only thing worth buying it for. Once management realised they were not going to be able to roll out expansion of that brand across the globe, that was pretty much game over for me. Now it appears to be a damage limitation exercise.
Nice synopsis!
Does anyone have any thoughts on Ao World (LON:AO.) appreciate this outside of the remit here, but the valuation looks way to high. I get the fact there last statement looked promising as most people are forced to buy online at the minute which has played into their hands very well.
Quick NAV calculation comes in around £38m. Its been loss making for years with a net debt of £82m, Receivables have also doubled to £112m, not sure this can all be account for with their increased sales?
Not willing to short it whilst the market is so strong, but be interesting to watch where this settles.
Ao World (LON:AO.) I also think is way too high, up 60% YTD. It may well have seen strong sales due to lockdown but has no history of showing operating leverage. UK operating margin was 2.5% in FY16 on revenue of £500m and 2.0% in FY20 on almost £900m of revenue. Europe made a bigger loss in FY20 on €150m of revenue than in FY16 on €40m of revenue. The shares bounced 50% on in line H1 results last year only to drift back over the next couple of months. Difficult market to be short anything but at £700m market I am short AO.
I agree. Ao World (LON:AO.) looks a pretty rubbish business, on a sky-high rating.
sales is vanity, profit is sanity. AO has lots of the former and little of the latter (although same applies to the retail part of Amazon). Probably quite a few investors have had a telly or fridge delivered by them recently and pleased with the service. Profit margins are tiny however.
(Tandem (LON:TND)) TANDEM's RNS this morning intrigued me.
"Tandem Group plc (AIM: TND), designers, developers, distributors and retailers of sports, leisure and mobility equipment, announces that a statement is tomorrow being posted by the Company to shareholders from one of its shareholders as permitted under the Company's articles of association, in relation to certain AGM resolutions."
Does anyone have a clue what this might allude to ?
if you are registered on ADVFN the letter is posted in full. On the TND thread. Something to do with board pay being higher than is allowed, and company refusing to acknowledge or deal with the problem. Not sure if copy/pasting the letter here is allowed
There's quite a strong grouping of activist private investors in Tandem & they're looking to push the board to take a make pro-shareholder stance (as opposed to the present pro-board stance!) when running the company. I suspect this is an example of them holding the company to account over their current behaviour.
if you can access ADVFN and the TND bulletin board, the author of the letter has posted it, assuming that it's the genuine article.
ECO Animal Health (LON:EAH)
I hold this runty type share in my portfolio (lesson here don't but what i buy) , another company that has failed to deliver on the future expactations as laid out by their broker at the time i purchased my shares.
Is the news today of the best kind of tubthumping update where they have beat expectations for the year ref profits and EBITDA and have started the new year in similar a strong fashion?
Errrr - actually that rather does appear to be the case here rather puzzingly with these present times.
Overall Group revenue for the year ended 31 March 2020 is expected to be ahead of the restated revenue for the year ended 31 March 2019 and significantly ahead of market expectations.
ECO has started the new financial year strongly. The strength seen in the Chinese and US markets at the end of the year ended 31 March 2020 has continued into the first two months of the current financial year. This is also reflected in order books which provide good support for first half revenues.
They do have covid related concerns though that make them cautious on outlook and rightly so.
I would love to say job well done to mangement here but the Chumbawamba reference is very apt - as the improvement today is from a level where we really have been knocked down and out previously - current profits are probably only 50% of peak years - and this was meant to be a growth story stock when i bought !. So this update alone won't be enough to do anything but make back some of the profits they had lost over the last couple of years.
Lets hope that in the end that Tubthumping song sums up the whole covid situation - specifically i want to get down the pub and have a Whiskey drink a Vodka drink a Lager drink and a Cider drink. Shame it doesn't come in time for my 50th party this weekend where i am forced to choose who my 3 proper friends are and will make do with a measly 5 litre keg of toffee chocolate porter - luckily the task of inviting friend to parties gets easier as you get older as we tend to have less :)
Happy 50th this weekend. Thoroughly enjoyed your diatribes (learn and laugh is always a good combo). May I politely suggest that the reason you have less friends is that you write so well and fluently - it makes others jealous as a rule!
Happy birthday and thank you both for making me smile and for your perspicacity in putting announcements in to context - from a soon to be 49 year old.
Portmeirion (LON:PMP)
I hold this runty type share in my portfolio, another company raising funds when the shareprice is probably at its low point.
Note per the news below directors have agreed to stump up £0.66 million - thats a commendable effort if we presume they can add up and havent got their decimal points in the wrong place !
Unfortunately my maths doesnt add up to £0.66 million based on the associated numbers provided so i suspect embarrisngly for them its them that can't add up and not me - my maths suggests its £0.07 million - probably less than the cost of their annual ski-ising holiday each. Apologies in advance for querying the board if i can;t add up.
Concurrent with the Placing, certain directors and a member of the Company's senior management team, along with certain other existing Shareholders have agreed to subscribe for an aggregate amount of approximately £0.66 million at the Issue Price pursuant to the Subscription.
Looks like dilution is 25% - fair play to the company in that they have outlined specific areas where funds will be invested and the reasons all seem reasonable other than the last one.
accelerate all online channel sales growth and increase next day delivery warehouse capacity;· extend the Wax Lyrical line to hand and body products;· build a more significant presence in Canada and revitalise the Canadian market;· invest in UK manufacturing efficiencies driving improved operating margins; and maintain a strong balance sheet.
correct me if i am wrong but a well run company with a sound balance sheet making decent profit for many years shouldnt need to raise its sharecount by 25% just for some minimal "ongoing" investment like this. If you need to raise funds at over a 5 year year low point with regard to sharepice that suggests you don't have a strong balance sheet. I am not convinced they will have a stong balance sheet afterwards unless spend funds generate extra profits the word "maintain" should not have been included. In their defence they have the covid related exceptional excuse that is similar to a football manager blaming the rfef when his star striker can't hit the back of the net - not a dig at Joelinton - he has started banging in the goals now he is back in training.
I will continue to hold and probably pick up some entitlement in the belief this company may at some stage partly regain former glories - all i know if my extra semi forced purchase will be less of bad investment than my purchase over 900p unless its a complete wipe out - probably like being a 100 year Porsmouth fan remembering the days when your team won back to back league titals - never to be repeated (we all know only the big 6 and saudi backed teams can win the league right ? - unless your team name begins with an L)
Botanic Garden sells for a good price on Ebay as the patterns are calming and the china sturdy.
My morning smallcap tweet: Photo-Me looking ugly
Photo-Me International (LON:PHTM) Gulf Marine Services (LON:GMS) QUIZ (LON:QUIZ) Hornby (LON:HRN) Portmeirion (LON:PMP) Orchard Funding (LON:ORCH) ECO Animal Health (LON:EAH) XLMedia (LON:XLM) Flowtech Fluidpower (LON:FLO) Spectra Systems (LON:SPSY) Panoply Holdings (LON:TPX) Boku Inc (LON:BOKU), Ergomed (LON:ERGO)
Photo-Me (PHTM) guides FY(Apr) rev down 5.5%, adj pretax £28m (£42.6m), ex restructure costs & writedowns of £14-18m.. Plans restructure of UK, China and South Korea businesses. Cash at hand £66.5m. Believes has "sufficient liquidity available and anticipates it will continue to operate within its banking covenants, subject to a modest improvement in trading conditions over the coming months."
Gulf Marine Services (GMS) banks sign new debt structure as mooted in March.
Quiz (QUIZ) putting UK & Ireland store co into admin and group will buy it for £1.3m. Will retain 90% of jobs. Believes prepack will enable group to operate an economically viable store portfolio alongside its online, UK concession and international channels.
Hornby (HRN) celebrates 100th anniversary of the 1st Hornby locomotive.
Portmeirion (PMP) £10m placing + OO at at least 375p, a 2.5% disc, to accelerate its growth strategy and margin improvement.
Orchard Funding (ORCH) FY(July) lending expected to be below market expectations but earnings higher because certain costs associated with the banking licence application have been deferred.
Eco Animal Health (EAH) guides FY(Mar) rev & EBITDA significantly ahead of market expectations and up YoY. Gross margins have improved through H2. Current trading strong.
XLMedia (XLM) to dispose of the majority of its Finnish-facing Casino assets, along with certain other publishing sites, in line with strategy of 'refining' (LOL) its publishing portfolio and refocusing on regulated and high-potential markets.
Flowtech Fluidpower (FLO) AGM stmt. Rev down 30% in May, from 40% in Apr. Adj EBITDA roughly breakeven in April and May.
Spectra Systems (SPSY) has been underbid for a five year Asian central bank contract for the supply of taggants and sensors. Winner's price was 50% less than the incumbent's pricing. I hold.
Panoply (TPX) buys Arthurly, a technology services business with particular strength in the Microsoft Technology Stack, for £412k. Expected to be immediately margin and earning enhancing to subsidiary Notbinary.
Boku (BOKU) string trading in lockdown with existing merchants benefiting from increased demand for home entertainment. Total Payment Volumes up 35% in 5 months to May
In line: Ergomed (LON:ERGO)
Also Restaurant (LON:RTN) to close 125 of 210 of its dismal Frankie and Bennys in a prepack.
Flowtech trading drop in April and May reflects comments I've heard from a number of B2B facilities management/technical support type businesses recently. The hope is this trend will continue as more of the economy reopens. However B2C, especially for services requiring access to homes, are still on the floor. Is the recovery in share prices generally getting ahead of what will be delivered this year and maybe even next?