Small Cap Value Report (Wed 11 May 2022) - BOTB, DTY, HSW, VTU, TENG, ANX, CTO

Good morning, it's Paul & Jack here with our usual daily review of company news. We've done some shorter sections, to cover more companies, see the agenda below. Today's report is now finished.
Agenda -
Paul's Section:
Best Of The Best (LON:BOTB) (I hold) - a reassuring update for FY 4/2022, with revenues as expected, and profits "slightly ahead" of expectations. With trading now apparently stabilised, after a large drop in previous expectations, the PER of 10 is looking good value again.
Vertu Motors (LON:VTU) (I hold) - stellar results for FY 2/2022, from this well-managed chain of car dealers. The bonanza, fuelled by high used car prices, is continuing. Valuation is strikingly cheap, even if future earnings drop right down again. The balance sheet is chock full of freehold property, and shares trade at about a 20% discount to NTAV - this doesn't make any sense to me. Strikingly cheap.
Quickies (no sections below in main article) -
Ten Lifestyle (LON:TENG) - £50m market cap (up 1% to 60p today) - I’ve had a quick skim of the interim results from this corporate concierge service provider. It’s still loss-making, and the weak balance sheet (negative NTAV) doesn’t provide much comfort. The company is hoping for improved business as travel resumes. It’s made losses every year, quite heavy in some years, since listing in 2017, so for me the business model is unproven - not an attractive investment proposition, especially when we’re in a bear market. So not one for me. [No section below]
Anexo (LON:ANX) - £150m market cap (up 3% today to 126p at 12:22) - this is a credit car hire (re accidents) and other claims business (e.g. dieselgate claims). Fabulous profits reported today for FY 12/2021, very low PER. But there's a catch - the profits are not turning into cash, in fact cashflow was negative, because all the profits are going into increased receivables. Receivables are a staggering £188m, on £118m revenues. This looks a lot like Quindell, for those of you who remember how that booked huge profits, but ran out of cash because it couldn't collect in its payments. Accident Exchange was another one further back, that also sank under the weight of non-payment of receivables. Bank debt is also high. I wouldn't go anywhere near this share for these reasons. It's on my "avoid" list. [No section below]
Tclarke (LON:CTO) - £66m market cap (up 3% today to 149p) - a strikingly positive trading update for FY 12/2022 to date. "Very confident" in meeting market expectations for the full year (helpfully guidance of 21p EPS is given), so that could turn into a beat maybe? Record order book of £585m, with a third being data centre installations. My view - this is a low margin contractor, doing large & complex electrical/IT installations. Hence it should be on a low PER, due to high risks. If you think a recession is coming, then this is a risky sector to get involved in, because historically orders have dried up (look at what happened to the share price in 2008 for example). That said, current trading & outlook sound really good. So if you're not expecting an economic downturn, then it might be worth considering.
Jack's section:
Dignity (LON:DTY) - the group says it has gained market share but revenue and profits are down considerably. New industry regulation is incoming and the group needs to sort out its capital structure. Against that backdrop, a fall in average revenue per funeral and the number of deaths is a worry. The turnaround could work out, but for now there is too much risk in my view.
Hostelworld (LON:HSW) - an industry-wide recovery in travel bodes well in the short term for Hostelworld, which managed to scrape through lockdowns with c20% equity dilution. It was a dangerous period though, and cash burn was a real threat. If all goes well then the stock could recover from these levels, but I’m unsure of the longer term prospects.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul’s Section:
Best Of The Best (LON:BOTB) (I hold)
400p (pre market open)
Market cap £38m
Best of the Best PLC (LSE: BOTB), the provider of online competitions to win cars and other prizes, is pleased to provide the following trading update for the 12 months ended 30 April 2022 (the "Period").
Trading seems to have stabilised, after an intensely disappointing performance over the last year -
The Company reports that its revenue performance for the Period has been consistent with the market guidance issued at the time of its interim results on 19 January 2022, with pre-tax profits slightly ahead.
This was one of my top performing shares over quite a few years, but everything went horribly wrong, once it became clear that booming trading during the pandemic wasn’t sustainable. Or rather, that’s only half the story. As you can see from graph 1 below, revenues actually have settled at about double the pre-pandemic level, so a lot of the growth has actually been retained. The bigger problem was that online marketing costs went through the roof, thus meaning that BOTB was forced to cut back on new player recruitment, which it needs to replace customer churn.

This dependence on online marketing was a hidden flaw in the business model, which nobody seemed to spot in advance (I certainly didn’t). BOTB became heavily dependent on Facebook ads, and then those ad prices went sky high. That’s probably due to a number of new competitors entering BOTB’s space, some of whom have deep pocketed backers such as venture capital or private equity, e.g. Omaze.
As you can see above, this squeeze in online marketing caused a large fall in profitability from the pandemic boom year, as the operational gearing worked in reverse (since incremental ticket sales are mostly additional profit). Again, many investors (including me) just focused on the upside from the operational gearing when the company was growing, and forgot to take account of the risk of profits plunging if sales went into reverse, so another lesson learned there to always think about downside scenarios before they happen!
Listening to management too much was another mistake I made here. They were unrelentingly bullish about the company, apparently not realising that they were getting a one-off boost from the pandemic. Although they did have the foresight to bank £60m with Director sales at £24 per share in April 2021. The price is now £4 per share, so I bet the buyers are thrilled with that deal!! Lesson here is perhaps focus on what Directors do, rather than what they say!
My opinion - you might be wondering why I held on to my shares after a series of brutal profit warnings? It’s mainly down to valuation. My view is that management is very experienced in this niche, and they should find a way to adjust the marketing spending to improve effectiveness. Therefore profitability should rebuild, but maybe not to the pandemic peak of 122p EPS.
FY 4/2022 looks to be around 40p EPS, based on broker forecast, and confirmation from the company today that it’s slightly ahead. That means we’re on a PER of just 10. With trading now apparently stabilised, I think that’s good value. Hence I’ve got a target of maybe £6-8 per share, where I’d possibly look at exiting.
That said, BOTB could be worth holding long-term, because historically it’s been a nice cash cow, paying generous special divis with surplus cash. The business model is capital-light, so profit readily turns into distributable cash.
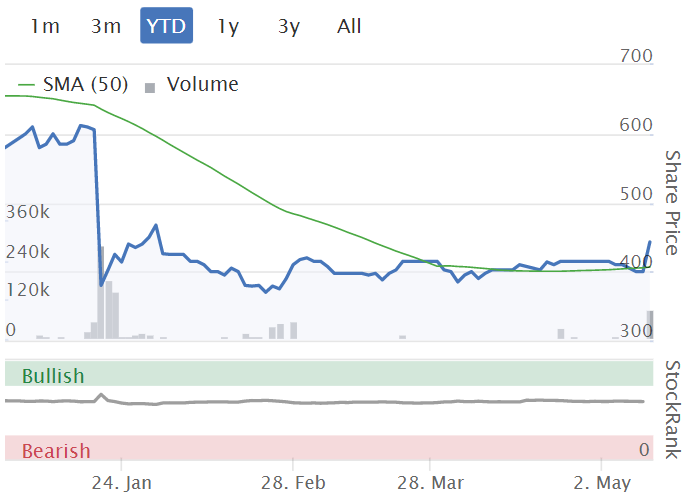
The 400p level seems to have become a floor this year, despite most other small caps crashing this year, BOTB has held firm at 400p. Therefore we might have seen a bottom, possibly? Shares are tightly held, and not very liquid, so when there’s good or bad news, the share price reaction can be rapid & large.
Overall, I think my strategy of sitting tight and waiting for recovery looks to be the right one here, judging by today’s brief update.
We probably won't see a big re-rating of the shares until the squeeze on disposable incomes is over, as having a flutter in a supercar competition is very much discretionary. Although people keep buying lottery tickets and find money for cigarettes when they're poor, so maybe dreaming of winning something might be an outlet for people, regardless of their disposable income?
.
Vertu Motors (LON:VTU) (I hold)
50.5p (up 5% at 09:09)
Market cap £181m
Vertu Motors, the UK automotive retailer with a network of 160 sales and aftersales outlets, announces its final results for the year ended 28 February 2022 ("Year").
"Gaining market share and investing in brand and technology"
The table below shows what a staggeringly successful year VTU has had, driven mainly by an unprecedented surge in profit margins for used vehicles, due to supply shortages. The whole sector is having a bonanza, as we’ve known for a while. Apart from hapless Cazoo, which using a “disruptive” (i.e. suicidal) business model, which managed to generate a loss of £549m on revenues of £668m recently reported!
Disrupters - VTU’s CEO has previously been dismissive of the wave of new entrants trying to disrupt the used car market, saying that their only advantage is their huge marketing budgets. Once that cash has been blown, I suspect a lot of the new entrants advertising on our TVs all the time now probably won’t be around in a few years’ time. Maybe TV’s Rylan will have to find a fresh source of funding for his monthly tooth-whitening budget, once Cinch have disappeared?!

.
For valuation purposes, I am inclined to ignore the bumper profits of £80.7m (17.92p EPS) for FY 2/2022, and instead work on a normalised EPS of something like 5-6p - i.e. similar to the pre-pandemic 4.99p achieved in FY 2/2020.
We also have to consider the risk of future earnings undershooting on the downside, for 2 potential reasons -
- Increased overheads, as staff (understandably) want a bigger slice of the cake in salaries & bonuses, and
- As used car prices return to normal at some point in future, when supply normalises, then that could result in dealers having to sell cars at low, or even negative margins for a little while, possibly?
Valuation - on FY 2/2022 results, the PER is below 3! This indicates that the market is fully discounting these bumper profits as a one-off. That means, even if profit next year halves, the PER will still be less than 6. So this share does look strikingly cheap, even on reduced profits.
If we take a pessimistic view, that EPS could fall right back to 5p, then the PER would only be 10. So whichever way things go, I reckon this share is priced attractively, i.e. cheap.
Plus remember that bonanza profits feed through to a rising cash pile, and increased balance sheet strength, giving scope to bolt on more dealership sites.
Current trading - this bit caught my eye, and shows that the bonanza is continuing, with profit so far this year level with last year -
Strong trading performance delivered in key months of March and April with trading profit of £19.1m (FY22: £19.2m)
Supply constraints are continuing, but this has helped achieve record profit margins, so I see this as a positive.
Cost increases are mentioned.
Share buybacks are continuing.
Government support - I like the way this is shown clearly on the P&L. It was £36.5m in FY 2/2021, dropping right down to £6.6m in FY 2/2022. Note that about half of the prior year’s Govt support has been recouped in corporation tax paid this year.
Dividends - a 1.05p final divi will be paid, on top of the 0.65p interim divi. Obviously with EPS of nearly 18p, the company has much more capacity to pay bigger divis. However, companies which did well from Govt support measures, need to be careful not to attract unwelcome attention by showering investors with big divis so soon. So I think the prudent approach makes sense. We can expect bigger divis in future, I imagine. Plus ongoing share buybacks,
Balance sheet - NAV is £331.9m. Deducting goodwill of £103.5m, and £1.8m other intangibles, gives us NTAV of £226.6m. Divide that by 358m shares in issue, gives NTAV of 63.3p per share. The company’s commentary mentioned 66.8p NTAV, so a slight difference to my workings, I’m not sure why.
There is a pension surplus of £9.1m.
Car dealers tend to have very large working capital, being mainly the cars (inventories), funded mainly by trade credit lines (e.g. from manufacturers). I usually look for current assets to be roughly the same as current liabilities. In this case, there’s a surplus, with C.A. of £610.7m, and C.L. of ££571m, so that looks fine.
The main feature of VTU’s balance sheet is the huge PPE (property plant & equipment) of £254m. This is mostly lovely, lovely freehold property. Therefore the shares are absolutely copper-bottomed with a ton of freeholds. This almost eliminates risk for investors, and as I always say with VTU, this share is really a property company and a car dealership combined. What’s not to like about that? It’s so great that VTU management recognise the value of freehold property, which to me means -
- Securing sites forever, with no risk of them being whipped away by a landlord
- No uncertainty about upward-only rent reviews (a horrible system, well past its sell-by date), and
- Long-term capital appreciation on property values.
Indeed, management recently bought the freehold for a successful site, thus securing its long-term future. It very much frustrates me that the fashion in finance for many years, has been for “efficient” (i.e. weak) balance sheets, to boost some quality metrics. I prefer the opposite - an inefficient balance sheet, laden with surplus assets - because it means the business can survive any downturn with ease, and may attract a takeover bid from a financial buyer that has spotted the assets - so hidden value always gets my vote.
Cashflow statement - looks terrific, no issues here.
My opinion - this all looks smashing. I cannot understand why the stock market places such a gloomy valuation on VTU, it doesn’t make sense to me, even if we normalise profitability to what the company might achieve when car values reduce again.
Why on earth is this share trading below NTAV? That’s just wrong.
On fundamentals, I think this share is worth 75-100p, which I’ve arrived at by taking into account NTAV, surplus cash (that can be used for further expansion), and earnings.
Hence I’m happy to hold, taking a long-term view.
I’d say the chances of a takeover bid are also very high with this share, and we’ve already seen a couple in the sector. The key attraction there, is that a bidder could line up a sale & leaseback on the freeholds, using that to fund most of a takeover bid. So this share could attract a financial buyer, as well as trade buyers.
All in all, and ignoring short term market volatility, this share looks to have excellent risk:reward at 50p per share.
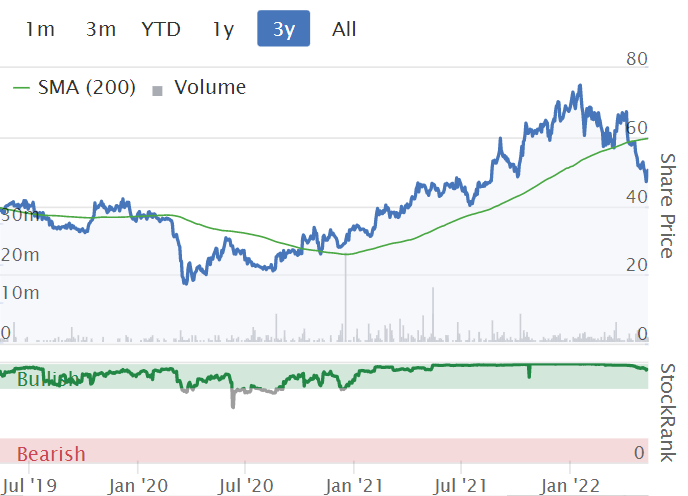
The recent drop looks a buying opportunity to me. Although we need to factor in the obvious point that household incomes being squeezed could lead to people deferring big ticket spending. Although that's offset perhaps by supply constraints, so people can't often get the cars now, even if they want them. So reduced demand may not hit sales, if there isn't enough supply to meet existing demand.
.
Jack's section
Dignity (LON:DTY)
Share price: 465.69p (-6.86%)
Shares in issue: 50,036,916
Market cap: £233m
Q1 trading update for the 13 weeks to 1 April 2022
Dignity is the UK’s only listed end-of-life provider. A grim business, but a defensive one, Dignity had been seen as quite a high quality stock but cheaper rivals have made for a far more competitive backdrop in recent years and the impact on the stock price and company valuation has been stark.

The past four years of rangebound trading has seen some shareholder churn, with deep value specialist investor Phoenix Asset Management building up at c30% stake. That could be a positive. They no doubt have influence at this point, and they are focused on the turnaround of struggling businesses.
Q1 underlying revenue has fallen by 22% to £73.9m, underlying operating profit is down some 67% to £9m, and the number of deaths fell in the period, from 204,000 to 166,000. A decline in figures following the worst of the pandemic and some painful strategic decisions is perhaps to be expected.
The group has reduced average revenue per funeral in order to improve competitiveness, and says it is seeing some signs of improvement now as a result.
Increased competitiveness is showing up in across-the-board growth in market share at the cost of average revenue per funeral… Both funeral market share and crematoria market share grew strongly as the new strategy started to deliver the growth on which it depends.
Funerals market share increased from 11.5% to 12.7%, while crematoria market share has increased significantly from 11.1% to 12.6%.
Capital structure
The combined effect of the drop in the death rate following the pandemic during a time of strategic change for the Group is what we were protecting against when we sought and agreed the deal with our bondholders. That gives us the ability to pursue the right long-term strategy whatever happens to the death rate this year. It also gives us the time to agree a more long-term solution for the capital structure which we are currently working on.
It is still our intention to address the capital structure most likely by use of the crematoria portfolio without undermining the integrated nature of the Group. We will make further announcements on this in due course.
The group's primary financial covenant requires EBITDA to total debt service to be above 1.5 times. The ratio at March 2022 was 1.61 times, down from 2.13x in December 2021. Not a particularly comfortable position given the fall in trading.
FCA regulation
Will be introduced from 29th July 2022 and Dignity believes this will lead to a number of operators leaving the market.
Safe Hands, a medium sized funeral plan provider in the sector, has since entered administration. Dignity plc took immediate action by fulfilling funeral plans for families that require a funeral in the four weeks from Safe Hands entering administration without charge.
So perhaps Dignity could benefit from this regulation over the next few years, if it leads to less competition. But it could also lead to more pressure for the group. Considering the declining revenue per funeral, lower deaths rate, and need to address capital structure, I don’t take comfort from this added layer of uncertainty.
The company frames regulation as an opportunity but I view it as a concern.
Conclusion
It’s still early days in the turnaround here, but it’s quite possibly a situation worth monitoring. There has been no equity dilution and that leaves potential upside for risk tolerant investors.
I’m ruling the shares out for now though, as the risks to equity are considerable. The combination of falling deaths and lower revenue per average funeral is concerning.
And when we add to the mix talk of “addressing the capital structure”, then the risks to shareholders must not be understated. This kind of situation can lead to very painful results for equity.

It does sound like some kind of sale and leaseback of the crematoria portfolio could be in the works but I haven’t seen any detail here. That would be a potentially transformational announcement worth looking out for, but there’s c£500m of debt against £331m of net PPE, and presumably only a portion of that is crematoria.
Debt levels have been coming down but remain at high levels. The market cap here is c£250m but the enterprise value is £785m.

The group also has poor liquidity levels. Liquid assets are a small proportion of total assets, and the group has a negative net asset value.

So the group is executing a turnaround, but not from a position of financial strength. There are three distinct issues here as I see it: the operational recovery, new regulation, and the financial position. Any one has the potential to scupper the others. I’m happy to stay on the sidelines, monitoring developments.
Hostelworld (LON:HSW)
Share price: 84.29p (-4.07%)
Shares in issue: 117,505,396
Market cap: £99m
With travel once again on the agenda, Hostelworld is seeing something of a comeback.

Previously I’d had concerns here regarding well-funded competition, but at sub-100p the investment case might have changed. Crucially, there has been limited equity dilution - 97m shares in issue in FY18 compared to 118m today, so 21%.

However, I see Paul’s previous coverage of the stock flagged an ‘unusual and expensive’ new debt facility including warrants worth 2.85% of additional dilution and 9% + EURIBOR in carrying interest. This deal likely staved off further dilution back in August.
Management says the strong start experienced in the first 12 weeks of 2022 has continued into April and early May, with week 18 net bookings at 73% of 2019 levels and revenue at 97% of 2019 levels (due to higher booking values).
Overall, we are seeing the recovery continue across all destinations and demand segments. In particular, booking demand into Europe, our largest destination in 2019, has almost fully recovered to 2019 levels with some markets exceeding 100%. We also see booking momentum returning in Oceania and Asian destinations as markets reopen for international travel, albeit more slowly. Finally, long haul bookings have now reached 70% of 2019, with trips from the US and Canada into European destinations at 2019 levels.
Conclusion
A brief but encouraging communication to the market. Hostelworld believes it should capture a slice of the pent-up demand, which it so far has done, with performance stronger than expected. There are inflationary pressures to consider, but this stock is obviously exposed to a recovery in travel.
The balance sheet looks ok, with £25m of cash ably covering £13.1m of current liabilities (as of 31 December 2021), but cash burn was a concern. Hopefully that is now in the rear view mirror, but there are no guarantees.
Profits have obviously tumbled over the past couple of years but, looking at the chart, the longer term profitability track record is not hugely encouraging and the group had been struggling to generate meaningful revenue growth in recent years.

So I think it’s quite possible that the share price appreciates due to an industry-wide recovery, assuming trade normalises and cash burn reduces, but what then for the long-term model? It’s not hard for larger and broader competitor platforms to include hostels in their offering, and if they are attracting more traffic and have better funding then I could see Hostelworld having a tough fight for market share.
Booking.com for example generated $6.8bn in revenue in FY20 and has hostels on its site. Hostelworld isn’t a company I’ve followed for a while so perhaps I’m missing something, feel free to comment, but the above does put me off seriously considering the stock. I recall a profit warning in FY19 as a result of reduced bookings, lost market share, and higher promotional costs.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

29 comments
After market announcement of relatively large purchase by Norcros (LON:NXR) of bathroom panel maker for x8 EBITDA and an £80Mn enterprise value. Part funded by a £18Mn placing. No doubt more details (but hopefully no skeletons) to follow but the deal looks quite good - highly related to current business, in a rapidly growing segment and a fair price.
Alphawave Ip (LON:AWE) - second big director purchase in 2 days. And this one is sizeable at £3m following yesterday’s at £0.6m
The trend and level of Vertu’s returns on equity explain why it has seldom made positive returns over cost of capital for equity shareholders and that is directly reflected in the share price history.
£HSP. A really excellent webinar this morning lasting a full 2 hours. Some brokers and a few PIs at the event with questions both from them and web attendees. Great to find a company explaining just what they do in real detail. Fascinating. I see that the sp has risen 6% today.
Mark
Hargreaves Services (LON:HSP) = Hargreaves Services
Good morning Paul, and thanks for great write up on Vertu Motors (LON:VTU) which seems really undervalued. On your comment on Cinch and white teeth, I seem to remember that I saw that Cinch had bought around a 10% share in one of the big ones like Vertu Motors (LON:VTU) and for the life of me I cant remember which! Do you or any readers have any idea. I also have Pendragon (LON:PDG) and Lookers (LON:LOOK) so may have been one of the three.
My notes - "takeover offer by Constellation Automotive (Cinch, We-buy-anycar) for £MMH.
So looked at Vertu Motors (LON:VTU) as a potential takeover play - but maybe management would be resistant. Good value, healthy and pays a dividend - but the future is unknown. I'll stick with the oilers as you need them to put in the motor even indirectly the Tesla.
Cinch is owned by Constellation Group which bought 19.9% of Lookers
Thank you for covering Vertu Paul, I agree with your comments about the share price and your brief mention of Cazoo! We'll buy a few more Vertu, I also expect the dividends to rise in line with your thoughts on the payout.
Bill Blaine’s morning porridge is a good read today.
https://morningporridge.com/bl...
Here is a small excerpt:
“ If you are holding good and great companies you really have little to worry about. Sure, the stock price may decline as the economic picture develops, the great correction of 2022 will continue as a falling tide lowering all boats, but ultimately good companies will bounce back, they will pay dividends and they will resume on trend mean-reverted growth.”
I think Vertu Motors (LON:VTU) is somewhere between fair value and expensive as current earnings are a sugar rush due to macro conditions rather than the reward for good management and capital allocation (I question both). This is a stale view a little from me as I owned several years ago buying on spikes down to the 40p area and selling for modest profit into the higher 40s as I came to the conclusion they were a bad capital allocation business.
They talk a great game but they fail to deliver IMO. In recent years they moved to buying expensive premium franchises (I think for after sales and the higher margin used car biz) away from their buy cheap and build. Its really a massive shift in strategy they've not really clearly acknowledged.
They are vulnerable to normalisation of used car prices with volume maybe still impaired and any cost or reg pressures around aftersales (I think there's a chance of investigations into aftersales care market - often a shoddy service with very high margins).
Looking at their results its notable that gross margin stayed pretty constant despite the large bump in revenues due to pricing. I find this a disappointment given the scale of the revenue bump (40% YoY) - why no leverage in here?
Then looking at operating expense it rose by 30% YoY. Its a little hidden in the figures but c.10% of that is called 'non core' as it relates to acquisition and disposal costs...that's a bit cheeky definition though as buying and closing operations a repeat activity. You may ask what happens if they standstill and don't acquire? That's a good question and I don't have a neat answer but my guess is that wont be good and isn't really viable. Refresh is an ongoing cost. Add in that I suspect there has been very low marque brand related costs in last couple of years due to covid issues and it looks like costs will go up in coming years (...undoubtedly much marque repositioning to come...and the premium brands they've been buying into have high marque costs and always want to refresh/dazzle and that cost goes to vertu)...
...BUT govt related reliefs to the business rolling off account for slight less than 10% of YoY cost increase...so adjusted its more like a 20% increase in expense YoY -> looks good relative to revenue bump. Nevertheless I believe there's a lot of smoothing to come there and expenses go up whilst profits and revenues face some pressure.
There also looks to be a bump in aftersales revenue that might be driven by catch up work (repairs etc - note when you go for your annual under plan service they suggest a whole load of repairs that are non essential usually...maybe they stopped that during covid?).
Unless there is a secular change in the car retail market and/or Vertu has had true operational transformation (something they talk about endlessly but never achieve) then the rating should be low given the capital intensity. I don't place value on the special use real estate portfolio. This may be overly conservative of me but I don't see it as easily realisable value...in a life or death situation it might...but the poor operating dynamics and high capital intensity will likely mean emergency funders ain't willing to step in early so the value of the property portfolio will not be felt by shareholders.
Note that trading year to date is driven by new car sales with the rest looking poor. New cars don't make much money so that dynamic could lead to a profit disappointment. I think later in year we get some walking back of revenue and profit expectations. If used car sales normalise in price but volume remains low then it could be nasty.
Anyway, my view may be jaundiced on this. I'm a cynical past holder that came to conclusion it talks a good game but doesn't deliver. Buyer beware etc :)
Hi Mojo,
Re. Vertu Motors (LON:VTU)
Always good to have a well-argued bearish/neutral view, thanks for posting :-)
Regards, Paul.
Thanks...I'm often wrong...this may prove a learning opp for me!
Great results from Vertu Motors (LON:VTU) I believe car prices will be higher for longer than the market thinks so still more good news to come. One issue for me is that the company has bought back almost 10 million shares and will continue to do so in the coming year. I would prefer an annual dividend as a percentage of profit or a special dividend. This would make this AIM company more attractive to IHT investors and maybe result in a higher share price over a longer time. Buying back shares also reduces liquidity which for me is an important issue in times of market stress. It seems to be the trendy use for excess cash at the moment. Any one else fancy a divi over share buyback?
Hi Glen,
With Vertu Motors (LON:VTU) net tangible assets at 67p per share at present, I am all for share buybacks to the maximum extent they can afford. It is when a company buys back shares when they are relatively expensive that it becomes a problem, but that is far from the case here.
Divi every time!!
Seems bizarre to me that Duke Royalty (LON:DUKE) (I hold) should be punished so heavily (was down 6.7%) for what has been a hugely successful placing at 10% discount to yesterday's close - they went for a minimum of £16.5m but raised £20m. Yes, there's some dilution for existing holders who'll have a smaller share of a bigger pie, but the money's not to support the business but to lend out to SMEs like a mortgage (fixed monthly repayments that'll clear the debt if paid to maturity). The deals have the added attraction of a with-profits rider - if the businesses make profits, DUKE gets a share.
Needless to say, I like their business model and their fixed overheads as related to their funds under management means there's significant operational gearing, so I went for the placing via Primary Bid and, as an existing holder, got a full allocation which doubles my holding.
Edmund Shing gave them a mention here. I hope I'm not missing something - I thought they might have been up given the massive show of confidence in what they are doing.
Ive been a shareholder of this company for sometime . The downside is that they keep doing new share issues and the share price is still below the price of the several fund raises.
I hold Duke Royalty (LON:DUKE) so whilst I am registered with Primary Bid I did not do a top up, annoying would have made a small amount today but who knows the value when it actually hits the share account.
My holding though is in an ISA, so for tax free income, so in reality there is no option to top up... frustrating but will write to management, I am down but still hold happy with the dividend.
I would compare with Supermarket Income Reit (LON:SUPR) where they offer the additional shares to all holders no matter where held so continue to add through the open offers in the ISA.
Tommy
Here is the Treatt (LON:TET) analyst presentation from yesterday including the Q&A video & podcast. This is a Lord Lee favourite. As Jack alluded to yesterday, long term holders have been rewarded and by the sounds of things over time, will continue to be so. Yes, there's a H2 weighting, when the higher-margin healthier living categories are expected to perform better, hence the higher profitability. Edison have raised their revenue forecasts to reflect the strong momentum but their profit estimates remain broadly unchanged, due to mix considerations and cost inflation.
Separately a few webinars next week:
Cerillion (LON:CER) interim results presentation, Monday 16th May at 2pm. Results were published on Monday. Revenue up by 26% and adj EBITDA up 50%. The pipeline is up 31% to £172m and they're expecting further new contract wins in H2. Liberum see 'upside risk' to their forecasts and have a target price of 1120p. Louis Hall, Co-Founder & CEO and Andrew Dickson, CFO will give a webinar fillowed by Q&A. Register here.
Eneraqua Technologies (LON:ETP) who IPOd November 21 will give us an introduction on Wednesday 18th May, 1pm. They are energy and water efficiency specialists. Through their own IP they support clients replace gas, oil or electric heating systems. They offer a range of communal/district heating solutions utilizing, gas, air source heat pumps (ASHPs), ground-source heat pumps (GSHPs) or hybrid systems. They have achieved a 3 year CAGR of 38% and cash conversion of 80%. They have a very healthy order backlog. I think they're interesting. Register here.
A little bit of a different one. Allia C&C/RCB webinar on income-generating bonds, which offer 3-5% yield through an investment in socially responsible organisations eg. care of the elderly, support housing for people with learning difficulties, affordable homes, places of beauty etc. Webinar on 17th May, 3pm. Register here.
And finally the Srt Marine Systems (LON:SRT) investor webinar. They provide software to monitor maritime traffic. Some of their market should be driven through regulation. It includes coastal and territorial water surveillance and security, fisheries monitoring, management and illegal unregulated and unrecorded (IUU) detection, search and rescue, waterway management and aquatic environment monitoring, as well as individual leisure and commercial boat owners. Simon Tucker, CEO and Richard Hurd, CFO will present on Wednesday 18th May, 4pm. Register here. So far, it's proving quite popular.
Re Best Of The Best (LON:BOTB) - this might be a PER of around 10 for FY22, but if H2 performance is annualised then next year's EPS figure might only be 29.4p. (Based on H1 EPS being 27p and FinnCap this morning saying FY22 results will now be 41.7p EPS - meaning H2 is 14.7p). I think it's better to wait until signs of growth again and the detailed breakdown in the full-year results.
Hi
Nextenergy Solar Fund (LON:NESF) just about within the SCVR market cap size, posted its unaudited operational update.
For some reason not as an RNS but its on my Stocko newsfeed. This link might work (or you can call up the Stockreport and use the 'News' option).
https://www.stockopedia.com/sh...
Highlights are as follows.
Financial Highlights
· +9.1p (+8.7%) increase in unaudited NAV per ordinary share to 113.5p
(31 December 2021: 104.4p).
Increase in unaudited Ordinary shareholders' NAV to £669m (31
December 2021: £615m).
Ordinary shareholders' unaudited Gross Asset Value ("GAV")
of £1,150m (31 December 2021: £1,094m).
Ordinary shareholder cumulative total return since IPO of 53.6% (31
December 2021: 50%)
Gearing (including preference shares) of 42% (31 December 2021:
44%).
5.0% increase in target dividend to 7.52 pence per ordinary share
(FY21/22 7.16 pence per ordinary share).
The Company is predicting a dividend cover of between 1.3x and 1.5x
for the current financial year.
Recent share price has been upward (even in these market conditions).
Some might find this a useful diversifying growth and income play for a portfolio.
If some are interested there are a few interesting presentations through this YouTube link. They offer a rich insight into the sector and the fund. If you watch some of the vids, they elaborate on the substance behind the fund, its partners and their ambitions.
https://www.youtube.com/result...
I bought a starter position yesterday. I particularly like that although they are building and operating solar farms (useful to hold 'real assets' in these inflationary times), they are now evolving their operations to co-locate storage batteries within their farms and thus add energy trading to the mix. Also, I liked as a plus point, they are developing non-subsidised solar farms, both here in the UK and internationally (US, Spain, Portugal, Poland and Italy). Which decouples future value away from government subsidies which can be pulled almost without warning.
For my portfolio, Nextenergy Solar Fund (LON:NESF) now compliments my small holding of Gresham House Energy Storage Fund (LON:GRID) , which operates battery farms. Another diversifier, growth and income play.
I am a new comer to this sector but have been fascinated by the research I have encountered and really like that this solar/battery combination an evolving sector, innovating rapidly whilst being lifted be the macro tends of ESG and green energy. I will be digging deeper into wind/solar/battery combinations in further research.
Regards
Howard
The chairman and a non-exec at Gaming Realms (LON:GMR) have bought a total of £130k of shares in the company.
Are directors’ dealings significant? That’s anyone’s guess. GMR are one of those growth companies where the share price has been drifting down with the market. However, they recently became profitable and the growth pipeline looks quite strong so the valuation is now looking like it makes more sense and the insider purchases would tend to support that. (Stockrank has historically been poor of course as unprofitable in the past).
While there is a theory that online gambling is going to slow down now lockdown is over with this company the strong growth is continuing and they are expanding into new territories, so much less affected by that.
Was considering selling, but the management team purchases have convinced me that the growth story is still valid.
Good morning Paul and Jack, I'm hoping Vertu's impressive results bring a smile to holders faces today, they've cheered me up after watching far too much of our portfolio falling. I'm told by motor trade friends exceptional used car margins are still holding but Robert Forrester points to the importance of consumer confidence going forward. Nevertheless I have great confidence in the management team at Vertu to continue its growth. I hope one of you has time to comment on the results.
One aspect of Vertu that I think is easily overlooked is that they are a significant on-line car trader. Nice to have that in combination with significant property assets. The exceptional period for used car sales has to end eventually but it's already extended far longer than I initially expected.
PS I hold.
I was expecting to see a significant move in the SP on the back of these excellent results for Vertu Motors (LON:VTU) Surprised to see that its less than 10% and falling at the time of writing. Just shows the degree of negative sentiment in the market at present. Every rise is seen as a selling opportunity. Good news is tempered by warnings about future costs/sales and the cost of living. We need a change in the direction of the inflation rate to change the mood.
Vertu Motors (LON:VTU) numbers, although very good, were not that much of a surprise and any reference to future inflation/supply chain/consumer weakness will currently be taken as bearish .
US inflation numbers out @ 1.30pm (our time) , commentators are thinking there may be a chance of a fall in the rate, which is probably why markets are up this morning.
PS . I have looked at Vertu Motors (LON:VTU) a couple of times and the numbers etc are good but as a long term investment what is the picture for car dealers going forward ? EV's, manufacturers bringing the whole sales and servicing procedure in house a la Tesla , my conclusion was that there was too much uncertainty.
As flagged by Mr C, Vertu Motors (LON:VTU) full year 2022 results are ahead of forecast, with Adj profit before tax £80.7m, the beat due to the higher gross margin at 12%. Basic adj EPS 17.92p. The March & April sales are up 4.3% against strong comparatives . The order book is strong, although a caution about consumer confidence in the face of rising domestic costs. Liberum retains 2023 forecasts of PTP £35.4m, with a price target of 100p.
PIWORLD will host an investor presentation where you can ask your questions to Robert Forrester, CEO & Karen Anderson, on Monday 16th May, 8.30am. Register here.