Small Cap Value Report (Wed 11 Oct 2017) - CCT, QUIZ, VTU, PHD, CRPR

Good morning, it's Paul here.
It's not been a good start to the day. The council are cutting down a huge tree nearby, so I have the loud buzzing of chainsaws to contend with, making it difficult to concentrate. Plus there's been a profit warning from something in my portfolio - £CCT So let's start with that. I've put the tickers of companies of interest (which I intend reporting on here) today into the article header. I've got plenty of time available today, so there's probably also scope for 1 or 2 reader requests, within the sectors that I cover.
Profit warnings just come with the territory for small caps. Hence why I don't let them bother me too much. It's a straightforward decision - is the company in a downward spiral (which would make an immediate selling of the shares the most sensible decision)? Or, are the problems being reported limited, and fixable? (in which case I would hold, or buy more). Plenty of companies do recover from profit warnings, hence why I think the concept of automatically selling after a profit warning is far too simplistic. Each situation is unique, so there will never be a one-size-fits-all strategy that is guaranteed to work.
The fact that a lot of people do sell instantly on profit warnings (often due to stop losses on spread bet accounts) can create some nice buying opportunities, when fundamentally sound companies are sold off far too aggressively on a profit warning which might have no bearing on the long-term prospects of the company.
Character (LON:CCT)
Share price: 357p (down 19.8% today)
No. shares: 21.1m
Market cap: £75.3m
(at the time of writing, I hold a long position in this share)
Trading update (profit warning) - I'm quite surprised that the market has reacted so negatively this morning to the latest update. The company had already told us here on 19 Sep 2017 that market conditions were challenging, and that a major customer (c.8% of total sales, estimated by one broker) Toys R Us, had filed for bankruptcy protection in USA & Canada.
Results for y/e 08/2017 - the company had already reported that results would be in line with expectations. This is reiterated today, as follows;
As reported in September, the business has had a solid finish to the 2017 financial year. Accordingly, the Directors anticipate that, Group underlying pre-tax profits for the year ended 31 August 2017 are projected to meet current market estimates. The Group's balance sheet remains strong.
To put a figure on that, the forecasts I've seen are around 51-52p EPS - so at this morning's lower share price, the (how historic) PER is just 6.9.
As we know, the market looks into the future, not backwards.
Results for y/e 08/2018 - this is what has spooked the market today - somewhat surprising, given that the company had already warned previously about the issues it was facing, but there we go;
UK sales are OK. The issue is with international;
Our international and "FOB" sales have been adversely effected by a combination of several factors, not least of which is one of the world's largest toy retailers entering into Chapter 11 bankruptcy protection in the US and Canada, which has had subsequent knock-on repercussions in every market where it trades (including the UK). Our international customers are also taking a very conservative approach to purchases.
At this early stage of the Group's new financial year the Board consider that, based on the latest sales and market data available to them, the Group's performance for the year ending 31 August 2018 is now expected to be significantly below current market estimates.
Broker forecasts - so far I've only seen one broker note this morning. Panmures have revised down their forecasts, in a new note this morning, which is available on Research Tree.
Based on the new EPS forecasts of 38.1p 08/2018, and 45.3p 08/2019, then the forward PER is 9.4 and 7.9 - which looks good value - providing that this is the full extent of the damage. Bear in mind that the net cash is now 25% of the entire market cap, and the PER would be a lot lower still if you adjusted out the net cash.
Also note that forecast dividends are 21p and 25p. At the current share price of 357p, that would produce divi yields of 5.9% and 7.0% - a very attractive return. Those forecast divis are still well covered by the reduced earnings forecasts. Note that Character has a strong balance sheet, with net cash, which further reinforces my confidence in the projected divis.
Today's comments on divis are reassuring;
Furthermore, we are committed to maintaining our progressive dividend policy and continuing our share buy-back programme, as and when considered appropriate.
Note that the company's website shows 24.2m shares in issue, but about 3.3m of those are held in treasury. Stockopedia shows a net figure of 21.1m shares in issue, which is in the same ballpark.
Outlook comments sound upbeat;
Nevertheless, the Directors believe this to be a temporary downturn and that the Group anticipates returning to its previous growth pattern during the second half of the 2018 calendar year, and this ultimately is expected to be reflected in the financial performance for the year ending 31 August 2019.
The single biggest factor underpinning our optimism is that during 2018 we shall be introducing exceptionally exciting new products, many developed in-house which, together with the current product portfolio will, the Directors believe, give the Group its strongest ever product line up.
Additionally, even in these tough trading conditions, we expect our cash flow to remain positive, our reserves to grow, and our Christmas stocks to remain under control.
So this seems to be a situation where investors who look through the current difficulties, and accept that they are temporary, could end up with a nice buying opportunity. The risk is obviously that problems get worse, and another profit warning has to be issued.
Balance sheet - I thought it would be useful to refresh my memory on the most recently reported balance sheet. It looks excellent, here are a few key measures as at 28 Feb 2017;
Net Asset Value (NAV): £25.2m
Net Tangible Asset Value (NTAV): £24.5m (there is only £729k of intangible assets to be deducted)
Current Ratio: 2.27 - very strong, and this includes net cash of £18.6m - that's almost 25% of the entire company's market cap.
Overall then, this is a really strong balance sheet with plenty of surplus working capital. So there should not be any issues over solvency, even if trading deteriorates a lot more.
My opinion - based on the information provided in Sept 2017, and more recently today, I see this as a good buying opportunity. So I've currently got a buy order in, to increase my existing position size. My main worry is that the price could fall further - my broker reckons that sellers have not finished yet. It's usually a mistake to buy on the day of a profit warning. However, when the price is falling, then you have better liquidity - so it's often the only time you can actually buy a stock like this in decent size.
I've no idea what the exact low point will be in the share price, and don't really care particularly - because the price now looks sufficiently cheap on (revised) earnings forecasts, and with a very attractive yield, that it's cheap enough for me. I accept the risk that there could be another profit warning - that risk is why the share is now so cheap.
The key points for me are that the main reason for the profit warning seems to be a one-off factor outside their control - the insolvency of Toys R Us. Also, the new products in the pipeline give good grounds for optimism in H2 of 2018 and into 2019. Therefore I see this as being a possibly bumpy ride, but where I should be paid nice divis, and see a decent capital return in say 1-2 years.
It should be said that I generally tend to be a bit too willing to give companies the benefit of the doubt! Also note that the stock market has never really attributed a generous valuation to this company - it always looks cheap.
As always, please remember that I'm only giving a personal opinion, and reporting what I'm personally doing with my portfolio. I might possibly add some to BMUS, but haven't decided yet. The onus is on readers to do your own research, and take responsibility for your own trades. Hence why I never give recommendations. If something in your portfolio goes wrong, you're to blame, not me! That's why I never give recommendations - because I don't want the responsibility or hassle of people blaming me for stock ideas that go wrong, as inevitably many will.
I'm particularly keen to hear from anyone who's bearish on CCT - it's vitally important to consider the negative case on a share. Obviously I reserve the right to change my mind at any time, on any share.
QUIZ (LON:QUIZ)
Share price: 183.5p (down 1.9% today)
No. shares: 124.2m
Market cap: £227.9m
(for the avoidance of doubt, I no longer hold a position in this share)
Pre-close trading update - for the six months to 30 Sep 2017.
This is a clothing retailer, both from physical stores and on the internet (like a lot of other companies - so its emphasis on being "omni-channel" is not unique at all).
This update is unsatisfactory, in that it only mentions revenues and gross margins. It doesn't give the key piece of information, which is how the company's overall profit compares with market expectations. Failing to be clear about this just introduces doubt, and makes me wonder whether costs might might be running ahead of forecast? That's the only explanation I can think of, as to why the update only mentions sales growth, and gross margins, but not net profit.
QUIZ, the omni-channel fast fashion womenswear brand, is pleased to announce a 35% increase in Group revenue to 56.1m (H1 2016: 41.5m) for the six month period to 30 September 2017 ("H1 2017"), compared to the same period last year. Gross margins remain in-line with expectations.
QUIZ's strong growth in H1 2017 reflects the brand's continued expansion in the UK and targeted international markets across the Group's omni-channel model.
Online growth is excellent, but coming from a low base;
The QUIZ brand has continued to grow rapidly online with Group online revenue increasing by 204% to 13.8m in H1 2017 (H1 2016: 4.5m) reflecting the benefit of opening the new 180,000 sq. ft. Distribution Centre in the summer 2016, increased and effective marketing spend, particularly through digital channels, and the broadening of the product ranges available to customers.
Valuation - I'm waiting for my broker to email me some research. In the meantime, the valuation shown below on Stockopedia is based on the broker consensus figures supplied by Thomson Reuters. As you can see, this share has a fairly aggressive PER of 26.0. On Stockopedia this is calculated as a blend of the current, and next financial years forecasts, which makes all shares comparable, irrespective of their financial year end date.
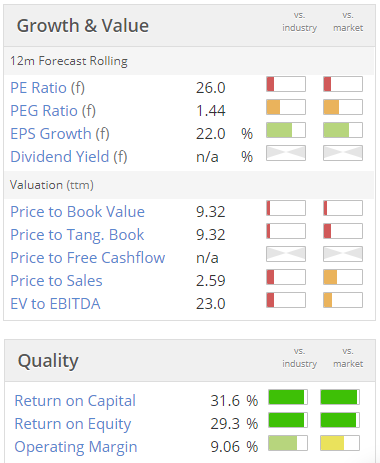
So the deal here is that above average growth commands a relatively high PER.
My opinion - I was really impressed with management at a pre-IPO meeting, so I participated personally in the IPO. Although very soon afterwards, my nagging doubts became more at the forefront of my mind, so I ditched my shares into the initial price surge.
Overall, my current view is that it seems a fairly good business, but that it operates in a crowded market, and isn't sufficiently special to make me want to hold it long term. Also I feel the IPO price was high, with investors being prepared to over-pay for an online fashion retailer, given how spectacularly well Asos & BooHoo have done. The trouble is, online retail is only a small part (although growing rapidly) of Quiz.
So for now, I'm happy to sit on the sidelines. It's the type of business that I would consider buying back into if it misses profit targets, and drops to a more realistic valuation.
Vertu Motors (LON:VTU)
Share price: 46.25p (down 1.6% today)
No. shares: 393.5m
Market cap: £182.0m
Interim results - for the 6 months to 31 Aug 2017. This is a car dealership, operating from 124 sites in the UK. Car dealers seem to be very out of favour with investors currently - due to new car sales falling, cost headwinds (e.g. from forex), Brexit fears, plus longer term issues of how electric & self-driving cars will change the sector. So could there be a value opportunity with these shares, or are earnings likely to fall in future?
Performance looks pretty good;
Adjusted profit before tax up 7.2% to £20.9m
Adjusted EPS of 4.24p (up from 4.06p). Remember these are only 6 month figures, so if you double them to crudely annualise, then the PER is amazingly low, at only 5.4.
LFL new car sales are down heavily, at -14.7%. That's awful - it's what you would expect in a deep recession. However, used sales, and aftersales are both up - which has clearly taken up the slack from lower new car sales. Used sales & aftersales contributed 71.7% of gross profits.
Costs seem to have been well controlled, with £0.8m in like-for-like cost savings overall - so other cost increases have been more than fully absorbed by savings elsewhere.
Outlook - the company confirms that it's trading is consistent with full year market expectations. I am also delighted to see the company include a very helpful footnote as follows. All companies should do this;
2 The Board considers market expectations for the financial year ending 28 February 2018 are best defined by taking the range of forecasts of adjusted profit before taxation published by analysts who consistently follow the Group. The current consensus of adjusted profit before taxation as at 11 October 2017, based on the published analysts' forecasts of which the Board is aware, is £31.8m.
Note that as the company achieved £20.9m in H1, then this implies a much lower lever of profitability in H2, of £10.9m adjusted profit before tax. So that invalidates my comment above of just doubling H1 profits to estimate full year forecasts.
Forecasts - several broker notes have hit my inbox today. They're reducing future profit forecasts by 7-10%. For example, one broker is forecasting 6.3p adj EPS this year and next year. Another is forecasting 6.3p this year, and 6.4p next year.
Therefore, brokers are basically telling us that the company won't be growing its profits any time soon. To me that makes me worry that profits might have already peaked, and could be heading downwards. This explains why the sector is on such a low rating - based on today's updated broker forecasts, Vertu is on a forward PER of 7.3.
Asset-backing - the low PER obviously reflects the wobbly outlook for new car sales. It seems logical to assume that lower new car sales would feed through to lower aftersales revenue, after a time lag?
However, the market cap is also rather well supported by net assets.
NAV £264.6m
NTAV £168.6m (which compares with the market cap of £182m)
There is net cash, of £20.8m. Although note that, whilst it may not need to borrow from its bank, the group does effectively borrow heavily from the car manufacturers. So trade payables is gigantic.
Therefore current assets are £609.8m, which is mainly inventories of new & used vehicles, and current liabilities is a similar number, at £612.8m - which is mainly trade payables (i.e. money owed to the car manufacturers).
The other main assets are freehold & long leasehold property - which is a very nice position to be in.
Therefore, arguably this company has 2 supports for the share price - one being earnings, the other being its property portfolio. This should provide decent downside protection, even if earnings decline.
My opinion - sentiment feels very poor towards this sector, and valuations reflect that.
I'm quite tempted to buy some shares, for a possible future recovery. The property asset backing interests me too - as there could be potential upside from that, e.g. selling under-performing sites to developers.
Overall, it looks moderately interesting to me as a possible value share. My main worry is that the sector might have already reached peak earnings, and could now see declines. That's what the very low PER is suggesting to us. So the downside risk is that an apparently cheap share could end up being not so cheap after all, if earnings do fall significantly in future. On balance, think I'll probably steer clear. I'm more interested in companies & sectors where earnings are rising strongly.
Proactis Holdings (LON:PHD)
Share price: 163.5p (down 4.4% today)
No. shares: 92.7m
Market cap: £151.6m
Preliminary results - for the year ended 31 Jul 2017. This is an acquisitive group of companies focused on spend control software and services.
The problem we have in analysing the figures, is that a significant acquisition (Millstream) was made during the year. Then a huge acquisition was made just after the year end (Perfect Commerce LLC) - which was classified as a reverse takeover due to its size (involving a £70m placing at 165p, and £45m of new debt facilities).
Therefore the composition of the group as things stand today, is very different to how it was during the year end 31 Jul 2017 - rendering the historic figures to be almost meaningless.
I can't even rely on EPS calculations, as this is obviously based on the average number of shares in issue during the year, being 48.8m on a fully diluted basis. Here we are, just a few months later, and the share count has almost doubled to 92.7m. Therefore earnings have to almost double this year, to achieve the same EPS.
The acquisition of Perfect was justified by the expectation of £5.0m in group cost savings.
Balance sheet - looks very weak. Although substantial new equity was raised after the year end, in a £70m placing at 165p, this was used to part fund the Perfect acquisition. So the next set of accounts will probably also look weak - with intangibles getting larger with every acquisition.
FinnCap has published a new note today (available on Research Tree), in which it forecasts balance sheet NAV of £99.4m at 07/2018. However, intangible assets is £138.7m within that, meaning that NTAV would be negative at -£39.3m. Personally I don't normally invest in any company with negative NTAV. So for me, the balance sheet is a deal-breaker here, hence I wouldn't invest.
Earnings forecasts - FinnCap forecasts adjusted EPS of 11.4p in the current year 07/2018, and an increase to 13.7p in 07/19. Assuming we can rely on those figures, the next question is what level of PER does the group deserve? I would have thought a PER of 15-20 would make sense. Therefore that targets a share price of 205p to 274p. This compares with the current share price of 163.5p - so there's some upside if things proceed according to plan, but it doesn't look madly exciting to me. Plenty could go wrong along the way, as the growth is nearly all coming from acquisitions & restructuring - fraught with risk.
My opinion - I tend to steer clear of highly acquisitive groups - there's just too much scope for something to go wrong. Also, I don't like the weak balance sheet here - with significantly negative NTAV forecast. So overall it's not for me, but I wish shareholders well, and hope things work out for the company.
I note that a highly-regarded tech analyst has raised question marks over the wisdom of the Perfect acquisition. That's another reason which is adding to my caution here. I think I'd like to revisit this in a year's time, once we have a full year's trading of the enlarged group.
James Cropper (LON:CRPR) - there's been a sharp correction in the share price here. The company has responded today with a reassuring-sounding update;
...Overall, therefore, the Board expects the Group to achieve management expectations for the current financial year and remains confident of the Group's prospects over the medium and longer term.
More detail is given. To summarise, higher pulp prices have been absorbed by improved performance in other divisions.
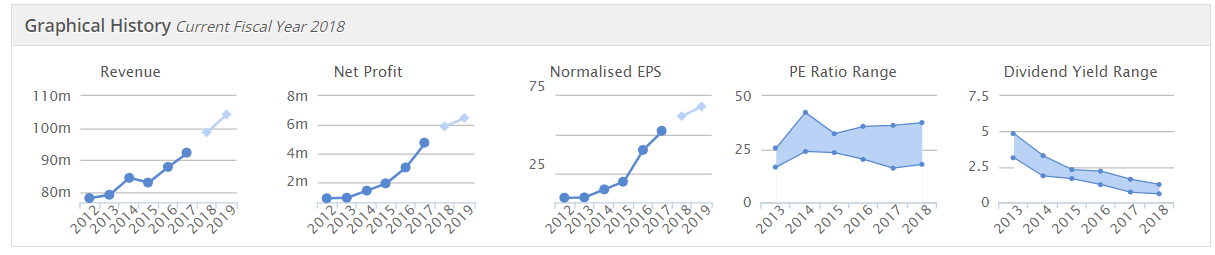
My opinion - I don't really understand why this share is rated at over 20 times earnings.
The progression of profits has been quite good, but note how the divi yield has been reducing steadily, and is now only 1%.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

57 comments
The last time I looked at Character Group's accounts, it struck me how dependent its profits were on currency stability. Its royalty deals were largely in US dollars but its income was mainly in Sterling. I was wondering if anyone has done any analysis to figure out how currency volatility impacts its bottom line? Incidentally, am I right in thinking that most of the company's debtors are covered by credit insurance?
Bid/offer spread quite annoying with CCT but I guess this is part and parcel of small cap shares. Being quoted 410p offer yet digitallook showing spread of 385.00p / 405.00p.
Life's too short so stuck in an order to buy at 405p and will leave it in the lap of the gods.
With reference to Character Group price fall today , currency volatility must be adding to there problems also .
Re. Proactis Holdings (LON:PHD) Having analysed this share and in particular having reviewed the finnCap report, I am not as cautious as Paul is about it.
Yes, the negative NTAV is a red flag, but there is a lot to like about it.
Based on the finnCap report and focusing on the projected FY2018 data,
- sales are expected to grow by 142% to £61.5m
- adjusted and diluted eps expected to grow by 32% to 11.4 This takes into account the huge rise in number of shares resulting from the recent acquisitions
- operating cash flow goes up from 5.6m to 14.8m and FCF from 1.8m to 5.2m
- the debt position is well within acceptable limits. Net Debt/ EBITDA ratio is only 1.0 post recent acquisitions
On today's sp of 163.5p , the projected PE comes to 14.3, and PEG = 0.44. Their main competitors have much higher PEs. (SAP 27, Oracle 19)
So if management focus on bedding down the acquisitions and realise the identified synergies, the company's SP should be north of 20x earnings multiple.
decl.: no position long or short.
While normally I have learned Paul is right to screen out weak balance sheets, the counterbalance with Proactis is recurring revenues. I haven't yet had a sniff of clients choosing to move elsewhere, which is my biggest worry.
Jon
I sold CCT at 5.25 a few months back as I was cutting back in expectation of a summer pull back in the markets generally and was waiting for the long awaited correction. Whilst it's been a good earner for me its never going to be a 10x return stock and they are dependent on winning the licenses to be able to sell the products. A loss of say the Peppa Pig license would be significantly detrimental to its results.
Must admit to being tempted at sub 4 pound to go back in again.
They just renewed Peppa pig (for 3 more yrs I think) a few days ago FWiW. They've had the licence for donkeys years and are becoming the go to guys for new UK licences
Paul, I have a small holding in Proactis and wondered if you could expand a little on your comment that "I note that a highly-regarded tech analyst has raised question marks over the wisdom of the Perfect acquisition". Please could you reply as to who this is and what the question marks were - or at least give the analyst's name so that I can contact him/her myself? I haven't heard such comments myself so would like to know more.
Cheers.
Hi rivaldo,
If I anonymise something, it's because I've been sent a broker note through a third party, and don't want to compromise my source.
Regards, Paul.
I am also a holder of CCT. And take all Paul's points on board and agree with most of them. If there is a bear case then it's the structural shape of the toy market itself and CCT's over dependence on the UK market where inflation-adjusted consumer disposable spending is trending down 0.3% year in year.an NPD trade survey says that worldwide growth in toy sales is 3% with only the UK and Australia showing negative growth.
Apart from the loss of ToysRUs and the decline in UK consumer spending power, the other question marks over CCT might be demographics, and the possibility that CCT may not have the right products. (Bearish comments in the past have focused on the fact that Star Wars, a revived Disney franchise, may be eating into CCT's market share.)
It's also disappointing that CCT reports caution on sales in overseas markets when these are growing in terms of total sale volumes - source NPD. Or cd it be that Disney is taking the lions share of this growth with overseas distributors being cautious about the impact of Star Wars - the next Star Wars film is released December 15 and Disney is anticipated to release two a year for the next three years.
On the guru screens.. im working my way through the screens ,reading the books (i have a small library now)..instead of buying another stock I buy a book. Im up 100k in a year in my SIPP.(38% up) Last year i must have bought 40 -50 stocks and lost about 40k on top of charges..
The dreman box k came from the US via amazon
I think in the benjamin graham book (hard reading) as was the tiny titans (what works on wall street) they did say stocks can be boring.. its like a itch.. i just dont scratch it..
Im also not checking my stocks 300 times in an hr.. :)
Once I get more confident I will buy in again, but it seems the trick is to hold for 2-5+ years
I was buying and selling every other day and holding for 4 months
Heres the link to the guru screen, the book was recommended on amazon via his other one which I have yet to read... his experience as an analyst really open your eyes
https://www.stockopedia.com/screens/guru/david-dreman-17/
Thank you. I'd like to get away from being glued to the trading platform so an investment in education seems like a good idea.
Hello Paul/all
I reckon all the comment on Character (LON:CCT) and none on Vertu Motors (LON:VTU) tells us that Vertu is quite deeply out of favour. No-one can find a reason to like this company and sector...so its going to be hard work to prove a case out meaning valuation is low. Management need to prove out their model and competence. I am quite bearish generally so I am only interesting in things that are quite out fashion at the moment (that's a warning for how to contextualise what I say!).
Vertu's general results are cracking in the situation of 15% decline in new car sales which is significantly worse than the industry average. The exception to the positive is the operating cash flow being weak due to working capital impact.
On working capital there seems to be a bit of management rinky dink going on which will either prove to be a buffer against further deterioration in market environment or source of upside cash flow surprise for FY results. That said more work needed by me to make sure there isn't something odd. They've actually tightened inventories a bit but it is payables and receivables that has gone against them with a net working capital impact of -£30m. They are still cash flow positive by about £3-4m for the HY due to sale of some of property portfolio raising £14m. There's cash going out to capital investment too in HY (>£8m) which has been relatively high in recent years. This business has been generating good ongoing cash which has been deployed into acquisitions and investments, as well as supporting dividend growth.
On new vehicle sales they have underperformed the industry averages due to their mix which is low on high end motors (apart from Jags and Land Rover where they are slightly above averagely exposed) to the tune of something like -16% relative to industry average (-16% on the premium BMW, Merc, Audi sort of motors and if Toyota and VW are thrown in as part of premium then -24%). They are very exposed to the lower end stuff with Ford and Vauxhall being their most significant overexposure. That's quite a headwind as premium names have held up really well.
My guess (but not a reason I hold the stock) is that sales will at least normalise and perhaps recover going forward as the issue looks to be price sensitive buyers wigged out by the diesel fiasco (if you are on a budget then you can't throw money away on cars). Diesel sales down 20% whereas petrol is flat...electric/hybrid vehicles up 40% in Sept YoY! More price sensitive buyers are sitting it out to see what happens in the whole diesel-electric fandango...they will be cautious to switch habits. This is not (at the moment anyway) a story about the UK consumer being exhausted.
My guess is that management are being super conservative in their guidance for the full year and that upside should emerge for year end as long as UK hasn't gone over the edge. Earning growth at Vertu has been good but IMO suppressed by its acquisitive approach. Revenues have nearly tripled in the last 5 years but that has been partially achieved through issuing shares to acquire (share issuance has nearly doubled no of shares in same period). Earnings have risen approx 150% over same period.
Acquisitions tend to deflate earnings near term and take a few years to feed through into robust earnings for the acquired dealers. There is a bias to acquiring things that can be boosted/turned around. Some that may be seen in the average sales price per unit acquired being well below Vertu averages - typically acquired business run at 2/3rds to 1/2 revenue per unit compared to established franchises. There could be something dodgy in the data I have derived there or a timing factor but it could indicate both poorer sales performance that they can pick up (there's more for me to understand there perhaps through management Qs).
I think that management should hold back on acquisitions at this point and prove out their portfolios ability to produce positive cash flow even in a tough environment. If they do that they can re-rate plus show earnings growth and that puts them in a much stronger position to go back on the acquisition trail and create a new value add cycle through acquisitive growth.
I hold as I think that 'idiosyncratic' earnings growth will prove out (round number of 50% assuming no retail armageddon) and so a re-rating. This stick has held 14x PER in past and in US auto retailers have recently been at that mark. I see a double to triple in price in something quite dull with bearishness in the price and quite protected downside.
Best wishes
Paul
lavinit, I agree with you about Vertu Motors (LON:VTU) and bought some more first thing on what I thought were outstanding results in the circumstances. Just a few things to add:
The working capital situation is well explained later in their results. As Paul Scott said, they are lent new cars by the manufacturers. Even better still (from a cash situation) they can reclaim VAT on the new cars before they've either paid for them or owe VAT collected from selling them. This must create an enormous temptation to keep committing to new cars even in a slow market, especially if you're short of cash. It is a very good sign both that Vertu have not done this, and that this is a potential cause of reduced margins and delayed financial distress by their competitors.
The second main cause of cash outflow was a relative increase in second hand stocks in advance of the plate change in the expectation of lower trade ins. Again, if you were short of cash it would have been tempting not to do this (even if you had the management foresight) and so again this is a source of competitive advantage.
I agree that they need to take care not to stretch themselves with acquisitions, but there is no sign of them doing this so far, and for the reasons highlighted above (as well as the unpopularity of the sector) there could be some real bargains if they hold out.
Yes, the dealership mix is unfortunate at the moment, but hopefully more defensive in the medium term.
I actually think it is quite likely that the UK new car market has peaked forever, with near term exchange rate / diesel headwinds being replaced with rising interest rates and then changing ownership models. But I think the decline will be slow and Vertu can still make a excellent return by a) being a consolidator in a shrinking market, like Trinity Mirror (LON:TNI) b) by selling off redundant freeholds above book price for housing (or at least, at prices inflated by the future possibility of such).
Finally as icing on the cake, they also have a small but significant pension surplus. This should act as a hedge against interest rate rises affecting new car sales.
Hi. Any chance of looking at TEF. Reads alright until you get to the 2nd from last para. H1 18 will be significantly lower than H2 2018 and also lower than corresponding period last year but will be in line with expectations. Is this a warning of things to come? Share price hardly moved. Thoughts on how to read this would be welcome.
Very interesting thread today. I am a holder of AGY and like the potential upside...anyone else a holder?
So far the shares I own are up 115%...so a promising start.
Paul
I'd like to second Martin's request for your thoughts on Proactis (PHD). There is a lot that I like about the company but the volume of acquisitions worries me. I find it hard to make sense of where they are going given all the changes. And there are always execution risks in any acquisition.
Julian
Mark minervinis book is good and easy to read.
Im doing my best to work through all the books on stockopedia and currently reading. :-
Contrarian Investment Strategies: The Classic Edition: Beat the Market by Going Against the Crowd By David dreman
Fabulous book, amazing information around brokers and the inaccurracy of most broker estimates and why its a no no to recommend a sell.. Fascinating stuff. One of my favourites so far.
Combining minervinis strategy with others (ben graham) has given me modest profits without losing the intial amount invested
All this reading Im trading less and losing less on the spread and fees every time i sell.Just holding now my stocks and its boring but its growing.
redrichmond....it took me some time before I realised that boring and growing is good....most mistakes that are possible to make...I made....Always good to read someone else has the same thoughts as yourself...
Redrichmond
Where did you find the Contrarian Investment Strategies book? I can't see it on Stockopedia.
Thx
Ian
Hi Ian
I think it is this one:
https://www.stockopedia.com/screens/david-dreman-low-pe-screen-57/
On my Kindle but not yet read!
KR
Michael
Character (LON:CCT)
Only 50,000 shares (0.24%) not as many as I expected but it's a start.
"Wednesday, 11 October 2017
The Character Group plc
Transaction in Own Shares
In continuing its stated objective to enhance shareholder value, Character Group (AIM: CCT.L) announces that it has today bought-back for cancellation 50,000 ordinary shares of 5p each in the capital of the Company ("Ordinary Shares") in the market at a price of 380 pence per Ordinary Share. The Ordinary Shares acquired for cancellation represent approximately 0.24 per cent. of the current issued share capital of the Company (excluding shares held in treasury)."
I think they mentioned further share buybacks in this morning;s RNS, have let the market settle somewhat (price indicates bought last hour or two) and have announced quickly in order that they cannot be accused of creating a buying opportunity.
Expect more, if not today, then over the next week or two.
Character (LON:CCT)
As suggested in earlier post- "Expect more, if not today, then over the next week or two."
Another 70,000 shares bought in adding to the 50,000 earlier.
"In continuing its stated objective to enhance shareholder value, Character Group (AIM: CCT.L) announces that it has today bought-back for cancellation 70,000 ordinary shares of 5p each in the capital of the Company ("Ordinary Shares") in the market at a price of 385 pence per Ordinary Share. The Ordinary Shares acquired for cancellation represent approximately 0.33 per cent. of the current issued share capital of the Company (excluding shares held in treasury)."
The 120,000 total equates to around 0.6% excluding treasury.
I generally subscribe to the school of thought that tends to ignore price movements though the more I witness in the small cap market, the more it seems that there's a little more signalling here than in other markets. in saying all that, I had put the recent sell off in CCT down to PIs circling back on the FD story after reading across from the shenanigans at Accrol. So, to my naive eye, this looks like a dip to buy and I've been doing so this morning. I own Accrol too so maybe the jokes on me but unless there's something seriously underhand this stock is 'buy-with-both-hands' cheap...
Hi Paul. You've mentioned your own portfolio vs BMUS a couple of times over the last few weeks or so. It would be really interesting to get a better understanding of how your approach to your own portfolio differs to that when compiling BMUS. I get the feeling it may be technically more complex (using spread bets and other instruments), greater turnover (?) and have more large caps, but I'm only reading between the lines!
Hi Christoph,
Hi Paul. You've mentioned your own portfolio vs BMUS a couple of times over the last few weeks or so. It would be really interesting to get a better understanding of how your approach to your own portfolio differs to that when compiling BMUS. I get the feeling it may be technically more complex (using spread bets and other instruments), greater turnover (?) and have more large caps, but I'm only reading between the lines!
Yes, you're pretty much nailed it!
BMUS is just a simplified version of my personal portfolio. So I include all my real money main positions in BMUS, in roughly the same size proportion. So take Character (LON:CCT) for example - I've held a smallish long position in it for some time now, but now I've increased my position size today, it might go into BMUS. There isn't room for everything in BMUS, so I have to want to sell something, to buy something else. Whereas in my personal portfolio, I have no such restrictions because I can use gearing in spread bet accounts, thus giving more flexibility.
It's also just yet another thing to remember to do. I just haven't got the time to keep BMUS meticulously updated, so it tends to be something I do from time to time, when there's a spare few minutes. It's only an example portfolio anyway, and was initially just set up by Ed as a fun thing for all the Stockopedia team. Although I think he also had an ulterior motive, in wanting me to actually prove, with hard statistics, that my stock-picking approach does actually work well (in bull markets anyway!)
Regards, Paul.
Hi Paul,
Any views on PHD Finals today. I seem to recall that you said you were holding off from buying these until these results emerged?
Martin
Proactis Holdings (LON:PHD) gets a positive write up in today's daily email from TechMarketView. I'll probably buy when it looks as though the sellers have finished.
Regarding the timing of the Character (LON:CCT) 8am statement. I think they dropped a Clanger!
(Possibly only amusing to anyone above a certain age that still thinks the moon is made of cheese).
I'll get my coat ....
Gus.
Good morning Paul & thank you for looking at requests.
Could you please look at Scapa (LON:SCPA) and their interim results if you have time (assuming it’s £694m market cap is not too large for you)?
I hold
Hi AstonGirl,
Scapa (LON:SCPA) is too big now for me to cover here.
But I did see its trading update today, and it looks very good - ahead of expectations. The share price probably already reflects that though, as it's not cheap.
Regards, Paul.
Hi Paul, could you please comment on INSE / CEO resignation if you find the time. Thanks!
Hi Sunny350,
Hi Paul, could you please comment on INSE / CEO resignation if you find the time. Thanks!
I've had a quick look at the announcement, but not really sure what I can add.
Obviously if I held the share, then it would be a concern that the founder/CEO had suddenly departed - it might be for personal reasons, it might not - who knows? I wouldn't want to speculate on that.
My main remit here is reviewing the day's most interesting small cap trading updates & interim/final results.
Regards, Paul.
A piece of unusual news this morning is the cancellation of ZAI 's NOMAD status. A number of companies now have to scramble to get a new NOMAD or be delisted.
This adds another layer of unexpected excitement to owning AIM shares, but on this occasion I am somewhat encouraged by evidence that there is actually someone working in the AIM regulation offices. It is rarely possible to see this.
I do not believe at AIM needs more regulation (unlike pleas from others including ShareSoc), it is supposed to be a looser market and shareholders should understand that. But there are some regulations and it is necessary that those there are are followed and policed.
Your comments sound a bit hysterical to me!
I've not seen anything whatsoever at Character (LON:CCT) which suggests we can't trust management.
Sorry, I'm not hysterical at all and feel a lot better having sold Character (LON:CCT). I am a little upset at myself though for not selling when the FD left. Like many shareholders, I'd been concerned by the recent fall on no news. And today, lo and behold, we get the news!
The reason for the lack of trust are twofold:
1. I don't like share prices falling over a number of days before a profit warning RNS. It shows that someone at the company is leaking information to "certain market participants". The confidentiality of price sensitive information is the responsibility of the company management. By all accounts this happened last time they issued a warning but I wasn't a holder at the time.
2. I don't like companies that issue RNS'es when the market is open. It's pretty clear that someone knew before 8am this morning a warning was coming, so why did the rest of us have to wait an hour beyond the usual 7am release time. As someone that always reads the news relating to my holdings before 8am in preparation for the open I was caught unaware like many others this morning.
If you're not annoyed by the above, then fine, it's what makes a market but now I know why this company has always been cheap. It deserves to be!
All the best, Si
I would agree about the suspicious fall in the share price in the few days prior to the RNS.
However, this unsatisfactory trend is surprisingly common.
Regarding Character (LON:CCT), I sold immediately when the FD left. Any kind of FD departure is a red flag, but I found this particularly concerning:
* He was summarily dismissed without explanation.
* Before his appointment again afterwards there is a concentration of power with the founder, major shareholder and MD also being FD. I saw no intention of appointing an independent FD.
* Analysing the rest of the board realistically only Jon Diver would be both aware and willing to speak up if there was something wrong.
I see no valid reason for timing announcements at 8am.
In my opinion these factors create risks that make the share deserving of some kind a discount.
(Edit: Sorry everyone for repeating much of what had already been said - when I started there were no comments but I got distracted and took a long time to finish my message)
Never a good sign when a co DISMISSES CFO.
From initial research he seemed a 'lightweight CFO (not a good sign either). Why does a co with promise & potential take on a second or third tier CFO?
The Times reports: "The circumstances surrounding the sudden departure of Mark Dowding, who joined Character Group in 2012, were not immediately clear to investors, but it has emerged that a disciplinary hearing was held last week which led to his abrupt exit."
STOCKREPORT highlights "likelihood of earnings manipulation."[HIGH].
Does this suggest a further drop in share performance?
Kiran Shah, the joint managing director, co founder and biggest shareholder, has returned to the role of group finance director after Mr Dowding’s departure.....
Management are old stalwart Toy retailers, so co might be in good hands.
Character Group has warned that its performance for the year to the end of August 2018 was expected to be significantly below current market estimates. In a trading statement on 19 Sep, the group said that conditions in its markets remained challenging.
An update said: 'The board notes, however, that the portfolio of brands serviced from our UK base continue to trade well, with domestic sales holding up at levels comparable to the same period last year and against the year to date trends of the toy industry as a whole.
'Our international and "FOB" sales have been adversely effected by a combination of several factors, not least of which is one of the world's largest toy retailers entering into Chapter 11 bankruptcy protection in the US and Canada, which has had subsequent knock-on repercussions in every market where it trades (including the UK).
'Our international customers are also taking a very conservative approach to purchases.
'At this early stage of the group's new financial year the Board consider that, based on the latest sales and market data available to them, the Group's performance for the year ending 31 August 2018 is now expected to be significantly below current market estimates.
'Nevertheless, the directors believe this to be a temporary downturn and that the group anticipates returning to its previous growth pattern during the second half of the 2018 calendar year, and this ultimately is expected to be reflected in the financial performance for the year ending 31 August 2019.'
One is reminded of Ed Croft & SP team's analysis on stocks with profit warnings, namely: The Profit Warning Survival Guide which notes an overall 2 year decline after a crash (60% of the fall happening in a single/first day/40% over next 2 years."
Janet Thornton the founder, CEO and driving force behind Inspired Energy (LON:INSE) resigned today for personal reasons. I believe this to be a genuine reason as her husband remains an executive director and presumably if anything untoward was afoot he would also have departed? I think the company has now grown to sufficient size not to be too disaffected by Ms Thornton's departure.
The share price has fallen in the last couple of weeks possibly in anticipation of the announcement and may provide a buying opportunity but as I already have a decent holding I have not bought more.
Re Character (LON:CCT)
I've been reading Minervini and, if I understand him correctly, one should have bought in 2014 (when the 50 day MA moved above the 200 day MA) and sold in May this year when they crossed back again.You could argue CCT has reached Minervini's stage 3 or possibly 4 now.
I recognise his strategy differs from yours and a low PER and high yield dividends make it look more attractive now but personally, I'll sit on the sides until upward momentum is restored and those MA indicators shift back again. Why? Like many, i think a market correction is likely in the next year or so and so I worry about any investment where a recovery in performance is 18months+ away.
Is there a particular site please that explains the Minervini principles?
I feel I am rather risk averse compared to a few on here, Paul included - I am generally one to buy on good news and sell on bad news. I made a very modest profit on CCT back in 2015 when I sold them and am glad I don't hold now, and would not buy based on the statement issued. My own view on sections of the announcement are as follows:
Our international and "FOB" sales have been adversely effected by a combination of several factors, not least of which is one of the world's largest toy retailers entering into Chapter 11 bankruptcy protection in the US and Canada, which has had subsequent knock-on repercussions in every market where it trades (including the UK). Our international customers are also taking a very conservative approach to purchases.
This indicates that there are MANY factors that are affecting trading, not only Toys R Us overseas going bankrupt. Any of these could get worse. Looking at the previous update, in less than a month trading has significantly deteriorated.
At this early stage of the Group's new financial year the Board consider that, based on the latest sales and market data available to them, the Group's performance for the year ending 31 August 2018 is now expected to be significantly below current market estimates. Nevertheless, the Directors believe this to be a temporary downturn and that the Group anticipates returning to its previous growth pattern during the second half of the 2018 calendar year, and this ultimately is expected to be reflected in the financial performance for the year ending 31 August 2019.
Based on how things seem to be going from bad to worse I'd be taking the directors' beliefs with a pinch of salt.
The single biggest factor underpinning our optimism is that during 2018 we shall be introducing exceptionally exciting new products, many developed in-house which, together with the current product portfolio will, the Directors believe, give the Group its strongest ever product line up.
This all sounds really good... IN PRINCIPLE, but what if customers/toy retailers don't agree, and some of the new products flop? Admittedly, the new link ups sound promising.
I don't understand the comment "My main worry is that the price could fall further - my broker reckons that sellers have not finished yet. It's usually a mistake to buy on the day of a profit warning", though this lack of understanding is likely due to my lesser experience in the market - if one does not have a comfortable level of certainty that the price has stabilised and that it is usually a mistake to buy on the day of a profit warning, then why would one? I have seen it work the other way around, a company issues positive market and investors get sucked in on the day of announcement only for the price to subsequently decline the following day. If I don't have a good level of comfort on the day with the announcement, then I wait until the next day to see if the price continues to appreciate.
I think it has been said on here before that the "low PER and high yield dividend" combination is not necessarily a good combination, and on average in fact it is distinctly a warning sign for potentially further trouble. On the plus side, CCT's net cash position is some comfort... but if things get worse then those dividends may well get reduced.Just my own thoughts... hoping CCT pull through for all holders on here :-) The price is currently slowly (dead cat?) bouncing back, but only on lots of small buys alongside some big sales.
Hi Andrea,
I don't think there's a better substitute than buying and reading his book. It's at odds with Paul and Graham's more long term strategies (from which I have profited handsomely) but in uncertain times, I think it's worth understanding how to profit in shorter timeframes.
I Agree that Mark Minervini's book is well worth reading - it's one of the best investing books I've ever read. Possibly the best actually. It's not just that he has a tried & tested formula for profiting from multibaggers in bull markets, but the book is generally full of investing wisdom. I'm currently re-reading it!
Here's the Amazon link, which has a "look inside" bit:
https://www.amazon.co.uk/Trade-Like-Stock-Market-Wizard/dp/0071807225
What I like about Minervini, is that you can adapt his approach to suit yourself. So I don't copy his approach, but have blended in some of his ideas into how I like to do things. So personally, I will buy much earlier than Minervini, because I'm perfectly happy to sit & wait maybe a year or two for a stock to come good. Whereas he wants quicker returns, so he'll wait until the chart is signalling what he wants to see - basically he only buys into an up-trend.
Anyway, Minervinin's track record looks astonishingly good, so that's the type of person I want to learn from! Always good to consider different approaches, and his is one of the best I've ever seen.
His crucial insight is that if you search for only low PER stocks, you will actually be screening out almost all the future biggest winners. That was a huge eye-opener to me, so I'm now much more prepared to pay a high price for a stock that meets my most rigorous criteria.
Anyway, it's a great read - highly recommended!
Regards, Paul.
I'd also recommend Minervini's latest book 'Think & Trade Like a Champion: The Secrets, Rules & Blunt Truths of a Stock Market Wizard'. For me it's worth the price just for the chapter on selling.
"His crucial insight is that if you search for only low PER stocks, you will actually be screening out almost all the future biggest winners. That was a huge eye-opener to me, so I'm now much more prepared to pay a high price for a stock that meets my most rigorous criteria."
- William O'Neil makes the same point in How to Make Money in Stocks. (I can hear Ben Graham sucking through his teeth from beyond the grave!)
Regards,
Ed
Hi fwyburd,
I don't think Character (LON:CCT) is even remotely a Minervini type stock. Remember that his focus is exclusively on looking for multibaggers, and catching the big upward moves. A great strategy, if you can pull it off! I'm a fan of Minervini, but as he says himself, there are lots of different ways to make money from the market. Hence why I also like low PER/high divi yield/strong balance sheet situations like CCT. If a fundamentally good business runs into fixable problems, then the market can sometimes give us a nice entry price.
Regards, Paul.
P.S. Note that CCT also has very good quality scores on Stockopedia - generating excellent ROCE and ROE, together with a good operating profit margin. So my feeling is that it's a better quality business than the current price suggests.
Paul,
Regarding your comment "CCT also has very good quality scores on Stockopedia - generating excellent ROCE and ROE, together with a good operating profit margin", can I presume that this is only historically accurate, and in theory this state of affairs may well be debatable going forwards after today's announcement?
Andrea
Hi fwyburd
I'm a Minervini investor. Here's how I played CCT:
- Bought VCP breakout on volume 03/12/2014 @ 237. Sold all 11/03/2015 @ 332 when it broke the 50 day MA.
- Bought VCP breakout on volume 30/04/2015 @ 412. Sold all 24/08/2015 @ 474 when it broke 50 MA.
It's been trading sideways since 2015 and hasn't met Minervini's criteria since. I very much doubt Minervini would have held through the sideways consolidation. I agree with you, to me it looks like its transitioning from a Stage 3 topping out phase to a Stage 4 decline.
Morning Paul. Thanks for your informative piece on Character (LON:CCT). Do you have a view on the High Earnings Manipulation Risk in its Stockrank?
My morning smallcap tweet:
ZAI Corp Finance bombshell - disqualified as nomad. Clients need new one by 19 Oct. Clients: UKRproduct, Alpha Returns, GCM Resources ,Central Rand Gold, Univision, Eqtec, Obtala, Northwest Investment Group, Zibao Metals, Grand Group, Clear Leisure, Polo Resources.
Speedy Hire (LON:SDY), QUIZ (LON:QUIZ), Character (LON:CCT)
Speedy Hire (SDY) £180m asset based finance facility extended by 3 years to October 2022. Interest shaved by 25bp. "At 30 September net debt is now expected to be less than £65m, and this revised facility, with significant headroom, gives us greater flexibility to support our strategy for growth, and lowers our cost of debt."
QUIZ (QUIZ) H1 trading. Rev up 35%, gross margins in line.
Character Group (CCT) warns FY will be significantly below forecasts. Why did they put this out at 8am exactly?
Paul,
I bought more Character (LON:CCT) on what I agree is an over reaction by the market.
The company confirms results out on 4th Dec and therefore the closed period does not commence for three weeks. I expect they will be in the market today hoovering up the share at this price.
I think international retailers are holding off on purchases thinking that because of the ToysRus administration they will pick up excess stock on the cheap. However with 11 weeks to Christmas they can't hold off for much longer. Overseas sales are significant but only 25% of sales.
Dave
Overseas sales are significant but only 25% of sales.
Yes, but the other side of this is that most of their costs are in USD. So if the USD denominated sales also decline it is like a double whammy! Of course, it depends on where you see USD:GBP heading in light of Brexit, UK interest rates etc. in the next 12 months. FWIW I'm not bullish on GBP.
All the best, Si
Thanks Si. My comment was not currency related but refers to the part of the business more affected by the ToysRus situation
"the portfolio of brands serviced from our UK base continue to trade well, with domestic sales holding up at levels comparable to the same period last year and against the year to date trends of the toy industry as a whole."
Dave
It should be said that I generally tend to be a bit too willing to give companies the benefit of the doubt! Also note that the stock market has never really attributed a generous valuation to this company - it always looks cheap.
And today we are reminded why giving companies the benefit of the doubt is not always a good thing and why this company always looks cheap on fundamentals! The price has declined the last few trading days and this morning we get an 8am profit warning RNS. Completely our of order IMHO. I dumped the lot and should have done so after the FD left a month ago; when will I ever learn - ALWAYS sell after the FD leaves. If the management can't be trusted I just move on these days.
Good luck to those holding.
All the best, Si
Si,
I agree an FD leaving is not generally good news but in this instance the previous FD and joint MD, founder I believe and 10% shareholder resumed the role he had held 18 months prior. The statement also refers to the Board's lack of confidence in the departing FD which presumably they would not say if he departed merely due to trading difficulties.
Dave
I agree an FD leaving is not generally good news but in this instance the previous FD and joint MD, founder I believe and 10% shareholder resumed the role he had held 18 months prior.The statement also refers to the Board's lack of confidence in the departing FD which presumably they would not say if he departed merely due to trading difficulties.
This all presumes that you can trust what management say and that their explanations are totally honest. At 8am today I realised I could not trust them. At the very least they run a very leaky ship and have no problem putting out profit warnings whilst the market is open. Both red flags to me.
There's plenty more fish in the sea and I don't have to invest in Character (LON:CCT). Onwards and upwards. Another lesson learned!
All the best, Si
Hi simoan,
Your comments sound a bit hysterical to me!
I've not seen anything whatsoever at Character (LON:CCT) which suggests we can't trust management.
When the problems emerged with Toys R Us in Sept 2017, they informed the market immediately, with the caveat that they didn't yet know the full financial impact. Today they have updated us again, giving more details. So what's the problem? I agree that it would have been better to issue the RNS at 7am, not 8am, but that's hardly a crime is it?
Anyway, looks like I probably bought your shares, so I'll take good care of them! ;-)
Regards, Paul.