Small Cap Value Report (Wed 11 Oct 2023) - FORT, CLX, WJG, BRCK, SDG

Good morning from Paul & Graham, here we go again! Busy again for news, and lots of backlog things too, so we're already hard at work!
Graham's Youtube show is live again at 11:30 today (recorded, so can be watched later if you're interested - I think they're very good, and an easier way to absorb the SCVRs if you have the free time), covering: Watkin Jones, Calnex, and Eneraqua. I'll be taking a break and tuning in myself, with possibly some gentle heckling in the chat box ;-)
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Summaries
Forterra (LON:FORT) - down 6% to 135p (£288m) - Q3 TU - Paul - AMBER
It's a profit warning, but the market seems sanguine about this, with only a relatively modest drop of 6% - possibly because industry statistics could have already been known by many investors. Also the share price has already fallen below pandemic lows, anticipating weaker trading. I go through the detail below, and can see this might be a good recovery trade in the medium term, but there are also some doubts.
Calnex Solutions (LON:CLX) - down 30% yesterday to 66p (£58m) - Trading Update (profit warning) - Graham - AMBER - BLACK [PW] on summary spreadsheet
This was an awful profit warning with revenues now anticipated to be 20%-30% lower than expected for the full financial year. Large customers are responsible for a large chunk of Calnex revenues and they have been slow to place new orders. I’m keeping an open mind.
Watkin Jones (LON:WJG) - down 5% to 33p (£85m) - FY23 Trading Update (profit warning) - Graham - GREEN
This developer has had a very difficult year. It posted a huge profit warning in July and today brings another, albeit of a milder variety. A loss seems likely for FY23, then modest profits in FY24. But the cheapness has intrigued me, with NAV much higher than the market cap.
Brickability (LON:BRCK) - flat at 46.5p (£140m) - Trading Update & Acquisition - Paul - AMBER/GREEN
An in line with exps update for H1, but a FY 3/2024 downgrade is slipped out via Cavendish. The 10% impact on FY forecasts is partially offset by a significant sized acquisition also announced today. With a PER below 5x on updated numbers, I cannot ignore the value here, whilst acknowledging the macro headwinds. I like its capital-light distribution model, which seems better than the capital-intensive manufacturers.
Sanderson Design (LON:SDG) (Paul holds) - up 1% to 106.5p (£76m) - Interim Results - Paul - GREEN
Good H1 results, and in line FY outlook. Bulletproof balance sheet. Priced to warn on profits, but so far it hasn't, thanks to buoyant licensing income. I remain attracted to this high quality business. Takeover bid possible? Wouldn't surprise me.
Paul's Section:
Forterra (LON:FORT)
Down 6% to 135p (£288m) - Q3 TU - Paul - AMBER
Forterra plc (the 'Group'), a leading UK manufacturer of essential clay and concrete building products, provides this third quarter trading update for the nine-month period ending 30 September 2023 (the 'period').
It’s bad news, not entirely unexpected though, as there’s publicly available data about construction activity I believe, hence to some extent the market should have anticipated this news -
The signs of market improvement seen in May and June did not continue into the second half with market demand deteriorating in July and August.
Figures published by the Department of Business and Trade show UK brick despatches in July and August 2023 averaged 16% lower than in June 2023, and 28% lower than in the corresponding period in 2022. Within this, August was weaker than July and our own despatches suggest a further softening in September. These figures also highlight that UK brick industry despatches are currently running below the levels seen in 2009.
Pricing has “remained resilient”
The above has impacted profit -
…expect full year EBITDA to be below previous expectations.
Cutting production, consulting on mothballing a factory in Claughton.
Inventories building, as fall in demand faster than reduced production.
New brick factory in Desford is coming on line, seems rather ill-timed, but I’m assuming it will be more efficient, being new.
Outlook - it's assuming 2024 will be similar to 2023 (no signs of green shoots yet then).
There are some positives though -
As we set out at the half year, we expect FY24 results to benefit from a more stable energy cost environment, a stabilisation of customer inventory, the substitution of imported bricks as well as the full year benefit of previously announced cost reductions, offset by reduced operating efficiency driven by a reduction in production.
Growing political focus on increasing housing supply ahead of a general election reinforces the Board's confidence in the long-term industry fundamentals and the Board remains confident that the Group remains well placed to benefit when market demand recovers.
Broker update - there’s plenty of detail in the above, but no financial specifics.
So the next step is to see if any broker updates crunch the numbers for us? Yes, we have a company-sponsored update from Progressive.
Key points (it’s a Dec 2023 year-end) -
Forecast revenue reduced by 9% to £367m (FY22 actual was £456m)
Adj PBT forecast reduced by 26% to £27.9m (FY22 actual: £70.6m!)
This concerns me a bit - year end net debt now forecast at £82.2m (prev. f/c: £59.9m) - *check the last balance sheet* - see below.
Forecast EPS now 9.8p (FY22 actual: 26.0p) - vs StockReport consensus of 13.6p
What we’re clearly seeing above is a sharp downturn in revenues, and a geared impact on profit, with EPS down 62% comparing 2023 with 2022. Obviously that’s driven by macro factors, primarily soaring interest rates making a house purchase less, or unaffordable for many potential buyers. Corresponding retrenchment in house production by some of the big builders is clearly a knock-on effect. All of this is well-known, and explains why share prices of both builders, and building supplies companies, have been falling so much.
Then at some point share prices begin to factor in a recovery, usually months before an actual recovery is evident. We know the drill! It’s just the timing that is difficult to predict, with rallies so far often turning out to be false dawns.
Timing doesn’t matter so much if you’re patient and unflappable as an investor, and if companies have strong balance sheets (thus eradicating dilution or solvency risk).
Or, if you’re a risk-taker, then homing in on the more geared companies with bombed out share prices can (sometimes) deliver the biggest % gains, but at the risk of a wipe-out.
Your money, so your choice, in terms of what level of risk you’re prepared to take. FORT looks low-medium risk to me, depending on how macro develops.
In smaller caps, the lack of liquidity often means price moves are exaggerated too - which is what provides us with opportunities, but also causes us stress!
Valuation - I’m quite impressed that the share price has (so far anyway) only dropped c.6% to 135p (at 08:51), although on low volumes, so anything could happen in future. The most I can say is that at least there hasn’t been an early panic sell-off.
On the revised 2023 forecast of 9.8p, that’s a PER of 13.8x
Bear in mind this is a sharp downturn year, so paying 13.8x a bad year’s forecast earnings, seems to me pretty reasonable. The big question is, what extent of earnings recovery are we anticipating in future, and over what timescale? Also could pricing come under pressure in future, if a glut develops (sounds like that’s already happening, based on the inventories rising, and having too many factories). So we cannot just assume that everything returns to normal soon, especially as FORT says it sees 2024 being similar to 2023.
On balance then, I suspect earnings could remain under pressure, and reduce further, but that’s little more than guesswork.
Dividends - are likely to be cut sharply, from 14.7p in 2022, to 5.5p in 2023. A further deterioration in trading could see divis cut more, or completely, but they should rise again once performance recovers.
Balance sheet - always crucial for me, especially in a downturn.
NTAV was very strong at June 2023, at c.£193m, but that’s dominated by £245m tangible fixed assets - obviously making bricks requires a lot of land and equipment.
Working capital was £151m current assets (incl. £17m cash), and £126m current liabilities incl. negligible interest-bearing debt. Bad debt risk from big customers should be close to zero, given the balance sheet strength of the big housebuilders, assuming they buy direct (they might buy through Brickability (LON:BRCK) too possibly?)
The bank debt is all in long-term liabilities, of £67m, and I reckon this element will have risen to nearer £100m by year-end. Therefore it’s important to inspect the last Annual Report to check what the bank facility terms are, in particular the net debt: EBITDA covenant.
Forecast EBITDA for FY 12/23 (after today’s PW) is still high, at £53.9m (per Progressive note), which stacks up OK against the forecast Dec 2023 net debt of £82.2m, a multiple of 1.52x, which should be alright I think. That’s assuming the bank covenant definition of EBITDA is the same as the Progressive forecasts. So no alarm bells ringing here over debt, in my opinion.
Paul’s opinion - the muted initial reaction to this profit warning is quite encouraging I think.
Is it too early to be fishing for the bottom in the share price, given that FORT says it’s not expecting any recovery in 2024? Possibly. Prices could fall, worsening profits, if there’s a glut of bricks. Or, political measures to step up housebuilding might trigger a recovery. Also, interest rates are a big unknown too - a rapid fall could trigger a very strong asset price bounce, and rebound in housebuilding. We just don’t know!
Meanwhile I think FORT is securely financed, with a nice balance sheet, although net debt creeping up a little high.
It’s going on my watchlist, but I’m not ready to push the buy button yet. So for now, I’ll go with AMBER, but I can see attractions here as a recovery trade over the medium term.
Brickability (LON:BRCK)
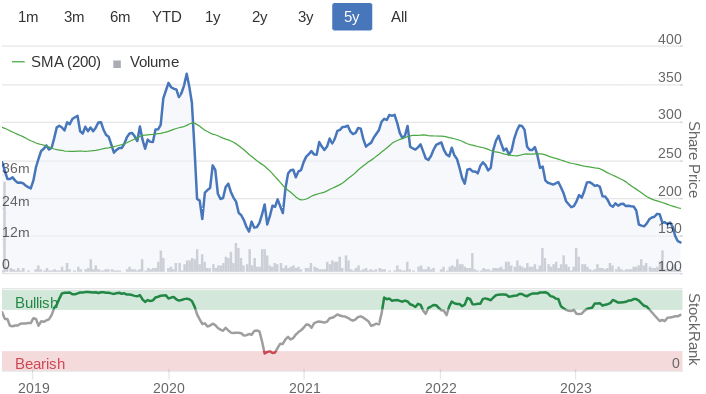
Flat at 46.5p (£140m) - Trading Update & Acquisition - Paul - AMBER/GREEN
Brickability Group plc (AIM: BRCK), the leading construction materials distributor, issues the following trading update for the six-month period to 30 September 2023 and is also pleased to announce the acquisition of Group Topek Holdings Limited, a specialist cladding installation and remediation contractor (the "Acquisition").
Continuing the bricks theme, this is a distributor of bricks, often on a drop-shipping model (where it acts as an intermediary, but doesn’t handle the physical goods). Lots of acquisitions mean it has also diversified into other building products.
I have a favourable impression of this company, and particularly liked the last webinar they did, when management struck me positively as tenacious, and answered all my questions very well. That’s just subjective of course, so could easily turn out to be wrong. Outsiders never know what’s really going on inside any company, although we like to think we do!
Acquisition of Topek - a substantial deal, £27m cash up-front, plus up to £17.7m in deferred consideration over 3 years, subject to performance, and encouragingly with BRCK having the option to pay in shares, at the then prevailing share price. I like that structure.
Topek is a specialist cladding installation & remediation business, and is said to complement BRCK’s other 3 cladding-related businesses.
It’s said to be earnings accretive, and is being funded from cash & an enlarged £100m debt facility. This helps reduce bricks from 80% at IPO, of revenue to 60%Sounds intriguing.
Trading Update - strikingly better than FORT, with H1 trading being in line with expectations.
However, it sounds more cautious, without quantifying it for H2 -
Whilst the Group has traded in line with Board expectations through H1 FY24, and the Acquisition will be immediately earnings accretive in the current year, forecast reductions in newbuild volumes are expected to have a corresponding impact upon the performance of the Group's existing businesses throughout the second half of the current financial year.
Is that a veiled profit warning? Yes it is!
Let’s see what the brokers say.
Broker update - Cavendish comes to our rescue, many thanks, with a clear update which trims forecast underlying EBITDA in FY 3/2024 by 10%, and 20% in FY 3/2025. This is then partially offset by additional profit from the new acquisition.
New adj EPS is 9.4p for FY 3/2024 (StockReport consensus is 9.75p), and 9.5p for FY 3/2025.
These make the share price of 46.5p look very good value - a PER of only 4.9x.
Paul’s opinion - I can’t ignore the super-low PER, in a really tough sector, and really bad macro. Imagine what that PER could drop to, once recovery starts.
I’ve previously been green on BRCK, but went amber on 5/9/2023, after a wobbly-sounding update and the potential for a profit warning.
Today we basically do get a beautifully finessed, mild profit warning for H2. But that’s fine I think, as macro conditions are pretty horrible, and the share price has already tanked.
It’s been suggested that BRCK’s distribution (as opposed to manufacturing) of bricks is arguably a better, and less operationally geared business model. I think comparing FORT with BRCK today, that seems to stack up. Yet BRCK is much cheaper on a PER basis, despite seemingly being more robust, and less cyclical.
BRCK would be my sector pick, I like it at this bargain price, and I could be tempted to dip my toe back in with a starter position, at some stage, who knows?
Sanderson Design (LON:SDG) (Paul holds)
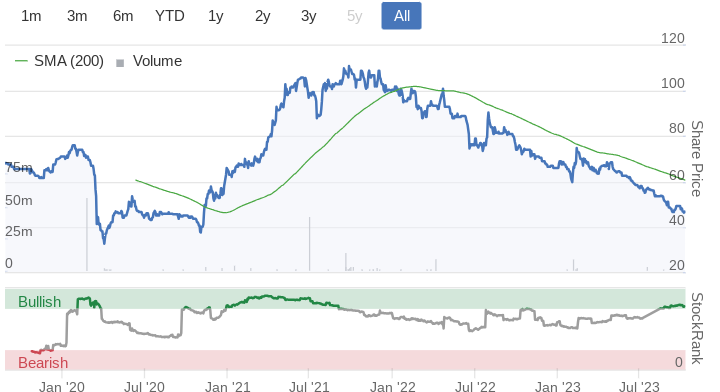
Up 1% to 106.5p (£76m) - Interim Results - Paul - GREEN
Sanderson Design Group PLC (AIM: SDG), the luxury interior design and furnishings group, announces its unaudited financial results for the six months ended 31 July 2023.
Let’s change the order around a bit, by jumping to the company Chairperson’s summary -
"We are focused on growth opportunities in the US, where we are currently under indexed, on driving licensing income internationally and on mitigating the softness in the UK market through cost saving measures.
Our licensing activities had an outstanding first half and continue to drive the Group's profit growth in the current year.
As we enter the key autumn selling period, we are encouraged by the high level of sampling from recent product launches, by our pipeline of licensing opportunities and by the strength of our balance sheet. The Board's expectations for the full year remain unchanged."
I had to read the above section twice to understand it. In particular, industry jargon such as “under indexed” might mean: performing worse than competitors, or might mean that SDG product is not properly exposed to enough distributors, I’m not sure, but from the context it’s possibly the latter?
Also, “driving licensing” income at first conjured up images of high end fabric or wallpaper coverings for peoples’ driving licences - what a lovely idea for a niche product I thought, I must spangle up my own identity documentation. No that can’t be right! This also reminded me of school, having to wrap dilapidated textbooks from the 1950s with torn out sheets from discarded wallpaper sample books. Anyway, back to the plot.
Given tough macro, the financial highlights look impressive to me - in brief:
H1 revenue flattish, down 2% to £56.7m
Adj PBT up 8% to £6.8m - impressive that this grew on flat revenues, and a nice profit margin too.
Adj underlying EPS 6.6p, just for half the year remember (which look roughly similar in seasonality)
Adjustments are small, which reassures.
Retains a lovely net cash pile (excl. leases) of £15.9m - significant relative to the £76m mkt cap.
Recording of the analyst meeting is available here, I’ve just started watching it.
Balance sheet - for the size of business is really strong. Also bear in mind that SDG also has valuable back catalogues of designs, which are very valuable.
I’ve been through all the detail here numerous times before, suffice it to say that SDG’s balance sheet remains completely bulletproof in my opinion.
The only unusual item is the £4m increase in long-term receivables, re minimum income from licensing deals. So this has been booked to profit, but takes time to turn into cash later.
Paul’s opinion - overall I think SDG is trading well (thanks to bumper licensing deals) in touch macro. It’s very well-financed, and (subjectively) I think well managed.
The stock market seems to have priced-in a profit warning that, so far anyway hasn’t happened.
I see this as a quality company, at a bargain price, but could easily drop 20-30% on a future profit warning, like so many companies. Hence why owning a basket of them, and accepting that one or two might disappoint, is my preferred approach at the moment.
It could be a niche bid target too.
Overall, thumbs up from me.
Graham’s Section:
Calnex Solutions (LON:CLX)
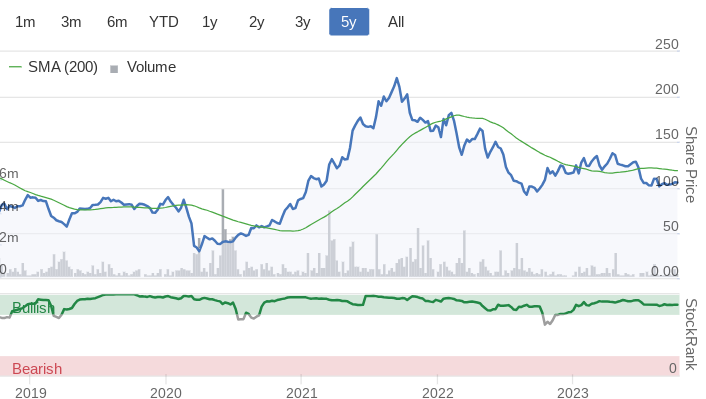
Share price: 66p (-30% yesterday)
Market cap: £58m
Calnex Solutions plc (AIM: CLX), a leading provider of test and measurement solutions for the global telecommunications and cloud computing markets, provides an update on trading and outlook for the full year to 31 March 2024 ("FY24") and beyond.
This share dropped like a stone on yesterday’s trading update. It already had a very serious profit warning last March:
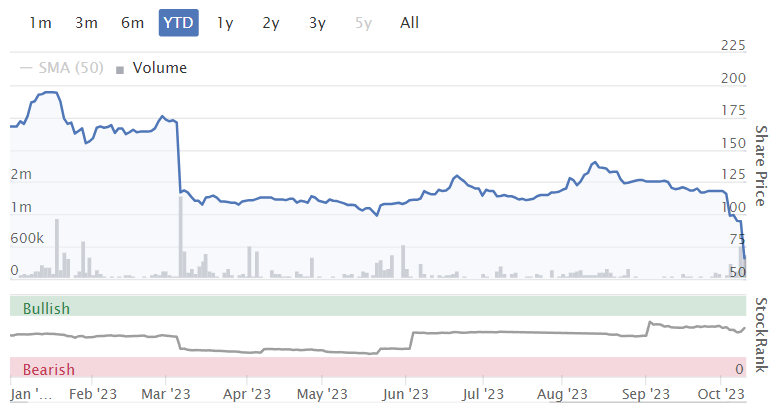
Here are the key points:
“Order inflow has remained at the subdued levels experienced at the start of the year, with the precise timing of future customer orders remaining uncertain”. The outlook for the sector “has not developed momentum”.
Revenues for H2 should be higher than H1, but revenues for the year as a whole should be “20-30 per cent below market expectations”.
You probably don’t need me to tell you that this is a huge miss versus expectations.
Cavendish have suggested revenues for FY March 2024 of £17m; the previous consensus forecast was £24m.
Cash position is £13.5m, “following investment in inventory”. Scrolling back to the most recent full-year results (for FY March 2023), I see that the cash figure then was £19.1m.
That’s a £5.6m cash outflow in six months, apparently due to inventories increasing. But the total inventory balance six months ago was only £2.7m.
Does this mean that the inventory balance has doubled or even trebled in this short space of time? During a period when revenues fell?
This says to me that the company was truly blindsided by the reduction in orders. If they had predicted lower orders and lower revenues, then surely they wouldn’t want their inventories to increase like this?
CEO comment gets in the obligatory mention of AI!
Whilst the telecommunications market outlook is currently challenging, the expansion of our product portfolio to areas outside of telecommunications and our strong sales pipeline mean we are confident in a return to growth in FY25.
Looking to the longer-term, the underlying market drivers continue to build, such as the need to upgrade telecoms infrastructure to deliver the promise of 5G, and to enhance data centre operations to support the demand for cloud computing and advancements in AI and Virtual Reality technologies. As a result, our confidence in the long-term prospects for Calnex remains high.
Graham’s view
I feel hamstrung here by my lack of understanding of Calnex’s products. So instead of giving my conclusions, here are some questions which I would like to ask:
To what extent is this company’s success due to technology that it owns, especially patents and owned software? The website GoodIP lists 11 patents globally for Calnex Solutions Ltd, which doesn’t strike me as a lot. A big company such as Google LLC has nearly 18,000. Strix Ltd ( Strix (LON:KETL) ) has over 1,000.
If the company is not relying primarily on patented technology, then what is its unique selling point to customers? E.g. is it the design expertise of Calnex employees?
How can the company manage its customer concentration risk better? I see that its top 10 customers were responsible for nearly half of its revenues over the past three years. It doesn’t take many of them to slow down their orders to produce a nasty profit warning such as that we have just witnessed.
Checking the StockReport, I see that Calnex passes some bullish stock screens that I usually quite like: the T Rowe Price Growth Screen, the Philip Fisher Growth Screen, and the Neglected Firms Value Screen.
The Quality Metrics have recently been excellent:
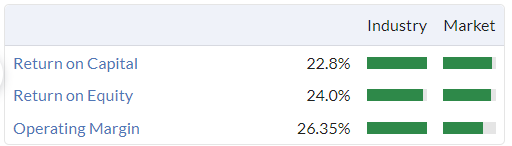
Also, as Roland has previously noted, the CEO Tommy Cook owns 20% of this one, so that’s a positive.
As you can probably tell, I haven’t formed a strong opinion on this one. So I’ll have to stay neutral for now. I’m open to the possibility that it’s a quality company that is simply going through a tough time with its concentrated customer base.
Watkin Jones (LON:WJG)
Share price: 33p (-5%)
Market cap: £85m
This homebuilder and developer provides a full-year trading update for FY September 2023.
The year just finished:
The company “was successful in achieving its operational objectives”, however there have been “certain additional costs, including acceleration costs to ensure successful completion on two schemes”.
The company now expects revenue of over £400m and underlying PBIT of “approximately breakeven”.
PBIT seems to be the same thing as adjusted EBIT, i.e. adjusted earnings before interest and taxes.
The RNS doesn’t give me all the information I need, but the latest note from Progressive Research helps a lot: they have reduced their pre-tax profit forecast by £3.5m, from breakeven to a £3.5m loss.
They also cut their revenue forecast by 7% to £419m. So it’s looking like a miss on revenues (on forecasts which had already been downgraded).
The current year:
There is no change to guidance for the current financial year, FY 2024.
The existing guidance (as set out in July) is that the company will generate PBIT of £15m to £20m in the current financial year.
The company already has secured revenue of £330m, but still has some work to do to get to the £400m total. I see that the StockReport shows an older £500m revenue estimate - estimates have fallen very significantly from that level.
Net cash is better than expected at £43m (prior estimate £20m).
Graham’s view
Paul has commented on this one much more frequently than I have (see the archives). The last time I looked at it was back in October 2022, at 100p per share, when I took a neutral stance, noting that the shares were trading at a high premium to NAV and worrying that the company’s strong earnings record might not be sustainable in a period of higher interest rates.
The most recent interim results showed net assets of £165m, or £153m excluding intangibles.
So whereas this stock previously traded at a big premium to NAV, it’s now at a significant discount.
Earnings have evaporated and the company is now likely to post a loss. So on a P/E basis, this is going to look expensive. Whereas when earnings were strong, it looked cheap!
But as we’ve previously observed, cyclical companies often look cheap when they are expensive, and then they look expensive when they are cheap.
Watkin Jones now satisfies the Ben Graham Deep Value checklist:
These shares are down by 67% year-to-date, and down by 83% over five years.
The net cash balance now covers half of the market cap.
So I’m going to turn positive on these shares. One for the bottom drawer, perhaps?
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

80 comments
My sincere thanks to rmillaree, Tommy H and Boon for responding to my post this morning.
In response I will go through the Saga numbers very closely as I agree with rmillaree that profitability per passenger, bearing in mind the cost of the assets employed namely 2 very expensive Ships, does seem dissappointing. Saga will say "we have to be competitive in a very competitive market" I guess.
Tommy H I have for the last 3 months been using "Stops" and like you I use 20% or less if the share keeps falling which tells me I got my timing wrong.
Boon I have 22 Holdings with 30k in cash. In 2021/22 I averaged 30 Holdings.
hi portugull
Saga (LON:SAGA) will likely make £85-90m of ebitda on the 2 cruise ships next year. More importantly the cashflow (after repayments of debt principle and interest) should be £20m+ (in H1 it was £8m and is on track to exceed)
With River cruise and travel now moving into net cashflow as well this adds to that.
So the key is not the Cruise business making hay but the Insurance business - assuming market re-pricing happens and net cash generation returns to normal that's where you get your kicker.
At that point the business is paying off large chunks of the ship debt each year and generating cash inflows that are easily enough to bring net debt to ebitda into that 2-3 range.
So it isn't ships that is disappointing at all or proving a drag on the share price - it is Motor insurance cash generation (or lack of) which is keeping debt/ebitda ratio too high.
YouGov (LON:YOU) now up nearly 30% since yesterday morning. Paul, you teased us with the prospect of some revelations from the accounts last night. Happy to wait until tomorrow or Friday if you've done enough for today. Please just don't forget us holders :-)
Sorry BnB, we're just getting overwhelmed with news every day at the moment, it's almost impossible to concentrate and type up notes when you've got a blizzard of news & views coming at you from all directions!
The short version with YouGov (LON:YOU) - I've not looked at it for several years, and clearly they've built a super business. However, it seems to be run for the benefit of the staff and management, with share-based payments and purchases of shares for the employee trust considerably dwarfing shareholder divis.
Also the highly material acquisition in progress is key to deciding how things are likely to progress. Doesn't look cheap to me.
All said though, it looks a very interesting business, but not something I would pay anything near £1bn for. Given the superb track record though, and high operating margins, it might be worth paying up (which it was in the past, as it turns out).
Regards, Paul.
Hi Paul
Thanks for your thoughts on YouGov (LON:YOU). It’s a sad fact that businesses of this vitality rarely come on offer without substantial SBC. You’re right to raise it but it goes with the territory. Look at Eagle Eye Solutions (LON:EYE) for example. Hopefully there are sufficient scraps for us ordinary shareholders to feed on.
Regarding Calnex Solutions (LON:CLX) I noticed this quote from the Spirent Communications (LON:SPT) warning last week.
‘…….initial 5G Standalone (SA) launches have remained sluggish during 2023 due to the complexity associated with deploying…….’
For me, that comment seemed to resonate with the political controversy about Huawei being one of the few suppliers capable of delivering 5g, and also the commentary in the Calnex prospectus which suggested the step change in complexity associated with 5g would be a growth driver for their testing technology.
If some of the slowdown in 5g rollout is being caused by other factors which are not directly related to economic concerns then that in turn could impact the timing of a pickup in activity for Spirent and Calnex.
Are there any subscribers with industry knowledge who could comment on this question – is the slowdown in 5g rollout mainly driven by economic concerns or are their other factors at play e.g. technical issues, safety concerns, planning issues? Thank you.
Are there any subscribers with industry knowledge who could comment on this question – is the slowdown in 5g rollout mainly driven by economic concerns or are their other factors at play e.g. technical issues, safety concerns, planning issues? Thank you.
I think you need to take into account who the end customers are for 5G equipment. Generally they are large incumbent, highly indebted, telecoms companies. Look at the balance sheets of these companies. They are bound to have one eye on their future debt requirements in a rising interest rate environment. IMO it’s way too early to call the bottom for the telecom industry.
I think you need to take into account who the end customers are for 5G equipment. Generally they are large incumbent, highly indebted, telecoms companies. Look at the balance sheets of these companies. They are bound to have one eye on their future debt requirements in a rising interest rate environment.
Undoubtedly correct. The flip side of the argument is that the incumbent telcos are pretty much mandated by national governments to implement 5G. There’s only so far that they can procrastinate before political pressure threatens their licenses.
I've been out of the industry for a while, but this article gives a pretty good explanation.
https://www.bttcomms.com/4g-vs...
Basically, the range of 5G is terrible 1000 feet compare to 4G where you get about 10miles.
So if you want to have 5G coverage you need a ridiculous number of cell towers. It's just not feasible - both with planning and cost.
To me it's completely the wrong technology for what the industry actually needs/wants. It would have been much better to get a smaller bump in speed and keep the same range.
And on top of this it is easier for networks to link what 5G cells they do install -typically in busy metropolitan areas - back to the 4G packet core rather than investing in 5G SA. The jump in electricity prices last year also had a shockingly huge impact and has focused the minds of operators on turning off 3G cells as a priority. So 4G plus a smattering of 5G cells (and retaining the old 2G network) is good enough for now for many operators.
I'm not sure many "investors" bother to read the annual reports of the companies they invest in - but they should!
In the Calnex FY23 annual report, under the section on principal risks it notes: "In FY23, 69% of Calnex’s orders were distributed through Spirent."
Now on the 4th October Spirent released their trading update commenting: "The telecommunications market is extremely challenged at this time, with Spirent's largest customers delaying their expenditure and technology investments. The uptick in demand we witnessed in the second quarter dissipated over the summer months and the anticipated rebound in September has not happened"
Had they read the annual report, Calnex investors would have taken notice of Spirents profit warning and put 2 and 2 together. They would have been able to get out around the £1 level.
Thanks for your responses which have answered the questions I have been pondering.
It will be interesting to see if @cer is affected by the telecommunications slowdown. With less direct exposure to 5g it was able to shrug off the first round of warnings from Spirent and Calnex.
For Calnex Solutions (LON:CLX) watchers I noticed Spirent Communications (LON:SPT) released a bullish 5g report on Investegate on 20th Feb.
The report points to an improved outlook for stand alone 5g network deployment and talks quite a lot about testing.
Gore Street Energy Storage Fund (LON:GSF) Have I missed an event regarding this fund. Price is falling sharply- yield is now 12%. Cannot see and Company RNS to explain or any macro event ?
Gresham House Energy Storage Fund (LON:GRID) - A lot of funds in this sector are falling Gresham House Energy Fund has fallen from £1.70 to £0.89 in the last year, there is hardly anything moving northwards. On a separate issue, not sure if anyone follows Midas Share tips in the Daily Mail on a Sunday but surprising how they only provide update on tips most of the time when the share price has increased not when it has decreased. For example they tipped £HMI (Harvest Minerals) at 13p now just above 1p. I have e-mailed twice querying why they don't provide updates when share price has decreased, yet to receive the courtesy of a response.
Gore Street Energy Storage Fund (LON:GSF) Have I missed an event regarding this fund.
The SP of all similar cleantech instruments is being hit by an interest rate double whammy. On the one hand, it’s much harder for developments to show a profit at higher costs of capital, so the price must fall to reflect the diminished earnings. On the other, the dividend yield needs to show an attractive spread above the risk free rate, which has exploded upwards. And yields move inversely to values, which must fall to deliver the required yield.
All the renewable infrastructure funds have been whacked for the reasons you have given (basically all related to higher interest rates), but the battery storage companies have taken an additional hit due to a sharp fall in revenues within their particular niche (I haven't looked into detail as to exactly what's caused this or if it likely to improve).
Most of the other renewables ITs have performed well in terms of cashflow. I would personally much prefer something like Renewables Infrastructure (LON:TRIG) if investing in the sector as it offers better diversification and fully operational, but still on a 25% discount.
I need to look further US and Irish income seems to be holding up. UK is weak.
That's right, Gore Street Energy Storage Fund (LON:GSF) made a deliberate effort to be well-diversified geographically and that's certainly helped them. I guess the other thing with them is the development risks - they have a lot of assets still in the construction phase and that obviously involves risks and costs. As it stands the dividend is not covered.
Gore Street Energy Storage Fund (LON:GSF) I hold ;-( I get they would have to issue new cash more cheaply but their B/S has almost no debt, so they should maintain margins and pay a div of somewhere close to 11% - not bad if your bought the shares yesterday! It looks too cheap to me but expect to see a good yield in the short term not a recovery of price.
My bet would be regulatory... some bombshell going through consultation, bill in parliament, etc... causing the tanking of Gore Street Energy Storage Fund (LON:GSF)
As always, the key risk of investing in a highly regulated environment is that the company's fortunes are sometimes dictated by minor changes in government regulations and policies. To be successful, requires keeping a finger on the pulse of all these changes... hard for anyone to do who's not plugged in to the industry, or plugged in to legislation and politics.
Gresham House Energy Storage Fund (LON:GRID) . I agree it's the sector bearishness and perhaps a bit of selling of ESG funds forcing the pace. But at least five directors bought small amounts at higher prices. If you really want to push it though, I attended the Capital Markets event of something a bit similar, Gore Street Energy Storage Fund (LON:GSF) last week, couldn't see anything going wrong with the thesis that got me buying at 78p against a NAV of 115p. NAV now 116, I bought more at just under 70p, for 11% yield at this price. No recourse needed to new equity, their cash will go to identified projects which will increase NAV further. Sometimes price are bonkers because of the infectious nature of fear. I am very confident this will get back closer to NAV in two years. Even with a continuing discount limiting it to, say 100p, that's over 60% in two years. Perhaps people are greedy for more?
GCP Infrastructure Investments (LON:GCP) and Triple Point Energy Transition (LON:TENT) seem undervalued at this point too. May I point out that none of these are 'going to zero'?
If anyone cares I've started listening to Algys Investment Podcast 6 episdoes, I've listened to Terry Smith & William De Gale so far both been good.
Housebuilders et al... doesn't seem to be any impact at all yesterday from Keir Starmer saying he will build millions of new homes.. thought that comment might be a catalyst... loathe as I am to ignite a house prices discussion..does that mean the market doesn't believe him?
Housebuilders et al... doesn't seem to be any impact at all yesterday from Keir Starmer saying he will build millions of new homes.. thought that comment might be a catalyst... loathe as I am to ignite a house prices discussion..does that mean the market doesn't believe him?
He’s a politician, so why would anyone believe him? You’d have to be a fool, especially as we approach a general election. He can promise whatever he wants because he knows he’ll have a ton of excuses when he doesn’t deliver. How you can make a business case for building a million houses no one can afford, I have no idea.
Reading through viewers comments and profit warnings, council funding shortages, its interesting that Rishi has indicated HS2 money will be provided to the local councils so they can allocate accordingly. Call me cynical but isn't this passing the buck down the road, I can envisage the headlines in the passage of time, that the money was provided but the projects were not delivered blaming it on the councils who we all know that most are in strapped positions and struggling to provide local services, fixing potholes etc.
Rishi has indicated HS2 money will be provided to the local councils so they can allocate accordingly.
Call me cynical
probably rightly so !!!
I was reading that the list of projects issued that could benefit was actually specifically going to stuff that had previously already had funding secured and included projects that were completed many years ago likle the manchester airport link. The reality is probably that there is no pot of cash and whether it goes anywhere useful or not if it does exist i think we should all be cynical of.
Manchester Airport link was clarified as extension to another terminal.
What I found most outrageous was that 1/3 of the savings on a capital project will be recycled into funding revenue repairs, filling potholes. No mention of measures to address the 10 year wait to connect renewables to the grid, to support more charging points and the construction of new homes.
Does this go back to previous promise the world to win votes strategy? Such as scrap all student debt.
If he was talking we are going to make fundamental changes to land allocation and planning laws, have spent ages looking at the details and have a plan for NIMBYs and all that...
After a very trying year in the Markets I have been reviewing my loosers and by that I mean my "real stinkers"
Boohoo (LON:BOO) Saga (LON:SAGA) RBG Holdings (LON:RBGP) GB (LON:GBG) Anglo Asian Mining (LON:AAZ) and Fresnillo (LON:FRES) are my big loosers because I allowed them to fall without taking action. Entirely my fault.
I listen to Pauls Weekend Podcasts which are brilliant and very amusing at times and he feels Boohoo may be taken private so I might as well hang on.However it seems it is Shein the Chinese Competitor who is eating their lunch that is the biggest problem.
Saga I keep convincing myself just needs time to truly benefit from its 2 new Cruise Ships.
RBG is 85% down so why sell at the bottom? But will it go to zero I hear you ask?
GBG seriously overpaid for its acquisition in the USA so I am fairly confident it will recover and I have made £15k of profits on this share in the past.
Fresnillo is down 54% but in the recent past Sept 2020 I made a £10k profit so I feel I just have to be patient.
AAZ has fallen dramatically since Jan 2023 from 123p to 50p leaving me down 70%.
I have put up this post as I suspect I am not alone in having this problem and I would welcome all views.I think it was Mark Minervini who said if you dont use stop losses it is like driving with no hand brake. Food for thought.
Hi portugull. Youve identified the problem yourself, and you probably know what the solution is.
All I'd add is before pressing the buy button have your downside plan already formed in your head. If you're using a stop loss write it down, draw a line on a chart or set it with your broker so you aren't tempted to move it.
Saga (LON:SAGA)
Saga I keep convincing myself just needs time to truly benefit from its 2 new Cruise Ships.
Think of the current conditions ref cruising - i would say they should be right in the middle of a purple patch right now - they have very decent booking rates etc. However the anticipated profits are still non existent ?
ref recent update ref cruising segment
At 24 September 2023, the booked revenue for the full year of £155.8m was 46% ahead of the same point in the prior year, with the volume of booked passengers 27% ahead. This places the business on track to return to an Underlying Profit Before Tax4 for the full year, in line with previous guidance.
Note saga is an incredibly difficult one to value it could easily be back at 300p in no time at all or could be closer to nil if they need to raise funds at time shareprice is depressed.
If they cant make fantastic profits this year ref cruising whats going to be materially different next year ?
Note there is some hope as booking for next year and prices for next year and up on where we were this time last year - perhaps eaking 15% extra icnoem makes all the difference if that can all be booked as profit in a good year - but why are they not making profits right now ?
Ref overall approach there is no magic answer you pay your money and take your chance - all i would say is that iif you are nvesting in companies without rock solid balance sheet that includes cash in the bank and no large payables that arent funded from liquid cash you are always leaving yourself wide open to quick price drops if the begging bowl may be needed.
Hi Portugull
Firstly the fact that you have looked at your portfolio, and shed a few tears that is a good step.
There is not a wrong or right answer, each of us has our own plan.
Doing nothing is actually an action, it is deciding to stick with your original plan!
Reading the 100 baggers book it would say you hold forever and maybe you get your moon shot in it talks about things like the falls in Amazon or Microsoft. Or this can be described as using the Coffee Can approach.
I personally have gone for a manual stop loss, I do not get to look every minute, hour or day at the things, I miss profit warnings, stuff gradually sliding, so my main cut losses is 20% from purchase, sometimes depending on when I look and day I do give a chance to bounce back or it has gone down and up again in that time such as Airtel Africa (LON:AAF) .
I would like to say that I have a drop from peak manual stop loss too, but that often gets missed, but that is trying to get into the habit of bank the gains too.
There is no wrong answer, do what you feel is right, and it will be.
Good luck
Tommy
How many shares are there in your portfolio?
If you're holding, say 100 shares. Then 6 "stinkers" over a year might be acceptable. And you shouldn't beat yourself up too much.
If say they were part of only a portfolio of 20, then you have problems.
Need that context to know whether its a problem or not.
I use a spreadsheet to note down for each stock what would be an acceptable exit point if the SP fell. For AIM stocks it's usually 20%. For main market small/mid caps 15% and for larger companies 10%. That is my rule of thumb but I scale up and down depending on size of holding and also on the overall markets, which means I can (and do, probably too often!) give a bit of leeway to struggling stocks if every share is struggling. Obviously, the stops can be adjusted if the SP rises.
I've tried setting stop alerts formally but stopped as they have been triggered on occasion when I didn't want to sell. My bad as I obviously wasn't paying attention.
Portugull: Would you buy any of those 'stinkers' today? If not I'd suggest sell the lot and invest in something you like. Or just treat the wife/family or friends to a night out on the proceeds. Feels so much better when you ditch the crap in your portfolio.
Then don't ever let anything drop more than 20% again without selling. Robbie Burns is so good on this topic. The mental side of this investing lark can be hard.
I'll admit that whilst I've sold most of my crap, sometimes in stages to overcome the personal investment, I still have some big losers that I intend to hold til they come right (or I see the light). Sadly I've always thought I know best and am regularly reminded that I don't.
You really can't argue with the market. Well you can but it doesn't get you anywhere!
Good luck
And if you can't bare to sell the full position in those stinker's selling 50% in each is a great start,.... and you know what,......relief
Difficult to know when to pick up some of the better run businesses in the construction sector, some attractive valuations which will no doubt recover strongly once the macro picture for construction improves.
In terms of next year the CPA (where most manufacturers, distributors, merchants look to for guidance on the market) will soon (November) release their Autumn view for the coming years and change the market outlook from +0.6% in 2024 to a negative %.
Sorry guys, yes my ramble was about Sanderson Design (LON:SDG) , earlier post now annotated
Sanderson Design (LON:SDG)
Impressive interims given the exceedingly gloomy economic backdrop, especially in the UK. Admittedly licensing income has carried the day as this falls straight through to the bottom line, but there is an awful lot to like:
The Disney collaboration looks particularly exciting. Trading in line with a PE of 8 or thereabouts, I remain a happy holder. I am far from naïve, but could easily see the share price moving towards 200p in better times, when brand sales improve and the importance of licensing income diminishes. I would add that at the current level the company in my view looks a bid target, given its irreplaceable IP.
Also a shout out for Avingtrans (LON:AVG) that announced a £14.5m of contracts for its Metalcraft subsidiary. Another very well managed company in my opinion.
I hold both.
Who are you talking about?
Jonno
Presumably that was about Sanderson Design (LON:SDG) . Can you edit your post to make it clear?
What has happened to the Avingtrans (LON:AVG) forecasts, they have been slashed by about £6m, for both the next 2 years, a few weeks ago, are they correct?
The reduction in eps is taking account of the investment required in the medical division to support the development and marketing of the Adaptix portable X-ray scanner and the portable helium free MRI scanner that is being developed by Magnetica. The medical division doesn't currently contribute to profits but has significant potential.
You may want to watch the very recent interview that Paul Hill did with Avingtrans (LON:AVG) management on Vox Markets; link below.
Q&A with Avingtrans CEO, Steve McQuillan & CFO Stephen King - Vox Markets
OK, many thanks for that info. and link, I will have a look.
SDG and Avingtrans
Fully agree
SDG is rock solid, the real interesting point is US growth and I think Lisa Montague is targeting the US which is very smart . No point chasing the UK but to get a slice of US with its design archive portfolio is very good thinking .
Avingtans lovely well run company not cheap but not expensive and the CEO and CFO are just rock solid .
Sanderson Design (LON:SDG)
The market is littered with failed US expansions so “very smart” needs to be qualified!
I’d say that the idea is good and the US market has potential assuming the Sanderson design cater to US taste….the two don’t always translate well. The other thing is not to spend much money on tackling that market. It has to be small targeted investments that test and repeat.
In the UK we often forget cultural differences are quite wide and significantly impact the target audience desire to buy. Remember Hotel Chocolat expansion in Japan or Purplebricks taking their estate agent model to the US as just a couple of examples where shareholder value was destroyed very very quickly. Boohoo similarly because they failed to have a warehouse facility on the ground.
MPAC (LON:MPAC) have done it much better as they bought a rapidly growing US packaging business with clients / facilities in place and appear to have integrated the management well.
Not saying Sanderson Design (LON:SDG) won’t be successful in US but it isn’t guaranteed and investors need to watch for signs of reducing cash balances being diverted in that direction.
Nonetheless a business in my watchlist too.
There is an impressive list of Major Shareholders too - but I suspect that Sanderson Design (LON:SDG) is one of those shares with an 'emotional' attraction - people love the product, buy the shares
Just catching up over the weekend, so who knows if someone will see this (I wonder whether Stocko could/should introduce a notification system...) Anyway, I made some notes on their USA strategy from their FY23 presentation:
Management believesUSA is a significant growth opportunity. Lots of run way there. They've invested quite heavily to get the foundations right, but good signs including:
I came away impressed and thought they were doing the right things. The thing I find most challenging is being blind to what market conditions are actually like in the US. I.e. is it reasonable to only be growing at 10% in H1...
I must be missing something!. H1 underlying adjusted pbt £6.8m, licensing (100% margin) £6.9m. The core business isn’t making any profit.
Sanderson Design (LON:SDG)
Being frank their 100% margin statemment ref licence income is a bit of an outrageous falsehood. In prior update they even advised these large licencees get dedicated support staff. So practicably speaking there are specific direct costs that they choose to ignore when they say its 100% margin this licence income.
Ref this not being part of their core buisness i think they would say its exactly the opposite - the licencing cashflow is decent % of their core buisness model.
Note if you think about it they need to have designers doing stuff anyway (that they sell) as part of other segments to have the stuff to licence in the fisrt place - so in theory nowt wrong with reverything else makes zero profit as long as you know licence revenue is going great guns and catches up with shortfall elsewhere.
Fair point. But from what I’ve looked at most of their licensing contracts expire in 2025 and their H1 £6.9m could be all they will get for this FY. A few years back they had a very large licensing agreement (from memory £5m or so) which was not renewed and total income/profit from licensing virtually went to zero.
Agreement was with H&M, meant to add.
Sanderson Design (LON:SDG)
i am with you on the sketchiness here ref licencing and lack of clarity as to whether this may be a spike - but from what i have read licencing does seem to be more important than it was. So hopefully it either holds up or is at least covered by shortfall. Wouldnt blame anyone for not investing here on this basis as we cant complain if they deliver bad news next year and at that time explain that 2023 was a spike. EDIT more info supplied by proessive see below
to be fair to the company ref shareholder communication they do make progressive broker notes accessible via link on their website and they have upodated note dated today as it happens. this confirms expectations up to 2026 are to deliver 12 mill plus adjusted pbt each year - so overall they are confident of at least matching teh now going forward
they (progressive) also say the following ref licencing which does kinda back up the thoughts that licence revenue isa core part of earnings and hopefully wont completely subside anytime soon.
Licensing hasbeen recognised as, and cultivated as, a core strategic pillar by SDG, capable of developing profitable long-term relationships with its partners, while extending the reach and
customer awareness of its brands and their heritage.
Licensing has developed into a core and sustainable part of the group, which will continue
to mature across territories and product categories. It enables the group to focus on its
manufacturing strengths of fabrics and wallpapers, while monetising its intellectual
property across and into other product areas such as housewares and bedlinens. The
developing relationship and partnership with NEXT shows how great the potential of
licensing can be, and we envisage further strong licensing partnerships being developed
across territories and product areas.
Cambridge Cognition Holdings (LON:COG)
£1m contract, revenue to be recognised over 2 years. No comment on what that means for financial outlook. Potential for a larger follow-on contract, but after this one.
I think the more important bit is this:
The contract combines the Company's proprietary CANTAB®
touch-screen cognitive assessments with verbal assessments from its
recent Winterlight Labs acquisition, for the first time. Additionally,
the Company will supply its electronic Clinical Outcome Assessments
("eCOA")
Of course we don't know whether Winterlight/eCOA has been thrown in as a freebie to get a reference contract, or whether the buyer paid significantly more for the enhanced offering.
However, it is hopefully an indication that the integrated product is in a sellable state, and that they can sell it.
It also shows the management delivering on one of the contracts they mentioned they were hopeful of signing in their webinar post the results and the "unpopular" £3m secured loan.
Seems like a continual jam tomorrow stock. The share price suggests market lost patience some time ago. Shame though.
For a company that has doubled revenues from £6.7m to over £12m in a couple of years I'm not sure the "jam tomorrow" is a fair observation?
Has the market lost patience with them? Possibly, and the £3m loan didn't help, but that is also an opportunity for investors with multi-year investment horizons.
Hello Monty Carlo
I agree Cambridge Cognition Holdings (LON:COG) is not a jam tomorrow stock. The first stage was the turnaround, doubling revenue, building a decent order book and sorting out the balance sheet. COG operate in a vey hot sector so acquisitions were always going to be very expensive and early stage or they get even more expensive. They say they have done the hard work to integrate Winterlight and Clinpal. It can be difficult to get to the next rung on the ladder but I have confidence in management and hope that this contract is an early indicator that they are moving in the right direction.
Since 2020 management have always been reliable and demonstrated high levels of integrity. About a year ago Matthew Stork CEO flagged in advance that growth would be substantially slower this year due to inflationary pressures on clients' spending. Management do seem to be experts in their field and look to have bought with a vision and best of breed. The following paragraph from the RNS is interesting:
"Cambridge Cognition and its Winterlight business are recognised as world leaders in accurate cognitive assessment for neurodegenerative disease trials. Having acquired Winterlight in January 2023, Cambridge Cognition developed an integrated front-end within the first few months post-acquisition and now offers the broadest proprietary solution for touchscreen and voice assessments in clinical trials. Cambridge Cognition is the only company that can offer this unique set of cognitive assessments and eCOA as a single vendor solution."
The combination of industry expertise and also business acumen are often difficult to find but there are good signs of both at Cambridge Cognition. It is of note that this contract is with a new client.
I 'kicked the tyres' hard of this one after the interims and share price drop. They appear to have an excellent product, decent order book and high margins of around 80% and there is a lot of potential. I have been a holder since 2020.
I am assuming therefore you bought in the 30's and watched it go to above 180p....Nice if you took some profit along the way but AIM is a cruel mistress
Hi Grout123
I started buying Cambridge Cognition Holdings (LON:COG) at 22p and have watched the share price rise and fall, selling and buying at various moments along the way.
Telecom Plus (LON:TEP): A bit big for SCVR but worth looking at both for read across to small cap players (e.g. Good Energy (LON:GOOD)) and popularity with heavily followed bloggers Naked Trader and Cockney Rebel
Trying to decipher today’s announcement which at first read is as clear as mud.
The announcement has two parts. A trading update with no numbers (which to me suggests it’s not the main purpose of the update) and an update to its key supply contract with EON.
Firstly, the trading update:
‘reaffirm our guidance for the full year and look forward to providing a further update with our half year results on 21 November 2023’. Sounds positive.
Next, the contract update where it summarises some technical changes to the agreement with EON. The contract is still until 2033 but the calculation driving how much TEP pays EON has changed.
Importantly, TEP explains the contract changes are required, on the one hand, to provide a broader set of fixed price contracts to residential and small business customers and, on the other, to provide ‘time of use’ contracts suitable to EV charging, home generation and storage users.
In other words, TEP is investing because its electricity offering has fallen behind the fastest growing parts of the market where it lags the likes of Octopus, Good Energy and Ovo Energy.
It concludes by saying ‘we therefore anticipate modestly increasing our investment in the proposition from FY26 to further accelerate our growth trajectory’.
In summary, I think they are saying that whilst the current financial year’s FY24 numbers are good, forecast FY25 profits for future years may need to come down.
I hold TEP and GOOD.
I hold Telecom Plus (LON:TEP) TEP too and don't understand why you think "forecast FY25 profits for future years may need to come down". I see their statement saying they have greater flexibility to adapt their product offering to better match the requirement of the end customer, and this will require investment to maximise the potential in the various markets, especially new ones. Agree / disagree?
With Octopus/GOOD investing in the role out of solar panels / heat pumps I am assuming they will need to offer discounts to tempt customers from incumbents. Octopus/GOOD are targeting comprehensive tariffs covering feed in rates (for electricity generated at home and fed into the grid) and discounted rates both at pre determined times and opportunistically at times of low grid utilisation e.g. Sunday evening.
If you're all set up I dont see why you would move across to save some money on mobile phone etc.
'Time of use'/EV and 'feed in tariffs' require more complex IT infrastructure e.g. app development/partnerships with EV OEMs. For example, Octopus has a collaboration with BMW. Now doubt some of this will be Capex but some will come through operating costs and the Capex obviously needs to be depreciated at some point through the P&L.
TEP and CNA
Neither of them are small caps. why bother with TEP if one can hold CNA?
TEP has gone no where in 5 years but CNA has been to hell and coming back to life.
Stockopedia also prefers CNA which recently hit a high of 170 but retreated to 150 and now is back to hit a new 5 year record high soon.
In line from Sanderson Design (LON:SDG) (I hold), with licensing mopping up the declines in brand and manufacturing sales. My worry with Sanderson Design (LON:SDG) is overall revenue has been flat for a number of years now with the Group leaning on licensing income to increase profits, but licensing can be unpredictable and lumpy. Has anyone previously mapped out when licensing income is due to come through? i.e. is there any risk it suddenly drops off anytime soon?
Sanderson Design (LON:SDG)
goods points Tortoise - i 100% agree with your worries her. Particularly when company uses superlatives like "oustanding" with regard to the licence segment current figures . In some respects they should be telling us if this is likely to "not be repeated next year " and there is very little given away albeit they seem confident ref that segment and teh rest of this year - so poor that they havent confirmed that its not one of spike that drop back down. I guess i would rather have it than not but they really need to communicate what expectatrions are ref lumpiness - perhaps that has been flagged up somewhere. Good news today was the lack of any bad news albeit if there is bad news it will no doubt arrive after the lord mayors show. I have to presume licencing probably will not match this year next year unles they advise otherwise.
Carcrash from Eneraqua Technologies (LON:ETP)
Broker says it all-
Forecasts materially reduced Having rebased forecasts on 23rd May for a rephasing of projects as a result of pressures on RSL budgets, we further reduced forecasts on 31st August to account for the potential impact of the proposed changes to net nutrient neutrality rules. We revisit forecasts today as a result of the further project rephasing, reducing our revenue forecasts by 30%/19% in FY24/FY25, with our adj. PBT forecasts and our adj. EPS forecasts reducing by 69%/66%. We expect net cash of £1.0m at the Jan. ’24 year end (H1’24: £0.5m), rising to £3.5m in FY25.
Eneraqua Technologies (LON:ETP) H124 overview by CEO video & podcast.
If you want to put your questions to management there's a webinar at 11am this morning, register here.
Vp traded resiliently through H1’24 against a backdrop of challenging macro-economic conditions, which impacted general construction and housebuilding activity, as previously communicated. Infrastructure demand remains supportive across water, transmission and rail, which are benefiting from long-term regulatory programmes (AMP7 for water and CP6 for rail). The Group’s overseas businesses have traded well, at levels ahead of H1 2023.
Vp’s medium term prospects look bright under the leadership of new CEO Anna Bielby and we make no changes to our forecasts.
In our view, Vp’s share price weakness over recent months overlooks the Group’s impressive track record of long-term growth, high returns and the successful navigation of previous economic cycles.
With the shares trading at a 50% discount to historic average trading multiples, we maintain our Fair Value estimate of £10.90 per share
Net gearing is my main concern.
Figures published by the Department of Business and Trade show UK
brick despatches in July and August 2023 averaged 16% lower than in June 2023,
and 28% lower than in the corresponding period in 2022. Within this, August
was weaker than July and our own despatches suggest a further softening in
September. These figures also highlight that UK brick industry despatches are
currently running below the levels seen in 2009.
Information from the Forterra (LON:FORT) trading up date this morning.
Also on Forterra (LON:FORT) :
Commissioning of the new Desford brick factory
continues to progress, with the challenges of replicating the product
range now overcome. Although output in the last quarter was below plan,
the weaker market demand has meant there was no impact on sales.
So they have a brand new factory which is operating below capacity, and they are now mothballing Claughton & cutting Aircete production. And yet "pricing across our range of products has remained resilient overall".
This raises two questions...what happened to the argument that they can supplant European imports with their high shipping costs (insufficient product overlap?) and just how much spare capacity is there now in this industry?
My morning smallcap tweet: Hitting a low and hitting the roof
Eneraqua Technologies (LON:ETP) Cellular Goods (LON:CBX) Cambridge Cognition Holdings (LON:COG) Forterra (LON:FORT) Watkin Jones (LON:WJG) VP (LON:VP.) Avingtrans (LON:AVG), Telecom Plus (LON:TEP), Discoverie (LON:DSCV), Sanderson Design (LON:SDG)
◄Eneraqua Technologies (ETP)► H1-July. Warns FY rev and profit substantially below market expectations due to clients delaying projects. Prudent to expect rev and profit miss in FY25 as well. [SP=90 Cap=30m]. I hold.
◄Cellular Goods (CBX)► formalises agreement with Springtide Seaweed to form kelp farming carbon removal JV. [SP=0.44 Cap=3m]
◄Cambridge Cognition (COG)► wins £1m 2 yr contract for a sizeable later stage clinical trial. Potential for a further contract of slightly higher value. [SP=70 Cap=24m]
◄Forterra (FORT)► warns FY-Dec EBITDA below exp dut o weak demand in July and Aug. [SP=143.8 Cap=306m]
◄Watkin Jones (WJG)► warns FY-Sep PBIT only breakeven due to additional costs. Net cash c. £43m. No change to the FY24 guidance. [SP=34.85 Cap=89m]
◄Vp (VP.)► guides H1-Sep 'solid'. No numbers! We continue to closely monitor the impact of weaker markets in housebuilding and general construction; however, we remain confident that the Group will continue to provide shareholders with an attractive level of returns." [SP=490 Cap=197m]
◄Avingtrans (AVG)► wins £14.5m of contracts. [SP=393 Cap=129m]
In line: TEP, DSCV, SDG
Morning Paul, I notice that you have flagged Calnex Solutions (LON:CLX) who issued a shocking rns late yesterday severely reducing their revenue for this year. Surely a sign of recession when companies delay capex
Also I noticed that the previous rns was of a director selling. Coincidence?
Enjoy the podcasts cheers
Similar to Eneraqua Technologies (LON:ETP) this morning who have warned of delays to contracts with both Local Authorities who are facing pressures on local budgets and water companies.
“As a result of these challenges and the anticipated delays, we expect our revenues and profit for FY24 to be substantially below market expectations. ”
Calnex
After the profit warning by SPT last week this was expected. I hold SPT which is a bigger company with a good track record. share price is slowly recovering but the whole sector is in the doldrum. No visibility but lots of hope!
Spirent Communications (LON:SPT)
RNS today - CEO Eric Updyke bought 100,000 shares at 97.1798p yesterday so management are presumably hopeful too.
Spirent Communications (LON:SPT)
Yeah, but they also spent £56M buying back shares at nearly double the price, so what do they know?
He's essentially putting back the money he received from selling the options he got in May. So I don't view it as too big a statement
Ouch.Clx almost 20% down today too.Someone or 2 clearly still want to get out of Calnex.I'm guessing the market sees the big telecoms cos won't be reversing and changing tack anytime in the sooner future.The company has traded on a fairly pricey growth p/e, but sector growth should come back eventually..