Small Cap Value Report (Wed 12 June 2024) - DFS, CGS, FDEV

Good morning from Paul & Graham!
Explanatory notes -
A quick reminder that we don’t recommend any shares. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech, investment cos). Although if something is newsworthy and interesting, we'll try to comment on it. Please bear in mind the "list of companies reporting" is precisely that - it's not a to do list. We typically cover c.5 companies per day, with a particular emphasis on under/over expectations updates, and we follow the "most viewed" list of readers, so if you're collectively interested in a company, we'll try to cover it. Obviously with the resources available, we can't cover everything! Add you own comments if you see something interesting, and feel free to discuss anything shares-related in the comments.
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to, if they are using unthreaded viewing of comments.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. And/or it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom),
Frozen SCVR summary spreadsheet for calendar 2023.
New SCVR summary spreadsheet from July 2023 onwards.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
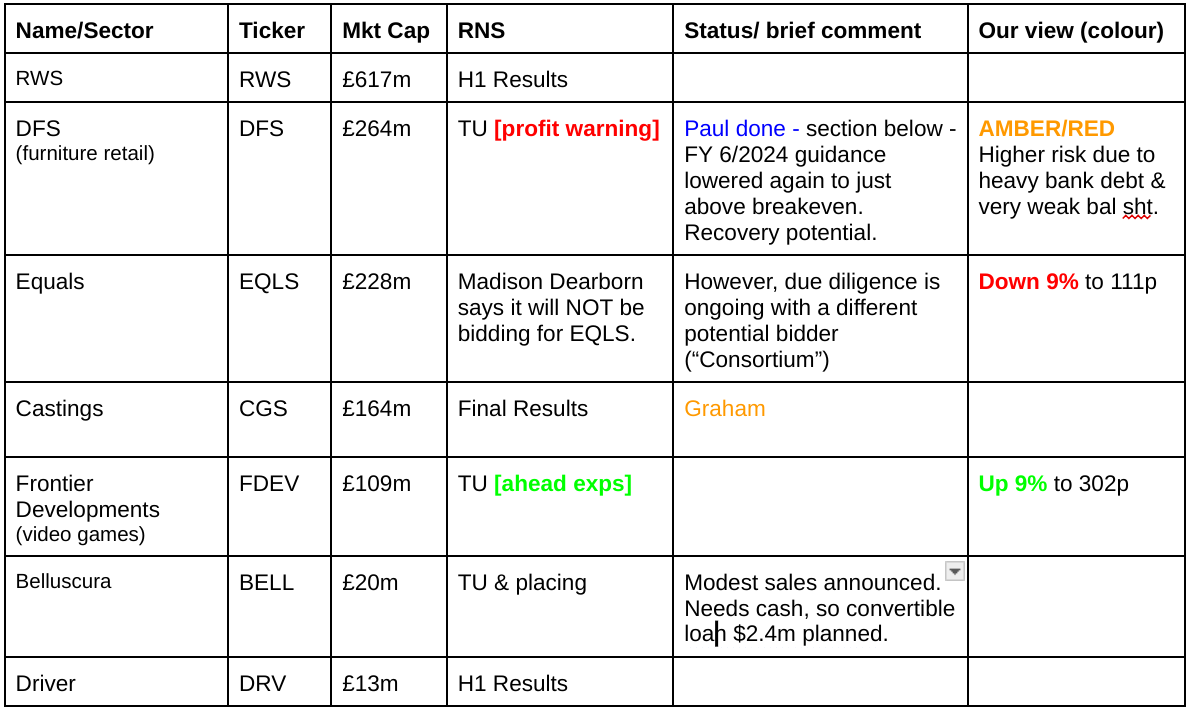
Companies Reporting
Summaries
DFS Furniture (LON:DFS) - down 8% to 103p (at 08:29) £243m - Trading Update [profit warning] - Paul - BLACK (PW), on fundamentals AMBER/RED
It's another profit warning, caused by very weak demand, and delays/costs of shipping. I can see the upside case when demand begins to recover, but for me it's the terrible highly geared balance sheet that's a deal-breaker, requiring us to take too much risk to access the upside potential. It could work out well in a recovery, but just be aware you're being asked to take a fair bit of risk, given how high bank debt has become.
Castings (LON:CGS) - down 0.5% to 368p (£158m) - Final Results - Graham - AMBER/GREEN
Today’s outlook statement reflects the continuation of an existing trend, with lower demand from truck customers than previously and no immediate signs of an improvement. EPS downgrades can be found in the broker notes. I’m switching to AMBER/GREEN as the stock is not as cheap as I previously thought.
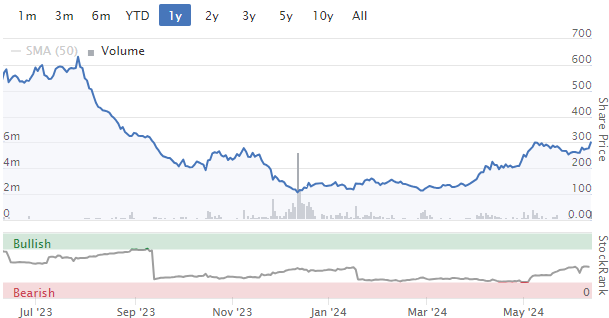
Frontier Developments (LON:FDEV) - up 8% to 300p (£118m) - FY24 Trading Update - Graham - AMBER
This is great news with adj. EBITDA beating expectations by over £5m and the cash balance also beating expectations, reversing the cash drain seen in H1. I would like to be more positive on this video game developer but it’s still in recovery mode and is still not expected to generate any real profits until FY May 2026.
Paul’s Section:
DFS Furniture (LON:DFS)
Down 8% to 103p (at 08:29) £243m - Trading Update [profit warning] - Paul - BLACK (PW), on fundamentals AMBER/RED
DFS Furniture Plc, ("DFS" and "the Group"), the market leading retailer of living room and upholstered furniture in the United Kingdom, announces the following update on recent trading through to 11 June 2024 of the 53 week period to 30 June 2024.
PR headline tries to put a positive spin on this profit warning -
MARKET SHARE GAINS AND COST BASE ACTIONS PARTIALLY MITIGATE A WEAK TRADING ENVIRONMENT
Background - I last covered DFS on 19/3/2024, when it issued a profit warning too, alongside soft H1 results showing little profit, and reduced the full year PBT guidance by £10m to £20-25m. Soft order intake in Jan & Feb, and Red Sea shipping delays were mentioned back then. I marked it AMBER/RED due to the dreadful, over-geared balance sheet - not a good setup, where management recklessly geared up the balance sheet to pay divis they couldn’t afford. On the positive side, DFS is market leader, and should see an upturn in demand from improving disposable household incomes and rising consumer confidence.
On to today’s news -
Consumer demand has “remained challenging”.
Red Sea shipping issues has delayed products, and increased freight costs.
Revised guidance, is down again - this is for FY 6/2024 -
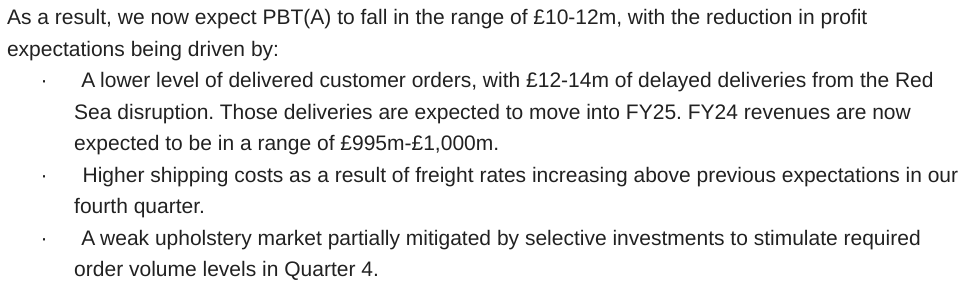
Further down it calls the upholstery market “very weak”, demand down another 10% on weak prior year, to a “record low”.
Gross margins are actually up 140 bps, despite shipping problems.
Cost-savings of £25m implemented, it doesn’t say what these are. I suppose the big controllable costs would be marketing, and staffing.
Bank debt looks far too high, for a business trading barely above breakeven - management seem oblivious to the risks of their reckless financial strategy - paying unaffordable divis and buybacks in recent years, funded with bank debt. With the market cap not c.£240m after this morning’s 10% drop, the level of bank debt below (this doesn’t include leases remember) is clearly much too high - so covenants would need checking, to see if there’s a danger of it needing to do another emergency equity raise, like the one it was forced to do during the pandemic - obviously no lessons were learned from that -
“Net bank debt at the end of the period is expected to be £165-170m (total facility size £250m).”
Outlook -
Recent trading and outlook into FY25:
We have been encouraged by an improving trend in our Group order intake, which is up over +9% in our fourth quarter to date, in line with our expectations. The recent improvement comes as we annualise weaker prior year comparatives and also following successful initiatives to strengthen the product ranging and pricing in Sofology and reintroducing 4 year interest free credit at select times to maximise revenue and profit in this difficult trading environment.
Whilst the economic outlook remains hard to predict we expect the widely predicted lower inflation and interest rate environment to have a positive impact on upholstery market demand levels with the declines experienced across the last three years starting to reverse and the market slowly recovering in our FY25 period. We are well placed to capitalise on any market recovery given our market leadership position, the operational leverage in the business and the progress we are making on our cost base.
Paul’s opinion - obviously this is another disappointment, but not a disaster. A bullish view might be that it’s still just about profitable, despite very weak market conditions. Hence operationally geared upside to profits should just be a matter of time as consumer spending recovers.
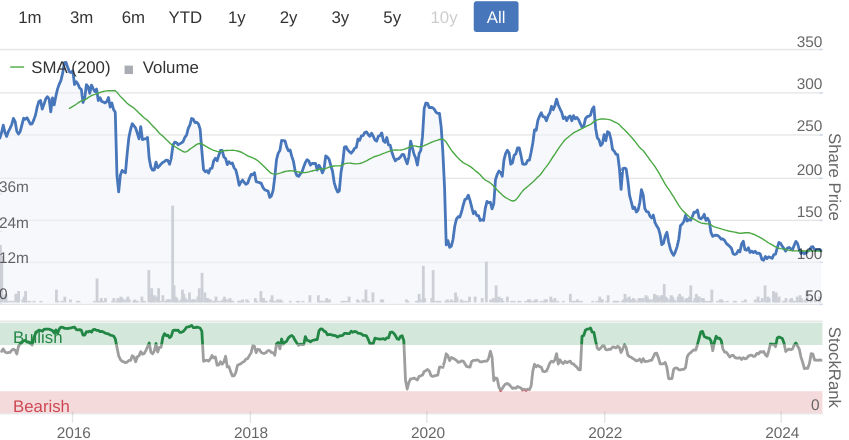
Shares are at/around an all-time low, and as we saw from a similar low in the pandemic, the recovery in share price was strong, albeit didn’t hold due to the wider impact of higher inflation & supply chain problems.
If DFS had a strong balance sheet with net cash, I’d say it would be a good punt for a recovery. However, it actually has a terrible balance sheet with way too much debt. So for me that remains a big problem that puts me off, so I’ll stick at AMBER/RED. If you’re not worried about the debt, and are happy to assume the bank will remain co-operative, then who knows, you could see a good recovery in this share as recovery (hopefully) begins to kick in.
Cheap equity could make it a bid target too. So for more adventurous investors, this might be worth considering as a recovery idea maybe. Could it be the next McBride (LON:MCB) and come roaring back from near-death? Just be aware you’re taking a lot of balance sheet risk, which could end badly in a downside scenario.
Not a good track record as a listed company -
Castings (LON:CGS)
Down 0.5% to 368p (£158m) - Final Results - Graham - AMBER/GREEN
This is a remarkably short final results statement, but that’s normal for Castings.
Key points for FY March 2024::
Turnover +12% to £224m
PBT +27.5% to £21.3m
“Despatch weight” (i.e. output or sales volumes) fell 5%, with the implication that the growth in turnover/PBT is a result of price increases and cost control, not underlying growth. The company points out that last year’s despatch weight was the highest since 2014.
Inflation: it was a year “of relatively stable input prices” (the same can’t be said of the prior year). A fixed price electricity contract ended in Sep 2022, but the additional power cost that followed was surcharged to customers.
Demand: the financial year started with an “unprecedented level of demand”, due to post-Covid backlogs, but it finished more quietly:
As we entered the second half of the year it became apparent that the OEMs had satisfied the backlog demand and we started to see schedules at a lower level. This was especially evident in the final quarter of the financial year and these reduced levels have continued into the new financial year. We are currently operating at a level approximately 20% below the highest point in 2023/24.
Foundry business: the absolute level of profits was broadly flat but the profit margin fell from 7.3% to 6.4%.
For one thing, the profit margin was impacted by lower volumes, due to the loss of production efficiencies.
Additionally, the profit margin was hurt by the increase in the cost of electricity, although with customer surcharges offsetting this increased cost, the absolute amount of profit was unaffected.
A new production line is planned to increase capacity by 15% in June 2025.
CNC Speedwell (machining): “a very good performance” with high volumes and sales up 36%. Note that only 5% of revenue, or about £2m of revenue, was generated from external customers.
Outlook:
Our heavy truck customers are suggesting that the current lower levels of demand are likely to continue in the short-term with the potential for a slight increase in the autumn. We will continue to develop opportunities with existing customers in areas such as the electrification of lighter trucks and build relationships in other markets such as wind energy, agriculture and in the US.
Dividend: a 5.6% increase in the total dividend for the year to 18.32p plus a special dividend of 7p. So the total yield for the year is about 7% on the current share price (but it’s important to bear in mind that the special “supplementary” dividend is non-recurring).
Earnings per share for the year is 38.45p (last year: 31.66p). So these dividend payments, even including the supplementary dividend, should be easily paid for from this year’s earnings.
Even if that wasn’t the case, the company reports a cash position of £32.5m, with no borrowings. Interest income on this has soared to £1.5m.
Pension schemes: are in surplus and are not shown on the balance sheet.
Balance sheet: net assets £134m, fully tangible and with few liabilities worth mentioning.
Estimates: I wish the company included some of this detail in the RNS, but broker reports suggest quite a poor earnings outlook for the company. Canaccord (with thanks) have reduced their FY March 2025 and FY March 2026 EPS estimates by 35% and 23% respectively, to 23.9p and 31.1.p.
Based on these forecasts the stock is trading at 15x this year’s earnings, or 12x next year’s earnings.
Graham’s view: I remain very impressed by Castings, as I have been for as long as I can remember following it. My only gripe today is that the company doesn’t give much of a hint about the earnings downgrades in today’s outlook statement. Although it must be said that the company has never published very detailed or lengthy RNS announcements.
As I said in May, it seems that this will be a quiet year for the company with demand somewhat muted. They do not typically enjoy very good visibility on future orders (although today’s statement does show that they are talking with customers about the outlook for demand later in the year).
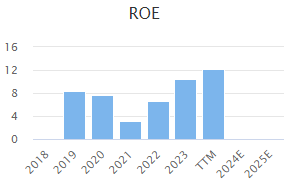
For me, this is still one of the highest quality manufacturing/industrial stocks I’ve studied. It has a strong tendency to generate an acceptable ROE despite running a conservative balance sheet - impressive stuff. However, to reflect my disappointment relating to the EPS estimate downgrades, and the higher PE Ratios they imply are currently attached to the stock, I’m going to adjust my stance to AMBER/GREEN
Frontier Developments (LON:FDEV)
Up 8% to 300p (£118m) - FY24 Trading Update - Graham - AMBER
Frontier Developments plc (AIM: FDEV, 'Frontier', the 'Group' or the 'Company'), a leading developer and publisher of videogames based in Cambridge, UK, reports provisional financial results for the financial year ended 31 May 2024 ('FY24') ahead of expectations.
We last touched on this share in May, when the company revealed its strategy around future game releases.
But in the short-term, we have results for FY May 2024 to digest. The market wasn’t expecting much from these results at all; here are the key points.
Revenue £89m (LY: £104.6m)
Operating costs cut by 20% in H2
Profitable on an adjusted EBITDA basis in H2 and in the year as a whole (including proceeds from the sale of publishing rights for a game).
The consensus estimate was for an adj. EBITDA loss for the year of £5.1m, so it’s a significant achievement to get a positive result, even if we are using a highly adjusted figure.
Cash improves to £29.5m. This has been a source of concern (as it has been shrinking), but it now bounces back from the £17.1m level seen at the end of Nov 2023.
Outlook reiterates the timetable for new game releases, as initially revealed in May. Additionally:
As well as the unannounced own-IP CMS game coming this financial year, FY25 will also see the launch of Frontier's third F1® Manager game, with F1® Manager 2024 confirmed for release on 23 July 2024 on PC, PlayStation® 5, Xbox Series X|S, PlayStation® 4 and Xbox One.
The Board is comfortable with the current consensus of analyst expectations for FY25 revenue of £87 million, and is confident of being able to achieve profitability in FY25 through a continued focus on driving return on investment and tight cost control.
Previous F1 Manager games haven’t been quite as successful as hoped - hopefully the third instalment will include some improvements.
Estimates: I view these estimates as highly uncertain, but for what it’s worth there are small upgrades to FY May 2025 expectations.
Unfortunately, the broker estimates still suggest negative adjusted EBITDA in FY 2025, e.g. Liberum has an estimate for adj. EBITDA of minus £2.6m (improved from minus £3.7m).
The company is then forecast to achieve real profitability in FY May 2026.
Graham’s view
This is a terrific update, relative to expectations.
The problem is that expectations were already so low. And even after upgrades, the estimates for FY May 2025 remain dismal.
As for the FY May 2026 estimates, I don’t believe that it’s possible to predict the success or otherwise of the company’s game pipeline so far into the future.
With so much uncertainty, and with another difficult year ahead, I’m going to remain neutral on this stock.
Why not RED? Because I do still believe that FDEV are very skilled when it comes to making CMS games (“creative management simulations”), and that’s what they are focused on now. Overall, their track record in this genre is excellent, and they still have cash to fund development in the short-term. So I wouldn’t want to bet against them.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

83 comments
..
I just cannot get my head around why Equals put themselves up for sale anyway? I have never bought a company because I think it will be taken over. I buy a company because it is a good company and as a result it could be taken over.
US CPI came in a 0.0% for May - I read a fairly thorough piece explaining why it would surprise positively - go figure. I wouldn’t go over board with one months data but after 4 months where all the data conflicted with cutting rates this is a welcome surprise. Concerns that rates may have to rise still can take a breather. This is welcome not just in the US. I think everyone will take an inflation break rather well. Energy prices are doing their bit. I did have a random thought that positive Ukrane developments could be positive for oil demand rather than supply. ( Negative for inflation of course). There is a Conference in Luzern this weekend so maybe some good news ( although Russia not invited) … we will see. For now, a zero month on month is very welcome.
Finally a US CPI no that plays ball ….
Hard to feel optimistic about Small Cap shares when they are going down again in the main recently like deflated balloons, only one real positive upwards projection thank goodness for Warpaint.
Just a 3 -5 % correction thus far for the indicies , back down towards the 50 day m.a.... hopefully will remain above that and then perfectly healthy to trade sideways for a while....
Anyone any thoughts on Billington Holdings (LON:BILN) tumble in the last week or so from shy of 6.00 to 4.85 on no apparent news or just profit taking!
Unclear to me, so would love to hear others views....but uptrend is still intact so topped up this morning...
Happening to quite a few shares this month. Probably profit taking after a good run. Ashtead Technology Holdings (LON:AT.) is another one that has fallen back no news. Probably a buying opportunity.
SRT Marine Systems (LON:SRT)
jamesalastair
As a follow up to your mentioning Kongsberg recently I did some quick research then contacted SRT Support with a couple of questions. For your info, I received the following reply
Dear Jim,
Thank you for your web site inquiry which has been forwarded to me. Firstly thank you for your interest in SRT.
Kongsberg is a large systems integrator with interests in the defence and civil-defence markets globally and so yes, we do see them as a potential competitor and do see them starting to see them in our market segments now that the civil defence marine market is showing itself to be very large and growing. However whilst certainly a large company with considerable resources and ability, they do not have a viable solution of their own and thus today we do not see them as material direct competition. We do not sell anything to them directly, although we understand they do buy some of our AIS transceivers vicariously via our dealer/distributor network.
I hope this answers your question.
Kind regards
Simon R Tucker
Chief Executive Officer
Good for you for following up on this. The problem with Stocko is unless you go back, you miss things and I nearly missed this. It certainly sounds more nuanced than I had thought.
OK.
NB Global Monthly Income Fund (LON:NBMI)
Good Morning, I am not sure that there are any holders left as it has reached the last stages of wind down. I have just had the payout from the redemption on 07 June hit my account today.
I am left with a small holding (<1% portfolio), and have had the corporate notice that this is going to go into formal winddown and handover to the liquidators and delist at the end of this month, and wonder what this means and if I can continue to hold in my SIPP past this date if the EGM motions are supported?
There is an easy option of just sell into the market today and move on.
Though the stated NAV is still ~20% higher than the sell price today, or 12% higher than the stated buy price (if I reinvested from the redemption would take me back to ~2% of portfolio), and a profit is a profit after all, but with an associated risk of achievable values in liquidation.
Whilst this is not a life changing number, it is more a learning point, as I hold a companies in formal winddown mode, so will likely get such statements in the future too and trying to work out a plan of action, or at least a checklist when this comes up again.
Thank you in anticipation.
Tommy
Hey Tommy,
NB Global Monthly Income Fund (LON:NBMI)
I don’t know this stock, but my own experience is that self-select SIPP providers hate de-listed shares, and may refuse to hold them. (When I wanted to keep a delisted share which was being taken private, I had to buy it from my own SIPP by paying the full take-private price).
Also, the final stages of wind down are a fees fest for the directors, accountants, lawyers, liquidators etc. These make a big dent in what is left for shareholders. And the final wind down takes a long, long time.
So if I was you, I would bale out now. But it all depends on your timeframe, attitude etc.
Best wishes
Ricardow
Thank you RicardoW, I have sold in Market this morning and now to work out where next. Take profits whilst still listed and stick with things that are listed. Must remember the liquidity rule, only buy what you can sell in one go, and unlisted you cannot sell. Tommy
Morning all - Singer Capital Markets have initiated coverage on Card Factory (LON:CARD) . Does anyone have access to this? Be very interested to have a look but I am not subscribed to them. Thanks in advance.
Card Factory (LON:CARD)
Are you sure?
Nothing on ResearchTree - they normally have Singer notes.
Did a search on Singer Capital Markets' web site - didn't come back with anything.
Castings (LON:CGS)
Graham’s view:. My only gripe today is that the company doesn’t give much of a hint about the earnings downgrades in today’s outlook statement. Although it must be said that the company has never published very detailed or lengthy RNS announcements.
surely this is market sensitive news and needs communicating to the market officially - are they allowed to not update the market and privately tell brokers that they now expect earnings will be 22% lowe rcurent year than we expected yesterday ?- if they can thats not acceptable set of rules on any level imho and we ned to take some action to get that changed. Its posible they may not agree with brokers i would have thought that less than likely though?
Surely unless company disagree with broker this is profit warning and should be flagged as such ? we are now into 3rd month of year.
also should this not be flagged as black profit warning in the header by stocky if current year earnings have today been downgraded by 35%
in many respects year end results normally rubber stamp what has been flagged up previously so imho whether they say it or not the most important bit (presuming no nasties) is if there is any change ref current year numbers.
surely this is a formal profit warning here ? albeit coming from broker not them.
Why would the company be paying a special dividend while issuing a profit warning.
who would benefit from a special dividend? Hmmm.
Castings (LON:CGS)
Why would the company be paying a special dividend while issuing a profit warning.
i don't follow the company closely so cant be 100% sure - but the curent year profit warning should be completely independent of the fact they chose to pay a special dividend - unless its material enough to make them calcel it. Normally a special dividend arises due to prior successful period that warrants higher payout for whatever prior reason - so unless the profit warning now would make that special dividend look "risky" i cant see any reason for them to not proceed as previously planned (or as planned now ref prior cash made) and ignore then profit warning.
Note the warning is simply adowngrade in current year profits - this is still a company delivering decent profits - the fact they now expect to make a little less this year shouldnt change the dedicison made to pay that special dividend based on prior good results or prior excess cash being stored up - Graham has confirmed that ten balance sheet seems to be fine ref this special dividend so the fact they will make less this year than expected previosuly isnt really an issue as they have the solid balance sheet to cope with that special divi.
In my humble opinion, Castings (LON:CGS) would be much better off buying back their own shares than regularly paying special dividends, which they have done for each of the last three years. The balance sheet is bomb proof and they often generate surplus cash. In spite of the very healthy 5% dividend yield, the market doesn't seem to rate them as the share price peaked at £5 ten years ago. Buying back their own shares would enhance their Earnings per Share, whilst increasing their Return on Assets and their Return on Equity. Long standing shareholders, such as me, might possibly see a re-rating of the shares!
hi rmillaree
Castings (LON:CGS) - (I hold).
Some background here may help understanding.
75%/80% of revenue comes from OEM heavy truck manufacturers. FY'24 ended 31/3/24 (and prior year) had exceptionally high demand as a result of pent up post Covid orders. Orders were so high that Castings (LON:CGS) did not have the capacity and had to outsource some work (in collaboration with customers) as flagged up in their half year trading update of 14th November.
Wind forward to the pre-close trading update on 1st May and we were told that underlying demand for heavy trucks was particularly strong in H1 but it had now normalised with forward schedules at a lower level. No guidance was given which rather left investors guessing.
Additionally their brokers stated that they would not update their forecasts until the final results were published (perhaps at the company's behest?), which has now happened and reveals a dramatic drop in forecast earnings.
Keeping investors in the dark as to the extent of the drop in forecast earnings was, in my view, a mistake (by the company and brokers). I agree with you that the way this has been delayed and delivered to investors can be construed as a rather strong profit warning and should not have been allowed to happen. As Graham says in his review, Castings (LON:CGS) tends to say the minimum in their RNS communications. In this case they got it wrong. I'll be kind and call it very poor PR.
The share price reaction today, down 16p to 354p, has been nowhere near as bad as might have been expected due to the strong balance sheet asset backing, continued profitability, net cash £32m and strong dividend record.
So investors are now left with a company that no longer looks cheap. It simply looks priced up with events on a FY'25 f/c EPS of 23.9p giving a PE of 14.8 which is marginally below recent years average (pre and post Covid) PE of 15/16.
In summary, the results were good but the forecasts worse than expected leaving the shares fairly / fully valued. The company is still producing very good profits and a generous yield. Not as attractive as it appeared before today's announcements but imho certainly no need for investors to panic sell.
Snazzy
Castings (LON:CGS)
Additionally their brokers stated that they would not update their forecasts until the final results were published (perhaps at the company's behest?), which has now happened and reveals a dramatic drop in forecast earnings.
its tricky
imho if forecasts have not been withdrawn and are taking huge hit today imho that most certainly should have been communicated via company directly to market - presumably rules are lax enough that soemhow they and other companies get away with it?
if forecasts had been withdrawn practicably speaking thats completely different and all would be above board as there are no expectations and the figures on stocky presumably were outdated info - doesnt sound like this is the case.
Overall here the money that matters might have known the situation here even though shareholders may have been kept in the dark to greater or lesser degree until today (they may have had some inkling perhaps though too?) - also if there is special dividend that perhaps could sweaten the deal and there might have been a bounce today based on that alone ? - not sure if that had been flagged up previously.
as ever knowing a company and watching like a hawk as to how stuff is communicated is important - companies like this often seem to rinse and repeat with surprises. to be fair to castings they may have little visibility before year starts ref whether the next year is going to be super good or not. I did previuously hold this company but sold on the basis they could easily have a poor spell based on stuff beyond their control - perhaps one of those odd companies that when times look bad its time to invest and when times loook good its time to sell up and wait for the next bottom of the cycle add time.
Castings (LON:CGS)
Sold this morning - but in no way was it a panic sell.
Basically lost confidence in management due to a 35% 2025 profit warning by analyst. I was expecting a dip due to normalizing but 35%?! Plus, if you don't have the balls to admit it yourself then you're not for me . Scrapped Portmeirion (LON:PMP) on the same basis.
The scenario painted by Canaccord shows the 2027 forecast still 12% below that achieved in 2024. There are lots of undervalued shares out there - this is no longer one of them - in fact I'd say its overvalued.
Also, you have to question, IMO, why they are spending £17m increasing foundry capacity when demand is currently falling .
But, each to his/her own and good luck.
A.
hi Albertos
I hope you didn't think I was implying that you had panic sold.
I fully agree with your response. This is indeed no longer an undervalued share but by no means the implied disaster the reduced broker forecasts might suggest.
I just felt it may perhaps be best to let the dust settle before taking any action but agree there are now better opportunities around.
Snazzy
Hi Snazzy
No I didn't think that was your implication - just wanted to make my decision making process clear should anyone be interested.
I cannot argue this is not solid company - its just its attractions after today are not what they were.
Also it was a general moan about the accepted norm in this country - analysts do the forecasts - why don't we follow the US where the company discloses the forecasts and the analysts comment on it. Every listed company has a CFO (or Finance Director if you prefer) but over 90% are silent preferring plausible deniability using the house broker and others.
Why do people wonder about the fall of the London as a financial center - its so, so obvious. Companies are not required to give guidance and everyone apart from financial institutions are assumed to be morons needing expensive financial advice.
Rant over .... until the next time.
Spot on Albertos.
However you gave away your US bias in your spelling of 'center' lol
Snazzy
Legal & General (LON:LGEN) - a very sensible strategy update today that I've been listening to. Market leaders in retirement solutions and a significant asset management business yet the market doesn't like the sharpened focus, potential sale of Cala, >20% ROC, updated capital allocation, 6-9% EPS growth target, 2% dividend increases + buy-backs. 9%+ dividend yield. Odd. There is no pleasing investors in sensible profitable dividend stocks with higher for longer interest rates. So much choice on high dividends. Anyone else wondering why there is no interest in such high quality (but boring) businesses?
Hi Topvest, yes I share your bemusement regarding Legal & General (LON:LGEN) and the negative market reaction to today's update. The dividend yield makes for a pretty compelling investment although I'd like to better understand the extremely low quality ranking (18) which is the main thing that puts me off. I'd be grateful for any informed views on this.
Similar with Just (LON:JUST) and Phoenix group (LON:PHNX)
Very unloved despite trading way below TNAV
I don't think the quality ranks really work for insurance companies so I wouldn't pay too much attention to that.
topvest
I’ve held Legal & General (LON:LGEN) for ages and am not surprised at the negative reaction to their update today. A key reason for this that many might not realise is that the 2% annual dividend increase is now lower than it was. The reason for that is probably the decision to go for buybacks.
Up till now Legal & General (LON:LGEN) has eschewed buybacks. That appealed to investors who don’t like buybacks, so some (including me as I don’t share the enthusiasm here and elsewhere for buybacks) will be very disappointed with this update.
And investors are probably disappointed with the uninspiring strategic update too.
Even so the negative share price reaction looks overdone and it increases the attraction of the dividend with the yield now 9% or so, so this dip looks a good buy opportunity. The share price dropped to current level in February and April and like then could well be followed by a useful bounce.
Agree Ken about response to Legal & General (LON:LGEN) buyback decision. Unimaginative and lemming-like behaviour late in the game. Don't they realise that the dividend is a huge part of what people are buying??
Legal & General (LON:LGEN) According to the commentary that I read the share price has reacted to the departure of CEO Michelle Scrimgeour.
Of course that's the CEO of the asset management division - not the overall CEO. I think the drop is more likely due to the 2% dividend increase target going forward - this will very likely lag inflation and I imagine disappoint a lot of income investors.
On Legal & General (LON:LGEN) I agree on the dividend. 3% growth is more ambitious, but I suspect that they are trying to keep some capacity for share buy-backs which is very sensible given the share price.
I also agree with comments around the quality rank. It doesn't work for life and pension companies given the c£100bn assets and liabilities in the balance sheet. Chesnara (LON:CSN) and Phoenix group (LON:PHNX) both also have low quality ranks as well, but yield about 10%.
My return target is >10%, so your pretty much getting that from the dividend on these well funded pension and life businesses. Their valuations are very odd. If interest rates come down a tad its not difficult to imagine what might happen in share price terms, as long as we don't get another recession.
Both Legal & General (LON:LGEN) and Phoenix group (LON:PHNX) saw sharp falls in their stock ranks when new IFRS accounting rules came in during the last year. I'm not an accountant so don’t fully understand why this is, but I’m sure someone in this chat can enlighten me.
Legal & General (LON:LGEN) etc. impacted by IFRS 17. Another stupidly over-complex accounting standard really. It means that when they write an annuity contract, for example, and receive the cash on day 1 they have to defer any profit over the life of the policyholder amortising it every year.
For Legal and General it pretty much halved the balance sheet net equity. Its over complicated in my view, and is ignored for solvency purposes etc. being added back. The CSM deferral is a massive number not far off the market cap of the company. Its the cash profits that matter, so numbers now shown in the Stockreports include these adjustments which lower EPS and NAV materially. Hope that helps, but not an expert on this!
Thank you Topvest
Goggled who makes UK tax rules. No clear answer emerged but something called "the UK government" and something called "the Treasury". So the "government" a bunch of ... and "the Treasury" holders of our massive gold reserves and sovereign funds, leaves who ... Mr Mandarin. HMRC are just the administration and police.
Might goggle "opaque" but as proles don't have the time, too busy paying the tax.
For those who want a more informed view on Zoo Digital the company published its quarterly update yesterday
DFS Furniture (LON:DFS) I doubt this makes DFS a great short term buy necessarily.Yesterday news of a possible ceasefire, and reduction or complete stop of Houthi attacks on Red Sea vessels, between Israel and Hamas, which could result in merchant vessels returning to the Red Sea and lowering freight rates.Let's hope so for everyone.A ceasefire would lead to 4% of global fleet capacity coming to market in 3-4 weeks.
Equals (EQLS)
What is Paul's/The Stocko community's view on the upteenth PUSU extension. My view is that it is creating a false market and the shares should be suspended until the matter is clarified. Others may disagree but I would be interested to know the reason for disagreement.
Equals (LON:EQLS) My view is that it is creating a false market
Absent an offer, shares look reasonably priced at these levels. While they would probably drop a little further if potential bidder 2 withdraws, I don’t see a false market. Everyone accepts that bids are part of the normal market model and anyone is free to hop off of the bus.
Equals (LON:EQLS) : PUSU is so out; this is the year of SAFE (spin along for ever).
@ExpectingValue on X :-)
The year is 2038. #EQLS have extended the put up or shut up deadline for the 174th time. The strategic review is ongoing, though the business now consists of only a bloke in a deserted office putting out RNSes
What is the other sofa company, a competitor of DFS Furniture (LON:DFS) ? The one with the better balance sheet, but smaller in revenues?
Are you thinking of SCS ? as they were acquired by an Italian Co at a knock down price some months ago
Yes! SCS! Forgot that they had been acquired. Annoying.
$SCS?
they were acquired and went private back in oct 23
Did anybody get their sofa (paid up front or on the never never)?
HSS Hire (LON:HSS) Bit of a clanger.Contract lostm worth 7% of total revenue and 10% of group adj. ebita year end 23, ending December 24 announcement.
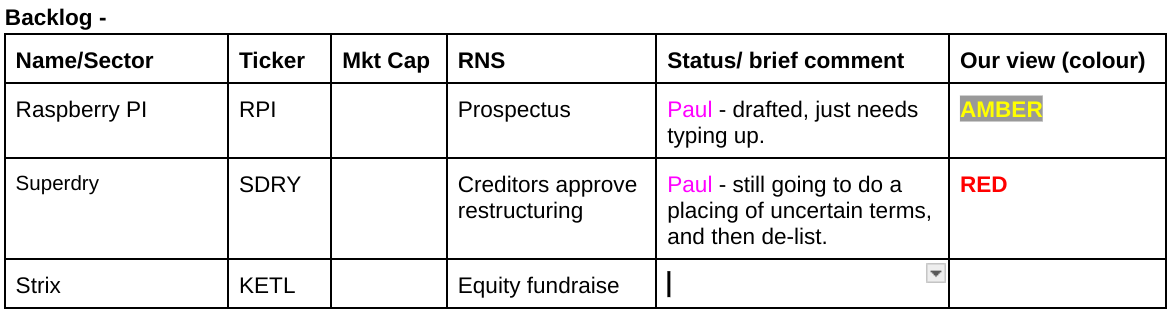
Strix (LON:KETL) - "Successful placing to accelerate deleveraging" - link to note: https://www.equitydevelopment....
Strix has completed a new equity placing initiated by an investor that will raise approx. £8m of proceeds, with the placing shares expected to be admitted to trading on 14 June. The funds will accelerate the pace at which it achieves self-imposed targets on the level of headroom on its key banking covenant. As such, the refinancing of the Group’s banking facility set for 2025 should now be on more favourable terms. The group can now speed up investment in sustainable growth should suitable opportunities arise, while remaining cognisant of the balance sheet.
We have slightly reduced our fair value to 167p / share, reflecting the level of adj. EPS dilution. In our view, the Group remains materially undervalued relative to its peers, particularly now its balance sheet has been strengthened.
Equals (LON:EQLS) "Everyone in favour of extending the PUSU deadline until July 2033, say aye"
£EQLS This situation seems to smell now of desperation, which is hardly good if you are the seller. I baled out a month or so ago, having for once made some money. Strange that the management were so positive in their pronouncements of performance (usually made good), and now so eager to sell out without a real explanation.
The other thing to remember about bid situations is that you can burn a lot of professional advisor fees in the process, and come away with nothing.
Strix (LON:KETL) starting to regret not buying as this one moved off the lows but interesting to see an existing shareholder taking a 5% additional stake at nil discount. The £8m raised will help with the debt pile but if they can genuinely get debt/EBITDA down to a 1-1.5* range then this could have much further to go. Seems to have been taken positively this morning which is unsurprising. One to start reconsidering I think?
Strix (LON:KETL) did pay off the debt they were saddled with at IPO quite rapidly, before they got a bit over-ambitious and racked up the current debt, so their cashflow should help again this time. They do have a covenant of debt/EBITDA that reduces to 1.4 in 2025, so still a risk of another placing to come. I hold.
Strix (LON:KETL) I feel I have to hold my hands up here as being lazily negative after their last trading statement and I sincerely hope I didn't put you off David as you seem to have very good contrarian instincts.
Note to myself - Do better research before posting sloppy drive by analysis based on priors
Strix (LON:KETL) thought of kettles. Excitement rose immediately - like a nice cuppa.
But wait.. water filtration, wellness, filtration - growth - wow.
Aqua Optima - have tried some of their products but still using the ol Brita (another WWII chemical company supported by the US $Clorox).
Strix brands - Laica, Billi, Astrea - never heard of so presume offshore - Brita is my go to.
Personally was watching Sharkninja (NYQ:SN) but at the weekend my super duper smoothy maker blew up. Took apart and tried to fix as you do but these things are not built for 'repair'. One day someone will mug you for the copper - but this is not that day.
All these essential lifestyle gadgets seem short term purchases. Live in London and descale regularly the kettle but still seem to replace every couple of years. Not going broke but annoying to replace something which just heats water. Grandma had the gas ring and a simply aluminium container with a whistle.
I'm focusing on the electrons that come down the cable and make it work and the companies doing it in the oceans and deep underground, hostile environments, for your convenience and make the kit work.
But Strix (LON:KETL) is supplying a lot (lots) of people with a basic essential piece of equipment.
Fascinating reaction to Equals (LON:EQLS) saying the MDB potential bid was off. Some investors clearly a bit too twitchy on the sell button again :-)
Whilst there is no bid going ahead with MDB there does appear to be a commercial partnership in the wings. That could be very interesting for Equals (LON:EQLS) in my view and for once management spending time with a suitor helping a business rather than hindering it! Makes a change. Well done mgmt.
But there is still another bid being discussed. My take on this is that Equals (LON:EQLS) management is not minded to sell on the cheap (good!) and therefore remains confident in their trading position and growth plans (also good). The consortium bid was higher and MDB didn’t want to go that high or compete and now management are in talks with them to see if the right price can be reached.
But commercial partnership potential also suggests MDB see strong potential in the Equals (LON:EQLS) technology and offering which is strong independent validation for the future imo. Do MDB see an application of this in North America they want to take forward, which could be fantastic ?
Intriguing - but not a 9% down announcement for me. Much more positive than negative I’d say.
Hi David. I completely agree that the news is not as bad as many investors first feared and I kept my finger well away from the sell button. But I don’t think we can eliminate the possibility that MDB might be engaged in a protracted fishing trip to glean as much as possible about the technology in order to reproduce it with their own developers.
Equals (LON:EQLS) Madison Dearborn are not going to make an offer for the entire company, but I note they remain in negotiations with management over certain product lines, presumably with a view to anything from a small purchase to a JV to a simple cooperation.
Hi BnB, you're probably already aware, but there were 2 RNSs re Equals (LON:EQLS) this morning. One from Madison Dearborn saying they won't be bidding. But the announcement from EQLS itself mentions that there is another "Consortium" interested in bidding for EQLS which is still interested, and doing due diligence.
EDIT: I see EQLS shares are down 9% to 111p in early trades, so looks like the market is losing interest in the potential bid story. I think Madison Dearborn were the front runners for a bid, so them pulling out (don't know why) definitely blunts the bull story I think.
Hi Paul. Yes, and the withdrawal of MDP could mean anything from they have been outbid by a hungry Consortium to the possibility that Equals is a crock! I hold (loosely, as I prefer WISE and am building a stake to which I was hoping to contribute any proceeds from EQLS)
Equals (LON:EQLS) I suspect the price drop is because having only one bidder will tend to either result in a lower price, or mean there was something MDB didn't like in the DD. I doubt the latter though, after such a long time.
Personally, I was disappointed to see the bid as the company was still on a great growth run with a 4X share price increase since the lows around Nov 2020.
The commercial potential for cooperation with MDB in the B2C area is interesting because it is the B2B business that has driven Equals (LON:EQLS) success. I don't know MDB's business but such an arrangement could bring a lot of retail B2C volume.
I imagine that, if the Consortium don't bid, the price will get another hit. Although it is one of my top holdings I would have a look at buying more in that circumstance.
Castings (LON:CGS)
Canaccord cuts its 2025 forecast EPS from 36.9p to 23.9p and its 2026 EPS from 40.6p to 31.1p.
That's a bit more worrying than suggested by the RNS , so I've sold.
A.
Castings (LON:CGS)
Very poor form if they have not communicated clearly in update the fact that they agreeing to such drops in expected future earnings - I doubt broker would be doing such downgrades without nod and wink or providing their explanation - if I held think I may have done the same as you have done here
RWS Holdings (LON:RWS) expects to hit expectations for the full year, but with an H2 loading and the tone was rather gloomy. I had been waiting for this TU but I’m not persuaded to jump in. Cash position has materially worsened.
DFS Furniture (LON:DFS) - Yesterday - "Shrutisha Morris will replace Nicole Burstow as the Group’s Deputy Chief Executive Officer (CEO). Ms. Morris will join the Board of Directors as Deputy CEO on 1 August." - Suspect she will go straight in as Number 1 perhaps ?
Driver (LON:DRV) - "Interim Results - Good start to Q3, pipeline growing" *** Link to research report here: https://www.equitydevelopment....
The strategic plan implemented in late CY22 is working, with utilisation levels benefitting from the move to a hub-and-spoke operational model and a return to profitability in the smaller Middle East and APAC regions.
H2 24 has started positively, particularly in Asia, as the relatively new office in Seoul is delivering on its early promise. The order pipeline continues to expand, benefitting from the rise in expert headcount. The Board has set aside £1m of ‘excess cash’ to buy back shares and to evaluate M&A in existing and related sectors.
We maintain our fair value of 40p/share. With a sector-leading yield, currently standing at 6.0% for FY24, compared to the average of its peer group of 0.5%, Driver’s share price remains undervalued relative to a basket of its peers and is heavily backed by cash and the NAV.
My morning smallcap tweet: Soft upholstery
DFS Furniture (LON:DFS) Belluscura (LON:BELL) Equals (LON:EQLS) Woodbois (LON:WBI) HSS Hire (LON:HSS) Checkit (LON:CKT) Frontier Developments (LON:FDEV) Genflow Biosciences (LON:GENF) Proton Motor Power Systems (LON:PPS) Dillistone (LON:DSG) Image Scan Holdings (LON:IGE) Castings (LON:CGS), RWS Holdings (LON:RWS)
◄DFS Furniture (DFS)► warns FY-June rev c. £1bn and adj pretax only £10-12m. Blames weak mkt, Red Sea delays. Demand in the upholstery sector down 10%. Q4 order intake was up over 9%, in line. [SP=112.6 Cap=264m]
◄Belluscura (BELL)► to raise up to £2.4m with converts. Terms yet to be agreed! Trading - sales of X-PLOR portable oxygen concentrator in the US $820k in Mar-May [SP=11 Cap=18m]
◄Equals (EQLS)► Madison Dearborn Partners pulls out of bid talks. PUSU extended for the eighth time, to 10 July. [SP=120.65 Cap=226m]. I hold.
◄Woodbois (WBI)► has restructured its Gabon Operation, cutting costs etc. [SP=0.54 Cap=21m]
◄HSS Hire (HSS)► loses Amey as a customer from Dec. It accounted for c.7% of rev and 10% of adj EBITA in 2023. [SP=8.4 Cap=60m]
◄Checkit (CKT)► expansion with Octaphama Plasma worth c.£718k over 3 years. [SP=22.2 Cap=24m]
◄Frontier Developments (FDEV)► guides FY-May ahead of exp with rev c.£89m and adj EBITDA positive. Guides FY25 in line. [SP=277 Cap=109m]
◄Genflow Biosciences (GENF)► gets €396k grant. [SP=3 Cap=10m]
◄Proton Motor Power Systems (PPS)► wins first follow-up order from H2tec. £££. [SP=2.18 Cap=36m]
◄Dillistone (DSG)► AGM stmt - trading is marginally ahead of management expectations for H1 but mkt has softened further in Q2. [SP=9.5 Cap=2m]
◄Image Scan (IGE)► wins £350k+ order for delivery in H2 FY24. [SP=1.52 Cap=2m]
◄Castings (CGS)► FY-Mar rev up 11% and pretax £21.3m (£16.7m). In line? Outlook - "Our heavy truck customers are suggesting that the current lower levels of demand are likely to continue in the short-term with the potential for a slight increase in the autumn". [SP=370 Cap=161m]
In line: RWS
Despite a few functionality challenges/teething problems with Loom, great videos you posted over the weekend Paul - thanks.
Agreed. They were really educational. I have set up some new screens following your videos. They have shown me how to go in to much greater detail and depth than I realised was possible. Thanks for taking the time to share these Paul
That's great to hear, thanks The Jayman & Norfolk'n'Good.
I had an inkling that the stock screening tools on Stockopedia may not be used that much by subscribers, so I wanted to flag up that the broker upgrades fields in particular make a great basis for a screen you can run regularly to spot good emerging opportunities in companies that are getting upgrades - very topical right now.
I appreciate the positive feedback!
They're not an official, polished Stockopedia thing, more just a user showing other users how I set up my own screens, complete with any glitches, because that's how the real world is! So I thought seeing me figure my way around the screens feature would be helpful.
Best wishes, Paul.
Apologies I've been out of the Loop (not Loom:) for the last few days. I'm pressed for time today; would someone kindly post a link to the videos so I can watch later/tomorrow?
Many thanks
Link to my broker upgrade screen video is here:
https://www.loom.com/share/896...
I'll have to add these to the links on the explanatory notes, bit pushed for time right now as I'm flying out to Washington DC at lunchtime, so need to get to Heathrow pronto!
Thanks Paul - enjoy Washington it's a great city!
Thanks Paul. Great concept. Why Don,t Stocko provide this as part of their service rather than you and us do our own separately?
They already do a section on how to build screens: https://www.stockopedia.com/le...
The problem with EPS is some are only 1 decimal place, not good if the EPS is only 0.2, need a big upgrade to go to 0.3
Getting the big picture on the presidency?
Took a tiny punt in JPmorgan US Smaller Companies Investment Trust (LON:JUSC) to test the waters outside of the madness - but not convinced with ETF's, not for this sector anyways.
Would be nice to hear the 'sentiment' on the ground outside of our supposedly 'impartial' news sources - lol.
Where can these be accessed?