Small Cap Value Report (Wed 14 Aug 2024) - BKS, STB, ULTP, IUG, PTEC, FLTR, SBDS, IXI, DIS

Good morning, it's Paul & Graham here!
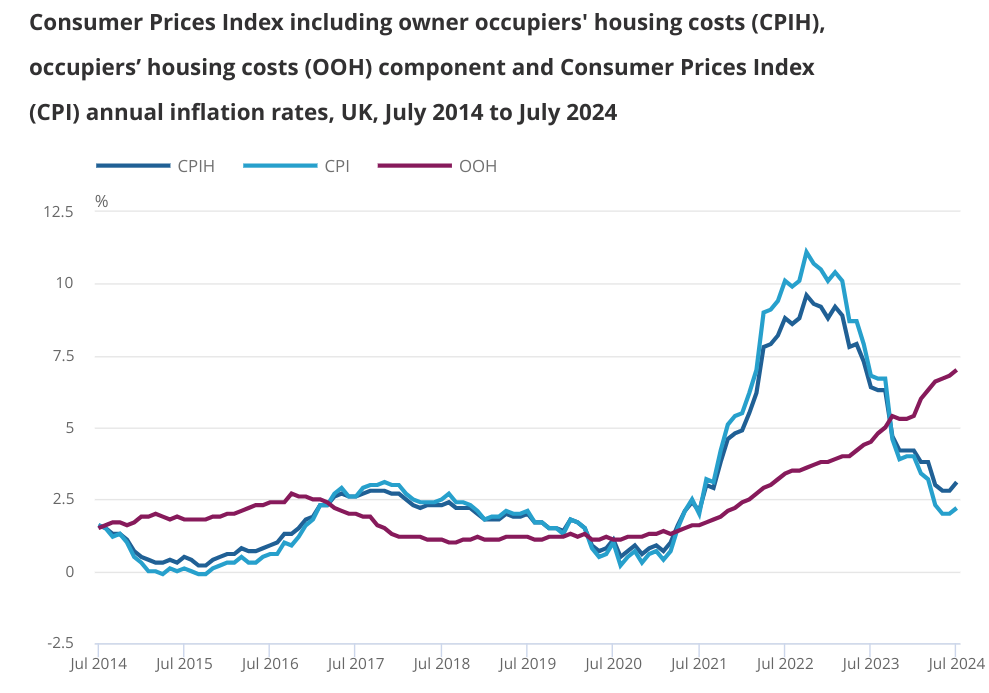
July 2024 ONS Inflation Report
Key points -
"The Consumer Prices Index (CPI) rose by 2.2% in the 12 months to July 2024, up from 2.0% in June 2024."
(a rise was expected by analysts, according to the BBC)
"The largest upward contribution to the monthly change in both CPIH and CPI annual rates came from housing and household services where prices of gas and electricity fell by less than they did last year; the largest downward contribution came from restaurants and hotels, where prices of hotels fell this year having risen last year."
Explanatory notes -
A quick reminder that we don’t recommend any shares. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech, investment cos). Although if something is newsworthy and interesting, we'll try to comment on it. Please bear in mind the "list of companies reporting" is precisely that - it's not a to do list. We typically cover c.5 companies per day, with a particular emphasis on under/over expectations updates, and we follow the "most viewed" list of readers, so if you're collectively interested in a company, we'll try to cover it. Obviously with the resources available, we can't cover everything! Add you own comments if you see something interesting, and feel free to discuss anything shares-related in the comments.
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to, if they are using unthreaded viewing of comments.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. And/or it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Others: PINK = takeover approach, BLACK = profit warning, GREY = possible de-listing.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom), Video update of results so far, June 2024.
Frozen SCVR summary spreadsheet for calendar 2023.
New SCVR summary spreadsheet from July 2023 onwards.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Phil Hanson's data analysis measuring performance of our colour-coding system in the SCVRs, from July 2023- Mar 2024 (with live prices). My video explaining/reviewing it.
My other video (June 2024) - How to screen for broker upgrades on Stockopedia.
Companies Reporting
Other mid-morning movers (with news)
Playtech (LON:PTEC)
Up 19% to 639p (£1.98bn) - Response to media speculation - Paul - NO COLOUR, but looks interesting!
This is all I’ve got in our archive for this gambling technology group -
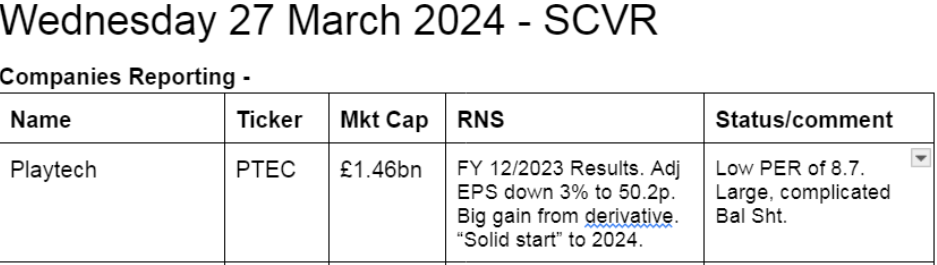
Sky News revealed at 10:14 this morning that -
“Flutter Entertainment is in detailed talks to buy Snaitech, a deal that would leave owner Playtech as a pureplay B2B operation…in a deal that could be worth about £2bn”
Is this really how price sensitive information should be revealed - by the press, during market hours? The regulatory rules are clearly unsatisfactory.
£2bn is an eye-catching figure, given that PTEC’s entire market cap is c.£2bn after today’s 19% rise.
Playtech has been forced to respond with this RNS today - key points being -
- Yes it is in talks with Flutter.
- PTEC has granted Flutter a period of exclusivity to do due diligence & finalise documentation.
- No certainty a deal will proceed, nor as to the terms (standard wording).
Paul’s view - this sounds like a well-advanced potential deal, which should have been disclosed to the market previously, thus they have created a false market in PTEC shares by withholding price sensitive information from investors. Imagine if you'd sold 20% lower, unaware that seemingly advanced bid talks for the largest business unit were in progress?
The next step for investors would be to do a spreadsheet to work out how much each part of the business is worth (or see if a broker has done it for you!). That should be fairly easy, as looking at the last accounts, it splits out Snaitech's EBITDA of 256m Euros in FY 12/2023, so convert into sterling at 1.17, gives £219m. Hence a £2bn valuation looks to be an EBITDA multiple of 9.1x. That’s assuming it’s done on cash/debt-free basis. Is that a fair price? I don’t know, maybe any M&A specialists could tell us if that’s the sort of multiple to be expected in this sector?
The Stock Report shows the entire group’s EV/EBITDA as 6.78x, so a disposal at a usefully higher ratio could add value maybe?
As mentioned last time, PTEC has a large & complicated balance sheet, so I can’t readily determine what the debt levels are other than to repeat the 283m euros shown as net debt in the 2023 accounts highlights. Suggesting that a £2bn disposal would leave it with tons of surplus cash.
That’s as far as I can go with it, without spending the rest of the day getting into the detail, so I’ll conclude with a “looks interesting, worth taking a closer look” conclusion.
Another thing to bear in mind is that quite a few bid approaches this year have fallen through, so the downside risk is you end up buying into a spike upwards, but as always that’s your call.
Flutter Entertainment (LON:FLTR)
Up 9% to 15,965p (£28.3bn) - Q2 Results - Paul - NO COLOUR
I can’t see any separate announcement from Flutter re the potential deal with Snaitech - please post a link if you find anything from them.
FLTR if you recall moved its main listing to New York (FLUT) but still seems to also be listed in London (FLTR).
FLTR has a horrendous balance sheet, with giant goodwill and intangible assets. Strip those out, and it’s NTAV is something like $(9)bn negative. There’s a lot of net debt too, at $5.5bn, a leverage multiple of a fairly high 2.6x.
Which raises the question, how is Flutter intending to finance the deal to possibly buy Snaitech for almost $2.6bn, given its already high debt?
There’s a gulf in valuation between FLTR (shares look over-valued), and PTEC (shares look cheap), so this looks again like the US-UK mismatch in valuations coming to the fore.
Intelligent Ultrasound (LON:IUG)
Down 6% to 10p (£33m) - Half-Year Report - Graham - AMBER
I would personally be inclined to stay away from this one as it’s a complicated situation where the underlying businesses don’t seem to be very good. IUG is selling its largest business for an enterprise value of £40.5m, and it then intends to make a “material return of capital following a review of the growth potential and capital requirements of the post-transaction business and taking legal and tax advice on the structure of a return”.
Unfortunately the post-transaction business is not doing very well. Today’s income statement shows continuing operations with H1 revenues of £4.5m (down from £5.8m) and an operating loss of £1.4m (H1 last year: operating loss £0.6m). The cash balance has fallen by £2m in six months to just £1m. Based on these figures, I’m not convinced that IUG shares offer much value here. A significant chunk of the disposal proceeds may be needed to fund their remaining activities.
Silver Bullet Data Services (LON:SBDS)
Up 11% to 86p - New Contracts - Paul - AMBER/RED
As others have commented, it’s impossible to draw any meaningful financial information from today’s buzzword-infused update (eg AI mentioned 6 times). These sound more like partnership deals, than sales contracts. No indication is given of size, other than it all sounds terrifically exciting, in huge & rapidly growing markets that SBDS might somehow be involved in.
Note also that it’s appointed Zeus as joint broker. I take that as a sign that another equity fundraise is possibly being planned, and a fresh set of investors are needed, but that’s obviously just educated guesswork rather than firm fact at this stage.
A reminder that the last accounts (see SCVR 29/5/2024) contained a “material uncertainty” going concern warning - clearly flagging that more equity is needed. I don’t care what anybody says, when you have a material uncertainty warning, combined with a new joint broker being added, that points strongly towards a likelihood of another placing. It's anybody's guess what the size, and price would be.
On the plus side, SBDS does sound quite interesting, but personally I’d want to know it’s financially secure before investing, which it isn't at the moment, due to that going concern note.
Punters love the story here, and it 8-bagged from mid 2023 low to Feb 2024 high - it’s since halved. So there’s scope for the same story to fire up investors again, if some meaningful (as opposed to today’s rampy-sounding) announcements are released. I do like the rapidly rising revenues, and shrinking losses though, so am happy to keep an eye on this potentially interesting company. But it needs more cash, so for the time being it has to remain at AMBER/RED, to flag the dilution risk, sorry to anyone infuriated by that. I'm happy to take a fresh look once it's properly refinanced.
IXICO (LON:IXI)
Up 37% to 9.0p (£5m) - Trading Update & Contract Win - Paul - AMBER
Some signs of life here, with a better than expected trading update, good order intake, and a contract win.
I previously flagged that this looks quite an interesting company, but then demand dried up. If it can rebuild revenues, and stem the losses, without running out of cash, then it could recover a bit maybe? Historically it was profitable.
Paul’s view - not a bad little company, but too small to be listed probably.
Distil (LON:DIS)
Down 32% (£2m) - profit warning & needs more funding. Paul - RED
Sales have almost completely dried up.
“This backdrop has created an immediate short-term funding need within the business and the Board is currently exploring funding options to address this need.”
Looks like it’s heading for zero I’m afraid. Who in their right mind would want to refinance this company, given its long & dismal track record? Maybe it could sell its brands for something, who knows? There's also a £3m "financial asset" on the balance sheet, which seems to be building a whisky distillery at Ardgowan - could this be sold to raise cash, or mortgaged perhaps?
Maybe DIS can survive, but it doesn't show any signs of being a viable business, and has spent over 20 years trying, as a listed company.
Summaries
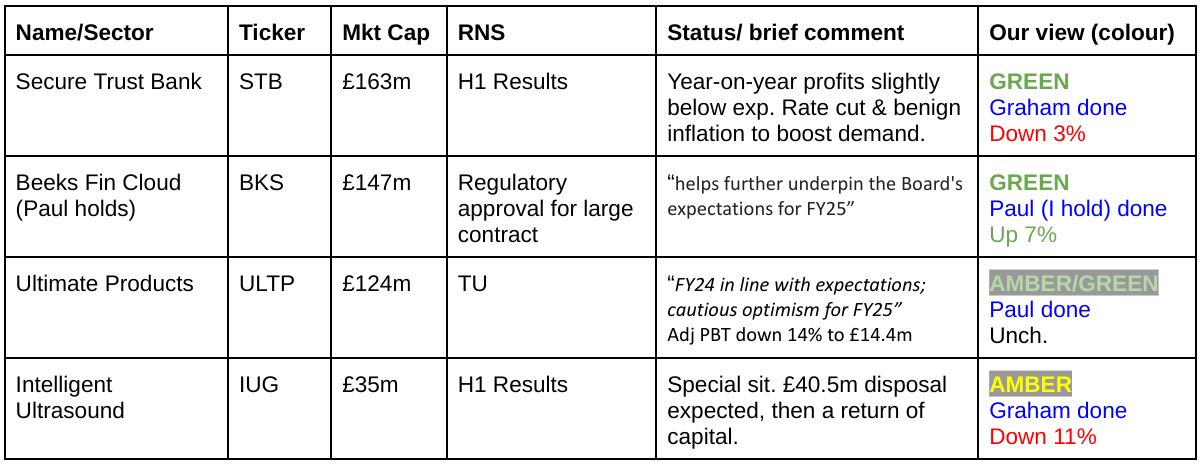
Beeks Financial Cloud (LON:BKS) - (Paul holds) - Up 8% to 238p (£158m) - - Exchange Cloud Contract Approval - Paul - GREEN
Excellent news that regulatory approval has been achieved for a major new contract. Expect further upgrades to forecasts.
Secure Trust Bank (LON:STB) - down 2% to 836p (£160m) - Interim Results - Graham - GREEN
An unusual picture for STB shareholders as they see a mild profit warning for the current year offset by upgrades to forecasts for future years. STB are positive on the economic outlook and very positive on their ability to hit medium-term targets. While I don’t know if I share their confidence, I think the risks are priced in at a PER of 3x.
Ultimate Products (LON:ULTP) - down 1% to 139p (£123m) - Trading Update - Paul - AMBER/GREEN
A profit warning in May 2024 knocked confidence, but things seem to have settled down now, with an in line FY 7/2024 year end update today. Valuation seems reasonable, balance sheet is fine with only modest debt, and there's a useful dividend yield too. I'm happy to move up a notch to a moderately favourable view.
Paul’s Section:
Ultimate Products (LON:ULTP)
Down 1% to 139p (£123m) - Trading Update - Paul - AMBER/GREEN
Ultimate Products, the owner of a number of leading homeware brands including Salter (the UK's oldest houseware brand, est.1760) and Beldray (est.1872), announces its trading update for the financial year ended 31 July 2024 ("FY24").
FY24 in line with expectations; cautious optimism for FY25
For context, we need to remember that it issued a profit warning in May 2024. Here are my notes from 10/5/2024 - with my summary below -
“Profit warning unfortunately, due to continuing softness in demand and customer de-stocking. Broker forecast is dropped by 21%, quite a hefty miss. Outlook for FY 7/2025 sounds better though, with order books improving. I think this deserves a c.20% drop in share price, as previous growth must have been flattered by customers stocking up.”
Hence “in line” today is actually c.20% below the original forecasts for FY 7/2024. So it’s not good, just that things haven’t deteriorated further.
Key numbers (draft, subject to audit) for FY 7/2024 -
Revenues 6.5% to £155.5m
Reasons given for softer trading - this is consistent with what they’ve said previously -
“supermarket ordering held back by overstocking, weakened consumer demand for general merchandise, and strong prior year comparatives having been bolstered by the exceptionally strong demand for energy efficient air fryers in H1 2023.”
Clear guidance - I like that they’ve included both EBITDA and adj PBT - keeping everyone happy -
“In line with market expectations, unaudited adjusted EBITDA* decreased by 11% to £18.0m (FY23: £20.2m) and unaudited adjusted PBT* decreased by 14% to £14.4m (FY23: £16.8m).”
Net debt is absolutely fine, no issues here -
“At the year end, the Group had a net bank debt of £10.4m (FY23: £14.8m), which represents a net bank debt / adjusted EBITDA ratio of 0.6x (FY23: 0.7x), well within the Group's capital allocation policy of 1.0x.”
Outlook - interesting comments for wider read across re Red Sea shipping costs -
"Trading at the start of the current financial year is in line with market expectations. The significant increase in shipping rates, arising from disruption in the Red Sea, has seen some recent stabilisation and is leading supply chains to adapt to a new normal. While this process takes place, the Group's commercial teams are working hard, as they did in the previous shipping crisis, to mitigate the short-term impact on gross margin.”
"Our FY24 performance was not without its challenges but I am pleased to report that many of the temporary headwinds are now easing, as reflected in a healthy FY25 order book. As we look ahead to FY25 with cautious optimism, we are confident in the proven resilience of our business model and the ongoing demand for our fantastic range of leading homeware brands."
Broker updates - we’re spoiled for choice, with 3 brokers updating. I go to ED first, as that’s effectively the company’s forecast, as follows -
FY 7/2024: EPS 12.3p, divi 6.1p (PER 11.3x, yield 4.4%)
FY 7/2025: EPS 14.5p, divi 7.2p (PER 9.6x, yield 5.2%)
Those valuations look reasonable to me.
Paul’s opinion - I don’t feel motivated to rush out and buy this share, but for a plodding type of portfolio, where you just want to own reasonably OK companies at fair prices, and receive a decent yield, and with a sound balance sheet, then this could be a contender.
In recent years management have demonstrated an ability to tackle whatever crises are thrown at them, from covid, through energy, and various shipping & supply chain disruptions.
Pre-profit warning I used to be green on this share, but then moderated to amber on the warning. Things seem to have stabilised since, and the valuation is quite attractive (assuming it achieves the rebound in earnings forecast for FY 7/2025), so I think AMBER/GREEN looks fair at this stage.
Please remember as always that is just my assessment of the facts, figures, and forecasts as of today. It’s not a prediction about what may or may not happen in future. We have to keep reminding people of that, as when something unexpected happens in future, they sometimes tell us that we got it wrong. My reply is always, no we didn’t get it wrong. The facts have just subsequently changed, which is what tends to happen in life!
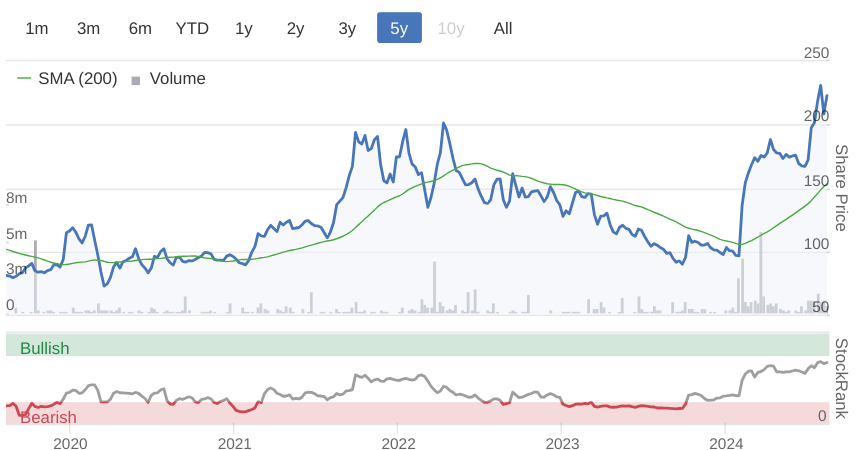
The 5-year chart below isn't amazing, but there have been decent divis on top, so total shareholder return not bad, especially considering all the macro chaos over this period -
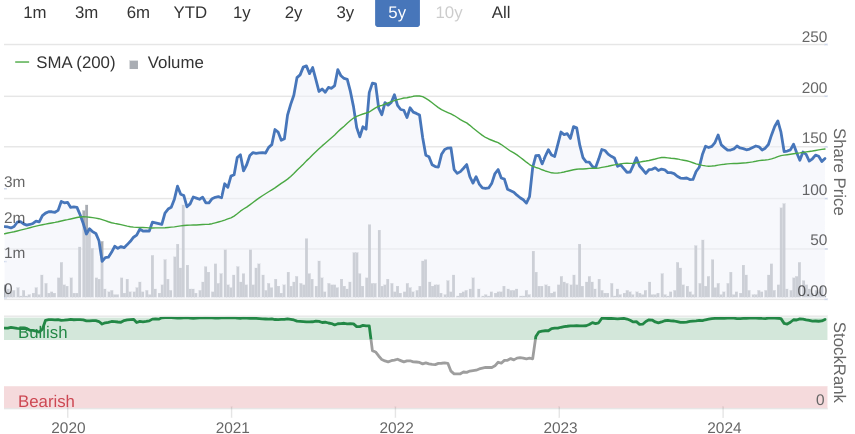
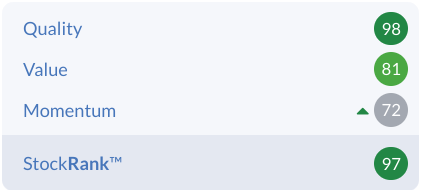
An importer of Chinese-made small household products isn't what I personally would consider a high quality business, but the Stockopedia computers just look at the numbers, and give it an almost maximum quality score - and a very high overall StockRank -
Beeks Financial Cloud (LON:BKS) - (Paul holds)
Up 8% to 238p (£158m) - Exchange Cloud Contract Approval - Paul - GREEN
“Beeks Financial Cloud Group plc (AIM: BKS), a cloud computing and connectivity provider for financial markets, is pleased to confirm that the conditional contract with one of the largest exchange groups globally (the "Exchange"), announced on 6 February 2024, has now received regulatory approval.”
This is very important news I think. Exchange Cloud is the name Beeks gives to its largest size contracts, where it provides white label computer connectivity services for large customers such as the Johannesburg Stock Exchange. They then sell services via Beeks to their own customers, generating revenues for both.
We had previously been told that another large contract was in the offing, going through regulatory clearance. The good news today is that approval has been received, and the contract is beginning to be implemented. I heard a rumour that it might be one of the large US exchanges, possible the NYSE, but I don’t think the client has been specifically announced yet.
EDIT: A google search has revealed this fascinating document, showing that (see footnote 9) the major exchange client is NASDAQ. This is already in the public domain. This document also explains quite well the advantages for traders, hedge funds, etc, using the NASDAQ/Beeks service, instead of having to go through all the cost, and complexity (and maintenance) of installing their own servers at the exchange. Once Beeks is installed, new clients can sign up and be actively using the service in hours. We'll just have to wait and see what level of take up there is, before forecasts can reliably be increased. It all looks very interesting to me, and a mkt cap of around £150m doesn't seem a lot for a company achieving this kind of success. Plus all the follow-on pipeline deals with other exchanges alluded to in the comments today. I am talking my own book of course, but am genuinely quite excited about the potential here. End of edit.
There’s a bit more detail here -
“Following receipt of regulatory clearance, the deployment of services and recognition of revenue has commenced. A further announcement will be made by both the Company and the Exchange when the full platform is available for customer deployments in due course. The deal helps further underpin the Board's expectations for FY25 and marks the initial phase of an intended multi-year partnership between Beeks and the Exchange.
This deal marks the third international exchange to sign up to Exchange Cloud, Beeks' multi-home, fully configured and pre-installed physical trading environment fully optimised for global exchanges to offer cloud solutions to their end users. With a proven ability to secure contracts with the world's largest exchanges, Beeks remains highly confident in fulfilling the product's transformational potential.
The Exchange Cloud pipeline continues to build, with advanced discussions taking place with other major Exchanges across the globe.”
What’s interesting about these deals is that they’re difficult to secure, taking several years of preparatory work, and proving up to the client that the service is bulletproof. Once installed, there’s no incentive for the clients to look at replacing Beeks, so it should lead to many years of reliable recurring revenues, which grow over time (land and expand). There is up-front capex, which is unavoidable, but the key point is Beeks is achieving rapid compound multi-year growth, and has now passed the tipping point where it’s profitable and beginning to generate cash. Each big new contract is another reference site, thus building Beeks' reputation. Importantly Beeks didn't suffer any outages in the recent worldwide IT glitch.
Hence I think valuing Beeks on conventional value measures is missing the point, due to the rapid growth. Whilst a value investor at heart, I can also appreciate that when you find an exceptional growth situation, it’s worth pushing out the boat in terms of valuation. Takeover deals, and bank financing, are done on multiples of EBITDA, or even multiples of sales for tech companies.
Importantly, the existing forecasts do not include anything for this latest contract win, as my understanding is it was deemed prudent to hold back until the regulatory approval was achieved. Hence we should now see further upgrades in broker forecasts.
I imagine we should see a 10%+ rise in share price today, and continuing rises. Although you never know how much has already been anticipated by the market, and there has been considerable volume in the last week or two. [EDIT: so far my optimism has not been shared by Mr Market, with only a 3% rise by 09:04).
See a new note out this morning from Canaccord, which gives some helpful valuation comparisons with global sector peers, suggesting BKS is still relatively good value.
Graham’s Section:
Secure Trust Bank (LON:STB)
Down 2% to 836p (£160m) - Interim Results - Graham - GREEN
They don’t lead with this as a headline, but this statement includes a slight profit warning:
We are still targeting significant growth in year-on-year profits, although slightly below our previous expectations.
Let’s review some of the financial highlights:
Loan book up 3.2% year-to-date, up 8.3% year-on-year.
PBT +14% year-on-year to £17.1m
Tangible book value per share up 3.1% year-to-date to £18.36.
The shares trade at an amazing discount to book value, with the potential for the share price to more than double if they traded at par - but deep discounts are the norm.
Medium-term targets: STB remains confident in its medium-term plans.
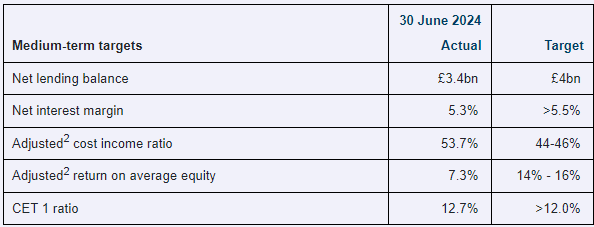
The loan book needs to grow another 18% to hit that £4 billion target, which should take another few years.
Net interest margin needs to improve a little; it went backwards in H1.
Adjusted return on average equity appears to be the major source of difficulty, with a large gap between current performance (7.3%) and target performance (14%-16%).
STB are confident that they can hit the adj. ROE target when their loan book reaches £4 billion, but I’d like to see a detailed explanation as to how that is possible. We see very few banks/lenders achieving ROE of 14%+, adjusted or not. Will they achieve it through immaculate financial performance or only through adjustments?
Leverage: the CET1 ratio of 12.7% is above target and implies a safe level of gearing.
The trend since the GFC has been for banks to have very safe solvency ratios, and therefore to earn low returns on equity (because they aren’t using enough leverage to boost their returns). In other words, the higher STB’s CET1 ratio is, the more difficult it is for it to achieve a high ROE!
Dividend: a rebased, lower interim dividend of 11.3p will be paid.
FCA/Borrowers in financial difficulty: this is relevant to our recent discussion of S&U (LON:SUS) and the FCA’s interest in how it treats its borrowers. STB is also under the microscope, and following a review, it now offers customers “a wider range of forbearance options to support them through financial difficulties”.
During the review period, STB paused collection activities in Vehicle Finance, with the result that more loans defaulted than normal and the impairment charge was higher than normal. Fortunately, these metrics are trending back towards normal now that the review is complete.
STB also acknowledges that it historically (up to 2017) paid discretionary commissions to brokers. These arrangements weren’t banned until 2021, but there is a risk of retroactive action. Next steps will be communicated by the FCA in May 2025.
Outlook: this is helpful for a read on the current state of the economy:
UK inflation appears to have stabilised around the Bank of England's target level and we saw a first reduction in the Base Rate for over four years in August, slightly ahead of market expectations. The new UK Government has outlined its programme of change to deliver growth, and business confidence is at the highest level we have seen in the last two years. We are therefore optimistic that the trading environment for our business and economic environment for our customers is improving. The Group expects to see further loan book growth in the second half and further progress towards the £4 billion net lending target which will support improved profitability.
Estimates: Shore Capital have downgraded FY24 EPS by 7%, but they have upgraded FY25 and FY26 estimates by 4% and 9% on the basis of an improving UK consumer and the identification of additional cost savings at STB. They think ROE can improve to 11% for the full year.
Graham’s view
We don’t cover this too often. Partly this is because I suspect that most readers find banks quite dull. It’s also partly because I personally prefer to study alternative lenders (e.g. pawnbrokers).
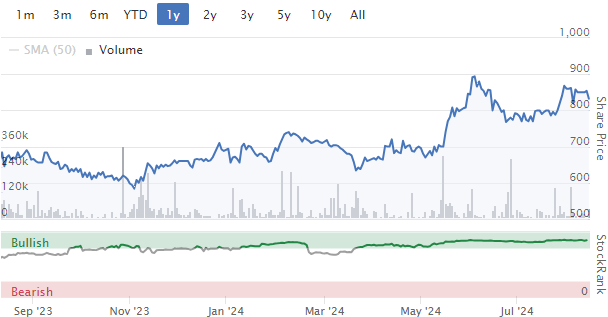
However, we did look at STB back in Nov 2023 (share price: 592p) when I felt compelled to take a positive stance on it. The PER was around 3x, and it was trading at a P/BV of 0.35x.
It’s up by over 40% since then, while paying dividends:
It’s a tough call but I’m going to stay positive on this one again today. Uncertainty never goes away but STB has worked its way through a difficult review period in the Vehicle Finance business and now seems to be on the rebound, and signs are positive that it will at least make some progress towards its medium-term targets, even if hitting them proves elusive.
Pricing remains dirt-cheap, either against the balance sheet or against earnings:
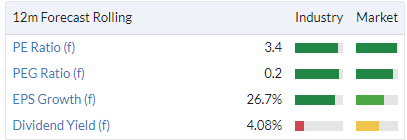
It passes 5 of Stockopedia’s bullish stock screens, including the Ben Graham Deep Value Checklist:
Is it risky? Yes, like any bank. The loan book of £3.4 billion is funded by customer deposits of £3.0 billion. All banks are risky investments, and all of them are difficult to analyse.
Beyond STB’s own actions and decisions, the FCA’s view on historic broker commissions remains to be seen and that is another source of risk, one that is firmly out of STB’s hands.
I’m happy to keep a positive stance on this one but as an investor I have never put all of my eggs in one basket, and I certainly wouldn’t put all of my eggs in a bank.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

75 comments
That's hilarious Paul - why would anyone be infuriated with you :D
Silver Bullet Data Services (LON:SBDS) - with the announcement of a joint broker I'd agree that it looks much more likely than not they intend to raise a bit of cash. I'd like to think it won't be much though and given demand it wouldn't surprise me if its only a small discount.
As I've mentioned before I have a half position that I'd be happy to top up on a raise but if they don't do one I'll still be happy. Let's see what happens.
In some respects if they raise some cash it will stop potential investors saying they need more cash and ironically could have a positive effect on the share price so might be worth doing just for that!!
Bill collector from my door, what can you do for me?
Foxtons (LON:FOXT) collecting the rent
I like very much this format of small sections for the movers rather than a few words on the table. This is very very useful and adds a lot of value to the content. Thanks Paul and Graham for your great work
We do our best, thanks Abel!
https://news.sky.com/story/str...
Nice one by On Beach group (LON:OTB)
Great news!Made me smile.Love the advert too.
Freight rates
Spoke to my forwarder
Freight rates heading down
dropping every couple weeks
Beeks Financial Cloud (LON:BKS) The new big client is NASDAQ, See the link to their announcement:
https://www.sec.gov/files/rules/sro/nasdaq/2024/34-100445.pdf
That should make it far easier to sell elsewhere.
If you're still watching Stockopedia planetx and wondering how to spend some of that wonga on a recovery play, did you read Paul's take on Distil today? I did and if you like a drink and DYOR you'll see De Rothschild (Baron Eric) topped up his holding on 3/1/24 by 34.3 million, he holds 140m. The top holder is Grain, mentioned by Paul who has 23.6%. I'm trying to give it up -- not alcohol, tiny loss making companies. Cheers.
Still watching
Distil looks s basket case ?
We don't hold planetx but I thought those two share holdings interesting when I looked at major holders after reading Paul's comments. Shareholders will probably get shafted but there's surely value in those brands above and beyond the market cap. Call option share price now.
Good luck!
And talking of meaningful movers, IXICO (LON:IXI) is today up 36% as I write, but on this occasion it is likely on the back of this morning's "ahead" TA, plus another contract win, plus a new note from Cavendish with a TP of 24p.
Mkt cap of £4.74m at todays 9.7p less Cavendish's forecast cash of £1.4 gets you to EV of £3.3m.
Again, not for widow, however I think there is early evidence of some traction now in the newsflow.
YouGov consumer confidence data adds to the barrage of positive data about the UK economy. We've had upticks in Services and Manufacturing PMIs, construction output, house prices and now consumer confidence. And at the same time we've had inflation (core measures) continuing to fall , 10 year bond yields falling , wage growth moderating and our first interest rate cut with two more forecast before the end of the year. Good news is going to show up in order books and outlooks before P/L's but just maybe there is the tiniest chance in the world of AIM actually going up this year ?
Big bump (about 25 percent) and heavy dealing in tiddler Cordel (LON:CRDL) . Anyone any thoughts? I have a very small holding and have thought that it may eventually get swallowed by someone further up the food chain.
There doesn't appear to be any RNS today but the newsflow lately has been that of steadily winning (and extending) contracts. Their FY results were announced on 30 Oct last year and their TA this year was 23 July, and pointed to FY revs up 45% at £4.4m. Cash was £1.02m which seems very tight. The TA also announced the appointment of Cavendish as sole broker.
I guess the bulls (myself included) will be looking carefully at the Oct results announcement for the latest trading outlook and evidence of profitability coming into view.
There has to be the chance of a further fundraising though? The last raise was Mar '23 - £1.7m / 28.6m shares at 6p and was oversubscribed.
There has been consistant but fairly small director buying (and no sells) over many years.
IMO it's certainly one to watch if you like getting involved at the micro end of the market.
Good news for those with O+G holdings, such as Serica Energy (LON:SQZ) and BP (LON:BP.) - I hold both
LONDON, Aug 14 (Reuters) - Britain's approval of a new BP-backed gas-fired power station was lawful, London's High Court ruled on Wednesday, dismissing a legal challenge over the project.
Climate campaigner Andrew Boswell took legal action over the decision to build the power station with carbon capture and storage in Teesside, in northeast England.
Net Zero Teesside Power, a joint venture between BP BP.L and Equinor EQNR.OL, aims to build a plant with up to 860 megawatt capacity with post-combustion carbon capture.
Boswell's lawyers argued that ministers did not give adequate reasons for their conclusion that the development would "help deliver the government's net zero commitment".
Judge Nathalie Lieven dismissed Boswell's case in a written ruling on Wednesday, saying: "The development was strongly supported in national policy, both planning and energy policy."
I noticed this article yesterday referring to a Bank of America poll of fund managers, finding that investors are most attracted to the UK market.
If this is true then it should perhaps bode well for some of our more maligned fund managers such as Jupiter Fund Management (LON:JUP) which was up 6% this morning.
I've noticed more anecdotal evidence of changing perceptions towards the UK market in some recent episodes of the excellent Money Makers podcast series. Interviews with a variety of investment trust managers would seem to affirm a trend towards allocations taking advantage of the perceived undervaluation of UK assets.
Do you have a link to the BoFA article?
I'm sorry I don't - it was in the live business feed on the Guardian yesterday.
FT article suggests Value investing is due for a big comeback
Value investing has fallen out of favour in an era dominated by AI-driven tech stocks like the "Magnificent Seven," despite their recent price dips. From its peak in 2007, value investing has struggled, hitting a low in 2020, but signs suggest it may be poised for a comeback.
The argument for value lies in its current affordability, resilience during inflation, and its potential to outperform growth stocks if inflation rises. Historically, value stocks have done well in inflationary periods, offering a margin of safety as higher inflation typically leads to higher interest rates and economic volatility.
To benefit from value, investors could consider portfolios that focus on the fundamental economic footprint of companies rather than just market capitalization. With the current growth bull market showing signs of fatigue, now might be an opportune time to shift towards or blend in more value stocks.
There unlikely to be a clear signal when the growth bull market ends, so there's no reason to delay adjusting your portfolio.
Sky does it again:
EXCLUSIVE: Flutter Entertainment, the owner of Paddy Power, is in detailed talks to buy Snaitech, the Italian consumer gambling arm of London-listed Playtech (LON:PTEC), for about £2bn - a deal worth more than Playtech’s entire current market capitalisation.
Top ups or new ?
Just had a pretty big liquidity event .
Had to sell off some planting land for forestry thanks to the canadian red footed goose .
Despite being able to legally shoot then (i dont for clarity) the fact they touch down one or two days for a quick foragr on a corner of my land whilst on the last leg of their migration meant 3 years of bird surveys .
Also changes to carbon credits now only being applied to broadleaf not coonier means no carbon credits . Expect a shortage of uk timber in 20 years but no one thinks that far .
Anyway big fat chunk of wonga hitting my account this week and probably putting some onto aim .
Centaur will probably increase holding a bit more
Real Estate investors - looks a sure fire 20-30% gain in next 24 months better than 5% in the bank just starting pickinv up a fee
Wynnstay - still believe in it especially in the 340s thats safe
Nationsl World - might have to over rule my distaste for nanagemrnt as its a silly price .
Any “no brainers” with linited downside , i may need this money at some point so 1-2 year strategy .
i do like my recovery plays .
Not looking multi baggers high flying growth nonsense .
You'll have noted an increased investment by a single investor in Croma to 7.4% this morning planetx, I know you like that small company, we hold too. We also hold Wynnstay and have topped up recently although we're underwater now as some farmers fields were. MBH still seems cheap to me and Ramsdens is our top holding now if that's any good to you, pawn shops look like being needed for quite some time. If you fancy a balls out recovery play you could buy Getech, please....
Croma
Ive been adding last week or so on weakness between 67-69p
With very poor liquidity at moment in some of these snall illiquid holdings you can nick a few from tine to time at intraday around 5% below normal trading .
Dont want to go too much higher on croma due to liquidity and dont want to breach 3% as that gets into RNS requirement level .
Planetx, Id be interested to know what's caused the damascene conversion on National World (LON:NWOR) considering your previous strong thoughts on management?
Wolf
National world
Harwood and Rockwood have started building a stake
The company is withoit doubt the wrong price with a self serving ego driven guy at the helm.
On the basis Harwood. /Rockwood wont allow david montgomery to fill his own boots at the expemse of theirs its tweaked my view
Hi planetx, I have been following some of your fancied Deep Value companies and have just checked back. Tyman delisted a couple of weeks ago, but not having bought any of its shares am left wondering. Can you give any details, but of course you may not have held any either.
I never held Tyman.
The only delisting I had was Holders which was a lesson learned .
Tyman didn't delist - they got bought out by an American company at a half reasonable valuation of around 400p a share
Card Factory (LON:CARD)
Marston's (LON:MARS)
Just (LON:JUST)
Keller (LON:KLR)
Natwest (LON:NWG)
All on single figure p/e's, with forecasts going up.
Ok, balance sheets, JUST a bit complicated and MARS working at debt reduction.
Happy hunting.
i own but with current debt levels Marston's (LON:MARS) is a total crapshoot imho !! - when mars say they are working on debt reduction other than selling their crown jewels they have made remarkbly poor progress - i would say they have sold some more crown jewels just recently that will materially help debt - the problem is they previously expected chomping dividends from the jewels they have just sold - so debt down but expected future income will also be down on the basis that dividend stream no longer exists. Look good short term but nice earner given away to keep their heads above water !!
I am liking Whitbread although downward pull in CPHI not helpful but below £8.50 value there and Tribal, with bid at 74p last year got legs at this level. Hope they give you food for thought.
Tribal
Thats top of the list now
Looks very interesting
thanks for the nudge
XPS Pensions (LON:XPS) - recurring index linked fees
Renew Holdings (LON:RNWH) - infrastructure beneficiary
Fonix Mobile (LON:FNX) - underrated cash machine
Mortgage Advice Bureau (Holdings) (LON:MAB1) - housing recovery
I own all
If its short term type plays with no capital gain - Legal & General (LON:LGEN) is what I would do whilst waiting, Patiently.
Although the devil in me wants to ask whether you still hold Filtronic (LON:FTC) as that might have been termed as 'multi baggers high flying growth nonsense'. (I hold)
But I do note your 1-2 year view. Together with Legal & General (LON:LGEN) I do like Phoenix group (LON:PHNX) too, perhaps more so.
But, TBF you seem to be ahead of the game and I'm always interested in your views.
Planetx
hVIVO (LON:HVO) :-D
Big cash pile, growing, inexpensive and good margins...... I know, I know......
Marks and Spencer (LON:MKS) - what's not to like, plenty of growth to go for and paying divi's again
Avation (LON:AVAP) at a whopping 60% discount to NAV with a very valuable relationship with ATR
Palace Capital (LON:PCA) is interesting as it winds down - could be 20-30% over next year and poss more if yields come down.
Marks and Spencer (LON:MKS) Is a 2.5x bagger for me and my best performer as far cash returned from an investment and I think still more to come.
I have a fondness for them, my mum worked for them in Oxford St for many years and I worked there for a few months. I was brought up on their end of date food sales to staff. When my mum retired they looked after her, even when her Alzheimer's started she was still allowed to go to the retirement club.
I think the M&S knickers elastic is being stretched but looked at it's Oxford St competitors from 20 years ago they are not even G-strings now.
Ultimate Products (LON:ULTP)
Current trading
Trading at the start of the current financial year is in line with market expectations. The significant increase in shipping rates, arising from disruption in the Red Sea, has seen some recent stabilisation and is leading supply chains to adapt to a new normal. While this process takes place, the Group's commercial teams are working hard, as they did in the previous shipping crisis, to mitigate the short-term impact on gross margin.
@planetx, if you're looking in, can you check with your forwarder if rates are stabilising? tia
Capital (LON:CAPD) announces the sale of its shareholding in Predictive Discovery for 31m USD. I think this represents around two thirds of its investment holdings - I see this as a positive step as, rightly or wrongly, the City has never liked these investment holdings alongside the core business, and I am sure is a factor behind it very low valuation. Share price been quite weak recently so hopefully this news can drive a bit of a rerating.
Capital (LON:CAPD) - Yes, very positive and long-awaited. I was also very heartened when Rockwood took a small stake in their "springboard/opportunities" pot (3% of their portfolio as of June 24) Hoping they will upgrade this to a core holding.
Green rating by Paul in March and a good piece in Mark Simpson's post in July worth checking out. Need to get the momentum score up!
Capital (LON:CAPD) I've held for a while and been disappointed by the poor SP performance. Particularly the recent drop on what seemed like positive news. The response to the news today is positive and I'm hoping we will see an improvement in SP. Some significant volume today.
My reason for holding is that I see a long term growth story here with the expansion of MSALABS and now the acquisition of a share of Eco-Detection with an exclusive deal to be the provider of this technology to the mining sector.
Miners can pay for investment in MSALABS from savings in mandatory assay testing.
It makes perfect sense for miners to be able to continuously monitor emissions in to local water courses to prevent environmental problems and demonstrate to the local community that they are not polluting the local environment. Again, installing a remote sensing device saves money on manual water testing and more comprehensive results.
I hope that the reduction in debt will enable the company to invest heavily in the roll-out of both MSALABS and Eco-Detection as I see these as win-wins for for the large miners and Capital (LON:CAPD). It is also a way of diversifying away from simply providing drilling services. Both technologies should have a moat once installed (lower costs for the miners) and a stickiness (hard to change supplier).
Charts attached. Daily chart shows possible bottom with significant volume, MACD and TSI curling up and crossing over. Rising RSI.
Weekly chart shows long term channel in which Capital (LON:CAPD) has been trading. Currently near the bottom of the channel and bottom of BB.
This is really good news in my opinion. Capital (LON:CAPD) have been investing significant amounts of capex in growth and it's left their balance sheet quite stretched (in my opinion). MSA Labs is currently losing money - from memory they lost about £6m last year? so that'll be sucking up cash. With gross debt approaching $100m, it lookes like Capital (LON:CAPD) are approaching their debt capacity so I've had some concerns about their ability to maintain their levels of investment.
Liquidating their investment portfolio seems like an obvious solution so I'm glad management have made this decision. (I hold)
sevenmonks
Re £CAPD I see MSA Labs raised $10m as per the 07-Jul-23 RNS...
https://www.investegate.co.uk/...
And that Capital (LON:CAPD) provided in excess of 80% of this.
Is this how you concluded MSA Labs lost £6m last year????
I've just double-checked, Note 25 of the 2023 annual report on page 131 shows a $6.5m loss, $1.3m of which is allocated to a non-controlling interest so I was a little off.
Thank you sevenmonks re Capital (LON:CAPD)
Beeks Financial Cloud (LON:BKS) - this is good news and the reg approval took about as long as I expected it to. Success begets success so as this rolls out it significantly increases their chances of winning other exchanges and tier 1 contracts. This becomes very sticky revenue so these types of businesses tend to trade at higher multiples.
I expect to see upgrades to forecasts over the next few months though not immediately. Suspect brokers will wait to see relative success of this exchange contract and adjust accordingly from there.
4D AI tech from tiddler Silver Bullet Data Services (LON:SBDS) getting more traction from large players:
Leading Programmatic Ad Buying Platform Integration Contract
Silverbullet has secured a new contract to integrate its 4D AI technology with one of the world's largest programmatic self-service advertising buying platforms. This partnership enables advertisers to execute campaigns across multiple formats, including Video, Connected TV ("CTV"), and Display, by leveraging 4D's advanced contextual data set. The Ad Buying Platform transacts US$9.6 billion of spend on its platform, currently growing at a rate of over 20% year over year. With the rapidly expanding global programmatic addressable market projected to reach approximately US$799 billion by 20281, this partnership is ideally positioned for 4D to benefit from brands' spending on the partner platform.
4D Mobile Leading AD exchange Integration
Silverbullet has secured a new contract to integrate its 4D AI technology with one of the world's largest programmatic self-service advertising buying platforms. This partnership enables advertisers to execute campaigns across multiple formats, including Video, Connected TV ("CTV"), and Display, by leveraging 4D's advanced contextual data set. The Ad Buying Platform transacts US$9.6 billion of spend on its platform, currently growing at a rate of over 20% year over year.
https://www.investegate.co.uk/...
with the rapidly expanding global programmatic addressable market projected to reach approximately US$799 billion by 20281 - well that's the first AI forecast I actually believe might be true!!!! Disclosure I have spend t my career in Tech - I am deeply skeptical about the AI hype. So far revenues seem to be driven by tech companies selling to tech companies and funds pouring into marketing. This also happened in the .com boom. The industry seems to be bereft of real examples of AI applications being adopted/delivering value in the end markets in anything like the volume that valuations imply.
Hi Paul, hasn't inflation risen by 0.2% not 2.2%, so the end rate is 2.2%?
The annual rise in the CPI in July was 2.2% compared to June when it was 2%, so the inflation rate has increased by 10% (if you want to be alarmist).
Yes, the new annual inflation rate (CPI) is 2.2%, up from last month's 2.0%.
thanks
Possibly the most important number for the BoE is not the volatile CPI number but the services inflation number which reduced from 5.7% to 5.2% , well ahead of the bank's forecast of 5.6% . The hawks on the committee have consistently referred to the stickiness of services inflation as their biggest concern, if this is trending towards 3% then the path is clear for more interest rate cuts.
Sales growth still expected to resume in FY2025
Ultimate Products (LON:ULTP) owner of the Beldray and Salter brands - released a trading statement today which was in line with market expectations at both the sales and EBITDA level. After a down year in FY2024, sales growth is expected to resume in FY2025. We make modest changes to our FY2025 forecasts in this report but retain our 200p Fair Value for the shares.
As expected, sales revenue fell in FY2024, by 6% to £155.5m compared with our own £157.4m forecast. Sales performance was constrained by supermarkets cutting back orders to reduce inventory levels, as well as weakened overall consumer demand for general merchandise. Moreover, this year’s outcome compares with a period of unusually strong buying of energy efficient air fryers in FY2023. We expect a strong bounce back for sales revenue in FY2025 as international momentum gathers pace and Beldray and Salter benefit from their re-brands in the UK.
Based on a select group of comparable consumer goods companies we reiterate our estimated 200p Fair Value for ULTP shares. We highlight their superior yield and a miserly current 0.8x EV/sales ratio. At a 200p share price the company’s FY2025 EV/EBITDA would be 8.9x and its prospective P/E ratio an undemanding 13.9x. In our view, investors should consider the potential for a material rerating of the shares, driven by a return to positive sales momentum.
Read our research here: https://www.equitydevelopment....
Secure Trust Bank (LON:STB) H1 overview by David McCreadie, CEO video & podcast.
I know Graham will cover later but here are the main points.
Secure Trust Bank (LON:STB) - I'm a long suffering shareholder here. Their results always appear to be on the slightly disappointing end. They seem very poor at hitting their own targets.
Today's results were a prime example - lots of fluff, very cheap, excellent value to book.........but they hide a mild profit warning the best they can (takes a while to find it) and cut the dividend but call it "rebased and progressive". Who are they kidding? Maybe themselves!
Arbuthnot Banking (LON:ARBB) is the better run of these two in my view and used to own a majority stake in Secure Trust Bank. They sold out a few years after demerging this - Henry Angest, the banking veteran at Arbuthnot, is a good judge of things.
Anyway, they are valued at well below book value for a reason. They are not consistently earning returns > than their cost of capital and the dividend yield is also below a bank deposit rate. It's fair value until they do better in my view, particularly with all the regulatory scrutiny.
MoM Inflation down by 0.2% , first decline in over 6months.
Good to see services inflation down but gas prices have almost doubled from 55p per therm in March. Expect a big rise in energy costs in the autumn.
Do you think that's right? my impression is energy bills are not priced off 55p currently and even though gas prices have picked up, at current levels not an issue. A much healthier position re storage across Europe compared to the big spike of 22 augurs well to avoid a repeat.... and to have meaningful impact on inflation, prices would have to remain high. Year on year gas prices north of 125 would be my guess as pushing costs up but it's just a guess.
Oil and gas prices surge amid rising global tensions
https://news.sky.com/story/oil...
Gas is trading about where it has been so there will be minimal energy cost changes.
Our energy prices are not based on spot - they are based on a variety of factors so 70-120p therm is going to make very little difference against last year.
Gas prices have started to move up over recent weeks. This is the main driver of electricity prices. My impression, for what it's worth, is that gas prices have bottomed unless we see a nasty global recession. There is risk to the upside if we have a cold winter or some unexpected geopolitical event. Of course, we also have all the transmission capex and RPI subsidies kicking in as well. With wage inflation still c5% inflation is not beaten.
I agree that Gas prices in he UK now have a different floor to the 50p therm historical range but that new floor has effectively been factored in to the energy price caps over the last year so at these prices don’t expect energy costs to households/businesses to change very much this winter. It will all be around the margin. So I don’t see any big price hikes on the immediate horizon that would impact inflation.
That said I find the new governments policy on energy and North Sea as quite likely to cause gas price volatility and potentially some large jumps in gas price in the future. Investment will slow significantly imo and at some juncture a pinch point will come. Maybe they think they won’t be in power long enough to deal with the fall out and will conveniently be able to say they saved the planet whilst the subsequent brown outs and gas price explosion was someone else’s fault??!!
They would have been much better in my view incentivising gas production whilst penalising oil production if they really want to stop carbon production. The oil market is international so UK taking such an approach wouldn’t threaten our own energy security but a blanket approach across all fossil fuels clearly does. The UK despite its weather quirks does not have sufficiently reliable wind or solar combined with long term battery storage to move away from gas in the near term so in the absence of new technology they are playing fast and loose with UK future. You’d think they’d have learnt from recent events but it appears not and the blinkers are on! In energy once the Capex disappears you don’t fix it quickly either so it would be a multi year problem which could be economically disastrous further down the line. Hope I’m wrong.
My morning smallcap tweet: Distil running on fumes
Distil (LON:DIS) IXICO (LON:IXI) Crossword Cybersecurity (LON:CCS) Beeks Financial Cloud (LON:BKS) Silver Bullet Data Services (LON:SBDS) Versarien (LON:VRS) Hellenic Dynamics (LON:HELD) EQTEC (LON:EQT) Secure Trust Bank (LON:STB), Ultimate Products (LON:ULTP)
◄Distil (DIS)► warns on FY-Mar25 but still guides a rev rise. First 4 months rev down 55%. Blames economic environment, weather. Co has increased promotional activity causing an immediate short-term funding need. [SP=0.41 Cap=4m]
◄IXICO (IXI)► guides FY-Sep rev £5.5-5.9m and EBITDA -£2.1m, ahead of market expectations due to contract wins of £5.8m since March. [SP=6.96 Cap=3m]
◄Crossword Cybersecurity (CCS)► £1.2m PA cost cuts. CFO scarpers. She is thanked. [SP=4.45 Cap=5m]
◄Beeks Financial Cloud (BKS)► gets regulatory approval for the Exchange Cloud contract announced 6 Feb. Underpins FY25 exp. [SP=221.75 Cap=147m]
◄Silver Bullet Data Services (SBDS)► wins contract to integrate its 4D AI technology with one of the world's largest programmatic self-service advertising buying platforms. Lots of jargon but no projected rev. [SP=78.4 Cap=14m]
◄Versarien (VRS)► wins c.£200k contract for co to act as a 'print partner' to support Building For Humanity. [SP=0.07 Cap=2m]
◄Hellenic Dynamics (HELD)► winding-up petition over £85k debt settled with repayment schedule. Two directors loan £5k and €11k. [SP=0.99 Cap=1m]
◄EQTEC (EQT)► receipt of £2m owed by Logik Developments near after latter agrees deadline of 16 Aug for receipt of finds from delayed property sale. [SP=1.3 Cap=3m]
◄Secure Trust Bank (STB)► H1-June. Warns FY profit slightly lightly below mgmt expectations. [SP=854 Cap=163m]
In line: ULTP
Thanks, in particular for “CFO scarpers. She is thanked”. Racy.
For long suffering holders of Sherborne Investors (Guernsey) C (LON:SIGC) (just me I think ) there is a glimmer of hope that Navient (NSQ:NAVI) may finally be about to work. There is announcement that the Healthcare Business Services division has been sold at approx 3x book overnight. The Govt Services business is still in active discussion. These transactions post completion pave the way for significant returns of capital and upgrades to cash earnings. My hope would be they are taken well but who knows in this market. Sherborne Investors (Guernsey) C (LON:SIGC) trades at a huge discount and if Navient (NSQ:NAVI) reacts well to this news then the discount should close since this is the last transaction the vehicle will pursue. An achievement of their target would yield a price for Sherborne Investors (Guernsey) C (LON:SIGC) well in excess of 100. It would appear we are entering the final chapter....at last. Welcome news either way.
Halleluia!
Beeks Financial Cloud (LON:BKS) - Confirms Regulatory approval for working with the major exchange previously announced........And BKS also say, "The Exchange Cloud pipeline continues to build, with advanced discussions taking place with other major Exchanges across the globe.".....So more to come.
Not one for those wanting to make a quick buck but I still maintain Beeks Financial Cloud (LON:BKS) is one of the more exciting companies in the UK at the moment. No reason why it can't continue to grow both it customer base but also the great thing about the cloud is that existing customers use ever more data and so there's solid growth for those customers as well as new. If you look at the big cloud providers they generally can get a good 25-35% margin on their cloud business. Obviously they benefit from economies of scale but you could argue that Beeks benefit from being in a niche area where their customer are willing to pay a premium for the standard.
Either way I continue to hold and expect it'll get taken out but hopefully not until it reaches a much bigger value than it is today
Beeks Financial Cloud (LON:BKS) is one of my largest holding in my portfolio now. I agree, it will be taken out - just how much. I suspect at least twice the price now, given the CE owns over 30% and has slowly been dripping some of his holding onto the market taking some money, but still has circa £50m invested.
If we assume, that one of the largest exchanges in the world are now deploying Beeks products should place it in the top ten, whilst rumoured to be NYSE, could also be Nasdaq, or London (I'm assuming it will be an English speaking exchange), then this would be a game changer insomuch that other exchanges will be looking to see if they can bolt on too.
Gordon has already spoken about an exit strategy, it wouldn't surprise me if he wanted double the current price, where he could walk away with a cool £100m.
With regards timing of a takeover of Beeks Financial Cloud (LON:BKS) (I hold)I have just seen on Discussions Page, Today, Funnymoney - Notes from Justin Waite interview, the following:
The CEO does not provide a specific timeline for selling the company. He mentions that while they will eventually scale and sell the business, it's still "a long way away" from where he thinks they can ultimately get to. He states:
He emphasises that while selling is part of the long-term plan, it's not imminent. The CEO has a target in mind for where he wants to take the company before considering a sale, but he doesn't disclose this target publicly. He also mentions that they receive frequent interest from private equity firms, but they consider the timing is not right yet for such discussions.
Beeks Financial Cloud (LON:BKS) CEO has said on a number of occasions during presentations that he would sell the business and he does have a number in mind. My guess and it is a pure guess based on no information, is £1b. Beeks is also one of my largest holdings as the growth opportunity is significant and we should see further positive leverage.
To be fair I would sell my business for £1bn too! :-)