Small Cap Value Report (Wed 14 Feb 2018) - WATR, HSS, HSP, OTMP

Good morning, it's Paul here.
My apologies that yesterday's article, a car dealerships special, was anything but special - actually it blew its head gasket immediately after leaving the showroom. Sorry about that, I got writer's block & there was nothing forthcoming unfortunately. So some time today has been allocated for me to go back & finish it.
Firstly I'll rattle through the handful of trading updates today from small caps.
Water Intelligence (LON:WATR)
Share price: 200p (up 11.4% at 08:10)
No. shares: 12.07m
Market cap: £24.1m
Q4 trading update & corporate development
Water Intelligence plc (AIM: WATR.L), a leading multinational provider of precision, minimally-invasive leak detection and remediation solutions for both potable and non-potable water is pleased to provide a trading statement for the year ended 31 December 2017.
We are also including an update on our corporate development as we expand our offerings to become a "one-stop" platform with a variety of cross-selling opportunities....
My first job is to look up "potable" in the dictionary! For anyone else who hasn't heard that term before, it means drinkable.
Key points;
- Strong revenue growth - up 45% to $17.7m (note that this is a mainly USA business - 88% of H1 revenues came from USA)
- Growth mainly came from corporate (i.e. own-operated), rather than franchisees.
- Insurance channel looks an interesting growth area - revenues rising from $0.66m in 2016, to $2.5m in 2017;
Insurance channel momentum: first national account implemented; second account signed and in process of implementation; pipeline developing
- Adjusted PBT rose 21% to $1.7m
- Tax cuts - in USA should increase PAT in 2018 & beyond
- Water loss is an increasingly important issue, globally (e.g. forest fires, Cape Town apparently close to running out of water)
- Net debt $1.2m
Outlook - rather long-winded, but this is the key bit;
Global market demand for our solutions is increasing given climate issues and natural resource constraints. The wind is at our back, and we hope to make a difference. We believe that 2018 will bring significant additional revenue growth, both organically and through selected re-acquisition of our franchises.
Profits should also be further enhanced by recent tax legislation in the US, which is expected to materially reduce the Company's tax rate during 2018 and beyond.
Broker update - these days (post the disastrously inept MiFID II) we can only get hold of commissioned research, and notes from the house broker (as this is deemed to be sponsored research). There's an update today from the house broker (available on Research Tree). Its forecast EPS (in US currency, which I have converted into sterling at £1 = $1.39) are as follows;
2017 forecast EPS 8.7c = 6.26p PER of 31.9
2018 forecast EPS 11.3c = 8.13p PER of 24.6
2019 forecast EPS 13.3c = 9.57p PER of 20.9
Personally, I wouldn't buy this share based on those figures - the valuation looks very full, for such a small company. However, I wonder if the house broker might possibly be rather too cautious in its forecasts? It seems to have included little benefit from reduced tax in the forecasts, and is also basing these numbers on revenue growth slowing down considerably from what has been achieved in 2017.
So, the valuation might make more sense if you think the house broker forecasts are too low.
Dividends - nothing historically, and nothing forecast. So this share is for growth investors, not value investors.
My opinion - overall, I think this looks an interesting little company. It's growing strongly, and operates in an area (fixing water leaks) which is very relevant. So I can see why some readers will like this share.
For me, the price looks up with events for now. Mind you, if the company beats forecasts, then that could propel it higher.
Another key point is that I'm trying to avoid opening new positions in very small, illiquid shares. If there's another (maybe worse?) market sell-off, then I generally want to at least have the option of being able to sell, which is often not the case with things this small. So buyers of tiny company shares like this need to remind yourselves that selling could be impossible in another market downturn. That's not a problem if you're only buying a small scrap of shares, or are happy to ride out market sell-offs, but for larger positions, we can be left high & dry in a market sell-off. That's worth considering, in the context of your own tolerance for risk.
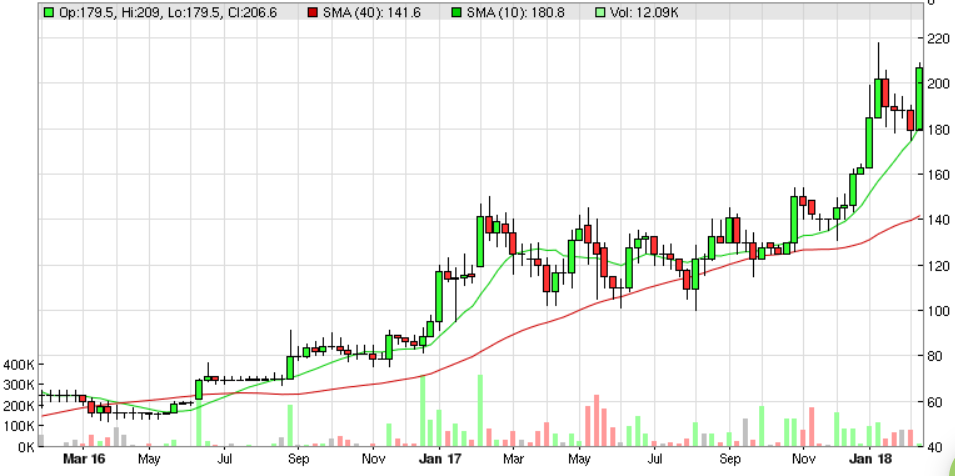
So far, so good though - what a smashing chart (see below);
HSS Hire (LON:HSS)
Share price: 25.0p (up 3.1% today)
No. shares: 170.2m
Market cap: £42.6m
Trading update (and strategy progress)
This is a chain of equipment & tool hire shops - operating from around 230 locations in the UK & Ireland. Its website is here. Today's update covers the 52 weeks to 30 Dec 2017.
Regulars here might recall that I've been consistently negative about this share, since it floated with a full listing, in Feb 2015. The main reason for my negativity is that the ship was holed below the waterline from day 1 - specifically its terrible balance sheet, laden with far too much debt, and negative net tangible assets. There have also been operational problems, and trading losses. Clearly the business was in no fit state to have listed on the stock market at all.
It was clear to anyone who checked the Admission Document, on page 149, that the pro forma balance sheet had negative net assets at the time of floating, in early 2015. That has remained the case since. So the big issue here has always been its very weak balance sheet.
People occasionally ask me why we write about companies with serious flaws (such as HSS) in these reports? The reasons are that it's important to warn readers about companies with financial problems, to help you avoid investment losses. Also, occasionally, these can be interesting turnaround situations. Although it pays to set the bar high, when assessing whether a turnaround is real or not, because many turnarounds don't actually work out as hoped for.
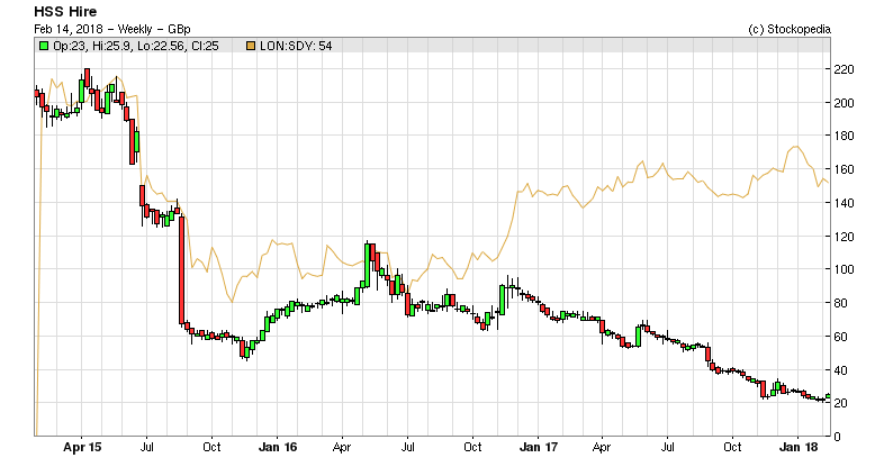
Competitor Speedy Hire (LON:SDY) also ran into operational problems at a similar time to HSS. However, with its very much stronger balance sheet, SDY has managed to sort itself out. That's very much in contrast to the massive shareholder value destruction at HSS, as you can see from the chart below. The main green & red candlesticks are the price of HSS shares. The (rather feint, sorry it's not possible to change the colour) comparator line is the share price of SDY. Note how HSS has destroyed nearly all its shareholders' value over 3 years, whereas SDY has only lost about 20% of shareholder value (excluding divis):
For that reason, I'm always inclined to favour companies with stronger balance sheets. Crucially, a strong balance sheet gives management time to sort out operational problems. Whereas a weak balance sheet can plunge a company into crisis, consume management time, and the shares into a tailspin, when problems emerge.
Anyway, let's see what the company says today;
Current trading - it's profitable at the operating profit (i.e. EBITA) level;
Since HSS last updated the market on 29th November 2017, trading has been positive with the Group maintaining solid momentum.
The Board is pleased to reaffirm that full year performance is in line with guidance given in August, of H2 adjusted EBITA of between 8m and 11m.
Ah, I just spotted that this refers only to H2. I didn't spot that on first (quick) reading, assuming that it was the full year figure. So on checking the H1 results, it's clear why the company is coy about giving the full year figure - because H1 adj. EBITA was negative, at -£7.3m. Put that together, and we're looking at full year EBITA of only £0.7m to £3.7m.
To me, this feels a bit misleading, so my hackles are up a bit - this announcement looks to have been over-PR'd, in an attempt to polish the proverbial.
Revolving credit facility - extended, but the company admits that it needs to be refinanced this year;
HSS also announces that it has successfully agreed with its lenders to extend the 80m revolving credit facility (RCF), which will now mature in July 2019.
Management continues to make good progress towards refinancing the Group and expects to complete this during 2018.
The bank debt isn't a particular problem here. It's the additional loan notes which look unsustainably high to me - which expire on 1 Aug 2019. Therefore the company faces a debt brick wall in July 2019. Both the bank facility, and its loan notes, will need to be refinanced by then, otherwise the company goes bust.
Curiosity got the better of me, so I've had a dig into the most recent (2016) Annual Report. It contains some fascinating information on the debt structure, as follows;
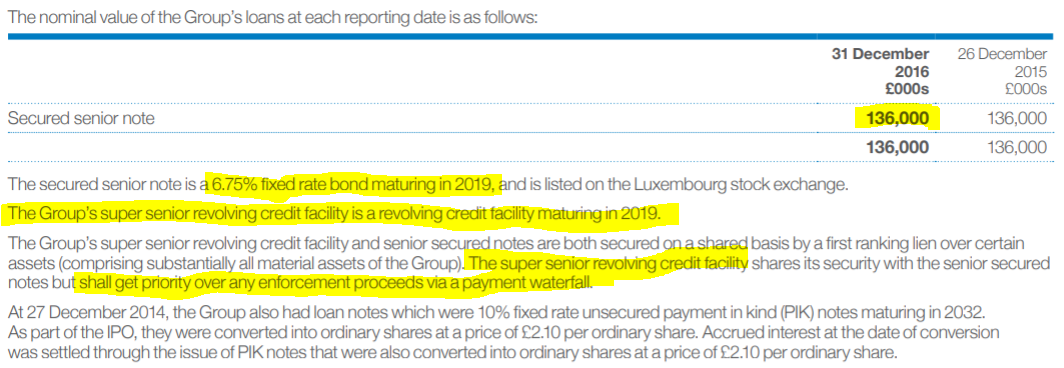
I've not come across senior, and super-senior debt structure before. It's quite straightforward though, reading the explanation above (note 17, on page 101 of the 2016 HSS Annual Report). The bank effectively ranks ahead of the loan note holders. That explains why the bank is prepared to extend its RCF until just before the bonds mature - because it's first in line to be paid off from asset disposals (well, after any preferential creditors anyway) in a winding up.
I've put a request in to my stockbroker to get a current price on the bonds. Not because I want to buy any, but to ascertain how much below par they are, which would indicate how negative bondholders feel about the likelihood of them getting their money back.
OK, my broker has just emailed me live prices on the bonds. They're only at a small discount to par, 95.8 Bid, 97.3 Ask. This indicates that the bondholders seem confident of getting their money back, i.e. par value of 100, plus interest between now and 1 Aug 2019. That's assuming that there's liquidity in the bonds, which there might not be, given that it's a small issue of £136m in total. If that's concentrated in the hands of a small number of holders, then the price could be artificial.
Therefore the biggest issue facing HSS is whether, and how to refinance its £136m bonds before 1 Aug 2019. To my mind that looks possible, so it's not necessarily an insurmountable problem. Although I imagine that a fresh equity element to a refinancing package is highly likely - meaning that existing shareholders are highly likely to be diluted, potentially at a deep discount, at some point this year.
For this reason, I would consider this share uninvestable until the refinancing is done. The big danger for private shareholders is that a refinancing might exclude them, if the company decides it has to do a discounted placing. There's no guarantee that an open offer for existing shareholders would be included. So it's just too risky.
Another way of looking at it, for punters, is that the shares could be seen as a call option on the restructuring & refinancing working out. In that case, and with a good dose of luck, there's an outside chance that the shares could recover strongly. Would I want to risk 100% of my money though, just on the off-chance that all the moving parts successfully slot together? Definitely not!
Note also that the bonds attract about £9.2m p.a. in interest expense. It's possible that a refinancing might reduce that rate, but not by much, would be my guess, as it's quite high risk lending. Therefore after taking into account interest expense, the company remains loss-making. No wonder they want to steer us towards EBITA, which ignores interest expense.
There's lots more detail about restructuring the business, which I won't go into here. It sounds extensive though, including this bit;
In the first half of 2018, the testing and repair of all fast-moving products will be completed closer to HSS's customers, using the Group's skilled colleagues across our network of distribution centres and branches. This change will mean far better levels of utilisation and efficiency for the Group, with improved availability for customers as more products will be available for hire in branches.
As part of these changes, the Group will recognise a provision for exceptional costs of approximately 40m, including an impairment of related assets of 7m. This is expected to give rise to a net cash outflow of 2-3m in 2018, followed by net cash inflows of 7-8m annually over the following seven years.
Overall then, I see this share as, at best a special situation, and at worst a punt that could result in a heavy, even 100%, loss. So definitely not one for me, being much too high risk.
Hargreaves Services (LON:HSP)
Share price: 346p (down 3.9% at 12:39)
No. shares: 32.0m
Market cap: £110.7m
Interim results - for the 6 months ended 30 Nov 2017.
Hargreaves Services plc (AIM: HSP), a diversified group delivering key projects and services to the industrial, energy and property sectors...
This business was originally a UK distributor of coal. However, that activity is now winding down, so it has diversified into other areas, and also is property-rich.
In H1 2017/18 the key P&L numbers are;
Revenues down 12.1% to £150.3m
Underlying operating profit of £2.3m up 9.5% on prior year H1.
I'm losing interest already. The interim dividend is held at 2.7p.
This share seems to be more about asset disposals, to release locked-in value;
... the Board remains confident that there is substantial shareholder value to be realised.
Net debt fell by 44% to £20.6m, and is expected to remain at a similar level by year end of 31 May 2018.
There is a nice summary of the group's strategic aims, and progress to date, in today's results;
In April 2016, we announced three key strategic objectives.
First, to report an Underlying Operating Profit from the Distribution & Services business in excess of £10m by the year ending 31 May 2018. This was achieved in the year ended 31 May 2017, and these interim results indicate that this improved operating performance is being sustained.
Second, to create more than £35m of value from the Property & Energy portfolio by 2021. To date only £2.4m has been realised in cash from the Property portfolio and the work to realise further value continues.
The successful development of the Blindwells site will be a key demonstration that the Group possesses substantial latent value in the land portfolio.
A key element of the value creation in the Property and Energy portfolio is the separation and spin off of the Energy business into Brockwell Energy Limited. The process to secure funding for Brockwell is well advanced with discussions progressing with several credible financial institutions. The Brockwell management team and their advisers have indicated that they are confident of achieving financial close within the next few months.
Finally, to generate £60m of cash from the realisation of Legacy assets. To date, £27m has been recorded and the net book value of the remaining legacy assets is £33m, compared with £42m one year ago.
My opinion - after reading the above, I'm having to file this in the "too difficult" tray.
It's clear that to value this share, a sum of the parts calculation, would be most appropriate. I haven't got time to do that work.
Note that the balance sheet has NAV of £134.9m, which reduces to £122.8m NTAV, or 384p per share (compared with a share price of 346p. The thing is, that some items on the balance sheet (e.g. property) might be worth more than book value, whilst other assets might be worth less than book value. So I can only guess at what the shareholder returns would be. Disposals might attract tax charges on any profit over book value.
I think you also have to consider the opportunity cost, with an asset realisation type situation like this. It's all very well hoping to make x% return, but you might have to sit tight for several years, during which time your money could have been generating a faster return on something else.
There's not enough information to enable me to value this share, therefore I can only say that I'm neutral on it. I do recall several lunches with management going back a couple of years, and they struck me as pretty shrewd. The CEO has a big personal holding, so is certainly incentivised to squeeze every drop of value out of the assets
Onthemarket (LON:OTMP)
Share price: 143.5p (floated at 165p on 9 Feb 2018)
No. shares: 60.53m
Market cap: £86.9m
This is the UK's 3rd largest property website, after Rightmove (in which I have a short position) & Zoopla. It was originally formed in 2015, as Agents Mutual - set up by a group of estate agents who were fed up with paying hefty fees to Rightmove. It failed to de-throne Rightmove, and ended up being an also-ran.
Floating on AIM could be seen as a second attempt to make the concept work. The shares joined AIM last week, and has raised £27m net of fees in fresh funding. Plus existing funders have converted their loans into shares.
The huge problem facing any new entrants in the property portal space, is that Rightmove is so dominant. Estate agents have to use Rightmove, since about 90% of properties are listed there, hence Rightmove is where the customers go. This has enabled Rightmove to become enormously profitable, and become more-or-less a monopoly.
Can OTMP de-throne Rightmove on this second attempt? Probably not, is my view. However, if it does succeed, then the shares would be a serious multi-bagger - Rightmove's market cap is currently about £3.9bn, about 45x the market cap of OTMP. Therefore OTMP shares could be seen as an option - i.e. they'll probably not work out, but if they do, then the upside could be very big.
What is OTMP doing differently? Not very much, as far as I can see - its website looks like any other property portal. It's trying to persuade agents to give it exclusive property listings, and to list properties first on OTMP's portal, before putting them on Rightmove. These supposed advantages can then be used in its marketing, to persuade customers to switch from using Rightmove to using OnTheMarket instead. That seems a very tall order to me, but it has a new pot of money to do renewed marketing.
Another interesting development, is that now its shares are listed, OTMP can do deals with estate agents, and incentivise them with share options perhaps? I read some research on OTMP just before it listed, and it has plans afoot to double the number of estate agents that use it. So I wouldn't dismiss it just yet.
My opinion - I wasn't tempted to participate in the OTMP IPO. Usually, if I get access to an IPO, it probably means that there isn't much institutional interest, so it's instead offered to pond life like me!
I think a better way to play this might be to short Rightmove (LON:RMV) which I did some time ago. My rationale for doing this, is that RMV now faces a renewed competitive threat, coming from a different angle - i.e. OTMP is still mainly owned by estate agents, with a vested interest in it succeeding. So maybe the original disrupter, Rightmove, could now itself be disrupted?
The other thing is that RMV makes too much profit. Therefore, I think it is potentially vulnerable to some kind of different competition. For example, if Google, Apple, or Amazon decided to start offering a free, worldwide property portal, it would kill Rightmove stone dead. Also, Rightmove now has very little organic growth potential, as it already has near-100% market penetration.
It will be fascinating to see how this pans out.
(work in progress)
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

32 comments
Hi Paul,
As a property wantrepreneur, I am not sure Rightmove (LON:RMV) is impacted by on the market.
Specifically, agents I have dealt with using OTM (2016) used OTM and Rightmove. They dropped Zoopla because OTM wanted exclusivity and agents needed rmv.
Don't know OTM, don't like agents, although recently I have been impressed with one (not listed)! I hope to be long rmv and zpg one day when valuation is more palatable mainly because Google could if they choose rip them (and many in many industries) to shreds!
Long Google voting shares and everything :)
Paul,
You correctly highlight the risks involved in investing in small, illiquid companies. For me, however, this is one of the attractions of Water Intelligence (LON:WATR).
- Its smallness means that there is potential for it to 10-bag yet still be a small-cap.
- Illiquidity will benefit holders if and when the market notices the growth story here and rerates accordingly.
The annuity-like contribution from the franchise business leaves me confident that the business will survive any economic downturn. With only surplus funds invested, I feel able to ride out any adverse consequences of illiquidity, in the strong belief that the underlying value of the shares will persist even if the price, for a period, does not.
(The same comment is made on the Water Intelligence (LON:WATR) thread, so apologies for spoofing both boards)
Paul
Re Water Intelligence (LON:WATR), I know that you have commented in the past about the dangers of owning highly illiquid shares. Things are great on the way up, but as you say can be almost impossible to dispose of on the way down. Your own personal experience, and honesty, about the problems this caused you in the financial crash is a lesson for us all, and I think we are all grateful for you sharing these experiences.
Water Intelligence (LON:WATR) is a share that I've held for approximately 2 years, so I am really interested in the following paragraph:
Another key point is that I'm trying to avoid opening new positions in very small, illiquid shares. If there's another (maybe worse?) market sell-off, then I generally want to at least have the option of being able to sell, which is often not the case with things this small. So buyers of tiny company shares like this need to remind yourselves that selling could be impossible in another market downturn. That's not a problem if you're only buying a small scrap of shares, or are happy to ride out market sell-offs, but for larger positions, we can be left high & dry in a market sell-off.
Could I ask please, is there a rule of thumb as to what constitutes a "larger position"? Is it:
With regard to Water Intelligence (LON:WATR), I am aware of the risks, but the company seems to be executing its strategy quite well, and I believe the issue of water conservation is only likely to grow. As such, I believe it t be a long term hold. Years ago (perhaps it was the long hot summer of '76) I have a vague memory of a prediction that in the future countries could wage war over water rather than oil. Let's hope not, but the problem of population growth in Cape Town and California has thrown the issue of the importance of water into sharp focus.
Regards
Paul
Hi Paul ,just to point out the front page of city am that pension fund deficits,when revalued have benn drastically reduced give the 10 yr gilt yield etc,David
Hi Paul, I happened to have to go to my local HSS this morning to hire a heavy duty drill. It has never been impressive but today I was the only customer, just a few bits of very tired looking kit on display. I know it is a sample of one but this unit is in St John's Wood on a busy junction and could be something of a showpiece. It has not changed in 15 years. Staff seemed ok but it felt like a business from 15 years ago. With the debt they are carrying and an out of date model it looks like a zombie company to me.
Excellent report on HSS, good insight to those with limited knowledge on the structure of bonds within a stock.
Fully agree. I really appreciate it Paul when you go through why balance sheets matter and can make a company simply uninvestable. HSS Hire (LON:HSS) seems a perfect example and showing how this will almost certainly cause an equity dilution shows me something extra to look out for. As you say why go anywhere near it beforehand?
A good example of how these reports make me a better investor. Keep up the good work!
Hi Paul,
Could you have a look at Bilby (LON:BILB) please, I know its not currently your favourite sector but it looks a great little company and a very stable looking Board.
thanks.
Hi Dean,
Could you have a look at Bilby (LON:BILB) please, I know its not currently your favourite sector but it looks a great little company and a very stable looking Board.
There doesn't seem to be any news out today from Bilby, so there's nothing for me to cover.
These reports are driven by each day's trading updates & results statements, not by random requests from readers!!!
Regards, Paul.
ok thanks Paul, I get it now !
Hi Paul,
As you've got it in the header, I'd appreciate your view on Hargreaves Services (LON:HSP) . The operating performance (revenue and profit) is usually a tad underwhelming, but this is primarily about the net asset value of the energy and profit portfolio, and the ability of management to realise it.
It rests a lot on (i) the ability of (and faith shareholders have in) the management, and (ii) patience. For my part, I think management have done admirably so far in taking what was a fast declining industrial business focused around coal, and turned it into property and energy project development company, partly funded by strict cash management of the 'old' business. They seem realistic and patient.
In today's interim results, NAV has reportedly gone up to 423p per share, which compares favourably with the share price of c.350p, and it also pays a dividend. It won't happen quickly, but I think there's some old fashioned value in them thar hills.
Thanks
Chris
Paul, writers block, proves you are human after all. Do you find glaring at the stock market some days, you should find something to trade, everyone else is, but you can’t ruddy find anything, and it’s depressing?
Morning Paul, would be interested in hearing your thoughts on the cash call announced by Galliford Try (LON:GFRD) this morning.
Morning veganvader,
Sorry, Galliford Try (LON:GFRD) is over £800m market cap, so outside the scope of a small caps report.
Regards, Paul.
Paul,
Galliford Try (LON:GFRD) was over £800M at yesterday's close, but it's well under that market cap now when you factor in today's 19% drop (at time of writing).
Although reading through the Galliford Try (LON:GFRD) releases this morning, here is another example of a company doing the apparently irrational by launching a fully underwritten £150m equity fundraising while confirming it will pay out approximately £24m in dividends in April. What do you reckon - at say a 2% u/w fee on £24m, that's about £500,000 of shareholder value given away. Go figure ...
Gus.
Fundraising to pay dividends is crazy, as at Galliford Try (LON:GFRD). But it suits the city in many ways - those who earn commissions from the raise, the income based funds that want steady income (and some of whom will sell if the div is cancelled), any board members and families with large holdings who may be more interested in cash now and who don't worry about the fund raise costs.
It won't stop unless someone can work out a way to stop or restrict it, or there's a big change in city culture to take a wider view on total return.
I'm doubtful we'll see either!
Peter
It's all about perception........market has been marking Galliford Try (LON:GFRD) down for a while based on Carillon type exposure worries so....
1) Shore up the balance sheet and put those concerns to bed.
2) A cancel of the dividend would however,be perceived even more poorly so rebase it at 2* cover as that will put a bit of a floor under the share price.
3) post summer 2018 when project is finished and cash comes back recycle into house building business at 15-20% margin.
May not be the most efficient use of cash but given market irrationality around yield I can see why they've done it - largely to avoid an even bigger fall in share price that would prove more dilutive on a capital raise.
Last time Water Intelligence (LON:WATR) was discussed I found myself put off by the overly effusive language around revenue growth, with little comment about profits. Shares are up c. 50% since then I think, ho hum.
Anyway today's report is more helpful I think and certainly leaves this still looking interesting imho. With adjusted pbt up 21% (from +8% in the previous year). I can't help still being irritated by the slightly by the language in several places, but that's probably just me being curmudgeonly! "Note that profits before taxes unadjusted actually grew faster at approximately 50% year-over-year." - So what - surely the point of adjusted earnings it to show the real underlying growth?
With that in mind I can't resist a little "compare and contrast" even though the other two co.s are outside of the remit of this column.
Coca Cola HBC AG (LON:CCH) - RNS titled "EXCEPTIONAL SET OF RESULTS" - really? Can't you just let us decide how good they are? Volume growth of 2.2% and revenue growth of 4.9% hardly seem to fit the bill of "exceptional". "comparable ebit" growth of 20% is more like it -AFAIK this has been delivered in emerging markets with modest revenue growth and significant margin expansion. - Could be interesting (but with an £8Bn market cap - well outside the remit of this board).
Northamber (LON:NAR) Interim report meanwhile is almost hilarious with its forthright candour.
"It is refreshing to be able to open a report to shareholders with an overdue sense of delivered achievement."
"Not only is it pleasing to report an improvement, but gratifying when the constituent elements of that improvement vindicate our policy of constantly moving towards more specialised, technical and higher margin products. "
(turnover up 9% , GP up 8% and operating losses more than halved.)
Outlook :
"Whilst now moving faster in a better, and we hope a right, direction, the current position is far from satisfactory. Each step forward appears to be thwarted by adverse happenings undermining the confidence of our customers' ultimate users, which hampers achieving the goals and targets we set for ourselves.
Nevertheless we will continue to strive and take advantage of every opportunity to take the company forward, with a return to profitability when we can make use of the accumulated pre-tax losses, for the benefit of all shareholders.
Realistically, we cannot be over-optimistic on short term results but more hopeful than not that those improvements we have shown might continue as we move through 2018 and beyond."
So, I think I'd take that as a profit warning then - nevertheless I really warm to the language used.
At a market cap of only £7m - clearly again outside of the remit here and an SR of only 21 probably not of interest anyway, but I do like the honest views on performance and prospects.
Water Intelligence (LON:WATR) Thanks for this Gromley. I thought it was just me that was being irritated by the language. It seemed to take a long time to cover the ground. It maybe we are both just curmudgeons however !
Long £WATR
Re: Water Intelligence. Response to Housemartin2
No, it is certainly not just you who is irritated by the language of the company's announcements. On 9th August I made the following post on another board about Water Intelligence:
"Is it just me or does anyone else think these results are badly written? For example the Chairman's statement starts "Our Interim Results support our priority of accelerating corporate development to gain visibility in the market as a multinational growth company that provides end-to-end solutions for the worldwide problem of water loss through leakage." That sentence is much too long and very awkwardly phrased. Water Intelligence, please get someone who can write press releases in a concise and easy to understand way. Wading through all the unecessary guff, it actually looks as though the company is doing OK which I guess is the main thing! "
Disregarding the poorly written communications, one reason I invested in this company some time ago was that the company's size was very small compared to the size of the markets it was addressing and it looks as though it is continuing to make progress in these markets. It also has some intellectual property which may help to provide competitive advantage.
Morning Paul,
Keystone Law (LON:KEYS) seems quite interesting but can find no broker notes, nada!
Calls itself "The fast growing, UK Top 100, challenger law firm".
Any view most welcome, I think it's a case of wait til April (actual results).
Thanks in advance and good luck with the Car Retailers Special!
Hi Matylda - Keystone Law (LON:KEYS) certainly did issue a positive trading update and I had another look at the IPO document to get an understanding of the business and the risks.It talks about being a challenger law firm and "disrupting the traditional law firms".
My understanding of the business is that it uses the services of 250 lawyers to perform legal work across many different industry sectors (but specifically excluding personal injury and property conveyancing). These lawyers are effectively self-employed and they will bill KEYS through their personal service companies. The rates typically are between 60 - 75% of the total fee. KEYS will pay the lawyers once it receives the money from the client. Therefore, from a working capital cash perspective, it does not require to fund payment upfront. There are certain advantages that the IPO goes into; work life balance, earn more fees than being employed by a firm, cross-referring work, and flexibility.
However, there is a significant risk here: it's based on a tax advantage. If the lawyer bills through a limited company and then declares dividends, there is less tax being paid. In addition, for KEYS it does not need to maintain a payroll and pay over PAYE & NIC to HMRC or have holiday and sick pay entitlement. If the lawyer predominantly works 30+ hours a week doing work for KEYS then is being self-employed justified? Could GPs employ the same model, as they traditionally operate a partnership agreement? Sorry, but I do find the whole set up being labelled as disruptive slightly disingenuous.
Also, it's not clear who brings the work in or the client. Is it the lawyer or is the work provided by KEYS? If it is the lawyer, then why does the lawyer require to go through KEYS and also is giving away > 30% of revenue justified for central support?
Finally, a lot of KEYS growth is predicated on increasing lawyer numbers.
I think you are essentially backing the management team here who certainly have relevant experience in the field.
I've opened a starter position in Keystone Law (LON:KEYS). I think the attraction for the solicitors is the increased freedom of operating in a "dispersed law firm". The model has similarities to franchising which can be a very attractive type of business to own.
I'm not sure it's all about the PAYE and NIC elements. The notional tax credit on dividends has already been abolished so the savings are not what they were anyway. Anyone going this route now would be prudent in my view to budget that they will pay themselves via normal PAYE as that's the way things are headed with IR35.
But I don't think that will stop Keystone's ability to recruit. I think it's more about the attraction of the operating model and a lifestyle decision.
The costs of overheads like professional indemnity insurance and online access to legal databases are high so some central administration and purchasing makes sense. And most employed solicitors don't earn anything like 60% of their billings.
Well gajri - Thank you for that detail on Keystone Law (LON:KEYS).
That's a dubious model it seems, I will be waiting on those actual results.
Thanks again to you and others for comment.
Water Intelligence (LON:WATR) seconded please, seems intriguing, as does Iofina (LON:IOF), 'specialists in the exploration and production of iodine and halogen-based specialty chemical derivatives... pleased to announce the completion of construction and commencement of production at its IO#7 IOsorb® plant.' I don't hold as I'm opposed to fracking but wish I had spread bet its recovery!
I'd be interested in your views on Plus500 (LON:PLUS) who just released their preliminary results, thanks
Hi lemonjar,
I'd be interested in your views on Plus500 (LON:PLUS) who just released their preliminary results, thanks
As it's a £1.3bn company, Plus500 is outside the scope of my coverage of small caps (I usually go up to about £400m mkt cap, sometimes a bit above).
At a quick glance though, the results today look spectacularly good. The valuation looks cheap.
The big issue of course, is whether these profits are sustainable, or whether the regulators will catch up with them & clamp down? Personally I'm steering clear of this one, but as you can see from the share price, people who ignored the regulatory risk have absolutely cleaned up!
Regards, Paul.
Ah yeah indeed, forgot to think that. Thanks in any case, & agree with your comments. They acknowledge the regulatory environment a couple of times in their update, generally saying the right things. Partly my take is they've obviously developed a very capable trading technology that's able to scale up, to do that I think you need to have very solid software engineering. With the money this is now generating it gives them options, e.g. diversification, OEM deals, acquisitions. All entirely speculative on my part, I just think good dev + lotsa money = possibilities (including avoid being curtailed by regulation.)
I bought a stake a month ago when it peaked so happy to see it now go above that on today's update.
To give some context on Plus500 (LON:PLUS)
I sold a couple of months ago around the 1200p mark following a similarly upbeat trading statement. I have done very well out of the share having first bought at circa 400p so I am inclined to think nicely of the company. However, my rationale for selling at the time was 3 fold - and I think this holds after this set of results too....
(1) this share has never traded on rich valuation multiples due to both domicile & reg risk - think debacle around KYC and account opening a couple of years back
(2) Although I love the free cashflow I worry slightly about ACPU (acquisition cost per user) which has fallen dramatically (circa 2/3's) - basically marketing. I wonder if this will have a forward knock on impact to future earnings growth
(3) Any negative rulings/restrictions on the industry following ESMAs consultation will likely have a sharp initial impact on the share price despite what the company says about the possible impact. Especially so given that investors are likely to interpolate that ruling across to most other jurisdictions.
The share has exhibited lots of volatility in the past and as a consequence I am currently sitting on the sidelines awaiting ESMA as I suspect the run up to that will give a cheaper re-entry point.
(I note stock has not been able to hold onto early gains of 100p+ either and is now flat/slightly down)
My morning smallcap tweet:
Origin Enterprises (LON:OGN), Keystone Law (LON:KEYS)
Origin Enterprises (OGN) CFO resigns. Sounds amicable.
Keystone Law (KEYS) Guides FY profits comfortably ahead of current market expectation.
Water Intelligence (LON:WATR) please, Paul, who have issued quite a detailed year-end trading update this morning.