Small Cap Value Report (Wed 15 Jan 2020) - RBG, QUIZ, MBH, RDT, INCE, TEG

Good morning, it's Paul here.
Just to clarify, for any new subscribers who may not be aware, this is was a placeholder article, which is posted early every weekday, so that readers can add your comments from 7am on RNSs. Then I update the article section by section throughout the morning. Official finish time is 1pm, when the SCVR email goes out, by which time the bulk of the report is usually done. If I have spare time, I then add more sections on some days in the afternoons, which is bonus content that I'm doing in my own time.
Many thanks for the smashing positive feedback yesterday, I really appreciate it!
Today's report will focus initially on Revolution Bars (LON:RBG) because this is one of my big 4 personal holdings. Once I've got my head around that, then I'll look at other companies reporting on trading.
Estimated time of completion today is 2 pm
Update at 14:05 - today's report is now finished.
Revolution Bars (LON:RBG)
Share price: 88.8p (up c. 7% today, at 09:25)
No. shares: 50.0m
Market cap: £44.4m
(at the time of writing, I hold a long position in this share)
Revolution Bars Group plc ("the Group"), the leading operator of premium bars trading across the UK under the Revolution and Revolucion de Cuba brands, is today providing a trading update for the 26 weeks ended 28 December 2019 ("H1 FY20") and also for the important Christmas trading period through to and including New Year's Eve.
Background - this is a turnaround situation under new-ish (18 months), operationally focused management. The share price lost two thirds of its value, after the aborted 203p cash takeover bid from Stonegate, as investors clearly didn't believe the turnaround was likely to work.
What went wrong?
- Old management too focused on expansion roll-out of new sites, took their eyes off the ball on existing sites
- Brain drain of key site managers & area managers - led to demotivated staff, high staff turnover, and hence deteriorating performance
- Distraction of protracted bid process from Stonegate at 203p per share, and interference from nightclubs operator Deltic
- Older sites became tatty, as refurbishment cycle delayed
- Competition intensified
- Cost headwinds
Action taken
- Expansion halted
- Dividends stopped for the time being to focus on debt reduction
- Numerous "work streams" initiated to improve operational performance
- Refurbishment programme started, to bring old sites back up to scratch
Quoted share prices - the market is currently showing the prices of RBG shares as - Bid: 85.2p, Offer: 91.0p, an apparently wide spread. However, the published prices on small caps are not the real prices. The whole system is appalling actually, and something needs to be done about this.
The real prices are currently;
Bid: 87.29p (size: 35k shares, with a 40k bid just behind at 87.18p)
Offer: 90.3p (size: 6k shares. next offer price is 5k shares at 90.42p)
As you can see, the share is well bid, and the spread is not 5.8p, it's actually 3.01p
How long can the LSE allow this rigged system to continue, where the genuine prices (on RSPs) are hidden from view? It wastes so much time having to find out the real prices by enquiring with a broker, or putting a dummy trade into an online dealing platform. We need proper price transparency, with the quoted prices being the real prices on RSPs. Everyone should have free access to all the pricing information, in real time. That would level the playing field between professionals and everyone else.
Generally speaking, when a share is well bid, and thinly offered (as in this case), then it's usually going higher. Although remember that there can also be hidden orders working in the background - e.g. a market maker might be bidding for stock because he's working a big buy order for a broker. If for example, I wanted to buy 100k shares in RBG, I would ring my broker, and say something like "buy 100k RBG, at 88p or better, good for the day". He would then ring a market maker, and give them the order. The market maker then accumulates stock on the bid at (say) 87.5p, and at the end of the day passes that stock over to my broker, who rings me up and says typically, "You've been part-filled, you buy 35k shares at 88p. Shall I continue the order tomorrow?"
Orders that are working in the background like that don't get printed until the end of the day, or in some cases may not be printed for some time later, until the order has completed. There are rules on when trades have to be reported.
This is why sometimes a share price will rise or fall apparently out of kilter with the printed trades - that's because there's a large buyer or seller in the background.
Today's update - this is a good (but not blow-out) announcement . I'm pleased with it, because I think it confirms that the turnaround is working, and should gather further momentum in 2020, driven by refurbs of under-performing sites.
Xmas/NYE trading - peak trading, which RBG generally does well in (7th consecutive year of LFL increases). Sure enough, we have an excellent performance, with LFL sales up +4.0%
H1 trading - covering the 26 weeks to 28 Dec 2019.
Positive LFLs, with an improving trend, but not as good as Xmas;
H1 LY (Jul-Dec 2018): LFL -4.0%
H2 LY (Jan-Jun 2019): LFL -2.9%
H1 TY (Jul-Dec 2019): LFL +1.2%
Within the +1.2% for H1 TY there is an improving trend, as follows;
Q1 TY (Jul-Sep 2019): LFL +0.7%
Q2 TY (Oct-Dec 2019): not disclosed
Q1+Q2 TY (Jul-Dec 2019): LFL +1.2%
Looking at it simplistically, by assuming that Q1 and Q2 sales are roughly the same, then this implies Q2 LFL growth of +1.7%
Future LFL sales should continue improving, because of;
- Operational improvements across many workstreams
- Refurbs (the main driver of the turnaround) - 15 planned for this year
- Soft comparatives
- 3 under-performing sites closed in H1
As you can see, hopes for further improved performance are not just on a wing & a prayer, there are specific actions driving improved performance.
Profitability - measured at the adjusted EBITDA level, which I'm fine with, as it's a good proxy for cash generation. This is absolutely key, and again is reassuring;
The Board expects the Group's Interim results to be published on 26 February 2020 with underlying earnings, as measured by adjusted EBITDA** on a pre-IFRS16 basis, to have improved in line with market expectations.
** Adjusted EBITDA excludes exceptional items, bar opening costs and share-based payments.
It's a pity the company didn't add another footnote specifying what the market expectations are. However, the house broker has issued a one-pager today, available on Research Tree, which is well worth taking a look at.
Forecast is for £12.3m adj EBITDA in FY 06/2020, which is a lot of cashflow for a company with a market cap of just £44m. This is really important, as it confirms to me that the company is generating plenty of cashflow to both self-fund its site refurbs (about £200k apiece), and pay down debt. My understanding is that there's no corp tax to pay this year either. Mgt previously indicated that net debt should reduce by c.£5-6m this year, although I think the property deal (see below) might roughly halve that reduction.
Adj EPS is forecast to rise from 3.4p LY to 6.6p TY - a PER of 13.5
Property deal - this is very interesting;
The Board is also pleased to announce that since the end of the interim reporting period, it has exchanged contracts with real estate investment company Aprirose, landlord of nine of the Group's properties, to surrender five leases of loss-making sites and re-gear a further four leases with a small net rent reduction but with a 25 year term.
The transaction is expected to complete in March on payment by the Group of a premium equivalent to less than three times the annual trading losses of the five lease surrenders.
The net effect of these transactions is to improve the Group's on-going full year operational cash flows by c£1.2m per annum.
The background to this, is that in 2007 RBG did a sale & leaseback of either 9 or 11 freehold sites (my notes are confused on this), in a transaction with a landlord called Aprirose. It looks to have been a bum deal, as some of the 25 year leases (so 12 years left to run) turned out to be millstones, with heavy trading losses due to uneconomically high rents. As I've said before, re IFRS 16, leases are only a liability in the real world if trading from that site is loss-making.
The problem with this, is that landlords really don't care if the tenant is trading at a loss, providing the tenant is solvent & can keep paying the (inflated) rent. RBG even closed 2 of these sites, since it was cheaper to pay the rent on an empty site, than trade at an even bigger loss.
I discussed this issue with management a while ago, in some detail, and the upshot is that it was a roughly £1m p.a. drain on cashflow. RBG had made provisions on the balance sheet for this issue.
Today's news is really positive - the issue has been fixed. The landlord would require a substantial payment from RBG to allow it to surrender uneconomic leases. This seems to have been agreed at a payment due of about £3.5m, combined with agreeing new 25 year leases on the 4 other sites. This will enable the landlord to revalue its own freeholds upwards, on the 4 sites that RBG is keeping. RBG must be trading profitably from those 4 sites, or they wouldn't have signed new 25 year leases on them. There is some risk here though, if those 4 sites subsequently become loss-making, so ideally I'd like a bit more colour on this.
The upshot is that, after paying the c.£3.5m premium to surrender the 5 loss-making sites' leases, then RBG's cashflow will improve by £1.2m p.a. - NB this is not in the existing forecasts, so it's great news.
Debt - I like this bit;
Whilst external cost pressures persist, we will continue to manage cautiously, using excess cash to reduce indebtedness below one times EBTIDA before we will consider further expansion opportunities"
That's very prudent. Bars are highly operationally geared, so frequently get into (sometimes terminal) trouble in recessions, when sales can drop sharply. Therefore it's much safer to have a low level of debt, or net cash.
My opinion - so far so good! For me this share was a success (cash bid at 203p) that went badly wrong, because like a fool I didn't sell at the time. I met new management several times, and decided to back their logical & thorough turnaround plan.
I think the share way overshot on the downside, and with the turnaround clearly now starting to work, then there should be decent upside here, as more old, tatty sites are refurbished.
Will it get back to 203p? Probably not, but by my calculations & estimates, I see recovery to c.120-150p being possible. The likelihood of recession in the UK seems to have dramatically receded in recent weeks, which is great news for bar operators. Plus the c.6% rise in minimum wage in April will be both a cost headwind for RBG, but will also put a lot more money in the pockets of its customers. It's likely to thin out the competition too. Therefore, I think we could see LFL sales accelerate to maybe 2-5% in 2020, which would be great if it happens. Fingers crossed!
I don't want to hold this share forever, but my reason for continuing to hold is that I think it's the wrong price - too cheap. There could be another takeover bid at any time also. So a nice each-way bet.
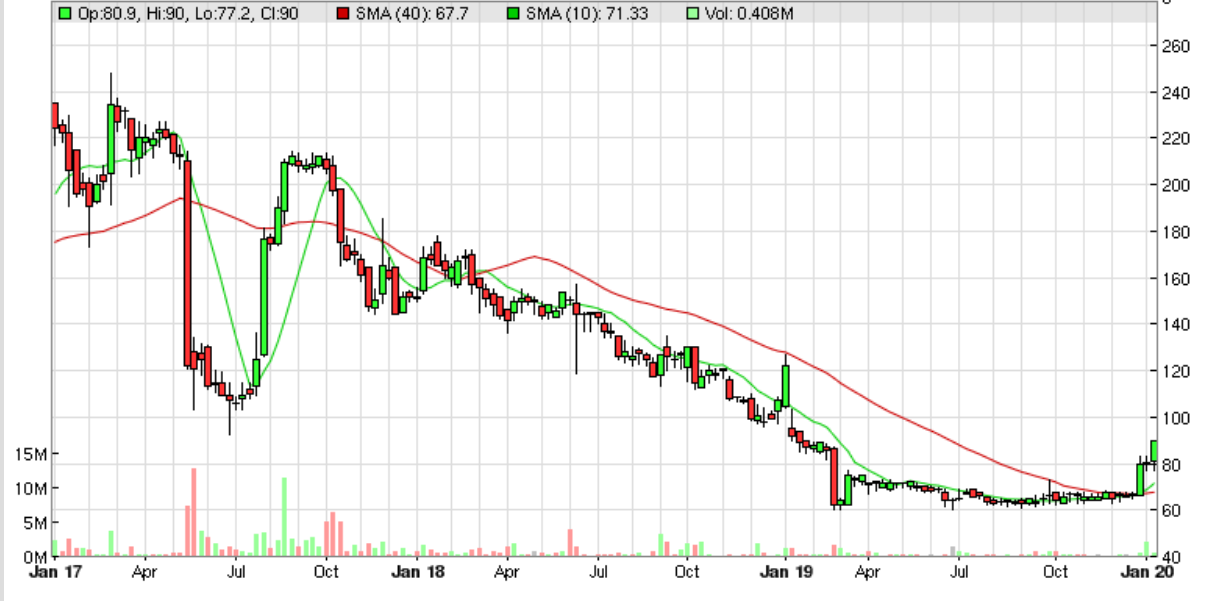
Here's the 3-year chart, showing the profit warning in 2017, then the takeover bid (which fell through). It's been agony holding all the way down, but I never imagined it would go down to anything like this low. Anyway, things are starting to look up now.
EDIT at 11:48 - something else that just occurred to me, this is why RBG would make an attractive target for a takeover bid;
- An acquirer could increase profits by removing duplicated costs, e.g. bolting it onto their existing systems (accounts, admin, area managers, etc)
- Opportunity to add a few million to profits through bulk buying power of a much larger drinks/pubs group. It's sometimes said that RBG is sub-scale
- Legacy property problems fixed, which might have put off acquirers
- Revolution bars are mainly late night bars, and make their profits on Fri & Sat nights. Hence would make a nice bolt-on acquisition for a more traditional pub operator, because it's targeting a different section of the market
This is probably why Stonegate were prepared to pay about 7x EBITDA a couple of years ago. With EBITDA currently £12.3m, 7 times is £86.1m, or 172p per share ballpark takeover price? i.e. a bidder would value RBG differently to private investors, hence it's worth more to them than it is to us. End of edit.
Edit at 19:47 - Additional points which have occurred to me since posting the above;
Expansion - once the basics of the business have been sorted out, and debt reduced, then the roll-out of new sites could resume. This presents an opportunity, in that in future this share could re-rate back to being a growth company.
Property deal - some of us baulked at RBG signing new 25 leases (announced today) on 4 of the sites that it is retaining with landlord called Aprirose. It's just dawned on me that RBG already occupies these sites (hence knows them inside out, and what level of rent is affordable), and RBG is already committed to occupying these sites for another 12 years from now, on the existing 25 year leases signed in 2007. Therefore it is actually only committing to another 13 years on these sites, over and above what it was already committed to. And the rents have come down, albeit described as only by a small amount.
End of edit.
QUIZ (LON:QUIZ)
Share price: 16.3p (down c.12% today, at 12:06)
No. shares: 124.2m
Market cap: £20.2m
QUIZ, the omni-channel fashion brand, announces a trading update for the seven-week period from 24 November 2019 17 November 2019 to 4 January 2020 ("the Period").
[dates corrected in a replacement RNS at 17:11]
- Revenues down 9.3% - looks like some sales were pulled from Xmas towards Black Friday (effectively a mid-season sale)
- The only bright spot is own website sales, up 5.9% and a higher proportion at full price, so presumably higher gross margin
- Unprofitable sales through third party websites have been terminated - makes sense, but will depress the sales figures
- Total online sales declined by 14.8%
- Standalone stores (i.e. not concessions in Debenhams & other dept stores) down 7.0%
- Gross margins OK - broadly in line
- Inventories carefully managed, and down on last year
- Net cash of £10.7m at seasonal peak of 4 Jan 2020 - expect this to fall though
- Cost-cutting has "largely offset" impact of lower sales
Overall - broadly in line with Board's expectations.
It's tempting to have a little punt on this, for a recovery, but I can't get away from the perception that this is a pretty rubbish brand, and not aspirational at all.
At £20m market cap, and £10m cash in the bank, it could have some value. The leases are short, so shouldn't pull down the whole company. Danger is that at any sign of a recovery, mgt could take it private, snatching away the upside.
On balance, I'll probably steer clear. It could go either way, I don't know what's the more likely outcome.
Briefer sections now, as time is running short (due to me spending 5 hours on RBG)
Michelmersh Brick Holdings (LON:MBH) - trading update for FY 12/2019 reassures - in line with expectations for profits, and strong cash generation means net debt is better than expected.
The shares have had a great run, like so many other things, so maybe people will want to start banking profits at some point? That's my worry about so many shares right now. I wouldn't want to chase up a price, if it's already risen substantially, and trading is only in line.
Forecast for 2020 shows negligible earnings growth, so there might be an opportunity there for the company to beat expectations?
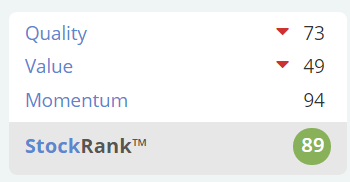
Very good StockRank, so might be worth a closer look? The outlook for UK housebuilders seems a lot brighter, and it makes sense that should read across to brick makers.
Rosslyn Data Technologies (LON:RDT) - I had a quick look at this last night, after a bullish note came through from Equity Development, trumpeting contract wins. However, on looking at the figures, it's clearly going to need refinancing due to a ropey balance sheet. Cashflow looks poor too.
Potentially interesting products, but I'd want to see it on a much firmer footing financially before considering a punt on this.
INCE (LON:INCE)
Share price: 48p (down 46% today, at 12:38)
No. shares: 37.0m
Market cap: £17.8m
The Ince Group plc (AIM: INCE), the international legal and professional services company...
Several readers have asked me to look at this, as the share price has almost halved today. The reason is that it's announced a bombshell fundraising at 45p, which is a huge discount of 50% to last night's close. Although the share price started to plunge on 6 Jan 2020, when it was 115p, falling to 89p in the week before this placing announcement. Funny that. There had been no news from the company since 28 Nov 2019, so this looks like there might possibly have been some illegal insider dealing going on just before the placing, by someone who knew that a deeply discounted placing was imminent.
Management stretched the balance sheet too far, and it looks as if they've been forced into doing a fundraising by the bank. This is complete incompetence, and I see the CFO is leaving. Isn't it weird how so many professional services companies can't manage their own finances?
All this was easily predictable, because it was obvious that the balance sheet was shot to bits. I pointed that out here in the SCVR from 25 July 2019, after the group posted apparently strong results and modest net debt, but there was a massive problem, as I commented in July 2019;
Is there a catch, yes of course! If it looks too good to be true...
The main catch is that there's a ton of deferred consideration, around £29m, plus more since the year end, which is payable in c.3 years.
Balance sheet - is terrible. -£21.7m NTAV even after recent fundraising.
[excerpt from SCVR 25 July 2019]
It seems a bit conceited, quoting my own report, but it's relevant in demonstrating that emergency, discounted fundraisings can be easily avoided by never investing in companies with diabolical balance sheets.
Edit at 20:00 - Several readers have contacted me today to say thanks for steering them away from buying what would have been a disastrous investment. I'm delighted to have helped protect you from a heavy loss. End of edit.
Ten Entertainment (LON:TEG) - full year trading update. Several readers have commented on this, so I'll have a quick look. I wrote a positive piece about it here on 2 Oct 2019, thinking it looked good value at 239p. Like so many other shares, it's soared in recent months, so have we missed the boat at 314p now?
Today's update reads really well, but the bottom line is that it's only in line with expectations, so shouldn't move the share price particularly.
The valuation still looks reasonable, forward PER of 13.4, and a decent yield of 4.38%.
High StockRank of 90.
I think this could have further to run, if markets remain in exuberant mood. I think it's a good idea to buy leisure, rather than retail, because there's evidence we may have reached "peak stuff", and that people want to spend more on experiences rather than more physical possessions.
Time's up for today, see you tomorrow!
Regards, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

80 comments
I was reflecting on the significance of Ten Entertainment (LON:TEG) announcement that it now has 70% of its estate using the more cost effective Pins and Strings. Not understanding what Pins and Strings technology is, I Googled a manufacturer of such equipment who claim it is simpler/cheaper and gives the customers reasons to play more games and to return . Does seem like a "Game Changer" which is and will both reduce cost and boost sales.
Pins and Strings
Easier for Your Customers - Because they have a better experience in your center and are more likely to return.
CenterPunch deck lighting illuminates the pins, enabling dazzling light shows that will excite and engage your bowlers.
Quietest Operation - Your customers don’t hear the machines running, making for a more pleasant environment in your center.
Keeps Customers Informed - If a problem occurs during play, customers are updated on the scoring monitor and notified when it’s okay to bowl again making for a better experience.
Reliability - Your customers are not kept waiting for the pinspotter to set pins or for their balls to be returned.
https://www.bowltech.eu/en-en/products/pinspotters
An additional Ten Entertainment (LON:TEG) efficiency snippet from the Telegraph Questor today....
....As an example of its efficiency drive it has developed a proprietary lane booking system that helps maximise lane utilisation and minimise waiting at peak times, and has recently introduced “iServe”, which allows customers to order food and drink to be delivered directly to their lane.
Seems Ten's innovation continues and is another "Game changer" - I hold. Ian
”Quoted share prices - the market is currently showing the prices of RBG shares as - Bid: 85.2p, Offer: 91.0p, an apparently wide spread. However, the published prices on small caps are not the real prices. The whole system is appalling actually, and something needs to be done about this.”
Thank you for this explanation (though I still dont quite understand it all!) and it demonstrates how much more I still have to learn
Also for your insights into £RGB even if it is not one for me.
My broker is showing currently showing 87.4/90.8, the spread tend to be wider in thinner trading such as early morning before 9am, some traders don’t trade at this time. I suspect those quoted prices were early in The day. Some shares have very wide spreads but other similar size companies have narrower spreads not sure why, is it to do with liquidity?
Also the size of the trade can affect the price, I see trades of 1 share are often outside the spread quoted, not sure why anyone does 1 shares deals. Large orders also can go through at odd prices. This is why Stockopedia prices which are the last trade are a poor way to show share prices in my opinion.
This is my day job so I will try to explain a little about market microstructure in small caps - bear with me!
The RFQ (request-for-quote) system used predominantly in small/micro caps is designed to create liquidity without unduly impacting those compelled to provide it (i.e. the market makers). The orderbook (SETS) system used in the majority of large and mid cap names is structured differently, where instead participants place limit orders with prices and sizes they are willing to deal at, and when a match occurs (i.e. a buy limit order and sell limit order are at the same price), a trade takes place. Spanning the two, there are hybrid RFQ/orderbook stocks where market makers' quotes for NMS appear on the orderbook alongside regular limit orders.
The RFQ system is ideal for small names and I'll try to explain why. The point of having market makers obliged to quote is to provide liquidity where it may not be readily there, i.e. there is not a ready stream of simultaneous buyers and sellers, which is certainly the case in your typical small or micro cap. Remember the market makers (or in this case, more specifically the RSPs, or Retail Service Providers) are in competition with each other for your business, and the price you receive when you send an RFQ is from the best priced market maker in your size at that time. If you were to force market makers to publicly display their RFQ grid (i.e. all the prices/sizes they would be willing to deal at) as Paul suggests, this would make them less competitive, and perversely would actually reduce liquidity.
For example, as an RSP, imagine if as part of my normal course of market making, I'm long 100,000 shares in a stock which has NMS of 2,500 shares. So I'm long, and in size. In this case I want to get back flat, and so I would be a keener seller of stock, and in larger size, than I would be a buyer, where I may not want to price so aggressively. If I had to display my quotes publicly, what do you think would happen? The market (i.e. those watching the orderbook, be it other market makers, or hedge funds, or whoever) would see I was a seller in size and would sell ahead of me, driving the price down. Like showing your hand in poker, I'm at an immediate disadvantage. By showing my hand, my long position is now losing money, but I still have to get rid of it in order to balance my book and continue to make a market. So in order to prevent this from happening, I would take the only sensible option, which is to not quote my full size, instead dribbling out my position piecemeal. As a retail customer this would impact you, since if you were to want to buy say 50,000 shares, or 100,000 shares, you wouldn't be able to do so in one clip, and would have to therefore trade multiple times in much smaller size, and possibly at a wider spread. This is *exactly* how the SETS system works in big caps, but for small retail there it's not a problem as this piecemeal market is more than sufficient for the large majority of retail flow.
(In fact RFQ in very large size is indeed a thing, and is one of the avenues that institutions have to trade with investment banks who market make in significant size - in the tens of millions of £ - in your typical large cap name, with tiered pricing outside the usual bid-offer spread. One of the other alternatives is using an algorithm which splits your order up into time buckets and places small limit orders over the course of a time period to minimise your impact on the market and achieve a better overall execution price.)
As a retail investor, you can always ping the best-priced RSP to figure out what price they are willing to bid you for/offer you stock at in your size, so retail are not as a disadvantage. The bid/offer prices you see quoted on financial websites are the prices and sizes the market makers are obliged to quote in, and are ultimately there to give you an indicative range in which you will be able to trade. Asking for an RFQ to see if they are willing to improve on that is actually a good thing, tightens up spreads and provides significantly more liquidity to small cap investors where years ago there was none.
That's a great contribution Gav, even though I knew some of it already to get a grounded view is really useful.
Even though I know that improved execution prices could be of great benefit, it is not something I have really focussed on - maybe I should.
With this in mind, can I pick up on :
Are you able to provide an "idiots guide" as how how one might go about this? (eg 1 find the best priced RSP & 2 "Ping" them".)
That might be a really basic question, but as I've not really focussed on execution costs not to me. (As they used to say on 'millionaire' - "It's only obvious if you know it")
Hi Gromley,
Thanks for your nice comment. Short of asking your broker, it's really just a case of requesting electronic quotes in different sizes, and seeing what comes back (and don't click the "execute" button when you're given the 15 second timer!) Price level changes will almost always be at round levels. So if you want to trade 50,000 shares, I would try 10,000 first and see what price you get back. Then try 50,000 and see if it's any worse. If the price is higher, try 25,000, and depending on what quote you get back, you may wish to try 20,000, or 30,000 or maybe 32,500 (often price levels change at increments of 2,500). You ideally want to get as much as you can at the price level before moving up to the next price band. If you find the price steadily increasing as you increase your size, it's most likely because there is a limit order on the book (which may even be on NEX, not on LSE) which the RSP will be leaning on, knowing they can cover the balance. Bear in mind that trading a small amount at a lower price, hoping to come back for a second bite at the same price, doesn't always work, as the RSP will have the chance to adjust their pricing between your quotes such that the second time you go back, the quote may be higher, and you may well have been best off doing your full size at the slightly higher price the first time round!
Bear in mind that if you are being offered a large amount of stock without the quoted price being higher than it was for a small amount of stock, this is a sign that the RSP offering this best price is already long of stock which they are looking to get rid of. If they get any longer (i.e. someone else sells to them) then they are likely to reduce their price next to see if they can entice anyone to take their shares off them (i.e. their quote goes down, which will most likely affect the best bid-offer). Basically, if you are being offered a significantly larger amount of stock than is normally available, the next price move is probably downwards. Conversely, if they are only offering a small amount of stock (and you may see the market tighten up such that occasionally you may only be able to get a few thousand shares available electronically), the RSP will be short and if someone buys further, they will raise their price to entice sellers, which will allow them to square off their position.
When trading small caps in size, typically you may find you can only really buy significant amounts on down days, and sell on up days, because the RSPs will typically be long of stock on down days which they are able to readily sell to you, and vice versa on up days. The other point people should take note of is to leverage results days and trading statements, as there will be liquidity around then anyway and the market maker will be doing a lot of two-way business, meaning they will probably offer larger amounts of stock for both buyers and sellers, and possibly with a tighter spread. So if you want to buy more, or sell on a profit warning, do so quickly while the liquidity is there!
May I echo Gromley’s thanks for these comments Gav. Really useful to know. Even though I’ve been investing for many years, I’m a bit wet behind the ears when it comes to the technical aspects of trades execution.
Thank you Gav for sharing you professional insight into quotes and pricing.
Hi Gav,
Very interesting, thanks.
Just one small point. I'm not suggesting that market makers should be forced to disclose publicly their positions. I was just suggesting that the RSP prices (not necessarily the size) are publicly quoted, rather than us having to waste time to call a broker or put in a dummy trade to ascertain what the real prices are. This would improve liquidity, because people would be more inclined to deal, if they could see that the real spread, which is often much tighter than the published prices on financial websites.
As an aside, I spent an afternoon at Winterfloods, years ago, and it was fascinating to see the teams of market makers at work. One guy was absolutely manic, I could almost see steam coming off his keyboard, he was doing trades & moving prices of about a dozen fairly liquid small caps, simultaneously, plus chatting to me at the same time! Market makers are basically just traders. There's nothing mysterious about it. And as you say, they're competing against each other (and us!)
Best wishes, Paul.
Really good piece on £RGB , the only worry I have is, how do they make money outside of Friday and Saturday night?
The spread price is the widest price at within a normal volume trade, if your broker only gets you the price at the widest prices then you need to change broker, I rarely pay the highest price, often well within the spread or even around midprice. You can set a limited order which will fill if the price drops to your set price. On HL you can see the latest trades which gives you an idea of what is happening. For more trading details I think you need to buy Level 2.
Great report on Revolution Bars (LON:RBG) Paul. I hold (only since mid Dec). Thanks also for the general insight on the invisible professional brokering and trading. Very useful info.
How long can the LSE allow this rigged system to continue, where the genuine prices (on RSPs) are hidden from view? It wastes so much time having to find out the real prices by enquiring with a broker, or putting a dummy trade into an online dealing platform. We need proper price transparency, with the quoted prices being the real prices on RSPs. Everyone should have free access to all the pricing information, in real time. That would level the playing field between professionals and everyone else.
Completely agree. From my own experience working at a small cap broking house, market making in small cap stocks is very profitable, and tends to support the barely profitable aspects of stockbroking like research&sales and corporate broking.
Interesting debate. Suspect many readers will have online holdings in SIPP and ISA form and are therefore rather stuck with the online quote rather then being able to work a trade with a broker on the phone. I have one which often trumpets the fact that they have improved the purchase price by x %. Might be worth going for a limit price rather than the vanilla bid/offer quote to get inside the price you are given on the screen.At times of high activity post an RNS the quote often disappears and you are invited to ring up the dealing desk..
Re: Ince (LON:INCE)
Once again Paul your analysis has saved me a great deal of money. I was getting tempted to buy in to them last week and early this week. But I always look at the discussion thread on Stocko before pulling the trigger and re-read your report from last July. Which put me right off.
Thank you
Cheers
Francis
PS: Congratulations - you have been on fire over the last few months, amazingly dependant and wide coverage of the small cap universe peppered with interesting macro and trading insights. Whatever it is you're taking, I could do with some! Great stuff
Do not underestimate Michelmersh as a stable, boring, dividend stock - just right for oldies like me!
Hi Paul
Thank you for your in depth Revolution Bars (LON:RBG) analysis today. Really helpful and interesting.
Jon
Paul, an excellent piece on spreads and market-makers, as ever.
Another reason why stated small-cap spreads are a PITA is that they are used as the basis for the spread to which SB firms then add their margin, so you are paying a chunky margin twice over.
Grumpy - if you call up then often you can get it done at a much better price. Obviously, no good if the price is moving quickly.
Hi grumpy5,
Paul, an excellent piece on spreads and market-makers, as ever.
Thanks! Glad it was useful.
Another reason why stated small-cap spreads are a PITA is that they are used as the basis for the spread to which SB firms then add their margin, so you are paying a chunky margin twice over.
You can get round this problem by phoning up the SB company, and asking them to work the order for you. This is what I do. As opposed to placing your order online, which is much more expensive for small caps.
The SB co buys the stock at the cheaper price (or rather they do it via a CFD provider), then adds their fees onto the improved price. Therefore I receive the full benefit of getting inside the spread at the cheapest available RSP price through my SB accounts.
Spreadex are by far the best SB provider for small caps, I've found, and will happily work orders for you in obscure small & micro caps, to avoid the problem of wide quoted market prices.
Obviously controlling/minimising the gearing is the key bit with SB accounts, and not over-concentrating into something illiquid.
Regards, Paul.
As someone who has only ever bought shares through an ISA or SIPP through HL, this sounds interesting - can anyone point to a good guide to investing using SB accounts?
|If Spread betting is new to you I can recommend Robbie Burns book - The Naked Traders Guide to Spread Betting.
1pm (LON:OPM)
#managedselfharm in the short term -> increasing bad debt provisions despite relative reduction in own book lending and move to even more brokered on loans (a way to profit from risks they don't want to take on their book but a lower quantum of earnings from it), infrastructure investments related to combining successfully acquired businesses (wouldn't being doing that pre current LTIP vesting if it were in play) and they have been slow to grow lending when others say the demand is there (looking at you PCF (LON:PCF) ).
Waiting for the LTIP with 60-110p strike to roll off in summer and then step on the gas
High profit and conservative lender. Value + 'released' growth should see a price head towards 100p....and then there's high margins and growth to keep it going.
Nothing is ever a slamdunk but this is close....unless mgt commit suicide by doing an acquisition after guiding they wouldn't for foreseeable future as share price not favourable....it would be a way to truly kitchen sink the price ahead of a new LTIP.
What's not to love? :)
Thanks for your view on 1pm (LON:OPM) (I have a toe in the water), including:
" ...it would be a way to truly kitchen sink the price ahead of a new LTIP."
It's only January, but I think it's clear that you have already won the 2020 award for Most Cynical Comment Of The Year. I salute you!
Re Revolution Bars (LON:RBG)
I am a holder
Thanks for the analysis Paul. A broadly steady as you go trading update. I agree the debt reduction target is important, and cash flows look good.
I was a bit bamboozled by the property deal, which seems to have involved a reverse premium to get out of some obligations, but my heart sank a bit on hearing a new commitment to a 25 year lease, but difficult to comment further without knowing the sites involved. Unfortunately, the saga around leases tends to show you that making long commitments to Landlords is generally not a good idea for most businesses in the current economic environment. My personal experience has left me cynical about Landlords, their upwards only rental clauses, their estimation of term end dilapidation costs etc, though some can behave well. However, assume the worst is my working hypotheses.
Was my reading right that they say their sales growth came from the additional premises they acquired before pausing their site acquisition policy?
It would interesting whether they have made any progress on their food offerings in terms of sales?
I don't expect too much in the way of fireworks on the share price for the time being.
trident - re Revolution Bars (LON:RBG)
Yes my eyebrows shot up a little to read about them taking on new 25 year leases.As you say though, it is site specific and whilst I don't know many of the Revolution Bars (LON:RBG) sites at all, the very few I do I would imagine to be relatively easily "passed on".
This, and particularly the last five words of the quote above "in the current economic environment", led me to muse on something.
Maybe, now is exactly the time to be locking in generous lease terms on retail property?
Pretty much everyone and his/her dog seems to be of the opinion that we are witnessing "the time when the internet murders the high street". In fact though, whilst I do not deny the permanent structural changes, I do think there is an element of economic cyclicity here that is perhaps being overlooked.
You probably have to consider here how much faith you have in the management (not my forte) and judge whether they are more likely to be acting stupid rather than smart.
Just as a somewhat related bit of personal experience I was recently vaguely looking at a lease offer on a Pub / Restaurant including accommodation and the rental deal looked to me extremely attractive just for the accommodation. It got snapped up fairly promptly, so I didn't get the chance to review with the tied supply agreements gave much scope to generate operating profits or whether it was a trap for the aspiring pub landlord. It certainly gave me pause for thought.
Back to Revolution Bars (LON:RBG) , when I read Pauls recent holdings review I winced a little as I felt he was still being too trusting (or perhaps even in denial). But perhaps his faith is in the course of being vindicated - although I have no position here, I genuinely hope so.
Revolution Bars (LON:RBG) I'm trying to get my head around the LFL progression, and not sure I can from the information available.
In the report above, Paul gives the LFLs for Q1 (TY) as 0.7%, therefore showing a progression to date, with LFLs for H1(TY) as 1.2%.
But in their last prelims, RBG distinguished between LFLs including refurb closed days of 0.7%, but excluding refurb closed days of 1.2%.
If the value they're using in today's update is excluding refurb closed days, then given LFLs over the xmas of 4%, this would imply weaker LFLs in Q2 (TY) overall. I think this would change the narrative somewhat, though not terminally, as it would at least lead to questions as to whether the refurbs are just driving short term gains from curious customers, but not sustained repeat custom.
Have I got this right, and does anyone know which LFLs they're using in this report?
*Edit* - it does say in the update "Like-for-like* sales for the 26 weeks ended 28 December 2019 were +1.2% higher representing a further improvement on the 0.7% increase reported after 13 weeks", so I suppose that we should give management the benefit of the doubt and assume they're reporting LFLs including closed-days. However, I'd have liked that stated explicitly in the update.
Revolution Bars (LON:RBG)
Wherever the real LFL numbers lie between 1 and 4% ish, I find it very hard to view these numbers with anything like the glowing optimism that the management or Paul do.
In general terms costs such as wages are rising and so there needs to be a price increase to cover these extra costs. So, either this LFL increase is a small price increase that may just about cover these costs (meaning volume growth is minimal to non-existent), or it is a small volume increase with a minimal or non-existent price increase (meaning margins will be eroded if costs are increasing) (at unchanged business mix).
So either way this is pretty uninspiring. The only inspiring aspect is that it appears to be less bad than before.
By comparison M&B have reported Christmas LFL increase of +5.6%
It could be argued that Revolution operate in a different market position to M&B however the M&B number shows that the public are spending money on drinking and eating if the venue/format works for them. While Wetherspoons have not reported Christmas trading, their previous trading update was +5.3 LFL. So, this also supports the view that the good operators in the drinking/eating segment are growing faster than Revolution.
The class operator in the same niche as Revolution was the privately owned Be At One. Interestingly, they were snapped up by Stonegate. Perhaps this means that Stonegate saw Be At One as more attractive than Revolution. (I’ve not seen any trading update from Stonegate unfortunately).
So, Revolution’s headline sales numbers say to me that the format/business is still not working well when clearly other formats are working better. The notion that it is a takeover target any time soon seems like wishful thinking as the format clearly isn’t going to deliver the growth that an acquirer would want.
Hi Graham,
Fair points about Revolution Bars (LON:RBG) but I think you're overlooking what is for me the most important thing. Namely that the reasons it's under-performed are being gradually fixed. In particular, the older sites are tatty and badly need refurbishing. That's started, so it will almost automatically drive decent increases in future LFL sales growth.
Similarly with the operational improvements, these are starting to have an effect, but there should be lots more to come.
Therefore I think we should see Revolution Bars (LON:RBG) as very much a work-in-progress turnaround, and not the finished job. As you say, LFL growth around 1-2% is definitely not exciting from an investment PoV. But I reckon, once all the pieces come together, we could be looking at nearer 5% LFL growth later this year. That's what makes it a lot more interesting than you suggest, in my opinion.
Regards, Paul.
Excellant analysis on RBG. This was your ‘Top Pick’ at Mello last May, then priced at 71p. Significant improvements since then. Good call.
Paul: many thanks for the section on Quoted Share Prices and the commentary on Revolution Bars (LON:RBG). Both sections are super helpful.
Cheers
Andrew
Camtab, Aislabie and others interested in the hydrogen vs electricity discussion. Having watched for ages I've very recently taken the plunge with ITM Power (LON:ITM) . Only a small position but hopefully looking to increase as funds become available. I don't expect it to start making lots of money for years but feel they should be supported.
I'd love to get a hydrogen cell car if only there were a decent number of filling stations - the roll out does seem very very slow. I guess it's the chicken and the egg situation but there are manufacturers out there seemingly developing more vehicles. I'm sure you already know that Shell have a few sites (very few) providing hydrogen for cars where the hydrogen is "made" on site using renewables (so no real storage or transportation problems).
I'm persuaded that mass electricity for vehicles is a long long way off - the grid as it is simply couldn't cope with the demand.
Another interesting article just popped up: -
https://www.abc.net.au/news/2020-01-15/denham-near-shark-bay-first-wa-town-to-be-powered-by-hydrogen/11870472
Warning - I'm one of those who opted for a Sony Betamax in the early days of recording TV programs.
Thanks Laughton for that. Yes I believe there are 15 hydrogen stations at present and we need 65 is the view to make them viable. The Shell stations are a deal with ITM. I believe there are 3 hydrogen cars at present all Asian producers, hyundai, toyota and nissan (i think). There is a prediction there will be over 20 models by mid 2020s. View seems to be hydrogen is the answer for lorries large vans whereas smaller run around cars will stay with elcetricity, largely for the reason you state that the grid couldn't cope with electrification of that scale anyway.
I also bought ITM several months ago, but surprised at the big and fast share price gains since. Assume it is fast growing recognition that hydrogen/fuel cells is an alternative to pure electric, and ITM in good position to benefit?
No reason why there can’t be a big future for both electric and hydrogen. . Also as retiring boss of BP pointed out recently, the death of diesel and petrol vehiclles is a very long way off. Ditto aeroplanes and commercial ships and cruise ships where fiel consumption is registered NOT in how many miles per gallon they do, but in how many gallons per mile!
And in addition to the car Companies mentioned by Camtab, BMW and Honda can be added to that list. Honda are working with Isuzu to develop hydrogen powered trucks as they see more potential for fuel cell technology in commercial vehicles than cars. Indeed it is for commercial vehicles, along with trains and aircraft where the advantages of hydrogen become clearer.
e.g read this link on fuel cell powered trains in Germany and note the combination of hydrogen fuel cells and intelligence high performance batteries:-
https://dieselgasturbine.com/akasol-supplying-battery-systems-for-fuel-cell-powered-trains/
Also from the above article:-
“Our decision to replace the entire diesel fleet with Alston hydrogen trains makes us a trailblazer in the transportation revolution.”
I’m convinced hydrogen potential has been overlooked, but what I have no idea about, and as holding ITM wish I did know this, is whether ITM is the right Company to be invested in to benefit. The share 5 bagging in a few months suggests it could be. Or it could just be a lot of punters like me buying for the hope value and hunch that ITM is the right choice.
Looking forward to reading your commentary on RBG Paul. I was filled at 90p this morning, as it seems to me that the price is now clearly turning up for the better alongside fundamental strengthening.
Would like to average up here in time - illiquid for now though. Current spread is 85.2p-91p.
My AGM report on RBG is on ShareSoc's website.
Hi Paul any chance of a gander at INCE (LON:INCE) if you have time big discounted placing today seems to have been news leaking ahead of the announcement looking at the drop off in the price.
Would be good if you could highlight any red flags you would have seen in this stock to help the learn angle for the guys & girls who follow you.
No drama if your stacked and don't get a chance.to take a look
Regards Andy
Seconded on INCE (LON:INCE)
I don't hold this, but this could be a valuable educational process in order to avoid similar situations next time. It just seems odd that a company would have to discount a placing so much.
There was a lot going on in the accounts. The reason for the fundraise seems obvious from the half-year report: they were running out of cash and had only small headroom on their borrowings.
It appears that most of the profits they make are attributed to non-controlling interests, not equity holders: would this give rise to a situation where the headline figures look excellent (thus making the company look extremely cheap) but the reality is something else?
Paul ran his critical eye over Ince (LON:INCE) a couple of months back [edit: see SCR for 28 Nov 2019], and rightly deemed it uninvestible due to the horrendous level of debt. I thank him for that, as he kept me out!
This fund raising will not solve the problem either, so please beware!
Actually, with INCE (LON:INCE) the "debt" is only half the "debt problem" because "deferrred consideration" isn't debt (according to some) so their "total debt" didn't include their total debt. Meanwhile lease liabilities now are "debt" even though they aren't really debt (according to others). Hope I've cleared that up.
Morning Paul, any thoughts on Frontier Developments (LON:FDEV) trading update today would be greatly appreciated
Encouraging update from Ten Entertainment (LON:TEG) , though it looks like this was already priced in.
I hold alongside Hollywood Bowl (LON:BOWL), both of which I feel are great business models positioned in a growing area of the market (where consumer spending on 'experiences' seems to be on the rise). Could Ten Entertainment (LON:TEG) be a target acquisition for Hollywood Bowl (LON:BOWL) at some point!? Looks like it would represent good value
hi Paul
Heard anything from Sosandar (LON:SOS) regarding when their trading update will be released. Pretty key info based on the last year strategy and results. As a large portion of my portfolio I am nervously waiting on this.
Thanks
If Boo Hoo can get their trading results out yesterday then surely SOS can, unless of course summat's up. No reply from them regarding e-mail sent to Finance requesting potential date for update so sold out. Why risk it?
I would be nervous for Sosandar (LON:SOS), as I am about UP Global Sourcing Holdings (LON:UPGS)
Despite the old saying about bad news travelling fast, it seems to me disappointing or underwhelming company news tends to be sifted through carefully to try and pick out the positive bits whilst market beating news generally gets out the door fairly quickly.
But then I am a bit of Eeyore!
Hello Trident
What's the connection Sosandar (LON:SOS) and UP Global Sourcing Holdings (LON:UPGS) ? Other than in the broad retail area?
Its a bit nerve jangly for sure but there seems some clues that UPGS should be performing okay - B&M European Value Retail SA (LON:BME) have expanded a decent bit through new stores (disappointed LFL), its been reported generally that homewares had a good Q4 / Christmas period (where UPGS focused) and the German consumer (their new growth market) had a robust time of it too. Higher £ will have helped costs a little too
The only connection other than a very broad retail background is that they both don't seem to have issued trading statements at a similar time to the prior year announcement.
For UP Global Sourcing Holdings (LON:UPGS) last years announcement was pretty positive, and there is some general wariness the background to retail sales has perhaps dented upsides.
All speculation at this stage of course!
Thanks for the clarification re UP Global Sourcing Holdings (LON:UPGS) angst.
Last year was billed as unscheduled update given such good trading conditions expectations needed to be raised. Both that year and prior year 2nd week of Feb was time of 'official' update. The 2018 one was bad of course. Not many to go on....I note that mgt have been keen trumpet positive in the RNS which I'm generally wary of...that said my guess is okay trading and I think since warning after IPO the approach has been to guide low-ish and match to outperform. We'll find out in few weeks
This is probably a really good approach on these high risk results shares. All shares I have held like this tend to fall more on bad or even lukewarm results than they increase on good news. Good brave shout.
A very exciting trading update from Immotion (LON:IMMO) today. They announced the installation of a 6 seater cinema at the London Eye, the UK's most popular paid tourist attraction. The installation will feature their unique VR Roller Coaster experience, Tower Coaster - London, where customers will be able to see London from 400 feet above the Thames, enjoying the sites of the city. This installation joins the 8-seater mini-theatre installation at neighbouring Sea Life Centre. Due to great demand at the Sea Life centre, the number of installed headsets has recently been increased from 4 to 8 after a short trial. This highlights the experience is in high demand and suggests Immotion have a first class offering.
The company have also announced today that in Q1 this year, they will be installing a total of 93 headsets across a further 5 entertainment sites, 9 aquariums and 1 European Zoo. The majority of these new installations will be deployed in aquariums, increasing the total number of aquarium partners from 14 to 26, with aquarium based headsets rising from 52 to 107. Average weekly revenue per headset in the Aquarium sector through 2019 was £476 and during the busy Christmas holiday period an average of £794 per week was achieved. Once all the installations have been completed the company will have a total of 394 headsets in the field.
Based on forecast costs, the company reported today that it it will reach monthly EBITDA break-even at or around the end of Q1. The company have previously stated that c.400 installed headsets is the magic number for break even, anything beyond that and the revenues fall straight to the bottom line. The business model is exciting because of its recurring revenues and the exceptional operational gearing as more headsets are installed.
Immotion are moving very quickly signing partnerships with blue chip clients like the O2 and the London Eye. They are targeting quality over quantity by only signing partnerships with customers who have high footfall. For example the London Eye attracts 3.5 million visitors every year. With this in mind, I would suspect each of the 6 headsets installed at this location should be able to achieve average revenues in excess of the £476 per week they are currently achieving from the aquarium sector.
It is still very early days but the signs are looking good. The company have a goal of 1,000 installed headsets by this time next year. I suspect this will be difficult to achieve but it I like the ambition of the management team.
Ten Entertainment (LON:TEG)
Ten Entertainment (LON:TEG) continues to be at a significant discount to Hollywood Bowl (LON:BOWL) which bemuses me - perhaps others have thoughts on this.
I think Hollywood Bowl has some better metrics (other have said) than Ten entertainment - can't remember exactly what those are. eg if their depreciation charges or more conservative then it sould be then p/e differential is warranted.
I would also say the individuals who were involved in this company originally - some think can't fully be trusted. I think Paul has commented that he would not invest in this company at present due to this fact . Note those individual(s) i think are less connected to this business now but i think are still connected.
Being honest i had a bit of a punt on these when the price was waaaay depressed with woodford selling - but i am becoming more confident with each update that the company is delivering a sustainable business model despite the 40%+shareprice appreciation in 9 months - so at present i have no plans to cash in my chips.
One slight surprise is that stockopedia shows that the consensus forecasts for 2019 and 2020 EPS have been trending down slightly over the last 6-9 months - that has a come as a bit of a surprise, but at least the trend in increased profits 2020 compared to 2019 is intact - they did mention accelerating investment around the half year stage - whilst saying they were on plan to meet expectations, so that's slightly confusing although it may simply be a stats or timing issue anomaly with the stocky numbers perhaps?
Interesting on "connected persons" for Ten Entertainment (LON:TEG) rmillaree.
I also did a compare vs Hollywood Bowl (LON:BOWL) and what that effectively tells me is that whilst it is probably slightly higher quality in terms of metrics (ROCE, gearing etc) and also obviously a bit bigger/better brand (perhaps?) the growth in earnings is significantly less at 4% vs 17%, whilst trading on a rolling PE of 20 vs 13 for Ten Entertainment (LON:TEG)
On balance then whilst Hollywood Bowl (LON:BOWL) is clearly a really good company I'd say it is now fairly valued at PE of 20. On the flip side Ten Entertainment (LON:TEG) clearly has more capacity tog row over next couple of years and is probably undervalued on relative terms. I'd expect it to trade at a small discount to Hollywood Bowl (LON:BOWL) so maybe PE of 16/17. Therefore happy holding Ten Entertainment (LON:TEG) looking for a 20-30% re-rate.
David: I agree about the re-rate potential of Ten Entertainment (LON:TEG) vs. Hollywood Bowl (LON:BOWL). The forward 12M rolling PEG on the former is 0.9 vs. 4.9 PEG for the later - Quite a difference. Have taken an Ten Entertainment (LON:TEG) initial position this morning and will review again with the May AGM outlook.
M Winkworth says profits modestly ahead of market expectations. Final 1/4 divident up 10%; SP up 14.5% as I type. Interested in views. Must dash.
Richard
Yes ,good announcement from M Winkworth (LON:WINK) along with interesting commentary on London property market, which they say is showing signs of life, solid company.
I have for some time held ITM which is fast moving outside of the remit of this page as it is one of my few shares that has done well! They have announced their results will come out 27th Jan. I find this an interesting study in equity investing. It is easy to hold shares not doing well (often incorrectly) because you are never wrong and sooner or later the market will recognise your genius (right?) But shares that have done really well? Wow that's tricky, because in your head is the resounding sound of confirmation and it will of course continue to "infinity and beyond" and make you very rich. We are continually told that the successful investor runs his profits. But too often I have run profits only to come back down to earth. So ITM! My thinking is going, it has risen on a recognisation (supported by Blackrock yesterday) that we have to do something about burning fossil fuels (or we will all go up in flames). There are not too many options and this is the most compelling. So whilst results won't be necessarily good, looking forward demand must rise. So I guess I am a holder but perhaps like Icarus the heat will burn my wings and I shall fall to earth again!
The niggling question with the hydrogen economy that is at the heart of ITM Power (LON:ITM) is how do we get the hydrogen in the first place. The energy put in to create the hydrogen is always going to exceed the energy you get out (as long as normal physics hold). So then it is down to convenience and efficiency of storage.
Using the initial power to charge a battery gives you an easy to store power source. It has difficulties but apart from weight (key for aerospace) nowhere close to the problems of storing hydrogen.
Clearly the refilling as opposed to recharging is for now clearly in hydrogen’s favour but battery technology (and swap out possibilities) are constantly bringing down the difference.
Transporting the energy for recharge is also clearly in battery’s favour with the physical transport of hydrogen being a high cost alternative to a cable.
For specialist functions hydrogen has much to recommend it but apart from uses where weight is critical it has difficulty competing and in its need for original power generation does nothing for the carbon problem. (If you are persuaded that a growth of 100 parts per million in the atmosphere actually is a problem)
Thanks for your response Aislabie. I suppose my thoughts are that if you use electricity in any form it s either generated by hydrocarbons or renewables. If you use renewables then that must be good and likewise if you use hydrocarbons then you are transferring carbon into the atmosphere which is definately bad. I agree batteries will improve and I like the look of graphene to just this end but again time will tell. Finally am i persuaded that growth of 100 parts per million i the atmosphere is a problem? Crikey me and all of the scientist community know this is a problem. I have travelled the world and seen the results of this. The last time the atmosphere held this amount of carbon was circa 3 million years ago during the pliocene period when water was believed to be 20 m higher than today. Imagine the misery that would cause?
One of the issues about Hydrogen production is apparently the input energy required to make it, and then storage issues, as it theoretically explosive (hence it energy density)
Apparently these problems are being worked on with new fuel cells etc.
With regard to ITM the one project I was interested in was apparently feeding hydrogen into a mix with the natural gas system in Germany, reducing the overall carbon release.
As gas is still proposed as a carbon reducing initiative relative to coal and oil powered powerstations, this seemed to have positive features to me,
But I don't know if it was deemed to be a successful project or not.
Trident, you said
"With regard to ITM the one project I was interested in was apparently feeding hydrogen into a mix with the natural gas system in Germany, reducing the overall carbon release."
Have you looked at the RNS from 2/1/2020 (link below)?
https://www.stockopedia.com/sh...
This describes a similar pilot project that has started in the UK.
I have been in an out of Itm Power (LON:ITM) for many years (mostly losing money until recently) but they now have far more strings to their bow and their projects are gaining traction.
With regard to the power needed to produce hydrogen, one of the things ITM do is use excess energy created by wind turbines to generate hydrogen as a method of storing power for later use.
There are some excellent articles on the ITM website https://www.itm-power.com which are well worth a read.
Shopping365
My comment was based on something I saw last year that struck me as interesting.
On the principle of write first and research afterwards (a bit like my investing strategy, of buy first and research later!) , I did look up their website afterwards to see where the project had got to.
Still looks interesting. I think we should be looking at 'easy' carbon reduction wins, and this strikes me as a good contender to reduce emissions from household and industry energy use.
I am not currently an investor in ITM. It strikes me that it is still at the early days of monetising its hydrogen strategies. But could be promising in the mid term.
Its the old VHS/Betamax conundrum for where the scaled up energy resources will come from in the future, particularly in motorised transport, but can't help thinking if they can crack it, hydrogen has a lot to offer. Whether ITM will be the go-to company for some of that remains to be seen, I guess.
Another company with a different approach in this sector, which I must say I think is a complete punt at the moment, is £PHE. It has developed a system to convert old tyres and non-recyclable plastics into gases including hydrogen. You might like to read all about it here https://www.powerhouseenergy.n...
With a stock rank of 9 and a value rank of 0 it is certainly not one for the faint hearted, but maybe one for the watch list.
Trident they tested it in Germany with Thuga and it has been successful. They also announced successfully on work they have been doing with Keele University in this country recently. Keele were chosen because they have a discreet closed system.
Ten Entertainment (LON:TEG)
Although just "in-line" was impressed by today's TU. LfL sales growth is 8% and seems to have accelerated in the second half.
Ten Entertainment (LON:TEG) continues to be at a significant discount to Hollywood Bowl (LON:BOWL) which bemuses me - perhaps others have thoughts on this.
Phil
(I hold)
I am a Hollywood Bowl (LON:BOWL) holder so could be seen as biased, but best advice is to use the excellent "compare" function here on Stockopedia and you will see a direct comparison on lots of metrics between the two. I did this myself this morning !!
Of course Hollywood Bowl (LON:BOWL) has had a major re-rate since last results on 13th Dec 19, and is now possibly fully (or over) priced, but I believe has much more in the pipeline with the development of the mini golf etc. Plus it has an outstanding management team and a CEO who bought it from private ownership, developed it, IPO'd it and now led it to over £3 a share - real skin in the game.
Ten Entertainment (LON:TEG) Hollywood Bowl (LON:BOWL)
I have indeed used the compare function many times and this is what highlights the issue. If you look at the "Forecast valuation and growth" section Ten Entertainment (LON:TEG) is much better. In fact this is borne out by Ten Entertainment (LON:TEG) having LfL growth of 8% and Hollywood Bowl (LON:BOWL) ,at its last results 5.5%.
You could also argue that its foray in escape rooms is potentially more interesting than mini golf.
The reality is probably that they're both good and you take your choice and I suspect some hold both.
Cheers
Phil
Ten Entertainment (LON:TEG) Hollywood Bowl (LON:BOWL)
I have indeed used the compare function many times and this is what highlights the issue. If you look at the "Forecast valuation and growth" section Ten Entertainment (LON:TEG) is much better. In fact this is borne out by Ten Entertainment (LON:TEG) having LfL growth of 8% and Hollywood Bowl (LON:BOWL) ,at its last results 5.5%.
You could also argue that its foray in escape rooms is potentially more interesting than mini golf.
The reality is probably that they're both good and you take your choice and I suspect some hold both.
For me it's very simple. If you have an industry with a few main players, always buy the market leader, especially if they have good management who can deploy capital efficiently. This may sound too simplistic but it has worked for me down the years.
Twenty years ago, when I wanted exposure to semiconductors I bought Intel, not AMD. When I wanted exposure to big software I bought Microsoft, not Oracle. When I wanted exposure to networking I bought Cisco, not Juniper. If you stick with the market leaders within a mature market you won't go far wrong.
All the best, Si
Good point Si.
But sometimes they get sleepy or do something daft.
Phil
Good point Si.
But sometimes they get sleepy or do something daft.
Phil
Yes, they do but if they are dominant enough even that doesn't derail the long term performance - reminds me of the Buffet quote about buying companies that even an idiot can run because at some point they will! Look at the period Microsoft went through under Steve Bullmer (buying Nokia for chrissake!) and Intel throwing good money at rubbish like McAfee.
Surely the thing about bowling alleys is that it is more of a land grab - is the second placed player going to want to spend the capex to open a new outlet in the same town as the market leader? I don't know the answer to that but you get my drift about first mover advantage which seems real in this instance.
Besides, on an EV/EBITDA basis (the normal way of comparing similar companies) Ten Entertainment (LON:TEG) is not that much cheaper i.e. 10.81 plays 12.37 for Hollywood Bowl (LON:BOWL) according to Stockopedia. Ten Entertainment (LON:TEG) also has pretty weak current ratio, so not sure what the situation is with working capital. Personally, I have developed an aversion to red on a StockReport :)
All the best, Si
The land grab argument seems the most persuasive.
There are about 320 sites in the UK - Ten Entertainment (LON:TEG) have @45 and Hollywood Bowl (LON:BOWL) have @60. They already have about a third of the market. From my limited historical research Ten Entertainment (LON:TEG) seems to buy existing sites from the very fragmented remaining two thirds and Hollywood Bowl (LON:BOWL) seems to develop new sites in retail parks etc. Except for the major conurbations I can't see there being space for more than one so head to head competition doesn't seem to be an option in the main. In fact they both seem to be concentrating on refurbishing/improving their current sites rather than expanding - both seem to have only opened 2 in their last financial years. But perhaps purchasing clout may come to the fore in the future.
Take your point on EV/EBITDA but if Ten Entertainment (LON:TEG) does grow faster than Hollywood Bowl (LON:BOWL) then the discrepancy will grow.
I don't think in a cash business (which is growing and sound) that the current ratio is as important a measure as normal.
Cheers Si
Phil
There are about 320 sites in the UK - Ten Entertainment (LON:TEG) have @45 and Hollywood Bowl (LON:BOWL) have @60. They already have about a third of the market. From my limited historical research Ten Entertainment (LON:TEG) seems to buy existing sites from the very fragmented remaining two thirds and Hollywood Bowl (LON:BOWL) seems to develop new sites in retail parks etc.
Well I think you've hit the nail on the head here, then. Clearly Hollywood Bowl (LON:BOWL) generate higher sales per site - it has 15 more sites but generates 50% more revenue than Ten Entertainment (LON:TEG) so they are much better at extracting cash from customers.
All the best, Si
Not necessarily, it could be that the sites are larger. 50% more revenue but the Hollywood Bowl (LON:BOWL) is about 4x the size of Ten Entertainment (LON:TEG).
Not necessarily, it could be that the sites are larger. 50% more revenue but the Hollywood Bowl (LON:BOWL) is about 4x the size of Ten Entertainment (LON:TEG)
As I said, I'm a simple soul. Let's just call a bowling alley a bowling alley. It could also be that Hollywood Bowl (LON:BOWL) is better at selecting sites i.e. where the locals have more disposable income and spend more on average per game. I don't know, all I know is Hollywood Bowl (LON:BOWL) was undervalued when I was collecting at 200p and now it's probably not. However, I don't see any good reason to switch into Ten Entertainment (LON:TEG) as it looks the poor relation of the two to me.
Simple simoan
That's a bit superficial isn't it Si? (Not always a bad thing)
I've not really looked into the comparison, but surely this may well just mean that Hollywood Bowl (LON:BOWL) has the bigger sites?
Their ROCE is approximately the same TEN : 20.5% BOWL : 20.7%
Although whether ROCE is a meaningful comparative I cannot say given that 'Capital' now includes the 'economic value of future committed rental payments'. So that measure may flap in the wind somewhat dependent on lease renewal or break clause dates; especially when we are talking about a relatively small number of sites in both cases.
You would perhaps expect the larger player to be more 'efficient.' That looks broadly true with Bowl winning on Operating margins, 21.9% vs 15.6% (both are good imho)
From just a superficial look I cannot really see which I would prefer, but I'm not sure how far they are really "competitors" or whether they just operate in the same field with non-overlapping monopolies(ish).
If I was specifically looking to invest in bowling, I could perhaps make a case to invest a little bit in each.
That too is very superficial and there may well be a case to consider one a much better prospect than the other, but nothing immediately comes to mind.
That's a bit superficial isn't it Si? (Not always a bad thing)
I've not really looked into the comparison, but surely this may well just mean that Hollywood Bowl (LON:BOWL) has the bigger sites?
Their ROCE is approximately the same TEN : 20.5% BOWL : 20.7%
Although whether ROCE is a meaningful comparative I cannot say given that 'Capital' now includes the 'economic value of future committed rental payments'. So that measure may flap in the wind somewhat dependent on lease renewal or break clause dates; especially when we are talking about a relatively small number of sites in both cases.
Yes, superficial by necessity as until yesterday I was not familiar with £TEN - in fact when I see reference to it I always get confused with that basket case Ten Lifestyle (LON:TENG) ! I didn't wake up one day and decide I needed to own shares in a ten pin bowler operator like Hollywood Bowl (LON:BOWL) (it's just a good profitable company with sound management that is throwing off cash) so I have never compared the two companies before. I was only responding to the initial request for comments from Phil to make the point that £TEN didn't seem that much cheaper to me. Personally, I find comparing P/E's based on adjusted EPS to be a pretty blunt instrument for comparing two companies and prefer EV/EBITDA.
You are correct that ROCE is similar and growing for both companies - this is good! However, this misses the point I was trying to make with reference to revenue per site. How efficiently management use the company's assets is better illustrated by ROA which has been 20-40% higher for Hollywood Bowl (LON:BOWL) in the past few years.
Anyway, I'm sure everyone is well and truly bored with this by now. I'm certainly not trying to say that Teg Group Ord (LON:TEG) would make a bad investment!
All the best, Si
Maybe the smaller company of the two offers some tak-over potential?
Interested in Ten Entertainment (LON:TEG) although the results announced today look like a boring "in-line".
Jim
Thanks for covering this Paul.
Comment deleted
My morning smallcap tweet: INCE to rinse holders, no Xmas fizz for Quiz
Gamma Communications (LON:GAMA) Everyman Media (LON:EMAN) Revolution Bars (LON:RBG) QUIZ (LON:QUIZ) M Winkworth (LON:WINK) INCE (LON:INCE), Centaur Media (LON:CAU), Ten Entertainment (LON:TEG), Michelmersh Brick Holdings (LON:MBH), ATTRAQT (LON:ATQT), Knights Group (LON:KGH)
Gamma Communications (GAMA) guides FY adjusted EPS slightly ahead of consensus with rev in line.
Everyman Media (EMAN) guides FY rev £65m cf F/C £67.4m. Pre-IFRS 16 EBITDA up 30%.
Revolution Bars (RBG) in line. Will "urrender five leases of loss-making sites and re-gear a further four leases with a small net rent reduction but with a 25 year term." Will pay compensation of less than three times the annual trading losses of the five lease surrenders. Will save £1.2m PA cash.
Quiz (QUIZ) Xmas trading weak with rev down 9%. Gross margins broadly in line with expectations. Co has largely offset the impact on profitability of the lower than anticipated sales by taking actions to improve gross margins, enhance efficiencies and reduce costs. So "overall performance in the year-to-date remains broadly in line with the Board's expectations." I hold.
M Winkworth (WINK) guides FY rev and pretax modestly ahead of market expectations.
Ince Group (INCE) £16m placing, OO and staff offer at 45p, a nasty 49% discount. Will be used to reduce the amount of the Group's drawn down working capital facility.
In line: Centaur Media (LON:CAU) Ten Entertainment (LON:TEG) Michelmersh Brick Holdings (LON:MBH) ATTRAQT (LON:ATQT) Knights Group (LON:KGH)