Small Cap Value Report (Wed 15 July 2020) - PMP, GFRD, MCS, AIR, CARR, ARC

Good morning, it's Paul here with the SCVR for Weds.
Estimated timing - I should be mostly done by 1pm, but will probably need a bit more time to get everything done, so let's say 3pm.
Update at 14:34 - sorry, I nodded off after lunch (trainee pensioner!) so will keep going until 5pm.
Update at 16:40 - today's report is now finished.
Please see the header for the shares I'll be reviewing today. I've included a couple of reader requests.
.
Vaccine hopes
Every now and then the US markets get excited about the prospects for a covid-19 vaccine. I've been glued to CNBC (American financial news channel) for months now, following events. The positive attitude there is astonishing, compared with the seemingly all pervading negativity of UK small cap investors. Whatever problems the economy and covid throw at the markets, they just brush it off as temporary and irrelevant in the USA, chasing share prices higher. The argument goes that whatever problems emerge, the Fed and the Govt will just keep throwing ever more stimulus, and back-stopping borrowings to enable even normally insolvent companies to continue trading (the one exception so far being Hertz). Plus a vaccine is supposedly going to eradicate covid, so why worry about it? Doesn't this strike you as overly optimistic? It does me.
Last night after hours, vaccine hopes caused the futures to gap upwards. I got stopped out again. It's proving very expensive taking a bearish view on the US markets, so think I'll have to just admit defeat there. However, I'm seeing so many similarities with 1999-2000, it's uncanny. E.g. the Robinhood (a free dealing app) traders, who are chasing momentum shares ever higher, and buying every dip. The experts are scoffing at their naivety, but (so far anyway) they're making money.
With casinos & sports shut, the assertion is that people are instead gambling on the stock market, concentrating into wildly speculative valuations on things like Tesla (where I'm still short). This is clearly the euphoric last stage of a bull market in my view, I think conditions are setting up for a market crash, or at least a very big correction - at least in the pockets of crazy over-valuation. IPOs are booming across the pond, and generally going to a big premium. Again, another feature of a manic bull market. Yet it feels completely different here in the UK.
As one CNBC commentator said yesterday;
It's not a stock-pickers market any more. It's a day trader's market.
I've never seen such an extreme dislocation between economic conditions, and the stock market. There again, as many commentators keep saying, the stock market is not the economy. It's highly concentrated in truly remarkable tech companies, which arguably do justify their high valuations, e.g. Facebook, Google, Apple, Amazon, etc.
Its all so confusing. If I'd told you that the US markets would rapidly recover all their losses, and even make new all time highs, within 3-4 months of the crash back in March, you'd have thought I was out of my mind. Who predicted that? It feels dangerously like a bubble to me.
.
Garment sector - sweatshops
The controversy over Boohoo (LON:BOO) (I'm long) rumbles on. The allegations are that some of its suppliers (or a supplier?) was operating a sweatshop and possibly paying staff as little as £3.50 per hour - which of course is illegal, as it breaches minimum wage regulations. I'm not sure if it's actually been proven, so we have to be careful what we say.
Clearly, anyone not paying minimum wage needs to be prosecuted. There's no point in having regulations like that, if companies are going to flout them.
Is BooHoo's business model shot to bits then? Of course not. If they can't buy garments in the UK at an attractive price, then they'll source them overseas. Reality check to everyone virtue signalling on social media about this issue - practically every garment that you've ever worn, was made by someone who was paid peanuts. That's how this (and many other) sectors work. There's a reason why clothing has barely changed in price (or even gone down) in the last 30 years - it's because globalisation has seen the production move to low wage economies. Therefore I suspect we'll see BOO move production elsewhere, or it could manufacture in small quantities in the UK (test and repeat model), then place a larger repeat order with a low wage overseas factory.
Boycotting BOO just means that lots of people who need the work are going to become unemployed. Of course it's not right to (allegedly) pay machinists £3.50 per hour. But there's a reason people work for that money - they can't get better paid work. The alternative is unemployment. The overall effect of boycotting BOO is to make poor people unemployed here, and to move production to sweatshops in somewhere like Bangladesh or Vietnam. How is that a positive outcome?
This is the (admittedly uncomfortable) truth. Is BOO unethical? I don't know. But its protestations of innocence look a bit weak, given that this Guardian article linked a former BOO Director to an apparently dodgy garment manufacturer in Leicester.
Should we all sell our BOO shares then? That's up to each investor to decide. I'm not. I'm in the markets to make money, not to virtue signal. Customers want cheap clothes, and it's not my job to police the working conditions of people who make them. That's what Governments and their various agencies are there to do. What seems to be happening is that ethical funds are selling out of BOO, creating a buying opportunity for the rest of us. Like all previous scandals in this sector, it's all likely to blow over quite quickly, and the share price is likely to recover over time. That's a buying opportunity in my book.
Before chastising me for being so ruthless, have you ever owned shares in tobacco companies, drinks sector, etc, which kill their customers? How about the supply chains for the electronics or car sectors - how many sweatshops provide components for them? Or as someone pointed out here, that nice shiny iPhone in your pocket was made in a factory where they had to install suicide prevention nets outside the building. The process by which poor people & countries achieve economic development, is by making stuff for richer people/countries. That can be an unpleasant process.
Quiz (LON:QUIZ) (I'm long) put out an announcement earlier this week expressing surprise and abhorrence that it too apparently used a sweatshop in Leicester. It's made no difference to the share price, because (a) was anyone surprised?!, and (b) it's too small to have ethical funds invested in it. That reinforces my view that the BOO share price is only temporarily depressed.
Bear in mind that BOO's brands sell internationally, so those overseas sales are not likely to be impacted by the allegations made in the British press. Hence I reckon BOO is probably facing nothing more than a temporary hit to profits this year. It's still delivering stunning growth, and bolting on brand after brand to its machine. Hence why I'm happy to hold my nose, and keep buying.
.
Portmeirion (LON:PMP)
Share price: 362p (up 1% today, at 10:32)
No. shares: 13.97m
Market cap: £50.6m
(I'm long)
Portmeirion Group PLC, the designer, manufacturer and worldwide distributor of high quality homewares under the Portmeirion, Spode, Royal Worcester, Pimpernel, Wax Lyrical and Nambé brands, updates on trading for the first half of the year.
Portmeirion has a 31 Dec 2020 year end. Note that it has a strong seasonal bias towards H2 in a normal year, because some of its key products are Christmas related. Therefore H1 is normally comparatively weak, plus of course this year we have the covid disruption to contend with, which would have impacted sales from Q2.
H1 Sales - this is much better than I was expecting;
Our sales for the six months to 30 June 2020 are approximately £32 million (2019: £34.9 million), representing a decrease of 8% compared to the previous year. Our like-for-like sales, excluding the sales from our Nambé division acquired in July 2019, were down 20%.
Sales in June show an improving trend, being down 9% vs last year, on a like-for-like (LFL) basis - not bad.
E-commerce - this is interesting. The renewed focus on online sales is what tempted me to dip my toe in with a small purchase of Portmeirion shares recently. It seems to be working well;
Our own ecommerce sales in our core UK and US markets increased over 90% in the first half and over 100% in Q2 against the prior year. Growth in ecommerce sales has played a core role in our strategy in recent years and we expect to see continued strong growth in the second half of this year.
As previously mentioned, I tried out the online ordering process, and was impressed with the product, delivery, etc.. Once a customer has purchased a small set of plates & bowls, as I did, from the attractive Botanic Garden classic range, then Portmeirion can tempt them to buy additional pieces, matching cups & saucers, etc, by email. I get rather too many emails from Portmeirion offering good discounts. With the wholesale and retail margin rolled together, this should be good, profitable business for the company.
Profitability - this is also much better than I feared;
We expect to report a low single digit £ million loss before tax for the first half of 2020 (2019: £0.5 million profit). Our business has a significant second half weighting in sales and particularly profit generation.
We are currently seeing good order intent from customers for our key seasonal trading period and assuming no further Covid-19 disruption and the trend of improved month on month trading continues, we are confident that we will return to profitability in the second half of 2020.
As you can see, H1 last year was not much above breakeven, so I think a "low single digit £ million loss" in H1 this year seems a creditable performance, and will have benefited from the furlough scheme.
Fundraising - my worry at the time, was that the group might have been bleeding cash badly, so I was sceptical about the reasons given for the fundraising in June. Today's update reassures me that my fears were misplaced. Although I still suspect the bank might have encouraged the company to raise fresh equity. £11.2m (net of fees) was raised at 380p, which wipes out net debt of £10.0m, taking it to a £1.2m net cash position after the fundraise. With £15m unutilised bank facilities - that looks very comfortable.
Although we do need to be careful to remember that the covid crisis has allowed companies to stretch their creditors, particularly VAT and payroll taxes, and rents. Hence all net debt/cash figures need to be treated with caution right now. Those stretched creditors will need to be paid in early 2021. Hence we need to adjust the figures accordingly to arrive at the true underlying picture.
My opinion - I'm really pleased with this update, and am surprised the share price has not responded more positively today.
We can buy at 364p today, which is a better price than the recent placing at 380p, yet today's buyer has the benefit of a very reassuring trading update. Whereas buyers in the placing were buying blind (no financial information was given about current trading). I attended a virtual meeting re the placing, and was impressed with the clear strategy for growth via new product ranges, accelerating online sales, and expansion into Canada. Whereas in the past, I found the strategy too sluggish, and was plodding along using acquisitions for growth rather than developing the great brands they already had.
I think today's update has given me the confidence to add to my position when I have some spare funds (a fully committed elsewhere at present).
It gets a thumbs up from me. I don't see this share shooting the lights out, but do see it as likely to be higher in a couple of years than it is now, if management execute well. It's got through the covid crisis better than I expected.
.
.
Galliford Try Holdings (LON:GFRD)
Share price: 108p (up 7% today, at 11:40)
No. shares: 111.1m
Market cap: £120.0m
Galliford Try Holdings plc ("Galliford Try"), the UK construction group, today provides the following update on trading for the year ended 30 June 2020. The Group expects to announce its results for the full year in September 2020.
I'm very rusty on this one, not having looked at it for 4 years. So readers probably know the company a lot better than I do.
This bullet points really jumps out at me;
Well-capitalised, with cash at 30 June 2020 of £195m (2019: net debt £57m) and average month-end cash during the six months to 30 June 2020 of £140m.
Even the lower monthly average cash of £140m, is higher than the market cap of £120m. It's not often you see that. Although there could be corresponding creditors, if e.g. the cash has come from customers paying up-front? I'd need to see the full balance sheet to properly assess it.
I've just been looking at the last reported balance sheet as at 31 Dec 2019, but there's a problem with this - the big disposals didn't complete until 3 days after the balance sheet date, and no pro forma balance sheet is provided. I don't have time today to plough through the numbers, and try to reconstruct the balance sheet after the disposals.
Covid - seems to have had a nasty impact, as you might expect;
As expected, the combination of site closures and reduced productivity significantly reduced revenue in the final quarter of the financial year. Along with the cost of implementing our new operating procedures and lengthened site programmes, this has led to a material reduction in gross margin in the financial year to June 2020, with divisional operating margins expected to show a loss of c5%. Productivity levels on our sites have gradually increased since the beginning of the lockdown, and we start the new financial year with productivity close to normal and operating margins expecting to improve in line with our target.
Operating at a loss of 5% for the year, on quite large revenues, sounds pretty bad.
The group's strategy seems to have been disposal of the best bits, leaving a pile of cash, and a loss-making building business.
My opinion - neutral. There's not enough information for me to form a view. The cash pile does interest me though, so I'll have a proper nose through the next results when they're published in Sept 2020.
After the big disposals in early 2020, the remaining business seems to be a construction group targeting large mainly public sector contracts. That type of business often seems to go wrong - low margins, on large complex projects, just is not an area I would want to invest in.
.
Mccarthy & Stone (LON:MCS)
Share price: 74.75p (up 0.5% today)
No. shares: 537.8m
Market cap: £402.0m
This might take me a while to plough through the accounts, as it's the first time I've looked at this developer of retirement properties.
McCarthy & Stone (the 'Group'), the UK's leading developer and manager of retirement communities, announces its financial results for the six months ended 30 April 2020 (2020).
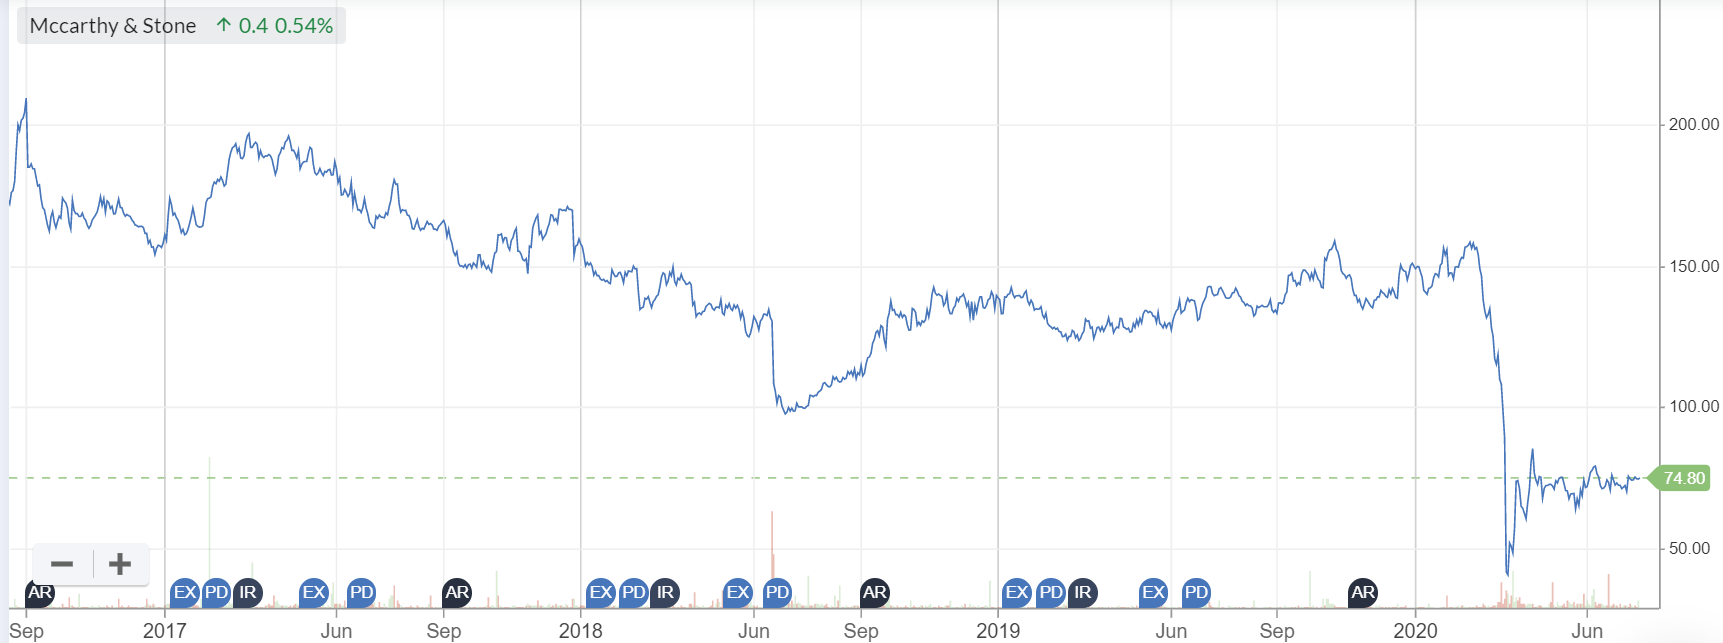
This company floated in Nov 2015. As you can see from the chart, it has been a lousy investment so far;
.
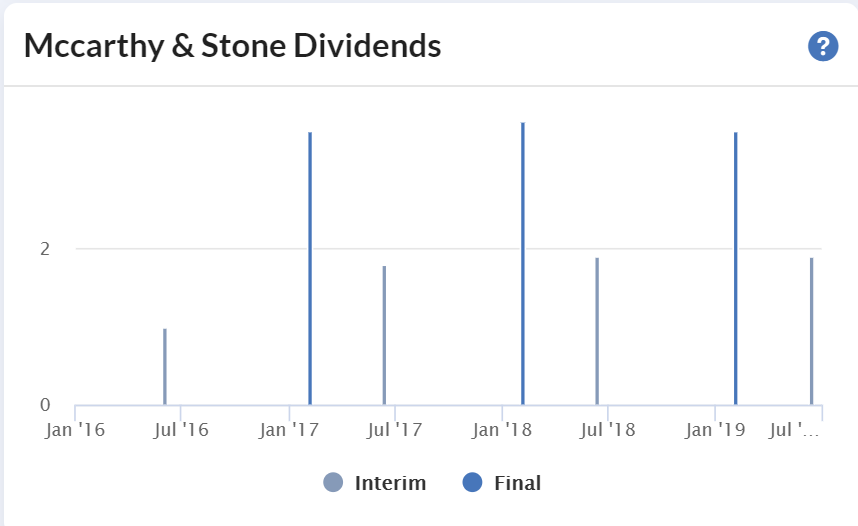
Although it has paid 17.2p in total dividends since floating;
.
Given that covid only really impacted the last month and a bit of this H1 (ending 30 April 2020) then I'm surprised it's had such a big impact on the numbers. Maybe that's because I imagine April would normally be a busy month?
A few snippets to give a flavour;
- Completions down 44% to 471
- Revenues down 64% to £101.1m
- Underlying profit before tax - a loss of £(26.9m) versus a H1 prior year profit of £18.9m
- There must be a ton of exceptionals, as the statutory loss is much larger, at £(91.3m). Yes, it's £60.4m impairment of brand & goodwill.
The above suggests to me that things probably were not going well before covid struck.
Covid impact - the financial impact is one thing, but the human impact is just as important here. I can see that, as a (probably the) leading brand for retirement homes, it's a key issue how it managed its sites. Sadly, care homes were not properly protected, with the NHS discharging elderly patients into care homes during the start of the pandemic, without testing them for covid, thereby introducing the virus into many care homes, killing large numbers of frail people. We experienced that in my family. It just swept through a dementia ward, killing nearly all the residents, including my sister-in-law's father.
Independent living is clearly a much better solution to protect the elderly, rather than communal living in a care home. Therefore I can see that MCS could be a big future beneficiary of this seismic change. These are very strong statements;
Responded early to Covid-19 with absolute focus on our customers and our people resulting in Covid-19 infection rates being 27% lower than the over 65's UK population and four times lower than the over 85's
o Currently only one confirmed case on our developments
That alone makes this share potentially interesting - this could provide a positive tailwind in future. Assisted living is clearly a much better option than a care home, where possible. It's not always an option though, if someone is too frail, and needs round the clock care.
Balance sheet - looks strong to me. NAV is £695.1m, with most of the assets being inventories (i.e. land & unsold properties in various stages of build, I imagine). Intangibles are only £4.3m, giving NTAV of £690.8m. This compares very favourably with the market cap of £402m. Why is it trading at a 42% discount to NTAV? That looks a very pessimistic valuation. Does anyone know why?
Outlook - some interesting stuff in here, although I'm worried about the H2 financial impact bit below, which sounds ominous;
Early activities demonstrate that sales leads and gross reservation rates are increasing in line with this gradual ramp up plan. While we are passed the peak of the crisis, the financial effect will be weighted towards H2. However, given the significant level of ongoing uncertainty, the Board currently have little visibility as to the expected FY20 outturn.
Guidance therefore remains suspended until we have greater clarity of the Covid-19 impact on the business and wider UK economy.
Throughout the pandemic, the independent retirement living sector has proved to be a safe and happy place for older people, and it is clear that it has an important role to play in the post Covid-19 world. It provides an alternative 'Third Way' for those needing assistance and there is now a real opportunity to redefine how we support our ageing population in future. Our unique proposition, unrivalled capability, strong brand and new land opportunities, along with the heightened focus from policy makers, ensures that we are well-placed to capitalise on this exciting opportunity.
It should also get a decent boost from the Stamp Duty holiday on under £500k properties. Therefore, H2 might turn out better than currently expected, I speculate.
My opinion - too early to form a firm opinion, as I've only just started looking at it. I like the strong balance sheet, and I particularly like the deep discount to NTAV. In normal circumstances this business makes a high profit margin, because it can charge more for retirement properties.
From what I've seen so far, this share looks interesting, and worthy of a closer look.
.
Air Partner (LON:AIR)
Share price: 85p (down 13% today)
No. shares: 63.6m
Market cap: £54.1m
AGM Trading Update
There's not a lot new in this update. We already knew from the previous updates that H1 performance was exceptionally strong, due to one-off work related to the covid crisis (e.g. moving PPE, and repatriation flights).
Outlook comments sounds more cautious today, but we knew this was coming, so I'm not sure why anyone would have sold today. Maybe sellers were hoping the bumper profits would continue for longer, or possibly they weren't paying attention to previous updates?
To date, the Group's trading in July has been more normalised and we have seen fewer emergency freight flights and less repatriation work. However, as previously reported, we are encouraged by the level of enquiries we are receiving from our customers returning to our Private Jet and Safety & Security products and we are anticipating a profitable month.
While we are very pleased with our performance to date in the current financial year, visibility for the second half remains limited, with economic and regulatory uncertainty from the impact of the COVID-19 pandemic. In line with this, we have undertaken a number of cost saving initiatives to reduce our cost base to reflect the likely future demand patterns for our aviation services.
That doesn't sound great, does it?
There's a separate announcement today about another contract win for its security division, which looks an interesting growth business.
My opinion - I feel positive about this company, but wouldn't be interested in buying at this level, because the bumper profits this year are a one-off.
That said, this could be an interesting share to hold if you think a second wave of covid is coming. Also, people who can afford it are likely to want to use private jets, to avoid hanging around in airports. So I can see this being a good sector to invest in. With a bumper H1, and a placing, then the cash position looks very comfortable. That increases the likelihood of decent divis in future. So it could be a good share for income seekers maybe?
Set against that, the outlook comments, and cost cutting do suggest that the future isn't particularly rosy right now.
Hence why I'll stay neutral on this one for now.
.
Carr's (LON:CARR)
Share price: 113p (up c.4% today)
No. shares: 92.5m
Market cap: £104.5m
Trading update & confirmation of dividend
That's quite clever, putting "confirmation of dividend " in the title of the RNS, eye-catching for income seekers.
Carr's (CARR.L), the Agriculture and Engineering Group, announces a trading update for the 19-week period ended 11 July 2020.
It's an in line update - remember them?! All the companies I've ever asked, have confirmed that "Board's expectations" and "market expectations" are the same thing.
Overall, trading remains in-line with the Board's expectations for the current financial year.
The Group continues to trade through the COVID-19 pandemic with no material financial impact seen to date.
That sounds excellent.
The agricultural division is doing better than expected, but the engineering division less so, being affected by temporary delays to projects, and less work from the oil & gas sector.
Cash is also ahead of expectations.
Divis - a 2.25p interim divi will be paid in October - a nice expression of confidence.
Outlook -
The Group remains well placed owing to its strong and diverse businesses, robust financial position and the ongoing demand across the majority of its markets for the provision of essential products and services.
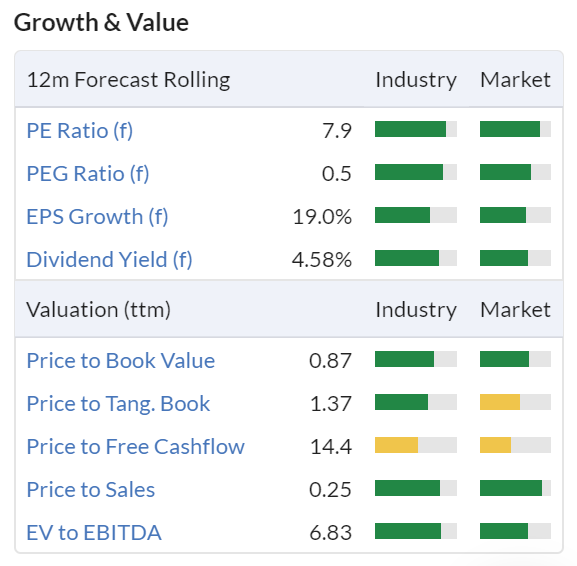
Valuation - since we've just had an in line update today, then that's the only situation where I would rely on broker estimates. at the moment Hence these figures are probably reliable, and it's a sea of green;
.
My opinion - looks a really nice value share, assuming nothing goes wrong in the future.
And finally, a reader has asked me to look at this;
Arcontech (LON:ARC)
Share price: 184p (up 13% today)
No. shares: 13.2m
Market cap: £24.3m
Trading update
This sounds positive;
Arcontech (AIM: ARC), the provider of products and services for real-time financial market data processing and trading, is pleased to announce that profit for the year ended 30 June 2020 is expected to be in line with market expectations.
Unaudited net cash at 30 June 2020 amounted to £5.01 million (at 30 June 2019: £4.06 million).
The Company has continued to invest in sales and marketing resources and confirms that no staff have been furloughed, and that the Company has not drawn on any publicly available funding or delayed payment of PAYE and VAT.
Subject to shareholder approval at the Annual General Meeting, the Board anticipates paying a dividend in line with the Company's dividend policy.
I've had a quick look at the StockReport, and it looks quite good - only tiny revenues of c.£3m p.a., but making a profit of c.£1m p.a. - a huge operating margin. In this type of (rare) situation, I find it always pays to check that Director remuneration is not artificially low. That can be a way of producing great profits, but on an unrealistically low cost base.
Growth - this is the crux here. If a business making a bumper profit margin can start generating strong growth, then profits can go through the roof.
Overall - looks potentially interesting.
All done for today. Sorry this report took a while to gestate, but I got there in the end.
Best wishes, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

114 comments
Reading comments today is like back to the future....
Its like 1999 all over again but actually even more bubblicious. In 99 most of the market cap wasn't in the TMT wonders....yeah they were on super high multiples of zero (haha)...but many were generally concept stocks or real tech business but with high endless capex spend (as they operated in a real world not virtual).
Blast from the past -> Amerindo https://en.wikipedia.org/wiki/Amerindo_Investment_Advisors
These guys were the genius asset management visionaries of the times. They were seeing the shapes that no one else could see. They were being drenched in $$$$....they went boom in hubris.
There were more mundane ones like Nordea's growth team. They created a 3 stage innovation discount model where the stage one was what you had today, stage 2 was what you were investing to create 3-7 years from now and stage 3 was the genius of innovation you earned and profited from due to your darn innate innovative soul...if you were right breed/culture/etc. That way they could justify infinity prices for Nokia. Alliance Capital were the US version of Nordea and bigger too...but the Scandis just did it with more panache...I actually loved them even though it was clear bs (they believed it of course)
Nordea and Amerindo where yesteryears version of ARK. I love ARK. They are darn smart and interesting....and its so their moment. They will be right about a lot of stuff but then fail to make money out of being right. By design they're not going to sell Tesla and buy US Bancorp when its time....and lots of their portfolio wont work out...zeroed capital. But they will be heroes whilst it runs.
But 1999 was a period of relative positivity about the broad future of western societies (particularly US obvs) and the mega multiple went into fairly mundane mega caps - Coke, GE, heck even some retailers and financials. Rates coming down and 'great moderation' also helping push up the multiple along with passive flows from mid 90s on and early quant-momentum strategies. Party, party, party!
2020 is more bubbly in the tech names. Not as they aren't real businesses (well some of them...is Uber a business or a p1ss take?)....its more bubbly as it posits an impossibility that the world is screwed except a few exulted futurist businesses. This is a mad narrative. It is an impossibility that our world collapses into these names. Mainly for financial and capital reasons...but also for social and political ones. The forces required to support that dimensional collapse into a handful of exulted names and those names to be stupendously dominant and valued would be like a societal forging and revolution like we've never seen before.
In my trading account I'm shorting mega tech. Not as I think its for sure peaked out but as I want to feel the burn as it goes up. I want to have the pain and lose some money (its small relative to proper portfolio). I want to feel the pain of resisting the 'inevitable' brave new world. I want to doubt my judgement and feel anxious about my views. If I capitulate I want it to be a hard won capitulation just so as I can feel even more disgusted remorse when the bubble breaks and I didn't stick with it.
Its really not about making money or being right. Its about pacing myself in the scream of the insanity.
I've got no idea when this ends....macro pimps the ride...up and down.
Yee-hah! Ride it boys and girls....or slip your Tesla into perpetual ludicrous mode....
Night night don't let reality bite
mojorealitydouche out
xxx
Looking forward to the publication (allegedly tomorrow or Friday) of Phase 1 clinical trial results from the COVID-19 vaccine being developed by the Oxford group in collaboration with AstraZeneca. The vaccine would not have been advanced to international Phase 3 clinical trials without positive safety and immungenicity results so the Phase 1 results will be positive. I shall be looking for any hints about the possible effectiveness of the vaccine and if these are provided, this could mark the beginning of the end of the pandemic.
Thx for looking at Arcontech (LON:ARC) (which I now hold). I am back home now and have been able to check Leon Boros now has a 4.033% holding.
Any chance you might have him back for an interview? I think you did a couple with him in one of which he mentioned £BVXP. In his recent PI World webinar he mentioned 4basebio 4BSB
So I think you might have a reasonable amount to chat about!
Can understand that you might be to busy.
Have a good evening.
Michael
Leon talks about Arcontech in the PI world interview. https://www.piworld.co.uk/category/education/leon-boros/
I don't own it, but fascinated by the company. I used to work for large banks in equity research, so I feel like I should understand the product...but I don't. There doesn't seem much background information on it, Bloomberg, Capital IQ, Datastream and the others have an Excel add in, so I can't figure out what Arcontech are doing that is so valuable.
Company does not seem to do investor presentations either, or at least not much available on website.
From their website, if anyone can translate this into English let me know:
CityVision Excelerator: A Tier 1 client sought to deploy a high performance transport layer for market data across the enterprise. There was a major issue however in that their incumbent Excel Add-in used by hundreds of internal consumers of market data was not able to talk to the proposed transport layer.
After testing Excelerator and another solution in great depth for over six months, Arcontech emerged as the clear winner in the selection process. Since then Arcontech has worked closely with both the provider of the transport layer and the Tier 1 client to build a bridge to the transport layer via Open MAMA and at the same time further configured Excelerator to meet the specific packaging and internal protocol needs of the Tier 1 client. Excelerator has now been rolled out to two hundred users on a global basis.
Arcontech (LON:ARC)
For any interested I actually used Excelerator about 10 years ago in what is now a FTSE100 company.
It's simply a clever Excel Add-on.
I remember being impressed with it, but the fact that the company is still the size that it is after all these years implies to me that underlying long term growth is limited.
As an aside I was also put off by the large customer concentration (59% with top 3 customers) and Asia revenue actually decreasing (27k to 2k - not sure what currency that's in from my notes).
In any case good luck all holders.
A
Hi Paul
Surely "Board expectations" and "market expectations" must be reasonably closely aligned. Any board which has expectations which are significantly different from market expectations would be exposing itself to legal action if it did not update the market accordingly, would it not?
Hi Sunday Trader,
Yes that's right. I've asked several brokers over the years why RNSs sometimes use the term "board expectations" instead of "market expectations". The reason seems to be that analyst forecasts are for the full year. Therefore performance during the year cannot be technically in line with market expectations, as brokers have not produced part-year forecasts. So they switch to "Board's expectations instead".
Personally, I think this is a silly distinction. Plenty of companies say that part-year performance is consistent with full year market expectations, and that's all we need to know.
Therefore it seems to be inconsistency between brokers, advising companies in different ways.
In a similar vein, some brokers fiercely tell companies that they cannot give guidance to the market. Whilst many companies do give perfectly clear guidance in their RNSs.
It's a big failing of the City - who are trying to protect their big fees, by being gatekeepers to information. Long overdue that the vested interests were swept away. Let's write to Dominic Cummings!
Regards, Paul.
Hi Paul, you wrote:
"It's a big failing of the City - who are trying to protect their big fees, by being gatekeepers to information. Long overdue that the vested interests were swept away. Let's write to Dominic Cummings!"
Are you implying that it's more effective to write to the unelected Cummings than to our elected MPs?
Well done Paul for an excellent and extensive report today. many thanks
cheers
Francis
I appreciate it, thanks Francis! Sometimes I need the whole day to let things gestate,
Anyone have a view on Ilika (LON:IKA) which has stormed upwards over the past few days on no apparent news. Solid state batteries are a hot tech area so maybe a bid is coming?
Last week's results included this
Operational highlights:
· Increased commercial demand for evaluation samples of Stereax® miniature solid-state batteries triggering investment in large volume manufacturing capacity
· Specified and ordered key equipment to support 70x increase in Stereax manufacturing capacity
Ilika (LON:IKA) is a serial disappointer that missed every one of its project targets listed in its IPO doc. It's kept alive on grants.
In 2018 an EPS profit was f/c in 2 years' time. Result: loss.
In 2014 an RNS was headed "Validation of Worlds 1st Solid State Battery". The co refused to re-issue the RNS when I pointed out it was not the world's first Solid State Battery.
It kept mentioning electric cars in RNSs when its cells were (and still are) many orders of magnitude away from such use.
I don't hold.
IKA...yes I think the mkt has just woken up to their statement of last week there they said they were looking to increase battery production by 70 fold. Not 70 per cent. "Specified and ordered key equipment to support 70x increase in Stereax manufacturing capacity"
As you say, hot area and closed at highs tonight so a bid at about 150p approx would not be a shock. Disclosure; holding
Ilika (LON:IKA) really doesn't know if it wants to be over or under the 100p mark today - could just finish directly on the £1 to keep everyone happy.
Round numbers do seem to be the strongest of all support and resistance lines.
$TSLA is interesting, yes the share price has become detached from its present time fundamentals, however its not the first time a stock has done so and gone on to prove its worth. It has also shown remarkable loyalty from fanboy like stock holders that have utter conviction in the long-game. The current share price performance is as much about it being misunderstood as a business and its previous under valuation than its seeming detachment from current reality.
Tesla is a vehicle manufacturer, an energy company, a tech and software company, an AI company and shortly to be a service company - ride hailing. It is also self sustaining, cash positive and experiencing exponential growth and with it, commensurate savings. It is a market leader in its field(s) in what are markets of huge growth. One eye opener for me on the vehicle side is the cost of production of the impending Cybertruck vs Fords F150, the best selling vehicle in the US. The Cybertruck will be 6x cheaper to produce than an equivalent F150. Also be aware it sells every car it produces, it carries no meaningful unsold inventory and is only constrained by production output, which is growing hugely, and not by demand (it has 500K reservations for the Cybertruck).
Wall Street appears to have awakened to its reality and we have seen a number of significant upside adjustments to analyst forecasts in the past few weeks. There is a lot of intelligent analysis on YouTube, and ArkInvest are one of the most bullish analysts on Tesla, and if you get time to read their analysis you will see how they deconstruct their valuation which presents a very interesting view on Tesla's business. The other factor is Elon Musk, like Bezos, he is fiercely driven and intelligent. It's no surprise that his other business SpaceX is embarrassing Boeing, NASA and to a lesser extent Blue Origin, by shaking up the establishment with other level, unconstrained thinking.
The 'Robinhood' spike makes great headlines but the reality is the share is not hugely liquid as they will likely be S&P500 within a few months and this will signal substantial demand from funds to buy Tesla stocks in their millions. Hedge funds are gobbling up what they can now with a view to selling on to funds and institutions upon such an event, and it is unlikely that Musk will sell his personal holding nor likely to have a new public offering (but if they did this would strengthen them by investing in new Gigafactory production), and the many small investors will hang on so we are likely to see another spike in share price. I can honestly see $2000 before this period plays out.
I wouldn't risk shorting $TSLA. In fact I am long and will hold for at least a decade.
This smells like a stock pitch from 1999!
This smells like a stock pitch from 1999!
I would disagree - it sounds like pitch that matches the great company sucess stories of the last 20 years like google/facebook/amazon/microsoft etc which have all been very expensive on old skool metrics. Most 1999 tech stocks had no material level of sales ! - Tesla certainly does.
You can't doubt the technical lead that Telsa have compared to all the other car companie - sorry that's poor wording - i would say you are probably wong or uninformed if you doubt the technical lead that Tesla has over all the other car companies. Their eco system to me is very akin to apple IOS and look how that worked out of Apple. I sold my Telsa shares on valuation concerns around $370 (they halved after i sold so i was kinda right at the time) and i can't argue with anyone backing against them on valuation grounds alone but the reasoning laid out by Thunderball makes complete sense to me and matches my view of how well Tesla will probably succeed - nothing is guaranteed though you just have to look at Nokia to see that any company can come a cropper for slightly random reasons
You should listen to Bethany Mclean's podcasts on SolarCity and Tesla. Then see if you are so keen.
Technical lead.
They can’t even get the panels to line up or the paint to stay on.
It’s a mixed bag. The electric drive train and controls are years ahead of everyone else. The suspension and ride quality are great. They seem to really mess up on the rest of the process of turning that platform into a vehicle.
But I just viewed a YouTube review by Rory Reid of the new Mercedes EQC. They have retrofitted an electric drive to the existing platform. It weighs 2.5 tons, the Center of gravity is too high, and it struggles to go round bends. So nowhere near Tesla even though it looks good.
IGotPoesJacket
Technical lead.
They can’t even get the panels to line up or the paint to stay on.
I would agree the quality of the paintwork and to a lesser extent the panels is the big weakness in their production at present , somthing i would expect them to address over the near short term.
However the fact a business has a couple of weaknesses doesn't mean it doesn't have many more important strengths - if you want to get an impartial overview of where Tesla are look at the Sandy Munro teardowns on youtube of the Tesla. I doubt there are many more knowledgable than Sandy when it comes to critiquing cars and its reasonably clear that overall he is very impressed with the direction Tesla are going in.
Sure, but the simple fact is, most people aren’t fan boiz and won’t put up with poor build quality and poor service.
When you’re trying to compete with well built cars with similar ability to go the same range, like the ID.3, ID.4, i4, the Mach-E who are cheaper, you can’t afford for anything to be shoddy, especially when you try to state your car is “premium” but it isn’t even painted properly.
The big advantage is the super charger network. As someone in the market for an EV, that’s the only reason I would consider a Tesla. But Musk needs to leave first.
I see a couple of major threats to Tesla. Persistent lower petrol prices and lower household incomes would delay consumers switching to more expensive electric cars. Cash strapped governments may not continue to subsidise EV purchases. Many of the major car makers are investing big on fuel cell vehicles could make heavy range limited battery EVs such as Teslas obsolete in the medium to long term.
Agree with Momoko. In addition, fFuel cell technology (once it has a decent enough range, e.g., 1500-2000 miles perhaps?) and the infrastructure to change/recycle them, will be what really boosts EV vehicles imo. That, or a significant rollout of national infrastructure to support recharging of existing tech vehicles, as we're slowly seeing (e.g., lampposts doubling up as chargers).
I think an EV today is very much a nice to have for most people. Putting cost aside for a moment, the obvious practicality of the need to charge regularly and often is a problem for many. Unless you live in a brand new block of flats (where even then chargers are limited), or you have a driveway/offstreet parking where you can easily install a charger, or maybe at work you may be able to get away with charging... the process is still generally prohibitive for most. Can you imagine a terraced row of houses with no off street parking, wires/cables dangling across the pavement every few meters? Repeated row after row of street? Or perhaps people who live in older style blocks of flats where there is no practical way to get a cable to the car to charge it. It'll come eventually, but I think it's slowly getting to the point where infrastructure will first need to grow to support the current gen of EVs, before the next gen (fuel cells or whatever trumps that) slowly becomes available, affordable, and then finally established.
Infrastructure throttling is a valid point however don't tar the rest of world with the UK's poor infrastructure implementation record (take a look at UK broadband rollout vs rest of the world). China is Tesla's biggest market and they are more progressive, and America is way ahead of us. I would add that Tesla has the best charging network in the world, and the UK - its Supercharger network which coupled with Tesla battery technology advantage, offers massive charging speed benefits, which is only part of the technical advantage.
The road to significant EV adoption is long, say 7-10 years, but it will happen, it is already happening and Tesla's advantage strengthens their hand every year that passes as the EV market grows. They also only have a small % of their product sector but dominate the EV market with significant technological advantages and lower production costs, which is a significant factor.
Government subsidies only apply to sub £50K vehicles, all manufacturers face this, but the over £50K market is generally where most Teslas have been to date so its not affected them to date. However as Teslas are significantly cheaper than other manufacturers at present, this is an advantage. Tesla have yet to compete in small vehicle markets as they are choosing the more profitable sectors to create a halo around the brand. Tesla cars are designed as 100% EV and not a bastardised combustion engine vehicles. This is a advantage in many ways too in both successful design/product terms, and price.
Unfortunately I don't have time to answer all the valid points raised but the Tesla advantage should not be assumed to be just numbers of vehicles sold comparatively vs other manufacturers as their business model is multifaceted. The commercial vehicle and taxi business models using EV's have staggering business case advantages. And its autonomous fleet using its massive AI advantage will take eventually compete with the Uber/Lyft market too.
Don't forget the solar and powerwall business. This is massive and growing too.
There is no commercial vehicle.
There is no taxi business.
There is no autonomous fleet. Tesla are last in several surveys into the major companies researching self driving cars.
All in the roadmap and baked into [some] analyst bull case forecasts
We call that “vapourware”. You’re paying today for something that doesn’t, and probably won’t ever, exist.
..
To say nothing of the competition. Although Tesla is selling more cars, revenues have been falling as the prices are falling. I'm about to buy an EV - its a Hyundai Kona. Very nice, well equipped, good range. Lots of car companies like Volvo and BMW about to come our with new models.
KGB1953 I hope you enjoy the Kona. The only issue I have with many ev s is they are SUVs which are by design a heavy car and using much more energy than lighter cars. One of the key tenets to environmentalism is not only moving to more renewable sources of energy but that we use less. I hope you don't take this as any form of criticism more an observation which your comment made me think of.
TL:DR go look at @teslacharts on Twitter.
Wow, you’ve swallowed the kool aid good and proper.
The stick is being manipulated higher by someone making large calls early in the morning when trade is thin to give the impression of momentum and suck quants and momentum traders in.
It’s now bigger than every auto manufacturer except Toyota, COMBINED. Yesterday in the intraday swings, it gained nearly a whole Ford, then lost more than a whole Ford before regaining nearly a whole Ford.
It makes huge losses, the average selling prices are falling and the stafement “its more than a motor company” when 95% of its revenues are from the motor business is laughable.
It is not self sustaining, it is not cash positive and it is not growing exponentially. There are large amounts of related party transactions.
The last 8 quarters have seen a decline in sales and the average selling price is falling. Earlier this week it was forced to cut the selling price of a vehicle not 3 months old by 5%.
The not road legal in a single country, Clusterfk, will not cost 1/6 of the price to build of the F150. You’re in a dream land.
If it carries no meaningful inventory, why are there hundreds of photos taken in the last week of Tesla lots overflowing with cars?
I could go on destroying your case line by line by I’m not even halfway through and I’m bored. Last point, just look at how much outstanding litigation there is against the company, including the Solarcity trial. It’s so bad the directors can’t get insurance.
By your response I can only assume you are disgruntled Shorter? I am not going to get into a argument, but I hold Tesla, and only after a lot of research. The references I make are facts that are freely available to those who which to look into it. It was also based on the caution of more casually informed opinion that prevails amongst those who lazily compare Tesla’s business against conventional car manufacturer's.
I will add some items for clarity and context: my opening comment was about Paul shorting Tesla. My first paragraph stated that the current valuation is detached from its fundamentals, I am not arguing this point or trying to justify it, far from it. The point I was trying to make was that it was possibly foolish to short Tesla at the moment due to the impending S&P500 listing and its liquidity issue where I see the price only going higher on the trading update due on the 22nd if, as expected, they post a profit in a difficult QTR. After all they beat Wall Street production estimates by 30% last time which coincided with the last big bump. My sentiment around shorting and Tesla’s real value has nothing to do with the current share price. It’s only my view. My Tesla holding can fall a loooong way before it loses money.
But the statements I made are not from “swallowing coolaid good and proper”, it is information out there in analyst reports, journalists and matters of fact. Tesla is a growth company, its financials are completely different to established mass market car firms. Tesla, like many tech growth firms, are heavily reinvesting to ramp production facilities and establish market share.
Tesla production is centred around their 4 Gigafactories. The Gigafatories are being built on a roll-out basis are growing production every year. Significant efficiency improvements through investment are being realised year on year at established Gigafactories which is also improving profitability and production volumes.
Tesla doesn’t have meaningful inventory - look at their own website which will offer only a handful of completed units in each model. Also inventory aggregators such as Tesla-info.com/inventory will show you what new stock is available - basically nothing. Try any other brand and see what its says?
Sales are growing every year despite your assertion otherwise, see here: https://cleantechnica.com/tesla-sales. Free cash flow is over $1B. It has been ‘profitable’ for the last 3 qtrs and likely this one too despite Covid. But declared profit only just enough to assuages the shareholders, the real ‘profit’ is currently better employed on R&D and cap ex. That has served Jeff Bezos pretty well to date.
They will be best placed to be first to market with fully Autonomous driving because they have invested heavily in the technology. Every Tesla on the road already has the cameras and tech on board and is sending data back to Tesla HQ Consequentially they have over 2billion of miles of data vs second placed GM with 1.3m miles. They will likely achieve licensing ahead of everyone else.
Tesla’s commercial vehicle the ‘Semi’ is due for release in late 2020 and only delayed due to battery shortage. This is fact.
Average selling price is declining because Tesla is entering the volume market and its niche £80-100K Models S & X are being dwarfed by the mid market Model 3 and Model Y. They cant build them quick enough. They will only enter the lower priced, lower profit sectors of iD3 & 4 when their production facilities are in place.
Why take my word on the Cybertruck cost vs Ford’s F-150, I am only referencing respected industry expert Sandy Munro’s Munro & Associates assertion that the Cybertruck was ‘genius engineering’ and owing to it using high grade stainless steel in flat panels as a exoskeleton, it used little cost and resource on forming body panels and no requirement for a paint shop (a major production cost). Read it here, its not my “dreamland”:
Vehicle teardown and costing guru and the CEO of Munro & Associates Inc. just appeared on the Autoline After Hours show and presented his expert analysis on the Tesla Cybertruck tooling costs and estimated capital expenditure (CapEx) on yearly production.
Interestingly he compared the CapEx of the Cybertruck vs. Ford’s F-150 with respect to an annual production rate of 50,000 and 600,000 units — according to Sandy Munro, at the rate of 50k units the Cybertruck CapEx will only be $30M a year while for the F-150 that is $210M and if Tesla succeeds in producing and delivering 600k Cybertrucks a year, the CapEx for Tesla will only be $125M vs. F-50’s $615M.
Tesla Cybertruck can be produced at only 15% to 20% CapEx compared to a Ford F-150, this gives the Cybertruck a huge cost efficiency advantage and big potential for being profitable, the simple design and straight lines of the Cybertruck are a winner here.
As I mentioned, Teslas advantage is multi faceted and their superior Supercharger network and battery technology which squeezing more real world miles out of their batteries than anyone else and ability to charge far quicker is part of it, you admitted as much yourself.
DYOR.
"Yesterday in the intraday swings, it gained nearly a whole Ford, then lost more than a whole Ford before regaining nearly a whole Ford"
I found this genuinely hilarious! top marks. Also quite outstanding statistics to get your head round.
..
$2000 dollars this year, in fact maybe within 3 months. It was $1760 on Monday briefly.
God knows where it will be in 10 years, thats a whole new world, and one they are best placed of all current manufacturers to take advantage of.
There is the TSLA Q. crowd...... Basically saying bankrupt! No one makes money long term out of cars. Their operating margin is 4.7%. Have you seen their accounts? Profit from selling emission credits were more than the income from selling cars. SolarCity and the 'promise' to have a million solar roofs?
I rarely make requests and suspect I am too late now but do you have any thoughts on Arcontech (LON:ARC) who issued an inline RNS today causing shares to rise 20%.
I used to hold and have re-entered today with 1% (re-)starter position. I believe Leon Boris has a significant position.
Thx.
Michael
For any who follow Open Orphan (LON:ORPH) and this morning's option to buy "CHIMagents Limited" does anyone know why there might be no record of a Ltd with Companies House?
Based on the CEO's LinkedIn page (here) it looks like the company has only been in operation for 2 months.
This looks like a red flag. Thoughts from any observers appreciated.
A
It is recorded at Companies House but with minimal information since incorporated 2/6
https://beta.companieshouse.gov.uk/company/12638260
Open Orphan (LON:ORPH)
Ah, thank you. It seems that the company incorporation is so recent that Google hasn't yet had a chance to scrape the Companies House page yet!
I think the fact that Open Orphan (LON:ORPH) have announced an "option" to buy a company that is <6 weeks old is enough to rule me out.
a) Why not just buy it?
b) Why buy anything that has just been incorporated?
I'm sure there might be a reasonable explanation, but I'm already put off by something that appears unnecessarily complicated.
GLAH
It's being acquired for a nominal sum. I view it as an "acquihire" - buying the company to get the people.
Re: £Boo
Thanks for your additional thoughts on them today Paul and for your coverage of Galliford Try Holdings (LON:GFRD)
One question: have you thought about interviewing Mahmud Kamani? I believe he would be open to such a request (given your support of Boo over the years) and it would be amazing for us readers to get his perspective.
cheers
Francis
I doubt whether Mahmud's minders would let him do an interview!!! I would also have to invest in a bleep machine :-)
Hi Paul, I gather that Tom Winnifrith has recently interviewed him so perhaps Mahmud would be amenable?
cheers
Francis
Great comments on Boo as always, thanks Paul. Tom Winnifrith spoke to Mahmud last night for an hour and then talked about it at length in his bearcast today... I think everyone here would be far more interested in any interview ‘you’ do with Mahmud so I’m all for it! If he’s willing to talk to Tom, hed be a fool not to talk to you
Thanks for the comments on Boohoo (LON:BOO) with which, for what it’s worth, I agree and I have just topped up to a 5% position. With my new mindset (post March where my over weight positions caused me to melt down and sell) this is my maximum position unless I feel particular conviction to give a stock a higher allocation. Renewed momentum in Boo would be a reason.
Regards
Michael.
If i have a particular view on a market or index, I will often express that opinion via a short or long ETF. There are also leveraged ETFs out there that do the trick and although its a punt on direction it can be useful if you are so inclined to do so..
Anyone got any views on £ptal
They seem to be at a low point at the moment but resuming operations later this month... Wondered if anyone had any insights?
TMG ?
Re £PMP. I read the update as saying they received £11.2m and repaid c.£2m of debt. I think some of the rest will be to fund losses rather than going into cash. It’s got a PE of 6 but accounts show EPS has been declining. Cheap but hard to get excited about as a potential investment?
Re Portmeirion (LON:PMP). I read the update as saying they received £11.2m and repaid c.£2m of debt.
I initially misread the news at first and presumed they had only reduced the debt by 2 million and spent the rest (nearly made a fool of myself yet again) - stangely i kinda convinced myself this was a plausible outcome which shows what strange times we are in.
If we look at what the release says.
Our balance sheet remains strong and excluding the benefit of net proceeds from the equity raise of £11.2 million, we have been able to reduce net debt from the 31 December 2019 level of £12.3 million to just over £10 million.
They specifically say excluding the benefit of of the net proceeds - so i am prety confident the debt came down completely ignoring the £11.2 mill that came in - which is an unexpected bonus - albeit its a 1 digit numbers game when you have their losses - so presumably the payables have increased or there is some other change to the value of whats on the balance sheet that will impact cashflow at some stage. I am guessing they have potential for some positive cashflow benefit from intangible w/offs/amortisation.
Ok but how did they find their losses? Why would they need £11m cash?
Portmeirion (LON:PMP)
Ok but how did they find their losses? Why would they need £11m cash?
do you mean fund their losses?
as per my previous post they would have funded their losses by a mixture of things - mostly likey by increasing what they owed out in payables. a big chunk of this is likely to be deffered vat.
Other possibilities are reduced debtors or reduced inventories etc.
Why would they need £11m cash?
good question
first up as a company that is likely to make nil profit this year and has £10 mill of debt they may have been under pressure from their bankers or had worries about the future viability of the buisness in these unknown times.
There are also the specific reasons they provided at the time of announcement - all of which sort of make sense in a waffly kind of way.
accelerate all online channel sales growth and increase next day delivery warehouse capacity;
· extend the Wax Lyrical line to hand and body products;
· build a more significant presence in Canada and revitalise the Canadian market;
· invest in UK manufacturing efficiencies driving improved operating margins; and
· maintain a strong balance sheet.
Re Portmeirion (LON:PMP) - I could be making this up but I think they have also previously spoken about being open to small acquisition of either complementary brands or distribution partners (having done so in the GFC). It's just a not a core plan. Having raised the cash, they will now options if things turn out a bit better than when they decided to start the process of raising money (when armageddon was still a possibility). There must be lots of little distressed candle/glass/decoration companies in their space right now.
I would rather they focus on driving organic web sales which I see as the best medium term opportunity but they should keep their eyes open for opportunities.
(Always interesting to think the other way; now with more cash and a low price, are they themselves an attractive target. Paul has suggested this before. I think there will be lots of M&A activity in the next 12-18 months, especially if you include takeover of companies in administration or taken over by banks and sold.)
Yes I'm pretty sure I reported the Portmeirion (LON:PMP) cash position correctly. I'm careful about making sure I've correctly understood everything before writing about it. Occasional errors do slip through, but not in this case.
It would be good if companies would provide a pro forma balance sheet after the equity / debt raises.
That is an interesting comment about Boohoo (LON:BOO) and whether as investors we too should think ethically, or should investors just be interested in profits?
I try and be ethical in my investments, there are certain industries I wouldn't invest in, however looking at my portfolio now I am nowhere near being 100% ethical.
I still don’t see the value case. It’s in a PE of around 40 and the shares are higher than this time last year. I think people are fixed on the run up to over £4 and may be kicking themselves for missing out and hope it will go there again. Just as likely to go back to £1.50 and I can’t see it as investible. One for the day traders.
It's a growth case not an immediate value case. You are paying for future growth. Even so, the shares being higher than last year surely means better value than last year (or less bad value if you prefer) since the business has grown since then and global revenues are up?
There's risk and an uncomfortable rollercoaster, but even so most brokers - including some who have cut their forecast-agree it is oversold at present.
I haven't been kicking myself because never really analysed Boo before this. Wasn't aware of the run up to 400p, but have looked and see it as a reasonable entry for the global growth opportunity
£NXT has a PE of 10. Why would you pay four times that for Boohoo (LON:BOO)? At this time.
Because Next is on a forward looking PE of 20, Boo is on a forward PE of 26. Next EPS growth forecast is -33%, Boo is +37%. Because Boo taps into social media effectively and has a global reach and is bolting on brands into its infrastructure. Saying that I like Next too - it's solid, I believe it's a bit undervalued but not hugely, but I still like it as a business.
Why would I pay more for BooHoo? Because I believe in it's future growth, and that expensive now will look like value later.
As Munger, I think, said growth and value are joined at the hip. One does not by a value stock in the hope that it won’t grow or a growth stock that you don’t consider to be good value.
£AMZN is the classic example of this. I looked at this for my son’s JISA in 2015. I knew was a growth stock but also assumed it couldn’t be good value. It has 16 bagged since then.
Boo is a growth stock and at the current price good value based on that future growth.
I hold
Regards
Michael
More or less all Amazon's increase in profit and value comes from Amazon Cloud Services. Where is the comparison with Boohoo (LON:BOO)?
Boo global logistics, infrastructure and marketing engine. That's why Boo bought Oasis and Warehouse.
It is that Amazon has been A growth stock and considered over valued almost since IPO’d but history has proved that not to be the case.
I first bought Boo in 2015 for 37p when it was considered to be over valued and I think it is fair to say that many commentators have said it was over-valued from there all the way up to 415p.
Not really Paul's sort of company, but I thought the trading update from Capital (LON:CAPD) was better than expected. They still don't quantify the COVID cost impact, but this seems to be moderate and improving. Stocko rates it an SR of 91. I topped up this morning.
Yes similar with Major Drilling Group, MDI in USA. There should be a cyclical upturn in metals drilling if precious metals stay high and other metals esp Copper are recovering.
Re the Robin Hood investors, a list of their most popular holdings was included in John Authers daily note on Monday.
Curiously it would appear that these so-called speculative investors are drawn mostly to 'old-world' cyclical stocks rather than NASDAQ/FAANGS.
Top five : Ford, General Electric, American Airlines, Disney, Delta Airlines
There was some speculation that Ford in particular was being pulled along in the Tesla slipstream. Bloomberg reports that....
"Almost 40,000 Robinhood accounts added shares of the automaker (Tesla) during a single four-hour span on Monday,
If this is correct it is quite astonishing.
Interesting article on the Telegraph last night - "Fast fashion firm Asos (LON:ASC) axed contracts with a string of clothing suppliers after it uncovered possible serious threats to workers' health, safety or human rights. The company's inspectors found major ethical breaches at almost a quarter of suppliers visited in 16 countries, including seven sites in the UK, according to a 2018 report leaked to the Telegraph."
Boohoo (LON:BOO) aren't the only ones impacted here and I'm sure more companies will be added to the list.
Reference - https://www.telegraph.co.uk/business/2020/07/14/asos-axes-almost-quarter-uk-suppliers-ethics-worries/
This reinforces the point that the ongoing mess in Leicester has lost jobs to abroad because ethical companies who want to buy in the UK cannot place business there.
This reinforces the point that the ongoing mess in Leicester has lost jobs to abroad because ethical companies who want to buy in the UK cannot place business there.
When the new government customs control processes come into force - and it appears from what Gove is saying that they'll apply deal or no-deal - you'd think that would make sourcing from abroad both more expensive and slower. So if the current investigations force better standards in Leicester then perhaps there'd be more demand for their services from higher end suppliers who are willing to pay more.
I've no idea how that that might impact Boohoo (LON:BOO) although I suppose it might increase local costs at the same time as making overseas sourcing slower and costlier?
timarr
For anyone wanting to listen to a thoughtful bull case for the market recovery.
https://podcasts.apple.com/us/podcast/bill-miller-on-the-classical-value-portfolio-podcast/id730188152?i=1000484057025
Bill Miller beat the S &P 500 for 15 consecutive years, a deeply rational man worth listening to.
I received this today from my broker (HL) - ingenious scam, I thought others might be interested.
Ponos Industries LLC (‘Ponos’) has announced details of a Mini-Tender Offer for up to 2 million shares of Verizon Communications Inc (‘Verizon’). As you hold shares in Verizon we are obliged to notify you of this offer but wish to draw your attention to the unusual conditions and risk warnings outlined below:
The Tender Offer price is USD60.00 per share. However, the offer is conditional on the price of Verizon shares going above USD60.00 and Ponos could extend and delay the offer for an infinite amount of time until the share price of Verizon is above USD60.00. If you give an instruction to tender your shares, you could have your shares unavailable to you for an unspecified period of time (until the share price goes above USD60.00) and you would have no rights to withdraw your election. You are therefore likely to end up selling your shares at a price lower than the market price at that time.
Verizon is in no way connected with the offer and recommends that Shareholders do not tender their shares. A full statement from Verizon is available at https://www.verizon.com/about/news/verizon-mini-tender-offer-ponos.
The U.S Securities & Exchange Commission has also issued an alert concerning ‘Mini’ Tender Offers of this nature, which can be found at http://www.sec.gov/investor/pubs/minitend.htm.
Paul: "The alternative is unemployment."
Probably not an either / or. There is evidence that many people in such situations claim unemployment benefit with a nod and a wink from the employer. I've read the same about the Boo issue.
It does raise the issue of Basic Income. I can see the arguments both ways, but in this case if you had no minimum wage but introduced a Baisc Income scheme, then you would probably generate more of these jobs at little cost. In this case the workers would simply be taking their Basic Income instead of their unemployment benefits.
Finland trialled Basic Income and it seemed to fail to generate jobs, but that may well be because of the Finnish jobs market and the way they set up the trial e.g. as I understand it they didn't change any of the condititons that would have encouraged employers to create jobs, such as minimum wage.
Unless something changes many countries are soon going to be looking for radical ways of creating jobs. I don't think we've heard the last of Basic Income but unless someone tries it on a holistic basis including dumping the minimum wage then I can't see it working.
Interesting point. I wonder how people would be able to claim unemployment benefit and work at the same time? My understanding is that the rules for Jobseekers Allowance are quite tough, and people have to provide proof that they're actively applying for jobs, otherwise the benefit is withheld.
I heard that companies can breach minimum wage by putting reduced hours on the payslip. i.e. if someone works say 40 hours, at £3.50 per hour, then it's shown on the payslip as something different, e.g. 16 hours at £8.75 per hour, thus appearing to meet regulations.
I wouldn't be surprised to hear that half the workers in these suspect companies are completely off the Books. Some owner/directors are very deceitful types enjoying the high-life and bling that goes with it.
Silver Moon
My view is that there is a strong and good argument in favour of a minimum wage. The UK should not be engaged in activity where it is genuinely unviable to pay more than £3.50 an hour.
Singapore vastly raised its minium wage many years ago and found the effect was a big boost to productivity.
Here in the UK, having a reasonable base wage incentivises employers to invest in manchinery, IT, training and organisation such that productivity increases. In turn this leads to a prosperous economy.
Very basic textile production where it is unavoidably labour intensive most probably has no real role in the UK economy.
Reading about Boo, I'm not especially concerned about the PR damage from the low wage scandal. It will probably be forgotten quickly. Rather more worrying is that it seems to be a family company headed by a charasmatic individual,and with cross family business dealings involving the PLC. In my view these are where the risks mainly lie for PLC shareholders.
Re: Basic Income
As Michael Portillo has pointed out, our electoral system pushes even right-wing parties to over-promise on spending pledges to bribe the electorate, so that we perpetually live beyond our means and sink further into higher national debt. Southern European governments took it to extremes, e.g. allowing civil servants to retire at 50 on full and generous pensions at the tax-payers' expense. Basic Income largesse at the tax-payers' expense would become an electoral arms race. That's why I, reluctantly, decided I couldn't support the idea.
Re Portmeirion (LON:PMP) - relative to others (ie still bad !), a neutral trading update today shows H1 (Jan-June) sales down LFL -20% (-8% incl Nambe). Net sales still down 9% in June in a heavily operationally geared business but with most of its volume/profit in 2nd half, no real insight into medium term despite some warm mgt words. In profit terms, " low single digit £ million loss before tax" (so £3-5MN?) in H1 and 'profitable ' in 2nd half if no major new catastrophe. So <1 year profit wipe out - not great but not terminal. At least no news of major overseas distributor problems or bad debts - my key worry for them.
Highlight is clearly the >+90% increase in own website online sales, a declared key strategy (and an opportunity historically underplayed by a company selling gifts/ collectables!). I like that Nambe, acquired July 19 added £2.9Mn as I think this good potential to be rolled out globally and is complementary and more modern than other brands. (I fear that UK "history" brands like Spode will suffer as Britain's status/reputation declines. The new 'middle aged spenders" globally do not see Britain as clearly as 20 years ago and I think population/economic shifts will drive this further. This is especially true in key market US where Anglophile East Coast WASP are declining in economic influence vs Spanish/Asian populations with fewer cultural links to the UK.)
Having raised £11.8Mn gross in June 20 via an equity placement at 380p with roughly 25% dilution (& whose open offer to small shareholders was only 55% subscribed), no risk to go under but doesn't look like a fast winner in a global recession. Easy to avoid buying a new salad dish but equally may benefit from stay at home / home cooking gains and sterling weakness vs dollar.
I am happy to hold for a steady recovery as key brands brands stil have long term value but expect that will take a couple of years.
Portmeirion (LON:PMP) trading update today.
I have recently topped up here (hmmm reminds me of the film dumb and dumber not sure why) as the company has raised fresh funds so will hopefully be in a less precarious position. seemed like the right thing to keep my % ownership reasonably intact by handing over more cash despite being over 505 down on my fisrt lot of cash i handed over!
Ok they raised a tidy £11.2 million in June - and have advised excluding this sum debt has reduced from 12 mill in december to just over £10 mill. So that is a decent covid/war chest they have or should we say their bankers will sleep happier at night.
Low single digit loss (is that one finger up in the air method of financial planning?) in H1. Note h1 is seasonally low 6 months they only made £0.5 mill profit last year h1 and ended up with £5.8 mill profit at year end.
What about the h2 ?
we are confident that we will return to profitability in the second half of 2020.
Hmmm - not giving much away are they - i should damn will hope they are making a profit H2 - so not exactly shooting the lights out with their optimism.
at £50 mill market cap - i am a happy to slog this one out - hopefully post covid £5 mill profits + will be be back on the table - then they just need to push the buisness forward and get their mojo back.
Can Portmeirion (LON:PMP) get back to its former glory days? I wonder; while having bought into the placement to add to my holding, I decided and extended my investment in gold miners today.
Silver Moon
Paul - I would be interested in your opinion of AFX trading update this morning.
Still growing through the pandemic, net cash - growth not fully factored in here?
I'm an Alpha Fx (LON:AFX) holder and I like it when companies are proud and confident enough to give back the government furlough money.
Following the outbreak of COVID-19, the Group took the decision to utilise the Government's furlough scheme. The Group furloughed six of the 113 staff employed in the UK at 31 March 2020. As the situation has become clearer, and in light of current performance, these furlough payments have now been repaid to HMRC.
Sorry, I don't cover companies like Alpha Fx (LON:AFX) . I think Graham might have looked at it before?
I think mask discussion should be a separate thread, everyone will have a strong view so id suggest creating a thread if you want to discuss that (lockdown thread worked well to keep this focused on companies) And i am finding it difficult to not give my view having just been muzzled in spain if stepping out the front door, damn, failed.
Paul could you give us your opinion on Galliford Try results today?
I suspect Galliford Try Holdings (LON:GFRD) won't be on your radar Paul but would love your view if you feel inclined. Mkt cap of £112m, net cash £195m and 90% of revenues already booked. I can't fathom why the shares are so depressed apart from the obvious (low margin, lumpy contracts, construction etc) but irrespective of this, there does seems value here at current prices.
Cheers
Francis
Look fantastic on the face of it and I hold.
Net cash figure of £195m could be potentially misleading due to VAT payment deferals .
The average month end net cash figure of £140 millions is the one I would use. Even using this lower figure, compared to a market cap of £112 millions (Stockopedia figure) before start of trading today, the mkt cap is 125% covered by cash. Stonkingly cheap on the face of things.
Who are you talking about please?
Another request for GFRD. "Since January 2020, the Group has operated with net cash, and with no debt or associated covenants". It seems to me that if you are going to be in this sector, this company must be on your list to consider..."the strong order book, with 81% in the public and regulated sectors" so perhaps less risk. Hit an all time low just last Friday so plenty of possible upside after this update and maybe limited downside with so much cash and no debt.
One reason may be caution.
I recall they bought a company that built some Scottish schools and basically the walls fell over under high winds. That was some time ago but some may think there is more of that lurking.
Galliford Try Holdings (LON:GFRD)
One question i would have is has this construction entity made profits if we look at say a five yera period? If it has made didly squat over the last 5 years whats the reason for believing things will be better going forward?
Having said that i would have semi confidence that the next 5 years may be better than the last 5 years which have been ridiculous with all the outsourcing companies having chased turnover at the expense of profit - paid the directors millions and then all pretty much golne pop. I would like to think that there may be less stupidity nin that regard going forward - i would be slightkly worry though as all it would take is for the Chinese to turn up and all they require is that steady cashflow leaves the uk and ends up in China - thats all too easily done in this sector leaving creditors owed the money that has departed to China even if the company has made nil profit. I would say taht potential is a bit of a conspiracy theory of mine - i have no specific reason to believe this would actually happen - other than its potentially an easy money making route.
On GFRD...I fully agree with Paul's comments above that construction is not a great place but I have also read today that following the sale of the housebuilding arm and return of cash, there is always the possibility that the company could sell the rest of the company to a much bigger competitor for decent money and return something like £2.40 per share in total in cash. That cash pile is a very large cash pile and my main reason for being invested.
Galliford Try Holdings (LON:GFRD)
That cash pile is a very large cash pile and my main reason for being invested.
barnetpeter - do you have any idea of what % of that cashflow is actual real cash that they could just do with what they choose. Companies like Galliford Try Holdings (LON:GFRD) often run super pimped up with large liabilities - if there was no cash buffer on the balance sheet i guess they would be a lot less creditworthy - it would also potentially mean they are only one slipup away from dscounted rights issue if they were to get rid of the cash. I would agree its better to have it and that might be the best value extraction by returning cash and then winging it from there.
Who are you talking about please?
I remember buying Galliford Try in 2009 based on very similar observations made by a colleague and that worked out very well. But then they owned housebuilding businesses which have now been divested so I'm not so sure in the residual contract construction business. The Aberdeen bypass contract caused them a lot of woes and expense. e.g. https://www.constructionenquirer.com/2019/02/13/galliford-try-construction-hit-by-more-aberdeen-bypass-losses/
Yes my only major worry is that they work on low margins on very large contracts. If unexpected expenses arise a 1% swing in margin on £3.2BN would wipe out significant profits
Reassesed this position and sold, I misread the RNS this morning and had overlooked the significance of the short term margin drop. Will wait for the results. My major concerns are a loss on large orders would wipe out the cash reserve. While I don't think this is likely it made me realise the risk reward is not as great as I first assessed.
If you want to know about what the sort of things that happen in this business, just look at the projects like the Aberdeen Western Bypass, this is one of the projects that sunk Carrillion...
https://www.constructionenquirer.com/2019/02/13/galliford-try-construction-hit-by-more-aberdeen-bypass-losses/
Reasonable update out of RLE today. I hold and will continue to hold.
I'm less impressed with PCA; how do directors manage to earn free shares in return for halving the share price? Who writes these incentive schemes?
Some companies are made for their Directors. I could mention Centrica (LON:CNA) as another instance but had better not.
My morning smallcap tweet: Electric SUV racing is no joke.
Capital (LON:CAPD) Arcontech (LON:ARC) Finsbury Food (LON:FIF) Air Partner (LON:AIR) Batm Advanced Communications (LON:BVC) Allergy Therapeutics (LON:AGY) Carclo (LON:CAR) AFC Energy (LON:AFC) Mission (LON:TMG) MaxCyte Inc (LON:MXCT) Hydrogen (LON:HYDG) Alpha FX (LON:AFX) Portmeirion (LON:PMP) Woodbois (LON:WBI)
Capital Limited (CAPD) guides H1 rev up 19% as gold price boosts mining. Outlook "encouraging signs of improvement in the [lockdown] situation, with the resumption of smaller exploration projects and easing of some travel restrictions"
Arcontech (ARC) guides FY(June) profit in line.
Finsbury Food Group (FIF) guides FY(June) rev down 3%. with steady monthly improvement during Q4. Net debt down 24% to c.£27m. Outlook "barring a significant return to lockdown, the Group anticipates a gradual recovery as consumers readjust shopping and consumption behaviours both in and out of home."
Air Partner (AIR) AGM stmt: 5 months to June significantly ahead of budget with U/L pretax at least £10m. Trading in July has been more normalised. Visibility for the second half remains limited, with economic and regulatory uncertainty from the impact of covid. Enters Australian market through its security business Redline to develop and deliver a Security Management System for ISS Australia and New Zealand.
BATM Advanced Communications (BVC) launches three new diagnostic kits to significantly advance the diagnosis of COVID-19 and other respiratory illnesses. Includes improved antibody test that measures quantity, not just presence. Expects to commence sales and production of the kits around end Sept.
Allergy Therapeutics (AGY) guides FY(June) earnings above market expectations, partly thanks to delaying R&D. Rev up 6%. Will repay furlough monies.
Carr's Group (CAR) trading in line. Will pay interim div of 2.25p.
AFC Energy (AFC) to supply zero emission, hydrogen fueled, off-grid power to Extreme E's groundbreaking inaugural electric SUV racing series in early 2021. Just PR and for a pointless race format at that. What next, clockwork wheelbarrow hurdles?
Mission Group (TMG) trading ahead of initial projections at the outset of the pandemic with H1 rev £29m (£39m) and pretax -£2.2m (+£3.4m). Short-term outlook remains uncertain.
MaxCyte (MXCT) guides H1 rev up 30%. Outlook 'confident'.
Hydrogen (HYDG) guides H1(June) net fee income down 34%. Net cash up £2m in half to £6.5m.
Alpha FX (AFX) guides H1(June) rev up 16%.
Portmeirion (PMP) guides H1(June) rev down 8% and LFL down 20%. Expect a ow single digit £ million loss (£0.5m profit). Outlook "We are currently seeing good order intent from customers for our key seasonal trading period and assuming no further Covid-19 disruption and the trend of improved month on month trading continues, we are confident that we will return to profitability in H2."
Woodbois (WBI) £13.1m placing & PrimaryBid offer at 2p, a 37% discount, last night.
in continuation of yesterday’s discussion about masks, the evidence is getting stronger and stronger with yet another supportive study published yesterday in the journal of the American medical association (JAMA)
Such lo tech solutions can save the economy and the endless political dithering does little to help!
https://jamanetwork.com/journa...
Wear a mask. No brainer
can you believe that #NoMask is trending in UK twitter?
Of Course I can - the power of (anti)Social media - Opium of the millennial masses
Social distancing costing e.g. Dunelm £150k a week though, and seemingly compromising productivity improvements.
Social distancing costing e.g. Dunelm £150k a week though, and seemingly compromising productivity improvements.
This is in line with what J Sainsbury (LON:SBRY) reported the other week. The benefits of increased demand and the business rates holiday were wiped out by Covid security costs.
I'm finding it very hard to make a positive case for non-food face-to-face businesses where they have online competition. If we take some potentially conservative figures - say a 10% drop in demand due to recession and and a 10% move to online then how many retailers can survive with a 20% drop in sales for the next 6 to 9 months? And that's before considering extra costs. Even the figures from Ao World (LON:AO.) yesterday didn't look too bad - and I've always considered that a terrible idea badly executed.
Yes what's the alternative? As we can see elsewhere in the world, if you open up too aggressively you end up with spikes and hospitals overloaded. And if hospitals are full then society can't really function so we see lockdown measures reintroduced.
Still, as investors, we have a choice, unlike a lot of the shop owners.
timarr
Morning Paul, any chance of casting your peepers over Mccarthy & Stone (LON:MCS) results today please? Many thanks.