Small Cap Value Report (Wed 16 Oct 2024) - GMS, VLX, SDG, XPS, MONY

Good morning from Paul & Graham!
UK Inflation Falls
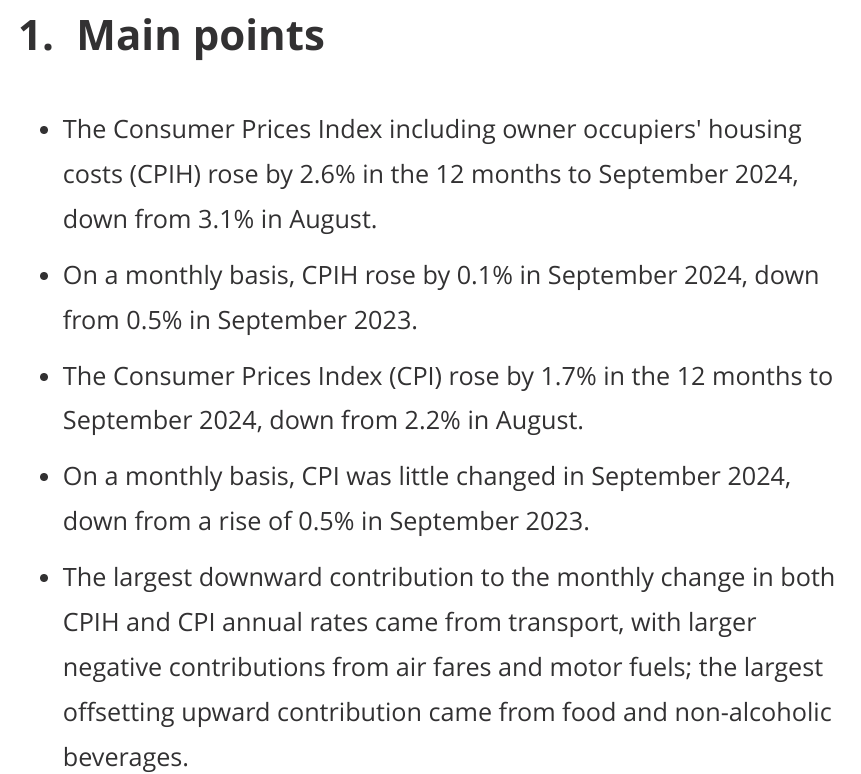
ONS data out this morning shows that CPI inflation data for Sept 2024 shows a sharp fall to 1.7% (due to a sharp rise last Sept dropping out of the comparatives). As the press are reporting, this probably makes it more likely that we'll see further interest rate cuts - which should be good for equities of course.
Excerpt -
Explanatory notes -
A quick reminder that we don’t recommend any shares. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech, investment cos). Although if something is newsworthy and interesting, we'll try to comment on it. Please bear in mind the "list of companies reporting" is precisely that - it's not a to do list. We typically cover c.5 companies per day, with a particular emphasis on under/over expectations updates, and we follow the "most viewed" list of readers, so if you're collectively interested in a company, we'll try to cover it. Obviously with the resources available, we can't cover everything! Add you own comments if you see something interesting, and feel free to discuss anything shares-related in the comments.
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to, if they are using unthreaded viewing of comments.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. And/or it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Others: PINK = takeover approach, BLACK = profit warning, GREY = possible de-listing.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom), Video update of results so far, June 2024.
** New SCVR summary spreadsheet for calendar 2024 ** This is the live one! (updated 6/9/2024)
Archive - SCVR summary spreadsheet for calendar 2023.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Phil Hanson's data analysis measuring performance of our colour-coding system in the SCVRs, from July 2023- Mar 2024 (with live prices). My video explaining/reviewing it.
My other video (June 2024) - How to screen for broker upgrades on Stockopedia. More stock screening strategies here (possible bargains?) - 21/9/2024.
Companies Reporting
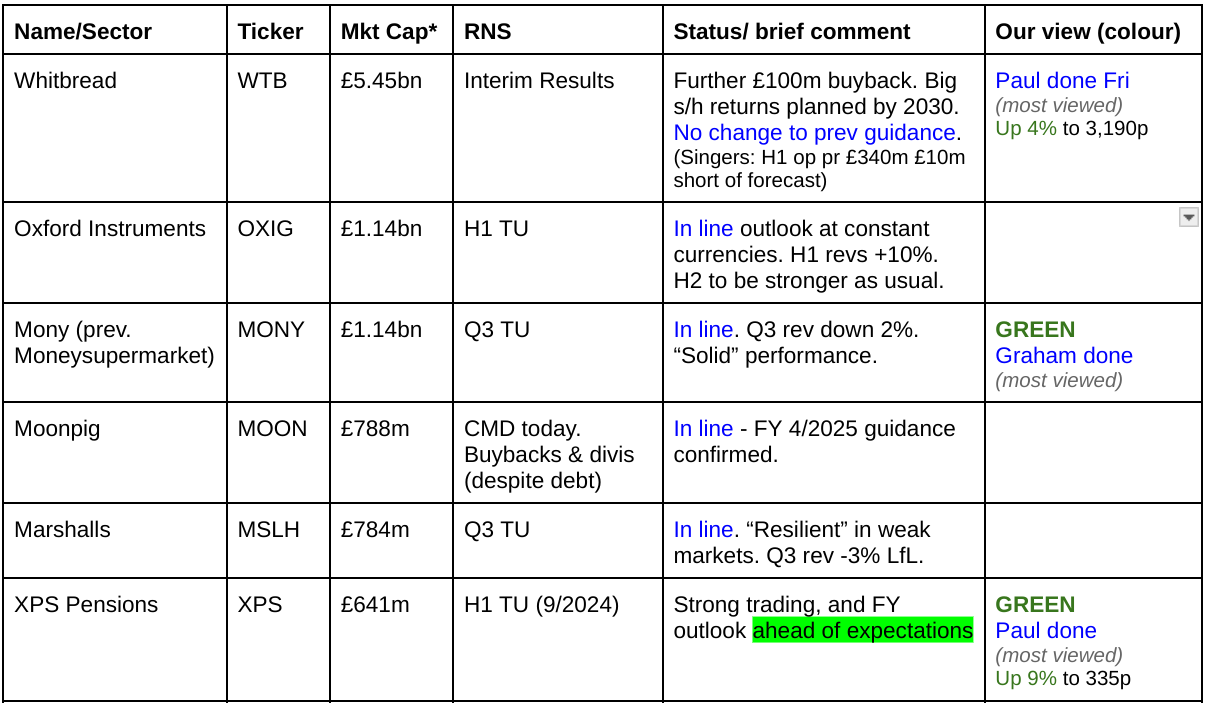
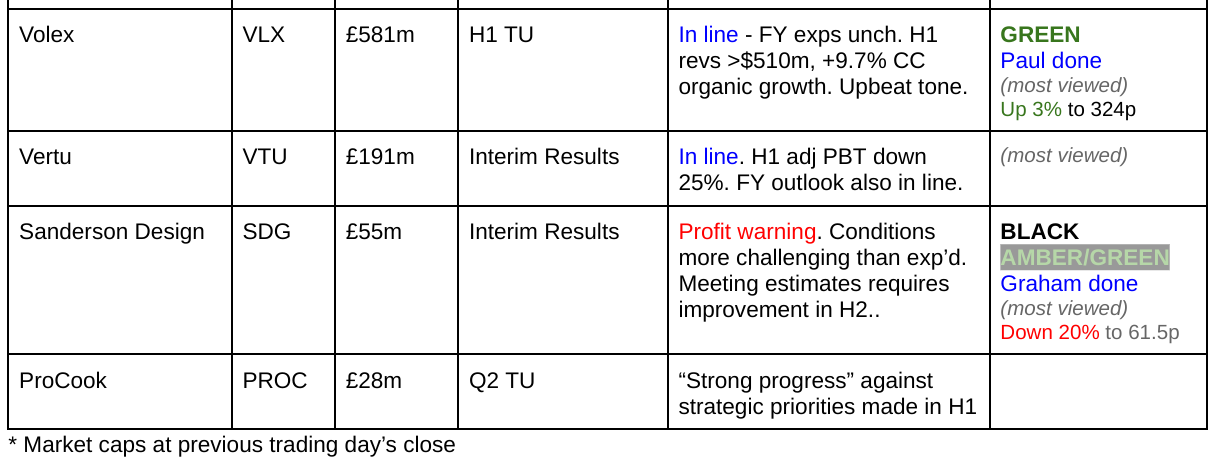
Summaries
Volex (LON:VLX) - up 3% to 324p (£586m) - H1 Trading Update - Paul - GREEN
This buy & build electrical connectors group reassures us once again, with a positive sounding update, and trading in line with expectations. I continue to view this share favourably, as a reasonably priced, good quality, well managed business, that seems to be executing a series of worthwhile acquisitions.
Gulf Marine Services (LON:GMS) (Paul holds) - 17.7p (£191m) - Call with management - Paul (I hold) - GREEN
I was able to have a Q&A with GMS management yesterday, with some useful points covered. Hopefully my notes below are reasonably accurate. It reinforced my view that this is a very good investment idea (I hold) where rapid deleveraging looks set to continue rewarding equity holders. Positive demand/supply situation looks set to continue. Divis likely to start next year.
Sanderson Design (LON:SDG) - down 18% to 62.85p (£45m) - Interim Results - Graham - BLACK (profit warning) AMBER/GREEN
SDG says that hitting prior expectations “is reliant on a predicted improvement in trading” after a tough H1. The analysts take a more pragmatic approach and reduce estimates: new revenue forecasts are 2% lower and adj. PBT 5% lower. I’m leaving the stance unchanged for now, as it is possibly in deep value territory.
XPS Pensions (LON:XPS) - up 9% to 335p (£697m) - H1 Trading Update [ahead exps] - Paul - GREEN
Impressive H1 TU, ahead of expectations. I think the 9% rise in price today looks justified, and valuation still looks reasonable.
Paul's Section:
XPS Pensions (LON:XPS)
Up 9% to 335p (£697m) - H1 Trading Update [ahead exps] - Paul - GREEN
Ahead of expectations updates are quite rare at the moment, so thanks to IanB who flagged this in the reader comments below - it eluded us, in our initial scan of the RNS. Some companies seem to use a different reporting method, as Moonpig (LON:MOON) also slips through the net too every time they report.
I think XPS is very good, and gave it a GREEN at 283p on 21/6/2024 with impressive FY 3/2024 results & outlook. It wasn’t cheap, but I concluded that the shares were worth the price.
It’s continued powering ahead, with shares making a new all-time high today on another positive update.
XPS Pensions Group plc ("XPS" or the "Group") is pleased to provide its post-close trading update (unaudited) for the six months ended 30 September 2024 ahead of its interim results on 21 November 2024.
Continuing operations revenues up an impressive 23% in H1.
I won’t repeat all the detail here, but suffice it to say that everything sounds positive. Key drivers of strong performance are lagged price rises from high inflationary period, and ongoing regulatory changes in the pensions advisory/management area.
Outlook -
“The Board is pleased with the Group's performance in the first half of the year and, notwithstanding an even tougher comparative period in H2 is confident of achieving full year results ahead of its previous expectations.”
Broker update - thanks to Canaccord, with a brief update note today. It has held back on updating forecasts, given that we need to find out what the Budget says. So no upgrade today, but it points out that 51% of FY revenues have already been achieved in H1, so the forecasts are likely to be raised a little.
Paul’s opinion - yes I like this one, it seems a good quality company, growing profits remarkably quickly. Which does raise the question whether profit growth might be benefitting from one-offs, so checking that growth is sustainable would be a key area of focus if I decided to invest here.
Note that the balance sheet NTAV is negative, as it’s done a lot of acquisitions. Debt was mostly cleared from a disposal last year, so nothing to worry about there.
Whatever it’s doing, is clearly working, so the profit & cashflow growth at XPS are impressive.
It was priced on a forward PER of 16.8x last night, and a 3.8% yield. Shares have gone up c.9% today, but earnings forecasts are also likely to rise somewhat, so valuation is still likely in the same ballpark.
The news is good, and valuation still looks reasonable, so I’m happy to stick at GREEN.
Volex (LON:VLX)
Up 3% to 324p (£586m) - H1 Trading Update - Paul - GREEN
Volex (AIM: VLX), the specialist integrated manufacturer of critical power and data transmission products, today releases a trading update for the 26 weeks ended 29 September 2024.
As usual Nat Rothschild’s acquisitive group pleases with a reassuring, and quite upbeat-sounding H1 trading update.
Instead of the waffle we often get from many companies, this update gets straight to the key point -
“Strong momentum sustained through the first half; full year expectations unchanged”
Note that broker forecasts have been gently eased down in recent months, so this looks like good expectations management by the company -
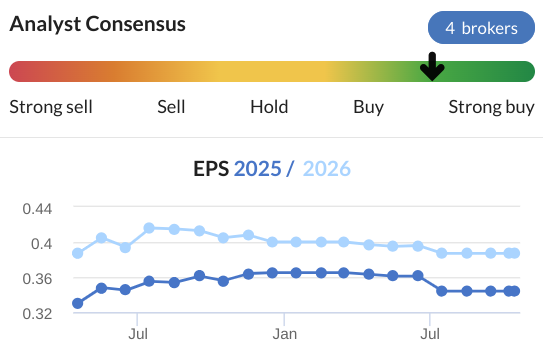
My summary -
H1 trading in line with expectations.
H1 revenue >$510m
Organic revenue growth (constant currency) impressive at +9.7% - I’ve queried before whether this is flattered by high inflation in Turkey, but I think readers thought it would probably be invoicing in dollars or euros, which sounds credible. Maybe someone could ask if Volex do another webinar?
The five sectors Volex supplies have nicely balanced each other again, with growth in EVs (electric vehicles) and consumer products mentioned, offsetting some softness elsewhere.
Margins good, but vague on specifics. Just says within target 9-10% range.
Continuing to invest in increasing capacity & efficiency measures.
Outlook - reassures -
“Volex delivered strong growth in the first half of the year, despite a challenging macroeconomic background. This is a testament to the Group's strong positioning in specialist markets delivering critical connectivity for customers. The Group is benefitting from a diversification strategy targeting structural growth markets and leveraging strong customer relationships, and is well positioned to continue the current momentum through the second half of the year, with full year expectations unchanged.”
Diary date - 15/11/2024 for H1 results.
Broker updates - nothing available, but I imagine given this is an in line update, there would probably be no changes.
Valuation - the StockReport has 34.4 US cents for FY 3/2025. Convert at £1 = $1.30, gives us 26.5p, and at 324p the PER is 12.2x, which I think looks reasonable. Remember to factor in that VLX has increased debt a fair bit, to help fund acquisitions, and this was $121m (excl leases) at 3/2024.
Today’s TU should have provided an up-to-date net debt figure, so that’s a gap in the reporting. Better still, companies should report their average daily net debt, to give us the full picture. I’m not concerned about Volex’s debt, but would like to be better informed as to what the numbers are, as we need that info to properly value its shares.
Paul’s opinion - I’m pleased with this update. I remain of the view that Volex has established an excellent track record as a reasonably-priced buy & build share. I’m not holding personally at the moment, as mentioned in a previous podcast, I sold them temporarily due to wanting to lower my exposure to AIM during this volatility over Budget measures. My view on the the fundamentals at VLX haven’t changed at all, it’s still a positive view, so another GREEN. I suspect once UK small caps are out of the doldrums, this share could enjoy a useful re-rating. Meanwhile management are quietly getting on with doing a good job, despite challenging macro conditions. That should mean stronger growth once economies recover. It could also benefit from reshoring closer to Western economies, and I also like that it is positioned well in structurally growing markets. So it’s another thumbs up from me. I hope to rejoin holders as a small shareholder myself, in due course!
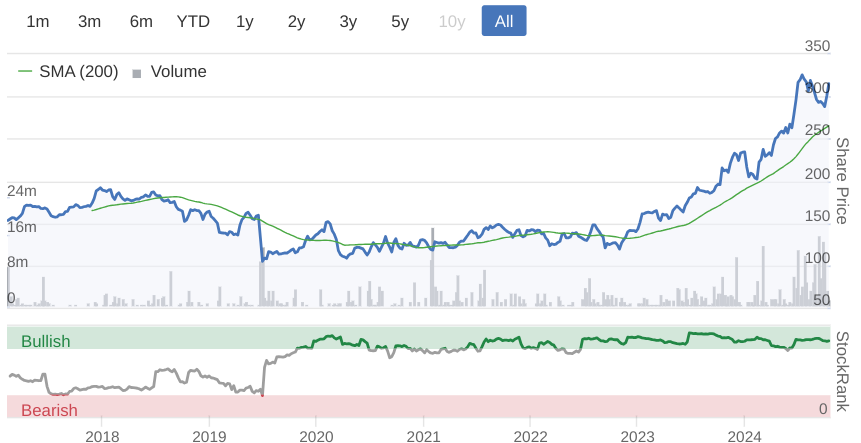
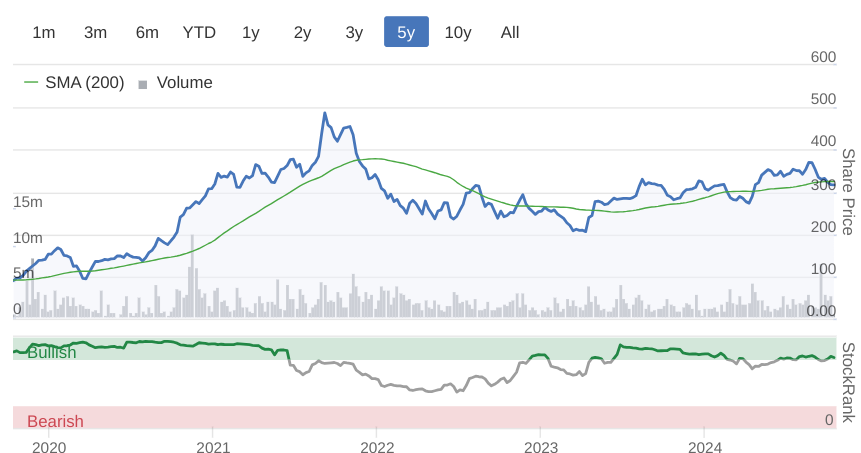
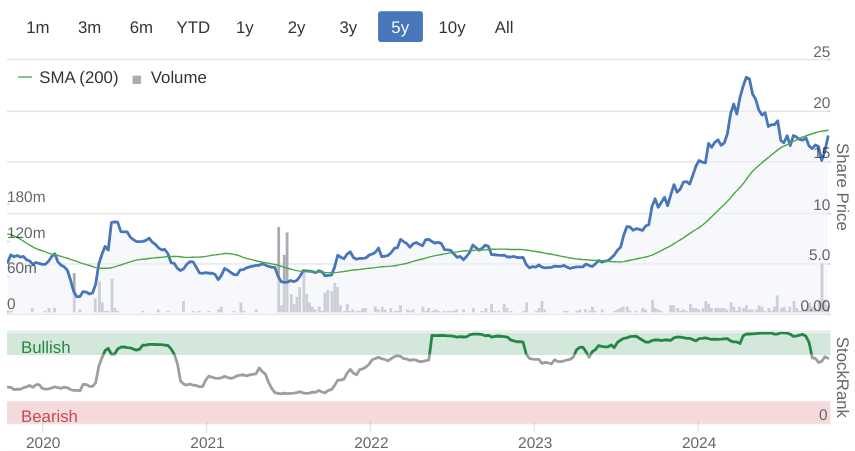
Despite all the multiple crises of the last 5 years, VLX shares have tripled -
Gulf Marine Services (LON:GMS) (Paul holds)
17.7p (£191m) - Call with management - Paul (I hold) - GREEN
I had a call with management yesterday, as this share interests me, and I wanted to ask about several queries raised by me, and other investors.
As usual, this is just my recollection of the gist of what was said, so apologies if anything isn’t quite right.
Background - I’ve covered GMS shares a lot over the years. The investment case is that it’s a highly cash generative, deleveraging investment situation. Previously excessive debt is now rapidly reducing, with the upside flowing to equity holders.
There’s a detailed slide deck from Sept 2024 here on their website.
GMS owns a fleet of 13 modern, well-maintained vessels used mainly in the oil & gas industry, hired out on long-term contracts at daily rates of c.$32k, mainly in the M.East.
Opportunities in the repair & maintenance of offshore wind turbines. One ship does this in N.Sea, and one is being moved from M.East to N.Sea. Existing fleet only need minor modifications to change use from oil & gas, to wind. Also opportunities in additional new geographies (eg. South America) are being bid for. So mgt see good potential for further growth.
The fleet is relatively new (vessels have a life of c.40 years, but GMS depreciates them over 30 years, and their fleet is average 14 years, with one older vessel of 28 years skewing that number).
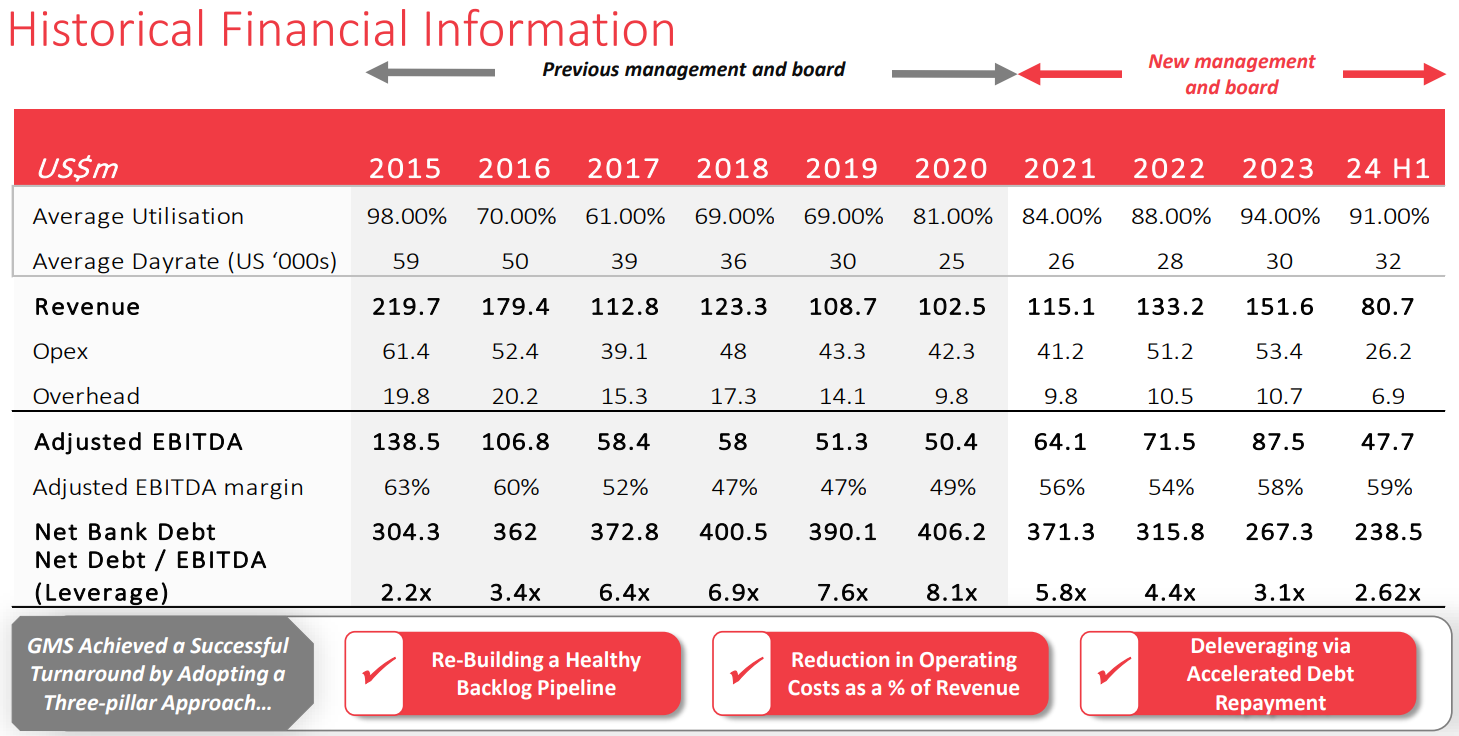
Slide 7 below shows how previous management saw a crash in utilisation, and daily rates from 2016, which saw net debt soar from 2.2x EBITDA to 8.1x EBITDA by 2020. In the last 4 years, debt has come right down again, and is now only 2.6x EBITDA.
So I focused my questions on the risk of something similar happening again if the market rates once again crashed?
New management are “extremely careful” with gearing now, and are targeting 1.5x or below in future.
Would still be profitable & cash generative even if utilisation were to crash to 60-70% again.
Even if oil & gas market does crash (not expected), these vessels would still be needed for maintenance & repairs.
Utilisation shouldn’t have dropped as low as it did, mistakes were made with not being flexible enough on pricing, hence unnecessarily low utilisation 2016-19.
Market rates are gently rising, with strong long-term demand, and very good order book (c.$500m), growing rapidly.
Contracts are a mix of fixed, with options to extend. Historically, customer options are nearly always exercised.
I asked about new ship capacity being built, and could that lead to a future glut of supply? Mgt ran me through the industry numbers, something like 68 vessels currently in use (so GMS has something like 20% market share). 15-20 new ones are being built. 6-7 in the industry are over 50 years old, so likely to be retired. Industry requires about 30% increase in numbers, so it all balances off, and demand is likely to remain ahead of supply. Which is why operators are keen to lock in supply with long-term contracts, hence GMS’s rapidly growing order book.
Can contracts be cancelled by customers? Some have penalty clauses, but most don’t, but in practice in an adverse market customers are more likely to negotiate price discounts, rather than cancel.
Dividends - as RNSd, being considered, decision will be made next year.
Seafox overhang - when will it clear? Seemed to think the main sellers are done now. Was surprised that Seafox agreed to a discount by selling at 17p, when share price was 20p.
Warrants - related to banks, 2 holders. One has sold some, the other is keeping them for now.
Risk from Arab/Israeli contract? Doesn’t operate in the Red Sea, and no sign currently that any facilities are likely to be targeted, as not in danger areas.
Book value of ships - how does it compare with open market value? Open market value is higher. This makes sense to me. Some bears were suggesting these are overvalued ships, which doesn’t make sense, because they’re generating huge cashflows, so of course they’re valuable, given that demand is still outstripping supply and likely to continue doing so.
Paul’s opinion - I’m very reassured by the above, as all the main risks seem to be fully under control. Management strike me as very open, and gave direct answers to my questions. They’re keen on shareholder engagement.
EDIT: Do have a look at the full slide deck, it's full of useful information. This is the final slide below - which reinforces that the favourable conditions GMS is enjoying look set to continue -
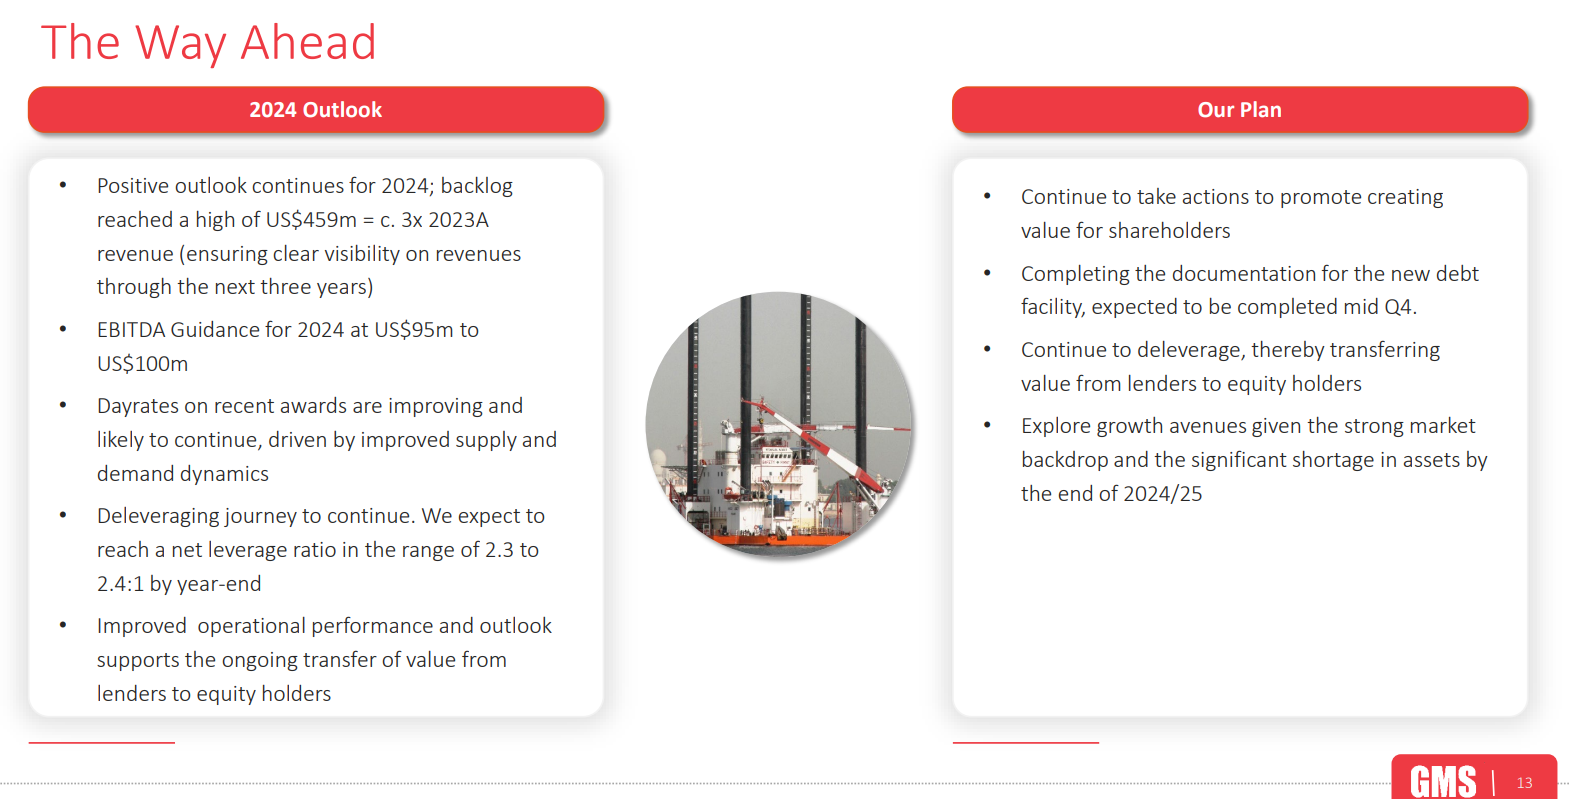
Near-disaster to multibagger, and possibly more to come, the numbers suggest to me -
Graham’s Section:
Sanderson Design (LON:SDG)
Down 18% to 62.85p (£45m) - Interim Results - Graham - BLACK (profit warning) AMBER/GREEN
Sanderson Design Group PLC (AIM: SDG), the luxury interior design and furnishings group, announces its unaudited financial results for the six months ended 31 July 2024.
The numbers published today aren’t pretty. Here’s an excerpt from the table:
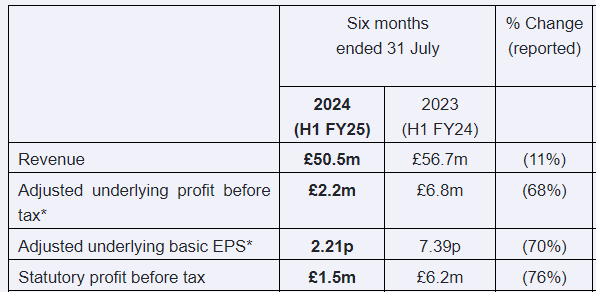
The fall in revenue reflects “a challenging market in the UK and elsewhere whilst growth was delivered in North America”.
The collapse in profits is due to the drop-off in ordinary brand product sales but also due to lower licensing income (£4.1m in H1 is this year, vs. £6.9m last year).
For many companies, licensing income is a form of costless pure profit, which means that any reduction can have a dramatic effect on profitability.
On the bright side, SDG says that the lower licensing income in H1 was in line with expectations, and that it still expects to have full-year licensing income that’s “approximately the same as last year’s”.
Net cash has fallen from £16m (Jan 2024) to £10m (July 2024). Reasons: capex, inventory build-up due to lower than expected sales, and a payment to offload a pension scheme.
Interim dividend will be 0.5p (H1 last year: 0.75p).
Chairman comment: makes clear that trading has been “more challenging than expected in almost all territories”, and concludes with:
Delivery of the Board's expectations is reliant on a projected improvement in trading during the remainder of the financial year, which includes our important pre-Christmas selling period."
Instead of saying the above, which implies that hitting previous expectations can’t be relied on, perhaps it would make more sense to say that the company has new (lower) expectations for the year?
Estimates: speaking of expectations, Progressive have published a note with a new FY Jan 2025 adjusted PBT estimate of £7.6m (previously: £8m). That’s a 5% cut.
Their estimate of unadjusted PBT gets a 12% cut, to £5.6m.
Graham’s view
There’s no getting away from the fact that these are terrible results and the outlook statement is poor with the company now likely to miss prior expectations.
However, the collapse in profitability is understandable when you consider the weak environment that has affected so many of the companies we cover in this report. Sanderson has suffered a 14% reduction in product sales in its domestic market - most companies would struggle with this.
There are still reasons for optimism, in my view:
Like-for-like sales of 6% in North America. Sales in North America could potentially catch up with sales in the UK in a few years.
The drop-off in licensing in H1 was only due to the timing of deals. Licensing revenue is often lumpy, but the full-year result is tracking in line with various new deals and extensions signed.
The balance sheet has tangible equity of £60m. As noted by Paul in a text to me this morning, working capital (current assets minus current assets) is £38m. That’s not far off the market cap!
Therefore, despite the implied profit warning in today’s announcement, I’m inclined to leave the AMBER/GREEN stance unchanged - see coverage in August. I don’t view this as a comfortable purchase or a sleep-sound type of investment, but the risk:reward still strikes me as interesting!
Momentum is downhill:
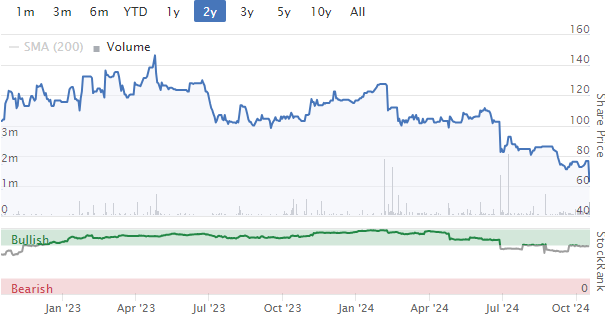
But it is passing lots of value screens: 6, to be precise! For example:
MONY (LON:MONY)
Down 5% to 201.7p (£1.1 billion) - Q3 Trading Update - Graham - GREEN
This update is in line with expectations and the company helpfully informs us that it is expected to produce an adjusted EBITDA of between £135.8m and £142.1m, with an average consensus estimate of £140m.
Last year, MONY made an adjusted EBITDA of £132m, so it’s in line to make a nice improvement on that. The real, after-tax profit figure was £72m.
Here are the Q3 revenue results:
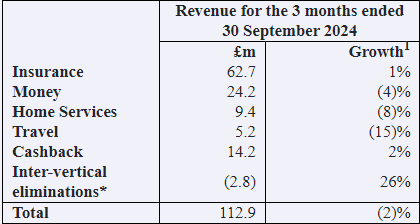
The “Home Services” segment includes broadband, energy, landline and mobile phones. Along with Travel, it’s the main point of weakness. There was “soft demand from customers in broadband and fewer compelling new handset launches in mobile during the period”.
In the Travel segment, there was “lower conversion in car hire”.
The much larger revenue contributions from Insurance and Money held up better, perhaps in a sign that consumers are more focused on saving money than on discretionary spending. Credit card switching was strong, but there were few offers to switch current accounts during the quarter.
Year-to-date, the company has achieved revenue growth of 2%, with 9% growth in insurance making that possible as most other segments declined.
SuperSaveClub now has over 750,000 members with 11 products available to members.
Outlook: confident that it will deliver results in line.
CEO comment: pleased with continued progress.
Graham’s view: we tend not to cover this one any more, due to its size, but I’ve been a fan of this company for a long time and it’s on the “most viewed” list today.
It gets a QualityRank of 99, with fantastic quality metrics arising from the fact that it’s a successful online business that doesn’t need to use much capital to generate its profits.
It was last mentioned in this report back in 2019, when it had a market cap of nearly £2 billion.
Today the market cap is only £1.1 billion. It should generate about the same level of profits this year as it did in 2019 (unadjusted for inflation).
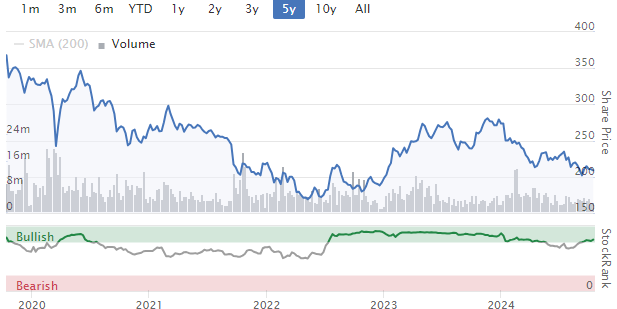
At modest earnings multiple, I would have to say that this looks interesting and so I’ll go GREEN.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

79 comments
On the inflation numbers today, the press and central banks always quote CPI numbers. What a nonsense number it is though + it's highly misleading. CPIH and RPI are 0.9% and 0.8% higher and are the proper inflation measures.
CPIH
The Consumer Prices Index including owner occupiers' housing costs (CPIH) is the most comprehensive measure of inflation. It extends the Consumer Prices Index (CPI) to include a measure of the costs associated with owning, maintaining and living in one's own home, known as owner occupiers' housing costs (OOH), along with Council Tax. Both are significant expenses for many households and are not included in the CPI.
Owner Occupiers' Housing Costs inflation is at multi-year highs of 7.2% and impacts most people in the real world (1/3rd of households have a mortage and nearly every household pays council tax)!
Topvest. Slightly overstating things aren't we? CPIH for year to September 2.6% down from 3.1% last month according to the ONS site I've just looked at. I see it was running at an annual rate of 6.3% in August last year. Or am I wearing the rose tinted specs again?
As misleading as official stats may be they are the basis for decision making and I for one am looking forward to reductions in interest rates over the next quarter. These reductions should help with housing costs as mortgages become cheaper and effectively help to reduce most measures of inflation further. Wouldn't you agree?
Even if the stats are faulty the trend seems to be generally positive. And what's the point in railing against the system? Surely better to see where it points and act accordingly? I have often been in a majority of one (and look where it's got me!) so have some empathy.
sevenccc - CPIH is 2.6%, CPI is 1.7% so it is 0.9% higher. I am only really repeating what the Office for National Statistics says - they publish the data and use CPIH as the most comprehensive measure, and CPI as an inferior index. Be nice if the establishment could use one measure rather than CPI, CPIH and RPI and pick the lowest!
The trend is clearly positive - I agree. The point I'm making is that mortage costs and council tax is ignored in the CPI number and that is running at 7.2% (and still increasing) which is surely quite painful if you have a mortgage (which fortunately, I don't).
MONY (LON:MONY) , was last mentioned in this report back in 2019, when it had a market cap of nearly £2 billion. Even with this reduction in market cap, if the business is viable and well-run then this business should make shareholders happy? I hold.
Edit: Meant to say that it's the worrying rate of inflation that sends people to comparison sites, not so relevent now as was in 2019.
Has anyone any thoughts on the Applied Nutrition IPO which is currently open to retail investors?
https://www.stockopedia.com/sh...
Looks a decent IPO. Founder will reduce to 30% , but JD Sports are the main seller down to 5%.
It's a bit expensive at a P/E close to 20 and it won't pay a dividend at the start, but does look interesting with no leverage.
Supreme (LON:SUP) looks more attractive price wise, but it has the budget vaping risk hanging over it at the moment.
Protein market is a saturated. Recent sales growth driven by marketing and not sustainable in a highly competitive market. They do have brand recognition but so do another 5-10 brands. P/E 20, no chances, maybe 8-10 tops. Ill be looking to short post listing euphoria.
Also Applied Nutrition have probably been helped by MyProtein (owned by THG (LON:THG) ) making a meal out of their rebranding. Look at the shocking YoY revenue declines at MyProtein over the last 12-18 months.
However, that rebranding project is now complete, and should, in theory then drive stronger competition against Applied Nutrition, starting from Sep/Oct already.
So perhaps they are floating very opportunistically at the right time... with a good set of last 6-12 months results... which then gets more challenging going forwards...
All conjecture on my part, I am not an expert in protein market. Maybe AN is really that much more superior to MyProtein and the rest, and taking market share sustainably.
I read about that.Impressive as the founder only founded the company in 2014 and was just an ordinary bloke into going to the gym who noticed a trend i'm guessing, had a go and put in the grind.Obviously protein powders and associated health accoutrements are even more expensive than ever now for a bit of dried whey in some nicely marketed plastic pouches.No idea why as i doubt the inputs have increased massively..?I prefer buying a few chicken breasts for a lot cheaper but have tried them and they all taste ok but younger people love them i think (A lot of focus amongst younger women too about looking strong rather than skinny like back in the day with Kate Moss and building your glues aka Kim Kardashian and clan).Have been around for a while obviously with THG (LON:THG) making a lot of their profits there historically.Still impressive.A real go getter it seems like the young Gym Shark founder!There's another smaller US listed company, which bought a protein powder company out of adminstration, that's doing really well the last few years FitLife Brands (NAQ:FTLF) .They also have a partnership with local UFC stars Paddy and Molly off the tele from their website!
There is definitely a big trend at the moment on Strength vs Cardio in the gym going population.
There was an article recently (can't remember maybe FT? Bloomberg?) about gyms struggling to adapt to this new demand for Strength machines (ie weights) vs Cardio (ie treadmills). They can't very well just swap out the treadmills for weights, as it costs quite a bit of capex, etc.
This, of course, will be a tailwind for Applied Nutrition and MyProtein for a few years to come. Maybe also Science in Sport (LON:SIS) with their protein products too.
Plenty of good chat here re. possible changes to CGT, removal of BPR (ref AIM) etc.
So though I would share this. It'd Dan Neidle's latest musings on CGT, and income tax comes in too.
Relevant because some believe he has influence with Reeves. It could therefore give an inkling of the direction of travel, should the new govt want genuine reform.
At least what you get from Dan is well reasoned arguments, often well backed up. Whether or not you agree of course is another matter. But I like that he wants to preserve some reward for genuine risk taking, even if I personally think it should be rewarded a bit more!
Dan's the man who kind of helped to bring down Nadhim Zahawi over his tax affairs too. He's a former magic circle tax lawyer, who now runs Tax Policy Associates. He's quite active on X as well.
Dan is of course very political (national Labour party level) but his articles are substantiated, of quality and objective - he tries to distinguish between technical tax policy and political choices and/or priorities.
His key campaigning theme is reforms which might reduce inefficiencies in the tax system, hopefully reducing complexity and distortions.
His view is firmly that more tax can be raised if there is genuine reform and in some cases that might be quite radical (e.g. reforming stamp duty and property taxes).
We'll shortly see whether Rachel Thieves has been listening . . . . . . .
So thought I would share this
Full of insight and sadly likely to be ignored!
Thanks BnB. And thanks for your fantastic post the other day about your holdings, with pithy synopses.
At the risk of being blackballed for political commentary I find it extraordinary that all governments look principally for how to pull more money in from the electorate, rather than how to rationalise wasted spending.
For example, I was recently involved in a national process to do with NHS procurement. I participated in a zoom where there were 100 participants, all being paid, where an exhaustively tedious process was brought to a conclusion and the conclusion was - there was not enough evidence to form a conclusion. We had told the organisation this at the start but hey ho....
Removal of old dead wood is at least as important as funding of new initiatives, and yet this is rarely considered.
DD
Lord Darzi produced a report stating that the NHS did not need more money, a few weeks later Rachel Reeves says she is going to raise more money for the NHS.
The NHS principally needs to do two things:
1. Weed out the clipboard operatives who do nothing except talk about what those involved in actual patient care are doing.
2. Decide whether spending 80% of all healthcare costs in the last year of a patient's life is sensible. Obviously it isn't - when the tide is coming in, it's coming in no matter what you do - but societal norms expect intensive treatment instead of acceptance of the approach of the end of life. This is the biggest challenge, and hardly anyone is willing to acknowledge let alone embrace it.
You clearly didn't read the same Darzi report as everyone else!
Just one headline from his summary letter (there are more):
"16. Capital. The NHS has been starved of capital and the capital budget was repeatedly raided to plug holes in day-to-day spending"
Maybe I missed a nuance or two, but I think he wants us to believe that people who start companies really haven't put any capital into them, and so when selling, other than inflation proofing there shouldn't be any entrepreneurial discounting schemes or similar? But he doesn't seem to recognise that many businesses sacrifice the chance to make more by reinvesting spare cash in the business, or taking out personal loans.
To me this smells like an academic who has never tried to build a business, and doesn't know the stress it causes, not least when Govts hammer you from all sides, let alone market forces. He just looks at what is best to raise money for the Govt, and frankly that isn't a winner for those other than State employees, the feckless, or unjustified benefit huggers.
Some may not set out to make capital gains, but at some point it is important to know whether you should stay in the game. The constant switching is seriously disincentivising.
XPS Pensions (LON:XPS)
Thanks for the XPS write-up Paul. Very useful.
BTW, the ticker is incorrectly shown as XPP rather than XPS at the top of this page.
Funny goings on at Funding Circle Holdings (LON:FCH). Directors have been selling but the company itself is continuing buybacks at twice NAV and despite having six-bagged in a year. Is there some share-price-related bonus in the offing??
As a holder of Funding Circle Holdings (LON:FCH) I, like you, keep an eye on Director dealings
The £5m share sale by former CEO & current NED S. Desai coincides with his stepping down from the board later this month so is understandable. The £350k sale by CFO O. White may relate to CGT budget concerns as there is a current pattern of share sales in other companies I follow. I have been impressed by CEO Lisa Jacobs in the presentations I’ve watched & note she hasn’t sold any shares to date
Funding Circle Holdings (LON:FCH) reassuring thanks Aston Girl. I hold too, I should have said. Still don't think much of the buybacks at this stage though, but I appreciate we often have opposing views expressed here on that topic.
Corero Network Security (LON:CNS) (I hold) price has been continuing to rise nicely whilst most of AIM falls.
But please can someone explain why yesterday there were 2 trades at 16.08.35 and 16.08.36, both for £1.1m when the market buy price was 24.5p immediately before and £24.4p immediately after?
I'm guessing connected parties - are they hoping HMRC won't spot the price wasn't at a massive discount?
Oxford Instruments (LON:OXIG
Slightly outside the scope of the SCVR, but highlighted in my rundown of the BnB fund as significantly undervalued, this quality name issued a trading update today that belies the recent trajectory of the shares, which have sunk on sector woes (see Spectris (LON:SXS) Spirax (LON:SPX) etc). A nice 5% bump this morning provides some confirmation of the thesis.
AIM index performance has been terrible for multiple years now. Hardly surprising as while there are some good quality Companies on AIM it’s otherwise overloaded with junk.
There’s yet another example today. Versarien (LON:VRS) share price now just 0.03p has lost ANOTHER 40% today on yet another placing. As so often there was supposedly good news just ahead of this Placing. I. e agreement with Balfour Beatty and then a positive corporate update.
Earlier this week Vast Resources (LON:VAST) also somehow succeeded in getting yet another Placing. There must have been around 30 placings and share consolidations yet still somehow they can get Placings away. Why? Why do supposedly “professional investors” support them in the teeth of evidence that they shouldn’t?
Surely the house brokers who provide bullish notes that defy reality and presumably promote these fund raises each time, realise they are promoting junk? They surely can’t be as clueless as the many small investors who stay convinced and hold the shares all the way down to these 99% losses?
A quick look at the ADVN bbs shows multiple posts on these shares with the quality of the comment mostly as bad as the quality of the share! That’s another thing with rubbish shares. They are SO popular on bulletin boards. Why do so many invest in and get so addicted to shares like these?
And one of the ADVFN threads is headed “Will Vast Resources (LON:VAST) be the biggest multi bagger of all time? “ YES it might be in the vast number of shares it’s issued over the years. As for multibagging share price….the current price is after shares consolidations!
I’ve never looked at Vast Resources (LON:VAST) or Versarien (LON:VRS) so can’t post on why they’ve failed to deliver, but I have over the years kept a close eye on 80 Mile (LON:80M) because it was so popular on Mike Walters bulletin board. (He closed it at the end of last year).
80 Mile (LON:80M) too has had multiple fund raises and like VAST and VRS the share price is down to a fraction of a penny, and again down 99% long term. 80MILE used to be JAY (Blue Jay Mining) and their big project was an ilmenite Mine at Dundas in Greenland. Over bullish Management promised full production and £ hundreds of millions in revenues along with bumper profits by 2019. Management over promised and delivered nothing for years.
In the end they didn’t even start to build that Mine, And a year or so ago they abandoned it for good……….but I had a look at their recent updates before posting this to see they are now going back to square 1 with new Finds at Dundas!
Why, why why don’t investors both amateur and Professional see through it all? SP Angel is House Broker for JAY and issued bullish notes and unrealistic target share prices all the way down. They are also the House Broker at Versarien (LON:VRS) .
Shore Capital, joint broker at Vast Resources (LON:VAST) in an update 3 years ago wrote that the Market was misreading the Medium Term prospects. No it wasn’t. The Market sees through all this nonsense and hence those 99% share price falls.
E.g Cavendish Financial (LON:CAV) (I hold) is broker for Eden Research (LON:EDEN) a Company with seemingly must use environmentally friendly products yet in getting on for 20 years they’ve had hardly sales. And again with one placing after another and bullish Broker Notes that keeps the show on the road. And somehow Eden Research (LON:EDEN) and Cavendish Financial (LON:CAV) between them even managed to get the MIDAS column to tip EDEN ahead of the most recent placing. The share quickly tripled and they got that placing away at a good price. Needless to add the share price fell heavily again after that Placing and Open Offer that some rushed to buy in.
No wonder the AIM index has gone nowhere for so many years now.
Yes, i have always been surprised why rubbish shares are so popular on ADVFN boards. The comments are usually idiotic, not sure how these guys have any money to invest. They are mainly bombed out jam tomorrow shares that attract a certain type of clown.
I use the comments section on ADVFN as part of my selection process. The more nonsense there is in the comments, the more likely the share is a dud. VRS being a prime example.
I use the comments section on ADVFN as part of my selection process. The more nonsense there is in the comments, the more likely the share is a dud. VRS being a prime example.
On that basis you would never have held Warpaint London (LON:W7L) which has been my best performing share over the past couple of years. That said, I generally prefer a quiet bulletin board.
Fire lit under Fonix (LON:FNX) this week. Can’t all be down to Strictly!
Seller cleared i would say
Black hole getting bigger...
Reeves aims to close £40bn funding gap as she plans tax rises in Budget
Figure is significantly more than the £22bn fiscal hole the government previously identified
https://archive.ph/Q90d5
Report I saw this morning talked about 22bn for stand still and indicating the rest is money to be gathered in for investing in priority areas such as housing. May make Vistry (LON:VTY) (I hold) an interesting share again at current prices.
Perhaps. Although given the Irish govt will receive a guaranteed 14 billion euros from Apple, which it has already committed to spend on infrastructure/housing etc, I'm happier holding Cairn Homes (LON:CRN) which still has over 5% div, daily share buy backs - rather than wait for the ifs and buts with Vistry (LON:VTY) (same dividend too, assuming its not cut).
I agree Viz with the Cairn Homes (LON:CRN) sentiment. Unlike Great Britain - I believe Ireland is also running an €8bn surplus too. Very different budget situation on top of the usual housing crisis. And I believe there are a limited amount of Irish builders...Waiting patiently for the turnaround...
Thousands of new homes to be built as part of the government’s plans to get the country building again.
https://www.gov.uk/government/...
and to finance recently agreed public sector pay awards
Hi Glass half full
Good to see you at Mello last May. I hope that you are well.
Not sure if you still hold Equals (LON:EQLS) , if you do I admire your patience.
As for me I still retain a large holding in Sigmaroc (LON:SRC) , which in time, perhaps when house building recovers will become more appreciated. I am a fan of the entrepreneurial management team and led by CEO, Max Vermoken,
Keep well
Well according to the article the big number is a "funding gap" and the little number is a "black hole" .
Not sure what is happening with the Stock Exchange feed this morning, but lots of mid-cap stocks are showing with strangely wide spreads at the moment on 'Stockwatch'. I wonder how it looks on other platforms?
Interactive Investor prices are all over the place. At least they are for me. Most quoted prices are below actual.
ii pricing is frequently all over the place for me. They always deny any problems.
Yes, ii seem to move the price from the bid to the mid price when the market closes each day...I moved to ii from share centre when they took them over and queried this at the time as it was a change from what share centre did.
Sharepad has a problem with bid/offers not showing for many stocks but level 2 is working.
from sharepad support:
I want to extend our sincere apologies for the data issues we're experiencing this morning. Our team is fully committed to resolving this matter swiftly and effectively. Rest assured, we’ll keep you updated on our progress as it develops
Hello dragon,
Is Share pad level 2 any good? guessing cheaper than ADVFN?
If you pay for the live price, Sharepad, L2 is included for £74. I have nothing to compare it to as it's long time ago that I tried ADVFN's L2, I believe it includes data from Aquis which Sharepad doesn't, well it does but very delayed.
You see the book and the trades as they happen, which is level 2, so yes it's good.
I still haven't found / invested the time to research how we can ( if possible ) circumnavigate the market makers ... definitely irrelevant for FTSE 100 and most of the FTSE 250, but Aim / Small Cap ...there seems to be only a small subset of the market where you can place bids and offers which will get filled fairly effectively... any insight from more experienced practitioners very gratefully received... otherwise crossing fingers for US style liquidity and depth :)
By which I mean... placing bids and offers directly on to the market...
The only broker that I know provides this is, IG and only on SETS shares, you have to pay a fee for L2 access. SETSqx does seem to have a book, but I don't know how you place trades on to it, I have noticed sometimes trades appear below the book on Sharepads L2. Don't assume your trade will fill though, sometimes you will only get a partial fill. You can also participate in the Uncrossing trades, but that is a mystery how you get a fill, I tried a couple of times.
Might be wrong but think for SETSqx ones that trade mostly through the market makers during the day, you can still place orders directly into the auctions that occur a handful of times each day and cut the market makers out during those auctions. The IG L2 product is relatively cheap imo but not especially user friendly interface.
I will hazard a guess that a blizzard of dealing problems will be encountered on the day of the Budget and for days afterwards as positions are adjusted.
More excellent numbers and good momentum from XPS this morning. The business seems to be in a very sweet spot just now and the valuation doesn't seem stretched . One of my best UK mid-caps at the moment.
Volex (LON:VLX)
Fair-play to Nat Rothschild and the team. Nice straightforward update, no manipulative wording. Operating margins of 9 to 10%; full year expectations unchanged.
Volex (LON:VLX) remains under appreciated and the price is at odds with the company’s performance. Changes in the tax regime may impact the former, but not the latter. Nat Rothschild has not sold a share, albeit he is a wealthy man and retains over 25% of the company.
Sanderson Design (LON:SDG)
Looks like I dodged the impact of this morning’s interims, as I sold shortly after buying, once I had digested the somewhat disingenuous share awards to management as a consequence of the remuneration committee moving the goal posts.
With regards to Volex (LON:VLX) is it really under appreciated or just not as good as we think it is as an investment.
I sold last week after about 4 years of holding. Seen the price go from around £2.50 to £4 then now back down to £3.17. The Stockrank has dropped from a 98 to todays 76, so is STOCKO trying to tell us something.
No real movement following todays inline, are there not just more exciting opportunities out there?
Volex (LON:VLX)
Must admit i am on the fence leaning in - per stocky the forecasts for this year and next have shown decline in expected eps this year and next over the last 15 months. I wont really knock the company for that reductions are minor and may perhaps even be non core trade related - but obviously as things stand despite there being a clear upward projection ref numbers the trend in those bottom line numbers has been down. I was looking for the downward trend to stop - todays update on the face of it seems "job done" ref this year. It will be interetsing to see if brokers move the stick up / down or unchanged ref next year. Note the curent and next years expected net profit totals are a big leap on what they have done historically - i think if they can deliver these expectations on a "clean basis" broadly speaking , that will have been a great job done by managment in delivering the promised land on hopefully sustaianable basis.Presuming the future is still rosy i would have less reason to worry when those numbers look more in the bad that i have done previously when the forecasts looked like "hard work".
Ref knocking the companys stockrank - you have selectedly quoted a 98 total whne anything over 90 looks like it was a very temporary blip - with numbers that are pure stats you will sometimes geta blip here that doesnt mean alot. Looking at the average it has possibly been over 80 bit but to me the 79 curent value is much more reflective of teh average than your selected 98 moment in time. To be fair the the computers than 98 blip was at lower shareprice level and shareprice did go up - so i supect that was simply time when the shareprice hadnt caught up with improving financials.
I dont argue there may be more excitig opportunities and i also dont hold but i am pretty close to taking an opening stake here if things keep ticking over numbers dont trend further down and the price stays where it is. I see it perhaps as less risky now than it has been in the past due to the fact it seems to be delivering ref the step change increased profits.
With regards to Volex (LON:VLX) is it really under appreciated or just not as good as we think it is as an investment.
I see a company that has tripled revenues since 2016, turned loss into substantial profit and whose shares have 10-bagged without multiple expansion. That’s the very definition of a good investment. If you draw a line on the share chart from the start of 2016 to today and ignore all the wiggles - and especially the aberration that was 2021 - you’ll see a nice upwards sloping trajectory. And it is less expensive today than it was in 2016.
What’s holding the stock back, as opposed to the company’s performance, are its low margins and poor cash flow conversion, which means that while it is cheap on a P/E basis, it provides a disappointing FCF yield, at only 3.5%. For the multiple to re-rate and provide a boost above and beyond the pace of eps growth, FCF generation needs to catch up with profits growth. Another bull run in small caps wouldn’t hurt either.
Volex (LON:VLX)
Ref the disappointing FCF - i think that probably too be expected - albit the devil is alwasy within the details when acquisitions and capitalisation of spending etc may be at play. They have gone from $615 mill turnover 2022 to $1100 mill expected next year - so it shouldnt really be any surprise the profits have been eaten up with working capitlal and acquyisition related stuff - one would like to hope though that it wont take long for that to reverse and it to turn into lean mean cash generating machine and and when the growth phrase drops down. - havent really looked at the detail but i would perhaps expect this would just naturally happen over the next 24 months - unless they specifically invest for future growth - unfortunately it would make sense them taking improved cashflow and reinvesting - hey ho amazon had little reward for many years as it reinvested and that wasnt a bad business.
Sanderson Design (LON:SDG) That was a great sell, there was a very interesting piece in last week's IC detailing how the business looks to be run for the benefit of the board as oppose to shareholders, targets consistently missed yet bonus shares still awarded with no explanation given.....you can get away with it in a big company with larger revenues but starts look to very iffy when the Board's remuneration outsizes profits.
Could you provide the link for this article? Thanks.
Yesterday quite by chance I discovered that the Investor Meet Company on their Website are using AI to produce a Summary of Results and I listened to Saga (LON:SAGA) Results condensed to 14 minutes.
I have to say it was entertaining and extremely good.Well worth a listen especially if you hold the shares.
Wonder what others thoughts are on the usefulness of this service as another tool in the toolbox? The couple of results I listened to were rather bullish which obviously could just be down to the companies themselves being well positioned.
I will admit to being a tad unnerved at how conversational and natural the voices / presenters were, given all AI generated. Clearly I'm going to have to adjust to any forthcoming AI revolution....
its clever however I wouldn't use it as a shortcut to hearing the whole thing, there is definitely find detail missed out.
*fine and important
Marston's (LON:MARS)
The delivery of the strategy and financial targets are underpinned by a strong balance sheet [Huh? £1.5bn net debt!],
Marstons is a very risky company to invest in imho - but personally I will give them a pass if they want to say their balance sheet is strong - net debt excluding lease obligations is only 885 mill so the 1.5 billion is practically speaking a nonsensical number that includes future rent due on their non freehold pubs
The freehold property they have has indicated market value of £1.5 billion - so on reasonable loan to value calcs the debt is nothing like your quoted figure and does offer some solid tnav backing that can allow them to use the strong term
Imho their issues are more to with their ability to pay down debt than the overall balance sheet - no issues with solvency they could sell up and still have positive tnav - it’s just whether they can continue to service debt and get a positive outcome and if they did sell up whether the surplus would deliver more than current share price.
I see no mention today in the brief update ref paying debt down - there is probably more info available but I suspect them being sketchy suggests they aren’t confident debt will fall quickly. Imho a rerating back to historical higher levels is much more likely only if they can pay down debt materially whilst investing to keep their estate in decent fettle - will be interesting to see if they can reduce debt at all short term !!
Sanderson Design (LON:SDG) and its more bad news bit of a SAGA.
My morning smallcap tweet: Is there life on MARS?
CAP-XX (LON:CPX) Versarien (LON:VRS) Cloudcoco (LON:CLCO) Zytronic (LON:ZYT) 4Global (LON:4GBL) Feedback (LON:FDBK) Eco Buildings (LON:ECOB) Norman Broadbent (LON:NBB) Allergy Therapeutics (LON:AGY) PROCOOK (LON:PROC) Image Scan Holdings (LON:IGE) Marston's (LON:MARS) Sanderson Design (LON:SDG), Volex (LON:VLX), Vertu Motors (LON:VTU)
◄CAP-XX (CPX)► wins 1 year order from smart meter sector in South Africa. Expects contract will lead to further orders from this customer. No $$$. [SP=0.17 Cap=5m]
◄Versarien (VRS)► £450k placing at 0.0325p, a 40% discount, to keep the lights on. No of shares now 3.7bn. [SP=0.06 Cap=1m]
◄Cloudcoco (CLCO)► proposed sale of CloudCoCo Limited (IT managed services business) for up to c.£9.2m or £7.8m max debt-free. Leaves product reseller business. Guides FY24 rev £27m+ and net debt c. £6.9m "reflecting a challenging year due to, inter alia, rising costs".
Trying to raise the tone with some Latin? Well the sale is minus malum toleratur ut maius tollat I suppose. [SP=0.11 Cap=1m]
◄Zytronic (ZYT)► warns FY-Sept rev only £7.2m down 16%. "Trading conditions remained challenging and based on current order intake, the Board does not anticipate a material recovery in volumes over the short to medium term." Strategic review to assess: a new strategic business plan; orderly solvent liquidation; sale of co; delisting; selling assets and continuing as a cash shell. [SP=52.25 Cap=5m]
◄4GLOBAL (4GBL)► wins two-year extension of its framework contract with the Peruvian government. Value significantly higher than the original contract. [SP=45.5 Cap=12m]
◄Feedback (FDBK)► Diagnostic Enhanced Advice and Guidance diversions achieved through the Bleepa platform are now eligible for reimbursement under the NHS Elective Recovery Fund. [SP=38 Cap=5m]
◄Eco Buildings (ECOB)► orders update. One is for €3m, expected to be received in 2025. [SP=9.5 Cap=8m]
◄Norman Broadbent (NBB)► Q3-Sept rev down 16% but marginally up on recent Q2. Market conditions continue to be challenging. [SP=6.5 Cap=4m]
◄Allergy Therapeutics (AGY)► £40m secured senior loan facility with ten year warrants with a strike of 0.1p. Upfront arrangement fee (not disclosed). Interest SONIA plus 9.5%. [SP=4.13 Cap=197m]
◄ProCook (PROC)► Q2 rev up 9%, "a solid platform for profitable growth in the period ahead." In line? Throw me a frickin' bowl here. [SP=25.5 Cap=28m]
◄Image Scan (IGE)► further to July RNS co has agreed and finalised the contract and commercial terms with NP Aerospace for the supply of ThreatScan portable X-ray system. Worth c.£3m over 3 years, subject to successful trial. Profits will be largely recognised in FY25 and FY26. [SP=3.05 Cap=4m]
◄Marston's (MARS)► Capital Markets Day to announce new near and medium-term financial targets including £50m+ recurring FCF and EBITDA margin expansion of 200-300bp. "The delivery of the strategy and financial targets are underpinned by a strong balance sheet [Huh? £1.5bn net debt!], with no material refinancing requirement for at least 10 years." [SP=41.75 Cap=265m]
◄Sanderson Design (SDG)► H1-July rev down 11%. ""Trading conditions at the start of the second half have been more challenging than expected...Delivery of the Board's expectations is reliant on a projected improvement in trading during the remainder of the FY." [SP=77 Cap=55m]
In line: VLX, VTU
Article in the FT yesterday referred to a paper published by Robert Howarth (no relation) of Cornell Uni;
https://www.research.howarthla...
The paper questions the environmental credentials of LNG mainly due to methane emissions surrounding shale gas, that contribute 40% to the total emissions. The report is naturally criticised but since it was in the FT I figure it's worthy of observation for obvious reasons. I don't own Plexus Holdings (LON:POS) .
Interesting that emissions from modern tankers are criticised, despite having greater fuel efficiency and lower CO2 emissions, since it claims methane slippage in their exhaust results in higher total greenhouse gas emissions. The paper goes on to compare LNG to Coal in a positive light.
In related news, seems like a wave of announcements re new nuclear at the moment, micro plant plans in Wales, Google Nuclear AI Data centres, 3 Mile Island etc and so momentum is building which is a positive trend. I have Yellow Cake (LON:YCA) and Geiger Counter (LON:GCL) and am on the look out for more in the space.
Rolls Royce?
Absolutely, somehow I have managed to constantly regret missing this one. Although in fairness it hasn't been nuclear that got the shares going.
Cameco (TSE:CCO)
Volex (LON:VLX) Half year trading update "in line with expectations, with revenues in excess of $510 million"
Reassuring given recent weakness which if it persists would appear to be connected to potential removal of PBR relief (I hold and may top-up)
Paul, thanks for the Gulf Marine Services (LON:GMS) write up, and the very early start to the day!
Thanks Tim! I wrote up my notes yesterday evening. Am trying to do more calls with management of companies that I highly rate, as it really adds value for me, and the readers I think. Time is the only constraint.
Agreed - That is a great interview - Thanks for the time and effort required there Paul - Much appreciated.
Gulf Marine Services (LON:GMS) Excellent questions asked Paul, that was perfect, thank you.
Hi Paul, thanks for the GMS write-up - appreciated. Did you discuss the purpose of the $300m debt facility that they are currently in the process of arranging?
Hi Temeraire,
"Did you discuss the purpose of the $300m debt facility that they are currently in the process of arranging?"
Only briefly mentioned, as it's not really important - just a routine refinancing of the existing borrowing facility - which is used to part-fund the fleet of ships.
Management said that the borrowings are now on normal (and more favourable) terms, because GMS is no longer a distressed borrower. Rapid debt reduction is shown on the slide deck -
agreed fantastic write up ..... the price finishing above 19p for the day. I wonder whether this report was one of the key drivers affecting the share price today