Small Cap Value Report (Wed 17 July 2024) - RM., SOS, RNO, CHRT, HVO

Good morning from Paul & Graham!
That's it for today, we've covered in good depth the top 3 most important companies that readers are viewing the most.
Explanatory notes -
A quick reminder that we don’t recommend any shares. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech, investment cos). Although if something is newsworthy and interesting, we'll try to comment on it. Please bear in mind the "list of companies reporting" is precisely that - it's not a to do list. We typically cover c.5 companies per day, with a particular emphasis on under/over expectations updates, and we follow the "most viewed" list of readers, so if you're collectively interested in a company, we'll try to cover it. Obviously with the resources available, we can't cover everything! Add you own comments if you see something interesting, and feel free to discuss anything shares-related in the comments.
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to, if they are using unthreaded viewing of comments.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. And/or it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Others: PINK = takeover approach, BLACK = profit warning, GREY = possible de-listing.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom), Video update of results so far, June 2024.
Frozen SCVR summary spreadsheet for calendar 2023.
New SCVR summary spreadsheet from July 2023 onwards.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Phil Hanson's data analysis measuring performance of our colour-coding system in the SCVRs, from July 2023- Mar 2024 (with live prices). My video explaining/reviewing it.
My other video (June 2024) - How to screen for broker upgrades on Stockopedia.
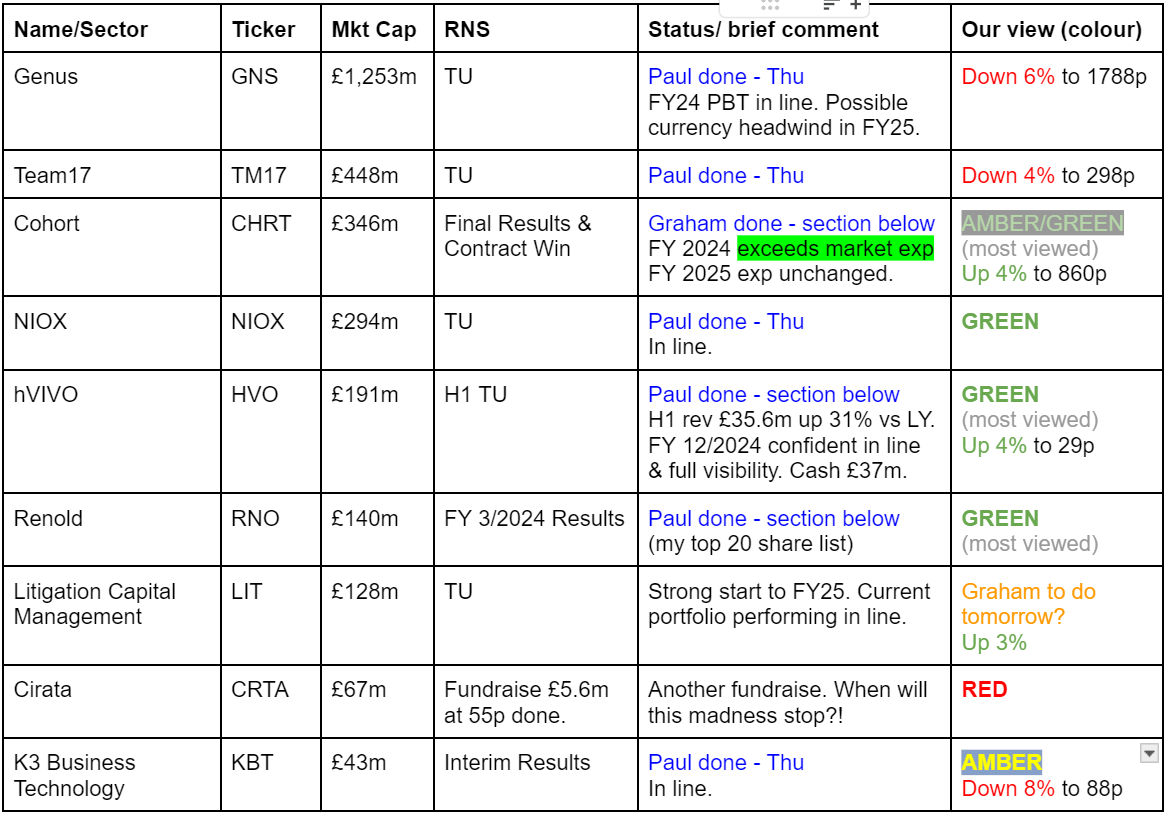
Companies Reporting
Summaries
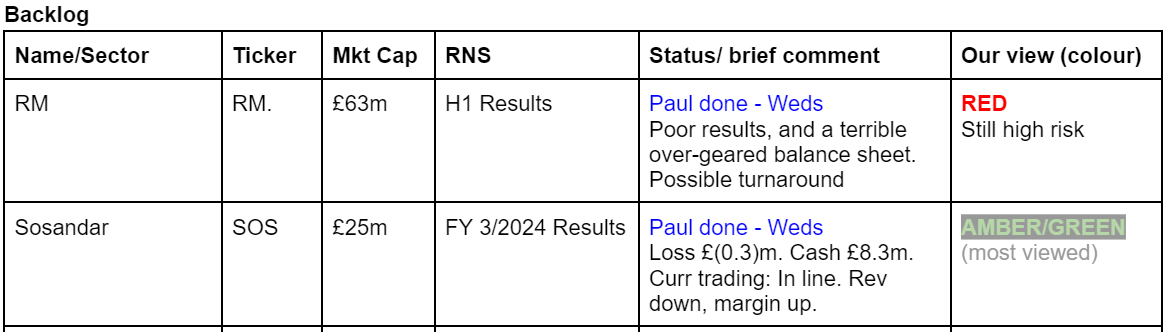
RM (LON:RM.). - down 11% to 75p y’day (£63m) - Interim Results - Paul - RED
Harwood are talking about a good turnaround here, so it could become interesting. However, the H1 numbers look bad to me - especially the over-geared balance sheet. It jumps through hoops to get a clean going concern statement, with covenants very tight in a downside scenario. Considerable risks, so I'm flagging that with a continuing RED. Risk:reward doesn't work for me at the moment, but I'll keep a close eye on it. Sometimes risky situations can pay off.
Sosandar (LON:SOS) - unch 10.25p y’day (£25m) - FY 3/2024 Results - Paul - AMBER/GREEN
FY 3/2024 was a disappointing year. Originally planned to make £3.1m, profit, it ended up at a £(0.3)m loss. Strategy of reduced discounting & much higher margins has kicked in for Q1 2025, I think it's only working due to steep cost cutting. On the plus side, balance sheet is bulletproof, with a third of the market cap in net cash, and excitement could be triggered by imminent opening of 2 physical stores. So I reckon there could be a trade here for a bounce maybe? Longer term, the jury's still out.
Renold (LON:RNO) - 62p (pre market) £140m - FY 3/2024 Results - Paul - GREEN
Strong results, slightly ahead of substantially increased forecasts. This chains maker is turning into a nice quality business, after a multi-year turnaround. Still quite modestly valued, but I raise a flag about seemingly excessive share options (12.2% potential dilution). The pension scheme remains cash hungry. Balance sheet and cashflow are both fine. Modest divi introduced. Outlook comments are too vague.
Cohort (LON:CHRT) - up 4% to 861p (£355m) - Final Results - Graham - AMBER/GREEN
Fine results from this defence stock as had been well-flagged by prior trading updates. The outlook for 2025 is unchanged although the company did announce some fresh contract wins from a UK government customer in a separate RNS this morning. It’s undoubtedly an impressive defence stock but at a PER of over 20x I think it might be greedy to expect further large gains from this level.
hVIVO (LON:HVO) - up 3% to 28.7p (£196m) - H1 Trading Update - Paul - GREEN
Strong H1, thanks to full utilisation, and completing contracts early, with a softer H2 expected. Reiterates full year guidance, but Cavendish raise forecast profit due to better than expected margins. Plenty of cash thanks to customers paying up-front. I continue to like this GARP share, still reasonably priced.
Paul’s Section:
RM (LON:RM.)
Down 11% to 75p y’day (£63m) - Interim Results - Paul - RED
RM plc (‘RM’), a leading global educational technology (‘EdTech’), digital learning and assessment solution provider, reports its interim results for the six months ended 31 May 2024.
Strategic plan driving strong progress in contract wins and business transformation
I last looked at this troubled company almost a year ago, when it issued a profit warning, had too much debt, and issued a “material uncertainty” warning with H1 results here on 9/8/2023. So I had to flag it as high risk with a RED, at 50p back then. Please do remember our colour coding is not meant to predict the future, but RED is just a flag that something serious is wrong. Armed with the facts, you can then decide if you think risk:reward is good or not.
In aggregate, REDs under-perform, but within that some do recover and do well. So for more risk tolerant investors, there can be opportunities amongst the REDs, and AMBER/REDs, if you know what you’re doing.
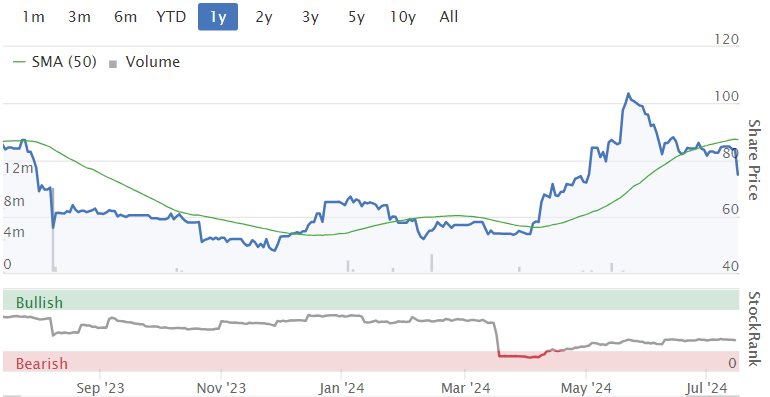
RM shares traded sideways until April 2024, then a strong rally started, although it’s now given back about half of those gains, including a sharp 11% drop yesterday when its latest H1 results came out.
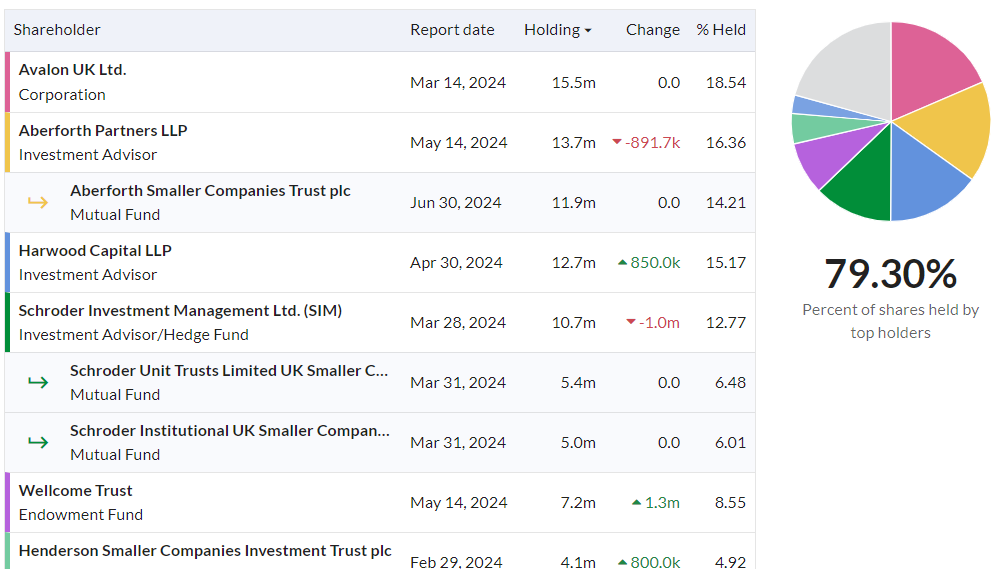
The Harwood stable have a chunky 15% holding, and the shareholder register is quite concentrated, with the top 6 holders holding c.75% - hence deals of some kind (eg disposals, takeover, etc) would be easy to organise here, as only 6 phone calls would be needed to strike a deal. As we know, Harwood is highly effective at getting things done at problem/turnaround companies, and RM has been mentioned positively (as having upside potential) in interviews, eg with Richard Staveley.
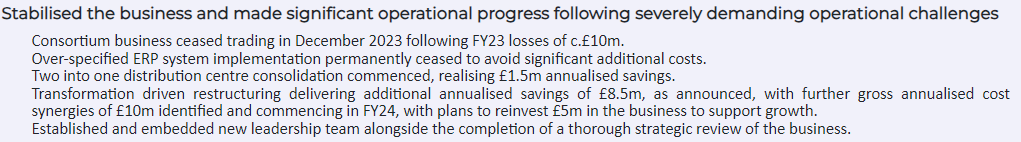
RM has had big problems. Eg this extract from the FY 11/2023 results, published 14/3/2024 gives a flavour -
H1 highlights this time are more like lowlights - note these numbers are for continuing operations, so a disposal must have happened -
H1 revenue down almost 10% to £79.2m
Adj PBT is negative £(3.7)m, although improved from £(6.7)m in H1 LY.
Adj net debt is still worryingly high at £52.7m, which has increased from £45.6m at the last year end, Nov 2023.
Current trading and outlook
Reflecting the shift to longer-term recurring contracts in Assessment, leading to revenue on H1 contract wins being accounted for in future periods, and uncertainty regarding the timing of a general election having impacted UK schools’ spending in H1, the Board now expects full-year revenue to be broadly flat year on year (excluding Consortium)
Trading in H2 to date has started on an upward trajectory in line with our expectation for like-for-like revenue decline in H1 to be offset by H2 performance
Adjusted Operating Profit for the full year is expected to be in line with market expectations
During FY24 we fully expect to operate within our banking covenants, allowing for working capital and capital expenditure required to fund our future growth plans, alongside continuing interest payments and committed pension contributions
Some positive signs on pipeline & order book -
“we have grown the pipeline of assessment platform customers by 70% to £170m, and the Assessment contracted order book by 50%.”
Use of the term “stakeholders” is a good reminder that this company is financially distressed -
“This is an exciting period for RM, and although it will take time for the financial benefits to flow through, I am confident that our strategy for growth will deliver for all our stakeholders.”
Bank facilities - good news that the £70m facility is extended to July 2026. New covenants look non-standard, and too complicated for me to assess -
“Since the year end, the Group has secured an agreement with Lenders, which extends the existing £70.0m bank facility to July 2026. The fixed charge over the shares of each of the obligor companies (except for RM plc), and the fixed and floating charge over all assets of the obligor companies granted previously to Lenders, remains in place. Under the amended facility covenants have been reset as follows:
A quarterly LTM EBITDA (excluding discontinued operations & Consortium) covenant test from February 2024 to November 2025, which is then replaced by a quarterly EBITDA leverage test and interest cover, which are required to be below and above 4x respectively from February 2026; and
A ‘hard’ liquidity covenant test requiring the Group to have liquidity greater than £7.5m on the last business day of the month, and liquidity not be below £7.5m at the end of two consecutive weeks within a month, with a step-down period applying from 15 September 2024 to 24 October 2024 and 1 January 2025 to 21 March 2025, during which the minimum liquidity requirement is reduced from £7.5m to £5.0m.”
Dividends - can’t be paid for now, due to the bank facility blocking divis until net debt is down to 1x EBITDA for 2 consecutive quarters. Again, a reminder this is a financially distressed company.
Pension deficit - good news here, that the cash hungry pension scheme is nearly sorted out -
“The deficit recovery payments of £4.4m per annum will continue until the end of 2024, before reducing to £1.2m until the end of 2026 when recovery payments cease.”
Going concern - in note 1 is a lengthy explanation of why they think going concern should still be adopted. So it no longer contains the material uncertainty phrase that we saw last year. However, I read lots of these things, and this one seems to me quite weak. Included within note 1, it says that in a downside scenario there could be no headroom left on a key bank covenant at Dec 2024, which would require mitigating actions such as stretching creditors (which it admits has been done before) - eg negotiating longer payment terms from suppliers, and withholding staff bonuses. Those are desperate measures only taken by companies close to insolvency. So my view is that the financing situation is clearly tight, and RM does not have much financial headroom to survive an unexpected downturn in trading, were that to happen. So RM remains risky - with an elevated chance of an emergency placing being required, or even insolvency, if trading doesn’t go as planned. So investors need to monitor trading closely, and I would suggest selling on the first sign of things deteriorating. Although to be fair, it’s very rare for listed companies of this size to actually go bust.
Balance sheet - this is the deal-breaker for me, it’s terrible!
NAV is £12m. Deduct £45m intangible assets, and £15m pension surplus (as it’s not really a surplus), gives me negative NTAV of £(48)m. That big hole in the balance sheet is similar to the net debt figure of c.£53m. I think sooner or later, RM will need to repair this balance sheet with an equity raise of about £30-50m. That depends on what profit (if any) it can make once the turnaround measures have taken full effect? IF RM becomes decently profitable in future, then it could support some level of debt, but not this much.
Broker updates - nothing available.
Paul’s opinion - broker consensus data on the StockReport shows a return to profit in FY 11/2024, then tripling in FY 11/2025. IF that’s achieved, then the shares could re-rate. But remember that the net debt of £53m is not far short of the market cap at £63m, therefore I would only put this share on a low PER of say 7x FY 11/2025 forecast, which comes to 53p. The current price is 75p, so I feel this share remains over-priced, as we’re being asked to pay up-front for a turnaround that hasn’t even started to come through in the numbers (it’s still loss-making). Although mgt do explain why they think better numbers could come through in H2.
Good luck to holders, but it strikes me as a complicated, and high risk turnaround situation. The team at Harwood are the experts at this type of thing, so their research is much more detailed than my superficial reviews of the figures. They could be on to something here, who knows, but for me, the risk:reward balance isn’t right. I don’t want to take this level of risk in the hope that turnaround actions might work.
The terrible balance sheet, and excessive debt, means it has to be a continuing RED from me. IF strong numbers come through in H2, then that would be the time to consider improving it to amber/red, but I need more proof first. Support from the bank, extending its facilities, is a positive development though, although those covenants look tight in a downside scenario. It won't be cheap either, I bet the bank have taken their pound of flesh on interest rates and fees.
Remember also with Harwood, that when things get tough, they have been known to screw over small shareholders, eg with onerous convertible loans, heavy dilution, delistings, etc. So they’re not looking out for anyone’s interests other than their own. Hence I find them a double-edged sword when I see them on a major shareholder list.
Sosandar (LON:SOS)
Unch 10.25p y’day (£25m) - FY 3/2024 Results - Paul - AMBER/GREEN
Sosandar PLC (AIM: SOS), one of the fastest growing fashion brands in the UK, creating quality, trend-led products for women of all ages, is pleased to announce its financial results for the year ended 31 March 2024.
They might need to re-think that description, as it’s not really growing any more - due to a (previously announced) strategy to focus on higher margin, full priced sales, instead of chasing revenue growth through discounting.
It traded at around breakeven for FY 3/2024, with an H2 weighting to profits -
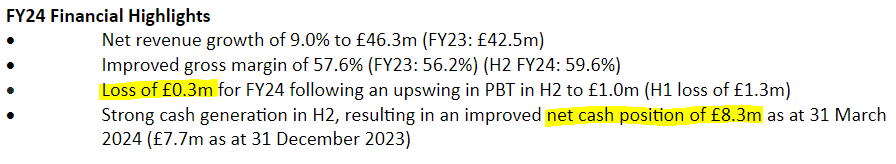
Bear in mind, it made a maiden profit of £1.6m a year earlier FY 3/2023, so the 2024 result is a big step backwards on profitability, back to c.breakeven. But it’s not a disaster, SOS is still in the game, and has robust finances.
Physical stores - the first 2 are set to open in Sept. They are likely to trade well initially, as new stores usually do. Locations are Marlow and Chelmsford. I think a bullish RNS on the initial trading results from the first stores could give a boost to this share price from 10p, so there could be a nice trade here for 10p buyers over the next 2-3 months.
Balance sheet - NTAV is £18m, which includes £8.3m of cash, and no borrowings.
This is very strong, as there are negligible fixed assets.
Current assets are £22.0m, all liabilities are only £5.7m - a very strong position.
Tangible net asset backing is 72% of the market cap.
Inventories seem too high at £10.9m, albeit that is down from £12.4m a year earlier.
Current trading - a striking rise in gross margin, as SOS stops discounting, to achieve high margin, full price sales. It’s gone up a whopping 670bps to a high 63.4%. However, that has come at the price of Q1 2025 sales down a fairly alarming 28% to £8.2m.
Yet they claim a significant improvement in Q1 profitability. That doesn’t make sense to me, so I’ve put the known numbers into a spreadsheet, then a formula to work out costs, as the balancing figure. This shows (below) that Q1 losses reducing can only have come from a large reduction in costs -
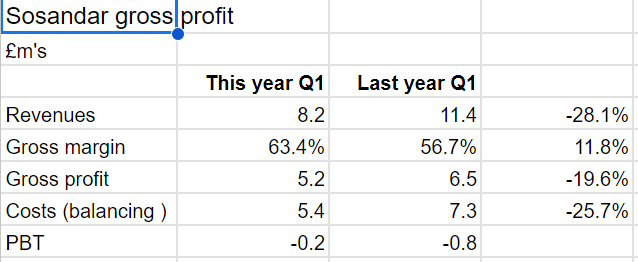
As you can see, gross profit fell 19.6%, so the improved gross margin (up from 56.7% to 63.4%) only recouped about a third of the lost gross profit from sales being down 28%.
I wonder what costs they slashed to achieve this reduced loss in Q1? There would be some useful savings in variable costs from lower revenue, eg lower post & packing, lower warehouse costs for dispatches and returns, but I reckon there must have been a lot less marketing spending too.
So it’s not clear to me from these figures that the less discounting, higher margin strategy is working. That’s a difficult strategy to implement, as I’ve had first hand experience of. You can try to sell everything at full price, but if customers refuse to buy it, then you have to discount it, to shift the product, and avoid a ruinous build up of inventories (as has eg happened at Dr Martens (LON:DOCS) ). It’s ultimately customers who decide how much discounting retailers have to do.
Paul’s opinion - do we see SOS half full or half empty? I think there are strong arguments for both a bull and bear view actually.
Bull
SOS management have created a new brand from scratch, and reached breakeven in a very challenging market.
Very strong balance sheet, with ample cash.
Potential profitable trade from first store openings, if early trading is positive (which it should be).
Low valuation, only £25m, 72% backed by NTAV.
Commercial, hard-working, passionate, and proven management.
Capital-light business model, with hardly any fixed assets, outsourced distribution.
Successfully selling through third parties, such as Next, M&S.
Data - knows exactly where its existing (online) customers live, so should be able to choose ideal physical sites.
Bear
Big profit warning on 18/10/2023, forecast profit fell from £3.1m to £0.1m, and they missed even that, at £-0.3m actual.
Maiden profits in FY 3/2023 have disappeared, only now trading c. breakeven.
Unrealistic (I think) medium term targets of £100m revenues & 10% PBT margin.
Will they squander cash pile on physical store fit-outs (est £200-400k per site)?
Horrible sector, very difficult for smaller players to make money.
Fashion risk, as we’ve seen demonstrated by SDRY, Burberry, etc.
Overall, I’ve historically liked SOS, but that doesn’t matter - we look at every share with fresh eyes every time. I was green on 14/7/2023, but the 18/10/2023 big profit warning shocked me into moving down to AMBER. Then AMBER again on 10/1/2024, and on 16/4/2024.
With the share price now about 20% lower at c.10p, and a reminder today of just how strong the balance sheet is, I’m going to push the boat out a little, and edge up to AMBER/GREEN. I think there’s a reasonable chance of a fizz of excitement when the first physical stores open. That could give a possible 30-50% bounce in share price, I reckon, within 3 months. So it could be a nice little trade. There’s also the chance the market could factor in a full store rollout, if the first few shops do well. And what immediate downside risk is there? Very little I think, considering that robust balance sheet. Longer term, I’m uncertain, the jury is still out.
Renold (LON:RNO)
Down 3% to 60p (£136m) - FY 3/2024 Results - Paul - GREEN
Renold (AIM: RNO), a leading international supplier of industrial chains and related power transmission products, is pleased to announce its audited results for the year ended 31 March 2024 ("FY24").
Record trading performance, significant earnings growth and strong cash generation, dividend resumed
This industrial chains & gearboxes group is a long-standing SCVR favourite. It’s on my top 20 share ideas for 2024, currently up 77% YTD. Actually RNO was also on my top 20 for 2023, and that’s up 190%, so it’s been a good one to stick with.
Very good profit growth, driven entirely by higher margins (increased efficiency from more capex), on almost flat revenues -
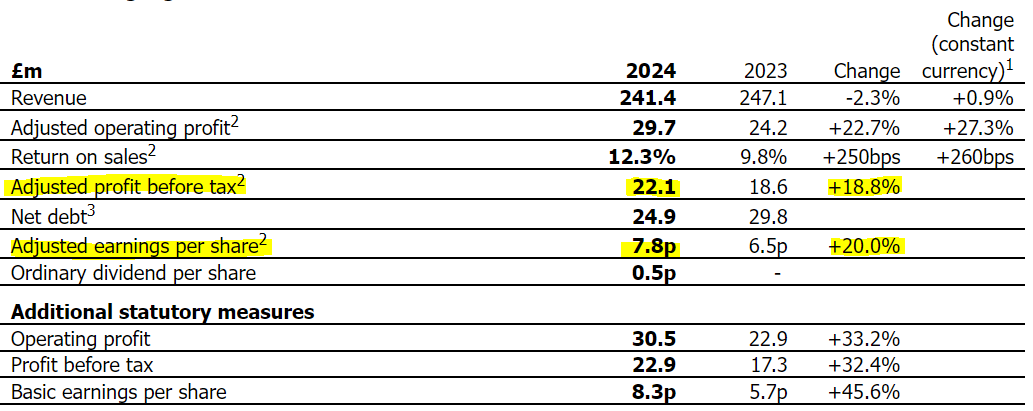
At 62p/share the PER is 7.9x - RNO shares are always cheap because of the large pension deficit. However, this ignores 12.2% dilution from options -
Share options - note that Cavendish uses a lower 6.9p adj diluted EPS figure, so it looks like there are a lot of share options. Yes, here we are note 5 says there are 27.5m nil cost share options, that’s 12.2% dilution, which looks very high. I normally prefer share options to be in low to mid single digit %, so 12.2% seems excessive. We should be valuing this share on the 6.9p diluted EPS number, taking the PER to 9.0x
EDIT: I nodded off, so missed the management webinar today. But apparently mgt said that the share options are not dilutive, because they are paid out of shares held in treasury. Although as we can see from the cashflow statement, the treasury shares have been bought in the market, using shareholder's cash. So that's cash spent on buying shares which could have otherwise been paid out in dividends. It's strange that the results contain the diluted EPS number, and that it's not made clear that there won't be new shares issued.
Dividend - a small divi of 0.5p is introduced, first one since 2005! It’s actually had dividend-paying capacity for a couple of years I think, but has previously preferred to focus on acquisitions instead. This is only a 0.8% yield, but it’s a start!
Adjustments to profit are small, and statutory profit is slightly higher than adjusted profit, unusually.
Net debt is down usefully, but it’s not stretched at only 0.6x EBITDA. Debt has been under control for a while now.
Order book & intake -
Order intake of £227.5m (FY23: £257.5m), impacted by a shortening in duration of the order book in H1, reflecting improved supply chain conditions. H2 order intake up 7.5% over H1 (8.4% at constant exchange rates)
Closing order book consistent with the half year position at £83.6m
I can accept that explanation - it seems reasonable that with supply chains improving, customers would revert to more normal ordering patterns, instead of over and early orders when supply was constrained.
Outlook -
There are various interesting snippets scattered throughout the commentary, here are some excerpts which seem most important to me -
“The business is now at an inflection point where we are starting to see the compounding impact of the many recent exciting initiatives as they come to fruition. We have a very clear strategy and are executing it diligently. Our continuous improvement initiatives are building an increasingly efficient, productive and resilient business and are providing an ever improving platform to support our commercial initiatives."...
I trust management here, as they’ve been straight in RNSs, tell it like it is, and I’ve also found them straightforward in individual calls that I’ve occasionally had over the years.
“The Group has performed admirably in the face of continued supply chain and inflationary pressures. However, the strong and improving trading and financial performance of the Group, particularly increased cash flow generation, is providing greater flexibility to exploit future organic and acquisition-related growth opportunities, while re-introducing the payment of a dividend to shareholders.”
Current operating environment
The effects of the war in Ukraine, especially in terms of higher prices for energy and materials as seen in the UK and mainland Europe were less marked in FY24, only to be replaced with new economic uncertainties brought about by geopolitical factors, such as de-globalisation and re-shoring, increasing trade tariffs and the continuing impact of general inflation, higher interest rates, and growing pressure on labour rates around the world. The volatile operating environment the Group has faced over recent years abated slightly during FY24, however we remain conservative around our timing expectations of a full return to normal, and expect further headwinds to persist to differing degrees in the new financial year.
We have been carefully developing our acquisitive growth strategy and opportunity pipeline. The scale of the highly fragmented industrial chain market is clear and this is the sole area that we are focussed on for acquisitions, providing us with many appropriately sized and relatively low risk opportunities.
Over recent years the business performance has been on an improving trend despite the many economic and geo-political difficulties. Renold continues to demonstrate the strength and resilience of its business, its market position and its business model. We expect the new financial year to be no less challenging, and we remain vigilant as to the environment within which we operate. However, we start the year from a positive position with good momentum and confidence in the capabilities and fundamentals of the Renold business and the markets we serve.
The continuing review of our capabilities throughout the Group is identifying opportunities for the upgrade and development of existing manufacturing processes across our international locations to create higher specification, higher performance products. This review will also facilitate standardisation across more product lines which, in turn, will enable us to benefit more comprehensively from our geographic footprint and economies of scale. In addition, flexibility between manufacturing locations will support increasing customer expectations for supply chain diversification, for risk mitigation and a changing tariff environment, improving even further our value proposition.
What’s missing? - I always expect to see, from every company, a clear statement on current trading and outlook vs market expectations. That seems to be missing from today’s Renold update, which is bound to unsettle some investors. Fudging this issue with more general commentary isn’t enough, and it raises questions. Less is more - are you trading in line with expectations, yes or no? That's what most investors want to hear.
The commentary seems both confident, and cautious, so it’s difficult to know how to weigh up all the above.
Broker update - thanks to Cavendish for a note this morning, hopefully they can clarify what the outlook is like. It says FY 3/2024 is “slightly ahead of upgraded expectations”, so a tick there.
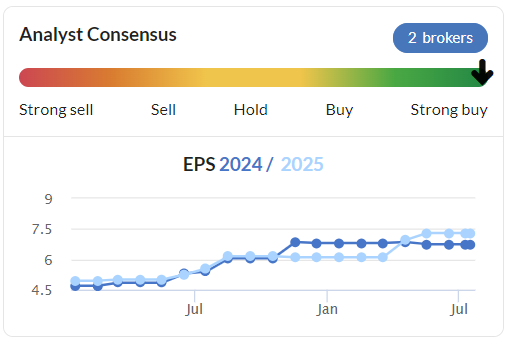
FY 3/2025 forecast is “slightly increased” by £0.1m to £22.8m adj PBT, so only a very modest 3% increase in profit is expected in this new financial year vs LY. That’s fine, and as you can see below, the trend on broker consensus has been excellent so far - big increases already (helped by acquisitions) -
Balance sheet - NAV is £50.2m, up usefully from £39.1m a year earlier.
Intangible assets total £40.8m, not excessive for an acquisitive group. Remove these, and NTAV is a modest £9.4m. However this includes the hefty £57.1m accounting pension deficit. That’s fine, it’s a manageable long-term liability, so if we remove that, the rest of the balance sheet has NTAV of £67m, which is quite good. Working capital is healthy, with a current ratio of 1.68
Overall, this looks absolutely fine to me. Renold was financially stressed in the past, but it certainly is not now - this is a decent setup, and low risk in my view. We obviously have to adjust the PER downwards by a few points to allow for the still cash-hungry pension deficit, which is what the market price of the shares already does.
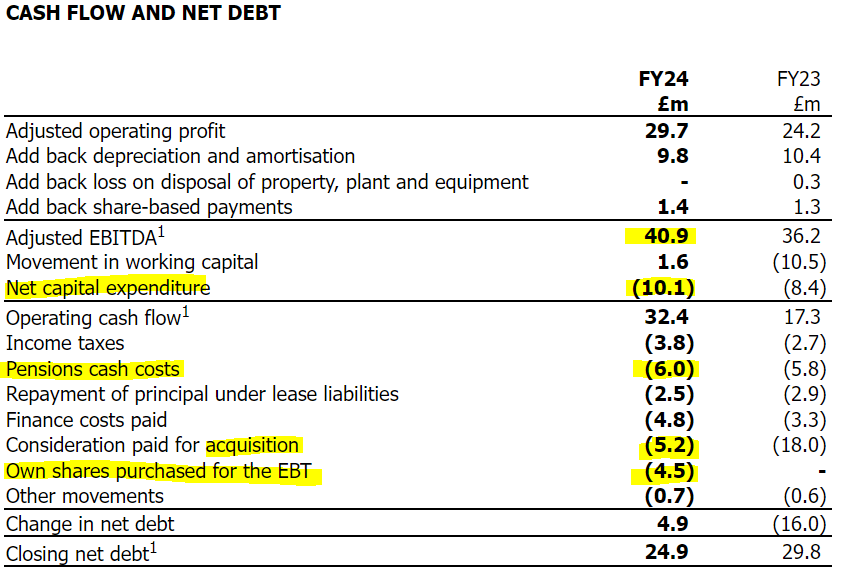
Cashflow - I like this simplified cashflow statement below, where I’ve highlighted some key items. This shows what an excellent cash generative business RNO is, despite the drag of the pension scheme, generous EBT purchases, capex, and an acquisition. It still generated free cashflow after all that lot - so in the long run, this has considerable dividend-paying capacity -
Retail investor presentation with Q&A is at 17:30 today - follow this link.
Paul’s opinion - I think RNO looks good still. It’s been a very slow turnaround, taking many years, but the figures show a transformed group, making a healthy 9.2% PBT margin, with a sound balance sheet, modest debt, and a credible buy & build acquisition strategy in a fragmented market, where Renold has a long-standing premium brand name.
It's a quality business, priced like a value share, so I see further potential upside in the share price, longer term.
My only reservations are that the outlook comments ducked giving us a clear indication of how FY 3/2025 is progressing vs market expectations. That introduces some doubt, together with some caution in the commentary.
That said, forecasts have already been greatly increased, so I think it makes sense to pause for breath and keep expectations grounded for now.
On fundamentals I’m happy to stick at GREEN, but think the short term price is maybe up with events for now?
Also I think we need to challenge management on the apparent overly generous 12.2% potential dilution from share options, although only a small proportion of those have actually vested so far.
Note that the employee benefit trust is now the biggest shareholder, with 12.1% - I like that a lot - certainly a great way to motivate & retain staff, let's hope it's not just management who benefit from this. I’d like to see more companies do this. Although of course shareholders have paid for these EBT shares, whilst only now receiving a small divi for the first time in 19 years! So maybe there’s an imbalance there in terms of who benefits from Renold existing? There again, look at the share price, and I don’t suppose anyone will be complaining at having a six-bagger from the lows. With time, I think it’s going higher too, with 100p looking achievable with patience, I reckon. Providing nothing goes wrong of course.
hVIVO (LON:HVO)
Up 3% to 28.7p (£196m) - Trading Update - Paul - GREEN
hVIVO plc (AIM & Euronext: HVO), a fast-growing specialist contract research organisation (CRO) and world leader in testing infectious and respiratory disease products using human challenge clinical trials, provides a trading update for the six-month period ended 30 June 2024.
Record H1 revenue and EBITDA margin
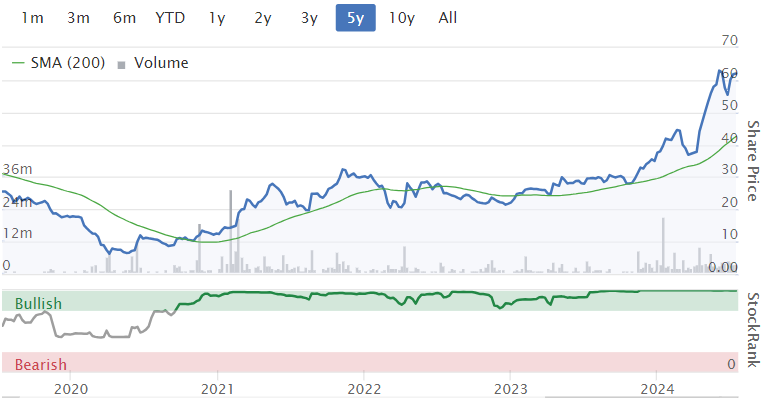
We like HVO here at the SCVR, and have been consistently GREEN on it this year & last.
It seems a reasonably priced growth company. I reviewed its impressive FY 12/2023 results & outlook here on 10/4/2024.
H1 highlights today -
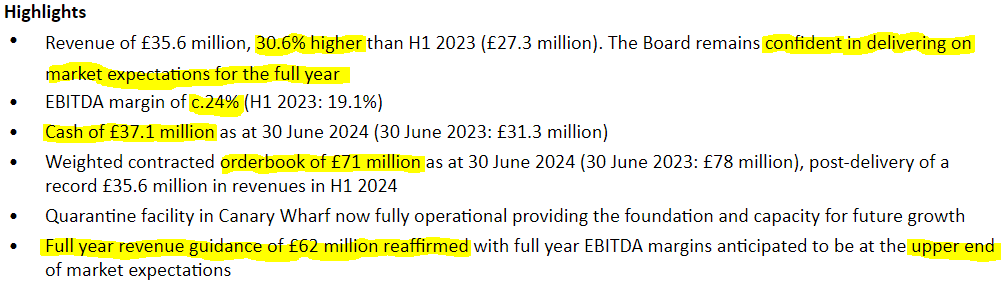
My comments - very strong H1 revenue growth, although the full year guidance of £62m revenues suggests a slowdown in H2 to only £26.4m, down 26% on H1. That looks odd - does this mean they’ve set the forecasts low to be beaten, or that H1 was an unusually strong period?
Striking increase in EBITDA margin to c.24%, up from 19.1% H1 LY.
Order book actually down 9% from the same point a year ago, which again might point to an unusual burst of activity in H1?
This bit seems to confirm that H1 was unusually good. I don’t understand why moving to the new Canary Wharf site sounds like it’s reducing revenues, surely it should be doing the opposite? -
“During the period the Group was able to utilise its three quarantine facilities to deliver a number of projects ahead of schedule which provided a boost to revenues and margins. This has contributed to a H1 revenue weighting for 2024, from July 2024 the Group will solely operate from its Canary Wharf quarantine site.”
More on that increased EBITDA margin -
“The increase in margins is a positive indicator of the margin achievable in the medium term for the business with the Canary Wharf site expected to deliver improved operational efficiencies.”
Cash - HVO benefits from receiving cash up-front from customers, and it now has £37.1m, flat against £37.0m at end Dec 2023, but up nicely vs £31.3m cash at end June 2023.
Orderbook & visibility - the orderbook gives us advanced notice of trading, and I have to point out that it has fallen - let’s hope this is a blip, and not a sign of demand peaking? Great news that we can relax about FY 12/2024, with the whole year’s revenues now seemingly in the bag -
The Company's weighted contracted orderbook stood at £71 million as at 30 June 2024 (30 June 2023: £78 million), with 100% of FY 2024 revenue guidance already contracted and good visibility into 2025. The orderbook value as at 30 June 2024 reflects the exceptional operational delivery of £35.6 million revenue in H1 2024, including the acceleration of several projects contributing to a faster conversion of contracted work versus previous periods. hVIVO has a broad pipeline of live opportunities, including a number in advanced stages, making the Group well-positioned to increase its weighted orderbook going forward.
Outlook - sounds positive to me - with positive newsflow on contract wins sounding likely -
“The Group reaffirms its full year revenue guidance of £62 million and anticipates that EBITDA margins will be at the upper end of market expectations on the basis of the strong performance in the first half of 2024 and full visibility for the remainder of the year. Its organic growth strategy is also underpinning the Group's medium-term revenue target of £100 million by 2028, the majority of which is expected to be achieved through sustained organic growth complemented by small, strategic bolt on acquisitions.”
“ In addition, the current sales pipeline includes several advanced stage opportunities that we expect to convert in the coming months. “
Brokers - any changes today to forecasts? Cavendish updates us (many thanks).
Forecasts for both FY 12/2024 and FY 12/2025 have been raised by 6% and 3% respectively, due to higher EBITDA margins being plugged into the spreadsheet.
12/2024 goes up from 1.25p adj EPS, to 1.32p (PER 21.7x)
12/2025 goes up from 1.48p to 1.53p (PER 18.8x)
Those PERs look reasonable to me, for a nicely growing, good margin, niche business.
Cash is forecast to keep building, to £46m by end 2024, and £57m end 2025.
Balance sheet - is pretty good. At Dec 2023 NTAV was c.£29m, which only supports just under 15% of the market cap. So this share is all about earnings & cashflow, not assets. Remember a lot of the cash pile is timing-related - receiving cash from customers before providing the service, so I’d be careful about using enterprise value figures here.
Dividends are tiny - surely it can now start paying proper divis now the business is more established? Forecast divis for 2024 & 2025 are less than 1% yield, I’d want to see it doing a lot better than this.
Paul’s opinion - unchanged, I see HVO positively, so am happy to give it another GREEN.
It seems a reasonably priced, GARP share (growth at reasonable price).
My only reservation is that big profit margins always attracts competition, sooner or later, if there isn’t a strong enough moat of IP. I’m not convinced the moat here is strong enough to prevent that happening eventually. After all, HVO built this business quite quickly in recent years, so why couldn’t someone else do the same, if they have the expertise and some startup funding? Hence why I think it’s not a share to chase up to expensive levels. Thankfully it’s not expensive, with a 2025 fwd PER of 18.8x, and comfort of plenty of cash sitting in the bank.
So I remain positive, and let’s hope the forecasts are beaten again, which HVO has a history of doing. Yup, it’s GREEN for me!
Graham’s Section:
Cohort (LON:CHRT)
Up 4% to 861p (£355m) - Final Results - Graham - AMBER/GREEN
A powerful headline from this defence stock, for the full-year results to April 2024.
Record revenue, adjusted operating profit and order book of over half a billion pounds. Further progress expected.
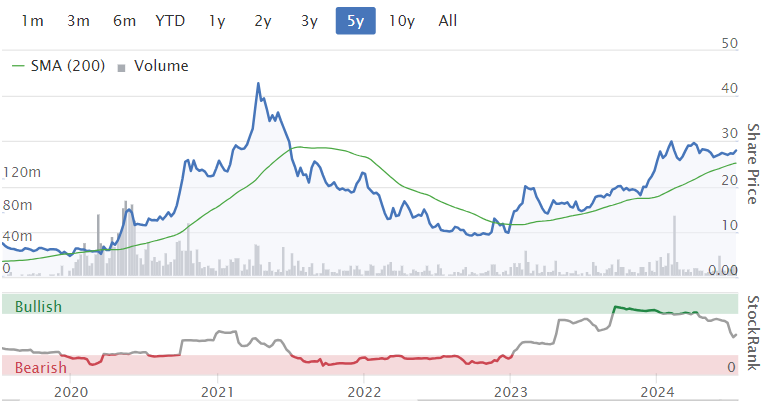
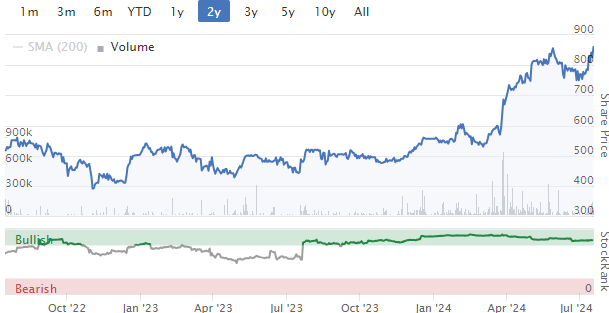
The share price has caught up with the story:
And the optimism is backed up by a very strong set of headline numbers published today. Some key bullet points:
Revenue +11% (£202.5m)
Adj. operating profit +11% (£21.1m)
Adj. EPS +18% (42.89p)
Dividends are increasing by 10%, after the company finished the year with net funds of £23.1m.
As noted in the headline and previously disclosed in trading updates, Cohort’s order book is £519m as of the year-end (last year: £329m). The company took in nearly £400m of new orders with long-term delivery dates extending all the way to 2037.
Orders for short-term delivery were strong too, covering “over 90% of current market revenue expectations for 2024/2025”. Since year-end, that has increased to over 95%.
Chairman comment excerpts:
…We have good prospects to secure further long-term orders for our naval systems and support work…
We continue to expect another year of good growth in trading performance in 2024/25. Given planned capital expenditure and expansion in working capital to support our record order book, net funds are likely to decrease.
We are optimistic that the Group will make significant further progress in 2025/26 and beyond, based on current orders for long-term delivery, our continued investment in the businesses and our pipeline of opportunities."
Later, the Chairman emphasises the Ukraine conflict and “persistent tensions in the Asia-Pacific region” as helping to drive global defence spending and in turn driving up Cohort’s order intake.
Earnings adjustments: it’s pleasing to see that there is almost no difference between actual operating profit (£21.1m) and adj. operating profit (£21.1m). A big reason for this is that Cohort benefits from R&D credits (£2.9m), and these offset the cost of amortisation in the list of adjusting items.
Graham’s view
First off, I should say that I have limited knowledge of the defence sector. But there are some traditional pros and cons when it comes to defence stocks such as Cohort:
Pros:
Companies can benefit from long-term contracts, e.g. Cohort’s naval orders.
Customers (governments) are extremely unlikely to default or pay late..
There is always going to be a baseline level of defence spending from Western governments..
Cons:
Contracts are lumpy, i.e. large and unpredictable. For example, the new £135m contract from the Royal Navy which Cohort acknowledges has “distorted some of the value comparatives”.
War and politics are unpredictable, and demand will fluctuate accordingly.
My general assumption is that defence stocks should trade at average or slightly below average P/E multiples.
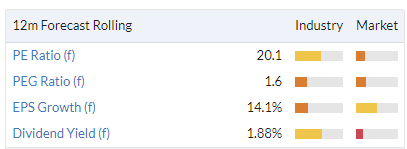
Stockopedia has noticed this too, and thinks that Cohort’s valuation is quite rich:
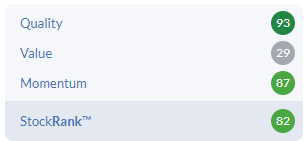
The ValueRank is only 29:
Against that, you have a company experiencing wonderful momentum, both in its share price and in new orders. A separate RNS today reveals £21m of orders from “a UK government customer”, for delivery within a year.
When Paul covered this stock in May, he acknowledged that the valuation had reached a fair level, but kept his positive stance due the company’s excellent momentum. The share price then was 807p.
At 861p, I think it’s reasonable to make a slight adjustment. I’m going AMBER/GREEN, as I think the easy money has already been made here.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

121 comments
My view on EVs has for some time been that batteries should have standard connections and be replaceable. On Twitter I saw footage of a Chinese approach where batteries are swapped rather than recharged - car drives onto platform, is lifted up, battery is removed by an automated arm and a new one inserted. Job done in 30 seconds. Separate the battery from the car and a lot of the charging and depreciation issues go away.
Cohort (LON:CHRT) (I hold)
Hi Graham
Thanks for your write-up.
It was interesting reading your thoughts that "defence stocks should trade at average or slightly below average P/E multiples."
I must admit to actually giving the company a higher rating because it is a defence stock, with a lot of recurring orders, but perhaps my thinking is incorrect?
A couple of additions to your commentary if I may:
ORDER BOOK + MEDIUM TERM REVENUES
I really like the additional Order Book detail provided by the company as one large Order Book number that stretches out to 2037 doesn't tell us very much.
Accordingly it was good to see the material increases in FY+1, FY+2 and FY+3 order book revenues from FY23 to FY24 (£142.7 ---> £184.1, £71.2m ---> £105.9m, etc...)
This bodes well for the medium term.
MARGINS
A few months ago management mentioned that the medium term target was for the company to have a net margin of 12% up from the 7.5% achieved today.
In the call today (there's a transcript on the website) the company as much as indicated that the margin is already going up by 1% in FY25 vs FY24.
I think it's perhaps also worth highlighting that Adjusted OP margins hovered around 19% in the years before covid, in contrast to the 15.5% reported in FY24, which was the lowest it has been since 2016.
The higher 12% net margin target therefore doesn't seem so unrealistic when compared with historical figures.
The combination of both higher revenues and higher margins bodes well for the medium term.
CAPEX + CASH GENERATION
There will be a one-off £12m increase in FY25 capex, bringing total capex to £17m for the year.
Even with this I predict that the company will be easily cash flow positive (before working capital movements.)
Capex is then expected to drop back to £5m pa in the medium term.
I'm personally hoping for FY26 cash generation of c£24m vs a current EV of £330m.
Apply a high multiple and there's definitely a lot of upside to come; of course if you're correct and a lower multiple is required then perhaps the share price is indeed up with events.
---
Some final points that I think are worth mentioning:
Cohort (LON:CHRT)
"defence stocks should trade at average or slightly below average P/E multiples."
I'm not sure that's actually the case?
BAE Systems (LON:BA.) trades on a forecast 17.6x
The aerospace and defence sector on 19.2x
FTSE100 is on 13.9x
I can see where the impression comes from - traditionally defence contractors have been high capex large metal-bashers dependent upon long term government hand outs. Not so much nowadays.
I'm not sure that average figures are particularly helpful as the defence industry is not a homogenous grouping and even less so with respect to the smaller firms.
Cohort (LON:CHRT) is not even included in the Defence and Aerospace sector - its listed in the technology sector. Which may be a more accurate way to look at its prospects?
There are a couple of points in my mind
[1] Defence spending is forecast to rise significantly. Given the constraints on government budgets this will takes years - and I expect current forecasts greatly underplay the eventual level of defence spending required now that the peace dividend is clearly illusory. We should expect multiples of successfull defence companies to be higher for some time?
[2] Defence is changing very rapidly. There will be winners and losers as faster adoption of newer technology - particularly unmanned technology in terms of sensors, effectors and intelligence play a bigger role. This effect is additional on top of the general increase in spending.
[3] The biggest impact upon a defence companies prospects happens when it develops the right technology at the right time - capturing large export markets.
Cohort (LON:CHRT) seems highly rated as a traditional defence company. Not so much as a technology company. If it turns out to have 'must have' technology it's not expensive at all.
Having said that I agree that the easy money has been made.But whether the price is now up with the story depends a lot upon the detail of the story - and that needs a lot closer look at the technology and prospects that I've not done,
cheers
Mark
I think the biggest change in defence spending is the shift from heavy metal bashing into cyber risk. My son works for a government-focused management consultancy with a strong specialisation in defence. And it’s all about cybersecurity. Perhaps that reflects the skill set of the consultancy’s staff, but I’m hearing the same from other sources.
Renold (LON:RNO)
Tuned into the investor presentation tonight - slides here. CEO and CFO both came over well IMHO - relaxed, confident and competent. Kicked off by emphasising that while UK HQ'd, this is nonetheless a global business with bases across the world and only a small percentage of sales in the UK.
Pension. Slide 11 makes the point that they are executing on a plan to manage both their main UK and German pension schemes. The aim is for the UK scheme to become self funding by 2031 and for the liability associated with the German scheme to have halved to £9m by 2032.
EmployeeBenefitTrust share purchases. They were at pains to emphasise that these shares were purchased from the open market and earlier in the year at prices lower than today. No dilution of existing shareholders. Furthermore this a one-off top up of the trust while the SP was low, rather than something we should expect every year. CEO said that performance targets are mostly in relation to a 5-10% increase in eps, with smaller awards against lower targets. This suggests this is more of a senior management annual incentive scheme, rather than the kind of broader scheme Paul might have admired.
CEO ended by confirming continued opportunities for M&A in the fragmented Chains industry and saying how excited he was by prospects in the US market particularly, where he saw many businesses moving their manufacturing bases back from the far east.
Just to add to the pro EV debate, I have had a Tesla since 2016. Now have 150 000 miles on it still with the same brake pads and disks! It basically doesn't need servicing. Battery failed at 60 000 m and was replaced under warrantee. Only had four sets of tyres. Great car, love it, saves me around £8k a year over a dirty diesel.
Just to bring it back to the stock market, companies like Ilika are quietly doing great things. Their solid state battery has achieved power density parity with lithium but no lithium of fancy metals required and they are not flammable and charge much faster. Also Gelion worth a look. The future may exist within AIM.
Yes llika does look to be progressing very well with its battery. I wish them good luck and great success.
A solid state battery only refers to there being a solid electrolyte instead of liquid or gel - it doesn't preclude the use of lithium, either as an oxide or as a metal. Quite a few of the proposed solid state batteries are using lithium oxides because of the energy density theoretcally available. llika are using an oxide but don't state whether or not its lithium.
Either way it's a very different beast from the li-Ion cell and very promising. I'd go so far as to say its progressing faster and better than I'd expect - but that may just be me being taken in by the marketing blurb. Interesting that they are working with MPAC (LON:MPAC) on the production line?
cheers
Mark
Not sure what started the anti-electric car thread but I feel there needs to be some balance on here.
I constantly read arguments against electric cars which are often from people who have not owned one. I bought an iPace 5 years ago and absolutely love it. We recently bought my wife a Model 3 and its even better (for range and charging)!
Here are the reasons for owning an electric car:
1. They don't pollute your local neighborhood. The school kids in your local primary school won't have to breath in the nasty additives that combustion engines spew out and are known carcinogens.
2. The CO2 argument is complex and I am skeptical about many CO2 calculations. However if the electricity grid were powered from nuclear power stations then the electric car would only produce CO2 during production.
3. I never have to stand in a fuel station. I spend almost zero time charging my car. It happens overnight. This makes me happy as refueling cars is not a chore I enjoyed.
4. Its very quiet.
5. It has the acceleration of a top end petrol car at a much lower price tag (the Tesla model 3 at least).
6. The model 3 recharges at 500 km/hr (when low on charge) at a supercharger, and they are everywhere.
7. The iPace has done 35000 miles on its original tyres. My 3 previous Audi's got nowhere near that. Not sure who started the rumour about excess tyre wear but I have found the opposite.
8. The Pace battery is still giving me 240miles (about the same as the original range)(270 is the nominal if you drive like Miss Daisy).
9. I've spent £200 every 2 years on servicing (there is nothing to do). A fraction of my old diesel Audi's (there was always something that needed doing apparently!).
10. On long journey's you need to take a break before you get to 300 miles. The Tesla charges so quickly you barely have time to go to the toilet and drink your coffee. So it's not an issue.
11. Maybe I should have put this at the top. I pay 7.5p/kWh charging overnight. The Tesla does at least 270 miles (normal driving) from 90kWh which is around 2.5p per mile. I believe a good diesel cost around 15p/mile in fuel.
You always hear people saying that it would make driving around Europe difficult and you couldn't go off-roading in the alps. True but that is not normal driving and can easily be managed in other ways.
I realize this is not SCVR stuff, but the car market is, and I felt there needed to be some points put forward for the reason so many people now own an electric car. If I had to change one of the cars tomorrow then I would only consider another electric car.
Tesla superchargers are not everywhere, the nearest one to me is about 30 miles away. There are very few in rural locations.
Diesel is about 11p a mile.
Cost of a Tesla? And depreciation against a 5 year old petrol car?
the whole point at present is that we havent reach price parity yet if you are on a budget and clearly ev's are not for everyone as we should all expect with only 10% of cars on the road being ev.
ref diesel being 11p a mile - it may be for you but the offical hmrc rate for the mid size diesel car is 15p per mile so the 15p is imho the perfect benchmark rate to quote
https://www.gov.uk/guidance/ad...
ref cost - i think tesla model 3 (basic) and bmw 3 series are about the same price new
I just noticed this story today - MG are offering a lifetime warranty on their EV batteries. MG announces an extended lifetime warranty for High-Voltage Battery, Electric Drive Unit, and Power Electronic Bloc being the first and only brand with the guarantee of confidence for EV owners (mgcars.com)
oh dear - does that mean they wont be around in 9 years time ? (sarcasm alert)
I personally found that regardless of the available public charging infrastructure what has put me off is the number of apps etc that you have to sign up to get a car charged publicly. Some will do it on a tap card basis, other require pre loading of £'s before charging. Compared to 'normal' cars its a right old faff, and not particularly consumer friendly, as providers are each trying to recoup a bit of margin for providing the service.
Octopus have provided a general card so that you can use this on public charging sites, but I gave up with all that and rely on a home charger for my Hybid, which of course is an additional fitting etc charge in itself.
Also fully charging an average electric car is not particularly quick on a public charging site if you can find a reliable charger.
EV champions/evangelists wont be put off I guess, but the slightly wary end of the market will take more convincing for a number of reasons.
Of no interest to myself as I am keeping my Passat Blue Motion for as long a spossible but in another way and this is my holding of shares in Good Energy (LON:GOOD) which owns a chain of public car chargers.
I agree with Graham's view on Cohort (LON:CHRT), the easy money has been made and now it's the time to run the winner if you got in before the rally but not expecting huge raises anymore but who knows, Mr Market is unpredictable.
Regarding Renold (LON:RNO) the possibility of a big dilution is something that put me off
Personally I wouldn’t touch an electric car atm. The batteries produce that much co2 to make them that they need to do about 90k miles before you see a reduction in co2 compared to a petrol car. And the batteries are not lasting that long! So it’s a big con as electric cars are worst for the environment in terms of co2. Also, because the battery life is not long enough electric cars depreciate quicker in value despite costing a lot more to buy than a petrol car. Then because the batteries are so heavy, the tyres wear out 20% quicker than a normal car. And ofc there is the charging of them, not enough chargers and it costs similar to petrol to charge them. I would be interested in knowing what percentage of people can actually charge up at home. I’m guessing 60%+ can not charge at home. So for the common people, electric cars cost more, cost more to run, depreciate quicker in value and are actually causing more co2 to be released into the environment. Sounds like a bargain to me!
There are some fair points (tyre wear, lack of public chargers) but most of your post is nonsense gleaned from ill-informed internet speculation. Battery tech is constantly improving with regard to the carbon cost and life is constantly extending with each iteration. As for the cost of a “full tank”, it’s about £13 a charge. How much do you pay at the pump - £60, £70, £80? Then there’s the much lower cost of servicing and maintenance. I don’t like the extra weight because it dulls the driving experience and it’s not green to swap out of a perfectly good ICE car. But the arguments in favour of EVs get stronger with each new model.
Agree, no shortage of FUD when it comes to EVs, and it gets a bit dull seeing the same tropes coming round again and again. Haters gonna hate...
On some points of order I would say £13 is steep - a decent EV tariff is 7p/kWh (ie £7 for a 'full tank' for me). Having recently driven a petrol car (VW T-Roc 72 plate) for a week or so I would say the ICE driving experience is terminally dull - the total lack of power and acceleration took a while to get used to. But it was pleasantly efficient compared to the last ICE I drove (I managed 50mpg, engine cut out when stationary reduced consumption, dropping to 2 cyclinders when coasting, decent features), although the 400g CO2/mile cost at the tailpipe somewhat dwarfs the 30g (or less) CO2/mile from the EV (and never mind the colossal embedded CO2 cost of getting the fuel from the ground to the pump). Also it is probably always green to swap out of a good ICE car, as that will trickle down the 2nd hand market (and at the end of the chain push an old inefficient ICE off to the scrappy/recycler..)
They will improve for sure. Just not convinced they will be good enough for a few years yet. £13 a charge is good then. I read and thought it was quite a lot higher. Currently I pay £45 for a full tank. Albeit it’s a small tank but I do get 660 miles from it.
A friend of mine does drive a Tesla. He loves it. It he has also had to have the battery replaced twice at £15k a time. He’s just glad it’s a company car and has not had to pay for the replaced batteries.
It he has also had to have the battery replaced twice at £15k a time.
are you aware that Tesla do 8 year 100k mile warranty on batteries?
https://www.tesla.com/en_gb/su...
8 years or 100,000 miles, whichever comes first, with minimum 70% retention of Battery capacity over the warranty period.
It’s great to hear everyone’s opinions on ev cars. Very interesting.
I did expect Tesla provided a warranty on the battery but didn’t know the details. My main point of a battery being replaced is the co2 cost of it. Is it greener when the battery needs replacing? Which leads to the question of how many batteries need replacing under 100k miles and how many miles will they last on average?
Ev cars are undoubtedly greener locally.
The next question would be, how many people in the uk are capable of charging up at home?
I think if you can charge up at home and have solar panels then there is a very strong point in getting one. It may well be worth considering buying a storage battery for the solar panels too. I believe Tesla sell them for the home. Ofc something else worth investigating is if you can actually get someone who repairs solar panels. There are plenty of installers but getting someone to repair can be a nightmare. At least it was for my mother.
I think you do need storage battery if have solar panels, as most of the electric is generated at not the time of most demand. Tesla do batteries but they were expensive at around £10k, probably cheaper now.
My main point of a battery being replaced is the co2 cost of it. Is it greener when the battery needs replacing?
I guess thats open for debate i wont dispute that these cars might not be as green as they appear. Obviously if batteries fail and need replacing each replacement needed ups the co2 costb thats an obvious given.
Which leads to the question of how many batteries need replacing under 100k miles and how many miles will they last on average?
I hadnt realised the link i had previuously quoted had excluded cars with replacement batteries - so the data linked is likely not then full picture - its not inconsistent with the Tesla claims of 85% average after 200k miles though -(i wouldnt necessarily trust their stats) ideally i would want full recent survey factoring in duds. It depends what you are looking at though duds matter for co2 numbers but if its in warranty duds they probably dont matter for owners as its no loss to them. I am struggling to easily find meaningful data of dud numbers - they appear to be very low percentages but i cant find a proper good dataset - preumably well under 10% at 150k miles i would guess though - even less at 100k - i dont have link to back that up with proper scientific numbers sketchy link below thats eems waaay ton good to be true.
https://www.teslarati.com/stud...
The next question would be, how many people in the uk are capable of charging up at home?
it looks like 1/3 of households dont have driveways or garages and only 56% were reported as having homes ready for charging at dec 22. Something between those 2 numbers i would suggest at present . The obvious solution in towns is to put cables in street with pop up bollards - thats one for the future though.
Hopefully solar and battery will continue to improve what is a work in progress now - clearly battery tech should be more advanced in 5-10 years time and cheaper to boot - that could have all manner of benefits when it turns up helping grid stability etc - at some stage the cash will need to be spent on infrastructure that is for sure. Ref solar fixing stuff - thats always an issue when stuff is niche - one would hope over time the skills arrive to support what is needed.
So to me good progress has been made to date bearing in mind its only really been mass marekt the last 5-10 years at noin silly prices - they will need to be the whole package long term though with infrastructure spending needed - i am positive but the proof of the pudding is in the future so i am not going to bother arguing with someone who takes the alternate point of view - time will prove ev's a winner or not at least we are in position to push forward if they can deliver range and reliability at the right price point.
But the 5 year old EVs only have a range of around 100 miles, on a good day. A 5 year old e Golf is around £12k, not too bad. But if the battery goes then it is a write off. Petrol, l hardly pay anything. When l had a diesel l filled up about 3 times a year. Now l'm filling up about every 3 months, mpg about 54.
lnsurance, how much is that a year? Tax and servicing should be lower.
If l had solar panels, l would consider an EV in a few years time.
Thanks for all the posts on ev cars. I’ve really enjoyed reading them. So much better getting facts from actual drivers than reading up on news reporters who we all know are not to be trusted.
BnB - you mentioned it costs to £13 for a full charge- what distance do you get out of that? Also have you noticed a big difference in milage between winter and summer? Cheers in advance.
I filled up my car today. Cost me £24.25 for 340 miles since last filled up. (I actually pay £22 as I use a fuel card). I worked out the mpg between the last two fill ups to be approx 90mpg.
picture is showing how many miles I get on full tank and average mpg over 16k miles.
BnB - you mentioned it costs to £13 for a full charge- what distance do you get out of that?
I don’t have an EV. That’s a prudent figure taken from my research. Some claim only £7 per charge. As for distance, my working assumption is 200 miles, so that’s the equivalent of 90 miles to the gallon. Or 170 miles if you take the lower cost estimate. Now, you can just about get the lower mileage out of a small capacity diesel. But you’ll be polluting the air with your poisonous particulates, no matter how good the filters. And spending far more on repairs and maintenance. So it’s not a simple calculation.
I’m playing a waiting game while my 8 year old 3 series petrol estate, which any petrolhead will tell you is all the car you’ll ever need, and refined over half a century to the point of perfection, continues to perform superbly. I gave it a mid-life refresh 3 years ago with all of BMW M Performance division’s performance upgrades (engine, exhaust, brakes, LSD) and it was like having a new car for a surprisingly small outlay. Best upgrade I’ve ever done.
Apologies for the enthusiast digression, but the pleasure I take in my ICE vehicle is buying me time to let technological progress bring the electric world to the point where the case in favour is irrefutable. I don’t believe that point is far off.
Also, because the battery life is not long enough
There is alot of nonsense spoken on both sides of the debate - if we specifically look at Teslas in the US real world data suggests the average charge left after 230k miles is 80% plus.
https://www.nimblefins.co.uk/s...
? The data from the study shows that the average Tesla battery still regularly provides over 90% of the original range up through 100,000 miles or more on the odometer. Past 125,000 miles or so, the range starts to drop off, but cars in the survey still delivered over 80% of their original range even at the highest mileage levels.
For example, the handful of cars with 200,000+ miles were still getting 81 - 87% of their original range, equivalent to over 200 miles.
Obviously not all manufacturers will produce cars as reliable at Tesla and i would expect uk performance to be less good but i dont think by any stretch of the imagination you could say that is "not long enough" if you get the right car and its gets the average performance and you do the average uk petrol car range of 6k miles per year - in theory there should be no issues ref battery life on average.
I’m guessing 60%+ can not charge at home
Thats till leaves 40% who can and thats the point at present - these cars are heavily targeted at that 40% group !!
it costs similar to petrol to charge them.
Providing you charge on cheap overnight tariff at home its much cheaper than petrol
cost more to run
Well you point out all the down sides here and non of the up sides - cheaper fuel , less parts , brake pads should need changing less often. I wouldnt gaurantee its much cheaper but i would bet there are plenty of people who have found it cheaper or not much more if you start asking around.
.
Just as a quick heads up!!
Live on VOX Markets at 9.30am Friday (19th July), I will be interviewing accomplished income investor Roland Head of Stockopedia.
Here we're planning to cover lots of fascinating stock ideas including: #BRBY #CLIG #JFD #PAGE #PAY #RWS #SQZ #RS1 #TRIG & many more.
Alongside of course, trying to answer any questions that you might have. So please feel free join us here on Youtube.
Everyone is welcome. Lots to discuss
Last week I posted "For those with an interest in US stocks, news just out Quantumscape (NYQ:QS) has signed a deal with Volkswagen to ramp up solid-state battery production in QuantumScape" (I hold). SP is currently up 30%, I won't be selling.
Today I bought a starter position in Altyngold (LON:ALTN). Chart is indicating a bullish flag with a target of 170p. Would be great to hear from any followers/holders.
FT reports the UK's used electric vehicle (EV) market is booming due to a significant drop in prices, making EVs as affordable as traditional petrol cars. Data from Auto Trader shows that as early adopters upgrade to newer models, secondhand EV prices have fallen to match those of used petrol cars. This price parity has driven a 63% increase in secondhand EV sales in the first half of 2024 compared to the previous year. The average prices of used EVs, like the Tesla Model 3 and Polestar 2, are now comparable to or lower than those of similar petrol cars, such as the BMW 4 Series. Even though EVs make up only about 2% of the used-car market in the UK, nearly 10% of secondhand cars under five years old listed on Auto Trader are now fully electric. This is a big increase from less than 1% four years ago.
Must be nuts buying one until the charging infrastructure is significantly better
It depends on whether you can charge at home (and many people can) as well as your driving usage, particularly if it is a second car. I note quite a lot of drives housing an electric and an ICE. As people discover the driving pleasure and the reduced cost of electric driving I see a steady, if not stunning rise in electric cars. With second hand prices affordable the “let’s try it as a second car” concept being quite attractive
The main upside is if your employed and higher rate tax payer, or director of your own ltd company and go the lease route either through salary sacrifice if employed or as business expense if a director tax savings are big.
Otherwise I'm with you stick with a petrol or diesel but if you don't go far in one and can home charge in the above two scenarios you would be bonkers not to have an electric car and keep an old reliable diesel to use on the occasional long trip.
Must be nuts buying one until the charging infrastructure is significantly better
There is plenty of suitable purchasers waiting for the right price imho - electric cars are so niche at present (16%) - its a given that 80% of people wont be buying electic. electric is perfect (if the price is right) for those who are lucky enough to have 2 cars and who can charge from home easily and dont need both cars to do regualr long trips. There is probably plenty single household cars who also dont do that many long trips that they might get away with electric. At 20% ish market penetration thats still plenty of room for use to grow without forcing those to use where its clearly not fit for purpose (probably 70% at present?)
Obviously the infrastructure needs to massively improve to for uptake rates to continue growing fast.
Most people i know dont do many long trips and could charge from home but aint bought probably on price - so deffo an untapped market - albeitfor 70% it probably doesnt work.
Most people i know who have had electric cars have ben very happy with them - those not so happy are probably the ones who probably shouldnt have got one in the first place as they probably didnt research the realities sufficiently.
Expecting soemthing at under 10% market penteration to have full infrastructure in place now is imho ridiculous - obviously the infrastructure imporvment will be a limiting fcator but hopefully not forever.
New electric Porsche Mayan* out yesterday has a quoted range of 388 miles (probably 300 miles in the real world). That means topping up at a public charging point is only required for the very longest journeys. And you can have one (without fancy options) for the cost of an equivalent Kia/Hyundai! If my 8 year old Beemer wasn’t such a beloved member of the family (and Q car-ed to the nines), I’d be all over that deal.
*buyer beware - I have shares in Porsche AG
I'm a car guy. I work from home but walk more than I drive, yet have 5 cars usually to choose from.
I was an early adopter of EVs, as I also love tech. Prior to the Ukraine issues, it made such an impact in just running costs, when one could get under 3p per KW off peak, which meant at my mileage was so much cheaper than anything I had.
I ran a BMW i3s on my wife's work scheme and it was a complete no brainer, and performance was blistering quick, so much so that my 911 rarely left the garage as was so easy and simple to drive without having to worry abour getting oil temps up and cooling down etc...
She left her job and wanted to look at purchasing similar; however, I think the big issue that may play out is the lifespan of batteries. Most manufacturers advise that 8 years is what the will warranty for, but for me, when I looked at getting a 2nd hand Volvo XC90 hybrid, I was put off with this potential £10k+ payment required when, or if the battery does die. Much easier to purchase a diesel D5.
What would be a good idea is to see how these batteries are performing now given that they have now reached 8 years+ and then see what companies might benefit from the (what I believe to be) low estimates on battery performance, or vice versa.
Sorry for the waffle, but this may account for some of the lower prices in the EV 2nd hand market.
re EV's
There are two very different type of consumers here and hence two very different markets i.e. those who are able to charge at home and those who cannot.
If you are able to charge at home you have all the benefits, therefore an EV is a no brianer.
If you are unable to charge at home (and particularly if you drive long journeys) then an EV just doesn't cut the mustard.
It clearly depends which of the above camps you are in as to your likely opinion.
Also a point that earlier contributors have not highlighted much is the imbalance of time wasted charging at public charge points versus the time taken to fill up an ICE with petrol / diesel. Bear in mind also the cost of charging at a service station is now equivalent to the cost of a tank of petrol / diesel.
I can charge at home. It is not as clear cut as you suggest. I would not save much money as l do low mileage. Filling up takes about 20 minutes a year. One charge up would take longer. The extra cost of an EV and higher depreciation would wipe out any gains from fuel, tax and servicing. Insurance is also much higher.
I can't really see the point of me changing to an EV, at the moment. Also 5 year old EVs, only have about 100 mile range. I tend to buy 5 year old cars and keep for around 6 years.
The big concern with EV, is the battery going, which seems quite likely in cars over 8 years old. If that happens, it would be a huge loss.
So EVs depreciate much more than non EVs? Why are prices falling so much? BMWs are going up in value according to that chart.
I might be wrong and I know nothing about cars.... is the fact that 2 year old Electric cars are much cheaper now than in say 2022 reflective of the drop in new Tesla / Polestar prices ?
is the fact that 2 year old Electric cars are much cheaper now than in say 2022 reflective of the drop in new Tesla / Polestar prices ?
i think it is simply a supply and demand thing - there was limited supply of electric cars in 2021 and 2022 - heck people, could go out buy a porsche taycan new and it was worth the same as new 6 months later due to waiting lists so people had to buy second hand if they wanted one now. Obviously that was silly. What has happened more recently is that preumably the first big round of ev's purchased on tick when teh boom started have come to the end of the lease period or reached the point where balloon payment needed to be made if one didnt want to sell. So large volume of vehicles came on the market around teh same time probably without a pool of people willing to pay top dollar - so prices have collapsed. Thats all due to market forces - i would expect prices will likely normalise at some stage.
anyone buying a new fangled electric car without much production history and expecting it to hold value well was imho pretty stupid. Probably the exception being the tried and telsa models that have somewhat proved themselves - even then though if there is a glut of facny looking bmw's and ipaces up for sale at bargain prices thats gonna affect the price soemone can get for their tesla.
Obviously there will currently genrally be a reluctance to splash 20k on second hand electirc car if that will be getting anywhere near the end of the warranty.
Ref pricing of new Teslas - i dont think prices have changed much at the bottom end howver if they havent increased with inflation and are cheaper now in real terms thats obviously going to affect depreciation rates of older cars somehwat.
hVIVO (LON:HVO)
I've previously assumed hVIVO use animal testing in either its Venn Life Sciences or hLAB offerings, but I don't know if this is true. Does anyone have this information easily to hand? I'd normally do more research to confirm for myself, but ongoing time commitments for family issues, an upcoming holiday deadline and mainly laziness unfortunately prohibit me from doing so.
Whilst I'm here, I want to repeat the frequent accolades to Paul, Graham on on occasion Roland for their fantastic work and insights into each day's small cap news. It is such a help, either to back up one's own research, or to provide new ideas that I'd not have found through my favourite screen. It is truly a must read, even if most weeks there is so much valuable comment and analysis that I don't catch up on all the material until the weekend. Thanks so much.
Thanks Paul and Graham for highlighting this share, I like it more today than when I invested. It sounds like with strong revenue visibility already, they have a good chance of exceeding the 2025 targets IF they have capacity do do so. I’m not sure why they were able to ‘accelerate’ recent trials (resulting in strong H1) but may not be able to do so from the CW site. It seems that demand is very strong and that additional contract wins will emerge from the pipeline as long as they can service them. That then leads to the question of scalability. How much do they need to reinvest to increase capacity and is it linear? Any comments on this from anyone who understands the model better would be appreciated.
As an aside I raised GDR here a few days ago and have built a good position. I know that Paul is negative on this and didn’t believe the REX raise would pass muster but they appear to have pulled that off and are now well funded (well, sufficiently for now!) and with two genomic tests at an advanced stage of commercialisation with a combined £300m market opportunity and no existing alternatives. Its already rallied 150% but I feel that a market cap of £22m is still tiny compared with the potential. Even if they capture 10% of the opportunity at 30% margin this must be worth £100m+. All assuming that they aren’t outcompeted and that they can scale the technology. Anyway it’s actually an interesting stock given the history of disappointment set against recent NICE guidance supporting one product and FDA breakthrough device status awarded.
Hi Paul
Just a couple of comments re Renold (LON:RNO) where I bought a few this morning but am not expert as perhaps I should be.
First of all the results are for the FY to 03/24, not 12/24... a very minor point.
In terms of your criticism of the Outlook statement, I am not seeing too much difference between today's RNS and the FY 23 results. So perhaps they are generally conservative or don't have loads of visibility. Anyway, today vs a year ago is :
2024 "Outlook
I am pleased that the Group continued to perform strongly throughout the year reflecting the hard work, strategically, commercially and operationally, that has been undertaken over recent years by our employees across the world. The business is now at an inflection point where we are starting to see the compounding impact of the many recent exciting initiatives as they come to fruition. We have a very clear strategy and are executing it diligently. Our continuous improvement initiatives are building an increasingly efficient, productive and resilient business and are providing an ever improving platform to support our commercial initiatives.
We have been carefully developing our acquisitive growth strategy and opportunity pipeline. The scale of the highly fragmented industrial chain market is clear and this is the sole area that we are focussed on for acquisitions, providing us with many appropriately sized and relatively low risk opportunities.
Over recent years the business performance has been on an improving trend despite the many economic and geo-political difficulties. Renold continues to demonstrate the strength and resilience of its business, its market position and its business model. We expect the new financial year to be no less challenging, and we remain vigilant as to the environment within which we operate. However, we start the year from a positive position with good momentum and confidence in the capabilities and fundamentals of the Renold business and the markets we serve."
2023 "Outlook
I am pleased with the Group's strong performance over the year, which reflects the benefits of the strategic developments completed over prior years and the hard work that all our employees across the world have contributed during a most difficult period. Our employees have responded excellently to the challenges we have faced, and I thank them for their dedication and commitment to the Group and our customers during these extraordinary times.
Throughout the reported period the business performance has been on an improving trend and finished particularly strongly as supply chains eased in the last quarter. We expect the current financial year to be no less challenging, but we remain vigilant in the environment within which we operate; however, we started the new financial year from a positive position with good momentum and confidence in the capabilities and fundamentals of the Renold business and the markets we serve."
I am not seeing too much difference but would be very happy to be corrected.
In tonight's presentation from Renold (LON:RNO) the question of forecasting was addressed referring to improvements in cashflow, intentions to acquire additional profit enhancing businesses which they do not include in any forecast, and confirmation their style is to be conservative which I fundamentally prefer. So much better to under forecast and over deliver.
They also addressed the inference there could be dilution going forward and specifically stated that recognising and anticipating future liabilities, depressed share prices encouraged them to make purchases in the market and they now hold adequate shares to address all known requirements. Ergo they categorically deny any dilution will take place.
They came across to me as competent and focused, keeping me involved where other presenters just drone on and on, apparently loving the sound of their own voice. I have owned these shares for a short period of time yet already have a comfortable paper profit to reassure me they really could be at a tipping point.
Onwards and upwards.
Renold (LON:RNO)
Ergo they categorically deny any dilution will take place.
If they are having to spend cash resources though to buy shares in the market to avoid dilution - then practically speaking there is still the cost akin to the dilution that would have existed
If not its akin to saying share buybacks that reduce shares in issue are completely free - they arent the company depletes its cash pile or similar to get the end result done. Ie fullyn funded by other shareholders.
i am presuming the situation here is that freebies have been given out and thats been funded by company buying shares in the market. Ok they may have got a good deal ref price paid fo the shares but that with the benefit of hindsight. to me its 100% clear the other shareholders are fully taken the hit paying for those freebies .
Sosandar (LON:SOS) I just don’t get it. £25m for a breakeven, ex growth ecom business which happens to be opening 2 shops. Crazy.
Hi Ben,
You may already have tried this but I tend to use this search in Google (rather than Stockopedia) when trying to find old articles/discussions:
site:stockopedia.com [search term] so for uranium site:stockopedia.com uranium
Sorry if I'm teaching you to suck eggs!
Is anyone aware of a way to search for older discussions by using their title. I wanted to find the most recent discussion on the topic of 'Uranium'. But it seems you can only search for specific companies. Any ideas?
You can search for Porter Collins (co founder of seawolf capital) famous for being one of the big shorts during the Financial Crisis.
He has some interesting views on Uranium (not necessarily my views) and on LNG. I prefer the LNG play and i hold Golar LNG (NSQ:GLNG)
All the best
Thoroughly recommend On The Tape Podcasts for those who don't know... 2nd most important after Paul's :).... very US centric , but often contain Danny Moses ( Big Short ) and occasionally Porter Collins....
Try searching under Yellow Cake (LON:YCA) and Geiger Counter (LON:GCL) that may find them. There were 2 quite long threads on uranium in the last year. Yes annoying can't search on titles or words, on here.
Here is one: https://www.stockopedia.com/co...
Thanks all, very helpful. I own Yellow Cake (LON:YCA) was just looking for the discussion post which I've now found. Contemplating a top up on this pull back.
Renold (LON:RNO) Paul, the dilution from share options may not be as bad as you fear. It looks as though the EBT has been purchasing existing shares in the market which it can use to satisfy share options. If the EBT holds enough shares to satisfy all existing share options then there would be no dilution when the options are exercised. A little more research in this area would pay dividends for those interested in investing in this company. I do not hold.
Renold (LON:RNO)
Renold (LON:RNO) Paul, the dilution from share options may not be as bad as you fear. It looks as though the EBT has been purchasing existing shares in the market which it can use to satisfy share options. If the EBT holds enough shares to satisfy all existing share options then there would be no dilution when the options are exercised. A little more research in this area would pay dividends for those interested in investing in this company. I do not hold.
where on earth does the EBT get the shares from though to do that ? - unless its outlined otherwise i would be preuming its exactly as Paul has highlighted practicably speaking - i would guess any mitigation has to come ultimately from company normally ref funding ?
Renold (LON:RNO)
Sharewallah
A very good question which does relate to one of my assumptions below, so I thought I would do some digging.
Shares in issue at the start of FY24 were 225.4m and as per Stockopedia, that is also the number today. This would imply that any options have been exercised in y/e 2024 are from shares held in the EBT. However the number they use in their calculation of eps for FY24 is 206.9m, which implies that they have deducted 18.5m shares which relates to the average EBT holding. This is why they have correctly added back all the outstanding options over 27.5m shares to get to a diluted EPS.
It's also interesting to note that there will probably be another issue of option after the results. Last year on 25 July 2023, they issued 3m shares to the CEO and CFO. Probably at this price, it will be closer to 1.5m.
Renold (LON:RNO) I decided to sell my holding in Renold this morning as I reviewed the financials. It's been a great investment and the management seem to have done a good job.
I usually sell far too early, so it could be an opportunity for everyone else, but I thought it would be helpful to share my thoughts:
1. You have to dig into Note 5 to find the adjusted diluted eps of 6.9p (up 17% on LY of 5.9p). I would prefer that this figure was shown on the front page of the results as the options are nil-cost and the performance means that they are likely to be exercised.
2. Obviously this eps figure needs to be adjusted for the pension contributions to really understand the position. Taking the £6.0m from the cashflow as presumably this is the element that isn't taken into account through the P&L, gives me an eps adjustment of 2.6p which leaves my view of adjusted diluted eps of 4.3p, a multiple of 13.9x. (Caveat - I'm never sure how to deal with any tax credit of the pension cash contribution, so I may be overestimating. But this tax figure isn't obvious in the cashflow, so I am assuming any impact is already in eps.)
3. The pension situation here is very complicated, but I think it is far from sorted and I find it disappointing that the assets in the UK scheme have reduced from £101.6m to £100.3m after a cash contribution of £4.6m. Yes the UK liabilities have also decreased to £140m, but this is attributed to an increase in discount rate to 5%, which is surely going to reverse over the next few years.
4. So with my adjusted PE of 13.9x, I am slightly disappointed to see revenue going backwards and a fairly cautious outlook statement. So the risk/reward dynamics have changed for me at 60p. They have done a great job on profit growth but it hasn't come from revenue increases.
5. For acquisitive companies, I like to see a laser-like focus first on organic revenue growth (eg Diploma (LON:DPLM) or Judges Scientific (LON:JDG)), but I don't see that with Renold, the numbers are not disclosed.
6. Finally while I was digging through the accounts, I was disappointed to see that the annual bonuses are based 70% on Adjusted EBITDA and 30% on Adjusted Operating cashflow. Personally I prefer more bottom line targets such as adjusted diluted EPS and FCF excluding acquisitions.
I'm very interested in other views.
Renold (LON:RNO)
3. The pension situation here is very complicated, but I think it is far from sorted and I find it disappointing that the assets in the UK scheme have reduced from £101.6m to £100.3m after a cash contribution of £4.6m. Yes the UK liabilities have also decreased to £140m, but this is attributed to an increase in discount rate to 5%, which is surely going to reverse over the next few years.
Should you not be fully expecting assets to move in line with liabilities though - so i would presume (happy to be confirmed wrong) that its likely they party hedge changes in rates - so i would expect the assets to move downward to track lower future outgoings if there is hedging in place even though they have not confimed that fact. Overall as long as figures are reasonably neutral then i would always say its job done normally - to me the main priority is that liabilities and deficit are trending down not up - so in that regard having less committment than they did last year and les deficit seems to be "job done" this year.
Note i dont disagree that pension might be to risky for some to hold - the numbers here evidence that they are spending the cash to somewhat stand still - so not holidng does make sense if one feels pesnion is too big a risk - but thats not new news today and the fact the deficit and overall liabilities are both down £3 mill plus i would be looking at that as a good result this year - unless some expert was telling me they should have benefited big time this year due to change in rates
On Renold (LON:RNO) and pension deficits.
"Should you not be fully expecting assets to move in line with liabilities though"
Sort of. But...
You are valuing a theoretical pension liability (big number based on assumptions set by the actuary) against actual pension assets that nowadays are often largely in gilts (another big number possibly adjusted), and subtracting.
As interest rates rose, liabilities fell based on current assumptions and the assets, well it depends what the assets are. So pension deficits tended to shrink or go away.
It looks like interest rates are likely to fall over the next year.
So I would expect liabilities to rise and assets to change .
My key point: Unless the liability has been gotten rid of there is risk when interest rates change.
Renold (LON:RNO)
rmillaree, thanks for making this point, it's good to test the thinking. I would make a couple of points:
1. I was partly making the case that the cash contribution needs to be considered when considering underlying eps as it's an ongoing cash outflow. With a deficit of £40m, then it is likely to be required for the foreseeable future and it increases with RPI up to 5%.
2. With regard to the reduction in assets, it's an interesting question. When you look at the y/e 2022 figures, the discount rate was 2.75% in the UK fund, which led to a deficit then of £87m. So unless the assets have have been reallocated to different instruments, which they may have been, my assumption is that the deficit will likely increase when the discount rate falls. The pension note 18 in the accounts is worth a read to understand the structure that has been set up to protect the fund.
Renold (LON:RNO)
1. I was partly making the case that the cash contribution needs to be considered when considering underlying eps as it's an ongoing cash outflow. With a deficit of £40m, then it is likely to be required for the foreseeable future and it increases with RPI up to 5%.
I would 100% agree with this sentiment - my point was only really that i didnt think much had changed compared to previously so not new bad news as such something that has preumably similarly been the case previously
2. With regard to the reduction in assets, it's an interesting question. When you look at the y/e 2022 figures, the discount rate was 2.75% in the UK fund, which led to a deficit then of £87m. So unless the assets have have been reallocated to different instruments, which they may have been, my assumption is that the deficit will likely increase when the discount rate falls. The pension note 18 in the accounts is worth a read to understand the structure that has been set up to protect the fund.
I would agree anything is possible here - although then figures looked tickover to me i would not disagree with anyone whose research suggests things may get worse if they were materially worse not so long ago - my quick look was only that. Would be interested in comments from anyone who knowws the score. Should we not be expecting though that where there is a deficit in the pension scheme most of the time the people running the scheme will have top priority that any deficit should "not be getting bigger" and ideally it should be reducing pronto - so i would normally expect contributions would be expected to ensuring in the future things do not get worse normally. I havent looked but an exception might be if the pension scheme operator has allowed reduced payments due to poor business cashflow/profits . If my assumptions are right then that just leaves natural variability - so you could be right that they have temporarily benefited leading in deficit reduction that will unwind later. With total scheme liabilities of £160 mill £4.5 mill pa plugging the pension shortfall seems about right and as you say perhaps safe to preume payments will carry on and may increase , with any reduction in payments being bonus.
On point 2, the pension adjustment. From note 5, a cost of £2.9m in relation to pensions has already been deducted through the finance cost line to get to the diluted adjusted EPS. So I think deducting by £6m is includes a double count for £2.9m.
I prefer to evaluate this share through the cash flow statement. After paying for pensions and expensive debt, there is only around £5m or £6m left for shareholders after investing £15m in Capex and M&A for mediocre / nil growth.
Given this investment I agree that management need to be much clearer and provide numbers on Renold (LON:RNO)'s growth prospects.
Renold (LON:RNO)
Thanks Cuddlesticks, I think you make a very good point on the double count, although I only see £2.7m in note 3.
I also agree with you on FCF, which is my other key measure.
Paul, I get the impression from your bio that you might have been (maybe still are) a bit of a raver. If you’re on the coast today, and wandering around town, look out for an extravagantly dressed (anything from pantomime dame to red carpet catwalk to pure fancy dress) small, middle-aged, tatooed Thai woman. In town for 24 hours only. She is the amazing Gig, who arrived penniless in the UK and went on to become deputy mayoress of a town local to me via the complete transformation of its night scene - from spit and sawdust old man pubs to the hip scene built around the now legendary and original “rave in a pub”, the Golden Lion in Todmorden. She is one of the most extraordinary people I have ever met. Should you chance upon her, know that she likes nothing more than to meet the locals. But, be warned, there’s no night out like a night out with Gig!
Kenmare Resources (LON:KMR) Kenmare - not a stock featured normally on this board - its mining but very niche and so the update posted this morning not featured but its a stock that ticks many boxes albeit its working in Mozambique. Cash on the balance sheet and good divi with a significant moat and yes, I hold.
Kenmare Resources (LON:KMR) I only allow myself one miner at a time and picked Serabi Gold (LON:SRB) Stocko like them giving them a rank of 100. Any thoughts on SRB over Kenmare?
Since you ask I wouldn't really like to say but I always fancied Kenmare Resources (LON:KMR) but have never bought in. I did buy Serabi Gold (LON:SRB) in the aftermath of Covid when there was so much optimism around so I'm not that much in profit. In hindsight I could have made a lot of money buying at the very lowest shares prices in each company but looking to the future I'll be sticking with Serabi Gold.
Silver
@Kenmare Resources (LON:KMR) Serabi Gold (LON:SRB) Thanks for your thoughts Silver Moon. Off topic and not the right forum but your moniker got me thinking. Are there any thoughts on here about physical silver e.g Ishares Physical Metals (LON:SSLN) I think the future for silver may be bright.
Hi Peter, silver has always lagged behind gold and probably always will and prefer to leave investment in that direction to others with more money.
Peter
The future for silver and gold seem bright, esp with government debts at current levels and growing. I hold Ishares Physical Metals (LON:SSLN) and Wisdomtree Metal Securities (LON:PHGP) and rather than pick individual miners hold VanEck Gold Miners UCITS ETF USD A (LON:GDGB) .
Thanks Silver Moon & JimMcLad for the food for thought/things to research
Only one miner at a time with the current commodity boom under way and the net zero suicide cult destroying our energy security for the future? Interesting.
In keeping with the sage advice from Capitalist Exploits I myself hold at least 10% of my portfolio in basic mining materials and especially gold, silver, uranium and copper. I also like Kenmare Resources (LON:KMR) and Serabi Gold (LON:SRB)
Fair point BabisG. I only have one individual miner but also have some in diversified funds. I should have explained better. Personal preference after managing to loose money on Sylvania Platinum (LON:SLP) , Tharisa (LON:THS) and Central Asia Metals (LON:CAML) to my shame.
Hi Peter - Yes they are both miners - but other than that its like comparing apples with pears - KMR mines heavy minerals - is operational and profitable .
Kenmare Resources (LON:KMR) Don't disagree and did hold Kenmare back when Harwood were really behind it but sold out when they started backing away. I seem to remember Chris Mills saying "the easy money had been made" for Harwood. This was a while ago though and haven't looked at it much since but remember liking the operation and management so maybe I should take another look.
Kenmare Resources (LON:KMR) I hold and think it is interesting. I am not an expert but there's a few points you need to consider. First they are moving to a new area of their acreage for a significant part of their output (~50%) which involves Capex of circa $340m which they intend to fund via cash flow and debt. There is clearly risk associated with executing this. There's also another big Capex project they are looking at which has a longer time line. Second, demand for their product is rising and supply has been reduced by the Base Resources mine coming to the end of its life. The new Base Resources mine in Madagascar could change this but will take time to develop and I don't think has been agreed yet. Lastly there is a pesky Irish withholding tax on dividends they mentioned on the last call, which I think you can reclaim.
I hold as well, with much the same reasoning (and doubts) as you. Balance sheet rock solid, good divi, world class resource, undervalued.
However Mozambique brings country risk, material project has execution and cost risk, recent production has missed targets, worker fatality brings regulator risk, and commodity price risk.
My reading of the update is that prices are improving, production is coming back up and project is on track. So some of those risks I list above are lessening and continued production performance combined with a better macro demand picture could mean the share price could recover from it's recent drop.
ZIGUP (LON:ZIG)
getting back to this one (Pauls update 10/07/2024)
current year expectations
Paul probably rightly so gave zigup a bit of stick the other day for not mentioning current year stuff
I can’t find anything about performance in the new financial year. There should be a comment about current trading vs market expectations, but that seems to be missing. All companies need to be strict about reporting this in every update, so it’s worrying what they duck out of saying this. Let me know if I’ve missed it, as I haven’t got time to read all the narrative, but have searched for “expectations” and “current” (trading), to no avail.
I was going to defend zigup on the day and say they have a very useful investor page they update regularly confirming current year broker expectations link below. The only problem here is that info was out of date as they are still referencing ye 30/04/2024 info.
https://www.zigup.com/investor...
I did email them on the day to say it would be hepful if they could include current and next years info or ensure current year exists as soon as we get into the new year. They have made the following update on the website so presumably an update is coming soon.
Following our FY 2024 results on 10 July we are currently compiling FY 2025 consensus and will update this page shortly to reflect coverage analyst most recent views.
So they do have a process and it does mostly work - other than when its clearly out of date like now. I know not whether they will take on board my comments - i possible should have requested they confirm info in results update.
To be fair to this company if expectations had moved materially i would have expected some comment. Note slight uptick current year on stocky with slight downtick next year - those look like natural adjusts to me - eg brokers might perhaps be aligning with others rather than brokers straying away from the pack ?
Paul has downgraded the company from green to amber/green on concerns ref disposal profits excessively contributing to profits. To be sure prices of vans are still high compared to long term average but the easy money here has probably been had.
There are some lovely detailed notes in the acounts update here that provide more info - note they had to reduce depreciation charges as they couldnt keep depreciating vehicles obviously well below market values.
They confirmed that on lfl basis those changes would negatively impact 2025 and 2026 numbers by £25 mill and £18 mill. So current estimates reflect these adjusts. Up to now the company have managed expectations fantastically well with the return to normalisation ref vehicle prices.
Note the flip side of bumper disposal profits is that they need new fleet all the time and if prices are higher then they wil be less likely to be able to get good deals ref the vans in use and thats what their profits mostly are getting value out of the vans they buy. eg they may need to pay top whack to lease. So i deffo see some upside in supply returning in volume at normal prices (which is when i would expect used prices to fuly normalise) - as they will probably be able to return to getting bulk deals from manufacturers - on ewould expect while supply is limited manufactors would be extracting top whack rates ref new flett.
They have also said the following ref depreciation so it seems like overall they are finding reasonable middle ground
Depreciation rates on vehicles purchased in FY2025 will be set based on management's best estimates of future residual values when those vehicles are sold, with holding periods ranging from 12 to 60 months.
So on the basis the company knows where they are and they can probably estimate reasonably where prices are going i would expect the current year and following year forecasts should reasonably factor in sensible sales prices and these forecasts show sensible minor reductions in net profit that should be expected based on FURTHER normalisation of prices and above adjusts ref £25 mill £18 mill that flattered the 2023 and 2024 numbers. Note to be clear here 2024 eps is 54p 2025 eps is 53p and 2026 eps is £50.6p - so managed minor dip in numbers.
In summary the longer we go with further normalisation in prices and supply returning the more i have confidence that what the management expect here is what they feel can be delivered (management have hardly puta foot wrong ref managing expectations- and if there was expected huge dropoff in winfall profits not being replaced by gains elsewhere in the buisness i would have fully expected that the numbers would reflect that - so i for one am happy that based on where we are i am not expecting drop in eps numbers to the extent that 1/3 of their profits will depart out the door. Other parts of the business seem to deffo be picking up any slack needed. Perhaps personally knock off 10% at present to be cautious ref further normalisation of prices - but personally i think the picture here is as rosy as its been since i started holding.
RM A little reminder for those not in the loop, it is the biggest holding in Rockwood Strategic (LON:RKW) Their latest fund sheet is here: https://www.fundslibrary.co.uk... Their argument is that they expect margins to revert, and think the new management are capable of achieving it. Richard Staveley is the lead portfolio manager of RKW.
RM (LON:RM.) Yes, with reference to Paul Hill's interview with Richard Staveley, they started buying when the SP was about a 1/3 of current price. Richard S. thinks it's worth £170m market cap (currently £62m ish) so thinks there is still significant upside in the coming quarters. High levels of debt but he hopes to see them sell off part of the business in the next few months. Great contract with Baccalaureate and the exam marking assessment business is a gem according to Richard.
Great admirer of Richard and have dabbled with trading RM but not convinced enough to invest long term. Will watch with interest though.
Thanks Peter T,
I always find Richard Staveley interviews pure gold, it's so clever how Harwood really drill down into the business model, and work out the potential at turnarounds, I have huge respect for them.
So I'm not disagreeing with them at all, and RM could work out well, especially if a disposal sorts out the debt. Just to pre-empt people saying things like this in future, "You were RED on RM, and it's multibagged, so you got that completely wrong you dipstick!"
However my stuff is just simple reviews of the facts, figures & forecasts, which at this stage look pretty awful at RM. Hence it's RED for now on our cautious review of the facts, but obvious upside on that if Staveley's turnaround case works out as planned.
So this could well be a situation where the risks are worth taking, since there's a well-argued bull case on a turnaround.
It just means taking on a bit too much risk for my liking, given that it's in a precarious financial position at the moment. So I'm happy to let other people take that risk, and hopefully earn the upside if it works out well.
Regards, Paul.
RM (LON:RM.) I don't disagree with you Paul on RM or pretty much anything else really (apart from maybe one time regarding FTC and I refrained from top slicing prior to the SpaceX thing)
Richard is open and honest in his interviews and what he says often comes to pass sooner or later (it pays to listen carefully to what he says) but he is, after all, talking his own book. You are giving your impartial straightforward review of the facts, figures and forecasts in front of you on the day which, alongside Graham, Roland etc. is unrivalled and invaluable to me and many others I'm sure. I never understand those who go back to your historical reviews to criticise in the way you describe above.
A curse of those who would call you a dipstick! (That's genuinely just reminded me to buy some oil for my ride-on mower (paid for by profits from CMC Markets (LON:CMCX) and Trustpilot (LON:TRST) thanks to you and Graham so thanks for that too! I often think of you both as I'm trundling round on it)
Spectra Systems (LON:SPSY) Apologies if this was noted yesterday:
Simon@BrilliantLeader·1hReplying to @BrilliantLeaderFollowing on from this news yesterday there was a brief follow up interview with the CEO. Tantalisingly, it ends with “… we’ll have good news coming again soon” #SPSY
Re: Spectra Systems (LON:SPSY) CEO interview, here’s the link https://www.proactiveinvestors...
Spectra Systems CEO Announces Major Contract with Central Bank for Sensor Manufacturing - YouTube
This is the link for that interview.
The details of the new new contract are written on the white board behind Nabil ;-))
Team17 (LON:TM17)
If I had had a holding here at 7.00am this morning I wouldn't have one at 8.00am !
newsfile.refinitiv.com/getnewsfile/v1/story?guid=urn:newsml:reuters.com:20240717:nRSQ6565Wa
Either the company has no respect for it's shareholders or things are not quite going to plan.
The early price action would suggest others feel the same.
Team17 (LON:TM17)
Well said Helvellyn - not sure where and when they lost the plot.
In november 2023 they mentioned specific EBITDA and advised they would update ref this year at year end results date. Year end results outlook section looked very sketchy - did i miss any updates ref specific numbers then ?
and now we get this - it would have been fine if they had provided earlier guidance like last year.
If i have not missed anything the board should be taken to task for treating shareholders with contempt. How much time does it take to confirm what current marekt expectations are ?
the only good news is that forecasts dont appear to have dipped per stocky recently - so it does appear they are still on track - rather than having forecasts reduced recently to say they are on track to those reduced numbers as some companies do sneakily (Saga we are looking at you)
so despite poor communication it doesnt look like there are any hidden nasties here - presuming stocky forecasts are live and real !
looking at where we are ref the expected numbers for 2024 and 2025 actually look decent with the worst of it over (if current forecasts are to believed). On that basis p/e of 14 seems pretty reasonable without doing further digging - not sure if there is the danger of over capitalising costs here ?
So without doing deep dive everything looks fairly ok here at face value - is 4% decline today within natural variability ? could market have been expecting upgrade ? i know not. To me though with decent profits pencilled in my worry would more have been bad news related than looking for upgrades !
Lots of ways you can look at this but we keep hearing how interest is returning to the UK smaller companies sector and yet RNO remain on 8 times. Surely they should be trading on 10 to 12 times? They have shown management are capable. They have delivered a turnaround. They are in a fractured sector with lots of enhancing acquisition possibilities. There is a clear pathway for their pension issues. The 2nd half? " Encouragingly, order intake in the second half increased over the first half by 7.5%, or 8.4% at constant exchange rates. The closing order book at 31 March 2024 of £83.6m remains close to record levels and was unchanged from the half year position (30 September 2023: £83.6m)." It feels to me that this needs a rerating. Holder.
Renold (LON:RNO)
"It feels to me that this needs a rerating. Holder."
It has had one this year to be fair, Cantab. A cracking pick by Paul for his top 20. I don't know how long you have been holding for but anything longer than a few months and you will have seen handsome gains.
It does no harm I think to have a period of consolidation. I agree with you on the long-term prospects.
Absolutely Whitbourne. I have had it since 18p. I am really stating that IMO they should trade on a multiple of 10 to 12 times given much like the pension is known and the business is delivering. I am probably a seller 75p to 80p. I have been in this long enough to know the market won't upgrade because I tell it to, so this mornings price fall doesn't bother me much. Hope that is not too defensive, if it is not intended. All the best.
"I have had it since 18p" Great call! and thanks for the reply. We are in vigorous agreement.
Renold (LON:RNO)
ASA International (LON:ASAI) This micro finance provider to many developing countries is , to me, the kind of company that you WANT to do well ! Good update today, trading ahead of expectations and on a lowly PE of 5 before any upgrades. Though not without risks. As it’s a financial, wondering if Graham can cast his eye over it ?
ASA International (LON:ASAI) - agreed, it's the sort of company one wants to do well. But maybe more as a mutual, or similar, rather then a commercial company listed in London?
I also really wanted to like ASA International (LON:ASAI) ....
But despite all the "good" they say they are doing, look at the director's renumeration report...
The CEO's salary is ridiculous for the size of profits.
The "advisor" (ex-founder?) salary / yearly pension is also ridiculous.
hVIVO (LON:HVO)
Tick from me - the main thing is the margin - now up to 24%. That’s decent and ahead of schedule in terms of what they told us the medium target would be. Originally they said 20-21% in short term and wouldn’t get past that until new facility open and more operating gearing kicked in. So to achieve that now is good and suggests strong and disciplined mgmt.
get anywhere near their £100m revenue target at 25% margins and this should be much higher in my view. Cash very strong - should be £45m by y/e by looks of things (remember whilst some of this is up front cash from customers it is “own” cash as these are non refundable deposits. So even if a customer drops out of a trial hVIVO (LON:HVO) keeps the money).
Order book visibility very good - next 18 months. Clearly had a bumper delivery in H1 so that dropped a bit but interesting to see them flag a number of material orders at advanced stage. Looks like 2nd half is pointing to £26m (vs £37m) revenues so perhaps a small beat could be on the cards here?
Edit: looking at broker note I reckon it’s still conservative so this looks like it is in a cash adjusted PER of only about 10 now. Feels too low for a global CRO . Price targets are now up in the 40ps for whatever that’s worth.
Hvivo
Totally irrational Red flag od rhe day for me
Yamin '”Mo” Khan, Chief Executive
Find the insertion of a nickname into a CEO name just really annoying .
Makes this something I couid never invest in due to the mental health issues this would give me every time I was forced to read it .
Totally irrational Red flag od rhe day for me
Yamin '”Mo” Khan, Chief Executive
I’m less troubled by the fact he has a nickname than by the totally indecipherable transition from Yamin to Mo!
Surely they are merely stating what he is normally called, but have to put his birth name in RNSs.
His full name is Mr. Yamin Mohammed Khan.
hVIVO (LON:HVO) This is one that got away for me. I was in around 15p and then decided I had enough CRO action in my two large positions stateside and could do with allocating the small position elsewhere. Since then, operational performance has been excellent - the “reverse curse of BnB”!
You’ve been very vocal in support of the name, and well done on a great investment. I was talking to my bank’s Health and Life Sciences analyst last week and he sees the CRO sub-group as the best risk-adjusted play in the sector. I imagine you’re staying long and strong, while I need to think about pouncing on any weakness. Not that there’s any sign of that!
I hear you BnB!It’s very annoying when that happens.
I’m quite happy with hVIVO (LON:HVO) as a longer term story. I think there are two dynamics at play
1) If you assume net cash moves to £45m (which in the absence of increased payouts or an acquisition it should) then the PER is not much more than 10. I think broker has deliberately slightly undercooked its margin at 23.3% and I think there is a chance of a revenue beat so I am expecting 1.5p EPS vs broker at 1.4p for this year. CROs usually trade on higher multiples than that - especially those with dominant global leadership in their field - so dynamic one is a multiple re-rating thesis.
2) If Mo has stated a medium 5 year target of £100m+ -of revenues then I’d back them to get there. He tends to be an under promise over deliver type of guy (the opposite of Cathal of course). They’ve already over delivered on margins getting close to that magic medium term 25%. Throw in the cash generation and I could see them at 60p+ over the next 3-5 years. That would be a compound return of some 30% if they do it in 3 years and just under 20% in 5. Both returns meet my criteria. Then it wouldn’t surprise me if they get bought so if its the right price maybe I’ll get lucky on timing.
Who knows how it all plays out - nothing is certain of course and 3-5 years is a long time in todays environment.
I think this is a really robust summary David, thanks for sharing. I totally agree that PER is too low considering the business. Ive looked at hVIVO (LON:HVO) a few times but only today opened a position for the first time. The chart also looks poised for a breakout having formed a solid base over a number of months.
hVIVO (LON:HVO) Oh dear its all EBITDA and profitable growth strategy, other than that things seem on the up. Où est le PBT
Octopus Investments up their stake to 4.42% from 3.1%
Record results at hVIVO (LON:HVO) . Cavendish raise pt to 42p.
Forecast is now 1.4p EPS this year rising to 1.6p EPS next year. Strip out the cash pile and HVO are trading on a P/E of only 14.6, falling to just 12.8 next year.
Time to re-rate?
hVIVO (LON:HVO)
Can we have that in English please?
All the best
You can see the PAT Mike - EPS is forecast at 1.5p and net cash should be £45-50m.
That puts it on a cash adjusted PER of about 10*.
CROs generally trade at 20+
Just a reminder that we are hosting an Investor Presentation with Cohort (LON:CHRT) management this coming Friday at 10am - you can sign up here: https://www.equitydevelopment....
iDealing
If anyone reading this uses or has used iDealing please let us know your experience with them - good or bad - by replying to my comment on a post here: https://www.stockopedia.com/co...
Many thanks
Cohort (LON:CHRT) - "FY24: record results and maintained momentum"
Cohort reported strong FY24 results, with revenue +11%YoY at £202.5m, which was 8% above our outlook, and (adj.) operating profit of £21.1m +11%YoY (3% above EDE). The closing order book was £518.7m +58%YoY with order intake of £392.1m, +78%YoY, and estimated 95% coverage of our FY25 revenue outlook. The year closed with net cash of £23.1m.
National security and spending on defence became an issue of top priority through the course of pre-election campaigning, with the Labour Government indicating that it would increase spending to 2.5% of GDP compared an estimated 2.30% in 2023/24. The Group reports good demand from both domestic customers and for exports, noting increased attention to defence spending spurred by conflict in Ukraine and ongoing tension in the Indo-Pacific region.
Our read-across to the market cap-weighted average of peers leads us to raise our Fair Value / share to 910p from 725p. Link to research note: https://www.equitydevelopment....
Cohort (LON:CHRT) I bought this recently when playing around with some screens and also looking at the charts which is a new thing I've been trying to learn, so only a small position. Figures look excellent.
Record financial performance:
Revenue increased by 11% to £202.5m
Statutory profit before tax up by 42% to £19.8m
Adjusted earnings per share improved by 18% to 42.89p.
Order book closing at £518.7m, a 58% increase from the previous year, providing long-term visibility and stability.
Order intake significantly increased by 78% to £392.1m, including a substantial £135m contract from the Royal Navy
Strong liquidity and consistent dividend growth, with a 10% increase.
Acquisition of Interactive Technical Solutions Ltd (ITS) expected to be immediately earnings enhancing
Over 90% of 2024/25 revenue expectations underpinned by the current order book
I suppose a few 'negatives' insomuch that they are dependent on key contracts from the Navy and exposure to Defence in general (which currently I think is a positive).
They will need to deploy capital on an ongoing basis, which may affect revenues moving forward.
Now, I bought this on the basis that it was not undervalued, if anything it was overvalued, some recent articles about good stocks doing well, felt like this was a chart/momentum play which I hoped to gain a decent gain (25%?) in a short time period (6 months). I will hold.
Decent looking Trading Update from hVIVO (LON:HVO) - reaffirms Revenue guidance and anticipates margins at the upper end of expectations. I have a small position here.
hVIVO (LON:HVO) Mo doing the rounds this morning.
&t=1sMy morning smallcap tweet: Your free taster of news morsels
Cohort (LON:CHRT) Chill Brands (LON:CHLL) Litigation Capital Management (LON:LIT) Cyanconnode Holdings (LON:CYAN) Versarien (LON:VRS), Niox (LON:NIOX), Brooks Macdonald (LON:BRK), K3 Business Technology (LON:KBT)
◄Cohort (CHRT)► wins 2 orders worth £21.4m to complete within 1 yr. [SP=840 Cap=349m]
◄Chill Brands (CHLL)► CEO Callum Sommerton cleared of misuse of inside information. FY-Mar UK 'purchase orders' £1.8m. US $66k. Co reviewing its revenue recognition policies. FY audit won't meet end July deadline. [SP=2.15 Cap=11m]
◄Litigation Capital Management (LIT)► FY-June realisations AUD56m. Outlook - investments continue to perform in line. [SP=110 Cap=128m]
◄CyanConnode (CYAN)► in India it has passed multiple Site Acceptance Tests across several key projects and has achieved "Go Live" status in one. [SP=7.88 Cap=24m]
◄Versarien (VRS)► outstanding convertible loan of €1.25m, plus accrued interest of €207k, converted into shares in its subsidiary Gnanomat. This is to allow Gnanomat to apply for local grant funding from the Madrid region. [SP=0.08 Cap=1m]
In line: NIOX, BRK, KBT
MrC - many thanks for your replies re iDealing. The link I gave was to my comment from the main post and you have to go to that to see the replies (another Stocko quirk!):
https://www.stockopedia.com/co...
I'm sure Renold (LON:RNO) will make a visit today. Leave the figures to the experts, but re-instatement of the dividend (at 8% by my comprehensive school maths) is my main take.
Edit: As other have confirmed, my maths is excellent, my reading is poor. 0.8% Dividend.
The dividend is only 0.5p!
All the best
Oops, that why I leave things to the experts, Dunce cap for me.
Renold (LON:RNO) 8%? I wish. 0.5p per share. Cork out of bottle though.
It’s a 0.5p divi on a 60p share price so 0.83%. Better than zero though.