Small Cap Value Report (Wed 18 Apr 2018) - IGR, VNET, ANCR, SYS1, KOOV

Good morning, it's Paul here!
I have limited time available today, due to preparing for the UK Investor Show this coming Saturday.
I'll be on the main stage for half an hour, from 10:26 to 10:56, chairing a discussion on small caps with Nigel Wray, and Paul Jourdan of Amati (whose main fund has been a stellar performer).
Shortly after that, at 11:05 our own Ed Croft is doing a 35 minute session called "Data mining for stock market profits". I know Ed always puts in a great deal of preparation for his sessions, which are always lively & fascinating. So I'm looking forward to this.
Then from 12:00 to 12:40, it's my time to be interviewed, for a live "bearcast", with Tom Winnifrith. I'm not quite sure why I agreed to do this, and could well end up regretting it! Tom is under strict instructions not to be too obnoxious! Also, it would be nice if he actually lets me answer the questions this year, instead of using it as a platform to harangue me with his own views.
After that ordeal, I will probably be holding court in the Westminster Arms!
I'm looking forward to catching up with SCVR readers on the day - old friends, and hopefully some new ones too.
Then of course, next week, we have the long-awaited return of Mello Derby. The 2014 event was fantastic. This is a slightly smaller, and more exclusive investment show, run by serious investors, for investors, led by renowned small/micro cap investor, David Stredder.
I befriended David at an AGM in 2000, and have since watched him go from success to success, consistently making high portfolio returns. Like a lot of successful investors, he deserves to do well because he just works so hard at it - constantly researching companies, meeting management, etc.
The community aspect of Mello is outstanding too - you couldn't meet a more friendly & supportive bunch of people. Many of us already know each other from online forums such as this, and Twitter of course. However, newcomers are also welcomed with open arms. So do come along if you can, and say hello to me & Graham.
IG Design (LON:IGR)
Share price: 417p (down 3.3% today, at 11:23)
No. shares: 63.88m
Market cap: £266.4m
IG Design Group plc, one of the world's leading designers, innovators and manufacturers of gift packaging, greetings, stationery, creative play products and giftware, announces a trading update in relation to the year ended 31 March 2018.
A nice clear summary at the start of the announcement. Please take note, other companies & advisers - this is the way it should be done;
The Group's trading accelerated in the second half of the year with all regions delivering strong revenue growth and increased profits.
As a result the Board anticipates a full year of overall progress and financial performance in line with management expectations.
More detail is given, with this comment on dividends catching my eye;
The Board remains committed to its progressive dividend policy and is considering increasing the Company's earnings pay-out ratio in future periods, to reflect both the improved financial performance of the Group and the positive outlook of the Directors.
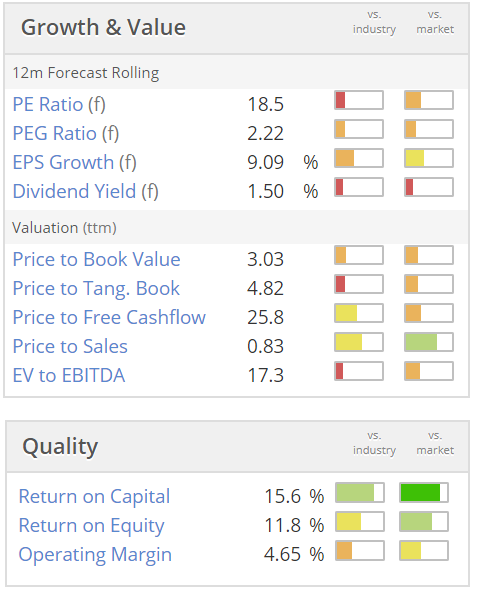
That sounds encouraging, although note that the dividend yield of 1.5% is low. So it's good to hear the intention is to increase that.
Management comments all sound positive.
Valuation - as you can see below, it's not cheap, but good companies rarely are.
As you can see from the Stockopedia graphs below, this group has established an excellent track record of profits growth;
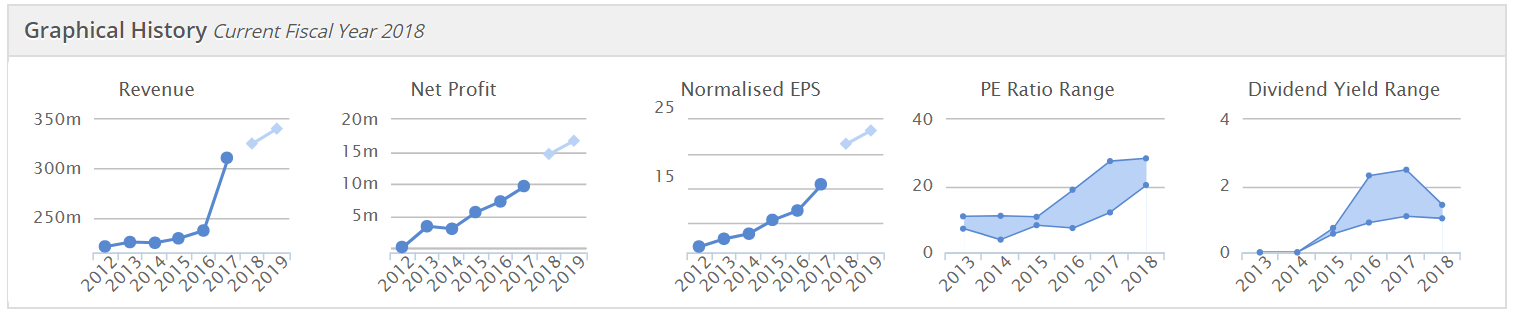
The big jump in revenues in graph no.1 suggests a large acquisition in 2017. So I would want to check the balance sheet, to ensure it's not too top-heavy with intangibles.
As you can see from graph no.4 above, the group's excellent performance has been rewarded with a re-rating upwards of the PER valuation. That's great for shareholders, but of course it does increase risk - if anything goes wrong, then highly rated shares have further to fall.
My opinion - I always write positively about this share, because it looks a very well managed company, performing consistently well.
The current valuation looks fully justified, in my view. So it gets a thumbs up from me.
Vianet (LON:VNET)
Share price: 129p (down 6.9% today)
No. shares: 28.27m
Market cap: £36.5m
(for the avoidance of doubt, I no longer hold a position in this share)
Vianet Group plc (AIM: VNET), the international provider of actionable data and business insight through devices connected to its Internet of Things ("IOT") platform, today provides the following trading update ahead of the Group's preliminary results for the year ended 31 March 2018, which are expected to be released on Tuesday, 5 June 2018.
As readers "wildshot" and "Gromley" point out, in the comments below, this sounds like a slight earnings miss;
Trading for the second half of the year has been largely as anticipated and, as a result, the Group's full year profits will be broadly in line with market expectations and ahead of last year's outturn of £3.32 million.
As such, the Board intends to recommend a maintained final dividend of 4.0 pence per share.
The divis have been the main reason to hold this share. It would be interesting to re-plot the share price chart, adding in dividends. The total shareholder return would probably look quite good on that basis.
Other points;
- Vendman acquisition is going well. When I last met management, which I think was last summer, they seemed very enthusiastic about Vendman.
- Material contract with a coffee company is also going well.
- Move towards SaaS revenues is suppressing short term performance.
- Smart Zones division (i.e. Brulines) profit is "slightly down year on year". Outlook sounds solid.
Directorspeak - is self-explanatory;
James Dickson, Chairman, commented: "The Group will again deliver good year-on-year profit growth. Importantly, this has been achieved whilst shifting the balance of Smart Machines sales from capital to recurring annuity based income.
The Group's medium to long term prospects are exciting, particularly for telemetry and payment solutions for the coffee vending market, where momentum is being boosted by good progress integrating the Vendman acquisition, and better visibility on delivery of the material contract win with a global coffee company."
My opinion - I regularly review my portfolio, and cull positions where I don't have big conviction. This is especially important when the stock market overall is going wobbly, and I need to reduce gearing, which happened earlier this year.
For these reasons, I took the decision to dispose of my Vianet shares. Also, I formed the view that the share price looked up with events at around the current level. The dividend yield of over 4% is attractive, although the fact that it has been static since 2013 indicates that the company has struggled to maintain this level of payout. I generally prefer rising divis, as they are less likely to be cut.
Overall, I see this as a solid, but unexciting share. I was hoping that by now the group would have diversified into other sectors, applying its considerable expertise in data management & analysis, but that hasn't happened yet.
It is making progress, but at a slow pace. Hence why I decided to sell up & move on, in the search for more rapid gains. There's a chance that this share could be re-rated at some point, if it manages to accelerate growth. So I'll keep it on my watchlist, and might re-enter at some point in the future, depending on how the newsflow & valuation develop. There's nothing wrong with this share, but I can't see any reason for it to rise in price, in the short term anyway.
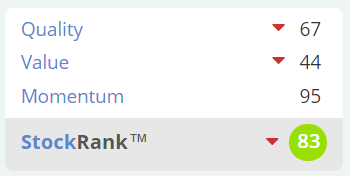
Stockopedia is positive, with a high StockRank;
Animalcare (LON:ANCR)
Share price: 211.7p (down 20.9% today, at 12:10)
No. shares: 59.9m
Market cap: £126.8m
Animalcare Group plc is a UK AIM listed veterinary sales, marketing and product development company resulting from the merger of Animalcare and Ecuphar NV.
I'm not familiar with this company, but Graham has covered it several times here.
Graham was previously positive about the company, but turned negative on it after a big acquisition/merger was done in 2017. Graham wisely concluded here in Jan 2018 that the situation was too uncertain to consider buying the shares.
The group seems to have changed its year end from 30 June to 31 December.
2017 results are slightly below expectations - because the phrase "broadly in line" is used, in the last sentence below. So it seems contradictory for the paragraph to be headed "2017 expectations unchanged". You can't simultaneously be a bit behind expectations, and also have unchanged expectations! Someone wasn't thinking when they wrote this;
2017 expectations unchanged
Expectations for the Group's first financial period ended 31 December 2017 remain unchanged, and as previously announced total revenues will show a year-on-year increase of c. 9.5% to £91.9m, slightly ahead of management expectations, and earnings for the period will be broadly in line with management expectations.
Profit warning - performance in 2018 is being hit by lower gross margins;
Sales growth is expected to be stronger across the Group during the current financial year as the integration of the businesses continues to progress throughout the year.
The Company is expected to deliver further incremental growth in underlying EBITDA, underlying net earnings and EPS against 2017 results, maintaining at least double digit growth at these levels.
However due to the impact on gross margins of a changing sales mix and competitive pressures, these levels of earnings, whilst still significantly ahead of the prior year, will be below market expectations for 2018.
Of course 2018 profits are going to be up on 2017, because the group did a massive acquisition (classified as a reverse takeover, where the target is bigger than the acquirer) part-way through last year.
Outlook - benefits from the big acquisition look to be deferred into next year;
In addition further synergies and cross-selling opportunities will start to take effect during 2018 as integration progresses, but will deliver a more meaningful impact on profit margins during 2019.
Dividends - current dividend policy will be maintained.
Balance sheet - the company says today that it has a strong balance sheet, which I treat as a potential warning sign. So the next balance sheet will need to be carefully checked.
My opinion - I don't really have a strong view either way. It's not really my type of share, and the newsflow seems disappointing. So why get involved?
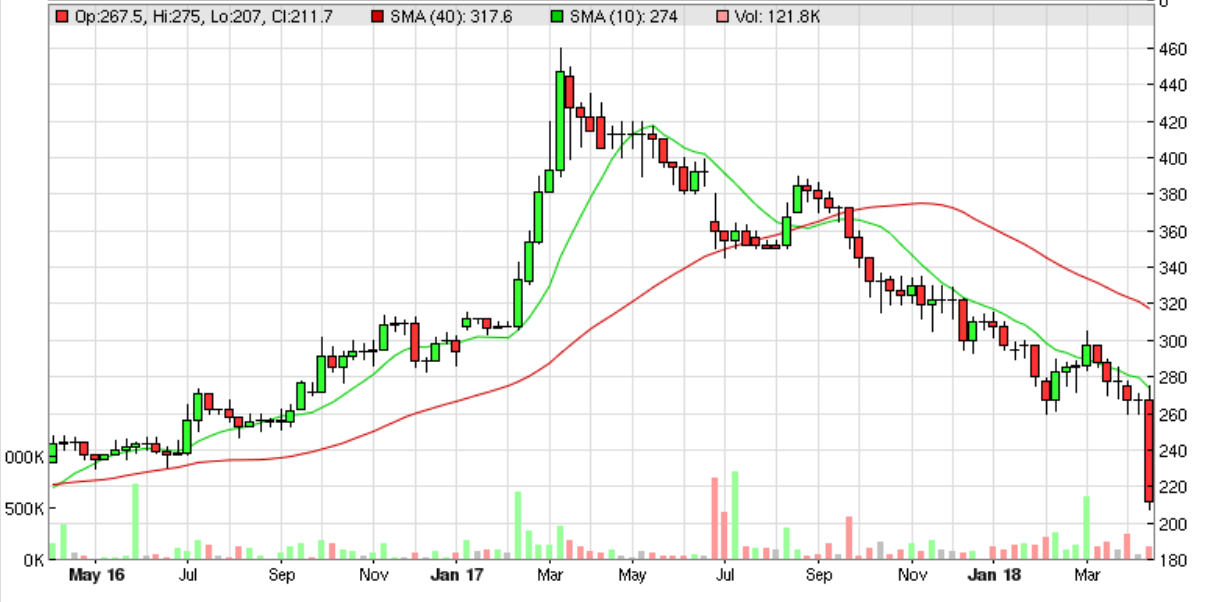
The inverted-V shape chart rather suggests that, so far, management seem to have screwed up last year's big acquisition.
SysGroup (LON:SYS)1
Share price: 320p (up 6.7% today, at 13:00)
No. shares: 12.48m
Market cap: £39.9m
System1, the marketing services group, today releases the following trading update for the twelve months ended 31 March 2018 ("2017/18").
The Company changed its year-end last year and its previous audited financial statements relate to the 15 months ended 31 March 2017. To ensure like-for-like comparisons, percentage changes shown below have been calculated using, as the base, unaudited results for the twelve months ended 31 March 2017 ("2016/17", and where mentioned "last year" refers to 2016/17).
The company gives clear guidance on its profit for 03/2018;
... As a result, the Company now expects Profit before Tax to be in the range of approximately £1.6m to £2.0m for the year.
The above range is a long way below the net (i.e. post-tax) broker consensus figure shown on Stockopedia of £3.68m. That figure doesn't look right to me, and might be out-of-date, as there's hardly any broker coverage of this stock. It doesn't seem to tie in with the forecast EPS of 2.66p, which translates into PAT of just £330k. So I'm afraid it's not clear how the company's performance compares with expectations.
By my rough calculations, it looks as if 03/2018 is likely to be EPS of about 11.5p. So if that's right, then the PER is 27.8 - not a bargain, but it's based on a poor year. So the market seems to be anticipating an improvement in trading in 03/2019 and beyond.
This whole announcement is excellent for its clarity. That's very unusual for marketing/PR companies. Normally companies in this sector seem to go the opposite way, and try to deceive readers with overly optimistic narrative, and often spurious adjustments to the figures. So it's really refreshing to read the honest, and straightforward reporting from SYS1.
How about this for being completely straightforward;
As previously announced, trading during 2017/18 has been disappointing...
The company has cut costs, in response to poor revenues.
New products have been introduced, but no detail is given on that.
Net cash of £5.7m at 31 March 2018 is indeed "healthy", as the company says.
Outlook comments - none.
My opinion - I very much appreciate the honest reporting from this company. It has said in the past that it has little revenue visibility, and that's the fundamental problem, which makes it impossible to accurately value this share, as we have no idea what future earnings are likely to be.
In the past, the company has been highly successful, and paid generous divis.
So the share might have some attraction, as a punt on management delivering a return to previous form. There's too much guesswork involved, for it to interest me. I certainly think management should be applauded for their plain-speaking in RNSs. There are many companies and advisers who should take note, and change their approach to be more like SYS1.
Far too many PR people seem to think their job is to deceive people. It really shouldn't be like that. Their job is actually to communicate clearly & honestly, and to thereby manage expectations and build trust between investors & companies. Even though SYS1 has performed poorly, I feel that I can trust the company's announcements. Hence I'm more likely to buy the shares, if the company does begin to perform well again.
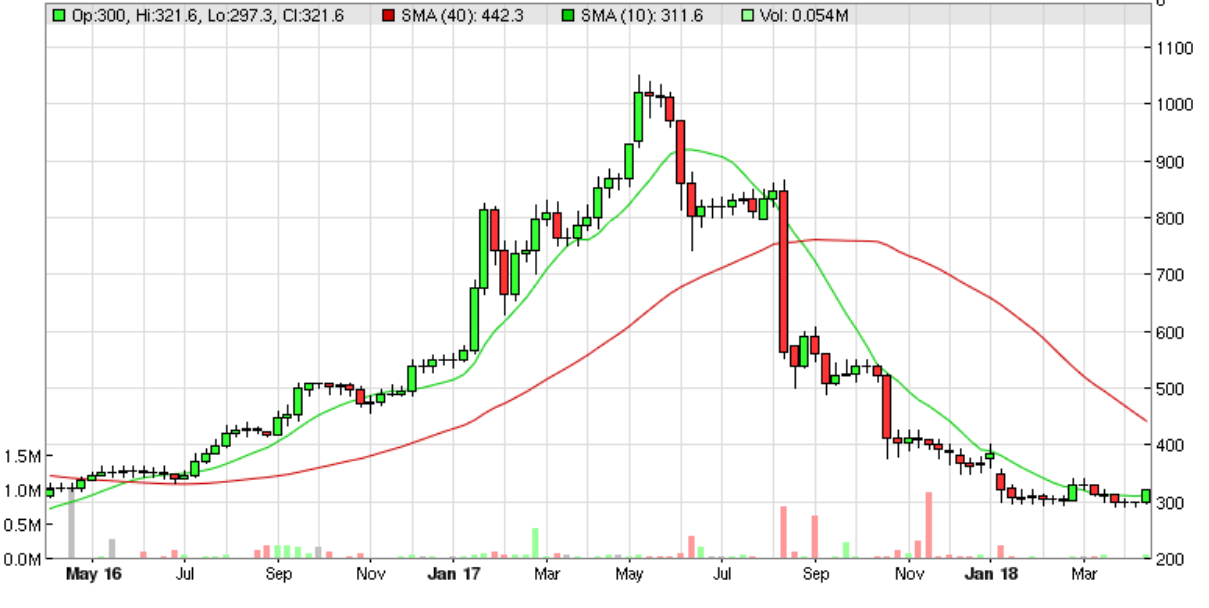
The chart looks interesting - somebody seems to be hoovering up sellers at around the 300p level. Could that now be a floor for the price?
STOP PRESS
Koovs (LON:KOOV)
Share price: 10.5p (up 21.4% today, at 13:56)
No. shares: 175.4m
Market cap: £18.4m
Share price movement & interim funding
The share price of this Indian eCommerce fashion business has been very volatile of late, and spiked up about 60% earlier today, to a peak of about 14.4p. This has forced the company into making an announcement. It seems the price spike was spurious;
Koovs plc ("Koovs", or the "Company") (AIM: KOOV) notes the recent movement in its share price and would like to inform the market that it knows of no specific reason for this price movement.
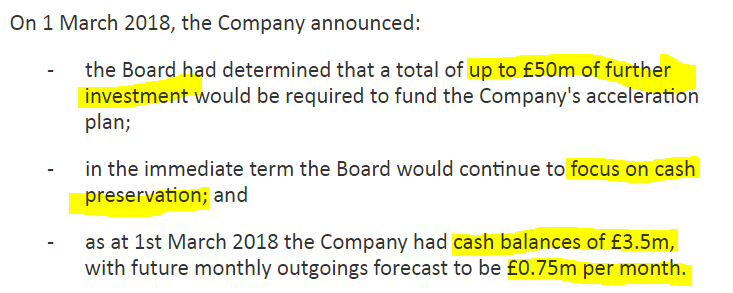
It reiterates the last update, showing that it's almost out of cash, and has a massive requirement for future cash injections;
Lord Alli is propping up the company until end Aug 2018;
The Company expects shortly to announce that it has secured interim funding via a loan of £1.5m from Lord Waheed Alli, a director of the Company. This interim funding will provide the Company with cash resources until the end of August 2018. On the basis this loan is entered into, it is expected to be classified as a related party transaction.
The company is still trying to raise more funding;
The Board actively continues the previously announced dialogue with potential new investors in respect of the £50m funding requirement and will update the market in due course.
My opinion - as regulars know, I've been consistently negative about this share, based on its lamentable financial track record. It's sad to see Lord Alli throwing more & more money at a concept that has failed to get off the ground.
In 5 years it has failed to generate meaningful sales, and has incurred heavy losses every year. At some point, sadly, it's just necessary to admit defeat, and pull the plug. I think there's a very high likelihood that we're nearing the end game. However, the company has almost gone bust before, and new funding was found, so who knows?
Existing shares are extremely risky, with a very high likelihood of a 100% loss. Hence this one comes with massive risk warnings, it's for gamblers only, at this stage.
OK, that's all from me today. Thanks for dropping by!
Best wishes, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

27 comments
Think you mean System1 (SYS1) rather than SysGroup (SYS) :)
rickbav - as this is your first post I think you should know that the standard £ followed by the epic code throws a wobbly if there is a numeric involved. Hence £ followed by sys1 has consistently diverted us to SysGroup (LON:SYS) today and £d4t4 doesn't work at all.
ANCR before the reverse takeover, had an excellent chairman who did what he said he would do. The new guys have no experience of buying or integration of businesses, hence a lot of shareholder value just got destroyed. The basic business model is good, so I'll let it keep falling until the time is ripe
The Animalcare (LON:ANCR) takeover won the Transaction of the Year award at the 2017 AIM awards.
(I also see the award for Best Use Of AIM in 2016 went to Conviviality.)
http://www.aim-awards.co.uk/archive/2017/winners/
John, looking back over AIM awardees they are a bit marmite - some have done exceptionally well and others have been complete dogs:
http://www.aim-awards.co.uk/archive/
I remember attending one investor event at the Chesterfield hotel in Mayfair (in the days of the mining / oil stock boom), taking a pee next to the ceo of Providence Resources (LON:PVR) and his broker, both crowing about receiving an award if I remember correctly. That stock was a complete dog and reminded me not to invest in companies with flamboyant CEOs, Tony O’Reilly I think his name was.
Anyway, Animalcare (LON:ANCR), what an example of taking a wrecking ball to a great little company. They had a nice little niche doing pet drugs and messed it all up. I remember feeling annoyed at the time as I so wanted to keep the stock but just felt shafted by the management in them agreeing to the reverse takeover. It just seemed the company was being stolen in the cheap by the two incoming CEOs of Ecuphar.
At the time, Ramridge did an excellent analysis on the Animalcare (LON:ANCR) post. It just showed how bad the deal looked to be. And it came true!
I'll be attending the UK Investment Show. There will be good speakers but the average company exhibiting is uninvestable for me. I have a look at their Stock Ranks and also last year's lot + one year performance in this article:
https://www.stockopedia.com/content/uk-investor-show-2017-ampamp-2018-exhibitor-stockranks-and-performance-trackers-354663/
RTC looks attractive but looks to be too small for most funds. Getting a large position must be hard and selling stock in quantity must be tricky and no doubt with a big spread.
That applies to all micro-caps. No-one would necessarily recommend taking a "large" position in these types of companies, but spreading one's risk with a number of positions in such companies has usually been a highly profitable methodology for me for many years.
As it happens, Chelverton Asset Management do own 6.8% of RTC. David Stredder (davidosh/Carmensfella) also owns 740,000 RTC shares.
Could I just point out (aside from all the brilliant Stockopedia data etc.) how excellent the Stockopedia community is. I was an Animalcare (LON:ANCR) holder prior to the reverse takeover. But following the announcement of the terms of the deal, among other comments on it was this thread (https://www.stockopedia.com/content/animal-care-reverse-takeover-195959/) which produced some excellent comments in a short space of time, dissecting the essential effects of the deal, the essential elements being all bad.
And the Stocko community seems to have been proven largely correct so far. Following my own review, and from reading all the other comments, I sold a long time ago, missing out (!) on a 47% decline in the share price (from announcement of the deal, to today).
You guys are great.
Chris
You are spot on Chris
I did exactly the same. The various comments on Animalcare (LON:ANCR) prompted me to review and then sell a short time after the reverse takeover and thus saved me from a substantial loss. I add my thanks for this to Paul, Graham (whose write ups were material in my decision) and all in the Stocko community
For those who like highly profitable microcaps, there's 3 good news stories today.
(1) Petards (LON:PEG) issued a very confident AGM statement. Revenues are slightly ahead of expectations. Order books are high, and good visibility of revenues plus potential "major new projects" provide confidence going forward. Before today it was forecast to make 2p EPS this year, against a 26.75p share price. It also has £2m net cash against its £14.9m m/cap.
(2) Enteq (LON:NTQ) issued a year end trading update "significantly ahead of its expectations". Importantly, it has $15.5m net cash against an £18.2m m/cap. It's an oilfield services supplier, and is particularly benefiting from the shale oil rebound in the USA, but is expanding globally, is run extremely prudently and "is well positioned to take advantage of potential opportunities".
(3) RTC (LON:RTC) (£5m m/cap) issued a positive AGM update. It's trading well, is experiencing "strong demand" and "is confident of the trading prospects of the Company in the current financial year". It's currently forecast to make 10p EPS this year, rising to 11.7p EPS next year - with 3.85p and 4.24p dividends respectively - against a 56p share price.
I thought the last results from RTC (LON:RTC) looked pretty disappointing - gross profit in both ATA and, particularly, Ganymede divisions were down and in GSS was up only about 5%; so improvements seem to be solely down to lower admin expenses, with margins looking pretty soft overall.
Good morning!
Thanks for the comments. I very much like it when members post a summary of the key points from company results here in the comments section.
This is my list of things to report on today;
IG Design (LON:IGR) - trading update
Vianet (LON:VNET) - trading update
Animalcare (LON:ANCR) - looks like a profit warning
SysGroup (LON:SYS)1 - trading update.
Then I have to do more work this afternoon preparing for Saturday's investor show, so limited time available again today, I'm afraid.
Best wishes, Paul.
Two requests:
1. IG Design (LON:IGR) Two directors presented at the PI World Investor presentations yesterday. There is a link to the PI World video in post 3 above. Both were very impressive. They really seem to know what they are doing. And the business seems to go from strength to strength. It’s only an inline update for 2018 but my guess, based on their confidence, is that forecasts for 2019 will start to edge upwards.
2. GB (LON:GBG) pre-close trading update looks very impressive. If I read it right, cash balances have increased significantly even after acquisition payments. Your help in picking through the acquisitions and adjustments to get to some real performance measures would be appreciated.
Disclosure - I am long IG Design (LON:IGR)
Looking forward to reading whatever you find interesting!
IG Design (LON:IGR) trading update today looks extremely positive, albeit ‘meeting expectations’. This company continues to go from strength to strength, despite the rather mundane product! Any thoughts Paul or others have would be welcome!
Another vote for Vianet (LON:VNET) please.
Looks an interesting company in the medium term
Dear All,
I would like to call on anyone who was a shareholder in Galasys (GLS) before they delisted in 2016. Shareholders have heard very little from this company since it delisted but i found out a listed Chinese company called Shiji Group purchased a majority share as of August 2017. My broker still hasn't been informed of any corporate action and after some investigation im starting to think there might be something a bit off.
It would be great to hear from anyone who might be in the same boat.
Also, if anyone has any advice on the matter that would also be appreciated.
http://www.shijigroup.com/news-center/newlist/?tx_news_pi1%5Bnews%5D=23&tx_news_pi1%5Bcontroller%5D=News&tx_news_pi1%5Baction%5D=detail&cHash=277dd0da85ff342b3877c9f4d166bd33
Regards
James
James
I'm not a shareholder in Galasys but a Companies House search for that name (https://beta.companieshouse.gov.uk/search?q=galasys) suggests that various companies of that name have recently bee dissolved or closed.
I see there's an email link for the Shiji chairman on the website whose link you gave. Does he respond?
Good luck!
Thanks for looking into this FREng. I haven't contacted the Chairman yet but he was next on my list having not received anything back from the COO who definitely speaks english. Its worth a go!
One of the good features of Investegate.co.uk is that they do not wipe everything when a company is delisted so I have just looked at GLS there. It appears to be a Jersey registered company so not with Companies House. I have sympathy with James in that it was delisted from suspension (due to nomad resignation) so no chance to get out.
I know that you follow LON:VNET Paul so would be interested in your views on their trading update today. "Broadly in line" suggests a slight earnings miss to expectations to me and a maintained dividend of 4p. Will the momentum continue with this share, with a P/E at c. 33 ratings seem high.
Vianet (LON:VNET)
I would agree trading "largely as anticipated" and profits "broadly in line" is indicative of a small miss vs expectations. A 6% fall though seems a little harsh, but perhaps the woolly words sew doubt.
"Profit" will be ahead of last years £3.32m, but as we're not told how much ahead that is not very useful, although later on profit growth is described as "good"
Incidentally I had to look up what that "profit" figure was - "Operating profit pre-amortisation of intangibles, share options and exceptional costs" that doesn't seem an unreasonable metric to use and there is no indication given of any significant changes to the excluded items.
One thing I find puzzling is that they refer to "progress on increasing the proportion of recurring revenue as a percentage of new sales" - last year they told us that recurring revenues were at 85% so a further increase to that should give pretty good earnings visibility.
But they also say : "Smart Machines revenue stream transition from capital sales to recurring annuity suppresses short term financial performance" - which suggests to me that they may be reducing installation charges and recovering more over the lifetime of the contracts. Probably good for generating growth, so long as the customers prove to be sticky.
They caution as ever on "challenges faced in its [the Smart Zones division] customers' core market of UK pub retailing"
Overall then I would say there's not too much to get excited about from this announcement, in either direction.
There remains an element of "jam tomorrow", with the comments on medium to long term prospects being "exciting".
I retain a small holding her, but given that short term prospects are evidently not "exciting" I am in two minds whether to continue to hold.
BTW - I don't know where you get a PE Ratio of 33 from? It is actually about 18x (possibly a little higher dependent on the size of the 'miss'). Dividend yield is a reasonable 4% - but bear in mind that the dividend has been held at 5.7p for the last 6 years.
Vote for Vianet (LON:VNET) here too please. There are some signs of green shoots here, though the book value looks too high.
Hi Gromley, thanks for some great analysis of £:VNET (also thanks to Paul too).
I was in a rush yesterday morning (before catching a couple of trains) so took the P/E figure straight from ADVFN. Admittedly I didn't take the time to manually work out the accuracy of that number.
IG Design (LON:IGR) in line trading statement. All very positive with 'trading accelerated in the second half ... gross and net margins increased ... USA significant overall profit growth ... Australia organic sales and profits advanced ... UK a new ... product category ... offers incremental opportunities.' Full year results 11.6.18.
Greater detail given in their presentation at the Progressive Equity Research - piworld presentation on Monday, here:
http://www.piworld.co.uk/2018/04/18/ig-design-group-igr-investor-presentation-april-2018/ c.40 mins
My morning smallcap tweet:
Newmark Security (LON:NWT), Petards (LON:PEG), Vianet (LON:VNET), SysGroup (LON:SYS)1, Animalcare (LON:ANCR)
Newmark Security (NWT) Safetell wins £1.5m contract extension.
Petards Group (PEG) AGM stmt: Q1 rev slightly ahead of management's expectations and almost 15% up.
Vianet Group (VNET) guides FY profits broadly in line with market expectations and up on 2017's £3.32m.
System1 Group (SYS1) guides FY pretax £1.6m to £2.0m. As previously announced, trading during 2017/18 has been disappointing.
Animalcare Group (ANCR) warns on 2018 due to the impact on gross margins of a changing sales mix and competitive pressures. Earnings, whilst still significantly ahead of the prior year, will be below market expectations.
Probably at the top end of the SCVR scale (market cap about £600m), but a decent Pre-close statement release from Identity Data Intelligence specialist GB (LON:GBG) this morning.
https://www.investegate.co.uk/gb-group-plc--gbg-/rns/gb-group-plc-pre-close-trading-statement/201804180700042461L/
Still looks expensive with a p/e around 30 and dividend of less than 1% but operating profit up 53% and revenues up 37% (17% “organic” excluding acquisitions) suggests it might be starting to grow into its punchy valuation.
Gus.