Small Cap Value Report (Mon 22 Jan 2018) - ACRL, DC., CNCT, ANCR, KETL, RBG, CCC, LTG

Morning!
News has been a bit hectic over the past few weeks, as companies updated for trading to the end of 2017.
Edit: Thanks for your requests, I am now also looking at Computacenter (LON:CCC) and Learning Technologies (LON:LTG).
I am updating my schedule today as follows:
- Accrol Group (LON:ACRL) - interims to October 2017
- Dixons Carphone (LON:DC.) - Christmas trading update
- Connect (LON:CNCT) - trading update
- Animalcare (LON:ANCR) - trading update
- Strix (LON:KETL) - trading update
- Revolution Bars (LON:RBG) - trading update
- Computacenter (LON:CCC)
- Learning Technologies (LON:LTG)
To cover everything, my usual article length will have to be cut - apologies in advance!
Graham
Accrol Group (LON:ACRL)
- Share price: 36.5p (+1%)
- No. of shares: 129 million
- Market cap: £47 million
To recap: this loo roll cutter listed on AIM at 100p in 2016, ran into financial difficulties last year, and has now resumed trading at a much lower level, after raising fresh equity.
The major cause of the difficulties was that the commodity Accrol uses, hardwood pulp, increased in price by 40%. Passing on this price increase to discount retailers couldn't happen fast enough to prevent a serious deterioration in the company's performance.
Indeed, Paul went back to the company's admission document, and found the risk warning where they stated in black and white that hardwood pulp was currently experiencing "oversupply", and that if its price increased, it would adversely affect the company's performance.
So it's another classic example of a well-timed IPO as investors got caught out by temporarily strong earnings, just before it floated.
Anyway, what next?
These results show revenue +13% to £72 million, but loss of margin results in a 35% reduction in gross profit, pushing the company into an operating loss of £5.7 million.
The company has a new CEO and COO, and has received £16.8 million in cash from investors through a placing.
The key debt-related figures are as follows:
- £29 million at October 2017
- Accrol then raised £18 million in a Placing, or £16.8 million net of expenses, so debt would have been reduced to c. £12 million if all funds were used for debt reduction and no further losses experienced.
(Of course, the funds raised weren't only used for debt reduction/working capital management. They are also being used for restructuring operations and improving health and safety procedures, which is an area where the company has had some difficulties in the past.)
- In November, the company forecast it would have maximum net debt of £23 million by April 2018. Latest broker forecasts are suggesting that net debt will rise to £24.6 million by April 2019.
Margins - this key operational metric has collapsed, down to 18% in the most recent period, from 28% in the equivalent period the year before.
Much more than investors may have realised, therefore, this stock is in large measure a bet on pulp prices. Passing on the price rises to customers is happening, but at the expense of top line volumes, and what if pulp prices keep rising? Won't the company suffer these same difficulties again?
My opinion - as flagged when I covered this company last, I think Accrol would need to raise more funds if it suffered a little bit more bad luck, e.g. if pulp prices rose again, if it hit against unexpected FX tailwinds, or if the operational measures it's taking turn out to be more expensive than forecast.
The net debt level is forecast to increase and is already not far off the level at which it was forced to raise more funds.
Arguably, there is a high-risk/high-reward equation here, so that if it did manage to avoid raising any more funds, and worked its way back to profitability, especially with the help of some macro tailwinds, then it could be very cheap at the current level. Maybe if you have a gambling mindset, it could be an entertaining trade! But not one for me, I'm afraid.
Edit: thanks to tabhair in the comments for pointing out that the CFO has resigned, to "pursue other interests". While the company might benefit from a replacement, I think this news elevates the risks involved for shareholders.
Dixons Carphone (LON:DC.)
- Share price: 194p (+3%)
- No. of shares: 1153 million
- Market cap: £2,237 million
Christmas 2017/2018 Trading Statement
I'm covering this well-known electricals/phone retailer as it is another important barometer of high street activity, which has knock-on effects for many other companies.
The Christmas update is a Q3 update for the full financial year, which ends in March.
It's a positive update:
- UK & Ireland Like-for-like revenue +3%
Electricals were a bit weaker at 1%, but mobile was up 8% with the help of the new iPhone.
International growth was stronger again versus the UK. Very positive in the Nordic region and Greece.
The "Headline PBT" forecast for the full-year is narrowed from £360 - £400million range, to a 365 Agile (LON:365) - £385 million range.
The company believes it grew market share in UK&I, i.e. that most competitors will have done worse than 3% LFL growth.
That's probably right. According to the ONS (external link), December retail sales across all segments were up just 1.4% by volume, the slowest growth since 2012.
If you add in the effect of inflation of 3%, spending was up 4.4%.
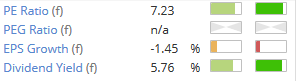
While I don't have the time to do a full assessment of Dixons Carphone (LON:DC.) as a potential investment opportunity right now, it's worth pointing out that its net debt level of £250 million is only a sliver of the company's market cap, and is lower than the net income forecast for this year alone.
It's trading very cheaply, no doubt as a consequence of the general gloom hanging over retailers, and looks worthy of a second look in my opinion:
For the high street generally, what can we take away from this update? I suppose it shows that in the current environment, it's more important than ever to find the stores which are growing market share - because if you're not growing market share, you're likely to be shrinking on an absolute basis in these conditions.
And with the cost pressures facing these companies, a bare minimum level of sales growth is needed just to stand still in terms of earnings.
I'm taking a balanced approach to the sector, being careful to only own my favourite names in my own portfolio, and keeping their combined weighting to a moderate overall level.
Connect (LON:CNCT)
- Share price: 75.7p (-28%)
- No. of shares: 248 million
- Market cap: £187 million
This is a specialist distributor with a particular emphasis on newspaper and magazine wholesaling.
Paul last covered it in October, noting that huge dividend yield it offered at the time (the share price was 96p). Offsetting that was the risk from the secular decline in newspaper volumes, and the company's debt and pension deficit position.
The market really doesn't like this update, though it doesn't sound that bad on the face of it:
Total Group revenue for continuing operations of £564.5m (FY2017: £584.9m) has decreased by 3.5% year to date, with the anticipated decline of newspaper and magazine sales more than offsetting revenue growth in Mixed Freight and Pass My Parcel (PMP).
Newspapers and magazines are performing in line with expectations in terms of profitability, but the other divisions aren't doing so well.
A nasty combo of contract delays, low margins and "market uncertainty" in Mixed Freight, and slower than expected cost reductions, reduce the anticipated PBT result for continuing operations for the entire group to a £42 - £45 million range.
According to the estimates available to me, previous guidance was for this come in around £49 million. So this is a material profit warning.
The rest of the statement is not very comforting. Planned cost savings of £15 million over two years will be more heavily weighted in the second year - shareholders can be sceptical about this, because weightings towards later periods have a habit of not happening.
Books division - it was in fact a double-whammy of bad news today, as Connect is potentially in dispute with a German investment vehicle which had (allegedly) agreed, conditional only on anti-trust approval, to buy Connect's books division. The vehicle now says it's not going forward. It's only a c. £12 million deal, but another unwanted distraction
My opinion - I'll be steering clear of this, as I find logistics a very difficult sector at the best of times. But it's worth noting that Connect (LON:CNCT) is still profitable. And it's operating in the hyper-depressed newspaper sector, which nobody wants to invest in. So if you are willing to do the research and satisfy yourself about the company's financial position, it could be a rewarding use of your time.
Royal Mail (LON:RMG) has a StockRank of 98, and a 500-year history. So I'd probably buy shares in that first, before I started researching Connect!
Animalcare (LON:ANCR)
- Share price: 295p (unch.)
- No. of shares: 60 million
- Market cap: £177 million
As you might guess from the name, this is an animal healthcare company.
It looked very attractive to me up until it engaged in the reverse-acquisition of a large Belgian company operating in the same space, in a deal which weakened the balance sheet and created massive dilution for existing Animalcare shareholders. At that time (July 2017), I thought the shares had become overpriced.
The shares have been drifting lower since then, so it might be worth putting them on our watchlist again.
Animalcare has deep relationships with vets and indeed with pets thanks to its range of medical products which are complemented by its microchipping business - it runs the second-largest pet microchip database in the UK.
Much hinges now on the integration of Animalcare with its European entity. Today's update informs us:
The integration is progressing as anticipated, but it is still at an early stage and as expected margins for the period to 31st December 2017 have yet to reflect the synergies that we expect to realise in the medium- to long-term. The Group is implementing a wide-ranging change agenda in order to establish a strong platform for the future that will deliver long-term shareholder value through the many opportunities available.
If the integration works, it could lead to a really successful and stable business.
It all became a bit too uncertain for me to want to get involved, but I could see these shares becoming a value opportunity again if they keep drifting, and as we get more news on the integration. Stay tuned.
Strix (LON:KETL)
- Share price: 142.5p (+3%)
- No. of shares: 190 million
- Market cap: £271 million
Strix listed in August 2017. It owns the patents for kettle safety controls, and has the global no. 1 position in this arena.
This is a full-year update for 2017. It is in line with expectations.
Global market share is maintained at 39% by volume (the company website previously put its market share at 38%).
Plans are on track with new product launches and newly-automated procedures.
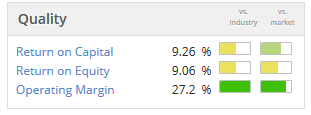
My opinion - this share is increasingly attractive to me, due to its market-leading position, and simple products.
We need updated financial statements to settle the nerves, as the company was reorganised for its IPO. At the moment, it still carries the general risk that comes with newly-floated shares. The vendors left it with some net debt, which is now estimated to be at £48 million. So that needs to be taken into account when looking at the cheap-ish PE ratio of c. 11x. And the customer list is a bit concentrated.
All that being said, I'm genuinely intrigued about the potential here. In the small-cap space, it's not too often we get to invest in companies with huge global market share in their industry. Full-year results are due on March 22.
Revolution Bars (LON:RBG)
- Share price: 172p (+3%)
- No. of shares: 50 million
- Market cap: £86 million
This bar operator updates for the half-year ending December 2017.
It was all drama last year, with a major profit warning, personnel changes, takeover offers, etc.
See for yourself:
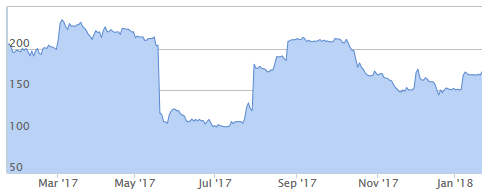
An all- cash offer was received at 203p per share, but the necessary 75% of votes in favour of the proposal could not be found.
Anyway, today's update bullishly presents a 10.6% increase in total sales and a 1.9% increase in LFL sales. Sales and profits are in line with expectations.
The LFL comparison uses a little bit of adjustment, taking 27 weeks to January 6 for each year, so as to include New Year's Eve.
I've had a quick look at Revolution's annual report for 2017, to see what is going on.
From the annual report:
The company has an accounting reference date 30 June and prepares accounts to the Saturday closest to this date. Throughout this report references to "2016" relate to the 53 week period ended 2 July... when discussing LFL metric the prior period comparisons have been adjusted to reflect an equivalent 53 week period.
Because the company always uses a Saturday as its year-end date, it creates this slightly messy half-year situation.
Last year, the 26-week period ended exactly on New Year's Eve.
This year, it ended the day before, creating an imbalance for comparative purposes.
So we have a 1.9% increase in LFL sales for H1. Within this, Q2 was up 3.1% and the 4 weeks in December were up even more. So the trend accelerated as the period continued.
Without the adjustment to include New Year's Eve, LFL sales are considerably less attractive: just +0.4% for H1, and +0.6% for Q2.
How to interpret this? Firstly, you need to trust that management aren't manipulating the figures. It seems reasonable to add an extra week to H1, so as to include New Year's Eve. But remember that if you do that, you can't also incorporate the benefit from NYE in your H2 numbers.
The other thing it implies is heavy reliance for performance on just a few days of the year. That goes with the territory in this sector, but it's a reminder of the risk you're exposed to.
Total sales were £73.7 million, helped by four new venues opening (Belfast, Solihull, Inverness, Putney).
Restatement - There were some accounting issues last year, noticed and remedied in H2. So the upcoming H1 results will show restated H1 accounts for last year. That's fair enough.
Outlook comment from the Executive Chairman is confident.
My opinion
I view the shares as approximately fairly valued. I understand that the company seeks to differentiate itself as a premium offering, but I tend to think of the bar/pub scene generally as being very price-competitive, except at the absolute top end.
If we generously ignore all of the "exceptional costs" from last year, the company earned £8 million in operating profit. Revenues are forecast to grow another 12% or so this year, and with the help of a little operating leverage, pre-tax profit is expected to grow to reach c. £10 million.
That's how we get the following value metrics:
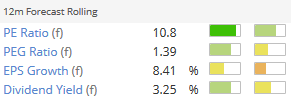
Again, that's probably about right, in my book, for a bar chain which is performing reasonably (assuming the adjusted LFL figures are the most relevant ones).
Personally, because of how the sector works, I'd need an above-average and well-covered dividend yield to invest in a bar/pub chain.
Stonegate were willing to pay more than the prevailing share price, because of their capability to strip out central costs, so that earnings would be higher within their stable. The company is not worth quite so much as an independent entity.
Also, 61% of votes were in favour of the Stonegate offer in October, so we already know that many shareholders would have been happy with 203p.
I can see this recovering toward 200p as the company continues to make progress. And then it will be up to the economic winds to determine what happens next. Putting my technical analysis hat on for a moment, I would expect to see psychological "resistance" at 203p!
Computacenter (LON:CCC)
- Share price: 1170p (+0.5%)
- No. of shares: 123 million
- Market cap: £1,435 million
This is a popular share in the comments. It was chosen by Ed for his New Year NAPS last year, having first entered the portfolio in 2015.
Share price performance has been excellent, and the Value Rank has moved back to an average level. The Quality Rank and Momentum Rank are thus the key attractions:
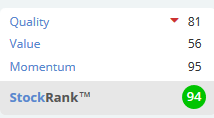
Some people hate the name, but it's a serious business, providing a wide range of IT infrastructure services to businesses. If It was listed on the NASDAQ instead of in the UK, it would probably have a PE ratio of 40x!
Estimates for 2017 were repeatedly upgraded. Today's update says results they will be ahead of the expectations given in November.
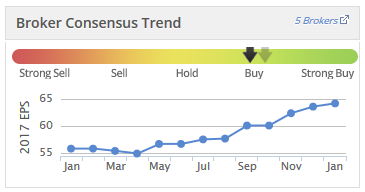
Rather than spending too much time analysing 2017, let's go straight to the outlook:
While we believe the positive momentum in the market is set to continue, there will be a number of one-off costs and investments within the Group in 2018 that will not repeat in 2019, which will hold back the enhancement of profitability in 2018. While it is still very early in 2018, the Board expect the year to be one of stable profitability.
This company produces forecasts and results in a clear and straightforward manner, which is one of the benefits of big-caps.
As 2018 progresses, maybe the share price momentum is finally going to run out, now that profitability is set to stall?
The long-term outlook remains fine, however. It has an impressive mix of public and private customers, which look like they might be quite "sticky" business.
I haven't spotted any red flags with it and suspect that it could be a good buy-and-hold investment.
Learning Technologies (LON:LTG)
- Share price: 84p (+12%)
- No. of shares: 572 million
- Market cap: £480 million
Thank you to readers for flagging this in the comments.
I covered this e-learning business in July, when the share price was 49p. Unfortunately, I had to put it into the "too difficult" basket, due to its acquisitive "buy and build" strategy.
Some far-sighted people have been discussing it here at Stockopedia, at this thread.
Today's news is an update for the full-year to December 2017. Adjusted EBIT and cash are both materially ahead of expectations.
Total revenues have almost doubled from £28 million to £52 million. This is partly driven by the £54 million acquisition of NetDimensions Holdings (LON:NETD) in March last year (see management interview here - external link).
On the much more interesting organic basis, revenues are up by more than 20%. The CEO discussed performance this morning in an interview which can be viewed here.
Note that one of the reasons for the improved cash position is the exercise of employee share options. I feel I must point out that this is not a positive event for external shareholders! The company gets cash from options being exercised, but at the cost of diluting the company's other owners.
The cash was also boosted by software licenses which were invoiced in Q4 - but I don't think all of these sales will have been recognised as revenues yet.
Those are only minor points. The big question is whether the company will succeed in its strategic objective:
In October we announced our new strategic objective to deliver run-rate revenues of £100 million and run-rate EBIT of £25 million by the end of 2020, financed through the use of internally generated operating cash flows and prudent debt financing, minimising dilution for shareholders. These impressive results for 2017 are an encouraging indicator of the progress that is being made towards this ambitious goal."My opinion - firstly, congratulations to those who have held this over the past couple of years.
I like the CEO's interview style. While he is describing a superb performance by the company for the year, he is careful to point out that the cash boost was thanks to some one-off factors and that it still won't be easy to reach the strategic objectives.
Apparently, the company started out as a professional services business. It was charging customers for its employees' time, but it wanted to evolve towards being a software business with recurring revenues. From an investors' perspective, the latter is far more attractive than the former! And on a run-rate basis, recurring revenues are now more than the 39% mentioned in today's update.
Company-commissioned research suggests that adjusted PBT will have been £13 million for 2017, rising to £14.6 million in 2018, off £56 million of revenues.
I don't think anybody can deny that the valuation of nearly £500 million is now at the expensive end of the scale, versus those forecast earnings. To justify the current share price, and achieve its goals, further acquisitions will be required.
Let's keep an eye on the company's progression from the current level.
I'm out of time for today, thanks for dropping by!
Graham
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

96 comments
Carpetright (LON:CPR).Got to agree that the company seems poorly set up for today's retail environment. CEO seems clueless and has no idea as to why footfall fell. Could even be another warning.
WOW! 8 reports - and in detail.
I learn so much from them - and from the comments from much more knowledgeable investors than me.
You've earned the next 3 days off Graham.
Revolution Bars (LON:RBG)
An interesting article in Sunday times on Restaurants / Bars through out the country, seems many are closing branches or not fitting out leases they have signed. there is now a multitude of variety & styles to choose from, the capacity of which is outnumbering the clients. Looks like rebalancing.
Graham,
Thanks for your marathon effort today - much appreciated.
First IPO of 2017. Maybe worth commenting on tomorrow:
investegate.co.uk/integrafin-holdings/rns/intention-to-float/201801220700044611C/
Thanks for flagging this, ratioinvestor. I have a couple of concerns: firstly, the float is targeting Institutional Investors who have been given access to the IPO document whilst private investors are limited to what was released as an RNS this morning. It is hard to assess the business when such limited information has been provided.
Secondly, I'm not convinced by the reason for the IPO other than to "enable selling shareholders to realise, in whole or in part, their investment in the Company". I may be being cynical here, but are the selling shareholders cashing out at the peak of the market. I know MIFID II (implemented on 3 Jan 2018) is having an impact on asset managers with certain costs increasing due to implementing the project and also "business as normal" costs in 2018. In addition, the landscape is becoming more competitive with more tracker funds & ETFs being launched with lower fees compared to active managers. So I wonder whether the historic growth has peaked?
Perhaps I am being overly critical, but without the IPO document in advance of the date of trading, it is tough to analyse.
Gajri, Good points. I think you can look at things both ways. If a company needs to raise money in its IPO than you can say it needs money to grow. If a company doesn't need money then you can say that it is profitable and self-funding. Your main point is: why are they doing the IPO? If they don't need money why not keep it private? I.e. are they doing the IPO to cash out? If so don't they think the future is good?
I also accept your point that if the end market is set to see tougher conditions then this would be a concern. My broader thoughts are that this is a profitable and founder driven company. These tend to be good IPOs but not in every instance. Certainly merits consideration. But I agree if there isn't a growth path then it is much less attractive.
Today's announcement from IntegraFin is the intention to float. In about two weeks they will announce a price range and two weeks after that the price. The prospectus hasn't been published yet. But it's a UK company so you can see the filing history at Companies House (https://beta.companieshouse.gov.uk/company/08860879/filing-history) which includes audited financial statements to Sep 16. There's also some useful commentary on business performance and KPIs.
In a main board IPO, there is a liquidity requirement of 25% typically. The IPO can consist of primary shares (new shares issued by the company) or secondary shares (pre-existing shares owned by the shareholders) or a mixture of both. IntegraFin is profitable, generates significant cash flow and had a 30 Sep 16 cash balance of £90m (which may include customer deposits). In circumstances where the company obviously doesn't need cash, where else would the shares come from? It doesn't seem unreasonable to me for the founders to take money off the table nearly two decades after the business was started.
Regarding IQE (LON:IQE) (and I appreciate there's a long running thread elsewhere on Stockopedia, but it seems to be a bit of a topic here today!), I recall Graham noting that he'd probably go short back in November, but that "fighting against momentum is usually a mistake."
https://www.stockopedia.com/content/small-cap-value-report-fri-10-nov-2017-cgs-vlx-iqe-239088/
That was when IQE (LON:IQE) had a momentum rank of 83. Today's is 50, just ten weeks later.
(I was long on IQE (LON:IQE), sold out, made a little bit, and now watching from the sidelines).
Revolution Bars (LON:RBG) - nice comment Graham. i think there is both a collar and a cap on this share for the time being. In the absence of any further indication of action from Stonegate, weakness will be met with people loading up while strength will be met with people who were prepared to sell at 203p doing so. Particularly arbs who bought at around the offer price (BoA). Stonegate are firmly in the driving seat. Deltic seemed at the time to be motivated as much by queering Stonegate's pitch (and continue to be so - they purchased 3% in November) but don't appear to have the resources to launch a bid. And they have, rightly, guessed that if Stonegate couldn't get through an offer at 203p they are unlikely to persuade shareholders to vote for a merger with a company that has a much weaker balance sheet. So stalemate unless Stonegate decide to come back to the table. Under the rules of the Takeover Code they would need RBG's approval to launch another bid within the next year. Deltic aren't similarly bound as they didn't make a bid last year. So, as I said, stalemate. In the current climate I don't think Stonegate need to be in any hurry. Trading at RBG is stable but not buoyant. They will surmise that they would need to offer more than 203p but it will be serve them best to wait and see if there is any sp weakness.
Hi mammyoko. Nice comment re: Revolution Bars (LON:RBG). Cap and collar is a good way of putting it!
Graham
Awesome effort today Graham, do wonder if you and Paul might be better off limiting it to four -five companies daily to save 12 hours research and keep the quality high.
Totally get it that the baying crowd myself included want all their fave's covered but I reckon at this rate you will both have requests for 20 stocks daily soon.
Maybe have one basket case per day we can all learn from the usual suspects I don't need to name them but it helps to see how you and Paul use Stocko to find the bombs waiting to go off.
Anyway keep up the awesome work.
Re Revolution Bars (LON:RBG) (I hold)
I make adj EBITDA (pre exceptionals and opening costs) of around £18m for 2017-18.
To me this looks fantastic for a company with an EV of just £87m.
Even with relatively meagre LfL sales, the estate is growing, so I'm not sure what I'm missing and why this share, to me, is so undervalued
Re ARCL. Their problem with the raw material getting more expensive is only a by-product of changing exchange rates and difficult to hedge. UK imports some 80% of timber consumption and this obviously raises the timber price so local growers raise their prices too. Demand increases and as most timber is harvested 30 to 40 years after planting the supply is pretty inelastic. There is increasing demand by biomass for the cheaper bits of harvested trees so difficult to see the raw material getting appreciably cheaper. TB
There was also an announcement of intention to float from IntegraFin (Http://www.londonstockexchange.com/exchange/news/market-news/market-news-detail/other/13503748.html). They operate Transact which is an investments platform for financial advisers. A bit like Jarvis Securities (LON:JIM) or Hargreaves Lansdown (LON:HL.) except focused only on FAs. 150k clients and 5k advisers with Funds under Direction (FuD) of £29.7bn which implies avg account size of £200k. There's an unusual line in the income statement called "Operating profit attributable to policyholder returns" which needs investigating. Could have some type of exposure to life insurance? Main list as opposed to AIM.
Sounds interesting. From the Compelling Economic Model tab in the press release:
"The Group has a highly attractive business model and an impressive record of consistently growing both revenue and operating profits. For the financial year ended 30 September 2017 ("FY2017"), the Group reported a high level of recurring revenues (96% of total revenues), an attractive profit margin (47% adjusted operating profit margin) and high cash conversion in excess of 90%.
- Continued strong growth was achieved in FY2017, with gross inflows of £5.3 billion (48.6% higher than prior year). FUD increased by 13.5% and profits after tax by 44% to £29.9m in FY2017.
- In addition, the Group has consistently returned value to shareholders, having paid a dividend and/or bought back shares every year since 2007, returning over £85 million to shareholders over this period. It has a strong balance sheet with no borrowings."
This is a SMALL cap site - what are people doing cluttering it up with requests for Dixons Carphone and Computacenter?
I much appreciate it when Paul or Graham branch out into areas of their own expertise ( like Paul's retail) but that is entirely their option.
Large caps are covered all over the place but this is our spot for the smaller stuff, so let's keep it that way.
The rules seem clear; no resources, no finance and no large caps, that leaves more than enough work for Paul and Graham, to whom I once again tip my hat in thanks
Hi, thanks for your comment! One small note for your information is that I do cover financial stocks.
Hello there! And many thanks Graham for the report! Has everyone been able to make sense of Revolution Bars (LON:RBG) 's annoucement today? I don't quite understand if it is a pre-profit warning. It just seems that the person who wrote it wants to say something is up, but doesn't quite say what it is... "Given that the adjustments were actioned in the second half of the comparative period, the half year impact needs to be appropriately phased and accordingly the first half comparatives will be restated."
This means that the prior year accounting adjustments were put through in H2 FY17 but need to be allocated between H1 and H2 to give fair comparatives for FY18. Where possible, prior-year adjustments will be allocated to the correct half-year comparative. Where it isn't possible to allocate the PYA to a particular half, it will be spread in some reasonable way across the two halfs
Getting quite fed up with this - mammyoko - No offense, yours is just the latest post - What are you talking about - H&T ( H & T (LON:HAT) ), Air Partner ( Air Partner (LON:AIR) ), Marks & Spencer ( Marks and Spencer (LON:MKS) ) - Something else?
I may as well go and read 90% cr*p on ADVFN as an unreasonable % of Stoko threads are now becoming cr*p because people cannot observe simple a single simple (logical) request. They are either posting comment without £ in front of the symbol - Or they are moaning that people are not using the £ symbol hence - In both cases the posts are useless - YOU'RE WASTING YOUR TIME AND OURS!
Is it so hard just to remember to use the £ symbol? If you don't then please realise you are posting a useless comment which people have to guess WTF you are talking about.
Ed - Can we have this or that to force people to do this or that? My view is - Ed - People know what to do, if they don't then their comment and hence intelligence should be treated appropriately.
Sorry all - Arrggggggghhhhhhh!
Matylda
I raised this early in 2015 as an idea request and it was rejected in the November
Force the inclusion of a stock code in every posting.
Force the inclusion of a stock code in every posting. There could be a few codes for non stock classifications but it would make searching for comments on shares in multi share threads a lot easier. Perhaps even then have a function to list all the comments on the requested share in a new 'thread'
1
vote
Vote
slartybartfast shared this idea · Feb 11, 2015 · Delete…
DECLINED · Nov 9, 2015
Re Accrol. Why are they making toilet paper out of hardwood trees anyway? We should all be using re-cycled toilet paper.
See whogivesacrap.org.
Paper has a Great Future:
https://www.youtube.com/watch?v=-rf7khCkhGk
Jane
Excellent vid :)
Regards
Howard
Can you cover a bit on Alliance Pharma (LON:APH) update please.
Thanks
ANCR reverse take over was always going to be messy, the Belgian team have no special skills in merging businesses and the senior people they kept on from the York HQ at ANCR were good but not startling, so change management is not likely to go well. The real synergies of the merger are more likely to come from enhanced sales of the exisiting range and better cross selling, but they could have done that without reversing into another company.
All in all a pity as the core business management was pretty good, even if some of the Directors were a bit dis-engaged.
bobo, the reverse takeover of Animalcare (LON:ANCR) did indeed shaft existing holders. I sold out upon this news, because for me it ruined what otherwise was a nice profitable niche and effectively gave away a large amount of the company.
I mused at the time that the incoming board members must have had some dirt on Iain Menneer - as otherwise why on earth would he have agreed on a deal that effectively gave two fingers up to existing shareholders?
Just like Graham said, patience might reward though and once things have settled down it might be worth a look again. Once I've got over my bitterness ;-)
Regarding Accrol Group (LON:ACRL), this bit worried me. I had thought that because Sterling had strengthened against the Dollar in recent month that Accrol Group (LON:ACRL) should be a beneficiary as their main input cost (hard wood pulp) would be denominated in Dollars. This isn't the case, a stronger Pound actually loses them money.
As a consequence of the fact that Sterling has progressively strengthened in value against the US dollar since October 2016, currency hedges which were taken out in late 2016/early 2017 and which were in place at 31 October 2017 were at rates which are now adverse to current market rates. If foreign exchange rates remain as is or Sterling strengthens further, these hedges will act as a drag on Company results until Autumn 2018, particularly for the second half of the current financial year.
So basically, it sounds like when Sterling was at its weakest against the Dollar, management decided to lock in the hedges. For me, it's not at all surprising that the CFO has resigned today. Whatever hedging strategy the company had in place here was executed on very poorly.
Also, we have pulp costs, which appear to be still increasing, so the company is still likely losing money when combined with the strengthening Pound.
Oh dear the £ sign in front of ticker doesn't seem to work - hence no link!
Not Mitchell and Butlers but Mitchells & Butlers (LON:MAB)1!!
Would you be able to cover £CCC? Would be interested to hear your thoughts.
re: Computacenter (LON:CCC)
Hi, I've added it the list! Cheers.
Mortgage Advice Bureau rather - link wont work
Would love you to cover Mitchells & Butlers (LON:MAB)1 also. Happy to hold on inline update with increasing number of advisors and return to growth in productivity. Outlook of modest growth in mortgage lending next year is also helpful to see.
High Street and general domestic UK doom is pervasive. Some stocks are getting hammered on bad news and many of the rest are implicitly tarred with the sh1tty stick if they lack newbie glamour.
Dixons Carphone (LON:DC.) seem to have provided a decent trading update. Electricals business has been decent and is now at the end of capital intensive reorg. Some business reconfiguration issues on forward basis for the phones business required to deal with changing behaviour of consumer.
Overall, the company seems to be priced as if electricals is a declining segment and the phones bit is doomed. The former is to be proven otherwise like all retail that competes with online however the initiatives from Dixons Carphone (LON:DC.) seem quite positive in this regard (selling point, delivery options, online presence, value adding services for the customer, significant store upgrade finished). Altogether, electricals business is anything but a dull retailer...if anything they may have too many initiatives in a bid to capture more margin.
On phones and mobile devices...well, they ain't going away and the company is dominant in the UK.
Too cheap and upside to earnings assuming no high street armageddon.
Views?
Hi Lavinit
My view for what it's worth is that almost everything Dixons Carphone (LON:DC.) sell is all will become a commodity product that can be easily bought through Amazon. For me the high street is in too much turmoil to be investable.
That said it is from the perspective of someone who likes shopping but does one 99% online as it is so much easier and you don't have to lug it home.
Kind regards
Michael
Hello Michael
Well you could be right of course. It can be quite crappy on the High Street.
However, at the moment Dixons Carphone (LON:DC.) is cheap unless you see its road to demise clearly in a few years. If not then its earns well and there's earnings and price optionality to the upside if they do particularly well (bought at 170p ish). It seems to me that the High St is under pressure for many reasons inc online...but it is inconceivable that the experience of shopping disappears anytime soon...some people have disposable income (or aspirations and a loan) and they will go shopping.
What's the optionality?
1) They dominate UK electrical retail like no other did. This gives them pull with suppliers and manufacturers
2) They invested considerably recently in the shopping experience. The new 3 in 1 stores look good (Currys, PC World and Carphone Warehouse). Moving from scrappy high streets to premium retail experience...and punters are going to do the experience (it may not be your glass of chablis but hey are you claiming to be representative?)
3) They are going after margin in services and attempting a sort of full vertical provider for the customer. Examples:
http://www.connectedworldservices.com/#firstPage
http://www.honeybeesolutions.com/
https://www.teamknowhow.com/
https://www.simplifydigital.co.uk/
Honeybee in real bluesky business looks interesting but could be BS...partnership with KPMG and Accenture to whom they may have paid a lot of wasted £s...time will tell. CW developed it as selling tool and seems to have been effective in that business. Team know how and simplify digital could be great...like an AA or Homeserve for electricals (there is a trust based market for that).
4) Other brands including Nordic and Greek plus Dixons travel (airports) and online UK mobile retailer mobiles.co.uk.
To keep it brief here's brand link - http://www.dixonscarphone.com/who-we-are/our-brands
Note https://www.idmobile.co.uk/ which uses Three's network but offers a more flexible service for customers (I think targeted at the less financially able and value for money)
5)) They recognised that they had been a bit crap at delivery and stock management and have invested to improve. Major investment in Nordic too.
I think a negative has been a split personality company. Old Dixons versus old Carphone Warehouse thrown together in 2014. IMO CW was the quality end but Dixons seemed to win the management positioning race. Departure of CEO and CFO in last couple of weeks looks problematic but it is quite possibly opportune. Who knows what went down but the release to day from chairman Baron Livingston of Parkhead (Hail! Hail!...he is a Celtic fan after all and ex director of that glorious club) hints this was very much a planned succession with him pushing the old out to usher in the new. My suspicion is also raised by the leak on Friday that CEO Seb James was leaving...on Friday I thought oh eff that will torpedo the stock come Monday but now it looks like James trying to control the media agenda and save face. I didn't know the guy as new to Dixons Carphone (LON:DC.) but I am now thinking a bit of a plonker (that posh floridity in language that can be an affectation to hide inadequacy - working in the city saw a lot of that!) and perhaps i have struck it lucky with my timing. Why?
Well, aside from football loyalties, I like Ian Livingston's past work. Good chairman to have. CW seems to be where the business quality lay and it should have got more of say in guiding the future. Looking at all the initiatives they have in place, they look interesting and potentially value adding. However, as an outsider there is a whiff of management consultants in alongside senior management making a brew that is a bit messy as impressionable management throw sh1t at everything to see what sticks. Always a bad sign when management consultants are in and not a situation to pay up a lot for stock. Its a hunch re management consultants at DC, not that I know.
The new CEO has the chance, with the aid of Livingston to sweep away any excess strategic flotsam...or make sure that they burn bright like a diamond or die in the next couple of years. At minimum they can cut away the extra stuff above and boost margins (short term at least). But my hunch is that there is value kicking around in there and Dixons Carphone (LON:DC.) is more than just retailer as a result...with good execution.
And as your enthusiasm in physical retailing has been rekindled :) ....may I interest you in this outstanding bargain:
https://www.stockopedia.com/content/scs-sofa-so-good-baby-302388/
Anyway, that's enough for now. I think I get a bump in price for rather mundane valuation reasons partly with the aid of lower capital spend on electrical retailers after major refit, lowered capital intensity in phones as they adapt model and a chance at a positive impact from pension deficit (never rely on that...could go either way but they have under control). And there's a chance at multi-bagger with good execution.
lavinit back at you, out
Hi Lavinit
Dixons Carphone (LON:DC.) This is a very good, constructive reply/bull case but I am afraid i just dont have the time, as very much a part time PI, to respond to each point. I wish I did. They are all very valid points and one possible alternative world.
I should have made it clear that I am in no way representative (possibly the opposite!) but I was going by what I see in my local towns (Worcester, Hereford, Gt Malvern) when I, rarely, visit them (they are just so dull and lifeless and few people seem to be carrying bags) and by the way the 35 young (under 30) people who work for me shop (Boohoo.Com (LON:BOO) $AMZN etc).
I am sure some destination centres will last (Bull ring, Oxford Street, Knightsbridge migh survive as destination shopping centres) but high streets in your average UK town as more and more people born in the internet age come of age are I think in terminal decline.
Anyway time will tell.
Kind regards
Michael
Hi Michael
I have some Boohoo.Com (LON:BOO) - its a moonbeam shot and of course could come unstuck...hard to see the execution when revenue goes so quick. I note that the board is quite techy / VC-y in inclination. This means that they will go for top-line at all costs. Could be good, could be bad. The girls and mums like it (more when buying for the girls than themselves).
Ciao
This is an interesting conversation. Boohoo.Com (LON:BOO) is my largest holding (13% of folio), earliest purchase has five bagged and overall is 4x for me. I have not sold any of my holding since first purchase in November 2015). My understanding is that the founders have a rag trade background, seem to be able to execute (dont understand “hard to see the exeution when revenue goes so quick”) and are planning for revenue 6 times larger than it is now.
I dont know what time frame you judge things over or whether you would classify yourself as a long term investor or more of a trader but I am looking at Dixons Carphone (LON:DC.) and Boohoo.Com (LON:BOO) in five to ten years time rather than at the end of the year.
As before time will tell
I'm new to Boohoo.Com (LON:BOO) at 180p so no bagging for me.
“hard to see the execution when revenue goes so quick” > they need to finance the building of new distribution capabilities (+ other things). They raised approx 2% equity to kick this off and they plan to finance the rest from cash flow...painless as the stock bulls along. If top line slows and costs rise on build then it will not appear so easy to finance it and that can negative feedback loop into valuation of stock. That's not a prediction, just an example. High top line growth can hide ills. That said they do make cash on it so this is no bluesky dream stock. But they are not immune from stumble.
I am long term but in the knowledge I can't see the future. Dixons Carphone (LON:DC.) is opportune purchase that I hope is medium to long term...there is no reason to love it too much but there is scope for duration of surprises. Undoubtedly boo has more upside potential than DC, but DC is perhaps safer to downside with decent upside (a double, perhaps more with good results). So I bought DC with lack of full understanding and doing work to catch up and make sure the price was right. I'm a lucky 20+% up.
I'm not fixed in my approach to investing. Perhaps best described as capital cycle and bit contrarian biased. I like stocks and sectors (and economies) that have learned the lesson of bad capital allocation...or have had to manage with capital discipline as they have not been fashionable. A great example of that is Argentina where I have investments since 2012 with many times bagging.
UK retail is interesting, particularly on the mundane and unfashionable high street side. There's pain and problems You are right that its got problems. However, its inconceivable that there will not be some form of destination retail going on over the next decade no matter how well online does. Recent Carpetright (LON:CPR) warning is an example of a retailer losing the battle and unable to withstands the sticks and stones of a rough time. IMO SCS (LON:SCS) is an example of retailer that (partly as a result of previous pain) has right fitted themselves for the environment (and is much cheaper too as everyone remembers its negatives whilst they have been willing to chase the past Lord Harris glories in CPR).
Best wishes
PS you just made the bull case for Bonmarche Holdings (LON:BON) ...you'd better back up that truck...old wifeys high street shopping in down at heal towns has got to be a growth industry...trade up from charity shop when feeling flush and need something else to do apart from bingo, coffee shops and the penny arcade.
Hi Lavinit
Could you expand on why I have made a case for Bonmarche Holdings (LON:BON) ? I cannot see it!!
Michael.
Hi Michael
It was meant in jest to some degree as its perhaps the ideal counter case to your view that the youngesters and monied are online shopping and the high street is dead. Bonmarche Holdings (LON:BON) is on all the crappy high streets so as the oldsters can go in browse and shop. I reckon its in the right place on the high street in crappy towns...as long as it gets its customer right.
I don't own it. I note that Graham (the writer) does (I think). Its an interesting one and I will look particularly as it has disappointed a little yet fallen a lot. Suggests perhaps an overreaction or too casual a negative sentiment...the other side of that is the view that Marks and Spencer (LON:MKS) went on their patch with a better offering and that is a real threat. I can get that. My mum was quintessential crappy town shopper...and for some reasons M&S holds status regardless of its woes and missteps.
There's cash flow and longevity punting clothes to old wifeys. Not too many want to compete with you either.
I'll respond later to your other point when I have time.
Best wishes
Paul
Hi Paul, I'd like to make clear that I don't own Bonmarche Holdings (LON:BON). I own Next (LON:NXT). Thanks.
Sincere apologies for tarring you with such a stock
Dixons Carphone (LON:DC.)
We have a big Curry's warehouse on a small trading estate which is great for browsing with a fantastic range on show. Very rare I buy "stuff" these days but we wanted a new fridge freezer a few years ago and checking online their prices were very competitive but visiting the store they were out of stock on anything that would serve our purpose and we bought online. Same happened just before Christmas when I checked out a Bluetooth speaker, sounded great none in stock. Went straight round to Argos and got one. I'm pretty determined to support local shops in preference to Amazon, I don't want them to get a monopoly but huge overheads of all that stock on display in local shops is a problem which affects the amount of stock for sale they could carry. Similar situation to when Comet started up years ago, everyone browsed in high street shops and bought at Comet, good for competition if you're a shopper but eventually a new offer comes along and upsets the applecart. Dixons survived as the likes of Rumbelows folded and the High Street became the preserve of pound shops, charity shops and estate agents but although I'm pleased they are surviving, I won't be investing.
Samsgrandad, no idea what stock you're talking about. Tag or don't type
Thanks for the tip runthejoules, I read Paul's comment just after posting and edited it, but did you know clicking on the link above my text "in reply to" would take you straight to the post I referred to.
You might find decaf coffee puts you in a better mood when posting, just saying.
Ha ha, 8 thumbs down for my comment but it did the trick! Dixons Carphone (LON:DC.) sure you can click 'in reply to' but it's quicker just to read it. Yes, hopefully soon Ed will update the software to proper threads though, for £200 a year!
Re Need to tag comments (or make it immediately clear what the subject matter is, if generic):
Doesn't deserve 8 thumbs down, in my view, even if you were venting a little frustration - it's a perpetual problem and continuing nuisance to Paul Scott and readers here in general - there's a lot to get through here: often 60 or more comments, and trying to work out what company is being referred to or what the subject matter is takes longer and adds unnecessary work for readers.
Or perhaps you can find a better use for your £200.
Samsgrandad! You have caused a fuss!
Anyhoo, see comment 65 for my response to your comment on Dixons Carphone (LON:DC.)
Valid comments but doesn't kill the case IMO...they make money and are cheap despite your criticisms.
There's room for improvement no doubt
Possibly "dry January" is causing some emotional reactions. Cheer up everyone only, just over a week to go, mine's a gin and fevertree tonic.
Revolution Bars (LON:RBG) results appear to be flattered by which period New Year’s Eve falls into for them. When they restate their LFL figures ensuring that both current and comparative periods include NYE the results are a bit lacklustre.
But it does make me wonder if some of the much better results from other bar groups such as Be At One are not fair comparatives.
Can I second the request for Learning Technologies (LON:LTG) please, looks interesting
Mortgage Advice Bureau (MAB1) issued an in-line update.
Mitchells & Butlers (LON:MAB)1 as you say issued an in-line update but share price fallen by 8%. Expected to beat expectations one assumes. Perhaps Graham might like to add to his very long list!
For Mortgage Advice Bureau (MAB1), I guess you can look at the numbers in different ways. On the plus side, the company says it will have delivered 17.4% revenue growth (using £109m) and about 13.8% EPS growth (using 23.1p as consensus and assuming in-line PBT translates to in-line EPS) on a 13.5% increase in advisers. They hit consensus despite not hitting their 15% target adviser recruitment and not insignificant investment in the business through two senior hires in 1H to lead the protection and mortgage offerings. The Australian JV was also established in Dec 16. It's possible this operated at loss in it's first year of operation and they've had to absorb their 45% share. Not entirely sure where this would show up in the income statement. They are still confident of delivering adviser growth as evidenced by: "We have a strong pipeline of potential new ARs, and we remain confident about delivering our growth plans, both organically and from new ARs." This statement, the CML forecasts for modest increases in gross mortgage lending, the direct to consumer advertising program which commences in 1H18, new mortgage application processes to reduce paperwork, and the continued opening up of the product switch/rate transfer (new mortgage with same lender) market suggest the outlook still looks bright. The product switch/rate transfer market is not included in CML forecasts but is estimated, by the company, to be about £90bn so their addressable market is approaching £350bn and their share is below 5%.
On the other hand, the CML estimate of £255bn for 2017 mortgage lending implies 2H17 lending of about £135bn, up nearly 9% on 2H16 and they entered 2H17 with 13% more advisers so +19.4% 2H on 2H looks a little light. At the EPS level, 23.1 consensus for the full year implies 2H EPS of 12.5p which would be +6.8% on 2H16 suggesting that margins contracted. This could reflect the factors highlighted above. Margins are also dependent on the mix of customers. Buy to let and remortgaging customers are unlikely to need any insurance products and insurance products carry higher margins.
It's also worth pointing out the company, historically, hasn't reported an "adjusted" EPS number (other than to exclude one-off gains). From memory, they didn't strip out share based compensation from the 1H numbers so there may be costs analysts would strip out which the company hasn't. That's just an observation. I am not implying that "adjusted" numbers will be better than what the company has indicated.
I like this business. I think the significant re-rating in the last 18 months is because it more closely resembles a platform business or a pipeline business that grows at attractive rates with minimal capex. It is exceptionally profitable if you look at net income as a proportion of net revenue (ie excl the revenue MAB collects but distributes to it's adviser network). And it pays 90% of profits in the form of a dividend.
Hi gsb,
Pity that you put all that trouble into writing comment no. 43, but forgot to actually state at the start of your post which company you're writing about! So all this "they", and "the company" is meaningless. You need to clearly set out the name and/or ticker of the company you're referring to. People are not going to bother to scroll backwards to find the original post, to check which company you're talking about. Instead they'll just ignore your post, so it was a waste of time writing it, without clearly stating what company you're talking about.
Paul.
Yes Paul - it's really really frustrating especially when there are a large number of companies being commented upon and where the original post might be some way back up the list (possibly even on another page).
Maybe the powers that be should look into the possibility of adding a feature where the company name and ideally it's ticker must be included for a comment to be posted??
Preferably the powers that be will have redesigned this feature in the new release to show comments in threads that can be easily followed rather than tacking replies on the end as currently.
If the highly intelligent users can’t get it right it’s designed wrong.
Preferably the powers that be will have redesigned this feature in the new release to show comments in threads that can be easily followed rather than tacking replies on the end as currently.
And hopefully they will fix the "£TICKER" so things like MAB2 ( Mitchells & Butlers (LON:MAB)2 ) and G4M ( £G4M ) work.
I agree it's frustrating when people don't tag their comments with the relevant company, and some people are serial offenders, but sometimes the conversation turns to an issue that doesn't apply to any individual company - perhaps an aspect of analysing company accounts, which might have been raised by commentary from Paul or Graham or a subscriber - so such a system will need to allow some generic options such as 'balance-sheet analysis', 'cashflow analysis', 'standard of company reporting' etc.
Your reminder arrived in time for me to edit the post to include reference to the company (MAB1). I've also discovered that clicking on the blue text after "in reply to" brings up the comment being replied to and the reply which, hopefully, will save scrolling when this inadvertently happens.
Hi Paul,
As already pointed out the £ sign followed by ticker doesn’t work for Mortgage Advice Bureau so some mitigation for gsb & request for guys at Stockopedia to see why Mitchells & Butlers (LON:MAB)1 comes up with Mitchell & Butlers!
Thanks
Re: Mortgage Advice Bureau (LON:MAB1)
Note - how good am I for fiddling to put this in as a hyperlink manually because the £ thingumy doesn't work for this one. Worth a thumbs up just for that!
Punished heavily for an in-line update. I've held it for quite a while and think it is a great company, but growth is clearly starting to slow a bit in percentage terms. No surprise as the company grows larger.
What's to like?
So, why did it get punished?
It's is probably past the time when this company is going to exceed expectations. It is solid, steady, predictable growth from here. No news on Australia. Is no news good news or bad news? There should have been an update on this. Slow down in housing market means fewer transactions in 2018 perhaps. Lastly perhaps the valuation had got a bit too high for the rate of future growth so a bit of a pull back was probably due.
But still a nice company as I see it so I continue to hold. Will be interesting to see how the Stockrank recalculates now the price has dropped a bit.
A request for Learning Technologies (LON:LTG) please. Revenue and adjusted EBIT growth looks great but it's difficult to see through the figures when the word "adjusted" is so prominent and there are no "non-adjusted" figures. The big acquisition of Netdimensions adds another complication.
Graham
I have just read your previous comments on Learning Technologies (LON:LTG) (21/07/17) all of which make complete sense. I am also usually allergic to acquisitive companies though Keywords Studios (LON:KWS) (on which I am long) has been a very successful exception. I am still interested in Learning Technologies (LON:LTG) partly because:
* recent director buying is encouraging
* the trading update (if I am reading it correctly) suggests that the NetDimensions acquisition may be the last
* they are now cash positive
* forward orders are very good
At the same time:
* shares in issue have been growing at a horrible rate
* share options (just a first glance) look very generous
I hope you can find enough motivation to have another look. I especially value the way in which you and Paul identify the negatives and so help us to avoid getting carried away by the directors' sales pitch
Hi julian,
re Learning Technologies (LON:LTG).
I've had a look at it now.
Thanks for your input. The only point I would quibble with you is that I don't think the NetDimensions Holdings (LON:NETD) acquisition will be the last. It might be the last one financed with new equity, at least. They are currently looking at new potential deals.
Best,
Graham
Any chance of a ramble on Michelmersh brick Graham Michelmersh Brick Holdings (LON:MBH)
Thanks
Another request for Computacenter (LON:CCC) please
Graham, I also would be interested on your take on Computacenter (LON:CCC) - what your general thoughts are on "returns of value" - is this good for shareholders or would a large dividend be better?
Thanks!
Wey Education (LON:WEY) have a new FD (he is also Company Sec) trained at PWC. Academy 21 merger complete. Months before ad campaign can be assessed but registrations up 40% on last year for first two weeks of Jan. NED has sold about £10k worth of shares, (33,333) still has 50k. up 1.61%. I hold
Has anyone got any comment on the large short taken out on IQE?
This is not news Clive. The shorters have been steadily increasing their positions over the last few months and now stands at 10.71% of declarable positions. Its been commented upon several times here. Personally, I don't hold but might if the price drops below 110p.
Thanks for your reply fwyburd. Good luck with all your investments. Regards, Clive
Indeed. IQE (LON:IQE) stock seems to be in a bit of a tussle between the shorters and long term believers like T Rowe Price and those who bought in the recent institutional placing.
What seems to have got people flustered is the heavy shorting of Carillion being a prelude for going bust and therefore a read across that this might be the case on other heavily shorted stocks.
But the situation couldn’t be more different in my view. IQE is a very technical business operating in multiple markets that are just beginning to experience rapid growth, that requires significant capex, and patience for these opportunities to come to fruition. It is thus a much misunderstood business (just take a look at the number of commentators who incorrectly refer to it as a chip manufacturer) and near to impossible to value on historic numbers.
Additionally, a number of the shorters took out some of their positions quite some time ago and their only chance of getting a return on those early positions is if they can drive the share price significantly lower by spooking the market.
In the end, you either believe the company has a bright future and so the shorters are just a minor distraction (my view - I hold a long term position). Or you can’t stand the volatility or don’t believe the good times are going to roll here and need to get out.
Re : IQE (LON:IQE)
These seems to be a view quite widely held on other more excitable message boards.
It may be true up to a point, but I do think that people get carried away with the view that {evil} shorters have a single minded obsession with 'manipulating' the prices of their shorts down. I'm minded to remember that the shorters are 'hedge funds', as in they hedge investments to take a broadly market neutral position.
Maybe they are long $AAPL and short £IQE? Or maybe, as IQE (LON:IQE) is apparently on a much richer valuation than it;s 'peers' , they are long a basket of peers and short £IQE?
If either of those are true, then they don't 'need' IQE to fall, their bet is simply that it performs less well than the other side of their trade.
When there are short positions, it's always worth reviewing your investment case to see if there is anything you missed, but no point imho over obsessing. Certainly sometimes big short positions come with situations like Carrilion, but more often than not they don't.
From what I have read the short interest is related to the rumour that Apple may discontinue production of the current iPhone X this summer.
https://www.forbes.com/sites/gordonkelly/2018/01/21/apple-iphone-x-buy-sales-specs-new-iphone-release-date/#4d8c2c2e10cb
Yes, but new model(s) with FaceID will replace it.
Re: IQE (LON:IQE)
Tom. The most recent shorting, a very small 0.1%, was on 16th Jan according to the shorttracker. The article you refer to came out on the 21st. I did a quick Google and it seems that this story first broke three days ago. So, it doesn’t seem like this rumour is the reason for the shorting.
Re: IQE (LON:IQE)
Fair points Gromley.
I don’t think the shorters are ‘evil’ manipulators. However, when I see them increasing their short positions in increments of 0.02% - 0.08% it doesn’t exactly feel like they have strong conviction about the future direction. But knowing that they know that each increase gets a lot of publicity on the boards etc, if I was them and wanted to the price to fall I would make a number of small incremental moves to generate more bearish sentiment on the boards rather than fewer, more significant ones.
By contrast, when I see Old Mutual near enough doubling their holding in Blue Prism (LON:PRSM) from around 9% to 18% as they did according to the RNS near the start of October, that seems much more like a strong conviction. (Disclosure- I am long on Blue Prism. Another bumpy ride!)
Valid hypothesis Graham, but equally if the shorters are indeed running some form of hedge, you would not necessarily expect them to show 'conviction' and indeed small changes might just reflect some form of rebalancing.
What I think is missing though from the whole "shorters working the price down" theory, is that I cannot think of a past instance where shorters have worked the price down and then successfully stampeded for the exit at or near the bottom. (To be fair I haven't really looked, but given how much this topic gets talked about in some places, you would think someone would have cited a few examples.)
I certainly dont think shorters are any more evill than people who are long a stock. They have a place in the market to enable price discovery.
But surely shorters fall into one of two catergories:
- They have spotted something (detrimental to the stock) that people who are long in a company have not
- They dont understand the company and why the price is where it is.
The problem is spotting which is which.
Simon Cawkwell about a year ago called Fevertree Drinks (LON:FEVR) a slamdunk short and I took the opposing view.
I have the opposing view (to the shorters) on IQE (LON:IQE) as did the Stockopedia computers until sometime in December when it went from Style High Flyer to Style Neutral.
Time will tell.
Same guys as the ones that shorted "Carillion" successfully I gather.
Worth considering given Apples sales not as strong as expected. They've considerable business with APPLE I gather.
We all saw what happened at Imagination. #IMG
http://www.telegraph.co.uk/technology/2018/01/21/carillion-short-seller-targets-welsh-apple-supplier-iqe/
According to Short Tracker, Marshall Wace currently have about 40 short positions of more than 0.5% of the share capital of UK listed companies. It’s what they do and like institutional long investors they’re not infallible ( Ocado (LON:OCDO) are on the list and are up 73% in the last 3 months) so I take their name on the IQE shorts register as a piece of data but not the sole grounds for a decision on IQE (LON:IQE) .
Gus
https://shorttracker.co.uk/manager/marshall-wace-llp/
Indeed. Everyone is fallible.
I presume their IQE (LON:IQE) position is based mainly on slowing APPLE (NAS:AAPL) Iphone sales expectations.
Time will tell if they're correct.
Ocado (LON:OCDO) - simply don't understand how this one defies gravity.Presumably because they have Goldmans backing them!
So how does one get the ticker thingy to work?
Computacenter (LON:CCC) expected to be ahead of expectations, they'd be good to look at!
Specialist brick maker Michelmersh Brick Holdings (LON:MBH) gives an “in line with expectations” trading update for revenues and profits. Reports Carlton Brickworks acquisition made last year bedding in well. Decent order book in place for 2018. Not much to add.
Gus.
My morning smallcap tweet:
Revolution Bars (LON:RBG), Goals Soccer Centres (LON:GOAL), Chamberlin (LON:CMH), IXICO (LON:IXI), Animalcare (LON:ANCR), Connect (LON:CNCT)
Revolution Bars (RBG) Q2 LFL up 3.1%. ""I am delighted with our sales performance in the second quarter and over Christmas" But still guides H1 in line with mgmt exp. I hold.
Goals Soccer Centres (GOAL) Warns FY profits will be broadly in line with the lower end of market expectations. LFL down 0.5% despite upgrading over half the estate.
Chamberlin (CMH) Machining Claim Update - "substantial progress has been made towards resolving technical problems. In addition a satisfactory settlement has been reached with the supplier of the new machining cells."
Oneview Group (ONEV) NED loans $300k for up to 90 days at 1% per month, pending large customer receipts expected later in the first quarter of 2018.
Ixico (IXI) AGM stmt. Co-founder Derek Hill resigns, will maintain his close relationship with IXICO in a scientific advisory capacity. New year has started well.
Animalcare Group (ANCR) FY trading: rev up 10%, slightly ahead of management expectations. Earnings are expected to be broadly in line with management expectations. Probably below then.
Connect Group (CNCT) Warns adj FY pretax (cont) only £42m to £45m despite rev in line. Offers up 4 reasons - a poor sign. Sale of Books Division to the listed pan-European mid-market investor Aurelius Equity Opportunities scuppered as buyer "can see no way of financing this transaction". Connect will try to force it through.
£RBG Sounds very positive but financially it's an 'In-line' trading update. Might be a tad concerned about "The financial statements for the 52 weeks ended 1 July 2017 included certain adjustments to accounting policies and practices, which required a restatement of the results of prior periods." So could be a sting in the tail come March...
Nevertheless, I can see the potential for a very positive uptick in the share price today.
Computacenter (LON:CCC) has just had a trading update. Would be great if you could have a look at them.
may I second the request for your thoughts on Computacenter :CCC please?
Given I heard no screams, I presume Revolution Bars (LON:RBG) was OK.
Phil