Small Cap Value Report (Wed 19 Jan 2022) - MORE, ACRL, BOTB, MIDW, SIS, PCIP, APP, ITS, EVE

Good morning, it's Paul & Jack here, in what is turning out to be a very busy week! Today's report is now finished
Agenda -
Paul's Section:
Accrol Group (LON:ACRL) - I review interim results. Poor balance sheet presentation makes it look highly geared, but it isn't once you strip out lease liabilities, confusingly shown as "borrowings". As mentioned last week, when it warned on profits, EBITDA does not translate into much profit, and the business model seems fundamentally flawed to me.
Hostmore (LON:MORE) (I hold) - I interviewed the CEO & CFO here - audio, 25 minutes - hopefully this is a good introduction to the company, and I challenge them on product quality & customer reviews. (no section below)
Best Of The Best (LON:BOTB) - H1 figures look solid, in line with expectations. But the H2 outlook is poor, with the big problem being increased marketing costs again. That results in fewer new players, and reduced profits. I'm braced for another share price fall today, which looks inevitable.
Pci- Pal (LON:PCIP) - a positive trading update. Very impressive growth in high margin, recurring, sticky revenues. Patent infringement legal case against the company is the fly in the ointment though.
Christie (LON:CTG) - a strong trading update, but difficult to quantify with no specific figures, and no broker research available. Looks to be family controlled. I have a stab at valuation, which looks reasonable, and it looks like market conditions for its niche might remain positive in 2022. Difficult to see much upside though.
In Style (LON:ITS) - an in line Xmas trading update, in terms of revenues. However, supply chain problems result in profit falling below expectations, so broker estimates are reduced today. It's a small player in a very crowded space, but so far is holding its own. Not something I would want to own though.
Eve Sleep (LON:EVE) - still loss-making. Still has cash, but it's almost halved in the last year. I suspect the chances of commercial success look slim now, and am stopping coverage now, unless something positive happens.
Jack's Section:
Midwich (LON:MIDW) - another profit upgrade from this audiovisual reseller, which has rebounded encouragingly from Covid disruption and is now reporting record levels of revenue and profits. I remain neutral as I think it’s a tough business model over the long term with low margins against a backdrop of generally rising costs, but the past few updates have certainly been positive.
Science In Sport (LON:SIS) - strong momentum online and underlying EBITDA growth to £2.2m. Net cash down from £10.5m to £4.9m, so still in the cash burn phase and investing for growth / scale, although it does look like breakeven is approaching. A good update on the whole, but it needs to be as the valuation remains quite rich.
Appreciate (LON:APP) - Signs of stabilisation, with the possibility of earnings upgrades once Q4 figures are received. The valuation is modest as the share price has collapsed, so it’s worth scoping out the chances of a rerating, but that same share price fall suggests a degree of skepticism.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul’s Section
Accrol Group (LON:ACRL)
23.6p (down 2%, at 13:08) - mkt cap £75m
I reported on ACRL’s profit warning here last week. The main problem is the 3-month time lag in passing on greatly increased input costs to customers. The company tries to persuade us that this is just a timing issue, but I see a deeper problem with its business model - volatile input prices, combined with low gross margins, and ruthlessly cost-conscious customers, makes it extremely difficult to predict profitability. To make things worse, the company is also capital-heavy, needing expensive equipment to turn large rolls of tissue into smaller rolls of tissue. Why would anyone find that an attractive business model to invest in?
The solution could be open book pricing with customers, i.e. charging customers on a cost plus basis, but customers may not be prepared to agree that. Supermarkets only make a wafer thin margin themselves, so are not known for their generosity in agreeing decent margins for their suppliers.
Also, ignore EBITDA here, because it translates into very little real profit. As I pointed out last week, the anticipated £9.0m EBITDA this year (FY 4/2022) would become only £2.2m profit before tax(PBT), due to heavy depreciation and finance charges which are ignored by EBITDA.
Interim numbers today repeat a lot of the situation, but what I want to focus today on the balance sheet.
On the face of it, the situation with “borrowings” looks alarming, and working capital looks weak (current liabilities a lot more than current assets) -

.
Note that intangibles can be written off, which takes NTAV down: £82,726 NAV, less £60,408k intangible assets = £22,318k NTAV - which looks adequate.
The items which alarm me are called “borrowings”, which looks like excessive debt. However, note 9 shows that this is mostly IFRS 16 lease liabilities, which can be safely ignored - because they are future years’ operating costs, which shouldn’t be on the balance sheet at all, in my view.
Therefore the debt position is actually fine. Poor presentation of the balance sheet rings a false alarm, and the company really should change how it displays lease liabilities, as 2 separate items on the balance sheet, not rolled in with bank debt, since the two things are completely different.
.

.
Strategic review - as mentioned last week, but the company sounds vague about what the purpose is. I wonder if the bank wants the company to de-gear? In which case I worry that an equity fundraising might be on the cards? At the current low share price, that could bring dilution, especially if a deep discount has to be offered, to entice shareholders to support an equity fundraise. I can’t imagine shareholders would be thrilled about propping up the company again.
Although there does not seem to be any problem with the bank covenants, so it could be OK -
The Group continues to operate well within its existing banking covenants and has more than sufficient liquidity to meet its existing and future needs.
The share count has more than tripled since ACRL floated in 2016, from 93m to 319m -
.

.
Do remember that these are annual averages, on the StockReport. So we also need to check the current share count, which is further down, near the bottom of the StockReport.
.

.
Maybe I’m barking up the wrong tree, thinking an equity raise might be needed? But what does the company expect, if it puts out vague talk about a strategic review?
My opinion - this share seems tainted, because the much vaunted turnaround hasn’t really worked, due to cost inflation. The business model seems fundamentally flawed to me.
That said, once it has passed on price rises, then profitability should rise. If input costs eventually fall, then profits could soar, which is what happened in the period before the company listed in 2016 - funny that - before crashing into 4 years of losses -
.

.
I’m satisfied that there’s no issue over solvency, as the bank debt is quite modest, so shouldn’t be a problem, but we can’t be certain of that.
For me, the upside is too uncertain, so it’s not something that interests me. The £75m market cap seems too high, given the very poor track record since it floated in 2016, with numerous problems, and hardly any divis paid over that time. The long-term chart since it floated in 2016 says it all (below).
Maybe there is recovery potential here, but it’s too uncertain for me to want to own any ACRL shares. There are better, simpler opportunities elsewhere I fell.
.

.
Best Of The Best (LON:BOTB) (I hold)
608p (pre market open) - £57m mkt cap
Interim Results (and H2 profit warning)
Best of the Best plc runs competitions online to win cars and other prizes.
Company’s summary -
Operational gearing, higher customer acquisition costs and increased prizes have reduced margins on broadly stable revenues
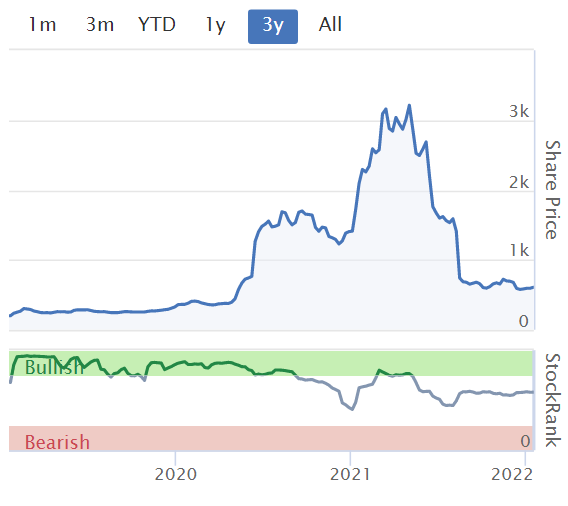
The highlights look good, in the context of a share price that collapsed after profit warnings last year -
.

.
What’s interesting, is that the big jump in revenues from the pandemic has largely held up. So the problem is not that business has returned to pre-pandemic revenues. The problems stem from higher costs (especially digital marketing), which seems might have been caused by increased competition, possibly bidding up the cost of relevant online ad words?
I’ve highlighted the underlying trend below, which still looks like a growth company to me, albeit with a one-off bumper year due to the pandemic.

.
Outlook - this is not good. Continued increases in the cost of marketing, means guidance for H2 is negative - given that H1 produced £3.0m PBT, this suggests H2 will only be £1.25-1.75m PBT -

.
Revised forecasts - many thanks to Finncap for updated forecasts this morning -
FY 4/2022 is cut 25% to 39.9p EPS (PER of 15.2)
FY 4/2023 is cut 32% to 43.9p EPS (PER of 13.8)
These forecasts are only slightly above pre-pandemic profitability, but revenues are nearly double pre-pandemic levels. So the problem is very clearly costs - marketing costs.
My opinion - I had hoped that the business was stabilising, and the H1 numbers are quite good in the circumstances. However, the outlook & guidance show a marked reduction in profitability in H2, and the full year, which is obviously negative.
Overall, I’ve assumed the brace position for the market open, and am assuming we probably see a fall to c.500p today.
I’m in for the duration, but won’t be buying any more at this stage. I need to see evidence of a more cost effective marketing strategy. As the commentary says, BOTB clearly needs to find a more cost efficient way of finding new customers, to replace the inevitable churn of existing customers.
We know there is massive operational gearing here, and long-serving management has a track record of fixing problems in the past, so I'm happy to continue holding long-term. It's not a big position size though.
.
.
Pci- Pal (LON:PCIP)
66.5p (up 15% at 09:10) - mkt cap £44m
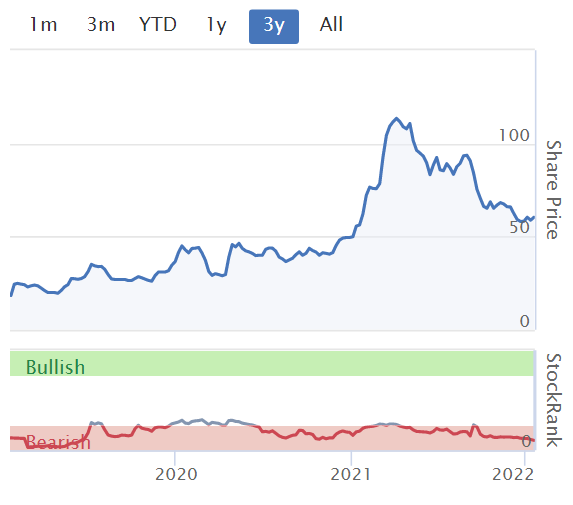
There seems a general pattern going on at the moment in small caps - most shares have been drifting down, often a lot, since peaking in H2 last year. Then when they report around now, we’re seeing some very large rebounds (e.g. SDG [I hold] yesterday), or they plummet on a profit warning (e.g. GATC yesterday).
There doesn’t seem to be any logic to the price moves downwards - it’s not necessarily a sign of poor fundamentals. That’s making it particularly difficult to pick stocks right now.
If you’ve got a small portfolio, then you have a massive advantage - get up early, latch onto the positive trading updates, and buy them on the opening bell. That’s working very well at the moment, because due to macro uncertainty, there are lots of people sitting on the sidelines in cash, waiting to buy companies with positive updates, so we’re seeing particularly powerful moves upwards on good news.
I’m looking nervously at my portfolio, and trying to imagine which ones are poised to shoot up on good news, and which ones are likely to issue profit warnings.
So far this year, it’s been mostly good, although BOTB didn’t help this morning.
PCIP has shot up 15% today, so the news must be positive.
PCI-PAL PLC (AIM: PCIP), the global cloud provider of secure payment solutions for business communications, announces a trading update for the six months to 31 December 2021.
Company’s summary -
Stronger than anticipated trading with significant revenue growth
Better than expectations, but still loss-making -
The Board is pleased to report an excellent first half of the year. All of the Group's key metrics are either at or ahead of management expectations, and as a result, the Group anticipates that revenue and losses before tax will now be better than the current market expectations for the full year.
Revenue - really impressive growth, up 72% to £5.4m for H1
Annualised run rate of recurring revenues (which they call TACV) is up 37% to £11.4m
New business is mainly coming from reseller partners
Very low customer churn of 3.4% - indicating very sticky recurring revenues, which are the best type of revenues
Cash of £5.5m (not stated whether this is gross or net)
Employee retention “very high” - not many companies report on this very important issue.
Patent claim against the company - this spooked me into selling out, and I won’t be likely to buy back in, unless/until there is clarity on this issue -
Proceedings in relation to the alleged patent infringement being made against the Company are ongoing and the Company is continuing to work towards an outcome that it believes will best benefit the business.
What does that mean? Sounds like a compromise might be being considered? That might involve having to settle in some way, maybe paying royalties to the patent owner, at a guess? Or fight it out in court, at potentially heavy cost?
Outlook - sounds encouraging -
"With the strength of trading shown to date, and a growing pipeline and partner eco-system, we now anticipate that the Group will exceed its current market revenue expectations, resulting in a reduced loss before tax for the financial year. The Board remains confident in the longer-term outlook for the Group and continues to invest in its ambitious growth strategy."
My opinion - this update sounds encouraging. You don’t find organic growth this strong very often, for a high gross margin, recurring revenues company. It’s a great pity the company ran into a legal claim for patent infringement, as that probably introduces too much uncertainty for me to invest.
Therefore anyone holding this share, is necessarily taking a risk on the outcome of the patent case. It might turn out OK, or it might not. Alternatively, that issue has probably reduced the market cap by about maybe £10-20m, which could be enough to cover the risk?
I think the share price would probably be a good bit higher, if the patent case is settled on reasonable terms.
PCIP looks a very decent, niche business, growing very strongly, albeit still loss-making - but with a very clear trajectory towards profit, due to rapid growth, and operational gearing.
US markets (with UK markets following) have seemingly taken a decisive turn against speculative growth companies, and are more favourable to value/GARP shares again. Hence I’m keeping that in mind, which makes me reluctant to buy into loss-making companies right now, not that I do very often anyway. There has to be a clear trajectory towards profitability, which there is with PCIP. So is it actually a speculative tech share? Probably not, so it might be worth considering. The market cap of only £44m is hardly extortionate.
As you can probably tell, I’m on the fence with PCIP - tempted to buy back in, but worried about the patent legal action. Tricky one. What do subscribers think?
I'm pondering whether to buy a small position for my SIPP, and forget about it for a few years.
.
.
Christie (LON:CTG)
114p (up 12% at 10:04) - mkt cap £30m
The Board of Directors of Christie Group plc (CTG.L), the leading provider of Professional & Financial Services and Stock & Inventory Systems & Services to the hospitality, leisure, healthcare, medical, childcare & education and retail sectors, is pleased to announce the following trading update:
This is short, and sweet! -
"Following an extremely strong year end performance in Christie & Co, our Business Broking, Valuation & Advisory practice, the Group's operating profit for the year ended 31st December 2021 is anticipated to be very significantly in excess of current market expectations.
We intend to publish the Group's preliminary trading results for 2021 in April."
That’s clearly positive, but not well presented, as it fails to give us either a footnote to explain what market expectations are, nor any numeric guidance on likely profits. Just “very significantly in excess”, which is pretty vague, and could cover a wide range of possible outcomes. Does it mean profit ahead by 20%? 30%? 80%? Who knows? Well the company does, but they’re not telling us.
I don’t see any broker notes available on Research Tree, other than Shore Capital from July 2021, that’s too old now to be relevant.
The only figure I’ve got to work on, is 6.62p EPS broker consensus for FY 12/2021, shown on the StockReport. Christie seems to have made about 10p EPS historically in most years, so perhaps it’s on course to return to that level?
If so, then the PER would be about 11 now, which seems reasonable, for what I see as an unremarkable, ex-growth, cyclical business.
Divis are coming back, so there should be a reasonable income from this share.
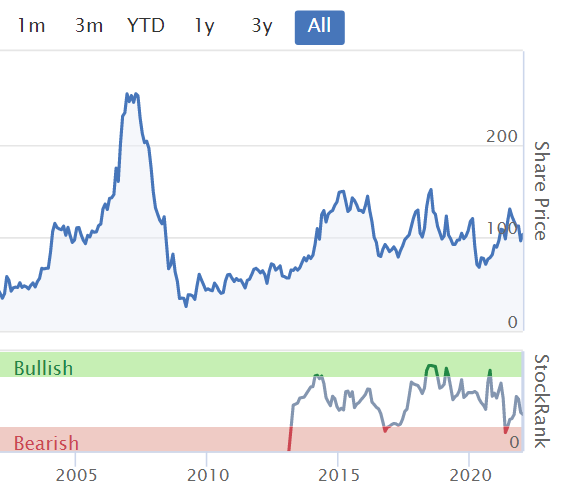
My opinion - all rather dull, this share has zig-zagged in a sideways trend for the last 7 years. It’s clearly trading well, because there’s a lot of deal activity going on in retail/hospitality property, and likely to increase further in 2022 when the rent moratorium ends - a lot of properties will be changing tenants when zombie operators are kicked out.
So Christie looks to have a decent outlook I imagine.
Is that enough to tempt me into the shares? In a word, no.
Note the shareholder register, with the Gwyn family looking to be in control. That's fine, and makes it a steady, safe investment. But where's the growth, and valuation excitement going to come from?
.
.
In Style (LON:ITS)
91p (down 3%, at 10:09) - mkt cap £48m
Trading Update (and Board Update)
In The Style, the fast-growing digital womenswear fashion brand with an innovative influencer collaboration model, is pleased to provide an update on Christmas trading for the eight weeks to 31 December 2021 (the "Period") as well as an update on its Board of Directors.
The year end is 31 March 2022.
8 week Xmas net sales £11.2m, up 21.5% on exceptionally good prior year comps (up 226% on 2-year view) - in line with expectations
Returns rate lower than in H1 (Apr-Sept 2021), trying to manage this down further
Gross order value is higher, but I reject this metric, because customers often over-order (e.g. 2 items in different sizes) then return the one that fits worst.
Partywear strong,as indicated by Next & Sosandar (I hold)
ITS thinks it is differentiated by using social media influencers. It’s not, everyone does it.
Wholesale doing well, in line, but most sales are still direct to customer through web, and app
Outlook - in line, for revenues, but what about profits?
Following the positive sales performance during the Christmas period, the Group anticipates achieving strong revenue growth for the financial year ended 31 March 2022 (FY22) in the range of £55m to £57m, in line with market expectations.
Supply chain - continues to incur extra costs & delays.
Late stock intake has caused more discounting.
Still profitable at EBITDA level, but only just -
As a result of these supply chain constraint issues, the Board now anticipates reporting a FY22 Adjusted EBITDA margin in the range of 1% to 2%.
CFO/COO - is stepping down in March 2022, to “focus on his health”. I wish him well, this is a brutal sector to work in. A new CFO is lined up, Richard Monaghan.
My opinion - I covered interim results here in Dec 2021. ITS looks to be holding its own, despite being a minnow, in a brutally competitive sector.
ITS also has plenty of cash on the balance sheet. Although as we’ve seen with private company Missguided, the wheels can very easily come off (Missguided needed a recent financial rescuer to avoid it going bust).
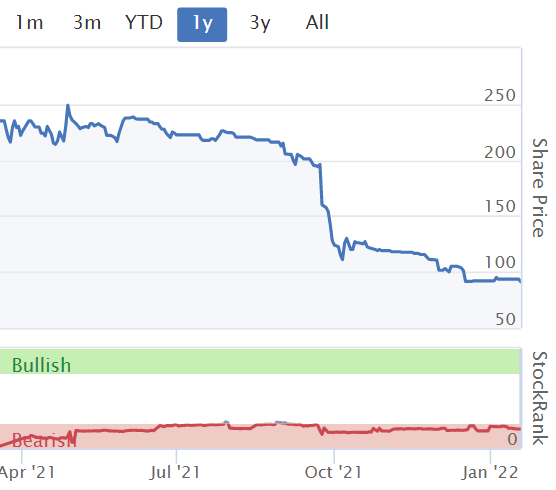
Forecasts are reduced today, on a cleverly disguised profit warning! It's now forecast to make a £(0.6)m loss for FY 3/2022. Not sure how the £48m market cap makes sense.
My worry is that, particularly for the smaller eCommerce companies, the money is made by staff, influencers, and Facebook/Google. That doesn't leave anything for shareholders in many cases.
It doesn’t appeal to me overall, as the sector is overcrowded, and picking a minnow, with me-too type product, doesn’t strike me as a way to turn rags into riches.
.
.
Eve Sleep (LON:EVE)
2.73p (down 23% at 11:50) - mkt cap £7.5m
Probably the last time I report on this seller of comfy mattresses.
FY 12/2021 trading update -
EBITDA loss of £(2.9)m in 2021 - H2 improved on H1
Net cash has reduced from £8.3m a year earlier, to £4.5m at end Dec 2021
Outlook - 2022 has started well.
Reckon they can get the UK& Ireland business to breakeven in 2022 (implying losses in France)
There’s an InvestorMeetCompany recording in the pipeline, which took place earlier today.
My opinion - overall, I don’t think EVE is likely to work. It’s in a very crowded space, and something the CEO said in a previous webinar convinced me to sell my shares, namely - “We’re up against against some very well-funded competition”.
Probably the best investors can hope for, is to be bought out by a competitor. I don’t think the “sleep wellness” strategy is a winner. There might be some value in the brand though, from previous marketing spending, making it a well-known brand?
.
.
Jack’s section
Midwich (LON:MIDW)
Share price: 626p
Shares in issue: 88,735,612
Market cap: £555.5m
Midwich distributes audiovisual (AV) tech to the trade market, with operations across EMEA, North America, and Asia Pacific. It floated back in 2016 and the shares have more than doubled since then, but is currently bumping up against a bit of a ceiling.

It’s a reasonably large enterprise now, with expected FY21 revenue of around £850m and a market cap of £555m.
The group is profitable, cash generative, and growing, though margins are fairly low and this could be a risk in a generally rising cost environment. The pre-pandemic norm was something like 4% operating margin.

Trading update for the year to 31 December 2021
The Board now anticipates reporting adjusted profit before tax not less than £31.5 million for 2021, which is ahead of previous expectations.
Midwich says it had a strong end to the year and now expects to report revenue growth of 20% to £850m (up 23% at constant currency), with an expected improvement in gross margins. The combined result is an upgrade to FY profit expectations. In fact, the group expects to report its highest revenues and net profit in history.
Adjusted net debt is £57m, around 1.5x adjusted EBITDA.
Diary date - final results to be released on 8 March 2022.
Conclusion
Midwich is a reseller. We’ve talked a few times about how much value this type of business, sitting in between providers and users, can add. On the one hand, it can be hard to differentiate your model and generate pricing power. Low margins are the norm.
On the other hand, those same issues mean that players that reach a certain size can create relatively durable scale advantages. This position of relative strength can facilitate acquisitions and further scale advantages, so you tend to see a few larger consolidators stripping out costs and generating synergies.
Midwich looks to be in the latter camp. Trading is again ahead of expectations and the group says recent acquisitions, including NMK, eLink, and Intro have performed well.
Assuming a 20% tax rate, net income might come out at something like £25.2m compared to current consensus of £21.8m, which would be a handy beat. The resulting 28.4p of earnings per share and an FY21 PER of 22x. Not in itself particularly cheap, so the market is expecting further growth.
The trading momentum is clearly positive though, and it’s a fast recovery from Covid disruption. Midwich has also successfully grown its revenues over a long period of time. So if it can continue along that trend while keeping a lid on costs, then it could continue to do quite well.

From what I’ve seen though, there’s nothing particularly exciting about the business model itself, so I suspect management execution and the pipeline and quality of acquisitions will play a key role. Nevertheless, it has the wind in its sails and this is not the first ‘ahead of expectations’ update it has released recently, so the direction of travel is positive.
Science In Sport (LON:SIS)
Share price: 70.5p (+2.92%)
Shares in issue: 135,100,931
Market cap: £95.2m
This is an interesting one. For a long time, it looked clearly too expensive for its size, although the management team sounds quite impressive and the sports nutrition market has attractive characteristics with potentially high margins.
SIS describers itself as ‘the premium performance nutrition company serving elite athletes, sports enthusiasts and the active lifestyle community’. It sells things like whey protein for gymgoers.
The CEO used to head the ‘Strategy Planning and Worldwide Business Development Director’ for the Nutritional Healthcare Division at Glaxosmithkline (LON:GSK) , which has always signalled to me that the team in place might know what it takes to make the company’s products mainstream.
The thing is that inkling needs to become quite a large part of your investment thesis here, as so far the group has been loss-making and equity-dilutive, with a sea of red across its Financial Summary. I’ve just never got that comfortable with it.

And you would need a lot of conviction to have held the shares over the years, I feel, given the level of volatility on display. Congratulations to anyone that picked up shares around the 25p mark though.

Trading update for the year to 31 December 2021
Revenue has grown by 25% to £62.7m and underlying EBITDA is £2.2m. The latter measure comes before share-based payments, which may or may not be appropriate depending on whether they are one-off. I see some comments in past SCVRs questioning remuneration policies (here and here), which is something to check.
That aside, it looks like a slight revenue beat on consensus of £60m.
PhD Nutrition is its premium active lifestyle nutrition brand. Revenue here is up by 19% to £29.7m. SIS, an endurance nutrition brand for elite athletes, grew sales by 30% to £33m. Product innovation delivered 32% of revenue growth, which is encouraging, as it signals a certain ambition to bring new products to market.
Gross margins increased slightly from 49% to 50%, driven by supply chain efficiencies, continued sales shift to online, and pricing, ‘more than offsetting commodity price increases’.
The accelerated capital investment programme delivered a new customer data platform, and a new supply chain facility in Blackburn is scheduled to open in late Q1 2022. This should lead to an immediate reduction in logistics costs.
Net cash has fallen from £10.5m to £4.9m as a result of these initiatives.
Online sales rose by 40% to £35m, up 28% on the group’s own platforms and +53% on third-party marketplaces. Great momentum here, with the online monthly sales record broken four times in H2 and a new sales record over peak November trading. Online is now 56% of total sales and is a ‘critical driver of ongoing growth’.
Retail sales - up 12% to £18.1m in the UK and +4% to £9.7m internationally despite pandemic restrictions.
Diary date - final results on 16 March 2022.
Conclusion
I’m typically wary of serially loss-making companies as the odds aren’t good, but some do make it. Science in Sport is a reasonably strong candidate in my view, although that loss-making status does elevate the risks, statistically speaking.
Still, with double-digit % revenue growth across its products, strong online momentum, and a new logistics facility set to reduce logistics costs in the near future, there could be an inflection point approaching. The group might have a degree of pricing power with its goods (based on comments noted above), and there’s a global opportunity for an experienced management team in this space, so we could see both high growth and margin expansion. Breakeven is in reach.
The cash burn is quite high though and the current net cash balance indicates that positive trends need to continue, otherwise further dilution could be a risk. That risk is probably reducing, but this is a crowded space too, with a lot of competition and M&A activity at the moment.
It’s a good update, but the price is just a little high for what I’d be willing to pay as things stand.
Appreciate (LON:APP)
Share price: 26.28p (11.36%)
Shares in issue: 186,347,228
Market cap: £49m
Not one I’ve looked at before, but a potential recovery situation with a Value Rank of 83 after a steep fall in the share price.

The valuation is very modest if the forecast earnings figures can be trusted, with a forecast rolling PER of between 6 and 7x.
Appreciate has a portfolio of brands designed for consumers (savings and giftings) and businesses (corporate rewards), providing vouchers, cards, and ecodes. It’s hoped that the move to digital could accelerate growth and allow it to capture more market share.
The historical core of the business was Christmas Savings (helping cash-strapped, lower income customers to spread to cost of the festive period) but this is now less than half of total billings. Now, the focus is firmly on Corporate billings, so the investment case is shifting.
Q3 trading update for the three months to 31 December 2021
Appreciate says this is a key trading period. FY20 comps are used, in order to strip out lockdown impacts.
Underlying Q3 billings (excluding Christmas savings) was 13% ahead at £96.1m, with December up 41% versus the same month in FY20 at £45.6m, so nearly half of the revenue for the quarter. This has been the group’s best-ever quarter for Corporate business (the most important segment for Appreciate), with billings here of £77.6m.
Total year-to-date billings +8% on FY20. Here’s the quarterly breakdown (presumably the difference in YTD growth figures of 8% and 1% are down to the free school meals scheme).

The first phase of Appreciate’s Enterprise Resource Planning upgrade was completed in January 2022. This replaces the legacy back office systems that support HighStreetVouchers.com.
Outlook - on track to deliver in line with FY expectations, Q3 momentum has continued into Q4 with underlying billings up 8% on FY20 and up 10% on FY21 so far.
Conclusion
The shares look cheap and there are signs of stabilisation, but there has obviously been a collapse in investor confidence.
Appreciate has mentioned a £7bn market opportunity before. It’s not something I’ve looked into, and it pays to be skeptical of large market figures as the addressable opportunity might be a smaller fraction depending on market share and relevant sub-segments but even so, a proportion of £7bn could mean ample room for growth.
Liberum has retained a price target of 66p, so it’s worth noting the scale of the gap between that and today’s share price. Perhaps there are some subscribers out there that can fill us in on the recent history and opportunity?
Paul and Roland have each looked at the company in the past (here and here), both voicing a degree of skepticism. So the business model itself requires a closer look and I don’t know enough to comment right now, unfortunately.
For now, the cheap valuation and stabilising operating figures suggest it could be worth doing some digging here as there is potential for a rerating.

Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

54 comments
hi Paul. Regarding Best Of The Best (LON:BOTB) increased online costs, I do recall when I spoke to the CFO of Marks Electrical (LON:MRK) him saying online advertising costs had risen substantially. So may be this is something to be concerned about for all online businesses.
Just to add my thanks to Paul for the informative interview with Hostmore (LON:MORE) which provides support for the view that the shares look promising - to the extent that I will increase my (small) holding. I thought Robert Cook (CEO) was suitably responsive to your consumer feedback on your Bournemouth mystery shopping!
Interesting announcement by Revolution Bars (LON:RBG) this afternoon. To issue a trading update for H1, tomorrow. Usually companies give a bit of notice, if they do, when the updates are coming.
They could have easily not announced and just issued a TU tomorrow morning. So why do the announcement, and with only a day's notice? Seems all a bit rushed.
Also this announcement itself seemed rushed, coming out just after 12pm instead of the usual 7am start of the day.
Product testing the night before?
For AIM listings reporting October year end in January seems quite reasonable. Many are advised to avoid the immediate Christmas period - pre and post - as none of the professionals looking.
AIM calendar year ends tend to report late March, early April depending on the timing of Easter - and of course the quality of their results! Auditors are also impacted to varying degrees by Covid and the Omicron outbreak may have impacted some of the second tier more.
It's those leaving it til the full 6 months are nearly up that worry me...
Hi Paul
A bit of piste here but you have been in this game a lot longer than me (most of us here?) and was wondering whether you feel that with the increased ease and reduced cost of trading and the “democratisation” of investing you feel that the volatility (the severity of the price of a stock being marked up or down on positive/negative news) has increased over the passed few years?
I have only been investing properly since 2012/13 but feel this volatility has got worse since then.
Thank you.
Regards
Michael
I'm not Paul but my two cents:
- Investing is a competitive game. If all the other players are better than you at pricing accurately and forecasting the future prospects, then you'll probably be the loser.
- If there is alot of "dumb" / "passive" money flowing in, I see that as great news. It means that for the great companies I hold shares, the SP can really rocket to massive highs, for me to profit from. Best Of The Best (LON:BOTB) could be one example that is relevant today. But also look at Thg (LON:THG) for a recent example, and maybe like Ocado (LON:OCDO) and Boohoo (LON:BOO) . Many investors went in for the story in the past 1-2 years, elevating the SP to unrealistic highs (in hindsight)
- This does mean that it is harder to find undervalued companies, as if there's lots of money sloshing around looking for shares to be invested in, it will lift all share prices across the board
- While volatility doesn't matter to me as a long-ish term holder, it is highly beneficial to those that do short term trading. If that's your strategy, you should love the increased trading volumes over the last few years. More liquidity, more volatility = more opportunity for short term trading.
re Pci- Pal (LON:PCIP) - I too sold out when it became clear that the patent dispute would be a lengthy overhang and the very tight liquidity only added to the risk, with a painful drift resulting. My take is that, litigation aside, the fundamentals are excellent. This share is very cheap on p/s basis. But I took the opportunity to roll my investment in the name into high growth US tech names that had been even more badly beaten up. Much more expensive valuation but I'm a long term investor and it strikes me that I'd rather have my money in a very liquid name whose products are part of the fabric of every Fortune 500 company than in an illiquid small cap whose product provides a fix in what I foresee will eventually become a redundant process as new technologies replace agent card transactions via phone call.
Medium term, I expect to lose out, as I see this as a great trade for those who can see past the litigation - good profits should come to investors well before the growth curve turns down . But I'm asking myself "which company do I want to own?" rather than "which share makes me money this year or next?"
Good luck to holders. My hunch is that all will be well in due course.
That's me done for today! We covered nearly all the beats, and warnings, only missing Centaur Media (LON:CAU) beat, but I'm too tired to do any more now, sorry about that.
I've changed the colour-coding, which is now traffic lights:
Green = above expectations
Orange = in line
Red = profit warning
The wording says which they are, so no problem for colour-challenged people :-)
Paul,
re your traffic light system. Great idea - except for us colour deficient blokes.
Red, green and orange? Have mercy.
How about Yellow, Red & Blue? Or any contrasting prime colours?
Food for thought. For some.
Hi psin,
re your traffic light system. Great idea - except for us colour deficient blokes.
You didn't read what I said!
We actually write the word "ahead", so you don't need to know what colour it is, to know it's ahead! :-)
Regards, Paul.
as I am on a roll today (too much coffee probably) seems there is quite a strong read across from Wh Smith (LON:SMWH) results out this morning to Smiths News (LON:SNWS) prospects. Both tracking around 6% higher on the back of it albeit Smiths News (LON:SNWS) really just bouncing off recent lows.
Kromek (LON:KMK)
Paul - I noticed this one was penned in red on your sheet and dismissed as a perennial loss maker, which is probably historically pretty fair. But I spot a contrarian opportunity that's worth looking at I think.
1) Company will be profitable this year. How do we know ? well 96% of H2 revenue is already covered so risk of a miss is now minimal.
2) 60% of next years revenue is already covered - that's £11m so actually to achieve same result as this year requires only £4m of new contracts. Forecasts are £18m (which is a 20% growth rate and requires £7m of new orders). I suspect risk of a miss is now low for next year, a beat is likely and a major beat is quite possible. Why? because 3 OEMS have placed initial orders this year and a number of new contracts expected from them in 2022.
3) Value - Canon bought Redlan Tech (only direct competitor of Kromek (LON:KMK)) for an equivalent of 45p or 3 * the current share price. That suggest there is a potential deep value play here. OEMs will be very keen for Kromek (LON:KMK) not to get taken out because they are now the only independent manufacturer. If another OEM buys Kromek (LON:KMK) it will give a major headache to the others in terms of supply and pricing. For this reason I consider a bid reasonably likely at some point but in the interim gives them a competitive tendering advantage.
I'm now long as I can see this potentially doubling or tripling in the next year or two and the downside risk is now much lower. Cash is fine in excess of £10m.
EDIT: as pointed out by rmillaree profitability measured by cash profit (not accounting PBT which will have amortisation/depreciation for a while to come - see below note)
Kromek (LON:KMK)
1) Company will be profitable this year. How do we know ? well 96% of H2 revenue is already covered so risk of a miss is now minimal.
Why does stocky suggest loss will be £5.3 mill ye 30/4/2022 - is that out of date info. Looks like first half was only £2.3 loss mill so that suggests higher losses H2. When you say this year are you llaking perhaps about Calendar year just started perhaps?
Thanks for flagging this one up i do like it when companies are morphing from losses into profits and the shareprice is up today so it does look like the news today was positive - one to have a look at when i get time. I aint no chartist but that chart looks horrendous - guessing it matches the companies history of failed promises perhaps?
Seems pretty late to be reporting October 2020 figures any reason why they are so tardy reporting wise? - probably a slightly harsh criticism here . Question to self what is average reporting time for companies ref releasing interims.
sorry - should have been clearer in wording. That's cash profitable (not accounting). Depreciation/amortisation will be around for some time given historic capex investment.
In Kromek (LON:KMK) case I am fine with that as the R&D is genuine world class tech in conjunction with the likes of US dept of defence etc. That generates very big moats / barriers to entry in the future. Of course that's all irrelevant if they don't subsequently start making cash profits and stop burning cash, which it appears is now starting to happen. Hence the contrarian play. The Canon acquisition and read through valuation gives me comfort I'm not entirely barking mad!! I'm not wedded to the stock but I think the risk/reward looks decent here.
Thanks for your post on Kromek (LON:KMK) - that does sound potentially interesting. I only skimmed the headlines, thought they looked rubbish, hence promptly moved on. But as you say, there can be interesting detail lurking that might suggest a turnaround.
I missed Audioboom (LON:BOOM) for the same reason - dismissing it due to a terrible track record, and missing out on a lovely recovery in share price.
I'll have another look at KMK when I have a quiet moment.
Best wishes, Paul.
yes I missed Audioboom (LON:BOOM) too for exactly the same reason and was a bit dismissive on Kromek (LON:KMK) but on reflection am long. Be interested to see peoples thoughts. Broker note on Research Tree from Cenkos.
davidjhill,
Thanks for flagging this up, it looks an interesting situation. I will do a bit more digging this afternoon.
Richard
Pci- Pal (LON:PCIP)
Hi Paul - I also like the company but am not considering a buy until the patent dispute is resolved. Although the price shot up this morning my guess is that investors will use that as a bit of a selling opportunity and we will see a drift back down.
I remember a patent dispute at Yourgene Health (LON:YGEN) in the early days. Management were at pains to point out that their defence was strong but the share price drifted, even on contract wins etc. It only recovered once the dispute was resolved. In this case I would expect Pci- Pal (LON:PCIP) management to say there is no merit in the IP infringement claim. If they were holding their hands up i'd be very alarmed for the company, but I did note the tone of the language in this statement being more around seeking to resolve, rather than defending robustly in court. This makes me think that a commercial agreement is now more likely. Assuming any settlement doesn't deplete cash meaningfully or eat heavily into margins then I'm likely a buyer on news of a resolution. Until then I view it as too binary a risk.
I hear that there is likely to be a Bye Bye Boris Bounce.
Any thoughts on this?
BSV
Any kind of bounce would be welcome in the markets at the moment Bluesky seems to be mainly miner's and financials heading north at the moment.
Morning all - reassuring update from Nahl (LON:NAH) for those of us that follow the company (I hold).
Bank facilities have been renewed out to December 2024 and they've made great progress with the build of WIP within the personal injury division, which will throw off significant profits and cash from FY23 onwards.
The critical care division is coming out of a period of investment (and subsequent margin compression), which means that it should see both profit and revenue growth in FY22.
With the CC division alone set to produce £4m+ of operating profit, the group seems seriously undervalued at c.£22m market cap.
Massimo
Hey Massimo
I read the £NAHL update a little differently. £40m t/o where Stocko feed suggests it was going to be over £60m, unlikely to be any net profit though close to breakeven whereas Stocko forecast had £6m+. On this basis a significant miss on earnings.
Are you working to a different set of expectations? I had scanned the Stocko figures previously and was looking for confirmation of progress in the TU today. Looks like at least 12 months behind expectations on this basis.
Hope that whoever is feeding through to Stocko is providing better forecasts on other shares. Can forgive covid screwing up some forecasts but this is a substantial and significant gap.
There aren't any brokers covering Nahl (LON:NAH) so not sure where those expectations come from...
Peel Hunt cover them, according to the NAHL website.
https://www.nahlgroupplc.co.uk...
Massimo - agreed, was reassuring to see the key indicators of a successful turnaround in the NAL business all moving in the right direction, namely % of total claims now being processed in NAL up substantially (will be interesting to see how much that can be ramped up this year towards their target of 50% of all cases). As well an upswing in H2 of close to 30% in the number of enquiries the company had received vs H1.
Good morning Paul,
Just wanted to say I am loving the new audio links that I have noticed being posted recently.... I can now listen at work on my headset! #Multitasking
Keep it up plz and have a great day.
To my untrained eye results look pretty decent this morning for Crest Nicholson Holdings (LON:CRST): circa 63% of 2022 target revenue already in the bag, adjusted profit before tax more than doubled from the previous year, net cash of £252 million against net debt £99.6 million the previous year.
Yields tad over 4.5% and has been touted previously as the kind of company one of the bigger players could swallow up at some point, not up much this morning so I'm not sure if that's down to current negative overall market vibe, possible cladding claims or something else.
Regards
Andy
Re £BOTB (no position)
I’ve always been worried about the lack of liquidity here. On a bad news day the share price gets absolutely hammered, which appears to be the case today.
The other substantial issue for a long term investor hoping that this will be a mid-cap one day is the lack of any significant barriers to entry in this business. If the company has strong success then it will be noticed and copycats will jump in to take away some of the pie so the business will not grow to the size it otherwise would.
If the higher cost of acquisition per new customer is because of increased competition I don’t see any reason for that to decline. But I am wondering if they have had to pay higher prices for the cars, as that’s become a sellers market due to shortages. If that’s the cause of higher costs then it may abate somewhat.
But overall I feel this is still one to avoid as there’s too much uncertainty, too little differentiation and always the threat of the regulatory status of the “competition” changing.
I would have thought that the additional concern for the small investor might be the prospect of the company being taken private. Management appear to hold /control about 50% of the company and the private option would offer an exit route for the larger independent shareholders.
The statement a little strange to my eye as it is says that marketing costs for Nov and Dec 2021 increased by 37% yet there was reduced customer acquisition in the same two months. It then goes on to say that it has a large and loyal customer base which to my mind conflicts with the above.
Effectively the company is paying more (a lot more) to acquire fewer customers. This is the marketing equivalent of trying to fill a bucket with a hole in the bottom and such a reversal from what was apparently successful marketing business should be more clearly explained in the announcement.
Disclosure – never held,
The Q3 update published today from Appreciate (LON:APP) is good. In a nutshell:
I think there's likely 100%+ upside with this share in 6-24 months because:
It's not a business I'd want to hold forever - Xmas savings and gift vouchers don't seem like high quality reliable businesses - but it's the short-term recovery play I am most excited about and following a further top-up this morning is now my second largest holding.
On Appreciate (LON:APP) there is a new note out today from Capital Access Group.
They note that the £381m rev and 2.9p EPS forecast for FY22 is light and should be higher, but say key risk is level of voucher/card redemptions by consumers in Q4 normalising, and so they refuse to upgrade both officially till the end of Q4. So would take it that as long as we don't have another set of tighter restrictions for Feb and Mar, we should be in the clear and definitely higher EPS than 2.9p. I haven't seen retail chains warn on a soft Janar quarter so presume customers are still spending almost at normal rates in Q4.
(I hold)
Re Appreciate (LON:APP) - I hold a small position and am also optimistic about a good recovery in 2022.
In my view, the evidence for recovery is there in this latest trading update. All year Billings are up +8% vs 2years ago, Q3 is up +13% and Dec +41%. Billings translate to rev and profit with a delay and the mix is shifting to better margin digital.
The need in 2022 to work hard to retain good (low paid) staff’s loyalty whilst trying to avoid wage rises plays into their 'employee of the month' and non-cash bonus style rewards schemes. These are the core of Appreciate’s business now. (Hampers are gone and I think the Christmas savings product might follow).
Love2Shop is the leading flexible multi-redemption brand in this space (all brands except single store own brand offers are weak as you are given the reward, not buy it).
Restructuring was well underway before Covid but accelerated by it so now more is in higher margin digital (and card) based products with much less in paper. Businesses that make the leap from analogue to digital well, do very well in my view but having all 3 formats (Digital/card/paper) helps them make the jump with lower risk.
As Covid fears subside, I think we will see a resurgence in physical retail as defined broadly ie including experiential and hospitality, not just acquiring physical product) and smaller businesses, the currently weak part of the mix will start to offer redeemable rewards again as they try to rebuild. The bigger players already are.
With no share dilution, we only need Pre-Covid profit to return to $12Mn for EPS to boom. Financially, we should get good divis (>6% yield) whilst we wait for valuations to recover although talk of a tailward from rising interest rates is overblown as i) interest rates are not going to go that high and ii) so much more of the business is digital
Obviously, the yield reflects risk (further lockdowns, potential LT move away from reward schemes) but risk /reward now looks good to me.
I keep Best Of The Best (LON:BOTB) on my watchlist as a reminder of how important it is to monitor director sales. The company has declined terribly ever since.
On top of their trading difficulties, Best Of The Best (LON:BOTB) also STILL seem to be unable to update the market in a timely manner. Just how long have they known they will miss market expectations by at least 10%, given they now expect to miss by circa 28%? Surely this should have been RNS'd earlier.
Best Of The Best (LON:BOTB)
shanklin100
Just how long have they known they will miss market expectations by at least 10%, given they now expect to miss by circa 28%? Surely this should have been RNS'd earlier.
I don't really agree this update is untimely (wouldnt say the same with gattaca this week)
They confirmed today that up to 31/10/2021 trading was in line - so nothing inconsistent with November update.
During the period under review, the business traded in line with market expectations
They have explained that in November and December things have been poor and my presumption is that these two months have changed the picture with regard to H2 - they couldnt habe nown this early november. So i think this update within 19 days of the November/December tow month period is very fair and reasonable from a timing perspective generally spekaing ? what am i missing here specifically with regard your timing beef? - are we saying they are two to three weeks late updating ?
but reduced customer acquisition in November and December 2021, together with a
cautious outlook means that we believe our revenues for the full 12 months will now be £34 - £35 million, with pre-tax profits expected to be £4.25 -£4.75 million.
You do have a good reason to be upset with management they said the following on 11th November.
The Board remains confident about the prospects for the business, both in the
second half of the financial year and beyond
Clearly they called it wrong here but with regard to future stuff its reasonably clear they are just offering an opinion on how they think things will pan out - its reasonably obvious the future is sketchy even if they are confident.
What is clearly obvious here is that reverse operational gearing type sitaution will magnify the downside nightmare if things continued to go bad as they have done (ie grim should have ben expected if they continued to struggle) . I don't think many saw that coming on the way up (fair play to any savvy bod who did) - but its more than obvious on the way down that this business is being battered from all sides at present with very little obvious route back to former glories.
I am sure Best Of The Best (LON:BOTB) are all over their daily sales and marketing costs; what else have they got to do? I have no issue with the November update but...
...I strongly suspect that their certainty of weak trading in November and December, and a much lower FY outcome, did not miraculously appear to them yesterday.
Clearly, as and when they were certain the FY would be at last 10% lower (vs the 28% identified today) than market forecasts, they should have issued an RNS,
That must have happened before yesterday... ...my guess would be at least a month ago but, even if it was just a week ago (IMHOunlikely), they should have updated the market then, rather than have a false market in the shares until today.
Best Of The Best (LON:BOTB)
That must have happened before yesterday... ...my guess would be at least a month ago but, even if it was just a week ago (IMHOunlikely), they should have updated the market then, rather than have a false market in the shares until today.
You could be right in your asumptions here i just think nothing is clear cut from my persepctive - i dont know the inner workings of how plc boards work real time and how often they sit down to do those crunch decisions with full picture of where they are. It doesnt seem unreasonable though for them to meet only once a month to sit down and go through summary figures for prior month - only at that time will they have the full picture. Would things have been clear cut on november figures alone probably not if thats a quiet month out of the 6. When would they sit down go through the full detail of December and know the full implications of poor sales numbers in December - probably till about now so timing does not seem unreasonable to me IMHO. That doesnt alter your valid point that there is the distinct possibility they could and maybe therefore should have acted earlier - to me its just not obvious that they should. I am keen as shareholder not to over micromamage management ref expectations and i am very aware in business there is not always as clear a picture of what is going on "in real time" as we may expect or hope is the case in that regard.If you feel mangement are not on the ball (like next are always) then that is an obvious red flag and a very very very good one IMHO - i would agree with your thoughts that perhaps they could have acted sooner , the danger with acting too soon is they are similarly made to look like fools if they warn quickly and the results later turn out to be in lin ewith prior expectations.
Best Of The Best (LON:BOTB)
Seems reasonably clear from today’s update that botb is not really a very good business model end of.Not sure I would have said that 18 months ago when my worries with regard to this business we’re more to do with potential regulation rather than it’s ability to to well trading wise. Seems though that they are being pushed from all sides and I am not convinced that due to the obvious external pressures being put on them they will ever be able to turn the tide without resorting to external acquisitions. My thoughts don’t really count for much as it’s just my viewpoint here but that’s the way I see it.
I take a different view on Best Of The Best (LON:BOTB) - that it is a decent business model, one that had a huge success during COVID, and over the next two years will still have a decent profit margin, cashflow positive, NTAV positive.
The only problem was the share price, and investors' expectations on future levels of growth and profits.
Having said that, I do think management aren't the sharpest tools in the shed. Understandable, since they were the legacy management from when the company was smaller, and also when it wasn't a 100% online business.
Its clear that marketing is the key function of a business such as this. They seem to do almost all marketing in-house (have not seen mention of agencies). So surely they should have a good calibre marketing team?
The only two notable "senior" profiles I could find on LinkedIn is the Marketing Director - Ben Hughes. Been there since 2010, and before that only had marketing experience at News of the World. Hardly relevant. Maybe good at offline marketing at airports, pre-online-BOTB era.
And then there is the Head of Acquisition, Vikki Adair-Wright. Who would be the one with the responsibility of running the FB campaigns, the customer acquisition marketing programme. But she joined the business in 2014 (pre-online), and before that was doing small time marketing for her own eBay/Amazon store, and also as a lowly marketing executive at Emma Bridgewater.
If I was the board of BOTB, I would offer both Ben and Vikki a golden parachute to leave quietly, and hire a strong external CMO and Head of Acquisition, ideally from the gaming or gambling industry. People who really know how to build a best-in-class digital marketing machine.
Sadly, I did a search and couldn't find any open job specs out there. That would have given me confidence that they're getting their marketing house in order; as such as I have to still sit on the sidelines here and watch this burning house for a bit longer.
Following an extremely strong year end performance in Christie & Co, Christie (LON:CTG) our
Business Broking, Valuation & Advisory practice, the Group's operating
profit for the year ended 31(st) December 2021 is anticipated to be very
significantly in excess of current market expectations
Hi Paul
Thanks for publishing the recording of your interview with Hostmore (LON:MORE) and asking some blunt questions re customer service . You can’t get this information from trading statements.
The management are clearly approaching 2022 in a very confident mindset and from a position of financial strength.
I also appreciated the CFO being open that the share price and low PER is not a result of forced sellers. I agree that a higher PER will come from investor confidence following successive positive statements.
They clearly have their eye on new stores which could change the figures dramatically.
Whilst they wait for new opportunities, lets hope they also spend money maintaining current estate so the fizzy drinks and steak are as they should be.
I expect the Bournemouth store to be perfect next time you visit!
Hi Revs8,
Thanks, good points. I was interested in how the CEO would respond to my criticisms of food/drink quality & pricing. I was reassured when he said, rest assured, after this call, I'll be straight on the phone to the store, and the drinks machine supplier, to make sure the fizzy drinks are sorted out. That's exactly the type of hands-on management that I look for. No doubt they have area managers to fix issues like this too, but you need a CEO who keeps an eye on everything too.
If the QSR (quick service restaurant) trial is a success, then that opens up the possibility of huge numbers of new sites. Although competing with McDonalds, Five Guys, Leon, etc, would presumably have to be at a much lower price than TGIs restaurants charge, so I'm not sure how that would work? Can you sell essentially the same, or similar, product much cheaper in a takeaway venue?
If it achieves the £30m EBITDA (after rents) for FY 12/2022 forecast by Numis, then the current mkt cap looks way too cheap. Especially as it's a self-funded roll-out, of 3 formats (Fridays, Fridays QSRs, and 63rd+1st).
Clearly an ambitious mgt team, with the funding & opportunity to expand quite quickly, with lots of favourable property deals available - this is a great time to be taking advantage of weaker competition going bust, esp when rents mortorium ends, and lots of zombie operators will get kicked out of properties by landlords, keen to re-let to a solvent, expanding operator.
Hence why I see 50-100% upside this year on MORE shares, which would take it up to a more realistic valuation, in line with peers such as Fulham Shore (LON:FUL) and Restaurant (LON:RTN) .
Regards, Paul.
Reading the Times obituary of Lord Sainsbury, whose statement ‘retail is detail’ remains highly relevant. Would like to think that Executives regularly sample their companies’ customer service. Nothing like the awareness (fear) of an Executive dropping by unexpectedly to keep managers on track.
Hi Paul, what's your view on the Science In Sport (LON:SIS) trading update?
Hi Paul, what's your view on the Science In Sport (LON:SIS) trading update?
Jack's grabbed that one. He's almost finished writing it, I see from our googledoc (it's great, I can actually see him typing it in real time!!!), so should be published shortly.
P.
CLIG produced a trading statement today. The usual solid stuff plus a stonking dividend (including a special). All told a 9.4% dividend yield and a prospective P/E post profit share of maybe 8. Yes, it's cyclical, but it just churns out the cash. I hold and added during the last year.
The special dividend looks amazing. However, while there is an overall small net inflow in this half year, the continued net outflows in its two main fund strategies is concerning. Most of the other fund managers I follow have had tidy net inflows over the last year and City Of London Investment (LON:CLIG) is under-performing in that regard. I have been a long-term holder of City Of London Investment (LON:CLIG) but recently sold out on those worries, waiting for a better entry price.
Quite right. Emerging markets typically decline when interest rates rise, which must be a factor. We are entering a choppy period with increasing energy prices, Covid, and muscular China/Russia playing a part. But emerging markets still offer some relative value. My biggest concern is the age of the private shareholders, although fund managers seem to outlive everyone else.
Hi Patrick
I have been in that quandary for a while with City Of London Investment (LON:CLIG) I hold only in one of the families investments (makes it sound a lot lot grander than it actually is) which is mum's ISA (aka pension) as an income part of that. So with an average buy of £4.20 back in 2020 yes I should have sold at £5.50+ and bought back in somewhere lower but that is rear view mirror world and I am not a good trader.
I continue to hold because of the income which is paid out for mum to live on, so whilst there is a worry about the longer term structural trends in the funds, given the overall negative market since September/November I feel the cautious approach is ok for now and continue to hold, though obviously selling is quick enough as it is log on and click the button. I think that if it goes down through £5 and keeps heading lower that will probably happen.
So whilst this has met the sell if falls >10% from peak (depending on the spread and pricing obviously) but also has partly what are you going to replace it with if you do sell, considering mum is about 20% cash right now? Though I would note that I look on yield against current price not bought price when doing that part of the monthly review.
I would note that I have sold out on Polar Capital Holdings (LON:POLR) and Premier Miton (LON:PMI) for similar reasons to protect capital with the falling share price, I like both companies but why fight the market when you have a smaller holding and trading costs are <1% for a buy and sell transaction. Mum is still 1% down from January 2020 in terms of capital value, some of that is obviously my mistakes and I put my hand up for those, hence the cautious approach.
Sorry no total conclusion, I continue to hold. Like the income, but then this is an income hold and I am fortunate to sit on a reasonable capital buffer having bought in summer 2020, but watching if there is a tail down like say Polar Capital Holdings (LON:POLR) or Premier Miton (LON:PMI)
Tommy
Hi Paul, would be interested in thoughts on BOTB interim results, if you could consider.
Many thanks.
Thanks for covering Paul
.