Small Cap Value Report (Thu 18 March 2021) - SIS, EVE, PMP, EMR, GYM, CAPD

Good morning, it’s Paul & Jack here with the SCVR for Thursday.
Timing - This report is now finished.
In case you missed it, I added another section on Science In Sport (LON:SIS) to yesterday’s report in the afternoon. It looks potentially interesting. Here’s the link. The InvestorMeetCompany results webinar recording is now live for SIS, here. I've only watched a bit of it so far, but will report back if there's anything interesting in it.
My diary for today includes a webinar from Eve Sleep (LON:EVE) (I hold) at 13:30 on InvestorMeetCompany.
Empresaria (LON:EMR) is also doing a webinar on IMC at 16:15 today.
I’m so enjoying all these results webinars, it’s great to “meet” management for lots of companies. Small company investing is really all about backing the right people, with the right business models.
EVE has a pretty awful track record, but what’s interesting is that it’s got plenty of net cash, and has pared losses by cutting back on the previously huge marketing spend. It’s trying to develop internet sales. We’re in a bull market, so I thought it could be an interesting punt - very speculative though.
Agenda -
Paul -
Portmeirion (LON:PMP) (I hold) - Review of its FY 12/2020 results.
Eve Sleep (LON:EVE) (I hold) - quick review of FY 12/2020 numbers - a big reduction in losses, and plenty of cash.
Empresaria (LON:EMR) - fairly resilient in 2020, but 2021 recovery sounds hesitant.
Jack -
Gym (LON:GYM) - Full year results dominated by fact that sites were closed for 45% of full year trading days; set to reopen from 12th April
Capital (LON:CAPD) - strong results from this mining services provider, with an equally encouraging near-term outlook
Paul’s Section
Portmeirion (LON:PMP)
(I hold)
572p (pre market open) - mkt cap £80m
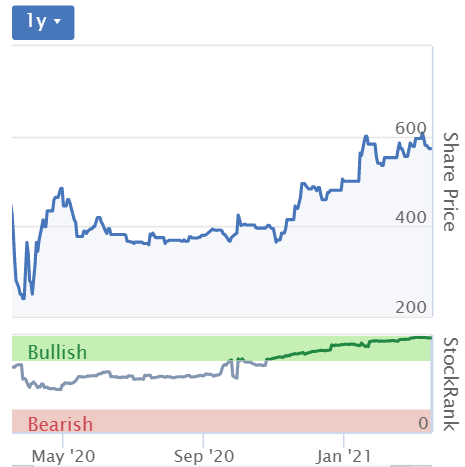
The share price chart here looks the same as everything else - plunging on covid in March 2020, then a bounce, flat over the summer, then a 50% gain since Nov 2020. I do sometimes wonder if there’s much skill in stock-picking, when you could have been long practically anything and made a similar gain in the last 6 months!
.
Results webinar - is being held tomorrow (19 March) at 11:30. Open to all, just click on the link.
Strong recovery in H2, ahead of market expectations
To be fair, I think the bar was set very low, so beating expectations isn’t particularly enthralling. Looking at the graph below, we can see how the darker blue line denotes EPS forecasts for FY 12/2020. When introduced pre-covid, the forecast was for nearly 82p EPS. That was then reduced to practically zero after covid struck.

.
Seasonality is important with PMP - it makes most of the profit in H2 each year, because a lot of its products are linked to Christmas & gifting.
See the table below, which I was delighted to discover buried in Stockopedia’s “Accounts”, then “Income Statement” area, which you then toggle to “INTERIM” and you then see sequential half years, enabling us to easily spot the seasonal trends for any company.
I’ve highlighted the H2 figures, to demonstrate how much more profitable H2 is than H1 -

.
In H1 2020, the company suffered, but not as much as I had feared, with revenues down about 8%, and instead of the usual £0-2m H1 profit, it made a “headline” (i.e. before some (small) adjustments) loss of £(2.67m).
H2 2020 was better, as expected, due to the seasonality, but still impacted by covid lockdowns. It made a headline profit before tax in H2 of £4.1m.
Full year 2020 figures, adding those two halves together, arrives at a modest £1.4m headline profit before tax, down 81% on 2019. Pretty bad, but that’s to be expected in the circumstances.
Online sales - this is a key area of focus, and is one of the main reasons I’m holding this share in my personal portfolio. Companies that are pivoting towards online sales, is a key area of focus for me, because the potential rewards are stellar if they get it right. Look at Best Of The Best (LON:BOTB) (I hold) where it gradually closed down the airport physical sites, to focus on growing its internet revenues. The closure of airport sites masked the decent growth online. It took them a few years to crack the digital marketing side of things, but the results this year have been staggering. When I started buying at about 120p per share, I never imagined it would be a 25-bagger in about 7 years! But given that an internet-based competition opens up potentially an almost unlimited global market, then the upside really is open-ended.
With that in mind, I very much like the more ambitious strategy of PMP’s new CEO, with particular focus on driving direct internet sales - which are higher margin too, because PMP gets both the wholesale and retailer’s margin. Although some costs are also higher, holding more stock, picking & packing, postage, customer returns, etc.
In particular, we have continued our transformation to a more online and digital based business and were pleased to see 69% sales growth in our own online website sales and that 47% of total sales in our core UK and US markets now go through all online channels (2019: 30%). We will continue to invest in this area and our capabilities and expect to see further growth in the years ahead.
That’s a good enough reason for me to continue holding PMP shares - the internet strategy is working, and delivering strong growth. Lockdowns will have helped drive up internet sales obviously, as physical retailers will have been closed at various times. Most companies seem to be saying that lockdowns probably accelerated existing trends to move business onto the internet, so I reckon this growth could continue, even when the shops have re-opened.
I bought some lovely “Botanic Garden” pottery from PMP, to test out the product & service, as mentioned here before. The product is lovely, and arrived well packed & unbroken. I now get (probably too many) emails from Portmeirion, with special offers, etc. I’ve subsequently bought more Botanic Garden products from them, twice. The point being that online sales create a direct relationship with the consumer, which PMP can then exploit for potentially many years. Its products are collectable, and of course get broken from time to time, so customers would I think have a good lifetime value. It would be interesting to find out what the key eCommerce statistic of LTV/CAC is (estimated lifetime value, divided by customer acquisition cost).
Balance Sheet - looks very good to me. Note that PMP raised £11.2m in a placing in June 2020, which greatly strengthened the balance sheet. However the dilution means the share count has gone up from 11m to 14m shares, which is a pity, as future EPS is not likely to reach previous levels due to that larger share count.
Net cash is £0.7m
There’s a small pension deficit, but it’s costing £0.9m pa. in recovery payments, which is material to profits, but should recede as a percentage of profits/cashflow when trading improves. Unhelpful though, and it needs to be factored into our valuation calculations.
Valuation - EPS was a statutory loss of (6)p, vs 54.6p in 2019. Ouch!
The “headline” EPS was only 4.95p (2019: 56.24p). So technically the PER is a nonsensical 115 times. Of course it doesn’t make sense to value the shares on a one-off bad year. It’s more logical to calculate what earnings the company might generate once more normal conditions pertain.
Many thanks to analyst Sahill Shan at N+1 Singer, who has crunched the numbers for us, and published an update note today on Research Tree. He has pencilled in only a modest increase in revenues of 2.5% for 2021. That looks eminently beatable to me. He’s assumed higher margins I think, so EPS shoots back up, from 5.0p in 2020, to forecast 36.4p in 2021 and 56.8p in 2022. His commentary indicates “upside risk” (i.e. forecasts could be beaten) if current recovery momentum is maintained.
Hence the forward PERs are 15.7 and 10.1 - good value in particular on the 2022 forecast, if it is achieved. Although I can see how some investors might want to wait for more evidence that the recovery is indeed underway, before committing.
Dividends - this used to be a high yielding share. What a pity they didn’t keep more financial reserves, as then we wouldn’t have suffered c.27% dilution in the equity fundraise in 2020. I hope companies learn from the pandemic, and beef up their balance sheets, rather than running up debt and paying excessive divis, which then leaves them in a mess when something unexpected goes wrong.
There are no divis for 2020, but PMP says today that it intends to re-commence divis in FY 12/2021. Personally I’d prefer them to grow the business faster, rather than resuming divis.
Outlook -
Covid - continues to disrupt in Q1 due to lockdowns - no surprise there.
This bit looks really good -
However, the strong growth we have experienced in online sales channels has mitigated much of the impact of retailer shutdowns and we are pleased by the improving trend of sales performance we saw in the second half of 2020. Encouragingly, we have continued to see this improving trend in the first quarter of 2021 and therefore remain confident of returning to sales growth in 2021.
My opinion - I’m happy with this overall, and will continue to hold for the long-term.
There seems good recovery potential in 2021, and I particularly like the strong online growth, which is now almost half all business.
I think PMP’s brands have untapped potential, with scope to widen the product ranges beyond just pottery & candles - e.g. hand and body care ranges are being introduced, which is a terrific idea. I’d like to see PMP’s brands become more lifestyle brands, and sell them mainly online, maybe even create a “marketplace” as leading fashion brands are doing, to become a portal selling lots of things from other companies too, earning commissions, without having to hold any stock, or handle/despatch the goods at all.
In the background, I think there’s always the chance a bidder from the USA could come knocking on our door. That’s fine by me, if they offer 1000p+ then I’d happily accept!
Has the strong share price in the last 6 months been justified? I think so, yes. For now, I think this share looks priced about right, and for me is a long-term hold.
Stockopedia really likes it - a very high StockRank, and it has a “Super Stock” classification too.
.

.
Eve Sleep (LON:EVE)
(I hold)
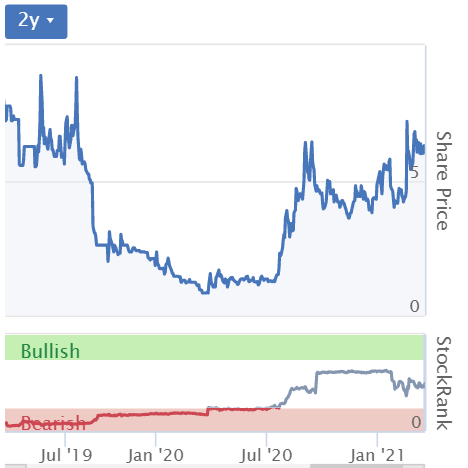
6.1p (down c.2%, at 11:57) - mkt cap £17m
As mentioned above, this company sells mostly memory foam mattresses, mainly online now I think.
It seems to be popular with traders, as the volume is surprisingly high for a micro cap - e.g. 17.3m shares have already printed so far today, that’s over 6% of all the shares in issue, just this morning! Hence expect price volatility here, as hoards of traders stampede in & out, sometimes after ramping/deramping it online.
We keep things fact-based here, so here are my notes from reading the accounts out today for FY 12/2020 -
- Revenue £25.2m (up 6% on 2019) - helped by lockdowns & home improvements trend
- Gross profit margin is high, at 57.3% (up from 53.1% in 2019)
- Various new definitions of profit are presented! Let’s stick with real profits, i.e. profit before tax - this is a loss of £(2.4)m in 2020, dramatically improved from £(12.5)m in 2019
- Marketing budget halved, but still substantial at £6.1m - giving further cost flexibility if needed
- Exited from selling on Amazon (too costly), and simplified IT by moving to Shopify - management seem to be doing lots of common sense things to focus on achieving profitability
- Current trading strong in Jan & Feb 2021, up 16% on 2020, due to easing of supply constraints
- Growth rate expected to slow in May 2021, as tougher prior year comparatives kick in (good transparency by disclosing this)
- Balance sheet - quite good, with NTAV of £6.2m, and a cash pile of £8.4m - looks ample, so probably won’t need to raise more equity. Note extremely low inventories, which would need to normalise at some stage.
- Retained losses of £(43.9)m means it won’t be paying corporation tax, if it does achieve profitability
- Share based payments of £522k in 2020, and £1,111k in 2019 - why? Call me old fashioned, but I wouldn’t expect to see share giveaways to management at all, at a loss-making company
- Cashflow statement - self-explanatory. Note £12.0m equity raised in 2019, and it capitalised £291k into intangibles - insignificant.
My opinion - we’re in a bull market, so that can be a good time to do some trades on micro caps that might attract a stampeding herd of punters. Judging by the high volumes traded, it looks like EVE is already on their radar.
With a cash pile about half the market cap, meaningful sales at a decent gross margin, and flexible overheads, this share could do alright.
Webinar starts on IMC shortly, at 13:30.
Overall, after going through the numbers, I feel that holding this share is not as daft as you might think (that’s a new classification, I quite like it, so will use that again, for speculative shares!). I think this share is best seen as a speculative special situation. So not for widows or orphans.
Note the Altman Z-score is terrible at the moment, I presume because it thinks the cash burn is still horrendous, but as the results today show, it has been almost eliminated. Therefore this score should improve when the data is updated.
.
.
Empresaria (LON:EMR)
49p (down c.3% at 13:02) - mkt cap £24m
Very small and illiquid, so I’ll keep this brief.
Empresaria, the global specialist staffing group, reports its unaudited preliminary results for the year ended 31 December 2020.
It’s obviously been a hugely disrupted year, so I think these highlights look quite good in the circumstances, and adj EPS of 4.1p seems to be slightly above the 3.98p broker consensus, so a small earnings beat -

.
Signs of recovery, as we’re hearing from other staffing companies too.
· 2021 guidance reinstated
· Resumption of dividend with a final dividend of 1.0p per share proposed (2019: nil)
Outlook comments seem surprisingly hesitant - I was expecting something much better than this -
Early indications of trading in 2021 are positive and although, due to our strong start to last year, adjusted profits for the first half of 2021 are likely to be behind the first half of 2020 we expect for the full year to deliver adjusted profits in line with or better than 2020. We enter 2021 well positioned to exit the pandemic stronger than we entered it and to take advantage of recovery in our markets."
It’s a concern that EMR is not expecting to beat H1 2020, given that Q2 would have been battered by covid lockdown 1 last year. Maybe lockdown 3 is having an impact this year? Ah yes, here we are -
... The increased level of national lockdowns and restrictions in several of our markets at the start of 2021 means we remain cautious on the immediate outlook, but believe we are well placed to take advantage as and when markets recover.
Balance sheet - looks rather weak. Take off the goodwill/intangibles, and NTAV is negligible, at £(0.6)m.
My opinion - the 2020 PER is 12.0, which looks about right to me.
For that reason, the weak balance sheet, and given that it sounds like 2021 might be about the same profits as 2020, I don’t see any reason to chase up the share price any higher for now.
The StockRank is strong though, so maybe I’ve missed something?
.

.
Jack’s section
Gym Group (LON:GYM)
Share price: 246.8p (+2.8%)
Shares in issue: 165,977,131
Market cap: £409.6m
Gym (LON:GYM) operates 186 low-cost gyms across the UK.
Pre-Covid, this was a promising Leisure sector roll out tapping into huge demand for affordable gym facilities. It’s only other real rival in the budget space was Pure Gym.
Then Covid happened and Gym’s sites were required to close for 45% of the trading days in the year. So these full year operating numbers will be ugly.
Given the pretty unique events of the past year, I’m not sure the risk:reward has ever been that attractive here over the pandemic period. I’ve found that with a few Leisure stocks actually, and I’ve been on the look out.
That’s less of a comment on the quality of any one operator and more a nod to the immense, existential risks that these companies have faced down, the debts they’ve taken on, and the equity they have raised. And, in some cases, the equity that they might still need to raise. Prices never got quite as low as I thought they might for some operators.
But, on the other side of the equation, we probably have a lot of pent up demand for gyms, pubs and the rest - so perhaps a normalisation boom in trade could paper over the cracks and justify the recovery in share prices.
Full year results for the year to 31 December 2020
- Revenue -47.4% to £80.47m,
- Adjusted EBITDA less normalised rent -120.9% to -£10.17m,
- Adjusted profit before tax -433.1% to -£46.53m,
- Statutory PBT -858.8% to -£47.19m,
- Basic adjusted EPS -397.4% to -22.9p; basic statutory EPS -988.5% to -23.1p,
- Free cash flow -151.2% to -£16.54.
The fact that these adjusted losses come after significant government help is quite sobering and the readacross for smaller, less well funded businesses remains a concern.
But assuming The Gym Group makes it through to the other side, which is increasingly likely now at least for most affected listed entities, then the results of the past year are obviously exceptional.
Debt is manageable, dividends have been cut, and cash flows should return once people can come back to gyms. But I also wouldn’t rule out another placing, especially at these share prices.
Eight new gyms opened in the period, increasing the total estate to 183. The company will also be hoping it can recover membership levels from today’s 547,000 to the 794,000 average for FY19. So there is cause for optimism.
The group also gives some useful guidance on the outlook:
- Gyms in England are expected to re-open on 12 April 2021 with gyms in Scotland re-opening 26 April 2021,
- Lockdown have seen successively higher customer retention rates. As at 28 February 2021 Gym’s membership level was 547,000 (31 December 2020: 578,000, and 794,000 at the start of 2020)
- 97% of current members say they expect to return to the gym as soon as possible, with 75% stating that fitness will be more important to them than it was pre-COVID,
- Focus on cash management; as at 28 February 2021, Non-Property Net Debt was £58.2m versus total bank facilities of £100.0m,
- Three new sites opening in April and one in May, with an additional four starting on-site imminently,
- A growing pipeline with six leases exchanged and several more in advanced negotiations.
Conclusion
I like The Gym Group but the main sticking point is valuation.
A lot of recovery is baked into the share price. In fact, a lot of growth is baked in. Meanwhile, paying members have fallen from 794,000 at the start of 2020 to 547,000 today and the group has raised £39.9m from shareholders, diluting the share base.
Harking back to the FY19 results, which were generated from 796,000 members rather than today’s 547,000, and with around 138m shares in issue rather than today’s 166m, the group generated net profit of £3.6m. Using the new shares in issue number, that would make for about 2.2p of FY19 EPS.
So getting back to that point would value Gym at 109x FY19 basic earnings per share. Taking the significantly higher FY19 ‘normalised income’ figure of £9.02m gives diluted normalised EPS of 5.4x with the newer shares in issue number, which means a recovery to FY19 levels would value the group right now at 44x normalised earnings. It just seems too expensive.
That said, I imagine quite a lot of lapsed customers will return to gyms and bring membership numbers closer to the FY19 average of 796,000 in relatively short order once gyms open up from 12 April. And it's also worth noting that operating cash flows typically far exceed the group's earnings per share figures.
Maybe some investors are more certain of the group’s growth prospects going forwards but, given the above and the recovery in share price, I don’t see too much of an opportunity here for now.

I do think the group has some good trading ahead of itself over the next year or two and budget gyms remain an attractive proposition. Providing affordable fitness is even more relevant as society is encouraged to improve health and recover from a global economic shock. The longer term growth thesis is sound.
A combination of market share gains, a post-lockdown surge in applications, and more readily available quality sites selling for cheaper could lead to pretty striking results over the next year or two.
But it’s my view that more attractive risk:reward opportunities lie elsewhere in the market right now. In some quarters, the ‘reflation’ trade looks a little overdone.
Capital (LON:CAPD)
Share price: 67.7p (+10%)
Shares in issue: 188,780,903
Market cap: £127.8m
Capital (LON:CAPD) provides ‘full-service mining, drilling, maintenance and geochemical analysis solutions’ to miners with operations in Africa. It has a young and expanding fleet of bulldozers, dump trucks, and mining shovels, as well as a fleet of 99 rigs.
There’s a lot of talk about commodities at the moment and it probably shouldn’t come as a surprise that business is good right now for Capital.
Can this continue? If so it might not be too late to climb on board here, even after today’s 10% rise.
- Revenue +17.5% to $135m,
- EBITDA +24% to $33.8m,
- Net profit after tax +138.6% to $24.8m,
- Cash from operations +34.6% to £36m,
- Diluted earnings per share +130.9% to 17.6c,
- Total dividend per share +57.1% to 2.2c,
- NAV per share +68.3% to 106c,
- Year end net cash balance of $5m ($35.7m of cash and $30.7m of debt).
EPS growth has been driven not just by strong operating performance but also by ‘substantial realised and unrealised investment gains’ across a portfolio of junior and mid-tier exploration and mining companies.
The year end investment portfolio was valued at $27.2m (2019: $12.5 million), recording investment gains totalling $13.6m, comprising $13.2m unrealised and $0.4m realised.
Capital's portfolio of long-term mine-site based operations increased to ten sites, comprising 18 individual contracts with the addition of the new contracts with Barrick in Tanzania and Firefinch in Mali. Partners include some familiar names like Barrick, Centamin, and Hummingbird.
There’s a lot of detail and contract activity here so I won’t go into the weeds too much. Suffice to say business is booming right now. Capital was awarded multiple new exploration contracts over the year, mostly in the West African region.
One specific contract worth flagging is the December 2020 award of a ‘transformational’ 120Mt waste stripping contract including load and haul and ancillary services, and an expansion and extension of the existing drilling contract at Centamin's Sukari Gold Mine, Egypt.
Together, these are expected to deliver US$235 - $260m of incremental revenue over a four-year term. It is Capital’s largest award of new business since inception, marking a ‘step-change in the scale of the business,’ and is expected to be earnings accretive by the end of the year.
Capital also completed an oversubscribed equity fundraising back in December that ‘introduced a new roster of quality institutional investors’. Gross proceeds of approximately £30m are being used to support the Sukari contracts together with key debt financing facilities.
Capital has also successfully agreed a further debt facility for up to US$17.0m of which US$6.5m is committed and available subject to finalisation of security.
Clearly, the group is scaling up. This is promising, but mining is also cyclical and so this brings risks should the industry suffer a downturn. Debt levels are probably worth keeping a close eye on.

For now the momentum looks good. Post year-end contract awards include:
- Three-year contract for surface delineation and open pit grade control for AngloGold Ashanti, Tanzania (previously announced);
- Three-year contract for underground delineation and grade control drilling for AngloGold Ashanti, Tanzania (previously announced);
- Initial six-month delineation drilling contract for Allied Gold Corp, Mali;
- Exploration drilling contract for new client Cora Gold, Mali;
- Exploration drilling contract with Perseus Mining in Côte d'Ivoire;
- Initial six-month delineation drilling contract with Aya Gold and Silver Inc in Mauritania; and
- Six-month exploration drilling contract for Endeavour Mining Corporation, Burkina Faso.
Conclusion
These are strong results and Capital looks well placed for a continued pick up in Africa-based mining activity. I don’t think we’ve missed the boat here.
Some big institutions have been buying in and, given the results and outlook, the share price looks cheap. Diluted EPS of 17.6c puts the group on about 5.4x FY20 earnings.
Capital guides to revenue of between $185m-$195m for FY21 and demand for drilling services ‘has increased strongly from Q4 2020, building further in Q1 2021’. MSLABS is working at near full capacity across all major laboratories.
MSLABS also sounds interesting - this is a global provider of geochemical lab services serving the exploration and mining industries. There could be growth potential here.
Given the buoyant outlook the shares do look cheap at the moment and I think it’s well worth spending a bit more time getting to know this company.
True, at some point there could be a downturn in mining activity, but there seems to be a disconnect between the positive outlook and today’s share price even accounting for the 10% rise.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

52 comments
Link to this tweeted by Capital (LON:CAPD) overnight. Essentially seeking to highlight that West Africa is a sweetspot for them... ...and presumably that their SP is completely wrong :-)
https://www.capdrill.com/news/white-paper-exploration-boom-in-west-africa-opportunity-or-challenge
Hi Jack
Thank you for your write-up on Capital (LON:CAPD) . Here's a link to the latest Tamesis Partners article. Its free to access but registration required.
Https://www.tamesispartners.com/research-portal#/portal/tamesis-partners/research/02461d34-5f21-4f56-aa54-d51403022041
Their note starts
FY Results – Strong on Every Level
Target price: 127p
P.S. Its probably pretty obvious, but I am currently long CAPD.
https://www.miningmx.com/top-story/45622-soaring-rhodium-price-will-contribute-half-of-total-sa-pgm-company-revenues-in-2021/
All the PGM producers are now totally Rh dependant - price falls occasionally on "buyers strikes" but comes back because it is very hard to substitute and in supply deficit. To me it doesn't matter whether you're in Jubilee Metals (LON:JLP) , Sylvania Platinum (LON:SLP) or Tharisa (LON:THS) (or others) just keep an eye on the Rhodium price and the demand /supply balance - nothing else matters.
Actually I think Sylvania Platinum (LON:SLP) produce approx twice as much Palladium (24%) as Rhodium (12%). Rhodium’s huge price rise the last couple of years distorts, as it produces so much of the profit. That said, the broker estimates had Palladium down for this year at $2k - $2.4K and Rhodium at $15k - $20k. With Pd at $2.7k and Rh at $27k....it’s possible estimates may need to be raised!
(Broker estimates dated Jan 2021, from Sylvania Platinum (LON:SLP) interim results).
For you followers of PGM shares Tharisa (LON:THS) and Sylvania Platinum (LON:SLP) - I notice that Palladium is up 4% today to over $2700, following the previous rises in the last few days from $2350 since announce re the impact of the flooding problems in the Nornickel Russian mine.
Palladium up 8% now but that is a small part of Sylvania Platinum (LON:SLP) production?
Rhodium price is far more important and that has fallen back slightly.
Rhodium is also up 8% today.
At this level rhodium is expected to account for half of all PGM revenue in South Africa.
It's still 23.7% of their prill production, Rh more important yes but not a 'small part' imo
Ok, do you have a breakdown of revenues and prices. Rhodium is now around 10x the price of Palladium.
https://www.sylvaniaplatinum.com/component/jdownloads/send/84-2021/529-hy1-fy2021-presentation
Thanks but I can’t open that link.
Strong move by Quiz (LON:QUIZ) today. Close to a 52 week high although nothing much on a historical basis. I read today that a ton of cash is waiting to buy anything and everything as soon as the High Street opens. Not long now! Credit card debt is DOWN 19.3 per cent in a year (courtesy the Money Charity statistics). Never known that before! Buy now pay later seems to be everywhere too.
People have been buying online. Some shops are open because they sell "essentials" such as toilet paper.
Will be interesting to see where the money goes.
Another request for a review of Capital (LON:CAPD) - Looks like a cracking set of results and further strong growth forecast. And Paul, as you like presentations, they’ve announced one for 25th March.
At the moment I just can’t touch those heavily dependent on things returning to normal. For one. I use the gym and much less people returned after the first outbreak. This stop start breaks the program and mentally people cannot cope. It means going through hell all over again.
Two. To many time wasters. I’ve heard it said and I’m seeing it in my gym. People are just standing around looking at their phones.
Then today.
FT March 2021
B.1.1.7 is believed to be the most transmissible lineage in the UK, causing about 97 per cent of disease, and has been found to be between 30 and 100 per cent more lethal than previous strains.
Professor Sharon Peacock of Cambridge university, director of the national infection service at Public Health England, has said it is “on course to sweep the world”. The variant had become dominant in every country it had reached and accounted for about 40 per cent of cases in the US and France.
Mr Contrarian doesnt miss much but he does appear to have missed the Vectura (LON:VEC) prelims today (slides available on their website). They are a CDMO in the inhaler market. They have been going through the initial phase of a major transformational programme, and look to be in a very good position now in a steadily growing market. I listened to the webinar this morning with the CEO and FD, follwoed by a lengthy Q&A from Peel Hunt, JP Morgan, Numis etc, and they were quietly impressive. Their transformation programme covers improvement on all fronts; rationalization of bases, closing two in Germany and Switzerland and concentration in UK; they are developing the D(evelopment) - the added value - side of the business and had two useful milestone royalties from Hikmar and ANO's and these royalties will continue for some years; they have the capital to go for complementary M&A but no plans currently. They have modestly (in terms of numbers)expanded their Business Development team, including on the E and W coast of the USA, and see significant organic growth and general competitive improvement as the focus for 2021. They have also won an important patent case and this will generate excess capital which they intend to return as a special dividend to shareholders of a useful 19p a share during 2021. NB SP today 120p. I would be interested in anyone comments - from either of the two supremos, Paul or Jack, or anyone of the rank and file of us. I have added to my holding this morning. Although it wasn't mentioned I would have thought that the market may well see a significant post Covid effect given the impact of Covid - and long Covid - on the lungs of so many sufferers (the ones who survived of course).
Here are my SCVR heat maps for today (prices as at ~10:40am).
I share these heatmaps with the intention of giving a visual indication of what is going on in the SCVR world: who’s reporting (and it's impact on the share price); and what’s moving more than 'normal'. There are no associated recommendations, implied or otherwise, just information. How, or indeed if, you choose to use that information is up to you.
Please read my [heat map thread] for keys to the heat maps contents, more (non-SCVR specific) heat maps, and an explanation of how I use heatmaps to guide me with my research.
Small / Micro Caps reporting today:
Big movers today in the SCVR world (moving more than a 20d EMA of the ATR against either yesterdays close, or today's open):
Warm regards, stay safe, and best of luck!
greensiax
Gym (LON:GYM) worth considering that when gyms reopen there isn't any new cashflow from returning customers as memberships have been frozen since lockdown. Effectively costs go up with no new revenue unless new members sign up. I don't expect to be paying my local gym for a few months post reopening. Also worth considering that home workouts have grown with new apps out there like FIIT (which I like using). The only reason I would go to the gym now would be for heavy weights.
Fevertree Drinks (LON:FEVR) - Not a small cap any longer but I think there are still interested parties here that have been in since it was.
Results today....I thought better than the market has taken them (SP down 8%). Considering all the on trade has effectively been closed for a year sales have held up pretty well. Big drop in the UK but up in the US where potential must still be huge. Europe also pretty good.
Assuming we really do start getting back to "normal" then back to previous sales trajectory beckons.
Short notice, I know, but live audio webcast presentation of results begins at 10.00am: -
https://www.investis-live.com/fever-tree/6040faa949aa2a0e00f3a9fa/gwvv
I'm a buyer US manufacturing commenced, mixers for Vodka and Tequila launched its party time soon
Thanks for the review of Gym (LON:GYM) Paul very interesting (I hold).
The current valuation is potentially a concern. I bought last year in the view that gym usage will receive a boost from 'pent up demand' and Gym (LON:GYM) is better placed than other operators to benefit from this and indeed expand and take out smaller local players that may experience business failure. As you say though, this may already be factored in more than I realised.
The other aspect i'm interested in is the increasing interest in the use of government funds for 'nudge theory' public health campaigns. A canny operator would probably quite easily be able to encourage the government to subsidise public gym memberships in the fight back from Covid.
I work in Pharma and I see some of these types of initiatives taking shape particularly in pharmacies, although poorly funded currently, that may change.
Jack actually.
Apologies, Jack!
SSP (LON:SSPG) yesterday announced a rights issue and 14,000 job cuts. They don’t see train and bus stations trade getting back to normal until 2024.
re Ssp (LON:SSPG) I believe that the job cuts happened a while ago and were already in the pre rights price. Yes, interesting views about travel recovery from someone very much at the coal face on these things
Capital (LON:CAPD) might be worth a look for Jack. Results issued at 08:41 today and very strong. Tamesis Partners have previously suggested the SP should be approximately twice current levels.
Edit: TP have left target price at £1.27 vs current price of 65.25p. Looks to be plenty of opportunity for upgrades
I'd also be interested in views on Capital (LON:CAPD) (I hold). Seems a strong set of results, with expectation of growth in to '21.
Yes please if possible! This seems like a v cheap share with lots of tailwinds (whether we are on the brink of a commodities supercycle or not) - but wonder whether there is something about this business that is not immediately obvious - as with the rest of the market going up for no reason this share price seems to stubbornly sit in a range!
(I hold). What I've suspected has been holding this share back is the Centamin contract. It is such a large part of future revenues that it really is make or break.
£CAPD @JCPr - I beg to differ on this point IMO, What has been holding back the SP is the ex shareholder CB selling out his shares. How many left? Not known. There is another fund (check out recent RNS, who is also selling out). Obviously the act of selling out in this case has nothing to do with the underlying business performance. CB has been selling since Oct 20.
So the situation is similar to Tharisa (LON:THS) - with if I am not mistaken Fidelity selling out their position and in £ORPH - Invesco selling. Let's hope in all 3 cases (I hold all 3), the dam will bust soon!
Gym Group / Boohoo . I hold Boo.
As Paul is discussing the re opening of gyms, etc, with another excellent analysis of Gym Groups results today. I thought I would mention the surge is Boohoo’s range of sports wear. Normally me and my friends would buy online from a famous online sports wear retailer, however recently Boohoo have upgraded their catalogue of sports wear, almost identical in quality for a fraction of the costs. There has become a huge demand now for Boohoo sportswear, amongst a lot of folks I know who take fitness seriously
Interesting to hear, I actually bought a pair of really good running shorts off them for £12. I've always been a fan of cheap excercise gear and they are certainly the best I've bought in that price range. The boohooman brand is also becoming more prominent and I frequently see the 'man' logo on TV.
I'm a holder of Boohoo (LON:BOO) and think it will grow massively when pubs, bars, restaurants and celebrations restart. One thing that concerns me however is the global acceleration of sales growth at Shein. The trajectory it is on is something I hoped boohoo would be able to target. I believe it is cheaper than boohoo's brands helped by the fact it's China direct and postage is subsidised by the UK tax payer. They seem to be gobbling up the online fast fashion market (if Google trends are anything to go by). I do think that boohoo's 'moat' in the UK at least is its ability to deliver next day or much more quickly than Shein - if you're going out and you want something quick it will be hard to beat- overseas I'm not so sure.
I've got confidence in the management to keep creating value however and given their heavy ownership I'm sure they'll overcome this. They also have a massive tailwind in that fast fashion on the high street is now very limited (globally) and becoming more limited every week. I like to remind myself that they don't need to own the entire the pure play online fast fashion market to sustain growth of 25%+ for the next few years. 3-5 years of that growth is still very small fry in the grand scheme of things.
The fwd PE is likely somewhere in the mid to late twenties for this year -when you takeaway the c.£300m of cash on the balance sheet- you're looking at a very attractive valuation (with Debenhams thrown in for free) matched by very few of my other holdings on an opportunity cost basis.
I've noticed Boohoo (LON:BOO) (I hold) are making a bit of a push in signing up some reasonably big sports names to sponsorship deals - Jon Jones recently signed up to a one year deal and will have a pretty big following both in the UK & US. A great move imo
Also agree there is great opportunity for growth once lockdown eases with people wanting to cheaply refresh their wardrobes ahead of holidays, nights out, festivals etc
(Shein) helped (inits fight with BooHoo et al) by the fact it's China direct and postage is subsidised by the UK tax payer.
This must be a bit of a LT risk for Shein - its removal is an obvious politically savvy green 'Brexit bonus' tidy up. It was created when China was much poorer and much less was online.
(A theme I keep raising is the risk of innovative green stealth taxes - dressed up as to save the environment but in reality to fill tax coffers with breaking election pledges. I support them BTW!)
Paul, I hope you find time to look at £PMP I really believe the underlying commercial operation is improving under the relatively new MD.
I particularly liked : "Own platform website sales increased by 69% to £11.1 million (2019: £6.6 million) and total online sales in core UK and US markets rose to 47% (2019: 30%)". In house online is also 10% better margin at op profit level acc to MD in IMC.
IMHO this is not just a COVID driven shift. It reflects it is (finally!) beginning to realise its online potential under some new digital savvy Marketing hires, investment in better in house warehousing/dispatch and smarter product devel. Simple things like better promo emails with clearer fonts and better photos - but these make a difference . They are still not first class but they do seem to be moving forward quite quickly now. (I am an ex FMCG Mkt Dir and used to send critical emails to the Head of Marketing but am now going to stop!)
Several other good plans also rumbling away underneath. The US/Canada operation has been scaled up and improved (Nambe, buying out 50% JV share of Canadian partner at a good price); Wax Lyrical was ready to relaunch in 2020 but pulled it; S Korea has been fixed (or at least wont get worse) by new products & distributors, clamping down on grey imports; focus on 3 core (US, UK, SKorea) and 3 new markets; various factory automation projects coming through. Indeed the 2 part "strategic plan" is reassuringly clear and doable - increase sales and improve margins.
Financially, last year it raised £10Mn fresh equity it did not in the end need. So some dilution but it now has the cash to do the excellent internal plans and bolt on some (too small for PE) acquisitions where these have run into trouble in P12M and then drive these through its larger network. Dividends will resume this year and I expect will be securely >5% by 2022.
I know you were a fan but went away. Is it time you came back? As you can tell I am a fan and hold (for me) a big chunk and I am going to fill my ISA with more before the year is out!
As y
Is there life after death? Perennial disappointer Mobile Streams (LON:MOS) seems to be showing signs of life under new management with a revised suite of products that seem to be gaining a bit of traction. A decent sized order announced this morning and the share price is ticking up albeit from a very low base. I hold (don’t all laugh at once!).
Gus.
Actually I bought Mobile Streams (LON:MOS) the other week. The new data streams business is coming from a zero base but over the last few months has gone from £9k p/m to £25k p/m with an apparent strong pipeline. So it seems that this is a £3m mark cap business with a product that is genuinely sellable and growing fast in a relatively hot area (data). I have no idea what it could be worth but strikes me that (when I bought it) at £2m mkt cap the risk/reward was heavily on my side. Going to be illiquid and I didn't buy a lot but it's a bit of a moon shot. If the pace of this growth continues for a while then it could look very cheap.
Probably worth pointing out it is not the same management that screwed up the old business badly so probably best not to examine the history since the product is also new. Interesting.
To be fair to the old Mobile Streams (LON:MOS) management they had a fairly bad run of luck. First their primary market, Argentina, went feral with economic and political melt down, exchange controls etc., cutting the main plank of their business off at the knees. Then they tried expanding into India just as the Telecom sector began to tear itself to pieces in an aggressive price war. Somehow the company avoided going bust and the new team do seem to be creating something that may yet have some substance. I doubled my original holding this morning - for the cost of a couple of trips to the supermarket, LOL. Probably one to stick in the Coffee Can under the bed for 10 years and forget about. Classic Sucker Stock I suspect.
Gus.
Gus, Given that the Mobile Streams (LON:MOS) business is now using AI to create compelling online content, perhaps you (and I) have been successfully targeted by the AI - which could make it a sucker stock of an altogether more modern kind.
Ah - I wondered what that buzzing in my ears was. Must have been the Mobile Streams (LON:MOS) AI rather than the tinnitus!
Yes but I'm unsympathetic towards the old management. One of the biggest downfalls in my view was their inability to hedge FX exposure to the Peso and that was what really set the spiral downwards. Successful business is also about being able to pivot when events change and I felt they were too late and in the wrong markets. Maybe Im being uncharitable but I also had some interaction with directors and felt they were somewhat arrogant.
Still, that said, the new management and new product means the company should be looked at with fresh eyes and not its history. Yes the legacy product may still have value but seems unlikely it will be ever be anything spectacular. The data product though is another matter and this is where my interest lies. Ordinarily this wouldn't be listed so it's more of a VC/PE play. Revenues are early stage but growing rapidly which is why it's interesting for me. I'm never going to put lots of cash up at this stage but I've got enough to make a handsome return if it does continue to grow.
Big Four Break up of big four accountancy firms.
On the subject of online presentation, today my thumbs up for decent treatment of PIs goes to Amino Technologies (LON:AMO) who are having their AGM with presentation and Q&A on IMC at noon.
At the prelims some people here questioned what they meant by being "software led" (they have moved from producing set-top boxes to concentrating on the software for IPTV and only still make the first if it includes the second) so here is your chance to find out more.
My morning smallcap tweet:
Plant Health Care (LON:PHC) Telit Communications (LON:TCM) XLMedia (LON:XLM) Directa Plus (LON:DCTA) Crimson Tide (LON:TIDE) Tekcapital (LON:TEK) Lookers (LON:LOOK) Mobile Streams (LON:MOS) John Lewis of Hungerford (LON:JLH) eve Sleep (LON:EVE) Portmeirion (LON:PMP) Audioboom (LON:BOOM) Sureserve (LON:SUR)
Plant Health Care (PHC) $10m placing at 14p, a 12% discount. Cash is for development, recruitment and working cap. [SP=16.38 Cap=41m]
Telit Communications (TCM) DBAY changes its mind TCM agreed to let it do limited confirmatory due diligence in order to submit an indicative offer. DBAY has 26% of co. [SP=207.5 Cap=279m]
XLMedia (XLM) to buy Sports Betting Dime fo $26m. £20m placing and £3m OO at 40p, a 25% discount. "he Acquisition cements XLM's market position in the rapidly growing regulated US sports betting market and, together with XLMedia's existing US sports betting asset (XLM), provides scale at local and national level." [SP=54 Cap=105m]
Directa Plus (DCTA) guides FY(Dec) rev €6.7m up €0.2m from prev guidance. Q1 rev €1.8m, up 20%. Plus operational updates. [SP=107 Cap=66m]
Crimson Tide (TIDE) 3 year contract worth over £1.2m from Compass Group which will use mpro5 to ensure compliance across a broad range of customer and legislative requirements. [SP=3.1 Cap=14m]
Tekcapital (TEK) £3.8m placing at 10p, 31% discount, which was too large a number to fit in the RNS. Cash for to increase investment in its portfolio companies. There must be a hell of a return on investment to effectively pay a 45% premium (1/0.69) over TEK's SP for it. [SP=14.11 Cap=13m]
Lookers (LOOK) now guides FY(Dec) U/L pretax c. £10m cf a small loss forecast as auditors work though the numbers pile-up. [SP=49.25 Cap=192m]
Mobile Streams (MOS) £480k (max) order from Quanta Media Group over 4 years with min £10k pcm for a year. "In addition to enterprise level access to the Streams data platform, the partnership has also identified opportunities to generate significant potential additional revenue from the MOS legacy business." [SP=0.22 Cap=3m]
John Lewis Of Hungerford (JLH) FY(June) out. Yes, June. This H1 rev flat, ahead of mgmt expectations. Business plan: "central scenario reflects the strength of current trading and projects a profitable second half of the year. Under this scenario we also expect to enter the new financial year to June 2022 with an order book which will be higher than in recent years." [SP=0.85 Cap=2m]
eve Sleep (EVE) FY(Dec) rev 6%, loss £2m (£12.1m), ahead of expectations. Current trading: rev up 16%. [SP=6.28 Cap=17m]
Portmeirion (PMP) FY(Dec) rev down 5%, pretax £1.4m (£7.4m), ahead of mkt exp. No div. Outlook: "Positive trading momentum from H2 2020 continue in Q1". [SP=558 Cap=78m]
Audioboom Group (BOOM) FY(Dec) rev in lineand adj EBITDA loss slightly better than recent guidance. Current ad bookings over 80% of the FY market expectations. [SP=440 Cap=69m]
Sureserve (SUR) exec chmh scarpers ahead of today's AGM. New CEO and chmn sought. He is thanked despite this poor form. [SP=72.01 Cap=115m]
Have not looked at Tekcapital (LON:TEK) before but after Mr. C's report on highly dilutive and 31% discount placing with no open offer I had a look and discovered that at the last AGM the resolution to authorise the Directors to disapply pre-emption rights was passed by 98.94%. The resolution was not for the amount most companies use but for "up to an aggregate nominal amount equal to £175,556.08, representing approximately 50 per cent of the Company’s current issued ordinary share capital".
https://www.tekcapital.com/wp-...
Shocking.
Portmeirion (LON:PMP) Final results. Strong recovery in H2, ahead of market expectations.
Revenue was £87.9 million, a decrease of 5.3% (2019: £92.8 million).
Like-for-like sales were £82.4 million (2019: £92.8 million), a decline of 11.2%.
Own platform website sales increased by 69% to £11.1 million (2019: £6.6 million) and total online sales in core UK and US markets rose to 47% (2019: 30%).
H2 returned to headline profit before tax of £4.1 million (2019: £6.9 million), FY20 headline profit before tax of £1.4 million (2019: £7.4 million).
Headline basic earnings per share was 4.96p per share (2019: 56.32p).
Empresaria (LON:EMR) FY20 results today. Here's an overview by Rhona Driggs, CEO & Tim Anderson, CFO. Video & podcast.
A strong start to 2020 with year-on-year operating profit growth in every month of the first quarter. They benefitted from diversification by sector and geography demonstrated throughout the year. Their group's balance sheet proved resilience, with adjusted net debt reduced to £13.6m (2019: £19.1m). Due to CV19 the net fee income was down 28% to £54.0m and adjusted operating profit down 40% to £6.2m, although they were profitable in every quarter of 2020. Guidance for 2021 has been reinstated. They resume the dividend with a final dividend of 1.0p per share proposed (2019: nil).
Also, see posted later yesterday:
Sthree (LON:STEM) Another international staffing company. Q1 Trading Update given on Monday 15.3.21. Mark Dorman, CEO & Alex Smith, CFO update analysts on the performance. The group delivered a strong performance ahead of management expectations. USA has bounced back robustly with net fees up 19% driven by Life Sciences. They also give an update on market trends they observe, companies are focussed on rebuilding global supply chains, much attention to ESG and sustainability, and obviously tech and automation are strong especially advanced robotics and digital commerce. Hear the full analyst presentation here: Video & Podcast.
Kape Technologies (LON:KAPE) FY20 results presentation, Ido Erlichman, CEO & Moran Laufer, CFO run through the the main events of the last year. The Group experienced strong revenue growth, with EBITDA ahead of expectations and improved profitability underpinned by organic growth initiatives. Trading in the first quarter of 2021 has remained strong with solid traction for Kape's solutions. It is anticipated that the enlarged group will generate revenues of between $197-202 million and Adjusted EBITDA of between $73-76 million for the full year 2021 on a reported basis. The Board remains confident in the Group's growth prospects in 2021 and beyond. Video & Podcast.
Hi Tamzin,
Will you be posting the Somero Enterprises Inc (LON:SOM) meeting soon?
Great service you provide to us PI's. Thanks very much.
Re Kape Technologies (LON:KAPE) this may sound a bit like sour grapes because I sold out at around 200p just before the most recent acquisition. However, I am very influenced by and a great admirer of Leon Boros. At the Mello Bash on 25.1.21, he was extraordinarily negative about the company; its ownership; the huge figures for revenue growth, high levels of EBITDA quoted and not matched by cash flow or return on capital. Looking further into the balance sheet, there are some very unusual figures such as deferred marketing costs. I may have lost a very significant opportunity here, but I feel very comfortable about being no longer invested in this stock. All IMHO of course.
Science In Sport.... where the directorship pays themselves a fortune at the shareholders expense for years of failure. Disgusting.
should add... if they are paying themselves that obscene amount of cash now, what are they going to be like if it does do well?
Science In Sport (LON:SIS) are not "planning" to breakeven for another couple of years either.