Small Cap Value Report (Wed 19 July 2023) - WJG, RTN, FIF, CHRT, SPR, PGH

Good morning from Paul & Graham!
Today's report is now finished.
News today from the ONS that UK inflation has dropped a little more than expected, but is still way too high of course. Here are the main points (with thanks to the ONS) -
- The Consumer Prices Index including owner occupiers' housing costs (CPIH) rose by 7.3% in the 12 months to June 2023, down from 7.9% in May.
- On a monthly basis, CPIH rose by 0.2% in June 2023, compared with a rise of 0.7% in June 2022.
- The Consumer Prices Index (CPI) rose by 7.9% in the 12 months to June 2023, down from 8.7% in May.
- On a monthly basis, CPI rose by 0.1% in June 2023, compared with a rise of 0.8% in June 2022.
- Falling prices for motor fuel led to the largest downward contribution to the monthly change in CPIH and CPI annual rates, while food prices rose in June 2023 but by less than in June 2022, also leading to an easing in the rates.
- There were no large offsetting upward contributions to the change in the rate.
- Core CPIH (excluding energy, food, alcohol and tobacco) rose by 6.4% in the 12 months to June 2023, down from 6.5% in May, which was the highest rate for over 30 years; the CPIH goods annual rate slowed from 9.7% to 8.5%, while the CPIH services annual rate was 6.3%, unchanged from May.
- Core CPI (excluding energy, food, alcohol and tobacco) rose by 6.9% in the 12 months to June 2023, down from 7.1% in May, which was the highest rate since March 1992; the CPI goods annual rate slowed from 9.7% to 8.5%, while the CPI services annual rate eased from 7.4% to 7.2%.
This was the brilliant presentation/Q&A by veteran, renowned fund manager Christopher Mills at Mello Monday that I was on about - it starts at 2:36:35
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £1bn. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk.
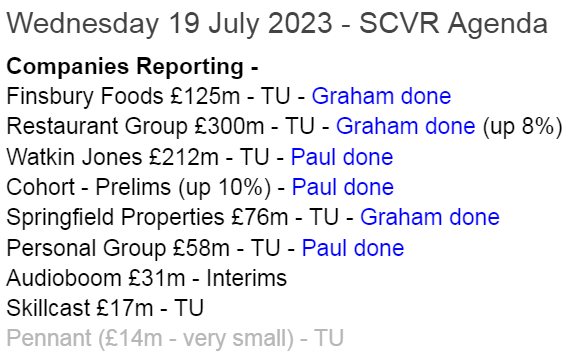
Summaries of main sections below
Watkin Jones (LON:WJG) - down 36% to 49p (£127m) - Trading update (profit warning) - Paul - RED
A very disappointing update, saying conditions have worsened again for this build to let, and student accommodation company. Profit warnings for both FY 9/2023 and FY 9/2024. Possible contract slippage. Another hefty increase of £30-35m in cladding remediation. Looks a mess short-term, but I still hope for medium-term recovery. Let's wait until the dust has settled, so RED for now unfortunately.
Restaurant (LON:RTN) - up 9% to 42p (£325m) - Trading update - Graham - RED
The market likes this update: they are “confident” on expectations for the current year. Post-Covid trends are boosting dine-ins and airport bars. I remain negative due to risks around possible disposals. Without disposals, I think they could use some additional equity.
Finsbury Food (LON:FIF) - up 1% to 96.6p (£126m) - Trading update - Graham - AMBER
Sales are in line with expectations at this bakery manufacturer. Management has succeeded in passing on very high cost inflation to customers so the company can keep performing well for shareholders. I’m tempted to go green but in the current market the price may be right.
Cohort (LON:CHRT) - Up 10% to 490p (£203m) - FY 4/2023 Results (unaudited) - Paul - GREEN
Good results, a bulging & growing order book, sound balance sheet, and a reasonable valuation - these are exactly the things I look for, so this defence group gets a thumbs up.
Springfield Properties (LON:SPR) - up 1% to 65p (£77m) - Trading update - Graham - GREEN
This Scottish housebuilder maintains a defensive posture and a cautious short-term outlook, as buyers remain subdued by the cost-of-living crisis and higher rates. This is a riskier housebuilder than most but the risks may be fully priced in here. An adventurous choice.
Personal group (LON:PGH) - Up 4% to 192p (£60m) - H1 Trading Update - Paul - AMBER/GREEN
An unusual company, which I don't fully understand! In line with expectations update today. Change of CEO. If it can return to pre-covid performance, then this share could re-rate, and continue paying out all its earnings as divis, as it has historically done.
Paul’s Section:
Watkin Jones (LON:WJG)
77p (pre-market) £198m - Trading Update (profit warning) - Paul - RED
Oh dear, this looks grim. We’ve had a couple of previous profit warnings from this build-to-rent and student accommodation specialist. However, it now looks as if the company’s previous reassurances that demand was returning to the sector was much too optimistic, and premature.
The CEO stands down today, to be replaced on an interim basis by the Chief Investment Officer, a long-standing internal candidate, whilst they seek a permanent replacement.
What’s gone wrong now?
They’re now saying it’s a “very challenging backdrop” for the sector, hit by macro & interest rates, with no talk about the recovery they previously indicated was supposedly happening.
5 projects were scheduled for completion by 30 Sept 2023 year end. One has completed, but a “greater degree of risk” on the others - so safe to assume some slippage (hopefully no cancellations?) here.
Exploring sale of a “limited number of non-core assets”
Impairment of assets c.£10m.
H2 could be another breakeven result (similar to H1) if projects don’t complete by year end.
FY 9/2024 also likely to be hit due to challenging conditions, with PBIT (operating profit) guided at £15-20m.
Provision for cladding remedial works has gone up again, by another £30-35m, which hits the balance sheet, but the cash cost to be spread over 5 years.
Cash positive, at £68m gross, and £36m net, at 30 June 2023. Although taking into account all the above, the balance sheet support to the share price seems to be melting away somewhat.
Paul’s opinion - this is a disaster, so I’m expecting a 30-50% share price fall today (writing this before 8am). No wonder the CEO has stepped down, as clearly his previous reassurances were wrong, and the risks were far greater than we were told.
Hence I can’t possibly keep a GREEN stance on this (which was always for a medium term recovery, as mentioned in SCVRs of 23 May, and 13 April, rather than any hopes for a short term re-rating). When the facts, figures & forecasts change, we change our minds. So I’ve got no other option than to go RED on Watkin Jones until the dust has settled.
Very disappointing, but a good reminder that when management keep reassuring us, despite being in a tough cyclical sector, they might not be giving a realistic version of the outlook. I need to be more sceptical about reassuring updates from cyclical companies. This makes me wonder about the brick companies - can they continue to perform well? Maybe not.
I think this one is a warning for us to keep away from obviously cyclical sectors like commercial property building, and anything that’s likely to be hit by interest rate rises. It’s too early to be bottom-fishing it seems.
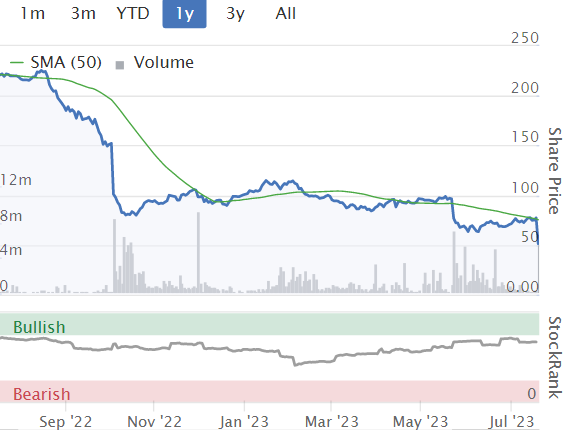
Cohort (LON:CHRT)
Up 10% to 490p (£203m) - FY 4/2023 Results (unaudited) - Paul - GREEN
Cohort plc (www.cohortplc.com) is the parent company of six innovative, agile and responsive businesses based in the UK, Germany and Portugal, providing a wide range of services and products for domestic and export customers in defence and related markets.
Cohort plc today announces its unaudited results for the year ended 30 April 2023.
Record operating profit, revenue and order book. Further progress expected.
Checking our previous comments on my quick reference summary spreadsheet, these were our previous views on Cohort, for background -
14 Dec 2022: 430p. GREEN. Good H1. Mgt upbeat about demand.
25 May 2023: 503p. AMBER. Slightly ahead exps for FY 4/2023. Large order book, so good visibility. Quite interesting at 14x PER.
On reflection, maybe I was too stingy only concluding with an AMBER view on 25 May, it should have been AMBER/GREEN I think! (I must have been having a bad day!)
FY 4/2023 Results -
Look very good, some key numbers being -
Revenue up 33% to £183m
Adj operating profit up 23% to £19.1m - a healthy 10.4% margin (of revenue)
Statutory operating profit of £15.3m is 20% lower, so are the adjustments reasonable? Yes I think so, the main one being amortisation of intangibles. It’s not capitalising anything new into intangibles (per the cashflow statement), and the £3.67m P&L amortisation charge ties in perfectly with the reduction in intangible assets on the balance sheet, so all good I think - it’s fine to adjust this out, in order to show underlying profitability.
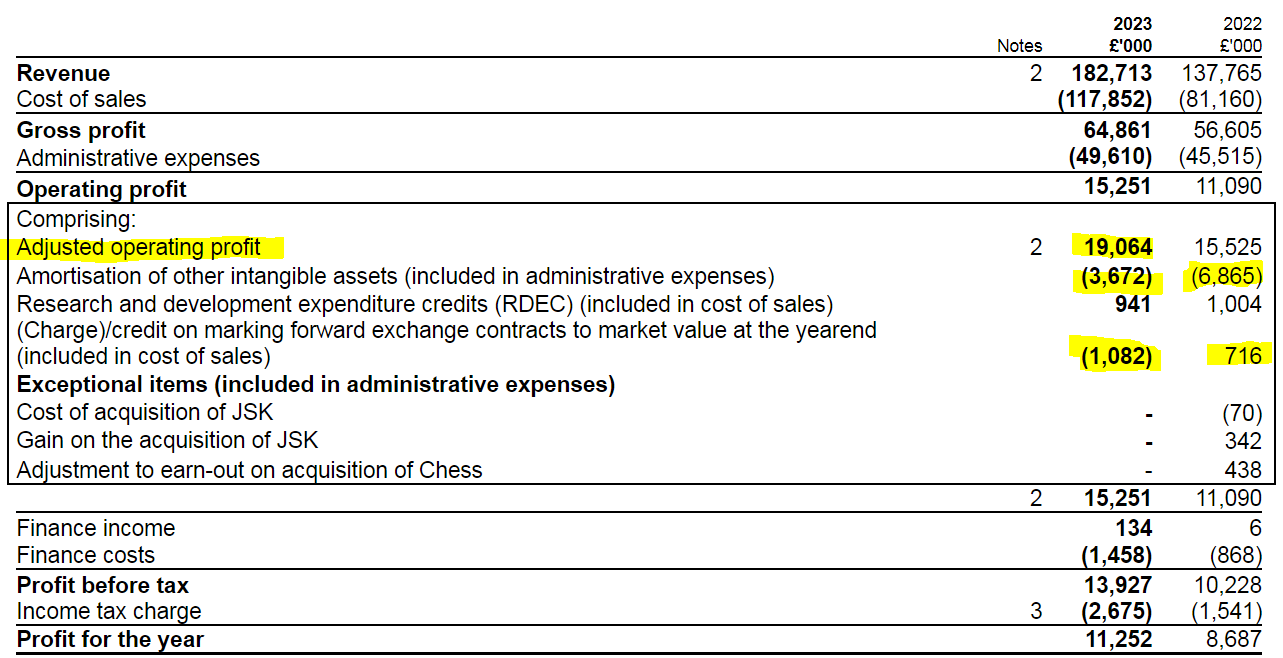
The forex adjustments above are also OK I think, as it evens out over the two years.
The problem with operating profit these days, post IFRS 16, is that it misses some lease costs, which are too far down, in the finance costs line. Hence why I prefer adj PBT as the best profit measure to use, but it isn’t provided.
So overall, for valuation purposes I think adj EPS is the most appropriate number, which is 36.5p, up 17%. Giving a PER of 13.4x - that looks very reasonable to me, for a nice quality, growing business. Assuming of course that profits continue growing - which you can’t just assume will be the case, with a business like this that tends to have large, lumpy contracts with customers.
Order book - this reassures me that most, and it’s up 13% to a whopping £329m, or 1.8x FY 4/2023 revenues. A big, and growing order book is one of the key things I look for in businesses like this, as it makes the risk of a profit warning much lower.
Dividends - a table is provided showing impressive long-term growth in divis. Total divis are up 10% to 13.4p, yielding 2.7%, not terribly exciting, but that is covered 2.7x by earnings, so the dividend paying capacity is much higher. The strong balance sheet also means Cohort is not in any way struggling to pay these divis, it’s easily affordable.
Balance sheet - net assets are £100m. I’ll take off the £56m intangible assets, arriving at £44m NTAV, which looks fine to me. That includes a £5.3m pension deficit, which would need checking out to see that it’s not an iceberg deficit. I can’t see any other info about the pension scheme in today’s numbers, that will probably be in the later Annual Report once it’s audited.
One query, to ask management if you get the chance, why does its balance sheet show cash of £41.5m, and bank borrowings of £25.8m? Surely it would make more sense to pay off the bank borrowings with the cash, to save on interest costs? Then just dip in & out of an overdraft when required for short term cashflow gyrations. Also, what is the average daily net cash, which is more meaningful than a 1-day snapshot on the year-end date?
Cashflow statement - provides a nice clear explanation of how this business works.
My summary (re-jigged so it makes more sense!):
£16.5m positive operating cashflow
(£2.0m) lease payments
£14.5m subtotal: real cashflow
This is spent on:
Capex £(5.2)m
Acquisition £(1.0)m
Divis paid £(5.1)m
Share buybacks £(0.6)m
New shares issued £1.1m
Bank debt repaid £(4.0)m
Exchange gains £1.2m
Total all the above, and cash is up by about £0.9m + £0.1m rounding.
That’s a nice roughly equal split, with positive cashflow paying divis, funding capex, and reducing debt.
They don’t really need to reduce debt, as there’s enough cash to pay it all off, so to my mind the cashflow would be capable of paying a dividend about double the current level. Hence dividend paying capacity (more important than the actual yield, in my view) is that Cohort could pay divis yielding 5%+ without straining itself. Although maybe just not yet, as the outlook says it needs to increase capex in this new year.
Outlook - here it is in full, this sounds very encouraging to me -
Encouraging outlook for Cohort
Our order intake for the year was strong and as a result of this success, the Group has entered the new financial year with a record order book of £329.1m. As we have indicated in the last few years, our order book is not only growing in value, but its longevity continues to increase. We now have orders across the Group stretching out to 2032. We have good prospects in the coming year to secure further long-term orders for our naval systems and support work, including from the UK MOD, Portugal and in export markets, as recently exemplified by the £26m order announced 9 May 2023 and a first order for our KDS anti-submarine system of over £7m announced on 30 May 2023.
The order book underpins over £140m (80%) of current financial year revenue expectations (2022: £128m). Following order wins since the start of the financial year of over £60m, that cover now stands at just over 90%.
Overall, we continue to expect that our trading performance for 2023/24 will be ahead of that achieved for the year ended 30 April 2023. We have had an encouraging start to the new financial year and our expectations for the full year are unchanged.
As a result of planned capital expenditure and expansion in working capital we expect that our net cash balance will decrease, but that we will maintain positive net funds at the year end.
We are optimistic that the Group will make further progress in 2024/25, based on current orders for long-term delivery and on our pipeline of opportunities.
Paul’s opinion - I’ve spent a fair bit of time on this, as it looks really good to me.
So an unequivocal thumbs up, GREEN, for what is clearly a GARP (growth at reasonable price) share.
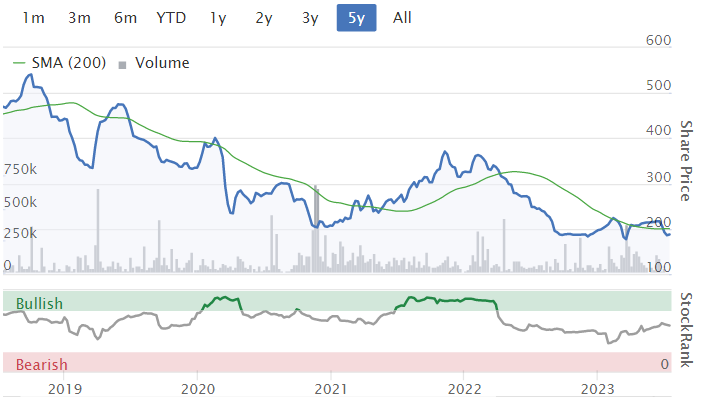
Cohort seems to have made good progress in the last 5 years, not reflected in the share price, so I think this could be a good long-term buying opportunity.
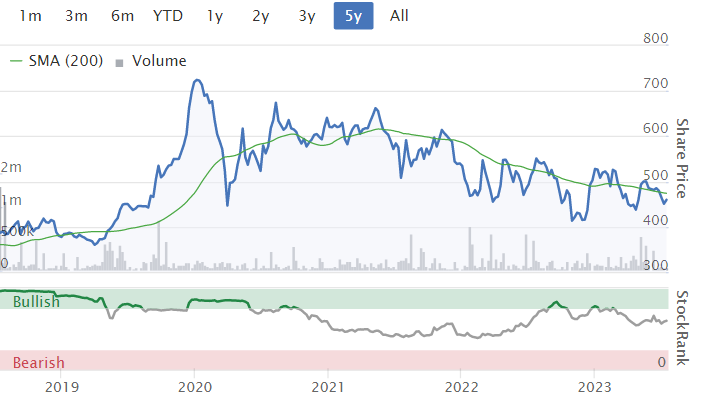
Personal group (LON:PGH)
Up 4% to 192p (£60m) - H1 Trading Update - Paul - AMBER/GREEN
Personal Group (AIM: PGH), the workforce benefits and services provider, is pleased to provide the following update on trading for the six-month period ending 30 June 2023 (HY23).
A rather long-winded update, and not a business I’m up-to-speed on, but overall it sounds in line with expectations, but with no footnote saying what these market exps are -
Board to remain confident that trading for the full financial year remains in line with market expectations.
H1 revenues £46.4m (up 34%) - nice growth.
H1 adj EBITDA up 75% to £2.7m
Claims to have a strong balance sheet, with £22.6m cash and no debt (I've checked, and the bal sht is pretty good)
Good visibility from recurring revenues.
That all sounds quite interesting actually, which has motivated me to have a quick look at the FY 12/2022 accounts, which are -
Revenue £87m (up 16%)
Adj EBITDA £6.0m (H1: £1.5m, H2: £4.5m), so the H1 2023 EBITDA figure above is actually a step backwards sequentially on H2 2022.
Historically PGH has paid out almost all earnings as divis, and it did this in 2022, earning adj EPS of 10.6p, and paying out the whole lot in divis, so a nice yield of 5.5% - and that could grow considerably, if it returns to the pre-pandemic days of divis around 23p pa - an upside scenario case which could get it up to a 12% yield in future, possibly?
A goodwill write-off suggests that the company isn’t very good at acquisitions, which could be why the CEO is being replaced?
I’m not very keen on the list of costs on the P&L, it seems to be taking insurance policy risks.
Balance sheet at Dec 2022 looked OK, at about £25m NTAV.
Paul’s opinion - neutral, as I don’t know the company well at all.
However, even on just a quick desktop review, I can see that there might be potential here. If it can return to pre-covid profitability and divis, then that would justify a decent uplift in share price, I reckon. I can see why employers (customers) might now be wanting to buy enhanced benefits for employees, due to the importance of retaining staff in a tight labour market.
So this share could be one for readers to investigate further yourselves. Getting to properly understand the insurance products, and the risks, looks key.
Delisting risk is worth considering with the top 2 owning c.50%.
I'll go AMBER/GREEN I think.
Graham’s Section:
Restaurant (LON:RTN)
Share price: 42p (+9%)
Market cap: £325m
Covering this stock back in March, I was flummoxed by six different measurements of adjusted profits.
I also see that Paul, in May, described what they published as “a really badly-written, unclear trading update”.
So my expectations were low as I opened up RTN’s H1 trading update this morning. Thankfully, the final line of the update does state in simple English that the company is "confident in delivering management’s expectations" this year.
Before that, we had a couple of tables to review.
Here’s the main one:
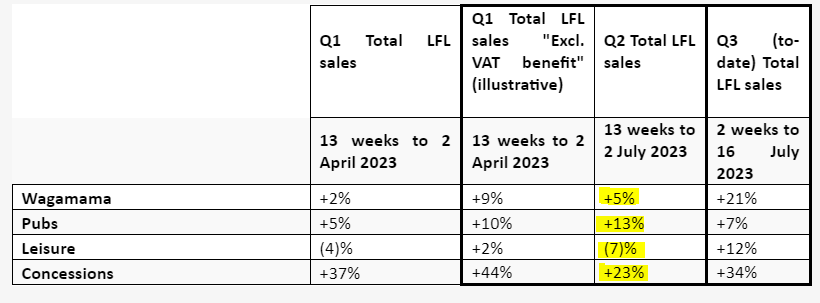
The numbers I’ve shaded in yellow are the new Q2 like-for-like figures (the Q1 figures were published in May). To me, it looks like a net deterioration compared to the illustrative figures seen in Q1.
RTN paid the best part of £600m for Wagamama in 2018, and its own market cap is now little more than half that figure. Even if RTN overpaid (by a lot), I think Wagamama remains one of the better parts of the RTN empire. But 5% like-for-like sales growth isn’t quite good enough in this inflationary environment, sadly. Hopefully Q3 will be better.
The company also provides a split of year-to-date delivery/takeaway vs. dine-in sales. I won’t subject you to another table, but the main point is that dine-in sales are much stronger than delivery/takeaway (comparing 2023 vs. 2022); this must be a lingering effect of Covid-related trends. Delivery/takeaway are down c. 10%.
Wagamama - has “outperformed the market”, and “recent openings are trading ahead of expectations”. Similarly, Pubs are outperforming the market with dine-in covers having increased year-on-year.
Leisure is the problem child. RTN puts a brave face on it, saying “good progress has been made on further improving cash generation”. More could have been said.
Concessions (airport bars) are showing the best year-on-year growth, “benefitting from the rapid recovery of passenger volumes and strong operational delivery”. Since this is a Covid-related recovery, I wouldn’t read too much into it.
Property - 35 sites are being closed, including some freehold sites to be sold. Wagamama continues to steadily expand.
Strategy - they are trying to get net debt/EBITDA below 1.5x by the end of FY 2025.
We also get this:
Whilst we are pleased with the progress being made in delivering these medium-term plans, the Board has continued to review its wider strategic options with the assistance of independent advisors in order to examine the potential to accelerate TRG's deleveraging profile and further enhance EBITDA margin accretion. In evaluating strategic options including potential disposals, the Board remains mindful that any transaction must be at attractive levels for shareholders and must reflect both the strength of current trading and the long-term prospects of our businesses.
Graham’s view
I said last time that RTN might want to think about raising more equity.
Today’s update gives more information about the “long-term strategic options” they are considering. We now know that they are talking to advisors, that they want to accelerate their deleveraging, and that disposals are on the table.
I agree that they should deleverage faster. Even a net debt/EBITDA profile of 1.5x would not be very good, since EBITDA is a very poor (in my view, almost useless) measure of profitability for a capex-heavy sector such as this. And RTN is only aspiring to achieve that leverage profile by the end of FY 2025!
Whether they raise equity or make a disposal is up to them - the economic effects are similar. If they can get good bids for the troubled Leisure business, they should do that.
In the meanwhile, I am going to maintain my RED position on these shares because in my view they should be trying to get a deal done, to get onto a comfortable financial footing (net debt last seen at £186m, excluding leases). But there is no guarantee that any deal is going to be on favourable terms for shareholders, and they could be left holding a much smaller (but hopefully more profitable) business afterwards. Or else they might raise equity.
The current market cap of £300m might seem low in comparison to sales of over £900m, but the quality of this business is questionable and its financials are uncomfortable. I could switch to a neutral stance if the shares were being priced as options on the debt, but I don’t think we are there yet.
The statutory numbers don’t lie:
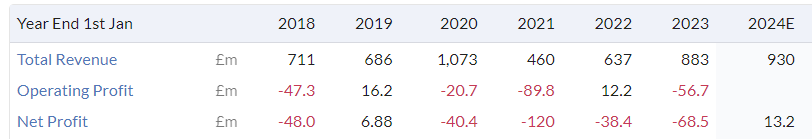
(Paul: note heavy dilution over this period, avg shares up from 277m in 2018 to 765m now)
Finsbury Food (LON:FIF)
Share price: 96.6p (+1%)
Market cap: £126m
Finsbury Food Group Plc (AIM: FIF), a leading UK speciality bakery manufacturer of cake, bread and morning goods for both the retail and foodservice channels, is today providing an update on trading for the financial year, ended 1 July 2023, prior to entering its close period.
This is a low-margin food manufacturer that usually trades at a cheap-ish level:

The P/E ratio is currently 9x, which is about average for it.
Based on our notes in the archive, we tend to have a mildly positive view on it.
In recent times, high raw material Inflation has been passed onto customers, keeping it in the black.
Key points from today’s full-year trading update:
Sales up 12.5% organically, up 16% including an acquisition. Sales are in line with expectations.
Growth in sales is driven “primarily by price”. As we’ve noted before, volumes aren’t changing much.
It has been “an incredibly challenging environment” but Finsbury has weathered it thanks to “commercial terms, operational improvements and other supply chain and overhead initiatives.”
The company also sounds very pleased with its small (£6m) acquisition of Lees of Scotland. According to the Lees website, it was previously listed on the stock exchange, from 2005 to 2012! It had the ticker LEE.
Performance at Lees has been in line with expectations:
Lees has a well-established number one position in the UK meringue category and strong relationships across a high quality and diverse customer base. This provides Finsbury with the opportunity to build upon both businesses' existing retail relationships and unlock further commercial opportunities, including out of home eating.
Graham’s view
I’m tempted to go green on this one, as it has previously traded at a PER of 12-13x. However, that may have been during periods when the market generally traded at richer valuations. In the current market, we aren’t short of possible bargains. In other words, Finsbury may be cheap but it’s not alone!
I will say that as food manufacturers go, this may be one of the better ones. It has almost always made a profit and earned a good if unspectacular return on capital. I would sleep somewhat soundly at night owning this one.
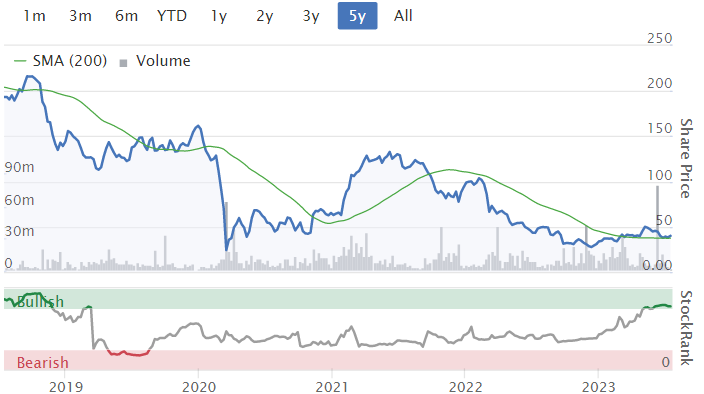
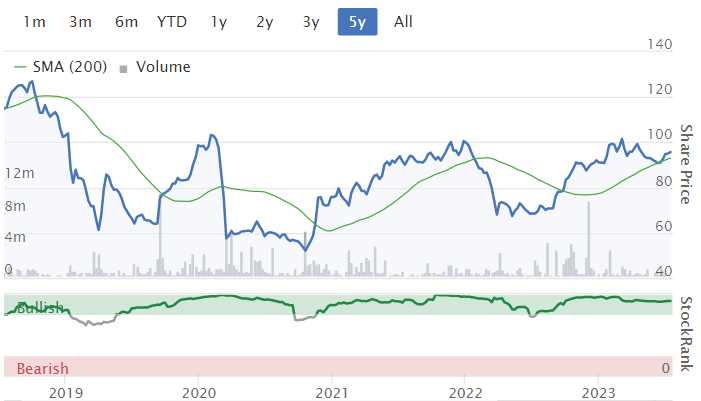
I’ll stick with AMBER but it’s a close call. Stockopedia computers think I should be more enthusiastic:

Springfield Properties (LON:SPR)
Share price: 65p (+1%)
Market cap: £77m
Springfield Properties (AIM: SPR), a leading housebuilder in Scotland focused on delivering private and affordable housing, provides the following update on trading for the year ended 31 May 2023.
I stayed neutral on this in February (share price: 80p) due to what I perceived as limited liquidity headroom for the company. It had temporarily increased its overdraft as I suspected it had probably come close to maxing out its RCF.
Let’s catch up with this full-year trading update:
Revenue approx. £330m (the prior consensus was c. £340m)
PBT will be in line with expectations (Equity Development have “adjusted” PBT at £16.1m in their initiation note published today).
Landbank is 16,300 plots. This is a slight reduction on last year’s figure (16,650 plots).
Gross development value unchanged year-on-year at “c. £3.5 billion”. (although last year, they left out the “c.”!)
Net debt is £68m at year-end. This is massively up year-on-year due to an acquisition, but it is down from £74m as of November 2022.
Profits will be lower for FY May 2023 compared to FY May 2022,reflecting “the impact of significant build cost inflation, particularly on fixed-price contracts in affordable housing, affecting margins across the Group.” It was already known that Springfield was taking a break from this sort of work, due to the problem that rising costs can make it unprofitable.
We do have some good news on this front:
in June 2023, the Scottish Government increased the affordable housing investment benchmarks by 16.9%. This is expected to enable housing associations to increase the price of affordable housing contracts to progress the building programmes required to meet the Government's affordable housing targets.
Private housing has also had its fair share of challenges, although at least prices have been able to rise freely to offset rising costs. The average selling price achieved is now £290k (last year: £245k). With the ongoing cost of living crisis affecting confidence, Springfield reports that its forward order book ended the year lower than it ended the prior year.
Strategy: the company has taken a defensive posture. They have reduced land-buying activity, paused recruitment/reduced staffing, cut costs, and even sold some land.
CEO comment excerpt:
We remain cautious about the near-term outlook, particularly given the softening in demand following the increase in rates by the Bank of England to 5%. We are closely monitoring the economy and buyer behaviour in both the housing and land market and carefully managing our activities to limit our exposure in the slower sales environment. This will also ensure that we can respond quickly when normalised demand returns. With over half of our large, high-quality land bank having planning permission, we are well-positioned for when market conditions improve.
Graham’s view
I’m inclined to give this one the thumbs up, because my main concern last time was the use of a temporary overdraft - that worried me!
Since then, the company has made some progress in reducing debt and I would like to see it continue down this path. A housebuilder with net cash can feel like a very solid investment, while a housebuilder with net debt is a much more adventurous play.
The main attraction here is cheapness. Tangible book value per share should be in the region of 120p. It’s fair to question whether this value is “real” in the current environment, with rising rates, and to worry about stumbling blocks the company might run into. There is no guarantee that affordable housing will be profitable again in the short-term, although the signs are positive. So this is not without risk.
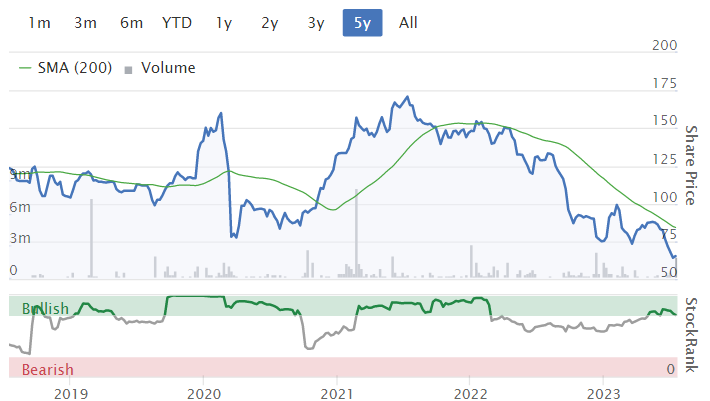
Ultimately though, I’m going to give this one the thumbs up, since I find it difficult to resist a value housebuilder. Bellway is at a price to tangible book of 0.7x, Redrow is at 0.8x, and Crest Nicholson is at 0.6x. Vistry is at a premium to tangible book (all using Stocko numbers). The discount in the Springfield share price can be justified by its elevated financial risk, but that’s what diversification is for!
Five Stockopedia screens also flag this stock as being worthy of further research. Mostly these are “Bargain” and “Value” screens. When full-year results are published, with the higher debt load, I’ll be interested to see if Springfield remains on these lists!

Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

129 comments
Thanks Paul for this detailed article ;-)
I have just bought some Watkin Jones (LON:WJG) as in my opinion it is now fundamentally and technically undervalued and oversold :-)
I also notice that one of the Directors has recently bought more shares :-))
A good long term hold :-)))
Thanks Paul - much appreciated.
Personal group (LON:PGH)'s main insurance product is a hospital plan but it only pays out a fixed amount when there is a claim, I believe, so its relatively low risk. Sales were hit during the pandemic as at that time they were largely offline.
Cohort (LON:CHRT) - a good summary. It's been on my watch list for years, but never quite caught my attention as cheap / attractive enough to buy.
On another topic....I have just frustratingly noticed that the takeover of Curtis Banks (LON:CBP), which I hold, is being looked at by the CMA. Is anyone else impacted by this? Not even a proper RNS today!
This maybe underlines Paul's point of taking less money when its announced rather than waiting for completion in this environment. No dividend and now possibly no deal!
This seems a bit excessive for a combined Nucleus/CBP £80bn AUM given the SIPP market is worth c£500bn in the UK. UK regulators seem to be getting a bit of a reputation for being too slow and way too onerous. Seems to me that they are too often destroying: value for shareholders, customers (through obvious cost savings) and the UKs reputation.
Here’s an idea ED (and I’m a big fan, btw), just put your disclaimer about being paid for research in your profile. Then it is clear who you are for anyone who cares to look. And then maybe we can all move on!
Great idea! Done.
Evening all, a lively discussion in the comments section today and we welcome it all. Some of you know us well, others less so. Ed and the team, if there is something we can do to make our status as paid for content clearer, we would welcome that discussion. We would like to stay in the comments section though, we enjoy it here!
As we have already touched on, we are regulated to the hilt and have no desire to go to prison, so you won’t find us front running. On the more nuanced point of whether the research adds value, you will all have your own judgements. We don’t carry Buy/Hold/Sell recommendations because they would only invite incredulity, and rightly so. We do carry detailed models and forecasts which you can then use to conclude your own fair value – we offer our interpretation, but DYOR will always apply. Use us as a tool, not the gospel.
Finally, to the many of you who have supported us on here, thank you. We at ED are all active private investors ourselves (within the compliance rules!) and spending our days looking at interesting growth companies is what gets us out of bed. It’s heartening to know so many of you appreciate that.
Good on you ED, I for one appreciate you posting.
There's lots of posts I have no interest in reading for various reasons every week so I just scroll past (some are ED's ). It's no big deal. I'd suggest others do the same if they don't like a post, there's no need to fill the board with yet more disclaimers.
Maybe the 3% move in the markets has given everyone altitude sickness:)
A major uplift in share prices of housebuilders and property companies today, such as Persimmon (LON:PSN) and British Land (LON:BLND) .
I guess this is because of today's UK inflation figures, which were slightly better than forecast. I hope the bank of England pauses base rate increases for at least a month, to see if this inflation beat is a trend or more of a one off.
It will take a few months to know, but there's a chance that the 18 months of base rate hikes might finally be having a sufficient effect. (Along with last year's commodity increases dropping out the year on year index.) Clearly, the hope that base rates are closer to their peak is behind today's rally.
My view is that things could still go either way and we won't have a real idea until at least October. There a numerous medium and small cap firms in the building supply chain. A couple if mine are Genuit (LON:GEN) and Forterra (LON:FORT) . Neither have been great investments recently. I think the 'learnings' for me are either to avoid cyclicals or at least insist they have very low gearing so they can ride out recessions.
A couple of mine are Genuit (LON:GEN) and Forterra (LON:FORT) . Neither have been great investments recently
I like and have bought both recently. I think they’re strong, cash-generating, dividend-paying companies with good climate, regulatory and demand drivers. I think patience will be rewarded. The charts certainly suggest as much. In the meantime there’s not a lot to worry about in terms of debt or negative P/L - though I don’t have a crystal ball.
Popped on to read todays report & comments as I usually enjoy everyone’s points of views
I’ve been trying to post more lately as I took on board Pauls request for more female investors; however based on some of todays posts I think I’ll take a break.
Perhaps I’m being overly sensitive but some of todays come across as aggressive and confrontational. Politeness and good manners cost nothing so I for one would appreciate it if we could all try please
Hey AstonGirl - don’t take a posting break: you have some interesting perspectives that the community will benefit from and I enjoy reading, so would a shame to lose that.
Please don't take a break. I enjoy reading your posts too as I'm sure do many others...
Let’s just make this forum useful for all participants.
Ingenta plc
A provider of technology and support services to content providers and publishers.
No debt and with a market cap of £16.3m , cash of about £3m , forward dividend of 4-5% , new contracts as they are entering the US market , and a free cash flow yield of 15%.
I have been adding this to my portfolio for the last two weeks.
DYOR.
Ingenta (LON:ING) is the tag!
Sorry for going off topic, but I have a question regarding how to accept the offer for Best Of The Best (LON:BOTB) . I was expecting some communication from my broker but so far I haven't received anything. I read the offer document and it looks to me that there is a different procedure to follow and it may not be through the broker as usual. Can anyone clarify this please?
Best Of The Best (LON:BOTB) Offer
aero79 - this is being done as a traditional offer which means that you need to positvely accept it. I assume that your shares are held in your broker's nominee a/c. If so it is tardy that they have not yet asked you and you should contact them asking them when they are going to take action. They wll have to accept on your behalf. No need to worry unduly - the offer is open and they need to give 14 days notice of when it will be closed to further acceptances.
Hi sharw, many thanks for this. I'll contact my broker as they can be slow sometimes, although there should still be some weeks.
EDIT: I've just received an email from my broker (IG) regarding the offer. Their deadline is 1 August.
Given the debate on paid research on here today, I have to observe it isn't the likes of Equity Development who cause me concern or who can be accused of misleading novice investors.
However - we do have individual posters who are active on these forums who are posting personal opinions and claiming they are statistical fact.
There was a particularly salient bit of correspondence in the comments section of Monday 17th July's SCVR, where a subscriber claimed "1 in 10 small listed companies survive and grow-the rest disappear-It’s a fact." and that in "90% of the cases they are ramping their shares and trying to con investors."
When challenged to provide a source for either of these claims the subscriber was unable to do so.
If we are really concerned about novice investors in these forums then perhaps we should all be more active in challenging spurious claims before we get too worried about FCA regulated research?
You are talking about me.
I have expressed my views , as I always do , and I do not have to explain anything to you(DYOR). And yes 1 in 10 small listed companies survive over the years (unfortunately). The last 2 years alone there have been several delistings (DYOR) of small listed companies and even more (and ,rightly not covered here) that offer nothing as listed companies to investors(again DYOR).
This is my personal opinions based on years of experience working first and then following the stock markets.
DYOR and stop insulting the participants of this forum.
You are trying to turn this forum into ADVFN.
It was an opinion, not a fact then?
Any chance of covering Personal group (LON:PGH) today? Another positive update for this workforce benefits and services provider. I get the feeling the new Chairman is really improving things and a new CEO is starting shortly, heralding a new era maybe?
Be good if Cohort (LON:CHRT) could be covered as well which is something I have on my watch list.
PGH is one my fav in the portfolio. Haven't recovered completely, potential be a great dividend payer.
Hi topvest,
I managed to cover both your requests today! :-)
Both interesting companies I think too!
Regards, Paul.
Reward for failure
The Bank of England paid out £25m in bonuses to staff over the past year despite warnings from its governor that employers should show “restraint” over wage rises
Just highlighting another excellent Ronald Head article yesterday:-
https://www.stockopedia.com/co...
The brilliant Small Cap Value articles and analysis is immensely popular and deservedly so, and always with lots of quality follow up comments too, but it’s a shame that other threads and some superb articles see far less interest and often with few follow up posts either.
Roland Head’s article yesterday turned out to be very well timed! The bombed out REITS sector will recover strongly again when interest rates are peaking and with likely cuts on the horizon. The sector will price that in, in advance,
REITS are leading the way today with gains of 5% to 8% today after the better than expected inflation news. Those covered by Roland are up between 5% and 8% and those in the few (just 10) replies are up similar amounts. There could be MUCH more to come.
It’s not just UK smaller companies that have struggled for so long and with very big recovery prospects in time. There are many other bombed out shares and Investment Trusts too, with Trusts at discounts as high as 50% where investors buying are paying 50p for an investment worth £1. And dividends are very high too, and some shares and Investment Trusts are confident of increasing them too. Last year even FTSE100 share Rio Tinto (LON:RIO) paid a 20% dividend, though lower this year as China woes hit the Mining sector ….for now. Quite soon the switch to clean energy/renewables could well see a major Mining sector bull market.
And what about shares like Aviva (LON:AV.) Legal & General (LON:LGEN) M&G (LON:MNG) and Phoenix group (LON:PHNX). All paying 8% to 10% dividends and (e.g LGEN and AV.) with expectstion of dividend increases.
I entirely agree with what Roland wrote yesterday. I have been bullish on Housebuilders for the last three months and have written about this in this site. The bombed out sectors of Property, PE, Packaging and small caps are still worthy of attention. Banks and the Insurance companies you mentioned are good values and pay excellent dividend.
Maybe today is the inflexion we have been waiting for. It may prove the "sell in May" not worthy of attention this year. who knows.
Yesterday Mello Investment trust session was very informative and worthy of listening to when it becomes available.
The four professional choices for the next five years were: Caledonia Investment trust, TR Property, JPM American trust and Uranium (etf or mining).
Here is a link to the Mello Trust and Funds show yesterday
Thank you David. Excellent overview from Edmund, but missed the panel session due to domestic commitments.
On the matter of REITS, I hold Palace Capital (LON:PCA) and Real Estate Investors (LON:RLE) both battered with conservative loan to value, trading at large discounts to NAV and yielding 7% and 8% respectively. Also both have been buying back shares, plus there has been very significant director buying at Real Estate Investors (LON:RLE) . Coincidentally Harwood hold both. See link below to the Vox Markets interview with Christopher Mills on 6 June.
Vox Markets Fund Manager Series: Christopher Mills, CEO of Harwood Capital - Vox Markets
I also bought TR Property Investment Trust (LON:TRY) for my daughter in her ISA.
Real Estate Investors (LON:RLE)
Hi Jonno
I took a look at this one recently. but remain unconvinced.
Rental yields are currently 7%, with debt on interest at 3.5% for at least 2 more years. That doesn't leave much room for profits on the leveraged properties.
If the company starts showing signs of reducing or preferably eliminating that debt load before 2025, then I'll be more interested.
I also have doubts about the book value of properties, especially the vacant ones.
If I'm wrong on the book values (highly likely), then there's definitely room for a large upward re-rating.
A
A very interesting day in the markets.... unlike the US CPI data ... this number was less easy to forecast, and not just reliant on a back number falling out of the data. The divergence in stocks and massive outperformance in the rate casualties, house builders, banks and REITs today, points to positioning for me. Moves of this scale are, more often than not, month ruining for institutional managers....and forced covering therefore follows. So closing shorts and underweights.
For the time being we are in goldilocks scenario where rate expectations can fall on the back of lower CPI numbers. The thing is CPI data is notoriously volatile so it would not surprise me if we drift into RORO (not risk on risk off) but "rate rises" on - "rate rises" off. Lates in the year differences in labour market conditions between US, EU, UK etc will determine what sort of CPI levels we exit at. Sentiment towards the US will be more important ... and the jury is out how Q4 will pan out.
If anyone has thought they missed an opportunity to buy sensible yield then it definitely remains. For example the Gen Accident Prefs discussed here with coupons at 7 7/8% and 8 7/8% are only marginally higher than last October ....when we had the Lizz Truss Gilt puke. (I own, appears little liquidity today FYI).
In summary the trend set off last week with the US CPI data has definitely tilted positively and so far this is panning out quite well for UK equities. Regardless of positioning I guess this is something we are all enjoying. Sadly the harder part follows as to when or whether to reduce exposure. I think this can run a while now... but my guesses are always pretty useless. Inevitably the data will take a bad turn at some point and being ready for that is the task at hand.
Re HL...I suspect many answers to issues lie in old tech and processes and they struggle to adapt
I don't get the fuss about ED. They are paid for research. That's clear. They provide detailed notes and facts on companies...often giving colour on issues that can't be made so easily in regulated rns statements. Of course, they will never issue a note saying sell sell sell.
They are FCA regulated. This means people at ED are not allowed to front run their own recommendations...if they personally own any stocks that they recommend through their paid for service there will be significant controls on how they do that (when they can buy, when they can sell, how long they must hold for and no short term trading). Ie, they ain't going to pump and dump on you! They probably aren't allowed to buy a stock between time of initial engagement discussion and their first research note for example. And they won't be allowed to sell on any sneaky inside news. I've been in a similar environment. Its onerous. A dodgy operator may always seek a way round the rules...but at v high personal risk.
There are many other stock commentators about (not Paul and Graham or others that do the SCVR tbc) that don't operate with such high 'cleansing' standards. I'm not gonna name names as many people here love those pump and dump stock cads and loose their sheet if I say anything about them. These wideboy stock commentators give low to zero analysis and are clearly touting their own holdings after they have built a position....they are using you, yet many of you seem more okay about this than paid for detailed research. They definitely wont tell you they are going to sell either...they'll sell and then maybe tell you...perhaps they will even put a short on to milk extra return from you.
IMO the above wideboys are pretty despicable. They use you and profit from you. You think they give you something but really they are just confidence tricksters...knowing that they can play on your uncertainty and anxiety for their gain.
So, do you know everything about a company and an ED note provides you no extra information? This seems the salient issue.
Maybe there has been a more than usual glut of information recently.. I have to say however that the read across yesterday from Diageo (LON:DGED) (25%ish margin) to Artisanal Spirits (LON:ART) (margin ??) must have involved the rosetta stone.
Perhaps you should do some research before stating something like that; if you’re interested these are the comparable margins…
Hi Snowbum,
I am interested, I was referring to the companies current operating margins, which I took as a good starting point.
I have looked at the figures you have quoted, by this count even naked wines would be an investment certainty, however does it not come down to how much profit is left after all of the company expenses, and how the company can sustain those profits long term ? I get that Artisanal is a growing business, and it is hoped that costs will stabilize / reduce whilst revenues continue to grow, and that their maturing stock will realise its value in years to come. They are however at the moment still operating at a loss, and their forecast has been cut to an even greater loss for 2023. I am not fully convinced by the membership model as being something that can be grown on a continual basis, maybe the international side will pick up but they seem heavily focused on the UK. It seems to me that the rate of new memberships has tailed off recently.
I still do not see the read across to Diageo, who are selling better known (but I would say lower quality) brands in large volumes at a profit (i.e. seen on their bottom line at the moment). Maybe my point of view would be clearer if I made the comparison between a read-across from Taylor Wimpey to Watkin Jones - after all, they are both in the housing business, right ?
We’ll agree to disagree and leave it at that. Even if 20% of the bottled value of Artisanal Spirits (LON:ART) ‘s existing stock is realised, that’s well over the current mcap of the company. This may not be the time to invest in growth companies, but with significant asset backing this somewhat derisks the proposition in my humble opinion.
Or maybe I just like Whisky too much!
I really appreciate your open and friendly reply. I am quite willing to be wrong ! being quite a big fan of whiskey as well. I will keep an open mind on Artisanal, and good luck holding - I hope that you are right.
I’ve been to the venue in Glasgow and was impressed. However I intend to conduct greater ‘direct market research’ at the Whisky festival at the SECC later this year, I’ll be sure to report back here - but depending on how it goes maybe not on the following Monday!
An I bet Snowbum didnae find any whiskey in their place in Glesga, that bein made elsewhere !! 8-)
To be sure to be sure :-)
Hi again Snowbum,
After reading your reply I decided to do a bit of further digging, it is of course why we are interested in investing - and you have got me interested purely on the fine wiskey level.
So.. watching their latest annual presentation, I can see now why they want to draw the comparison with Diageo, as they have managed to get a new FD who has worked for them. I did not know until now that 'premiumisation' was a word, shows how out of date I am. They are very keen to emphasize this trend to more premium products, pointing out the market is $7.6bn and growing... so plenty of headroom there then for their £22m revenues.
If I understand it correctly the quoted figure of £493m is an estimate of the value of their current whiskey stock in casks, is only if bottled and sold at the retail value. They quote the 60% margins (with an expectation of 70% if things go well), but this is gross margin and does not include all of the costs included in the sale of those bottles.
From a quick estimation of a linear growth, it seems like their existing stock of whiskey is good for another approx 12 years.
I have tried to be somewhat optimistic (or at least neutral) concerning what their future costs might be and here are my figures (I couldn't put the whole table on, as it was too small to read, but you get the idea);
So, I get a better forecast EPS than they are quoting for 2023, my estimation is that they will spend about £300m in costs to sell the £493m of their existing stock if all else is equal. I think that they have some good measures in place to reduce these costs, which will all show up as profit - all to the good.
My bull case would be that if they can keep a tight control on costs then the gross profit will filter down very quickly (if you excuse the mixed metaphor), and it is a big market as they point out.
My bear case is that the costs have remained high for a number of years now, and the if the people shopping at Waitrose are now considering Aldi, the whiskey membership will already be down the pan.
Great work cheeky_minnows, I appreciate you putting in the effort to pull some numbers together. In your bull case, you may also wish to consider the following points:
In your bear case, you may wish to consider that I shop at Lidl, and drink premium Whisky, as do many of my friends and family. I may look to save money in some areas, but like many, I don’t tend to be so discerning when it comes to entertainment and enjoyment.
From a chart perspective, I’d like to see a bounce around the current level, but if it drops further I won’t be arguing too vociferously with Mr Market!
I had a think this morning, and have changed my bull thesis.
Looking at the figures, they would make more money selling the wiskey out of the back of a transit on Glasgow market. What they need is someone poached from Diageo, who knows how to do it.... cue the new FD ! That must be the read-across :o)
I don't get the fuss about ED
At my age it’s a growing (or not) concern ;-)
<blush>...haha
With prescient danger of completely lowering the tone, Futura Medical (LON:FUM) has softened after the recent tip (Times) and, on a technical basis, is looking like it could be a good time to enter… (I hold)
The addressable market is apparently significant!
I agree mojo. We need more research to private investors not less, who cares what any brokers target price or fair value is, personally I never pay this any attention just like I pay stocko value ranks no attention. It's an individual judgement based on so many variables.
Plenty of spivs out there delighted to use private investors as you say, so going after paid research is very odd.
I agree - Equity Development are open about who they are - they don't post as 'Hannah' - so what is the fuss about? They also don't just come on here and post a link to their research and go away - they do engage with the discussion e.g. yesterday https://www.stockopedia.com/co...
That combined with the many company presentation webinars they do put them in a better position to feed back to the company concerned the views of PIs lke us.
Well they sometimes use the expression "adjusted EBITDA", as if BS earnings needs pumping with more BS. That really grates.
Haha...you're gonna need to take on the whole industry with that gripe. Would be weird/impossible for ED not to use adj ebitda.
BS earnings indeed! But there's always information and content in how the adjustments are made. And for early stage and/or heavy investing and acquiring companies an ebitda adjusted or not is kind of essential.
It is a rational and maybe astute decision not to invest in companies that require adjusting...but for those of us who do mess with these dirty murky little things then its all part of the game.
EBITDA....comes up on the forum again and again...
Last discussion was SCVR on 5/5/23 if anyone interested.
Just a little suggestion that:
EBITDA = BS Earnings
and adjusted EBITDA = Super-BS Earnings (hat tip to MrContrarian for pointing this out some time ago).
Yes indeed...but how many times did small cap luminary Christopher Mills use the term "EBITDA" in his Mello spot (link to vid posted at the top of today's SCVR)?
I lost count.
I agree. ED are decent. We all know they are paid for their reports but their reports are good.
There are several similar companies providing a poor service. Probably suffering from ED!
With a little experience, they show themselves easily. Oh wait, is that PC?
Well said , and 'onerous' is a mild description of the policies and controls that a proper, regulated firm must have in place these days.
mojomogoz, you've got yourself a job as our stand in compliance officer!
...just getting my charcoal grey suit and dark blue tie out of wardrobe...
I hold Rockwood Strategic (LON:RKW) . In the past 2 days I have received alerts from A J Bell about a proposed 10/1 stock split and about the resolutions at the September AGM. Stockopedia shows neither of these RNSs and the links that AJ Bell provides for further details just lead to the latest report and accounts.
The RNSs don't appear on the LSE RKW page either.
Has any other holder seen these RNSs?
PS.
Trying to call bottom & making calls on cyclicals is awfully brave.You either look a genius or a damn fool.Good luck with that one.
Having sold my Watkin Jones (LON:WJG) holding back in November 2021 I've printed off the Stocko Report closest to the actual date and have printed today's Report and put them side by side for a comparison. I'm thinking that shareholder sentiment plays a larger part in share prices than most small investors realise and that WJG is at this moment a Buy. To counter this view though, below the Balance Sheet there is a Financial Brief to be opened.....
Watkin Jones (LON:WJG) profit warnings create the usual conundrum to hold or exit. I have sold from two family portfolios, fortunately not significant positions. In time Watkin Jones (LON:WJG) will I believe recover. I believe that Gresham House recently took a 6% holding, poorly timed.
I still hold Watkin Jones (LON:WJG) in my portfolio. Will watch the price action and take a view. Incidentally I exited Vertu Motors (LON:VTU) AND PayPoint (LON:PAY) both at a reasonable profit. I like Vertu Motors (LON:VTU) and it is a takeover candidate but cars are big ticket items and the likely continuation of increased interest rates in the UK provides a big head wind. Wish that I had followed the same route with Watkin Jones (LON:WJG) but C'est la Vie.
As for PayPoint (LON:PAY) the delayed results and recently announced litigation made me uneasy.
Considering the recent investments by Carlyle in MJ GLEESON (LON:GLE) and Lloyds Banking (LON:LLOY) in Barratt Developments (LON:BDEV) doesn't this fall in Watkin Jones (LON:WJG) make them interesting to such investors ?
Just wanted to say a thank you to you Paul for correctly predicting that the PWs would keep coming at Watkin Jones (LON:WJG. I have been tempted to pull the trigger a few times lately and you’ve saved me a lot of money. Big love and gratitude to you.
Thanks BnB. Looking back, I shouldn't have stayed GREEN on Watkin Jones (LON:WJG) earlier this year, given my concerns over the reliability of forecasts. But as stated at the time, I was seeing it as more of a medium-term recovery. I should have gone AMBER, with hindsight.
Today's news is a lot worse than I expected, so moving to RED seems the only option. I haven't looked up the share price yet...
Regards, Paul.
Watkins Jones profit warning is more painful because today the rest of the house builders are having a stunning recovery.
The best day in years. Up between 5-7 percentage point.
This once more reminds me of the reason why I prefer larger companies.
I probably sell my stake at Watkins.
It was a falling knife and one has to accept that.
Why are Stocko shares prices so slow in updating? Watkin Jones (LON:WJG) is up 3% at 8.30am, in fact it is down 40%.
Price is down while the market cap stays the same. I have to rely on Google finance to check this.
Good update from Pebble Beach Systems (LON:PEB) . In particular there is a good reduction in debt in the half year - this used to be a pile of debt from the collapse of Vislink with an operating company attached but that is changing now. finnCap maintains eps 1.3p for the full year giving a p/e of 5 at 6.5p (+4% @ 08 15).
Thank you for your WJG comments Paul, what a bad start to the day! We hold, for now.
I just dumped my small holding at 46p just seems too messy for now.
Watkin Jones (LON:WJG) Just playing devils advocate here, but given the asset backing, the fact that these delayed sales will have to complete at some point and the fact the company has a good forward order book and no debt, isn't this an ideal buying opportunity?
The fact is that these institutions need to buy, they have to put their money somewhere. Agreed one would need to be patient but in 2 or 3 years time this could look like a bargain basement opportunity?
Good point and it probably is a great bargain basement price. Personally I've lost all faith in the company though. I only want to hold stocks I like moving forward, so I sold and have a bit of cash. So now I get to go shopping
Watkin Jones (LON:WJG) Just playing devils advocate here, but given the asset backing, the fact that these delayed sales will have to complete at some point and the fact the company has a good forward order book and no debt, isn't this an ideal buying opportunity?
A good question indeed. Maybe yes. But only if the the sudden balance sheet weakness doesn’t necessitate a large and discounted raise. Or worse, they go bust.
Well the Chairman thinks so - he's just bought £200,000s worth. Isn't the problem from a PI point of view that the business model is based on a 'lumpy' income stream that is exaggerated by present credit conditions?
Even that stinks, they do a trading update without a sniff of good news and the Chairman buys £200k worth on a 40% drop..
Dodgy as
Hargreaves Lansdown Hargreaves Lansdown (LON:HL.) posted an update today.
I am not a shareholder but I am a client
HL. are the largest execution only broker in the UK, yet incredibly they do not offer a flexible stocks and shares ISA.. A couple of years ago as the rules changed and ISAs were made flexible, meaning that you are allowed to take out as much money from your ISA as you like and you are allowed to return it within the same tax year. Previously, any withdrawals could not be repaid and no longer sat within the ISA wrapper. This new option can be highly beneficial.
Happily, I have not needed to make any withdrawls for many years, but this must be frustrating for many HL customers.
I have 2 other execution only broking accounts, both of which offer a flexible Stocks and shares ISA.
I do not understand why HL do not. Would appreciate a response from HL.
Hope this info helps some of you.
Barclays SmartInvestor and Charles Stanley do offer flexible ISAs.
Maybe we could make a list below of companies which do or don't offer flexibility?
My thoughts exactly Michael. Customer retention / attracting new investors to the platofrm; seems like a no brainer.
I use HL for the majority of my ISA holdings but the flexibility ISA options elsewhere are getting tempting.
Because Hargreaves Lansdown (LON:HL.) want to keep hold of your money. When I tried to transfer some cash, from my ISA to another provider, it took ages, about 3 months, they delayed it as long as possible. Because they make money from your cash, why would they want to make it easy, for people to withdraw their cash?
HL don't quote online prices for gilts either, in my experience. Perhaps again to deter people from seeking higher interest rates for uninvested cash.
At least Hargreaves Lansdown (LON:HL.) do pay some interest now on cash, 3.5% on amounts over £100,000 which within an ISA is not too bad.
I think ISA need to be more flexible. Even moving cash from a cash ISA takes too long, Ive has bad experiences on both my transfers from ISAs and they did not even involve shares.
HL also do not allow you to do regular investments from cash already in your account. This option is available at Interactive and AJ Bell, at very low or nil commission. I have told them several times to wake up but to no avail.
yep, this is the reason I dumped HL and switched to II
I understand the point, but why does it annoy you so much if you don’t yourself use the flexibility? I can’t believe it’s that popular a thing (and maybe HL are not wanting to encourage investors to flip flop with their money, investing is meant to be long term) but what do I know.
We, Private Investors, are a small group of individual thinkers. Most people do not take control of their own investing. HL are the largest execution only provider and should provide the flexible option, many others do. It is not up to them to 'nanny' us and prevent us from having access to our own money. They should be providing all the options and we should be adult enough to take responsibility for our own decisions.
I know so little about these things but have been imagining that this dispensation applies to just the Cash ISAs.
No Silver Moon. FlexiISA rules apply to S&S ISAs too.
I have found the option useful in the past, with Barclays Intelligent Investor - but I would never recommend that company for numerous reasons.
Correct Roger Baron
I am referring to flexiable stocks and shares ISAs.
Barclays SmartInvestor has been terrible in the past but it is much better these days and dealing costs are just £6/deal. If you have a query, you can ring up, they answer and they do deal with the query.
As with everything, you need to be an expert in what you are doing, monitor it properly and also say when you are unhappy.
I'm with AJ Bell - who are generally very good ,but recently gave me the hump so I called HL to enquire about their SIPP/ISA charges .The lad who took my call asked for all my personal details - NI number ,DOB ,address etc - but not how much assets !? I refused to give him any details apart from my name so he refused to pursue the call LOL !! HL can effin do one !!
I fully agree with you Michael. All these broker accounts are very inconsistent. Charles Stanley Direct are flexible, but Interactive Investor are not which is frustrating.
I use these two brokers now after being solely Charles Stanley Direct for many years. Interactive Investor are cheaper, better to use , pay interest on cash and allow voting. Charles Stanley Direct are better on the telephone but have few other attractions now. Wouldn't it be great if they all offered the full package!
I tend to agree with your analysis about brokers, but Charles Stanley Direct is one of the very few ways that an investor can hold shares direct rather than through a nominee account (I think this route may no longer be open to new investors) and that has a number of advantages.
I mainly use Interactive and Jarvis for regular share trading. Both are relatively cheap (particularly II) and efficient. HL are very expensive have slipped a lot in my view. Accordingly, I rarely use them.
Cohort plc (LON:CHRT) strong prelims announced with record levels of both adj operating profit of £19.1m and revs of £182.7m. The Board's outlook is 'encouraging'
ALL investors can see the CEO and Group FD explain in more detail and take Q&a at a webinar THIS Friday, 21st at 11am, just register here : https://www.equitydevelopment....
CPI comes in lower than expected, Could we see a rise in the markets today? I hope the tide is starting to turn
Corero Network Security (LON:CNS) ARR driven cyber growth (new report from Equity Development). Full report here: https://www.equitydevelopment.co.uk/research/corero-initiation-report-july2023
Corero is a cyber software business that is overlooked by the market, in our view. Huge progress has been made over the last three years bringing the business to operational maturity. The company is predominantly now a recurring revenue business, but this does not seem to be recognised in the current valuation. Corero's technology has been validated with major market leading customers and go-to-market partners.
Group revenues have grown c20% compound between 2018-22A, enabling the business to fully recover its total cost base and report positive EBITDA since FY21A. Corero has repaid all outstanding debt and is now unleveraged. The recent trading update for H1E has confirmed strong trading with revenues growing 20% YoY to $10.6m and net cash on the balance sheet of $6.2m.
Back in 2019 the stock was trading around 5x EV/sales. On just 2x FY22A EV/sales the shares now, the shares look materially undervalued. We will be initiating coverage with forecasts in due course.
Reassuring update from Capital (LON:CAPD) today (I hold). Share price has been under a lot of pressure recently which has surprised me. Will this update see it fall out of the rising channel or bounce off the bottom? The later I hope!
Watkin Jones (LON:WJG)
Paul, you predicted that they would probably be another profit warning coming from this developer of BTR and student accommodation. Well, here it is. And it’s a doozy! It will be interesting to see the market reaction in half an hour and to assess whether this represents the bottom for what is, in many ways, an attractive business..
Watkin Jones (LON:WJG) - and the CEO has departed!
That's good as they seem to have lost their way, a shake up will do them good. The only positive I could see in that trading update is a strong cash position?
Read across to Empiric Student Property (LON:ESP) ? Who focus on student accommodation, albeit not build side, but own and operating side. Empiric have been very bullish about demand and occupancy rates in their latest statements.
Springfield Properties (LON:SPR) An undervalued, high quality growth story (*** initiation of coverage ***)
Full report here: https://www.equitydevelopment....
Springfield Properties is one of Scotland’s leading housebuilders. It has an enviable track record of growth and profitability and a reputation for building high quality homes in attractive locations. Whilst market headwinds have increased, in our view the 50% decline in Springfield’s share price over the past year is significantly overdone. The business has navigated previous cyclical downturns impressively and has emerged strongly from them.
We initiate coverage with confidence in the Group’s long term growth prospects and see scope for a material re-rating of the shares as investor sentiment improves. Whilst sector commentary is likely to remain cautious in the near term, we expect investor sentiment to improve once there are clear signs that inflation is easing and interest rate rises are coming to an end. We initiate coverage with a Fair Value per share of 110p, which is based on a sector multiple of 0.9x Price/ Book. This represents a level c.70% above the current share price.
Thanks for the advertorial .
Good to see the classic “we maintain our fair value” line at the end, love that .
Can you confirm the fee you get paid for writing this please so we can offset our new interest in the undervalued debt ridden low margin Scottish house builder with the with the openness and clarity that knowing you are on a monthly retainer to promote them means we can temper this announcement .
This also posted on LSE board .
For me personally I would rather paid researchers did not post on here especially without the clear caveat IM PAID TO WRITE THIS but I know I’m in a relative minority here so no problem just my personal preference
I would appreciate it if Paul Scott / the Stockopedia guys get Springfield into their daily analysis so we can get their thoughts on the fair value which Im guessing is the price target ?
Come to think of it what is the fair value quoted actually meant to be ?
Sorry but I can't resist....
'Let's see Paul Allen's fair value...'
In a world where we are starved of research, an absence of small cap coverage is an obvious externality of banning commission based payments ...... is it so bad for corporates to pay for coverage themselves?
The comment above clearly states that fair value is based on a sector multiple of 0.9x book...giving a share price of 110. I don't own and have no beef.... I do not see an issue at all with paid research being published here or anywhere else for that matter.
All research is aimed at increasing revenue to the publisher....normally transaction revenue...normally corporate M&A of some sort. So in the absence of potential deal flow perhaps we should expect more cos to publish paid research.
I don’t disagree that companies can commission a company to do paid research
However it simply needs to be clear
Exactly the same as “advertorials” that are very clearly (and legally required) to be highlighted when newspapers write pieces.
I also strongly dislike the “we maintain our fair value” based on sector multiples
Just my preference , I don’t believe readers here should have to “guess” or be expected to know “of course it’s paid research” or even then have to fall back on the DYOR trick .
For mr this is a forum of opinions of independent like minded individuals exchanging views and opinions and in many cases unique insights - this gives us maybe a slight competitive advantage as there are some smart cookies on here .
Muddying that with paid analysts is really bad form and I don’t like it but I can accept it but I think the caveat needs to be clearly stated .
It’s not so bad for the regulars but new readers don’t always know the score .
I’m happy to keep highlighting it as I doubt it’s going to get sorted .
For the record I wouldn’t touch Springfield properties and my fair value is not 110p and I’m not paid to write that .
A bit harsh, Springfield Properties (LON:SPR) has a stock rank of 80 and is rated as ‘contrarian’ , a winning style. I have taken an entry today as my ‘techie’ approach says the bottom here might well be in - look at the weekly volume!
This is a growth company, with an excellent land bank, in a market with strong demand, in Scotland where the housing market legislation is more supportive than the rest of the UK. Each to their own, but please keep a little perspective rather than these personal rants.
Didn’t realise it was a personal rant .
My humble apologies if you feel that way I think the point is clear and Paul Scott has gracefully acknowledged the point has come up with a solution to the clarification on paid research .
I actually know Springfield very well as I l bridged my friend who bought one of their houses .
My analysis and opinion on Springfield as a low margin housebuilder in a tough economy with raised mortgage rates is a bear view
You are bullish and have bought and I have highlighted bear points .
I don’t believe anything was “over the line” personal in any comments but if they were sorry for offending you .
Personal as in ‘belonging to you, from your person’ I take no offence, please don’t take my comment the wrong way. Always good to hear bear points. We all have different strategies at the end of the day.
We certainly do!
Corporates still not satisfied with the coverage they get on This Is Money at MailOnline. I say to those Pumpers "hands off Stocko"!
Morning planetx!
I would appreciate it if Paul Scott / the Stockopedia guys get Springfield into their daily analysis
We actually do report on Springfield Properties (LON:SPR) already, there are 5 SCVRs in the archive covering it.
Looking at our fairly manageable to do list today, SPR is on there, so I'll make sure either me or Graham cover it today :-)
As regards the commissioned research notes, personally I find them very useful, especially where we don't have access to notes from other brokers. Although as you say, the "opinions" and price targets have to be seen for what they are - commissioned PR.
Equity Development are open about who they are, so there's no deception taking place in my view. I know Ed did mention after some recent discussion here, that we maybe ought to put a flag against paid-for promoters, just to make it clear to newcomers that these are not honest personal opinions like the rest of us post.
(I never take any money from companies to say nice things about them, it wouldn't even enter my head to do that, and readers would smell a rat from a mile off anyway!!)
Regards, Paul.
Paul
Thanks
My point is it’s such a very easy thing to solve
Your flag sorts the issue and end of story
Doesn’t really need ongoing debate and until you have your flag system in place ask Equity development to specify it.
They will understand and it is actually better for them I believe as without it they are at risk (not totally unjustified) of being seen as pump and dump hype merchants not the creditable analysts they actually are (in 90% of the cases)
Finally I wonder what would happen when they are commissioned to write up a company they don’t believe in ?
Anyway this is affecting my mental health I need to go for a lie down .
Fully support having a flag system in place asap. There was one person who had stated he was unaware it was paid-for research, so there are bound to be others too. It completely resolves the issue.
I’ve no problem with quality paid for research from the likes of Edison. It’s no different to brokers plugging the shares of Companies that pay them. Often Edison and others (e.g quoted data) are far more thorough than the average broker note. And unlike some Brokers Edison doesn’t hide negatives either
e.g Edison have just issued an update on Investment Trust Henderson Far East Income (LON:HFEL) which I hold, attracted by the 10.5% dividend that has been increased for 16 years, is covered, and they intend to stick with their annual rise dividend policy. BUT it’s been at the expense so far of overall performance where HFEL is by far the worst in the sector.
Here’s the full Edison HFEL analysis:-
https://www.edisongroup.com/re...
Edison don’t try and hide that as can be seen from exhibit 6 in their HFEL analysis:-
Exhibit 6: AIC Asia Pacific Equity Income sector at 12 July 2023*
% unless stated
Market
cap £m
NAV TR
1 year
NAV TR
3 year
NAV TR
5 year
NAV TR
10 year
Discount
(ex-par)
Ongoing
charge
Perf.
fee
Net
gearing
Dividend
yield
Henderson Far East Income
386.6
(8.3)
(8.3)
(6.5)
33.3
4.0
1.01
No
106
10.0
abrdn Asian Income Fund
337.5
(4.7)
18.6
23.8
53.9
(11.8)
0.99
No
110
5.3
Invesco Asia
219.9
(0.5)
25.0
40.4
168.3
(10.1)
0.97
No
102
4.5
JPMorgan Asia Growth & Income
326.2
(2.4)
1.1
19.7
119.8
(8.5)
0.69
No
100
4.7
Schroder Oriental Income
633.8
(0.5)
21.6
27.8
97.7
(4.1)
0.86
Yes
104
4.6
Simple average (5 funds)
380.8
(3.3)
11.6
21.0
94.6
(6.1)
0.90
105
5.8
HFEL rank in peer group
2
5
5
5
5
1
5
2
1
MSCI AC Asia Pacific ex Japan
(5.4)
(0.8)
12.1
78.7
MSCI AC Asia Pacific ex Japan HDY
(0.6)
13.4
16.0
54.4
Source: Morningstar, Edison Investment Research. Note: *Performance data to 11 July 2023 based on ex-par NAV. TR = total return. Net gearing is total assets less cash and equivalents as a percentage of net assets.
Looking at the chart "legless trousers" comes to mind.
If you download a regulated broker note it always contains a very clear disclaimer at the end:
Equity Development Limited (‘ED’) is retained to act as financial adviser for its corporate clients, some or all of whom may now or in the future have an interest in the contents of this document. ED produces and distributes research for these corporate clients to persons who are not clients of ED. In the preparation of this report ED has taken professional efforts to ensure that the facts stated herein are clear, fair and not misleading, but makes no guarantee as to the accuracy or completeness of the information or opinions contained herein.
There is no subterfuge intended.
Do we really want them repeating that on every post they make on Stocko? It would get rather tedious I suspect. Whether they should be posting here in Stocko forums is a legitimate debate - personally I find it useful, provided they keep it brief.
We could do without the detailed company description (intro para) clogging up the forum....just tell us you've published with a one-liner summary of the conclusion and those who are interested can look further?
Its a free world and quite rightly everyone is entitled to an opinion. After providing free high quality research and access to company management to otherwise ignored Private Investors for the small period of 23 years...I think everyone else knows what we do, with thousands appreciating it. And we post under our own name.
This is not correct “I think everyone knows what we do”
The last time we had this debate one new Stockopedia reader did not know, you can check the thread .
One is too many .
Just add the note , no reason for you not to at all .
Solves any debate
A lot of PIs won't have a clue who you are or what you do. Just because you have been around 23 years, does not mean PIs will know about you.
To be clear, it was me that did not know who 'edmonda' was at the time. And to be fair to EquityDevelopment, they changed their posts immediately on that day to include their company name and the structure of the posts which are now much clearer.
It is a personal opinion that there will obviously be a bias to the posts of ED, they are being paid to promote companies to PIs. On the other hand, they are providing a service with the information about companies that might not otherwise be available, and potentially more contact from management. I suppose you get what you pay for...
Over the last couple of years I have had a pretty steep learning curve in my investment journey, but I guess that it is like that for everyone. There is a pretty quick realisation that sources of information are not to be trusted, unless verified several times over.
One of the big plus points for me of Stockopedia is the community as much as the StockRanks + data. I think that Paul and Graham have alot of respect because of their open views, I feel that they are as objective as they can make them (obviously everyone has their own preferences, and makes their own errors). I think that some of the pushback against the 'advisory' posts is because this spirit is in some sense being abused.
After seeing the improvement in EquityDevelopments postings, I dont have any further problem, and hope new subscribers will quickly realise their slant. Hopefully they can engage further, and reply to some of the bear cases that might be in opposition to their very positive analysis.
I have to end with ... what was their fair price for Watkin Jones (LON:WJG) ?
It's been 4.5 years since we covered Watkin Jones (LON:WJG) you can't hold us to that!
OK ;o)
I am so sorry you are being attacked for providing a valued service.
Keep up the good work and not listen or listen to all the harassment here.
Hi Planetx. Another potential solution to this problem is that Stockopedia could have a separate area of their site for all material which somebody has been paid to produce. (Stockopedia staff would be exempt from this and would continue as before).
If there was a separate part of the site for it, then Stockopedia could put a well considered and standard piece at the top of it saying things like:
"Persons or companies creating posts in this section have been paid to do so by a party other than Stockopedia. Readers should bear this in mind when they are making any investment decisions."
I think this would introduce the required level of transparency, and would be better than banning or strongly discouraging such postings. Sometimes these posting can be useful, and I would not want them to stop.
Agree
This is just an easy fix .
Doesn’t need debate just need a simple and clear action And never needs to be discussed again .
Finsbury Food (LON:FIF) (I hold). One recommended by a Roland a while ago. Appeared undervalued to me. Todays trading update reinforces my view that good food producers are able to pass on costs and improve performance. It looks like the acquisition of Lees is going to plan.
“Total Group sales of £413.7m, which includes the acquisition of Lees Foods Limited, increased by 16.0% versus the previous year, and 12.6% excluding Lees. The Group delivered a strong second half performance, with H2 revenues up 17.1% versus the corresponding period in the prior year.”
Will Finsbury Food (LON:FIF) will be covered today?
Thanks. Keep up the good work.
Nice company Finsbury food .
Interesting stake building by Dbay / LDG which are closely connected .
Richard Staveley also building .
I held bit recently sold out as I was eating too many cakes doing market research on their products .
Put on 5kg in a month .!
Hi Revs8, yes, we like Finsbury Food (LON:FIF) here at the SCVR, and me, Graham, and Roland have I think all commented favourably on it, as a decent value share, and a strong operator that has been able to capably pass on cost increases. Not the most exciting of shares, but it's a solid, decent company. We'll try to cover it today.
Regards, Paul.
Hi Paul
I agree that it is not the most exciting company but maybe worth the wait? I look forward to your thoughts.