Small Cap Value Report (Wed 2 Feb 2022) - IGP, COG, BKS, WYN, BKS, WAND, CMH

Good morning!
Agenda -
Intercede (LON:IGP) (I hold) - wins an impressive contract, but it's already in the forecasts. So it's helpful, but not likely to move the price much.
Cambridge Cognition Holdings (LON:COG) (I hold) - a big contract win, coming on top of a positive trading update last week. This company is on a roll, and looks cheap to me.
Beeks Financial Cloud (LON:BKS) (I hold) - making it a hat-trick for positive updates from my small software holdings today. Revenues ahead of expectations, after a big contract win, but it's ploughing back the extra revenues into higher overheads, to drive growth - the right strategy in my opinion. This company looks quite special, but it's not cheap.
Chamberlin (LON:CMH) - I'm flagging the 31% discount on a placing announced today for this tiddler. I'm worried about market conditions getting a lot more difficult for fundraisings right now, so want to warn readers to be careful about holding shares with weak balance sheets, too much debt, and a funding requirement. Because you might wake up one morning and find you're being heavily diluted in a discounted fundraising, which also clobbers the share price. Do be careful!
Jack's section:
Wynnstay (LON:WYN) - I hold - record revenue and profit ahead of expectations for the agricultural supplier. It’s been around for more than a hundred years now, and has grown dividends consecutively for the past 18 of those. Low margins and sector cyclicality are risks, but the group has a strong balance sheet and a good track record of cash generation, leaving it well-placed to consolidate in a fragmented market.
Wandisco (LON:WAND) - good Q4 means full year results should be in line. It’s heavily loss-making though and has a history of equity dilution, while broker forecasts have been reduced recently. Market cap of nearly £200m on about £8.6m of annual revenue and £37m of net losses. Perhaps sector specialists might be able to identify an opportunity, but I’m not convinced.
Market comment from Paul
I see that US markets (especially tech) have put in a very powerful rally in recent days. The trouble is, we don't know yet whether a bottom has been put in, or whether this is one of the big rallies that typically punctuate bear markets, before another leg down. Although it is encouraging that some of the mega tech companies have put out blockbuster Q4 earnings releases - e.g. Alphabet (Google) is up 11% overnight on a positive update. Apple was similar a few days ago. Another one we were discussing here was Netflix, which fell a lot on disappointing subscriber numbers, but is now bouncing strongly.
Looking at the more speculative, over-valued US tech shares, many have rallied, but remain deep in bear territory. So it looks as if valuation is still firmly in focus. The US sets the tone for us here in the UK. As usual, in small caps, we seem to have a big lurch down when the US wobbles, then just a half-hearted rally when the US storms back more strongly. it's frustrating, but there we are - there's not enough liquidity in the UK small caps space, so it doesn't take much volume to move prices a lot. That creates opportunities, so we shouldn't complain. Recent volatility has made me realise I need to be much more agile, and take advantage of this volatility, rather than just sitting & holding for the long-term (although I'll still do that on core positions).
With the pandemic now seemingly over, then re-opening trades look an obvious place to be looking for opportunities, especially after we've just had a panic/indiscriminate sell-off. Hence travel/hospitality/leisure still looks like a good hunting ground. Although it's very important to check how much each company's share count has gone up by. Just looking at the chart, and assuming it will recover to pre-pandemic highs will not necessarily work, where a company had to enlarge the share count a lot, in order to survive during the pandemic. There are also plenty of companies out there which still need to fix their balance sheets, becoming more pressing as Govt support measures gradually unwind. Banks may be less forgiving as interest rates rise - so watch out for highly geared, precariously financed things in your portfolios.
I also think it probably won't be long before people start to factor in easing of supply chains. Getting goods in for Christmas was obviously a major bottleneck, more so than usual. Now we're over that hurdle, plus a lot of companies have been stockpiling components (which also puts pressure on supply chains short term), then I think as investors we should be factoring in supply chains beginning to ease, and looking at the upside on share prices which should feed through from that. It surprises me that markets don't seem to be anticipating this factor yet, so there's an opportunity to get ahead of the curve there, I reckon.
There are always macro headwinds & worries. Even inflation, whilst a big factor for now, should moderate in 2023, as supply chains ease, and prices of some goods could even fall (e.g. secondhand cars), offsetting rises elsewhere. However, for now, I'm keeping my focus on companies that can pass on higher prices to customers with relative ease. Hence we should be carefully scrutinising trading updates for comments on price rises & otherwise mitigating higher costs. Labour is costing more, so companies need to be more efficient. So things like automating warehouses, etc, are important to look for, I think. Which brings with it risk, that projects could go wrong of course.
Finally, interest rates. Nobody seems to be talking about huge increases here, and in the past, central banks have backed off from big rises. So it seems to me that fears here look overblown, but who can say? Nobody knows.
Paul's Section:
Intercede (LON:IGP) (I hold)
Contract win - a fair size at $0.5m, and with upside for follow-on orders. With a "prestigious independent US Federal Agency". Linked to Microsoft. Clearly good news. IGP has a stunning client list, so I'm pleased to see it win new contracts. Before we get too carried away though -
The contract was included within the directors' expectations for the current financial year ending 31 March 2022.
My opinion - encouraging news. Maybe this might stop the rot, in the long drift down in share price in recent months? IGP is now profitable, and has a debt-free balance sheet. So historic problems comprehensively sorted out. Contracts are with major organisations, especially in the US, and produce reliable & long-term recurring revenues. IF it can step up growth from new contracts, there could be nice upside here.
Cambridge Cognition Holdings (LON:COG) (I hold)
Another pleasing announcement (I reported here on 27 Jan 20222, with a positive 2021 trading update from COG).
Cambridge Cognition Holdings Plc (AIM: COG), which develops and markets digital solutions to assess brain health, is pleased to announce that it has been awarded contracts worth GBP2.1 million to provide cognitive assessments, electronic diaries, and third-party hardware for two clinical trials in neurodegenerative disease. Revenue is expected over the next three financial years.
That’s quite significant, since total revenues were £10.1m in FY 12/2021, so winning a £2.1m contract over 3 years would add about 7% extra revenues p.a. COG contacts are high margin (c.80%), so each notch upwards in revenues is great for the bottom line.
I don’t recall contracts of this size previously, so this is certainly at least one of the largest contracts to date.
My opinion - today’s announcement gives more detail, which is worth reading, and reinforces my view that COG is clearly in a sweet spot, with a big industry tailwind now driving increased use of its cognitive testing software. there are barriers to entry here, as the key data & expertise has been accumulated over decades. Cognitive testing is a small part of the overall cost of new drug development, so the big pharmas tend to stick with a tried & tested provider like COG, and there's little competition.
COG is now profitable, has plenty of cash in the bank, good visibility from a £17.0m contracted order book at 31 Dec 2021 spread over several years, that should be up to c.£19m now after today’s news - almost double 2021’s revenues. So there’s very good visibility here, hence low risk of profit warnings.
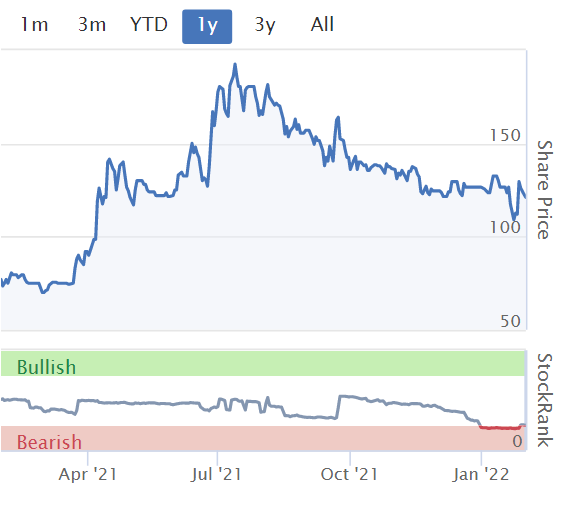
The market cap of £38m looks low to me, so I see plenty to go for. £100m+ market cap is my medium term target.
With positive newsflow, and a share price that has drifted down, this looks a good time to buy, I 'll see if I can scrape up any pennies to top up.
.
Beeks Financial Cloud (LON:BKS) (I hold)
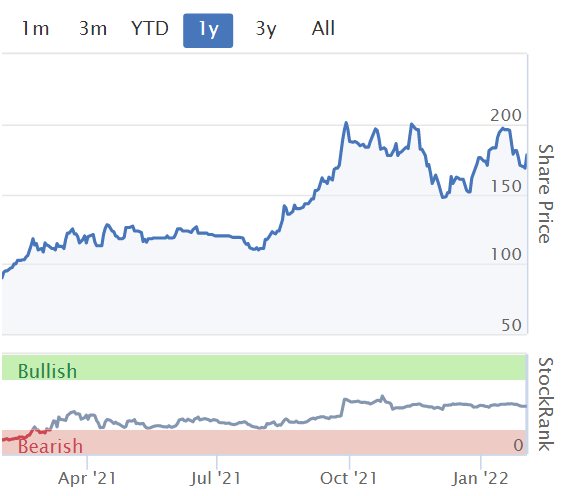
177p (up 5% at 08:13) - mkt cap £100m
$2.2m Proximity Cloud Contract Win and Trading Update Significant contract secured for recently launched offering, revenues for FY22 now expected to be ahead of current market expectations
Key points -
This new contract is spread over 4 years.
Another impressive client - “one of the world’s largest Foreign Exchange brokers”.
Proximity Cloud offering is new, only launched in Aug 2021 - so all the more impressive that it’s winning big clients - augurs well for the future, I suspect.
“Substantial pipeline continues to build” for this new offering.
Revenues for FY 6/2022 ahead of market expectations, but this is being ploughed back into growing the business, so no change to profit expectations.
Beeks occupies a very interesting niche, which is why I find this company very interesting - this provides some flavour -
With the ability to now offer fully hosted, or private cloud solutions, from the Company's network of global data centres or on client site, Beeks is positioned to cater to the requirements of all financial institutions, no matter their size, and capitalise on the rapid acceleration of Cloud deployment in financial services.
These latency sensitive environments need to be built, connected and analysed and Beeks is one of the few companies in the world that can provide this.
As a result, the Group's addressable market is extensive, with up to 20,000 financial institutions around the world, a large percentage of which maintain their own IT infrastructure and are yet to move to the Cloud computing model…
"The rate and size of new contract wins demonstrate the potential for Proximity Cloud, addressing a significant part of the Financial Services market for whom the public cloud is not sufficiently secure. "The successes with our tier 1 clients mean we are now recognised as an established technology provider to financial markets, with a track record and compelling reference clients, providing us with a strong foundation to drive our business forward.
"The prospects for Beeks have never been more promising and with a growing pipeline we are excited by the opportunity ahead."
My opinion - stock markets have turned against growth shares recently, so we have to be very careful about shares on toppy valuations. Do they really deserve a PER of 40?
In this case, I think Beeks does deserve a premium rating, because it’s achieving superb organic growth, and seems to be carving out a lucrative niche, in potentially huge markets.
Many thanks to Canaccord Genuity, which has provided us with an update note via Research Tree. It is now forecasting a fantastic growth rate of +55% for revenues - a big acceleration in growth, which reinforces my feeling that BKS is almost pushing on an open door with its superb service offering, which then produces high quality recurring revenues.
It’s not being run for profit, but for growth, but even so, forecast EPS is 3.2p FY 6/2022, and 4.5p FY 6/2023, hence the PERs are 55.3 and 39.3 - so make no mistake, this share is expensive. It’s very unusual for me to be prepared to pay that kind of multiple, but in this case, I think the high margin, recurring revenues, and very high organic growth, plus the large market opportunity & growing pipeline, do justify this type of valuation.
Any wobble in growth though, and it would get mercilessly smashed in price, so there are risks to paying up for growth.
Other downside risks which worry me are key personnel/expertise, rising salaries, and the nightmare scenario of hacking/data breach/system outages. Since this service is mission-critical for clients, it has to be totally secure, and have 0% unplanned down time.
Overall, I think there’s something special here, and very rare in the UK markets. Hence I’ll sit tight, and run this one for the long-term, without worrying too much about valuation. When you find something special, it can sometimes pay to just run with it, rather than obsess about valuation. Not something you hear often in a value/GARP column!
.
.
Chamberlin (LON:CMH)
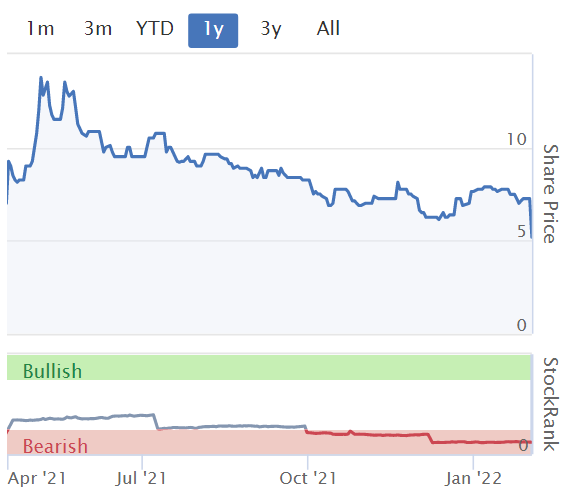
5.1p (down 29%)
No. shares: 69.6m before, +36.0m placing = 105.6m after placing
Mkt cap £5.4m after placing
This company is too small for us to normally cover here, but I want to flag it today as an example of one of my main worries at the moment - that the equity fundraising window seems to have slammed shut (as it normally does from time to time, in bearish market conditions).
Therefore any companies which need to raise fresh equity, often from a position of weakness, are not likely to get a positive reception from the institutions who participate in these things, and it’s the instis who set the price of placings too. If there’s not much appetite, then the price for support can be a deep discount, and hence big dilution for existing holders.
What I dislike about placings, is that it’s all done behind closed doors, with the shares still trading, which creates a false market. Instead, the rules really should be changed, so that shares are suspended once a fundraising begins, and all existing holders should be able to participate, not just favoured institutions. Sometimes there is an open offer added to placings, but it’s usually small, so a fig leaf.
The argument in favour of placings, is that they are relatively quick, and can allow companies to move fast if a good acquisition opportunity arises. Also, private investors can buy in the open market, if we want to increase our positions - although often the placing price will be lower than the subsequent market price, so all too often instis get an unfairly favourable entry price. That said, instis suffer from liquidity problems and can’t exit if something goes wrong, whereas we can. So there are arguments either way.
I won’t go into all the detail, but Chamberlin is raising fresh money at a 31% discount to the 7.25p share price yesterday. The share count will increase by 52% - quite heavy dilution, so existing holders will now have considerably less upside, if the share price recovers in future.
I don’t have any particular view on Chamberlin itself, as it’s too small. However, I do want to wave a warning flag to everyone here, that placings are likely to be more difficult to pull off, and at deeper discounts, in these more difficult market conditions. Therefore we need to be more careful than usual about buying/holding shares which have balance sheet issues, e.g. excessive debt, or could be in danger of breaching banking covenants, etc.
.
.
Wynnstay (LON:WYN)
Share price: 582p (pre-open)
Shares in issue: 20,311,177
Market cap: £118.2m
(I hold)
Final results for the year to 31 October 2021
Record results for the agricultural supplier, helped by improved farmer sentiment post Brexit, strong farmgate prices, and ‘exceptional’ gains from fertiliser blending activities.
- Revenue +16% to £500.39m, with ‘significant’ commodity price inflation,
- Underlying profit before tax +37% to £11.44m and reported PBT +57% to £10.99m,
- Basic earnings per share +60% to 44.4p,
- Net cash +10% to £9.24m and net assets +8% to £105.72m (£5.25 per share),
- Total dividend +6% to 15.5p.
That’s the 18th year in a row of dividend increases.
Wynnstay itself has been operating for more than a century now, with an excellent track record of cash generation and profitability despite the low margins and sector cyclicality, so it presents itself as a good dividend payer for long term income investors.

The group has a balanced business model and tends to benefit more than some others from inflation, as is borne out by these results. The earnings per share figure of 44.4p appears well ahead of consensus of 37.9p, and values the stock at 13x earnings.
I view that as reasonable value, but these results will likely have a positive impact today.
Wynnstay has two divisions.
Agriculture - revenue here is up 19% to £358.96m and operating profit is up 47% to £4.22m. Total feed volumes are 6.5% ahead year-on-year although operating profit is in line due to higher production and distribution costs.
Arable benefitted from a return to normal harvest tonnages and there has been a good Autumn 2021 planting season.
Glasson, which supplies raw feed materials and produces and manufactures fertiliser and added value feed products, has outperformed. This is due to a three-fold increase in fertiliser raw material prices in H2.
Specialist agricultural retail - revenue up 10% to £141.43m and operating profit +24% to £7.15m. Helped by increased farmer confidence and a return to farm investment after a period of uncertainty following Brexit.
Two bolt-on acquisitions, this is an important part of Wynnstay’s growth strategy, as it operates in a fragmented market in which it acts as consolidator. These have been integrated well, adding new customers and expanding the group’s trading area.
A new digital portal was launched in the first half, growing Wynnstay’s routes to market. Investment programmes to increase manufacturing and processing capacity are progressing. New senior hires have also been made, including Commercial Sales & Marketing Director, Group Engineering Manager and Environmental & Sustainability Manager.
The group’s three joint venture businesses (Bibby Agriculture, WYRO Developments and Total Angling, and Celtic Pride) have also performed well, contributing ahead of expectations.
Outlook - trading in the new year has started in line with expectations. There are challenges with rising costs but the group is ‘well-positioned to achieve its growth objectives for the year’.
Conclusion
I had an inkling Wynnstay was doing well based on previous updates, the general inflationary environment, and introduction of the landmark UK Agriculture Act reducing Brexit-related uncertainty over future financial support to farmers, so these record results in both revenue and profit are good to see.
The current level of financial support from the UK Government will remain unchanged until 2024, with a transition period thereafter, which will provide stability to the industry over the medium term. Following Brexit, the UK Government has agreed a number of trade deals with non-EU countries. Although some of these deals may also have increased the opportunity for agricultural food imports to enter the UK, they have opened up new markets across the world, at a time when global demand for food is continuing to increase.
The industry is cyclical though, so that might temper enthusiasm somewhat, but the group has been around for more than a century and understands what it has to do to grow and deliver shareholder value in the long term. It continues to invest in its business, is expanding its trading area, and is returning cash to shareholders.
A lot has gone right in order to facilitate these results, and the share price can be volatile. So if you hold the stock for a period of years then some downward pressure at some point is probably inevitable. There’s always the short term risk that poor weather or some other factor might lead to poorer harvests and performance.

The low operating margins, single digit ROCE, and cyclicality will likely always deter some investors.

But the group has a very strong balance sheet and is asset-backed. This is a significant strength and, alongside its balanced business model (which, management says, contains ‘natural hedges’ due to the breadth of activities) leaves it well-placed to weather tougher conditions and emerge from them in a position of strength.
Wandisco (LON:WAND)
Share price: 314.7p (-0.1%)
Shares in issue: 61,463,254
Market cap: £193.4m
Trading update for the year to 31 December 2021
Strong Q4 trading following significant contract wins both directly and with key cloud channel partners. Q4 bookings increased 30% to $8.4m and are up 17% to $11.9m for the year as a whole.
Revenues are expected to be in line with current market estimates.
Toward the end of FY21, the Company took steps to realise efficiencies in its business model through prudent sales reorganisation and effective cost management. The Company has a strong balance sheet, with WANdisco's year-end cash position expected to be approximately $27.8m, a 32% increase on the prior year, with $1.2m in trade receivables.
That sounds like forced cost cutting to me, rather than prudent business management. And the balance sheet does have a healthy net cash balance, but this is a result of sustained equity dilution rather than retained earnings. The fact WanDisco touts a 32% increase in cash suggests its ability to raise yet another $42m from long-suffering shareholders is some kind of operational highlight.
There are some signs of progress though: the transition to a cloud-centric, consumption-based model is leading to more predictable revenues, reduced discounting (metered pricing), and increased upsell opportunities. The cloud platform model of the "Commit to Consume" contract structure (where a customer is obligated to move a minimum amount of data over a given time) is now the standard. This helped drive strong RPO (remaining performance obligations) and bookings growth in H2 2021.
Conclusion
This is not the type of investment I tend to dig into. It sounds like some progress is being made, and perhaps the prospects are bright, but there are lots of loss-making companies that can make a persuasive pitch to investors.
The long term share price chart shows how speculative this stock is. Many will have got quite badly burned in that time frame. And even at these lows, WanDisco has a c£200m market cap on about £8.6m of annual revenue and a Value Rank of 3.

It remains loss-making. Cash burn and equity dilution are significant risks.

Shares in issue continue to rise, with money raised from equity holders pretty much every year for the past decade. See annual net issuance on the left and the cumulative total on the right below. This is a dream company for fee-chasing brokers and investment banks.

All the data points I’m seeing here suggest the company could continue to disappoint. Brokers have been revising down estimates.

I don’t have a view on WanDisco’s services, so I’d welcome any input from subscribers more familiar with the company. There are several points here that set the alarm bells ringing, statistically speaking, so I’m not convinced.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

65 comments
Latest from the FB Q4 results. Interesting data for Best Of The Best (LON:BOTB) holders. It looks like ad rates (globally, all sectors) reduced from Q3 to Q4. I infer that from the steep decline of Q4 vs FY, and the fact that most of the ad price inflation happened in Q2-Q3.
"Ad impressions and price per ad – In the fourth quarter of 2021, ad impressions delivered across our Family of Apps increased by 13% year-over-year and the average price per ad increased by 6% year-over-year. For the full year 2021, ad impressions increased by 10% year-over-year and the average price per ad increased by 24% year-over-year."
There's a better way to do this by digging out FB Q3 results but I'm lazy on my sofa at 11pm and personally, I don't think ad rates have come down in the UK in Q4. Dec was strong.
The strength in Wandisco is in its technology, not yet in its balance sheet. Although it has plenty of cash. It is the only company in the world that can transfer data from on premise to the cloud whilst its still being used, and collected on premise or cloud without interfering with its accuracy. Hence its contracts with the big cloud providers such as Microsoft, Amazon, IBM, Google, Oracle etc, who have included it in their cloud offerings. Gradually in my opinion, companies as they switch to the cloud, will realise what savings they can make, It has started to happen now, and will accelerate in years to come. Companies need to be in the cloud. It will become a flood, having a monopoly and massive moat.
I agreed with the story quite some years ago and bought in. However, after several years of management saying 'next year ...' and then it not happening. When they said "in the next six months" and then substantially disappointed, I decided the management couldn't be trusted, so sold out on a peak.
If you are an investor, I hope you are right !
What happens when all the data is migrated? Sure somethings are super sensitive but most cases you can create a geo-stretched cluster and load balance it. Which is what I suspect most organisations do and why there hasn't been a massive surge of demand - good enough, is, well, good enough.
Is it a niche requirement to have the same data on-premise and in the cloud, synced real-time? How many companies have this requirement?
And if this was "known" as a solution to the market a few years ago already, and many companies are already using cloud (see AWS and Azure revenues reported by Amazon and Microsoft), then the cloud market isn't very convinced of the need for £WAN . Otherwise their revenues would be more than the 7 digits it is currently.
It might be a shiny new toy that can flash colours and flip and do more than other toys, but not all shiny new toys can make profits?
Hi Paul, how are you valuing "Cambridge Cognition Holdings". Can you share workings?
See the archive.
EDIT: which is extensive: https://www.stockopedia.com/sh...
Here's today's agenda which Jack &* I drew up from the RNS today:
As the sun came out, I downed tools late morning, and went off to Bou'mth beach. Say hello to the goats!
Hi Guys, Would anyone happen to have any broker ratings for On The Beach (LON:OTB)? The last one I see was from Stocko in November. Would really appreciate it if any of you have it to hand. Many thanks. Paul
I'm torn in two ways by Cambridge Cognition Holdings (LON:COG) (I currently don't hold).
I first bought in June after Paul's PIWorld interview purely on the turnaround story and the news of a new order but writing that it was otherwise mad and breaking my 'no microcaps' rule. Quality 41, Value 9!!, Momentum 98, Stockrank 47, Momentum trap.
I sold in November on the news of the CFO leaving suddenly with no explanation.
I bought soon after, in December, on more positive order news and the story that management were turning the ship.
I sold again in January because I wanted the money for a different investment. It was the one to go as it had my lowest Stockrank of 21, classified as bearish and dropping, Quality 43 and dropping, Value 16 and Momentum 33 and dropping. It was on 2 short screens, including the 'cooking the books' Altman Z-score one.
I decided to cut my losses and set an alert for when it moves from micro-cap to small cap at market cap of £50m.
But I still like the turnaround story and the fear of missing out is strong.
Rules or stockpicks? The Stockopedia rankings have done well for me, but I know that they won't necessarily catch this one as they are essentially backward looking.
To buy or not to buy, that is the question. Again.
So with regard Cambridge Cognition Holdings (LON:COG) what we have is:
1. The CFO resigns with immediate effect (November)
2. Elevated bankruptcy risk (Altman Z score < 1.8)
3. Evidence of aggressive accounting (Montier score 5)
If you are going to ignore this trio of quantitative information, then I guess a fundamental data driven approach is not for you !
Well put, Epsilon! I've been bringing myself back in line by re-reading 'The Little Book of Behavioural Investing', the Naked Trader, and SIF and NAPS stuff on Stocko. So far, it's working. Rules rule!
It has driven home that, ranked by gain, from the top downwards are the stocks I bought after screening using Ed Croft's cookbook of financial ratios, and are companies that I would never have heard of otherwise.
After just over a year, subscribing to Stockopedia has been very worthwhile.
Hi Epsilon,
I think the measures you mention (Altman Z-score, and Montier score) are really useful, but they don't necessarily work for smaller companies that are turnarounds, such as Cambridge Cognition Holdings (LON:COG)
That's because the scores are calculated on the historic numbers. What I try to do, with my turnaround investments e.g. Cambridge Cognition Holdings (LON:COG) (I hold) is identify situations where the red flags no longer apply, but have not yet been reflected in the historic numbers.
So say the Z-score, with COG it's crystal clear from the recent trading updates & interim accounts, that the company is now well financed, has a decent cash pile, is profitable, and has a big contracted order book. Hence I would say the bankruptcy risk is close to zero. It would take something completely unexpected, say a massive legal claim against the company, to put it at any solvency risk.
Similar sort of thing with the Montier score. It's a red herring. I've been through the accounts with a fine toothcomb, and there is nothing aggressive at all about the accounting.
The one issue I do think needs some explanation is why the CFO resigned. That can indeed be a red flag.
Regards, paul.
Hi Epilson,
I agree with Paul Scott's comments regarding small companies and Stockopedia stats. They are historical and do not take account of turnarounds where there is a lot of recent progress with balance sheet, revenue growth and contracted order book.
If you wait for the Stockopedia report to change, you are likely to miss a large part of the price action.
Michael
Thanks for the note on (LON:IGP) Paul. If anyone is interested in this company their Meet The Company presentation from November is here
Presented by Klaas and the CFO and technical production manager. It is excruciatingly dull at times, but if you are or have sunk some cash in here it is well worth persevering. They seek to explain this quite complex subject and the strategy to move into the wider market through FIDO rather an having most of their eggs in the Fed, as this latest contract announcement demonstrates. They explain where they have come from and are trying to get to, COVID has hampered operations in Europe and Asia which should eventually unleash some pent up potential leading to the kind of success they have experienced in America. Next update not expected till June, so maybe a question of more patience as is the case with most of this market. They are possibly in the best financial position they have ever been. The UK government recently urged companies to ramp up their internet security. They talk about several important sectors especially health care. If they can just tap in to the bigger market hopefully we will see some of this much talked about 'accelerated growth' come through.
Plenty of tools to beef up internet security without having to pay for expensive third party products and I can't see how this adds much above the premium offerings from the likes of Okta and Microsoft identity products which are already license bundled. I expect this will forever be limited to niche environments with above average security requirements. I've not come across it at all in my dealings with NHS providers.
PROVEN SOLUTIONS
(LON:IGP)
Discover examples of MyID software deployments where we continue to help governments, federal agencies and large enterprises issue and manage secure digital identities at scale.
MJP. Maybe at cross purposes here? There are all sorts of attacks on companies and data breaches identity theft, ransomeware etc, which result in massive disruption and huge fines, like an oil supply in Africa which had to be closed downcast year costing millions of dollars. Not to be confused with anti virus companies supplying individuals protecting Pcs.
The Prime minister warned companies only last week to increase security.
Thanks. I work for a major IT company and have a healthy dose of cyber security as part of my day job. None of what you said detracts from the fact the premium Okta and Azure AD identity offerings secure the identity layer very well. Verified identity is pretty niche - someone's going to have to go a long way to intercept a device, and intercept the second factor and get past all the internal identity protections and access controls restricting what can be accessed, by whom, from where and then session controlling what can be cut and paste / downloaded etc.
It's widely understood that security starts with identity, it's the golden ticket after all, and from there is a whole series off cyber layered defences that stretch way beyond merely the identity layer.
It's super niche. Yes it may well be a viable business, but it's not going to rewrite internet security as we know it.
(LON) IGP, Thanks Paul for the correction. Investor Meet Company. 'Recurring error why?' Maybe its the bit after 'Meet and Engage with the company you invest in' that sticks in my memory more. I agree they are an excellent way for companies to present and answer shareholder questions. Pi World is absolutely brilliant. Director Talk is another useful interview. Personally I like to keep my distance from rose tinted bespectacled directors! I think Webinars are far better and great references, especially with IGP. Way too much to take in in one go.
MJP . Funny you should mention NHS. They have had 3 cyber attacks in recent years. The one in 2017 cost us over 90 million pounds!
Can't say too much, but an expensive identity facilitator in that case wouldn't have helped much.
I enjoyed that. Thank you Simon. You sound slightly eccentric, which I enjoy very much!! Bring it on!
I hold Intercede (LON:IGP). It has to be one of the most frustrating shares I hold. Like with most software companies, I find it hard to know how good their products are, or what they really do, beyond a vague understanding. The whole investment case boils down to whether they can meaningfully grow. Revenue has gone nowhere for years and recent profit growth has come from cutting costs (mainly staff). The current CEO comes across very well in interviews but he's been there 3 years now and hasn't delivered growth yet. I'm no expert on turnarounds but 3 years without meaningful revenue growth seems like a bit too long for me. The CEO talked about addressing revenue growth as the final stage of his turnaround but if that was missing piece of jigsaw & products were so good why not address it immediately ? This company has alot going for it. The customer list is exceptional, balance sheet strong, but no real growth yet. It just feels like it might be a bit too niche & not able to break into new markets. I'm also a bit worried that they're talking about acquisitions because that's another sign that there's little or no organic growth. Ah well, I'll keep holding for now and keep fingers crossed for a few big contracts to drop but I'm not holding my breath !
Simon, just to correct one small, recurring, error. (why?)
It is not "Meet the Company"
It's: InvestorMeetCompany - one of several excellent, free investor presentation services. I also love Mello, and PIWorld.
Beeks Financial Cloud (LON:BKS) CFO sold over 60% of his holding near the high in November - I hate seeing CEO or CFO selling out the majority of their holdings at a retest of a high. Optimism is lacking and it leaked into the share price.
I'll wait for some further SP fall.
No - you aren't really looking at this properly. The CFO sold 65,000 shares but a week later was awarded options over 195,000 shares. Directors sell chunks of stock for all sorts of personal reasons. He inevitably knew the options were coming his way and took a bit of cash for personal reasons. The amounts were small. The CFO has never had much stock and wasn't a founder.
If the CEO sold 60% f his holdings then I would be concerned but not this small sale by the CFO before his option grant. You have to look at context. Sales like this have been proven to have no bearing on share price. Founders taking out large chunks have.
Anyway, hopefully you never get the chance to get any if you're waiting for lower :)
Paul - an important point to note in Beeks Financial Cloud (LON:BKS) is that whilst it is ploughing back the excess revenue into its offering this year and next the revenues are likely to continue for many years so in 18 months time there will be a ramp up in EPS.
This is a classic P/E ratio trap I've mentioned on here a number of times. A business investing now will appear to be on a high PE but is actually growing future profits at a much higher rate than the PE gives it credit for. The PE only falls to nice low numbers when it is effectively no longer investing and thus also ex growth!
So Beeks Financial Cloud (LON:BKS) could stop the aggressive investment and appear to be on a PE of sub 20 at which point every GARP investor would be falling over themselves to buy the stock but longer term that isn't good for the business.
Morning Paul, re your market comments. Firstly excellent thought provoking material much appreciated
Re today's points - I believe companies such as Netflix will be a great barometer of household expenditure under rising inflation. Surely if you are having to decide if its "heating or eating" you have NO Budget to subscribe to services like Netflix.
An over simplification but as free household cash dries up such subscriptions will be cut. How many people desperate for a sunny holiday are now holding back as they are worrying about "heating or eating" It isn't just inflation but the worry of inflation that affects behavior
I think this an interesting point. I agree that it may impact netflix subscriber and fee growth but it is the last digital subscription I would cut. I believe its £6 or 7 a month in a world of £90 phone contracts it is small fry for a larger purportion of people than you'd expect.
In terms of the inflationary issue on a wider consumer scale I think there is certainly cause for alarm. I personally just received another 33% hike in my gas bill which I believe will take the bill for the year coming to £1200-£1300 which I Mark as well over 100% of an increase on last year. This is in a very new build to category B EPC. I shudder to think what those in less energy efficient houses are experiencing e.g. houses pre 2000s (from memory) before thermal insulation regs got to a decent requirement.
On the topic of housing: Another inflationary driver that (whilst it has been the pipeline for 2 years now) is creeping into the news is the red to white diesel requirements on building sites. This will add a decent clip to house prices, warehouses quarry materials and perhaps a whole host of other items that won't be seen until the new financial year. So I'm not sure inflation has crested yet. I handle a large supply chain and companies are passing on these price increases with a take it or leave it attitude.
Looking at the above along with upcoming NI rises, 2023 corporation tax rise qnd General inflation of everything. I get the feeling that its going to be a tough couple of years for the consumer and it is likely to be felt across much of my portfolio, which is decently weighted across retail, construction, travel & tech (in the form Samsung). I do hold ABF but a few defensives wouldn't go amiss.
The only thing that bolsters a bit of enthusiasm for the near term is the tight labour market. Wages are going up, perhaps not as fast as inflation in some industries but easily outstripping it in others. The average is 1 or 2 percent below inflation.
Wynnstay (LON:WYN) results do indeed look great although I was struck by the number of times mention was made of the exceptional contribution from fertiliser blending activities:
"exceptional gains from fertiliser blending activities"
"outperformance from Glasson, benefiting from three-fold price increase across the market in fertiliser raw material prices in H2"
"our fertiliser blending activities generated a windfall gain"
"Fertiliser blending... experienced a significant one-off benefit from the three-fold increase in selling prices towards the end of the financial year"
"Fertiliser blending activities at Glasson greatly outperformed expectations"
"experiencing a one-off boost from existing stock after sharp price increases towards the end of the second half"
"dramatic rise in fertiliser prices"
Clearly this won't be repeated so it'd be instructive to understand the size of this one off windfall. Total revenue within the Agriculture Division (which includes fertiliser) rose by 19% to £358.96m (2020: £302.58m) and operating profit increased by 47% to £4.22m (2020: £2.88m) so it's obviously been a significant contributor.
With the share price sitting at almost three times its March 2020 Covid low, there probably isn't a great deal of room for gains in the short to medium term, but as a relatively safe, income generating haven during any future inflation linked volatility, it's perhaps not a terrible place to seek shelter.
Thanks for the excellent Wynnstay (LON:WYN) write up Paul, yes superb results. There's a webinar with management on Monday 7th February at 12 noon. Everyone can register here. You'll be able to submit questions then, or in advance here.
Yesterday, Nwf (LON:NWF) gave a H121 analyst presentation, which is here, video & podcast, including the Q&A. Strong results with Fuel & Food offset weaker Feeds. H2 started with good momentum
And on Monday, Sthree (LON:STEM) presented FY 21 results. Video & podcast. A strong performance from this STEM (Science, Technology, Engineering & Maths) recruitment specialist. With STEM talent highly sought after, and as far as I'm aware, STEM the only recruitment specialist in the sector. They continue to invest in their platform to provide accelerated margins and are very positive looking forward.
With STEM talent highly sought after, and as far as I'm aware, STEM the only recruitment specialist in the sector.
Hi Tamsin, Sthree (LON:STEM) is the only listed pure STEM recruiter but Page, Hays and RWA all have tech divisions.
More importantly, combined they barely represent a tiny percentage of the turnover of fees in the sector. Recruitment is a highly diversified market and the majority of fees and certainly profits are earned by highly-focused specialist boutiques with a higher and more experienced calibre of headhunter than the banks of recent graduates that make up a high proportion of the big guns’ employees.
It’s an industry in which top performers almost inevitably end up setting up their own businesses in competition with their former employers, often as whole teams, so, aside a small number of exceptional and well-cosseted super recruiters, the largest firms trade on brand rather than talent.
I’m a regular proponent of Sthree (LON:STEM) here and long term holder. It’s very well positioned and I believe it has a good future. But regular industry rankings of recruiters by capability or profitability do not place SThree particularly high. It is better placed in DACH but the same conditions persist there.
Hi Paul can you flesh out how you see a tripling of the price of £cog please? It's good to be numbers-based rather than just hopeful otherwise it sounds rampy.
Hi Paul can you flesh out how you see a tripling of the price of £cog please? It's good to be numbers-based rather than just hopeful otherwise it sounds rampy.
You expect me to reply to that?!!! I respond to polite requests only.
Totally (LON:TLY) - been awarded a 2 year extension contract worth an extra £2.6m.
more info on company can be watched here:
Super update from Beeks Financial Cloud (LON:BKS) which has given us revenues ahead twice now already his year. The proximity cloud appears to be a very good offering for financial services with minimal competition and I can see this getting a lot of traction. Not overly cheap but given the growth, stickiness of customers, ARR visibility and uniqueness of what is becoming a must have product in FS it should, and will likely command a premium in my view, so I don't view it as particularly expensive either. Ensuring they can take advantage of this opportunity by reinvesting the revenues into the product makes sense to me. I am slightly surprised it is not up more than a few pennies this morning but I'm a long term holder on this one so hey ho!!
Super update from Beeks Financial Cloud (LON:BKS)
Interesting to contrast this with Intercede. I don’t want to knock the latter because, like Beeks, it is a profitable niche business with a blue chip client list. But my entrepreneurial divining rod doesn’t budge when I contemplate Intercede’s product and market position. Beeks, on the other hand, has me twitching like a teenager on his first visit to Amsterdam.
Intercede is lower risk and might be the better investment. But it’s filling a need for highly procurement-led customers which might be disintermediated or undercut at any point by competitors. Beeks, on the other hand, is providing the very infrastructure for its massively technology-led and free-spending cutomers’ digital transformation. That’s an incredibly sticky proposition, which, if successful, could become a sina qua non for trading operations globally. Some of that opportunity is in the price of course, but I’m along for the ride with reports from Alphabet and Microsoft showing no relent in cloud adoption.
yes and the key is guaranteed latency something that mainstream providers don't naturally focus on as it is quite specific (though not solely) to financial markets. Thus get this right and develop a good reputation and the scale of Beeks Financial Cloud (LON:BKS) offering is enormous compared to the size of the company. The value proposition has completely changed in my view now they are clearly winning business and it is all recurring.
As a follow up to Paul's comments on share counts, for newer members don't fall for the old trick of thinking in the main stock-info boxes that the number of shares held in the "avge share count" info is the actual number in issue today. For this you need to go down to the box of the corporate info (listing, directors, co. address etc) where you will find a line called "total shares in issue"
The total shares in issue is the accurate number and will reflect any recent share issuing.
For example Sigmaroc (LON:SRC) (I hold) have an average count for the year of 290m shares, but the total now in issue is 638m as they did a major buy-out of another company and issued shares to fund it (not always a bad thing as in this example).
Thanks for the interesting preamble again Paul.
On inflation, I was reading the other day that the Bank of England have around 50 economists or so and still have managed to make a right mess of forecasting inflation.
So, it seems to me that we should be very cautious about thinking that inflation will moderate later in the year and in 2023 as it seems to be hard to predict.
Some of the temporary factors may abate but others, such as lockdowns in China causing supply chain disruptions, may last much longer than we realise.
I agree about interest rates. The BOE may be too worried about the effect of higher interest rates on the heavily indebted to raise interest rates by much. But by not raising interest rates by much there is more chance that inflation will be higher for longer.
Companies with strong margins, that have a track record of managing supply chain issues well, and with little or no debt would seem to be a good way to build in some protection against these issues.
Paul. Thank you so much for your market comments. I particularly like your thoughts on the US markets and how they could influence the UK market. Also, I am sure I am not the only one with a sizeable amount in US tec. shares in my portfolio which have done very well for me over the last 5 years. It was interesting to hear you think that some of the good US tec shares may not be so overvalued as was generally thought.
Thinking of leisure and travel stocks, I doubt some of the big companies will make it to the pre-pandemic levels for many years to come. IAG and Carnival spring to mind!
TUI is possible better placed as more people prefer to have the security of a package holiday than going on their own.
I work in the Travel Industry in IT. We manage reservations. I would say, that people are straining at the bit to go on holiday after 2 years of being stuck at home, and that seems to be reflected in strong bookings. People will be cautious, to be sure, but hopefully things will improve. Speaking personally to colleagues and friends as well, they seem very keen to be jumping on cruises and overseas holidays as soon as they feel safe, and to get away this year. I think barring a black swan event, that there will be at least a modest recovery in the Travel Industry, although I agree, it will take some time to recover to pre-pandemic levels.
Possibly but considering how much they have fallen, I am confident that they are a very good buy at today’s prices. Particularly £IAG who during Covid retrenched many pilots and other staff and are clearly now in a very strong position relative to competitors .
I am loving these morning preambles Paul, very useful, please continue with these.
Best, NM
These morning updates are excellent. I follow the US stock market more so than the UK market now because ultimately the US indices move global sentiment and these updates on the previous US sessions are really good.
I am loving these morning preambles Paul, very useful, please continue with these.
Very kind, thanks Nursemaid. I only do those market comments if I think it's interesting, although am sounding like a broken record at the moment, repeating the same themes.
Above all, I do want to stress that I have no idea which way markets will go! My predictive powers are close to zero! So it's only ever just views, discussion points, etc.
Given how much positive feedback we've been getting on my general market comments, will definitely try to do more of that, and maybe put it ahead of comments on boring companies that are just in line with expectations. Although that's pretty much what we're doing now.
Thanks again for all the positive feedback, we're only human, and it makes us want to work harder for you :-)
Best wishes, Paul.
£SOM
Simple notification of holding from Canaccord Genuity Wealth, that they now hold circa 5% of company (2.7M shares).
The last Stockopedia major holder report says they held 9.8% in Dec 2020 (so offloaded around 2.2M shares over 2021). Have I understood this correctly?
If this is the case then my next question is to whom? If the shares have been dripped into the market then it wold have been suppressing the share price. If they sold in a block then who picked them up? I can’t see it.
Anyone able to assist me in understanding? If I’ve understood it correctly then it’sa plus point that the shares have been absorbed. Although you always wonder why a major shareholder is selling.
Hello Revs8, when was the RNS notification you refer to?
Hi ridavies
This morning at 6.59 on the stocko RNS feed.
Hi Revs8,
Yes thanks for flagging that Canaccord has dropped from 10% to 5% of Somero Enterprises Inc (LON:SOM) (I hold). That's usually Hargreave Hale, very shrewd stock pickers. So if they're selling SOM, I'd be curious as to why.
P.
Hi Paul
Glad I’ve understood correctly. I watch the Somero Enterprises Inc (LON:SOM) charts and flagged a while ago that I thought someone was drip feeding shares at a very controlled rate resulting in a very low volatility and tight spread.
Next obvious question is why and are they selling the other 5%?
You asked the question, why is the share so undervalued? In a previous SCVR. Now we know. The share price is being suppressed by a whale!
Staggered by the volume you and Jack are covering recently. Thank you.
Also noted your point about being more proactive when share prices move.
I came to the same conclusion and now trade around a core holding of my favourite investments.
Being nimble is one of the advantages we have over the big guys.
Cambridge Cognition (LON:COG)
Wins £2.1 contract over 3 years with existing client for trials for neuro degenerative disease.
Further confirmation for #COG reputation and tech.
Contracted Order book now £19m
Good start to the year so far
I hold
Investegate |Cambridge Cognition Announcements | Cambridge Cognition: £2.1 million contract
Wynnstay (LON:WYN) Final results.
"I am delighted to report record results in my first annual statement since becoming Chairman in March 2021. Underlying pre-tax profit* increased by 37% to set a new high of £11.44m (2020: £8.37m) and revenues increased by 16% to £500.39m (2020: £431.40m), also a record high. Both these results were significantly ahead of initial market expectations. Basic earnings per share, including non-recurring items, rose by 60% to a record 44.40p (2020: 27.73p)."
Great point - I'm a new subscriber to this service and one of the best things about it since joining is that it is full of great comments, writers and helpful content - no doubt issued by sensible people.
nice update from Beeks Financial Cloud (LON:BKS) this morning:
pleased to announce the signing of a $2.2 million contract over four years for its recently launched Proximity Cloud offering, with one of the world's largest Foreign Exchange brokers. This is another significant contract for the offering which was launched in August last year and is a new customer for Beeks, adding to the Company's growing number of tier 1 financial services customers.
and further:
Combined with positive trading with new and existing clients, this new Proximity Cloud contract win means that the Board now anticipates revenues for the year ended 30 June 2022 will be ahead of current market expectations. The additional revenue will be reinvested in the further development of the Proximity Cloud offering, to capitalise on its growing sales pipeline and significant market opportunity.
https://www.investegate.co.uk/...
I have been an holder of £BKS for a few years now. I worked in the past in the cloud business for one of the majors and if you can get this business right, its sticky from a customer retention perspective and can get a nice 30% profit margin (for a small company like beeks I assume 20%) in the longer term once the infrastructure is built out. If either acquired later or significantly bigger than where they are now I've always considered this part of my long term hold and nothing I have seen today has changed that view. The company really seems to be getting traction now and revenue is looking like it can accelerate on from here.
Very happy holder
many thanks Paul for an excellent write up. I am also a long term holder - I initially took a position based mainly on wanting to back somebody who came across as an honest, no-nonsense entrepreneur who knew what he wanted. Here is a flavour from "back then":
I think sometimes with these small-cap, innovative growth companies it really is all about the management and the "story" and perhaps less about the immediate accounting realities? (provided they can survive long enough of course!)
A few years later, we now appear to be on the cusp of securing long-term, meaningful recurring annual revenue streams and also building trust and credibility with major institutions that are re-designing their core IT infrastructure to more modern architectures. So I think there is a very good tailwind, however, am also aware this is not a pure SaaS story and thus there will be ongoing capex needs and with that exposure to supply-chain challenges and cost inflation pressures.
And as Paul highlights, a single security breach could prove devastating. Nevertheless, so far they haven't put a foot wrong - let's hope this turns into a true UK tech success story?
We had a few ill-tempered exchanges in the comments yesterday.
It's fine to correct something factually that someone else has posted. But it's not acceptable to then attack the other person & what you imagine to be their motives. Keep that kind of nonsense on Twitter or advfn please, not here.
Seeing as I have to behave myself here now, and be courteous to everyone, then so can everyone else! ;-)
Thanks, Paul.
I like when you don't pull your punches Paul!
Going back onto your commentary - I tend to agree with you, that there were some relatively cheap(er) US big tech that looked better value than some of the rubbish in the UK. I couldn't decide what to buy so I went for a basket of shares $EQQQ which I also thought would be able to pass on costs to consumers. I actually sold out of Boohoo (LON:BOO) to fund it, although I have been top slicing since the days of £4 (my in price was around £0.25 and I bought after their first profit warning), although still I intend to buy in later this year when conditions (and more importantly sentiment) improves.
Actually passing on costs are what I was thinking about last night - the hoarding of money during the pandemic by consumers has all gone. We are now at pre pandemic levels of money in the bank and with massive inflationary pressures a rate rise to boot (in April it will be worse once the domestic fuel cap is removed), so discretionary spending will be at risk in my view.
However I've relocated to Cheshire and discretionary spend here is different to discretionary spend in South London. High end bathrooms, kitchens, holidays to Dubai are common place and currently half of my road have rented a chalet with cook in Val D'Isere. I think they won't be affected as much as others.
So, as a result I'm looking at higher end retailers that can pass on any increases in price directly to consumers without it affecting margins or demand. I'm equally looking at companies at the 'other end' that will benefit from the consumer cash squeeze.
As a result I've been buying Watches Of Switzerland (LON:WOSG) and Shoe Zone (LON:SHOE) over the last 6-9 months which now both represent almost 50% of my portfolio and I should really take some off the table although I've stuck with them as: you can't get a Rolex/Patek etc for love nor money - waiting lists are massive. Equally, every time my kids need shoes, I go to Shoezone and I'm as impressed as I am when I do my shop in Lidl at the price/experience ratio.
Waiting lists for Rolexes are silly at present - however I'm not sure that helps Watches of Switzerland. I know exactly what I want and of course they try and direct you to another model they do have in stock - I don't want that one though, so I'll wait or just not buy one. Maybe a case or two of special wine instead.
There's the px of used watches which they make decent margins on which aren't available generally for your 'high street' official Rolex retailer.
I'm very long on spirits, not wines (mainly as I know nothing about it) - specifically aged whisky and more so rum.
Hello Paul,
I completely agree with you regarding courtesy and civility. It is one of the things that make the SCVR and Stockopedia in general better than other forums. Let's keep it about investing. One or two posters deserve a yellow card at least in my opinion. I really enjoy your preambles by the way but please don't put yourself 'under pressure' to do them every day because we love you 'just the way you are' . :-)
Thank you as akways,
Steve