Small Cap Value Report (Wed 20 Jan 2021) - ALU, PEBB, BOOM, ELCO, WIN, WJG, TMG

Good morning, it’s Paul here with the SCVR for Wednesday.
Timing - today's report is now finished.
Agenda - here are some updates from yesterday, which I prepared last night:
Alumasc (LON:ALU) - Trading update - big share price rise yesterday
Pebble (LON:PEBB) - My first ever look at this company. Trading update FY 12/2020
Audioboom (LON:BOOM) - Trading update FY 12/2020 - not a basket case any more?
Eleco (LON:ELCO) - Trading update FY 12/2020 - resilient performance
Watkin Jones (LON:WJG) - investor presentation is worth a look
On to today's news:
Wincanton (LON:WIN) - probably the best trading update today, materially ahead
Mission (LON:TMG) - Trading update - good recovery in H2, more than recouped H1 losses
.
Alumasc (LON:ALU)
Share price: 137p (up 21% yesterday) - mkt cap £49.6m
One of yesterday’s biggest risers, so we should have a look at it.
I reviewed its FY 06/2020 results here, but the cash-hungry pension fund deficit put me off. Pity, as it’s risen 63% since then.
Alumasc, the premium building products, systems, and solutions Group, today provides a trading update for the six months ended 31 December 2020, ahead of publication of its half-year results on Thursday 4 February 2021.
This looks impressive, especially the large increase in profitability -
Further to our AGM Trading Update on 22 October 2020, which reported a strong performance in the first quarter, we are very pleased to report that conditions in our markets have remained positive and that the Group's trading performance has continued through to the end of the first half of the financial year, with a record profit for the period being achieved. On an unaudited basis, for the first six months of the year:
· Revenue increased 11% versus the prior year to £45.6m
· Underlying PBT increased significantly, from £2.3m to £6.0m
· Cash generation has also been strong in the first half, with net bank debt reducing from £4.3m at 30 June 2020 to £0.2m at 31 December 2020.
Other points -
- Helped by catch-up demand following lockdown 1, and Govt support measures
- Won market share & “encouraging” export sales
- Margins helped by prior year cost savings of £2.4m
- Levolux turnaround going well
- Entered H2 with good momentum
- Healthy forward sales
- Mindful of economic uncertainties, pandemic & Brexit
- Market conditions positive, expecting demand to remain good
- Help to Buy & Stamp Duty could impact Q4
- Upbeat Directorspeak
- Considering resumption of dividends
Broker update - thanks to Finncap for its update note. EPS is revised up to 19.9p, for FY 06/2021, a PER of 6.9 - cheap, but remember the cash outflows for the pension scheme are substantial, so the PER is always likely to be low. That said, if profits grow this strongly & are sustained, then the pension scheme is far less of an issue, and could be seen as providing geared upside to the equity.
Forecast of 19.9p EPS is way above the existing broker consensus of 14.25p for FY 06/2021, so this looks a considerable upgrade, easily justifying a +21% share price rise (maybe more?)
My opinion - a really good update, with a positive outlook too.
I think this share could be worth readers taking a closer look at, based on my usual fairly brief review.
Please do always remember that I cover lots of stocks here, just to give a flavour, then it’s important readers do more in-depth research on the companies yourselves, as I might have missed something important due to time pressures.
It would be interesting to look into what products Alumasc makes, what competition they’re up against, etc. It looks fairly niche. Niche is good - less competition, and higher margins.
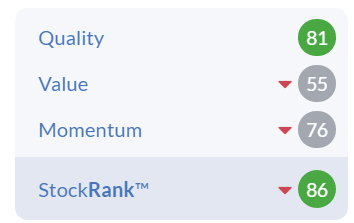
The StockRank is already very high, and could rise further once updated market consensus forecasts feed through.
.
Pebble (LON:PEBB)
129p (up 8% yesterday) - mkt cap £216m
This is a new company to me. It floated on AIM in Dec 2019, at 105p, with most (£56m) of the £79m proceeds from the placing going to selling shareholders.
It seems to have 2 businesses;
Brand Addition - design, sourcing & delivery of branded products. Not sure I fully understand this part of the business. Some case studies on the website would help.
Facilisgroup - a SaaS business serving the promotional products sector.
Director buy - the Chairman bought 108,803 shares at 130p recently - noteworthy. I like £six-figure Director buys at small caps. It can mean things are going well, sometimes.
26 Nov 2020 - in line with market expectations trading update. Confident outlook comments.
19 Jan 2021 (yesterday) - Trading update
The Pebble Group, a leading provider of technology, services, and products to the global promotional products industry, is pleased to announce that the positive momentum achieved across the Group in Q3 20, continued throughout the final quarter.
As a result, the Board now expects that the results for the full year ended 31 December 2020 ("FY 20") will be ahead of market expectations with Adjusted EBITDA not less than £9.5m.
It made £2.6m adj EBITDA in H1, therefore the above implies £6.9m in H2 - a big improvement. Note that adj EBITDA of £2.6m in H1 only turned into adj PBT of £0.9m. Sounds like it might be capitalising some costs onto the balance sheet? Yes, the interim results show £1.05m on the cashflow as capitalised “purchase of intangible assets” in H1 which is probably development spend in the software division. That’s up from £1.48m in FY 12/2019.
For this reason, EBITDA is not a reliable figure for my purposes.
Cashflow - this is a question mark. In 2019 it didn’t generate cash after exceptional items, nor in H1 2020 (OK that was during lockdown 1, so I can forgive that). Therefore, I would like to see the full 2020 accounts and scrutinise cashflow properly before being able to form a clear view on this share.
Other points in trading update -
- Net cash of £7.1m
- All major clients & partners “intact”
- Small acquisition made in Dec 2020
- “Well placed for growth in 2021”
Balance sheet as at 30 June 2020 is OK, nothing special. NTAV of £12.8m, so there’s not really any asset backing to speak of, you’re buying a stream of future earnings, not assets.
My opinion - it’s only my first look at PEBB, and I’m not madly impressed. Not for a £216m market cap anyway, which looks distinctly toppy to me.
I’ll have a look at the 2020 figures when published (due out in late March) in more detail, but for the time being it doesn’t get onto my list of possible purchases.
.
.
Audioboom (LON:BOOM)
305p (up 11% yesterday) - mkt cap £48m
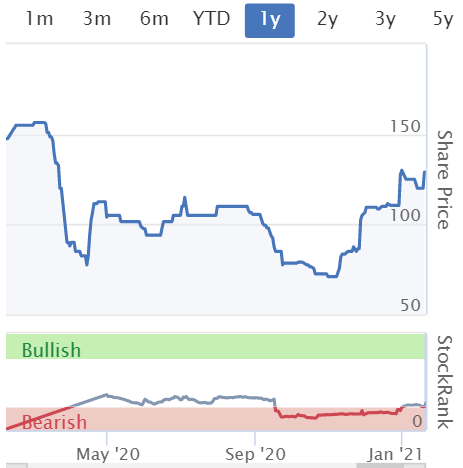
I’m quite surprised this is still going, as it looked in a poor state in recent years, with a lamentable jam tomorrow track record - rising revenues, but continuing losses. Still, let’s keep an open mind, and see what it says today.
Audioboom (AIM: BOOM), the leading global podcast company, is pleased to provide a trading update for the 12 months ended 31 December 2020.
Record quarterly performance, 20% annual revenue growth and significant year-on-year adjusted EBITDA improvement - ahead of market expectations
Revenue $26.8m, up 20%
Still loss-making, even at the adj EBITDA (best possible measure) at $(1.8)m - improved from $(2.9)m loss in 2019
Q4 sounds better - almost reached adj EBITDA breakeven, at $(0.2)m - a record quarterly performance it says
Cash looks a bit low, at $3.3m, with another $3.3m loan facility
Forward ad booking sound quite good -
The Company has made a strong start to 2021, having already signed advertising bookings representing over 50% of the current market forecast for 2021 Group revenue… it is the Board's expectation that Audioboom will be EBITDA positive for the year ending 31 December 2021.
Capitalised development spend - I was expecting to see a ton of payroll costs parked on the balance sheet, but no, this is a pleasant surprise. Looking at the last interims & full year figures, nothing seems to be capitalised, and intangible assets on the balance sheet are nil.
Therefore, the company is doing itself a disservice by quoting EBITDA as a performance measure, it should quote proper profit, which would be about the same. I am happy to help, there is no charge!
My opinion - I was expecting this to be the usual car crash of previous years. But actually it’s not bad. There’s a glimmer of a viable business possibly appearing here. Although whether it’s worth £48m is another matter.
We’re in a mad bull market for tech stocks (mainly in the USA, but some of it rubbing off here), and we see hot money causing big price moves in speculative UK small caps every day.
I could imagine BOOM catching a speculative frenzy in this environment, where punters don’t seem to care about valuation.
It’s not for me, but I wouldn’t completely pour cold water over anyone describing some speculative upside here, in a roaring bull market.
.
Eleco (LON:ELCO)
89p (up 5% yesterday) - mkt cap £73m
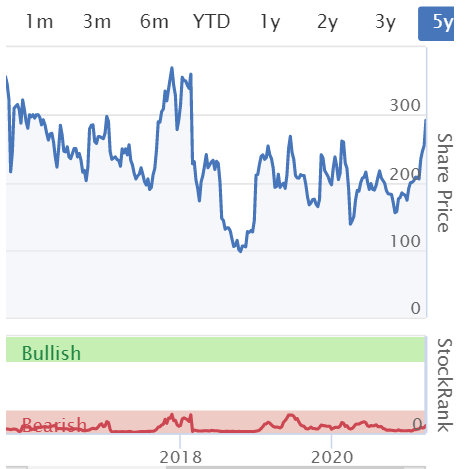
This is a decent company, I’ve looked at it several times in the past, and been impressed. It provides software for the construction sector.
Trading update - for FY 12/2020.
Revenues similar to 2019, at c.£25m
PBT at least 10% ahead - presumably achieved by cutting costs?
Covid restrictions impacted face-to-face services, e.g. training
Net cash up by £5.0m to £6.1m - looks healthy
Pleased with new customer wins & greater uptake from existing customers
Nearly completed strategic growth review
My opinion - a decent company, and resilient in 2020, which deserves a premium rating. Need to see an acceleration in growth I think, to drive the share price consistently higher.
.
.
Watkin Jones (LON:WJG)
(I hold)
205p - mkt cap £524m
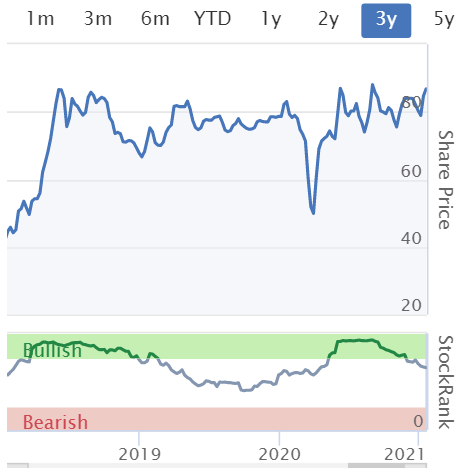
See yesterday's report for my main write up on this developer of student accommodation, and a growing build to rent division.
This is a post script, as I listened to the results presentation webinar recording last night. Two important points came out of it, which I hadn't previously realised;
1) Limited competition, because the institutions that WJG forward sells its projects to, don't want counter-party risk. This shuts out SMEs from competing in this lucrative niche.
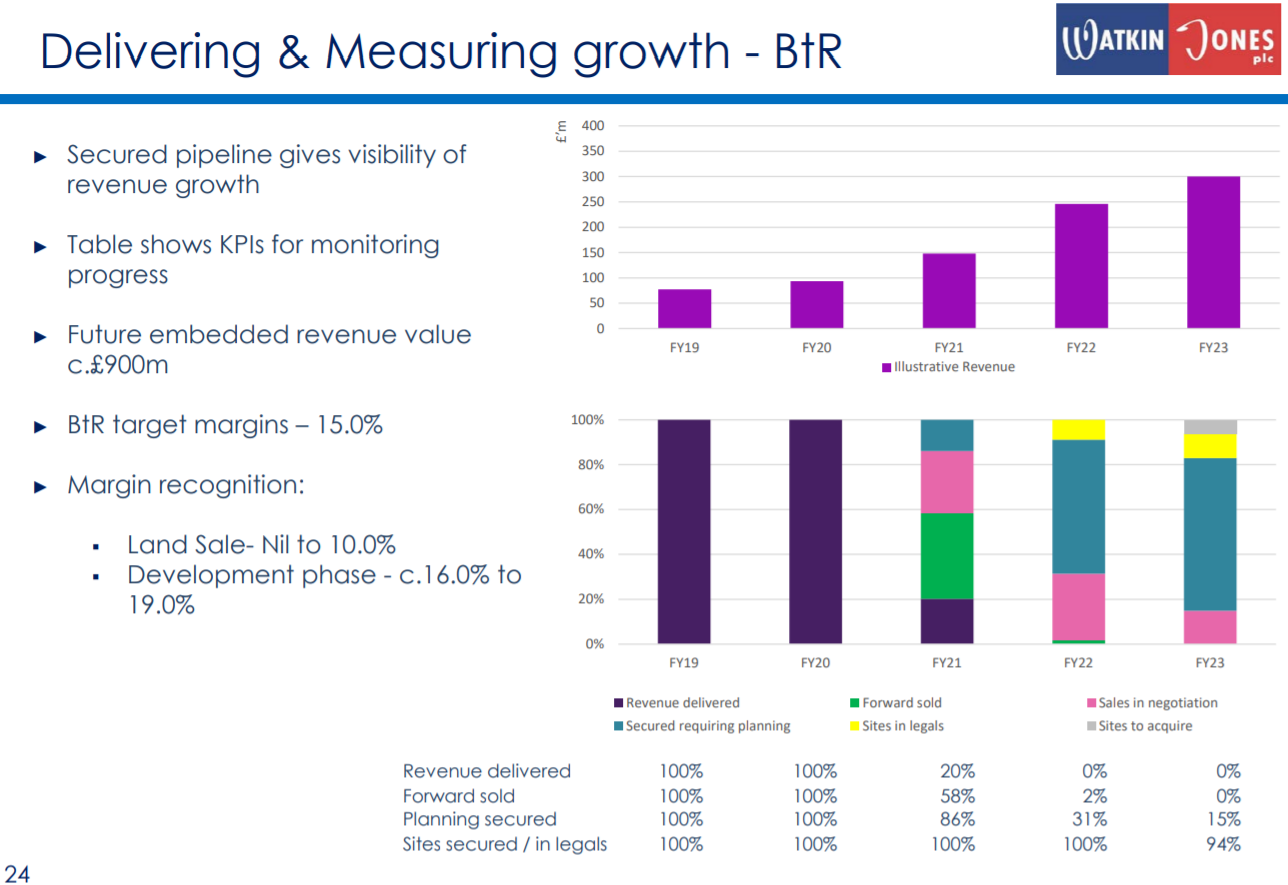
2) The pipeline of new projects has greatly increased - see slide 21 of the slide deck. Slide 25 shows that the purpose built student accommodation division has a pipeline fairly static (but up on 2020) of c.£300m p.a.. However, slide 24 (see below) shows that a big increase in the Build to Rent division is in the pipeline, mostly in the planning stage for 2022 & 2023, but secured for 2021. Therefore I think the future outlook seems promising, and should lead to increases in EPS, if projects are completed on time.
.
.
Overall, WJG shares have had a good run of late, and could be up with events for now. However, taking a medium term view over the next 2-3 years, then I think there's a decent catalyst for a share price appreciation, if earnings do rise as planned.
It's a good structural sector to be in - because there is strong demand from institutions for buying property assets that give them a yield which is linked to earnings (via residential rents). Ideal for pension funds, for example.
It's going on my list of things to buy more of, when the market has sell-off days.
.
Wincanton (LON:WIN)
304p (up 12% at 09:12) - mkt cap £379m
I wrote about this logistics company 8 times last year, being impressed with its performance, but pointing out some significant negatives - huge pension scheme with a deficit, some regulatory/tax dispute with HMRC, and a weak balance sheet. See my notes here from the last interim results. Still, we're in a bull market, and that can lead to negatives being ignored by investors who like to run with the momentum. Although remember that problems can come back to bite at a later date, once the momentum traders have banked their profits!
Nevertheless, today's Q3 (Oct-Dec 2020) update is impressive. Key points;
- Strong trading, especially eFulfilment (revenue up 40%)
- Total Q3 revenue up 10% on LY
- Recent contract wins, including Brexit related Border Clearance Centres, covid testing kits, Waitrose, and Dobbies garden centres
Overall -
The Group's strong performance means the Board expects profitability for the current year to be materially ahead of market expectations, assuming no unforeseen severe COVID-19 impact in the closing months of the year.
Forecasts - unfortunately, the brokers that report on Wincanton don't let us see their work - there's nothing on Research Tree. That's very unhelpful. How does it benefit the company by keeping PIs in the dark? We're less likely to buy the shares if we can't see any research, so it's a mistake.
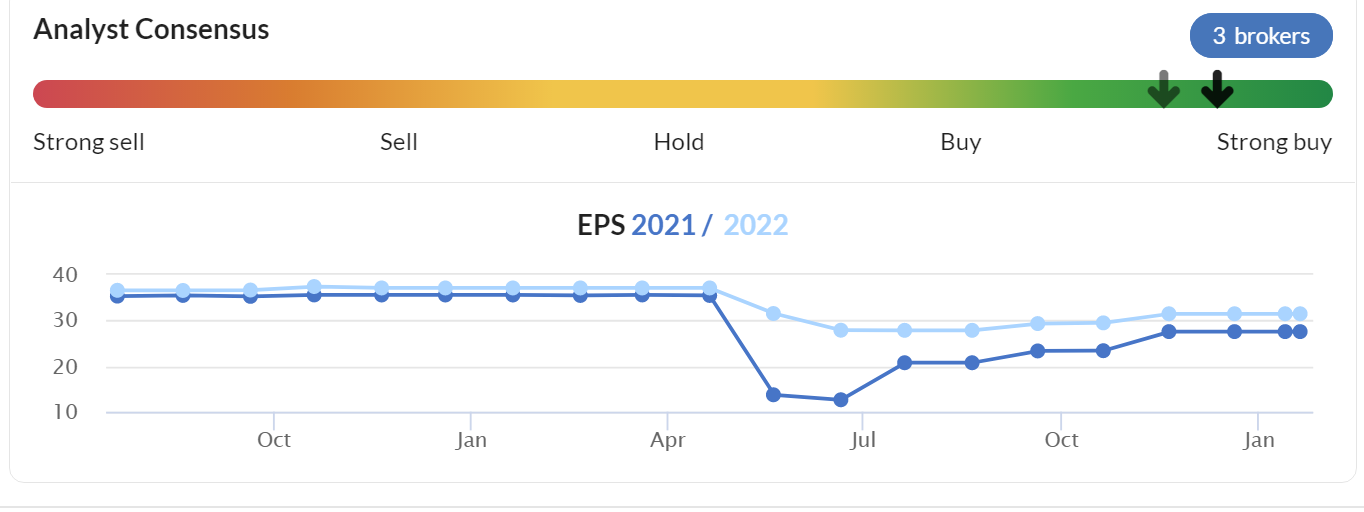
Looking at the consensus numbers on Stockopedia, note that whilst EPS forecasts have been rising since bottoming out in May-June 2020, they're still below pre-covid levels, so let's not get too carried away with the out-performing updates more recently. Allowing for today's update, it looks like the latest forecasts might be back up to pre-covid levels of around 30-35p at a guess. So that implies a PER of roughly 8.6 to 10 - good value, but bear in mind the weak balance sheet & pension scheme issues.
.
.
If you compare Wincanton (LON:WIN) with Clipper Logistics (LON:CLG) then it looks a bargain, although CLG has a better growth track record, and doesn't have the legacy issues (pension, etc) and weak balance sheet that Wincanton has. In my view both are fundamentally very good companies, so worth considering. They're probably the best 2 logistics companies in my universe of small caps.
.
Mission (LON:TMG)
74.5p (up 12%, at 11:27) - mkt cap £66m
The MISSION Group plc (AIM: TMG), the alternative group for ambitious brands, today issues a trading update for the year ended 31 December 2020.
“Strong recovery” in trading in H2, reversing H1 losses.
For context, TMG made a £(2.2)m headline loss before tax in H1. The statutory LBT was very similar, at £(2.3)m, so not much in the way of adjustments.
As a result, the Group now expects full year headline PBT performance to be over £1m, comfortably ahead of market expectations.
This implies H2 profit of over £3.2m - that’s an impressive turnaround, although clearly the economy improved a lot in H2, so I would have expected some improvement on H1.
Guidance for FY 12/2021 -
Mindful of the ongoing restrictions resulting from the pandemic and our traditional second half trading bias, we again predict H2 2021 to out-perform H1 with a return to a pre-pandemic run rate by Q3 2021, leading to a strong start to 2022.
Is that a cleverly worded profit warning for H1 2021? Maybe. I think it’s guiding us towards not expecting too much from H1 (Jan-June 2021). Although they will be up against soft comparatives, as will be the case for many companies, so H1 2021 figures could look sparkling against last year for many companies. Incidentally, Next (LON:NXT) said that it will be showing comparatives against 2019, not 2020, when reporting its 2021 trading, to show the true underlying picture. I encourage other companies to consider also giving us that information once we get into interims results season later in 2021.
Net debt - has reduced sharply to £1.3m at year end, significantly better than market expectations, we’re told. Although we’re not told either way, if the company has benefited from stretching creditors. That’s a disappointing omission.
Dividends - reinstating the 1.53p deferred 2019 final divi - good news.
Diary date - 14 April 2021 for publication of final results FY 12/2020
My opinion - this looks a decent update, it’s good to see the group bounce back in H2.
I’m not keen on its last balance sheet, overweight with intangibles from acquisitions, and NTAV is negative.
Post covid, I think companies need to strengthen balance sheets, and have permanently higher cash reserves, rather than just go back to normal, and paying out divis from a weak balance sheet. So personally, I think TMG has got its priorities wrong there, and don’t seem to have learned the lessons from the pandemic, of the need to expect the unexpected, and have financial reserves on hand to deal with that.
I’m wondering if the FY 12/2021 forecasts might be a little challenging, given the caution about H1 performance? This type of people business wouldn’t normally command a high PER either.
Overall then, it looks priced about right to me.
.
I'll leave it there for today, see you tomorrow.
Regards, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

96 comments
Given conversations on this blog re Saga (LON:SAGA), see headline below from than respected investor information source the Daily Mail.......
"Saga becomes first travel company to require all passengers to be vaccinated - as cruise customers face rush to get TWO jab doses before first voyage on May 4" https://www.dailymail.co.uk/ne...
Firs cruises also put back to start April (Ship 1) and May (Ship 2). However seems to be confidence in finding passengers so maybe an extra 5-$10Mn incremental loss at most against ever increasing likelihood of a restart from some point in Q2 as vaccines roll out. Hence prices continuing edge up. (I hold)
April and May didn't make any sense to me in terms of timings given the twelve week gaps between first and second jabs in the UK so I looked on the Saga website and that says sailings will start in May and June.
In order to allow our guests sufficient time to be fully vaccinated, we have decided to delay the restart of our cruise programme which was due to commence on 3rd April with Spirit of Discovery. Instead our programme will begin with Spirit of Adventure’s inaugural voyage on 4th May and our Secrets of Corsica and Sardinia cruise aboard Spirit of Discovery will now sail on the 2nd June. We will be contacting all guests affected to discuss their options.
I still think they are being optimistic. According to this online calculator a 70 year old with no underlying conditions will get their second jab between April 22nd and May 10th.
Yes, safe to assume May as the earliest date now.
Looking at Carnival, Norwegian, Royal Caribbean... they're also guiding around that.
But that's the minimum date. And if you need everyone on the cruise vaccinated before it sails - when are the crew getting vaccinated? They're all in the 20-30 age group....!
City of London Investment (LON:CLIG)
Like all holders (presumably) I was very happy with the TU today. Topped-up infact.
However, the RNS once again included this information:-
"The Company wishes to inform that, subject to being in an open period, Barry Olliff, Founder and Director, wishes to refresh his selling intentions to sell 250,000 shares at each of 475p, 500p and 525p. In addition, the Company will no longer provide trading intentions for Mr. Olliff post 30 June 2021, which is the Company's year-end."
This is not new news, and I was aware of his selling intentions. What I can't decide is whether this formulaic exit (it sort of sets ceilings which might put off new investors) is better than a one-off placing.(this obviously would be at a discount and have a one-off impact, but would remove the overhang in one go and then everyone can move on).
Wondered if any others had any thoughts?
Phil
Re CLIG - as you say this is not new news regarding Barry Oliff's share sales. He has set out structured selling of shares for a number of years as his retirement became closer and this seems to be his method of working.
I also hold
Re Quartix Holdings (LON:QTX) ABB you may be interested to hear that Buffetology / Keith Ashworth-Lord seems to have taken the whole 15%. They previously appear to have held 2.97% taking their new holding to 17.97%. I recall that KAL has previously divested where he was unable to get a meaningful stake so it may be that, on this occasion, the figleaf of creating additional liquidity may actually have some validity!
I've recently been attending the Mello Mondays and I was enjoying the series of presentations by Mark Simpson, so much so that I bought his book "Excellent Investing".
I've been really taken with the ideas in the book, research shows that over the long term defensives outperform and the quality and value are more important than momentum. And that small caps are where PIs hold some advantages over bigger players if one is patient enough to hold over a longer term.
After reading a few chapters, one of the things that struck me when reviewing what I am holding is just how much of my portfolio is targeting momentum and how little value I have across my stocks with only really Creightons (LON:CRL) and Warpaint London (LON:W7L) as reasonably priced defensives. Everything else is on a tear, most of it on P/E over 20 and a lot over 30+.
I then look at the comments on this board, people stating that companies with virtually zero revenue, often with barely a product to market, are going to "do a Tesla" and I think to myself - it's time to go look for QV.
So, my initial plan is to have about 1/5 of the portfolio trying to "shoot the lights out" with low value but products that are in growing sectors. I call this my "Punts" portfolio - the money I can afford to play with and am not afraid to lose. Another 1/3 or so in high quality companies that might on a stretched valuation but have good revenues, good growth and and a big, existing market to grow in, and the rest I'm going to pivot back to QV and wait for my day in the sun.
It's a shame this board has turned into a place where some people are trying to pump their crazy high valuation / low revenue stock picks, but I guess that's always going to happen wherever stocks are discussed. Thankfully this is a tiny minority. My sincere thanks to those who are trying to keep this board on topic and focused on Small Cap Value and input insightful comments.
These are obviously comments about my discussion opened below about Clean Energy which you already commented on below (I am part of the 'tiny minority' apparently), even though it included several small caps, but it is clearly an industry which is outperforming at the moment so why shouldn't people here discuss outperforming investments and why they are?
You have done this several times when I have posted here about something, even though the point of my post is not focused on the over-valued nature of the stock, rather WHY the market is giving it a high valuation and whether it is warranted.
I think it is very sad that if someone talks about any company with a high valuation it is 'hype' and you feel the need to write separate passive aggressive posts about them rather than discuss the investment.
If you don't want to join in that discussion, then don't, no one is forcing you. You don't need to accuse people of 'trying to pump their crazy high valuation' because what people discuss here doesn't make a difference to the market.
It would be nice if people could be a bit more grown up here.
Sorry Thornabian, I think the SCVR does make a difference to the Market, it's where PI's get fresh ideas and you only have to count the numbers of instances when no sooner than an enthusiastic early morning report by Paul sends a share price immediately ballistic.
You are perfectly entitled to that opinion and it is very hard to prove that either way but I would just say there are a number of investments which people have been extremely bullish on here and they have just gone lower or have gone lower after positive SCVR - I'm thinking Boohoo (LON:BOO) recently, Sosandar (LON:SOS) and some others. This isn't a criticism of the opinion of those companies, just that the positive comments here doesn't result in rallies in those companies.
The market is much deeper and it seems only 200-300 different users read this daily and sometimes less. It says a few thousand reads above but I'm sure that is each read, not new separate users because the comments and likes are usually in the tens or low hundreds.
Maybe if it was a really tiny stock with £30k volume a day but that is a very low to the average trading volume (£50m or less market cap). In addition, the companies I have been talking about have been few hundred million market cap or low billions for some so they have high volumes so the claim I - or any others - are 'pumping' because we talk about a company with a high market cap to its balance sheet is just wrong.
Boohoo (LON:BOO) is a £4Bn plus company that's extremely liquid and followed extensively by brokers and researchers.
Sosandar (LON:SOS) on the other hand absolutely was influenced by this board, and continues to be.
You're confusing anecdote with data.
And if you want to stop people of stating you're pumping (against the moderation guidelines by the way), you should state your position in the stocks you comment on, which is also stated as a requirement in the guidelines, though it appears to be loosely enforced.
"Sosandar (LON:SOS) on the other hand absolutely was influenced by this board, and continues to be.
You're confusing anecdote with data."
Sosandar (LON:SOS) has been talked about here for a few years from when it was over 30p and is now about half that, so I don't think this board has really influenced it and certainly not 'pumped it up' - that's what the data says to me. If people want to take the risk on it then that's on them and they need to do their own research. I did and didn't buy, for example.
I don't think it adds anything to say it - or any other company - is hype or not. Whether a company is expensive or not is all part of the discussion, we can't sit here and talk about bargain basement penny stocks all the time because if they are any good, their valuations will go higher.
"And if you want to stop people of stating you're pumping (against the moderation guidelines by the way), you should state your position in the stocks you comment on, which is also stated as a requirement in the guidelines, though it appears to be loosely enforced."
I don't have any stake in those Clean Energy companies, I was just opening a discussion about it.
I previously mentioned I had sold a company on here before and was then told "Nobody cares if you have sold". So there is a general issue with politeness either way.
Unless someone is actively saying "this is a buy", I think it isn't an issue because readers should always do their own research and actual discussion of the investments helps. This has just ended up taking up the board space without discussing investments.
Well, the guidelines don't say whether one should declare a position in a stock discussed when they're long or short, they state one should declare whether or not a position is held.
not nearly as much as Simon Thompson of the IC. It's basically impossible to buy at his tipped prices cos word gets out before publication and the price has soared. What's even worse and frankly shameful of the IC is that the same tips are published in the paid for "premium service" alpha report just before being ramped further in his column in the weekly mag. If I'm lucky enough to be holding one of ST's tips I generally view it as a selling opportunity.
I absolutely think the regulators haven't kept up with the digital age and aren't keeping on top of "influencers" at all. I've lost count of the number of influencers I've been made aware of on social media who are pumping stocks whilst selling down, and talking their own book. Even people with billions of AUM or billionaires in their own right.
The lack of enforcement in the US is starting to cause real problems over here too.
It's a scandal in plain sight. Come the next crash (could be tomorrow, could be 10 years from now - not predictions from this seat) there's going to be a lot of questions asked. Especially how certain people have ended up with a big chunk of Stimulus money meant to help families. All in my own opinion - other opinions vary.
There's nothing wrong with Simon Thompson or the IC promoting stocks.
As long as he discloses whether he holds them, or profits directly from promoting the stock.
If you can prove either way, I'd be happy to connect you with journalists as it would be a big scoop.
Social media influencers - that's where it gets more dodgy as many do front-run and profit from their pump and dumps, without disclosing to their followers.
Well two points. I never named anyone and didn't accuse any of those named by others of doing anything wrong and it's quite clear in my post I am being generic about the lack of oversight in the markets recently. One of the rules of justice is not just that it should be done, but that it should be seen to be done. Regulators should regularly communicate how many investigations they are conducting and some generalities about what they are investigating to give confidence to market participants they are keeping an eye on what's going on, at all levels, from small PIs to big institutions.
I do note that it is mentioned in the post I replied to that prices are seen to move before the information is published, that needs investigating, which is my point one. And by investigating, we first need to establish if the prices are moving in an unusual way before the information is published and then we respond appropriately once we know for sure one way or t'other. I would highlight there are many people involved - I used to play trading card games that regularly released new sets of cards - despite the best efforts of the producers of the game and the people they employed in their supply chain, often someone somewhere would leak images and details, it's in some human's nature to reveal a secret that isn't their's to reveal, but that doesn't mean we should accept it especially when there's gains and losses involved.
Point two, I would state that selling a tip and then releasing for free some time later that you have tipped something to allow the people who pay for your services early access at lower prices is, morally questionable. If you think your information could have the effect of moving the price, my opinion is that one is duty bound to act ethically and not create false markets. And I would say the same for any publication - they should disclose which shares they have tipped in a timely manner to all market participants. The reasons why they have tipped it, sure, keep behind a paywall, all information they use should be public anyway.
I saw an interview with one of the Market Makers (Winterfloods) who commented that they read Simon Thompson and react accordingly. Especially noticeable when most of his recommendations trade on SETSqx. I'm an IC Alpha subscriber and I haven't noticed him publishing there first.
no sooner than an enthusiastic early morning report by Paul sends a share price immediately ballistic.
I report on trading updates. It's those that move the share prices, not me!
Hi Paul, of course I'm aware of that but you are the wake-up call to Stocko's followers if you don't mind my saying so. I could be a lot richer were it not for the fact I never have any spare cash, always have to sell another stock to buy one that flags up and I reinvest dividends more or less as they come. But I do look in at 7 am every day of the week and take note.
Silver
What does he mean by long term?
I agree that momentum shares can be short term although a few do go on and on. But you don't have to hold them long term. I think Ed has done some articles on momentum which may disagree with his findings.
Do you have any facts about defensives outperforming? I'm struggling to think of any.
Have you looked at the top QV shares? Not many appeal to me. I have found QM work quite well for me. QV I did a folio of the top 20 QM shares and it did not perform very well, it was down over 50% at one time and finished around -25%, the QM folio performed much better, ending up about +20%, 3 shares were up over 100%. Although NAPs did outperform it.
I do hold some defensives but none have performed that well but they have not gone down either. Actually Begbies Traynor (LON:BEG) which I would regard, as defensive, has done quite well.
Well, that's kind of the point of Mark's book. Doing the Woodford / Buffet thing. He gives several examples where sticking it out is the right thing to do. There are many ways to make money in the markets, but most PIs lose - for every £ gained there's a £ lost (even if that loss is only an opportunity cost rather than cash).
I don't think anyone's saying "don't chase momentum" but momentum can turn, and turn fast. Mark gives good examples of how much the market grows without chasing high risk shares - and I think there's a massive difference in chasing the momentum of something like Boohoo (LON:BOO) (I hold) with good Quality and comparing that to something that barely makes any sales with high momentum. And we're talking on average right? If you took 10 tech stocks in the Dot Com era on massive valuations and 10 defensive stocks, even if one of your 10 was Amazon you'd have done better on average with 10 defensives (according to the research).
So, I think, personally having not yet finished the book, there's nothing wrong with holding some "shoot the lights out stocks", but I don't want to be holding too many of those and want to get out quick at the first signs of trouble. And QV stocks don't have to mean no growth, I bought Warpaint London (LON:W7L) at 58p Sept 2019 (and had 4.3p of dividend with another one to come in the summer with luck) and Creightons (LON:CRL) at under 30p in Sep 2018 with over 1p in dividends since then, again, with another to be paid shortly.
It's only with luck that the Covid "Black Swan" tooks months to play out (it was the most slo-mo crash ever I think, everyone saw it and no one believed it), and I sold out of my high momentum stocks and went 50% cash at the end of January last year. I bought almost exclusively high QM stocks starting March/April and doubled the portfolio since. I don't think that is sustainable and luck only gets one so far, you can't ride that train too long.
I think it's all about balancing risk / reward and not having to worry too much when the market swings against you. At the moment I'm literally not sleeping worrying about my high M low V (usually around 50 Q +-10) stocks, it's time for me to do something different. :)
I don't have problems sleeping at night, if you do then you should change your investing.
I have taken some profits, on some recently and try to keep my portfolio balanced and similar size positions. At the moment I have too many different shares but I'm trying to concentrate more this year, ones that are not performing, will get culled and the money will be reinvested into the better performing ones, as long as they are not too expensive. Yes I agree about risk reward, I have sold some of my CMC Markets (LON:CMCX) today as it does not look so good anymore, same for Cerillion (LON:CER) last week.
I do still have a fair proportion in cash.
Oh, and I forgot to add my usual regular mini disclaimer - I am an idiot and my opinion isn't worth much. I try to mention that at least once per week but I sometimes forget :)
That's okay - I'm sure we all remember even if you forget!!
Only joshing :-)
Personally, I always assess critically the argument that ANYONE presents and act or respond accordingly - anyone that decides "oh yes he's a clever chap and he says X, so the answer must be X" deserves all they get. So I think the disclaimer is unnecessary, every posters views should be treated with suitable scepticism.
Except of course for my views, which should be followed without question! I am after all a very stable genius - biggly.
LoL Gromley !
To me you are always Mr Filtronic for those three crazy months in 2018. I suspect some remember me for my vigorous defense of Plus500 (LON:PLUS) prior to them discovering the "drafting error" in their previous accounts.
Have to admit I always assume people posting on specific companies are long in them - simply because probably about 80% of my posts are - the remainder are on what I'm watching and a minor bits of random stuff I've become aware of. The reason is simple - what I hold is what I know about. I do try and follow the convention of disclosing when I hold but no doubt sometimes I forget. I do think it's worth pointing out I see very, very little evidence of ramping in this daily report (which I presume is the main reason for disclosing), but do see a lot of people wanting to hear a contrary view - the battle against confirmation bias is continual and good to see.
As you say everything should be subject to your own research - I don't even take what Paul says on face value and he's good.
Keep up the good work.
Phil
Mr Filtronic! Shheesh.
Yes those were a fun few months.
And then less so!
Thankfully I'd gone through my fledgling phase of believing I had the midas touch a couple of decades earlier so I was sized appropriately!
In the context of : "over the long term defensives outperform and the quality and value are more important than momentum."
I presume that by long term, he means that if you hold only one "type" of share (Factor if you will) over a full cycle (whatever that really means) defensives (QV) will outperform Momentum.
Whether that is actually true and whether or not it is unchanged by the much more rapid dissemination of market information compared with 2 or 3 decades ago - I cannot say.
However even if it is true; if one can judge the market cycle, then one will invest in then one will do even better by investing in the appropriate factor at the appropriate time.
Ed Croft made a similar point the last time we were all together at Mello that over the full cycle "conservative" stocks will outperform "speculative" stocks. However during a raging bull market (so called "risk on") speculative investments will roar ahead. During a bear ("risk off") speculatives will significantly underperform.
Even the pandemic hasn't really shaken the market out of the decade plus Bull market. In fact with the confluence of a good time for speculative tech & biotech stocks together with the appearance of the generation of "robin hood" investors has reinforced the bullish sentiment.
Do I think we are heading for an uncomfortable 'bust' (that may be a bloodbath for the unwary)?
Yes. Yes I do. But as ever (I wrote something quite similar a few years ago) I have no idea whether it will be next month, next year or next decade! I do know that it is closer today than it was yesterday (but only by one day).
Caution - imho - is always a virtue for investors, but I am not convinced that there is a lot of it about at the moment.
.
Thanks for the kind words IGPJ.
Just to be clear, although I am a QV investor, I do think Momentum works since there is a fair amount of academic evidence for it, just that no strategy works all the time. So momentum faces these big draw downs periodically as do all successful strategies. In fact, I’d go as far as saying that in order for any strategy to be successful over the long term it must be difficult in some way or others would arb it away.
What is key is to find a strategy that suits your unique personality since this is one you will stick with during the inevitable periods of underperformance. One of the things I attempt to do in my book is give people the sight into how their personality may affect the strategy they should choose.
That said, I agree that valuations look pretty stretched across the board. At the end of the day, regardless of how strong momentum is, a company is worth the discounted stream of future cash flows returned to shareholders. If a company is on a very high P/S it must grow rapidly for a long time to be worth buying whatever its other positive attributes such as high gross margin or strong share price momentum. In the long term, the maths on this is inescapable.
Ha, I didn't realise you posted here :)
Thanks for responding. I hope I didn't butcher your thoughts too much and I am still working my way through it, I try to do a little at a time so I can let the thoughts sink in and think about what changes I could / should / don't need to make :)
City Of London Investment (LON:CLIG) I would suggest that Asset Mgt companies rather than looking at multiples of earnings, a multiple based on AUM would be more appropriate and City Of London Investment (LON:CLIG) comes well ahead on that measure.
For me, I think the outflows from KMI acquisition is perhaps the most worrying, but I understand that the acquisition was structured on basis that clients would retain the services, their own fund performance has been good (shame that it has been so good clients have had to re-balance out)
I hold - it is a high return business, exceptionally well managed (and seems like it is continuing under new management) and plays a very healthy dividend. The marketing synergies with the recent acquisition + hopefully the general growth in the market should support fee income on what is predominantly a fixed cost base ex bonuses.
Interesting article - With an eye on retail / hospitality - Alex Reilley from Loungers sharing his view of pending doom and gloom - https://www.bighospitality.co....
Air Partner (LON:AIR) (I hold)
I personally was expecting Underlying PBT to come in closer to £12.9m so I am disappointed with today's updated.
Having said that I will continue to hold.
At the last update the company stated a normalise cash position of £15m. I take this down to £10m to account for increased receivables (during peak covid the company was insisting on cash up front + it has customer deposits).
That gives a true EV today closer to £33m.
In "normal" times the company delivered an underlying PBT between £4m-£6m.
I for one believe "normal" times will return, albeit with increased Private Jet customers.
A company:
is far too cheap in my opinion. Well, I hope so anyway.
A
I see Innovaderma Innovaderma (LON:IDP) has got a placing away raising £4m. Also proposing an open offer to raise £0.5m with shareholders being offered the chance to buy 1 new share for every 12 that they hold. Large director involvement although a majority of it is the conversion of the recent director £500k loan.
"The net proceeds are intended to be used to strengthen InnovaDerma's balance sheet, provide capital to accelerate the Company's global Direct-To-Consumer strategy and to enhance its e-commerce infrastructure and operational capacity"
Issue price 35p, "the Placing Shares and the Open Offer Shares (assuming full take-up) will together represent approximately 47.0 per cent. of the enlarged issued share capital of the Company"
Hi muzmano,
Great, thanks for posting that about Innovaderma (LON:IDP) doing a placing. I hadn't spotted it.
Here are my notes from 11 Jan 2021, where I was cautious about things until a refinancing had been done. Now it has been done, the share might be a possible turnaround situation, although personally I wouldn't pay more than the 35p placing price.
The NED converting his loan into equity is an impressive commitment.
Regards, Paul.
I'm surprised that Innovaderma (LON:IDP) felt they needed as much as £4.5m (or whatever the net figure will be).
I suppose if you are going to do it, you want to avoid doing it twice!
That's substantial dilution so I'm pleased to have sold on the first warning.
With the business hopefully now full shored up, it might start to become interesting.
However there is still the substantial write down of intangibles to be revealed and I can't help but think that will see a further reduction in the SP, so I see no urgency to be buying at this time.
Results would normally be towards the end of Feb (maybe later this year?) so once those are out might be the time to look again.
It is interesting that there was a TR1 2 days ago showing that Roger Steven McDowell now held 730,000 shares. If it's the Brand Architekts Group, Roger McDowell.
Yes, I can see it drifting down for a while. Hopefully with the cash raised from the placing they will be able to exploit the international opportunities for the current products. Investing in this share has been a hard learning lesson for me. Sold most of my holding on the trading update.
There's a "significantly ahead" TA today from £MIDW. £710m revs and £14m PBT - although Stocko here shows 2021 PBT expectation of £16.5m. Significantly ahead of rebased management expectations then.
Frustratingly there's nothing on Research tree since early 2020.
Paul commented on a "mild" profit warning back in 2019 and it made a placing funded (at 500p) acquisition in Feb 2020 (yes!). So it's still at a discount to this raise.
I put it on a watchlist as it appeared in an Investors Chronicle Alpha Quality Screen, noting at the time that it was the only company that passed all seven of the screen's tests.
It doesn't appear to be screaming value right now but clearly it is still suffering from the shutdown of events led business, which clearly will be last to unlock.
Pre Covid (2019) it made £17m and the acquisition allegedly brings (brought) in $6.1m EBITDA and cost then $46m - not too bad a price? It got them firmly into the US - the biggest AV market, and one allegedly showing good growth potential.
Net debt is down to £20m.
I'm still on the fence. Just thought I'd being it to everyones attention. Comments greatly appreciated from those doing a deeper dive!
Midwich (LON:MIDW) My son works for the company. Obviously covid hit the company hard but things are starting to look up. There as been some redundancies and still some partial furlough but as an account manager he is starting to get busy in a traditionally quiet period. No position.
Another very good statement from Galliford Try Holdings (LON:GFRD) No debt, no pension liability, order book at £3.3 billion and cash at year end of £209 million. That may include some monies owed to government and suppliers but even so, the market cap is around £150 million so not bad in an unfashionable sector. Dividend to restart with results to be announced in early March.
The most "undervalued stock of its type" as some claim? I do not know about that. I do not really like the sector at all but the big cash pile and lack of debt has kept me as a holder even though the stock has doubled since November. One key is the yield. The historical yield is over 41% but that was before the housebuilding arm was sold last year. My personal current target for this year for the stock is 220 pence (I cannot see any broker targets) but that will partly depend on the dividend of course.
Pleasing Q3 update today from Wincanton (LON:WIN) and not just growth from their E-fulfillment business. A nice business. Share price up 10% or so.
Potentially a positive cross read to Eddie Stobart Logistics (LON:ESL) from Wincanton (LON:WIN) and £CLG. As mentioned previously, Eddie Stobart Logistics (LON:ESL) is in a turnaround. Last TU was quite positive with new contract wins and the financials appear to have vastly improved. A hectic few days! (traders are riding this stock it seems). I no longer hold a position.
Certainly interesting moves in clean energy companies lately.
Companies like £CSIQ Canadian Solar (up 96% in 1yr), £PLUG Plug Power (up 474% in 6m and 1,165% in 1 yr), Invinity Energy Systems (LON:IES) (up 296% in 1yr), £TPIC TPI Composites (up 169% in 1yr), and Powerhouse Energy (LON:PHE) have seen a huge rally since Biden won and the series of government pledges around the world for renewable spending on hydrogen/wind/solar/battery technology and grid balancing which will be required from it. It is continuing into this year with near 10% moves a day on several days. I'm sure some people will think 'bubble' but the market seems to be starting the year with a big re-rating for Clean Energy and with it being the big outperformer and maybe it will be the year for renewables? We have seen that before but the political landscape does seem very different at least..
Plug Power with a market cap of $26bn and only $440mio in sales and never made a profit is certainly a stretched valuation today.
However, it did get me thinking whether anything and everything will be battery powered from a renewable source like hydrogen batteries; and maybe with solar or wind now that it is cheaper, and not natural gas too. It is an interesting idea when you dig in to the applications.
I'm interested to hear what people think, bubble or buy future valuations as it is the future? (Dare I say it, how Tesla's share price went last year)
Let the debate commence. :)
I hold £INRG ETF which tracks 30 companies that make up Clean Energy Index. Given that it is hard to select the actual winners and losers in this emerging sector, unless you are really into the tech. However, I think it is a theme that will continue to develop. I see that there was an interview with John Wagner (Morris1602) who won the 2020 Stock picking challenge, and he selected mainly Clean Energy providers.
Hi Andy,
£INRG is interesting and has a little over 10% holding in Plug Power (biggest holding), I can't decide what I think about it but it is certainly an interesting concept and the market seems to like it based on the price.
Analysts and brokers seem very conflicted about it too with JP Morgan saying it is 'richly valued' but could have an addressable market much bigger but others disagree. They seem very conflicted on it too, quite fascinating to watch.
Thornabian
Thornabian
I also bought a very small position in £CHRG Wisdom Tree ETF for battery solutions, to get exposure to the emerging and existing Battery companies. Appreciate its not a small cap, but for info. DYOR of course and swipe down if no interest.
The Canadian fuel cell company Ballard Power is reported to be looking to raise finance via green bonds to make acquisitions, looking particularly at Europe where:
There are a “handful of very strong companies, some of them in different parts of the value chain."
Yes not surprised with the big spending coming from Germany (10bn) on battery technology too. There are a few interesting battery companies emerging but could end up with a lot of competition and consolidation later down the line.
https://www.reuters.com/articl...
I’m thinking this the Small Cap Report and multi billion companies are best discussed elsewhere.
A number of them are not even one billion - Invinity Energy Systems (LON:IES) is £160mio market cap, I included larger ones because you can't discuss the market without discussing the whole market and the competition.
Clearly a good profit in recycling batteries.
I see Air Partner have a trading statement out today which actually given the times is pretty good. I struggle with these shares. I like the look of the company but it is just in the wrong sector for me. Yet even in these times it says it will be turning a profit before tax of no less than £11.5m for the full year. Not much to go on but guddang!!
Hi Paul,
Thanks for writing up those sections last night, the SCVR is always an interesting read.
Would it be possible to look at Mission (LON:TMG) ? I was surprised that they were able to be profitable in the current market, I would have thought companies would be reducing marketing spend? The reduction of debt was nice to see too.
Yes, I'll take a look at Mission (LON:TMG) a bit later.
Thanks Paul
J D Wetherspoon (LON:JDW)
the company has fallen on its sword for the second time since lockdown here and issued some more shares giving part of the company away. It's probably not totally unexpected but it's an indication that bods who hold shares in other similar companies might not be over the worst of it if they are seeking to avoid further dilution in their shareholdings.
The shares now stand at 1230p compared to 1120p issue price - nice little earner for Investec bank.
The only good news is that they have got this fundraising away at higher price than the previous one.
Perhaps the company will once covid is over make amends and do a sharebuybacks when the good times return - they had done a fairly decent job until recently of reducing the share count - something we so rarely see here with uk listed companies - Next being the main standard bearer in that regard. Obviously share buybacks only ever work if the future prospects of the business are reasonably bright - sharebuybacks tend to go wrong where the future prospects of the business are not so bright.
RE: J D Wetherspoon (LON:JDW)
This placing isn't just about protecting the business but also picking up distressed pubs on the cheap. Although personally I'm not particularly joyous about that it makes sense at a business level. If I was an investor this is the behaviour I'd want to see - I can accept a small dilution now if it will lead to above average earnings in a couple of years.
I'd also note that the scenario planning laid out in the placing update is a model of good practice for companies. That said, it would have been rather more palatable if Tim Martin hadn't spent shareholders' funds producing propaganda berating the government for not following the Swedish model of how to deal with CV-19 ...
timarr
J D Wetherspoon (LON:JDW)
This placing isn't just about protecting the business but also picking up distressed pubs on the cheap. Although personally I'm not particularly joyous about that it makes sense at a business level. If I was an investor this is the behaviour I'd want to see - I can accept a small dilution now if it will lead to above average earnings in a couple of years.
Thanks for that timarr - i had completely missed the bit about potentially increasing estate size with part of funds raised - i also missed the trading update ! - so to the extent that funds raised are to be aggresive in that space at present i am 100% behind these plans.
I'd also note that the scenario planning laid out in the placing update is a model of good practice for companies. That said, it would have been rather more palatable if Tim Martin hadn't spent shareholders' funds producing propaganda berating the government for not following the Swedish model of how to deal with CV-19 ...
I am a fan of JDW shareholder no no nonsense communication (one can ignore waffle) . I will fully tolerate Tim Martin's rant's on the basis that he has earned the right to rant - and most of his rants kinda make sense if we ignore the somewhat OTT brexit ones :). Ref the swedish model of covid everyone has their own opinions in that regard - i think generally speaking the numbers they have produced ref the covid transmissions going through their pubs have tended to suggest that their outlets havent generally been more risky than most other areas of society - i do understand why the pubs are the easy fall guy in that regard though being a completely discretionary psatime.
A bit like next - wetherspoons do seem to be able to generally see the bigger long term picture with regard to what will do best for shareholders long time - whether that be reducing share count as they previously did or increasing the freehold % as they have been doing recently. I sometimes wander if some uk plc boards make decisions more like politicians than part business owners. Looking at the latest freeholds stats they have done a great job behind the secenes upping the level of freeholds they have in the last 10 years - as long as they can mange the extra debt (not gone so well this year :)) - having the freeholds for them to me is a complete no brainer for most large established sites in busy areas. If they had fresh new board faces every few years would these fresh new faces be sitting down and thinking about the pircure for teh next 15 years - not very convinced. It bizarre how their way of working in seen to be at odds with good corporate governance in that experienced bods only have limited shelf life before they should be moved on.
ref freeholds
PropertyAs at 14 January 2021, the company had 872 pubs which were able to trade in the absence of lockdown restrictions. 64.3% of the company's pubs are freehold. This has increased from 41.3% in FY2010.
Up until 2020 their policy of buying back freeholds was an excellent way of improving shareholder value - translating cheap loans into a valuable asset on the balance sheets while lowering fixed costs in a highly cash generative business allowed them to improve EPS year on year and I've been a huge supporter of £JDW.
However I do wonder if the lease model like Revolution Bars (LON:RBG) may prove to be an advantage going forward. Pub groups have delayed or simply not paid landlords, performed CVAs and renegotiated lower rents or walked away from unprofitable sites while JD has been rather constrained to continue paying the bank on the loans. Consumer drinking patterns are going to be significantly different after CV19 and the locations that worked well before may not be the same afterwards - consider how public transport will work, central London location pricing, after office drinks, students studying online, pubs supporting retail shoppers, tourist levels and behavior - for all of these and more the new world will probably be different with massive footfall changes around our cities and pubs will have to adapt. Owning the site may make this difficult.
On the other hand, J D Wetherspoon (LON:JDW) say they haven't revalued their estate since 1999 (really surprised to find out this was allowed by their banks) so you would guess even with current values of pubs being depressed there is probably a lot of value hidden in that balance sheet.
I don't think this was mentioned yesterday. but Tim Martin is not the only one raising cash to buy up pubs.
Ex Green King boss raises £200m to invest in struggling pub companies
Bidding war coming for the Nags Head?
Lovely Jubbly Michael.
This buyback just shows me how little I understand the stock market. J D Wetherspoon (LON:JDW) issued 15% last year and another 7% today so roughly 23% of shares issued. Company is no longer trading at that big a discount to Pre COVID pricing despite building debt, burning cash for a year and still some doubts about how the CV19 future is going to play out. The shares were issued at a modest 5% discount but shares rose on open.
The market seems to be buying into the vague references to buying pubs on the cheap with the money, perhaps seeing the traditionally strong balance sheet of J D Wetherspoon (LON:JDW) leaving it in pole position to capitalize on a restart versus competitors.
Interestingly as read across, J D Wetherspoon (LON:JDW) best case for reopening is 31st March and worst case 3rd May. They see trade being totally back to 2019 levels in 2022. I don’t believe a word of it...
J D Wetherspoon (LON:JDW) .
Agree with your caution. Presumes Covid effect will disappear and everyone will return to previous behaviour. Not sure of either. There's worldwide worry about mutations escaping the vaccines and Israel seems to be indicating their impact is much lower than expected (though I'm not sure how there’s been time for them to be effective). And will as many customers have the money and desire to spend the same as before?
All I know is that a steel spring can only be stressed so far before it stays bent or snaps and so it will be with Covid lock-downs and other restrictions. I'm thinking something will give before May is out. Apart from looking forward to indulging myself in one the 3 Wetherspoons in my area.
J D Wetherspoon (LON:JDW)
Company is no longer trading at that big a discount to Pre COVID pricing despite building debt, burning cash for a year and still some doubts about how the CV19 future is going to play out. The shares were issued at a modest 5% discount but shares rose on open.
All i would say here is that up to now the company hasn't actually been building up debt from trading losses - and thats before the proceeds of the latest fund raising - so there is a chance the funds raised could roughly match their "trading related" covid losses once we exit lockdown. It is a somewhat murky picture though as to what the overall cost will be - you sould turn out right if lockdown carries on well into this year.If we do take the viewpoint that funds raised cover trading losses then the reduction simply due to extra shares only does seem about right in arough and ready fashion. Certainly they may exit covid with less competition and more chances to up margins that being the case.
per the tuesday release
Net debt plus trade and other payables have remained at approximately the same levels from the year end 2019, as shown in the table below:
Yeah, I'm not clear I fully understand it (does net debt include the tax deferrals they talk about?). But clear that if they raised £138m at end of April and net debt is at best the same as then today, then that money is gone and has not in any way created shareholder value. Note as well:
- Capital Expenditure. In the financial year to date, to 14 January 2021, £22.0 million of capital was spent on the development of a small number of pubs, the completion of a number of freehold reversions and on IT and maintenance projects, a substantial reduction compared to previous years. The equivalent capital expenditure for the same period in FY2020 was £127.5 million.
- Repairs and maintenance. Repair costs have been reduced from a weekly run rate of approximately £1.6 million pre-Covid to approximately £0.25 million per week during the closure period.
Some of above 2 items will be OK because there is less wear and tear on the premises - however, pub buildings are cash hungry things and a lot of the "savings" above will simply be deferred into the next few years.
They see trade being totally back to 2019 levels in 2022. I don’t believe a word of it...
But why not? After the Nov lockdown ended, pubs were thronged. So much so positive covid cases leapt, and the government had to do a massive full u-turn and shut down... you guessed it... pubs again.
We have a nation of alcohol loving people (stretch too far to call them alcoholics?). Who like beer. And sitting in pubs with their friends and family (or alone). JD Wetherspoons occupies this niche. Cheap beer, for those that need to drink frequently.
J D Wetherspoon (LON:JDW)
I hesitate to add a post that is only vaguely related to small cap shares but I wanted to, in a polite way, respond to this.
Before I took early retirement in August of last year I spent the last 20 years of my career in the charitable sector, and during that time came into contact with many alcoholics. I have also been a regular user of pubs for almost 40 years. The fact is that very few alcoholics drink in pubs. They either do it on their own at home or, sadly, on the streets or in parks. Pubs, or at least the sort that we as private investors might be interested in such as J D Wetherspoon (LON:JDW) or Fuller Smith & Turner (LON:FSTA) or Marston's (LON:MARS) , would soon bar them anyway. Their managers have reputations and licences to think about, plus not wanting to offend regular customers who drink sensibly and spend money on meals as well.
Regarding Saga (LON:SAGA) , as a reasonably affluent 57 year old I would probably be in its target market for a cruise, and I must admit I quite fancy the idea of one. But I'm not likely to get the vaccine until late summer at the earliest, so even if the cruises start in April or May, for the time being I would give them (excuse the pun) a wide berth.
Gostevie
I refer here to £AGL. There is another very positive report from yet another research centre, this time in London, Ontario, Canada. This is not the usual posting, and I dont want to waste readers' valuable time. However, I think that in the next year, with FDA approval in the USA expected Q2, the company's great alternative to physical biopsy (Parsortix) in the diagnosis and treatment of many cancers, including breast, ovarian and prostate, should take off. I admit to being puzzled as to why it hasnt already, given the potential size of the market opportunity, not to mention the huge advantage to the cancer sufferer, but........I am not the scientist! To avoid taking up too much space here, I intend to use the excellent Stocko Discussion facility on the Angle (LON:AGL) page for future comments, with just a reference here. Thank you for interest here from JimMcLad, John Eustace, Quilleron, rogerh on the 11th and 12th of Jan, and the response to Quilleron's e-mail posted here a few days later. I look forward to Angle (LON:AGL) joining my multi-bagger league table. IMHO, it deserves it, commercially and ethically.
Angle (LON:AGL) looks to me like a convincing incremental advance rather than a genuine medical breakthrough. Goals in cancer management from the population health perspective are effective screening for pre-metastatic detection and subsequent diagnosis and treatment. Something like 80-90% of deaths in oncology are from metastatic cancers. Reaching the patient before cancerous cells hit the blood is definitely preferred, and Angle (LON:AGL) tech doesn't eliminate the need for biopsy on pre-metastasis solid tumours. It screens cancer cells in the blood which are usually metastatic indicators. It's a convincing tech, but not a game-changer in my humble opinion.
My pick in this space would be Polarean Imaging (LON:POLX) (I hold) whose polarised xenon units increase efficacy of lung MRIs by 1000s of %, raising the possibility of screening for lung cancer, plus they sell the polarised xenon for recurring revenues. Also awaiting an FDA decision.
Deleted - somehow posted twice.
Angle (LON:AGL) I would have to argue that Parsortix is a game changer from both a detection and especially ongoing treatment pov. (I hold). I’m also happy to follow ridavies idea of moving this thread to the Discussion area. To give one example of the system’s capability from a published paper– a lady in the USA had opted to have a ‘preventative’ double mastectomy and hysterectomy as there was a history of cancers in the family. Her doctors had found no evidence of disease but she was adamant they proceed. In parallel it was agreed a blood sample would be put through Parsortix which gave a positive result. Only after a tissue biopsy was carried out after the main surgery did they find a cancer. I understand single CTCs are an early cancer indicator, clusters show metastatic acceleration.
Also happy to move the thread to the Discussion area, though not sure how. It seems to hold a lot of old postings going back to 2011. Interesting reading through the first one from 2011 that Parsortix was intended to come to market many years ago...
For those interested in Angle (LON:AGL) you might want to watch the upcoming webinar on 27th January. The links to accessing the webinar can be found by visiting the Angle website https://angleplc.com/
WEBINAR: A technology review of CTC harvesting methods – what are the differences and why does it matter?
AGENDA
I did hear back from Angle (LON:AGL) which was pleasing and this is what they said (probably some of what will be covered in the webinar):
"There are several differentiating features between Guardant’s technology and approach and those employed by ANGLE.
Guardant, together with other larger companies focused on the liquid biopsy space (Grail, Foundation etc) analyse fragments of dead cancer cells known as circulating tumor DNA (ctDNA). They are all essentially using the same technique which is to extract the plasma which contains the ctDNA and then undertake next generation sequencing analysis. The utility of this analysis is limited to analysing DNA alone and cannot be extended to RNA or protein analysis (since it is looking at tiny fragments of dead cells). ANGLE’s patented Parsortix platform, which captures intact living cancer cells and harvests them for downstream analysis, can provide this potentially valuable RNA and protein information, which is important for informing decision making during clinical trials and treatment options in a clinical setting. Further, as we capture intact cells then, unlike ctDNA, these can be cultured for multiple uses including drug testing and we have also had key opinion leaders with breakthrough research in relation to CTC clusters which have been shown to have up to 80X metastatic potential. The liquid biopsy market potential is huge and we believe there will be multiple winners as the most appropriate technique will depend on exactly what you are trying to achieve.
I should point out that, whilst differentiated, we do not view these approaches as mutually exclusive. The companies focused on ctDNA are all potential customers for Parsortix, since the same blood sample from the patient can be used both for ctDNA and for CTCs if Parsortix is used.
In addition, all the big liquid biopsy companies operate as service laboratories which receive and can process blood samples and analyse them, but they do not have a product that can be sold to hospitals. Parsortix, in contrast, offers (i) patented product sales and the hospitals can analyse the patient samples themselves (which is what they would prefer to do so they can retain the value of the test) and (ii) we are also now setting up clinical laboratories of our own to speed up adoption of the technology as an accelerator and demonstrator."
FDA must be a foregone conclusion and seems they still have a long way to go to generate the revenues that would justify the current valuation.
I’ve asked £AGL if the Webinar will be recorded and made available on the WEB site - I’ll advise on response.
Multibaggers with 10 Bagger Potential - CMC Markets (CMCX)
forecast revised upwards, see link below.
https://www.stockopedia.com/co...
BSV
Good morning Paul,
TP group, #TPG announced last week that it was looking at offers being made for its marine division and has subsequently engaged professional advisers. It passed with virtually no comment here and yet the value of the division is a significant part of the £50m MCap group producing over £5m profits. I have been following progress for several years now and have been buying on dips as the bigger picture has emerged. I believe that this is a pivot point for the group when significant value will be crystallised so an excellent time to direct investors to do independent research.
TP group has stated that it wants to be the company that national infrastructure & security organisations rely on to solve their most pressing challenges, transform how they operate in an evolving world, and be trusted with their most valued assets.
The group has engaged with advisers to assess the return of possible divestment of the 'original' marine engineering business comprising lucrative existing and forward contracts with the Royal Navy and other national submarine fleets.
The CEO, Phil Cartmel, took the initial business Corac and added the maritime engineering division after realisation that Corac was too R&D intensive. He has spent the past 5 years acquiring five speciality businesses that have now achieved the critical mass to operate as a cohesive and progressive offering. They have a multitude of capabilities, and the more I research each component part of TP the more I see the overall objective having been met. Whilst each is specialist in its own field, there is a huge amount of peripheral overlap in Osprey, Polaris, Sapienza, Westek and ALS. Given the fact that the maritime business has allowed TP the kudos, respect and provenance to engage with many high-barrier-to-access players and projects I can see the space that PC wants the company to occupy. I honestly believe that the group has now achieved the critical mass it needs. Maritime, whilst being the catalyst for this transformation, has now become perpheral; valuable, but peripheral. The dilemma is now that by selling the maritime division, the combined remaining assets are very valuable as a skillset not just to TP but to many other predators. Apart from an offer for the maritime division, we could well see a bidder for the maritime-divested assets or indeed one for the whole group. I believe that this is going to get very interesting as the more I research TP group comapanies and their overlaps, the more I see a wealth of hidden value in high-growth green and ground-breaking areas and technology.
Northstar is the technological platform around which many of the other skillsets can input. If my research is correct I see all parts of the ex-marine group contributing to autonomous spacial navigation and awareness in three dimensions - below sea, on sea, on land in air and in space. Exciting projections as each of the component divisions has valuable input and the potential for the whole is considerable.
Your comments would be most welcome. There is considerable information online especially concerning Northstar. Thanks.
Very nice post..seems like you have done plenty of background work on the makeup of the Maritime business. Might be of interest to the likes of Avingtrans. I have been thinking of a top up in this for a while. Like you I 'inherited' this from a badly made purchase of Corac.
This is quite a common theme at the smaller end..disposing of cash hungry manufacturing type operations to focus on the more value added such as Saas.
In fact another example of a company doing similar is Eleco (LON:ELCO) (see above). You don't have to go back too far to see that they had a range of building products companies which they sold out of.
Feeling a bit chipper with decent enough updates on a couple of holdings IQE and Pearson, and a nicely timed first time position in Angle made yesterday.
If IQE can turn off the spending taps it could be a good one for a move back over three figures..one of the UK's few high tech companies. They certainly have a lot of kit in situ.
I sold out of AIR as well, wish I had waited. The recent lockdown is most likely good news for them.
The gripe I have is that why are these results underlying? If it was the other way around and the pandemic harmed them, the losses would be booked as exceptionals.
Seems obvious to me that the repatriation flights and other business came at a great profit - the government were being price gouged over everything it seemed in the early days of the pandemic. Paying millions for a 747 home must have seemed great value compared to some of the mask deals it was cutting.
But that sort of stuff seems to be a one-off and unlikely to be repeated. I somehow doubt they will dare separate the profits out as it'll make bad press.
Re AIR. I sold this morning. In all honesty I was expecting a drop , so glad to escape with a modest profit. Two funds have reduced holdings this week. They seem to have given as little info as possible when I would have thought there would have been quite a lot to tell the market. This update was just a reiteration of the last one confirming modest profit. It beat expectations because of the 10 million profit in the first half. Admittedly there will be a further update next month, but this was making minimal communication with the market a new art form!
I think there could be more demand out there other than the obvious covid related work. The complications with brexit/trade rules could create some consistent demand. Also when you consider airlines globally are not expected to pick up to 2019 volumes until 2024. Then there is significantly less supply of freight options available.
this site is a great source to read across into the sector. https://www.lloydsloadinglist....
Re Air Partner (LON:AIR), (I hold) emergency repatriation flights are part of their core business activity, as is arranging freight flights at short notice, so I can't see why they should be excluded from underlying profitability.
What we are seeing here is that the group's business model is more resilient than the market is giving them credit for - such short-notice activity compensates for any drop-off in the bizjet bread & butter stuff. Though I think there is plenty of scope for demand by HNW punters for biz jet flights to surprise on the upside this year.
My morning smallcap tweet: WIN winning, Ridgecrest buries holders in new paper
MJ Hudson (LON:MJH) Supply@Me Capital (LON:SYME) Capital (LON:CAPD) Deltex Medical (LON:DEMG) Tekmar (LON:TGP) Wincanton (LON:WIN) Deepmatter (LON:DMTR) Faron Pharmaceuticals Oy (LON:FARN) Air Partner (LON:AIR) Ridgecrest (LON:RDGC) Argentex (LON:AGFX) Sabien Technology (LON:SNT) Hornby (LON:HRN) Mission (LON:TMG) GetBusy (LON:GETB) IQE (LON:IQE), RPS (LON:RPS), Galliford Try Holdings (LON:GFRD), Bonhill (LON:BONH) [Edit] Surface Transforms (LON:SCE)
MJ Hudson (MJH) allows CEO more time to repay a loan made in Dec 2019 to buy shares. The NEDs and Nomad think this is 'fair and reasonable'. I don't. [SP=48.36 Cap=83m]
Supply @ME Capital (SYME) Shariah compliant Inventory Monetisation Platform approved by the Shariah scholar board. CEO says "I'm thrilled." [SP=0.52 Cap=170m]. I'm short.
Capital (CAPD) CFO scarpers to return to South Africa for personal reasons. He is thanked. [SP=62.5 Cap=118m]
Deltex Medical (DEMG) guides FY(Dec) rev £2.4m (£4.3m). Hit by reduction in elective surgical procedures as expected. [SP=1.96 Cap=11m]
Tekmar (TGP) wins contract worth over £4.5m to supply products to protect subsea cables. [SP=61 Cap=31m]
Wincanton (WIN) guides FY profit materially ahead of market expectations as Q3 rev rises 10%. [SP=272 Cap=339m]
DeepMatter (DMTR) sells multi-year, limited-use data licensing agreement to Merck to provide proprietary chemical structure and reaction data content. No £££. [SP=2.35 Cap=22m]
Faron Pharmaceuticals (FARN) bexmarilimab shows early signs of efficacy against cholangiocarcinoma, the fifth cancer to respond. ""The new discovery of the role of soluble Clever-1 as an immune suppressive molecule is striking." [SP=345 Cap=162m]
Air Partner (AIR) guides FY(Jan) U/L pretax at least £11.5m, ahead of market expectations. [SP=67.8 Cap=43m]
Ridgecrest (RDGC) the cash shell makes £2m placing at 0.6p, a nasty 57% discount, for working cap and "assist it in identifying and pursuing acquisition opportunities." 4x dilution and of course the board get options to g'tee continuing brilliant perfrmance. [SP=1.35 Cap=2m]
Argentex (AGFX) vaguely informs that trading has continued to improve. CFO resigns, three month handover. She is thanked. [SP=127 Cap=144m]
Sabien Technology (SNT) fails to get regulatory approvals for the proposed RTO in sufficient time to avoid AIM cancellation. The withdrawal allows co to stay on AIM. Issues convets of £1.25m (strike 0.05p) to keep the lights on. Shares resume trading. [SP=0.19 Cap=3m]
Hornby (HRN) Q3 rev up. No numbers. Guides FY rev up 15-20%. "January to date has been a slower start that we would have liked" due to lockdown affecting warehouse and Brexit delaying couriers. "We have now largely worked through these issues and will start shipping to Europe imminently." [SP=66.2 Cap=111m]
Mission (TMG) guides FY(Dec) pretax over over £1m, comfortably ahead of market expectations. Bank debt £1.3m (£4.9m), a significant improvement on market expectations. [SP=65.79 Cap=60m]
GetBusy (GETB) guides FY(Dec) rev slightly ahead of market expectations. Recurring rev up 15% at constant currency. Net cash £2.3m noticeably ahead of market expectations. [SP=86.5 Cap=43m]
IQE (IQE) guides FY(Dec) rev c.£178m up 25% and consistent with guidance of at least £170m. Net cash c.£2m (-£16m) due to strong sales, capex cuts and cash mgmt. Makes a change for this cash guzzler. [SP=75.7 Cap=606m]
In line: RPS (LON:RPS) Galliford Try Holdings (LON:GFRD) Bonhill (LON:BONH)
[Edit] Surface Transforms (SCE) last night announced £17.9m placing and £2m OO at 50p, an 11% discount, to expand capacity. I hold.
Excellent results out from CLIG today, and a raised dividend. I hold. Good prospects and a high divi, assuming that you believe in emerging markets. Retiring founder slowly selling down.
Astounding results out of AIR, I wish that I still held.
Morning GreyInvestor
Air Partner (LON:AIR) (I hold) trading update - remember it made £10.5m u'l PBT in H1, due to one-off boosts from lockdown flights.
So £11.5m for the full year isn't anything to write home about, even though they say it's ahead of market expectations.
egards, Paul
Thanks for that, quite right, I should have paid more attention (I was listening to the surprisingly good Taylor swift album at the time!).
Maybe you should take a look at CLIG? If I understand the run rates correctly, they are likely to raise profit forecasts (and continue to generate very high returns). But it's cyclical; dependent upon emerging market P/E ratios. The retiring founder has run the company very conservatively. There are share options floating around for the refreshing management team, but all of the incentive schemes are well and fairly targetted.
Hi GreyInvestor,
Sorry I don't cover the Asset Management sector, as I don't have any insights or experience of investing in those companies. Plus I have to draw the line somewhere, as it's not possible to cover everything.
Jack is busy on other stuff today I'm afraid, otherwise he might have had a look at it.
Sorry about that!
Regards, Paul.
Hi Paul, Dan from Mello here, no chance you could please look at BONH is there? Not been covered before. No worries if not
Hi Dan,
I had a quick look at Bonhill (LON:BONH) but it's very small at £8.6m market cap, and the company's history seems rather lacklustre. It quotes an EBITDA profit, but I'd be interested to see whether that would turn into proper profits! It used to be called Vitesse Media.
For those reasons, I didn't think it was worth spending any more time on it, sorry about that.
Regards, Paul.
A number of comments here on the RNS from Air Partner (LON:AIR) some not knowing what to make of it.
I share the confusion: why has this been issued as opposed to the usual detailed one? It looks as if the latter will be in February as planned implying that this had to be issued now under the warning rules - if a company becomes aware of a substantial divergence (+ or -) from expectations there must be no delay to informing the market.
At the Interims the Board reported that it expected modest profits in H2 but how do you define modest? I would say that adjusted PTP of £1m was modest compared to £10.5m in H1. So presumably the RNS was issued because this is "ahead of market expectations".
They then fail to state what those expectations are. That is particularly difficult in this case because it is not easy to find the answer. If the market had priced in the £7.3m shown on Stocko (implying H2 loss of £3.2m - inconsistent with 'modest profit') the price would have rocketed this morning.
Sharecast (ex WebFG ex Digitallook) no longer gives consensus forecasts, which used to be used by a number of brokers such as HL so it is getting much more difficult to find these so I am lost. Does anyone know of any other source for forecasts that does not cost a large amount?
Hi sharw,
Re:your opening comments, the management of this company has always been at best incompetent. I held the shares some years ago and vowed never to do so again.
City Of London Investment (LON:CLIG) excellent returns.
My Fair model suggests a share price above 600p by year-end.
As always DYOR.
BSV
Hi Bluesky
I also hold City Of London Investment (LON:CLIG)
I would be interested to hear how you derive a PE of 16. Looking at a random peer group (Premier Miton, Jupiter, Liontrust) a range of 12-14 appears more sustainable?
BW
Steve
Hi Steve,
City Of London Investment (LON:CLIG) is focused on the Emerging markets and associated greater growth rate. With the recent acquisition, the average gowth is about 11% over the next 10 years (note 50% expected from 2021 numbers). The PE is my personal estimate of fully paying for the growth today.
Kind regards,
BSV