Small Cap Value Report (Wed 21 Aug 2024) - WNWD, ANX, WJG, MCG

Good morning from Paul & Graham!
Explanatory notes -
A quick reminder that we don’t recommend any shares. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech, investment cos). Although if something is newsworthy and interesting, we'll try to comment on it. Please bear in mind the "list of companies reporting" is precisely that - it's not a to do list. We typically cover c.5 companies per day, with a particular emphasis on under/over expectations updates, and we follow the "most viewed" list of readers, so if you're collectively interested in a company, we'll try to cover it. Obviously with the resources available, we can't cover everything! Add you own comments if you see something interesting, and feel free to discuss anything shares-related in the comments.
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to, if they are using unthreaded viewing of comments.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. And/or it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Others: PINK = takeover approach, BLACK = profit warning, GREY = possible de-listing.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom), Video update of results so far, June 2024.
Frozen SCVR summary spreadsheet for calendar 2023.
New SCVR summary spreadsheet from July 2023 onwards.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Phil Hanson's data analysis measuring performance of our colour-coding system in the SCVRs, from July 2023- Mar 2024 (with live prices). My video explaining/reviewing it.
My other video (June 2024) - How to screen for broker upgrades on Stockopedia.
Companies Reporting
Summaries
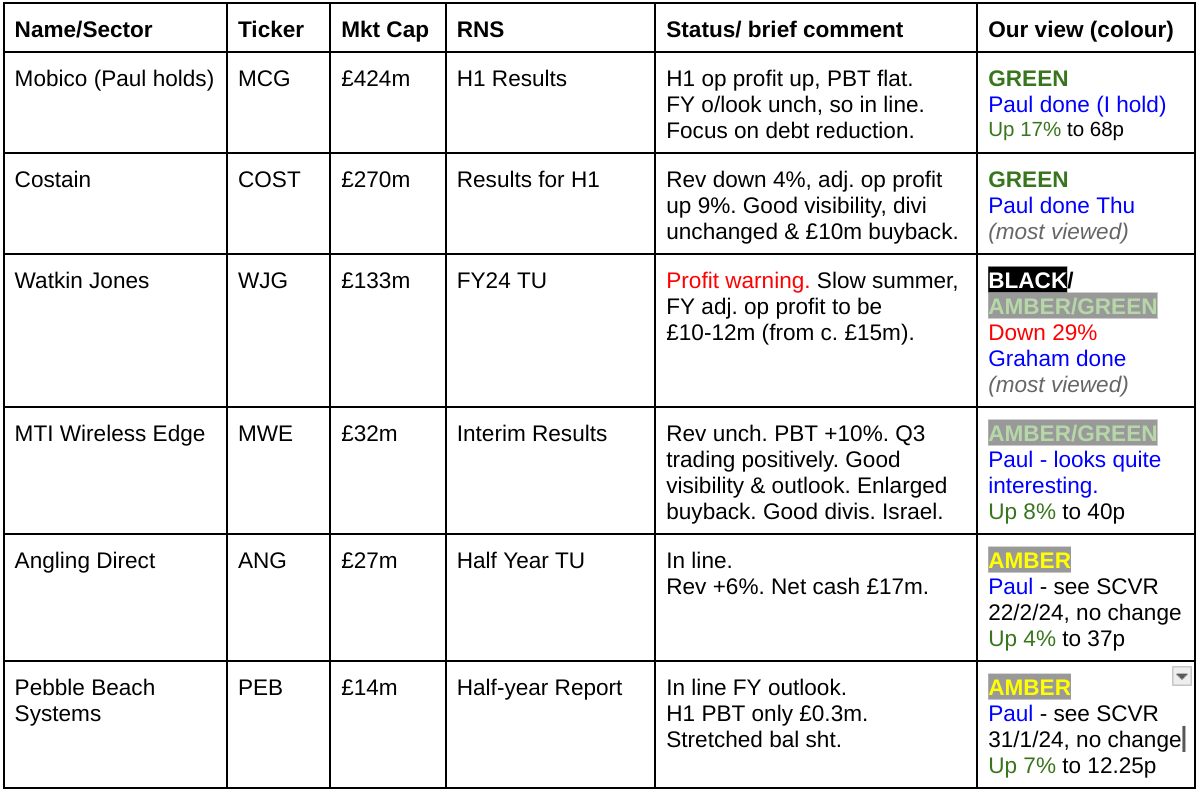
Watkin Jones (LON:WJG) - down 29% to 36p (£93m) - FY24 Trading Update - Graham - BLACK/ AMBER/GREEN
Another profit warning from this developer of rental and student accommodation. It’s disappointing to see uncertainty around interest rate cuts being blamed for a failure to do deals, as interest rate hikes were previously seen as a problem. A reminder to all of us that this is a difficult sector. I like to keep things simple by taking a bullish stance when they trade at a deep discount to tangible NAV. WJG is back down at a discount so I’m happy with AMBER/GREEN.
Windward (LON:WNWD) - down 2% to 118p (£104m) - Half Year Report - Paul - AMBER
An interesting growth share, but tricky to value right now, as it's still loss-making. Seems to be moving in the right direction, with strong growth in recurring revenues. Cash adequate, but balance sheet overall is quite weak, and could benefit from a small top up placing I think - not a deal-breaker. I'm keeping an eye on this one, it does look intriguing, although comes with Israel risk.
Anexo (LON:ANX) - down 2% to 62.5p (£74m) - Interim Results - Paul - RED
No progress made in H1 to collect in the ludicrous giant receivables pile. This looks an almost exact re-run of the disastrous Accident Exchange & Quindell, which ended in tears. Although better borrowing facilities have been set up. A deeply flawed business model, don't be fooled by the low PER, it's cash collection that matters, and it's hopeless.
Mobico (LON:MCG) (Paul holds) - up 17% to 67.5p (£417m) - H1 Results [in line] - Paul - GREEN
I take a deep dive into H1 results from this international bus/coach operator. I think it looks good, and with debt reduction now a priority, equity could re-rate. Trading is in line, breaking a trend of reduced forecasts.
Paul's Section:
Mobico (LON:MCG) (Paul holds)
Up 17% to 67.5p (£417m) - H1 Results [in line] - Paul - GREEN
This is an international group of public transport companies, mostly buses & coaches, plus rail operations in Germany.
Presentation slides for H1 results are on Mobico’s website here - well worth looking at, for a user-friendly overview.
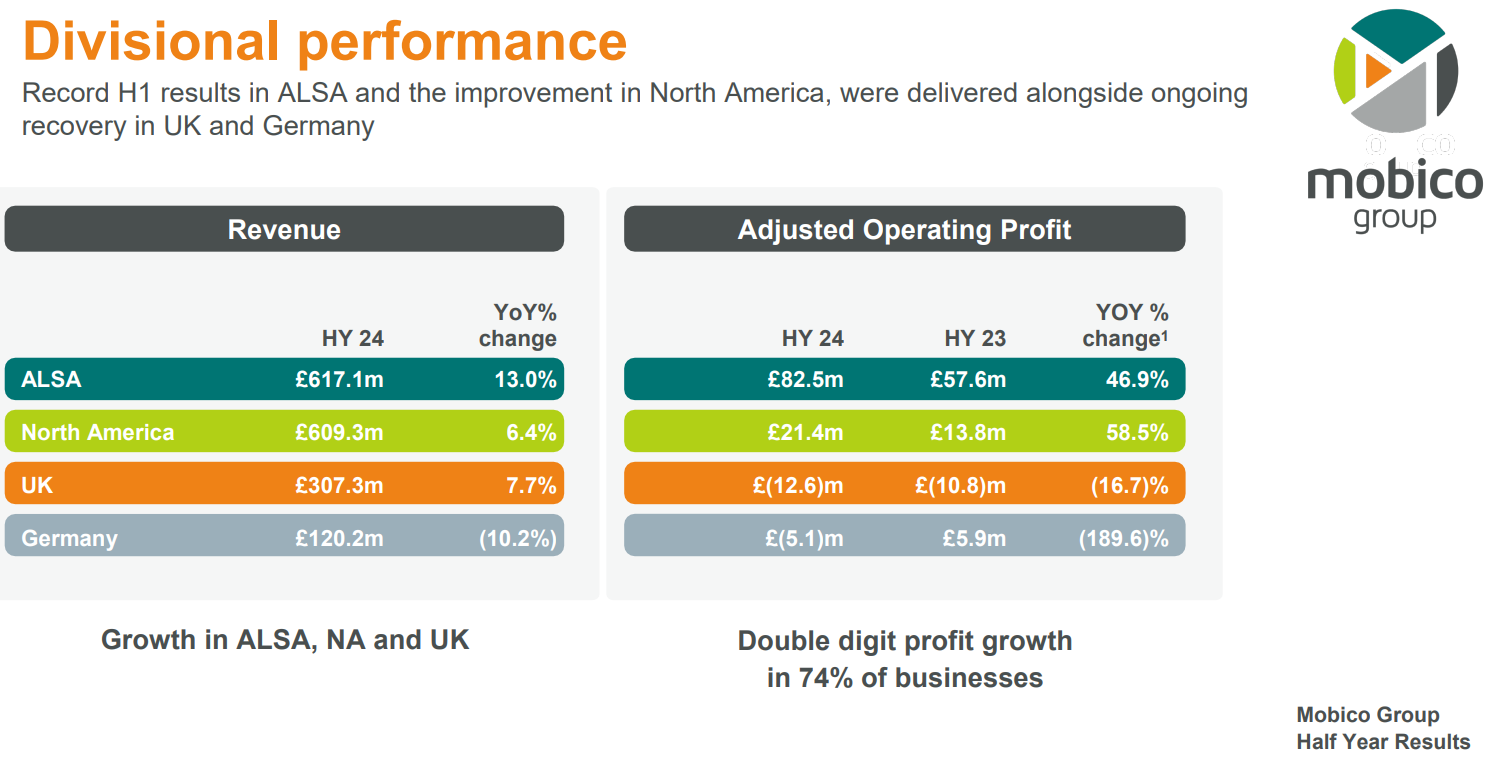
This slide below shows the revenue/profit by division. As you can see, ALSA (the leading bus company in Spain) is the jewel in the crown for profitability, putting in a barn-storming result this year so far, and the divisional outlook for ALSA is also good -
“We expect momentum across the business to continue in H2 24”
N.America is profitable too, but at a lower margin.
Whilst UK & Germany are problems - loss-making in H1. I wonder if Germany is worth keeping at all? It might make sense to dispose of that division, if it can’t be turned into a profit-maker again. It seems a highly regulated, and generally problematic division (eg driver shortages).
The US school bus division is up for sale, in order to reduce debt, but I can’t find any reference to how much might be raised from selling this part of the group. Let us know in the comments if you have any details on that.
No broker notes are available for guidance.
The financial highlights table below helpfully provides both adjusted and statutory H1 results, and obviously the large net debt is a big issue here, with de-gearing being prioritised by management -
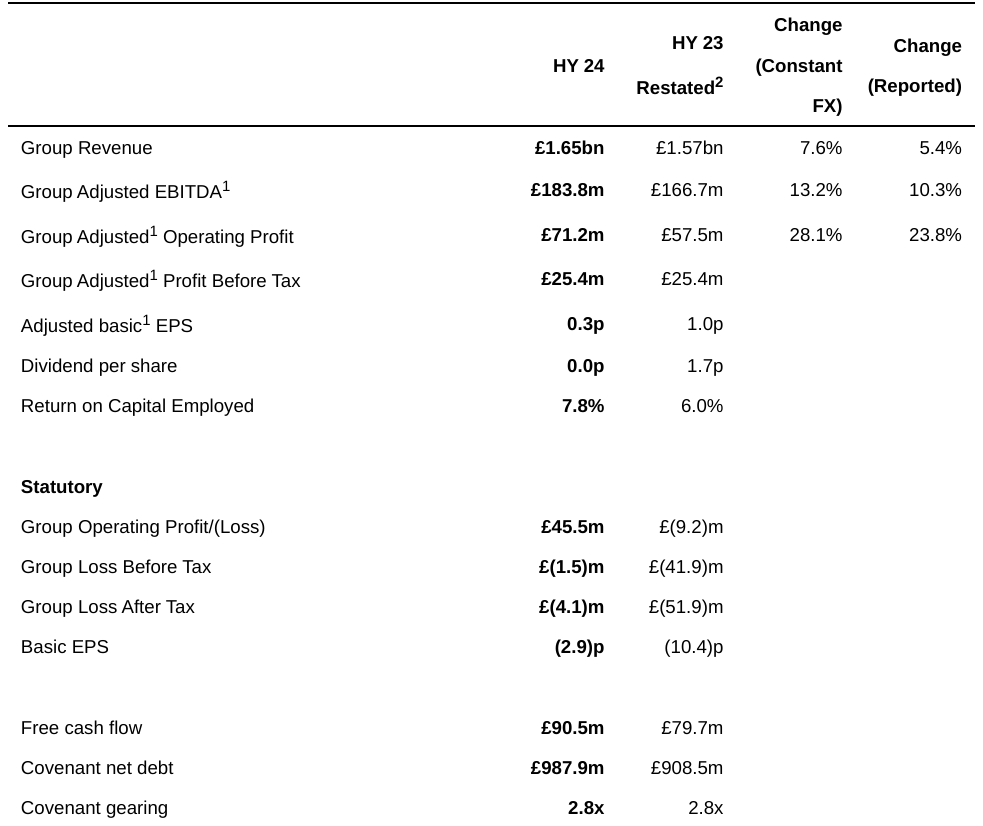
Adjusted H1 PBT is unchanged at £25.4m, yet adj EPS has fallen from 1.0p to only 0.3p
The interim divi has been passed - which makes sense given the priority is debt reduction.
Outlook is reassuring -
“Based on current market conditions, Mobico remains on track for Adjusted Operating Profit for 2024 to be within the range of £185m to £205m, with improvement in covenant gearing, relative to FY 23, expected at 31 December 2024.”
However note that the commentary also says finance costs are expected to rise to £90m for FY 12/2024, consuming nearly half of that operating profit, leaving adj PBT of c.£105m for this full year - implying a heavy H2 weighting to profitability.
The trend of broker consensus forecasts has been poor, so seeing things stabilise with today’s in line outlook is encouraging.
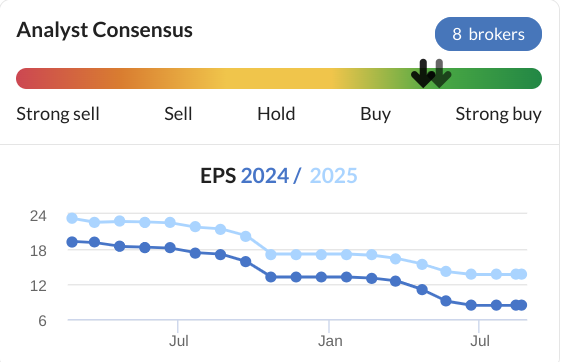
The slide deck indicates that cost & efficiency actions are underway to improve the under-performing parts of the group.
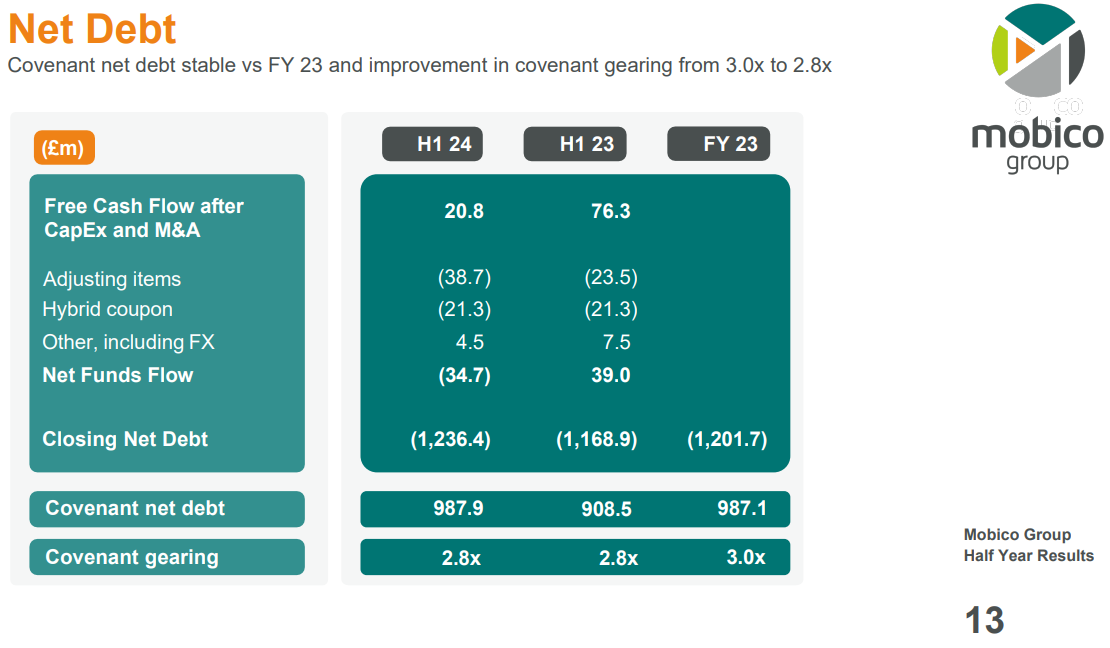
Net debt - it’s the covenant debt that is the key number, and it’s big at £988m - over double the market cap, hence why the PER is so low at forecast 4.9x
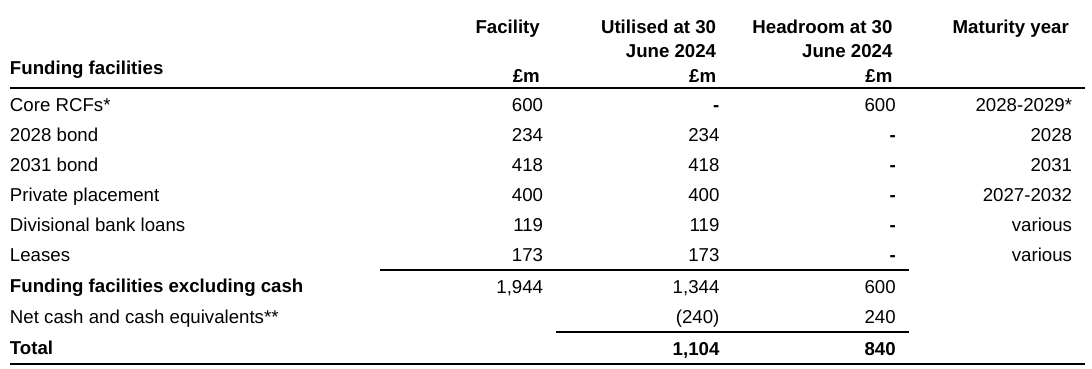
Structure of the debt is good I think - loads of liquidity available, with £600m RCFs undrawn, and the bulk of the debt in use being bonds (secure, and long-dated) -
Note that some of the bonds were refinanced on very good terms (4.875% coupon, Euros) in Sept 2023 - see RNS here. This is how they have traded since issue, as you can see very close to par currently, hence no sign of financial distress here -
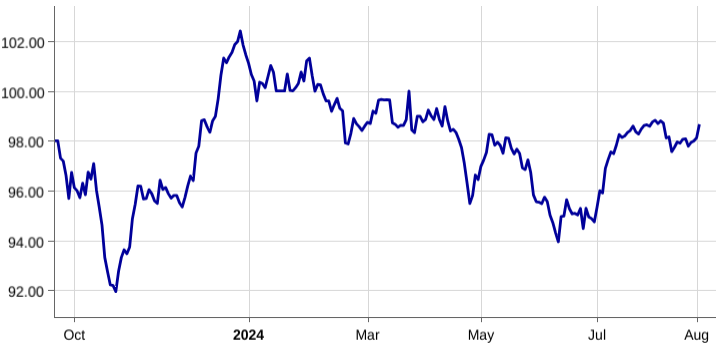
(Thanks to Frankfurt Boerse for this chart)
Debt reduction - this all sounds sensible -
“Mobico has made clear its commitment to debt and leverage reduction. Whilst we are able to achieve that through the growth of Adjusted EBITDA and Free Cash Flow, targeting net debt / covenant Adjusted EBITDA of 1.5x to 2.0x by FY 27; we have also made clear that accelerated solutions are preferred to reduce debt levels. As such, the Group confirms that the formal process to dispose of its North America School Bus business is underway. Furthermore, operational controls have been tightened over aged debt collection and capital expenditure appraisals, including an increased focus on asset-light transactions. “
As mentioned here before, I don’t see MCG’s debt as a crisis. It’s high, but maturities are long, and there’s loads of cash headroom. Although it’s getting a bit close to the covenant limits. That’s why an in line, unchanged FY 12/2024 profit outlook today is so important - as it means the covenants shouldn’t come under pressure from further profit falls -
“The Group maintains a disciplined approach to its financing and is committed to an investment grade credit rating. Our Moody's and Fitch ratings are Baa3 and BBB- respectively.
The Group has two key bank covenant tests; a <3.5x test for gearing and a >3.5x test for interest cover.
At 30 June 2024, covenant gearing was 2.8x (31 December 2023: 3.0x) and interest cover was 4.4x (31 December 2023: 5.2x).
At 30 June 2024, the Group had utilised £1.3 billion of debt capital and committed facilities, with an average maturity of 5.8 years.
At 30 June 2024, the Group's RCFs were undrawn and the Group had available a total of £0.8 billion in cash and undrawn committed facilities. The table below sets out the composition of these facilities.”
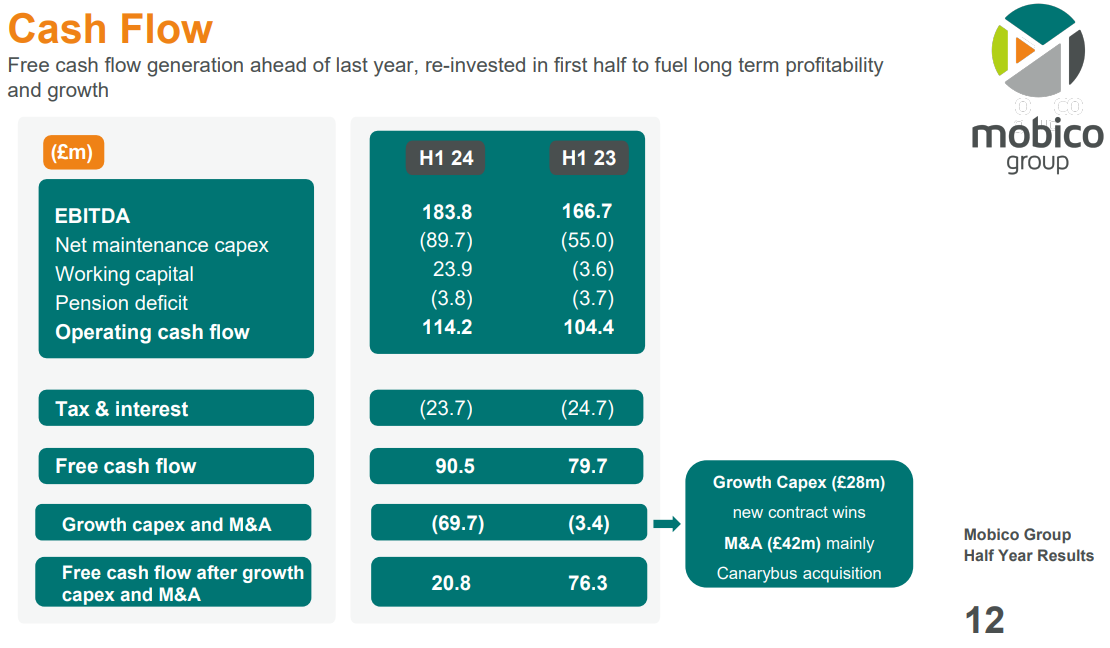
That’s loads of liquidity actually, and means MCG has been able to spend plenty of expansionary capex, eg this useful slide below on cashflow - note the heavy expansionary capex, which is not a business in financial trouble clearly - and remember these are only half year numbers, so it’s a lot of business for just a £417m market cap (plus the debt of course) -
Going concern statement - is clean.
Balance sheet - overall it’s lousy! NAV is £1,024m, including £1,567m intangible assets. Hence NTAV is horribly negative at £(543)m. That’s obviously wildly different to what I usually look for (positive NTAV, and net cash)!
But this is the reason why this share is so cheap, at only £417m market cap.
Equity could re-rate as debt reduces, especially if a decent price is achieved for the US school buses disposal - that’s our catalyst, I reckon.
Paul’s opinion (I hold) - I like MCG, and am encouraged that my decision to buy recently looks like a good move - there was an element of uncertainty, so I kept the position size small initially. I’m thinking about increasing it further now I have more up-to-date, and positive information.
It’s not a share I want to hold forever, I just took the view that it seemed to have fallen unreasonably low, and could be a good trading opportunity to make a turn on a re-rating and partial recovery in share price. A 100p price target feels about right to me to sell or top-slice, but that depends on the future newsflow and the US disposal. A favourable outcome there could keep me in for a longer term re-rating possibly.
A good rummage through today’s numbers confirms my view that this could be a good recovery share. Although maybe a deeper restructuring is needed, to clear out the stuff that isn’t worth owning (eg. German rail) and make a simpler, higher quality group with less debt, focused on ALSA, and further European expansion.
Debt is high, but not life-threatening.
So I’ll push the boat out here, and go with GREEN.
Obviously I’m biased since I own some myself, hence why we are required by Stockopedia to disclose our positions. Although we always try to be objective regardless of personal positions.
Company’s summary is nice and clear, I like this -
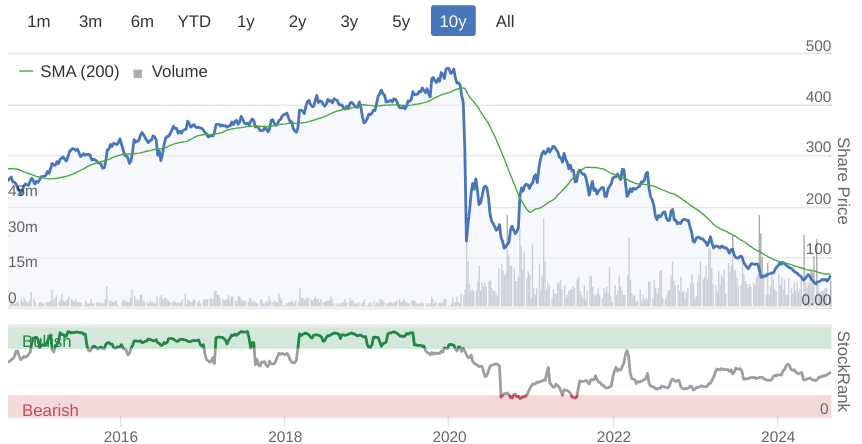
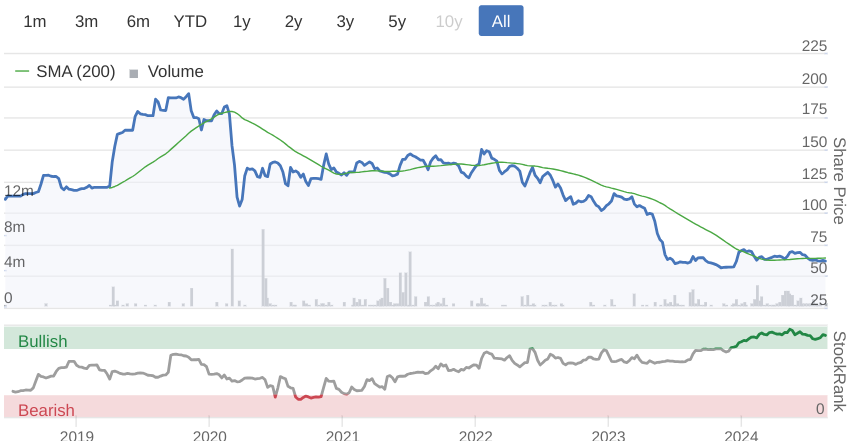
The long-term chart is striking. See how the pandemic starting in early 2020 clobbered things, but after the initial recovery bounce, shares have been in a seemingly relentless downward spiral. Note that the share count has risen, but not by a huge amount, from 513m to 613m shares. So theoretically, this share could multi-bag if they succeed in returning profitability to pre-pandemic levels. Maybe my personal price target should be more ambitious?!
Windward (LON:WNWD)
Down 2% to 118p (£104m) - Half Year Report - Paul - AMBER
Windward (LON: WNWD), a leading Maritime AI company, is pleased to announce its financial results for the six months ended 30 June 2024 ("HY 24").
Floated in Dec 2021 by Canaccord at 155p in Dec 2021 - admission document is here with 17m new shares, and 5.3m sale shares. The company received £22.5m in new funds from the IPO, and the total share count on admission was 81.6m.
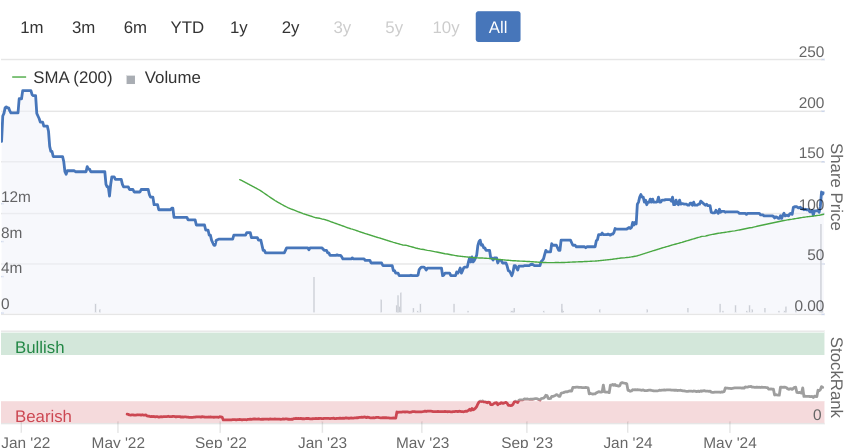
Shares fell heavily, finding a bottom in 2023 c.37p. Since then, there’s been a strong recovery, with the price having roughly tripled to 118p currently.
It’s a nice story - an Israeli tech company that uses AI to monitor threats to shipping - very topical of course with the attacks on Red Sea shipping.
After it was flagged to us by readers, we’ve looked at WNWD here 3 times this year -
12/1/2024 - TU ahead exps, but still loss-making. Enough cash.
21/2/2024 - Could be an interesting trade for the adventurous.
27/3/2024 - In line TU.
H1 Results out yesterday, key points -
Strong revenue growth, up 37% to $17.6m in H1
ACV (which sounds similar to ARR) of $37.2m, so it sounds mainly recurring revenues.
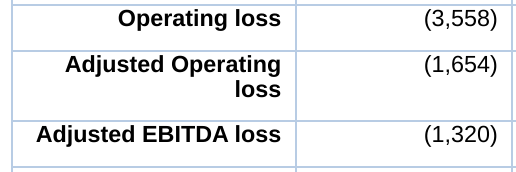
EBITDA loss of $(1.3)m, reduced 66% from previous year’s H1 - so still loss-making, even at EBITDA (flattering) measure.
Loss before tax in H1 was $(4.0)m (H1 LY: $(5.7)m loss) - so it’s still well away from actual breakeven.
Cash pile has fallen in six months from $17.3m to $13.8m.
Outlook - closing in on breakeven, but the way this is worded, it’s not actually breakeven! -
“Strong base of recurring subscription revenues and reduced cash burn underlines confidence in achieving breakeven adjusted EBITDA run rate during FY24”
“Trading in line with recently upgraded market expectations* on revenue for FY24, and confident of achieving an adjusted EBITDA2 break-even run rate during FY24”
“* For the purposes of this announcement, Windward believes market consensus for the financial year ended 31 December 2024 to be revenue of $36.2m, adjusted EBITDA loss of $1.6m and cash of $16.1m.”
The main adjustment is the $1.9m share based payments, which seems excessive in a half year. Other than that, adj operating profit and adj EBITDA are quite similar, which is good -
Balance sheet - thin, with only $3.5m NAV, including $1.0m intangible assets = $2.5m NTAV.
Note that the cash pile of $13.8m has all come from advance payments by customers, recorded as “deferred income” creditors totalling $15.3m.
It’s quite normal for SaaS companies to be funded like this, but it’s worth noting that continued cash burn could tip this balance sheet into negative NTAV, so it doesn’t have much resilience.
Having a healthy market cap of £104m, and a good, topical story (AI, maritime safety, etc), if I were having a chat with management I would suggest their best move would be to raise say £10m fresh equity to bolster the balance sheet, which would only be 10% dilution. It’s a pity when you see under-funded companies with buoyant share prices miss the opportunity, only to regret it later if something goes wrong, and they have to raise funds from a position of weakness, and at a much lower price.
After all, the whole point of a listing is to provide access to growth capital.
Cashflow statement - share based payments of $1.9m in H1 TY, and $1.3m H1 LY seems a lot for a loss-making company. US-style rewards for management it seems.
The good news is that it capitalised very little into intangible assets, only $0.5m.
The rest of the cashflow looks pretty clean.
Paul’s opinion - I’m only checking the facts & figures remember. No surprises here, we already knew the story - rapid growth in recurring revenues, and breakeven within sight. Probably enough cash to get there without needing another equity raise (although I think the balance sheet is thin, and could benefit from a top-up equity raise - which would also help reassure blue chip customers).
I suppose the key question would be how much more growth is possible, and will it start generating cash and be able to pay divis in future?
The clients sound like blue chip organisations, and having high recurring revenues is positive.
I’ve no idea how to value Windward, but it looks an interesting growth story, so worth doing some more research on, I think. £104m market cap sounds up with events for the time being, maybe?
You have to assess what the future holds, which is the difficult bit! All I can say is that there are some good elements to this story, and I can see potential here, if strong growth continues. If growth stalls, then the market cap would crash of course, that’s the risk you take with loss-making growth companies. This seems one of the more credible ones I’ve seen.
The trouble is with all listed companies, we only get our information from the company itself, and obviously they tell the bullish story. Ideally it would be good to talk to someone who actually uses WNWD services as a customer, to find out what it’s really like. That’s true of all companies actually. Customers often have a very different view from what the RNSs say! As one fund manager once quipped, we should be employing private investigators, not financial analysts, to properly understand companies.
Since listing -
Anexo (LON:ANX)
Down 2% to 62.5p (£74m) - Interim Results - Paul - RED
I have a very low opinion of Anexo - see SCVR 1/5/2024 where I explain its horrendous accounts - my summary being -
“Same problems as before - reports huge profits, which then just sits in debtors on the balance sheet, uncollected. Receivables absolutely absurd, at £234m. Gross borrowings of about £62m are fiendishly expensive, as I think it borrows from anyone at any price. Hence finance costs on P&L more than doubled to £17m. Paul’s view - probably doomed to eventual collapse, in my view. Very similar to Quindell and Accident Exchange.”
Yes I know it’s awful to quote yourself! But they’re important points.
On to today, have things improved I wonder?
“Anexo Group plc (AIM: ANX), the specialist integrated credit hire and legal services provider, is pleased to report its Interim Results for the six months ended 30 June 2024 ('H1 2024' or the 'period').”
With this type of business, I almost completely ignore P&L numbers, as they can report anything they like. Cash collection (which ranges from very late, to never) is what matters. Failure to collect in cash is what killed off Accident Exchange and Quindell. This looks a re-run of those.
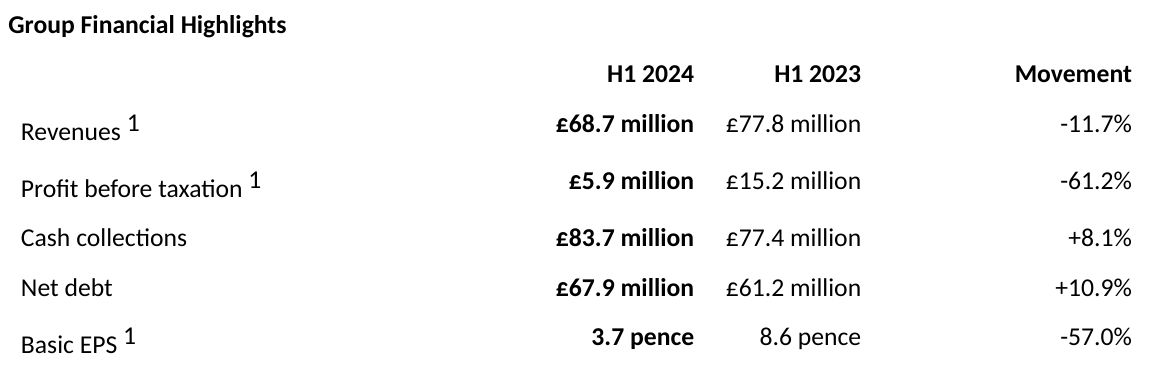
Let’s look at what matters -
Balance sheet - no major changes. NTAV is £162m - that’s more than double the market cap! Bargain then? I would say definitely not. The reason being that receivables (unpaid invoices sent to customers) is a ludicrous £243m, slightly up on 6m and 12m comparatives. This is the huge flaw in the business model of ambulance chasers like this. Their customers are not actually customers. They’re organisations that ANX has lodged legal claims against. As we saw with both Quindell and Accident Exchange, the insurance companies don’t pay the claims, and instead wait for the ambulance chasing firm to go bust, or in desperation offer a heavily discounted batch settlement. It’s just a terrible business model.
The market knows this, which is why ANX shares are priced at a large discount to NTAV - because the receivables contain an unknown amount which is uncollectable.
Don’t be fooled by the low PER!
Worse still, as they book large profits, they have to pay tax on the imaginary profits, making cashflow even worse, in this sector.
Cashflow statement - this is the thing to focus on. It’s very clear that Anexo didn’t generate any free cashflow at all in H1. Its operating cashflow of £9.2m quickly disappears once you take into account £4.4m interest paid, and £4.3m lease payments. It can’t afford the £1.8m dividends in my view, and as previously mentioned, it’s scrabbling around for debt wherever it can be found (in creditors).
Outlook comments - don’t seem to tie in with the numbers, which clearly show that cash collections have not improved - because receivables has gone up, not down -
“The focus in the first half of 2024 has been firmly on the conversion of profits to operating cash flows and managing claim acceptances in line with cash collections. The second half of the year is always more significant as a result of seasonality; this has been factored into our forecasts, which indicate that performance in the second half will outperform that of the first half.
The continued growth in cash collections, following ongoing investment in the legal teams and IT infrastructure, allows the Group to increase activity, without the need for significant increases in net debt. Management look to the second half of 2024 and beyond with optimism.”
In this sector, I’ve learned the hard way not to believe a word they say. Focus on the numbers - in particular cashflow, and receivables.
These companies only become viable if they can generate serious reductions in receivables, through co-operation with the insurance companies that decide whether to pay these claims, as demonstrated by ZIGUP (LON:ZIG)
Refinancing - this sounds quite positive -
“In August 2024 the Group agreed a £30m loan facility with Callodine Commercial Finance LLC. The Group has drawn down £20m of this facility, to provide further headroom and to repay the loan provided by Blazehill Capital Limited, the refinancing significantly reducing the overall cost of capital to the Group.
In August 2024 the Group also agreed an increase in the funding available under the facility provided by Secure Trust Bank PLC. Secure Trust have extended the funding period within the £40m facility limit previously agreed.”
I’m worried about Secure Trust Bank (LON:STB) as this looks a large exposure for them (market cap of £164m).
Paul’s opinion - other experienced investors might remember Accident Exchange and Quindell. Both had pretty much identical business models to Anexo - lots of legal claims made, big profits reported, but all the unpaid claims pile up into vast numbers in receivables.
I remember Accident Exchange vividly, as I kept buying more shares as it fell in price, eventually averaging down numerous times until it was a large part of my portfolio, and ultimately on a PER of 1.9x, which I thought was cheap, but of course it was a red flag. It took me a long time to realise that the business model was totally flawed, as it couldn’t turn its claims into cash. In the end it de-listed, with the shares worth almost nothing, and an aggressive financier gave it a cash lifeline to try and take legal action against the insurance companies who refused to pay its claims.
There’s only one number that matters in Anexo’s accounts, £243m in receivables.
Lenders seem willing to support it, hence a stay of execution, but sooner or later they might begin to realise that the receivables are of distinctly dubious quality and collectability (in a reasonable timeframe).
I’ve seen this all before, several times, hence I remain flagging a lot of risk here at RED.
It might turn out to be alright, but why take the risk? In this case, I think the high value scores are a mirage - because I’ve seen it all before in this sector. As my old company solicitor used to say, sales are a gift until the invoice is paid. Same here - those revenues & profits booked mean nothing until the cash is collected in, and there’s currently £243m of unpaid invoices! The only way to collect in such big arrears is to offer bulk settlement deals, which it sounds like Anexo has done with VW, but that’s not resulted in improved figures has it? This is a can of worms, I’ll be steering well clear, at any price.
Poor track record since listing -
Graham's Section
Watkin Jones (LON:WJG)
Down 29% to 36p (£93m) - FY24 Trading Update - Graham - AMBER/GREEN
Commiserations to anyone holding shares in this developer overnight.
Here is the bad news:
As set out in our half year results announcement on 21 May 2024, we had a number of schemes being actively marketed, with the subsequent sale of a substantial PBSA development located in Stratford, London, announced in July. Nevertheless, overall market activity through the summer has been slower than anticipated, principally due to the continued uncertainty over the pace of interest rate cuts, and as such we believe it is now unlikely that we will close any further transactions before the financial year end.
Operationally, the company has continued to “execute effectively”. But the absence of new deals will mean a weaker-than-expected full-year adj. operating profit of £10m to £12m (the financial year-end is in September, so there’s still one month left).
The existing forecast for adj. operating profit was £15m (with thanks to Progressive Research).
Their adj. PBT forecast gets cut from £11.5m to £7m, i.e. a 40% cut.
Unfortunately the bad news doesn’t stop there, as there are knock-on effects to future financial years.
Outlook section acknowledges that interest rate cuts should ultimately help, but:
…The lower number of transactions in FY24 will, however, have a consequential impact on the results in FY25, given that schemes will not contribute to revenue in future periods until they are forward sold. While we have a number of further schemes that we expect to take to market in FY25, given the slower pace of activity currently, we believe that a more prudent set of transaction assumptions should be applied to the next 12 months than previously assumed. As such, we do not currently expect adjusted operating profit in FY25 to be above FY24…
Progressive Research haven’t published estimates for FY25 yet, as they wait for the outlook to become clearer.
Remedial works: no change to the position here. As of March 2024, the gross provision was £55.7m, of which £33m was to be paid out in future financial years.
Net cash is described as “robust” and is anticipated to be c. £65m at year-end, ahead of expectations (£52m). After today’s share price fall, that cash balance covers c. 70% of the market cap.
But the company still isn’t convinced that it has enough cash:
While the Group's robust net cash position provides it with a strong financial underpin for its committed spending requirements, it is nevertheless a limiting factor on the extent to which we can take advantage of market conditions and further develop our pipeline. In light of this, the Board is undertaking a review of a range of options that may be available to enhance its medium and longer term funding position, thereby allowing the Group to capitalise on a market recovery.
I wonder if this is to a large extent because of the cost of remedial works, that will eat into the cash balance over the next few years?
Graham’s view
In October 2023 (at 33p), I upgraded my view on this share to GREEN as it was trading at only about 55% of its tangible NAV, and it passed Ben Graham’s Deep Value Checklist.
That was pretty much the low:
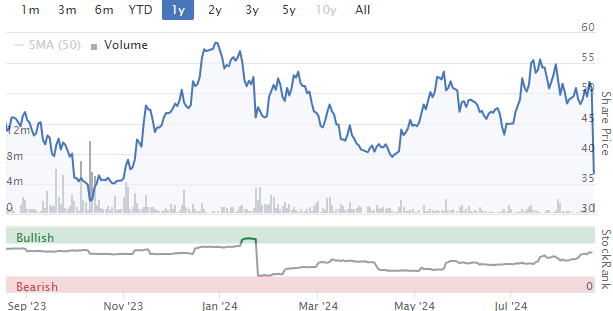
In January 2024, at 48p, Paul was neutral, noting the accident-prone nature of the business, including the growing provisions for remedial works.
Today I’m going to hedge my bets a little bit and go AMBER/GREEN.
As of March 2024, WJG had tangible balance sheet equity of £121m, a handy 30% premium to the market cap (and the company has been profitable since then).
Against that, we have to balance the importance of a series of profit warnings and the effect this should rightfully have on our confidence in the business. Interest rate hikes could be blamed for previous profit warnings, but now uncertainty around interest rate cuts are to blame for the latest one. Shareholders could be forgiven for running out of patience (as it seems many of them have this morning).
Provisions for remedial works haven’t grown recently, but are another legitimate source of concern.
Existing provisions will drain cash in future financial years, and the company is not entirely satisfied with its current cash balance - but would it really raise equity at this valuation? Surely an enlargement of its bank facilities would make sense? After all, if the opportunities thrown up by current market conditions are so attractive, then there should be little doubt around the company’s ability to repay increased debts.
I find this one puzzling, as I thought conditions were favourable for developers of rental properties, especially student accommodation. So I’m perplexed by WJG’s inability to hit its financial forecasts. But I do like this type of stock at a material discount to NAV! So I’m willing to take a mildly positive stance at this share price.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

79 comments
Paul - thanks for the analysis on #mcg
National Express is a strong brand and debt reduction remains the key priority. After listening to the webcast I feel the business could be on the cusp of a turnaround with the medium catalyst being sale of their US school business.
Analysis on #anx is right on the money. It's a flawed business model because third party insurers never pay credit hire claims. Litigation takes months if not years and the party to the proceedings isn't the claims management company (#anx) but the claimant who is long gone by then. The debtor book will always looks healthy but cash conversion absolutely piss poor.
Fabulous output Paul, with further acknowledgement of Graham's contribution and Roland's assistance.
As I have said before the SCVR is worth the annual fee on it's own. Such a good website with a very knowledgeable investor base, some of whom I suspect knock spots of the majority of professionals investors.
Congratulations to Ed and the team.
Science (LON:SAG)
Just to note that the exec chairman and at 20.78% the largest shareholder, Martyn Radcliffe, has bought 30,000 shares over the last 3 days.
That's £140k so far? Perhaps he'll keep going?
In the recent results he had something of a rant on the low valuation of the company currently. And that the board were considering options. Presumably the board has decided that buying back the shares is a good option as there is/was a company buyback in place.
Also an observation. The exec chair does not participate in the LTIP/CSOP - interesting alignment with shareholders? Not seen often? As Science (LON:SAG) is primarily a people knowledge based business I approve of an LTIP/CSOP run in this way? As charlie munger supposedly said - 'Show me the incentive and I'll show you the outcome.'
cheers
Mark
Hey Paul, It appears that you are truly smashing it with your recent purchases. Today, Mobico up nearly 18%, very well done indeed! It would be great to know when you are buying any shares so we can all benefit from it. Thank you very much for your continuous excellent work!!
For all holders of Telecom Plus (LON:TEP) like myself you may not be aware that the UW account app and webpage has no functionality re the submission of meter readings despite emails prompting a reading. This has been the situation for over a year with customer service responding repeatedly with " we are aware of this and are working on a fix". This may not be a big deal but it does make me less inclined to remain invested.
Thank you for the comments on WJG Graham, perhaps being an optimist by nature is not conducive to safe investing but while there's a touch of Green on here we'll add a few more. It's hardly a coffee can investment but time will tell if there's still a good business in there trying to get out.
According the FT today, UK chancellor Rachel Reeves is planning to raise social rents by CPI + 1% over the next decade in order to help housing associations not only build more affordable homes.
But also importantly maintain and improve existing properties - many of which are dilapidated and run-down. In turn presumably also boosting firms like Mears (LON:MER) , who trade on only a 9x PER.
https://www.ft.com/content/e25...
In addition private registered social landlords such as some social housing REITs may also be beneficiaries. However, any rent hike above CPI will be tied with a commitment to investment in existing stock. The challenge for the government will be Housing Benefit/Universal Credit - how will a rent hike impact the treasury.
Should also provide another boost for Kinovo (KINO)
I see one of Paul's stock suggestions for 2024 Porvair (LON:PRV) is down over 5% today so far. I hold and have always regarded this company as a kind of "steady eddie" kind of outfit. Admittedly the value ranking isn't great but I bought this earlier in 2024 thinking there would be a chart breakout - which did occur- but it has retraced since. This is no denigration of Paul's choice BTW
Any thoughts as to why the decline and particularly today's fall
I still hold
There can be a wide diffference (spread) between the buying and selling price of Porvair (LON:PRV) . The price is based on the last traded price which could be just one share. There is not a lot of volume going on it. It is worth going onto the London Stock Exchange website to look at the number of shares traded and the prices. Porvair shares are notorious for large movements on very little trading. I would tend to avoid paying too much attention to one day's share price movement
A quick way to see near real-time trades, prices (and the day's graph) is the ADVFN app. With a free account , the live prices stop almost immediately but the current display remains visible (unlike the advfn website which obscures the screen when live prices time out with a free account). Set up a monitor and you can see the latest prices of all the shares. Click on one and you get the daily graph and tab that shows trades and news. I often look at the way prices have moved in the last few minutes before I place a trade, if I'm selling into a sharp rise or trying to see the bottom of a sharp fall.
Porvair (LON:PRV)
Took this as an opportunity to buy.
No news. Looking at the transactions the slump took place due to little volume. Only about 15k at the time.
Probably wrong as normal.
General observation - I remain very impressed with Paul and Graham and their objective analysis of stocks!
Paul - can you shed some light on Mobico (LON:MCG) results today which I am very pleased about after my entry price of 56.55p. Plan to hold this until the deleveraging plan is in full flow and hopefully the sale of NA School Bus too.
Thanks Paul for an excellent summary on the pros and cons of investing in Windward (@WNWD). Apart from an outbreak of world peace, I do not see any obvious challenges to the continued growth of the markets in which Winward operates,
However, it was concerning to see the RNS report that Maritime Invest Scandinavia, one of Windward’s biggest long-term shareholders, had sold out just before the latest results announcement. Its stake appears to have been taken up by West Elk Capital, a little known US fund manager.
According to its website it manages a concentrated portfolio of well-researched, small public and private companies and looks for businesses that have large addressable markets, recurring or repeating revenue models with a stable customer base.
It seeks out companies that have "the potential to become much larger over time, and yet today may be overlooked, misunderstood, and mispriced by the market."
I'm not concerned about the sale by Maritime Invest, it isn't the only early investor at WNWD that has exited as others come on board.
I note that Paul points to the Israeli angle as being a negative, but I can't quite see why.
My understanding is that although domiciled in Israel its London and US operations are larger and that any escalation of the recent troubles wouldn't impact the business in terms of operations. The CEO's relocation to London with his family underpins that for me.
As for continued growth, they have really only started to scratch the surface on the commercial aspect and there are plenty of long term growth opportunities there.
Profitability is clearly in sight and I feel the balance sheet is adequate to see it through to profit, although I wouldn't have an issue with a raise of circa £10m as Paul mentions.
I note that Paul points to the Israeli angle as being a negative, but I can't quite see why.
Israeli listed companies have a reputation for being run for the benefit of their founders and the management, not their owners (you and me). There are numerous examples to back up this apparent prejudice and I personally do lend it some credence, as do many here. Nevertheless, there are exceptions and I own a couple.
I get that BnB, but there are also plenty of UK based quoted companies that are also guilty of being lifestyle operations, or seemingly run for for the benefit of management.
I think Windward looks like a decent operation with some very big blue chip customers and equally impressive partners, so hopefully it will go on and deliver.
Watkin Jones (LON:WJG) 'In light of this, the Board is undertaking a review of a range of
options that may be available to enhance its medium and longer term funding position, thereby allowing the Group to capitalise on a market recovery.'
Anyone know what they mean by this?I hate cryptic rns messages.Just spell it out, they must already have a decent idea of what their options.Are they wanting a rights issue or a placing or convertibles or debt or what?All i know is it doesn't sound great tagged onto the end.Especially as they said earlier the market isn't great currently.Therefore what opportunities do they need extra money for exactly?Why not focus on what you can do right now instead of trying to do extra nice stuff when their end market doesn't seem to be great currently, unless these land market 'bargains' are at rock bottom prices never to be seen again?Basically i'm happy to hold and wait it out as long as it's not shareholder dilution is what i'm trying to say i think (as my buy in price isn't much above here-(admittedly perhaps not the best reason, but i 'feel' i guess their end markets will eventually recover and the company still stands a chance of eventually returning to past glories)!
Dear StrawberryDreams
Watkin Jones (WJG-LON)
When management last presented to shareholders they talked about operating joint ventures with institutional investors who would act as a financial partner. I am guessing, of course, but I suspect that this is what they have in mind rather than either a conventional rights issue or additional bank debt. However, it would have been helpful to clarify this in the statement as I suspect some of the selling today has been influenced by the fear of a diluting fund raising of some sort.
Kind regards
Phillip
Thanks Phillip.Gives a bit of reassurance as i don't mind the odd dilution but would rather avoid it now if i can.Think i'll just continue holding, especially as Graham noted asset value is higher than marketcap, and hope next years numbers are somewhat sandbagged or at least in line, as rates go down some instituions might chance their stance and timeframe to invest.
I'm wondering whether this business model worked best in a period of virtually 0% rates and QE as like with REITs the yields would have appealed much more then?Why invest if rates aren't necessariy going to stabilise a whole lot lower over the long term?Although maybe I guess time is needed for any potential future rate cuts and the quant)um to be processed by potential institutional partners..Perhaps naievly i would have assumed that build to rent could be a popular investment within the general 'macro' of labour's future housing proposals and watkin's might get a bit of that enthusiasm, but it's still early doors.At least a subsidiary of Lloyds Bank decided to partner recently although for student accomadation.However i'm wondering why they put that out there a while back as i thought it was already in the old numbers... although admittedly it didn't exactly move the market soaring higher.
Thank you Paul. Windward (LON:WNWD) - I hold. Flagging that on Thursday's (15th) SCVR report I covered one way of thinking about the valuation. More details there, but in brief: they do need to keep up momentum, however it's only a small hop, skip and a jump (Vs the leaps they've been delivering already) before they start looking cheap on earnings. The below is stale given the share price since then but it gives you an idea. Position unchanged.
Anexo (LON:ANX) and Secure Trust Bank (LON:STB) - I'm trying to get my head around Paul's concerns.
"I’m worried about Secure Trust Bank as this looks a large exposure for them (market cap of £164m)."
STB has a loan Book of a shade over £3B, so a £40M exposure is just noise, surely? Sure, if the worst happened they might have to write off the lot, which against a typical £30-something Mill. average profit wouldn't look great if they did it in one hit. I can't see how much of the £40M is drawn, nor what it is secured against. Either of these could be mitigating factors in any loss.
That 2023 £36M profit for instance was net from £185M revenue and within that there must be provisions generally. No lending is without risk.
I hold STB, not ANX and hat tip to Paul for flagging it but on reflection I think I'll be sitting tight. What am I missing? I've followed Paul for long enough to trust his opinion over mine!
I think I’d have a few questions about the quality of risk management at Secure Trust Bank (LON:STB) if they think Anexo (LON:ANX) is a suitable borrower…what other horrors lurk in their loan portfolio that we are unaware of …
Secure Trust Bank (LON:STB) So do the recent share purchases by 2 of the board with a combined value of £250,000 show ignorance, recklessness, hope or something else? I have not thought of the board as inexperienced or reckless before.
I’ve no idea how good their judgment is ..all I do know is I wouldn’t lend Anexo (LON:ANX) £40m..under any circumstances.
Secure Trust Bank (LON:STB) looks great value on most metrics though
Agreed. Perplexing.
James Latham (LON:LTHM) I hold
Nice steady as you go AGM statement
"Revenue for the first four months of the current financial year, namely 1 April to 31 July 2024 is £127m compared with £128m for the same period last year. Volumes are up 3.1% on the same period last year. Margins remain consistent with the second half of the previous year. Overheads and resulting profit are in line with market expectations.
Our cash balances remain strong, and debtors days and bad debts remain consistent with the same period last year.
Most of our customers remain busy and are more confident than at the same time last year."
Interesting that volumes are up whilst revenue isn't. Margins presumably a little down although product mix has a lot to do with both.. Happy to continue to hold this well run company which should benefit from any increased building activity .
Paul, you kindly looked at Costain (LON:COST) on Friday 17th May at my suggestion and came away pleasantly surprised. Its updated today and also announced a £10m buyback, so would be curious on your assessment on Interims and this cash return to shareholders.
Then, if you still feel like a challenge, I would propose Pebble Beach Systems (LON:PEB) which released Interims and has whittled away at the debt further since you last reviewed on Jan 31st. Order intake and order book up, pricing strengthening & maintains guidance today. I feel the broker PT of 20p is realistic, so decent upside exists on this basis, but wonder if your view has moved on it over the past 6 months or so?
Costain (LON:COST) a second request please if it’s allowed
Remains a low margin business but I hold for the water contracts it’s winning. We look to be entering a golden age for construction (said slightly tongue in cheek given the underinvestment in the water sector) but I can see the new contracts continuing
Synectics (LON:SNX) "Synectics, a leader in advanced security and surveillance systems, was notified on 20 August 2024, that the estate of David Coghlan, former Chair, no longer holds a notifiable interest in the share capital of the Company.
"The estate" held 8.9% of the company in May. The second biggest in the company I believe. Could this have been holding back the SP a little and be seen as a good thing now they are done (or, at the very least below notifiable)?
Moring Peter. I was wondering the same. The company scores very highly on Stockrank, was awarded a lovely contract back in June, and this selling could have been holding it back.
Synectics (LON:SNX)
Not studied the company previously but it does look interesting looking at forward earnings etc. However Downing Strategic Micro-Cap Investment Trust (LON:DSM) is winding down and returning capital to shareholders (see below). It currently holds 8.84% of the company, which I would have thought is likely to keep a lid on the share price.
"In July, the Company’s NAV decreased by 9.3% and the share price increased by 40.0%. Adding back the effects of special dividends, the respective changes were -1.5% and +5.0%. The share price change was driven by unusual trading ahead of the requisitioned general meeting.
The meeting was held on 5 August and all resolutions were voted against by a significant majorityof voting shareholders. The Manager will therefore continue the managed wind-down and return of capital of the remaining assets comprising Centaur Media, DigitalBox, Norman Broadbent, Real Good Food, and Synectics.
The Manager and Board remain focused on maximising the available value of the positions and minimising ongoing costs in order to maximise ongoing distributions to shareholders."
Synectics (LON:SNX) Apparently they are not selling down their holding but have said they are transferring the holding to another of their funds.
They (Downing) said they would do the same with JNEO, and then promptly sold into the market. I would place little faith in sincerity from Downing.
Fair play murrb.
Yes, this is exactly what I believe has been holding down the sp. Previously I thought it was Downing selling out as they are winding down the trust, even though they did say they were not selling more but transferring the rest. The ex-chair selling out explains why this has been held back. Good rise today and looks like it is all buys going through. Just need a break above the previous high at 198p to confirm a breakout.
Synectics (LON:SNX)
Here is a snippet I've taken from the Simon Thomson "Alpha" in Investor Chronicles.
Whether you agree with him or not, it's a pretty good write up.
I have a small holding here I bought at the start of 2022 at around £1. I've no intention of selling as I personally see this as a long term holding. They have their fingers in so many sectors there is likely to be additional contracts and growth that imo just hasn't recovered yet despite the sp seeing 100% increase from it's lows.
Target price
Admittedly, Synectics shares have performed well over the past year as more investors have
spotted the earnings growth story that is gaining momentum. However, the rating gap with peers
is still far too wide and has potential to narrow materially, so long as the business continues to
perform well.
To put the potential upside into perspective, even if the share price rallies 50 per cent to 280p by
the end of 2025, the shares would still only be rated on a cash-adjusted PE ratio of 10 once you
adjust for a projected closing net cash of £6.9mn (38p) at the November 2025 financial year-end.
That’s hardly a bumper rating for a company that is forecast to double EPS to 29p over the
2023-26 forecast period.
From a technical perspective, although the share price hit resistance at the 200p level, and has
moved sideways since late February 2024, this has enabled the 14-day relative strength indicator
(RSI) to unwind from overbought levels and now has a neutral reading. A break-out above the
200p resistance level would be well worth noting as it would signal that the consolidation period
is finally over and the next stage up-leg in the rally has started. Given the strong fundamentals
supporting the earnings growth, it would pay to buy in well before.
So, offering 50 per cent upside to my 280p target price, Irate the shares a buy.
I would be interested in any thoughts on Mobico (LON:MCG). Interim results today no worse than feared, although debt has nudged a little higher. The key to me is the sale of the US school bus business. They had to pull it once already which isn't a good sign but it looks back on track following a strong bidding season. A fair sale price for the school bus business would transform the Mobico balance sheet and leave it looking very cheap (and there is a potential bidder on their share register).
Ramsdens Holdings (LON:RFX)
The share price appears to be gaining traction, currently around 223p. As to why, apart from the obvious, they are cheap and the company is performing well; my best guess is the gold price, which is heading towards $2600. With the dollar falling, presumably due to the anticipated interest cut by the Fed, but who knows, it is likely to track higher in the near term.
All crystal ball gazing of course, but having bought Ramsdens Holdings (LON:RFX) close to 200p, I am happy to watch and wait.
Ramsdens Holdings (LON:RFX) l also read secondhand watch prices had recovered. Yes gold price is going up but $ is falling, so in £ terms not a huge gain. I have held for a while, looking to sell.
It is the currency part of the business that is deemed to to be their jackpot card.
Watkin Jones (LON:WJG) Views on management credibility gratefully accepted. Another falling knive for me!
Watkin Jones (LON:WJG)
Ex-holder here who sold out on the bell this morning so feel free to take my comments with a pinch of salt.
Having held for several years (initial position bought in 2016), and with benefit of hindsight, the company started to lose its way when Mark Watkin-Jones stepped down several years ago.
I took an instant dislike to his replacement, Richard Simpson. He struck me as smarmy and frankly, not someone I would like running my company. My mistake was to give him the benefit of the doubt. Now, I am not casting aspersion, Richard may well be a lovely, well intentioned chap, but his tenure can hardly be seen as a huge success given his subsequent sacking. My dislike of him and the fact one of his first acts was to institute a bleep bleeping LTIP for Management should have been my cue to cut and run. I despise LTIP's on principle, and I can't think of any company that has introduced an LTIP and suddenly gone on to great things. I am happy to be corrected there. They are simply a way for Management to help themselves to free shares/money especially when they are nil cost, as this one was.
In Richard and the company's defence they did face the unprecedented Covid crisis as well as the Liz Truss omnishambles of a Premiership and the Grenfell fire and subsequent cladding issue, but the company seemed to lose it way and has become accident prone. The new Management may well still be 'kitchen sinking' but they have been in charge for a year now so surely that would all have been done?
The dividend was slashed in 2023 and then finally cut, but the LTIP continued to pay out. Clearly Management deserve those free shares for doing such a good job of destroying shareholder value, and shareholders shouldn't mind missing out on their dividend.
Today's latest PW was the final nail in the coffin for me. I did buy some more circa a year ago on a previous PW. That was a mistake, as Mr Hindsight now shows me. But the turnaround that I expected has not materialised and it looks like it will take another year to eighteen months before we really see it.
The company is far from a basket case, their capital light business model should mean there is limited danger of bankruptcy etc. but frankly there are much better places to invest. Those places shouldn't need a year to eighteen months to start to make progress either.
Reading back over this post, and with Mr Hindsight's helpful insight, it's clear the warning signs where there a long time ago and I really should have sold out years ago. Lesson noted. Still, you can't win them all and even the best (of which I do not consider myself one) make mistakes. Thankfully it was one of my smaller positions so the lessons were not too expensively learnt.
You put all that so much better than I could Jeremy Rea, we'd had good profit from Watkin Jones under previous management and I made a bad mistake to think it would be repeated after their pandemic related struggles. This morning was ouch time here but I await Graham's measured comments before either joining you, doubling down or doing nothing. I could live with waiting a year or more and quite a few IHT avoidance funds have holdings, I also think the shortage of student accommodation is still in their favour but I applaud your decisiveness.
Thanks JASVFS.
Having thought on it a little more I think there are a few lessons I, and possibly others can learn from Watkin Jones (LON:WJG.
I'll post them here partly to help reinforce them in my own head and in the hope they may help others avoid similar pitfalls. With the double caveat that they are only my thoughts and the only Investors/traders who avoid losses and or profit warnings are those on Twitter who somehow magically always manage to sell at the very top and buy at the very bottom. ;-)
1) If a founding family, or the remaining member of the founding family, sell/step aside, that is a good time to reassess your holding with a bias towards selling. In this case I would have walked away with a solid profit.
2) Similarly, if the new CEO strikes you as the type of 'used car salesman' you would run a mile from, reassess your holding, with a strong bias toward selling.
3) If one of new Management's first tasks is to create an LTIP for themselves, sell. Especially if it is nil cost, as this was. I appreciate various opinions are available on LTIP's, but if Management implement one almost as soon as they take up their new role it tells you who the company is run for and where Management's priorities lie.
4) Catching a falling knife is dangerous. It's almost as if there is a clue in the name! proceed with extreme caution when attempting it.
Apologies that does somewhat duplicate my earlier post.
Again, those are merely my reflections on the Watkin Jones (LON:WJG) saga. Others will have done well by taking directly opposite actions. There are so many ways to make and lose money in this game.
Hopefully my ramblings help some avoid potential losses in the future.
Excellent post, Jeremy! Thanks for sharing your views on WJG. G
Watkin Jones (LON:WJG)
Unfortunately, the way this company has been communicating recently has (hopefully erroneously) reminded very much of Inland Homes, who went bust in Oct 2023. They always seemed to be winning contract after contract, but then went into liquidation in double quick time (all 20 group companies, I believe Secure Trust Bank had also lent them money,
----------------------------------------------------------------------------------------------
(In September 2023, Inland Homes, a property developer based in Bucks, appointed administrators and began selling off its assets. The company's collapse came after it admitted to breaching loan covenants with HSBC and Secure Bank Trust in February 2023, and said it expected to lose £90 million in 2022. Inland Homes also lost its CEO and the rest of its board in 2023. In October 2023, administrators FRP Advisory said they couldn't save any of the 20 companies in Inland Homes' group because there wasn't enough money to keep trading. They also said they had received expressions of interest in Inland Homes' assets, but couldn't predict when or how the assets would be sold. )
----------------------------------------------------------------------------------------------------
I have mistakenly held onto Watkin Jones through at least 3 profit warnings:
1)Fell 20% on 23/05/23.- bad trading report and big dividend cut - many orders delayed but not cancelled!
2) Fell 40% on 19/07/23.
3) THIS SHARE FELL ANOTHER 33% today (21/08/24) to 34,2P. Reduced profits forecast for Y/E 30/09/24 AND 30/09/25,
My note today : Too late to sell now - should fully recover eventually (famous last words),. Again buy no more until CERTAIN THE BOTTOM IS IN!
Good luck all here. Hopefully I am just paranoid,
Regards, blue2guit
Watkin Jones (LON:WJG)
I should have said I am a holder of both Watkin Jones (LON:WJG) and Secure Trust Bank (LON:STB) , and was a holder of Inland Homes (was INL).
Inland Homes website is still on the web, just as it was when it was wound up. IE promoting developments, extoling the virtues of the company etc etc, You would never know it isn't trading now!
Watkin Jones (LON:WJG)
Wow, just wow - has minnow Rosslyn Data Technologies (LON:RDT) secured a contract with Amazon? SP into orbit at the open!
https://newsfile.refinitiv.com...
https://x.com/CapitalPmh/statu...
Rosslyn Data Technologies (LON:RDT) Placing incoming?
Rosslyn Data Technologies (LON:RDT) Interestingly Paul mentioned the AI angle in the SCVR on 4th March:
"Looks very high risk, and a stale story (v poor track record), but it’s in a sexy sector - could sentiment turn on contract win announcements maybe? Claims that its new AI module, “offers a transformational opportunity”. One for optimists only!"
Company says today:
"The Customer was attracted by, amongst other factors, Rosslyn's agility and also the development work being undertaken, based on Rosslyn's AI solution, to automate the data classification process and to establish an enterprise-grade procurement data lake. Accordingly, the Customer and Rosslyn have also established a co-innovation partnership, with the Customer providing funding for the development of next-generation technology, including AI elements, to enhance Rosslyn's platform."
Rosslyn Data Technologies (LON:RDT) looks interesting now, once they have their funding sorted out.
One for the watch list
I guess Rosslyn Data Technologies (LON:RDT) is so small market cap wise that it doesn’t take much to shift it quite a bit higher. Don’t know anything about the company so no view but I think Paul Hill either does or used to own it so maybe he has a take.
.
Well done with the report on Anexo (LON:ANX) , Paul, and the read across to Secure Trust Bank (LON:STB) . I always appreciate your forensic eye for detail, and your willingness to stick your neck out even when a minority of readers quibble.
Agreed, very helpful but also a little worrying as the red flag and strength of concern is hardly evident anywhere in the Stockopedia analysis. ... 5 long screen ratings, Stock Rank 89 (Quality 85)
I think that this is perhaps the point? It's all very well mechanistically using metrics to filter or to rate, but it's the lens of applying knowledge to try and further understand a situation that is the genuine "value add" here for me, anyway! It must definitely helps my understanding!
(And, for me - I invested in Accident Exchange back in the day - from memory didn't fare too badly and got out with a c20% loss. I turned that experience into knowledge of a similar situation for Quindell, and successfully deployed bargepole and watched with popcorn to hand. Having no knowledge of Anexo, I'll research today... but suspect Paul's reading of the situation is compelling. As he says.... you're never forced to make an investment, so why make one when the risks appear to be outsized in one area?)
I was about to say the same thing. A stock that comes up on a number of Ben Graham screens. "ANX shares are priced at a large discount to NTAV - because the receivables contain an unknown amount which is uncollectable" and highlights a weakness of the Graham value screens. It serves to highlight the fact that screens are indeed only screens. In respect of the Graham screens they would benefit from a filter on receivables. Healthy balance sheets are so important. The useful flowie ratio that motley fool produces also a useful indicator of how ruinous this current assets to current liabilities is for the company. They deduct cash from current assets and measure this against current liabilities less short term debt. Around 8 times for this company when you'd expect something closer to 1 or less. if a company was managing its balance sheet well. The pitrioski score and z score also useful guides.
My morning smallcap tweet: Cut & paste done in haste
Watkin Jones (LON:WJG) Rosslyn Data Technologies (LON:RDT) Eco Buildings (LON:ECOB), Angling Direct (LON:ANG), Mobico (LON:MCG), Costain (LON:COST), Pebble Beach Systems (LON:PEB)
◄Watkin Jones (WJG)► warns FY-Sep adj op profit only £10m to £12m (£0.2m). Warns on FY25 as well. "Market activity through the summer has been slower than anticipated, principally due to the continued uncertainty over the pace of interest rate cuts, and as such we believe it is now unlikely that we will close any further transactions before the financial year end." [SP=50.9 Cap=131m]
◄Rosslyn Data Technologies (RDT)► guides FY-Apr rev £2.9m, in line and adj EBITDA loss £2.5m (£2.0m) and EBITDA loss of £3.3m, ahead of management expectations. "Focused on achieving positive adjusted EBITDA and cash generation on a monthly basis by the end of FY25." Also wins £2m+ three year contract. [SP=9 Cap=2m]
◄Eco Buildings (ECOB)► £450k placing at 10p, a 13% discount, to complete delivery on the previously announced 25,000 sqm order for wall panels. [SP=11.16 Cap=9m]
In line: ANG, MCG, COST, PEB
... And?
Waiting for a value added comment here to the Costain (LON:COST) results.
Welcome to Stocko :)
Can someone advise the best website to view daily buy / sell trades
ADVFN ?
Buy/Sell trade detail on places like ADVFN are highly unreliable. They are based purely on the assumption that any trade below the mid price is a sell and if above it's a buy. Worse, it's based on the mid at the time of the trade being reported, so large trades, reported late, are often misattributed. The graphs look pretty but are not something to attach any real significance to.
They are as good as you can get, so not so helpful in illiquid stocks, where there are many delayed trades. Obviously ignore the deignation of buy or sell which is calculated as described above.
LSE website - No specific buy or sell but at least its information from the horses mouth
Gattaca (LON:GATC) - the cash pile is deceptive
There was a good discussion last week in which various investors, Paul and me included, mulled over the huge cash pile at otherwise uninteresting, struggling recruiter, Gattaca. The bull case being that the cash represents over 75% of the market cap, making shares very cheap. And this at a time when the market could well be troughing.
The latter part of the bull case remains valid, but is equally the case for several far higher quality recruiters with comparably attractive charts. But, and I apologise for taking a while for the penny to drop - it’s been a while since I was operational in the sector - the cash is going to disappear if/when business picks up. Temp businesses are very cash-generative when temp numbers are falling, and cash-consuming when the numbers rise. Workers have to be paid well before the business recovers the cash from customers. Because the business runs on such low margins, this effect is greatly exaggerated. Consequently, any upturn is going to eat rapidly into the cash pile. Indeed, you can see this anticipated in the cash flow forecasts for the coming years, which anticipate a rebound in turnover and profit, but a fall in net cash.
Consequently, I see the current cash as protection against bankruptcy, but not as a straightforward offset against the market cap. It is working capital that will be consumed in the next upturn.
Good morning BnB
I defer to your better knowledge in the recruitment sector, but, having quickly compared Gattaca (LON:GATC) to Staffline (LON:STAF) and Robert Walters (LON:RWA) , Gattaca is the only one with an EV lower than the Market Cap.
If I follow you correctly, won’t that allow the company to increase payroll substantially, if and when the sector starts picking up?
The new business generated will lead to increased profits, and the cash pile will be stocked up again when the bills are paid. (Obviously, I’ve oversimplified here, but it still leaves them in a better position than others in the sector)
All the best (I hold)
If I follow you correctly, won’t that allow the company to increase payroll substantially, if and when the sector starts picking up?
The amount of cash available has no bearing on their ability to sell more temps - that is down to market demand and the capabilities of the salesforce. It simply lowers their cost of working capital. But only very slightly, because the cash pile is still very small relative to the cost of sales and hence their working capital requirements, which will accelerate rapidly in periods of high demand, as will turnover.
The new business generated will lead to increased profits, and the cash pile will be stocked up again when the bills are paid
The very low margins on which the business operates mean that profit accretion is slow relative to movements in working capital. So the business will have to wait until there is a downturn for the cash pile to be replenished as contracts roll off. This would not be a good point at which to try to bank investment profits as there will be none!
All that said, I think the balance of probability is that GATC will make you money in the short to medium term, simply on account of the stage in the business cycle. But that applies to all recruiters, most of whom are of rather higher quality.
Kromek (LON:KMK) results deferred again?? Were due out last week, and then again today?
I imagine you are getting your info on results release dates from Stockopedia which are usually just a guess based on last year’s dates. Try looking at the companies own investor relations web pages or email them asking for a definitive date.
Kromek (LON:KMK) stated in May 2024 trading update that results would be issued in September.
Thanks both. Yes Stocko date keeps moving forward ... I looked on the company website briefly this morning without seeing it.
Anexo (LON:ANX) I can't quite work out if you are positive or negative on this company's prospects!!! Haha
Thank you for your analysis on Castings yesterday Paul, the colour change is giving me pause for thought.