Small Cap Value Report (Wed 22 Feb 2017) - HOTC, PRSM, MCB, TMMG, LGT, NCC

Good morning!
Apologies, but I got distracted & was very tired yesterday afternoon (haven't been sleeping well lately), so I didn't get round to updating yesterday's article any further until early this morning. I've added new sections on dotDigital (LON:DOTD) and Utilitywise (LON:UTW) to yesterday's report, which is here.
It's quite difficult to clear the decks and write about companies here, because I've just got so much else going on during the day, constant distractions. Hence why it's sometimes easier to finish off articles in the evening, or early morning. Also, during market hours, It's terribly easy to drift into "ticker-watching" - where I end up just monitoring prices, and not actually doing anything constructive. Although having said that, ticker-watching can throw up opportunities, when you sometimes spot unusual price movements, and a jump in trade volumes - which can be turning points, or signs of someone stake-building, etc.
Right, on to the trading updates & results today which have caught my eye.
Hotel Chocolat (LON:HOTC)
Share price: 266p (up 4.2% today)
No. shares: 112.8m
Market cap: £300.0m
Interim results - for the 26 weeks ended 25 Dec 2016.
Seasonality - a key point to note with this company is that its profits are pretty much all generated in H1. This is important because, when skimming through the results at 07:30 this morning, I looked at EPS for the half year (of 7.8p), doubled it to annualise it, then thought hang on that doesn't look right, as it implied a PER of only about 16. Either the company has massively out-performed forecasts, or I've overlooked a large seasonal variance between H1 and H2!
It was the latter of course - I then checked back to last year's adjusted profit of £8.2m for the full year, and it looks as if more than the whole lot (£8.8m) was generated in H1. So H2 looks to be slightly loss-making.
Aside from forgetting about seasonality between H1 & H2, the other clanger I'm sure we've all dropped before, is forgetting that you're looking at half year figures altogether, and wrongly doing your sums based on them being full year numbers!
These pitfalls reinforce the importance of at least one strong cup of coffee before work starts at 7am.
Anyway, back to the figures, and the highlights look really good to me;
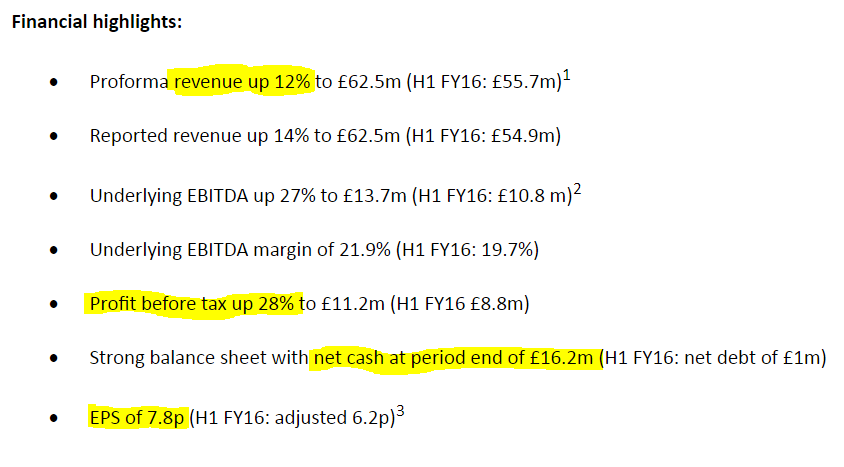
Revenue growth was helped by the opening of 10 new stores, which is quite a rapid rate of expansion in 6 months, giving a total of 93 stores at the period end. Mistakes happen if a retail roll out is done too quickly, so I hope they're keeping on top of the detail.
EBITDA margin - this needs to be treated with care, as the strong H1 seasonality will inflate this number considerably. It will be a lot lower for the full year.
Gross margin - is up 60bps, due to investment in the factory - important to note that HOTC makes its own product (I don't know whether they make all their own product, or just some - do any readers know?). The company even owns its own plantation in Saint Lucia, which I think adds nice credibility to this up-market chocolate brand.
Net cash - I nearly fell off my chair at the huge jump in net cash, but on closer inspection this is driven by a big increase in creditors. It's also a seasonal spike, after receipt of peak trading over Xmas. So expect cash to have dropped somewhat by the year end.
Balance sheet - overall the company looks financially robust to me, although there are a couple of unusual (but not worrying) items which I'll flag up.
There is debt of £6.6m in "Chocolate bonds", which looks to have been an innovative way to fund the business in the past. Although this debt is looking a bit expensive now. Mind you, if customers opt to receive payment in product, then I can see how it is a nice way of driving customer loyalty.
Chocolate bonds pay a return either in boxes of luxury chocolates or by way of a Hotel Chocolat gift card. For those bonds with a return in the form of chocolate, the coupon is fixed by number of boxes. For bonds where there is a return paid by way of a Hotel Chocolat gift card, there is a fixed rate of interest. The interest as stated on issue of the bonds ranged between 6.7% and 7.3%.
What a neat idea, I like it!
As regards creditors, this struck me as rather high at £25.8m, so have a look at note 6 giving the breakdown of this;
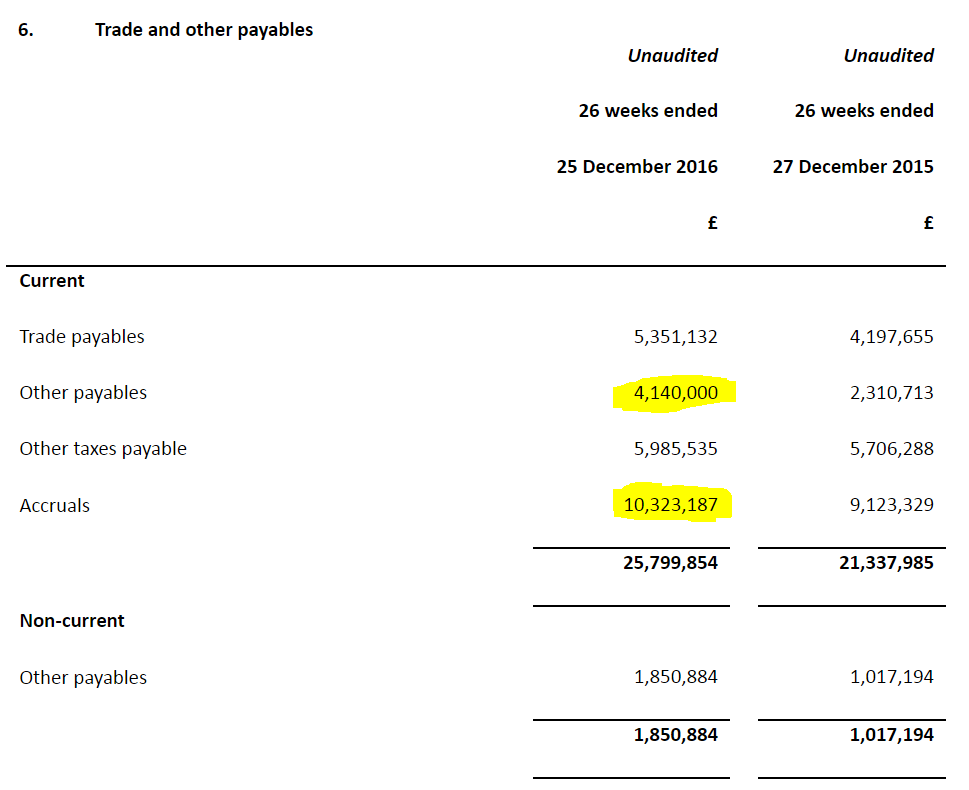
I've highlighted the unusual items above. Trade payables is usually the bulk of overall current liabilities. Yet here it is only about 20% of the total. Taxes payable - fair enough, that's probably the VAT due on Xmas sales. I'm not sure what the £4.1m "other payables", or the £10.3m "accruals" figures would be. Those numbers strike me as unusual.
Perhaps the accruals number is deferred income? For retailers this is landlord incentives for entering into leases (rent-free periods and reverse premiums), which appear on the balance sheet and are then gradually worked through the P&L over the period to the next rent review usually.
I don't think these unusual creditors are anything to worry about, but do bear in mind that they indirectly flatter the cash position.
Dividends - there's no interim, but the company says it intends paying a final divi.
Outlook - self-explanatory (below). It's trading in line, but mentions cost pressures.
Since the end of the period, trading has continued in line with expectations. The plans for the key Mother's Day and Easter seasons build upon the successes of Christmas, including improved gifts and children's ranges. The pipeline for new stores is encouraging with the new formats providing increased flexibility to adapt to different locations. We are in the process of finalising our next set of capacity and capability investments for our production facility in order to ensure we can both meet our growth aspirations and improve efficiency in the years ahead. The transition to the new website happened on time and now provides us with exciting growth potential.
The headwinds facing all retailers in the UK are widely projected to drive input cost inflation, however the Group seeks to mitigate these headwinds through a combination of vertical integration, UK-based manufacturing, and currency hedging. A strong differentiated brand that offers great products and customer service, priced as an affordable luxury also provides further mitigation, giving the Board confidence in the Group's continued progress.
The tone sounds upbeat, and the figures are good, so this business seems to be humming along very nicely.
My opinion - the business gets a firm thumbs up from me. These are smashing figures, and it looks a decent retail roll out, with a very nice brand & differentiated product.
Valuation? Hmmm, not so great. I've subscribed to Research Tree, to make it easier to look up broker research. Liberum has issued an update today, increasing its forecast adjusted EPS from 7.4p to 7.6p. The new figure gives a PER of 35 times this year's earnings. That's a punchy rating.
Moreover, in FY18 and FY19 the EPS rises forecast are not that big - rising to 8.2p and 9.4p respectively.
To my mind, if I'm asked to pay a PER of 35, I want to see much stronger EPS growth than that.
Overall then, I really like this company, but it's going to have to seriously out-perform forecasts to justify such a high rating. Maybe it will, I don't know. As things stand, personally I wouldn't be interested in buying any above 200p, and even that would be a stretch. So at 266p, it's definitely not for me, but for valuation reason only. It's clearly a very nice business, and could be one of those stocks where in future we'll all be kicking ourselves for being too tight to pay up for it now!
Blue Prism (LON:PRSM)
Share price: 485p (up 8.5% today)
No. shares: 62.2m
Market cap: £301.7m
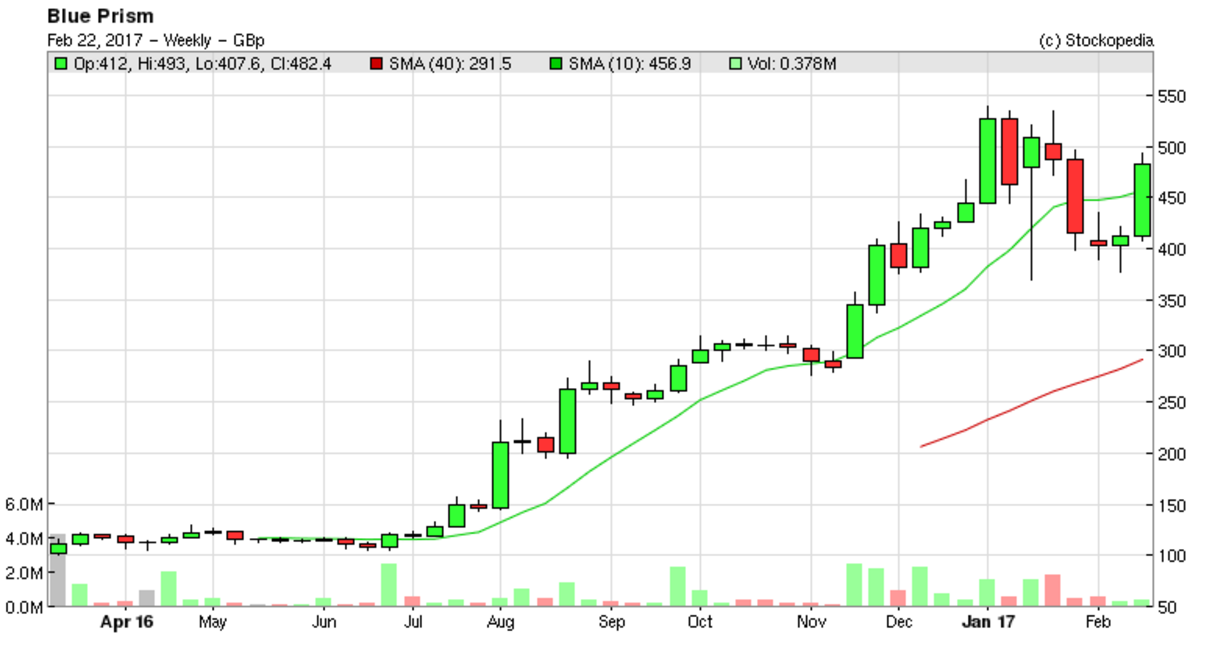
Trading update - this share has certainly captured investors' imagination since it floated on AIM in Mar 2016 - see share price chart below.
It's basically a software company which automates back office functions, at big companies like banks. The point of difference being that it works like a human, i.e. logging into various other computer systems like a user, and then carrying out processes which were previously done by humans, according to pre-determined rules. It sounds clever, and there are some impressive clients already using it.
The company has a 31 Oct 2017 year end, so it reports today on Q1 performance, as follows;
The Board is pleased to report that the positive trading momentum detailed in the Group's full year results for the year ended 31 October 2016 continued into the Period.
Blue Prism secured 83 new software deals, of which 49 were new customers and 34 were upsells to existing customers. All new deals were secured indirectly via the Group's channel partners.
Taking into consideration the above trading performance in the first quarter of the current financial year the Board now anticipates revenue for the full year will be materially ahead of existing market expectations.
Materially ahead suggests to me at least 10% above.
Directorspeak - says the company has a strong pipeline, and is confident.
Valuation - is basically impossible, the way I look at it. The company is growing quickly, but incurring increasing losses. That's partly because there are up-front payments to channel partners for each sale, which run ahead of the (high margin) recurring revenues from the end customer.
Given that things are at an early stage, nobody really knows what the figures might look like in the future. Clearly at £301m market cap, and with the company forecast to be loss-making this year and next, there are very ambitious expectations baked into the price. So if anything goes wrong, and the company fails to grow as expected, then expect a huge drop in share price.
On the other hand, if you're bullish, and believe this company is uniquely placed to dominate back office automation, then the sky could be the limit. We're in a roaring bull market, so people are happy to make very bullish predictions. For now.
My opinion - this is way too jam tomorrow for me, especially at £301m market cap.
Good luck to holders. Just a reminder though, that hardly any high-flying AIM jam tomorrow, loss-making stocks actually end up delivering what people hoped they would during the big bull run.
Also, I question whether what this company is doing is unique? Surely other software companies must be developing similar products?
I'm running out of steam now, so just a few quick comments to finish off with;
McBride (LON:MCB) - interim results to 31 Dec 2016 are out today.
- The headline figures look good - e.g. adjusted operating profit up 30.1% to £22.9m.
- However, it seems that forex translation into sterling has been a major contributory factor, with the equivalent figure in constant currency being much smaller, at +9.6%
- Turnaround strategy, of focusing on higher margin business is working well, with the operating margin up 120bps to 6.2%
- Balance sheet is OK, but note this is a capital-intensive business, with large fixed assets, funded by bank debt.
- Pension deficit has gone up to £41.8m, up from £31.1m six months earlier. Not a disaster, but worth noting & adjusting the valuation.
- Bank covenants - the company specifically states what they are, which is very helpful (e.g. Net Debt: EBITDA must be below 3x ). All companies should be required to publish their bank covenants (where applicable)
- Outlook comments are a bit wobbly, taking about cost price inflation, and a time lag between that being recovered from customers.
Full year expectations remain unchanged - so the fwd PER is 12 for this year, and a 2.7% dividend yield. That valuation looks about right to me.
Mission Marketing (LON:TMMG) - Growth Share Scheme - or a so-called "management retention and incentive scheme". Gone are the days when paying a decent salary to management, and a bonus in good years, and share options, was enough to incentivise them.
Apparently, to get these guys out of bed, they want to have a clear run at getting 5.7m free shares in the company too.
This is a terrible scheme - a complete con, in my view. The wheeze goes like this. Management (almost all Directors) have bought new A shares for 0.01p each (shelling out £570 in total, unless I've dropped a decimal place). If they can subsequently drive the share price up to 75p for 15 days or more, then their almost worthless A shares transmogrify into new ordinary shares, free of charge. Thus diluting existing holders considerably.
Given that the share price is currently 41p, then some might say, what's the problem? If they do get the share price up by 83% to 75p, then don't they deserve to cash in with £4.3m of free shares?
You could look at it that way, but I've seen similar things like this before. What can happen is that suddenly the Directors are dead keen to turn up at investor events, and will give presentations, and put out bullish RNSs until the share price is pushed up to the trigger point, and held at that level for a few weeks. The reward is then paid out, and the share price is then likely to crash back down again. Meanwhile management may have dumped their free shares, and can safely move on, with bulging back pockets. So retention of key people is not assured with this type of scheme at all.
Cynics might see this scheme as akin to a company-organised pump & dump.
Who on earth thought this would be a good idea? It makes the Directors look like a bunch of spivs. I sold my shares in disgust when this scheme was first announced. Although putting my cynical hat on, I suppose now that we know management are incentivised to ramp the share price up to 75p, then there's quite a strong argument for buying some at 42p, and seeing how they get on.
What a crummy, sleazy scheme though. Let's hope HMRC pull the rug from these schemes, and slap on a big tax charge.
I've never seen any convincing evidence that management incentive schemes work at all. In my view they tend to be counter-productive, attracting greedy, self-serving people to join a company in the first place. Then encouraging them to do reckless things, with no personal risk, to pump up the share price in the shorter term, leaving shareholders to pick up the pieces longer term.
Look what happened at £PEB when poor quality management cooked up fancy management incentive schemes, only to then run the company into the ground - gearing up to make acquisitions.
So a massive thumbs down from me to TMMG management, for cooking up this grubby little scheme to effectively steal some of the company from its shareholders, the way I see it. I don't think schemes like this create value at all. All too often they destroy value, by encouraging Directors to take stupid risks.
Graham has just emailed me the following section, per reader requests;
Lighthouse (LON:LGT)
Share price: 14.25p
(+16% yesterday)
No. shares: 127.7m
Market
cap: £18.2m
Final Results year ended 31 December 2016
(commentary by Graham Neary)
Some great results
for this financial advice group yesterday. The most important bullet
points from my perspective:
- PBT +119% to £1.9 million
- Revenues down slightly but up 2% if you adjust for the loss of platform-based trail commission.
- Revenue/adviser up 6% to £99k (from £93k)
Additionally: an asset management division was launched in October, and the final divi is raised by .02p to .18p.
Chairman comment:
The increase in average annualised revenue per adviser and change in revenue mix towards higher margin divisions largely offset the impact of the removal of platform-based trail income arising from the "sunset clause" introduced by the FCA to leave revenues and gross margin broadly unchanged. The above, together with an on-going focus on the Group's operational costs, resulted in a substantial increase in earnings.
The “trading highlights” box shows that operating costs were slashed from £13.2 million to £12.3, which more than fully accounts for the increase in operating profit.
As a general rule, it’s more valuable to see earnings growth via sales growth than from cost cuts – since there is a limit to how much costs can be cut, but there is basically no upward limit on sales!
But there is a sunny side to Lighthouse’s earnings growth, with the mix of recurring revenues continuing to increase (up to 50%, versus 48% last year), so the quality of earnings looks to be increasing.
There’s a sweetener to the results with a £750k tax credit too – be careful in case this affects some automatically calculated PE ratios!
Net Cash: Rises slightly to £8.1 million, but note that there is about £4 million of regulatory capital.
Outlook Summary: “well placed, with a solid financial position and net cash, to take advantage of opportunities”.
My opinion: It seems like a really solid set of results to me. The FCA’s reduction of trail commission for platforms such as Lighthouse was out of their control and is just part of the regulatory hazard of the financial industry.
The balance sheet doesn’t worry me at all. Cash flow is affected by growing provisions which is normal for new business strain.
Valuation looks
pretty attractive to me too, at less than 10x PBT with a decent
outlook. So I’d be fairly optimistic on the outlook for
shareholders here.
We're on fire today! Graham's also just emailed me a section on an interesting (as in disastrous) financial stock;
NCC (LON:NCC)
Share price: 99p
(-44% since yday)
No. shares: 276.5m
Market
cap: £274m
(this section written by Graham Neary)
Some dramatic news here as a planned Capital Markets Day was cancelled yesterday.
NCC operates two
divisions: Assurance (much larger in terms of sales) and Escrow.
The Assurance side – which includes Security Consulting, Software Testing and Web Performance – has seen reduced sales and profitability in the UK, Europe & North America. All services are affected, so it sounds like something systematic has gone wrong it.
Helpfully, there is an estimate of the damage: full-year EBITDA might turn out around 20% below the prior range, which was £45.5 million - £47.5 million.
Some fairly ominous pieces of text explain the counter-strategy:
In light of the deterioration in trading in the Assurance Division through the current financial year, the Board is initiating a comprehensive review of NCC Group's operating strategy. This will include a review of all of the Assurance businesses, how they operate and how they sell.
In addition, given that the significant and planned rise in central and divisional operating costs this financial year has not produced the anticipated improvement in sales, there will also be a review of how the assets and resources of the Group can be more efficiently deployed and utilised.
Consultants are being appointed to support the review – often the precursor for difficult or unpopular decisions.
My opinion: One might argue that a 20% reduction in EBITDA doesn’t warrant a 44% slide in the share price, but for things to take such a sudden turn for the worse in Q3, across multiple services and geographies, should rightly spook shareholders.
Also, NCC has been pursuing an acquisitive strategy, with a lot of amortisation/exceptionals in the accounts recently, so EBITDA of £37 million might not translate into very much profitability, depending on what sort of restructuring costs might be in store.
Last year, there was £19 million in exceptional costs as well as £8 million in amortisation and share based payments. Those exceptional costs included goodwill impairment, restructuring, write downs of development intangibles, and acquisition costs.
It strikes me as quite a lot of exceptionals and makes me wonder a bit about the quality of real earnings here.
Net debt at November 2016 was £49 million out of total facilities of £112.5 million, so at least there is good headroom.
But with so many moving
parts, I would have marked down the shares by about 50% after this
RNS.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

42 comments
Re:TMMG - I for one certainly hope they are planning for a pump and dump
As that'll give me the opportunity to sell out of this company !!!
As I too, am appalled at the need to incentivise what are already well paid executives
Glossy article in yesterday's Saturday Telegraph magazine on Hotel Chocolat (LON:HOTC) . Great scoop to have it placed the week before the Easter chocolate binge positioning the confectionary company as a broader "lifestyle brand" doing good things with local farmers in the Caribean while taking chocolate from being a commoditised treat for the kids to an aspirational purchase for "right on" metropolitan adults. Kind of Willy Wonka meets Jamie Oliver meets Terence Conran. Marvellous.
I agree with Paul's original comment that the shares look expensive (even more so following a further rise since the original commentary in February) on conventional metrics but having balked at buying Fevertree Drinks (LON:FEVR) at 500p on the same grounds at the start of 2016 (now north of £15), I can't help thinking that I might be missing a trick here as another premium brand takes root and appears to defy gravity. May just have to have a nibble ......
Best,
Gus.
Gus
You may want to read up about the rise and fall of Thorntons, the premier chocolatier. They had a great business until they crashed and got rescued by Ferrero, the Italian company. 2014 or 2015? This is just my recollection and can't remember the full background. Could be worth researching before you commit your funds to HOTC .
Thanks Ram - will do. I am by nature more of a Value investor who gets a nose bleed when the p/e gets above 20 so I'll probably look but not touch for now. It does intuitively seem like a decent business which is probably sufficient reason for me not to jump in based on previous experiences.
Best,
Gus.
Well I agree obviously that one's opinion should be based upon facts. Its a fair criticism that one should be able to back up statements with evidence. At the same time what about your statements you made about cyber security. How do you know about the subject? Do you have some qualification or are you expressing something you learned on the internet.? Nowhere do you present any evidence to back up your statements.
Cheers,
Al
Well I agree obviously that one's opinion should be based upon facts. Its a fair criticism that one should be able to back up statements with evidence. At the same time what about your statements you made about cyber security. How do you know about the subject? Do you have some qualification or are you expressing something you learned on the internet.? Nowhere do you present any evidence to back up your statements.
It's my day job. The only facts I have stated are to describe how the internet works which is pretty common knowledge. I also understand the range of services that NCC provides and the market they address and that this has no relevance to cloud providers - this is not the target market at all and I think you will find beyond a point companies like AWS leave you to your own devices e.g. network penetration testing which is exactly what NCC do.
If you believe the internet is not constantly prone to cyber attacks ranging from 14 year olds in their bedrooms to nations states with buildings full of highly trained hackers, then you must be living on a different planet to me! There is totally a place for companies like NCC, particularly as things will get exponentially worse with the Internet of Things.
All the best, Si
How on earth was a non executive director allowed to buy shares in Treatt (LON:TET) a couple of days before their great announcement today? Surely this is insider trading (or have I not understood the rules)?
Amazingly good statement from Treatt today - will really look forward to your write up later I hope
Thanks for the write up on NCC (LON:NCC) Graham. I bought some of these shares before all the profit warnings rolled in. Fortunately I felt that the valuation was quite high at the time so I only dropped a very small amount of money into this. This sector is still very appealing to me and I hope that they can get things back on track.
Re NCC, the share price drop is undoubtedly as a result of the total lack of confidence now in the management of the company - you can read my comments here: https://sharesoc.wordpress.com/2017/02/22/ncc-group-all-credibility-gone/
Thanks for writing about NCC (LON:NCC). It seems they made a bunch of acquisitions without knowing what they were doing.
I see they raised £124m last year, which went to fuel acquisitions. That's a bit of a red flag right there. IIRC correctly there was some criticism over the price paid, too.
FTAlphaville today reported on comments made by Cannacord: "On our new forecasts, the stock trades on 17.3x 2018 earnings" and express an "ongoing concern about the weak cash conversion linked to accrued income".
Considering the hash that NCC has made of things, it's difficult to see how that rating is justified.
All a bit of a mess, really.
Really appreciate the effort you've put into today's report. Thanks gents.
Great use of the word transmogrify Paul!
Agree HOTC is pricing in a premium rating at the moment and any missteps will be painful. However the other change over the next few years is the revenue mix where expectations are that online revenues will continue to grow, and the 23% growth announced today is a good sign this is moving in the right direction. This should drive group margin expansion as online will be less capital intensive and higher margin.
The shares looked expensive when they listed last May and have risen 40% since. I decided against dipping my toes in the water back then on valuation grounds and have missed out as a result. Although to be fair, IPOs often over promise and then under deliver, so on the whole, I don't mind being a little circumspect and waiting for tangible delivery.
Completely agree with your comments on Mission Marketing (LON:TMMG) management helping themselves. It nearly went bust in 2008-9 and the management want a special reward scheme! Thanks for drawing everyone's attention to this.
I am a long term holder, BUT I really hope when they are in front of investors they get the Alex Ferguson "hair dryer" treatment.
In fairness to the mgt team at TMMG - I think their business and record is miles apart from PEB.
It was a new mgt team that rescued TMMG in 2010 and since then they have reduced debt considerably and increased EPS.
Their track record of Robert Day and Peter Fitzwilliam is good (completely different to the Vislink story)
TMMG is in effect a holding company with 3 staff members. The Board appears so large because the directors of each agency is also on the Board. These directors are in effect mini entrepeneurs and are doing a day job as well as being on the Board.
The business has a track record of EPS growth, debt reduction, and dividend growth
Shareholder communications are clear and the website informative
A very high % of their client base has stayed with the firm for 10 years
Over c.20% is going to senior managers - not huge but significant.
The mgt team own 40% of the shares so a 'pump and dump' is not likely as they would be destroying their own wealth.
In specific numbers
- the dilution is 6% of the company if it doubles in price
- the mgt team are getting 12% of the gain between today and 75p
If 75p is achieved ....
- it will be the highest share price in over 10 years,
- it will be 75% above a range bound price over the last 3 years
- it will be 7.5 times the share price of their rescue rights issue 7 years ago.
And for clarity of my opinion ...
are the directors very well paid - yes
is their pay excessive compared to other companies with EBITDA of 10m - probably not
should they need an extra incentive or reward - no
has the company weaknesses - yes
- high intangible on B/S
- uses good CASH flow to make in fill acquisitions (in fairness not unlike NFC)
- people based business so profits can walk out the door (maybe GSS prevents this?)
So it is far from a perfect company, and it is not a model example,
but I do feel it is miles apart from the situation at Vislink.
The mgt team do already own 40% of the business (so shareholder friendly has an interesting context!)and as, on most metrics, the share price is lowly valued,
I think this puts a floor on the share price (back up by chart) and is a good trading opportunity with FINALS only 4 weeks away and the mgt now incentivised (even more to double the share price)
declaration: I first bought in 2010 and currently hold
Thanks for this: we are both long term holders of Mission Marketing (LON:TMMG) and we both agree management should not need an extra incentive or reward.
On the 40% ownership: I have worked at a couple of stockbroking firms which were 100% owned by management. Yet that didn't stop the management putting their own self interest ahead of that of the organisation. Those stockbroking firms have not survived.
PERHAPS the shares Mission Marketing (LON:TMMG) are lowly valued because investors think that management can not be trusted. Or investors feel that management are more keen on feathering their own nest, rather than creating a valuable business?
Re Mission Marketing, if you own 40% of the shares isn't that incentive enough??
Interesting announcement just now from Purplebricks (LON:PURP) about US expansion and a placing. It'll be interesting to see if this gives it a big leg up tomorrow. Suddenly the £500m market cap looks cheap! Shame the placing isn't open to private investors though.
Yes, very interesting from Purplebricks (LON:PURP). It's a huge opportunity, but there's not a great track record for UK businesses expanding into the US.
Given the placing is only at a 0.6% discount I don't think we can complain too much, although I expect the market reaction will be positive and the price may rise further. Maybe someone in the market knew what was coming and that helps explain the recent price rises?
I topped up my holding today - I would have bought more if I had known!
Just reading through the PURP release and the US market is unsurprisingly enormous:
"The Company's management estimates that total real estate commission income in the US is in the range of c. US$70 billion annually (compared with US$4.3 billion in the United Kingdom)."
Partly because the fees charged in the US are incredibly high at 7%...
"The Listing Agent will agree with the seller a commission (typically up to 7 per cent of the sale price) and list the property on a Multiple Listing Service (MLS)"
I'm a happy PURP holder but I need to do a lot of work on understanding the US market better. Obviously the opportunity is huge but the US has been a graveyard for a few UK expansions and I wonder how the incumbent competition will react to this.
The problem for cybersecurity testing as a business right now is that most companies aren't going to pay for it unless they have to. The financial penalties for screwing up tend to be minimal. It's only in extreme cases (TalkTalk, for example) where it plays into execs leaving or a long-term suppression of the share price or of profits. There has been talk of insurance companies demanding tests to determine premiums but, with costs and penalties still manageable, that's not likely to happen.
If there is a change in legislation (unlikely in the UK and US, possible in the EU), then the market becomes more valuable. But, until then, it's something that looks to be a big market that really isn't – unlike subscription security software services like antivirus, email scanning etc.
NCC management believe that the EU General Data Protection Regulation which comes in to force in 2018 will bring in more work for their assurance business. The fact that we are supposedly leaving the EU is irrelevant. Whilst Britain may not be a signatory to this regulation, it will require compliance if identifiable data is held for EU citizens.
@ JohnEustace you would think Cyber Security firms would be booming but does not seem to be the case. The US listed Cyber Security firms have been treading water at best and in some cases the bottom has fallen out (Fire Eye).
I read somewhere that the advent of migrating software to the cloud such as to AWS and Azure has changed the dynamics of the industry. The cloud services companies provide cyber security services as part of their client services so previously some of the cyber security needs of individual firms migrated to the cloud providers which decreased the addressable market. I have never looked at NCC in great detail so not sure if that applies to them.
I read somewhere that the advent of migrating software to the cloud such as to AWS and Azure has changed the dynamics of the industry. The cloud services companies provide cyber security services as part of their client services so previously some of the cyber security needs of individual firms migrated to the cloud providers which decreased the addressable market. I have never looked at NCC in great detail so not sure if that applies to them.
I assume you probably read this in an Amazon Web Services marketing brochure because unfortunately it is false and the worst kind of misleading rubbish possible!! To connect to any cloud service you need to use a computer network (normally using a web browser on a PC or mobile device) which is connected to the internet through a series of routers before it even gets to the cloud service provider network and at every step of the way the security of your connection and data is open to cyber attack. It is the devices, networks, routers etc. that NCC helps to secure from attack and for most companies their current security apparatus is totally inadequate. It may well be that the cloud provider has impeccably secure network infrastructure of their own, although I somehow doubt it and it can be safely classified under "they would say that, wouldn't they".
Unfortunately, it's not the first time I've read comments like this. I didn't want to start a technical discussion and I'm only replying because it's important that false information is not allowed to grow legs which it can easily do on the Internet. Cloud services are no more immune to cyber attack than anything else you do using a PC or mobile device to access the internet. If you want ultimate security use a PC not connected to any network or the internet sat inside a Faraday cage! :-)
All the best, Si
Your assumption is incorrect. It was from one of the tech blogs I regularly read. Unfortunately I can't remember which one I would have to do a search for it.
I also just have a basic understanding of networks etc... but the point being made in the blog post was not that individual companies needed to forgo basic cyber security just that they did not need as broad spectrum of services as was anticipated several years ago. Hence the Cyber security market was thought to be much bigger than what reality is currently showing.
Like I said I don't follow NCC but their numbers seem to indicate they have a sales problem or their technology and services are not competitive.
Cheers,
Al
Sorry, my assumption was meant tongue in cheek, but it's important that we only deal in facts here so that people can make investment decisions. This thread has a few "I read somewhere..." or "A mate told me..." type posts which frankly are not good enough for a high quality discussion, particularly where they are used in hindsight. Let's have links to references we can all read to make our minds up and leave conjecture passing as fact to other lower quality discusson boards.
All the best, Si
Yesterday I attended a E&Y USA web presentation in regards to tax automation in the US using RPA. According to E&Y there were 2200 participants. Blue Prism was mentioned by name along with two other companies as leaders in the field. One of them is a wholly owned subsidiary of Pega Systems a Nasdaq listed company which isn’t a pure play in the space and the other named company was a private entity. E&Y made a strong financial case in having software robots do some of the mundane and repetitive task related to tax preparation and filing. Judging by the feedback from the questions asked and the poll results I think the topic was fairly new to most participants. This is merely my impression but I think they certainly raised interest where there was previously none. Also full disclosure I am a shareholder since the IPO.
I understand that people use the dot bust as a cautionary tale and unlike many of the companies in that era I see that there is true economic value in Blue Prism propositions. The industry is at the land grab stage so at this point in the short term profit are irrelevant and I understand that would be a sticking point to quite a few people. Revenue is increasing rapidly and the last time I check 83% of it was recurring. Once Blue Prism’s or their competitors product are implemented in a client organization there is a switching cost in time and money in changing RPA provider. I also see the possibility of existing clients adding additional software robots once they are comfortable and happy with their initial experience.
"Outlook comments are a bit wobbly, taking about cost price inflation, and a time lag between that being recovered from customers."
Paul, this time lag may well be related to the increase in the price of crude over the last few months and McBride (LON:MCB) perhaps now coming to the end of their forward buying contracts for cheaper petrochemicals-derived surfactants used in their foaming products (shower gel, washing-up liquid, shampoos, etc.). There could well be a time lag of several months before they are able to pass those raw material price increases on to their customers who may have fixed-price supply contracts of longer durations.
The valuation of IT / Software companies like Blue Prism (LON:PRSM) with its stratospheric mcap show how more moderately valued some of its peer group companies such as D4t4 Solutions £D4T4 are, having a mcap of only £55m, profitable and paying a dividend. Lots of chasing hot growth / story stocks at the moment and it will end in tears for some.
Could the Hotel Chocolat (LON:HOTC) accruals be unredeemed gift vouchers?
Thanks for PRSM write up Paul, I had thought I was missing something in the big rise... but the market/buyers are focusing on revenue growth and ignoring the fact they are loss-making and make no mention of whether these losses will increase or decrease; so "too jam tomorrow" I totally agree with and will avoid... it's almost harking back to the tech bubble mentality, and we all know what happened then :-/
I believe I am right in saying that Berkeley Energia (LON:BKY) were among the companies present at the ShareSoc event in Altrincham last night? If anyone went along I’d be interested in any views.
(I hold a position in £BKY)
Many thanks, James
Blue Prism (LON:PRSM) has issued an upbeat trading statement today. It seems strange that it was preceded by a broker reduction in forecasts.
In January, Accenture announced plans to certify more than 600 people on Blue Prism's robotic process automation technology, and today's update says that all the new customers have come through agents. Despite the current and forecast losses, I'm beginning to wonder whether this might be the ealy days of a major software superstar.
I don't hold - I dismissed it at IPO as a story stock :-(
FREng - Re. Blue Prism (LON:PRSM) Just a note of caution. The RNS says revenues will materially exceed. Doesn't say anything about impact on the bottom line. If you look at the historical data losses have been widening and current broker forecasts are higher losses.
Whether this RNS results in the co. moving into profit is a moot point. Personally I'd like to see a trajectory of closing the gap. Until such time I'll remain on the sidelines.
There have been numeral waves over many years of squeezing back office costs via better processes and more automation. I am not totally convinced that Prism have a compelling offer, let alone a silver bullet. Could be wrong.
Paul, I see NCC has fallen almost 50% since their announcement yesterday afternoon. Is this one you follow at all?
Hi John,
NCC (LON:NCC) is outside my remit, as I don't usually cover financials.
However, I have flagged it to Graham, and am hoping that he might be able to write a section on it, for me to copy/paste into today's article, later.
Regards, Paul.
although it is one of those price dislocations that open trading opportunities:: came up on my opening gap scan I run each morning, nice tactical trade with a tight stop
Re NCC (LON:NCC) , the excellent TechMarketView notes that the escrow business is half of NCC's revenue and performing in line. they add: " We think public and private sector demand for cyber security software and services will remain strong in 2017 and NCC Group is well placed to capitalise. However some organisations may be putting consultancy projects on hold until the regulatory uncertainty caused by Brexit, the EU’s forthcoming general data protection regulation (GDPR) and Network and Information Security (NIS) directives, whatever “equivalent” UK legislation will eventually look like, and EU-US data sovereignty issues dissipates. Market dynamics may also be impacting NCC’s performance, with business lost to other consultancies like PwC, and large SITS suppliers such as BT, HPE and IBM combining advisory projects with product implementation and service delivery."
Current shorts on NCC run at 5%+, 6 different asset managers, 4 of them in last month. 4 months back a friend in the industry was quite negative on NCC management abilities, when he saw i had them in my portfolio, should have listened to him.
I bought some NCC (LON:NCC) after their initial profit warning then thought better of it and got out quickly. The management must be doing something badly wrong to make a mess of things because it strikes me that they should be in a massive growth area.
So it's further support to all the recent Stockopedia research about avoiding profit warners for a good year after the warning - and ask your friend for us who he does recommend in this space?