Small Cap Value Report (Wed 22 July 2020) - WIN, TSTL, CALL, DISH, SGC, QXT, BLTG

Good morning, it's Paul here with the SCVR for Wednesday.
Today's report is now finished.
.
Wincanton (LON:WIN)
Share price: 187p (up 9% today, at 11:42)
No. shares: 124.5m
Market cap: £232.8m
Wincanton plc ("Wincanton" or the "Group"), the largest British third-party logistics company...
This update today sounds excellent. Key points;
Underlying profit before tax for FY 03/2021 significantly ahead of current market forecasts, and not less than £30m. That's assuming no resurgence in covid. Various contract wins (Waitrose & Morrisons) & renewals are mentioned.
Improved demand across most of the business.
Liquidity/debt -
Cash collection and liquidity management remain strong and current net debt remains significantly below the prior year position, primarily due to the deferral of payments.
As I keep saying, companies must disclose how much tax they have deferred, otherwise cash/debt figures are meaningless & misleading. In this case at least the company admits that the reduction is net debt is mostly due to tax deferral, although I would have preferred to see the numbers in a table clearly separating out the short-term benefit from deferrals. Remember these deferred payments have to be paid up by end March 2021. Here is the Govt guidance on VAT deferrals.
My opinion - this seems a good company, clearly experts in logistics. I explained here why the balance sheet is such a mess. The pension fund in particular is an ongoing, and very large, cash drain. That rules it out for me, but for people who don't worry about balance sheets, then there's nothing to stop the shares going up. With a very good update today, this share looks like it's going higher in the short term. At some point I think it will need to do an equity fundraise to fix that balance sheet.
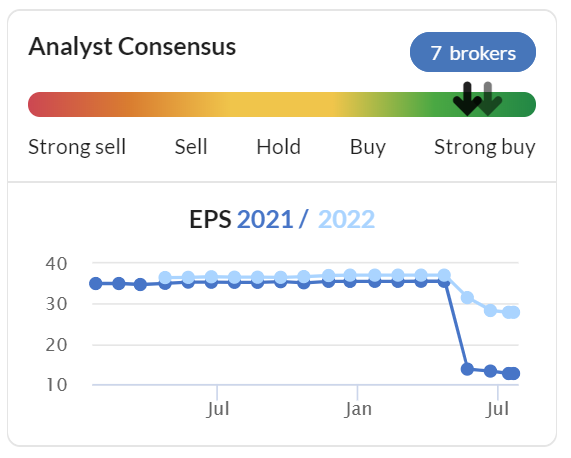
Whilst a beat against expectations is good, it seems that forecasts were reduced far too much, given that a lot of its business is defensive stuff like supermarkets. The darker blue line below is the current FY 03/2021:
.
Tristel (LON:TSTL)
Share price: 410p (down 12% at 08:26)
No. shares: 45.3m
Market cap: £185.7m
Tristel plc (AIM: TSTL), the manufacturer of infection prevention products, provides a trading update for the year ended 30 June 2020.
A reader posted below saying that this update looks good. The market seems to disagree, with the share price down 12% at the moment. Hence I've moved it up my running order, and will see what's what.
This sounds rather good;
The Company confirms that results will be ahead of market expectations and expects to report turnover of no less than £31.6m (2019: £26.2m), a 21% increase, and adjusted pre-tax profit (before share-based payments) of at least £6.8m (2019: £5.6m), a 21% increase.
There must be a sting in the tail re outlook comments then.
Covid impact - this is a rather long-winded explanation, so here's the key bit;
Commencing in March, the Company experienced two powerful countervailing forces:
1) a decline in the use of its medical device decontamination products as hospitals worldwide postponed all but the most critical patient appointments to free up resources to deal with COVID-19 related cases, and
2) a surge in purchasing and use of its hospital surface disinfection products.
During the last four months of the year, when the impact of COVID-19 was at its greatest, global sales were £11.8m compared to £9.1m in the same period last financial year, an increase of 30%.
That sounds reasonable, but I would want to know if the gross margin is similar, or different, for the two lines of product.
Note that the surface disinfection products rose from 9% of revenues pre-covid, to 27% of revenues during covid. This looks to have proven an excellent cushion for reduced sales in the other, main product line. I'm wondering if this could be maintained long-term, alongside a recovery in the main product line, which could be a nice driver for increased profits?
FDA approval - as I would expect, there's been a delay due to covid. This is part of the high valuation of the company, i.e. hopes for FDA approval and the opening up of a large new market.
Outlook - rather long-winded again, but maybe this bit has spooked some investors?
We have some concern that the UK, which will account for approximately 35% of our global medical device decontamination sales this year, might lag behind our other markets in catching up with the patient throughput...
"We are cautiously optimistic for the Company's prospects in this financial year and beyond."
Maybe cautious optimism isn't enough to support a high rating?
Forecasts - there's an update note out today, this is how the figures look, which I've adjusted for the current share price of 410p;
FY 06/2021: fc EPS 12.3p, and divi of 6.3p = PER of 33.3, yield of 1.5%
FY 06/2022: fc EPS 12.7p, and divi of 6.5p = PER of 32.3, yield of 1.6%
That looks pricey to me. However, if you think the company could beat forecasts, and price in the future benefit of possible entry into the USA market, then I can see how this valuation could be justified.
My opinion - I've followed this company for years, and think it's a decent, growing, high margin, niche business.
My concerns relate solely to valuation, which has looked very rich for some time. I'm not attracted to this share at the current price.
If you like the company, then today's drop could be a long-term buying opportunity maybe? I personally wouldn't pay more than say 20 times current year forecasts, so about 250p is the level where I'd get interested.
EDIT: Many thanks to blueskyventurer for providing this link to Tristel's presentation slides. End of edit.
.
Cloudcall (LON:CALL)
Share price: 75p (up 5% today, at 09:39)
No. shares: 38.8m
Market cap: £29.1m
(I'm long)
Investor presentation online is today at 14:30 - signup link here. I wanted to submit a question, but cannot find the "ask a question" button. I usually watch the recorded version in the evening, as too busy during the day.
CloudCall (AIM: CALL), a leading cloud-based software business that integrates communications technology with Customer Relationship Management (CRM) platforms, announces the following trading update for the six months ended 30th June 2020
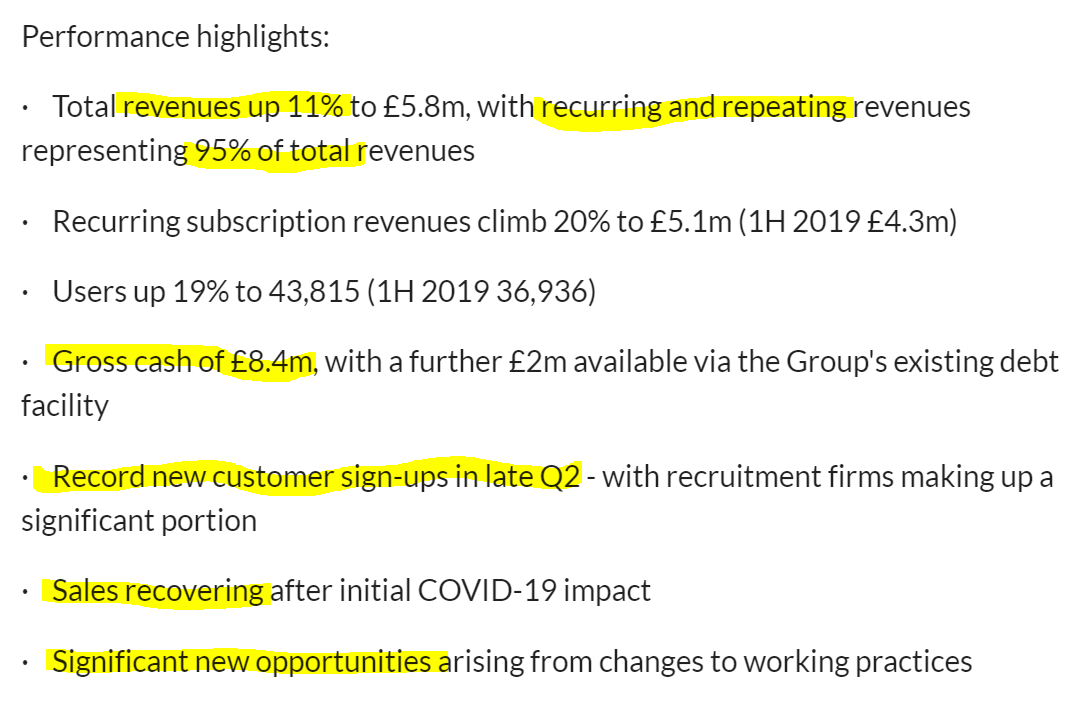
To save me some typing, here are the main points, with my comments below;
.
.
Covid has obviously had an impact, which is as I would expect, so the slower growth rate in H1 doesn't concern me. That's a known factor, and is already in the price.
What's more important is that things are now recovering. Hence I think the market is likely to focus more on the positive current trading "record new customer sign-ups in late Q2"
Plenty of cash, following the big fundraising last year, so cash burn of £250k per month is fine for now, it won't need to do another placing for a while, if at all. The change in strategy from lots of small, sometimes botched, fundraisings, to one big fundraising last year, was sensible, and the timing lucky.
The market is supposed to be forward-looking, so a one-off hit from covid is something we should be looking through. Although that memo doesn't seem to have reached a lot of AIM investors! That provides buying opportunities I think, so one person's poor results are another person's buying opportunity. Take your pick.
Work from home trend should be good for CALL. The integration with Microsoft Teams is beta launching in August. There's some good stuff in today's update, although we always get exciting-sounding updates from this company.
Guidance - 2020 revenues in line with 2019. Without covid we would have been looking at 20-30% growth, so it's been unhelpful but not disastrous. No guidance given for 2021.
My opinion - AIM just isn't the right place for this share. There's a massive tech boom going on, especially in the USA, where CALL would be valued at multiples of the current valuation, with so much private equity money chasing up growth stocks. Given that CALL has a good chunk of it business in USA, it's encouraging that a couple of US tech investors have cropped up with major shareholdings, and apparently were keen to properly fund the company in the last placing. American investors are far more ambitious, and longer-term in their thinking. It's a pity we can't get some of that to rub off on the UK markets, where all too often growth companies are starved of cash, and miss big opportunities due to a focus on achieving breakeven/profits too early.
I think this share looks dirt cheap, if you look at it in the context of tech valuations elsewhere. I'm hopeful of a premium priced takeover bid at some stage. In the meantime, it's taken a hit from covid, and is now recovering.
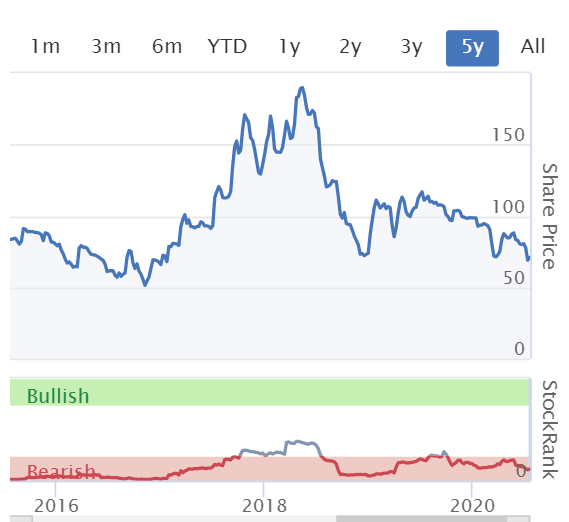
The bearish argument for this share, is that it's taken years to grow, and is a constant cash burner, usually missing forecasts. So I can see why some investors are tired of it. If so, then just sell up & move on. As you can see from the 5-year chart below, it's been disappointing but not disastrous so far. Of course that doesn't matter in the slightest. It's the future that matters.
.
.
Bigdish (LON:DISH)
Share price: 2.4p (up 14%)
No. shares: 364.2m
Market cap: £8.7m
(I'm long, disclosable stake)
Statement re share price movement
This share is wildly speculative, so should come with giant, flashing neon warning signs!
I've taken quite a big stake in it, because I like the potential multi-bagger potential, and am perfectly happy with the elevated risk.
It's in the process of adapting its business model for the umpteenth time, to morph into a booking platform (not just discounting), offered free (initially) to restaurants and takeitaways, in order to disrupt the price-gouging platforms like JustEat, Deliveroo, UberEats, etc.. A very ambitious goal, for sure! The idea is to get restaurants to sign up by offering it free (don't laugh, plenty of successful online businesses started that way), thus incentivising the restaurants to promote BigDish to their customers, in order to boost their profits. That should in theory reduce the need for a big marketing budget to end customers.
BigDish has an existing IT team in the Philippines, and a proven telesales team in Manchester. Therefore, it should have what it needs to roll out the revised business model.
On the downside, it needs to raise more cash (I'm confident that can be done, from a strategic investor, not from the UK stock market - note it has a full listing). It last raised money at 7.2p from a US investor, last year.
What's all the excitement this week then? The share price began rising yesterday, and someone on the advfn board (a nest of nutcases & vipers) posted a link to BigDish's Twitter account, which teased that it had signed up a national pizza chain. A bit naughty, but this company's communications are often quite chaotic & counter-productive! That's just the way it is.
Today's RNS was probably prompted by the trigger-happy Tweet. It confirms that Pizza Hut has signed up for the BigDish platform;
The Company notes that Pizza Hut has registered for the government's Eat Out To Help Out scheme. Pizza Hut have agreed to join BigDish in order for BigDish to amplify Pizza Hut's participation in the initiative. The Company will be seeking to add more restaurants who are participating in the initiative. As previously announced, the Company is not charging restaurants to join BigDish in order for BigDish to amplify participation in the Eat Out To Help Out initiative.
My opinion - I'm fully aware of all the bear arguments against this company - pre-revenue, cash burning, needs a fundraise, etc.
However I also see potentially multibagger speculative upside. Restaurants and takeitaways desperately need a yield management platform, to spread out business more evenly throughout the week. This is exactly what BigDish is designed to do. By widening the concept into disrupting existing intermediaries like JustEat, there's a potentially nice outlook. The telesales team is already in place, so hopefully we might see progress resume, after the hospitality sector slowly comes to life again.
Signing up Pizza Hut is an undoubted coup, and is a nice reference client, to help the sales pitch to other chains, plus independents of course (desperate to try anything to survive, so I'm expecting recruitment of restaurants to accelerate).
This is far too risky for most investors.
The share price seems to be in the hands of day traders, and volume is consistently very high, considering how tiny the market cap is.
.
Stagecoach (LON:SGC)
Share price: 54p (up 7% today)
No. shares: 550.2m
Market cap: £297.1m
Preliminary results
Stagecoach Group plc - Preliminary results for the year ended 2 May 2020
Several readers have asked me to look at this, so I'm working on it now. As I'm not familiar with the company, it's going to take me a bit of time to plough through everything, so this section should be up by 13:00 to 14:00.
Here are my initial notes / to do list so far;
Focused on bus operations now (8,300 vehicles) - rail franchises have ceased, and not bidding for new ones
Available liquidity of £800m - sounds a lot. Key issue is terms & availability of debt funding - more work needed on this.
Will lenders force it to raise equity? Dilution level/price?
Current trading is EBITDA positive, due to Govt support measures - how come? Subsidies increased for routes? What is subsidy formula?
Was performing well prior to covid. Little point in analysing P&L, since it's now historic/irrelevant due to covid causing plunge in customer numbers
Pension deficit - look into this, how significant?
No divis for now, as I would expect. Scope to resume future divis?
Recovery potential, if covid is beaten? Time needed for customers to return? Permanent loss of custom? (or will things return to normal over 2 years, as typically happens with air travel/terrorism, etc?)
Outlook - what I like about this, is that it sounds like the business is operating around cashflow breakeven. That should buy time to survive & come out the other side of the covid crisis. That's a much more appealing investment proposition than say airlines, where the business case could be permanently broken, and they're burning cash on an epic scale in the meantime.
With the continuing uncertainty of the COVID-19 situation and the UK's recovery, it remains difficult to reliably predict profit for the new financial year ending 1 May 2021. In the short-term, the actions we have taken and the continuing support of government should ensure we continue to generate positive EBITDA (earnings before interest, tax, depreciation and amortisation) and avoid significant operating losses, and we are working to re-build profitability over time....
We expect a lasting effect of the COVID-19 pandemic on travel patterns with an acceleration in trends of increased working from home, shopping from home, telemedicine and home education. We anticipate that it will be some time before demand for our public transport services returns to pre-COVID levels and we are planning for a number of scenarios. We are continuing to review our cost base, to reduce overheads and plan for adjustments to direct and semi-direct costs across a range of scenarios....
That's quite a balanced commentary, which gives me confidence in the diretorspeak.
Bus support grants - this answers my question about how it's managing to achieve EBITDA breakeven, when so many buses seem to be nearly empty;
COVID-related government payments have been available to bus operators in respect of periods from mid-March. In each of Scotland, England and Wales, we have seen a continuation to a large extent of payments to regional bus operators of concessionary revenue, tendered revenue and Bus Service Operators Grant at pre-COVID levels. Regional bus operators in England have also been able to access COVID-19 Bus Services Support Grant ("CBSSG"). The amounts receivable by bus operators for periods from mid-March are subject to a reconciliation process, which has not yet been completed and therefore gives rise to some uncertainty in estimating our income for the year ended 2 May 2020 and thereafter.
My opinion - I've only scratched the surface of this, and have already twigged that this is highly complex. I'd have to spend a whole weekend on this, to make any sense of all the issues. That's way beyond the scope of these articles.
Therefore I have to conclude that I'm neutral. Although I can see the logic in just taking a small punt on this share, on the basis that Govt will want to keep the buses running, far more so than e.g. bailing out airlines. I see it secured £300m of funding under the Govt CCFF scheme. There seems plenty of liquidity, so little to no risk of insolvency any time soon. Could be worth a punt, maybe?
.
A couple of quickies to finish off.
Quixant (LON:QXT)
115p (up 2%) - mkt cap £76m
Quixant (AIM: QXT), a leading provider of innovative, highly engineered technology products principally for the global gaming and broadcast industries, is pleased to provide an update on trading for the six months ended 30 June 2020
Densitron subsidiary is doing well & upbeat outlook (especially for products aimed at medical market)
Gaming market sounds grim;
Gaming, which is the key market for the Group, has seen only minimal orders during the past three months, with most of the Group's gaming clients closed due to the Covid-19 pandemic...
Improved activity in June from gaming market.
Liquidity - sounds fine, but no indication is given on how much deferred tax payments has boosted this;
... solid net cash position at 30 June 2020 of $14.2m (31 December 2019: $16.1m). The Group also has additional unutilised lines of credit of over $12.4m, including a new $9.4m UK Government-backed Barclays revolving credit facility, should additional facilities be required.
Therefore there seems little to no insolvency risk. Receivables collection has been good.
My opinion - neutral. I like the strong balance sheet here. However, checking back I see that it issued a profit warning before covid.
The key gaming market should gradually recover, but over what timeframe? On balance, I'd like to see the interim results, before forming a view on this group. The problem with trading updates, is that companies can say what they like, there's no structure or consistency to it. Hence we rarely get the full picture. That's why I'm wanting to see interim figures later this year, to properly assess things.
.
Blancco Technology (LON:BLTG)
184p (down 6%) - mkt cap £138m
Trading update today - sounds quite reassuring, in line, for FY 06/2020;
Blancco has continued to benefit from strong structural tailwinds which have supported continued revenue and profit growth in FY 2020. Although the COVID-19 pandemic lengthened sales cycles in the second half of FY 2020, the Board expect results for FY 2020 to be in line with current market expectations with revenue of approximately £33.4m (FY19: £30.5m) and Adjusted* Operating Profit of approximately £4.0m (FY19: £3.5m). As anticipated at the time of the Group's interim results in February 2020, cash generation has continued to improve in the second half of FY 2020 and the Group ended the year with £6.7m of net cash (30 June 2019: £0.1m).
It doesn't seem to say how much cash has been boosted by Govt schemes - a glaring omission.
Outlook comments are a bit cautious, hence the 6% drop in share price today;
In the short term, the challenges created by the pandemic of lengthened sales cycles are expected to temper growth in the early months of this new financial year. However, our pipeline is strengthening and the widespread implementation of remote working has led to a noticeable increase in the purchase of IT equipment which is likely to lead to increased demand for our services in the medium term....
My opinion - neutral. Given its past, I don't particularly trust this share. The valuation looks pricey too. So it's not for me.
.
That's me done for today. See you tomorrow!
Regards, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

78 comments
Could you find time to comment in tomorrow’s column on the Countryside Properties Retail Offer announced today. I’m a (slightly confused!) shareholder.
As an aside what are people's thought on £AO announcement today? https://www.bbc.co.uk/news/business-53470022
AO World (LON:AO.)
As an aside what are people's thought on £AO announcement today?
Would i be correct in saying the shareprice needs to be over treble the current level before employees get a penny?. I hope this isn's a distraction technique so that they can then fob staff of with below par payrises. It's not exactly a company that has been setting the world alight when it comes to maing any real profits from what it does.
As an altenative to having nothing though in that regard i would say its a great step forward compared to being offered nothing.
As a shareholder (in general i don't hold shares here) i don't mind schemes like this in theory if the hurdle starts high enough as this one seems to do if it only starts paying out when shareprice has trebled (is that the case?)
Surely it will push employees to buy more shares to push it up and investors will follow to ride the wave. The bonus is worth 1 and a half year's salary for the employees so it isn't a small bonus.
Will be good for AO to fund expansion if that happens.
Interesting idea and will be interesting to see how it plays out.
Cloudcall (LON:CALL) Overall theme was positive for me. Last month was biggest on record for new sign ups so clearly moving back in the right direction again after initial covid disruption. In the US revenues only dipped 15% and are coming back quickly versus UK which plummeted 50% (due to furlough schemes) initially but has since rebound 20%+ and continuing.
Quite a relaxed/informal meeting as is usual style and target of $50m pa revenue brought up a few times. The new CRO (chief revenue officer) has actually built and sold 2 telco type businesses before having reached that kind of number. He is from, and based, in the US and seems pretty switched on and confident in the product and conversion which is good to see.
Lots of talk from new CTO on becoming a data company (loads of collected data they can translate and help customers take advantage of using AI : interesting but clearly jam tomorrow). Will be integrated into Teams very soon which is more immediately positive I'd say.
I asked the question about listing in US. CEO said gets asked this a lot. 40% of shareholder base is US and the CRO clearly would like this to happen as well. However, disappointingly the rhetoric was about focusing on what they are doing and growing revenues, "but never say never". I really feel he is missing a trick. I reckon the US would value this business at 3-4* the current price and that would allow them to make a step change in growth in my view. The market simply doesn't value this type of tech business here in the UK and (in my own view) overvalues it in the US, but that is where the game is and management should spend some time on that, especially as much of their business and opportunity is Stateside as well as 40% of their shareholders. This was a tick in the negative column for me alas.
Gan (LON:GAN) did this to fantastic effect recently. Meant to buy some, didn't....kicking myself :)
IN REPLY TO NETTLE I use the "gross gearing + pension" which is shown on the stock report on the right about 2/3 of the way down.
Many thanks for this. A lovely easy way to do a quick check. Previously entirely missed my me!
Regarding Novacyt Sa (LON:NCYT)
People might find this article interesting... https://www.qmul.ac.uk/media/n...
See the company has now released an RNS about this....
Dear Paul
Excuse my ignorance, but I'm very confused about the important issue of Pension Deficits. Clearly it is worth checking before making any investment.
You write of Wincanton that "The pension fund in particular is an ongoing, and very large, cash drain." But when i go to the balance sheet on the Stockopedia page it gives "the Total Funded Status" as a seemingly healthy £94 million. Stocko tell me that "the Total Funded Status" column is synonymous with Pension Deficit. But this does not seem to match with what you have written. Can you explain?
And is there a very simple and robust way of checking Pension Deficits via Stockopedia? And if i'm too late for Paul, if anyone else can help me, i would be grateful.
Wincanton (LON:WIN)
And is there a very simple and robust way of checking Pension Deficits via Stockopedia?
I would always recommend going to the year end latest accounts - you should be able to find these easily via the news section sometimes the published annual report may contain extra useful info omitted from the year end accounts (download from company website).
First comment i came upon is as follows (ye 31/3/20)
Financial position
The Group's balance sheet has been strengthened over recent years, with a reduction in net debt and the pension deficit. Net debt at the year end reduced to £10.1m (2019: £19.3m) and the pension moved into a substantial surplus on an IAS 19 basis at 31 March 2020 (£94.4m surplus compared to a prior year net pension deficit of £7.1m), although this surplus will reduce as financial markets settle down.
This may sound like realy good news - but the fact the amounts can change by a random £100 mill in 12 months kind of underlines the danger here it could esily swing the other way twice as much !
It sounds like they know there is a defecit practicably spekaing as they say the following.
If they need to pay £18 mill a year (i do not know how long so extra research needed!) that underlines the potential risks involved - you could end up with equity being worthless if medium term cash generated may all end up being taken by the pension they have wrapped around their neck. Note i know no details so more research needed to work out the full detail and its the full detail that you need to know - size of the pension asset invested and liabilities being probably number one of importance - the bigger the size of the scheme the more risk .
The cash contribution to fund the pension deficit on a technical provisions basis of £17.8m comprises £18.5m of annual deficit contributions, less £0.7m of administrative expenses incurred by the Company. Contributions for the year ended 31 March 2021 were scheduled to be £18.2m, being the annual deficit contribution of £18.9m less the administrative costs incurred directly by the Company but, in response to the COVID-19 situation, agreement has been reached with the Scheme Trustee to defer £6.1m of these contributions into the following financial year, subject to the level of cash dividends paid in the year.
Many thanks. Most interesting. It shows that someone like me should be wary of most published figures!
£TSTL. Nice set of presentations.
https://tristelopenday.com/
BSV
Great, thanks. I'll add a link to the report above.
Stagecoach (LON:SGC)
Thank you Paul - Great write up and I appreciate your cut-through.
The small cap markets are a bit bonkers at the moment. A lot of tiddler dawgs are going up substantially without any news. Gold is flying of course and I guess gold fever is catching hold. I also put it down to SNG FOMO....SNG being the stock that has soared 500 per cent this week.
One interesting stock that put out news today is EVE. This company sell beds and was a favourite of Woodford. Trading ahead of expectations, generated first positive cash flow was their headline today and the stock is well down on historical prices. It also has a lot of cash...way above the current market cap....even after a decent rally today. Much of this is Woodford cash (strictly speaking, investor cash) and I see this as doing well after the inevitable overhang is cleared. Volatile and risky I guess. I hold from lower and am a buyer rather than a seller at this level.
Another Woodford stock on the rally (after SNG where his funds owned 22.2 per cent ). I have never invested in his funds in any way but it does make me cross that many pensioners will soon be receiving a final payout (after a VERY long delay) that will mean they will lose substantially on their investments.....despite the fact that some of those investments are now flying up in many instances. This seems such a con to me....almost a legal fraud. "Great news, your investments have soared. Bad news. We sold them all off at a bargain basement price to a load of City types. Here is your pittance". Disgusting.
I had a smallish investment in Woodford right from the start. Net net I will be down around 20% when all said and done so not a disaster but not good either!
What annoys me was that the PE style element of the portfolio was just liquidated at bargain basement. It would have been much better actively managed over time on a company specific basis. As you say Woodford will say he was vindicated but those that followed him will feel shafted. As all PE and Venture Cap firms know the value is in the portfolio, not the individual stocks, as you can never tell which ones will make you 20* your money and which will go bust. The problem here is that the portfolio was just at the point in the curve where you'd expect to start to see big gains in some of the companies (eg come in Synairgen) where failures will likely have failed earlier. So I am amazed anyone thought the timing was right to liquidate it off at probably the worst possible timing. Sell the stuff that ends up succeeding at bargain prices and absorb all the losses of those businesses that failed. WTF!! and all in the name of apparently "protecting shareholders"
Even if people felt Woodford had lost it and needed replacing based on poor liquidity available for redemption requests and the like I can't see that the subsequent liquidation strategy has been beneficial in the short, medium or long term, but hey I'm sure I need protecting from myself..................
This seems like hindsight to me
Given the absolutely miserable record of failure of the Woodford investee companies and that many investors wanted to get out, who can say with any certainty which investments should or should not have been sold and when? Do you wait one year, five years, ten years?
It seems to me that Woodford’s success rate was so low he was destroying value rather than adding it.
A couple of successes in a sea of ineptitude do not redeem him in my view.
The challenge with the Woodford fund would seem to be that he was running a PE/VC portfolio approach in a traditional fund structure. The PE/VC model works best when a set amount of capital is invested across a portfolio of illiquid companies, recognising that some will fail and that others will spectacularly succeed, overall giving a good rate of return. The capital cannot be easily withdrawn once invested - it is committed, which gives the fund manager 10+ yrs to execute on the investment strategy.
A traditional fund structure allows investors to buy in and out of a fund on an on-going basis. This simply doesn't work with a PE/VC model that invests in smaller, illiquid stocks.
Whether the investments being made were good or not can be debated, but in a normal PE/VC fund this is normally judged at the end of the fund life (typically 10 years). Investors racing to exit the fund meant that Woodford never had the chance to prove his investment thesis. Perhaps a different fund structure that committed capital might have been a better vehicle for his investment strategy.
This is one of the advantages we have as private investors - we can move relatively easily in and out of small, illiquid stocks. Much more difficult for large funds to do this.
This deserves a thumbs up as the neatest description of what Woodford was trying to achieve. His idea was reasonable – but the vehicle was inappropriate and not communicated properly to investors.
Yes – I would agree with other posters that the portfolio was sold off far too cheaply. There was money to be made in liquidating the portfolio
A number of the recent Bigdish (LON:DISH) RNS's seem to be non-news events. I.e. almost more to create interest in the share than inform its shareholders. I note that Zak Mir is the Digital Communications Officer, a name I recognise in the past
My two pennies worth on Bigdish (LON:DISH)
Due to Pauls involvement in this share I did take a look under the hood in recent weeks with some research of my own. I had considered a small punt knowing fully well that could result in a 100% loss.
Two things dissuaded me. The RNS of last week "re-inventing" its strategy with zero revenue. On the one hand I can see the long term logic of offering the service for free and generating interest but it's more about recognising the previous business model wasn't working which makes you question management generally. The second was the involvement of Zak Mir. Now I don't want to turn this into a mud slinging match or descend it into a typical bulletin board but his involvement to me is a massive red flag having seen his calamitous history. I have no doubt that as "digital communications officer" he is the architect of all of the ramping. It may be an effective strategy and the share price has gone from 1.5p a few days ago to 2.5p now but while I wish Paul all the success with this investment I can't get involved.
As an aside, I took a look on the LSE bulletin board yesterday for the first time in years to gauge the interest in the share. I shan't be re-visting any time soon. Apparently for every 100 branches of Pizza Hut that sign up you should be adding 1.5p to the share price. Good old Zak
Perfectly fair points, and I hear what your're saying re Zak.
DISH announcements are consistently very rampy. I agree.
253 pizza huts in the UK..so at least another 1.5p!
They are probably franchises, Pizza Hut itself may not be able to guarantee volume.
I had the great misfortune to meet the smooth-talking Zak Mir almost 15 years ago. He was instrumental in persuading me to sign up for an 'advisory CFD trading service' operated by Blue Index. He was touted as the TA 'brains' of the operation. Each morning he'd look in his tea leaves and pronounce on the direction of half a dozen trades. The team of brokers then phoned round their 'clients' persuading them to place a hugely over-geared CFD trade on that recommendation. Most were closed out at their stop loss (2% of the underlying, I recall) and very few ran to a profit.
By the time I ended the arrangement I was already £30k down in 4 months and too embarrassed even to claim the CGT tax loss! There were multiple flaws in the process. Just one: how did the firm decide which clients were called first with the day's latest hot tip? BI itself of course trousered their healthy commission on losing as well as winning trades!
Blue Index was forced to close by the FCA a few years later. I haven't followed the story but thought some reprimands were issued. Maybe I could have claimed compensation but I preferred to treat it as an education through the school of hard knocks.
Would I trust Mr Mir now? No, though I accept leopards can change their spots and it sounds like his current role carries less potential for harm.
May I have your thoughts on Stagecoach (LON:SGC) please Paul. There was a trading update / Preliminary Results for the year ended 2 May 2020 today.
Yes Stagecoach (LON:SGC) please Paul... magnifying glass on todays announcement if you have time please - seems like it will be rerated even if things turn positive with CV as my daughter tells me significant portion next year's lectures will be online and also of course WFH is an operating costs winner for service sector employers
Re universities moving to teach online, I think it was a recent podcast with Jeremy Siegal who thought this was highly likely and probably much better as the students watch his lecture online, and they get together to discuss and debate it, far more productive was the view. Another example of a trend being supercharged/
If you google this topic looks like the worlds universities are looking at this. Are there providers out there , Wey Education (LON:WEY) comes to mind but very specific or is this just another reason to buy Microsoft?
I would not have thought Wey Education (LON:WEY) would benefit but Zoom, Microsoft and maybe LoopUp (LON:LOOP) would be more likely to.
If you google this topic looks like the worlds universities are looking at this. Are there providers out there , Wey Education (LON:WEY) comes to mind but very specific or is this just another reason to buy Microsoft?
Most of the big online education companies are based in the US and China. They're very expensive.
Over here the obvious play in the space is Pearson (LON:PSON) - where the activist investor Cevian Capital has recently taken a 5% stake. It's the content that's key - universities are using Zoom and Teams, etc, for the comms.
timarr
OK, I'll look at Stagecoach (LON:SGC) - it's not going to be quick though, as ploughing through results for a company I'm not familiar with, is time-consuming.
Thank you Paul.
I don't think I deserve a "Down Vote" for politely asking... fortunate that we're here to build wealth, not practice a popularity contest.
My thoughts:-
If the country was getting back to normality (bars, offices, retail, city centres, commuting) then SGC is a potentially good recovery stock, second only to Wizz Air Holdings (LON:WIZZ) in its Stockopedia Transport Sector rankings. I can't see this happening in 2020 now.
The Management talks a good game, especially on the Social Responsibility, boasts saving The UK a small 200,000 tonnes of CO2, 44% of the fleet now Euro Cat 6 or clean energy, at the heart of The Government's traffic reduction strategy, bidding internationally for new franchises. I personally like Brian Souter.
No more Dividend in the foreseeable due to high debt and a pension liability.
This starts to make my holding seem toxic.
Just asking. Why hold? What return are you targeting and what do you need to believe for it to be achieved by this company ? Do we all hold loss makers too long? I know I do.
I may not be loss making (currently -1.31% BE @ 56.82p).
In penance for my Central Asia Metals (LON:CAML) and EVRAZ (LON:EVR) holdings, my Stagecoach (LON:SGC) has green credentials.
I meant your investment - though perhaps you have made a gain. If so apologies.
Stagecoach (LON:SGC) and others in the bus and train space have complexity all over. Not least is the regulatory environment, but also pensions, labour relations, fuel prices and so on. The EV is dominated by debt which magnifies moves in equity. Personally I don't think it is worth PI time trying to work all these out.
I remember having Firstgroup (LON:FGP) which was Ok and even went to £6 plus. Now?
Re: Tristel (LON:TSTL) watch out for the share-based payments which some consider excessive, this was mentioned regularly on these reports but not seen it mentioned recently.
Hi Paul
Interesting commentary on Wincanton (LON:WIN) - I don't hold. As I read the pension fund accounting, and I may well be completely wrong, there is an accounting surplus on the value of the pension fund - i.e. the accounts are claiming that if the company were wound up now then there would be a surplus of 10% or so of the pension fund to help pay off the lease obligations. But the actuarial valuation of the fund shows a deficit, which the company is currently paying off at the rate of something like 17 million a year in real money. I don't see how the company's real financial position can be assessed in the face of that sort of discrepancy in the numbers.
I know, pension accounting is absolutely crazy. I covered this in my last report on Wincanton (LON:WIN) here on 17 June. Ultra low interest rates, apparently forever, makes pension schemes an even bigger problem for the future. Although they should be gaining from asset values going up (equities and bonds)
One thing to remember about pension deficits is that trustees of a closed DB plan will tend to have a long-term objective of off-loading their liabilities totally, over perhaps 10-20 years. Typically via bulk annuity contracts (for smaller funds) or through a complex array of interest rate, inflation risk and longevity hedging instruments overlaid on bond investments (for sophisticated funds). Either of these 'end-game' positions will be priced on appreciably more cautious assumptions than the IAS19 valuation or the on-going triennial funding valuation. Whether the trustees can achieve this position will depend partly on whether they manage to achieve sufficient investment profits in the interim from their current (mis-matched) investment strategy, whether the employer can be persuaded to chuck a bit more money at the problem (especially in 'good' times) and other factors.
It all gets complicated! A useful (perhaps cautious) rule of thumb might be to assume that the current level of deficit recovery contributions will be maintained for at least as long as indicated in the notes to the accounts. Because, when the end of the recovery plan nears, it's easy for the trustees to argue (sometimes with support from the Regulator) that the employer is accustomed to this level of annual contribution so let's continue this for a few more years while we attempt to get closer to a buy-out position.
A small piece of news - The Guardian reports that Robinhood will not now be launching its service in the UK and will be retiring its introductory website shortly.
Perhaps not that surprising but must be disappointing for those who had signed up for the service.
Just seen that this has been discussed on another thread..
Interesting, thanks. Is there any reason given for Robinhood deciding not to launch in the UK, do you know?
Morning Paul,
I received the following email from Robinhood yesterday morning. Not too much info tbh.
Hi there,
We’re saddened to share that we’ve made the difficult decision to postpone our UK launch indefinitely. We'll be closing our waitlist and taking down our UK website shortly.
The world has changed a lot over the past several months and we’re adapting with it. On a company level, we’ve come to recognise that our efforts are currently best spent on strengthening our core business in the US and making further investments in our foundational systems.
Since we announced our intent to launch in the UK, we’ve been fueled by your excitement for Robinhood and humbled by your response. We’re sorry that we cannot deliver the product we promised you this year.
Although our global expansion plans are on hold for now, we will continue our work to democratise finance for all and we look forward to the day when we can bring this mission to the UK.
Sincerely,
The Robinhood UK Team
They may be concentrating on the USA set up for a good reason!
Service outage causes a class action against the company by clients
https://www.cnbc.com/2020/03/2...
They have looked and probably thought how do we make any money? The US is very low/no cost across the trading/wealth management/platform arena and they try to make money with bolt on stuff like advice etc.
The cynic in me says they've realised the UK regulators are on the ball. But obviously that couldn't be the case.
In totally unrelated news, Citadel have just been fined $700k (yes really, not even a million) by US regulators for front running client's large trades.
The excellent performance announced by Tristel (LON:TSTL) this morning was driven by sales of their hospital surface disinfectant products.
During the last four months of the year, when the impact of COVID-19 was at its greatest, global sales were £11.8m compared to £9.1m in the same period last financial year, an increase of 30%. Medical device decontamination product sales accounted for 61% of global sales in this period, whilst sales of hospital surface disinfection products accounted for 27%. Tristel estimates that COVID-19 resulted in a temporary reduction of £0.5m in medical device decontamination product sales and an increase in sales of hospital surface disinfection products of £2m above the underlying trend.
The engine here was its new Cache range [my bold].
As can be seen, Tristel was able to navigate its way through the COVID-19 crisis by mitigating the fall in demand for its primary product portfolio by a rapid increase in supply of its hospital surface disinfection products. The Company has invested heavily over the past three years to create a product portfolio for hospital surface disinfection and has given the portfolio a different brand name: the Cache Collection. Whilst anchored upon Tristel's proprietary chlorine dioxide chemistry, Cache incorporates other cleaning and disinfection chemistries widely used in hospitals. The key theme of the Cache proposition is a powerful environmental and ecological message.
In the run up to March, the Company had been building its inventory of Cache product components in preparation for a full-scale launch towards the end of this year. Tristel was thereby able to take advantage of unprecedented buying by hospitals of all types of disinfectant products in several geographical markets where the Company had already obtained necessary regulatory approvals. These markets were principally the UK, Belgium, the Netherlands, France, Hong Kong, and China. The COVID-19 experience has validated the Cache proposition and accelerated the rate of customer acquisition beyond the Company's pre-pandemic business plan.
A beneficiary of the success of Cache is Byotrol (LON:BYOT), which announced a collaboration with Tristel (LON:TSTL) in march this year.
The Agreement relates to three specific technologies
1. A concentrated surface disinfectant initially targeted for use in hospitals, dispensed from Tristel's proprietary Cache system of innovative packaging solutions; and
2. A concentrated surface disinfectant with long-lasting (8 hour) anti-microbial efficacy also to be dispensed from Tristel's proprietary Cache system. This product is a concentrate version of ACTIZONE, a Solvay technology developed in conjunction with Byotrol; and
3. A unique surface disinfectant combining Tristel's proprietary sporicidal chemistry, with Byotrol's long-lasting anti-microbial technology, also based on the ACTIZONE technology platform. The combined product will speedily eliminate spores on application, and will then remain active against microbes for an 8-hour period after application. Tristel will incorporate the jointly developed formulation in several packaging formats under the family name "Tristel8".
Byotrol (LON:BYOT) had revenue of £5.66m in 2019, so the benefit from the Tristel (LON:TSTL) collaboration, combined with the wider opportunities offered by COVID-19, may be very material to its valuation.
Tristel results:
https://www.investegate.co.uk/...
Byotrol/Tristel collaboration:
https://www.investegate.co.uk/...
Paul, encouraging results from Stagecoach today if you have time to have a look. Think it qualifies as small cap after recent falls at £300M, thanks.
Can someone kindly shine a light as to the SP reaction of Tristel (LON:TSTL) after such a good update. TQVM
I think some investors jumped on thinking, ‘COVID = disinfectant = massive sales gains’ . They disinfectant devices which have been used less during lockdown, but still have posted gains. That distinction perhaps has suprised some? I suppose some people expected it to be in orbit and are disappointed.
I don't follow the stock but would make 3 observations. The run up in share price in the last 10 days - it can sometimes be better to travel than arrive. Outlook - the uncertainty over timing in the return of volumes in patient throughput, covid 19 has negatively impacted some of their business. Open day presos from 9am today on the website - investors should be scrutinizing.
Big holding of mine, may be the US certification process has got even slower due to travel restrictions. Another reason could be the balance between BAU and Covid "one offs". I think many of the "one offs" are here to stay. IMO they are very positive results and the only question is the punchy valuation - which has just got less punchy.
”Revenues from overseas markets up 32%” Accounting for 60% of total revenue. Maybe investors are worried about the lack of progress in trade negotiations with Europe.
Hi Maxistaxis,
Tristel (LON:TSTL) is already highly rated. Results for FY2020 are good with 21% growth.
The forward-looking statement for FY2021 suggests some risk to growth, for example, USA FDA approval has been delayed, and for growth to continue at the current rate hospitals need to return to pre-COVID operations. Neither is certain hence the share price reaction today.
I still am long on the Tristel (LON:TSTL) as the long term prospects are still excellent.
DYOR
BSV
Interested to hear your comments on Bigdish (LON:DISH) Paul. I made a small investment last week when it dropped into the 1.4's and see its shot up in the last few days. Any obvious explanation?
There's an RNS out today, saying DISH (I'm long) has signed up Pizza Hut. I'll comment further later today, let me get the main stuff out of the way first.
My morning smallcap tweet: Part 2/2
Boku Inc (LON:BOKU) Mediclinic International (LON:MDC) Drumz (LON:DRUM) Tristel (LON:TSTL)
Boku (BOKU) guides H1(June) rev at least $24.7m ($23.5m). Underlying Payments revenue up 13.5% but Identity division rev down. Guides FY adj EBITDA at least in line with expectations, up at least 65%.
Mediclinic (MDC) vague AGM stmt - continued improvement in operational performance in June. Mediclinic Southern Africa rev down 12%.
Drumz (DRUM) name change from Energiser Investments.
Tristel (TSTL) guides FY(june) ahead of market expectations with rev up 21% and adj pretax at least 21% up. Has applied for Canadian registration of the Duo foam product for ophthalmology. USA lockdown has prevented two important parts of the FDA submission from progressing in H2. "To maintain the momentum that has built over the past four months we need hospitals, especially in the UK, to return to pre-COVID-19 levels of patient throughput. Whilst we believe that hospitals will revert to more normal levels of activity, we cannot be certain as to timing."
The update from Tristel (LON:TSTL) is much better than I had expected. I had thought the COVID impact would be much more negative than it was - instead they are reporting a good increase in revenue for the last four months of the year. Expensive, a PER of somewhere more than 30, but probably justified by prospects.
The Cache range (surface disinfectant) is promising and they seem to have managed to get themselves into a lot of countries very successfully- to me that’s the future value. I was disappointed how negatively the market reacted this morning but they didn’t try and ‘hype it’ in the update? I use a lot of disinfectant everyday (medical) and properly designed and evidenced products are needed - the volume being used is eye- opening
Interesting your comments about Cache and sounds like you are in the profession somewhere. If Cache really takes off Byotrol (LON:BYOT) will be a beneficiary as they have recently sold a license to TSTL that essentially extends the protection life of surface their cleaners. Disclosure - I am not a medical professional!
My morning smallcap tweet: Part 1/2
eve Sleep (LON:EVE) Maestrano (LON:MNO) Iofina (LON:IOF) BigDish (LON:DISH) Scancell Holdings (LON:SCLP) Lamprell (LON:LAM) Barkby (OFEX:BARK) Avacta (LON:AVCT) Diaceutics (LON:DXRX) Zoetic International (LON:ZOE) £MEAR Quixant (LON:QXT) Cloudcall (LON:CALL), Anexo (LON:ANX)
eve Sleep (EVE) guides H1(June) rev down 6% but Q2 was up 25%, ahead of the Board's expectations. U/L EBITDA loss £1.2m down 80%. Cashflow positive. Leaves FY expectations unchanged "but is increasingly confident in the out-turn".
Maestrano (MNO) guides FY rev £885k, down 2% but up 2% at const currency. EBITDA -£227k (-£304k). Confident of continuing growth in FY21.
Iofina (IOF) H1 production flat at 284MT. Guides H1 340-360MT. Refinancing delayed by covid, anticipated it will be completed within the two-month extension recently granted by current senior lender. Hemp: seed sales from the JV through its sales partner have been much lower than expected due to covid and a lack of a comprehensive USA hemp crop insurance.
BigDish (DISH) re SP rise - Pizza Hut have agreed to join BigDish but reminds us that DISH is not charging now.
Scancell (SCLP) £9m placing and OO at 5.5p (20% disc) and £6m convertibles with a low strike of 6.2p. Cash needed for drug trials and to continue initial COVID-19 vaccine development until non-dilutive funding or third-party partnering transaction.
Lamprell (LAM) guides H1(June) EBITDA broadly breakeven. Backlog $580m (Dec: $470m). Net cash up. Confident.
Barkby (BARK) op update. Gets £1m covid loan. £1.9m income from completion of Hastings site expected by end of August.
Avacta (AVCT) begins work with Gov't CONDOR programme to evaluate and validate the high throughput COVID-19 bead-assisted mass spectrometry laboratory assay developed with Adeptrix. Up to 1,000 nasopharyngeal swab or saliva samples per day can be analysed by a single technician.
Diaceutics (DXRX) wins $1.27m contract
Zoetic (ZOE) partnership with cannabinoid research experts GVB Biopharma, represents the first large scale commercial hemp study. Will terminate Colorado greenhouse facility lease due to changed business model.
Mears (MEAR) guides H1(June) rev-cont down 8%. Pretax-cont (before the amortisation of acquisition intangibles) -£6m (+£16.7m). Co expects to see a recovery in activity levels in H2. Continues to look at disposals to cut debt.
Quixant (QXT) H1 rev down but no figs! Net cash $14.2m down $1.9m in half.
Cloudcall (CALL) guides H1(June) rev up 11% to £5.8m. Cash at hand £8.4m. Cash burn cut to £250k a month. "Since May, as homeworking became more established, sales numbers have steadily improved - largely driven by the recruitment sector...By early June, the upturn had accelerated, and we began receiving enquiries from more sizeable organisations."
In line: Anexo (LON:ANX)
Cloudcall (LON:CALL)
Very poor update from cloudcall this morning. They expect nil growth this year. With current rate of cash burn at over 2 mil per year they really are now heading backwards at the exact time I would have expected they would see material uplift in sales due to COVID. Perhaps their customer pool may be more Covid closed office type than rather than remote worker type. Surely with recurring sales retention at near 100% and nil growth and amazingly high margins they shouldn’t be throwing shedloads of cash down the drain?
I disagree. Of course CALL (I'm long) took a hit in Q2, so did most companies, as new business dried up. That is completely as expected, so why would anyone be surprised by that? Markets look forwards, so it's all about the outlook comments. With business now improving, and the trend for work from home, this all plays to Cloudcall's strengths. Plenty of cash, so no further dilution. This share looks very cheap considering it's operating in a sexy sector. Growth should return to normal, or above, if you look forwards a few months.
RE: Cloudcall (LON:CALL)
It's an interesting update. I don't like the narrative very much, it reminds me of me trying to justify some product or another :-)
However, there is some validity in the argument - the initial reaction of companies moving to home working was to enable simple video conferencing but as time has gone on and the realisation has set in that this will be the new normal in terms of working they're looking for deeper integration with business tools. The disappointing thing, really, is that Cloudcall (LON:CALL) is only reacting to this trend and hadn't anticipated it - not the pandemic, obviously, but the trend to remote working has been evident for a while.
On this, however, I'm less convinced:
Of course CALL (I'm long) took a hit in Q2, so did most companies, as new business dried up. That is completely as expected, so why would anyone be surprised by that?
Most of my investments - so far - saw earnings increases in Q2. The obvious trends towards online shopping and home working are the overwhelming drivers. Cloudcall (LON:CALL) ought to be in that space, hopefully their Teams integration will put them there rapidly. Businesses that are successful will probably get snapped up by the big players quite quickly.
Andy Haldane, the Deputy Governor of the BoE, repeated his assertion this week that so far we're seeing a V shaped recovery. The press is dubious but I think they've missed the point by focusing on the high profile High Street cutbacks. The companies doing well at the end of the recovery will be very different from those at the beginning. Haldane is looking at real-time data - stuff like the fact that non-food online payments rose 42% YoY in June, compared to a 3% rise the previous June.
Hermes, the parcel delivery company, announced 10,000 new jobs this week. The warehouse REITS have collected near 100% of their quarterly rents while most retail REITs are struggling. I think it's hard to see anything more than a partial reversion to the old norm at the end of the crisis - and the longer it goes on, the weaker that reversion will be.
timarr
Haldane is looking at real-time data - stuff like the fact that non-food online payments rose 42% YoY in June, compared to a 3% rise the previous June.
To reply to myself - non-food online payments rose 48.2% YoY in June.
https://home.kpmg/uk/en/home/m...
Like for like UK sales - excluding closed stores - increased by 10.9% in June. Online is obviously the main driver. You can see why Haldane is stating it's "so far, so V" - but that doesn't help the High Street much.
Hope is that July will be better with the reopening of pubs and restaurants.
timarr
Are you really saying that business dried up this year for companies offering cloud communications products that support remote working?
That seems a bizarre claim to make given the explosive growth in Zoom for example.
No, what I'm saying is that CALL's existing pipeline (office based recruitment companies) would have obviously dried up temporarily. It's now improving, no doubt helped by the work from home trend. The commentary today covers all of this. Remember that CALL is not a simple communications tool, it's a CRM integration, so not something that people just pick up and use on a whim, like Zoom.
I don't fully understand the product offering at Cloudcall (LON:CALL) but is there enough of a differentiation from MS Teams/Zoom for it to gain rapidly in terms of market share? Those are the ones we use internally / and with other companies we engage with. MS Teams in particular is very strong and also enables basic chat, file sharing, video recording etc and has been essential for our move to home working. We were using more and more before this anyway as have offices in multiple geographies, but it has obviously been accelerated this year.
I don't fully understand the product offering at Cloudcall (LON:CALL) but is there enough of a differentiation from MS Teams/Zoom for it to gain rapidly in terms of market share?
Cloudcall (LON:CALL) isn't a competitor for Teams / Zoom. In very simple terms it's online Customer Relationship Management. The announcement today includes narrative around the integration in progress with Teams and Microsoft's support for this.
I wouldn't read too much into the MS support - they'll be supporting anything that looks interesting and which may give Teams an edge.
timarr
Thanks timarr - have made note to have look into it in a bit more detail as in market only going one way.
Cloudcall (LON:CALL)
Paul
I disagree. Of course CALL (I'm long) took a hit in Q2, so did most companies, as new business dried up. That is completely as expected, so why would anyone be surprised by that?
I think i have managed to miss their recent covid related update(s) somehow , or did not realise (or forgot) from those updates that turnover was expected to be pretty much static year . Looking at the stocky numbers they are (and presumably were) showing minimal expected increase in turnover 2020 - so you are 100% correct that i should not be surprised by the lack of growth announced today as it was already flagged up. Early indication that when you hit the big five o' memory is one of the first things to fail.
I would say i do find it dissapointing that they seem to be so affected by covid when their products specifically help people to work remotely - lookup don't seem to be having the same issue. I guess each buisness has its own specifics in that regard.
I think in Cloudcall (LON:CALL) 's defence that their product will take a bit of IT integration work to get it talking to the client's core CRM system, so I can understand potential customers not wanting or being able to take on that risk while having to transition overnight to remote working. Businesses just wanted comms solutions that they could download and get working immediately.
But that does imply that Cloudcall will only be able to gain business when things are more back to normal and their potential customers are back in their offices and in a position to think efficiency rather than survival.
Hi Millarree,
I agree one would have expected COVID-19 market conditions to be favorable. Can't find one reason to invest, but many to go short;
DYOR.
BSV
Alot of positive news
Tristel (LON:TSTL) - (manufacturer of infection prevention products) 21% increase in turnover and profit. Cash balances of £6.2m with no debt
Diaceutics (LON:DXRX) - (diagnostic commercialisation) announces a significant new client contract win with initial contract is worth $1.27 million
Kingfisher (LON:KGF) - (Hardware) the Company anticipates its half year adjusted pre-tax profit to be ahead of prior year.
Computacenter (LON:CCC) - (technology partner) substantially ahead of the same period last year
GYG (LON:GYG) - (superyacht painting) Group revenue increased 41.8% and swings into profit