Small Cap Value Report (Wed 23 Dec 2020) - BOO, AVAP, IMMO

Good morning, it's Paul here with the SCVR for Wednesday.
Timing - I'll leave it there for today, as Countdown is about to start on Channel 4 (a nice way to de-stress after 7 hours of market & writing stress). I managed to get all but one of the numbers rounds right yesterday, and both conundrums too (pressing pause helps!). So I declare today's report duly finished.
It's quiet for newsflow today, but I've got some backlog items that I'll write about, so you won't be short-changed! In all honesty, I haven't really got anything else to do today that is pressing, so I'm quite happy to do some writing here instead.
.
Live Xmas harp recital, tonight (and tomorrow)!
Last chance for a unique, live Christmas harp recital (45 mins), from my sister-in-law, Lauren. We got very positive feedback from everyone who joined in her last harp recital of Xmas carols, live on Zoom. It's a really nice, feel good thing to do, with your friends & family., even if you just have it as beautiful, soothing background music (there's no audience participation, so everyone can relax!)
Goodness knows we need something to get us into the Christmas spirit, and if this doesn't, then nothing will!
Tickets are here. It's only six quid. I'd be very grateful for your support for my family, a struggling, but incredibly talented musician. It's not really about the money, she could just do with some moral support right now, with almost all her usual gigs having been cancelled this year.
The arts is a sector that's often overlooked, but the people in that sector have been devastated by covid/lockdown, destroying their livelihoods. To be blithely told to re-train isn't very helpful (a Govt website suggested my brother, a professional saxophonist, should re-train to be a bomb disposal specialist. Seriously!). Lauren applied for jobs in supermarkets, stacking shelves, to make ends meet, but didn't even get an interview. So it's not easy for middle-aged people steeped in the arts, to switch to something else.
Boohoo (LON:BOO)
First, our daily Boohoo (LON:BOO) (I hold) update
The Guardian are at it again, with yet another article highlighting low wages & poor conditions in a factory (this time in Pakistan) which seems to have been an unauthorised subcontractor, making garments for BooHoo. No doubt the factory makes garments for other brands too, but the Guardian likes to pretend that only BooHoo clothing is made in sweatshops, whereas of course it's a sector-wide, global problem.
BooHoo has suspended the supplier while it investigates. On the positive side, it sounds like the factory had been audited, but that the auditors had been fobbed off, possibly?
From the Guardian's short video, it does look like the factory in Pakistan might be dangerous, with what looks like scaffolding standing on bricks, supporting something above (the roof maybe, it's not clear), motorbikes stored indoors (although it looks like they are just inside, in what looks like a loading bay), and a rather grubby stand/squat hole in the ground type of toilet, like the ones they used to have in French bars until quite recently. Not very nice, but not altogether surprising in a poor country.
As we saw from the recent Parliamentary hearing, which BOO management asked to testify to, the company is clearly making serious, and strenuous efforts to clean up its supply chain. Rome wasn't built in a day, and it's incredibly difficult for retailers to police global supply chains, particularly because so much work is subcontracted, often without the retailer's knowledge, to poor countries with lamentable standards of safety, hygiene, and low wages.
I suppose you could look at this 2 ways;
1) Well done to the Guardian for investigating, and reporting on a shoddy setup overseas, or
2) Why the obsession/vendetta with persecuting BooHoo, when it has admitted failures, and is making strenuous efforts to fix the problems, which are endemic in the entire industry, not just for BOO?
This issue has been ongoing since May 2018 - I've just found a copy of the FT magazine which highlighted "Britain's Dark Factories". Journalists have rehashed the story repeatedly ever since. I'd like to see some balance, with all the other retailers challenged about their suppliers working practices. It's not clear why BooHoo seems to have become the lightning rod for the whole sector.
Will it impact the share price today? There's no reason why it should, because this is a known issue, and the company has already explained its detailed & serious plan of action. At this time of year though, with thin trading, anything can happen.
.
Hedging again?
I'm starting to get jittery again about the shorter term market outlook, so have put an index short on as a hedge, to help me sleep at night a bit better. So I thought it might help concentrate my mind, if I jot down the bull & bear points for the markets overall;
Bull
- According to the press, the likelihood seems to be that Oxford/AstraZeneca vaccine may be approved imminently - very bullish for many companies in problem sectors, since it would allow a rapid roll-out, and vulnerable people protected by (or before) Easter, allowing lockdown restrictions to be lifted permanently
- Brexit deal could be agreed any day the problem areas sound surmountable. Surely some face-saving (for both sides) compromise can be thrashed out? EU always seems to reach deals/fudges at the last minute, this is normal
- Huge Govt stimulus, so even in downside scenarios, Rishi is likely to hose down problems with cash, which is exactly what he's done so far. All funded by QE, so no issue with Govt debt - which is a total red herring (BoE owns £845bn of c.£2,000bn National Debt). This means any spike down on bad news is only likely to be temporary, much like March 2020 covid crash
Bear
- Covid cases rising fast, new more transmissible strain, news likely to get much worse before it gets better, race against time to vaccinate the vulnerable
- More severe lockdowns from now until maybe March, could do a lot of fresh economic damage possibly?
- Brexit chaos if no deal?
- Global logistics problems & cost of freight rising, and slowing down - could trigger profit warnings?
.
There are probably other things that I've forgotten. I'm bullish medium term, but am worried about the short term outlook. The above sounds like a recipe for potentially (maybe extreme) volatility. Hedges could easily be stopped out, even if you get the ultimate direction right.
Conclusion - I've fully hedged my portfolio with a short on the Dow (not particularly logical, but it's what I always do, so am comfortable with it), for now. I wanted to strip out the Brexit volatility, hence why not using a UK Index short.
If the market goes through the roof, then my index short will just get stopped out, for a loss of about 2% of my total portfolio. But my longs would probably go up more than 2%, because they're mostly things that are geared to a recovering economy.
I have looked at using Put Options as hedges, but they're ludicrously expensive. You have to be right not only about the direction, but also the timing of a big market move, because the daily decay of time value element of options seems quite high I've found when using them. There's a good case for using index options just before some major event, e.g. an election, or referendum, because they seem to be priced on recent historic volatility, not anticipated volatility. But that sort of options stuff is probably best left to the experts!
.
Avation (LON:AVAP)
135p (up 1%) - mkt cap £84m
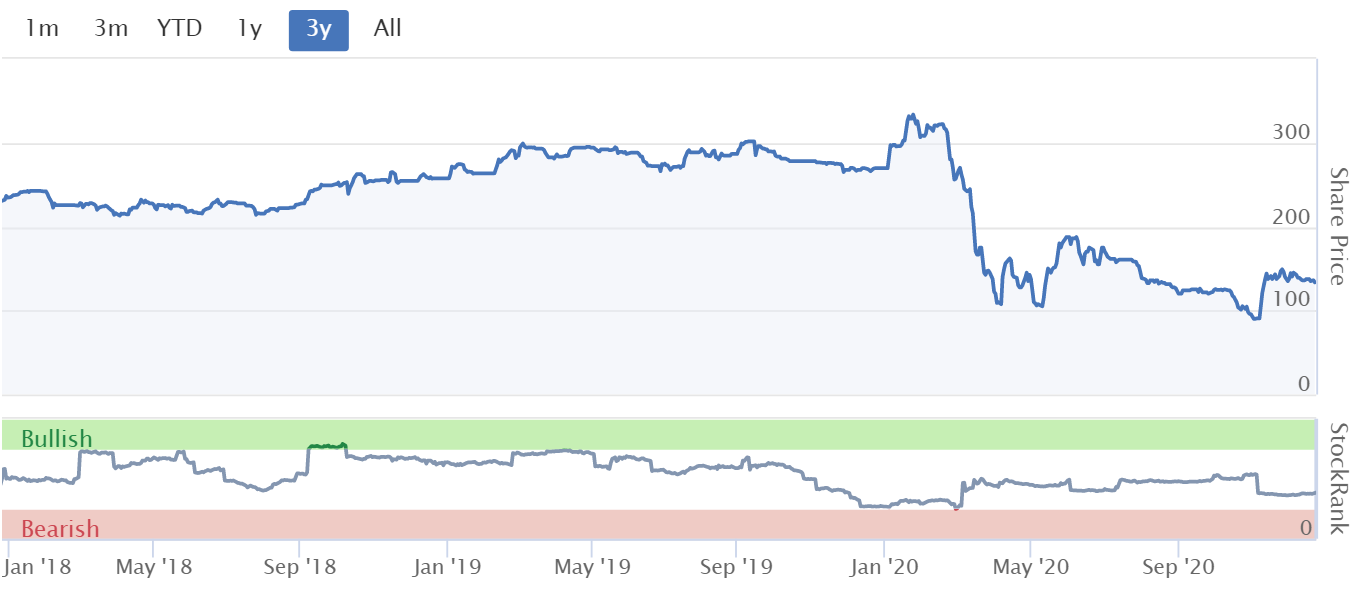
I've not looked at this passenger aircraft leasing company since covid struck. Obviously its share price has been slammed, and barely recovered so far. Could it be a recovery candidate? Or, could struggling/insolvent airlines drag it down?
.
.
Summarising today's update;
- AGM being held on Zoom at 9am today
- "Satisfactory" results for FY 06/2020 (revs $135.3m, PBT $14.7m)
- Fleet is now 46 aircraft, 19 airlines, 15 countries, newish planes (4.5 yrs avg)
- Pandemic - AVAP supported airlines with deferred payment terms ($13.7m), and agreed amended terms with AVAP's lenders (rescheduling $26.5m of loan repayments)
- Airlines returning to service, but sector remains challenged & debt collection challenging - likely to remain difficult, even with vaccines rollout
- Phillipine Airlines restructuring - could reduce income for AVAP & impair assets - no figures given
- Bonds maturing May 2021 - negotiating with bondholders to extend maturity. Could involve increased costs. Company "stands ready to explore all alternatives" if negotiations fail
Outlook - optimistic in the medium term, looking for "opportunistic purchases" of aircraft
We have an opinion that air travel passenger movements will exceed previous levels when a treatment or vaccine is deployed, and passengers perceive air travel to be safe. Therefore, post COVID-19 we remain optimistic and expect significant opportunities for a rapid return to growth."
My opinion - the main risk here seems to be the negotiations with bondholders. It would be a good idea to check the price of the bonds, to see how distressed the bond market thinks they are. In this type of situation, a lot hinges on who owns the bonds. If they've been bought up by aggressive funds, who intend to play hardball, then things could get messy. Or, if the bondholders are co-operative, and want a quiet life, then things could work out fine. That's key information I don't have, so I can't value this share, or assess the risk.
Therefore it needs to be seen as a special situation type of investment.
The other thing to consider is whether the aircraft need to be written down in value on the balance sheet? What happens if customers go bust or restructure? Airlines generally have taken a battering, and with often shattered, highly indebted finances, they don't exactly make the most appealing sector to be leasing assets to. There again, planes can be re-let to new customers. As aviation recovers in the coming years (and I expect a big bounce from Easter, as people are likely to be craving holidays, having been denied them in 2020), then business could gradually recover. That would potentially give decent upside on the current share price.
If you know what you're doing, in terms of researching bonds, and financing generally, then this share could be an interesting one to look into. I'm neutral on it, as it's much too complicated for me to research properly in the timescales available here. Hopefully I've flagged the main issues above.
.
Immotion (LON:IMMO)
3.79p (up 15%) - mkt cap £15m
I've not looked at this company before, so give me an hour or so to read up on it...
This company is involved with virtual reality headsets. I'd love to try out one of those, they look great, but apparently can cause motion sickness. IMMO listed in July 2018, on AIM. Raised £1.2m before fees, 30m new shares in a 4p placing recently (Nov 2020). Mgt bought 12.5m of those placing shares, a good sign of commitment.
It seems quite early stage, with small revenues.
July 2020: £62k
Aug 2020: £339k
Sept 2020: £305k
[taken from RNS 19 Nov 2020]
Trading update today -
Immotion Group, the UK-based immersive entertainment group, is pleased to update the market on current trading.
Adding to the above revenues;
Oct 2020: £369k (launch of "Let's Explore Oceans" in mid-Oct)
Nov 2020: £573k
An improving trend there.
The home product looks interesting - it's cheap because it uses your smartphone to do the graphics. Have a look at this. Has anyone tried out this product? If so, I'd love to hear more about it - warts & all.
Since the launch in mid-October 2020, sales of the Home Based Entertainment product, LEO have exceeded expectations with total units sold up to and including 22 December, of over 11,000 generating total retail sales, including VAT, exceeding £800,000.
Following the recent placing, announced on 19 November 2020, the Company has now secured further stock, as well as identifying an outsourced fulfilment facility, allowing it to target a launch of the product in the USA in the second half of February 2021.
The product is now manufactured entirely in China, with complete boxes being supplied direct to our fulfilment houses. This process will significantly reduce product costs as the Group moves forward.
Location Based Entertainment - this seems to be another part of the business, with installations in several countries, as well as the UK. Covid lockdowns are forcing some closures.
It says demand will be very strong when "any sort of normality returns".
IMMO also sells disinfection cabinets called Uvisan. It's recommended by Hewlett Packard.
Summary - 2020 has been a tough year, impacting LBE revenues. Hoping for a strong bounceback in 2021. Cash of £1.9m at 21 Dec 2020, remains vigilant on costs, which it says are at a sustainable level. Enough cash to reach profitability.
My opinion - it looks moderately interesting. There must be so many companies active in this VR sector around the world, I'm not sure what is unique, or sustainable, about this company to make it worth focusing on? This type of tech tends to develop fast, which can often leave behind small, modestly funded companies, even if they have some early success. So it's probably not for me, but good luck to holders.
.
All done for today, see you tomorrow (half day usually on Xmas Eve).
Regards, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

137 comments
Paul Ed and all
I would just to wish you all at Stockedia a very Merry Christmas- I have particualrly enjoyed Pauls assessments of shares and details of his own home life !!
Ed's work on Stockopedia has been excellent and I believe all who use it will gain both in terms of knowledge and experience
My own performance of 105% in 2 years is largely due to the information I have gained from using Stockopedia ( and selling out of the market for 3 weeks in March !)
Happy Christmas to you and all subscribers
Simon
@barnetpeter
Thanks. Thought the same too. Any form or derivative type instrument, including ETN's, is stated. Key also is apples to new position, so existing trades can be retained. So stock buys are still permitted. Otherwise Argo Blockchain (LON:ARB) would have to delist / imagine the impact would have flagged this and made it known publicly if the case.
Thanks
I held an ETF bitcoin tracker which was doing reasonably well until HL messaged me on 30 October as follows:
The Financial Conduct Authority (FCA) have recently published rules which ban the sale of crypto-currency derivatives and Exchange Traded Notes (ETNs).
The FCA have asked that investment platforms like HL remove these types of investments by 6 January at the latest. Having reviewed the FCA assessment, we’ve made the decision that from Friday 30 October you will no longer be able to purchase new units in the funds listed below.
You can continue to hold the units you already hold or sell them at any time.
Also concerned at the prospect of their no longer a market I sold them and have consequently missed out on the subsequent rise of at least 50% by my calculations. Maybe I shouldn't have sold? Anyway, FCA clearly knows what is best for me. Thank you FCA.
Good old FCA - always turn up to count the bodies , never able to prevent any wrong doing or dodgy schemes/advisers /providers.One way to maintain exposure to the Crypto market is to open a Pro. spread bet account. BEWARE ! A Pro. account can create an unlimited liability ie , you are not limited by your account balance as with an ordinary account.
Thanks but think I’ll give that one a miss!
Westway001
Sorry to hear of this !
I've gone the other way where I've recently gone long in a $BTC Trackers, Warrants and a few Canadian Miners ($HIVE/$HUT8/$BITF) via DeGiro. I am also pondering a SB on $ETH and just leaving it to run during 2021 (with a very low stop level).
$BTC these days just requires too much margin, so instead will think about SB positions in the Miner stocks ... ahead of 6th Jan.
I am relatively bullish about prospects in 2021. A real shame that you weren't clearly advised by your broker, leading to a premature close of your position. But still time to re-enter if you also are bullish about the near future ...
Best of luck
Spl183
You can buy exposure to Bitcoin on Revolut ('fintech' bank). They also have fx interbank rates either no fees. It is brilliant, I use it whenever I go away and just pay in the local currency on card as normal.
with no fees*
Hi, I wonder if there is interest in a biotech share being introduced here from time to time. The standout share of the year, Novacyt, held by many here, is one such. When the technology matches the moment, there can clearly be extraordinary gains.
Scancell is a possibly interesting share. Very speculative so ultra DYOR. I have held it on and off for many years and have on at least two occasions been happy to get back to breakeven and escape. In common with most early-stage biotech shares, they needed frequent injections of cash, not helped by large director salaries. They also seemed rather slow in developing their science. At the same time as applying for a US study, they applied to use a new drug delivery system. Naturally, approval took even longer than usual. They do have unusually good data on melanoma survival, albeit in a small patient group.
The Scancell science has moved on. Apart from their regular cancer-related activity, they are also developing a ‘second-generation’ coronavirus vaccine with Phase 1 trials to start as soon as possible next year.
‘In response to the COVID-19 pandemic, Scancell has turned its clinical expertise in cancer to produce a simple, safe, cost-effective and scalable vaccine to induce both durable T cell responses and virus neutralising antibodies against SARS-Cov-2, the virus that causes COVID-19. The Company believes this combined T cell and antibody approach should give more potent and long-lasting responses, ultimately leading to better protection.’
As far as I know, there are only four vaccines being developed in the UK – Astrazeneca/Oxford for which approval is expected and where the efficacy rate in older people (I am one of them) doesn’t seem completely clear at the moment; GSK/Sanofi, where there is now a delay until the end of 2021; Imperial College, which I believe should be commencing trials soon and Scancell.
It seems that multiple vaccines and different vaccine approaches may be necessary with this virus.
I am not a scientist and very much welcome feedback from others more qualified than me both scientifically and investorially.
Scancell received a £2,000,000 grant from Innovate UK for the vaccine program. A large US healthcare investment group Redmile has also bought into the company in a big way and they are now fully funded going forward.
Many thanks to Paul and Jack for the daily SCVR and to Stockopedia itself. It has been a complete revelation since joining a few months ago and my portfolio bears little resemblance to last year (for the better, I hasten to add).
The statement that Scancell's vaccine 'approach to offer combined T cell and antibody responses,,,,ultimately leading to better protection' sounds like a load of BS. All vaccines are supposed to do this and for Scancell to actually demonstrate that its vaccine offers better protection (compared with what??) will require long and expensive clinical studies.
I used to work in the pharma industry and knowing the enormous failure rates in product development, will never invest in individual start-up pharma/biotech companies. Even if a product completes all the clinical trials to get to commercial launch, only 10% of them make any money.
The rumour mill believes a Brexit deal is about to be announced. FT100 up in anticipation, £ soaring and bookmakers offering 1:5 odds on it happening (now lengthened to 1:4).
Could be great news, who knows
cheers
Francis
Yep UK saying it is done. - Sky News.
Laura Kuenssberg: "David Frost and EU’s Steph Riso are still in negotiating room in Brussels - deal is NOT finalised - seems very likely it’s heading that way tonight but not signed and sealed" "Final touches"
"On final lap" a number of other sources.
Odds have now shortened to 1:8 on a deal being done in 2020. $ at 1.3534 to the £
FT100 up, pound soaring. Not often those two things both happen.
GBP strength should push the FTSE100 down...but its a nutty world, all sorts could happen!?
Santa rally - yay!!!
Domestically focused (Mainly the ftse250) will certainly outperform but they are all down trodden so even a 5% rally in £ won't offset the 17% difference to other index in YTD performance. The FTSE is trading significantly below usual averages to earnings.
Hi Cmpeckham - Can you recommend a company that provides options on indices or individual stocks to retail investors competitively & with decent liquidity?
Many thanks to the Stockapedia team for all their advice this year and Happy Xmas
I'm not sure what you are looking for exists, but for UK retail I would suggest the spread bettors such as IG. Good luck.
It might be a quiet day for news but a fantastic day for the number of risers! Bitcoin miner Argo Blockchain (LON:ARB) has had a strong rally today on potential news of a float in the USA ....but nowhere near the top 20 .
Another stock worth a mention is Ilika (LON:IKA) This battery maker has broken up sharply on bid speculation over the last few days. Exactly the type of "green" company that I see having an excellent year in 2021 .....unless an early bid does come in.
My biggest winner of the second half of the year is Wishbone Gold (LON:WSBN) A highly successful professional investor suggested it was a buy in early July at just over 1p. More to the point, he bought in heavily. No interest. Only he and I were buying (me purely on his recommendation). Today the price hit 16p. There are some very smart investors around that are well worth following!
Finally, the risers board yesterday was full of stocks that had raised money via the Primary Bid site earlier this year . The great thing about this site is that it offers stock to small retail investors not just to those that are looking to flip for a small premium and / or "forward sell". These days, Ftse 100 and 250 stocks are offering through the site rather than just dodgy miners. Well worth signing up to in my view.
Seasonal greetings to all! Here's hoping for a great 2021.
Maybe i misunderstand the situation but i have just sold reluctantly my Argo Blockchain shares as my online UK stockbroker has informed clients that UK retail investors will be unable to buy cryptocurrency related assets from january 6th. That does not mean one has sell Cryptocurrency assets but to me after january 6th it might be a struggle to find buyers for Argo Blockchain if one wishes to sell.I made a nice profit on them and i am not taking the risk.
Obviously if they list in the USA it changes the situation but there is no guarantee that the USA govt will not follow the UK govt.IG Index have also informed clients one will not be able to go long cryptocurrencies after january 6th and again reluctantly i have had to close my long position on Bitcoin
Thanks for that Metatron. FCA website is stating the below. But can't see where it states also applies to buying crypto related stocks ? If the case, US has already banned CFDs.
To address these harms, the FCA has made rules banning the sale, marketing and distribution to all retail consumers of any derivatives (ie contract for difference – CFDs, options and futures) and ETNs that reference unregulated transferable cryptoassets by firms acting in, or from, the UK.
I don't think that means stocks. I think they mean buying bitcoin on margin....which could be ruinous.
As I understand it they mean you cannot buy Bitcoin or other cryptos as a retail investor on margin or with credit card. If you are can elected professional investor you can still trade crypto assets on a spread bet etc.
Argo (LON:ARGO) aren't a crypto asset they are a PLC and have shareholders, plain and simple. No different to any other listed company.They might mine crypto and sell it as their business model, but nothing stopping them from doing that and should be nothing stopping anyone buying or selling shares in the company. If I were you I would seek clarity from your online broker.
Hi barnetpeter,
a very interesting post re Wishbone Gold. Are you able to disclose the identify of the "professional investor"?
And a happy new year to you also!!
wsbn i got 200k at 1.35p 5/8/20 traded it up to 10.43p in and out, out since 4/11/20 should of held would be worth32k£ today but i have to work... a screen for small market cap, less than 100million shares in issue and a penny share required.
IMMO - plucky little company that creates the right new products at the right time.
Pushing LEO into the US could be a game changer for them. HP's endorsement of Uvisan is encouraging. I'll buy more at under 4p if I can find the cash.
This is my first post.
Paul/Jack. I avidly read the SCVR on a daily basis as well as the comments that accumulate during the day. Great stuff that has put lots of £s in my pocket. Thanks.
I would welcome comments on £CNE. (CAIRN ENERGY) which I hold. The international arbitration went as expected. The Indian Governments position was always frankly preposterous imho. I am surprised the share price has only gone up 20% today with the $1,2BN award plus interest being approximately equal to the pre-award market cap. I know that the award must have been priced in to a degree but this is ridiculous.
I guess there is a feeling that the money will not be forthcoming anytime soon or that it will be turned into an incentive for Cairn to reinvest in India to make it more of a win win but it feels like a lot more than 20% to me.
On top of the tax arbitration award, there is also the Senegal sale resulting in a 32p per share special dividend with a consolidation to ensure that the div plus share is the same value as the pre div plus share. I get the rationale for the dividend essentially returning £250M to shareholders but do not get the rationale for a consolidation other than to keep the charts looking pretty.
Hi millbank71,
Welcome to Stockopedia, and I'm glad you like the SCVRs!
Best wishes, Paul.
Boohoo issue is a signal that management is not managing in depth so my view is don't touch it and don't blame the Guardian!
The report doesn't seem to have harmed the price today! Although far less convinced of the owners than Paul, I can readily imagine from looking at the chart and the fact that good results are likely to be announced in mid-January that a good increase in price is more likely than a fall.
Really not happy with myself for selling Boohoo (LON:BOO) @ 290p.
Paul, re: Boohoo (LON:BOO), what are your thoughts about competition from unregulated fast fashion retailers like Shein? Shein seems to be pitching for the teenage market and undercutting BOO on price, although the quality is poor and the (Chinese) company is secretive, so there's little information about its own suppliers. If BOO's costs rise because of increased internal compliance, might it begin losing more market share to the likes of Shein who don't have the same constraints?
Obviously the Guardian will thoroughly investigate the shein supply chain now they've set the precedent.
SCS (LON:SCS)
Just dumped another 2 batches of 5000.
3rd time round, price had dropped by 1p... so figured I might just sit the last 6000 shares out.
HL now says I have £25 profit for 15 months investment. :-) I don't get out of bed for £25!
PS: Also I note Google Finance still says only 14,888 traded today, last trade 11:06:07 . Something funny goes on.
SCS (LON:SCS)
Just dumped another 2 batches of 5000.
How funny. You'll never guess what? I just bought them! 10k at 206p!! LOL :-D
Maybe we should create our own internal market here on Stockopedia, where people can cross small cap stock at the mid-price?!
Regards, Paul.
Looking at the market cap at £79m versus the Cash on the balance sheet (last reported at £82.3m) looks like you get a furniture business thrown in for free :)))) I hold.
isnt some of the cash customer deposits?
Some yes. It is an example of what I think of as the myth of cash.
(If you believe in cash on the balance sheet then My Cashley was paid several millions to take ownership of Game Digital.)
Here's a breakdown I often look for.
As far as I know, they don't explain what their "accruals" are but at least we know that they are money that does not belong to the shareholders.
Re SCS (LON:SCS) ... If the company is profitable and can comfortably service its debt/liabilities then the enterprise value could be MV net of cash?
Stocks123456,
What do you mean by "enterprise value could be MV net of cash"?
I am perhaps somewhat renegade on this point, but if (to quote) "the company is profitable and can comfortably service its debt/liabilities " then why look at the balance sheet?
The issue for me with Scs (LON:SCS) is that its second from bottom on my book in terms of gain. 2.5% is an underperformer compared to my other 8 stocks. I bought in too high.
Anyone filling their boots when SCS was 180p and lower will probably feel very remunerated.
You can see 2.5% in a day from other stocks. SCS took the furlough dole-out where as the winning shares did not. As lockdown III drags on, we move another quarter away from good news and dividend resumption.
Hi Gromley, thinking about this again, if i were to sell this business, how much cash could i extract without affecting the business ? I suppose that would be the value of the net assets.
Ahh thanks Stocks - I just didn't understand the abbreviation you had used.
Based on what I have looked at today my (provisional) answer to "if i were to sell this business, how much cash could i extract without affecting the business ?" would be zero - I do not see any evidence that they have surplus cash.
Hi Gromley,
Surely your analysis of SCS's balance sheet is looking at a shutdown situation? i.e. all the cash would be needed to settle the unwinding of creditors. In reality (even with covid) that didn't happen - they continue selling online, and have the buffer of a big order book to continue manufacturing & delivering. Then when allowed to re-open, the showrooms saw massive pent-up demand, and the order book rapidly refilled.
Therefore, I think the business model for SCS has been battle-proven, and it could probably use some of the cash for, e.g. a sensible acquisition.
As long as they can keep rolling the working capital, then there should remain a large cash pile all year around (fluctuating somewhat seasonally).
Of course, DFS took advantage of the cash, spent the lot, and took on debt too. Then they ran into trouble, and had to do an equity fundraise during the crisis.
For me, the SCS (I hold) cash pile is very nice, a big plus, but it's cheap on an earnings basis too, and well set up to pay bumper divis in the next few years. Hence a good value share to hold for the long term I think.
Regards, Paul.
Hey Paul,
I over-simplify for effect to be honest.
My point is essentially that people seem to automatically associate net cash (or negative net debt) to free cash being 'available' to shareholders.
In most cases it is really just part of the working capital equation. (Absent a full drill down, it look like that may the case for SCS).
The reason I mentioned My Cashley was that (from memory) GMD had an apparent negative EV which I think caused some to draw entirely the wrong conclusions.
I'm certainly not averse to SCS (LON:SCS) - it is on my list for a more detailed drill down with a mind towards a potential buy, but the apparent "cash pile" doesn't wash for me.
I'm actually quite a fan of businesses that can operate on negative working capital (having worked on one for much of my first career) however I don't see it as being automatically positive in investment terms.
SCS (LON:SCS)
You can thank myself and "Old ManFit" for closing the spread down to 205p to 206p.
I know you like SCS, Mr Scott... but when I've got profits of 25% to 50% on my book, a share that only makes me 1 to 2% no dividend, doesn't seem like a winner.
My mistake is, my Dad bought in @195p so got a winner with good timing, but I didn't get in until 230p, so really I've done a averaging down salvage exercise only.
Back in the special club this afternoon, by 0.7%.
I would say that if we could all have bought more of the 25%+ club and not have bought and/or exited earlier our not so good club then we could pat ourselves on the back and go stand outside the pub and drink a can bought from the off license as no doubt the supermarket has sold out!
I am still learning by the day and can think of several poor decisions that look disastrous in the rear view mirror (e.g. stop loss meant I sold Sdi (LON:SDI) @ 50p way back when) but then I got anchored and didn't over come that, so double error!
But welcome back to the special club which I am assuming means in the black for 2020?
Tommy
I am trying not to brag!
I broke my first investment Million this month, closing @ 1,001,137.71 tonight.
The figure fluctuates + or - 6% all the time so I'm in and out all the time presently.
I estimate growth (across all my businesses combined) to be 40% this year, 100% since Jan 2018.
My error rate - the amount of mistakes and regrets - is at least -10 to -20%.
As Paul so aptly said, anyone would have probably achieved the same thing by good luck using the Stockopedia StockRank toolkit. A rising tide raises all boats.
Today, I reduced Scs (LON:SCS) as Sir Paul bought.
At 1628, I placed all my cash (£38K) on £SUK2 . Sir Paul is hedging. My intuition suggests we've had a good few days; Lockdown III and I think we may have some "chop".
Not sure there maybe an EU deal.
In @ 642p.. Trigger @ 660p.
Paul
Many thanks for the direct expert advice you gave recently on which I am pleased to say I pulled the trigger immediately.
As a swift consequence, I thoroughly enjoyed last night's Christmas repeat of Yes Minister much more than any of the poorly written woke trash around nowadays. I'd forgotten what it was to laugh out loud at aTV programme and Paul Eddington has never been finer. (Jonathan Lynn was good enough to sign his book Comedy Rules for me a few years ago...ahem, just saying).
I have also very much enjoyed and benefited from your jottings throughout the year (my first investing year, since April) , and, while I am on, this being my first comment, I greatly value your palpable good-heartedness (as well as the comments of my adjacents).
Merry Christmas to all.
Julian
"I have looked at using Put Options as hedges, but they're ludicrously expensive"
If you think puts are expensive then why not sell calls? There are various ways of doing this. You could, for example, sell out-of-the-money calls to the value of your portfolio (or perhaps 120% of the value) or maybe sell at-the-money calls to say 50% of your portfolio value for a partial hedge.
Puts and calls should be the same "expense" because they can be arbitraged by the professionals. Buying a put is the same as shorting the index and buying a call. So, if you believe puts are expensive, then why not sell the equivalent call and take advantage of that, while hedging your portfolio at the same time? Also, if you sell calls, you wont get stopped out by volatility in the same way, which has obviously been a problem with your other hedges where you just short the index.
I'm not advocating any of these approaches, I'm just saying they exist and do not suffer from the problems you highlight. In the right situation, options have their place and can be used to do things that other instruments can't.
Here are my heat maps for today (prices as at ~11am).
Overall state of the market by ICB Industry classification:
Key to the Industry heat map contents:
SVCR world filtered to 'interesting' instruments ('interesting' means: reporting soon or recently; trending; breaking out; increased volatility - volume / ATR up; moving more than a 20d EMA of the ATR):
Small Caps with RNS news today ("N!!" in bottom row of the heatmap tile means report / update today):
Big movers today in the SCVR world (moving more than a 20d EMA of the ATR against either yesterdays close, or today's open):
Big movers today (not restricted to small caps):
And finally the key to the heat map contents:
The heatmaps are ordered by Stock Rank™, and are limited to the top 75 instruments. I define Small Cap using the Stockopedia Small Cap Size Group definition: Market Capitalisation between GBP 50 million and GBP 350 million.
The heatmaps are images and will be resized by your browser to fit your screen. If the heatmaps images are too small to read on your screen, right-click on the image and select 'Open image in new tab'. This will open the heatmap in a new tab in your browser where they can be zoomed as necessary.
I use heatmaps a lot and generate many (from my own application and database) to help focus my research. I use them to help me quickly find instruments which pass my basic 'tradeable' criteria (a 'T' in the top-right of the heatmap tile, meaning: profitable; low-debt; reasonable liquidity), have a high Stock Rank™ and Quality Rank, and are trending (Tr+ or Tr++) or breaking out (Br+ or Br++) ideally on increased volume (V+). I then research the identified instruments in more depth using the Stockopedia StockReports.
How (or indeed if) you use these heatmaps is up to you, I contribute these SCVR related ones here in the hope that others may also find them interesting or useful. I aim to post sometime in the morning when I can, but sometimes work / family and other priorities get in the way.
This will probably be my last opportunity to post until the New Year, so Thank You all for being such a great and community and especially to Paul and Jack for providing such great analysis. Hope you all have a great, and safe, festive period.
greensiax
A Trading Update from Nexus Infrastructure (LON:NEXS) on October 22nd said
"Nexus Infrastructure plc, a leading provider of
essential infrastructure services, utilities connections and smart
energy infrastructure, announces a trading update ahead of its annual
results for the financial year ended 30 September 2020, which will be
announced on 11 December 2020."
Has anyone seen an explanation why the results have not appeared on schedule?
Duplicated Deleted
SCS (LON:SCS)
A bit of personal commentary on SCS (LON:SCS) from me. This is my worst performer on my book currently and I want out. You know when you no longer believe in a share (a car, a house, a girlfriend...), its time to let it go as there's better options out there.
Its an absolute bugger to sell SCS (LON:SCS).
To sell £50K - HL quotes 203p (a loss for me).
I tried breaking my sale in to smaller and smaller chunks.
Eventually I tried executing 6 x 4000 shares at the same time... however HL blocked the second trade... (next time I'll try using more PCs).
So I ended up selling
4614 @ 206.38
4000 @ 206.125
This is a lesson learnt. These uninteresting low volume high spread shares... probably are not worth the bother. The price drops as soon as even as your own small trade hits the wires.
I still have 16,000 shares to dump... but I am minded to hold on until the price perks up again.
Agree with the above and you get multiple commissions charged.....been there with IG.
I was in SCS too, must have dumped at roughly the same time, it seems to cycle between 210-220 and 180-190 with a 5-7% spread depending on which way the wind blows.
Avation (LON:AVAP) (I hold)
Paul - NAV on this business is north of 270p so it trades at half that. The key to the business is that demand for planes outstrips supply. Thus, if as a lessor you can get hold of planes, you can lease them out with no interest rate risk and make 12% a year on them. So actually once the lease expires and you are handed back the planes the capital is paid and the plane is free and unencumbered. However, that is usually after 8-10 years and these planes have 20 year plus lifespans. So, impairments are really only on two items (1) the forward value of the lease when an airline gets into distress and (2) the value of second hand planes going down, which for well looked after planes is less likely as there is a demand/supply imbalance. Bit like Redde Northgate (LON:REDD) at the moment.
Now Avation (LON:AVAP) generally have flag carriers as customers so carry lower risk and most (think 70% odd) are now Asia where planes are flying. Clearly PAL, who has one aircraft, needs to restructure hence the credit risk impairment. of the forward lease but it is very small in the grand scheme of things. Some customers like Vietnam Airlines are expanding and taking more planes - regional routes, Avation (LON:AVAP) key focus clearly bounce back quicker.
The key risk (and key misstep by management in my opinion) was launching the bond offering originally. They have plenty of banks who will lend based on aircraft as an asset, thus allowing them to limit any contagion if there was a default on a particular loan or customer but in the search of lowering interest costs the company chose to tap the bond market. This is all well and good but if the bond market goes into dislocation at the time you want to refinance that becomes a problem. They have at least given themselves plenty of time to solve the problem though and the statement at the AGM today is somewhat reassuring even if it doesn't look like it at face value. Previously announcements about the bonds have not contained any information but today we see where those discussions are heading. More expensive certainly but reading between the lines an extension appears to be potentially palatable for both sides. There is a lot of security for bondholders so actually probably doesn't make a lot of sense for them to not extend as long as they get a commensurate rate of return, though you can never tell of course.
Are you sure about flights in Asia? I know some countries such as Thailand, there are hardly any flights because of Covid-19 and everyone who visits will need to do 14 days quarantine. Yes Vietnam Air is expanding or it was but there is a lot of competition from the Low Cost Carriers (LCC) on most of it's routes. I did fly with them from Thailand to Japan, doubt I will use them again. Flights to Myanmar are cancelled. Flights to and from Vietnam are very limited. There are restrictions visiting Japan.
Your comment seemed to imply flights in Asia are normal, this is not the case.
Go and watch the Avation (LON:AVAP) presentation on their website post the initial covid disruption. They show what's happening in Asia in terms of air traffic. Regional/Domestic flights are pretty plentiful and most of the airlines that Avation (LON:AVAP) lease to are operating well.
In particular Vietnam airways who I think are now Avation (LON:AVAP) largest customer where domestically they have almost doubled domestic flights from something like 1000 to 2000 per day through the pandemic, rather remarkably.
I'm not implying anything is normal just that when doing research it is sensible to look at the specifics rather than lump everything into one global category. Remember Avation (LON:AVAP) doesn't care if the airline is flying - only that it has the financial strength to continue paying for the leases. Their largest customers in Vietnam and China appear to have that and are flying many domestic and regional routes so are not grounded either. This just reinforces my point around financial strength.
For example if Avation (LON:AVAP) had a heavy weighting towards UK or US carriers or long haul flight dependent operators I would be particularly concerned but they aren't. They are focused in a sector that currently is operating a good number of flights and the domestic/regional routes will come back much faster than long haul. Nothing about the current situation is normal it's just that I view the main factor holding Avation (LON:AVAP) back is the risk in the refinancing of the bonds rather than the credit risk of the customers. Of course another worldwide grounding of air fleet could change all that, but let's hope that doesn't happen.
Avation (LON:AVAP) 2,000 Vietnam Airlines flights per day? Really. Hard to believe. Many flights to/from Danang are cancelled. There are about 50 flights per day from Hanoi. I'm struggling to find anything like 2,000 per day, maybe per week?
I had a look at the presentation, did not see anything about Vietnam Airlines, did you mean Vietjet Air? Vietjet are a small LCC.
Most of the fleet are turboprops. Total fleet is 46. If only 46 planes, how can they being doing 2,000 flights per day just in Vietnam? Unless I'm missing something?
Yes, I meant VietJet (not Vietnam Airlines : was thinking of my previous travels on them!!) and its's flights per week. I think I'm going mad today....obviously too much Christmas festivities involved :D
It's not that Avation (LON:AVAP) planes are doing 2000 flights p/week it's that VietJet are doing that overall and are financially stable, profitable and growing their routes and numbers of flights rapidly even through the pandemic. Vietnam overall is at a load factor exceeding 80%. As Vietjet is one of top two largest customers of Avation (LON:AVAP) it is unlikely to be having a problem paying its leases. Was meant as an example of Avation (LON:AVAP) customer base.
7 of their 18 customers are national flag carriers as well.
I did have a look at Vietjet financial information. Leases have been affected by Covid: "Reduction of fleet by returning 6 wet leased aircraft.
– Negotiating lease holiday period with its lessors from 3-6 months."
I don't know if these were Avation planes or not. Going forward this should not matter unless Covid gets worse, I see there has been a recent outbreak in Thailand. Myanmar the situation seems quite bad.
Vietjet have ordered many new planes, does that mean they need to lease them?
I'm not keen on turboprops, surprised Avation has so many in it's fleet, I only use them if there no other choice.
I have never flown with Vietjet, they have a poor reputation.
Not sure how stable Vietjet are financially, the H1 figures don't look good, I also came across this which was about 2 weeks ago: "has asked the government to encourage commercial banks to offer it soft loans of VND4 trillion dong (USD173 million), for which it would pay the principal and interest in 2023-2025, local media reported.
Speaking at a seminar titled “Overcoming crisis, developing Vietnam’s aviation sustainably”, the carrier’s chief financial officer, Ngọc Yến Phương Hồ, revealed that the company had incurred substantial losses over the last nine months, forcing it to sell assets, slash wages by 50% to 70%, and pay minimum salaries of VND8-10 million (USD350-430) to many staff."
I held Avation for several years before selling out in Feb this year when it become obvious this was going to be damaged short term. I would consider buying back into this at the right time because as Paul says the rebound is going to be big on airlines and the amount of planes scrapped this year will mean a big shortage.
For me the key is sorting out the bondholders first and if that can be done without too much pain then I think the share price could appreciate nicely.
Agree Brookeda - for me the key is resolving the extension of the bonds sensibly. If they can do that then unless we have another global airline lockdown again their residual customer base looks decent enough to be industry survivors and that means there should be little write down of Avation (LON:AVAP) revenues.
I felt when they did the bonds that they were moving away from the core stability of the original business model and it did concern me a bit in case of a financial crisis but I hadn't envisaged anything like this pandemic of course.
I think it is a bit misleading to think of Avation (LON:AVAP) as trading at 50% of NAV, as there is so much debt on the balance sheet. If the debt is valued at par, then the enterprise value (debt plus equity) is probably only closer to a 10% discount to the book value of the planes (this is a very rough calculation.)
In addition, the bonds are not trading at par. In November, the company bought back some of the 6.5% May 2021 senior bonds at 65% (when they had only 6 months to run to maturity) - so with a significant risk of capital loss priced into them. The discount on the bonds indicates that bondholders are not feeling too comfortable on the security they hold. Today's RNS indicates that bondholders might be prepared to extend maturities (for a fee and increased yield). There must be a risk that any agreed extension will lead to a significant transfer of value from equity to bondholders.
(I have no position.)
No Wimblesdonsprinter - NAV includes the debt - ie it is the capital value of assets minus any debt (hence the "Net"). You are double counting the debt.
Edit : The unsecured bonds of $346m are included in the total debt at par to come up with $220m NAV after impairments in 2020 results. Divide by share count and you get 265-275p
Should the bonds get redeemed at 70p in the £ it would actually add 100p to the NAV!! Of course that is very unlikely though they have bought back a few million at that kind of price, down to around $341m now. They have around $120m of cash I think so if bondholders don't extend they will either need to sell a portfolio of aircraft for $220m with the corresponding drop in earnings, or refinance with banks etc. There are a few options out there - in this particular case the bondholders don't hold all the cards. That said it needs to be sorted and will hold back the share price recovery until it is.
I think wimbledonsprinter is making a different point.
I don't know if that is true , but that I think is what ws was suggesting.
If so that does present some risks.
it strikes me (slightly light heartedly) that the only way the company could square this circle would to be raise some cash on the quiet and buy up all of the bonds immediately before the bond market wakes up to the fact they are not going to default.
That's of course hypothetical - I haven't looked at the company - in fact I'm not totally sure now what company we are talking about - having come in to the middle of a conversation ;-o
Gromley - no you need to look at the accounts. Debt is counted as redeemed at par in the calculation of borrowings against NAV. ie the full $346m (now $341m) is deducted from the value of the assets
So (rounded) Assets (post impairment ) = $1.4bn
Liabilities at Par = $1.17bn so NAV = $230m or £171m divided by share count 62.67m = £2.73
Liabilities at current Fair Value = $1bn so another $170m (only $85m corresponds to the bonds though). So if you were to redeem at fair value NAV would be $315m or £235m / 69.67m shares = £3.37
david - in that case I would probably agree with you - as I said I hadn't actually looked as whatever company this is we are talking about - I just thought wimbledonsprinter had made a different point to the one you were responding too.
#theperilsofjoiningaconversationinthemiddle.
I doubt the average Boohoo customer reads the Guardian or makes an in depth appraisal of working terms and conditions where their purchases are made. Or compares against other retailers.
I absolutely agree that customers of Boohoo (LON:BOO) (I hold) don’t read the Guardian, but shareholders and potential shareholders certainly do. With the market very much driven by sentiment I do wonder how long the significant miss match between this company’s fundamentals and performance will be so out of kilter with their SP. Will even the most stunning results close the gap, or will this perpetuate for some time to come?
I have looked at using Put Options as hedges, but they're ludicrously expensive. You have to be right not only about the direction, but also the timing of a big market move, because the daily decay of time value element of options seems quite high I've found when using them. There's a good case for using index options just before some major event, e.g. an election, or referendum, because they seem to be priced on recent historic volatility, not anticipated volatility. But that sort of options stuff is probably best left to the experts!
Thanks for the heads up, I have been wanting to get into options for a while so I started educating myself on it but haven't got to the pricing of them. Spread betting is off putting - not least because 76% of IG clients lose money on them - but b/c you really have to be smarter than the experts to win because they have an axe in the underlying market and other hedges...
BTW: I watched the Fixing Fashion broadcast with Boohoo (LON:BOO) and the execs. The experts were just trying to trip Kamani up and kept shutting down Andrew Keaney, one of the audit guys BOO have brought in to clean up their act. The questions on Kamani meeting up with the unions were ridiculous. No thanks for a UK company creating UK jobs! And no mention of what £ASOS et al play in fast fashion etc. It was an unfair session on £BOO. I hold Boo.
Hi snooker18,
I agree. Although the chairman in the BOO parliamentary session was quite good, and tenacious. The two MPs were hopeless, and just have their own agendas, the Leicester MP needs to be seen to be giving BOO a hard time, and Caroline Lucas is just a naive communist! Neither displayed the slightest understanding of business. I find that a worrying theme whenever I watch anything in Parliament (committees, etc) - it dawns on you that the people representing us have little to no understanding of the real world. I think that's because we don't pay them enough. Anyone who's been reasonably successful in commerce, would have overheads to match (big mortgage, kids in private schools, etc), so decent people couldn't afford to become an MP. Hence why we end up with either independently wealthy people, or the dregs from the public sector, as MPs. There are some very good, dedicated backbench MPs too, so I don't want to tar everyone with the same brush. Not many politicians strike me as people that I would think of as high flyers, in a job interview for a (say) middle management role in a small-medium business. They're usually just not commercial enough. It's all about virtue-signalling these days, trying to sound compassionate, and flinging money around willy-nilly. What happened to personal responsibility? You never hear any of them talk about that.
Regards, Paul.
You are 100% correct on personal responsibility - the gov't has (and is) wasting far too much £ on this pandemic, hosing anyone that pipes up with created cash as you say.
RE: I think that's because we don't pay them enough.
......But they pay themselves a squire's estate!! Look at Boris and his mates - those contracts were never advertised.........
I am right wing but the current leadership is ......well!!!
The socialist poison is so prevalent in the universities that I cannot see where a new generation of leaders is going to come from. I was loudly complaining about a quote from AOC, Alexandria Ocasio Cortez, the other day. "Millionaires don't make a million, they take a million".
My daughter who is studying International Relations at Sussex chimed in to say that she was right and that I should think of all the hourly paid staff who had contributed to the wealth a millionaire had made and how they had been exploited.
We had a frank discussion and I retold my story of leaving school with 3 O levels, starting out as a temporary warehouseman at Hoover and ending up being sponsored through university by them.
I convinced her that the issue is not the millionaires but the something for nothing envy riddled attitude of a lot of the extreme left wing as promulgated by The Guardian that is the problem. At least, I think I did.
As an aside, I was picking and packing at Hoover during the 3 day week, 3x12 hour shifts a week. Loads of fun. My niece has just started a picking packing job with Amazon in Truro, started as a temp on the bottom rung, has now been taken on full time and is as happy as a clam. All the left wing driven stories about how tough it is working for Amazon are bullshit. Good training, good conditions, lots of staff benefits. Unfortunately for The Guardian, Amazon would also like their employees to put in a fair days work for their money, which is, of course, outrageous.
Hi alpha2 - The young and their propensity to be socialists is an old topic
He who is not a socialist at 19, has no heart. He who is still a socialist at 30, has no brain.
Otto von Bismarck
Yes, I was on the Thatcher, Thatcher milk snatcher protests! But I did not hate the rich simply because they were.
Alpha2 - That to me Sir smacks of your good breeding and the era in which you were young, educated and of the standards of that time.
You may draw your own conclusions as to the cause of the differences today. A festive good day to you
Hear, hear!
I note the reference to Amazon; I think in fact that is another very fast growing company that did have some real employment issues and related scandal, albeit these actually were about their workers rather than those of their suppliers, but has addressed them and moved on rather successfully!
I think your summary of most MP's is far too generous
Spread betting is off putting - not least because 76% of IG clients lose money on them - but b/c you really have to be smarter than the experts to win because they have an axe in the underlying market and other hedges...
Snooker18 - I think that you may find the same applies to the Traded Options market.
The only time I was able to make it pay was when selling out of, or at, the money calls against shares I held to give some protection against a falling market especially to earn a bit of extra money on convictions long term holds. But then the market sails on, your shares get called, and you end up having to repurchase at a higher price.
In the end I gave up. It was way too much monitoring for, in the end, not that much gain.
@Snooker18 / @Laughton,
I have dabbled with SB probably once a year over the past few years. Too much time spent and little reward being the recurring theme ... in fact a slowly reducing balance to point where get fed up and make a silly, naive high stake bets / get stopped out.
However, over the past few months I have started trading US equity Options via a US broker. Wow, so many complex variables to understand / strategies to try and master ! Also subscribe to a Charting set up Slack group, which I must admit has been a great resource/ relatively fruitful of late. First couple of Option Platform deposits I made have been wasted not managing initial trades properly and then left to expire worthless. However, these were small positions and very much part of the learning curve. I am now looking at oversold US small caps based on chart set ups, and mostly employ credit/ debit vertical spreads, requiring much less premium (that willing to lose), but can offer c 4 x return max profit. Also, premiums for laggard names, before they attract 'herd volume' can be v reasonable to extent your CALL leg (i.e. the lower value leg) can be set at just ITM or lower to be more conservative. Typically, looking at 60-90 day expiries to factor in time decay / volatility, etc. Looking to exit way before maturity and setting profit level at 50% or 100%. At this point in time, I have had a good run of a handful if recovery play trades over the past week. Prob to do with Russel2K's surge since Nov. There are pullbacks/ red days but of late the US market tend to recover very quickly, even same day as seen this week. Albeit clearly that could all change very quickly ... but still very much to learn. The Tasty Trade YouTube videos are a great start, explaining things in a simplistic way.
As well as stock buys / Options, I occasionally spread bet set ups on IG.com where there is still some room to go versus estimated resistance or pullback levels. Setting an exit just below the forecast level. What I have learned repeatedly is that if you are convinced on a stock then it is best to set stop below the lowest level of the day and, of course, be prepared to lose that much, So what seems to be working at the mo, is small frequent bets within a reasonable sized pot. AS well as actually executing a 'buy low/ sell high' strategy and better understanding of charts too. Letting winners run, via trailing stops and accepting losses as part of the game. In theory if you are convinced on ultimate direction, and strong-minded enough to ignore the choppiness then you should end up with some degree of success. Also, to note, with SB/CFDs being banned in US, SB can be a useful tool for real time scalping during parabolic moves. Noting unique/ volatile times these days, i.e. opportunities are event driven ... Think my efforts are driven by the FOMO I suffered not being able to trade in run up to Lockdown 1 !
Sorry, bit of a waffle but just thought would share my early experiences. Would welcome hearing about other successes people have had lately in spread-betting endeavours, noting the tax-free benefits of same.
Best of luck to all in the markets.
Spl183
Useful...I was using Jim Schultz - Tasty Trade as he does make the dry theory on options v. accessible....
TKS Laughton
I have had some success with spreadbets by treating them as share purchases by taking the longer term bets 3 6 or 9 months and having a stop loss st about 20%. Good way to get exposure to overseas markets like USA at a reasonable cost.
Re Boohoo (LON:BOO) I thought the committee came across as uninformed, shouty, pushy and we’re not listening, it was a complete Kangaroo court. An embarrassing display of rude, self righteous time wasters. What was the guy they wheeled out there for with his factory Covid question without any substance about? And then these ignorant, rude people where trying to tell the people who had there stuff together how they should run their business. I felt it was racist and chippy, I really felt sorry for Kamani, a man who was humble, a hard worker and his achievements belittled. Not an old boy, not in the club. Patronised, instead of accepted for his contributions to jobs and building of a big TAX PAYING business. We need all those we can get. It was so obvious BOO had their ducks in a row that the committee didn’t want to see the new narrative as they were still stuck in a past based on what they’d read in the papers and seen on the news. Hardly an unbiased source, selling bad news. Terrible research. And what about the police doing the policing !!!
As you can see it made my blood boil! We looked like a bunch of idiots.
Merry Christmas everyone!!!
Large, high profile companies tend to get more scrutiny than small, lower profile ones.
In my experience, health and safety inspectors expect large companies to be near faultless and I’ve sensed a ‘make an example of them’ mentality at times to generally shock the smaller operators who are too many to police into action as a result.
Environmental activists will generally target high profile companies because it gets them more publicity. Likewise main stream journalists are not going to write about companies people have never heard of.
Boohoo (LON:BOO) are probably getting a lot more scrutiny now simply because they are very successful, large and high profile.
I’m not sure where an expectation of fairness comes into this. Why would we expect fairness? A newspaper journalist isn’t being paid to be fair. It seems that the only certainties right now are negative Boohoo articles in the media and the subsequent cries of “unfair”.
Are you saying that all other large retailers such as ASOS, next, m and s, primark etc are squeaky clean and, if so, how do you know?
No. I’ve not said anything like that at all.
Did you mean to reply to a different post?
Left wing journalists tend to the end of the spectrum that understands 'the causes of poverty, but not the causes of wealth'
Here is the next piworld 2020 round up interview with Stephen English. We interviewed Stephen back in April 2020. Here, he updates us on joining Stellar Asset Management on 1st September 2020. Stephen discusses, what has gone well and how to avoid value traps, advising don’t buy a recovery stock unless it’s rallied significantly, citing Volex (LON:VLX) Next, what didn’t go so well and learnings, where he discusses Shoe Zone (LON:SHOE) Finally, he outlines the investing case for Dx (group) (LON:DX.) which is his pick for 2020. Full of Stephen's wonderful analogies and humour, alongside some tremendous pearls of wisdom.
Video & Podcast.
Paul's wonderful interview in this piworld 2020 round up series, plus other guests (Leon Boros, John Rosier, Richard Leonard & Cockney Rebel), can be found here.
An excellent series Tamzin, thank you. Could you be persuaded to be interviewed, perhaps with Paul doing the honours?
Hi Somersetal,
An excellent series Tamzin, thank you. Could you be persuaded to be interviewed, perhaps with Paul doing the honours?
Great idea! I'm up for that Tamzin, how about it?
Best wishes, Paul.
Great idea, look forward to this one!
Paul, re Boohoo the ineluctable truth is that once companies get attacked they seldom fully recover no matter what remedial measures are put in place and irrespective of how they perform.
The glittering uplands up you have in mind will always have a fog of suspicion overhanging.
Thanks for all your great work this year especially for the BOTB and Novacyt heads up and insights- they were much appreciated.
I imagine Boo gets attacked, as its the biggest, most successful and high profile. And as such they need to lead by example.
“Re Boo the ineluctable truth is that once companies get attacked they seldom fully recover no matter what remedial measures are put in place and irrespective of how they perform.”
Err, Apple supplier appalling working conditions, suicide epidemic, suicide prevention nets out side workers dormitories....Apple appears to have moved on just fine since!
As stated previously I have been involved in these moral panics (within a social care context), the process once a panic/story has been firmly established takes time. For a year, 18 months nothing changes the narrative, and then one day it just stops, because actions have been taken, there is nothing more to address, and different stories/issues become more relevant/interesting. There has been no condemnation of Apple for worker conditions/suicides and poisoning from use of the chemical n-hexane (2010 & 2011) for years now. Many may not even know about the stories. The company appears to have done ok for itself and shareholders since and has been recognised as an ESG leader for some time (even if half of it appears to be cost cutting!).
If Boohoo (LON:BOO) proceed with all the things that they are doing, to address their supplier issues, (which in my opinion look excellent, particularly as the Board clearly gets the issues and appearnvery committed to addressing them) then by 2022 there should not be anymore stories to keep the narrative running, or at least not in relation to Boo.
Incidentally, as with Apple, I suspect that a side benefit of addressing supplier issues is that they will be very sensitive to all ESG issues and are likely to make significant strides in a variety of directions. The Chairman has ambitions for Boo to be a £20B turnover company, he is not going to allow the Company to mess up on these issues, or harm the business.
Martin
Apple is a great example to use for comparison, I find it laughable that Mr. Trump has been banging the drum for years about bringing jobs back to America, yet how would they start producing Iphones for the same price? It just wouldn't happen, to stay competitive the work will always naturally gravitate to the cheaper/more competitive labor markets. Yet like you say, they have done fine.
On the subject of ethics I don't think we need to look far though to find more ESG issues within our own jobs market that gets overlooked, lets look at automation. All the big supermarkets are introducing more and more self service tills, car production plants, automation in warehouses are becoming more and more advanced and there is no denying this will be helping the bottom line, pleasing shareholders and leveraging the directors bonus's. Yet no mention about the sustainability of the future jobs they replace. But I am sure you will find plenty of ESG funds with such like in their portfolios.
Sure we could argue jobs are created designing and installing these machines, but I cant help but think there is a ever growing number of low skilled workers in our own country fighting over fewer jobs. I would like to see some of these journalists expand on their ideas rather than dragging the same companies over the same issues.
Paul, re Boohoo the ineluctable truth is that once companies get attacked they seldom fully recover no matter what remedial measures are put in place and irrespective of how they perform.
I don't think that's right. There have been numerous "scandals" over many years, with the fashion sector, over brands exploiting cheap labour in poor countries. They're quickly forgotten by customers.
Some investors might give BOO a wide berth for now, but the figures do the talking, and they'll end up either missing out on a big riser, or buying back in at a higher price, in my opinion.
Paul.
P.S. To give due credit, I think it was Jack who wrote about Novacyt here, although I did discuss it with readers in the comments section & bought some myself around 400p.
Are you seriously saying that if Boohoo grows eps at ridiculously high rates for say the next 5 or ten years that the share price will not be materially higher? If so all the market evidence is against you as the saying is something like ‘in the short term the market is a voting machine but in the long term a weighing machine’
I don't agree, the news will focus on a topic for a while and then move on. I remember there were some attacks, on JD Sports Fashion (LON:JD.) a while ago, by the media but the shares bounced back quickly.
Amazon and Next (LON:NXT) were also attacked.
I remember similar issues to Boohoo (LON:BOO) with Marks and Spencer (LON:MKS) many years ago, which was to do with under age workers, which apparently led to many young looking workers losing their jobs. It is difficult to compare life in 3rd world countries to the UK, many don't have any social security safety net. If you don't work then you may not eat or your family may not eat.
This Boohoo (LON:BOO) news is getting a bit stale now. No wonder the share price has not fallen today.
I would challenge that using the example of Nike, which in the past was tagged for allegations of using child labour in overseas factories. Nike did then what Boohoo (LON:BOO) are doing now and cleaned up their supply chain. I see no reason why BOO cannot emerge similarly successfully from this.
Other random market thoughts.
1. UK takeovers. UK is very cheap by global standards and has been deemed uninvestable since Brexit first announced. That plus access to cheap capital..US investment grade debt still 2%. So expect deals to keep coming.
2. Positioning globally quite extreme now on the long side. Hedge funds as fully invested since 2010.
3. Q1 clearly going to be worse. I expect this will lead to more fund raising. Mixture of more balance sheet repair and "growth " capital. Suspect more likely in equity as banks still being difficult on new lending and corporate bond market only really works for big caps. More issuance likely to mean less upside?
4. Some stretched looking valuations. Most analysts now talking about 2022 numbers..what happens if we start looking at 2023. I've started looking at some 2023 numbers and the risk reward just isnt there.
I'm sure there's more!
Merry Xmas everybody and many thanks to all the excellent contributors but especially Paul and Jack.
MH1, agree with all you said except point 4. UK companies may seem to have stretched valuations but really in a zero/ negative interest rate world with walls of money looking for a home, the FTSE is massively unvalued compared to global peers. There is one reason for this - Brexit - it has introduced a cloud of uncertainty which the market has had trouble pricing in and therefore has just ended up discounting UK shares over the past four years in response. I would argue that once we get past Q1 next year, there is a chance of certainty on Brexit (whether positive or negative really) that will cause a revaluation versus peers. If that is matched with some confidence on COVID being dealt with, there is a chance of a major move up in UK markets that takes all boats with it.
The below table is a little out of date but this situation has only exacerbated during 2020:
If we can get clear of Brexit, I’m going to turn extremely bullish on the UK.
We are actually in agreement. There are certain companies that I consider overvalued or will have to do plenty of work to grow into their valuations. However, I am currently 95% UK. There are plenty of opportunities even though the risk reward is not as clear as it was pre vaccine.
The most stretched valuations I look at are the tech names in the US. A lot of huge multiples of sales. I'm not smart enough to know who are the winners or how to value a lot of them. Let alone the Ubers or Doordash types which I just never see being profitable enough to justify current market caps.
Agree on 1-3 and there are some quite interesting IPO's comping up too - Darktrace, Revolut, maybe Graphcore? Deliveroo too but I'm not a fan.
On point 4, Early on in the covid panic, $5 trillion left equities and moved into money market funds. Much of this returned to equities in November. Just an interesting point to note, does that mean markets are near back to normal or stretched?
https://www.cnbc.com/2020/06/2...
https://www.cnbc.com/2020/11/1...
Each person will have their own view but I think there are quite a few strong companies 'reasonably valued' and dare I say, a few 'cheap' but strong companies - I don't see as many of these now compared to back in April-July time though.
Maybe something like the UK housebuilders which are held up by govt policies, or maybe Itv (LON:ITV) (possibly but have a lot of competition), or everyone's new favourite investment - alternative energy - something like Aggreko (LON:AGK)
I'm not recommending anyone should buy any of these because that would be taking a view on their future, I'm just saying they don't look stretched on a fundamental level and there are pockets which look a good price and might have improving prospects in 2021/22/23 and beyond.
£BOO. I too find the constant desire to have a go at Boohoo very perplexing but it does seem to be the “English” way to have a go at success. There has already been quite a lot of vilification heaped on the Issa brothers, who started with one petrol station in 1999. And yet it is these successful companies that pay for The Guardian’s beloved state services. Odd.
I think one has to be very careful about judging standards and levels of income in other countries against those expected, and normally attained, in “western” countries. The wage level quoted 29p an hour is meaningless without context on the standard of living. To give that some context GDP per capita in Pakistan is $1,130 and in the UK (on a PPP basis) $44,288. That is 30 times greater than Pakistan. Therefor 29p/hour is the “equivalent” to £11.36 per hour in the UK. (Some economists might shoot me down on this but I don’t think it an unreasonable extrapolation).
As for squatty loos, that is almost laughable. I have used a “squatty” in France in the last 12 months.
I hold Boohoo (LON:BOO), my largest holding.
Regards
Michael.
I think one has to be very careful about judging standards and levels of income in other countries against those expected, and normally attained, in “western” countries. The wage level quoted 29p an hour is meaningless without context on the standard of living.
RE: Boohoo (LON:BOO)
It's less about comparative income and more about obeying the law.
The wage quoted is 10,000 a month, the minimum wage is 17,500. So, if true, workers are being underpaid by about 40%. From what I can see the minimum wage is roughly equivalent to the GDP per capita, although that fluctates a lot from year to year.
timarr
Tim
Thank you for your comment on £BOO.
I suspect that Boohoo is turning in to a marmite stock but I will need some convincing that the investment case for Boohoo (LON:BOO) as being woefully under valued is not correct.
Of course there is no excuse for breaking the law under any circmstances but:
I always value your comments Tim when you post here regardless of which company it is about.
[EDIT} Have emailed Booho about amount of product produced in Pakistan though I don't expect an answer!!
Regards
Michael
I always value your comments Tim when you post here regardless of which company it is about.
Hi Michael
Thank you. It's always nice to be agreed with but I've always found the most valuable contributions are those that force me to re-evaluate my prior convictions. Those have made and saved me a lot of money down the years.
On Pakistan minimum wage I suspect the answer is that GDP per capita fluctuates a lot from year to year. Presumably that's in part due to exchange rate variations, but they'll also be at the mercy of world events such as we've all been experiencing this year.timarr
MichaelFBS
To give that some context GDP per capita in Pakistan is $1,130 and in the UK (on a PPP basis) $44,288. That is 30 times greater than Pakistan. Therefor 29p/hour is the “equivalent” to £11.36 per hour in the UK. (Some economists might shoot me down on this but I don’t think it an unreasonable extrapolation).
I am not an expert but i will gladly try and shoot you down in flames here Michael seeing as you asked for it :)
Wikiedia suggests the minimum wage in paksitan is $144 dollars per month so its looks like 29p per hour is very much illegal slave labour rates that should not be equated to anything that is acceptable or generous even if the maths behind your calcs may be technically correct.
I would say the logic of your calcs don't quite seem right or fair either- i would say a figure of $44,288 is completely non relevant to what an individual needs to subsist in the uk - so doing comparisons that may seem favourable compared to that number don't sit quite right when the minimum wage in paksistan is probably simply enough to get very basic food and hopefully a roof over ones head and probably very little more. In the uk nowadays you are deemed poor i think if you don't get at least one weeks overseas holidays - never quite understaoof the logic of that.
Minimum wage per month in $, not £, and doesn't quote how many hours can be worked....
Thornabian
Minimum wage per month in $, not £, and doesn't quote how many hours can be worked....
I think its 8 hours a day which seems about right - i am well aware the $ converion rate and i stand my my comments and numbers unless corrected.
If we say they are paid 40 hours per week * 29p per hour * 4.333 weeks in the month thats £50 pay for the month - well below $144 minimum wage whatever exchange rate you use nless i have flunked my maths here. Its clearly illegal and exploitative - i stand by my comments therefore that Michaels original calcs were giving the wrong impression by saying they were bascially above minimum wage "equivalent" when exactly the opposite appears to be the case. I only did quick calcs mind so am happy to be corrected if my calcs are wrong as they may be.
Luckily for Pakistan's economy, it isn't in the EU and the 48 hours a week legal limit doesn't apply - not that many people actually only work less than 48 hours within the EU, I have certainly worked over that many times. But I digress slightly. My point is, in China, India, Pakistan, Bangladesh and many other EM countries, they work 6 or 7 days a week and the pay is not high due to wage demands and that is why low margin companies seek out these areas. China had this for many years and the progression of the economy has lifted millions out of the lower class by drawing in business and slowing improving productivity to upscale the economy.
It might seem exploitive in the regulated 'West', but it isn't even a considered fact in many countries and I'm not just being flippant about that. They either draw in the work, or they don't.
We can sit and say it would be great if everyone got £15 per hour but that would make most industries unviable and why those industries seek cheaper areas to do the same manufacturing and supply to manage costs.
To continue this crusade of everyone needing to be paid more and more, is just driving businesses to these cheaper and cheaper and less regulated places. That isn't something which can just be ignored and say "so what, force them to pay people more".
Some balance and perspective is needed.
Michael, I'm so missing my annual month in France. One of my most memorable times is when I watched nearby as my wife was chased out by a flood after flushing a partially blocked hole in the ground, a good job there was swing door. Another time, another place, nesting swallows flew in and out over my wife's head a three-quarter door of a loo that positively hummed. Naturally I performed my number ones as Frenchmen do.
Regards,
Silver
How did we get onto this topic? Do you remember those traditional French toilets where the women had to walk past a row of peeing men to get to their cubicles?
:-) I think because The Guardian brought up “squaties” as an indication of poor corporate governance!! Sorry to be flippant about a serious issue but I ran my own business for 30 years (and couldn’t wait to get out for about the last 10 of those) because at times (most of the time?) one seemed to be working for the government or complying with some regulation or other that had been introduced with no thought to the real world.
Regards
Michael.
Hi Michael
Me too!
I found that the worst ones were the vast array of HR regulations that were brought in during the late 90s, early 00s, which every time I looked for advice on their meaning/implications the solicitors would say, no one knows until case law has built up, in the mean time don’t do anything that could ever possibly be later considered unlawful, do everything 5 times over to ensure that you can demonstrate compliance. Talk about the ‘precautionary principle’; what a disaster for actually running a successful business....and in my experience mostly did little for good workers, the people who benefited were con people, HR and Lawyers.
Martin
very well put Michael . Could not agree more and Boohoo is also my largest holding .
Morning Paul.
Wondered if you might look into this tiddler:
Cambridge Cognition (COG) provided an RNS on Monday of another contract win for £700,000 mostly for 2021 but very little market reaction.
I estimate that COG have now booked at least 70% of revenues for 2021. This seems to be an interesting turn around to me. Last figures mentioned for 2020 were rev of 108% of projected so on course for this year.
I hold
Michael
Hi Michael,
After years of under-performance, I think Cambridge Cognition Holdings (LON:COG) is starting to look moderately interesting as a turnaround.
The big problem is lack of market liquidity, I tried to buy some stock a while back, and only got 5,000 shares (about one tenth of what I ordered). Hence why I lost interest at that point.
The de-listing risk worries me too.
There's clearly demand for its niche product, and I think it's quite high margin, if they do win contracts, so could be good operational gearing there. I met old management a few years ago, at a wine bar in the City (free beer, yay!). The PR chap raised a smile when he said (after the presentation) - "If you would like to try out the product on an iPad, and see how it measures cognitive impairment, then please go over there. Alternatively, if you wish to cognitively impair yourself, then please go over there" (pointing to bottles of beer lined up on the bar)!
It's a simple product, but there's masses of data, accumulated over decades, behind it. The argument has always been that, if it becomes a standard part of testing new drugs/treatments, then it could be lucrative for COG. They've been saying that for years now, and it's really very much at the stage where investors want to see results, not more promises.
Shame it's not more liquid. I'm reluctant to get stuck in something this illiquid, but think I've just talked myself into trying to get a few more in the market!! Thanks for flagging it.
Best wishes, Paul.
Thanks Paul.
Well I hope you chose to suitably impair yourself with some beer!
Agreed, it is small and illiquid.
In May 2018 SP was 170p, A while later there was a delayed contract and a lost contract as the client had merged or been acquired (no fault on COG's part) and the SP started falling. Simon Thompson was recommending and then bailed and SP fell further to around 30p and then C19 to below 20p. And then a placing in Feb at 20p. Directors participated and have good options and high targets.
New CEO arrived March 2019 - has got rid of poor sales staff and kept better ones. Has a much more commercial focus and has streamlined the biz. Contracts have been coming in. Most recent comment about 2020 revs was 108% of revs. Cash is improving. as mainly receive payment at start of contracts. Approx 70% of 2021 rev already booked. Management say there are in many discussions.
Margin is 81/82% and costs pretty stable so operational gearing if many contracts come.
Had a video call with CEO and CFO after Interims. Their body language was very positive and their faces kept breaking into smiles every time I asked a question. I considered this a particularly good sign.
Good luck Paul, if you get some more shares.
Obvs there is considerable risk here. DYOR.
Michael
Re Boo, I hold.
Paul, never bother, it may be a great day again to buy on a spike down.
Merry Xmas to you , Jack and subscribers
Pip. X
On Boohoo (LON:BOO) there are large scale on ongoing concerns about the fast fashion industry in general. However, this particular run of articles wasn't triggered by the offshore concerns but by the possibility that shoddy working practices in Leicester were contributing to the spread of CV-19.
If investors are interested in the broader analysis of the fast fashion industry rather than something that focuses specifically on Boohoo you could do worse than start with the the Parliamentary report from 2019:
https://publications.parliamen...
In that report a number of FF retailers were specifically praised for being engaged - ASOS, Burberry, M&S, Tesco and Primark - while a number were criticised for the opposite - Amazon, Boohoo, JD Sports, Misguided, Sports Direct, TK Maxx and Kurt Geiger (the latter failed to even respond). A number of recommendations were made and the government rejected them all:
https://publications.parliamen...
Where this will go is anyone's guess, but it's unlikely the campaigns to regulate fast fashion will go away. In the meantime consumers show little sign of disengaging, regardless of publicity.
timarr
Thanks timarr, it would be fun if MSM once in a while also shared wider context like this.
It could be argued that, given Primark’s good reputation in this area, Boohoo (LON:BOO) were already beginning to get to grips with this supplier problem by appointing Primark’s COO as their new CE in September 2018 (started March 2019). The problem for Boo as a large and growing company is that this sort of change takes time to implement, not least as a very large proportion of it is not within their own company.
I am pleased that these improvements are taking place, and think Boohoo will be better for them, but it is fascinating that generally the Government and police appear to have completely relinquished any responsibility for policing and prosecuting companies who break their laws such as H&S, VAT or minimum wage in this sector! I imagine branches of Government still take quite a direct interest in other sectors, eg the production, tax and sale of alcohol.
Anyway, thanks to all for making this such an interesting, enjoyable and productive forum.
Remember that however gloomy things look today, others are having a far harder time. Just read the latest newsletter from ZANE (charity) to see what real hardship looks like (as Paul has highlighted they are very worthy of our support).
Happy Christmas, and best wishes for 2021!
Martin
(I hold Boohoo (LON:BOO))
Would appreciate your thoughts on Immotion (LON:IMMO) which I hold. Australian location experiences have been able to stay open, US open with some limited to 25% capacity and UK now shut. They don't give total revenue figures apart from October and November which see significant increases on September 2020. Creditable from management to launch a Lets Explore Oceans a new home entertainment product which has been selling well in the UK shifting £800k in 2 months. And to monetise the Uvisan disinfection cabinets originally developed for in house use. The accreditation from Hewlett Packard for the Uvisan cabinets is promising as is the launch of Lets Explore Oceans in the US in 2021. As holder would have liked to see some revenue figures for the Uvisan products . I do concur with their summary that 'Whilst the short-term impact of Covid-19 is very frustrating, we remain confident that demand will be very strong for our LBE offering when any sort of normality returns. This would result in very substantial uplifts in revenue and contribution from our LBE business.' Happy to hold into 2021.
I finished selling my holding last week - had nearly 3 million shares and took around a week. If you compare this update with the previous trading update, there is a lot not said. Previous update mentioned EBITDA but this one does not. They had sold 3600 headsets at time of previous update with a further 7000 sourced = 10,600. Now they report 11,000 = not much difference. No figures for Uvisan.
Previous update talked of £400,000 for headsets excluding VAT, now £800,000 inc VAT. Providing figures ex VAT in one TU and in next TU inc VAT is IMO misleading. Don't like this and leaves me to wonder if other stuff is presented in a clever way which I might miss. Not necessary to report like this.
I sold as I think C19 environment will last longer than expected and received an email from Immotion offering me a LEO at a discounted price which made me wonder about the sales.
Luckily I bought my shares at an average of 2.5p and sold average just over 4p so happy.
My morning smallcap tweet:
SEEEN (LON:SEEN) Immotion (LON:IMMO) MaxCyte Inc (LON:MXCT) Carclo (LON:CAR) NMCN (LON:NMCN) Infrastrata (LON:INFA) Powerhouse Energy (LON:PHE) Avation (LON:AVAP)
SEEEN (SEEN) in line. Ghastly pile of jargon at this absurdly named tinpot: "video experience platform that enables creators, brands and publishers to unleash video for improved digital marketing yield and connected audience experiences, including frictionless e-commerce..." [SP=25 Cap=12m]
Immotion (IMMO) Oct rev up 21% on Sept, Nov up 87% despite covid closures. [SP=3.26 Cap=13m]
MaxCyte (MXCT) guides FY head of market expectations in the core life sciences business (before CARMA costs). CARMA? [SP=456 Cap=350m]
Carclo (CAR) wins 10 year framework agreement with a major global OEM for the manufacture of complex medical diagnostic disposable devices. Production contracts (subject to a number of conditions) expected in 22H1 with full production volumes in 22H2 when rev expected to be £10m and £15m PA. [SP=12.2 Cap=9m]
NMCN (NMCN) guides FY loss of £11.2m. Also £5.3m of FY19 pretax adjustments to five contracts in the Water business. The total (£16.5m) is greater than Oct guidance of £13.5-15m. Improved debt collection and delay to supplier payments to operate within current overdraft facilities of £15m. New debt package will be in place by the end of Feb. [SP=275 Cap=29m]
Infrastrata (INFA) £7.4m placing at 45p, a 12.6% discount, for capex. Also OO. [SP=51.3 Cap=33m]
Powerhouse Energy (PHE) see no reason for recent SP rise. [SP=7.7 Cap=286m]
Avation (AVAP) sunlit uplands foreseen at AGM. "Avation is optimistic about the medium term opportunity for air travel particularly the turboprop and narrow-body aircraft sectors. The Company will position itself for a return to growth through opportunistic purchases and delivery of its orderbook." [SP=130.5 Cap=82m]
Hi Paul,
Looks like, if you have not bought them already, you will have all day to buy those parsnips :-)
Morning shanklin100,
I'm sorted thanks! A 10pm trip to ASDA last night (they're open until midnight today too) has replenished the pantry! Very good price too, only 20p!
Hi Paul
LOL, very pleased for you (and your mother).
Kind Regards, Martin
Glad you got them Paul
I was rooting for you
LOL Mike!
I thought the price was below par, a snip! :-D
I'll get back to writing the report...
Regards, Paul.
All this despite the Blockade of Britain. At least we'll not run out of fish...
True but no one wants to eat it.