Small Cap Value Report (Wed 23 Oct 2024) - CRDL, BPM, FRAN

Good morning from Paul & Graham! All done now. Have a nice afternoon!
Explanatory notes -
A quick reminder that we don’t recommend any shares. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech, investment cos). Although if something is newsworthy and interesting, we'll try to comment on it. Please bear in mind the "list of companies reporting" is precisely that - it's not a to do list. We typically cover c.5 companies per day, with a particular emphasis on under/over expectations updates, and we follow the "most viewed" list of readers, so if you're collectively interested in a company, we'll try to cover it. Obviously with the resources available, we can't cover everything! Add you own comments if you see something interesting, and feel free to discuss anything shares-related in the comments.
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to, if they are using unthreaded viewing of comments.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. And/or it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Others: PINK = takeover approach, BLACK = profit warning, GREY = possible de-listing.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom), Video update of results so far, June 2024.
** New SCVR summary spreadsheet for calendar 2024 ** This is the live one! (updated 6/9/2024)
Archive - SCVR summary spreadsheet for calendar 2023.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Phil Hanson's data analysis measuring performance of our colour-coding system in the SCVRs, from July 2023- Mar 2024 (with live prices). My video explaining/reviewing it.
My other video (June 2024) - How to screen for broker upgrades on Stockopedia. More stock screening strategies here (possible bargains?) - 21/9/2024.
Companies Reporting
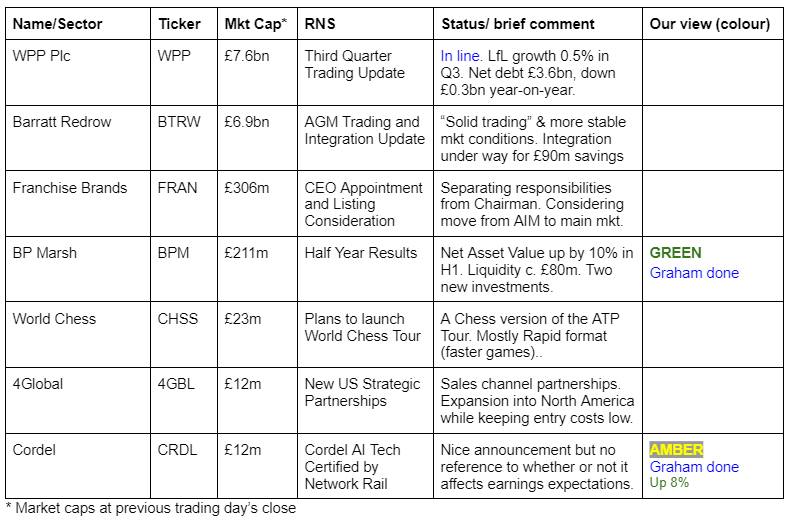
Summaries
B.P. Marsh & Partners (LON:BPM) - up 1% to 574p (£213m) - Half Year Results - Graham - GREEN
I’m happy to stay positive on this high-performing investor in insurance startups. This is the type of investment vehicle I like: they invest in a niche which we can’t easily access, and they do it well. The discount to NAV is still over 10%.
Short Sections
Cordel (LON:CRDL)
Up 8.5% to 6.2p (£13m) - Cordel AI Technology Certified by Network Rail - - Graham - AMBER
This calls itself “the AI platform for transport corridor analytics”. It automates railway line inspections and surveys using video systems and LiDAR (the laser technology that’s increasingly being used in cars).
Today’s announcement signals progress: “Network Rail has provided a Certificate of Approval for Cordel's AI-powered outputs for Electrified lines.”, with approval for the Cordel system throughout Network Rail infrastructure.
CEO comment:
Cordel achieved this approval for capturing and processing data from trains running at full speed in passenger service. Network Rail has some of the most stringent infrastructure monitoring standards in the world, and we believe this approval consolidates our position as the most advanced supplier of AI-driven railway infrastructure insights.
Estimates: Cavendish have left their forecasts unchanged on the back of this morning’s announcement, which says to me that this approval was already baked into forecasts. Estimates suggest that adj. PBT will be close to breakeven in the current financial year (FY June 2025: £0.4m adj. pre-tax loss estimate).
Graham’s view: Paul gave this “AMBER/GREEN (speculative)” back in April. I share his view that this looks like a nanocap with a real, innovative product that works - which is more than can be said for many nanocaps!
I also note that the company recently raised £1m at 6.5p. Its cash balance had fallen to £1m (as of June 2024). So it should have enough cash to keep the wolf from the door for the time being.
I’d like to maintain the AMBER/GREEN stance but for me this is too early-stage so the best I can do is AMBER.
Franchise Brands (LON:FRAN)
Up 4% to 165p (£320m) - Group CEO Appointment and Listing Consideration - Graham - AMBER
We’ve been neutral on this one (Oct 2023, June 2024) but the company has been a decent performer and remains highly ambitious with two changes announced today.
Firstly, the CEO of FRAN’s Waste & Water division has been appointed Group CEO and a member of the Board. The idea is to split off some responsibilities from Exec Chairman Stephen Hemsley, who co-founded FRAN back in 2008 with Nigel Wray (they were both heavily involved with another small franchising operation, Domino's Pizza (LON:DOM) ).
With the new Group CEO taking charge of day-to-day leadership, Mr. Hemsley will be able to focus on “the strategic and corporate development of the Company, including Group finance and future acquisitions”. He will remain Exec Chairman, i.e. he is not downgrading to a non-Executive function.
Secondly, FRAN is considering a move away from AIM and onto the main market:
Given the scale and growth ambitions of the Group, the Board is beginning to consider a move from the AIM market to the Official List and Main Market of the London Stock Exchange. Today's announcement of the appointment of a Group CEO and separation of management responsibilities for the strategic development of the Company and the day-to-day leadership of its businesses is the first step in that journey. These considerations are at an early stage
Graham’s view
First, I think it’s usually a good idea to have both a Chairman and a group CEO, rather than a combined role in one individual. Corporate governance 101 says this. So splitting off some responsibilities away from the Exec Chair makes perfect sense to me.
Ideally, I’d want the CEO to also be in control of strategy and financing, and for the Chair to provide oversight of this. FRAN haven’t achieved that yet, but perhaps they will down the line.
As for moving from AIM, I don’t think it matters too much at this stage. FRAN is too small to get into the FTSE-350 Index (you need about £500m to qualify) and if they are in the FTSE Small-Cap Index on the Main Market, I don’t think that will attract many more investors compared to an AIM listing.
If or when their market cap gets over £500m, that’s when the big reward of a Main Market listing is inclusion in the FTSE 350.
I’m happy staying neutral on FRAN.
Graham's Section
B.P. Marsh & Partners (LON:BPM)
Up 1% to 574p (£213m) - Half Year Results - Graham - GREEN
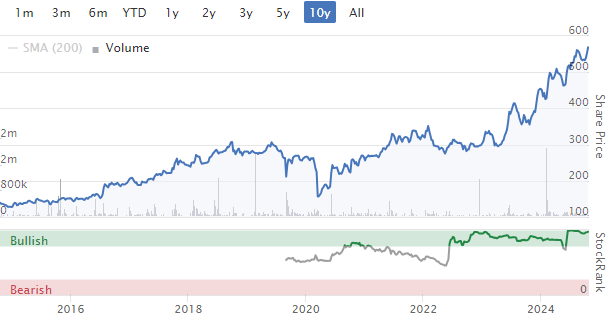
I’m a long-term fan of this investor in the insurance sector. It has truly compounded wealth for its shareholders over the years:
Today’s half-year results to July show continued excellent progress:
10% growth in Net Asset Value per share over six months (to 691p). Including the effect of options, diluted NAV per share is 658.5p.
Total return 12% over six months, including dividend payments.
Chairman Brian Marsh OBE welcomes a new CFO and says:
"We are pleased to report another strong set of results, delivering growth in portfolio value, investment realisations and shareholder returns.
"The completion of the disposal of Paladin during the period showcases the success of B.P. Marsh's investment model, our ability to identify opportunities and to back successful management teams.
"We remain committed to maintaining this momentum, leveraging our expertise to drive further sustainable growth via new investment opportunities and follow-on funding.
New investments: three investments were made in H1 and so far in H2, two new investments have been made. Both new investments are in underwriting agencies. In my experience, BPM typically risks small amounts of funds on new investments but is very likely to provide further funding as the investee grows.
There is great emphasis on the track record of investee management and since BPM focuses on a narrow niche within the insurance industry, it seems to be highly skilled at assessing management teams in this niche.
Cash: BPM has been drawing in cash thanks to two large disposals that have brought in over £90m.
It has paid out the first £4m of a planned £12m in dividends, with another £4m planned during FY Jan 2026 and again in FY Jan 2027.
Whereas the company previously bought back its shares when it could do so at a 20%+ discount to NAV, this summer it started buying back shares at only a 15%+ discount.
More recently, it has been buying back shares with the requirement of just a 10% discount.
While the buyback programme has only been for £1m, which isn’t really material, I think the willingness of the company to take advantage of the remaining discount is positive for shareholders.
On today’s figures, the current share price is a 17% discount to NAV (using the higher NAV estimate that ignores potential dilution).
New CFO role: BP Marsh has hired its Group Management Accountant as the CFO.
I have the impression that BPM likes to hire internally and that its senior people tend to stay at BPM for many years (the new CFO has been with the company since 2013). Is this a good thing? I would say yes! It’s good for stability and culture.
Graham’s view
I’m happy to stay GREEN on this one as usual.
Even on a fully diluted basis, the discount to NAV is currently over 10%.
Given BPM’s track record, I’m inclined to think that it’s worth its NAV.
I should point out that calculating NAV for BPM means putting a value on unquoted investments whose value isn’t guaranteed in the same way that the value of a portfolio of liquid investments is guaranteed.
However, BPM’s calculations of values were verified by its recent large disposals.
Therefore, after another strong six months, I’ll continue to give it the benefit of the doubt.
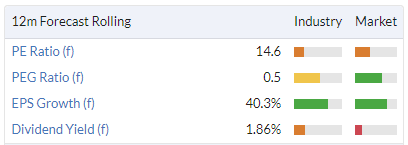
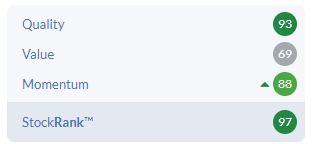
The StockRanks agree with me:
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

63 comments
Happy to see lowly rated "value trap" Pennant International (LON:PEN) (I hold) pick up a contract today from the MoD https://www.stockopedia.com/sh...
£4.9m over 3.5 years from April 25. SP bumped up 12% immediately upon release of the RNS although not sure this will remain here.
There was also an RNS yesterday noting that Harwood upped their stake to over 11% (Rockwood also shown as having 9.65%)
Pennant had a fund raise back in May raising £1.36m at 25p and have been adding interesting characters to the board, including, in September, Klass Van Der Leest of Intercede (LON:IGP) fame who also purchased a small amount of shares to show willing.
Happy to go along for the ride here and see if they can make something of themselves.
Any other holders here?
Pennant International (LON:PEN)
Hi Peter, yes those contract wins were a nice little surprise to come home to today, tiny market cap with big ambitions, I'm happy to go along for the ride too....
Just a small correction to the write up of Franchise Brands (LON:FRAN. Hemsley and Wray were senior directors of Domino's Pizza (LON:DOM) the UK and Ireland Dominos Franchise business not (as reported) the Polish one. Clearly a much bigger and for many years a very successful business and a very successful investment. I am guessing the error was just a fat finger trade trying to pick the company using the @ function. Many thanks as always
Thank you so much! The @ function defaulted to something else, I must remember to check for that. G
Look, I know some of you, including Paul, have reduced some holdings and are holding cash in advance of
- the budget less than 1 week away
- the US presidential election less than 2 weeks away, and
- the BoE and Fed rate decisions less than 3 weeks away
but, I'm not very good at keeping my powder dry by holding cash and sitting on my hands.
In the hope that, like this time last year, fortune favours the bold and, as Paul Hill postulates, the budget concerns are overdone giving us a Santa rally to make up for the sideways market since the election, I have topped up
Tristel (LON:TSTL) , Franchise Brands (LON:FRAN) , Property Franchise (LON:TPFG) and Alumasc (LON:ALU) over the last week and looking to open a position in Volution (LON:FAN) as I see them all benefitting from the government's policies and lower interest rates.
Good for you. I’ve completed building a position in Tristel (LON:TSTL) this last week on the basis that, after recent action, it’s no longer offering decent capital gains to anyone who bought this side of 2018 and it isn’t an IHT planning plodder. Yet operational performance has been pretty good throughout, 2022 notwithstanding. I trimmed Alumasc (LON:ALU) at the top and will buy that tranche back if it falls much further (250p?)
I’m halfway through building another quality position and just waiting on an earnings update to buy the second half - or retreat.
Hello BnB
Don't quite understand/ get it ' and isn't a IHT plodder'. Could you please clarify - sorry to be a pain!!!
KBR
By “IHT plodder” I mean those AIM-listed companies with stable prospects and low volatility share prices that are beloved of those seeking a safe harbour for their attempts to avoid IHT in their dying years by claiming BPR. James Halstead (LON:JHD) would be the classic example.
It's interesting that you've picked up Tristel (LON:TSTL) as their progress in the USA is one year behind their expectations according to their IMC meeting. The danger is that hospitals in the US are more reluctant to purchase at all rather than merely slow to do so.
I always hear this and think, I cannot time the market. Most people agree and then try and time the market. It's very seductive. I cannot understand a countries or the worlds economics, but in a few companies, I think I can understand their economics. So rather than concern myself with things I cannot understand - but are important - I am focused on the companies that I like and so I will keep buying while the price is at or under my buying price. I don't buy with leverage and I always think I will own what I buy for at least 10 years. This helps me to stay away from speculating on trends that I am never going to be good at. For me, this trend of selling is an opportunity to increase my shareholdings in the companies I love (money love, not emotional love). I just wish lots of people would start selling their Berkshire Hathaway shares and get the price down to my buying price. And yes, I own Berkshire Hathaway shares and I am very happy that if I get what I want, the market value of my current net worth goes down as I believe my future net worth increases, a lot more and this is worth waiting for.
Warren - is that you??
No
you're a bit early for the Santa Rally !
Given the uncertainty caused by Rachel Reeves' forthcoming Budget on the 30th Oct.
What's the chances that in October, UK smallcap equity funds see their biggest outflow ever?
That said - if by fluke she decides NOT to touch IHT relief on AIM shares - then there could equally be a major Santa rally heading into the yearend.
Lot's of weird & wonderful stock movements ATM. Investors selling what they can, not what they want to.
I have pointed this out before, but more than 50% of BPR applies to unlisted privately held companies (your local greengrocer or restaurant). The proportion of AIM shares that will attract BPR is pretty small. Less than 4% of estates attract IHT.
Paul, you say "by fluke" but perhaps she weighed significant damage to the market (as a capital raising venue and the liquidity needed for the secondary market) versus the very small tax revenues it might raise (many estimate only 100m per annum)? We might hope she might be "scientific" about the best place to easily and reliably raise the revenue to fill the "black hole". Let's see
Just a heads up folkes re possible removal of aim bpr.
I've just been reading an article that mentions if it happens the two funds managers that could be hardest hit are Liontrust Asset Management (LON:LIO) and Premier Miton (LON:PMI) so if you have either on your radar your might want to hold off buys until after the budget.
Flip side is in the big picture if aim bpr goes it will raise buttons , employer ni is the big earner for government if it goes up, they could also make a huge amount if they dropped the personal allowance down by a thousand pounds but hopefully the latter won't happen.
Don’t understand that article comment. Liontrust Asset Management (LON:LIO) don’t run any IHT portfolios but they do run a very diversified set of global and special situations range that would be more likely beneficiaries of IHT outflows from other specialists in that arena. So makes little sense.
Not that this makes much difference. Until the budget is over it is all speculation and the ridiculous information void this rather naive Chancellor has created is filled. I won’t be buying anything until after the budget, let alone differentiating around asset managers. That said I haven’t sold much either as I do think a lot of the unnecessary uncertainty has been somewhat priced in.
I would imagine David its cross over holdings in UK small companies funds they run as I take your point they aren't directly involved in bpr market.
Apologies in advance as there seems little company news to discuss today and my nudge yesterday was timely as seven more subscribers got their tickets....We nearly always have just under half the conference attended by Stockopedia subscribers and Paul and Graham enjoy mingling and chatting with everyone...these are great networking events and there are some excellent write ups post event....nothing beats being there though.
So...
There are just four WEEKS until Mello's 10 Year Anniversary Show on Tuesday 19th & Wednesday 20th November 2024! Come and join us at The Derby Conference Centre, 9am-7pm.
This unique venue, with it’s unique sunken exhibition space, has been voted the investor favourite venue so we listened and here it is..
.
We have created a two day investor conference that will include 12 top quality keynote speakers, 8 educational workshops and panel sessions, 40 exhibiting companies plus over 60 company presentations for investors to evaluate and understand their current or potential investments. Paul, Ed and the Stockopedia team should be there to meet and chat in a wonderful, friendly networking environment
A selection of attending companies includes Warpaint, Time Finance, The Property Franchise Group, Polar capital, Smiths News, Rockwood Strategic, Transense Technology, Filtronic, Manx Financial, Lightscience Technology, Image Scan, RTC Group and many more!
The featured keynote speakers include leading Technology fund manager Ben Rogoff and Peter Pereira Gray the ex head of Investments at the £30billion Wellcome Trust, and many more.
For more information, click here: https://melloevents.com/mello10tickets/
For HALF PRICE tickets use code 50OFFSTOCKO https://www.tickettailor.com/events/melloeventslimited/1376680
B.P. Marsh & Partners (LON:BPM) Seems a class act. Not much liquidity. Big spread. I hold.
Watches of Switzerland (LON:WOSG)
"Watches of Switzerland Group PLC on Wednesday faced a call from investor Gatemore Capital Management to move its primary listing to the US.
Gatemore expects the Leicester, England-based watch retailer to generate the majority of its future revenue from the US market, and believes the move necessary to "fully unlock the value of its stock".
The move would lead to the retailer's exit from the FTSE 250 index, even if it retained a secondary listing in London.
Gatemore in September said it owned 1.9 million shares in Watches of Switzerland, a 0.8% stake."
Cordel (LON:CRDL)'s approval by Network Rail is a major endorsement of the company's technology & solutions.
Outside the UK, it also provides them with greater credibility on an international stage, especially in the US, where the rail network needs a massive upgrade.
£TRCS are already punting their rail related software through an affiliated reseller in the US with some modest success so far, but its taken quite a while, so I wouldn't hold my breath for imminent US returns?
It doesn't seem to make sense that these relatively small firms in the transport systems market act independently rather than pooling some of their expertise in tendering for larger contracts
Anyone know why Mears (LON:MER) falling this morning?
Anyone know why Mears (LON:MER) falling this morning?
It could be something idiosyncratic. But many shares have been taken to the woodshed recently, almost certainly as a result of CGT planning. Alumasc (LON:ALU) is the latest. Yet their intrinsic value is unchanged and I’m seeing quality at good prices.
This article is certainly the reason; https://www.ft.com/content/27a...
Yes, indeed. No one comes out of this looking good.
The other consideration with Alumasc (LON:ALU) is that even after recent falls it remains nearly 100% up over the past 12 months. There's a lot of capital gain in there, for those who want to crystalise some. But as you say, the underlying value is unchanged.
And why is Primary Health Properties (LON:PHP) doing so badly - you would have thought with interest rates coming down and their focus on the Health sector being supported by government it would be doing so much better ?
Primary Health Properties (LON:PHP) - has been moving lower as have most interest sensitive stocks. This is likely because the 10-yr gilts have been moving up 0.5% in the opposite direction to the pivot in rates coming down - this is the interest rate that matters to such stocks. BBGI Global Infrastructure SA (LON:BBGI) has sold off as well to give a similar example.
There was an article in the FT about the government seeking to renegotiate or terminate asylum seekers housing contracts as the margins were excessive. I think Mears (LON:MER) hold some of these.
Probably just last minute Budget worries , since I recall Mears (LON:MER) has a significant exposure to maintaining affordable/social housing?
If Rachel Reeves was to say do something sub-optimal (eg nationalisation, heavy-handed price controls, etc) then suppliers to the sector would inevitably take a hit.
There is an article in the FT entitled "UK ministers explore using break clauses in asylum housing contracts"
It names both Mears (LON:MER) & Serco (LON:SRP) & I suspect explains todays fall
MearsMears (LON:MER) I hold and taking a hit! Can’t wait to hear this budget next Wednesday and move on!
Interesting announcement from Cordel (LON:CRDL) . I feel this stock is overlooked but now gaining momentum. In summary they have an AI platform (hear me out!) for surveying train lines for safety / maintenance needs. Cameras fitted to trains survey the lines in near real time. Now has live customers in UK, USA (Amtrak), Australia, Mexico etc etc. Revenue to grow 35%+ to exceed £4.4m this year. Loss making but to be cash flow positive in FY25 and large global market opportunity with sales across several geo’s already.
Interestingly they recently raised £1m in a placing from Rathbones to accelerate R&D and expand the use cases for their tech. This was raised at a 25% premium at Rathbones’ instigation as they like the company so much and wanted to increase their stake. Director felt they can accelerate application of the tech to other uses so agreed. They note in the placing announcement that 80% of the funds will go toward additional R&D headcount, so seems genuine.
Growing news flow of contract wins over the last year. Contracts seem to be multi-year and train co’s have to certify the tech for safety/effectiveness so if not a moat as such there are at least technical hurdles and an early mover advantage.
I rarely see something that I think it a multi-bagger with early momentum and low valuation but this looks like a possibility to me. I’ve taken a starter position and will do further research. Current market cap £12m, and was £30m when it traded 18p at its high in early 2021 (having adjusted for shares in issue at that time). Since then it’s made very significant progress and looks quite de-risked with strongly growing revenue, news flow and additional cash in hand, while expecting to be cash positive without the need for further dilution. A lot to like here IMO.
Cordel (LON:CRDL)Thanks for bringing this to our attention. But why is the gross margin so low? I normally expect to find all the operating numbers in the red for early stage companies, except for GM, which tends to be up at 70-80% for fast growing tech businesses. Here, the GM is negative. Can you elaborate please?
According to broker notes the gross margin for y/e24 is 64% estimated improving to 70% y/e 25 which seems reasonable. However company not yet profitable
Thank you. Sharepad hasn’t got a number for FY24. Although historical numbers are unimpressive.
Hi BnB, gross margins are strong. I think you’re looking at operating margin which is of course negative including all expenses. The company has been loss making to date with cash flow breakeven expected during FY25.
From the latest interims gross margin was ~70% in H123 falling to 50% in H124. The explanation for the decline is that FY24 has seen several new customers onboard (and corresponding 108% revenue growth) which increases the sale of lower margin hardware in year. However these then become higher margin software clients going forward.
‘The delivery of a LiDAR unit in Mexico and hardware units supporting our Angel partnership reduced our normal operating margin, but this is expected to balance out positively in the second half as software and Data-as-a-Service components are delivered for these projects.’
I think you’re looking at operating margin
No. Sharepad has gross margin negative from FY18 - FY22 as I wrote earlier. But looking at LSE/Refinitiv, I see numbers approximate to yours. So it’s a data feed issue. Thanks for coming back to me. Looks better in that light. Probably too small to safely build a meaningful position for the fund but I’ll enjoy monitoring progress for now. Thanks for highlighting it.
Where do you see a negative gross margin?
Where do you see a negative gross margin?
Sharepad : Negative from 2018 through to 2022, barely positive in FY23, nothing quoted for FY24
Maybe these guys should get together with Petards (LON:PEG) Petards (an even smaller company) who are also into security aimed at rail companies
Making money out of Petards (LON:PEG) proved to be Mission Impossible for me so it was recently ejected fom my kennel. Cordel (LON:CRDL) may also prove to be high maintenance so I will be avoiding.
I was looking for Cordel (LON:CRDL) just recently as i had forgotten its name and somehow remembered it and forgot where from (must have been scvr).Only found Petards (LON:PEG) and was kinda sure it wasn't that and gave up.
I agree it could be interesting if it saves railway companies money and can scale/starts scaling getting rolled out across networks.Big ifs though!But it has some big names approving its tech, although i'd be interested to know more about how much their product costs and recurring revenues.Will try my hand at some digging.
Has anyone else subscribed for the Applied Nutrition IPO that closes this morning? I have applied for some shares as this (and Raspberry Pi) are virtually the only quality floats of 2024. It's often worth looking at floats when they are few and far between. There are some high profile investors involved with Applied Nutrition, so it will be interesting to see what it does on opening. I may just sell it into strength for a quick profit, if the opportunity arises.
Another thought - has anyone noticed this.."The 10-year note yield is up 60 basis points in 1 month since the Fed began rate cuts. For the first time since July, the 10-year note yield has crossed above 4.20%. Bond markets are trading like inflation is back and the Fed is raising rates." Short rates are coming down long rates are going up. All rather odd!
Curiosity how Applied Nutrition has been able to post revenue/profit growth from 2022 to 2024, hotter than any high-tech/AI company; yet Science in Sport SIS has been an unmitigated financial disaster for losses (see the Stockreport) despite possibly being the UK market leader for energy gel and bar wrappers, ditched by runners/cyclists.
Another thought - has anyone noticed this
It’s being driven by concern over a potential Republican clean sweep which would feed inflation (tariffs, tax cuts), spike the dollar and widen the deficit. All of which steepen the long end.
Re American treasuries topvest, an FT article this morning says as the odds on Trump winning are shortening, his policies will do the opposite of what he wants, the dollar will strengthen as it is now, and inflation will go back up. Good luck with the IPO.
Why do you think it makes a good investment? It would appear to have grown very quickly ... guiding to low double digit ... if achieved, attractive, if they can maintain margins.
Just casting an eye over doc. I quite like the area... although it does seem surprisingly profitable, FCF not so great though which may cause alarm over longer term sustainability of gross margins. This would affect valuation which looks quite a bit higher than 7x gross profit... an industry metric for acquisitions.
Agree it would be a massive own goal for Numis to put out a dud.
I think the working capital cycle would be my main focus.
Apologies, last point... I wouldn't invest (yet). Not because I like or dislike it as an investment, it would just have to be so compelling for me to get involved as a private investor. Let's say Google compelling. Having spent 20 years on the buyside I know how out of the information loop we are and so for me personally, it's too hard, without all the colour institutions get, that we don't. This doesn't make to wrong and as I say, you would hope Numis Deutsch don't fluff this. Sadly though, they probably don't care. Even if it's a good one, someone will throw some dirt at in the next month or so and that would be a suitable time to take a view. Fingers crossed though because it's good for if UK market can thrive and a strong IPO market is part of that.
RDHowarth - I quite like it because it's founder led, has big name investors in the IPO, its cash generative, high growth, high ROCE, good brands, internationally expanding etc. Not cheap, but if its priced at 140p it should go to a premium on day 1.
Looks a bit like Supreme (LON:SUP), but without the vaping negativity. I like Supreme and have been in and out a few times.
Fair enough, best of luck. Our definitions of FCF generative are obviously different.... a 60s conversion ratio would be a worry for me not a strength. Im not sure about big names tbh .... the backers are selling and I haven't heard who is investing.
RDHowarth - thanks. JD Sports are selling down their strategic stake, along with the CEO, Thomas Ryder, but just down to 30% which is quite healthy. £25m taken-up in placing from these North West big hitters: Mohsin Issa (Asda), Tom Morris (Home Bargains), Peter Cowgill (ex JD Sports CEO) and one other I believe. Andy Bell from AJ Bell is the Chair. Agree the free cash flow is a tad weak, but probably explained by debtor and inventory build up as they expanded into other countries. Low capex model and net cash is attractive. Anyway, we will see how it does next week.
Tom Morris is a very shrewd businessman and heads up an impressive operation in Home Bargains. A pity that it is a private company.
I would be interested in any company where he has some influence.
Re Bond markets.... in a normal world, you would expect a premium for duration risk. The opposite of an inversion. 200bp spread between base rates and 30 year yields is pretty normal. 6 month yields have hardly moved on the cut. As you say longer term yields are rising but still remain fairly flat, only 33bp premium for the additional term. The policy shift moves from a disinflationary bias to an inflationary bias. Evidence for a slowing economy is there but far from conclusive. As the fed is easing the bias longer term is for more inflation. I wouldn't say inflation is back... but if it settles in a range 2-3% then you expect a bond yield range of 3-6% ....which we sit comfortably in. On the face of it, you would think rate cuts are good for bonds. In reality recession is good for bonds. Not enough evidence yet to persuade investors to sell equities and buy bonds. If anything the reverse, hence the somewhat counter intuitive move.
Bloomberg reports IPO likely to be priced at 140p. Not much appetite in this climate.
#AppliedNutrition
I have dipped my toe in the water so to speak, as you say some high profile investors, A Bell as Chairman, small position will see what happens, not a great fan of IPOs but this does look promising.
I hope Paul is OK?
I have had the same thought after yesterday's rather brutal market reaction to both Plexus Holdings (LON:POS) and Hunting (LON:HTG) both of which Paul holds, I believe.
Yes, he's ok :-)
G
Lots of CHEESE last night!