Small Cap Value Report (Wed 24 April 2019) - Mello 2019, ABDP, BOO, TAP, LGRS, FDEV

Good morning!
These are on my radar today.
- Ab Dynamics (LON:ABDP)
- Boohoo (LON:BOO)
- Taptica International (LON:TAP)
- Loungers IPO
- Frontier Developments (LON:FDEV)
Mello 2019
A quick plug for this event, where I'm sure many of us will meet again, and some of us will meet for the first time.
Some recent additions to the list of companies appearing at this event:
- Judges Scientific (LON:JDG)
- Character (LON:CCT)
- Angling Direct (LON:ANG)
- RA International (LON:RAI)
- Pelatro (LON:PTRO)
... along with other favourites such as Sosandar (LON:SOS), Duke Royalty (LON:DUKE) (where I have a long position), Zoo Digital (LON:ZOO), Beeks Financial Cloud (LON:BKS), Scientific Digital Imaging (LON:SDI), etc. Click here for the company list.
The speaker list isn't bad either!
I've been informed that there are 50% discounts available with the code EB50.
Ab Dynamics (LON:ABDP)
- Share price: £20.55 (+7.6%)
- No. of shares: 20 million
- Market cap: £405 million
Some remarkable H1 growth figures from this company, which provides "advanced automotive test and measurement equipment", focusing on safety and autonomy features.
It has boosted its manufacturing capacity over the past year or so, enabling a tremendous increase in revenues. Operational leverage means that profits are turbo-charged:
- Revenues +69% to £25.8 million
- adj. PBT +95% to £6.4 million
Despite this strong growth, the interim dividend increases by just 10%. The company has been pretty clear about its desire to invest to take advantage of the opportunities it enjoys at present, so I guess this is not a big surprise.
Indeed, the company says today that the adjusted operating margin in H2 2019 will be similar to the FY 2018 result, due to "planned investments in resources, overseas facilities and infrastructure". It has new facilities in Germany and the USA, and wants to commence operations in other key markets.
Net cash increases to £18.9 million.
Order book provides "full visibility for the remainder of FY 2019 and into FY 2020".
Management - some turbulence at the top, as the company has a new CEO and the CFO is leaving.
Gross margin - we have a reminder that financial accounts are often a matter of opinion, as a reclassification of costs sees gross margin boosted to 50% (versus 35.6% under the old method).
Outlook - positive.
The second half of the financial year has started positively, and our order book visibility gives the Board confidence in the outlook for ABD for the remainder of 2019 and beyond.
Overview
This is an interesting company for me to look at right now, given that I have been processing claims by a certain manufacturer that it will soon have autonomous vehicles.
ABD produces driverless robots used in the testing of Advanced Driver Assistance Systems (for example, systems which brake to avoid a collision, if the driver fails to do so). Driving robots accounted for more than half of ABD's revenues in H1. Other major contributors to revenue include soft targets and driving simulators.
Vehicle manufacturers who seem to be happy with ABD products include Toyota, GM, Ford, Mercedes and Chrysler.
It's hard to disagree with ABD's view that the surge in demand for driver-assistance and autonomous vehicle testing is a great environment in which it should continue to grow. I have no specific information in terms of whether or not it has a relationship with Waymo.
Here's an article published last month by ABD, "How close are we to fully autonomous cars?". The author writes:
In my opinion, we're not going to see full (level 5) automation by 2021, it will certainly take much longer than the media will have us believe. But there is such heavy investment in this technology that it could be sooner than we think.
Today's update repeats this view with the statement that "the drive towards full autonomy... is proving to be far more complex than has been speculated on and publicised in the media." ABD expects a prolonged period of testing for ADAS and autonomous systems.
My opinion
With compound annual growth in ADAS-related sales expected to be greater than 20% for the foreseeable future, ABD could very conceivably grow into its current valuation of c. £400 million.
It has partnered with an impressive range of blue-chip OEMs, who speak in glowing terms of its products.
So there is a lot to like here.
This is how Stockopedia sees it:
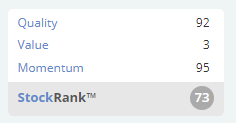
Quality is excellent - the company has achieved its growth without excessive capex and without taking on financial risk.
For example, spending on property, plant and equipment amounted to just £1.8 million in H1, versus £6.9 million in operating cash inflows (before tax and working capital movements). The balance sheet is strong.
So there is little doubt that it is outperforming the average business. Congratulations are due to the company itself and its shareholders, who are sitting on very impressive capital gains.
And the next few years are probably going to be excellent, too, with continued growth looking very likely.
But is it a buy-and-hold investment, with open-ended growth prospects, or will it run out of steam at some point, after the current wave of ADAS/autonomy testing is complete?
My problem is that I don't really understand what the end-market for ABD's products is going to look like in a few years. With a forecast earnings multiple in excess of 30x, I think the valuation does require a very good answer to this question.
To underline the point: revenue does not seem to be recurring in nature - visibility depends on the strength of the order book - and management's confidence in the future is based on its belief that autonomy/ADAS testing will be needed for "an extended time period". Maybe that period of time is 5 years, for example? After that, I wonder what might happen?
It's in my "too difficult" pile at the moment, but I hope it keeps going from strength to strength, for the benefit of shareholders.
Boohoo (LON:BOO)
- Share price: 229.8p (+6%)
- No. of shares: 1163 million
- Market cap: £2,673 million
This old favourite returns with strong results for FY February 2019, as many will have expected.
Revenue at £857 million (up 47% at constant FX) is ahead of the £843 million consensus forecast that is visible to me. Profitability measures all look strong, too.
Some highlights:
- excellent progress internationally (ex-UK sales up 64%).
- gross margin firm at 54.7%
Pretty Little Thing / Boohoo
I'm going to have to repeat myself and point out that the group seems to be driving forward very deliberately with PLT and potentially doing so at the expense of Boohoo.
Boohoo customer numbers are up by just 9% on the prior year to 7 million, while PLT customers are up 70% to 5 million.
Is it a coincidence that the Boohoo/PLT founding family still directly owns 33% of PLT? I would have my doubts about that.
Anecdotally, there has been a very prominent PLT poster advertisement outside my gym for several weeks, and I have noticed other PLT ads in public spaces where I have never seen a boohoo ad.
Because of the mismatched growth, "non-controlling interests" (i.e. minority shareholders in PLT) are entitled to 20% of the group's total profits for 2019, up from 12% in 2018:
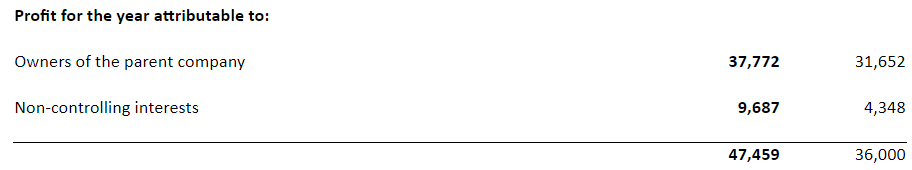
When you look at it this way, profits attributable to boohoo shareholders increased by just 19% in 2019, only half the growth rate in overall PBT.
To see the effect of the minority (or non-controlling) interests, you have to ignore most of the profitability numbers and instead focus on diluted EPS (up 19%).
Outlook - first few weeks of the new financial year are "encouraging". Long-term:
...we will continue to make investments across the group as part of our vision to lead the global fashion e-commerce market. Whilst this will require continued investments in people and infrastructure, we believe that the benefits of our multi-brand platform will continue to generate economies of scale, allowing us to target sales growth of 25% per annum, with an adjusted EBITDA margin of around 10% over the medium term.
My view
Overall, I have a positive impression of boohoo and its prospects - it's hard not to! It is still taking business away from the High Street, and should continue to do so.
However, it won't surprise any of you that I am currently priced out of this share (there is a reason why I was asked to help with the "Small Cap Value Report"!).
Specifically, I think that 19% diluted EPS growth is perhaps as good as it's going to get here in the short to medium-term (given how much of the growth is owned by the minority PLT shareholders), and therefore a forecast rolling P/E ratio of 44x (according to Stocko) looks difficult to justify, to me. The share price is more than 70x the EPS figure which has just been reported.
Taptica International (LON:TAP)
- Share price: 145p (-9%)
- No. of shares: 134.7 million
- Market cap: £195 million
Launch of Secondary Placing in Taptica
A large group of insiders are getting out of Taptica to the tune of 14.3 million shares, i.e. more than 10% of the company. An accelerated bookbuild is underway, so there should be news about the destination of shares soon.
It's yet more discomforting news for small shareholders who have seen the TAP share price dribble lower over the past 18 months.
Note that the forecast P/E ratio is allegedly just 5x. Why would all of these insiders want to sell at such a ludicrous valuation, with the company enjoying plenty of cash on the balance sheet and about to complete a "transformational" merger?
I have no interest in studying this, as it continues to stink badly.
Note that shareholder cash will probably end up being used to help the insiders offload, through the share buyback programme.
Loungers IPO
Placing and Proposed Admission to AIM
More details on the IPO by Loungers, with the publication of an admission document.
I don't have the time to read this document but I wouldn't be in a hurry to buy this anyway. The proposed enterprise value after admission (after outstanding debt has been repaid) is £212.5 million, or nearly £1.5 million per existing site. It currently has 146 venues.
Between 20 and 25 sites have been opened per year in the last few years, and the company is targeting another 25 p.a. in the medium term.
That sounds realistic for a couple of years maybe, but the potential it sees for 500 sites looks a bit far-fetched, given that:
1) the company will be in a net debt position after the IPO, so it would need a lot of consistent, internally-generated cash flow to fund all of those openings (or a lot of borrowing).
2) finding 350 new locations which are as attractive as the c. 150 they already have will not be straightforward.
As far as its competitive positioning goes, I've noted elsewhere that Loungers competes "with every element of the trade of a pub chain, coffee shop, or restaurant, whereas each of those operators only competes for a part of Loungers' sales" (the company's own words).
This doesn't sound like a strong competitive position to me. Indeed, it sounds more like a community centre than a money-making opportunity to me - community centres tend to be non-profit enterprises!
I'll watch this safely from the sidelines.
Frontier Developments (LON:FDEV)
- Share price: 1036p (+1%)
- No. of shares: 38.7 million
- Market cap: £401 million
People have been wondering what the next video game franchise from Frontier might be - now we have our answer.
It's called Planet Zoo - and here's the trailer. It looks fun! Maybe a bit like my old favourite Theme Park, except about 1000x more advanced.
Thanks everyone, that's all for today.
Graham
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

39 comments
For anyone following Boohoo (LON:BOO) I've noticed a material increase in instagram followers for both MissPap and Nastygal recently.
MissPap has gone from 1m ---> 2.4m in a matter of weeks
Nastygal had 1m followers in April ---> 3.8m today
There is clearly a big push taking place for these 2 brands at the moment.
No position, though I remain interested
the stink continues...
Taptica International Ltd (AIM: TAP), a global leader in advertising technologies for brand advertising and performance-based mobile marketing, has learned that Uber Technologies, Inc. filed a complaint in the Superior Court of the State of California (U.S.), County of San Francisco, against Taptica Ltd. and Taptica, Inc., four unaffiliated companies and numerous (up to a further 100 "John Doe") companies, alleging fraudulent concealment, negligence and unfair competition.
Based on the information available to the Company to date, the claims appear to be without merit; Taptica Ltd. and Taptica, Inc. will aggressively defend against these claims
We’ll see. Could just be Uber trying to use its muscle to beat down competitors. For example, Curb is one of the few taxi apps to compete well and it used Taptica International (LON:TAP) heavily for location and event based marketing. So, may be more positive proof than spooky counter proof.
Price has taken a dive as flux is high, investors are nervous and RhythmOne is being digested. Profit expectations are hard to fathom but being conservative they are probably a bit high as some tidying up at messy RhythmOne required (expect exceptional write down and costs of integration) but even then valuation looks very low implying something very bad is going to happen imminently....it might but unlikely this drive by Uber shooting is that.
I begin with the unorthodox view that concentrated portfolio is better than a diversified one. That is, those who have a deep understanding of both finance and markets should spend their time identifying a handful of truly excellent companies and buy them rather than scattering chips all over the investible world. With this is mind, AB Dynamics is such a candidate to be heavily concentrated in; It operates in a great new sector, has great management, and has outstanding financials (look at its latest report!). Moreover, it has hardly been discovered by the general public. No doubt, at nearly £22 per share, a great deal of good news has now been discounted but it is still a wonderful company with huge expansion plans. Tempted to sell here? Of course! Then again I have been similarly tempted throughout its journey from its IPO of around £1.00 in 2013. I dunno, maybe today marks the all time high print... but there's precious little evidence to support that emotional fear.
Although I have not been to a Loungers venue yet I did hear their MD talk a few years ago. The key takeaway was that the offer was designed to trade from secondary sites so they were not getting tied into high st rentals.
The locations, Newport, Chippenham, Staines, Epsom, Bury St Edmunds etc suggests that this has been working. There is still huge potential in those secondary towns. I was brought up around Daventry and Rugby, both pretty uninspiring places where price tends to determine success before quality. They could both do with a loungers.
It would also suggest they are well placed to expand into lots of vacated or empty sites in towns like that.. I think even if they continue to do well there will be far better opportunities to buy in further down the line.
I don’t think anyone knows exactly what is going on in Taptica but what I do know is that with the combination of the situation in Plus500, most people will be very cautious about investing in companies based in Israel. I still have a small position in Taptica in the hope that there is still some value remaining.
Taptica International (LON:TAP)
I do hold and am sitting on a nasty paper loss, which arose on the conviction (which has already been declared as a risk) of the now ex-CEO. I personally just cannot smell anything so bad as to cause the share price to drop 60% from its high. i.e. that this company is now worth 60% less than it was 16 months ago.
As far as I can tell the sellers today are outsiders?
Of course if everything (particularly the cash) is a tissue of lies then this will end up being my first zero.
purpleski, the cash seems real IMO
I sold a bit several weeks ago, partly due to price up decently on my buy and the RhythmOne merger adding opaqueness and probably some balance sheet cleaning to come. It was hard going to sell. Harder than it should be for a stock that isn't a tiddler and obviously has some interest on the buying side recently. I wonder now whether it was the ex insiders selling heavy.
Hi Mojo
Taptica International (LON:TAP)
Are you not concerned that the result of the placing has yet to be announced?
Phil
Yes I am concerned!
But then when I try to be rational through the noise (obviously a highly subjective and potentially flawed thing to do), I think I should still be there and not knee jerk away. I am assuming that during yesterday there was some price discovery and my judgement (obvs I mean guess but its not groundless) is that there are keen institutional buyer at prices above yesterday's price recently. The strategy of the group and now meaningful presence in US with blue-chip clients provides a considerable upside story, and the new CEO is reasonably impressive.
Waiting for imminent egg on my face ;)
Taptica International (LON:TAP)
For my sins I bought this at the current price a few months ago before the RhythmOne acquisition announced - yes there's stink but it seemed to me that there are real assets and capabilities. RhythmOne acquisition muddied water as its messy and less clearly productive assets. However, Taptica have a good record at acquiring assets and making them work hard and well.
My impression of the this acquisition process is that institutional investors saw value in Taptica and then viewed the acquisition favourably. Everyone with a decent position will understand that there will be a non cash earning write down coming from Taptica cleaning up some of RhythmOne's intangibles and goodwill.
Its all very disconcerting and visibility is low.
However, the news re placing clarifies why the price has been quite weak and assuming that pricing was active and meaningful today for the book being run by FinnCap (?) looks like 11% price fall is a decent win and there is demand for the stock (as was my perception).
The "insiders" selling are really now "outsiders" and in the case of the old CEO he has a need for money due to court judgement.
All squeaky bum time but as the mist clears I think there is somewhere from a bit to a lot of value here. New CEO seems good.
Boohoo (LON:BOO)
Great company. Very highly valued. A few points:
1) Very large pick up in accruals. Explained on call as relating to stock, new distribution relationships/terms and something else I've forgotten. But the move is £40m to £80m. This is meaningfully bigger than the rise in profit. Room for jiggery-pokery in there
2) PLT thing as people point out above is v cheeky
3) I felt like they were hinting that high revenue growth is over for PLT and Boo brands...without saying that Nasty Gal could take up the slack
4) In the UK they are now relatively big. There's not much space left for them to go. If they don't make it work in US then they are a lower growth company (they seem to be making it work decently there and just making the point).
5) How will the new CEO view things at PLT and the family connection? What disturbance could this cause for business and shareholders.
Impressive business but the rating is impressive too!
Mojo - on Taptica International (LON:TAP) I think you are pretty much spot on. The old insiders, who caused the stink, are now outsiders and moving on. Probably best!!
The RhythmOne (LON:RTHM) acquisition will need some tidy up. The buy back will continue to mop up loose stock.
I agree the new CEO looks decent and I think he is US based (is that correct?). Feels like this is moving more towards a US based/domiciled/centric business and away from previous Israel base.
I get why people steer clear though and I get why people think it is cash generative and good value despite the noise. Not for the faint of heart though!!
David, yes CEO's US based. The CFO is also moving to the US (now necessary given the US focus that has been created through RhythmOne and Tremor and will be focused on tidying up RhythmOne). Historically, Taptica accounting seems nice and clean and no expensing, hence the good cash to earnings compared to some software businesses.
The business is staying in Israel and listed UK for now (their words)...I can't remember exact reasoning why (might be in notes) but tax benefits mentioned and something about the ability to use losses against profit from some historic acquisitions (not very sure on this last bit as trying to dig out of memory and might be worth asking directly from them for the official line again).
Taptica International (LON:TAP) makes me as nervous as I am greedy. Its an uncomfortable combo. I often buy things with controversy on them and like to believe I have the understanding and mettle to ride the rough. TBH Taptica is hard to say have the understanding...I've got some good guesses but the RhythmOne acquisition is a curveball as is the general fast pace of developments in the area they operated in.
Historically they have shown the ability to find a gap they can exploit profitably and then push hard.
The best thing the new CEO said at the investor meetings was how he would be using cost cuts from merger to generate cash for investment product promotion. That makes a lot of sense. Its the type of business you can't stand still. He criticised RhythmOne management for targeting EBITDA number rather than maximising growth
Paul,
I recollect the PLT problem was flagged up at the time as there was a need to incentivise the minority holders as otherwise there was a risk that they would simply take PLT away. , Right? I have the impression you do not think that BOO will ever have the growth potential of ASOS, which seems surprising to me.
There were other ways of incentivising the PLT sellers which didn't involve giving away a third of the fastest growing brand in exchange for peanuts. In hindsight (and perhaps even at the time), that arrangement represented a colossal destruction of value for shareholders, which sticks in the craw somewhat given the 'related party' nature of that transaction.
Graham has done a quite rational analysis in calculating how much of the Boohoo (LON:BOO) growth is attributable to share holders, after stripping out the PLT minority interests.
Then it's a simple case of figuring out if the valuation is reasonable when considering the growth in shareholder EPS. Whilst the growth story looks very solid, I would also suggest the PEG is rather high once we strip out minority interests. So I wouldn't pay up this much for the growth.
Incidentally, I have also noticed PLT advertising much more than Boohoo advertising. (Charlie Munger would call it the power of incentives)
Also, from the webcast this morning, it seems a lot of the growth potential is overseas and the distribution costs are increasing as a result of this. One would think there could be some hard Brexit risk in there too, for EU sales.
Hot off the press a bid of 97p has come in for KCOM (LON:KCOM).
Yes, good news on KCOM on my coming home from lunch! Follows on the heels of MANX in which I also had a significant holding. I have no other telecoms. Anyone know which is likely to be next!
Afternoon Graham,
I wonder if you've seen the announcement from Frontier Developments (LON:FDEV) ? Planet Zoo has been announced, and looks fantastic. I wonder, should the game be a hit, if the company might bring in people to convert to tablet and/or console?
A great looking trailer.
Thanks,
IG
NB - I hold a long position in Frontier Developments (LON:FDEV)
I had a look at this announcement from Frontier Developments (LON:FDEV) and the Planet Zoo trailer.... and then the trailer for Planet Coaster too. I don't know much about computer/video games, but to me Planet Zoo doesn't look like a huge money spinner, at least in the short term, as (1) it's only being released on PC (do many people play games on PC versus PS or Nintendo?), (2) it doesn't look as fun on the face of it as Planet Coaster, and (3) it doesn't seem that new a concept overall. The graphics of both Planet games look great though.
But what do I know....
Re Frontier Developments (LON:FDEV) I agree the Planet Zoo trailer looks good. It also looks pretty processor and graphics intensive, so rather than try to port it to run directly on mobile devices I think it's a great candidate for running on streaming gaming services like Google's recently announced Stadia.
Tencent's strategic holding may complicate that, but I expect they are working on their own offering.
It fits with a current theme of mine which is looking to buy into providers of the content that the ever expanding streaming services will need, so I may get back on board.
Re Frontier Developments (LON:FDEV)
It's a nice enough trailer but I wouldn't expect it to transform earnings. I expect it will sell 'fine', though it might be a bit soon after their Jurassic Park game (the fundamental gameplay is going to be pretty similar). Maybe it's been cheap and quick to make as it may share a lot of the same code? I'd also point to the lack of success of other zoo management games in the past (e.g. Zoo Tycoon). Regarding the graphics, note the text at the bottom of the video 'pre rendered footage' - the game is unlikely to look like this while you're actually playing it. I work in the games industry, and 'pre-rendered' usually involves taking the most high fidelity versions of our art assets and making a film with them, at a cost of seconds/minutes/hours per frame, as opposed to the 16.6/33ms you need to do it in to make a game.
Wish you all the best, but this one doesn't excite me. Happy to be proven wrong though.
https://www.cnbc.com/2019/04/02/tencent-start-cloud-gaming-platform-test.html
Hi IG, I agree - the trailer looks very attractive! (this is not a comment on the game's chances of commercial success or the valuation of FDEV - I subjectively enjoyed the trailer, that's all!!)
Graham
Thanks for the detailed write-up on Ab Dynamics (LON:ABDP) .
I agree that true Level 5 AVs won't be available any time soon (if ever) but ADAS may keep ABDP shareholders happy for many years because AV software will need frequent updating for the foreseeable fulture and I would expect that ABDP's products will form part of the assurance process for their existing customers. I'm not clear how much they can increase market share or how much their target market will grow - and I'd welcome insights from any Stocko subscriber who has insight in this area.
Mi-Pay (LON:MPAY) reported today that it has reduced losses from 1.5p/share to 0.5p/share, extended contract with major clients, successfully launched a new service, slightly increased revenues and gross profits, and increased cash balances (mostly client money). The balance sheet looks acceptable, with no intangibles.
Mi-Pay is a highly speculative micro-cap but it looks as though the balance of risk and opportunity has shifted towards opportunity in the past year. I have taken a small position.
WANdisco (LON:WAND) reports lower sales and increased losses but director confidence. It was a "momentum trap" before these results - will it be a "sucker stock" tomprrow?
I haven't really looked at Loungers (and probably won't as I generally have little interest in IPOs) nor have I seen any of their venues.
However from reading some of the comments here, it sounds as though they are seeking to be somewhat "mid-range". I would just observe that this has been an uncomfortable place for consumer facing businesses to be in the last few years. That would certainly make me cautious without seeing them develop a solid track record of success.
I like the Loungers format. It allows them to trade all day and into the evening as a coffee bar / restaurant / bar. It's family friendly and the food is decent. The branding is consistent but the individual Lounge names include local detail.
My worries would be:
What rents have they signed up to?
They plan to expand from 146 sites (with 38 more in the pipeline) to potentially more than 500. The fifth hundred sites aren't going to be as good as the first hundred, are they?
Staffing. Assuming the B word happens, where are they going to get staff that provide a decent service, and at what cost? I've been eating out in the South East and in Edinburgh recently and it's been noticeable that the staff that know what they are doing, the ones that scan the room and catch your eye as opposed to hiding from it, well on the whole they don't have local accents.
I see that Loungers that was commented on by Paul recently will IPO at 200p on 29 April. No sure where this is in the prospective price range, but I suspect that it is on the expensive side. Perhaps Paul has a view.
It's always expensive when things float.
The concept seems decent to me. Visited one in Cardiff, and my own impression is that it sits between many categories - not quite a bar, not quite a restaurant, not quite budget, but not quite high-end either.
The type of footprint they have (entrance at street level only, restaurant on upper floors) seems very suitable for many high streets which will have large units going empty, with few tenants being able to utilise more than one floor of a big building.
Which gives it a great position IMO, on a high street itself the only visible competition for food might be coffee shops, fast food, or food courts in shopping malls.
I do suspect that the accounts might have been buffed up a bit for the market and there might be a better entry point down the line.
Interesting comment from Snoo on Loungers liking the format of street level entrance but upstairs provision of services. Outside London that generally doesn't turn out too well... Which reinforces a previous comment that they are aiming high with a target of 500 outlets.
Will have to try hard on the promotional front to get people up the stairs. Most popular mid-market offerings tend to do best when near the competition and all visible. Flow over from one to another, if they are any good, then makes up a useful proportion of trade. Difficult to see upstairs. Just a view.
Boohoo (LON:BOO)
Results look good but I couldn't help but notice that whilst statutory profits have risen 32%, the increase to the "owners of the parent company" is only 19% due to the explosive growth of PYT and the family minority interest therein. Think this will become more and more of an issue.
Phil
Yes the EPS was disappointing, not sure how the market will react.
I've only had a brief look this morning and, whilst I agree with your comments that Boohoo (LON:BOO)'s focus on PLT might be cause for concern (revenues almost doubled YOY), it's worth noting that NastyGal revenues also grew close to 100%.
Perhaps the company is happy to let the first Boohoo brand sail through now at a more pedestrian 15-20% annual growth, whilst simultaneously rapidly expanding every other brand they own, whether they are family owned or not.
On a similar note, I noticed a mention of the acquisition of MissPap last month by Boohoo (LON:BOO) , for which no RNS was issued - is this normal practice?
Personally as a holder, I'm excited by the prospect of the company buying up brands and turning them into giants - this is a far better strategy than relying on a handful of brands and the hope that they might last forever.
A
Morning Graham.
OK, I know it's not "small" but a lot of us have been in Boohoo (LON:BOO) for a long time and have, for better or worse, become quite attached to it.
Looks like a slight beat on expectations today but I kind of expect the market to have hoped for more. Would welcome any thought you have on the ongoing story if you have a mind, and time. Maybe Paul is lurking in the background and would care to share his thoughts?
For those interested, a live webcast of results presentation available from 9.30am and recorded version from midday at https://webcasting.buchanan.uk...
My morning smallcap tweet:
Westminster (LON:WSG), Vela Technologies (LON:VELA), Taptica International (LON:TAP), IXICO (LON:IXI)
Westminster Group (WSG) wins $3.48m container screening contract over 2 years. Rev largely in 2019.
Vela Technologies (VELA) placng at 0.1p, a 44% discount. And to sweeten the deal, buyers get 1/4 warrants at 0.15p. As if the discount isn't enough.
Taptica (TAP) founders inc ex CEO place 11% of co. Clearing overhang may help SP. I hold.
IXICO (IXI) wins £2m imaging services contract to support a phase study in Huntington's Disease over 7 years plus a smaller contract.
Superb interim results from Ab Dynamics (LON:ABDP) this morning. Broker forecasts were improved following the trading statement four weeks ago, but today's figures are still a significant beat. I expect further upgrades to ensue.
It's not a cheap share, but it is very high quality and still has very encouraging prospects.