Small Cap Value Report (Wed 24 Feb 2021) - VLX, BOTB, TOWN, ANG

Good morning, it’s Paul & Jack with the SCVR for Wednesday.
Agenda -
Volex (LON:VLX) - possible buying opportunity on spike down?
Best Of The Best (LON:BOTB) - another strong trading update. Takeover bids have been ended. Finncap upgrades profit forecast by 79%!
Angling Direct (LON:ANG) - year end trading update, and a mild profit warning for H1 for known reasons. Potentially interesting growth company.
Town Centre Securities (LON:TOWN) - resilient property portfolio trading at a discount to net tangible assets (this section from Jack)
.
Small Caps - price volatility
We’ve been having some interesting discussions here this week about the impact of IG’s decision to abruptly withdraw from offering about 900 leveraged products, mostly small caps. The reason is that they’re not making enough money offering these products, so are ditching them in order to focus on higher margin things. The problem apparently is that people like me sit on spread bets for small caps for long periods, often years, which ties up IG’s capital, for a paltry return (just a small profit margin on the funding charges).
Fair enough I suppose, it’s up to IG to decide which products they offer.
What I think is terrible, is how they’ve handled it, giving people only a week to stump up 100% margin by this Friday, on affected shares, then closing those positions anyway on Monday. Or you can buy out the share and put them in an IG owned shares account.
It’s terrible customer service, and they seem to think they’re too big and important to bother about what customers want or need.
It seems to be business as usual at Spreadex, who specialise in small caps, and hence I think a lot of people will be moving their business to Spreadex. I've done business with Spreadex for many years, and they've always been very fair, and supportive to me.
NB. I should emphasise that using leverage is extremely dangerous, and only suitable for experienced investors who know what they’re doing, and understand how to keep the gearing under control. Inexperienced punters should avoid spread betting at all costs in my view - it’s pretty much inevitable you’ll lose most, or all of your money. Probably quite quickly. I'm speaking from experience here!
Having a more general chat with my broker yesterday, he told me that market makers have been swamped with volume lately, and at times are turning off their RSPs (a system for quick & improved prices, for smaller trades in small caps). This is causing backlogs in getting deals done. When I placed an order with my usual telephone broker yesterday, he replied “I’ll try, but they’re not picking up the phones at the moment” (meaning the market makers).
So there’s definitely something funny going on at the moment, with the system seemingly struggling to cope with volumes, and large numbers of new accounts - I’m told that IG were seeing 6,000 new customer accounts being opened every day in February so far.
At some point recently, the stock market seems to have turned into a giant casino, with lots of new entrants punting on anything, and not necessarily understanding the fundamentals at all. Obviously that's happened in a much bigger way in the USA, with all this Reddit, Gamestop nonsense. There's nothing plucky or praiseworthy about anyone manipulating share prices, and they're breaking the whole system, causing brokers to withdraw products for more serious people like us. Maybe it's (at least partly) because sports betting isn't available as much at the moment?
It all sounds very much like top of the bull market stuff, just like 1999 actually. Everybody keeps making tons of money, until it all goes horribly wrong, sooner or later. I’ve no idea when that point is likely to happen, nobody knows. Maybe not for a while though, these things can run & run.
What I’m getting round to saying, is that we are seeing some peculiar price volatility, which might provide some good opportunities. Talking of which...
Volex (LON:VLX)
(I hold)
305p (down 5% yesterday, more intra-day) - mkt cap £464m
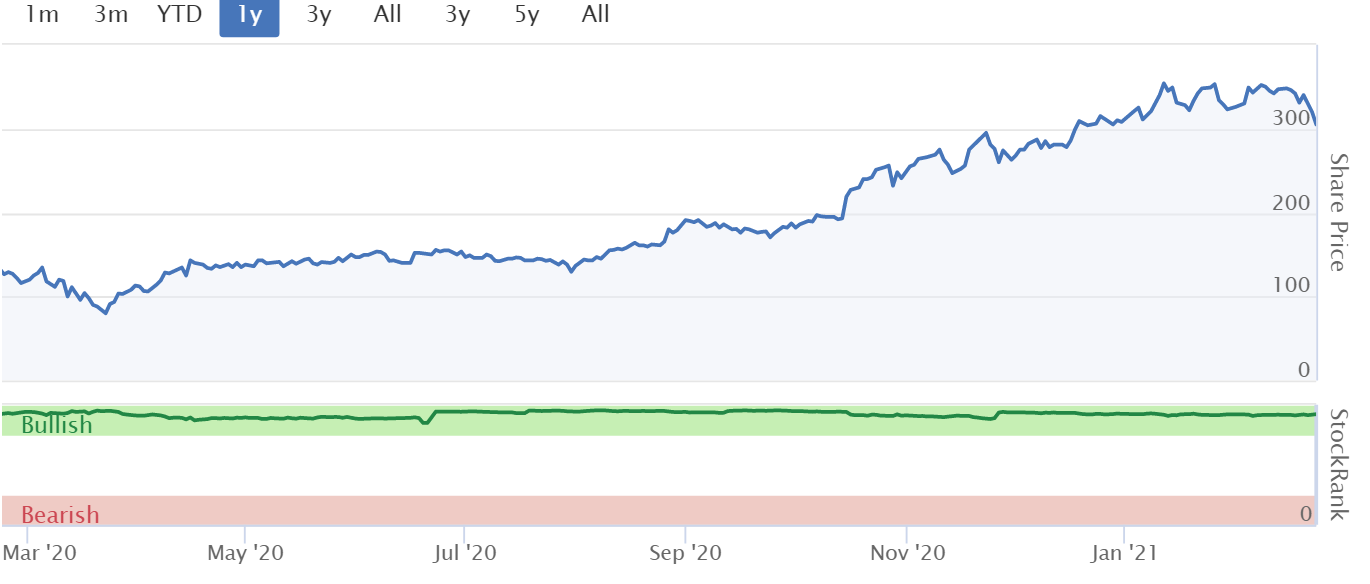
One share which caught my eye yesterday, is my 3rd largest portfolio holding, Volex . The fundamentals of the group are tremendous I reckon, with strong growth, combined with modestly priced acquisitions, meaning that the forward PER is only in the mid to high teens, despite the share price having been very strong in 2020. The share price may have tripled in the last year, but I think the fundamentals have fully justified this. It's not just soared to a bonkers PER like so many other things.
.
Despite this, in recent days, the share price suddenly plunged from where it looked stable at c.350p, to an intra-day low yesterday of about 280p. It just went into freefall. There wasn’t any news from the company, and it wasn’t on IG’s list of shares being removed from their system. For whatever reason, somebody was dumping Volex shares very aggressively, and it looked like panic selling to me. So I started buying, as I’m confident the company is a very good long term investment, hence I want to buy the dips, especially if someone is giving me the chance to buy 20% cheaper than a few days ago (when it wasn’t expensive to start with). If there's some temporary bad news, it doesn't matter to me, I'll ride it out, and buy more again.
The only reason I could find for the share price plunge, is that raw material copper price has shot up in price recently on world markets. Maybe this has spooked some investors in Volex into selling? Then I remembered something from the interim results webinar, which is still available here on InvestorMeetCompany, which talked about how the company hedges its copper exposure. So I’ve listened back to it, and jotted it down. This is what was said (in Nov 2020) - starts at 33m50s in the recording.
Question - How does the forecast increase in copper prices impact on margins? To what extent can you use pricing power to pass on those cost increases to customers?
Answer (Jon Boaden, CFO) - H1 (Apr-Sept 2020) benefited from lower copper prices. We had budgeted for $6k per tonne, but it fell as low as $5k in Q1.
We do hedge some (not all) of our copper exposure.
We also pass on a lot of our copper exposure to our customers.
Most customers have contracts that will re-price either quarterly or annually.
In a relatively stable market, this isolates us from most of the risk re copper, without being too onerous for our customers.
When the copper price is moving very significantly, with lots of volatility, that does mean we’re left with some risk.
In H1 we had risk of $0.3m to $0.4m, with quite large copper price movements.
We’re predicting high global demand for copper, and there are still some supply restrictions, especially in parts of The Americas.
So we’re expecting the copper price to be higher in H2, which will impact margins, but it’s quite hard to quantify, because it depends where prices settle.
[Source: InvestorMeetCompany presentation, 12 Nov 2020, from 33m50s]
I also remember that the CEO indicated some time previously that Volex can pass on copper price rises to its customers, but with a time lag. Hence it seems that the large rise in the copper price would hurt Volex’s margins only temporarily.
My opinion - this looks like it might possibly be an interesting opportunity. Volex has bounced a bit, and settled at about 305p. Broker consensus is for 20.9c in FY 03/2021 and 25.6c in FY 03/2022 (driven by the big recent acquisition kicking in for a full year). That’s sterling equivalent of 14.9p EPS and 18.3p. So at 305p per share, the PER is 20.5 and 16.7 - to my mind that’s attractive value for a business which is on a very good upward trajectory for earnings, is cash generative, and has a strong balance sheet. Plus there are 3 more acquisitions in the pipeline we’re told on the webinar, with management emphasising they don’t overpay for any acquisitions.
Another possible issue is that Volex provides the charging cables for Tesla cars. Hence the share price of Tesla taking a recent knock might impact sentiment re Volex? That would be completely irrational though, because Tesla's share price doesn't impact its purchases of charging cables at all! Also the thing investors like about Volex is the likely proliferation of electric vehicles with many other manufacturers, meaning Volex has a rapidly growing, potentially huge growth market in front of it.
I could be wrong, as it’s always educated guesswork with shares, but it seems to me the sudden spike down in Volex is probably more of an opportunity than a threat. Crucially, higher copper prices were already planned for, partially hedged, and the residual impact can be passed on to clients with a time lag under existing contracts. Therefore it really shouldn't be a problem at all for longer term investors. It might spook some short term traders though.
Therefore, even if H2 figures do disappoint, it doesn’t really matter because everything seems to be in place to recoup any lost profits from customer price increases.
I'm interested to hear what readers think, so as always please do add a comment if you have a view on this.
.
Best Of The Best (LON:BOTB)
(I hold)
2450p (pre market open) - mkt cap £230m
Trading Update & Conclusion of Formal Sale Process
Best of the Best plc, (LSE: BOTB), the provider of online competitions to win cars and other prizes, is today pleased to provide an update to shareholders on the continuing strength of trading through the third quarter of the financial year ….
Trading update - Strong trading continues, following staggeringly good interim results which showed H1 PBT of £6.8m (up 393% on £1.38m in H1 LY). It made 59.8p EPS in H1. Therefore the existing forecast for FY 04/2021 of 69.8p looked far too low.
Finncap has this morning upped profit forecast by 79% to £14.0m for FY 04/2021, or 125.2p EPS. That shouldn’t surprise anyone who was paying attention to the RNSs! It implies no incremental profit growth from H1 to H2, so could still be beaten. The company does tend to hold something back.
This means that BOTB must have one of the strongest trajectories of profit growth of any company on the market right now. Yet the PER is only 19.6 times the upwardly revised (and probably still cautious) forecast for this year.
The only question is how much lockdowns have boosted business, which is entirely online these days (no airport sites remain)? This management comment suggests that they don’t see strong trading as a one-off -
The Board is confident in the Group's position and outlook for strong, sustained returns….it remains on track to outperform its previous management expectations driven by the traction of the pure online model and increased confidence in marketing investment.
Strong trading and ongoing efficient cash conversion are reflected in the Group's increased cash balances which remain in excess of £10 million following the payment of the special dividend totalling £3.75 million on 5th February 2021.
Takeover bids - these are off, no great surprise there, as the process had dragged on for so long, there can’t have been many people who expected a bid approach to turn into an actual bid. Also, with performance so strong, why would we want to sell out? I’d rather the company remain independent.
I wish the company had given some indication of what price level the possible bids had been at. This is not stated in today’s update.
My opinion - I’m hoping for a spike down in price today, because (as mentioned before here) I want to buy more BOTB shares. There’s also the issue of it being on IG’s list of stocks that it is ceasing to provide spread bets on, on Monday coming. So I’m in the unusual position of hoping for a sharp spike down in the price of one of my holdings today! I won’t be the only one trying to buy, I suspect.
.
Angling Direct (LON:ANG)
74.5p (down c.6%, at 13:26) - mkt cap £57m
Here are my notes from the last trading update on 21 Dec 2020. This guided us towards >£3.8m EBITDA (equivalent to 2.8p adj EPS) for FY 01/2021. The balance sheet is very good at this share, so I’m starting off this latest section with a mildly positive overall opinion.
Trading Update today -
Angling Direct plc (AIM: ANG), the leading omni-channel specialist fishing tackle and equipment retailer, provides the following update in relation to trading for the financial year ended 31 January 2021 ("FY21"), ahead of announcing its Final Results on 11 May 2021.
- Revenues of £67.6m for FY 01/2021 (up 27% on LY despite lockdown disruption of intermittent store closures)
- Online revenues are 52% of the total at £35.3m (up 40% on LY)
- Stores LFL sales (a key metric) were only down 8%, which I think is good considering 30% of the time was impacted by lockdowns.
- Operational improvements are explained.
Overall -
As a result of these actions and the strong trading performance in line with recently upgraded market expectations, the Board expects to report a pre IFRS-16 EBITDA of at least £3.8m for the year, a significant improvement on the prior year (FY20: pre IFRS-16 EBITDA loss of £0.5m).
That’s the same EBITDA figure as mentioned above, from the 21 Dec 2020 update. It’s a little dressed up, to sound more positive than it is, so important to emphasise this is in line with expectations.
Cash position - at year end is strong: £15.0m. I’d want to see the full balance sheet, and see if there’s been any creditor stretch.
Current trading & outlook -
Lockdowns still in place, as we know, but I see this as temporary so can be looked through.
Logistics - post-Brexit, and Far East supply disruption mentioned.
H1 profit warning, but not quantified -
Notwithstanding the current abnormal trading conditions which will impact the first half….
No guidance provided for FY 01/2022 at this stage.
My opinion - this is a bit of a mixed bag. There shouldn’t be any surprises about logistics disruption, that’s a widespread problem currently, and lockdowns are hopefully just temporary. Overall then I see this update as being neutral.
Many thanks to Matthew McEachran of N+1 Singer, for publishing today a research note with forecasts for FY 01/2022 and next year. The numbers look quite cautious, with EPS of only 1.8p and 2.1p, so I imagine there might be upside on those, if as we hope, covid is finally sorted out this year through vaccinations. On the downside, we have to remember that in the future businesses probably won’t have the support of furlough or business rates support, and possibly higher corporation tax too, which means that revenues & margins will need to rise a lot just to stand still on profits.
Overall, at £57m market cap, with plenty of cash on the balance sheet, I think ANG shares look quite good. I like the split of sales, half physical stores, half online. Also it has some European online sales too, which might be tricky in terms of fulfilment at the moment. There isn’t much profitability at the moment, but that’s normal for smaller, growing companies. Once better scale has been achieved, then profit margins can rise, as things like online marketing spend deliver better results at a lower % of sales. That has been successfully achieved by Gear4music Holdings (LON:G4M) (I hold) for example.
Note below how over 3 years, the StockRank seems to have decisively moved from low rank, to high rank, which seems to be the Stockopedia computers signalling to us that this has moved from a bit of a punt, to a proper business with potential.
I’ll take a look at the next set of numbers, when they’re published, but am broadly positive on this share at the moment.
.

Jack's section
Town Centre Securities (LON:TOWN)
Share price: 110.35p (+0.32%)
Shares in issue: 53,162,000
Market cap: £58.7m
Here’s an off-the-radar stock: Town Centre Securities (LON:TOWN) . It develops properties and runs car parks in Leeds, Manchester, Scotland, and London. It focuses on mixed use developments close to transport hubs in these areas.
With all this talk of reopening economies, this company continues to languish. Net asset value is quoted at around £150m but the group’s market cap is closer to £60m.

It’s a family business, run by the Ziffs. Head over to Major Shareholders and you’ll see the name pop up a few times.
The chairman and CEO is Edward Ziff. He’s been at the company since 1981, on the board since 1985, and CEO since 2001. Ben Ziff is the managing director of CitiPark. He joined TOWN in 2008 and was appointed to the board in 2015. Then you have Michael Ziff as a non-executive director. So this is certainly a dynamic to be aware of.
There’s long-term vision here, although that can sometimes translate into an overly cautious approach for those hoping for substantial capital gains. Nevertheless, value is on display. The group trades at a substantial discount to net tangible assets and free cash flow is resilient.

Stockopedia classifies it as a Value Trap, lacking in Quality and Momentum. But, then again, it qualifies for the Momentum-focused Bold Earnings Revisions Screen and brokers have it as a Buy to Strong Buy.
Highlights:
- Portfolio valuation down 0.8% from June 2020
- Statutory net assets of £152.0m or 286p per share down 2.3%
- EPRA (European Public Real Estate Association) Earnings before tax of £0.2m (HY20: £4.1m), driven by an estimated £3.2m COVID-19 impact. £2.3m of this comes from lost car parking income and fixed costs.
- Statutory loss before tax of £3.5m (HY20: loss of £0.2m) and statutory loss per share of 6.6p (HY20: loss of 0.4p), including an unrealised £2.5m portfolio valuation and impairment movement
TOWN has been selling assets to reduce its debt level. £41.2m of targeted retail asset sales during the first half has reduced absolute borrowing levels 20% to £147.6m at December 2020. Loan to value has come down from 53.2% to 48.6% as at 31 December 2020. The group is paying an interim dividend of 1.75p, although this is down from 3.25p.
Rent receipts ‘remain robust’ but have come down slightly, from 89% to 87%.
Conclusion
Tricky conditions, but TOWN has managed to sell the assets it wants to sell at close to June 2020 valuations. That bodes well for the remaining portfolio, which is presumably of higher quality.
Meanwhile, the group’s pipeline has an estimated gross development value (GDV) of over £600m and ‘is a valuable and strategic point of difference for TCS’.
The chairman and CEO comments:
Overall, we remain committed to delivering on our accelerated four pillar strategy of: actively managing our assets, maximising available capital, investing in our development pipeline and acquiring and improving investment assets to diversify our portfolio.
So it could be worth investigating for those looking towards a recovering economy. You might need to be patient though. TOWN has a resilient and diversified portfolio of property assets, is prudently run, and looks to have a significant development pipeline.
Shares are now 110p and as recently as 2019 the group was paying out 10p in total dividends. These payments are forecast to recover.

Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

133 comments
I'm not sure I find it easy to distinguish between serious, even professional gamblers and frivolous, amateur "Johnny-come-lately" gamblers, particularly if the newbies have taken the pot by simply playing within the rules. I suppose it must be like losing at poker to someone who doesn't even know they are supposed to be the fish. I'll get me hat.
Here are my SCVR heat maps for today (prices as at ~9:00am).
Again, there is a lot of going on today so my apologies to those of you who don't like large heatmaps.
Small Caps with RNS news today ("N!!" in bottom row of the heatmap tile means report / update today):
Big movers today in the SCVR world (moving more than a 20d EMA of the ATR against either yesterdays close, or today's open):
Warm regards, and best of luck!
greensiax
PS: See my main heat map thread for more (non-SCVR specific) heat maps, and keys to the heat maps contents
You're thoughts on volex are the same as mine (also got a decent holding). Drop was due to general tech sell off and Tesla sell off (which doesn't affect volex, as volex is not only exposed to Tesla). I didn't add more on the drop off as I've been buying elsewhere, bit still remain long and strong in volex.
yes how could it be anything other than Tesla related?
Volex (I hold) & hopeful on prospects
What are folks views regarding how Governments will actually roll out the EV market. I’m living inner city if we all owned EV’s as we are told we will soon have too how does that translate to the infrastructure on our doorstep. I can hardly imagine space for enough charge stations they’re quite bulky plus space is a premium where you park one day you won’t be able to the next day etc. Once your in that charge spot then you block someone else from using even if the charge is finished.
Then there are what tech future has re solid state battery technology that not only powers longer but also charges fast so less requirement to recharge. That conjures up the picture of supercharge stations the main thing being that you charge when you’d normally be parked up. The weekly trip to the supermarket that sort of thing, large service station on the motorway when you’re ready for break etc.
The other consideration with driverless cars will we have more hourly hire type activity. Car drives to your door, picks you up you do your task and drives away and back eventually to base station. That’s less direct car ownership I for 1 have a second car hardly ever used that would work for me for 1 vehicle replacement but I’d not go to Hertz for the sort of task as that’s far too inconvenient.
Then there’s the folk on longer daily commutes, perhaps less of that post Covid and tech permits more work from home so some random charge points. Folk with their own garage / car space and are lucky enough to be able to have there own charge station - speed of charge less of an issue price of charger more likely to be a big consideration.
Putting all of these together they’ll all need products the likes of which Volex can supply but will it be Volex. A concern I guess would be that the market has such big potential will battery tech IP tighten up how and who can provide the charge? Volex becomes a 3rd party and inferior charge as battery companies determine how best to supply the power to their own product?
The key I guess is how in all of this mix does Volex add value to each aspect / end market. This has a lot of scale in my view but the journey could be bumpy. Possibly as governments set such a fast roll out of EV that’s in Volex’s favour being in the market early days?
I hold Volex (LON:VLX) and my answer to your question is probably not very Volex (LON:VLX) friendly.
I would suspect battery technology will get better and smaller, think mobile phones 1980s. If that is the case, for those who cannot charge from home, you will drive to a battery station and just swap out your battery and be on your way within minutes. Makes the journey from London to Edinburgh less stressful, not having to worry about running out.
Now if only we knew if I was correct and who is going to make these battery stations, we could be onto a winner.
Yeah Quantumscape exploded late last year with this solid state tech. It charges fast enough that I think you'd keep the same battery rather than switch out and who's going to want to switch it just doesn't add up all the extra manual handling. My take I guess is once that technology is developed is there also technology in how the power must be supplied to the battery to get the optimum out of the charge or possibly I'm over thinking it?
Not sure if this idea is a goer... The battery is the most important and expensive part of an EV. Why would you want to swap yours for someone else's which is an unknown quantity. Also I believe everyone will charge from home or at a parking site, so the need for "petrol" stations will diminish considerably, as you will get your 'petrol' at home.
I agree there will be a lot of innovation in the EV market over the next decade thou
How will the Govt. tax EVs? Because they are going to lose a huge amount of tax as people switch from petrol/diesel cars.
Re Volex future, NIO already offer Battery-as-a-Service https://www.caranddriver.com/n...
In many ways, China is leapfrogging the West. Xpeng don't offer BaaS but claim to have > 400 mile range. I think with hindsight the established autos missed a trick in not collaborating on a standard range of replaceable batteries a decade ago. Eg that would be wheeled out on a smart trolley jack and lifted into the car - but I'm not an engineer. Suspect it's unlikely to happen at this late stage but would have been an opportunity for VAG for example to go-it-alone over their entire range of brands. I think the answer is that different types of EV will evolve as optimum solutions for different territories.
As for Tesla's long-game, I thought TaaS was their objective for cities once autonomous is here. Just summon the closest driverless vehicle when you want a trip. Arguably huge environmental benefits once the vast capital/infrastructure of a vehicle is spread over dozens of users as so many cars spend 90+% of their time depreciating on driveways.
As with so many things, if we were developing transportation systems from scratch we wouldn't start from here!
Paul
I have a professional account with IG and the email to me says " Please close leveraged positions on affected share markets by 29 March" so might be worth re-checking.
Irritatingly I had to close one of my larger holdings Tremor International (LON:TRMR) and re-open in a share account, which meant that even though I tried to manage it on exchange still got hit with a 7p spread. Basically IG cost me 1.5% of my holding on a whim. I am mightily pi**ed especially as I now have to do this with a couple of other positions too. I can't even get through to customer service to find out whether they could move positions for me into a share account at a reduced spread! It's not as if I have a small account either so not sure why management seem to think alienating long standing profitable customers is a worthy cause!
I shall look at Spreadex on your recommendation now as well I think
cheers
David
Re Best Of The Best (LON:BOTB)
The biggest danger I see here is that it is so illiquid. If the news flow becomes negative for any reason it’s going to be the devil’s own job trying to sell out when others are trying to do the same.
No position.
"Possibly there will be a clampdown one day, eg if the debt charities find a surge in Cat 2 due to people being bored in lockdown with nothing to fritter their money on (gambling is the new entertainment!)."
Fortunately Charidees don't count, tend to be run by no-bodies and in some cases cranks. The World would be a very bad place if every Charidee - Greenpeace, The RSPCA animal liberation front, Trussel, XR, the nimbies, Mary Whitehouse, Camilla Batmancatdogadoo etc - got their way.
There are three reasons why regulations / bans are a bad idea:-
1. Governments are addicted to smoking, petrol/diesel, coffee, alcohol, speeding, gambling, and most other sins... because Governments derive stealth taxation from all these sins. Were they to illegitimatise any of the above, they would be cutting off both their powers of taxation and powers of regulation.
Consider illegal drugs, boy-racers, tobacco smuggling, and the evils this adds through being pushed out of legality or being highly taxed.
2. And, once Governments regulate (and tax) one minor activity, their tentacles quickly spread further and further. Rarely does a Government deregulate, detax, remove a yellow line, cheapen a parking meter fee. To add more burocracy and curtail freedom and opportunity is what Governments instinctively do.
Once one control is in place, what will they then have precedent to come for next?
3. Humans are clever and will invent ways to circumvent excessive controls.
UK_Investor_8888 I think that you might be surprised how many ‘nobody cranks’ serve the charity sector in some form or other here, and give their time and experience to help others and the wider world. There is more pleasure to be had than just gaming the system for your own gain, which is fine, but restricting of your pleasure outputs. Supporting others, or campaigning for improvements and getting involved in a bigger picture is a legacy. Share the love, that’s where real satisfaction is.
Re Charity.
You don't know me.
Anecdote
I know a beautiful cathedral-ed historic town. The do-gooders on a Sunday night turn up with some kind of feeding trailer (trough).
Result: historic market town has drug addicts, severe alcoholics, criminals, vagrants, beggars, prostitutes, and the streets and medieval alleyways are taken over by criminals on a Sunday night.
Charity does not sadly mean honourable people like The Rotary Club, British Legion, etc, but unfortunately harbours some very undesirable agendas.
Anglo Pacific (LON:APF) are also doing a placement of up to 20% of their shares today (Also available to retail through Primary bid).. Quite possibly insti’s and others are selling holdings with a view to buying back at a cheaper level in a discounted offering.
New to investing and trying to take in as much of the commentary as poss, so thanks for all the good info.
Re Amigo Holdings (LON:AMGO), there has been a lot of buying in the last week along with JP Morgan jumping in to some tune this morning. Does somebody know something we don't. Any views welcome thanks.
Re. Amigo Holdings (LON:AMGO) price movement, there’s a potential situation developing that could lead to a step change in value due to some ongoing legal action/corporate action. Suggest you have a look at Evil Knievel/Simon Cawkwell’s commentary and take it further if of interest.
https://masterinvestor.co.uk/e...
No position being taken or intended. Bear in mind, however, the general caveat that if you don’t know who the mug is in a poker school he’s probably sitting in your seat.
In relation to tracking the Rhodium price I like this one
https://tradingeconomics.com/commodity/rhodium#:~:text=RHODIUM%20is%20expected%20to%20trade,17148.60%20in%2012%20months%20time.
I attended the Mello event on Monday past and there was some discussion on whether it was Rhodium or Platanium that was driving the Sylvania (LON:SLP) share price.
There was a HY Results management meeting on Investor Meet Company yesterday and I believe that it clearly shows in the slide below that Rhodium is the key driver, followed by palladium. Although they produced 12.7% of Rh it equated to 60% of the revenue. I also spotted a good website from the mello event to track these PGM's www.moneymetals.com for those interested. Although Rh is expected to continue in a deficit for the next year it may be wise to track the Rh price on a regular basis.
Re Volex (I hold) nobody has picked up on the fact that Nat Rothschild reduced holding from 25% to 24.46% on 19 Feb. Previously the share price had been accelerated when he had increasesd to 25%
Was this maybe not just due to dilution? Not 100% on that though.
Hopefully the inaccurate "Nat Rothschild reduced holding" was just a mistake rather than intended to cause mischief. Obviously if there are more shares in issue and NR's holding stays the same, the associated percentage will reduce, in this case resulting in an RNS.
I don't think we should suggest that people are trying to cause mischief. We all makes mistakes!
Hi Ted,
You've got that wrong. I always check these things, as I check every RNS issued by companies in my larger portfolio holdings, using an email alert service. So I would have spotted if the CEO had reduced his stake!
What actually happened is that Volex (LON:VLX) has issued some new shares, as part of an acquisition, which has increased the total number of shares in issue. Hence that triggered the CEO needing to issue a revised Holding in Company TR-1 form, to disclose that his % has technically changed, but purely due to the issue of new shares, not through any selling on his part.
TR-1 forms are not at all user friendly, and have to be scrutinised very carefully, as it's easy to draw the incorrect conclusion as you've done. Here is the tell-tale explanation from the RNS that was issued:
.
.
Best wishes, Paul.
I suspect the reduction in Nat Rothschild's holding is dilution due to 3.3 million shares issued to the seller of DE-KA and the 1.4 million deferred consideration shares issued in respect of the acquisition of Servatron, both of which were admitted to trading on 18 Feb.
Volex (LON:VLX)
Yup. Going from memory when I looked at the RNS, NR still had the same amount of shares but his % had been diluted.
(Which means he can buy more without hitting the dreaded 30% - LoL)
I’ve a question kind of related to the Volex dip in recent weeks (and especially yesterday). I’m interested to know how people decide when to sell, when to buy the dip, or when to do nothing! Someone told me once to sell half of a profitable holding if it has fallen more than 15% from its peak as there’s a good chance that the market knows something that you don’t, and it will carry on dropping further. However, in recent months this approach has cost me money a couple of times (though I can also think of times where it could have helped - a lot of investors could have got out of LoopUp, for example, before its big drop). Luckily I held on to Volex yesterday. I know there’s no definitive answer that will work every time but Im interested to see how other investors think about it. Is it just decide on a case by case basis how confident you are about the company and its valuation? Thanks
I know that is one of the differences that sometimes exists between "investors" and "traders" and @Michael Taylor talks about it in his books, that when you are making a trading decision to buy you should also be making a decision when to sell (price or percentage). So yes you are looking for a price rise, but at what point do you either reduce your holding (e.g. price doubled so sell half and run the profit element only) or exit (e.g. the typical P/E for this sector is 15, it is now at 30 so is booking 2 years continued growth already I will take it all off the table).
My current rules on sell are 1. Profit Warning (thanks Ed with hindsight obviously!), 2. I identify something I feel is better (hence book profit/loss) as I am often 100% invested. I have penciled in earnings downgrade to be added to that checklist, and have a loose 25% loss in value (as no longer use stop losses after painfully losing on intra-day volatility lows last summer).
So as an investor I would like to find a (several) multiyear compounder(s) that achieve >10% CAGR year on year and just buy and forget. Maybe Fundsmith over the last 10 years or Best Of The Best (LON:BOTB) ?
But with the current volatility, and my own nervousness from last year, and knowing that I typically read this after 8pm. So if I have a buy decision (or sell) it is when I get time to log on the following day execution style, often a Monday or Friday. But I am thinking more into the "when to sell" as I am still rebuilding capital as for me the low point in portfolio value was ~July 2020 (2 off 3 portfolios I manage are back even, one is still down ~10%). So therefore I am more starting to think about booking gains rather than watch it go up, down, up again, down again such as £IGG. Hence something like Wynnstay (LON:WYN) with its recent rise is one such example, should I sell and book the gain, or continue to hold?
It is also worth looking at Roland Head's articles on introducing "Sell" rules to his SIFF folio, so whilst that is a run each month, it is something that can be done more often if you are able to.
Tommy
Volex (LON:VLX) was on my 'watchlist' so when it bombed I thought why? saw the IG shenanigans and thought ok buying opportunity. That's about as informed gambling as I can muster. What is the underlying market sentiment. What was the term "buy when blood on the streets", something like that. Although can get you into trouble. Hence why use Stocko so if get it wrong then at least can fall back on fundamentals and go long.
Volex (LON:VLX) when noticed the fall , I was tempted to jump in there. i presumed it was the copper price impact. Given, that Volex (LON:VLX) was near its all time high, I decided to pass it and not risk my capital. Instead, I jumped onto Sylvania Platinum (LON:SLP) instead which fell to 109-111p level. (the 3% divies were overly tempting! )
"When I placed an order with my usual telephone broker yesterday, he replied “I’ll try, but they’re not picking up the phones at the moment” (meaning the market makers)"
Probably not a surprise. A tacit admission that market makers only make a market when it suits them to do so..
Not true. (I used to be one).
they will usually just maker a wider market.
"Lets take a look at what you could have won"
EVRAZ (LON:EVR) of course is up 3.8% on yesterday following my massive sell. You could set your watch by this inevitability.
There must be a term for this somewhere - 'Murphys Law' does not fit. I dropped Kromek (LON:KMK) after getting bored and two days after 'boom'. Answers on a postcard sorry blog.
Regarding Volex (LON:VLX), what an intense hour I had yesterday. Both my stops on my spread bets were hit and it went to within 1 point of my stop in a large position in my ISA account . I topped up at 290 and bought back in the spread bet at 302, all running to and fro to my office in the Swedish school kitchen I run serving kids their meatballs! For the first time I nailed this opportunity instead of panicking and losing out. Only been trading 10 months but what a 10 months to cut my teeth on. Think I’m learning a little finally...
Fantastic Stuart! Hilarious the thought of you trading between meatballs :-)
Hi Stuart,
That's precisely why I don't use stop loss orders on individual shares - all you're doing is providing the market with a target to reach in order to help itself to your money!
I think stop losses are a substitute for proper research & sensible position sizing. But there again, I'm an investor, not a trader.
Your post does conjure up a hilarious mental image though, so gave me a good laugh, meatballs flying around, stressed out chef with mobile phone perched on shoulder trying to get a trade executed & shouting at the kids to be quiet! :-D
The market seems to be full of people who are trying to trade in & out of things, I have no idea how people think they can execute that well, whilst doing a different day job!?
Good luck with it anyway. Maybe we can, in time, persuade you of the merits of a longer term investment approach?! But each to their own I suppose, "whatever works, keep doing more of it", as my mentor always told me.
Best wishes, Paul.
and thank you Paul for SAGA...I am proposing you for a knighthood
Thank goodness I closed my account with IG 2 weeks ago, because I was kept waiting time and time again by their telephone staff. On the other hand the Spreadex team staff are excellent and east to deal with.
One review of Spreadex, says they were unable now to trade some AIM and small cap stocks on sb account, there had no warning about this. So is this just IG?
I rarely have to ring up, only if there is a problem, so telephone calling is not usually an issue for me as long as the platform is accessible. IG Group (LON:IGG) did have a problem for 3 days in January but since then it has worked well. HL also had some issues in January but not so much as IG.
Hi Paul, regarding IG and their disorderly removal of hundreds of shares from their spread-betting platform. I see several references to the positions being closed out by IG on Monday, yet my email from them states this will happen on 29th March. Can you or anyone here clarify why Monday is being quoted and/or put me right.
Many thanks
Hi 4351anf,
As I understand it, they are switching the margin requirement to 100% on Friday at 3pm (Paul has been told Monday so looks like again they are treating retail and professional investors slightly differently). If you don't have sufficient funds in your account at that time, it will trigger a margin call and liquidation of positions.
If you do fund your account fully, you may still hold these positions until the 29th March at which point they will be closed anyway.
Thanks Phuntt, that is what I thought
I just reported what IG told me in an email. Which is that 100% margin kicks in this Friday on the affected stocks, then the positions have to be closed or bought out on Monday. I think my account is probably classified as a professional account, so there might be differences between that and retail accounts, not sure.
That probably explains is, thanks Paul.
As Paul pointed out the IG situation will cause volatility in some share prices as it settles out.
The question I have is, will it only result in a lot of forced selling - or, a la Gamestock $GME, result in some short squeezes? One of the reasons I ask is £:CARD has shot up today on no specific news, it could be that the Vaccination news is so positive or that it appears such "good value" versus Moonpig, but I also understand that it has been heavily shorted.
An additional question - if we are about to see a short squeeze on various stocks is it likely to temporary (i.e. over the next couple of days)?
I think I understand why IG have made the move but it could have some unintended consequences.
As Paul has stated it’s not what they did but how they did it !!
Great report thanks Paul.
The difference is when comparing today to 1999 is that there is so much more money chasing the stock market without any options to put it elsewhere (for example, a bank savings account), plus it's so much easier and cheaper for the small investor to play with the big boys.
Exactly....and couple that to us all having the ability to buy and sell at the push of a button on our own devices. It’s no surprise there is a lot of volatility. MM’s took Scottish Mortgage IT (FTSE 100) off the electronic order book yesterday morning because they couldn’t cope with the volume.
#APF announcement today looks very exciting, repositioning the company from coal into nickel and now cobalt, immediately earnings accretive yet market does not like...?
Anglo Pacific (LON:APF) I think the reaction may be that the Market thinks they are a bit late to the party and therefore overpaying
(long Anglo Pacific (LON:APF))
Interestingly, I recently sold my Anglo Pacific (LON:APF) shares, because of the high coal content, but as you say they maybe too late as prices have already gone up considerably.
Likewise, I was trading Anglo Pacific (LON:APF), sold out at 107p just before the short seller legged it :( My bad. Anyways, cobalt acquisition sounds great. Only concern is how much $$$ premium did they pay for it. Usually, you buy mines when no one wants them NOT when everyone is rushing to invest into the EV revolution. So was the price right?
Here are my SCVR heat maps for today (prices as at ~10:20am).
Again, there is a lot of going on today so my apologies to those of you who don't like large heatmaps.
Small Caps with RNS news today ("N!!" in bottom row of the heatmap tile means report / update today):
Big movers today in the SCVR world (moving more than a 20d EMA of the ATR against either yesterdays close, or today's open):
Warm regards, and best of luck!
greensiax
PS: See my main heat map thread for more (non-SCVR specific) heat maps, and keys to the heat maps contents:
https://www.stockopedia.com/co...
Scapa (LON:SCPA)
Not sure if there is anyone left holding this company (if not i will switch of the lights when i sell) - we are nearly a month on from the agreed bid announcement at 210p per share - i have temporarily held on in the hope of a counter bid or higher offer bieng necessary. The market originally had the shares at 220p - presumably on hopes of higher bid coming along - now the price is 216p to sell - still a slight premium to the 210p - so i am tempted to take my cash and run.Does anyone else have an opinion on whether there could be sound reasons for not selling now that i may be missing. Not sure how much of a given it is that they will get the necessary acceptances to get this over the line refernce shareholders saying yes please.
Hi I sold half at 220p ish and I have sat on the rest, it does seem low ball but by now another offer or whiff you would of thought would come along. I see the danger as the offer being rejected (only 16% support this far I think DYOR) and the offeree not stumping up more cash. Paul did mention that he doubted the price would fall back too much, who knows look at this week gyrations.
I am not happy with IG
I have closed 46 positions with IG over the last couple of days (out of 80 Positions) and I am now waiting to see what happens on Friday.
I am now looking at other alternatives maybe SpreedEx or CMC Markets, any other suggestion would be appreciated.
I was very happy with them but not anymore
So I completely agree with both Paul and Caper4. I am sure IG could have handled it much better
It seems that everything in my favor is against me.
Disclosure: I own IG Group (LON:IGG)
I am speculating here, as not expert enough to state so authoritatively:
Perhaps IGG are doing the morally right thing? They are protecting retail clients from folly and self-harm. (I can live with this).
Perhaps IGG are reducing retail clients' exposure now to head off stricter (socialist) regulation. If they show that they can do the right thing and self-regulate ahead of the monolithic interfering quangos, then it makes stricter state interference and Chinese style market controls less necessary.
It certainly does embarrass myself as a shareholder to hear reports of poor customer service and crashing web systems. One comment says they are going to order a Ouijee board to contact the (dead) customer service.
A lot of punters will get hurt by dabbling in finance. There's a counter-argument that IGG are reducing harm to members of The Public.
Last comment: The reason to own a share is because of its aggregate value delivered. A StockRank of 94 is fairly good. Any decline in operational performance (and value) will eventually feed in to SR and share price, and then shareholders who matter (the big ones), might act.
Were is the thumb down button when you want it
"Were is the thumb down button when you want it"
The only thumbs Investors care about are The Capital Gain, The Yield and The Stability.
I've heard of 'diversification' but at some point put it in a ETF maybe? IG pumped the results day and snuck in an expansion into the US with some stupid named co. That got hammered but feel they are not too bothered by the SP. But loss of reputation is and need to be careful of brand loyalty. Charts are quite nice and just opened a spread bet account (probably not working now -duh) - perhaps IG got scared some upstart might break the system. Newby but learning fast.
How about 'Newby's Law' - sell the day before it takes off.
I don't hold IG Group (LON:IGG) and I don't have a IG account.
The warning at the top of the IG website states
75% of retail investor accounts lose money when trading spread bets and CFDs with this provider
So I don't think their main concern is is about protecting retail clients from folly, just like gambling companies they are happy to encourage folly (when it is profitable)
"75% of retail investor accounts lose money when trading spread bets and CFDs with this provider
So I don't think their main concern is is about protecting retail clients from folly, just like gambling companies they are happy to encourage folly (when it is profitable)"
You'd think that would frighten people off, wouldn't you. I guess like smoking, vaping, speeding, picnicking on a park bench, etc, The Public still do it in spite of the warnings.
I am afraid most of my investments are morally tainted, on products I would never wish used on myself or somebody (as if) I loved.
All I can say is that this is private enterprise, without State or Tax funding, paying taxes to The State, on regulated products, that people choose to want, are not forced into using, are deemed lawful, and there is healthy competition of operators and options open to clients.
I didn't make them do it when I bought my shares... Stockopedia made me do it. ;-))
My tuppence: isn't it time to use the IG experience to step back and question why our authorities (FCA/hmrc) continue to tolerate financial spread-betting? I see two categories:
1. the wealthy, experienced, intelligent, lucky, street-savvy (insert your preferred adjective) 20% of traders who win on balance and deprive the State of stamp duty and more importantly CGT
2. the 80% 'great unwashed' who are cleaned out after a few weeks, may give up, or may scrape a few pennies together again, then rinse and repeat (since they still harbour a gambling streak and 'financial grief' can be short-lived).
I just don't see how allowing SBs for either category serves any beneficial purpose to society as a whole. Category 1 should just pay their taxes in normal trading accounts while Category 2 probably should be discouraged from any individual share speculation.
Possibly there will be a clampdown one day, eg if the debt charities find a surge in Cat 2 due to people being bored in lockdown with nothing to fritter their money on (gambling is the new entertainment!). A new betting levy or financial transaction tax might be a start to reforming this anomaly. Or introduce CGT on SB gains - even if loss relief were maintained it shouldn't greatly detract from the CGT take from the net winners as the net losers would tend not to have other gains to offset.
Any holes in this analysis?
I was part of the great unwashed when I started investing. If I hadn't been allowed in the club I would be quite a bit worse off now. None of the professionals go into business to make you or I wealthy, they are in it for themselves. I think the problem they have now is that the little guys are doing rather too well. It's very naive to think they are out to look after us in any sense beyond paying plausible lip service to the regulators.
If no-one is allowed to fail then no-one is allowed to succeed.
Clearly a 'shark pool' but one where hope to 'nick a few quid' under their noses. Bit like miners ' holes in the ground with liars up top'.
wish there was a 'love this' button, as well as just a thumbs up.
we all have to start somewhere and today's newbies are tomorrow's pros to be...
I have no argument with the analysis, only the conclusions. Several counter arguments suggest themselves to me:
1) from the punters point of view, SBing gives significant advantages - accessing cheap leverage isn’t easy for retail clients without spread bets. Access to leverage is dangerous and should not be overused/ abused/ misunderstood but it also is also the only way to take advantage of the opportunity the market offers on those rare occasions it actually offers them and you spot them, especially if you don’t have access to a lot of capital (this is especially true in retail accounts where you can only lose what you put in - the risks lie with IG not the punters if there is a large market movement).
You refer to the “great unwashed”, many others on this site have talked disdainfully about young ‘Reddit’ style investors. However, these people have little to lose and everything to gain, they will quickly learn the lessons if they are being foolish, they tend to be young (unlike myself exactly the people who should be taking risks before life/ family/ responsibility weighs them down). The fact that IG is stopping action on a significant portion of their offerings could be because it became unprofitable because these people rather than treating spreadbetting as a fast action casino (as IG wanted), instead chose to buy and hold, therefore in effect accessing leverage (rather than continually paying large spreads which would make them profitable).
2) from the brokers point of view, I have often wondered about that statistic “75% of accounts lose money” as I have been a large investor in the sector for a long time. If most people invest a few hundred, quickly learn their lesson and move on, it takes 1000s of them to make up for 1 clever investor who invest millions and uses the system as a tax free way to buy and hold shares. I think the sector is probably profitable but note the very fact that IG are removing coverage on these shares tells us that they aren’t profitable (or at the very least not worth the risk they are taking on). I look at the list very differently than most of the coverage I have so far read.
3) from the government’s point of view, I reached the conclusion a long time ago that they should tax this industry, I personally hope they don’t (because it would cost me a lot of money) and honestly, I think it’s a long way off just at the minute
Paul's comments about stock market exhuberance remind me of two lines from the book 'When money dies' about Weimar inflation:
"The krone, at 25 Swiss centimes the previous Christmas, was now quoted at one-twelfth of a centime. Her shares, however, were going up. Gambling on the stock exchange had become the fashion — the only
way to avoid losing all one's money and perhaps to add to it."
"On December 15 1919, Frau Eisenmenger recorded that, whereas the downward movement of
the krone in Zurich had gone on, 'the value of my industrial investments is rising to an extent
which seems to be incomprehensible and almost makes me uneasy …"
I think we are witnessing this play out in real time now.
Re BOTB
(I Hold)
Very difficult in the circumstances of such a strong market performance for a buyer to pay what might be called sensible multiples, and satisfy a potential vendor.
Re: Best Of The Best (LON:BOTB) - but surely applies to absolutely everything else, shares, bonds, houses, collectors cars, wines, handbags etc. etc.
Very difficult in the circumstances of such a strong market performance for a buyer to pay what might be called sensible multiples, and satisfy a potential vendor.
Who's to say what "sensible" is? If you want to buy "it" then you have to pay what the seller is prepared to sell "it" for.
If you have 'exhuberant' performance levels rather than trending levels, difficult to say what is the right price. The seller wants to be rewarded, but the buyer can't predict whether there will be a levelling off . If Private Equity are involved they are very analytical, and this can be quite irritating when the business is doing 100 mph, is highly cash generative, pays dividends, and you have a significant holding. Different from an internet stock that performs strongly but loses money, where they need funding etc.
I think they might circle back at some future date, but for the moment it maybe a case of see you later.
Paul you asked readers' views on Volex. I used to own Volex (LON:VLX) but sold out in October at just above £2 - so I come with that baggage of having missed out on the last 50% increase in share price. I would also put myself in the basket of I like Volex (LON:VLX) as a company (which has lots of positives) but think the current share does not price in enough the negatives. The negatives, as I see it, are:
* Historically organic top line growth/ decline has not been clearly presented in reports, although delving into the number it is clear the power cords business at least has historically seen declining organic revenues.
* Growth at the bottom line has been impressive - but this has largely been driven through acquisition and, to me, this should be priced at a lower multiple than organically driven growth.
* Many of the businesses acquired (eg GTK, Silcotec and MC Electronics) have been on lowish multiples (around 6x EV/EBIT). To justify today's much higher group multiple (on Singer N+1's numbers, EV is above 11x 2022 EBITDA), you have to believe these businesses have fundamentally transformed themselves under Volex's management.
* The strategy has changed - it used to be the strategy that ongoing acquisitions would only be in the cable assembly business and that the power cords business was being deemphasised. But the Deka acquisition in Nov 2020 was in power cords. Admittedly, this could be seen as a positive that the management is now seeing many more opportunities in power cords.
* I was really impressed by Daren Morris and he appeared to do a lot more than a "normal" CFO. His departure in Nov 2020 was not adequately explained. I have wondered if it was a co-incidence it was announced on the same day as the Deka acquisition. But I do feel his departure was a loss.
* There is a lot of excitement around EVs and Tesla - but is developing power cords for EVs a business which will not become commoditized? Volex's history with Apple shows that having a glamorous, rapidly growing client is not a guarantee for success.
* Volex is reporting in USD so the recent rise of sterling should all things being equal be a negative for the share price.
Volex (LON:VLX)
No position and my private notes (June 2020) indicate that "I like it", but to add some bear points to consider (from my November 2020 notes):
Paul, re ‘Bull market, everyone keeps making tons of money’.
This is the harm of asymmetric reporting. I understand that in fact loads of Robinhood ‘investors’ got very badly burned on the GameStop fiasco...but of course that doesn’t get reported so much.
Spreads and liquidity on many small caps seem to have been affected by the IG Group (LON:IGG) decision. Given that the issue is with the margin required by their prime broker, it must be on the cards that Spreadex will be forced to follow suit. I suspect (hope) that that will be relaxed over time as one of IG's USPs was the breadth of its coverage and it won't be happy that it has had to pass on this decision. Surprised that isn't reflected in its own share price as, although they are claiming it was low margin business, many of those who trade in larger caps also trade in smaller ones and could decide to take their business elsewhere even if it turns out that they can only use alternative spread-bet companies for a short time before their prime brokers impose the same margin requirements.
If this is a permanent reduction in liquidity caused by the departure of IG (and, possibly) others perhaps it could have some significant (and positive?) consequences for those junky companies that need liquidity to come to the market. If IG aren't making money from trading UK small caps, then is it reasonable to suggest that the MMs are also not exactly coining it? I might be being overly dramatic about this but the spreads that I am seeing - even the real ones - feel to be wider than normal. A case of taking advantage of the demise of a player or an indication of a potential change in approach on UK small caps?
I am definitely feeling this wide spread at the moment. Trying to sell out of some Cloudcall (LON:CALL)
Officially, a decent 100bps spread, 89p to 90p. But even trying to sell at EMS size (1,500 shares, less than £1350) I get quoted at 87p! Well out of the official bid-ask spread.
Put a day limit order on IG for a good few hours, no takers at the 89p supposed "bid". I did see some other trades go through, at 89p and higher, so presume I probably need to pick up the phone and ask IG to push it through...?
Put a day limit order on IG for a good few hours, no takers at the 89p supposed "bid". I did see some other trades go through, at 89p and higher, so presume I probably need to pick up the phone and ask IG to push it through...?
I'd be very careful putting sell limit orders on small caps using an IG share dealing or ISA account. They use partial fills and so you could get a really bad execution if the limit is hit but there is not enough volume to fill the whole order.
As an example, I tried to sell a rump holding of about 1,000 shares in Zytronic (LON:ZYT) a couple of months ago @150p in my IG sharedealing account using a day limit order as I was going out for the day. When I got home and checked the account they had sold only 5 shares before the price moved down until the order expired. They had the barefaced cheek to charge me £8 commission for the privilege and didn't see anything wrong when I phoned to complain. It's not just their spread betting customers they couldn't give a toss about...
All the best, Si
Paul, definitely not having a go at you for your comments about the new traders but my son who years ago spent perhaps 18 months full time learning on his own without any instruction to deal in currencies in very large figures made these points below to me.
---------------
Paul is not the only person to have made these comments. It feels like there is some resentment of the new traders (not referring to Paul). The market is not owned by anyone. Everyone can participate.
Paul says they know nothing about fundamentals and will put it on anything. But he does the same himself sometimes, e.g. BigDish - that company had no fundamentals and it he says it was a punt. And he admits he lost everything at one point. Fortunately, he had the right to continue and learn and why can't these new traders have that same opportunity?
Apart from leverage being removed, I don't think all the new traders will be a big problem long-term for anyone that does not short. There is now always the chance a share will get a big Reddit pop! It is worth noting that GME is still more than double what it was before its monumental rise and fall.
I know the market is overvalued. However, I don't think that is the fault of the new traders and even if there is a collapse, I don't think the new interest in the market will disappear. These new investors will see it as another buying opportunity - they refer to it as a sale. We now have different times. We now have Reddit community with 9M members, Instagram, TicTok, etc. Instagram, in particular, is awash with inspirational images encouraging people to save, invest, stay focused, etc. People are trying to better themselves and although many currently know little about trading, I don't think most are approaching it in the same way as a football bet. Even if they lose their money, they know trading is a skill they can get better at and one day be successful.
----------------------------------
So what he is saying is that we now have a new landscape and market makers and investors are going to have to deal with it because they are not all going to go away. It will present advantages and disadvantages. Good luck!
Hi doublelutz
Great comment, love it.
I think it's a good thing young people are becoming interested in investing. Best to make your mistakes when young with little cash. Then old with your life savings.
The world changes and some golden oldies think the world has gone mad.
All the best
BSV
I agree with this. Shares are always promoted, but why is it that we're accepting of the Press, investor mags (and a certain well know small cap stock picker), informed Twitterati promoting stocks, but we don't like it if it's someone 'young' via TikTok, Youtube or a Reddit board? If the equivalent got my into shares when I was younger I would have been grateful for the opportunity to build my experience and knowledge a lot earlier than I did.
or he could just be saying "it's different this time"
Re 6000 accounts a day...Is this an opportunity to buy Hargeaves Lansdown then ?
(ignore post below....sausage fingers)
Nope. These are tiny retail traders, with £500 in the bank and thinking they can be the next big day trader after watching some Youtube videos and following /wallstreetbets
Reminds me of a post I saw on Reddit. New trader, with £300, on one of those "free" apps - Trading212? Made 32 trades in a day and was so happy he made 12%! Then he looked at his statement carefully, and he had paid out 16%.... in stamp duty..... he didn't realise there was stamp duty on each trade....
Re..more accounts opening.
re Volex (LON:VLX) I think the other comfort is that I doubt the market is evaluating the acquisition of DEKA as positively as it should. N+1 said the pro-forma eps for the acquisition was 27 cents in 3/22. Management guidance for the deal doesn't include any synergies (as per conference call). The main point of the deal(as I understood it), apart from scale etc, is to supply DEKA's European clients globally from their new facility in Indonesia . No idea when those revenue synergies show up (and maybe 3/22 is too soon) but they ought to be significant . So there could be an upgrade, notwithstanding copper, when brokers revise their forecasts now the deal has closed
Good morning Paul
Regarding Volex (LON:VLX), here is the link to my post from yesterday, which presumably you have seen, with positive contributions from other Stockopedia members. It came to very much similar conclusions as you.
https://www.stockopedia.com/co...
Hi Jonno,
No, I hadn't seen your post about Volex, thanks for the link. Looks like we're very much thinking along the same lines!
Regards, Paul.
Best Of The Best (LON:BOTB) I might be reading this wrong, but with a bid of 2,100.00 & an ask of 2,400.00, does that mean the spread is £3.00?
On IG I have an ask of 2509, bid of 2171.... 15% spread. Ouch.
On IG I have an ask of 2509, bid of 2171.... 15% spread. Ouch.
Yes, it's pathetic isn't it? Obviously, it's a great company trading very well with momentum, but for a £200m+ market cap to have a free float of only 16.5% is totally ridiculous. It's never been in my "investible universe" for that reason alone. There are plenty of more liquid fish in the sea...
All the best, Si
Best Of The Best (LON:BOTB) Spread was 18% at open, it only has 3 MM's. On a £250m company that's a lot of spread and must mean the MM's are nervous.
Remember that the free float with Best Of The Best (LON:BOTB) (I hold) is very small, and even within the 15% free float, I think holders are sitting tight, because the company is trading so well. So the share acts more like a £10m mkt cap company, than a £250m mkt cap one. Mgt owns most of the company:
Given that the free float is so small and the large stake holders clearly wanted to realise their gains will a sale of the company. Should we expect a secondary placing in the not to distant future...... 'to increase liquidity'!
Re: Best Of The Best (LON:BOTB)
Yes, I would think that is a distinct possibility. Would that be a bad thing here? Genuinely asking - I don't know. If it was like Quartix Holdings (LON:QTX) where Slater has taken a further 15% and will want to prop up his investment of £28m, it could be regarded as a good thing in that it provides at least one powerful check and balance.
I suspect although I don't know this that there is some family connection between Michael Hindmarch and Nicholas Berry (deceased) the progenitor of the Stancroft Trust and the previous owner of the Daily Telegraph. I have tried very hard to prove that to myself but beyond noting that Nicholas Berry and Michael Hindmarch were of roughly similar age and lived quite close to each other in Chelsea, I couldn't do so. No evidence in the public domain that they were at school or university together or anything like that. Why does that matter? Well, Stancroift have, in the past, sold some on the way up. They remain, however, significant shareholders and, if there was a personal connection between Michael and Nicholas, one of the 'soft' checks could have been that William has treated all shareholders well partly as a consequence of treating Stancroft well. If Stancroft sold out in a secondary placing that check might disappear. Therefore, it would be best if a placing happened for Stancroft to be replaced by someone else who was not a faceless asset manager but someone who, like Stancroft, were in it for the long haul. All complete and utter speculation on my behalf!
The problem with both the sale process and any potential placing is what would be left on the table for any investor? After such an explosive appreciation in the price caused by an equally explosive increase in the profits, it will need someone with vision to see how they can make such an investment work. With Slater's investment at Quartix Holdings (LON:QTX), he is taking a risk that he has bought at the top but once the low-margin insurance business is shed the potential growth from subscriptions in the US may mean that his purchase was well-timed. With Best Of The Best (LON:BOTB) , the potential in the UK is probably in full view and not masked in any way. The catalyst for continued profit and share price increases must surely be in taking the model into other territories. The fact that this hasn't happened is either because they saw plenty of expansion potential in the UK or that they didn't want the hassle of trying to expand overseas or because the model doesn't work overseas. Perhaps Paul, you can comment on what you know in that respect?
If it wasn't already obvious, I am seriously long of Best Of The Best (LON:BOTB).
Best Of The Best (LON:BOTB) - love the cars, toys etc - but 'spot the flippin ball' for gods sake. Electric vehicles are in the mix - good but won't tick the ESG overlords. And why drag out the takeover 'nonsense' for so long so get bored and sell for a loss. Bought some today though on sentiment - should have hold my original holding - duh.
Best Of The Best (LON:BOTB)
Hi Mammyoko
I have a rather large holding here so follow it closely.
Whilst I have taken a look at the CEO's details on Companies House and now know that his wife is apparently a famous designer (my wife recognised the name), I never went as far as stalking the details of his mates - an interesting touch and an interesting conclusion with regards to how it impacts us little guys/gals.
The biggest worry I see with Best Of The Best (LON:BOTB) is not regulation or competition, but the directors themselves. With so much control they can do anything they want, including delisting, and I do question why they continue to "take care of us" when they don't really need to. Last time I checked they would only need c.£60m to buy the shares they don't own.
Moving on...
INTERNATIONAL EXPANSION
For background, International Sales amounted to 16% of group revenue in FY20.
I actually go through the laborious task of tracking the winners and runners up each week so have a rough idea of where winners/runners up are based (UK or International) and how much is given away.
Whilst the below is not 100% accurate, it definitely implies that the growth this year is still coming from the UK.
Just to be clear, it shows that in the main Dream Car competition last year 28.3% of winners were based abroad and that figure is closer to 11.9% so far this year.
Whilst I would prefer the company to start looking to expand internationally it's good to know that the opportunity is still there.
FORECASTING
One of the advantages of tracking weekly prizes (which is 1 half of COS) is that it should be fairly simple to fill in all the other gaps and estimate:
(Note that total salaries - the other major component of OPEX was £2m and doesn't seem to increase by much each year.)
We know that the average weekly giveaways currently total c£117k and even a range either side of this shouldn't make a difference to forecasting for the last 2 months of the year, or indeed going forward with the current 3 competitions.
Note that this week all prizes include +£50k or +£20k depending on the competition - I like seeing this closer to the period end (Year End is April 30th) as it implies that the company is tracking ahead of its gross margin targets and wants to give bigger prizes away.
Putting that all together and assuming
gives me an FY23 Profit After Tax of £23.6m.
The current EV is currently £230m, so even on a tepid 30% growth trajectory (vs what looks like at least c.160% growth this year) the shares do look undervalued.
In fact, when I look a the Finncap estimates published today, I don't quite understand them as they are implying FY21 gross margins of 60%, which doesn't really look correct compared with the 63% achieved in H1.
Either gross margins are expected to fall, or Finncap are underestimating revenues - I personally think the latter.
FINNCAP
For reference this is what my forecast looks like with 100% growth for the next 2 financial years, I am aware this is ridiculous and highly unlikely.
I have been trying since the open to get an on line quote from H-L, wouldn't even quote a price, so may be MM have turned off quote machines again! Finally got one at 2500, but have decided if liquidity and spread is this poor on a day you think MM would be happy to sell, what would be the price for me to off load if the news was bad.
FYI The Times this morning says there are plans to raise corporation tax which is bound to impact our investments: 'Amid concern in the Treasury, Sunak will announce plans to raise corporation tax over the course of this parliament. It had been thought he was looking to put up the tax to 23 per cent. However, The Times has been told that Treasury officials are considering 25 per cent. Janet Yellen, the US treasury secretary, said recently that corporation tax in the US could rise from 21 per cent to 28 per cent.'
I would have thought it a good idea to keep CT low to attract more foreign investment particularly if the US are increasing their rates. Low CT rates seemed to help Ireland.
doublelutz
I would have thought it a good idea to keep CT low to attract more foreign investment particularly if the US are increasing their rates. Low CT rates seemed to help Ireland
Totally agree with you here doublelutz - i have always felt with the other taxes that exist and are levied on businesses - paye vat/business rates/net upcoming online sales tax etc etc - a rate of around 20% is a very fair level to enciurage companies to pay tax and pay that tax in the uk - most bods probably don't appreciate the level of other taxes being paid behind the scenes by your avegae business.
It's almost as if they have forgotten that they also brought in the 7.5% dividend tax 5 years ago or so to specifically to raise extra revenues that are reasaonably closely linked to level of corporation tax paid.
Just another excuse for those that can choose not to pay much uk corp tax / paye / vat and still extract billions out of the uk system to carry on doing what they are doing and probably up their levels of avoidance in that regard. You know who you are Uber/google/facebook - amazon and the like.
Just another excuse for those that can choose not to pay much uk corp tax / paye / vat and still extract billions out of the uk system to carry on doing what they are doing and probably up their levels of avoidance in that regard. You know who you are Uber/google/facebook - amazon and the like.
If the government wants "Uber/google/facebook - amazon and the like." to pay more tax they should change the law. I wouldn't pay tax I wasn't legally obliged to, so why should they?
Of course, they should change the law, but they're unlikely to do so unilaterally for fear of upsetting our American cousins.
timarr
Changing UK law would have a limited effect. That's why it's an international issue, and the US protecting its tech giants is such a problem. And that from low tax homes in the EU (Luxembourg, Ireland).
They're as slippery eels and a very wide net is needed to get them. With very fine mesh. Lots of little nets and they just swim free.
xcity
Changing UK law would have a limited effect. That's why it's an international issue, and the US protecting its tech giants is such a problem. And that from low tax homes in the EU (Luxembourg, Ireland).
Not sure i agree - infact i probably totally disagree - whats stopping the governmant slapping an OAPT (online advertising premium tax) of say 10% similar to Insurance Premium Tax - based on uk derived online ad revenue levied on end receiver of said cash? google and facebook have the exact data as to where their money is coming from customer wise - can you explain how that wouldnt likely work?
If any company does not comply it's easy enough to stop them dealing business to business with other uk entities which is pretty much how they presumably earn most of their revenue. With uber it should be fairly easy to tweek vat law to ensure entity billing customer for tranportation services must account for uk output vat - their argument that they are not a taxi company was always fairly week IMHO and probably would only take a minor rewrite of vat rules to sort.
whats stopping the governmant slapping an OAPT (online advertising premium tax) of say 10% similar to Insurance Premium Tax - based on uk derived online ad revenue levied on end receiver of said cash? google and facebook have the exact data as to where their money is coming from customer wise - can you explain how that wouldnt likely work?
Firstly, because the government only wants to tax the tech giants and doesn't want to hit homegrown companies - Asos (LON:ASC) or Boohoo (LON:BOO) for instance. And secondly because anything that targets the US tech companies specifically will invite US retaliation.
But there's nothing stopping any of this other than the government being unwilling to do something that annoys the Americans. So they drag in hapless local executives and publically scold them but do the square root of b-all to actually change anything. It's all theatre for public consumption.
I would expect them to target business rates on warehouses, though, that's an obvious area where they can raise more tax from ecommerce activity. But it'll apply to everyone.
timarr
timarr
If the government wants "Uber/google/facebook - amazon and the like." to pay more tax they should change the law. I wouldn't pay tax I wasn't legally obliged to, so why should they?
Thats exactly the point i was trying to make (presumably rather poorly) - its easy** for the government to tax these entities more but for some inexplicable reason they choose not to do so - whilst raising taxes on those that do pay their fair share - and at the same time ignoring the fact that google and facebook and amazon possibly have such dominance that they are probably monopolies that have unfair unfluence in theie areas of dominance.
** Hoperfully now we have left the eu we have more scope in this regard - i know particulalry with regard to vat law we were somewhat dictated to by the eu as to what we could do when we were a member state.
Hoperfully now we have left the eu we have more scope in this regard - i know particulalry with regard to vat law we were somewhat dictated to by the eu as to what we could do when we were a member state.
Not really. Let's be honest here - the EU hates the tech giants far more than the UK does. If VAT was the answer then they'd already have done it. VAT is a brute force weapon, that can't be directed to where it's needed.
The answer, of course, is digital sales taxes, which are being implemented by various EU countries plus the UK. That provoked tariff threats from the Trump administration so everyone backed off. Perhaps not surprisingly it seems that the UK has moved this out of the budget until the autumn.
The chances of the EU enacting a digital sales tax are far higher than the UK doing so as we would really, really like a US trade deal and really, really don't want to upset Biden's administration.
timarr
As far as I understand it - the companies siphon the money out to low tax jurisdictions by charging them "image rights" or other intangible costs. Surely we just need to put a tax on that, like making them not VAT exempt or something.
TAX - further on this issue - The Times today states how much HighStreet companies pay in Buz Rates - Hundreds of Millions against just £7m from ASOS. They missed off £BOO.....
That's a separate but related issue. So, how do you tax online companies is one question - although they pay VAT and other UK taxes, especially when UK based.
How do you stop companies charging subsidiaries excessive overhead "costs" that are actually a transfer of profits between tax jurisdictions to minimise tax liability is a different question.
Probably the most relevant quote on tax was uttered by yourself a few months back Tim "You can only tax someone/thing that can't leave the country" hence why the middle/upper middle class are an attractive target.
Regards Andy
Best Of The Best (LON:BOTB) announces end of formal sale process and positive Q3 update. The house broker this morning Finncap issues its first broker note since the announcement of the sale process last summer and expects adjusted EPS of 125p for year ending April 2021 and there's obviously good visibility at this late stage in the financial year. That was roughly in line with my calculations but hopefully now the wider market will appreciate this is looking cheap relative to growth.
Best Of The Best (LON:BOTB) is bound to have benefited from lockdown but I don't expect revenues to fall dramatically post lockdown because it has now built up that customer database and greater awareness of its business. Ticket prices are now much cheaper than early 2020 - I regularly play the midweek game for c.£1.25 or lower - which should also help purchases to continue and increase post-lockdown.
I also think they have worked magic with their social media marketing as Best Of The Best (LON:BOTB) adverts seem to be everywhere online for me!
The advertising is tracking you. That's why you're seeing so many ads.
Indeed.
I seeem to be being tracked by Nigel Farage for his latest investment scheme. I preferred being followed by BOTB.
I've had Farage on youtube, often when viewing financial videos, it is really annoying him popping up every 5 minutes with same message, who is going believe him?
Apart from that I don't seem to be tracked. I use Ccleaner which seems to clear them.
Urgghhh, yes, that Farage advert is dreadful. I kept reporting it as inapproprate for a while, but it still didn't go away. Get your significant other to buy some underwear online is my top tip, that always seems to improve the adverts displayed ;-)
My morning smallcap tweet:
Novacyt SA (LON:NCYT) Celtic (LON:CCP) Avacta (LON:AVCT) Best Of The Best (LON:BOTB) Angling Direct (LON:ANG) LSL Property Services (LON:LSL) Zoetic International (LON:ZOE) Electra Private Equity (LON:ELTA), Proactis Holdings (LON:PHD)
Novacyt (NCYT) R&D update including trial of covid lab test using saliva at AstraZeneca: 54000 tests averaged sensitivity of ≥95% and 100% specificity. [SP=684 Cap=560m]
Celtic (CCP) team manager resigns. He is thanked. Sports pages have more excitable reports. [SP=102.5 Cap=97m]
Avacta (AVCT) starts full clinical validation for CE MArk of rapid covid test - potential commercial launch for professional use end 2020Q1. Progess in both divs "has already enabled us to deliver major value inflection points during the first weeks of 2021." Pass the MBA sick bag. [SP=178 Cap=451m]
Best of the Best (BOTB) ends offer talks. Recent 20% fall must be a coincidence. Trading in-line. [SP=2450 Cap=230m]
Angling Direct (ANG) FY(Jan) in line with rev up 27%, pre IFRS-16 EBITDA at least £3.8m but no FY22 guidance. [SP=78.08 Cap=60m]
LSL Property Services (LSL) continued to deliver strong financial performance in first 7 weeks. [SP=241 Cap=253m]
Zoetic (ZOE) CBD products "now set to be stocked by one of the largest tobacco-focused retail chains in the US...a pivotal moment in the progress of our US rollout." [SP=75 Cap=147m]. I'm short.
Electra Private Equity (ELTA) all portfolio companies is trading in line. [SP=319 Cap=122m]
In line: Proactis Holdings (LON:PHD)
Avacta (LON:AVCT) test is for the antigen not the antibody which the immune system takes up to 10 days to generate. Saying that the test is quick is perhaps missing a more important point.
Good morning Paul, re Volex (LON:VLX), likewise I hold and wasn't expecting the buying opportunity yesterday. Looking at the graph Volex does seem of late to reach a summit and then fall away quite quickly only to return soon after. However this time around it's been sitting at or around it's high point for a little while, before returning to December levels in little more than one day. My observation is that while it's not entirely consistent there were some similar falls generally around basic materials yesterday, at least the ones I watch, including these often talked about examples: rare earth metals - Sylvania Platinum (LON:SLP) at -5.1% (okay, perhaps some profit taking), iron ore Ferrexpo (LON:FXPO) at -4.6, gold - Atalaya Mining (LON:ATYM) at -4.9% (all I hold); and many other examples in admittedly a volatile sector. I wonder if Volex just got caught up. It all makes me a little wary.
It also seemed just an odd day with a lot of swings, Boohoo (LON:BOO) (I hold) doesn't do any mining nor does it supply Tesla so far as I know, (unless Mr Musk is about to be unveiled as the new face of Burton Menswear?) Always a bumpy ride it seems but quite a fall on no particular news the last couple of days, at one stage touching about £3.30 yesterday before picking up a bit. Maybe fickle holders are terrified at the thought of the novelty of the high street reopening and the carnage of discounting to follow.
Paul, just a quick note on IG. I received a call from a very nice young man at IG yesterday afternoon who informed me that my affected positions would be automatically closed at 3pm on Friday, not Monday as stated above. Just pointing it out in case it affects anyone else.
The very nice young man received a pretty rough reception from me, which I feel fairly guilty about as I was was very much shooting the messenger...
Hi Phuntt,
OK thanks re IG. There might be differences with how accounts are treated depending on status re retail or professional. What a mess though. I can't believe how IG have so nonchalantly alienated so many clients. Very foolish indeed & just reeks of poor management, so I would now never buy any shares in Ig Group (LON:IGG)
Regards, Paul.
Exactly my view Paul. Used to have quite a significant holding but have sold the lot in the last few weeks with the last tranche yesterday. Would never use them again or buy their shares
Hence, my confusion, when after Tuesday was a bloodbath - i take a look at IG's SP and it had gone up 2%. U wot!!!!!!!
Hence, my confusion, when after Tuesday was a bloodbath - i take a look at IG's SP and it had gone up 2%. U wot!!!!!!!
Ig Group (LON:IGG) is re taking action to reduce risk and reduce lower margin business, so it ought to be positive to the bottom line. Hence the share price rationally ought to go up.
Over-reacting to personal experience rather than looking at the bigger picture is a fairly common behavioural bias. Once we get out of the small cap arena what individual investors think mostly doesn't matter.
timarr
Just to add my personal experience. I have an IG spread betting account but only hold 3 shares in it (one a c£10m market cap and one a c£50m market cap) but bizarrely none are in the list of shares to be closed out and I am free to add to positions. But worryingly from a customer service point of view, I have had no contact from IG announcing their change of policy. While I am not directly affected, I cannot see how it is not relevant to me that IG is stopping making markets in many small caps.
As for which shares IG are closing out and which they are not, it appears that the decision must have been made by AI - as it is not a logic intelligible to a human (at least not this one). For example, IG is stopping making markets in Witan Investment Trust (LON:WTAN) but not in Argo Blockchain (LON:ARB)
I think IG Group (LON:IGG) should put the list on their site and do it in alphabetical order, so it's easy to see which shares are affected.
I don't have a sb account with IG but I do have an ISA account.
I'm not happy with the way this has been handled and I have sold most of IG Group (LON:IGG) shares, shows poor management. I'm happy to continue with my current account with them.
However their customer service is poor, took me 70 minutes to get through to speak to someone in January. I was surprised to read an article i think it was in the IC that HL had the worst service. I did ring them up in January and it only took 2 minutes to speak to someone. I agree their service is not what it was but IME it is far better than IGs. IG however have a far cheaper dealing service and for me HL was not worth it anymore as I'm investing more overseas now.
"As for which shares IG are closing out and which they are not, it appears that the decision must have been made by AI - as it is not a logic intelligible to a human (at least not this one). For example, IG is stopping making markets in Witan Investment Trust (LON:WTAN) but not in Argo Blockchain (LON:ARB)."
CFD/spreadbetting brokers make their return via overnight financing fees & spreads.
So commercially they will:
* continue to make markets in stocks with wide spreads that attract churning day traders (Argo Blockchain)
* cease to make markets in narrower spread, 'buy & hold' type stocks (Witan)
Paul: Re Volex I see that Citiwire is reporting Judith MacKenzie of Downing Microcap this morning:
"Post the Deka acquisition and through significant free cashflow generation we can see a clear pathway to Volex meeting and exceeding management’s $65m operating profit target over the medium term"
Clue here may be "medium term"? I hold
Reading all the reports of brokers being swamped with new account applications in the wake of the Robinhood/Gamestop mania and the sudden discovery of trading as a 'working from home' pastime / gambling substitute, it sounds like there could be an opportunity here as they are likely to have a strong quarter (even if its a one off/short term uptick) which could give shares a short term boost. IG (and any others that also have a substantial practice in CFDs/spreads etc. that could follow suit) could potentially be hurt by the IG fallout and people transferring away to alternatives perhaps so they might not be the best picks. Aside from Hargreaves Landsdown (already quite pricy and lots of reports of unhappy customers) any other ideas on possible prospects in this area listed in London? Would ideally want to look for more of a pure execution platform provider/broker and without an associated investment management/funds exposure which would muddy the waters...
BIACS
Jarvis Investment Management have a very popular execution only platform X-O. I hold.
Jarvis Securities (LON:JIM)
Yes, I use their "Share Deal Active" Service for my SSAS and its very cost effective.