Small Cap Value Report (Wed 25 Oct 2023) - OMG, IGR, FRAN, RWS

Good morning from Paul & Graham!
Graham was too mentally frazzled from untangling yesterday's profit warnings to be able to do a YouTube show! But he's preparing for his 11:30 live (and recorded) update today as I type this - here's the link
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Summaries
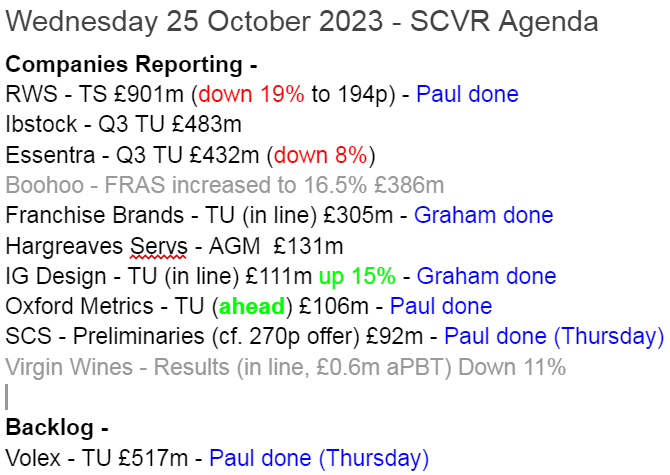
Oxford Metrics (LON:OMG) - 82p (pre market) £107m - Trading Update (ahead) - Paul - GREEN
This very cash rich group is trading well, about 9% ahead of expectations, with clear guidance provided today. Bear in mind that about half the profit probably comes from finance income on the cash pile. Should be a good day today, I think this one is heading up 10-15% (and I haven't checked the price yet, no cheating!).
IG Design (LON:IGR) - up 16% to 130p (£127m) - Trading update (in line) - Graham - GREEN
I remain positive on IGR after an “in line” trading update. The key point is that the company’s aspiration to restore operating margin to pre-Covid levels is unchanged. Through cost-cutting and pricing initiatives, and exiting unprofitable contracts, this remains their goal.
Franchise Brands (LON:FRAN) - down 7% to 146.8p (£285m) - Trading update (EBITDA in line, EPS down) - Graham - AMBER
Today’s announcement includes variations of the phrase “in line with expectations” four times, but that strictly applies to EBITDA, not to items further down the income statement. Higher interest rates have impacted EPS expectations. I retain my neutral stance.
RWS Holdings (LON:RWS) - down 17% to 197p (£750m) - Year End Trading Statement - Paul - GREEN
This detailed update for FY 9/2023 strikes me as fairly solid, given tough macro. So I was surprised to see shares down 20%. Maybe there's something nasty buried in broker updates that we're not allowed to see? (I have been told Singers were unusually critical today). Today it says performance is within the broker forecast range (near the bottom, we can guess). Finances are sound, with generous shareholder returns, and still retaining net cash. RWS isn't perfect, but I'm sticking with green just because the value is becoming more and more striking, whilst performance is still at fairly healthy levels of profit and cashflow.
Paul’s Section:
Oxford Metrics (LON:OMG)
82p (pre market) £107m - Trading Update (ahead) - Paul - GREEN
Oxford Metrics (LSE: OMG), the smart sensing software company, servicing life sciences, entertainment and engineering markets, today provides the following update on trading for the financial year ended 30 September 2023.
Record Revenue and Adjusted Profit outturn for FY23
A huge sigh of relief is almost audible from OMG shareholders! The share price has fallen almost a third from a recent peak of c.120p in July, to 82p at close of play last night. I imagine it should find buyers today, and rise maybe 10-15% at a guess? (I like guessing before 8am, just for fun).
I think some investors might have been worried that the strikes in Hollywood, and a profit warning from a sector peer in high end cameras, might have impacted OMG too. Although its very large cash pile protects the downside considerably.
The general small caps market malaise at the moment, means that some investors are selling first, and asking questions later. Hence price moves are often due to panic or forced selling, not informed selling (sometimes!). This is creating buying opportunities in some cases, and traps in other cases when the selling actually is informed. Trouble is, we can’t tell which from which until companies report how trading is going.
This is the key part -
The Group expects to report revenues of £44.0m and an Adjusted PBT* of £6.3m, both ahead of current market expectations* for the financial year. The Group finished the year with a robust cash position of £64.8m and no debt.
*Oxford Metrics' compiled market consensus as at 24 October 2023 is as follows: FY23 Revenue £39.00m / FY Adjusted PBT £5.83m.
Excellent, clear reporting there - why can’t all companies do this? Tell us the actual profit (not EBITDA!), and provide a footnote saying what market expectations are.
So we have a nice beat here in adj PBT, with £6.3m actual, vs £5.8m forecast, about a 9% earnings beat.
Net cash of £64.8m is c.61% of the market cap! So what the company does with that cash in future is key. Also note that this cash pile should be earning interest income of (my estimate) about £3m pa. That’s almost half the reported profit.
Bear in mind that inflation of c.7% will have eroded about £4.5m of the purchasing power of that cash pile, which of course does not get accounted for. So I would say that accounting methods mean that arguably cash rich companies are overstating their real profits at the moment through finance income that is not even offsetting inflation. Worth bearing in mind.
EDIT: mammyoko makes a great point in the reader comments below, that whilst OMG's cash pile may have fallen in real terms when measured against general price inflation, it's not being spent on buying general goods. It's earmarked for company acquisitions, which might have become cheaper given macro conditions. That's such a good point, I think it deserves inclusion here, with a hat-tip to mammyoko. End of edit.
But I think most investors will probably ignore this. It’s also something to think about if central banks begin reducing interest rates - investor interest in cash-rich companies may wane, as their finance income recedes again maybe?
Outlook - also sounds good -
Following the Group's strongest-ever first half performance, momentum continued into the second half driven by a particularly strong contribution from the Engineering and Life Sciences segments. Vicon continues to see ongoing demand for smart sensing into yet more applications from new and existing customers alike and the new Vicon Valkyrie system launched late last year continues to stimulate demand.
The Group as a whole remains in a strong financial position which enables the business to pursue its organic growth and M&A objectives in the year ahead.
The Group starts a new financial year with a solid order book.
More detail will be provided when Oxford Metrics announces its Preliminary Results for the financial year ended 30 September 2023 which is expected on Tuesday, 5 December 2023.
Paul’s opinion - expect a pleasant day today if you’re holding OMG shares, and well done for not bottling it during the recent price fall.
We’re very keen on OMG here, I’ve viewed it as GREEN in all 3 times we’ve reviewed it in the last year, and today’s update certainly reinforces that. So it’s GREEN again.
Very nice risk:reward on this, although do bear in mind that the sparkling profit might have come (about half of it) from finance income on the cash pile.
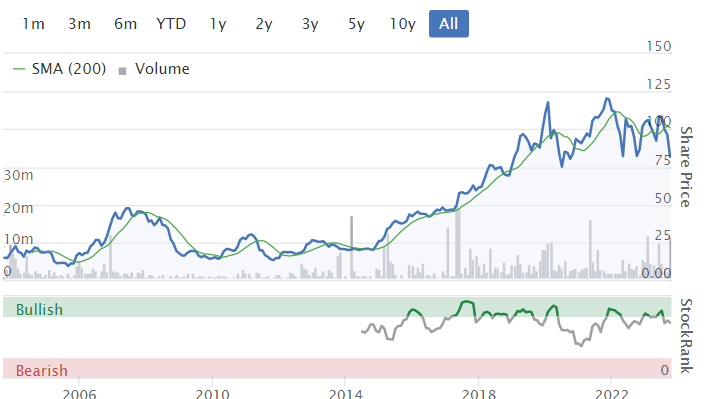
Long-term chart looks nice, and a fairly high StockRank too -
RWS Holdings (LON:RWS)
Down 17% to 197p (£750m) - Year End Trading Statement - Paul - GREEN
RWS Holdings plc ("RWS" or "the Group"), a unique world-leading provider of technology-enabled language, content and intellectual property services, today provides an update on trading for the year ended 30 September 2023 ("FY23") ahead of the announcement of its preliminary results on 12 December 2023.
The story so far, according to previous SCVRs -
27/4/2023 - 266p (after a sharp fall earlier in the week) on a mild profit warning. Attractive valuation, 9.8x fwd PER, 4.9% yield, net cash. AI worries? It looked attractive value on the day, so I went with GREEN.
8/6/2023 - 240p (up 6%) on solid interim results, and news of a £50m buyback. Again, it looked good value to me so I went with GREEN again.
Remember that our traffic lights don’t necessarily have predictive ability. We’re just reviewing the 3 F’s on the day (facts, figures, and forecasts). Things obviously then change over time, sometimes in unexpected ways.
Generally though, companies that have sound finances, which are trading well, and reasonably priced, should do well over time, unless something goes wrong (as it often does!). Plus we’re seeing loads of takeover bids too for (mostly) good companies.
On to today’s FY 9/2023 trading update from RWS, which starts off with a positive headline that clearly the market doesn’t believe is giving the full picture (as shares are down 17% as I type this) -
Encouraging progress with growth initiatives, new client wins and continued strong cash generation
Performance for FY 9/2023 looks OK (in the context of a bombed out share price) -
The Group expects to report adjusted profit before tax within the range of market expectations1.
1. The latest Group-compiled view of analysts' expectations for FY 2023 gives a range of £738.1m-£757.4m for revenue, with a consensus of £748.8m and £116.5m-£129.0m for adjusted profit before tax, with a consensus of £125.8m.
That ties in with the StockReport’s forecast net profit of £94.7m (ie PAT). If I divide this by 0.75 (to add back an assumed 25% corporation tax), then it’s £126m adj PBT, almost bang on the consensus figure of £125.8m provided by RWS’s footnote above. It would be easier if the StockReport also showed the pre-tax profit, not just post-tax (“Net Profit”), so we could tie the numbers together more easily with trading updates and broker forecasts, without having to do any manual calculations. Hopefully a future update might address that?
“Within the range…” is more likely to be at the lower end, as others have commented this morning.
Annoyingly, we pond life private investors don’t get access to any broker notes through the only bore hole in the ice available to us, the marvellous Research Tree. Given that the share price opened down around 20%, then I think it’s safe to assume that professional/institutional investors who do receive broker notes might have seen something negative first thing.
Hopefully something might come through later.
Other points, I’ll summarise -
Improved efficiency (cost-cutting) to maintain profitability, with more planned.
Forex hedging helped.
Challenging market environment.
Revenue down 2%, or down 6% at constant currency, and ignoring acquisitions.
Slightly improving revenue trend (down 7% H1, down 5% H2)
High client retention & satisfaction scores, plus some new customers.
AI is positive for RWS (did a “Teach-In” [yuck!] recently on AI)
Recent acquisitions have started well.
Strong cash generation.
Net cash was £23m end Sept (down from £72m a year ago), despite £31m paid for acquisitions, and £66m in divis & buybacks.
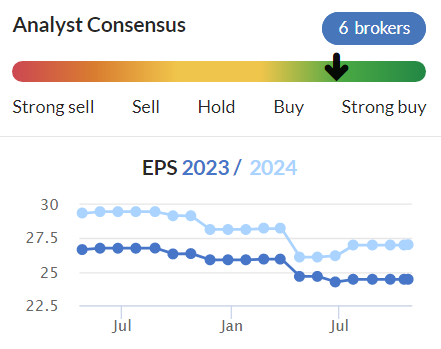
Outlook - there’s not really any specific guidance provided, and I don’t have access to any broker notes. The last paragraph says it remains confident about the “long-term prospects”, which investors often interpret in bear markets as meaning they’re not particularly confident about the shorter term outlook. So I imagine we might see further reductions in earnings forecasts, possibly continuing this trend below maybe? Although to be fair, the forecast reductions haven’t been as severe as the share price decline (down from c.700p in summer 2021, to 190p now). Could this be an over-reaction possibly?
Paul’s opinion - I’m in a quandary here. I keep reviewing it as GREEN, but the price keeps dropping! Yet the value metrics keep improving - we’re now on a fwd PER of 8.8x, and a forecast yield (plus buybacks remember) of 5.6%. The balance sheet is OK, and it has net cash, and remains highly cash generative.
So ignoring market sentiment, I see a good, still highly profitable business here.
We’re seeing signs of strain in many B2B sectors, as companies anticipate a slowing economy, so they cut back or delay some non-essential spend. I don’t see anything more serious or structural in evidence at RWS. It’s just seeing a bit of a downturn due to the same macro factors that are affecting lots of companies at the moment.
Performance is far from disastrous, and it’s saying in line with probably the bottom end of analyst forecasts today, again not a calamity.
Taken together, I think this share’s cheapness, financial strength with net cash, and an OK update today given the tough macro environment, means I have to stick with GREEN. That’s more down to the valuation though, If it was on a PER of 15x, instead of 9x, then I’d be amber.
As regards the commentary about AI. I don’t have the knowledge to ascertain whether the many companies that wax lyrical about AI in their commentaries are just AI-washing with buzzwords, to be perceived as being at the cutting edge of technology, or are actually embracing this area? It’s not actually intelligence anyway, it’s just sophisticated computer programs using vast amounts of data, and producing generally impressive results, but in RWS’s field it would still all need checking, as computers that don’t actually understand the content will make mistakes that a human should spot. That’s already beyond the limits of my knowledge, it’s just what I’ve heard clever people saying, and they sounded convincing! The fact that RWS did an AI teach-in at all, suggests to me that maybe there's more substance to their claims than at some other companies maybe?
RWS was already twitching away on my watchlist as a possible oversold bargain, and I think today’s update and c.20% share price fall has probably made me a little more positive about the value on offer.
Although I’ve not seen broker notes, other than an excerpt from an unusually critical Singers note, which a friend sent me, which sounded sceptical - very rare for a broker note, as they usually give a universally positive perspective.
Interesting one, have any readers looked into RWS?
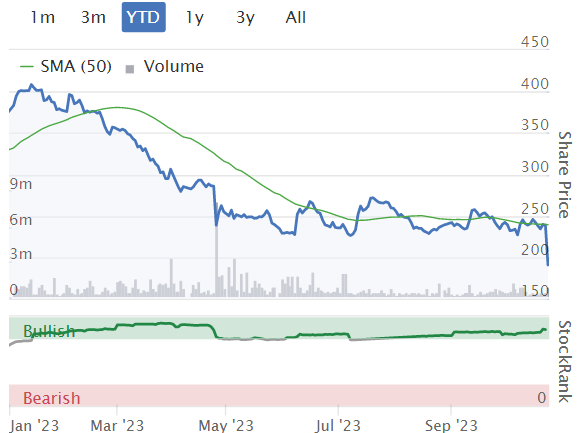
I see from the YTD chart below, that RWS still has a very high StockRank all this year -
Graham’s Section:
IG Design (LON:IGR)
Share price: 130p (+16%)
Market cap: £127m
This is “one of the world's leading designers, innovators and manufacturers of Gift Packaging, Celebrations, Craft & Creative Play, Stationery, Gifting and related product categories”.
Today’s H1 trading update is in line with expectations for profitability, but let’s take a look at some of the details.
Key points:
“Significant growth in profit and margin” compared to H1 last year.
“Net debt is significantly lower than a year ago, reflecting strong cash flow”.
The company says that debt and cash flow are both better than expectations for H1, but I presume this is just a temporary boost that is set to unwind in H2, as full-year estimates are unchanged.
Other key points:
There is “a return toward normal ordering seasonality” (recent years were disrupted, with H2 orders getting pulled into H1 due to supply chain concerns).
There is also “lower consumer demand for Everyday products in some markets and reduced order quantities guided by lower customer expectations of the forthcoming Christmas season”.
The result: lower sales in H1 vs H1 last year.
That might sound disappointing in isolation, but there are several other factors to consider:
a) we already had lower sales expectations for the current financial year (FY March 2024) vs FY March 2023, as the company has exited unprofitable contracts.
b) normal seasonality should provide a boost to numbers in H2.
c) strategic initiatives (cost reductions, higher pricing, etc.) have “more than offset the effect of lower sales”. So H1 profitability this year is higher than H1 profitability last year. I look forward to more detail with the interim results.
Graham’s view
I’ve touted this as a possible recovery stock for the post-Covid economy. Remember that valuation used to be far higher, over £700m:
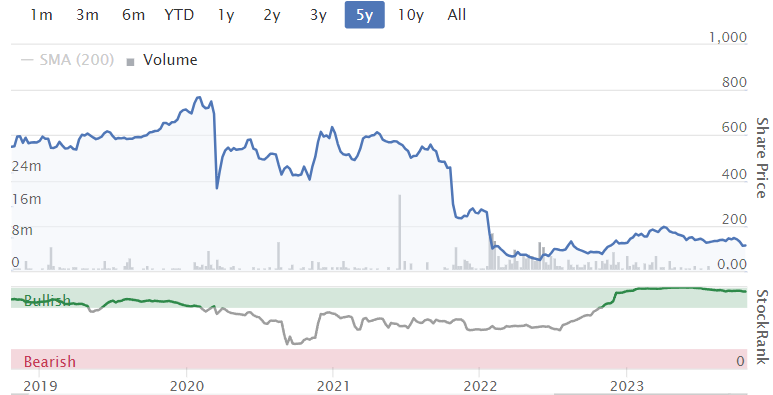
The company made an ill-timed acquisition at the start of 2020. Since then it has been battling with a range of difficulties, particularly the problem of inflation.
An investment thesis I’ve suggested is that as inflation feeds through from costs to prices, the company might ultimately be able to recover its old profitability metrics: it used to comfortably earn an operating margin of over 4%.
With sales of over $800m and a market cap today of still only £127m ($154m), perhaps you can imagine that it could prove to be substantially undervalued at that operating margin.
So for me this is the best part of today’s trading statement:
This represents a strong year-on-year improvement in profit and cash flow compared to the prior financial year, albeit sales will be lower for the reasons given. It demonstrates continued delivery of the Board's aspiration to return the Group to pre-pandemic operating margins by the end of FY2025.
The end of FY2025 is only seventeen months away. Maybe it’s not that long to wait for shareholders, for what would be an extremely valuable achievement? Of course it’s still only an aspiration, but I’ll optimistically retain my positive stance on these shares.
Franchise Brands (LON:FRAN)
Share price: 146.8p (-7%)
Market cap: £285m
This is another update that’s in line with expectations (*asterisk required).
Franchise Brands is the franchising business founded by Nigel Wray and others in 2008 (Wray previously made an extremely successful investment in Domino's Pizza (LON:DOM) ).
Share price performance has been quite good over the years:
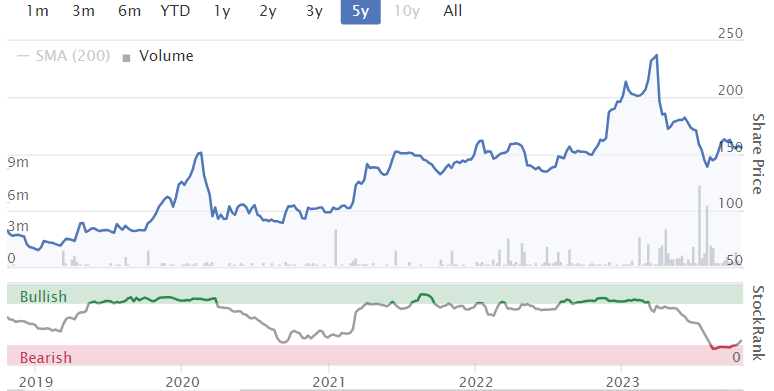
The last time I looked at FRAN I was neutral on it, noting net debt of £79m and plentiful adjustments to the profit figures. At the same time, I couldn’t rule out the possibility that this was the next Domino’s!
Here are the key points from today’s update.
B2B (Metro Rod, Metro Plumb, Pirtek) - “all trading at record levels despite some softening in demand over the summer period”.
Investors may be a little downbeat about this news:
Whilst the type of reactive services provided have resilient underlying demand whatever the macroeconomic conditions, demand naturally reduces when customers' equipment or facilities are not being used as intensively. Consequently, Q3 was a little softer than in H1, but we saw a modest increase in activity at the start of Q4.
Pirtek was acquired for £200m using both debt and equity. It “is integrating well and has met our expectations at the time of its acquisition”. Indeed, integration is being “accelerated” due to the cross-selling opportunities and the “significant opportunities to build a much larger business”. Sounds good!
Filta - mixed news, overall seems ok.
B2C (ChipsAway, Ovenclean, etc.) - “continues to operate in a challenging environment, although profitability is being maintained in line with expectations”.
Net debt has reduced by £3m in three months, to £76m. Unfortunately the interest charge is running at 8% on gross debt of £92m, “which is higher than projected”. Of course interest rates have risen since the time of the Pirtek acquisition. So FRAN is paying around £6.5m annualised on this debt load.
Outlook - adjusted EBITDA for 2023 remains in line with expectations at £29.3m. The Executive Chairman notes that “the trading environment has become more challenging as the year has progressed”.
Estimates - it’s easy to imagine that there is no downgrade to forecasts, but the RNS is clear that the adjusted EBITDA forecast is unchanged, not necessarily profits or earnings per share!
Indeed, brokers have been cutting forecasts this morning, including a 7% EPS cut at Allenby Capital (many thanks to Research Tree). This reflects the higher interest rate being paid on FRAN’s debt.
The new EPS forecast for 2023 is 8.7p. The EPS forecast for 2024 is reduced by a more modest 4% to 10.6p.
Graham’s view
I tend to agree that this company has good defensive characteristics - e.g. plumbing services are rarely considered a discretionary spend.
I also like the franchise business model, which the founders of FRAN have previously turned into enormous success for them and their co-investors.
So I remain open to the possibility that FRAN is a high-quality and attractive share that private investors should be trying to add to their portfolio. On the other hand, its earnings remain highly susceptible to adjustments: adjusted EBITDA of £12.1m in the most recent interim results converted to adjusted PBT of only £6.5m and a statutory loss of £1.2m.
On top of that, the balance sheet is not too healthy after the Pirtek acquisition: the interest bill has grown significantly and that means it will take longer to deleverage (i.e. the company will suffer from negative compound interest - paying more interest for longer!). The net debt to EBITDA multiple is about 2.5x which should still be comfortable but is at the upper end of the spectrum.
Therefore I feel that my neutral stance on this share remains the right one for now.
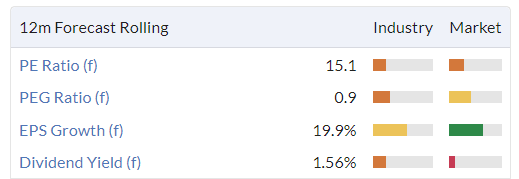
The StockReport also doesn’t see any reason to get too excited about it just yet.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

96 comments
For those of us foolish enough to invest in Unbound (LON:UBG) and fail to get out soon enough (guilty!!) received today this hardly unexpected announcement though my investment platform (AJ Bell). I fear a similar fate awaits Hostmore (LON:MORE. Fortunately they were a very small holding relative to my portfolio.
Unbound Group plc has been suspended from trading on AIM with effect from 27 July 2023, pending the release of an announcement regarding the Companys financial position.
Unbound Group plc is now considered to be a cash shell with no operating business under AIM rules. The company has 6 months from 18 July 2023 to complete a reverse takeover, or re-register as an investing company by raising GBP6 million in funds and publishing an admission document.
If a re-admission transaction has not been completed within this period, admission to trading on AIM of the company's ordinary shares is expected to be cancelled.
To view the announcement in full, please copy and paste the below link into your browser:
https://www.londonstockexchange.com/news-article/market-news/suspension-unbound-group-plc/16043270
To view the potential delisting announcement in full, please copy and paste the below link into your browser:
https://www.londonstockexchange.com/news-article/UBG/delayed-publication-of-accounts-and-aim-rule-15/16057384
Hi ACounsell,
You're obsessed with Unbound! Joking aside, I honestly don't think this is healthy.
A lot of us lost money on it - very painful (my losses from UBG and MORE were well into £6-figures) . The trick is to learn from our mistakes, and then move on, and not to repeat the same mistakes. Losses are completely normal in small caps investing. It's a game of averages - making more on the winners than the losers, over the long-term.
At least you managed to mention it this time without attacking me, which is appreciated, thank you.
We've gone over this loads of times before, but to recap, I think the main mistakes with Unbound were -
1. Debt - it was unclear from all the demerger documentation how much net debt Unbound would retain. It turned out that this was dangerously high, but it was hidden, and only became apparent some time later. I should have asked more questions about this, but just assumed that it would be appropriately structured. So a focus on net debt for new issues is vital in future.
2. Too much reliance on broker research. I definitely placed too much reliance on the Edison research, showing that both Hostmore and UnBound were very cheap, when the demerger of Electra Private Equity was underway. The reality was that we were flying blind, and the figures were opaque, due to the pandemic (as it turned out Hostmore received a large boost from pandemic support measures such as business rates relief, eat out to help out, furlough, etc).
3. Poor management - in fairness, a lot of us thought that management of UnBound were weak, and we discussed that in the SCVRs. Untried people, and remember the RNSs and webinars absolutely full of trendy buzzwords straight out of a coroporate speak handbook. They looked increasingly like chancers, and they were.
4. Unbound management lied to me when I spoke to them about the need for a placing. I absolutely ripped them to shreds in the SCVRs, when they announced a placing about a fortnight after assuring me they didn't need one. The CEO was a bare-faced liar, which I mentioned here, but it was too late by that point because the damage had been done to the share price. As I have pointed out before, once the facts changed for the worse, I did reverse my positive stance to a negative stance, as we always do. You've tended to forget that in the past, in a rush to allocate blame to me (thankfully not in your latest post, which I appreciate).
5. Flimsy business model. Unbound (Hotter Shoes) hadn't worked as a physical retailer, so they restructured, and gave it a go as mainly online. It might have worked with better management, but it didn't. Such is life. Unbound was only ever a little scrap of the total value in Electra Private Equity. The main value was in Hostmore.
6. Why has Hostmore bombed out? Mainly because of the sector problems caused by the energy crisis, and the consumer disposable income squeeze, neither of which had happened when we first looked at it. Nobody could have foreseen this, unless you're a time traveller from the future. So we shouldn't beat ourselves up over investments that go wrong due to unpredictable outside factors. We can of course sell our shares, once the facts change, which is what I did, although the losses had already happened by then. Or use a stop loss.
7. People who said that the business model at Hostmore is a not very good, tired 1990s brand which they have to pay a royalty to use (despite it arguably having little to no value now), have I think been proven correct. Also I think the previous CEO at Hostmore was useless, but a good talker. Remember my flat coke at the Bou'mth branch, a problem that he failed to sort out, in over a year, despite personally promising me on a recorded call that he would personally resolve it? That was one of several warning signs which led me to sell up at a hefty loss, as I could see that the detail was not being managed properly, he was too intent on opening new sites instead of properly managing the ones he already had. He also ran up too much debt.
On the positive side, Hostmore has survived to date, although its position with the bank looks very precarious, hence I see risk:reward currently as too loaded towards risk. Yet the consumer environment is now changing for the better, as wages growth has just overtaken inflation. Competitor (with similarly stretched finances Restaurant (LON:RTN) has received an unexpected private equity bid. Energy costs are rapidly receding, and input costs are also seeing falling inflation. So the hospitality sector could be worth a look with fresh eyes, I think.
Overall, I'm sorry you also lost money on Unbound and Hostmore, as many of us did here too. The facts & figures looked good at the time, but things changed for the worse. That's what happens, all the time. We just have to deal with it, and learn from each experience, and crucially not blame other people for our own mistakes!
Best wishes, Paul.
The mistakes are all mine! I’m not blaming or attacking anyone just posting a factual report I have just received which may be of interest to other subscribers.. We are all responsible for our own investment decisions and DYOR is the mantra of the SCVR. These two stocks are just two of a number I hold in a speculative pot of money in my portfolio and most of them, all selected by me, are deep in the red. Clearly I am not very successful at small cap investing despite the support of Stockopedia’s data and SCVR analysis. Unfortunately I don’t have too many winners to offset the losers. However, I am a pretty risk averse individual so never invest money I can’t afford to lose. To avoid any further debate and your concern that I am casting blame I will hopefully learn from my mistakes as you suggest and refrain from any further comment on Unbound (LON:UBG) and Hostmore (LON:MORE).
Thanks ACounsell,
I appreciate your reply, thank you. It's fine, and good, to discuss all this, so I was trying to open up the debate about the individual shares, not shut it down.
We should probably spend more time on postmortems of the (many) small caps that go wrong, so we can try to spot and avoid the signs in future.
All good, and I'm glad that you're seeing things the way you are now. It previously felt to me that you were personally attacking me for some share ideas that went wrong, by repeatedly referring to Unbound and Hostmore every time you post. Hence why I've tried to summarise what I did indeed get wrong, and learn from it.
Which all needs to be seen in the context of the latest stats that we've written about and given views on 577 unique companies here in the SCVRs in the last year - many of which will have deviated from what seemed to be the case from the 3 F's at the time (facts, figures, forecasts) on the day they report.
Anyway, I'm very pleased we've talked through this issue, and seem to have found some common ground.
Best wishes, Paul.
My goodness Paul. £6 figure loss!! Your portfolio must be in the millions to withstand that or did you have many eggs in one basket?
It's vulgar to talk about portfolio size, nobody does that unless they're needy.
The same could be said about those boasting of six figure losses?
Ashtead Technology Holdings (LON:AT.)
Ashtead Technology signs rental agreement with Reach Robotics - Ashtead Technology (ashtead-technology.com)
For any holders some more news from the Ashtead Technology website .
RWS Holdings (LON:RWS) Been following this for six months. Can see nothing to justify the big price drop today so have bought some shares. Might be a bit early but with the yield as it is now happy to sit and hold.
RWS Holdings (LON:RWS) Just read this in AJ Bell's SHARES daily "
The company-compiled consensus called for unchanged revenue of £749 million. Meanwhile adjusted pre-tax profit was expected to come in at £125.8 million, within a range of £116.5 million to £129 million.
Analysts at investment bank Berenberg lowered their 2023 adjusted pre-tax profit forecast by 5.5% to £120.5 million equating to an 11% fall compared with 2022 while also lowering their 2024 by 11% to £121 million.
Despite the challenges, Berenberg is keeping its Buy rating albeit with a lower share price target of 380p. ‘While recent trading has been disappointing, we do not see this as suggestive of a business facing structural pressures: rather one affected by a range of one-off and cyclical factors that should soon reverse.’
Commenting on the AI threat, the bank added, ‘We will publish more detailed work on this topic in time, but our view is that the prevailing market view fundamentally misunderstands the “expert in the loop” operating model that drives the industry, and insulates leading language services providers (like RWS) from this AI threat.’
RWS Holdings (LON:RWS) , if I’m not mistaken didnt their H1 mild profit warning (PW) indicate adjusted pbt would be at the lower end of the range £128m to £137m, now they are implying at the lower end of £116.5m to £129m, another PW of circa -9% (yes if the consensus of £125.8m v say £123m is applied it’s another mild warning), but either way it’s PW number 2, is the market reaction based on 9% reduced profit plus some for the potential PW number 3?.
Oxford Metrics (LON:OMG) Opened up with a decent increase of around 10% as Paul thought it might which in my opinion still undervalues company, but apparently there is still a seller in the market only just over 5% up at present, the market is just plain mad at present, I would not be surprised in all honesty to see further profit taking in the next couple of weeks and reverse the rise back to the 80p level the way the markets are at present its depressing.
Hi proffittpar,
Yes I completely agree - these are not normal markets. There's clearly a big issue with overhangs in lots of small caps, where any good news just triggers sellers grabbing the available liquidity, and price rises on good news often then being eroded, and prices going back down again to where they started.
I see this as a good thing for patient, long-term investors. It enables us to build a watchlist of intended buys, wait for bang up-to-date positive news, then bide our time and buy them at a favourable medium/long term price.
It's also infuriating for people who hold these shares, but that's just how market conditions are right now. A great time to be gradually deploying surplus cash, in my opinion, as you can just pick your spot, and invest at highly favourable risk:reward, as others are irrationally selling in either despair, or forced selling to meet redemptions.
Once the sellers are done, the conditions are then set up for a glorious bull market. This is exactly what happened in 2003. This time round we've also got the likely catalyst for falling interest rates and inflation in 2024. It doesn't pay to be sceptical at this stage in the cycle, I think it pays to be bold, whilst accepting there might be some more short-term drawdowns - few people can time the exact low, and you can't get the liquidity in small caps once prices start to move up significantly - it was almost impossible to buy cheap small caps in March 2020 for example, as there were no more sellers. You had to buy into a plunging price to get the size, a couple of weeks earlier, which was what I was doing, so I remember it well. Scary, but highly profitable once things turned!
Regards, Paul.
Gattaca plc (LON:GATC) for those who missed the live Webinar earlier in week and want to know why the shares have done well in the last year, here is the video of the presentation plus plenty of Q&A with PIs. Running time 50 mins:
https://youtu.be/NG3T0gXioVA
Hargreaves Lansdown (LON:HL.) - I hold a few, unfortunately, as its been a painful ride of late. I won't be adding more, until the stage 4 downtrend ends. I think the re-rating is due to a few issues: 1. Lack of momentum, 2. Sell-off in all income stocks. 3. Poor growth of late versus AJ Bell and Interactive Investor. 4. Concerns around lack of investment and 5. Although the financials look great, the growth is entirely due to net interest margin. If you look at the most recent annual report - £219m increase in net interest margin within revenue is offset by a £67m reduction in other fees. It's the latter number which is more critical to the share price. I think the sell-off is a tad harsh, but best not to go against the trend at this point. Best to watch and wait in my view. Quality business though.
We've talked a lot about potential takeover targets here recently and I think HL is one, especially at this price. It has c1.8m mostly pretty wealthy customers, which would be a great UK kicking off point for the numerous firms expanding their wealth operations, including JP Morgan, Morgan Stanley and UBS - all of which currently cover the 'Bentley' market in wealth in the UK, but less so the 'Audi' one as exemplified by HL in the UK.
And I suspect any vaguely respectable offer from any vaguely respectable offerer would be welcomed both by major sharehaolder Peter Hargreaves and HMG. And it's why I continue to hold and may even get some more.
Asset Managers
all are down, it is a fertile field now but fear of further drop stops me adding to any including HL.
I am more inclined to add ABRDN as I think ii is doing better than other money mangers.
ABRDN might be interesting as an asset play - the fund manager is rubbish but if you add up all the cash, the Phoenix stake and of course ii, you're effectively getting the core fund management business for free.
Back on TO talk also noticed Finsbury Food (LON:FIF) is sliding so a 6%ish profit to be made on the t/o which is still recommended but the board seem a little less convinced on the value?
May they raise the price to get it over the line? Sounds like a decent chance
Hi topturkey,
Good point, I agree that Finsbury Food (LON:FIF) is looking interesting again - slipped down from the 110p takeover bid price (which is a piss-take if you ask me, too low by far for a good business), so maybe this could be a buying opp - especially if the bidder is forced to up the price, which I think would be maybe 130p+ ?
Or will the instis be happier with a liquidity event, at a lower price? Who knows. I bet there's all sorts of negotiations going on behind closed doors with the big holders.
The nice thing with FIF is that medium term holders should do well either way, as it's a nice business, and cheap at the current price.
Will be fascinating to see how it pans out! Risk:Reward is just so good at the moment, for investors with balls, and some patience. I cannot remember things being this good, ever actually, in my investing lifetime.
Regards, Paul.
Some small cap sell off continues today or at least the ones I look at
Inspecs (LON:SPEC) another looking cheaper by the day. Last update was robust. Debt prerty low and being paid down slightly. Not immune to recession but must be getting priced in at these levels. Any reader thoughts?
Hargreaves Services (LON:HSP) inline statement today. Expectations reiterated after strong start to FY24.
Singer note. House Broker.
"Our sum of the parts valuation underpins a 770p TP (almost double the current price) making this a high conviction Buy idea."
I hold SCS (LON:SCS) and was thinking of selling out shortly after the ex-dividend date as there may still be plenty of bargains to be had with the proceeds and having to wait until the first quarter of 2024 or perhaps even later is putting strain on my patience. Then I come across this:
Now of course a takeover bid is always made with an eye to a bargain, will a competitor come in with a better offer? What do other Stocko members think?
Silver
...I dunno about a new bid...but what does strike me re SCS (LON:SCS) is that today's prelims would likely have taken the shares down a decent notch given the October sales cliff...
Thanks for your view mojo, and there is still time for me to make my mind up.
No worries Silver Moon…it’s not really a view, rather I’m pointing out dissonance. IMO dissonance is the only driver of prices..,but I’ll save you all from my dissonance theory of markets
I want to hear it
Agree think the bid is far too low ....they're paying c£100m for a company with c£70m cash sitting on the balance sheet so a bit of steal imho. Whether there are any other interested parties out there that's the $64k question. Even if not hopefully the institutional shareholders can force a higher bid price.
The bid was recommended by the board but not endorsed with irrevocable backing from any of the major holders so it would be easy for a counter bid at say 10% above the current bid. Also the cash on the balance sheet makes it easy to include a bid with a little leverage and repay from the money on the balance sheet.
Hi Silver Moon,
What's the source of your graphic please? Source is everything! Anyone could knock up a graphic like that, we need to know who prepared it, and what their credentials, and method of calculation are.
Thanks, Paul.
Right Paul, the answer is Simply Wall St, the site I find complimentary to Stocko. Also, it has as many virtual portfolios as I could wish for.
I tried Simply Wall Street and even for the top package it says only "5 Portfolio, Unlimited Holdings". I'd like more than the 10 folios Stocko give you but with at least 50 stocks in each one but haven't found another vendor yet yet.
Hi Funnymoney, I am talking virual portfolios and the means to further education. Simply is ambitious and is hoping for more PI support in that it wants to link its members real portfolios with the that member's stockbroker account. Now there is food for thought! Anyway, I can show you what I've got, below:
Some may remember my thread from when I set up The Big Dipper, it was supposed to be titled Riding the Big Dipper and what a ride it has been though not so hilarious as the Footsie All Share Index for the year to date. At present its performance stands at minus 2.81% which is a lot better than my real portfolio. FYI, forgetting Lookers, BAE Systems has been the best closely followed by Mitie but everything hinges on the purchase price. Buy Low Sell High,
Silver
I run more than half a dozen virtual portfolios, to me they are vital. Every now and then something from the past looks interesting again, on ii.
Thanks for that. By using the watchlists I can get to 10 "portfolios" in addition to what is on Stocko. I do really like that on Stocko you can tab through full screen charts (or any other 'view' (Stock Report, Director Deals etc.) with one click. I would much prefer to stay in just one place. Plus the fact that you can annotate charts so you can easily remember why you put the thing in the folio in the first place! If I haven't done that I have to start all over again as usually I have completely forgotten why I was interested in something.
I sell half
This must have updated from todays results as it now shows fair value at £.193, well within the offer price.
As someone has said, todays results would have dropped the SP.
I can’t help but wonder if the delay to publishing the results was somehow linked to this offer?
US BIG TECH. NVDA (Nvidia) to challenge intel with Arm-based chips for PCs. They are aiming to have something in 2025.
https://www.youtube.com/watch?...
Meanwhile, Intel is getting heavily involved in RISC-V. RISC-V is an open-source architecture that competes in the same arena as Arm. Arm is by far the more mature one, but great strides are being made with RISC-V. Miscrosoft are developing Windows for Arm. It seems to be early days, though, so don't expect to see Windows on Arm processors Real Soon Now (TM). I'm not aware of any public announcements that Micosoft has made to make Windows available on RISC-V.
A big problem with Arm is that there is no standard ecosystem. Every device has their own unique way of doing things, making it much more difficult to operate on. This is in contrast to what's available using Intel x86 chips, where things are much more standardised. Apple has moved into using Arm. It controls all aspects of the design, though, so it does not have this problem.
RISC-V is likely to have at least as many problems with fragmentation as Arm.
Still on the subject of AI, if you're in the mood for a bit of hilarity, check out "AI Olympics - 100m Race"
https://www.youtube.com/watch?...
PATRICK BOYLE. A general YouTube finance channel that I found recently is run by Patrick Boyle:
https://www.youtube.com/@PBoyle
He has created many interesting videos, and is well worth checking out.
CHINA. I talked about China a few days ago, so perhaps I'll single out his video "China's International Debt Crisis":
https://www.youtube.com/watch?...
His other videos discuss other interesting topics, so have a look at what else he has to say. At around 12:00 he says, pretty much as I have argued previously, that Chinese infrastructure spending both domestically and abroad over the last 20 years has been malinvestment. This is capital-destructive and why I have been warning that the risks to the Chinese economy are potentially much much worse than many people may think.
EXPN Just a little catch-up with Experian. The share price is up nearly 2% at 9:30 to 2459p. Shares were up less than 0.5% in early trading, which surprised me as to how tame that was. There was heavy volume yesterday, so maybe some fund manager dumping? We may not get a disclosure. Compare that with March 30 of this year, where there was heavy volume and the price went up. It seems reasonable to suppose that one of Train's trusts was doing a lot of buying on that day, as I saw a YouTube video from April where he said he had been buying. Interesting stuff.
Thanks Mark for mentioning Experian (LON:EXPN) (and the pointers to Tech news. I couldn't believe the sudden drop (approaching 10%) yesterday afternoon when I checked my holding today and considered selling on the assumption that there had been some sort of disaster (like a hack...). Not a small cap I know but here is the only place I know where we might hear something.
You're welcome. Sometimes not all regulatory releases are announced by all sources, so the occasional one can slip through the net. But I'm pretty sure there's no RNS out, and there's no news release that points to any problem as far as I can see. I've looked.
I'm not sure if you saw my little discussion of EXPN in the SCVR yesterday. It seems that EXPN is falling in sympathy with TRU (TransUnion), which fell around 25% yesterday. TRU's numbers seemed a little below estimates, the reaction was savage. I don't know about TRU, but I heard that it wasn't as good an agency as EXPN.
There was a lot of volume in EXPN yesterday, so I can only assume that someone wanted out for whatever reason. Pfft, who knows what traders are doing behind the scene. Seems like it might be more technical than fundamental. But I know squiddly about technical analysis.
Nick Train seemed to like adding to these back in late March, so you're in good company.
I'm also hoping its more technical than fundamental. Thinking back as to why I bought it (as in Ed Croft's blog about avoiding losses to see when "the story has changed"), it was because much of its earnings derive from the U.S.; maybe that makes it more susceptible to falling in sympathy with TransUnion (NYQ:TRU) as you suggest. That would tie in with it falling in the P.M. our time (once they woke up over there)? So we shall see what happens later (the mood doesn't seem positive over there today)...
Experian (LON:EXPN)
Yesterday's 10% drop was attributed to a readacross from rival TransUnion (NYQ:TRU) which dropped 25% on Q3 results that included a downward guidance for the full year and a $495m impairment on UK operations.
https://investors.transunion.c...
I think the reaction with EXPN overlooked the fact that TRU is much more concentrated on the US and that while the US and UK markets may be a little slow at the moment it is the Brazil operation that is expected to fuel growth for EXPN.
[Not quite one of Paul's mystery shops but I question the quality of TRU - I have a very good credit score from EXPN but not so good from TRU because they say I have only lived here for 2 years whereas I have been here for decades!]
Ha ha. It seems that I'm getting fairly consistent views that TRU is a rubbish version of EXPN both in terms of trading and its financials. Thanks for the news release. That $400m loss it made for the quarter sure wouldn't have helped.
So, I've received a bit of an education in credit agencies over the last couple of days.
Oo, just a little update. I discovered that TRU had a data breach about a month ago. https://securityaffairs.com/15... So thumbs down to TRU.
Following on from last weeks discussion on Instem (LON:INS) and potential special opportunities that are there for us private investors.
NB Global Monthly Income Fund (LON:NBMI) has released two RNS's this morning
1. It goes ex-dividend on 03 Nov 2023 with a payout of 2.1p
2. It completes the next partial redemption for 40.86% of your holding on 13 Nov 2023 for 80.77p
Currently the price is showing on Stocko to buy at 75.23p which matches what I am offered on AJ Bell.
Good luck
Tommy
ps. I hold NB Global Monthly Income Fund (LON:NBMI) in Mum's ISA
Relentless drift at Jupiter Fund Management (LON:JUP) continues. Wonder if a large holder is dumping or is a divi cut on the way? Views appreciated, tia
Jupiter Fund Management (LON:JUP) As long as forecast earnings keep falling its likely the share price will also fall. It would be defying gravity to rally against forecasts in such a weak market.
But WoSS there comes a point, across the whole sectoral peer group, where its just oversold and all the anticipated bad news is in the valuations? And Bouden54 is also right that it becomes a crude geared play versus medium-term market recovery.
Identifying that precise point is of course the challenge and best understood in hindsight.
Comparing Jupiter Fund Management (LON:JUP) to Liontrust Asset Management (LON:LIO) and Premier Miton (LON:PMI) (all pretty similar companies, with similarly mixed performance across their fund range and seeing outflows) - all down by similar amount YTD, although Jupiter has seen a shaper fall in the last month - perhaps it's just a case of Jupiter catching up with the others?
Perhaps the 3 of them could merge - they could cut out a lot of costs by merging all the duplicate funds and remove some of the very expensive fund managers (still no idea why fund management is such as well paid profession)
According to the trade press Jupiter Fund Management (LON:JUP) was hit yesterday as they held tad over 1% of Cab Payments Holdings (LON:CABP) , as an aside Paul/Graham any chance of a delve into RWS Holdings (LON:RWS) it comes up on one of my Garp screens and was a darling of small cap fund managers a while back I seem to remember chatting to Keith Ashford-Lloyd about it several years ago.
Yes, RWS Holdings (LON:RWS) is on our to do list, see agenda above. I'm working on it now.
any chance Paul please of having a look at SCT?
Hi alison,
We don't cover Softcat (LON:SCT) I'm afraid, as the market cap is £2.5bn, well above our usual upper limit of £1bn (see explanatory notes in every article). I only tend to break our arbitrary £1bn market cap rule, if something especially interesting crops up.
Curiosity got the better of me, so taking a very quick look at FY 7/2023 Results (issued yesterday), they look good - revenue down, but profit slightly up. Good profit margin. Special divi on top or normal. Outlook sounds positive. Balance sheet looks OK £244m NTAV, but very high receivables so I suspect a lot of pass-through revenues there? Net cash, so financing looks OK.
This looks a nice business, but is it worth £2.5bn? Not to me, no. As you can see below, the valuation metrics are punchy, so in a bear market I think there are probably better bargains elsewhere.
Market keeps falling and fund managers are a geared play on the market. Don't think there's much more to it than that really.
Pfft, I don't know. I do see on the analyst consensus chart that 2024 estimates have been downgraded a little recently. So it probably won't help. It's a member of the FTSE250 index, so maybe (pure speculation) that's not helping either.
Isn't there some regulatory cloud hanging over the industry at the moment? Something to do with exit fees. I'm not sure if, or to what extent, it would affect JUP.
PBV is 0.47, so it does look cheap to me.
I guess that's the frustrating thing about value shares. Things can go down and down and you never know where the bottom is. A lot of the time being early is indistinguishable from being wrong.
I'm going to look at the indices at the end of the year. The FTSE250 looks like it will have 2 years of losses in a row. The FTSE100 might, but we don't know yet. I seem to recall only once in the last 20 years we've had two years of losses. If they're both down, then the betting would be that 2024 will be a bumper year.
Or not.
hi Mark
A lot of the time being early is indistinguishable from being wrong.
An excellent point which I hadn't previously considered.
Especially valid for my holding in Headlam (LON:HEAD)
Snazzy
Jupiter Fund Management (LON:JUP) I wondered if I had read the balance sheet correctly, but looks like net cash is similar to current market cap? Not sure what that cash would entail? Would it be a TO target?
I particularly like it when a share you own has suffered a massive drop and you're hovering over Stockopedia waiting for Paul's verdict. And you wait and wait. And then it hits the stop loss and that's it. You're out. And then Paul's update appears telling you why you shouldn't have worried and sold.
Purely hypothetical...
RWS Holdings (LON:RWS) ?! I had to re-read before I realised what they were trying to tell me - 7.00 am is too early to be thinking! It's a micro position for me so still swayed by the director buys, PE, div. I don't know whether the study on profit warnings which Stocko did covers things like this? The announcement intimates that the first half was down but long term prospects are good.
I think this is an interesting case as regards whether to set automatic stop losses (see the recent Stocko article).
Hi Badgersbrook,
And then Paul's update appears telling you why you shouldn't have worried and sold.
That's not what we're doing here. We just look at each individual situation, and try to give a realistic assessment of risk:reward. Sometimes that will be right, sometimes wrong, as we can't predict the future.
The buy/sell decisions have to be very firmly under your control, our views definitely shouldn't be driving that process, maybe just part of the mix, forming part of your research perhaps. It's peoples' own individual insights that often determine success or failure, our analysis of the numbers is only a part of that.
Paul.
Any followers of Midwich (LON:MIDW) ? 12m rolling fcst of p/e 10, PEG 0.7, yield 4%
Outlook from last update on 5th Sept:
"With order books remaining healthy despite the broader challenging market conditions, the Board expects the momentum seen in H1 2023 to continue throughout the remainder of the year. As a result, the Board continues to expect trading performance for the full year to be in line with its previous expectations."
Director buys recently of £220k
The AV market seems to be relatively buoyant- my business is partly in the AV space. Looks like Video conferencing is still a strong market and Midwich have some strong brands. As I recall they are expanding in the US- I understand a couple of years ago they were looking at other UK acquisitions in the UK market but pulled out.
hi eParo
Midwich (LON:MIDW)
Cockney rebel is keen on this one. See his recent write up at https://cockneyrebel.substack....
I can see the attractions here but on balance I don't like the potential risks due to:
One to just watch from the sidelines.
Snazzy
Midwich (LON:MIDW)
.....and we can add falling ROCE for the past few years (32.3% down to 12.8% in 2022).
Hargreaves Services (LON:HSP) Another company in which the astute Mr Mills has a significant holding. His son, Nicholas is on the board. Trading in line on miserly metrics with no bank debt and at a significant discount to NAV, what's not to like, although I suspect that Mr Market will be completely disinterested.
I hold and am happy to add at current levels. On the matter of share price weakness, I suspect that concern over the company's participation on the now abandoned Birmingham-Manchester HS2 link played a part. This has now been dispelled.
Just goes to show as Peter Lynch stresses one needs to act on the facts and avoid speculation. Regarding the latter I would add that readers have as much idea where inflation or interest rates will be at the year end as Andrew Bailey!
Oxford Metrics (LON:OMG) - while the value of their cash pile has been eroded by inflation if they chose to spend it on the common basket of goods used to measure CPI, it is earmarked for an acquisition and, given how valuations of targets have significantly contracted over the last year, I would argue that it's value has, thereby, potentially increased. Only, of course, if they deploy it while valuations are depressed! They are certainly taking their time over this which can either be regarded as a good thing if you believe they will deploy it at precisely the right moment or a bad thing if you think it provides evidence that they are indecisive.
As their CFO has said that he doesn't want to take any risks with the cash pile and also wats it to be readily available to deploy on an acquisition, we may find that interest income is significantly less than you have suggested.
Thanks mammyoko, that's a great point re price of company acquisitions possibly being lower now for Oxford Metrics (LON:OMG) . Thanks for pointing this out. I've just edited the main report to include your point (with a hat tip to you!)
Although my point about earnings being inflated by interest income (which may not be sustainable) is still important to bear in mind, as EPS could potentially fall if central banks begin easing interest rates, where finance income could be generating half of earnings.
Best wishes, Paul.
Having exited the property market last year and now living a nomadic lifestyle, I am keenly aware that the proceeds from the sale of my property are being eaten away by inflation - I do have to use some of the proceeds on consumer products (although I have managed to avoid all UK inflation by living this year in Turkey, Greece and Japan).
Every day I console myself with the thought that while are my current holdings have suffered (or, to look at it another way, become cheaper) but the cash that I have remaining on deposit is more valuable than it was when I liquidated last year!
Enjoy the break and don't worry .
Really good points and write-up Paul Scott and Mammyoko.
I looked at Oxford Metrics (LON:OMG) a week ago as there were many attractions - massive cash pile, high levels of growth, very low PE taking the cash pile of over £60m into account accumulated from selling the poorly performing part of the company for a knock-out price etc.
I preface the following bear points by pointing out did not buy in as I've learnt to be cautious on new companies and my portfolio is highly concentrated.
1. I do not understand the product well and will it endure?
2. Will they invest the cash wisely and what into, especially in light of the original CEO leaving in July. New CEO likely good and been at OMG for a long time but nevertheless new to the role.
3. Massive director selling after the sale of Yotta for £52m. Importantly, although the share price has fallen back since then, there have been no purchases. If you are keen on the prospects for your business and the share price has fallen significantly, a lack of buying does not inspire confidence.
4. OMG has been trading very well but is this spike or likely to continue?
Oxford Metrics (LON:OMG) Fair point on money being on deposit Mammyoko but even on 3 or 6 months they could be getting around 5% currently. Not to be sneezed at....
I looked at Oxford Metrics (LON:OMG) a little while ago and was surprised how little interest income they received in HI 23 , around £500,000 from memory which rather put me off as I thought this was a lost opportunity. Although this would depend on what sort of account they had the cash in and when interest was credited.
I looked at Oxford Metrics (LON:OMG) a little while ago and was surprised how little interest income they received in HI 23 , around £500,000 from memory which rather put me off as I thought this was a lost opportunity. Although this would depend on what sort of account they had the cash in and when interest was credited.
I've noticed a lot of comments like this over the past six months. I guess they are from people who are fully invested and not managing cash themselves, as I am (currently I am 25% cash) . The best interest rates are available only in short term bonds, gilts etc., and Interest on such products is not paid out on a monthly basis (normally at the end of the term only or every 6 months for gilts) so why on earth should any interest accrued show on the balance sheet in the short term? If the finance arm is switched on it should spread cash across a range of product maturities to meet the companies own cash flow requirements. You also need to bear in mind that the same instant access savings products paying competitive rates to consumers are not available to corporates.
This rings a bell. I have a feeling I might have talked to mgt, or heard on a webinar, or something, that Oxford Metrics (LON:OMG) wanted to keep the cash ready for acquisitions, so accepted a lower interest rate on short term cash deposits. That might have changed though in recent months? Sorry for vagueness, I'm not sure on this point, as we cover almost 600 companies here, so it's getting difficult to remember everything LOL!
The previous interim results presentation covered this a bit: OMG - Interim Results (09/06/23)
* 29:39 - interest on the cash? -> will take no risks, already get attractive rates but need flexibility for potential M&A
Also
* 26:37- share buy backs/special dividend? -> if can't find decent acquisition then would maybe consider tender offer
My morning smallcap tweet: Losing the will to spiv
Oxford Metrics (LON:OMG) Belluscura (LON:BELL) Creo Medical (LON:CREO) SCS (LON:SCS), IG Design (LON:IGR), Franchise Brands (LON:FRAN), Hargreaves Services (LON:HSP)
◄Oxford Metrics (OMG)► guides FY-Sep rev £44m and adj pretax £6.3m, both ahead of market expectations of £39.00m and £5.83m. Engineering and Life Sciences segments strong. [SP=81.1 Cap=106m]
◄Belluscura (BELL)► possible offer revised to 4 TMT Acquisition shares per 3 BELL. Implies value of 20.25p. "Both companies have completed confirmatory due diligence and expect to be in a position to announce a firm offer shortly, and by not later than 5.00 p.m. on 31 Oct." TMT cap only £4.7m! [SP=27.4 Cap=37m]
◄Creo Medical (CREO)► EU regulatory pathway now allows launch of Speedboat UltraSlim device c. 18 months ahead of schedule ie early 2024. [SP=33.16 Cap=120m]
◄ScS (SCS)► FY-July. Outlook: Q1 weakening: order intake up 2.7% in Aug, 0.3% in Sep and down 4.4% in Oct. Net cash £57m end Oct. [SP=271 Cap=92m]. I hold.
In line: IGR, FRAN, HSP
Oxford Metrics (LON:OMG) TU shows a 10% revenue and profit beat to guidance, record revenue. Cash some 60%+ of market cap and debt free. Must be due a rise this morning??
Would like to think this is a TO candidate also. New CEO
Oxford Metrics (LON:OMG) I would hope that they aren't a takeover target. I think much more value could be created for shareholders by them remaining independent as management have shown themselves to be canny acquirers of companies that they have subsequently sold for much higher prices.
If they use the cash balance to acquire companies in the future as well as they have done in the past, shareholders would get a far better payback than the 30% to 40% uplift from a takeover. That would, of course, take much longer.
In-line update from RWS Holdings (LON:RWS) this morning although some of the commentary sounded a little downbeat unsurprisingly I suppose.
On an unrelated company, I’m interested if anyone has views on Hargreaves Lansdown (LON:HL.) from an investment rather than customer perspective. On the face of it, the value here is excellent and I know that Graham was recently very positive on it. I also listened to Roland and Mark both making the bull case for it on their excellent PI podcast recently. I had built a decent position but I exited recently as momentum started to look terrible. I’ve been waiting to get back in but a catalyst for me to cut my losses was noticing that it had entered the top 5 most shorted UK shares with 5.5% short interest as of yesterday and the shorts are increasing their positions. I wonder if anyone can shed any light on what might be driving the negative conviction?
It looks superb value at the moment, increasing competition from low cost providers?
Regulators demanding they pay interest on cash balances to customers rather than keeping most of it as profits?
I’m at a loss on the drop in share price, other than that it has everything I’d look for in terms of an investment.
I am in a share discussion group and one of our group said he was modestly negative on HL saying that (1) there is pressure on pricing and (2) HL only discloses net client gains and not gross gains and gross churn numbers.
Since that discussion (and with his views in the back of my mind) I have listened to most of the HL analyst presentations on their website (starting with the 2022 CMD) and I was taken aback by the tone of some of the questions (given analysts are generally a fairly easy audience). A large percentage of the questions are referring to these concerns: how many clients are actively leaving the platform, what is the profile of clients leaving the platform, what percentage of departing clients cite cost as a reason etc etc. Management answers to these questions are quite evasive, IMHO.
HL is well behind all the operational targets set at the CMD, profit growth has come just from net interest margin ( NIM) of around 200bps on cash (not active savings). £268m of FY23’s £735m revenue came from NIM on cash balances - up from £50m in FY22. What multiple do you want to put on this source of profits as probably investors will reduce cash balances (outside active savings, where profit margins are only c20bps)?
I have been looking at HL as a possible investment. I can see the attractions - it is on a P/E of 10-11x in a growing sector, in which it is the market leader. But given my concerns above I have held off for the moment.
Michael Ulrich of JO Hambro talked about Hargreaves Lansdown (LON:HL.) here on Monday (starts 42;35).
&t=653s
You have to be a little careful with the interest margin which is nearly 200bp ... the mkt would appear to view this as unsustainable and explains some of the PE difference between say AJ Bell (LON:AJB) .....
Low P/E and a lot of money in the bank with a decent dividend of 6.73% indicated... what's not to like? My strategy would be buy some now and add as it drops or moves higher. The main issue is people are back at work and trading less?
Hargreaves Lansdown (LON:HL.) I hold.
It is a hard one. It depends what you value. My partner uses aj bell. I find the ajb interface v. clunky and the choice of funds restrictive. Not that hl is perfect. ajb is slightly cheaper. hl will pick up the phone if you need a human (about 1 in 5 years)
Hl try to add value but... ...they cannot advise or reccommend so not sure what value that is unless they come up with some mechanical system like stockos. If they did and it worked wouldnt the advantage be arbitraged away as they are mass market?
Personally ...
Margins will be under pressure.
They have lots of clients and data. Someone will work out a way of adding value or charging more.
Clients are sticky especially once tje sipp is in payment.
Underneath it all they get a % of all funds under management and if you think that will not be ok over the long term why are you on stocko?
'Hl try to add value'
I find their analysis of the shares that I hold with them very useful. Helpfully, they email me when a new analysis becomes available.
Is anyone else having trouble accessing Sharepad this morning?
I am having to use a different Browser from Chrome to login
Can’t access using Safari. Security certificate has expired
You can still get in via Safari - click on details and there's an option to ignore the expiry warning and access the site
Yes, Security certificate problem.
communication from Sharepad:
I can confirm that our system is currently encountering technical difficulties that may affect your ability to login.
Our dedicated team is actively working to restore full service. We sincerely apologise for any inconvenience this may cause and appreciate your patience during this time.
Yes Security Certificate expired yesterday
Spoiler Alert
I still remain very positive on UK smallcaps long term in light of their low valuations.
That said over the past 3-6 months, UK & US bank stocks have traded poorly - which suggests to me something big might well break again (re mini banking crisis in March/April) given the elevated interest rate regime.
Indeed I suspect yesterday's eye-watering 14.25% interest rate on Pressure Technologies (LON:PRES) 'bridging' loan, is a reflection that the transmission mechanism from UK lenders & other capital providers is broken.
Unexploded ordinance anyone (re balance sheets)?
The something big at the moment is clearly interest margins under pressure because of an increase in funding costs and/or unrealised balance sheet losses.
The thing is, how much of a surprise is this? Not earth shattering and given where we are....do we really need to worry too much? The Move index is at stress levels - 128 - but has fallen back a little. VIX got above 20 before this retreat. My point is we were already quite stressed....and therefore it has impacted values. It is possible that the response to the "something big" is more important than the event. In the Asian crisis we built up to something big....opened on a Monday ( I think?) down 6-7% but that was the catalyst to buy not sell / panic. By lunchtime it was over....
The sooner the long expected crisis begins the sooner it's over in my opinion. Good companies will still fall but they will bounce back rather quickly although I can't imagine the UK is top of anyones fire sale list - mainly because no-one has much to sell.
Great comments RDH. Thanks