Small Cap Value Report (Wed 27 Dec 2023) - WHI, ANIC, SDRY

Good morning from Paul, and I hope you enjoyed the Christmas break.
Not a great deal of news today, but a couple of companies caught my eye, and also you need a place to discuss the day's news - so if the UK market is open, I'll write an SCVR.
There's also a lot of new content coming in the next few days from other writers, so I'll flag up those articles here at the top of the SCVRs, in case you miss them.
Here's a terrific article from Roland, explaining how he's set up a simple stock screen to find good small cap shares - I recognise lots of the companies in this screen as being decent small caps that we also like here in the SCVR. Highly recommended article!
Housebuilders - could benefit from press reports that the Govt is likely to introduce new incentives for first-time buyers. That's all very well, but will they be in office long enough to implement these measures, and would a new Govt repeal or support them? Who can say?!
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. OR it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
WH Ireland (LON:WHI)
Unch 3.5p (£8m) - Interim Results (Sep 2023) - Paul - AMBER
Poor results from this small stockbroker, but note the strong cash balance relative to the market cap, after a £5m placing in the period, which greatly increased the share count -
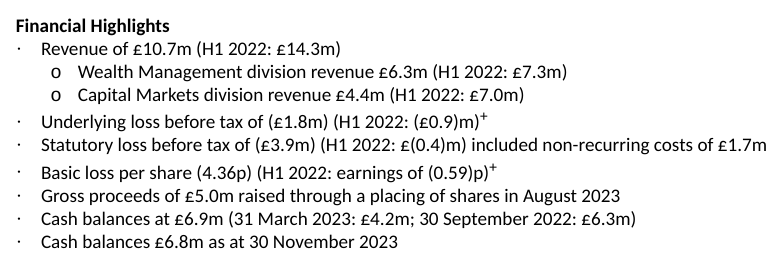
Cost savings - WHI has made deep cuts to its cost base, £3.8m annualised, including a large reduction in head count. Therefore this should benefit future periods, providing some upside on future profitability.
The £2.1m non-recurring costs are for redundancies, and project costs.
Tentative signs of improvement is noted in the commentary on recent trading.
Balance sheet - NTAV is level with the market cap, at £8.5m. Only minor lease liabilities, so no worries here about costly empty office space obligations.
Paul’s opinion - after an equity fundraise which has repaired the balance sheet, and deep cost cuts, WHI is probably looking more interesting now than it has for years. Historically it’s never really made any reliable profits though, and arguably there are too many smaller brokers still, with some merging (eg Cavendish from Finncap and Cenkos). Does that leave any room for a minnow like WHI?
I considered having a dabble here, for a rebound as the small caps space starts to come alive again, but taking everything into account, I’d probably be more inclined to punt on Cavendish Financial (LON:CAV) instead, which has a bit more scale, and has also done deep cost-cutting in its recent merger. Graham reported positively on CAV last week.
The liquidity in shares like these is very poor most of the time.
This whole sector is bombed out, and looks ripe for recovery, I think.
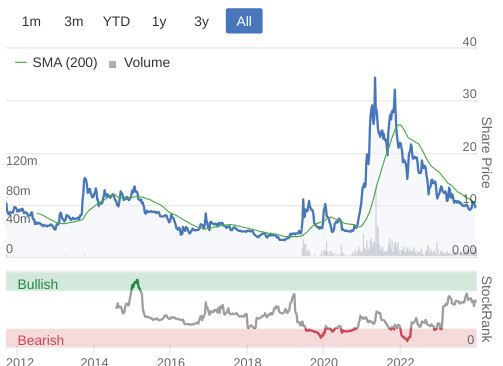
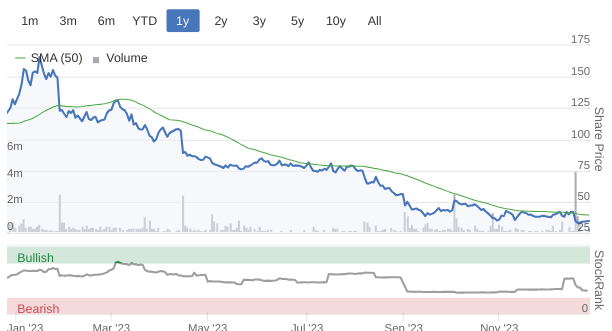
Note that the share count has roughly quadrupled recently, so it's unlikely to recover to previous highs on the chart when the share count was so much smaller, so not much point in drawing lines on this particular chart!
Agronomics (LON:ANIC)
Up 3% to 9.65p (£95m) - Final Results 6/2023 - Paul - AMBER
This is my first look at Agronomics, catching my eye on a quiet news day.
I think it’s quite interesting, and might be worth some deeper research, hence why I’ve decided to flag it.
This is an investment company connected to serial entrepreneur/investor, Jim Mellon (15.5% shareholder). It invests in a portfolio of “cellular agriculture” companies, such as lab-grown meat. So this share is a way to gain exposure to a portfolio of companies in that sector, without having to pick the investments ourselves. The hope being that amongst its portfolio, there might be one or more future stars. Obviously I can’t assess the prospects of the individual companies, and probably nor can you, so it’s maybe a bit of a punt? I heard Jim Mellon give a talk about new types of agriculture a while back, and he was very convincing.
The numbers out today show a big profit, which has come from marking up the valuations of its investments. That’s the worst kind of profit, as it’s notional, and completely dependent on the method used to value investee companies. I imagine these are loss-making and cash-burning ham tomorrow (geddit?!) projects, so some of them might turn out to be worthless, and others need repeated rounds of financing.
Note that shares are valued at £95m in total, whereas NTAV is much higher at £168m, so there’s an attractive discount to (possibly questionable) NTAV.
Paul’s opinion - on the briefest of looks, I can see some merit in having a small punt on this share, to get some exposure to what could be a huge growth area in future. I would never pay a premium for this type of share, but it’s now at a potentially attractive discount, so possibly worth a deeper dive, if you have time?
Do let me know what you think, if you’re already researched it.
EDIT: Very helpful additional points made by Mojomogoz here in the comments below - thank you!
Superdry (LON:SDRY)
Press reports originated in The Telegraph I believe, behind a paywall, and picked up here by Retail Gazette, indicate that it is in talks to dispose of more international brand rights, in the Middle East, and USA. It talks of "tens of millions" of potential cash receipts.
At about 36p share price (£34m market cap), SDRY shares are little more than an option on survival/turnaround. So it's probably going to be a zero, but if a miraculous turnaround is achieved, then it could be a multibagger.
The trouble with selling off international brand rights, is that the profits from those territories are then lost, making future trading results even more difficult.
I'm told that one broker has massively reduced FY 4/2024 forecast, to about £(45)m loss. The consensus (of 2 brokers) is now £(23)m, so maybe one broker has not updated yet, from the previous c. breakeven forecast, which has turned out to be wildly over-optimistic.
Paul's view - I've been very wary of this share for a long time, and maintain my RED stance. It's just for gamblers & traders now.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

77 comments
Agronomics (LON:ANIC) For individuals who may have an interest in Agronomics a new presentation has just been released: Agronomics presentation
I hold a position simply because it is rare to have an opportunity to gain some exposure to a new new industry at the venture capital stage.
All the best
Thanks for the heads up Paul Scott & Mojo regarding your insight into ANIC. Leopards don't change their spots!
Re Housing in 2024 - 25. I think the Builders and especially suppliers to construction (ie not just housebuilders will be very promising over next 2 years. Currently new builds are at multi-year lows and forecast to go down again next year - way below need level we need (whether we get more immigration or not!).
Infrastructure in areas from the water industry (sewage) to schools (RAAC) to tower blocks (cladding) to hospitals - almost all sectors are 'crumbling' and need repair, replacement or extending. The public will support 'investment' in these right now. Politically, Labour are also promising to bulldoze NIMBY's and will (rightly) shift the inter-generational balance back towards the young who really want more houses>
Furthermore, whilst it is said there will be 'no money' after the election that is never true: Govts can borrow, tax more or shift the tax burden. By taxing wealth, for example, they can realise money and not raise total tax even as they reduce or hold it for the young/lower income 'working families etc.
Construction also has a big domestic multiplier effect so will help get growth going (even if houses are really consumption items not investments!) so that'; so that's good for Labour too.
Housebuilders themselves are vulnerable here as they have arguably enjoyed excess returns in recent years (remember the Persimmon CEO) and will have lost the grip they have on the govt through political donations - they make start to give to Labour as they gave millions to Conservatives but probably to less effect. If they are 'forced' to 'build it or lose it' on land banks they will builkd even if asset values fall.....and construction suppliers like the brick companies will sell more and be able to protect their margins.
As ever, we will see!
A lot of credit understandably going to Paul and the other readers over the past few days. Just a little shout out to those working behind the scenes. Some of the new features on the site this year are great. I'm a particular fan of the daily and weekly leaderboard for most stocks. Its helpful insight to know what the community is focusing on. On that note, I notice Renold (LON:RNO) (I hold), is up in 2nd this week, I haven't noticed any news, did I miss something? Or are readers just being drawn to it's 100 stockrank maybe?
Renold (LON:RNO) is appearing in 6 screens now, so I think with that and positive commentary it's naturally drawing interest. Also note the increase in volume recently, a big tick for me especially as the share price continues to rise (I hold too!)
Renold (LON:RNO) looks a decent business in a specialist sector that I don’t think would be too adversely affected by a downturn + difficult for competitors to break in
Hello Paul - thanks for the comments on SDRY. You are spot on. Selling off IP to fund the ongoing cash losses. Perhaps they can sell IP in the Middle Eastern markets but I am doubtful if they will get much value in the USA as the brand may be seen as tired in that market which is more developed world/more competitive that the other territories they sold IP rights in previously which were emerging markets. Liberum (house broker) has not yet updated their forecasts; probably waiting for Xmas and New Year trading update before they do so. Peel Hunt downgraded sales from £590 to £506 for FY Apr 2024; Liberum were at £584m for FY Apr 2024. Cash losses are much worse that adjusted PBT as there are lots of impairments taken on property leases. Company is bleeding cash; sales down from £870m FY Apr 2019 (before COVID) to perhaps £500m FY Apr 2024; gross profit down circa 50% from £480m to c £260m FY Apr 2024. They are finding it hard to cut costs quick enough to rightsize the business. Wholesale revs were £335m in FY Apr 2019 and this year may be £115m - down by nearly 65%. I cannot understand why they do not do a CVA on UK stores.
Hi Paul merry Christmas, thank you for all the brilliant reports this year they have Been very helpful. I’ve been Following Agronomics for a while and feel they have quite and Interesting proposition. They are one of the only listed opportunities globally and the only one I believe London for small scale investors to participate in this space. They are not just solely focused on lab grown meat but have an incredibly diversified portfolio of companies. They have invested in a company such vitro labs that make leather. The top French and Italian fashion houses have already taken up all of their order capacity as the leather can be grown to any size and shape reducing waste and it also flawless because there are no natural damages to it such as cuts from barbed wire. They also invest in the picks and shovels of industry with liberation labs and their new precision fermentation factory in the USA which is looking to help with the chronic lack of capacity in sector. In their portfolio there’s lots more companies like this as they have set out to diversify themselves away from just meat and there are so many other opportunities.
In the last year this has moved away from science fiction and closer to reality as the FDA and USDA approved Upside foods and and Eat just with a no questions asked response. It will take time to get in commercialised but at least some of the government barriers have been passed.
I met Jim Mellon and the investment team behind Agronomics a couple of times at events and they really to have their finger on pulse of this sector. They were all incredibly knowledgeable not just in investment but the science behind the companies. There investment thesis seems to be an active investor with these companies. They sit on the board of many and look to invest in them all the way through there funding rounds and become helping hand the whole way.
Thank you for covering them today Paul hope you’ve had a lovely Christmas
Olly
Paul, thank you for writing the SCVR this week, and happy Christmas to you and all. Re. Agronomics (LON:ANIC), there have been some interesting comments from you and others on this today. I have some technical expertise on this area of R&D, so wanted to add my thoughts too. Agronomics (LON:ANIC) provides a diversified means of investing in cellular agriculture and there is a strong narrative for this approach around reducing environmental impacts and benefits for animal welfare. However, this is offset by the likely need to compete as a commodity and therefore on price (with maybe exceptions e.g. designer leather), the need for very large bioreactors with likely expensive cap-ex, and ultimately who is the target market. In terms of that target market, vegetarians and vegans often don't want to eat accurate meat substitutes even when made from plants. In other words, what might be regarded as the most committed part of the target market in terms of aligning with the environmental and welfare narrative, are unlikely to be interested. The price premium for other consumers will likely be the main challenge. In other words, I see technical (including scale-up), behavioural and price challenges, so it is in the too hard pile for me. I'm also reminded of Ed Crofts recent outputs on the traits of multibaggers, and the need to not have to invest pre-profitability and even before dividends are paid. I have previously invested in Benchmark Holdings (LON:BMK), which is involved in sustainable aquaculture; I still hold and like the business but wish I had waited longer before I invested.
Very interesting. Just from a personal aspect, my wife has been vegetarian for over 30 years & the last thing she wants to eat is lab based products made to look & taste like meat! I think this market is for those carnivores that want either a more sustainable product or are just curious to try. I seem to remember reading somewhere that Beyond Meat sales were disappointing, suggesting maybe a lack of interest after the initial excitement. On top of that, the meat substitute products are processed which is also a source of concern for the health conscious? Strangely enough, I did invest in ANIC several years ago & did ok but sold out for the reasons above. An interesting market all the same, will watch with interest.
It’s a bit of a Scroogelike comment but if Jim Mellon could invest as well as he talks he’d have retired long ago.
He has got the big US tech stocks completely and uttetly wrong.
Be wary of Jim Mellon. He is a very persuasive speaker. I used be in his thrall. Some of his listed companies have done badly. Speymill Deutsche Immobilien was a total bust for me despite being a Berlin property co.
Ditto Sefton Resources for me if anyone remembers that; however I worked out that my investment as a percentage of my net worth was similar to Jim Mellon. It was manageable for me, so I assume it was for him! Stockopedia suggests his shares in ANIC are worth $15m, he is worth around $1bn allegedly, in which case that's about 1.5% so if you buy, I would suggest that as a limit.
I am watching but do not hold. Apologies for any "mince pie arithmetic" in the above...
But it is your money that Jim was really after, I was a mug who was drawn in too.
Edit: Tendrils reaching everywhere, it's the dilution tool, stupid me. I hold Condor Gold (LON:CNR) and it bothers me.
On 5 December 2022, Condor Gold (AIM: CNR; TSX: COG) announced an update on the sale of its assets and a £1M investment by Condor's major shareholder, Galloway Limited, which is wholly owned by Burnbrae Group Limited which is, in turn, wholly owned by Jim Mellon, Condor's Chairman, by way of an exercise of warrants. The exercise of warrants will result in the issue of 6,666,667 new ordinary shares (Warrant Shares).
He is also a controlling shareholder, and has loaned a fair amount, to Webis Holding (LON:WEB) .No idea why as the company has gone nowehere for ages!Perhaps it's a pet project for him.They've been banging on about their US horseracing licence in California potentially being extremely valuable for ages with the roll out of online gambling licences in US states in the last few years.
My morning smallcap tweet: Clowns to the left of me, brokers to the right...
WH Ireland (LON:WHI) LMS Capital (LON:LMS) Eco Buildings (LON:ECOB) Mobile Streams (LON:MOS)
◄WH Ireland (WHI)► H1-Sept poor as expected.. Current trading and outlook: U/L monthly profitability achieved in Nov. £3.8m annualised cost savings. FY in line? [SP=3.88 Cap=9m]
◄LMS Capital (LMS)► sells minority interest in Medhost for $8.6m inc $1.6m deferred. $1.6m over book. [SP=23.93 Cap=19m]
◄Eco Buildings (ECOB)► Dominic Redfern has been suspended as Executive Vice Chairman pending further investigation. [SP=13.07 Cap=9m]
◄Mobile Streams (MOS)► FY-June.rev £1.8m (£1m). Pretax -£3.8m (-£2.5m). Could not find current trading. Material uncertainty going concern stmt. [SP=0.06 Cap=3m]
Hi Paul, glad your ignoring the edict from above that the SCVR is not required between Christmas and New Year.
In the latest of your always highly entertaining and informative podcasts you noted you bought a few Tortilla Mexican Grill (LON:MEX) recently. I'd be really interested in any further thoughts you have on this one if you have the time and inclination. (I hold a tiny amount also bought very recently from my "bit of reckless fun" fund)
On Beach group (LON:OTB) tipped by the Sunday Times
https://archive.ph/sWGtz
Burford Capital (LON:BUR) is up sharply today on news overnight that the Argentine President has said they want to pay the YPF judgment in full. It is a $16bn judgment, of which around $6bn is owed to BUR, and the company is accruing interest at the rate of around $1m/day. The shares hit £14 after they won the judgment, so it seems perverse they were on sale at £10.70 this morning after Argentina indicated the years of delaying and denial are over. The US market may take an even more positive view. I added this morning. It’s my largest position and I can see it hitting £30+ this year.
The company doesn’t talk about individual cases, but they had a public falling out with a client, Sysco, last year. It ended with Burford acquiring claims from Sysco that they had been funding. What is known is that the case concerns the fixing of meat prices in the US over an 8 year period. Sysco was the meat distributor and they were suing the suppliers. Price fixing is treated as racketeering in the US, and so is subject to triple damages, and all damages ore owed jointly and severally by all the defendants: in other words, you can go after any one for the lot. The defendants in this case include giants like Cargill. The best estimate is that this claim will be worth at least $6bn to Burford. With a current market cap of $3bn, those case alone would justify a huge uplift in the SP. But if you then start saying that such big cases are a natural outcome if the Burford process, what would a fair price be for the company?
"Milei suggested that the government would issue a bond without a fixed maturity while charging Argentines the “Kicillof tax,” named after Buenos Aires Governor Axel Kicillof who was the economy minister when the YPF lawsuit started." - https://www.bnnbloomberg.ca/ar...
I'm assuming the bond would go to the creditors. Otherwise Argentina would be better off negotiating a haircut on the sum owed and then issue a bond to pay that. Or maybe that's what he has in mind.
BUR would sell the bond if that happened, for a big haircut no doubt.
Burford Capital (LON:BUR) market cap is still only around half the value of their claim. Not to mention the underlying business itself, which should start to produce some big case wins this year. BUR was my best performing position last year but think it will have a lot further to go.
I'm sceptical personally of Burford Capital (LON:BUR) ability to get anything like value out of the settlement irrespective of Milei's current position.
Even if the bonds get issued they will trade way below par (probably distressed) and possibly in Argentinean peso so the debt gets heavily deflated away quickly given the high levels of inflation.
In that event perhaps expect Burford Capital (LON:BUR) to get maybe 20-30% recovery.
so trading at half the value of the claim is optimistic imo even with the rest of the business making up some of that value.
Remember, Burford Capital (LON:BUR) are a judgment debtor. They have a right to be paid in US dollars, and interest racking up at $1m a day until they are paid. They are not bond investors who have willingly assumed Argentine counterparts risk. They don't need to accept any bonds. Repsol did, but Repsol was under political pressure that doesn't apply to Burford.
The people I have spoken to who know international enforcement suspect Burford end up taking a haircut in the region of 10-20% maximum. There may be scope for creativity: if I was Argentina I'd be thinking of creating royalty bonds over the huge mineral wealth they are on the point of exploiting. But Argentina can only become the gas and lithium powerhouse it could be if it gets a lot of foreign investment. And that will be much cheaper if it pays its debts.
Burford Capital (LON:BUR)
They are not bond investors who have willingly assumed Argentine counterparts risk. They don't need to accept any bonds.
As per my prior post the argentinian pm has made it clear they simply dont have the money to pay this amount end of - thats the reality here.
If payment is to be made something like a bond offering or referred terms needs to come along. Its not like Argentina doesnt have history in defaulting on their obligations they do - and its time and time again. I think they have defaulted 9 times including 3 times in the last 20 years. In some respects i dont know why they arent defaulting again as they clearly dont have the money to pay.
Perhaps a positive spin would be a bond offering to get the funds now to pay pay the judgement - but one would have to be pretty mad to take on any of this "debt" imho.
Not a chance Donald imo. I've known Argentina for a very long time having traded its bonds professionally as far back as the 90's. People have short term memories and through that 30 year window have assumed leopards change their spots several times around debt repayments to no avail, so beware. The same goes for so called "international enforcement" experts who have generally consistently misunderstood the Argentinian effect (much in the same way they misunderstood Russia). And as for becoming a gas / lithium powerhouse - that has been going on for decades too (at least the oil/gas bit has).
Whilst the judgement is in $'s Argentina are never going to pay it in $'s in my view. they don't have access to that kind of money. They may well issue bonds, but the market isn't open to them to issue bonds in foreign currency as no-one will take them, and with the economic instability domestically (inflation and currency effect) it would be a catastrophe for the country to try and do so. History is not on their side here.
So the best thing they could do is issue bonds in Peso where they can deflate the debt effect, and there is something of a market (tho I seriously doubt $16bn worth). If Burford don't take a large chunk of them and sell locally at a discount then it probably won't happen at all. The alternative is this proposed Kicillof tax - do you have any idea how unpopular this will be in Argentina : locals having to pay a tax in USD when their own currency is devaluing and most are struggling? Most won't / can't pay. It will almost certainly be a failure imo, so would then have to be set at such a low level Burford will be getting a dribble of USD payments. Then Milei will get kicked out in a few short years as the next opposition leader will promise a reversal.
So by all means believe that Argentina will merrily pay more than 50% to Burford in the next decade but I'd be amazed if that happened. Then discount that back and work out the value of the rest of the business and is it really worth the current market cap? And how long will you have to wait versus the opportunity cost of not being invested elsewhere to really get anything?
I'd say the reality is that the talk will remain constructive whilst the action will be thin, watered down and long drawn out. We are not talking about a well financed country here, nor one that has a history of being able to honour its debt despite any good intentions, let alone pay that kind of repatriation from an international court.
Anyway all of this is just my opinion of course. I do not own Burford Capital (LON:BUR) and would not go anywhere near it at this kind of valuation. I do like the litigation space though and much prefer Litigation Capital Management (LON:LIT) which, I do own for what it's worth and consider much more reasonably priced.
Burford Capital (LON:BUR)
here is the text i could find.
his quote (Milei)
There is a problem here because we don't have the money. We do not have 16 billion dollars to pay. That is the reality. But we do have the willingness to pay.....one of the ideas we are working on is to create..... something called the Kicillof tax and that we Argentines have to pay a certain amount of dollars every year thanks to the monstrous error that Kicillof committed. .....You are going to have a new tax called the Kicillof Tax."
you may say they want to pay - but clearly at the same time he is also saying they dont have the money to pay.
https://twitter.com/alexbosser...
ref issuing bonds as an option - is anyone going to trust the argentinian government enough not to default on this bond later ?
I think that one scenario is Burford Capital (LON:BUR) finding a Sovereign Wealth Fund (SWF) that isn't subject to the commercial pressures (time, accounting, politics etc) that BUR itself faces and would take Argentina risk in pursuit of longer term not-necessarily-purely financial returns.
Take on Argentina debt for influence or a stake in the vast natural resources that the country has, for example : the Arabian Gulf has several SWF's who have a strategic interest in agriculture; an historic interest/expertise in hydrocarbons/petrochemicals; a current interest in 'green' technology; an economic /political interest in de-dollarisation and encouraging south-south trade. Argentina, along with Saudi and the UAE has recently joined the BRICS group, which is so far more an aspiration than a reality.
Some kind of a deal might tick a lot of boxes for an SWF investment committee, whether it be the one already working with BUR (identity unknown) or a.n.other.
The right deal would attract enormous publicity/kudos and could also - incidentally - be very profitable, which wouldn't harm its chances with the decision-makers...or (in the case of some of the Gulf SWF's ) the decision-maker.
I hold.
AFAICS/IMO etc etc
Burford Capital (LON:BUR)
Ref wanting sovereign wealth funds to get involved - does the fact they and private equity arent involved now not tell you something? Seems wishful thinking wanting something other than positive free cashflow from your investment to do the job with regard to an investment. I dont think any of us know whether burford is a good investment or not but we do know up to now it has burned cash and had historic accounting issues and has recently been on radar of sec (clean bill of health for now?) and been on the radar of peeps betting against the company being a good investment.
if this is a real business though that can convert sales to cash then at some stage the proof of the pudding should out - looks like sales are expected to materially decline next year so that might be time at which cashflow perhaps starts to improve if they can deliver.
One question what is the hit to burford if Argentina completely defaults on paying a penny back here ? - eg if they simply fully default on all debts and reset the clock as they have I think done many times before? I kind of see what option would be more popular to your average Argentinian voter if there is an option to simply not force them to pick up the tab here long term.
Is anyone looking at PFC?…..it’s still
Anyone know if NTQ- Enteq Technologies qualifies for Aim Inheritance Tax relief?
Badger1 you just need to go onto the LSE website which confirms that is is AIM
Enteq Technologies (LON:NTQ)
Hi Badger1 - being AIM, that's the 1st hurdle for BPR/AIM IHT relief. Then you need to convince yourself that it doesn't fall within any of the exemptions - not obviously to me.
There is no definite list. Investors Champion have a service giving their opinion, which seems to err on the side of caution.
At probate for my mother a couple of years ago, I was pleasantly surprised that we received 100% relief on all my mother's AIM investments
Re Agronomics (LON:ANIC) , always been curious and today read AR for first time. They likely need to raise cash (either placing or selling part/whole of an investment) as most (all?) their investments are pre profit plus many (most?) pre revenue in a significant way. So its likely that ANIC needs to keep putting in cash to support its investments today both in operational and a valuation sense (the latter as if they don't participate fully in future rounds its likely that the new capital will only participate on basis that sees old non participating capital squeezed down...regardless of what current legals say!).
More worrying is that payments for investment services are a bit opaque. The accounts say ANIC has no employees. The company website implies there are 4 people in ops team (ie the investment team). They do not receive any compensation according to literal reading of accounts...but I'd guess the £900k of 'sundry expenses' in note 4 other operating costs is significantly their compensation? This investment team is rather minimally experienced for the task they face IMO.
Directors Jim Mellon and Denham Eke own Shellbay Investments Limited. Shellbay receives 15% pa of any NAV per share increase. This year that 15% is worth £3.35m and Shellbay/Jim will take half of that in cash. Given that money's tight that seems a bad choice and the company can 'elect' to pay in shares if it wishes...ie Jim can say no to cash from the company he is chair of. Jim also owns 15% of the company...so double dipping his investors in way that would make a hedge fund manager proud. Jim's a rich guy so I'd assume he doesn't need the money. If he truly believed in ANIC he'd want the shares too and build his stake more. Taking cash doesn't make much sense...unless you aren't that confident in the current investments?
Its not clear to me why Shellbay (Jim and Denham) should get 15% off the top like that. Are they cellular biology experts? (no obvs) 15% performance fees is very very rich for providing 'deal know how' on venture investments that may or may not be worth anything.
Kudos to Jim though. He's designed a heads I win, tails you lose vehicle
(PS I'm not going to go down the rabbit hole here but there are many ways that the NAV per share can be goosed with early stage and pre profit venture companies)
https://x.com/mojomogoz/status...
Hi Mojo, thanks for that extra detail on Agronomics (LON:ANIC) - I was wondering what the Shellbay reference in the commentary was. It does sound rather unpleasant. That jogged my memory about another Jim Mellon that I got involved with years ago - I think it was called Speymill Deutsche, which owned a lot of dirt cheap buy to let residential property in Germany. They ran into trouble with bank debt in the credit crunch, and in the end Mellon walked off with all the assets, and I think from memory shareholders were hung out to dry. So we definitely need to check all the detailed arrangements before investing in any Mellon vehicles.
No worries... and I'm not expert and hoping for someone more knowledgable on company (Agronomics (LON:ANIC) ) to maybe put me right...
Definitely one for hanging investors out to dry.
I’ve been saying this for a long time, but Superdry (LON:SDRY) is a dead brand with no future. Nobody who currently matters is wearing it. The kids won’t touch it. The shops are full of stock that nobody wants. The stores are empty. Any positives? None that I can find. Bargepole.
LordGnome, I find that men of a certain age like the Superdry stuff. Two of my friends in the 45-55 age category wear it all the time and it's all they want from Santa, so I suggest that they don't sell the Lapland licence as part of their global licensing deals!
LoL Bristolian. Spot on with the age range. The people who grew up with David Beckham!
Happy Christmas all. Thanks to Paul, Graham and Roland for all their excellent work here and everyone else at Stockopedia for the brilliant content. It's a great community and well worth paying our subscriptions for.
It looks a very quiet day as usual at this time of year. The only real interest in the market this week is whether or not the S&P500 hits an all-time high or drops back at this point of chart resistance.
I’m watching this very closely topvest.
S&p has been rallying for some time now and looks to be extended / overbought. I have a feeling we’ll get a sharp new year sell off as we re-test the all time highs, so I’m looking for a possible short of the index around that 4800 area.
Very cautious about adding new longs until this area is resolved.
Yes, Breakout Trader, it will be interesting to see what happens. No idea short-term which way it will go.
Long-term the US is overvalued.
An interesting fact....Apple individually has a larger market capitalization than the entire UK stock market, France or China!
i.e Apple > the whole of listed China.....how can that be? It makes absolutely no sense to me. It's not even growing its revenue line!
Long-term the US is overvalued.
Long term the US market was not dominated by exponentially-growing, huge return-generating companies earning massive cash flows off relatively tiny asset bases. It's a different world today. I don't find the market exactly cheap today. And Apple looks overpriced to me too. But it always does and eventually last year's price ends up looking good value - you just didn't realise it at the time.
However, Alphabet and Meta ARE cheap today. What is more, even supposedly expensive Nvidia IS cheap, for the growth rate - and not just relative to its own history, but compared to its major competitors. I recommend the curious to ignore the headlines about its apparently extended run and do some research on the fundamentals.
Happy Christmas, Paul. And to all thread participants. Thank you, and to Graham and colleagues of course, for your prolific output through the year. After a year in which my heavily growth- and quality-focused fund prospered, I’ve been researching a little lower down the market cap and quality scale to rotate some cyclical (relative) winners into laggards. Balance sheet investigation isn’t as high a priority at the quality end of the market, and I’ve found your daily analysis of balance sheet risk and value across a multitude of names extremely interesting and educational as I take tentative steps down the quality ladder. Hopefully it’s helped me pick some good names and I look forward to posting about my additions when the positions are completed in the new year.
And hello from my wife, who is a big fan. As am I, of course.
Happy market back open day everyone!
Talking podcasts, did you listen to Justin's Christmas podcast on the 15th Paul? They have Plexus Holdings (LON:POS) down as a pump pretty much.
Are you still as confident in its potential?
Who is Justin?
hi Rusty2
Justin is Justin Waite. I find him very shouty and rampy and not an easy listen. I'd take it all with a huge pinch of salt.
The podcast is on Vox Markets with Paul Hill.
If you want to listen the link is https://www.voxmarkets.co.uk/m...
Snazzy
Oh him. Not keen on his style, I do find him difficult to listen to.
Do people really take any notice of his opinions?
Agreed. In their joint sessions, he just interrupts the more sober Paul Hill - which itself is saying something - constantly
Hi NewInvestor1972,
Re Plexus Holdings (LON:POS) - "Are you still as confident in its potential?" - of course! I do my own thorough research, and make my own judgements. I listen to opposing views, but unless they can disprove any of the facts, then it would't make any difference to me whatsoever.
I have to be in a particular mood to want to listen to Justin's podcasts.
Justin Waite
Yes very rampy and talks up his own holdings all the time, real pump and dump merchant who changes his “convictions” at the drop of a hat.
Can be entertaining but really just pumped up a lot of dross in the bull market mania when everyone became a stock picker to follow.
Was a big ramper of Gfinity, Polarean and other companies built on nothing more than smoke , mirrors , vapour and fumes .
Doesn’t take too much to unpick through his drivel and occasionally there is good infornation but as Paul says you need to be in the mood.
I am sure that Justin is a nice fella but I can only listen to him in small doses. To be fair I used to listen to all sorts of dodgy podcasts but over time I have hopefully become more choosy and tend to limit myself to ones I know are independent and intelligent. I listen to Tom Winnifriths bearcast but he does tend to become a bit obsessed with certain companies (bear and bull). So you have to be aware of that. I enjoy Pauls SCVR of course and Paul Hill is also a good listen. It's all a big learning curve! ATB and happy new year all!
To be fair to Justin he’s a very hard worker and seemingly never stops looking for opportunities, he covered the change in management at Destiny Pharma (LON:DEST) very early on this year and he’s was bang on about that. My biggest winner of the year, so I’m singing his praises. As ever it’s down to your own research, risk tolerance and investment technique.
Morning Paul thanks for opening up this morning. At least 4 days of silence gives us a chance to do some research and I found Enteq Technologies (LON:NTQ) which has acquired some drilling tech from Shell (LON:SHEL) and opened offices in Texas and Aberdeen to promote and sell the product. Could be timely and they do have sufficient cash for 2024.lets hope they have a brilliant sales team.
I noticed they were at mello recently and wondered whether anyone had seen the presentation and how it came across as I haven’t found a Recording. I remember you mentioned them in one of your podcasts.
I bought some today as a punt. Cheers
Hi richardho,
I've looked into Enteq Technologies (LON:NTQ) and concluded that it looks a potentially interesting project (steerable drill bits for oil & gas sector), but it's too early stage for me to want to invest any meaningful amounts in it. I've just taken a small position so it's higher up on my list for newsflow.
The CEO was at Mello, and was mingling at the bar, so a group of us had a decent chat with him. He reckons there's strong potential customer demand for their innovative product. I'm waiting for firm orders. With this type of share, I need to see clear signs of market demand, and decent margins. At the moment we have no way of knowing if the product will sell or not, so too early stage for me.
Enteq's CEO seemed a sensible chap though, and I thought gave honest answers. Obviously they're trying to stimulate some investor interest in the shares, hence coming to Mello.
Regards, Paul.
Thanks for your comments Paul
Happy new year
Good Morning All, would anyone know why Argo Blockchain (ARB) is up today? Thanks.
Argo Blockchain (LON:ARB) probably best to look on advfn to get more info about this one.
Looks like excitement about the possible bitcoin etf that could happen in America. The cryptoboys are hoping that brings loads more money into the field. If that happens then crypto miners could be a good place to be.
Thank you very much!
Crypto = Bargepole
Hi Desanj
All Bitcoin miners listed in the US have gone up in the last month (Stronghold Digital Mining (NMQ:SDIG) Bitfarms (NMQ:BITF) LM Funding America (NAQ:LMFA) as expectations are that Bitcoin ETFs will be approved by the 10th of January.
I do not hold.
Thanks
Thank you!
What I don't get is how a btc etf can work.
A ft100 etf works by buying/selling stocks in the underlying index. Generally ft100 stocks do not change a lot and there are deep liquid markets.
A btc etf works by holding btc and transaction costs can be large. Volatility can be high. Not sure what correlates with btc.
I can only assume that they will be similar to Gold ETFs but I am not sure if they will be approved. Recent price movement of Bitcoin and Bitcoin miners suggest that they will be approved. Who knows?
If ETFs are approved though and the upcoming halving in 2024 will drive the price of Bitcoin much higher.
I do not hold Bitcoin as I do not understand it , but something that will at some point have limited supply (21m Bitcoins by 2040) , and , if demand surges then the price will go much much higher.
Thanks
Hi Yiannos, I don't claim to know anything about Bitcoin so this is simply a hypothesis, but is there a chance that the approval of a bitcoin ETF would, after a period of adjustment actually have the inverse effect and bring the price down? At the moment there is a fixed limit to the amount of bitcoin available, which makes investors wary of not getting a piece of the pie, but once an ETF is in place, the fomo is gone and everyone can trade bitcoin just in a different manner, especially as it isn't a physical asset like gold or a stock that has asset backing.
ref bitcoin
You mention the limited supply of bitcoin being positive - is it a positive though ? Once supply of new bitcoins tails off as is already pretty much happened presumably transaction fees ramp up in % terms is that not the time when bitcoin is likely to implode once peeps realise that every sale (purchase too?) comes with fee to keep the whole house of cards going? if it’s static pool of intangible value with % of that value being removed from the system each year in ever increasing fees / higher than now fixed value it doesn’t sound like a great investment.
i have no idea how material these transaction fees are but it does look like these fees are already increasing materially compared to historical lows.
Argo Blockchain (LON:ARB) Speculation on spot bitcoin ETF'sin USA. I don't hold ARB, but do hold DAGB. https://cointelegraph.com/news...
Same with bitcoin miners in the US, Riot Platforms (NAQ:RIOT) and Marathon Digital Holdings (NAQ:MARA) over the pond.
I'm half wondering if Marathon Digital Holdings (NAQ:MARA) especially has been repeatedly heavily shorted recently as i'm sure they just constantly dilute their shareholders.On checking short interest is around 20%.US momentum once it gets going can be another thing!
Happy Christmas all.
Paul enjoyed the most recent podcast, especially when you briefly lost it.
Please keep them up for 2024 - always much appreciated and enjoyed to the full.
Haha, thanks The Jayman! I do enjoy doing the podcasts, and it's sometimes irresistible to have a little rant about something or other :-) I've amazed myself that I've been able to do (almost) a full year of podcasts in 2023!! It's easy to start these things, but much harder to keep them going.
Could you please tell me where I can find the link to the podcasts.
Could you please tell me where I can find the link to the podcasts.
It is as simple as googling Paul Scott podcasts
What’s googling? :))
Small Caps Podcast with Paul Scott: Episode 50: UK Small Caps with Paul Scott on Apple Podcasts
Thanks