Small Cap Value Report (Wed 27 Sep 2017) - CNKS, RM2, BOO, KETL

Good morning!
I didn't get around to covering requests yesterday but have now taken a look at Cenkos Securities (LON:CNKS), which did receive many requests. I'm posting my review of that stock first of all. And then it will be time for Wednesday's updates.
Cheers,
Graham
Cenkos Securities (LON:CNKS)
- Share price: 115.5p (+12%)
- No. of shares: 56.7 million
- Market cap: £65 million
This is a stockbroker in the small and mid-cap space which provides corporate finance, market-making, research, etc. It acts as Nomad to AIM stocks, where it's one of the most active fundraisers.
I traded in and out of these shares back in 2015. It's one of those companies with lumpy revenues from occasional large, one-off transactions which are difficult to predict until they materialise. It is furthermore exposed to cyclical movements in equity fundraising activity, which are completely beyond its control.
Its stock market listing is very useful for it, however, since shares are a heavy part of overall staff compensation. So it can conveniently buy shares in the open market for its employees, who then also have a convenient place in which to sell them, should they choose to do so.
The company's staff compensation model is one of the best in the industry: base salaries are relatively low, but they come with high variable compensation. This results in motivated staff and a track record of never generating a loss in its entire history, all the way back to 2005.
Anyway, on to Tuesday's results. The cyclicality is evident:
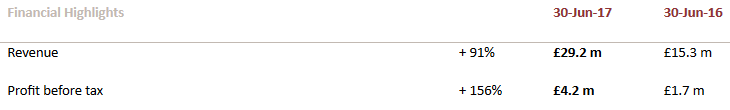
The profit after tax and EPS increased by even larger percentages. This was thanks to a lower effective tax rate.
Funds raised for clients in H1 increased to £982 million from £529 million the prior year, helped by the £386 million Eddie Stobart Logistics deal.
Costs rose 82% to £25 million, reflecting variable staff compensation. It's a people business, so you don't get operating leverage working the same way as you do with other stocks!
The interim dividend recovers strongly to 4.5p.
Including share buybacks, Cenkos has returned £105.6 million to shareholders since flotation in 2006. I should point out that's significantly greater than the current market cap!
This is what you want to see from a company like this. Paying out most of its earnings, while retaining sufficient funds for regulatory capital purposes, means that shareholders get immediately and strongly rewarded for taking the risk of holding a stock with such cyclical and unpredictable earnings.
And there is little point in those earnings being reinvested back into the business, since there are probably no reliable ways to earn an attractive return on additional capital, given the nature of this industry and the maturity of this particular company. So large dividends and share buybacks are exactly right.
Outlook sounds fine according to the new CEO, who had been a non-executive director since 2012.
We have made a very good start to the second half of the year. There is institutional demand to fund high quality companies and ideas. Since July we have been engaged in relation to a number of significant fundraisings and our pipeline for the rest of the year is encouraging.
My opinion: I don't think anything has fundamentally changed at Cenkos, so I consider it a pretty reasonable investment around these levels. I think I'd almost certainly get my money back in dividends and share buybacks, so for me, it's not a speculative investment at all. It won't be the next big growth stock, but it will make an honest effort to pay you over the years.
As an interesting anecdote, the founder sold a large chunk of his shares at 107.5p in 2010, describing the share price at the time as ludicrously cheap. I wonder what he thinks about the share price now!
£RM2
- Share price: 6p (pre-open)
- No. of shares: 407 million
- Market cap: £24 million
I identified this manufacturer of high-tech pallets as a short/sell idea at the UK Investor Show in April this year (along with £FJET).
The share price is down nearly 75% since then, but I don't consider this to have been a particularly clever call. The company has been a basket case for investors and the writing has been on the wall for some time now.
Today's results show H1 revenue unchanged at $3.7 million and a slightly reduced loss of $19 million.
It's trying to outsource produce to China, having already partially outsourced it to Mexico, but needs more funds to make this happen.
Today's statement estimates that cash reverses are sufficient to last to February 2018, or potentially Q3 2018 if it can sell some legacy assets. But the big picture is grim:
Should the Company not be able to secure sufficient additional funding, it will not be able to face liabilities generated by contractual commitments, including those for manufacturing and operations.
Worth noting that the value of inventories remains elevated at $17.5 million, or more than twice annualised sales.
My opinion: Totally uninvestable.
I'd like to think that Stockopedia agrees with me, as the StockRank is just 11.
Boohoo.Com (LON:BOO)
- Share price: 243.75p (-6%)
- No. of shares: 1148 million
- Market cap: £2,800 million

The online fashion retailer reports another impressive set of figures: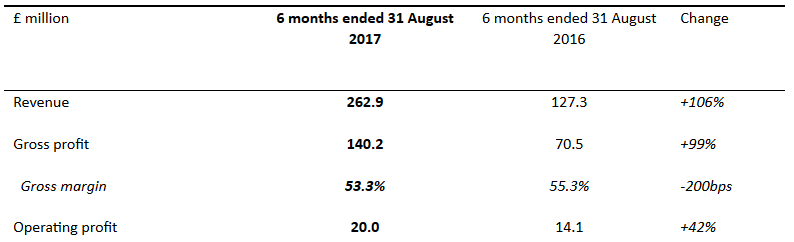
Excluding the PrettyLittleThing and Nasty Gal divisions, revenue at Boohoo increased by 43% (40% at constant FX), while gross margin was down 300bps to 52.3%.
The corresponding growth rates at the interim results last year, before PLT and Nasty Gal were as follows: revenue +40% (41% at constant FX), and gross margin down 480bps to 55.3%.
So the growth rate at constant FX is marginally lower this time, and the gross margin has fallen 780bps over two years. That seems like a lot of lost margin to me, but perhaps its the price of achieving sequential sales growth of c. 40%.
The overall operating margin has improved from 6.6% to 7.6% over two years. Moving in the right direction at least but perhaps more could have been expected?
Guidance
Full-year revenue growth is now anticipated to be 80% (up from previous guidance 60%).
As a result of significantly better-than-expected revenue growth from PrettyLittleThing and our investment in price, promotion and marketing, we now expect group adjusted EBITDA margins to be between 9% and 10%.
Every improvement in guidance was compared against prior guidance, but it's necessary to scroll back to the last trading update to see that prior guidance for EBITDA margin was "around 10%".
So the plan is clearly for accelerated revenue growth, at the cost of some more weakness in margins.
A new warehouse is set to double existing capacity by January 2018.
I seem to recall Boohoo being slow to set up an app. While the percentage of sessions which are app-based is unclear, mobile devices are now 70% of sessions. Surely that means a good app is critical!
Growth by geographical market is as follows (note that these % growth numbers are not like-for-like and have been exaggerated by the acquisitions):
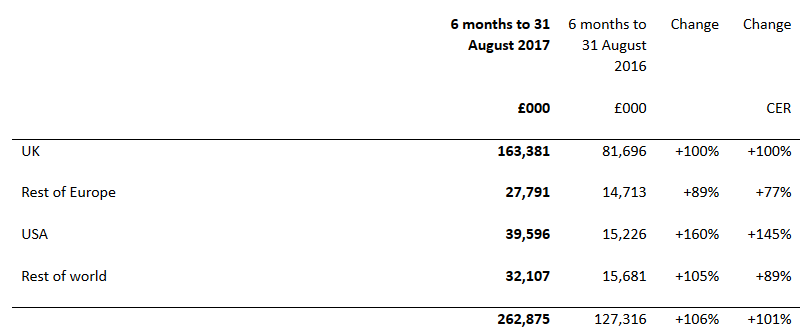
My opinion: What is there to say, that hasn't been said already? I summarised my view on this when I covered it in June - I said that it's probably overvalued, along with other quality growth stocks at the moment. But it's a fine company nonetheless.
Active customer numbers growing by 29% would not on its own be sufficient to justify the prevailing valuation, in my view, but the average order value and frequency of orders have also been steadily increasing.
Putting my bear hat on for a minute, I'd say that economic stress would put the brakes on order value and order frequency, and that Boohoo's growth would then be reliant primarily on the growth in customer numbers.
It would still be a quality growth stock, but the valuation might be a bit more terrestrial and a bit less stratospheric.
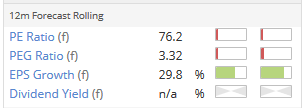
Strix (LON:KETL)
- Share price: 136.375p (-0.5%)
- No. of shares: 190 million
- Market cap: £259 million
The Strix website proudly states that its products are used about a billion times a day. I think that says a lot about caffeine addiction in addition to what it says about the success of the company! It's in the business of making kettle controls, and has been listed only since August.
Today's results for the period ended in June are in line with expectations, and look solid.
- Revenue up 6.7% to £42 million
- Adjusted EBITDA up 6.1% to £14.2 million
- PBT up 9.6% to £10.3 million.
Export sales are up 10% which is despite a 10% decline in China, whose stronger 2016 result was apparently due to a health scare. Strix thinks its market share there is c. 50% - amazing if true! It has a large factory in Guangzhou, China, and an estimated 38% global market share by volume.
The products must be extremely low-cost if 38% global market share translates to c. £40 million revenue over six months!
An interim maiden dividend of 1p will be paid in November.
Outlook is line with full year expectations.
My opinion: This is an interesting addition to AIM. It has been listed at a fairly ordinary valuation and perhaps that reflects the cheapness of the products themselves. Strix mentions "continued pressure from copyists" as a challenge it faces in China, where competitors no doubt can offer all sorts of even cheaper component parts.
But taking a look at its website, Strix's quality controls look utterly comprehensive, with certifications from a wide variety of bodies including Intertek (LON:ITRK). There are also four US patents mentioned.
So I'm open to the idea that Strix's competitive advantage is here to stay, and that the shares are priced favourably for investors.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

46 comments
Apologies Si, I misinterpreted what you were saying - I hadn’t considered a buy out, though personally, I believe the directors are the key to BOO’s success and would have to be involved for that to continue.
No need to apologise at all. I sometimes post quickly and don't make myself as clear as I should. The only reason I mentioned the Amazon thing was to make the point that Boohoo is not really that expensive when you compare it some companies for whom it would still be an earning enhancing addition :) I don't really expect it to happen.
I think it would be difficult for anyone to execute the design-make-test-sell loop any better than Boohoo but Amazon is basically a logistics company that could improve everything else and give it instant scale, and as we know, they really don't give a stuff about margins in their quest for world domination!!
All the best, Si
Saw the RNS about joint CEO Carol Kane selling 4.65m shares yesterday, which one could say is unhelpful.
When I see this I always contrast with Buffett, who has not sold one share of Brooks Macdonald (LON:BRK) in his 50 years at Berkshire. I have made £65k on £18 on Boohoo.Com (LON:BOO) (after the current fall) and am happy to hold on but I am always disappointed with insider sales like this.
Interesting price move and volume by Boohoo.Com (LON:BOO) today. It almost exactly mirrors the move and volume from the June 8th trading statement, except in the opposite direction. It is slightly odd that a statement which is inline with previous guidance has taken off the gain from the previous guidance but that is how sentiment works sometimes.
The big question now is whether the support will hold. At the moment I would say that over longer time periods Boohoo.Com (LON:BOO) is likely to continue to be a strong performer, but it is a fairly volatile share so in the short term it may well fall further. [NB: log scale chart below]
My guess (and it is only a guess I really have no specially insight in to these things) is that there were a lot of short term traders who bought into the news flow expecting an impossible announcement yesterday (you know sales up 300% and Nasty Girl turnover at $300m) and when they get an inline they all sell out of the stock.
As I say below Kane's insider trade yesterday is sunhelpful but for now I am holding firm.
I have held for 22 months and still think that in November 2025 this will considerably bigger than it is now and will outpace the market.
Volume today in Boohoo.Com (LON:BOO) was impressive and very unlikely to be due to stops triggering.
Fair comment. Something like 65m shares traded being about 10x the daily volume and roughly 10% of the "free float". I see an RNS out this morning that joint CEO Carol Kane sold 4.65m (about 10% of her holding) shares at 230ish-p which might have compounded the fall into the second half of the day. Interesting to see if other senior management or institutional investors were other big sellers.
Gus.
It's hard not to have some sympathy for Boohoo.Com (LON:BOO) management (and shareholders for that matter) after today's events. At face value the interims shot the lights out beating expectations across the board for its three primary business lines while also upgrading future expectations yet the shares ended down about 15% on the day. Doubtless some profit taking probably compounded by PI stop losses being triggered on the was down, especially after the 50 day moving average was breached but possibly a bit overdone?
It may be that the high water mark has been reached, but I've thought that in the past with this company and been confounded trying to trade out and back in again at a lower level on what I think will be a long term success in its increasingly international niche. I recall similar "top of the market" commentary in September 2016 when the shares went up through 100p and onto 120p before a similar 15% or so readjustment saw a lot of people selling (me included) before a further series of step ups in valuation. Having previously taken more than my original invested funds out of this one I was possibly one of the few buyers today and believe it will grow into its apparently fanciful valuation in time. As ever time will tell.
Gus.
With such a positive appraisal of Cenkos (CNKS) which I agree with as well, I wonder why it does not qualify for any stockopedia screens? Looks like the algorithms need to be updated a bit. It should qualify for some screen or the other as Cenkos has been around for a while.
Thanks for your comments on BOO Paul. Iappreciate your time spent on a share which is beyond what would normally be commented on on SCVR. I had the chance to bank good profits early on today but waited to see if there was going to be some improvement on the falling share price. Being my day off, I didn't want to sit in and watch the screen all day so to try and keep myself sane I got out to do some jobs. Hugely disappointing to see what has happened today on the back of a pretty good RNS in my opinion. I couldn't see anything there to hit BOO so hard and wonder just how many stop losses were triggered which continued the downward pressure. However, there must become a time in the day when pretty much all the stop losses will have been executed.
There seems very little room for the slightest disappointment in any RNS at present. So many stocks are down, particularly the higher growth stocks. Do you have an opinion where best to invest or avoid at present if growth stocks are falling?.
Very interested to read you believe that BOO in the long run will be way more successful than ASOS. Isn't that a case maybe for holding right now?, or do you think it is better to sell and buy back in at a lower level.
I guess one has to take a hit from time to time and just hold ones hands up and say, well, could have made a lot more profit but at least I am coming out with SOME profit.
Are we at a point where the market maybe irrational, but can stay so for far longer than we can stay solvent?. Always on a learning curve it seems.
Regards
CM
BOO - great results, but you have to wonder how good they would have to be for the share price to respond positively. Profit taking today, I think.
B2V
BooHoo are also pushing wholesaling, which is lower gross margin - e.g. you can buy their product through the Next Directory.
I wouldn't get too hung up analysing figures from BOO, as there are so many moving parts. In the long run, it's likely to be way more successful than Asos in my view, as they're just far more entrepreneurial. To a large extent, that's why it's on such a high valuation. But there are limits, and for me, it's too expensive right now.
Remember that a significant disappointment means a 30-50% drop in share price - people have tended to forget about that lately, but I fear we have some rude awakenings looming - not necessarily in BOO, but with other very highly-rated growth companies. This is a time to bank profits, in my view, in companies that have raced ahead in valuation, but are not delivering spectacular growth.
Regards, Paul.
I agree. Time to preserve your capital, which to me includes the gains made during the bull run.
I have been 90%+ in cash for over a month. Minervini setups are just not firing up as they were doing until a few months back. Most drift sideways or head south.
Well September is historically the worst month in the year for stocks. I'm finding a few good Minervini-like setups recently though less than earlier in the year - I've had success recently with Anpario (LON:ANP) which meets the trend template. Also I've had success with Filta Group (LON:FLTA) and £K3C which appear to me to be what he calls primary base breakouts from the IPO.
Slightly off piste, but as you mentioned it, I noticed that Boohoo, PLT, Quiz etc etc etc all new brands with NEXT - a much needed step change in their model and enough to convince me to buy back into NXT. They have a great website, logistics and growing international presence and have demonstrated their ability to adapt to this fast changing market.
As a long term holder of BOO (and a big fan - they just seem to be getting it right again and again) I am holding, albeit with slightly reduced profits after today! I also see a very bright long term future.
I wouldn’t worry about the app too much - people seem to place a lot of focus on having an app, but I have never yet downloaded an app for an online clothing retailer nor have my teenagers who regularly receive asos/boohoo packages. Instead I receive appealing, almost daily email alerts from them with enticing offers - e.g. 25%off before midnight. I am not exactly their target market ( far from it! ) but there is enough going on to keep me interested in their tall ranges, which is ever increasing, and, I noticed on a pair of trousers I was looking at, the reviews were predominantly from American customers. All good signs to me.
And to Simoan, honestly, I have no concerns re Amazon- certainly at the moment, it is the BRAND that is important - to buy your clothes from Amazon would be deeply uncool!!
And to Simoan, honestly, I have no concerns re Amazon- certainly at the moment, it is the BRAND that is important - to buy your clothes from Amazon would be deeply uncool!!
But that's the point - it would be the brand that Amazon would be buying for this very reason. No-one wants to buy food from Amazon either and that's why they bought Whole Foods.
All the best, Si
Sorry meant to give you a thumbs up and my arm jogged. My apologies.
Apologies Si, I misinterpreted what you were saying - I hadn’t considered a buy out, though personally, I believe the directors are the key to BOO’s success and would have to be involved for that to continue.
First thing I noticed when I read the Boohoo.Com (LON:BOO) RNS at 7:03 am was the drop in margins but this was advised by management previously and so I thought the initial 5-6% drop was about right. I decided to hold on because I like the management, this is a company of international scale just starting to grow in the US and even though it's very highly rated it's actually "walking the walk" (doubling warehouse capacity and automating), not just "talking the talk" like so many other highly rated shares I see currently. If it makes further progress, particularly in the US, it would not surprise me to see Amazon take it out at some point, however that's not the reason I'm holding.
BTW why does Stockopedia have it under "Software and IT services"?
All the best, Si
Hi Graham,
If you have time this week, I wondered if you might look at Nasstar plc [NASA], a £55m IT services co. which produced its interim figures on Monday [25/09/17]. Thanks.
xxx: I don't see a good case for investing in Nasstar (LON:NASA) as (on a superficial scan of its recent results and the Stockoedia page) it seems to have funded years of losses and acquisitions by issuing large numbers of shares, and it's still losing money and cash.
It's in a competitive market place, and seems to have current liabilities that exceed current assets plus cash. I'm surprised that it is able to pay a dividend. It seems to have done a recent restructuring, closing several data centres (OK if it's consolidation for efficiency, not so good if it's just cost-cutting, since it's in the IT hosting business).
What's the bull case?
Good question. I should say I do not know their area of operations, but having said that the attractive points are.
1High recurring revenue
2 A clear plan to service selected industries
3 The acquisitions do seem accretive, eg allowing the closure of several data centres and better service for customers, via a company they bought which has a presence in NZ, allowing 24hr cover.
The problem for me is that, whilst that is the narrative, the cost line has not fallen, but I am not sure whether that is due to closure costs being loaded in the H1 results...hence my request for further scrutiny !
The Boohoo.Com (LON:BOO) chart looks like it could be in what Minervini calls the Stage 3 topping out phase. Reminds me a lot of ASOS (LON:ASC) in summer 2011 actually.
Hi,
Boohoo.Com (LON:BOO) - very good results, but the shares are too expensive now, in my view. Fall in margin is deliberate - they're aggressively taking market share, and chose not to increase selling prices when sterling devalued. The CEO was adamant about this - I heard it from the horses mouth, in a telecon with him earlier this year. Also note that marketing spend has risen from 6% to 8% of revenues - again, a policy decision, to aggressively drive growth. I would buy back in c.150p, but not above. Note that sales in USA growing very strongly, partly due to NastyGal. It's a fantastic company, but share price has got ahead of events, in my view.
Cenkos Securities (LON:CNKS) - thanks for the review Graham! This share dumbfounds me. I have held for quite a while now, and keep getting massive dividends, yet the share price languishes. Cenkos are known to be fantastic at fundraising for clients, so have a very good point of difference. Earnings are lumpy, but the dividend track record (paying out more than entire market cap since floating in 2006) makes it a lovely share to hold, in my view. Am trying to buy more, but the market is so thin, I can't get more than a scrap. Might be best to wait, as I think the listing is mainly used as a way for employees to cash in their share options, as Graham suggests in the main article above.
Crawshaw (LON:CRAW) - I don't rate management here. Parachuted in from Aldi, but failed to demonstrate entrepreneurial skill to run a small company. Alienated customers with price rises, since reversed. I don't like the deal with 2 Sisters, on reflection. HOWEVER, the payback on new "factory outlet" stores is outstanding, at 12 months. So could be worth a fresh look maybe?
Hotel Chocolat (LON:HOTC) - I find the way they presented the figures to be very misleading. EPS up 100%, but that's because there were substantial exceptional costs in the prior year. Adjusted operating profit actually up from £9.0m to £11.9m. Fancy branding, but product is average & over-priced, in my taste tests. A bar of Cadburys Whole Nut tastes better, and costs a fraction of the price. So I see this as a fad company. Shares look wildly over-priced to me.
Xeros Technology (LON:XSG) - terrible results. I tried to short it this morning, but can't get a borrow unfortunately.
Mercantile Ports & Logistics (LON:MPL) - awful company, but 2 days of chunky Director buying announced. Could be something afoot? (I have a speculative long position in this, probably very foolishly!!)
Best wishes to all from Dubrovnik!
Paul.
Boohoo.Com (LON:BOO) - Despite upping full year guidance on revenue growth from 60% to 80% (which implies £530m revenue for FY18), there is still plenty of scope for further upgrades to come.
In order for the core Boohoo brand to come in at their revised guidance of 30% growth for the year, H2 growth would have to slow to less than 20% YoY compared to the c.40%+ growth seen in Q1 and Q2. The PLT brand would have to slow from c.300% YoY growth down to 80% YoY growth in H2 to hit their revised guidance, which would mean negative growth from H1 to H2. I'd suggest that a drop off in sales to that degree in a single 6-month period is rather unlikely even with consumer spending in the UK looking a bit sluggish.
So even with a more realistic drop off in the growth rate, they could still hit £600m revenue this year which would be more than double what they did in FY17, and considerably more than what brokers are currently forecasting. In that context, despite gross margins being in gradual decline and EBITDA margins being guided slightly lower due to increased investments for the future, overall profitability could still comfortably exceed forecasts so the headline PE and PEG ratios have to be taken with a pinch of salt.
Strix (LON:KETL) - The headline reported balance sheet is meaningless since it represents the pre-listing situation. To be fair the RNS does point readers to the pro forma balance sheet in section 4, which represents the post-listing situation and is therefore far more relevant, but I find it mind-boggling that a company can be brought to market when it appears to be technically insolvent, all the more so when they are paying dividends and have a pile of debt.
Hi bestace - Re. Boohoo.Com (LON:BOO) I am looking at the sp that has dropped near 10%, and wondering if this is an investment opportunity.
So I have carefully read Graham's analysis and yours to help me decide.
Both analyses are as usual first rate.
If I accept your premise that there is still a lot of revenue growth ahead, say double 2017, then my fag packet calculation says forecast eps growth (FY2018) might be 50% - 70% from current 36.9% broker forecast. On current sp this implies a pe of 72.
The difficulty that I have is looking at a very high pe against a slowing forecast eps growth, from 95.8% to say 60%. In a bull market this scenario would have passed muster. In today's climate, I am not so sure. So I have decided to sit on my hands.
Regards. Ram
I feel you have more knowledge than I do... but IMHO, if BOO's interim eps growth is only 24% and their forecast full year margin is actually going to be even lower than the interim one, then I don't see how they could possibly grow FY2018 eps by 50-70%. Even if they managed to grow the eps by 50% this would still mean a FY eps of only 3.25 giving a per of about 69 (at the price which has now fallen 14%) which seems rather overvalued... at least if one is valuing on that basis.
I've watched for a while, and I see the big margin drop and indication of even lower margin as a disappointment... hence the share price drop.
Is today's share price fall an investment opportunity? I'd also love to know the answer to that question! As is often the case, the answer will depend in part on your investing horizon so if you're looking for a Minervini-type investment which is measured in days and weeks rather than months and years, I suspect sitting on your hands may end up being the right thing to do, particularly given recent weakness in the wider markets (growth stocks in particular) and the fact that the next trading update probably won't be until December.
On a longer term view (which fits more with my investing style), I think the situation is more finely balanced. I don't think focusing on EPS for the next couple of years (and by extension the PE/PEG ratios) is entirely appropriate due to near term capex investment in warehousing etc. which is paving the way for future growth.
They are currently planning capacity for £3bn revenue, which I reckon they could reach by 2024 or thereabouts based on a growth path of 35% for FY19 declining gradually to their longer term guidance of 25% growth. Slap a 6% profit margin on £3bn of revenue gets to £180m profit, let's say a PE ratio of 18 to reflect lower (but not low) growth rates gets to a market cap of £3.2bn. Comparing that to today's market cap of around £2.6bn would be a CAGR of around 3.5% which is not exactly shooting the lights out, and on a 'per share' basis there may well be further dilution along the way so an investor's actual returns would be even lower.
There are a lot of ifs, buts, maybes, assumptions and moving parts in that last paragraph; other valuation methodologies are available and there is always execution risk as well as the risk of recession, financial markets crashing, increased competition etc. so on balance I would probably agree with Paul's view that the share price is up with, if not ahead of, events.
I also have some concerns about their strategy, which I alluded to in a previous thread. One of those was a lack of focus on customer churn which was raised again in the analyst Q&A this morning and I wasn't entirely convinced by the FD's answer.
Despite all of the above, I'm sitting on some shares I bought much lower down and I'm not really inclined to sell just yet. I did however sell a chunk of trading shares yesterday which I have bought back today, too soon as it turns out.
Hi unless I;m missing something Stocko shows Strix as having net cash ?
They had net cash up until the point they listed 6 weeks ago, as long as you're happy to exclude loans from related parties from the calculation of net debt (which is what Stockopedia does). At IPO, the private equity backers exited stage left, taking all the IPO proceeds as well as some of the new debt facility. So now the company has net debt and negative net assets to boot.
The Stocko figures are out of date as they are only reporting figures up to 31 December 2016. Presumably they will update in the next day or so to reflect the interims released today, but as I pointed out in my last post the reported balance sheet as at 30 June 2017 is meaningless because it is pre-IPO and reflects none of the capital restructurings that took place at that time, so the Stocko figures will continue to be out of date for another 6 months or so until the 2017 finals are released.
Have a look at the pro forma balance sheet towards the end of the RNS to get a more accurate and up to date picture.
Many thanks had a feeling you would be more on the money than myself out of interest do you know on average how far Stocko normally are behind updating stats against most recent information ?
I guess from what your saying if using the Stocko stats it might be wise with new issues to wait until the first set of stats have caught up to get a truer picture unless your iike Paul or yourself people who are good with balance sheets ?
Thanks again
I don't know for sure but I think it's normally a day or so. You are probably best off directing that question to the Stocko management.
I'd recommend always going back to the original source - RNSs, annual reports, company presentations and (in the case of recent IPOs) the listing prospectus. That might seem like additional work, but if you have a lot of money at stake I think it would be a false economy not to.
If you rely solely on the figures provided by Stocko, there is scope for errors, omissions, lack of context and poor interpretation of the original source (Strix being a prime example), bearing in mind that Stocko are themselves two steps removed from the original source as they rely on Thomson Reuters as a data source.
The timeliness of the updates to Stockopedia are in the bottom right hand corner of the screen and generally updates overnight as far as I am aware. But as you say the data can on occasions be wrong, sometimes due to wrong data from Thompson Reuters.
My morning smallcap tweet:
PCF (LON:PCF), Havelock Europa (LON:HVE), Crawshaw (LON:CRAW), ECSC (LON:ECSC)
PCF Group (PCF) Trading - exp FY beat.
Havelock Europa (HVE) H1 rev down 9% due mainly to a weak opening order book in public sector - particularly delayed schools building programmes. H2 is expected to be profitable, the results for the full year will be significantly below last year. CEO resigns immediate effect.
Crawshaw Group (CRAW) H1 pretax -£1.2m (-£0.4m) - profitability impacted by sterling weakness and shape of sales recovery. Trading: recent 6 weeks: Customer numbers up 5.4% but LFL still neg at -1%. "We are experiencing further margin pressure from the continued weakness in sterling...Market conditions remain challenging."
ECSC Group (ECSC) warns, drops 70 to 125p. Only floated in Dec at 167.
Hi Graham
Crawshaw butchers report wider losses this morning , I would like hear you opinion on them . if you have time .
Thank you
Re. £RM2 I remember looking at this company at the IPO stage and concluding that its business model was flawed.
Over the years a number of people have commented that this company is a basket case. Yet it has attracted Woodford with an investment of 28%, and Lord Rose as a Director.
Woodford's crown is slipping by the day.
I have a very large (for me!) holding in Cenkos Securities (LON:CNKS). I do a fairly regular keyword search on Investegate, that shows me all the RNS they put out on behalf of their client companies and keep an eye on the transactions page of their website. It was very obvious some months ago that they were significantly ahead of last year, and so the large rise in the interim dividend was no surprise. Since June 30th they have done a very large fundraise for Hurricane energy, with more to come from other client companies before year end it would seem. For those investors unable to do the technical analysis of company accounts that Graham and Paul do so effortlessly, this is a very easy way to track the fortunes of the corporate finance brokers. Essentially their profits seem very closely linked to the amount of capital they raise for their clients, and you can essentially track that in real time by spending just a few minutes a week. I also hold £NUM
What keyword terms do you use to search on Investegate Harry when looking at £CNKS?
Regards,
Imran.
I just search on 'Cenkos' Imran. It tends to list all the RNS announcements that they issue in their capacity as NOMAD. That way you get an indication of likely IPOs, placing and other capital raising. The 'transactions' page on their website then lists the fundraising by month and amount. They seem to be sporadic in updating it...,perhaps only listing them when their bill is paid?! The second half of the year (starting 1st July) seems to be going well.
Harry34. - thanks for this tip. I hold Numis (LON:NUM), who will come out with a trading update soon (full year end-Sept). Numis also has a transactions page (corporate actions - track record), which is also only irregularly updated. Numis (LON:NUM) has already said at end -July that the 4 months, April to July had been strong - seemingly benefitting from the same environment as Cenkos Securities (LON:CNKS) - but I doubt growth will be as strong.
Hi Imran,
I've just seen that Cenkos are acting as sole broker for a £350m fundraise for Civitas Social Housing. I presume their fees will be less than for that of an IPO, but it is a very similar capital raise to the Eddie Stobart IPO in H1. Further evidence that this is a very good year for them, and should mean that they will be paying out at least 5p final dividend - but I suspect higher.
Thanks Harry. I noticed that also.
RM2 is one of those companies that leave one baffled because at a market cap of £24mm somebody must have committed funds in the face of massive losses, an imminent cash crisis and revenue at barely 25% of market cap. It is astounding that anyone can be found to put their money into this.
It is I suppose a tribute to the mechanism of the market that it can find diversity of opinion great enough to cover both sides of a transaction in this stock
Hi Graham
Can you cast your eyes over the Trading Statement from PCF (LON:PCF) please?
Ahead of expectations and starting to see the benefits of its recently gained banking licence and cheaper funding flow.
Thanks
Can we get your thoughts on Appscatter (LON:APPS) please Graham? Loss-making but could have a lot of potential - but is it grossly overvalued already? Also vote for Strix (LON:KETL) - ta!
Done Strix (LON:KETL), rtj!
Early bird catches the worm