Small Cap Value Report (Wed 28 Jun 2017) - FRP, CRL, CRAW

Good morning, it's Paul here!
Market overview
It seems to me that the froth is coming off things. We've had a roaring bull market, with lots of speculative stocks zooming up. It's all felt rather euphoric, and it's been ridiculously easy to make money in growth stocks, in the last couple of years.
Conditions like that don't last forever. The skill is not in making money during the euphoric phase of a bull market - that's the easy bit. In fact, it's often the most reckless people who make the most money in bull markets - total junk can easily multibag for a while. The difficulty is hanging on to that money, once the bull turns into a bear. The reason that's tough, is because to maximise the gains in a bull market, you have to do pretty daft things - like ignoring valuations, and conventional value metrics. It's all about running the winners.
Then inevitably, at some point the music stops, and the party's over. Then the momentum stocks nearly all roll over, and give up a lot of the gains. With powerful rallies along the way, to suck people back in. I am seeing a lot of parallels between what's happening now, and my memories of 1998-2000. Excessive valuations for growth companies, in particular. Plus a big appetite for blue sky story stocks, at high valuations again.
I can't predict when the bull market will end. We're long overdue a big correction. So personally I'm feeling pretty cautious at the moment. I'm not interested in opening up any new long positions on expensive growth stocks, and have sold most of the ones I was in - e.g. Purplebricks (LON:PURP) - where the valuation is just too high now.
e-commerce stocks are still very interesting though - because the growth rate is still so high, something like 20% p.a. still in all e-commerce sales in the whole UK. The flipside of that growth, is that the market share has to come from somewhere. So I see older, more traditional retailers as being very vulnerable. Hence I'm short of Marks and Spencer (LON:MKS) , Debenhams (LON:DEB) , and Halfords (LON:HFD) for example.
Overall though, sentiment is really driven by the US markets. So if they keep going up, then the chances are, so will we. That's the bit we can only guess at really.
Retail leases
This is an interesting area of change. In the past, the standard lease terms were 25 year, with upward-only rent reviews. Then that dropped to 15-year leases typically, which has remained the case for several decades now. These horrible, inflexible leases, have killed off many retailers over the years.
However, the turmoil for retailers now means that increasingly they are insisting on only signing more flexible, and shorter leases. Next (LON:NXT) said this earlier this year - they're not taking on leases of more than 10 years, and usually lower.
Rents seem to be falling in many towns too. Next said that it is achieving rent to revenue of 5% on its new sites (as opposed to 7% on existing). This is very interesting, as it helps offset a lot of the other upward cost pressures faced by retailers.
Hence I wouldn't write off conventional retailers just yet. The ones who are flexible, and have short leases (which they can ditch, if the rent becomes unaffordable), and relatively low fit-out costs, could continue to trade well ( Shoe Zone (LON:SHOE) springs to mind).
The dinosaurs with huge property portfolios, and long leases, could end up in real trouble I reckon. So those are the ones to worry about.
Fascinating times!
Fairpoint (LON:FRP)
Delayed accounts are always a massive red flag.
Fairpoint said on 28 Apr 2017 that it intended publishing its 2016 accounts in mid-May 2017.
Then on 24 May 2017 the company said its 2016 results are expected to be published in June 2017.
So here we are, almost at the end of Jun 2017, and it's pretty obvious that something has gone badly wrong. Shares have to be suspended if a company doesn't report its accounts within 6 months.
Suspension of shares - this bombshell was announced at 7:30 this morning:
The Company announces that it has been notified by its bank, AIB Group (UK) plc, that it is unwilling to provide the level of on-going support requested by the Company.
As a result, the Group is unable to sign-off the audit of its annual report and accounts for the year ended 31 December 2016. Consequently, the Company will not be in a position to publish its annual report and accounts for the year ended 31 December 2016 by 30 June 2017 as required by Rule 19 of the AIM Rules for Companies ('AIM Rules').
Dealings in the Company's ordinary shares shall therefore be temporarily suspended under AIM Rule 40 from 7.30 a.m. today until such time as its accounts have been duly published in compliance with AIM Rule 19.
When the bank loses confidence in a company, it's usually the end.
Company law requires that Directors put a company into Administration, if they are trading whilst insolvent (unable to meet liabilities as they fall due). The company could possibly be saved, if a new lender can be found quickly, which the company alludes to today;
The Company is currently participating in discussions with alternative providers of finance who may wish to provide support to the Company's businesses.
Overall, I think shareholders should prepare themselves for a potential 100% loss here.
I'll await developments, as it's probably a bit too early to write a post mortem yet.
6 months ago, I thought there was a good chance the company might be saved. However, events have clearly moved on since then - delayed accounts was the big warning sign. Unfortunately I didn't pick up on that, because I don't follow the company any more (having ditched them a while back), and would have warned readers if I'd spotted it. Hopefully no readers are still holding this share.
Creightons (LON:CRL)
Share price: 32.7p (up 34.8% today)
No. shares: 60.6m
Market cap: £19.8m
Preliminary results - for the year ended 31 Mar 2017.
Quite a few friends hold this share, so I'm delighted to see that it is today's top % riser. They'll be putting out the bunting no doubt, as it's party time! I'll have to dust down my disco shoes. Only joking - they never get dusty, due to constant use!
The company manufactures toiletries & fragrances.
The financial highlights look fantastic - look at that growth;
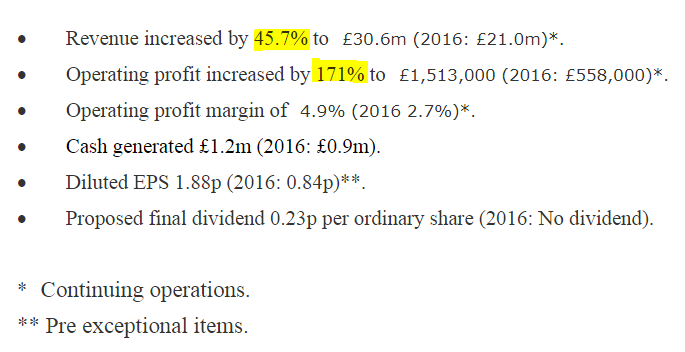
The key questions are;
- What has caused this strong growth in revenues & profit? and,
- Is it sustainable?
The Chairman sounds upbeat, and mentions increased production capacity;
"Creightons Plc ends the reporting period with an enhanced production capability now able to support innovation, design, development and production across the spectrum from value to premium market.
We believe this, with the increased production capacity, strengthens and improves the resilience of the business and will ensure the Group is well positioned to sustain profitable operations and to continue to seize new opportunities as they emerge in a consolidating market."
The MD added;
"The management team has achieved a significant improvement in the customer base, both in the UK and overseas, with a broader range of products, expansion in the premium sector, extended production capability and capacity, and continued positive cash generation. The Group is poised for further growth."
Balance sheet - looks very good. No issues at all that I can see.
NAV is £8.5m. There are only £0.5m in intangible assets, so NTAV is a healthy £8.0m
Working capital is plentiful, with a current ratio of 2.40, which is very strong.
My opinion - these are excellent numbers, and the company really seems to be on a roll. It has introduced a small dividend of 0.23p, for a yield of 0.7%. I would expect that divi yield to rise, if excellent trading continues.
The share price has already more than 3-bagged in the last year, so improved performance is now baked into the share price. The PER is 17.4 (based on 1.88p diluted EPS), so to be considered good value, the company would need to grow earnings further.
So the shares are now up with events, in terms of 2016/17 results. It sounds as if profits could grow further, which is what could propel the share price upwards even more. Looks an interesting situation, and well worth a closer look. Well done to existing holders!
Crawshaw (LON:CRAW)
Share price: 25.1p (down 13.6% today)
No. shares: 113.0m
Market cap: £28.4m
AGM Trading & Strategic Update - covering the 20 weeks to 18 Jun 2017 (since the company has a January year end).
LFL sales are still negative;
Group sales were up 5.1% for the first 20 weeks of the financial year with like-for-like sales down 4.5% for the same period.
The trading performance of the business continues to be stable following the improvement in like-for-like sales from the initiatives introduced throughout the estate.
Personally I wouldn't describe -4.5% LFLs as "stable".
The big issue here is how will the relationship with major shareholder 2Sisters Food Group pan out? Nothing much is said on this issue, apart from generally soothing words;
Following the announcement of our strategic partnership with the 2Sisters Food Group, we are making good progress on the transitional plans and operational synergies that will deliver the expected customer and financial benefits.
The standalone fresh meat factory shops are all trading in line with expectations. A further 4 new shops of this type are to be opened later this year.
Directorspeak;
"We are pleased with the progress we've made and the continued level of stability achieved in the core business against the current backdrop of industry-wide cost pressures and a challenging consumer environment.
Our new fresh meat factory shops continue to perform well and we are further encouraged by our most recent opening at Crystal Peaks, Sheffield. Our strategic focus for the rest of this year will be to open 4 more fresh meat factory shops and to ensure that we are maximising the customer and financial benefits of the new supply partnership across the estate."
My opinion - I've ummed & erred on this one, and just can't make up my mind.
It made a brief appearance in BMUS, but then I got cold feet & threw it out. At first, I quite liked the supply partnership with equity investor 2Sisters. However, on pondering it more, I came round to the view that the inherent conflict of interest with this arrangement made the share too difficult to value.
It might work out well, and 2Sisters might push a lot of cheap product into CRAW, in order to boost its profits, and drive up the share price. Alternatively, 2Sisters might seek to maximise its own profits, by getting rid of unwanted stock through Crawshaws.
I generally don't like any related party arrangements. It's much better when things are all done at arms length. For this reason, I have to file Crawshaws in the "too difficult" tray.
Incidentally, I've been updating my reports further in the afternoon & evenings this week, so there might be new sections you've missed. So if you're interested, it might be worth having a quick look on the SCVR landing page, which lists them all (scroll down).
Sorry, didn't manage to do any more sections on this report, was too tired. Sometimes it flows easily, sometimes it's a struggle.
Regards, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

17 comments
You mentioned in your article about shorting Debs, Halfords etc. How do you go about shorting stocks like this? What are the practical considerations etc?
Through spread bets or CFDs. Shorting is an expensive game you have to pay out dividends to the person who has loaned you the stock and pay short interest.
Hi Paul,I agree with your commentary on Craw.IF they accelerated the shift to factory shops AND upstream partner delivered much stronger operating margins it might fly. I was concerned no ' hint' on improving margins. Given LFL declines still significant vs new openings I'd worry it might be taken private rather than chasing the 40p warrants. A northern food retailer in increasingly tough economic times appears to offer as much risk as opportunity.
Paul, re Fairpoint (LON:FRP) thankfully sold my shares on Friday. It suddenly occurred to me to check what was happening with the accounts which I recalled had been promised, then I saw how they hadn't published them when they said they would and it was almost 6 months since the year-end. Crucially, you have often mentioned that late accounts is a red flag and that is what pushed me to immediately sell out. So thanks very much once again for your advice.
I agree about lots of rubbish falling away. Mind you UKOG has more than doubled on huge vol this week after an amazing statement. Does the Weald contain more oil than the North Sea ever did? Most unlikely but just the thought keeps me interested in this group of stocks.....despite all the warnings about oil explorers ending up in a puff of smoke!
Interesting observations Trident. I am also noticing the froth coming off smaller cap shares, in particular. The ones I am trying to avoid are those with higher volatility, perhaps suggesting PI leverage or poor liquidity.
Not much gets in my portfolio these days unless it's paying a dividend though! It helps me to be patient.
The other point that Paul makes regards valuations. When the market does turn, we will have to rebase our valuation models. PERs of 20+ seem to have become the norm.
Paul,
The AIM listed firm James Cropper (LON:CRPR) announced results yesterday. I noticed today that Stockopedia is flagging it as having a high risk of earnings manipulation whereas previosusly the risk was low.
Is there any chance you could look at why the Beneish M Score has changed so much and whether there is genuine cause for concern?
Any chance of looking at Molins (LON:MLIN) this afternoon / evening, please Paul?
Looking at my current portfolio I would say some of the froth of the AIM stockmarket bull run has blown off. However, of course those moving into some cash are to an extent creating a self-fulfilling prophesy, as in particular with AIM shares, with liquidity, wide spreads etc., they do move prices fairly rapidly even by smallish sales. As these prices fall more rapidly, they may push others wavering about cashing out some value to follow the trend.
It's worth taking a look at this AIM spreadsheet of all companies in the index. In particular, I would draw your attention to the sheet where companies in the index are weighted by market cap. Interesting to note that a small number of companies with sky high multiples now dominate the top weightings in the overall index.
http://www.londonstockexchange.com/statistics/historic/aim/aim-statistics-archive-2017/aimstatisticsmay2017.xlsx
Tabhair,
Thanks - that is really, really interesting data!
I hold a few companies in the top 25 by value but I am very pleased to see that none of them appear on the top 25 companies by monthly trading volume or monthly traded value. I much prefer investing in quiet, under-the-radar stocks. It makes me nervous when I own things that are highly popular and wildly controversial. Boring is good!
Rgds
Phil
"I'll have to dust down my disco shoes. Only joking - they never get dusty, due to constant use!"
Quote of the week!
Hello Paul,
Might you have time please to look at yesterday's results from PHTM? The share price has reacted fairly negatively towards them. It seemed to me that the headline numbers were excellent but driven significantly by exchange rate movements but would be interested to hear your thoughts.
Whilst writing as this is the first message I've sent can I say thank you for these daily reports. They are so very interesting, the first thing I look for at lunchtime! (Except my sandwich!)
Kind regards,
Simon
Hi Paul
Any chance you could cover Xafinity XAF? It's results were published today. One thing that puzzled me was net debt and net asset values. Would appreciate some expert explanation of these figures.
Thanks
Hi,
I don't cover that sector unfortunately - it's a pensions actuarial, consulting & admin business.
I'll email Graham, and see if he's around, and has time to look at it.
Regards, Paul.
Hi prem14,
Unfortunately, Graham was snowed under with other work today, so didn't have any spare time to look at Xafinity (LON:XAF) .
I did notice the following comment on XAF from a friendly analyst at one city brokers today;
Conclusion: Given they are about to get increased regulation headwinds I have no idea why anyone would own a stock where the upside is 5% growth on a PER of 19X.
Regards, Paul.
Thank you Paul, much appreciated. I will keep a note of that. You are right about being cautious these days. From last year until early this year my humble portfolio used to show upside but that has vanished although I can appreciate the dividends I get occasionally. So, yeah XAF sounds dodgy now to me.