Small Cap Value Report (Wed 29 Nov 2017) - IPX, MOTR, CINE, VRS

Morning Everyone,
Thank for the requests - as usual, I prioritise stocks which appear in the comments, while also keeping an eye out myself for new ideas! Paul will be back tomorrow.
Cheers,
Graham
Impax Asset Management (LON:IPX)
- Share price: 161.5p (-3%)
- No. of shares: 128 million
- Market cap: £206 million
This is an environmentally-focused asset manager which I've written about several times this year.
Unfortunately, I didn't have the spare funds to invest in it earlier this year, when it seemed quite cheap against its earnings and prospects.
The value proposition is different now that the share price has trebled in a year:
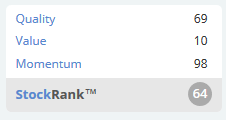
So today's slight dip in the share price is in the context of a company where great things have arguably already been priced in.
The results are excellent, as expected. In the year to September, AuM increased by over 60% (we already knew this thanks to the Q4 update:
Assets under management and advice ("AUM") increased 61% to a new peak of £7.3 billion (2016: £4.5 billion), rising further to £7.6 billion by 31 October 2017
Record net inflows of £2.1 billion across several strategies and geographies
So inflows were responsible for three-quarters of the AuM, with market movements responsible for the rest.
Note also that the $52.5 million acquisition of similar US outfit Pax World is set to complete in Q1 2018. This is a debt-funded acquisition which will increase the company's risk profile in the short-term, but could super-charge earnings per share in future years.
The financial highlights below show the effect of operational leverage, as op. earnings rises at a much faster rate than revenue.
It's worth bearing in mind, naturally, that inflows during the year will not have generated fees for the entire year. You only generate fees on average AuM, not on closing AuM.
Revenue: £32.7 million (2016: £21.1 million)
Operating Earnings: £7.9 million (2016: £4.2 million)
Profit before tax: £5.9 million (2016: £5.2 million)
What may be disappointing investors a little bit is the rather muted PBT figure.
£1 million was spent on advice related to the Pax acquisition. £0.6 million has also been lost in FX translation of the value of foreign currency in advance of that deal. There are some more costs which are contingent on the deal completing.
Without those costs, Impax would have reported a 44% increase in PBT - it just goes to show how expensive deals can be in the short-term, and why organic growth is so valuable.
Overall, though, the results look satisfactory to me. A lot depends now on the deal successfully going ahead.
I've warned previously about inflows being from a relatively small number of customer mandates.
Today we get an update on the level of customer concentration here:
Revenue from three of the Group's customers individually represented more than 10 per cent of Group revenue, equating to £5,243,000, £4,275,000 and £3,428,000 (2016: three, equating to £3,644,000, £3,267,000 and £3,003,000).
As the company gets bigger, it will hopefully also become less risky, from an investment point of view, as customer concentration diminishes. For now, it is still quite heavily concentrated.
One other thing that caught my eye - whatever about the rights and wrongs of climate change/anthropomorphic global warming, it sounds like Impax is excited about its investments in the sphere of resource efficiency. That's a sector which ought to do well, regardless of global climate change agreements:
We see a proliferation of opportunities to invest in smart systems to manage inventory control, production lines and warehouse space, and to reduce transportation costs across most industries, most notably in consumer goods. We are also following the rise of blockchain technology, which has the potential to transform resource efficiency across supply chains.
Outlook statement is confident.
My opinion
The market cap is around the same ratio compared to (pre-Pax) AuM as it was last time I covered it, c. 2.7%. Again, I consider that to be around average.
The Pax deal increases the level of uncertainty but brings with it strong potential rewards.
Overall, then, I have about the same opinion as I did last time. It's a nice company and I still think it has a positive future. The costs associated with integrating Pax may continue to weigh in the short-term, and the valuation is no longer obviously cheap against its peers.
Motorpoint (LON:MOTR)
- Share price: 175.6p (+2%)
- No. of shares: 100 million
- Market cap: £176 million
This is a used car supermarket focusing on the "nearly new" segment (cars less than two years old and with less than 15,000 miles on the clock. It claims to be the largest independent vehicle retailer in the UK.
There was some trouble with new sites underperforming not long after it IPO'd, but performance has recovered since then.
This is the common pattern of an IPO coming in quite optimistically, running into serious problems, and then giving investors much more interesting buying opportunities within the first year or two (assuming that the underlying business is sound).
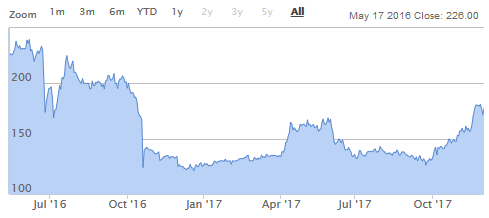
You could buy Motorpoint at nearly a 40% discount to its IPO price within the first year of its IPO, and it remains below its IPO price today:
Today's results show a healthy recovery, with adjusted PBT coming in as expected after the most recent update:
Revenue increased 18% to £483.2m (FY17 H1: £408.9m)
Profit before taxation and exceptional items up 64% to £10.5m (FY17 H1: £6.4m)
Profit before taxation up 304% to £9.7m (FY17 H1: £2.4m)
Just one new site was opened, so hopefully even if it were to underperform, the effect on group earnings would not be so bad.
Today, it's confirmed that the new-ish sites are now maturing well:
The new sites that have opened in the last two years continue to deliver an improving performance as they gain awareness in their local markets and increase our share in the nearly new market.
Outlook is in-line for the full-year result, with management expressing confidence now that H2 started well.
The interim dividend increases 50% in another sign of confidence. and there is a separate announcement of a share buyback of up to £10 million.
I'm a huge fan of share buybacks and I find it really interesting that Motorpoint are choosing to do this.
If I was running a company whose shares I thought were undervalued, and if spare cash flow was available, buying back shares is exactly what I'd do.
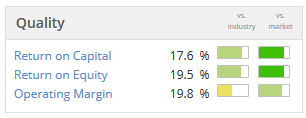
Like many other car retailers, Motorpoint's shares are cheap by conventional metrics. It also has a strong net cash position.
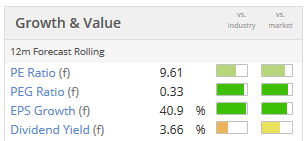
The question is what to do about this - you can do nothing, and accept a mediocre rating (which may be justified after all, given how competitive the industry is, and the macro headwinds).
Alternatively, you can increase the risk profile a bit, but give your long-term shareholders the chance to make a really meaningful return. Buying back shares is a great way to do that - it puts free cash flow to good use, it's cheaper than making acquisitions (lower transaction costs), and it removes shareholders from the register who don't believe that the shares are undervalued.
Maybe other car retailers should follow Motorpoint's lead?
The growth strategy is to open another 20 sites in the medium-term. It currently has 12.
But given what happened with the four underperforming new sites in the last couple of years, it seems to me that it would be better if growth happened at a cautious pace, to avoid running into too many complications all at once.
The company's minimum goal is to open at least one site per year, and that sounds like it would be enough.
The thing is that when the shares are rated on a cheap-ish multiple, then spending spare cash on buy-backs, as the company has announced, can be a lot safer and more productive for shareholders than opening new sites.
Cineworld (LON:CINE)
- Share price: 578.25p (-17%)
- No. of shares: 274 million
- Market cap: £1,584 million
Possible offer for Regal Entertainment Group
This is much bigger than we usually look at here, but is a popular share among readers and is one I've mentioned before.
Last time I mentioned it, I speculated that 2017 would be a better year for box office sales than 2016, based on the release of some slightly more interesting movies, and a few dependable sequels. That has indeed been the case if you look at the US stats here.
Cineworld has produced excellent growth in recent years through the consistent reinvestment of its earnings, and moderate amounts of debt.
This potential deal would transform it entirely:
The Board of Cineworld notes the press speculation regarding a potential acquisition of Regal and confirms that it is in advanced discussions with Regal, the second largest cinema chain in the United States, and is finalising due diligence in relation to a possible all-cash offer to acquire 100% of Regal at a price of US$23.00 per share (the "Potential Transaction").
Before news started to leak, the Regal share price was around $16. That makes for a generous premium at $23.
It also makes for a huge deal worth $3.6 billion or about £2.7 billion. Significantly larger than Cineworld's current market cap!
How to fund it - "incremental debt and a material equity raise".
It would qualify as a reverse takeover under the FCA's listing rules.
I've taken a quick look at the rules for reverse takeovers. Speaking very roughly, I think that any deal which involves the taking over of a larger company by a smaller company counts as a reverse takeover (the Consideration Test at this link). I could be wrong on that.
What this means is that Regal shareholders won't necessarily end up being majority shareholders of the combined group. If Cineworld raises enough funds from existing shareholders, and borrows enough additional funds, then existing Cineworld shareholders could remain in charge. We will have to see the finalised terms of the deal.
For now, I am not surprised that the shares have fallen, in advance of a very large equity raise. Anybody who doesn't want to contribute to the equity raise is going to end up diluted, and even those who do participate will face the risks associated with a higher debt load, assuming that the deal goes ahead.
But 17% being such a large fall suggests that rather large numbers of existing shareholders disapprove of the deal and do not want to stick around to see what happens.
Anybody holding it needs to decide for themselves.
My opinion
For me, this deal is too big. There must ways to gain access to the US market without buying the second-biggest operator!
Remember that the StockReports are available for international markets, so you can easily look at Regal's stats here.
By my calculations, the proposed deal will involve paying 23x Regal's 2017 forecast earnings, or 22x 2018 forecast earnings.
Like Cineworld, Regal earns a fairly ordinary return on capital and appears to be carrying around $2 billion in debt. That means the enterprise value for this deal is more like $5.6 billion, or over £4 billion.
Again, it's just too big. I would be selling if I owned Cineworld.
Versarien (LON:VRS)
- Share price: 39p (-12%)
- No. of shares: 147.5 million
- Market cap: £58 million
This is an advanced materials business, still at an early stage financially, but with rapidly increasing revenues. It sells "a range of standard and customer specific thermal products", along with various graphene and plastic products. In total, it has five subsidiaries with a quite diverse range of capabilities.
Operational highlights sound good, and include winning a couple of competitive tenders from the Centre for Process Innovation. It also received its largest order so far which must have been from Rolls-Royce Holdings (LON:RR.) ("the UK's largest aero engine manufacturer").
Financial highlights for the half-year are as follows:
Group revenues increased by 167% to £4.38 million (H1 2016: £1.64 million)
LBITDA* reduced to £0.43 million (H1 2016: £0.80 million)
Loss before tax almost halved to £0.77 million (H1 2016: £1.47 million)
LBITDA is the loss before interest, tax, etc.
Graphene sounds like the exciting part:
We continue to see significant interest from global OEM's wishing to use and evaluate the benefits of using our graphene powder and ink in their applications. The results of these collaborations will be known over the coming months, but require the purchase of additional equipment to satisfy just their sample and testing requirements....
Our focus now, is on ensuring that we support our potential large scale customers in conjunction with the renowned connections we have with both the Universities of Cambridge and Manchester, both of whom are shareholders in both the graphene companies and Versarien.
The company raised £2.8 million (net of expenses) this month, to buy new equipment for graphene production.
My opinion
It's a small, loss-making company. So I'm probably going to be cautious about it, as you'd expect.
For small companies, it's helpful to look at their gross margin to get an indicator of the value-add they perform. Hopefully, as they grow, operational leverage will kick in and then their gross profits will dwarf their operating expenses. That's the ideal, anyway.
The gross margin achieved by Versarien in the period was 24%. Of course, this is complicated by the fact that Versarien has several different pieces to it, and its mix of activities several years from now might be completely different to mix of activities it does today.
But for the sake of comparison, look at Morgan Advanced Materials (LON:MGAM), which has a market cap of c. £900 million. It produces advanced ceramics, carbon, alloys and graphite.
Morgan Advanced Materials (LON:MGAM) has a gross margin of about 60%. To me, that's what a really good margin looks like in the materials business.
So I'd have to be a bit sceptical about Versarien for now. Also, the valuation prices in quite a lot of success, since it is many multiples of forecast revenues out to 2019.
Good luck to any of you who are holding it, this one is not for me!
That's all from me today. Cheers,
Graham
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

78 comments
acdoug - The RNS said that Global City Holdings has 28%. It was pretty clear on that. Global City is the family vehicle. We could check in the annual report but I am pretty sure that is the case. See page 63 which makes it clear:
http://www.cineworldplc.com/~/media/Files/C/Cineworld-PLC/reports-and-presentations/cineworld-ar16.pdf
Hi Graham, just wondering if you still believe Rightmove is a Short, particularly whilst its in the middle of purchasing its own shares, which obviously keeps propping up its share price.
Re Barclays - disheartening to hear of the continuing transfer delays. I decided to largely 'sit it out' for the time being but will it become clear when delays have reduced? I really don't like the idea of being unable to sell holdings for 10+ weeks! Not even by phone if a sell-off hits? As others have said, it may be an idea to realise low-conviction holds before starting the transfer process.
For my ISA I opted to partially transfer £35k in cash to another ISA provider but even that simple transfer took them 7 weeks.
Another Barclays whinge. I was completing my CGT tax return last week and discovered Barclays has no trades data on my MarketMaster account prior to Sept 2012! Under the old system you could click on a share and see your full trading history. "Progress" no doubt!
Cineworld (LON:CINE) - Just a few pointers. It is an all cash deal so Cineworld would remain in control. It may be legally a reverse takeover but Cineworld would be buying Regal for cash. That is what Cineworld's announcement states. Interestingly Regal refer to it as a "merger."
US box office - The link you shared shows US cinema spending falling in 2017 to date on a year ago not increasing. This is why Regal's share price has been weak. US cinema attendance has been weak from what I have read this year.
Finally it is worth noting that Cineworld investors can vote the deal down. Given the share price reaction they may be likely to do so. Global City, the vehicle of the management, have 28% so they can't get the deal through. I would imagine the deal needs majority approval.
I agree with your general thesis that on face value it looks like a strange deal. The question is how attractive the US market is. I would imagine it is fairly mature. I would also of thought there would be few synergies given the different geographies. The only real argument for the deal is that Cineworld is buying into US cinema at a good time and buying a good operator. I can't seem to get figures for US cinema attendance but attendance in North America has weakened recently: http://www.the-numbers.com/market/
Shares in AMC and Regal (the two large US operators have been weak). The trouble for me is that if investors wanted US cinema exposure they could buy these companies directly. Why do investors want to fund a takeover through Cineworld at a takeover premium if there are few synergies? Cineworld's existing markets are also less mature than the US and so appear to have better prospects.
I would have to say that this is one of the most bizzare proposed transactions I have seen. Cineworld's combination with Cinema City a few years ago had some investors scratching their heads. The current proposed deal has investors banging their heads against a brick wall.
Two important corrections there - thank you very much.
Cineworld (LON:CINE) I think that the Greidingers EACH have 76m shares held in Global City Holdings - a total of 56%, and a simple majority, although the takeover may need 75% approval. I suspect they'll get it
I would take any day a decent dividend from a company than watch it do `share buybacks`.
The first is that nobody can predict the long term share price of a company and it could easily fall and stay for years below the share buyback price
In my experience a lot of company boards like share buybacks because the executives have lucrative options linked to short term share price performance whilst stockbrokers linked to the company like the commission action and there are probably hidden quid pro deals going on between executives and their stockbroker.
The one stockbroker I know well made his money from inside information
Hi all
For anyone interested there seems to be a rather big sell off in US stocks occurring as I type. I have about 30 in a US watch list. Virtually all a down over 7% some as much as 17%. A lot of my list are Tech and thus NASDAQ listed, but I think this could read across to UK stocks in the morning in areas such as IQE (LON:IQE). Obviously purely my interpretation.
Regards
Howard
Yes, interesting developments. It looks like the NASDAQ tech stocks have been tumbling. The other indices Dow, S&P and Russell look OK within the usual daily range. No sign of the tech shakedown spreading.
Hi I just did a reply to Herbie with this piece which adds insight into the chip makers sell offs
http://www.nasdaq.com/article/chip-stocks-tank-on-morgan-stanleys-soft-nand-price-outlook-cm883634
Regards
Howard
Thanks, yes I saw that yesterday. I hear investors are switching out of tech. Into banks and builders. I sold my IQE (LON:IQE) but do have some us tech shares. Will see what happens tomorrow.
Yes I saw that but that was before our close, Euro tech shares are down also but UK ones seem to have escaped today.
Herbie
This might have some bearing on the falls.
http://www.nasdaq.com/article/chip-stocks-tank-on-morgan-stanleys-soft-nand-price-outlook-cm883634
This might also explain the read over to European chip maker stocks. This is why I sense IQE (LON:IQE) might get hit a bit (I hold).
Regards
Howard
Re LON:CINE I agree with your analysis Graham. From my point of view most of the drop had occurred before I started to think and now the price looks very low against the previous valuation of the present business. It is interesting that the present management came in on a similar but much smaller deal but it is hard to see how the present one could be structured especially now. I guess there will be some head scratching going on.
MH
Versarien (LON:VRS) seems popular, I am looking at it now.
Vast Resources (LON:VAST) is in the resource space which I generally don't cover, sorry.
Thank you for the requests.
RE: Image Scan Holdings (LON:IGE) Does anyone know what's going on? Yesterday an LLP associated with the CEO sold 3.66% of the company and today Spreadex bought 3.1%. Spreadex are on the IGE website as a shareholder. Seems weird to me especially if he sold high and then bought back after the dramatic 20% fall. Surely the company should explain what just happened and not hide behind these share ownership vehicles trading shares with no clear beneficial owner. Or am I missing something?
Graham, interesting comments in the virtues of share buybacks.
I take a completely different view. I remember working in one back in the 90s for an electricity board who saw them as a way to increase eps (and hence management bonuses) without doing much. This was one of the early ones and they’ve become prevalent nowadays.
The problem is that most companies are not good judges of buying their own stock, and inevitably do them at completely the wrong time, at high prices. I don’t buy shares in a company so that they can buy their own stock, I buy them to invest in their business. So if they run out of ideas to invest in (never a bad thing, rather than squandering on a bad acquisition), then better to pay a special dividend. That puts cash in my pocket (obviously tax treatment dependent on circumstances).
All too often they are used by lazy, greedy management who have run out of ideas and want a way to guarantee their annual bonuses and LTIPs (not in every case I grant you...)
Thanks for the comment and it's good to hear about your interesting experiences in the past. Yes, buybacks do need to be well-executed, and are a hazard when they are not. Wouldn't you agree that dividends can also be badly executed? Many companies have given out big dividends a year or two before they went bust! Dividends and buybacks are both ways of spending money instead of investing in the business.
The solution to the specific corporate governance problem that you cite is for management to be rewarded on things other than EPS. Return on capital is a good choice. Swapping debt for equity capital then has no effect on management bonuses. Of course you still need somebody to decide what the right mix of debt and equity is, in that case. Rgds.
Hi Graham, agree with your points, and yes dividends can also be mis-timed! Unfortunately I tend to find few companies with enlightened management who base renumeration on measures other than EPS (for large caps) - or at least a mix based on EPS.
That's why generally I prefer companies who maintain negative gearing and have a lot of cash - it might be a drag on statistical performance but it's also a buffer. Even better when you find ones that have the discipline to hold increasing amounts of cash as the years go by - and not squander it on acquisitions!
And I feel that we're heading towards a time when companies with high borrowings will suffer compared to those that don't.
I agree,but do Motorpoint not have rather a lot of debt ? You referred to their 'strong net cash position'.
On Revolution Bars (LON:RBG), I'm sure Paul mentioned a few weeks ago that he'd buy more if the price dropped to 150p
They have bounced nicely from there
Revolution Bars (LON:RBG) seems to be coming back to life after being in the shareprice doldrums
Apparently Revolution Bars (LON:RBG) are opening three new sites, due to start trading before Christmas. I don't have any corroboration, just a post on the (hysterical) LSE site. DYOR!
Hi Graham,
Thanks for writing up about Motorpoint (LON:MOTR). You say that Motorpoint has a strong net cash position, but the Stocko report says the EV (£230m) is greater than the Market cap (£172m) which implies net debt but having read the interims this morning and looked at the balance sheet, I can't see any loans or borrowings. Trade payables are high but note 14 provides more detail about these. Am genuinely interested if the Stocko page is incorrect or if I've missed something.
Best wishes,
Imran.
Imran re. Motorpoint (LON:MOTR)
It looks as if Stocko data is wrong.
If you look at the balance sheet in Stocko, under long term liabilities, there is a £64.9m long term debt + £5.2m payables. Which matches up with the net debt position of 64.9 - 7.3 = 57.6m And EV = market cap172.3 + net debt 57.6 = 229.9m
However both today's interims and last finals do not have £64.9m as long term liabilities in their balance sheets.
The Stocko data looks to be correct - just that ThomsonReuters have chosen to reallocate the £64.9m relating to stock financing facilities from trade creditors to debt.
It certainly appears to be more like debt than trade credit:
I know some of you are interested in SafeCharge International (LON:SCH) (I don't hold), there is a positive trading update today which has buoyed the share price; in summary:
Trading ahead of the 2017 year-end has been strong, as a result the Group's financial performance for the full year is expected to be in line with market expectations.
The Company continues to make considerable progress with its strategy of winning Tier 1 customers within both traditional verticals and in new target verticals and markets...
The Board is encouraged by the Company's strong performance during the second half of the year. The Group will enter 2018 having expanded its Tier 1 customer base, with customers in new sectors, including travel and retail, and new markets, and with a strong pipeline which provides confidence for 2018 and beyond.
Hi guys, I will do Cineworld (LON:CINE) next. Cheers
Several comments on here regarding Cineworld (LON:CINE)
I have just realised the size of this:
Cineworld currently operates 2,217 screens across 232 sites (recent trading statement)
Regal currently operates 7,315 screens across 561 sites ( http://investor.regmovies.com/ )
Graham
£D4T4 half year results came out yesterday accompanied by a substantial drop in SP. If you have time, it would be great to get your thoughts. Thank you
Francis
(And before everyone shouts at me, I did put the £sign before but it doesn't seem to work!)
Does not seem to work if there is a number included such as £G4M.
lenovo chinese keyboard without gbp sign!
You can copy a £ over. Copy and paste.
lenovo chinese keyboard without gbp sign!
You can get a pound sign in Windows by holding down the Alt key, typing 0163 on the numeric keypad then releasing the Alt key. Num Lock needs to be on to type numbers on the numeric keypad - generally it will already be on except on smaller laptops. Alternatively you can copy and paste one in (e.g. from here: £ or by googling for one).
To get capital letters (used for stock tickers, the beginning of sentences, proper names and initialisms such as "GBP"), hold down the "Shift" key (just below "Caps Lock") when typing the letter.
Hold down the Alt key and type 156 on the keypad (not the numbers across the top). £, there, I just did it.
Another vote for Versarien (LON:VRS) please.
50% of posts today without the £sign. It helps everyone if you put the £sign before the ticker name so a link appears. For instance, say you are talking about IGE, put £sign before IGE to get Image Scan Holdings (LON:IGE). Simple.
Thank you fyburd I could not see how to do it.
LOL - So Cheeky - I saw what you did!
VAST are holding an open offer at the same rates as a recent placing so that its PIs are not disadvantaged. Not seeing anything on my Barclays Account I rang them. After a never ending series of "security" questions and a 20 minute wait the guy came back with the bald statement - "Barclays are not participating in that offer"
Odd. It could have something to do with this:-
the Circular is not, and is not required to be, a prospectus for the purposes of the Prospectus Rules and has not been prepared in accordance with the Prospectus Rules. Accordingly, the Circular has not been, and will not be, reviewed or approved by the Financial Conduct Authority of the United Kingdom
Alternatively, the announcement was only made 2/3 working days ago, and it's quite possible the paper work has yet to arrive/be processed. It always takes a few days for offer entitlements to turn up in accounts.
First rule of dealing with front line brokerage staff (at any execution only broker) - don't assume that what you are told is always accurate!
Peter
Please could you look at SND and GHH finals from yesterday?
I am also interested in the news from Cineworld Cineworld (LON:CINE). On a side note I am baffled why so many comments on this thread this morning are being voted down. (Very bizarre and I guess my comment will now be voted down.)
VRS & PETS please, although PETS is mcap £800m so probably falls outside your remit??
Thanks
VRS and Cineworld for me please.
VAST are holding an open offer at the same rates as a recent placing so that its PIs are not disadvantaged. Not seeing anything on my Barclays Account I rang them. After a never ending series of "security" questions and a 20 minute wait the guy came back with the bald statement - "Barclays are not participating in that offer"
I have never heard that before -How can they arbitarily decide to disadvantage their clients???
Re Barclays not participating in an open offer.
After the chaos and farce of the conversion from Barclays Stockbrokers to Barclays Smart Investor (BSI) - lots of stories available on the internet for those who haven't heard - I was hoping that BSI would settle down into a decent service. Your story suggests not. The only thing that has stopped me moving of Barclays are the huge difficulties and financial of transferring a large portfolio to another broker.
Any strong recommendations on brokers who provide a good service, get good prices on shares (trade within the spread) and don't overcharge would be very welcome
I believe a lot of BSI investors switched to Hargreaves Lansdown, they not perfect but service is pretty good. Think charges are similar, prices not bad, my main gripe is the forex charge on foreign shares. No trailing stop losses yet.
This is not a recommendation for a broker. It is a very strong warning re leaving BSI at the moment. I have finally managed to do so and it was a dreadful ordeal. I received advice that was simply wrong. It took 10 weeks to complete the transfer. I received different answers to my questions depending on who took my call. I could go on all day! It was so bad my wife wanted me to just sell and close the account thereby losing a significant sum In an ISA.
My advice would be to hang on in there for a few months until the backlog is cleared and your holding can be transferred more quickly. I wish now that I had waited.
My wife is still awaiting her ISA to be transferred and her transfer was started early September. As her account is of a lower value than mine with,at the moment, only one holding we are simply sitting that one out.
Thank you Mr Third Man for your warning re. leaving Barclays Smart Investors. I will take your advice and leave it a few months before transferring. That will also give me more time to check out the alternatives. And it is scandalous that the transfer process is so difficult. Any stockbrokers with decent computerised systems should be able to complete the process within a few days if they just wanted to be helpful.
I do hope all your assets transferred successfully, that you did not lose too much from being unable to trade during the transfer, that your wife's ISA makes its way across sooner rather than later and that the new service is better than Barclays (the last of those wishes won't be too difficult). Or maybe I should wish you a happier ending than the third man in the eponymous, wonderful film.
I decided in September to move away from Barclays and after some research moved to Interactive Investor whose prices are competitive and my experience so far is very good. Not a recommendation as such but worth adding to your list. They do answer the telephone promptly!
Surprisingly in view of what I had heard the transfer “only” took 1 month! However, extracting statements from them is like extracting blood from a stone. Problem also is the lengthy waiting times on the telephone. After many phone calls have finally received statements however there is a gap of about a month so further calls. The worst part is also to discover that despite requesting account closures all 3 accounts have cash in them from dividends. When I asked why this money had not been transferred over I was told they needed further specific instructions!
I am glad I took the decision to move my accounts away from Barclays and would take the decision again now even knowing the problems I would face.
Paul
Thanks Paul
I will include interactive investors on my research list. Good to hear that you are enjoying life after Barclays.
At one time I had execution only with iii and ISA with TD Direct. TD had a great website, were very quick producing tax documents at the end of the tax year and, and were speedy with issues.
iii took an age to produce end of tax year documents - I think from memory it was October! Their website was awful and the only area they did well at was that they allowed small companies to be part of their regular investment scheme.
Now that iii have bought the TD Direct business, at least they have a decent website. It remains to be seen if they can produce tax documentation in a speedy manner next April!
Thanks
It is good to hear that you are almost out now. Hope you can get the last the last statements soon.
Julian
Hello Julianh. Post 36. I had no wish to leave Barclays Stockbrokers but was told, before the Smart Investor introduction, that Non UK ie Channel Island residents (me) were no longer permitted to trade! I put in for a transfer (to IG) in mid July and the shares arrived there on October 6 after a great deal of chasing. Some dividends followed just yesterday and one is still 'in transit'. I lost several thousand pounds in being unable to trade (largely what would have normally been quick sales on profit warnings) my account being inaccessible from the date of the transfer request.
Despite the obvious charges it would have made much better sense for me to sell everything and repurchase through IG. On Tuesday this week I was offered £250 compensation and settled for £400. Not nearly enough but better than nothing!
KP, that's strange, as a non-UK investor I believe you are no longer able to put new funds into an ISA (I'm assuming it's an ISA you are talking about) but you are allowed to keep it open and trade...?
No it's not an ISA it was just a common or garden Marketmaster share dealing account I had with Barclays. I'd had it for about 14 years and then without any prior warning I was no longer welcome. So my request to transfer was made well before the Smart introduction and host of transfer requests. Still took about 12 weeks! Incidentally I'm very happy with IG.
Thanks Keith
I may have to follow your advice, sell everything, transfer the cash and take whatever loss there is as a result.
Hope you enjoy IG
Julian
I went through the process of moving accounts from Fidelity to Halifax and from HL to Halifax. HL transferred the shares in specie in about 8 weeks (2 weeks to notify me that it costs money and 6 weeks to effect the transfer after I paid them) but the cash took a futher several months of constant reminding. Fidelity to Halifax took about 5-6 months of constant prodding with each side (unsurprisingly) blaming the other and no one willing to pick up the phone to the other.
In researching my complaints to the Financial Ombudsman I came across a Telegraph article (http://www.telegraph.co.uk/finance/personalfinance/investing/isas/11108470/Three-months-Isa-transfers-now-take-six-days.html) where brokers appear to be extolling the virtues of an electronic account transfer system created in 2012. An excerpt:
"Rebecca O’Keeffe of Interactive Investor, the fund shop, said that since signing up to the system in August transfer times had fallen to six days from around a month previously.
“Some have been even quicker – our record is 13 minutes,” she said."
I wonder why nobody in the brokerage industry uses an electronic transfer system that's been around for 5 years and takes as little as 13 minutes to complete an account transfer? Oh wait, maybe it's because of what happens to people like this guy (http://www.telegraph.co.uk/investing/isas/it-cost-me-1000-to-leave-hargreaves-lansdown---but-its-still-wor/) who got charged £1,000 for a process that would have cost next to nothing to do electronically.
I use Hargreaves but less and less nowadays. I think they are too big these days to offer a decent customer service. Incidentally if you take part in primary bid offerings...Jarvis don't charge a £25 fee.
Hi Julian
I use AJBell You Invest.
Please note that this is not a recommendation, just feedback, but for me they are the 'Stockopedia' of the online broker world. That is, they listen to what you have to say and go beyond just paying lip service to any concerns you have; which cannot be said of other online brokers I have or have had dealings with.
Having said that, I have had very few reasons to contact AJBell as everything usually runs very smoothly, but if I do have something worthwhile to say they listen and if something important to ask, they reply promptly and correctly.
Maybe worth a look
Santa
Thanks Santa
I really appreciate your response to my question and all the other responses I have had. This really is a mutually supportive community. I also have an account with YouInvest and so far have had very much the same experience so they are definitely on my list of options to take over the portfolios currently being held with Barclays.
All the best
Julian
I am a Trustee of a trust which had an account at Barclays. They wrote and said they were not providing the service to trusts any more. You would think after that, they would want to get shot of me quickly. But no. It took around 3 months, and numerous phone calls. TIP: if you "escalate" to someone more senior, you can get yourself prioritzed.
I moved to Share Deal Active at Jarvis, who seem fine.
And I complained vigorously to Barclays who rang me today and offered me £200 compensation for my "inconvenience and distress!" So TIP No 2: if they have messed you around, complain!
Thanks
Congratulations on getting out well. I haven't heard of Share Deal Active so will definitely have a look at it.
Re: VAST Open Offer.
Hello jraitt, in contrast to your experience from Barclays I received full details of the Open Offer from Hargreaves Lansdown (where I have a fund & shares account) with a deadline of 7th December to decide if I want to participate. I only purchased the VAST shares a few days ago.
The investment club I chaired had a Barclays sharedealing account and my experience is that they provide an awful standard of service to retail investors, particularly if there is a problem that needs to be sorted out. My experience is that they are very unsympathetic to private investors. I actually ended up taking them to the Financial Ombudsman on behalf of the investment club.
I would also be interested in your views on IG Design I thought the video by the CEO yesterday was very encouraging and it is now on my watch list.
Another one that got lost under the duvet yesterday was £ACL now Discovery (LON:DSCV)
Along with inline results it announced an idiotic name change.
Comments on that as well as the results would be appreciated.
+1 for Cineworld (LON:CINE)
Motorpoint (MOTR) looks interesting if you have the time Graham. It reported interim results and a share buy back this morning. It seems to be doing well despite the malaise suffered by the car industry.
Cheers
jonno
Impax and Versarien too please Graham
And, if you have time it would be nice to have your thoughts on a couple of companies that got lost under the duvet yesterday:
* Treatt (LON:TET) - final results and a placing (at a very small discount) to fund growth
* IG Design (LON:IGR) - Interim results
Thanks
I'll second the request for a look at Impax Asset Management (LON:IPX). Graham has covered this specialist asset management group several times this year. Overall the figures look very good:
* assets under management +61%
* revenue +55%
* profit before tax +13%
* diluted earnings per share +72%
* cash reserves +32%
* diluted eps +72%
* and all of this before the hoped for benefits from the acquisition of Pax.
There are however quite a few large one-offs in both directions including acquisition costs (on the Pax acquisition) fair value losses on investments (what is this?) and a very large tax credit. In consequence revenue growth is significant, profit before tax growth is a much more modest 13% and eps growth (after the tax credit) is an impressive 72%
In a previous SCVR, Graham also warned that growth in assets under management can be the result in a few large new clients which may not be repeated in future years and may be reversed. At the same time, the acquisition should bring efficiencies of scale which should show in an improved bottom line.
I am long Impax Asset Management (LON:IPX), at the moment a relatively small holding.
As always lots of thanks to both of you for your excellent coverage. It is an added benefit that you have different interests and ways of thinking about investing.
12 months to the day that I first bought Impax Asset Management (LON:IPX) I have sold the residue of my holding (a third at 167p yesteday and the rest today at 152p having missed the opening price due to a pc malfunction!)
A great growth company but I feel the price has got ahead of itself and the future is all baked in at 150p.
Many of Impax's holdings and clients are outside the UK, which derisks possible downside with any weakness in the domestic economy. However the perrenial problem I see with asset managers is the double whammy if and when the market drops in that the value of their investments fall and some clients will go to cash. They have of course benefiited from this double effect on the way up!
Impax Asset Management (LON:IPX). Yes, for the business it is a double whammy if the market drops, but for shareholders it is a quadruple whammy:
* Reduced earnings due to a fall in the value of managed investments => share price falls
* Reduced earnings due to outflows => share price falls
* Reduced rating (PE ratio etc) due to lower future expectations (and in IPX's case, loss of momentum) => share price falls
* Reduced rating in line with falls in the overall market => share price falls
We can hope that the positive trends in IPX's specialisms will continue on through any wider market downturn. But if the "sustainability" investment cycle is genuinely separate and longer (or shorter) than the wider investment cycle then sooner to later they'll turn down together exacerbating the situation further.
Arguably it is the reverse of all these factors (along with the takeover of Pax) that have caused the share price to more than triple in only 12 months.
I was already on standby to sell some if it rose any further this morning. The references to market highs and an exceptional year in today's results read like a gentle warning to me. The funds under management at end of October were completely in line with previous growth.
After further consideration I tried to sell 1/3 a few minutes ago when the mid-price had recovered quite close to yesterday's close / today's open, but I couldn't get a sensible quote.
can you cover Motorpoint please (MOTR)?
Graham could you take a look at the CineWorld Announcement. They are discussing taking over RegalEntertainment, which would make them a substantial organisation but I fear a little over the added debt to their balance sheet. All comments of interest.
Hope Paul is on the mend
Impax Asset Management (LON:IPX) & Versarien (LON:VRS) both down (-3.9% and -12.5% - no, now 9%) on results that don't seem to have much new news in them. I am surprised by EVE, if I'd had a better night's sleep myself I might have got up early enough to read the RNS...
Would like ot hear about Impax Asset Management (LON:IPX) from Graham. I think Versarien (LON:VRS) might take quite a bit more research than a day. The ADVFN bulletin board guy Superg1 has been researching for three years.
My morning smallcap tweet:
eve Sleep (LON:EVE), Oxford Pharmascience (LON:OXP), HSS Hire (LON:HSS), LSL Property Services (LON:LSL)
eve Sleep (EVE) 11 months trading: UK rev better than exp at 105% up. Group rev up 130%. Exp UK Q4 profit "after marketing costs". Why say that? Of course after costs! No new FY guidance.
Oxford Pharmascience (OXP) FDA allows OXPzeroTM Ibuprofen formulations to be submitted for approval in the US without Phase III trials.
HSS Hire Group (HSS) Q3 in line but Oct marginally behind management expectations.
LSL Property Services (LSL) 10 month trading. Expects FY Underlying Operating Profit marginally ahead of its prior expectations.