Small Cap Value Report (Wed 3 July 2019) - NAR, SOLI, IMO, MLVN, SOS, LOOP, REDD, TPT, WRKS, PURP

Good morning, it's Paul here.
I'm up early today, to finish yesterday's report, so let's start with that.
Firstly, this section was sent in by Graham
Northamber (LON:NAR)
Share price: 46p (-10%)
No. of shares: 27.3 million
Market cap: £12.5 million
Sale of Warehouse Facility for £16.4 million
Graham writes - This is a share that I feel obliged to keep an eye on, as it was once a major holding for me. Aware of the "deep value" in its balance sheet, I attended the AGMs for a few years and, with one or two other shareholders, tried to impress upon the Chairman the logic in releasing that value.
I first invested in it in 2013 when NAV per share was around 81p. NAV had declined every year since 2007, after profitability evaporated. Tech hardware distribution became obsolete, and there was no economic reason to continue these activities. Northamber has been loss-making for almost a decade and has not made a meaningful profit for many years.
Unfortunately, the Chairman (also the majority shareholder) disagreed with our analysis, and ploughed on with the distribution activities.
After three years, I gave up and sold my shares for a tiny profit.
If I had held on to them until today, I would currently be sitting on a >50% gain from my entry price. But I would have had to wait six years for this outcome. The annualised return would have been ok, but nothing to write home about.
This is the problem with deep value investing - you need a catalyst to unlock value, and the catalyst can be totally unpredictable. How could it be predicted that the Chairman would choose to sell the company's warehouse in 2019, rather than 2021 or 2025? There is a massive opportunity cost in leaving your funds locked up for an unknown length of time in a dead business, waiting for payday, rather than simply buying shares in a good business which you can predict will continuously generate profits and shareholder value.
Indeed, even the sale of this warehouse doesn't guarantee that shareholders are destined for a big payday. NAR shares initially jumped much higher from their prior level of 29p, but that excitement has subsided today.
The reason is that the Chairman appears as determined than ever to carry on with distribution activities. Instead of giving the money back to shareholders, he is going to use it.
From the RNS:
"...the Sale provides an excellent opportunity to release a significant capital sum, whilst also providing time to source a more appropriately sized facility and location for the Company's warehouse requirements. The proceeds of the Sale will be used for general working capital purposes in support of the Company's strategy."
And the Chairman's comments:
"The proceeds from the Sale provide more tangible support to our business and the future development of our evolving strategies."
It doesn't get much more clear than this!
Being an honourable man, the Chairman doesn't draw a salary, so he is not enriching himself by carrying on. He would be much richer if he had invested Northamber's NAV into a basket of equity index funds ten years ago, which is something he could easily have done.
My feeling is that he has an emotional connection to the company he founded, and its employees, and continues to run it for that reason.
So where do we go from here? Northamber's official NAV gets a £10.4 million uplift from these sales, or 38p per share. NAV was just below 62p at December 2018, so let's call it 100p now. I haven't made any adjustment for tax on the sale.
NAV is due a further boost, some day, from the unrealised gains on Northamber's other freehold property. Until then, my best guess is that we will have modest ongoing losses from the legacy business. Perhaps the appreciation in the remaining property (a large office in Chessington) can offset its operating losses, as the appreciation in the warehouse has done?
If I adjust the December 2018 balance sheet for the warehouse sale, I get a pro forma balance sheet like this:
- PPE: £1.9 million
- Inventories: £3.4 million
- Receivables: £8.1 million
- Cash: £21.5 million (much higher than the company's market cap)
- Liabilities: (£7 million)
- Net Assets: £27.9 million or approx 100p per share.
It is a no-brainer for the company to buy back whatever shares it can pick up at current levels, and I am tempted to bet on this happening. At the same time, I'm reluctant to get involved in another waiting game which could last another 6 years or more. Life's too short!
Many thanks to Graham for this contribution - what a bizarre little company!
Back to Paul:
Solid State (LON:SOLI)
Share price: 445p (down c.10% yesterday, at market close)
No. shares: 8.5m
Market cap: £37.8m
Solid State plc (AIM: SOLI), the AIM listed manufacturer of computing, power and communications products, and value added distributor of electronic components, is pleased to announce its Final Results for the year ended 31 March 2019.
Key points, which all strike me as positive;
- Adjusted profit before tax up 18% to £3.5m
- Adjusted diluted EPS 16% to 35.9p
- PER of 12.4 - which looks quite good value
- Revenue growth of 22% splits into 10% organic, and 12% from acquisitions
- Order book recently (31 May 2019) is £35.9m, up 56% on prior year. An acquisition (Pacer) contributed most of the increase, but organic growth was still 20%. Impressive.
So why the share price fall? Is there something untoward in the outlook comments?
Outlook - this all sounds positive to me.
Macroeconomic headwinds "continue to be a challenge", but everything else sounds upbeat. It concludes with;
Over the next three years of our five year plan, we will remain focused on securing quality orders as we drive to achieve our goal we set at the beginning of 2017 to double the size of the business through a combination of organic growth and strategic acquisitions.
The Board is confident that the achievements of the last year and the growth in our open order book demonstrate that Solid State is making good progress towards achieving its goals and that the prospects for the Group remain very positive.
Current trading - a slight glitch here, with Q1 (Apr - Jun 2019) has seen a softer than expected order intake. Despite this, the group is still on track to deliver in line with expectations results for 2019/20.
Balance sheet - looks fine to me. Positive NTAV, decent working capital position, and net debt of only £2.0m - I'm happy with this.
My opinion - this looks a good value share, with management seemingly executing well.
It's done 10 acquisitions to date, which usually puts me off, but in this case the balance sheet remains sound, and diversification spreads risk.
I'm not entirely sure why the share dropped 10% on these results, given that they produced EPS slightly ahead of forecast (35.9p vs 35.0p forecast). Maybe I've missed something?
Overall then, this looks quite a nice GARP (growth at reasonable price) share, in my view, although it's not a sector that particularly interests me.
Stockopedia - loves it, a StockRank of 97, and Super Stock classification.
Also, note that this share qualifies for the "Tiny Titans" stock screen, which I've found to be historically a very good screen, picking up some excellent small caps. That screen has a very good long term track record too, so is worth checking.
IMImobile (LON:IMO)
Share price: 324p (unchanged yesterday)
No. shares: 66.9m
Market cap: £216.8m
IMImobile PLC (AIM:IMO), a cloud communications software and solutions provider, today announces its Unaudited Preliminary Results ("Preliminary Results") for the year ended 31 March 2019.
The headlines read well for this international group, e.g.
- Revenue up 28% to £142.7m, of which 17% is organic - impressive
- Adjusted profit after tax up 39% to £10.8m. Whenever PAT is quoted, I always check to see if there's been a favourable tax reduction! Only slightly in this case, as adjusted PBT is up 36% - so it looks like the company cherry-picked the better number for the highlights section
- Adjusted diluted EPS up 35% to 15.1p giving a PER of 21.5 - not cheap, but if growth continues apace, then it could soon grow into the valuation
Outlook comments sounds upbeat;
The Group is at a very exciting stage of development with technology developments creating momentum in the customer communications sector for more automation and use of digital channels. We are ideally placed to capitalise on this momentum and we believe there is no clear category leader in this market and that, due to our leading position in the advanced UK market, we have an opportunity to play a leading role globally.
The financial year has started well with trading in line with expectations. We continue to have good earnings visibility due to our established client relationships and healthy pipeline of new deployments and high proportion of recurring customer revenues.
We are confident in delivering continued organic growth across all parts of the business.
Lots of positives above. I think management has a lot of credibility here, having established a good track record. I've mentioned here in previous SCVRs, that I've met the CEO, Jay Patel, several times and been briefed on the business by him. Each time I came away highly impressed.
Other points;
Note the massive share based payment charge of £8.9m (versus £4.6m last year)
Balance sheet - not great, with negative NTAV - also receivables look extremely high, which would need looking into.
Cashflow - heavy capitalisation of intangibles (probably development spend) of £6.6m. Nearly £20m spent on acquisitions, part-funded by new bank loan. No divis paid.
My opinion - I like management, and the company. I'm less keen on the balance sheet & cashflow statement. So overall, probably not one for me, although it does look interesting in other ways, e.g. revenue & profit growth, sticky recurring revenues, etc.
Stockopedia's view is middling, with a StockRank of 53, but a positive "High Flyer" classification.
Malvern International (LON:MLVN)
Share price: 3.15p
No. shares: 258.6m
Market cap: £8.1m
(at the time of writing, I hold a long position in this share)
This is an education group, with operations in the UK & Far East. It operates language schools, accountancy training, and various similar activities. The story here is all about a turnaround under new management.
These 2018 results were issued in the nick of time, just before close of play on 28 June 2019. Any later, and the share would have been temporarily suspended. I see that as clearly unsatisfactory, and embarrassing for the company, highlighting gaps in the skill set of management. That's been addressed with the recent appointment of an experienced NED.
Apparently, the accounts had been prepared months earlier, but the various international auditors delayed things, and raised queries at the last minute. So the problem was more about the auditors not being well managed by the company, as opposed to the company itself being in a muddle with its figures, which it doesn't seem to be. Even so it's not good enough, and management realise that, so I don't expect this problem to recur, which is really all that matters. Mistakes happen, people have to learn how to do things at micro caps.
I'm philosophical about these things. At an £8m market cap company, you're going to get a few things going wrong from time to time. The more important thing for me, is that management seems focused on the turnaround. The attraction of which is the operational gearing.
To save me time explaining the business model, this video from our friends Tamzin & Tim at PIWorld is a useful introduction to Malvern (filmed at Mello London, in May 2019).
Outlook - sounds positive to me. Although the implication seems to be that the company was ahead of budget up to end April, and then slowed down to be just in line with expectations now. It's not the most clear wording, and could have been better explained, I think. Note the 2nd half weighting is normal, due to summer schools falling into H2;
"Trading in the current financial year has started satisfactorily and is in line with the Board's expectations for the year as a whole.
Trading up to the end of April was ahead of budget. Sales to the end of April plus sales booked for delivery in the remainder of the year stood at £6.9 million (2018: £3.9 million). As in 2018, trading in 2019 as a whole will be second half weighted as revenue in the second half will benefit from summer enrolments in London and Singapore, enrolment of the universities in the second half, and chartered accountants' courses in more demand through the second half of the year in Singapore."
My opinion - there's not really any point in me delving into the 2018 figures, as it was a turnaround year, with restructuring costs, etc.
The interesting numbers should be in 2019, with new contract wins, better focused sales, and restructuring largely done.
I bought at 4p in a placing some time ago, and see this as a 2-3 year turnaround. The current year is forecast to produce £1.1m adjusted profit before tax. If that's achieved, then the share could re-rate upwards, being seen as a successful turnaround.
There have been a few bumps in the road so far, so I'm probably about 50% confident in this share.
Sosandar (LON:SOS)
Share price: 17.5p (down c.11% today, at 10:24)
No. shares: 116.2m
Market cap: £20.3m
(at the time of writing, I hold a long position in this share)
Sosandar PLC (AIM: SOS), the online women's fashion brand, is pleased to announce its financial results for the year ended 31 March 2019.
I'll split this section into two parts - the detailed numbers for FY 03/2019 are largely academic, as we knew what to expect from the last trading update. So I'll come back to a detailed look at the numbers later.
Of more importance now is the outlook & current trading comments, which have spooked some investors (understandably). I contacted the company first thing, to ask about the outlook comments, which say;
"The new financial year has started strongly and in line with our expectations with June setting a new record for the number of units sold in a month.
Repeat orders for Q1 increased 122% year on year and Q1 has seen c.23% year on year revenue growth. This revenue growth has been achieved through strong repeat business with deliberately less emphasis on new customer acquisition as external factors resulted in a tougher acquisition environment.
Being an agile e-commerce business, we have been able to respond quickly to external forces, making the prudent strategic decision to hold back funds to invest for customer acquisition in future months where we expect to achieve a better return on marketing spend.
"With a clear growth plan, we are confident in the outlook for the year and very excited about Sosandar's long term prospects."
Here's a summary of my telecon with management this morning;
Q1. To my mind, it seems contradictory to say that the year (FY 03/2010) has "started strongly", and then to mention that Q1 sales are up only 23% (way below the 100%+ revenue growth forecast for the full year).
A1. The key number to focus on is the +122% repeat orders (from existing customers), which they are very pleased with. New customer acquisition spending was deliberately dialled down in April & May because the weather was awful (compared with blistering heat last year). They took the view that is was nonsensical to be spending the fixed marketing budget, trying to sell summer frocks, when it was cold & raining, which clearly makes sense. An example given is that the direct mail brochure for the start of June was held back, until the end of June, then sent out once the weather started improving.
Therefore management say the underlying performance, when adjusted for weather & reduced marketing spend, was as expected. They are not changing full year forecasts, and sound confident they can achieve it.
Q2. Surely the company now has a mountain to climb, to achieve full year forecast of c.£9.5m revenues?
A2. There's a bigger marketing war chest for the autumn season now, due to holding back in the poor spring weather period. A big expansion of the range is planned for autumn, with new designers & buyers being used for new categories (e.g. denim, which is doing well), plus footwear, and accessories ranges will be greatly enhanced. New factories are coming on stream, lots going on with product, which is why they are confident about the rest of the year. Some Sosandar designs are becoming perennial sellers, e.g. the fit & flare dress - Julie noted that Charlotte on Good Morning is today wearing one of these from Sosandar.
All in all, the tone of the conversation was really upbeat, they feel targets are attainable, and there is no change to the full year expectations.
Q3. I've noticed more discounting on your website, will this hit margins?
A3. Management took a tactical decision to clear slow-moving lines earlier. The discounting on website only applies to certain lines, they haven't done any across-the-board discounting. Have to respond to competitor activity, if other retailers go into sale early, Sosandar has to follow suit to a certain extent.
Slightly dodging the question there, but if margins were significantly different to expectations, then the company would have to say so.
Q4. Will you need to do another placing, as the cash looks sets to run out in early 2020, based on current burn rate?
A4. I got a rather generic reply on this, something like, we keep funding requirements under review, etc.
Cash - my view is that there is clearly enough cash for the time being. It may need a top-up placing next year, in my opinion. If this is done from a position of strength, after a strong autumn season, then it's not a problem at all - similar to the last placing, which was dilution of under 10%, and the money was offered to Sosandar unsolicited, by two institutions that were keen to buy in, in size not available in the open market.
The worry is that, if Sosandar has a bad season in autumn/winter later this year, then it could be forced to dilute existing shareholders more, with another fundraising at a lower price.
Therefore, being realistic, I think there's probably an increased chance of the company needing a bit more cash next year.
My opinion - obviously I'm biased, as I have a large long position here. Even so, I always try to think & act objectively, but unconscious bias can always creep in.
Trying to be even-handed, I'm not impressed with the growth rate slowing to only 23% year-on-year, but the explanations given by management do have credibility. If the weather had been warmer, and marketing spending higher, then the growth rate probably would have been 50-100%, instead of +23%. So on balance, I accept the explanations given. Although there has to be an element of doubt.
I feel that maybe the spring/summer range this year possibly didn't have the same impact as last year's? So there could be a mixed situation here - some external factors have had an impact, but possibly the product wasn't as good as it could have been too?
The repeat business statistic of +122% is very important, and that's the key driver of the business. The idea is that once a customer has been acquired, then the lifetime value could be enormous, as unlike say BooHoo or Asos, where customers have a fairly short lifespan, the Sosandar customer of 35 might still be buying Sosandar styles 20+ years later.
The share price has come down so much, that I feel the increased risk has already been factored into the valuation.
The tone of the conversation was very positive - management clearly do believe that they can hit the full year numbers. If they didn't believe that, then the forecasts would be lowered, but they're not being lowered. In the past, management have been straight with investors. Obviously they're putting their best foot forwards, as all companies do, but Sosandar has a history of beating forecasts on revenues - it had several upgrades last year. So I'm comfortable that management here know what they're doing.
For me, this has always been a long-term investment. On balance, I feel that the long-term picture is unchanged, and very positive. However, a soft Q1 certainly increases risk that full year numbers may not be achieved, despite management sounding very confident they can hit those numbers.
Therefore, I can understand why shorter term, or less committed shareholders, might feel that it's better to watch from the sidelines for now. There again, a £20m market cap, for the UK's fastest-growing pure play online fashion business, with enough cash for at least 12 months, is probably not going to be far from the lows. With the weather now improving, and marketing spend going back up again, it wouldn't surprise me if the next trading update sees an acceleration of the growth trend again.
Time will tell!
LoopUp (LON:LOOP)
Share price: 129p (down 44% today, at 14:11)
No. shares: 52.5m
Market cap: £67.7m
(at the time of writing, I have a long position in this share)
Trading update (profit warning)
LoopUp Group plc (LSE AIM: LOOP), the premium remote meetings company, is providing a trading update for the six months ended 30 June 2019 ("H1 2019").
The first bullet points lulls us into a false sense of security;
The Group continues to see strong demand for the LoopUp product. In addition to a £2.34 million contract renewal with leading global law firm, Clifford Chance, new landmark accounts wins during H1 2019 include a major European investment management association, a leading television broadcaster in Australasia, the world's largest private dispute resolution provider, and numerous major international law firms.
This is followed by a second bullet point which pulls the rug out from under investors;
However, due to:
(a) subdued revenue across its long-term customer base, which the Group believes has been driven primarily by general macro-economic factors rather than any material change in customer loss rate; and
(b) more senior quota-carrying pod staff than expected being diverted into management and training activities required to accommodate the dramatic increase in the number of pod staff,
the Group now expects revenue and EBITDA for the full year to 31 December 2019 ("FY2019") to be approximately 7% and 20%, respectively, below market consensus.
Quantifying the problem - the only recent broker note I can find is from Progressive Equity Research (who?! They seem to be a commissioned research company). It's a fairly detailed briefing note, published on 18 June 2019.
Existing forecast: Revenue £50.1m, Adj EBITDA £10.1m, Adj PBT £5.3m, Adj EPS 10.0p
My revised estimate: Revenue £46.6m, Adj EBITDA £8.1m, Adj PBT £3.3m, Adj EPS 6.2p
I've had to make some broad brush assumptions in the PBT & EPS figures above, so this is a best guess, rather than a forensic analysis.
Is it fixable? To my mind, this looks like a setback rather than a disaster. Although it does raise the question as to why existing customers are using the LoopUp service less? Are they using something else instead perhaps? Can it really be down to macro factors? I find that difficult to believe, because we're not in a recession.
Last year revenues were split 53% UK, 34% USA, Other EU 12%. LoopUp revenues should be doing OK, based on those geographies, in my opinion.
The problems with sales "pods" looks like a self-inflicted problem, due to over-ambitious speed of expansion. Still, things like that happen with fast growing companies, and is fixable, so I'm not too worried about that. It could even be a buying opportunity perhaps?
Other points in today's update;
Revenue split - expected to be 48% H1, and 52% H2
New video functionality - strong customer feedback, will accelerate roll-out in Q3. Sounds positive, and should generate additional revenues from existing clients
Revenue erosion of 7% in its long-term clients, is worse than net growth of 1% in 2018 - this is a concern. On the plus side, it says that it's down to across the board subdued activity, rather than client losses. Could this be an early indicator of a recession looming, perhaps? There have been other warning signs lately (e.g. the very poor building sector PMI this week in the UK).
Pod staff - increased from 63 at end 2018, to 112 currently - that sounds bonkers to me. What were they thinking, trying to expand so fast? However, it does help explain the profit warning - as new sales staff are useless to begin with, have to be trained, which takes time & money. The benefit is then felt the following year. So at least this should lay the groundwork for improved performance next year.
Management speak - described as growing pains, which I think sounds about right;
"We are experiencing some broad macro-economic headwinds in our business and have needed to take on board some learnings and growing pains resulting from what is essentially a very positive expansion of team size in our new business pods.
However, we believe the LoopUp product remains strong and differentiated in a very large addressable market, we continue to see excellent demand for that product, and we remain confident in our ability to deliver strong future growth."
My opinion - the LoopUp product is indeed excellent - I've tried it a while back.
I had to grit my teeth this morning, due to my spectacularly ill-timed initial purchase yesterday. Never mind, we just have to deal with profit warnings from time to time. I've learned to quickly put the disappointment and emotions behind me, and make a rational decision on whether to sell, hold, or buy.
This particular situation looks to me like a buying opportunity. The company has hit some bumps in the road, but still has a great product, and is growing. The market cap is, amazingly pretty much back to where it started, when the company listed in Aug 2016. It was only about one fifth of its current size (in revenues) back then, and operating around breakeven. Now, it's much bigger, and decently profitable. Therefore, I think the share is very considerably better value now, than it was back then.
I am minded to see today's profit warning as falling into the fixable, short term blip, category. Therefore, with the price having been smashed by such a large extent, this looks to me like a good buying opportunity. With a bit of patience, I could see this share recovering well. That's providing nothing else goes wrong, of course.
Reviewing the last balance sheet, I think it's adequate for now, but not strong enough to withstand a further, more serious downturn in trading - due to the bank debt. So if it warns on profit again, then I would be inclined to ditch it.
For now though, this looks a potentially good entry point, in my view, at c.130p. I think it's a fundamentally good growth company, now priced at an attractively low level. There could be bidding interest for the company at this level. As we were discussing here recently with Cloudcall (LON:CALL) - the Americans, and private equity, put very much higher valuations on these type of companies than AIM investors do - especially if there are any disappointments in the growth story.
Redde (LON:REDD)
Share price: 113.6p (up c.6% today, at 16:09)
No. shares: 306.7m
Market cap: £348.4m
Redde collaborates with insurance companies, to provide courtesy cars for the no-fault party in car accidents.
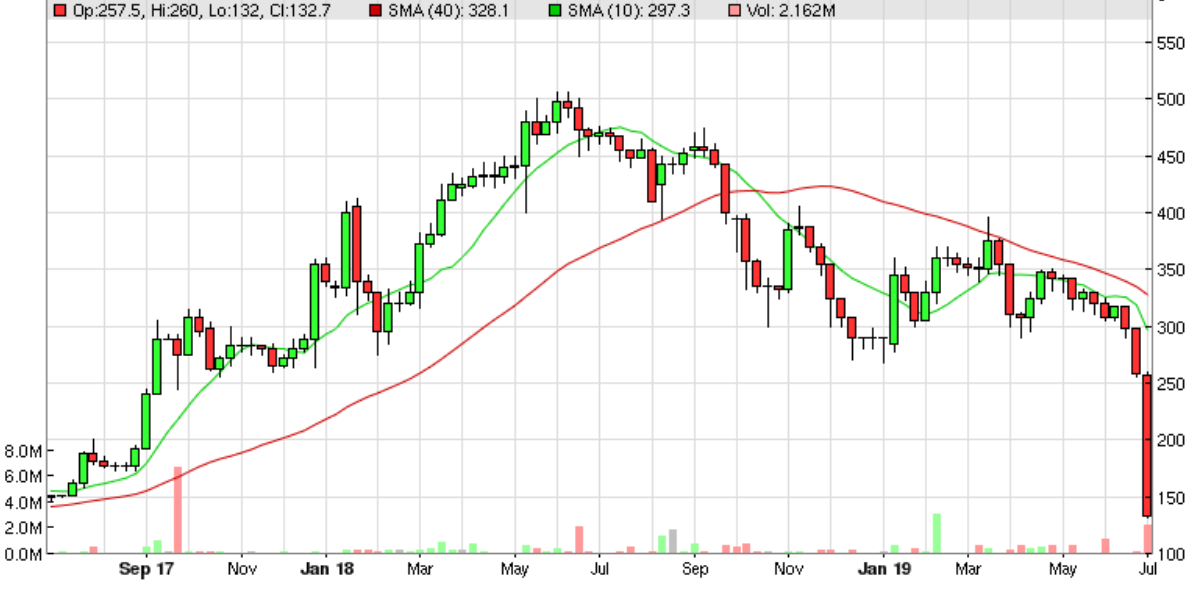
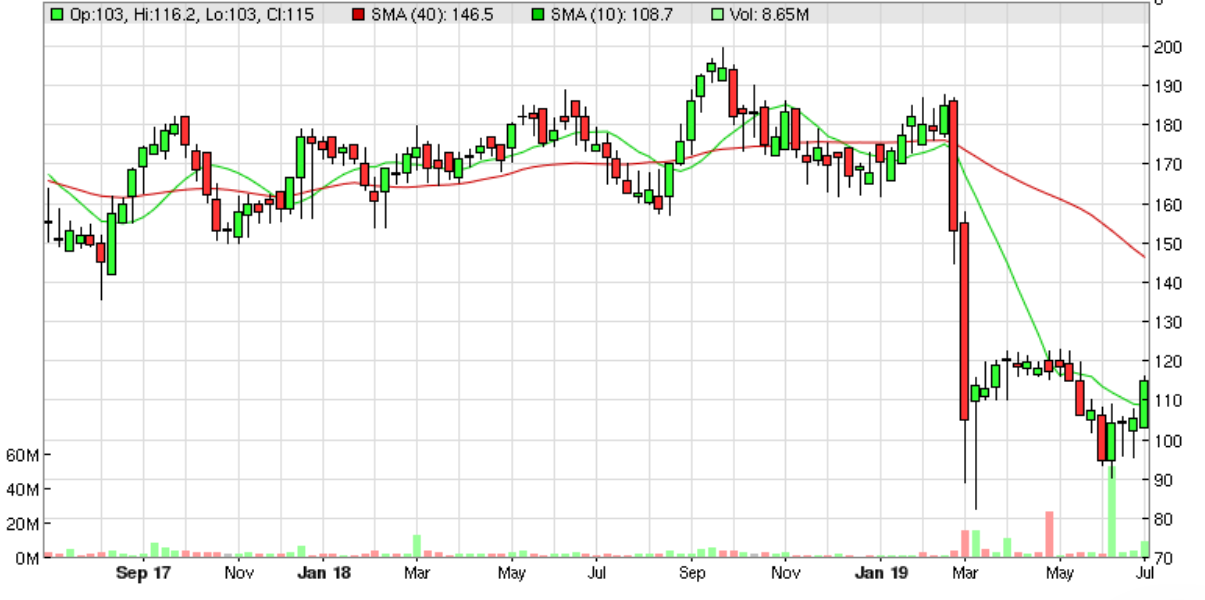
A quick recap - this share was a dividend paying cash cow, trading sideways between 150-200p per share, from 2016 to early 2019. It issued a profit warning in Mar 2019, due to the loss of a large client, and rumours of further possible contract losses. Insurers seemed to have realised that they're paying too much, and are trying to squeeze Redde's margins. Hence why the share price has been languishing either side of 100p lately.
Trading update for FY06/2019 - sounds reassuring;
Trading in the second half of the year ending 30 June 2019 has been in line with the Board’s expectations for both revenue and adjusted operating profits.
Contracts update - the big contract that was lost, is set to partially (for higher margin work) extend from July 2019 to Nov 2019. Whilst that mitigates the contract loss, it's still a lost contract, so getting 4 months more work is only deferring the loss in profits. I suppose the hope might be that Redde could regain the contract after that?
Further good news re other contracts;
In addition, since the 8 March announcement there have been a number of new contract wins in other parts of the Group as well as a contract renewal with a major insurer which have contributed to the Board’s confidence in its expectations for financial year 2020.
That considerably de-risks the outlook, at least for the next year.
Net debt figures, and news on a protocol agreement (whatever that is) are also given.
My opinion - things are looking up for shareholders here. This strikes me as a good update.
Forecast is for diluted adj EPS of 13.5p in FY 06/2019, then 13.1p in FY 06/2020
That's a PER of 8.4 and 8.7 respectively, nearly all of which is being paid out in divis, giving a stunning yield of 10.3%
A yield that high is rarely sustainable. If it is sustainable, then the share price would probably rise. Although the shock caused by the big contract loss has highlighted that Redde is vulnerable to insurers trying to squeeze its high margins down.
On balance, I don't have a strong view either way with this one, because future performance depends on how the various contracts with insurers pan out. That's unknowable to anyone outside the company.
Topps Tiles (LON:TPT)
Share price: 68.6p (up 2.4% today, at close of play)
No. shares: 194.9m
Market cap: £133.7m
Topps Tiles Plc (the "Group"), the UK's leading tile specialist, announces a trading update for the 13 week period ending 29 June 2019.
Sales were up +3.8% on a like-for-like ("LFL") basis, which looks rather good. Although the prior year comparative was soft, at -2.3%.
There's positive-sounding commentary in the announcement, which I won't repeat here.
My opinion - I like this share, but don't own any personally. The valuation looks reasonable (PER c.10, and 5% divi yield), and the business seems to be weathering tough retail conditions well.
Stockopedia loves it - a StockRank of 98, and "Super Stock" classification.
Purplebricks (LON:PURP)
Share price: 95p (up 2.2% today, at market close)
No. shares: 306.4m
Market cap: £291.1m
A leading online estate agency. The headline figures look rather scary;
- Revenue up 55% to £136.5m (this bit is OK)
- Operating loss of £-52.3m
- Cash down from £152.8m to £62.8m - massive & unsustainable cash burn (a fair bit on those annoying TV ads, no doubt)
- The CEO founder Michael Bruce, stepped down on 7 May 2019, following botched overseas expansion
- Australian business has been closed (previously announced)
- USA - PURP is also withdrawing from this market
- That seems to leave a profitable (£5.3m) UK operation, and Canada (small loss-making)
Outlook - wants to gain 10% of UK estate agency market. Current trading;
Current economic and political uncertainty in the UK means market conditions remain challenging with volumes continuing to trend downwards, partially offset by higher revenues per instruction.
My opinion - it's got £62.8m in net cash left, but I wonder how much of that will be remaining once the USA & Australian operations have been shut down? There could be balance sheet write-offs relating to those markets closing maybe?
Purplebricks shot for the stars, with an expensive overseas expansion, and it hasn't worked.
I'm struggling to see how the UK + Canada businesses are worth anything near the market cap of £291.1m. This looks a busted flush to me.
Works co uk (LON:WRKS)
Share price: 69p (up 10% today, at market close)
No. shares: 62.5m
Market cap: £43.1m
TheWorks.co.uk plc ("The Works", the "Company" or the "Group") the multi-channel value retailer of gifts, arts, crafts, toys, books and stationery, announces today its preliminary results for the 52 weeks ended 28 April 2019 (the "Period" or "FY19").
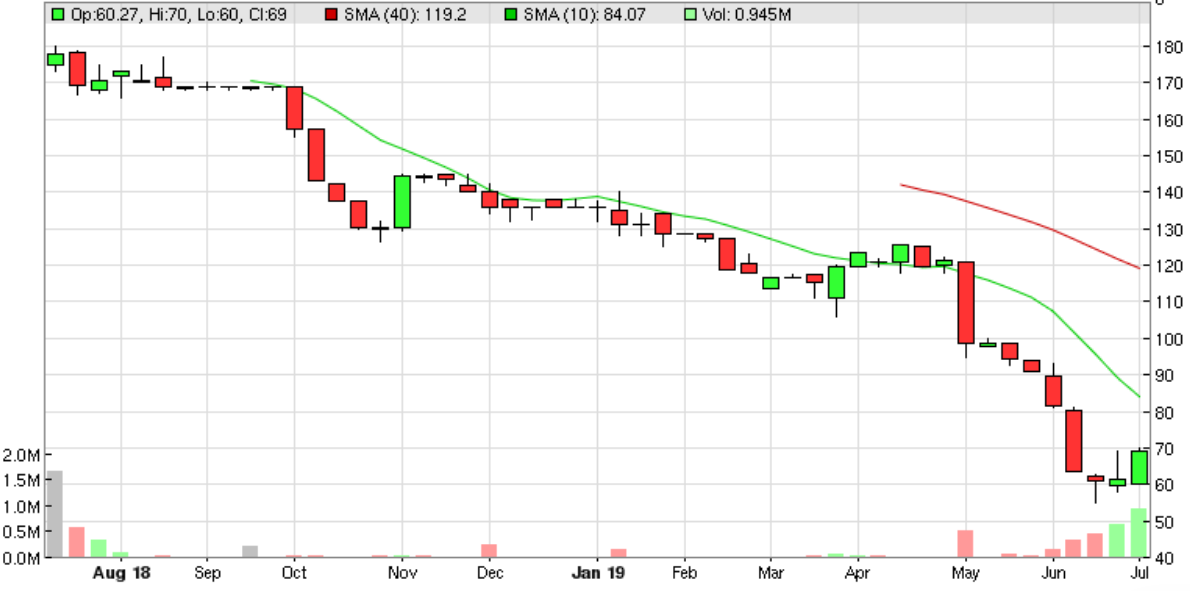
We've not looked at this company before here. It floated in July 2018, and has been going down in price ever since listing;
Results - the highlights look quite good - e.g. adjusted PBT up 58.6% to £6.7m, on revenues up 13.2% to £217.5m. That's only a 3.1% profit margin though, so profits could be wiped out easily, if revenues were to fall sharply.
Adj EPS is 9.0p (up 25%) - giving a PER of 7.7 - cheap, but why pay more for a low margin retailer? Confusingly though, a different EPS of 8.4p is mentioned below, which looks a more meaningful number, being pro forma figures. That would give a PER of 8.2
Store openings - this looks rather good actually. It opened 50 new stores (total now 497), and claims a payback period of 1 year on new sites. That's outstanding. They must be getting great deals on new sites from landlords.
Current trading - 9 weeks to 30 June 2019, LFL sales are marginally down.
Balance sheet - looks reasonable, almost debt-free. Trade & other receivables looks unusually high for a retailer, so I'd want to know what is in there.
My opinion - I wasn't expecting to like this share, but it's actually not bad. High gross margins, and getting good deals on new shops, mean that it's still profitable when other retailers are dropping like flies.
Its website looks to have some bargains - e.g. in books, Ed Sheerin's biography is only £3.50, and Linda Nolan's is an even bigger bargain at just £2.00, a saving of 89.5% on list price. Guess what my family will be getting for Christmas! I'm searching for Gordon Brown's autobiography, and am hoping that they will pay me to read it.
The trouble is, who wants to invest in retail shares at the moment? We've seen so many look cheap, and then get cheaper & cheaper, until they expire. Does The Works have enough of a niche to continue growing its profits? I don't know.
Phew, what a marathon today's report was! If you got to the end, well done you!
See you tomorrow.
Best wishes, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

53 comments
Re SOS weather really does impact sales. One hand bad weather shifts sales from physical stores to online which should benefit them. However if you have bought a spring 2/summer phase 1 range that contains lots of dresses, lightweight fabrics, summer prints and it’s 16C and raining people just won’t buy. A lot of clothing sales are need based rather than planning ahead - an emotional purchase.
I don't think that the problem for LoopUp (LON:LOOP) is strictly a macro situation. For instance Zoom (NASDAQ:ZM) which is a competitor in the video conference space for the first quarter of 2020 ( they have a January year-end) had US $122.0 million in revenue up 15% quarter over quarter and are guiding for an increase in revenue of approximately 5 to 6 % for the second quarter. The guidance for the full-year revenue was also increased to $535 to $540 million or an increase of 61 to 62% over 2019. That implies that the growth will accelerate in the second half of the year which makes sense since the second quarter is over the summer period but your mileage may vary.
The most flagrant difference would be in the Customer acquisition cost where Zoom more or less relies on word of mouth for the initial sales impetus. I used to own shares of Loop Up but sold them once I got a hold of Zoom's S1 and saw their numbers. That said the stock is horribly overpriced trading at something like a forward PE of 3020.
Just wanted to thank Paul for his review of Sosandar (LON:SOS) (which I hold a minute holding) and Graham for his analysis of Northamber (LON:NAR). Northamber (LON:NAR) is so fascinating I almost want to buy a few because it is so odd!
Investors behave differently in bull markets than they do in bear markets. That’s a rare heuristic that tends to hold true across markets, and across time.
Regime changes are infrequent, and among the most challenging aspects of being involved in markets, since what worked recently simply stops.
2017 saw a remarkable rise in UK investor risk appetite for high sales growth companies such as Sosandar (LON:SOS) LoopUp (LON:LOOP) & Purplebricks (LON:PURP) . Such a high risk appetite is perhaps typical in a maturing bull market.
Yet many of such companies have subsequently had stumbles in their fortunes & investor risk appetite has been replaced by risk aversion.
It is difficult to see how things reverse again until risk appetite returns. This could be 12-18 months away given that we now face an economic slowdown irrespective of any Brexit outcome.
The Stockpedia algorithm is remarkably consistent in its opinion of such companies - speculative, 'sucker' stocks.
does anyone know the placing price for £SOS? I've found 15.1p reported but don't have an offical number. As it was a reverse takeover it didn't appear in the IPO data from LSE . Have done a recent study using the LSE published data so interested in its price behaviour relative to the total set. Placing price is a bit of an anchor ( and if it is 15.1p then it held today despite enormous trading volume ).
For those who read Part 1 of the IPO Study , Part 2 is almost done - the missing 131. I'll post it by end of week
"Good ole" investegate comes to the rescue again ds
15.1p it was!
thanks Mr G, I have been using Investegate to track down the "missing", great source of archival data
SOS reverting to its placing price having been over 3 times that less than a year ago does fit the trading IPOs model .. although it has already dipped below the placing price...interesting one to watch
I note that Paul is planning to get around to the PURP results.
I think it is good that they are pulling out of Australia and USA. They tried to expand too far, too quickly. I note the loss in those two regions is stated as just greater than the total loss. Breakeven next year? Past record makes me skeptical that they will achieve that, but here's hoping.
Hi Paul
Thanks very much for your detailed analysis and comments about Sosandar. I'm glad I didn't wait to hear your views and sold my holding on Monday, after another decline in the price. I didn't like the SR metrics and also the steady decline recently in the price, and lost patience with it. I bought some Mission Marketing instead. I suppose the same principles apply in following momentum stocks higher, don't follow falling momentum stocks lower.
Thanks.
jim.
Very good that Paul is writing today's report at all. If I held both LOOP and SOS in size, I doubt I would be capable of concentrating enough on anything but the market drop in the value of my shares, to write coherently on these and other companies.
As it is, Paul has access to the SOS directors and has kindly shared their feedback with readers here.
Agreed. I'd be doing my nut...good job by Paul keeping the show on the road
Really painful drop in Sosandar (LON:SOS) share price - it seems that the outlook line has cost them badly, because there was a lot of things to like elsewhere in the statement otherwise.
If they are still on target for this year, then the co-CEOs could have re-iterated this in more definitive terms, 'we are confident in the outlook for this year' might be a bit mealy mouthed and open to interpretation.
Notable that there are a lot of small buys but all the big value trades have been on the sell side.
Paul, I try to avoid cluttering up the comments section with "me too" posts, but it gets to the point where it would almost be rude not to say anything. Already another great SVCR (and it's barely lunch time) - not only, but in particular Sosandar (LON:SOS) where you have the sector specialism and contact with the management.
I thought Sosander said at Mello that they would be focusing the marketing more at the most cost-effective times of the year, so am not concerned by the Q1 numbers. The issue is, as you say, the risk of a weak share price coinciding with a funding requirement. I have a starter position but it still feels far too early to get properly involved.
Sosandar (LON:SOS)
Just read Paul's comments on Sosandar and the readers' useful comments as well.
Key point is "Q1 has seen c.23% year on year revenue growth" followed by mgt's response to Paul's question as "New customer acquisition spending was deliberately dialled down in April & May because the weather was awful"
My view is these numbers are a miss for a startup, based on the following
Firstly, the total revenue number for the full year was £4.4m. In the scheme of things that's a fairly small number, given the size of the UK clothing market and their aspirations. If you are running a start-up you want to hit your numbers and grow fast, especially on such a low base, to prove to the shareholders (and yourself) the proposition has legs.
Appreciate the dimension of cash burn and the thoughtful discipline with holding back cash until the timing is right for max ROI. I get it, makes sense. But again, this is a small startup, you would think if they have a good lineup of designs and they are coming off such a small base, why not just crack on? My experience in a startup (not retail) was we sold all through the holiday periods. Yes, there was noise around lower conversion rates, but so what? We wanted to grow and we were constantly learning from being in market.
Secondly, I have experienced a similar situation personally, heading a marketing team when the CFO wanted to pull back on new customer spending to manage the year's numbers (marketing costs are fully expensed while revenues take time to materialise over the life time value of the customer). This of course meant heated internal discussions !
But while holding back on growth in the short term preserved cash, it slowed down growth of the customer base, dragging out the breakeven point and extending the cash burn phase due to ongoing fixed costs. In the long run it was a bad idea in terms of a five year P&L outlook and this timid approach ended up costing more.
To put this into numbers acquisition cost were around £40 - £80 (depending on channel) and lifetime value was £250 over three years. Cost today Jam tomorrow. In comparison another firm I worked for had plenty of funding so we built up the customer base fast, and it worked because it brought forward our breakeven point. Also it meant the business had scale and value, so when the investor exited they made a good multiple on the sale. So this raises the question is Sasandar making sub-optimal growth decisions from a start-up perspective, because they are inadequately funded?
Lastly, and I do not know retail at all, but if their proposition is unique (smart clothing to ex-young gen women) would have thought weather is less of an issue. Women are still going to work, needing clothes, and the shopping is all on-line. Not an expert here at all, but I view startups as 'new idea let's grow the demand's there'.
So, applause for Sosandar mgt for their cash discipline but as a small startup 23% growth yoy is low.
To be fair it's only one quarter they missed and also they stated June was a record month, so hopefully they can get back on track quickly.
Interesting write up on SOS - I am still not convinced about product being middle to top end, Insaid to my wife I will buy you anything you want but from SOS website and she chose nothing which has never happened before my wife is 34 so maybe she is too young for it and clearly without seeeing items can’t comment on quality but design probably rivals M and S and othe5 similar companies not the likes of Ralph Lauren but then that maybe the market they are aiming at.
Clearly the market knew something was up as share price has been drifting lower so someone has been told the information how see it is that management will competent and on to[ of the world at next trading update and share price will bounce back or else if they do not hit the numbers then it will be a money raising exercise at discounted numbers and the management will be shot to pieces.
I have a small ish holding and as I don’t know the management as well as Paul I have no idea how much I can trust them. I am always worried when people blame the weather for lack of sales as surely the public don’t stop buying clothes if it rains they just need the right products to buy and that is where online sales should be at a huge advantage - BOOHOO does not seem to have suffered the same issues and I doubt Next will, sorry to say but the weather I think is an excuse that is often used although I accept it has a bearing - if the weather on autumn is not what is expected then what happens to s\SOS predictions? I have just sold a hotel as it was too dependent on the BRITISH weather and if we are now saying that fashion brands profitability are down to the weather then for me that makes any fashion brand pretty uninvesatble especially given its erratic nature which is set to continue.
Paul’s points read well and I will keep what I have and remain an interested observer from the sidelines
The latest from the FCA could impact the likes of Plus 500 if holders are hoping for an upturn in crypto trading to support the share price.
"We are consulting on banning the sale, marketing and distribution of derivatives and exchange traded notes referencing cryptoassets to all retail consumers.
We believe that retail consumers can’t reliably assess the value and risks of derivatives (contracts for difference, futures and options) and exchange traded notes (ETNs) that reference certain cryptoassets. This is due to the:
inherent nature of the underlying assets, which have no reliable basis for valuation
prevalence of market abuse and financial crime (including cyberthefts from cryptoasset platforms) in the secondary market for cryptoassets
extreme volatility in cryptoasset prices movements
inadequate understanding by retail consumers of cryptoassets and the lack of a clear investment need for investment products referencing them
We think these issues will cause retail consumers harm from sudden and unexpected losses if they invest in these products. We estimate a ban could reduce harm by £75m to £234.3m a year for retail investors.
https://www.fca.org.uk/publications/consultation-papers/cp19-22-restricting-sale-retail-clients-investment-products-reference-cryptoassets
Another thank you, Paul, for passing on the results of your discussions with management at Sosandar (LON:SOS) . Very much appreciated. I only have a small toehold in this one given the level of uncertainty. For the moment I will hold and keep monitoring
I think Paul's overview of Sosandar (LON:SOS) thus far is fair, but it shows that Sosandar (LON:SOS) are not capable of powering through weather issues etc, and therefore vulnerable as all retailers are to the normal bumps on servicing customers. The facts that marketing spend can vary unlike the fixed overheads of bricks and mortar retailers is a plus, but there are no free lunches, and marketing will probably have to be expanded to make up the shortfall, and there is no guarantee that demand will respond, so it is a 'wait and see'.
It could possibly come good strongly at some point, and on that score Paul has obviously got more appetite for risk than me, and hopefully will get the rewards if the best scenario pans out.
Businesses do go through occasional difficulties, and it would be a naive expectation not to have some in the process of growing in a dynamic market. I hope they make the best of the situation.
I sold my interest a while back, after some initial retrenchment of the price but retain a watching brief should it spark to life again.
Paul many thanks for you honest comments on Sosander.
Was a holder until just after 8 am and feel somewhat relieved to sell.
Sosandar (LON:SOS)
Paul - if they are as confident as you make them sound, one would expect them to take good advantage of the languishing share price?
Hi mbdx7em21
Sosandar (LON:SOS)
Paul - if they are as confident as you make them sound, one would expect them to take good advantage of the languishing share price?
If you're referring to management at SOS, they don't have any money! The CEOs put "everything they had" into the company at start-up. The CFO is quite young, so I doubt has much spare cash either (although am guessing there).
Hence I'm not expecting to see any meaningful Director buys. I'd rather not see token Director buys (which advisers often encourage Directors to do), as it looks fake when companies do that, which is counter-productive in my view.
Regards, Paul.
Sosandar (LON:SOS)
Davidjhill
The key point is that with effectively no marketing Sosandar (LON:SOS) repeat orders were up 123%. That's great because existing customers are loyal and buying more. That has led to a reasonable increase in revenue at good margins for no further acquisition cost..
I would beg to disagree - this stat unless i am wrong is likely to give an out of context pimped up impression of how good repeat orders currently are.
Repeat orders comparisons are comparing repeat orders qe june 2019 with repeat orders qe june 2018.
Note in the 6 months to sep 2018 sales were up 408% - that is such a high % sales increase that most of the orders qe june 18 will have been from new customers - so the repeat order comparison is from such a low base the previous year as to be meaningless.
Note the fact that this stat may appear impressive but isnt that the the repeat order increase for year just finished was 391%. So in 3 months we have gone from 391% to 123% - thats a woeful comparative- although that is misleading slightly in the other direction as we are looking at 12 months period compared to 3 month period - so i am not taking that as a negative - more that both stats arent what they seem to be.
per interims to sep 18
Revenue increased 407% to £1.84m (6 months to 30 September 2017: £0.36m)
Sosandar (LON:SOS)
I held a position and sold today. Fortunately, I'd bought some 15-16p...unfortunately I'd topped up in high 20s.
Why sell?
1) Big slowdown in growth
2) Don't like that June has set a record in number of units sold rather than value sold...it has been noticeable that they have promoted discounting frequently in Q1...has the need to clear stock changed the dynamics of who they are in customer eyes
3) DIsclosure is generally not as clear as it could be and does not permit easy comparison. In that light the claim that repeat custom is so much higher YoY is irritating. It is a statistic that is surely much more relevant in a quarter on quarter context and as a percentage of quarterly business
4) Describing a poor sales result as agile is.... (can't say it)
5) On seeing CEO a couple of times now I have had a nagging doubt that she is out of depth leading a corporate. I expect the current co-CEOs to stay but redefine their roles clearly into creative roles.
6) Arbitrarily YoY sales growth of 50% would have pleased me. (see why I bought point 2 below)
7) It is great to have social media and 'brand ambassador ' recognition but a super growth stock needs to have pedal to the metal all the time. It is mgt and growth that leads social media and ambassadors rather than the other way round.
8) They obviously will need to raise cash to market hard and grow. The fact they have 'agilely' halted growth waiting for more opportune moment is wrong groove. The message is that they need a lot more cash to make a lot more impact...rather than a bit of cash to help keep the momentum rolling
9) Apr-June has been a bit unlucky weather wise and that has probably made stock and pushing sales hard. However, I feel that the fading of the animal print craze has left them a bit stylistically stuck and struggling to replace it and still grow significantly (this is very much a dodgy no nothing bloke comment!)
Why I bought
1) A little bit of an experiment in style terms for me as I'm usually a bit more contrary.
2) However, they seemed to have platform and a model that had been road tested by others and with the right product and promotion could grow rapidly. Looking at historical comparisons it is my belief that online company growing revenue at >50% (sometimes hitting big 100 in particularly good moments) is a one that trades on 5-10x current run rate revenues...and finding the right time to buy is extraordinarily difficult and one just needs to take the plunge
3) Tentative evidence that they had a successful and resonant formula
What's going to happen
1) The stock is going to trade down to market cap equals revenue so about 5-8p range
2) They will only be able to raise cash with significant discount and dilution to new lower price
3) Investors are always going to focus on when cash burn ends and profitability comes now. This makes managing the business extraordinarily hard as they really needed to keep the levitational magic of 5-10x revenue to keep the financing sweet such that equity holders were only ever skimmed lightly
4) SOS is here to stay and very probably becomes a recognised brand and perhaps even sizeable. Historic finance and success creates this outcome. But it doesn't achieve that within its current financial shell....the process of changing financial shell could be very messy...staying true and focused to the brand means partnering financially with someone with deeper pockets. Staying true to shareholders means managing cash burn first now and waiting until some good organic non expensive from marketing perspective growth can be achieved and only then tapping for more cash. That's a 2-3 year work through story
This is now a turnaround situation. It may become interesting as a result of that but there is a danger that the turnaround occurs inside a bigger parent...or non public VC backed situation
hi Mojo - I think you've taken a whole series of assumptions and leaps there. It's nothing like a turnaround story.
Pauls comments after speaking to management pretty much exactly mirror my earlier post based on their previous commentary. I prefer that as it is consistent narrative. When they describe "agile" they mean they can turn the marketing taps on/off on an agile basis so that they don't waste money. They have plenty of firepower to hit targets for this year without raising cash and current cash is targeting breakeven. However, that said I do think if they are offered a good deal on a raise they make take some more.
Your comments on fashion are also a bit odd if I may say so. Management are renowned over 20 years at being "on-trend" - I'd say it is unlikely for that to change now.
Hello davidjhill
I mean its morphed into a sort of turnaround story relative to previous narrative. Obviously its very different from say a Connect (LON:CNCT)
Maybe they have cash for current year sales target (a double on last year). But that would indicate they have idiosyncratic power as brand and selling entity whereas Q1 suggests they are ordinary go with the flow mortals
My comments on fashion are super on point ;) Its seems quite evident online and through mgt comment that they have struggled to find a vibe to replace their breakout animal print time. If there's not a hot thing and just a brand thing to punt then I refer you back to the paragraph above.
I might buy back...but I'll get it significantly lower is my view.
PS I didn't red thumb just as you disagreed with me!
Hi Mojo - lol, yes I know you aren't sensitive to that. I don't really care about red thumbs, they are just generally petty if someone is expressing an opinion, but hey ho :) I never red thumb an opposite opinion - it's equally valid to mine. Only time will tell who is right.
A wide ranging debate where we disagree with each other has to be a good thing at improving each of our investment process and thoughts.
Anyway back to Sosandar (LON:SOS) : you may indeed get it lower from a trading perspective. My sense is that the market has been waiting for a reason to be sceptical and it now is. I don't have that much of a position so I will buy more lower if I see a big move down unless trading changes. I have a feeling that the market has misunderstood todays numbers though.
I wonder if the recent broad industry comment in the press about slowing online sales is also affecting Sosandar (LON:SOS).
https://www.retailgazette.co.uk/blog/2019/05/online-retail-sales-continues-sluggish-growth-in-april/
https://www.drapersonline.com/news/latest-news/online-clothing-sales-growth-continues-to-slow/7035503.article
Eagerly awaiting Paul's SOS write up. DavidJhill above makes some very pertinent points.
The commentary from the company seems to suggest this level of growth is acceptable for targets. They would not have been allowed from a regulatory standpoint to post 23% and claim everything is good with forecasts at 100%+. They would of had to warn, or at least had drearier language around it.
I do think this will drift towards 10-15p though, even if fears are put to bed based on pure sentiment.
I am a long with SOS.
Sosandar (LON:SOS) I'm slightly surprised by the reaction on here. Management have answered many of these questions before in both their presentations and Q&A.
1) New customers are directly correlated to marketing spend. Higher spend = higher new customers
2) Acquisition cost (marketing spend per £ revenue gained) is lowest in Q1 and quite considerably so.
3) Thus spending on marketing when (a) it's a seasonal low and (b) has been an uncertain time for the consumer would be irrational unless you were chasing revenue at any price.
4) Thus I expected marketing spend to be heavily reigned in during Q1. This also has a positive impact on cashflow, which many of the comments on here about increasing losses etc completely miss.
5) The key point is that with effectively no marketing Sosandar (LON:SOS) repeat orders were up 123%. That's great because existing customers are loyal and buying more. That has led to a reasonable increase in revenue at good margins for no further acquisition cost..
So cash remains in the bank ready for peak marketing conditions, which in turn leads to a future big jump in new revenues. Repeat customers are also continuing to buy at an accelerated pace increasing those revenues further.
Thus management are happy with forecasts and confident in future as they can predict what the planned marketing spend will bring in terms of revenue and they can see what the existing customer base is re-ordering and how this will unfold.
I'd be interested to see if Pauls chat with management gives answers much along the same lines as I'm less keen on changes in narrative, but from what I've read it appears as if they are happy with that.
....would that you wrote the ( Sosandar (LON:SOS) ) RNS ! This is my expected 2nd order answer from Mgt.
The problem here is that you would still expect them to hit the >100% revenue growth in every Q, even if a particular Q's revenue was smaller due to seasonal factors..
Here is a crude round numbers example (and i'm ignoring Q on Q sales growth to keep it simple)
Company X's sales by quarter, are 10, 20, 20, 20 and its forecast to double revenue over the year from 70 to 140.
You'd expect the resulting revenues for the following year to be 20, 40, 40, 40 in order to hit the 140.
A 23% revenue growth for Q1 would equate to 12.3, which is well short of the expected 20.
Only 2 things clear re Sosandar (LON:SOS) at the moment: Q1 outcome was poor vs trend/expectations and the RNS was inadequate in explaining why (regardless if reasons are good or bad, credible or incredible) !! Clearly a gap vs expectations (in Q1 20 not FY19) has been poorly communicated.
Suspect a high readership / comments day ahead if Paul has already been in contact with Mgt and is promising a write up!! I will be one of them.
I continue to hold, believing in the strategy and not having the constitution to buy or sell 'on the bell'.
Looks like the MM's were equally confused with the statement, in not marking SOS down at the open. I was lucky to get out at an average of close to 19.5 and glad that I did as its now 16-17.
Sosander (LON:SOS) Q1 revenue slow down is going to need a good explanation. a retailer at this growth stage should be growing strongly sequentially not looking at year over year. I understand fashion is strongly seasonal but it requires some fairly heroic assumptions to get to FY revenue of £9.5m with only £1.0m in Q1.
Sold all my position first thing.
Morning all!
I'm just popping out for some breakfast (as I've been working since 05:40 today!).
I'll do a write-up on Sosandar (LON:SOS) (in which I hold a long position) when I get back. Had a quick chat with mgt this morning, who made some interesting points & answered my questions (which reflect the reader comments above on SOS).
That section should be published here by mid-morning.
Regards, Paul.
What are the forecasts?
Sosandar (LON:SOS)
thirty fifty twenty
I think it would make sense for Paul to speak to management / wait for broker updates before commenting - personally the news today left me with a bit of head scratching - so either waiting for new broker forecasts and or speaking to management makes much more sense than commenting without really having the full picture - part of the picture would be seeing what answers management give to any questions asked or seeing revised broker forecasts in black and white. Note i see it as a negative that the outlook comments don't speak for themselves - it will not take long though for projected turnover figures for the year to be released and that will answer the main question i have. I think if i have been holding this morning i would have sold out first thing at yesterdays price IF that was achievable.
Morning Paul
Any chance you could give your thoughts on Works co uk (LON:WRKS) results this morning?
I think you have mentioned them before, but they had a profit warning a couple of months ago.
Thanks
Dave
Hi cowlid,
Yes, results from TheWorks is on my list of things to cover today!
Regards, Paul.
"The new financial year has started strongly and in line with our expectations with June setting a new record for the number of units sold in a month. Repeat orders for Q1 increased 122% year on year and Q1 has seen c.23% year on year revenue growth. This revenue growth has been achieved through strong repeat business with deliberately less emphasis on new customer acquisition as external factors resulted in a tougher acquisition environment. Being an agile e-commerce business, we have been able to respond quickly to external forces, making the prudent strategic decision to hold back funds to invest for customer acquisition in future months where we expect to achieve a better return on marketing spend.
If this is a negative it would seem quite dramatic to me
Re Sosandar (LON:SOS) ,
it is Paul's biggest holding, it has a huge following on SCVR, he is up very early and no comment - I wonder is there the possibility he is an insider to some fundraising and is not able to comment. Pure speculation by me at this point in time but would be strange if no thoughts within the next 20 mins or so.
I have no position in £SOS
thirty fifty twenty,
Please don't post nonsense like that. I am not an insider on any stocks.
I've already spoken to Sosandar (LON:SOS) management, and will write up my thoughts when I've properly read the RNS, and digested everything. I'm not rushing out some ill-considered posts, and nobody should invent any reasons re the timing of any of my reports.
Thanks, Paul.
Hi Paul and my apologies if my thoughts + post caused offence.
In my defence I think that I remember that you have in the past, in relation to another stock, said after the event that you had not able to comment as you had been asked if you wanted to participate in a fund raise. If this is not true then I apologise to all for posting 'false news'.
Sosandar (LON:SOS) is on my watchlist primarily because I respect your opinion and analysis and I would try to time any purchase for the maximum benefit. The interpretation of the Q1 outlook today is critical to assess how the market with value £ SOS and if a further fundraising is now more likely. Thus I was genuinely expecting a short update comment from you....
e.g. "good results for 2018, Q1 comment requires some understanding, I will be in touch with mgt and post my thoughts later".
(this is similar to the pre market posts you have been trialling recently)
then it struck me that perhaps you may not be able to write. I appreciate that it would have been better to keep those thoughts to myself especially since I fully support the concept that you should feel empowered to write the SCVP at a timing that suits you.
best wishes and many thanks for the good work
Hi thirty fifty twenty,
Nice response from you, many thanks :-)
I've put up my initial thoughts on Sosandar (LON:SOS) now.
Best wishes, Paul
Sosandar (LON:SOS)
Q1 revenue growth for Sosandar (LON:SOS) is 23% year on year - is that a typo?
That's exactly what i thought a kind of does not compute moment/number bearing in mind sales are projected to go from £4.3 mill to £9.5 mill this year any i would expect yoy % increases to slow during the year due to tougher comparatives.
The company has said the following though - so i have to presume its my ability to compute that is the problem rather than anything actually being wrong??
"With a clear growth plan, we are confident in the outlook for the year and very excited about Sosandar's long term prospects."
Ha, I posted almost same thoughts at the same time.
Share price open kind of indicates we were wrong.
My morning smallcap tweet: LoopUp growth heads down
LoopUp (LON:LOOP), Telford Homes (LON:TEF), FFI Holdings (LON:FFI), Topps Tiles (LON:TPT), Purecircle (LON:PURE)
LoopUp (LOOP) guides FY rev 7% below consensus and EBITDA 20% below .
Telform Homes (TEF) rec offer of 350p, an 11% premium.
FFI (FFI) [last night] rec mandatory offer of 25p, 28% premium. Lumiere just bought 30.1% from CEO. IPO only 2 years ago at 150p.
Topps Tiles (TPT) Q3 LFL improved to +3.8%. Q2 was +1.8%. Both against weak comparatives though.
PureCircle (PURE) guides FY rev $125m and EBITDA slightly below the current range of expectations. Claim that new product is so good customers are cutting use of existing while they 'reformulate a number of their food and beverage products'. So what sweetener are they using in the meantime? Is no Stevia better than an old Stevia?
Q1 revenue growth for Sosandar (LON:SOS) is 23% year on year - is that a typo? Seems like a massive slowing of growth if previous year was 224%.
I think Snoo you hit the nail on the head with the Q1 growth.
I expect a significant markdown today on that sentence alone. The price reflects the future potential growth of the company which was expected to be about 80-100% for this year. If we are seeing 23% that's a huge slowdown which will increase the expect loss (there was a reference to them balancing marketing spend down to reduce some of that) and speed up the potential need of tapping the market for more money. When the share price was 30's that was much easier than now where a placing might only be done at about 15 (or less after today) which will obviously increase the dilution.
I am still long and hopeful but might need my tin hat today
Stocko projects £9.5m for FY2020 so the implied growth rate is over 100% - sure a slowdown but not to these levels.
It confuses me because it is couched in positive terms in the commentary, ie a 'strong' start to the year.
At the half-year stage for the previous year, revenues were £1.84m, so second half was £2.6m.
Making the assumption that sales accrued evenly reads to me for this year for sales for first quarter being £1.13m.
I hope there is something I have missed. At this point I am inclined to think that Paul will correct me.
Shame, but i've just sold all my SOS. Still believe in the management/company in the long term, but i see some choppy trading before then, with the added threat of a further placing as well. Guess i'll either buy back in the low teens or mid twenties... Either way, i'll need to see better evidence of either increased revenue growth or nearing break-even/profitibilty.
Also welcome comments on Sosandar (LON:SOS) this morning. Operating cash outflow static at £3.744m, which more or less equates to remaining net cash. So what are the chances of an equity raise this FY?
Cracking looking set of results from Sosandar (LON:SOS) this morning;
https://www.investegate.co.uk/sosandar-plc--sos-/rns/full-year-results/201907030700052755E/
Returns up from 44% to 50% but everything else looks really positive.