Small Cap Value Report (Wed 3 June 2020) - Re-opening, Zoom, FORT, ANG, VTU

Good morning, it's Paul here with the SCVR for Wednesday.
Estimated timings - there's very little news in my sphere today, so it should be possible to finish by 1pm.
Edit - I got carried away with macro stuff, so need more time to finish the company sections, say by 3pm.
Edit at 15:03 - today's report is now finished.
The Re-opening Trade
This is a theme that I am currently focusing on. As the economy re-opens, then companies are coming alive again, and there could be some bargains around, if the consumer comes out and starts spending again. The market is clearly becoming more optimistic that consumers may be more prepared to get out and spend money, than previously thought. I think that seems correct, for these reasons;
Many people are tired of lockdown. Younger people in particular seem to be realising that (if they have no existing medical conditions and are normal weight) CV-19 presents little to no risk to them. Bournemouth beach was very busy yesterday evening, in the glorious sunshine. I don't see any fear in people's eyes any more, and my hunch is that people could flock to the shops once they re-open, having been deprived of an enjoyable activity for over 2 months. I also think people are getting used to queuing, distancing, and wearing a face mask if they want to. Plus there will be terrific bargains, as fashion retailers rush to clear out excess spring/summer inventories. I reckon we could see a surprisingly strong re-opening of the High Street, but of course that's guesswork at this stage.
Evidence from the USA - is that whilst sales are down, they're not down as much as feared, particularly in apparel I hear.
Bank balances - a friend kindly sent me an interesting article from Bloomberg, stating that during lockdown, Britons have been hoarding cash - because we've got nothing to spend it on! Other than takeaways, beer, and buying random junk on Amazon after consuming the beer! Oh, and gambling online. In March & April, household bank balances rose by £30bn. What's the betting that this fuels a spending spree from 15 June? That sounds plausible to me, and share prices are reflecting the increased likelihood of that happening.
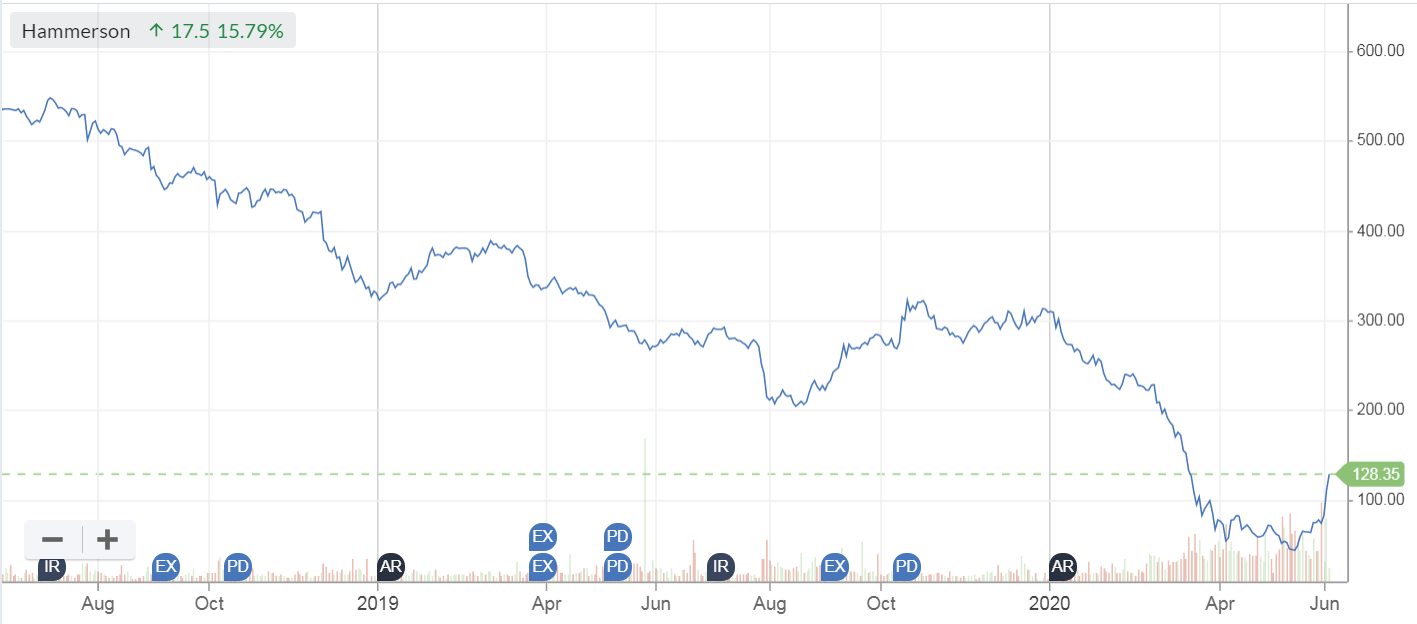
Property REITS - going bananas at the moment, I was a little early to this trade, buying Hammerson (LON:HMSO) and Newriver Reit (LON:NRR) some time ago, but they are now really coming INTU (geddit?!) their own. I reviewed the accounts of both, and concluded that they looked pretty solid on a balance sheet basis, therefore unlikely to go bust. Plus about 10% of HMSO shares were out on loan to shorters. Lovely! We're now seeing a beautiful short squeeze, resulting in HMSO miraculously becoming the 2nd most profitable position in my trading account. If the shops open successfully from 15 June, then landlords may not have to worry so much about rent arrears. HMSO is re-opening its flagship shopping centres on that date. The share price seems to be moving from this is going bust, to this looks like it's going to recover. I love situations like that, especially when shorters become forced buyers, because the upside is large, and it occurs fast.
Re-financing - many retailers are successfully refinancing, using equity raises and Govt-backed loan schemes. I'm sure there are likely to be many insolvencies, but perhaps not as many as feared. That's clearly what the share price of Hammerson is telling us;
.
DIY, consumer durables & moving house - being stuck at home for such a long period of time, we must all have become fed up with our surroundings? Therefore are we about to see a DIY boom? Some reports suggest it's already started, with DIY sheds being busy already apparently. Plus, the TV news showed long queues at an IKEA store which had just re-opened. For this reason, I recently bought some Topps Tiles (LON:TPT) - just above my target buying price of 40p. A recent sale & leaseback of property has strengthened its finances (freeholds are glorious things to have tucked away, as they can save the day when a crisis hits, as in this case). I remain bullish on estate agent Foxtons (LON:FOXT) on the basis that it has refinanced successfully, and market conditions could be over the worst. Also, I've recently gone back into Scs (LON:SCS) . Even Marks And Spencer (LON:MKS) is showing some signs of life. Dunelm (LON:DNLM) has been very good, I remain long there - a cracking business, that should do well on re-opening, in my opinion. Norcros (LON:NXR) could be another beneficiary, possibly?
There are lots of shares which could see a nice uplift, if consumers return to High Streets and shopping malls after re-opening day on 15 June. Hence why this is a particularly interesting area to look for bargains at the moment. Obviously the risk is that if re-opening is a flop, then prices could plunge back down again. I might top slice some holdings just in case.
The other risk is that some business may have permanently moved online, accelerating the slow death of High Streets? Or maybe we need a cull of brands which have had their day? Remember that brands which survive, will enjoy more market share of a probably smaller overall market.
I don't want to hold any of the above-mentioned shares permanently. These are trades, which I'll happily bank the profits on at some stage in the coming weeks/months, and move on. My feeling is that it's best to be in a well-protected bunker, when the 30 June interim results start to come out, in August & September, as the figures are going to look really, really bad. I'm not at all convinced that investors will just shrug off these figures as being a one-off. Some might, but it doesn't need many people to panic sell, to trash the price of smaller caps.
Work from home & Zoom
As mentioned previously, I shorted Zoom on absurd valuation grounds & that Google had recently launched a competing product, free. In recent days, I began to realise, from using Zoom, that if a tech product is taking off, then valuation doesn't really seem to matter in this booming market.
Friends persuaded me to use Zoom, and I now love it! Once a fortnight, I join a virtual p*ssup of my old Uni friends. It was a hoot, and I really enjoyed chatting to a couple of people I've not spoken to for 30 years.
Business meetings seem to now be migrating onto Zoom, and the couple I've participated in, have been very successful. It's not the same as sitting in front of someone, but it's a good substitute. Also, with everyone sitting at home, in casual clothes, I found it more relaxed. Plus of course, all the hassle, expense & wasted time of travelling into London, means that I'm getting a lot more productive.
My family are mainly musicians, and they have started using Zoom for online teaching. They even organised a very successful local concert, to showcase up & coming young musicians. The musical performances were pre-recorded, to get decent sound quality, and the whole thing worked brilliantly. I was amazed at the quality of the video & sound, when I joined the concert party (geddit?!). Discussing it later with my brother, he said the concert had been a great success, that the locals loved it, and donated £450 to pay fees to the young musicians. Isn't that lovely?! Bro said that musicians and colleges are all using Zoom now, and it works so well, he can't see any reason to even try out any alternatives.
Based on the above, I took an £8k loss on my Zoom short, and flipped it round to going long. This product could become ubiquitous, globally, hence trying to quibble over the current valuation was probably wrong.
I hardly ever make profits on shorting stuff that looks over-valued. $TSLA has humiliated me many times, for example!
It's generally better to quickly recognise that something is not going your way, and walk away, rather than stubbornly holding on, and seeing the losses mount. It can always be revisited at a later date, once the froth is starting to come off.
As regards working from home, I've discussed this with lots of my investor & city contacts. Most people seem to absolutely love it, although those with children are looking forward to the schools re-opening! My stockbroker works from home now, and says that with cloud-based software, it works seamlessly. Looking forwards, he may not even need an office in the city. Also, he said "we've got so much more money!" - says he can't believe how many years he suffered an unpleasant & expensive commute into London every weekday, spent £10 every day on lunch/coffees, then paid £7 for a pint of Peroni in some packed bar! Things are likely to be considerably different once this crisis has been overcome.
Personally, I hope we move to a hybrid model. Yes I like Zoom meetings, but I'm also really looking forward to meeting my city friends again for long, boozy lunches in our favourite restaurants, putting the world to rights, and chatting about interesting shares. Also I miss the buzz of the city.
It's great that many organisations, e.g. PIWorld, ShareSoc, and many others, are getting companies to do webinars & presentations for us. This is greatly improving investor access, and levelling up the playing field for people who cannot easily get into London for meetings.
If there is a mass return to working in offices, then I wonder if the shares which have boomed on working from home, could go into reverse somewhat? Who would want to be a commercial property landlord right now? We could see more vacancies as leases expire & tenants go under, maybe? Although there's also a lot to be said for having employees congregate in one building - usually more gets done, and good businesses build loyalty by bringing people together to fire off each other, etc.
EDIT: Something else I forgot to mention, is that over time, there should be better treatments developed for covid. In the USA they're very bullish on this, even talking about a vaccine later this year. I'm told by experts that this is highly unlikely, but who knows, they could get lucky. If that doesn't happen, then the US markets are clearly too high. On balance, I feel that if better treatments can bring the death rate down to a modest level, then society could get back to normal, with maybe just the most vulnerable being protected. For example people who have had transplants, have to take medication which suppresses their immune system, so are particularly at risk.
Therefore, rather than ranting on all the time about how the US market looks too high, I'm wondering if the market knows something I don't? Plus, as the old adage goes, don't fight the Fed! A year or two down the line, Govts and companies are likely to be drowning in debt, but for the time being, nobody seems to care. I suspect we might be in a new era, where interest rates have to stay at zero forever, regardless of what happens to inflation. QE could then be used indefinitely. Everything I learned at school & Uni about economics, and from my own experience, seems to have gone out of the window. End of Edit.
Oh well, I cannot put it off any longer, I'll have to plough through some rather boring company trading updates.
Let's start with a reader request;
.
Forterra (LON:FORT)
Share price: 215.5p (up 3% today, at 11:39)
No. shares: 200.4m
Market cap: £431.9m
Forterra plc, a leading UK producer of manufactured masonry products, provides this update and further detail on the measures it is taking to mitigate the impact of Covid-19.
Forterra has a 31 Dec 2020 year end.
- Gradual increase in despatches of goods to clients, as they resume operations
- Daily despatches now running at 50% of last year's level
- Revenue down 39% for Jan-May 2020
- April was the low, down 86%, May improved (but still awful) at -62%
- 12 of 18 manufacturing facilities are now operating, should be fully open by end July
- Trade body is forecasting that residential construction will improve in 2021, but still be down 20% on 2019 (seems quite gloomy to me)
- Restructuring underway, which will cost 225 jobs
Liquidity - this is self-explanatory, and sounds as if the company should be alright;
Balance sheet and liquidity
The Group entered the Covid-19 crisis with net debt (pre IFRS 16) of £43.2m at 31 December 2019.
The Group has access to a £150m revolving credit facility which runs to July 2022, which is presently fully drawn. At 31 May 2020 the Group had cash reserves of £79m as well as access to an undrawn overdraft facility of £10m.
In addition, Forterra plc has been confirmed as eligible for the joint HM Treasury and Bank of England Covid Corporate Financing Facility (CCFF) with an issuer limit of £175 million and is now able to access the liquidity available under this facility. The Board does not have any present intention to draw upon this facility, which provides the Group with additional headroom if required.
That's a ton of headroom.
Outlook - well positioned for attractive long-term market fundamentals. This clearly implies that the short & medium term are not looking great.
My opinion - it looks safe, i.e. not going bust.
I'm a little taken aback at how negative the short term outlook sounds. The company is clearly not expecting a V-shaped recovery in construction.
Dividends might be under threat, given the borrowings. I haven't got any recent broker forecasts to work on.
Overall therefore, I'm not really sure how to value this. Personally I would only be interested in buying at a much lower price. If you think the residential construction market could do better than expected, then this looks a decent company, which has produced good historic results.
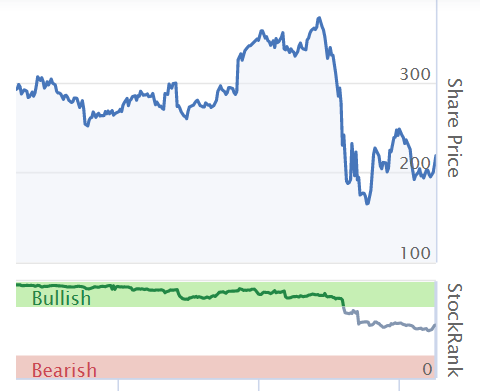
If we ignore the autumn 2019 surge in price, which was an indiscriminate rally after the Tories won the election & removed Brexit uncertainty, then the current share price is not that much below where it was a year ago. The outlook was vastly better then, than it is now. Therefore, I don't think the current price factors in the radically worse short & medium term outlook.
.
Angling Direct (LON:ANG)
Share price: 62p (flat today, at 13:27)
No. shares: 64.6m
Market cap: £40.1m
Angling Direct plc (AIM: ANG), the largest specialist fishing tackle and equipment retailer in the UK, is pleased to announce its audited financial results for the twelve months ended 31 January 2020.
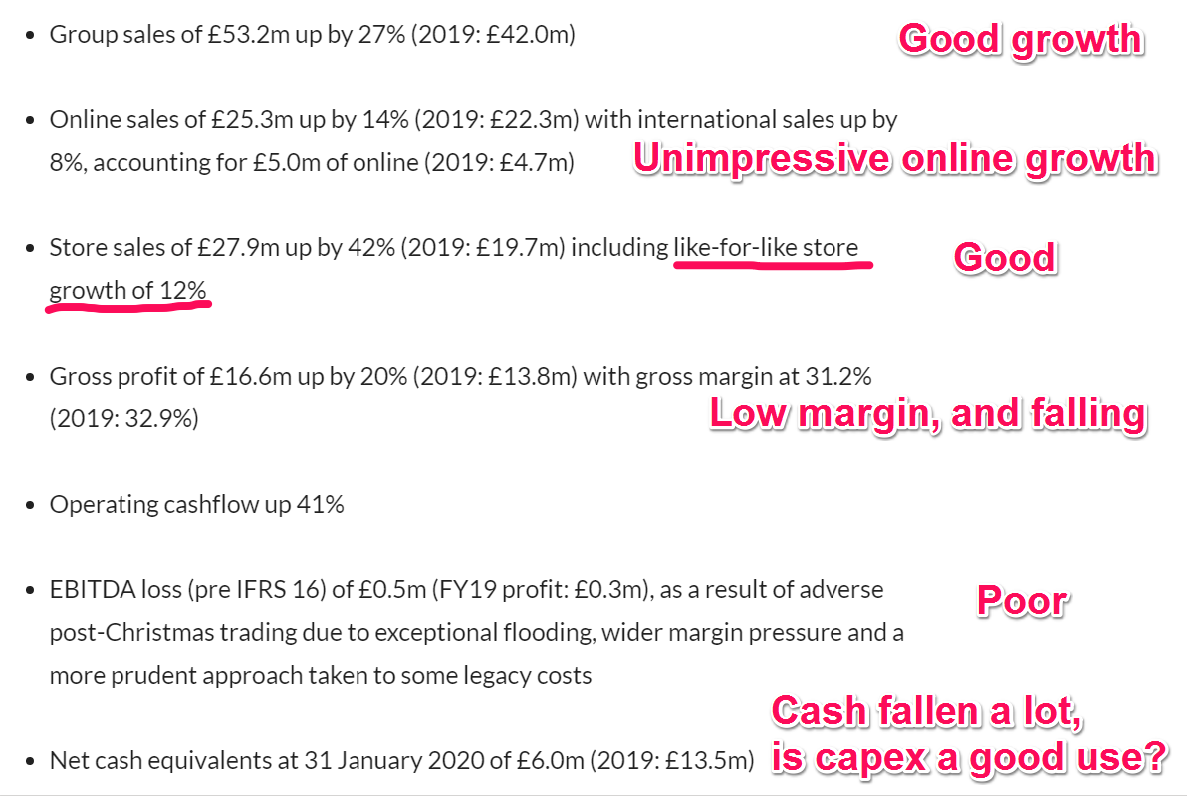
Let's try something new! I've added my very brief comments to the financial highlights section;
.
I think that's pretty much put me off wanting to dig any deeper. It's too low margin. That's tolerable for an online only business, but not one which has lots of shops too.
Cash is being spent on capex, acquisitions, and large inventories, but what for? There's no return for shareholders, because it doesn't make a profit.
I cannot see any attraction to this share.
.
Vertu Motors (LON:VTU)
Share price: 30.0p (up <1% today, at 14:24)
No. shares: 369.2m
Market cap: £110.8m
Vertu Motors plc, the automotive retailer with a network of 133 sales and aftersales outlets across the UK, announces its final results for the year ended 29 February 2020.
FY 02/2020 results were in line with expectations, at £23.5m adj PBT - not a lot, on £3.1bn revenues.
Guidance - none given.
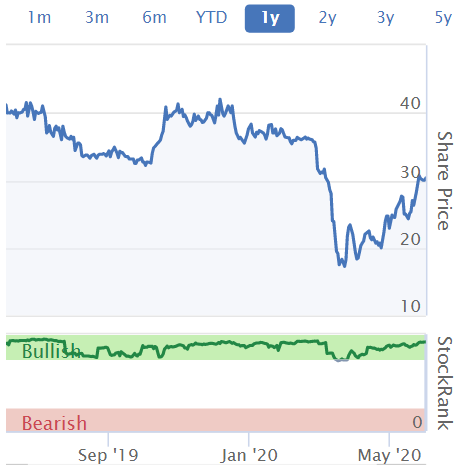
As you can see, the share price has rebounded very nicely, and is now back to the bottom of the range it traded before covid. Given the situation, I can't see any point in spending any more time on this. The valuation was attractive around 20p, but is probably about right, now it's rebounded to 30p.
.
.
I'll leave it there for today. See you tomorrow!
Best wishes, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

83 comments
Hi, despite the financial picture for the last year not being great for angling direct can't get away from the fact that fishing is very popular (as an outdoor and socially distanced activity people can do), the website has a statement saying there is unprecendented demand and delays in deliveries indicating they're doing alot of business. All shops are opening 15/6/2020. Noted a substantial fund holding declaration afew days ago. Google trends showing a massive spike in most fishing related searches recently and in my local park in London never seen so many people fishing. Anyway I'm pretty sure I will take a position in this, as turnaround potential. I know people will say that longer term things will go back to normal but doesn't the stock's popularity/price going up at least for some time. What do others think ?
I sold out of Angling Direct (LON:ANG) once the price recovered to near pre-covid levels. The company is barely profitable and I doubt people will splash out on the higher margin high end equipment in the current climate. Also the imported Japanese kit is likely to cost more, again hitting margins.
Hi
Paul really like you putting your comments in red - it’s very useful - maybe something you could look to do going forward.
Thanks hardeep. It's a bit more time-consuming, but I'll try to do more of this.
The bank balance bit is a great little nugget of information, I've been trying to find more data on this and UK consumer spending power.
The bank balance bit is a great little nugget of information, I've been trying to find more data on this and UK consumer spending power.
Remember UK unemployment is expected to peak at 10% and reduce to about 7% by year end. A lot of that saving is in the expectation of harder times ahead. I doubt anyone on furlough at the moment is considering a spending spree.
timarrReally enjoyed your pre-amble Paul, absolutely excellent and thought provoking.
Hi Paul
Loving the new comments you are leaving, please keep it up!
S
Hi Paul & all,
I'll give you a spanish anecdote to go with the French one, on opening up. Now, I've been fairly vocal about the NOT in proportion global lockdown, and it seems to me thats all now coming to the fore in the terrible media the UK endures...
But not to dwell on that. In Spain we had an incredible harsh Hugo Chavez, police state lock down & in the main the Spain are furious with just about every personal freedom being taken away. Not least after 3 months the final piece of 'control' being mandatory mask. Rightly or wrongly the majority are not having it. But, I slightly digress, the large shops & shopping sheds opened on Monday. Ive been every day to get a feel & to buy all the things we were to buy before the rude interuption. The UK followed Spain into lockdown and I believe will follow Spain rapidly out because the economy here & it will happen in the UK, was imploding. As it imploded the anger rose.
The rules have quickly been relaxed. I really cannot fathom what old Boris is doing with a Furlough until October (I mean what!!! what on earth is the reasoning for keeping people paid for another 5 or 6 months, if anyone has an inkling please do post).
So, we have all these guidelines here, and bureaucrats just love an opportunity to micro manage everyones lives, but the shops have been packed every day this week. The bars are all full, people distanced by two meters of course, 50% of internal space now usable for restaurants. Outside terraces have been allowed to double by the council's. The roads are full, the cars washes are full, and two Spanish business friends say they think they can recover the two lost months as the phones are ringing. Millions of jobs lost for sure but for me this is a good indication of pent up demand, There are still many old people walking around with face shields (which do nothing) and look at a child coming down the path in the same way as if Freddie Crougar had just jumped them. But hey, you cant blame them, the government told everyone 'it's gonna get you'. Mind you, lots then sit down for an Americano and whip off the hazmat, not much logic there but logic is a rare commodity these days.
So, I for one have gone from mega bearish too much more 'cautiously' optimistic.
The latest money week podcast with James Ferguson (who used to write for MW is excellent) he's no fan of lockdown but his comments on the effect of the money printing are very interesting & he's for Gold and equities as a result, because there is now so much more cash around.
I can easily see the leisure sector bouncing back, well at least the shares, for a short time if the above happens. Is a 24 year old barmaid really going to stop people standing together in a pub (regardless of the rules) ? Incidentally Brighton beach bars are open for take away. And if customers happen to sit on one of the tables outside, I mean what are they to do.... which is exactly what is happening.
Brilliant output again today Paul, thank you. I haven't been commenting much recently as I've been focused working on repairing my battered portfolio but have really enjoyed and valued your work over the last few months.
cheers
Francis
Paul, I like the way you put your comments in red next to Angling Direct's highlights. It make it easier to compare you comments with their's. It's like you're marking their homework!
Afternoon everyone,
Interesting comments Paul about Zoom. It's a difficult one to predict whether the growth and valuation will continue. It's likely there will be greater competition, like Google and Facebook's recent video product.
From an investors perspective, I'm surprised a few more companies aren't using these types of services for their investor presentations. I've joined a couple of company presentations through Investor Meet Company - https://www.investormeetcompan... . My initial thoughts is that the service is very good.
Some of my other experiences on conference calls/bridges have been quite painful. Hopefully more companies recognise there is room for improvement with better services available.
Does anyone have any other experiences that have/haven't worked well?
Cheers
Excellent insights Paul. I also enjoyed your interview on PIworld. Re: Zoom - When you mentioned recently that you had shorted it did make me think, as I bought some around the middle of April. Although I share your concerns about competition, Zoom could prove to be sticky for the time being, and having gained so much popularity in recent months, it's becoming the Go-To application for video calls. I now know at least a couple of people that have bought the premium version in the past couple of months. Momentum and price action are strong. I think with US large caps, sometimes valuation needs to be overlooked when momentum is the key driver of the moment. I'm not certain it will be the dominant video application in 5 years because technology applications are fickle and a better option could be around the corner. Until the momentum and price action changes, will ride the zoom up.
With regards the re-opening theme, what do people think about Greggs? I'm actually looking forward to a Greggs pasty when I get the chance.
Not many people have made money shorting US-listed SAAS stocks. In fact, its been a nice way to light your money on fire.
Zoom announced earnings after the market yesterday and just knocked it out of the park. Growth in revenue of 168% for Q1 2020 with net income coming at $58.3M, vs. a year-ago of $8.9M.
EPS guidance for Q2 2020 of EPS of $0.44-$0.46 (vs. consensus analyst estimate of $0.11) for the year the EPS guidance of $1.21-$1.29 (above an expected analyst estimate $0.44).
Even more impressive Zoom generated $252 million in free cash flow on revenue of $328 million in Q1 2020, or a 77% free cash flow margin. Which is jaw-dropping, to put it mildly.
I just thought I'd share this from Berlin. Obviously deaths much lower, less than 200 I think, v London 10,000. But yes, old people may stay in, but I doubt many under 35 years old will.
https://www.thelocal.de/202006...
Hi Paul,
Love your "try something new" Cut to the chase and then some :-)
I thought of you last night Paul................No, not in that way !
I live in a small town in the South of France & yesterday was the first day bars & restaurants were allowed to open & they were packed.
The bar managers obviously hadn’t anticipated how busy they were going to be as they kept on having to grab more tables & chairs & the socially distanced tables got closer & closer as the night went on as the managers understandably didn’t want to turn away trade.
It was outside, but I didn’t see a single customer wearing a mask & even the staff started taking them off as the night went on.
There were not many over 60’s out, but there were loads of youngish 18-25’s about which I would imagine would have a great read across for Revolution Bars.
How interesting, thanks for posting that re French bars & restaurants.
The US market is being propelled by the huge sums of money that have been poured into the economy by the Fed. I don't look at US valuations anymore tbh. I look at the earnings and sales figures for the past 6-8 quarters amongst a few other criteria and read the charts. I don't mean this to sound as though I have it all sussed out and don't make mistakes; I haven't and I do but 3 out of 4 stocks will follow the market trend which takes a lot of worry out of my approach.
Thanks for all that, Paul. Re business meetings moving to online, in Germany they’ve changed the law post-Covid to allow AGM’s to be held online. I’m hoping the law will be changed in the same way in the UK - very handy if you don’t want to lose a day travelling there and back! No sign of any change yet, though.....
In respect of (relative) winners when shop re-open, I think we also need to think about the weather. I doubt the patient, mutually respectful lines we have mostly seen to date will survive when normal British weather returns ie wind & rain. I might do 20mins for the for the must get fresh veg & weekly shop in Asda but not to go shopping for clothes.
However, destination shopping in big sheds on retail parks may do better as you can drive and there is lots of space inside. I therefore also expect a DIY/home improvement boomlet, with high value durables like sofas/ new kitchens /bathroom upgrades / home cinema etc doing surprisingly well.
People may choose to do up their house with the block of money they would normally put towards a foreign holiday, especially if they believe they will be spending more time there than before with extended home working. Cocooning was a consumer trend from a few years ago I would expect to come back. (Disc. I hold Norcros (LON:NXR))
Totally agree (disc hold Norcros (LON:NXR) and Scs (LON:SCS)) People have also been sitting inside in their homes looking at their rooms a lot and planning what they would like to do with them . Also seeing them more clearly as we shift from darker weather of March to sunlight in this spring which shows up the faults more. I have a painting project due in next few weeks due to this. Also agree with regard to clothes. Clothes shopping wont be as attractive any more for younger people as you usually went from shop to shop to see what there was and see which you liked best. Now there will be lots of time spent in lines potentially in the rain which I think will put off many
Norcros (LON:NXR) isn't one i've spotted before so thanks for mentioning Paul and Fegger and Zipmanpeter. looks very very good value indeed (should be closer to c£250-300m market cap perhaps easily? seems to have missed out on the rally as you say - any idea why? Profit warning earlier in year maybe, were they too pessimistic?). Have added a reasonable holding to sipp and will continue to appraise. Thanks
Norcros (LON:NXR)
seems to have missed out on the rally as you say - any idea why? Profit warning earlier in year maybe, were they too pessimistic?). Have added a reasonable holding to sipp and will continue to appraise. Thanks
Your best bet is to look back at the hitorical articles with regard to nocross and they will give you the flavour of why the buisness has hitorically been related very cheaply on p/e basis - albeit they had had a really good run to a more normal earnings multiple pre covid.
I would say the main reasons are
Large South African elemty to there sales / profit.
Historically large pension deficit , as they have acqyuired add ons over th eyears and beded them in the pension decicit isn;t as bad as a % of the larger combined entity.
Debt - the company has not inconsiderable debt.
Bolt on large acquisitions - they have newish acquisitions that some would probably presume need to p[rove they were worth the value the company paid for them.
Anemic organic growth.
That's probably "potential" red flags tgo put some or most people off - i am bit of a NXR fanboy when it comes to looking at the overall situation and saying the buisness is fundamentally wort more than a p/e of 5 or 6 ignoring covid. Generally spekaing pre covid looking at the cashflow from the main operatoions that shoudl be enough for dividend / acquisition rleated installments , small add ons pension payments and ability to pay down the debt. So it has the potential every couple of years to buy in extra profit without stretching the debt too far. I am guessing covid reasons will mean that temporarily the debt may be going up rather than down which is potentially another worry.
re Marks And Spencer (LON:MKS) watchers from alpherville....
Jefferies goes up to “buy” on Marks & Spencer, 160p target price.
MKS' FY confirmed improving Food resilience, a trend we expect to persist in the months ahead. Updates on liquidity and funding headroom reassured. These underpin MKS' staying power through the COVID-19 crisis. Clothing + Home will likely remain a share loser over the longer term. But Food is now a much-improved proposition. And the disconnect between equity value and FC potential is just too tempting. ...
We were impressed with MKS' Food progress pre-crisis. And are now reassured by its ongoing relevance to UK consumers. It is difficult to articulate how C+H will successfully defend share, but a stepped-up shift to a food offering with a stronger USP will make MKS a better business. One that is underappreciated on a cal 2021 FCY of 16.9% (vs 9.7% FCY for the major UK grocers/6.9% for UK non-food coverage). We would refrain from thinking in SOTP terms given the ongoing cash neutrality of the OCDO jv, but recognise the uplift to gross margins it provides to Food gm.
Storming up today Chemring (LON:CHG) 95% of revenue for second half of the year delivered to date and first halve of the year performance hardly impacted by covid. First half year profit more than doubled from same period last year and positive future outlook. Net debt has been slowly decreasing also over recent years.
Maybe worthy of further investigation.
Hi Paul, I too enjoyed and found informative your macro intro. Instead of just a ‘thumbs up’, I thought it nice to let you know! Jon
Keep the macro "ramblings" coming Paul, very useful, enlightening and at times amusing which is rather comforting for the somewhat solitary life we PI's live.
ATB,
NM
Thanks Paul
I just subsribed a couple of weeks ago and like the write-ups
We are annoyingly similar in our take on things and some of our poor US bets on things like ZM and TSLA. I've been punished twice on TSLA now this year and probably by luck more than judgement managed to get out of ZM short at profit in 160s before it went crazy again. I still can't bring myself to go long on valuation grounds but as you say these may be the winners of tomorrow and the valuation is justified, it just seems the market prices in the best case scenario of all plans going well and ignore risks. Are enough people going to pay for ZM ongoing? Very hard to say but it doesn't seem to matter, the "network effect" share pricing model ignores all fundamentals and EPS metrics
We should stick to small-med size UK shares. I seem to be doing well on many and then throw it away on ones like the above plus maybe the odd UK short recently (on things like AUTO and TRN which i'm happy with the business models on but just feel valuations are too high). Like you i'm a fundamental investor mainly and always kick myself for not more momentum investing, or being prepared to buy shares in something with a PE of 30+ in many cases - typically shorting these - and then see them edge ever higher!
Both me and the wife work for large cap retailers so where i can share any insights I will. As you say, Online seems to be going fantastically both in Gambling and Homewares and I suspect Retail will start strong on 15 June but let's see where it ends up. Certainly share prices seem to be reflecting this at the moment with valuations almost back to pre COVID levels in many cases. Dunelm (LON:DNLM) in particular seems toppy as is BME which i see a broker reduced from Buy to Hold today - if you're theory on people having loadsa dosh in the bank to spend is right... which it probably is given Furlough schemes and no train season tickets or Lattes.... then all retailers may benefit rather than just the bargain end
Look forward to sharing more ideas and info where i can to help support profitable trading decisions. (and if you do have any views on Auto Trader (LON:AUTO) and Trainline (LON:TRN) valuations in the meantime happy to discuss!) thanks.
Hi topturkey,
Welcome to Stockopedia, and judging from your maiden speech (!!) you're going to be a very good member of the community here :-)
Just to clarify one point from your post, you said;
... if you're theory on people having loadsa dosh in the bank to spend is right...
It wasn't a theory! The £30bn increase in household bank balances in Mar-Apr is factual - the Bloomberg article reported it as being sourced from Bank of England data published earlier this week.
I suppose the question is whether people are likely to spend that money freely, or hold it back through fear of unemployment? My feeling is that we're generally a nation of spenders & the future will look after itself, rather than savers.
Regards, Paul.
Yes, you're right of course. I saw that UK population also paid down record credit card debt over last two months. As you say, i guess the theory part was how much comes back into Retail and other sectors but i do agree with you being a nation of spenders that it will find its way back into the coffers of hospitality / retail.
In the back of my mind i still feel that a good chunk of the c9m furloughed jobs here and c40m laid off in USA will not be remployed when furlough schemes end or will be redundant by the Autumn at any rate and rihiring of new employees will be low. Plus also the trickle down of every large business (maybe except tech) seems to be significantly reducing all Capex has to impact the wider market and knock on effect to employment so we're in for tough times.
Paul
The extra £30bn in the bank is about £1,000 per household. I wonder how much of that is that most people haven't booked a summer holiday yet. Could be a big surge in bookings to Spain/Italy/France/Portugal when air bridges are agreed. I think likely a short burst of activity as shops open up as a release from boredom then a decline as job losses start to mount as furlough payments end. H1 results are going to look awful for a lot of businesses, will be interesting if investors can look through this and bank on a H2 recovery.
HB
Good points.
As regards holidays, I asked family members what their attitude is towards foreign holidays. They're not keen. If the proposition is to spend ages in spacially distanced queues in the airport for additional checks (temperature, swabs, etc), then having to wear a mask throughout the flight (horribly uncomfortable after just a few minutes), no food or drink, having to ask permission to use the loo, and maybe ending up catching covid into the mix, my family said they wouldn't even entertain it! Sounds more like mild torture, than an enjoyable holiday!
Even with air bridges, I'll be amazed if many people want to undertake an experience if it's anything like the above scenario.
Although it depends what the UK weather is like. Given the recent heatwave, there's no reason to go abroad. But if the rest of the summer is a washout, then maybe people might want to bask in the sun abroad, and put up with an unpleasant flight/airport experience?
I don't know the answer, but it will be fascinating to see how it all pans out!
Regards, Paul.
With the queues at B&Q since it opened, I think you might be right about the 'stay-cations'.
The retailer such as Dunelm (LON:DNLM) that spent money being omnichannel are much more resilient than those that haven't. They are also poised to pick up market share I reckon from the weaker capitalized and unprepared retailers that now need to spend significant CAPEX to get up to speed just to survive. I'll stick with Dunelm (LON:DNLM) management that saw where the market was going and spent accordingly.
The retailer such as Dunelm (LON:DNLM) that spent money being omnichannel are much more resilient than those that haven't.
Absolutely. Click and collect, e-commerce, anything to relieve pressures on the stores. Anything that needs high footfall to survive will struggle with social distancing. And omnichannel is really hard if you don't have the right platforms - get it wrong and you end up with tons of fraud.
The Associated British Foods (LON:ABF) update on Primark was quite good - most European stores reopening, all busy but the bigger ones with lots of footfall won't be able to handle pre-pandemic levels due to distancing. Larger basket sizes but maybe due to immediate pent-up demand - summer clothes for kids, for instance.
Overall discretionary retailers with a good omnichannel offer and those that need lower footfall will do very well I'd think.
On the IKEA thing - a lot of the demand is coming from renters needing to move. The Rightmove (LON:RMV) update the other day suggests a surge in rentals which are non-discretionary unlike house sales. Property agents specialising in rentals will probably be doing quite well.
timarr
Dear Paul, thank you for your insights. As always they are awesome and very well communicated. I appreciate your honesty regarding your short positions; it’s great when people post their successes as well as their lessons learned.... speak soon Sanjay
Taken from ProActive - be interesting to see if the Virus dies out or we get a second wave - If we are in the second wave camp I can see WSG gaining a lot more contracts for this type.....
Westminster Group PLC (LON:WSG) said it has successfully conducted a trial of its fever screening solution at the Stockholm Arlanda airport in Sweden in association with Menzies Aviation and their client, Air France.
The company said Menzies will continue to use its solution to conduct operational trials with Air France and other clients’ flights over the coming weeks to “fine tune” the delivery of the screening.
Westminster noted that feedback from the first live trial was “extremely positive” with all passengers screened.
"Working with Menzies Aviation on the trial has been excellent. We have worked hard in order to supply them with the correct solution for their fever screening requirements that is fit for purpose and has the least impact on an already complex procedure, and within the required time frame. I need to thank all those involved at Menzies Aviation both in the UK and their team in Sweden for their efforts”, Westminster Group’s general manager, Hamish Russell said in a statement.
"Westminster's fever screening solutions have been supplied to numerous industry sectors to detect, mitigate and defeat the spread of [coronavirus]. Westminster continues to add to its fever screening offering ensuring products are adaptable, cost-effective and can be implemented and upgraded into existing processes or technology", he added.
Shares in the company jumped 6.4% higher to 11.2p in early trading on Wednesday.
Don't forget that the tech part of Westminster (LON:WSG) is just a distributor and has been very volatile in recent years. This time they are lucky - as the services division has suffered from Covid the tech division has benefited. I have been watching them for years and owned briefly at one stage. At some point they may become profitable and cash generative and stay that way but if so then the success will probably be driven by service contracts rather than tech distribution.
They have had several false starts which were partly bad luck (oil price collapse, disease in Ghana, sanctions on Iran) and partially poor execution (ferry services in Ghana) but it is very fair to say that they are consistently vulnerable.
The one thing I would add is that I can see that in their developing world markets Covid could increase the priority of good security at airports bu that this will probably take some years to start showing through as service contract wins.
Yes, WSG seems to be principally a distributor/supplier of other manufacturers' products. And there are plenty of competitors out there doing much the same!
I agree with Paul that young people in particular want to get back to normal and a large number have money to spend. The problem is that until the present social distancing rules are relaxed shopping will not be much fun. For example, when girls go out to buy clothes they tend to go with a friend or in a group. They like to handle the clothes and try them on. Initially this will not be possible. Also, people will not put up with long queues and inconveniences for very long with a friend of mine having to wait over 2 hours at a B&Q store in order to pick up a pre-ordered item and saying never again. Business will only get back to normal when human interaction does and until then I think we have to rely on the internet.
People do want to get back to normal but will normal be a bit new? It seems to me that many people of all ages were already migrating online for their shopping needs and that this will only accelerate. The reason the likes of Boohoo (LON:BOO) have performed so well (oh why did I sell in March having held since they were 30p!).
“What's the betting that this fuels a spending spree from 15 June?” I suspect it might though it shouldn’t. I am “retired” and “comfortable” but my income has been hit (income from a holiday rental down by 80% and decline in my portfolio) and so I am hunkering down a bit as I can see worse to come after Q2 figures, and a possible second wave after the more relaxed social distancing measures, high post furlough unemployment figures in October/November just before Christmas which of course will trash Christmas sales and then comes December 31st. (Yes aren’t I a happy chappy).
Maybe I just don’t get it and I should hand my money over to someone who does (Terry Smith or Paul are you going to start an ETF!!) but for now I am prepared to back my interpretation of current events that we are in for a world of pain and I am happy to sit in Cash, gold and Anglo Asian Mining (LON:AAZ) accounting for 63%. On top of that I don’t have the mental attributes to trade in and out of stocks in a market like this or any market.
Share prices seem to be over inflated in some cases, as some of these companies are ( covid ) loss making and are likely to be for some time.
https://www.stockopedia.com/share-prices/vertu-motors-LON:VTU/news/urn:newsml:reuters.com:20200603:nRSC7426Oa
Final Results out at Vertu Motors (LON:VTU) which cover the period up to Feb 2020, but lots of interesting comments from the Chairman and Chief Executive with respect to the post results period through the Covid impacted economy. The transitioning to operating in a non-physical environment, managing cashflow (successfully - better than expected!) etc.
Some non-cash impairments to intangible assets in the year end Balance Sheet, taken on a view of change in projected discounted cash flows, but tangible assets still exceed the current share price.
The market seems happy but it would be good to get your critical eye on this one please Paul.
Hi dealtn,
Thanks for the synopsis on Vertu Motors (LON:VTU) .
I'll write a section on it later this morning, but am putting that off by doing some macro ramblings first.
Regards, Paul.
Enjoying the macro ramblings, as thinking through how the economic climate will evolve is relevant for all investments, not just the specific shares covered in detail each day. They also usually put a small on my face. Keep up the good work Paul.
Vertu Motors (LON:VTU)
for a company that has a £3 billion turnover i don't think the order backlog would give me any massive comfort.
On-line and telephone sales operations have continued and an order bank has been built up since 25 March, comprising 825 retail vehicle orders and 749 fleet and commercial orders. These firm orders and the order bank from previous months, as yet undelivered will be delivered to customers once the Government's restrictions on showroom operations are lifted.
I guess the bit below is positve
Additional working capital facilities have been approved by the Group's bankers, providing substantial headroom against our forecast cash flow requirements for the next six months. These cash flow forecasts assume a resumption of dealership showroom activity by the beginning of June.
The following possibly a bit more sketchy
The Group has and continues to enjoy, supportive relationships with our banking partners, Barclays and The Royal Bank of Scotland. Covenant waivers have been obtained for the May and August measurement periods with a further review agreed for the subsequent quarterly covenant measurement periods.
I see this share as a bit of a crapshoot that may go wrong at present , i would worry the high level of turnover probably comes with an inherent level of fixed costs that could easily be hard to get rid of if turnover materially decreases margin aren;t exactly great at the best of time.
Note there working capital position doesnt look great. Trade payables are 720 million and trade receivables are only £70 million. In theory the inventories of £640 million should fill in the shortfall If sales materially reduce and there is proportional reduction in payables and receivables. i don't know the inventory breakdown details (i guess it could be below market value if its cost price vehicles for resale?) but it's not generally the kind of asset i would generally want to rely on to provide cash necessary cash to pay the bills that will surelt be coming in at present. Perhaps a sale and leaseback situation could be used if they are really in difficulty. when the company says they have a"strong cash position" i am not sure i agree with them - it is a net debt position after all. With companies like this with a potential cash crunch could the directors end up making decisions in th best interests of bankers rather than shareholders - quite easily"!
AIM tiddler React (LON:REAT) raised £1.25m at 1.5p per share this morning.
https://www.investegate.co.uk/react-group-plc--reat-/rns/placing-to-raise-c--1-25-million/202006030700037467O/
In contrast to most current fund raises, this one was not to shore up he balance sheet, but to take advantage of COVID-19-related growth opportunities - REACT is in the deep-cleaning business and the current crisis is presenting both short and long-term opportunities.
The placing was over-subscribed and the share is up strongly this morning, to well above the placing price.
LSE
Off topic I know but I just felt, after some comments the other day, that it's worth another rant. I am reading on an 8in tablet
I have a lot of alerts RNS and price with them. Alerted today to Wizz Air Holdings (LON:WIZZ) results (Happy holder and have been so for a few years now)
Firstly it takes a delay to present the news. Then there are links in boxes on the right hand side which clutter the page.
Secondly in portrait mode IR cuts off the comparative figures
Thirdly in landscape mode it cuts off the initial letters of the text.
Why oh why do they change a perfectly good site to this - what a waste of money. The designer obviously does not look at the site the way PIs do
Grrrrrrrrr!!
PS Anything I am doing wrong or suddestions?
Steve
Sorry should be suggestions.
Perhaps suddestions is short for sudden suggestions
Anyway all welcome
Town Centre Securities (LON:TOWN)
I hold a small position, bought recently as a recovery play. Quite a huge discount to NAV. Large family ownership, they will want this to survive.
Not overwhelmed by today's RNS. They will pay the interim dividend on the basis "This decision is based on a review of cashflow forecasts and various operating scenarios". But then later go on to say "...it remains too early to quantify the on-going impact of COVID-19 on the business and as a result, all previous guidance on performance remains suspended at this time"
Well, if their cash flow analysis provides confidence to pay the dividend, please share.
They go on to say the car park revenue is largely gone. In the last half year results car parks 6.4m revenue so losing that knocks down OP after finance costs.
I see at the half year they seemed to have drawn down the OD and sitting on 24.9m cash so odds on they can see through the year.
Be interested in your views on Angling Direct Angling Direct (LON:ANG) who reported today. Delivered growth looks good, they have a low share of an expanding market and are the only scale player. They are beneficiaries of covid (fishing is a socially distanced sport). Prospects seem good but profits depressed by investments in acquisitions, IT and systems.
Hi Paul - Would be really interested in your views on Forterra (LON:FORT) - A company i've been in and out of and followed for a while. Their update gives an interesting outlook on the housing and construction sectors as well as their plans to address medium term demand drop.
Thanks
I would also be interested in Forterra (LON:FORT) - it is not a stock that I have owned but it is an interesting indicators for housebuilding industry (bricks and concrete). It has not been reported on often on this blog - but its market cap, which has fallen more than £250m from its pre-Covid level is now below £500m.
The market has taken today's update positively - as it seems to have ample liquidity £79m of cash, a £10m overdraft facility and the ability to tap into a £175m Government Covid facility, which the company says that it probably does not need.
Despite this, the update I thought made sombre reading. Net debt (exc leases) has increased by £28m to £71m in the five months to May. Revenue in the first five months of the year is down 39% and the current run rate is picking up from the depths of April but is still 50% of last year. 225 jobs are to go, unfortunately. Although the company is not providing forecasts it does report that the Construction Products Association is forecasting that the residential construction market will be 20% lower in 2021 than 2019 - so no V shaped recovery expected there.
Also I noted that in today's update on the liquidity situation, no mention was made of the £50m accordion facility, which is attached to the currently fully drawn £150m RCF and which expires in July 2022. This accordion facility was mentioned in the Dec 2019 results - so I found it intriguing why no mention was made of it today. I am only speculating but I wondered if the covenants on the accordion mean that it cannot be drawn.
Instem (LON:INS)
I hold. On the basis INS have a technical moat in a high-value area. Namely they have employed a number of staff skilled in pharma regulatory approval process and mgt knows this area as well. Hard for other firms to find these people, including the Pharma firms. Value is in reducing the approval process as even one month's acceleration in time to market is a large revenue pull-forward for some drugs sold at volume.
Yes agreed. I also hold. Average time for drug development is 13 years and INS have reduced this to 11 years. All the major drug companies are clients. INS claim to have some involvement in the process of bringing almost all new drugs to final approval. I have met management - competent, passionate and loyal. Phil Reason has been at INS for 17 years.
I looked at it a few months ago, nice business, good market position. Downside for me was in an interview when asked about dividends he said if they ever wanted to pay a dividend they would have to reorganise the capital structure. It rather put me off. Whilst I like growth companies even a small cash return has to keep some management focus surely?
Still, a nice 20% uplift in the SP this year for holders.
Morning Paul,
Can you take at look at Forterra
Interesting outlook update that has wider implications for the construction industry.
Thanks
can you take a look at Westminster please
Can anybody post a link to RNS feeds on LSE web site or any other site? This new design on LSE has me baffled. Thanks
investegate.co.uk generally easier/better....otherwise there is a tab RNS at the foot of the page on LSE.
many thanks
On a quiet day, 2 articles in market report of FT today, first re 30 year bond yields...no action in the 10 year yet but some steepening developing. This forces equity markets on to an inflationary footing if it continues... also, $ weakness, another story. Of course it may come to nothing as it does so often... but both are supportive of cyclical stocks, commodities, FTSE 100 and banks. Less so expensive safety/ growth sectors. Time will tell.
Morning Paul, Instem (LON:INS) would be nice if possible.
PCF (LON:PCF) - interims out today. I am a very uncomfortable (rabbit in the headlights) holder of this share. My one worry (and it should have been an elephant type worry) - is that they have previosuly reported very very low bad debt levels. This leaves not as much wriggle room really for a crisis compared to a company with more conservative provisioning. My logic for not worrying was that the majority of loans didn't really seem to be the type handed out to bad debt delinquents and the business plan overall did seem to be working very nicely expansion wise.
How are todays results ? - they have been quick to book a covid related impairment charge at 31/3/20 of £1.6 million. The crisis really didn't properly kick off until mid march - but it kinda makes sense if a boat load of bods rang up mid late march asking for deferrals - it looks like this has happened.
It will be interesting but nerve wracking to see how this stress test of their business model pans out. Not sure if its good if all their "good customers" pay of loans early as they have been given a freebie by the government and they are left with the reprobates.
It will be job very well done if they can keep the lights on , concentrate on doing the basics right - if they can avoid the need for raise more capital that is my hope - shareprice is down 40% from the peak price pre covid so not great dilution wise if they need to raise funds now. Although the shareprice had had a decent run up from the low price of 25p last summer.
The net interest margin in the period has taken a hit too - down from 8% to 6.8% - this is somehwat concerning and unexplained.
As with many other companies they have completly copped out and removed any marekt forecasts - for a finance company with a simple buisness model - not exactly helpful to me as a shareholder.
I am guesing the more sensible people are the ones who exited this share at the first hint of trouble - probably no surprise looking at the chart that the sensbile people were those who exited late feb and saw the writing on the wall with were we woudl be now.
I can't remember off the top of my head what the current book value of assets is - possible slightly above the current price. So if they do need to raise funds it probably isn't a complete disaster as long as they won;t be reporting material year end losses - without ANY guidance i am clueless as to how bad this may get.
Hi, This is one for Graham as he has covered before, I cannot remember whether he was a hold, or whether this was sold for his house purchase. T.
I would be interested in hearing your views of the Pcf (LON:PCF) H1 results today.
Morning Paul,
Enjoyed reading your write-up yesterday, particularly Intercede.
Today Instem have posted their FY results and am interesting to hear your view.
I hold
Michael
I’ve always found that it helps to stimulate Paul’s interest if you want him to look at a particular company.
Try saying something like:
Hey Paul, Instem’s £ins results are out today. They made a small loss but claim they made an adjusted profit of 3.2 million which is a beat according to the Stockreport. They’re putting the loss down to, amongst other things FX headwinds, capitalising development and amortisement of acquisitions - do you think the underlying performance is actually good?
I note they also have a significant contract win. Revenues are growing, PE is over 20 but the PEG is below 1.
Could be of interest.
Oh and if someone could tell me why £ins didn’t work, I’d much appreciate it.
Try caps INS - Instem (LON:INS) . Putting a full stop immediately after messes it up too, hence the space before.
Use capitals after the £
Thanks for this. I only have limited time/bandwidth, so cannot cover everything. Therefore, if people give a synopsis saying why a share's trading update looks interesting, I'm far more likely to add it to the list and write something about it. I'm first & foremost a professional investor, and write reports as a sideline.
Instem's CEO also says that business has been strong in 2020, cash balances are up and they 'anticipate a robust H1 performance'.
Hi Paul, I must say I thoroughly enjoyed your interview with piworld which I listened too the other night.
You refreshing approach which enthralls us here most days is even better in voice mode.
Can you add the link here?
Paul's interview is here.
How kind, thank you Brookeda! :-)
My morning smallcap tweet:
Vertu Motors (LON:VTU) DP Eurasia NV (LON:DPEU) Instem (LON:INS) React (LON:REAT) Angling Direct (LON:ANG) PCF (LON:PCF) Indivior (LON:INDV)
Vertu Motors (VTU) FY(Feb) U/L EPS 5.12 (5.1). Trading: £20m loss in Apr & May together, significantly improved on the Group's initial forecasts. Cash at 22 May £44.7m, up £14.7m in 2 weeks and significantly higher than initial forecasts. I hold.
DP Eurasia (DPEU) Mid March to end May system sales down 13%. Strong liquidity position: cash at hand and additional borrowing capacity at Turkish banks. Could repay Russia bank borrowings if needed. Sales increasing in Turkey as curfews lifted in some cities.
Instem (INS) wins $1m contract, majority recognised this FY.
React (REAT) £1.25m placing at 1.5p , a 2% discount.
Angling Direct (ANG) FY(Jan) rev up 27%, EPS -2.03 (-0.76). Online sales in lockdown 'robust'. Can survive a 'worst case' trading environment.
PCF Group (PCF) H1(Mar) EPS 0.8p (1.2p). Customer forbearance £138m at 29 May, 34% of lending book.
Indivior (INDV) loses patent claims 1-5, 7, and 9-14 in its SUBOXONE (buprenorphine and naloxone) Sublingual Film patent. Co may appeal. No idea if this is a big deal.
Results from Hipgnosis Songs Fund (LON:SONG) are, unsurprisingly, good. They're quite pleased with themselves:
We have become a FTSE 250 company in only 20 months, which I'm told is the fastest of any company ever on the index, and we are now the number 23 biggest yielder on the FTSE 250 meaning there are only 22 companies paying a bigger dividend than we are at a time when many have had to cancel their dividends altogether.
I'm quite pleased too, but I still haven't the faintest idea how you analyse the thing.
Goco (LON:GOCO) has an interesting update as well - less about the company and more about peoples' behaviour - seeing car insurance levels returning to more normal levels, for instance. However, I thought this was interesting given that they can track how, when and where people are looking at the site:
Despite some return to work and increasing normalised patterns of work at home, there has been little shift back to previous behaviours relating to device, and time and day of week, suggesting that even though people are searching more, they are adopting new life behaviours
Basically - still lots of people at home, now searching on desktop in the middle of the day rather than on mobile at the beginning and end. It'll be interesting to see how much that's maintained as lockdown is lifted.
As an aside - the LSE RNS service update may possibly be the worst website 'refresh' I've ever seen. It's quite extraordinarily bad.
timarr
I'm very happy with this : Ferrexpo (my largest holding) is pleased to announce that yesterday the Kyiv Court of Appeal fully satisfied the appeal of Ferrexpo AG.
I’m delighted too being a holder. It’s unlikely Paul will give it any air time as it is not UK, not small cap and is a hole in the ground
Yes sorry . Quite right. I did try to delete but seems you can only edit, so could have just mentioned something else. Strange reaction to news. So couldn't help but buy more!