Small Cap Value Report (Wed 30 Aug 2017) - GYM, HSS, OPTI

Good morning, it's Paul here.
Apologies for the mix-up yesterday. Graham & I got our wires crossed, and both thought that the other was writing a report. Anyway, I rectified the situation with a report on 5 companies which I published last night. So yesterday's report looked at;
Interquest (LON:ITQ) - another profit warning
Findel (LON:FDL) - trading well, but I have other concerns
Image Scan Holdings (LON:IGE) - positive trading update (I hold this one personally)
IG Design (LON:IGR) - in line trading update, and decent outlook
Real Good Food (LON:RGD) - another profit warning
Here is the link for yesterday's report.
GYM (LON:GYM)
Share price: 212p (up 3.4% today)
No. shares: 128.2m
Market cap: £271.8m
Interim results - this company operates 97 low cost gyms in the UK. It reports today on the 6 month period to 30 Jun 2017.
The shares listed in Nov 2015, at 195p each. So overall, little share price progress has been made since then, once the initial flurry of excitement wore off, as you can see from the 2-year chart below;
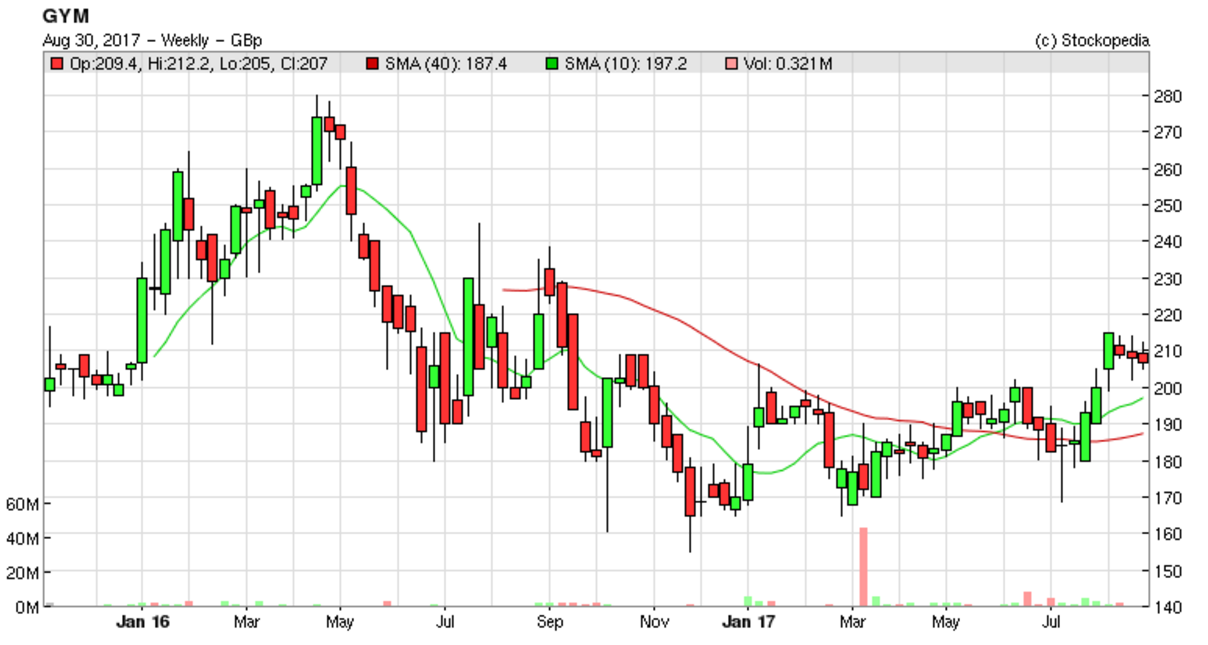
I like the chart - a long period of bottoming out, and now what looks like the start of an up-trend. Could this be a buying opportunity? Let's have a look.
The financial highlights cover the main points, with my highlighting the most important bits;
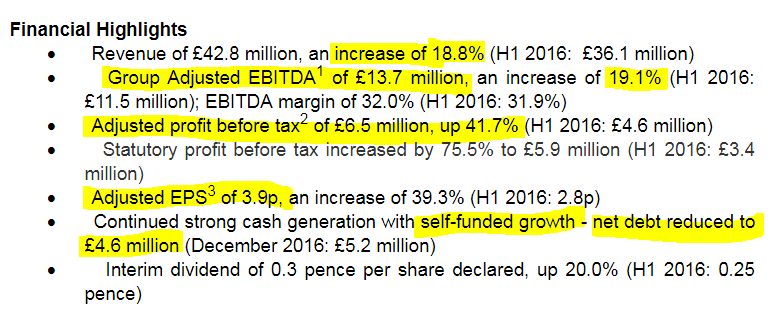
As you can see, there's good growth. This company is basically a self-funding roll-out - i.e. the cashflows from existing sites are being used to finance the opening of new sites. I really like self-funded roll-outs as investments. The beauty is that investors can just sit back for a few years, and watch the company expand & grow more profitable. That usually leads to considerable share price appreciation.
The main risk to roll outs is that operational problems are considerable. Management has to not only manage the growth, but also keep control of a rapidly growing business, which is far from easy, and requires strong management. The other risk is that competitors spot what you're doing, and copy or improve on the format, thus reducing returns. Other key risks include poor site selection (especially signing up over-rented sites, which become loss-making). Multi-site businesses are also feeling the strain right now from business rates increases, and staff costs (Living Wage, pensions, apprenticeship levy, etc).
This is quite a rapid roll-out;
Expect to achieve the top end of the guidance range of 15 to 20 sites openings for 2017
That's a fairly rapid pace of expansion, given that the company currently has 97 sites. Mind you, having visited a site myself, they're not particularly complex fit-outs. It's just a big space with lots of exercise machines & other equipment in it.
This company says that it is the market leader, in a sector (low cost gyms) with 515 sites (up from 450 in 2016, so competitors are expanding too).
I really like the customer proposition with this company. It's a no-frills gym offering, so particularly no swimming pools. However, they are big, and well-equipped gyms, at an affordable price - average revenue per member is £14.28 per month (down slightly against 2016). The beauty with gyms is that lots of people sign up, but rarely actually use the facilities.
Looking at the figures, the first point which jumps out at me, is the big difference between adjusted EBITDA (up 19.1%), and adjusted earnings is up a much higher amount at +40.3%. The main reconciling item is probably the depreciation charge, so I'll see if I can work that out. Ah, the company has given a reconciliation, and this confirms that the depreciation charge has only risen a modest amount, year-on-year. Therefore that helps boost the percentage increase in adjusted profits.
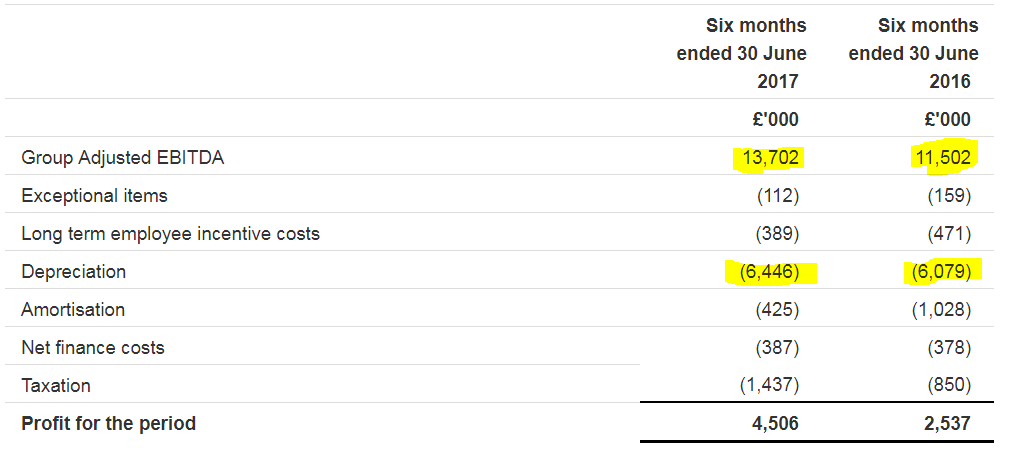
I'm not explaining this point very well! What I'm trying to say is that the EBITDA figure has risen by £2.2m, but the depreciation charge has only risen by £0.4m, so that gives a leveraged increased in % adjusted profits.
Note also that the site EBITDA margin is good, at 41.5% of revenues.
I've just found an explanation for why the depreciation charge has increased so little;
As a result of the annual assessment of the useful economic lives of property, plant and equipment, the useful economic lives of certain items of leasehold improvements and gym equipment have been increased. This has decreased the depreciation charge for the period by £0.8 million, compared to the depreciation charge under the previous useful economic lives.
Depreciation as a percentage of revenue decreased from 16.8% in the six months ended 30 June 2016 to 15.0% in the six months ended 30 June 2017.
That's a one-off benefit this year, in terms of the increased profit %. Therefore, I would treat the 41.7% increase in adjusted profit with caution. The underlying figure is actually lower than that, since the change in depreciation policy really should be adjusted out, in my view.
EDIT: A broker has estimated that profit would have been up 24%, if the depreciation change is disregarded. So this is quite a significant point to note.
Outlook comments are as expected;
During the second half of 2017 we will continue to implement our plan, opening new sites and bringing to maturity the gyms that have been opened during the last two years.
I am confident that the business is in as strong a position as ever to execute its strategy and deliver further profitable growth.
After a good first half we are on track to meet market expectations for profit for the full year and I am encouraged by the progress we are making.
Balance sheet - this is dominated by fixed assets (note that all property is leasehold), as you would expect. These have a net book value of £104.3m. There are also £48.8m in intangible assets (which I usually write off to nil).
The working capital position looks very weak, with a current ratio of only 0.35. However, in this particular case that doesn't concern me, because the business is so cash generative, and has plenty of headroom on its bank facilities. I think this is just the nature of the business.
The trade creditors figure of £36.7m is the stand-out number, in that it looks unusually large. No additional detail is given in today's interims. So I've checked the last Annual Report, to see what it contains, as follows;
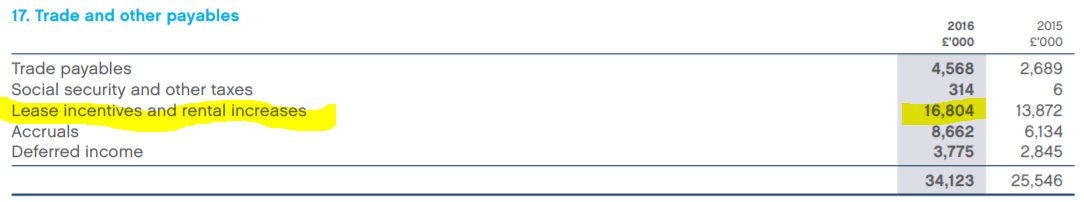
(NB. figures as at 31 Dec 2016)
I've highlighted the largest number within trade payables, which is £16.8m lease incentives & rental increases. Lease incentives are either cash receipts (reverse premiums) or rent-free periods, which a landlord offers to a new tenant, as an inducement for them to sign the lease. The tenant would end up paying a higher rent, if this type of deal is done, so that's how the landlord recoups the cost in the long run.
In the case of a reverse premium, the way it is accounted for, is like this;
DR Cash £x
CR Trade payables £x
Over a period of time, usually 5 years, the creditor is then gradually fed into the P&L as a negative cost - usually offset against rent payments. What this does is to spread the benefit of the landlord incentive over the number of years that it relates to, as opposed to it being booked as a one-off benefit in year 1.
Anyway, for our purposes, the key point is that whilst this is classified as a creditor on the balance sheet, it's not actually a creditor! i.e. the £16.8m highlighted above does not, under any circumstances, have to actually be paid to anyone. What this means, is that we can safely ignore it, in terms of assessing the company's financial strength.
Overall, NAV is £118.2m. Removing intangibles brings this down to £69.3m. That looks a perfectly adequate capital base, so I'm happy with the balance sheet.
Bank facilities - these look well-structured, and note that the company has only drawn down £10m of a total £40m bank facilities. So it is well-financed, and can comfortably afford to continue its rapid expansion using cashflows, and maybe a bit more bank funding if required. There are no issues here anyway, it all looks fine to me.
Cashflow - this is terrific. The business model generates loads of cash, which is then mostly used for capex - mainly new site openings. In H1 net operating cashflow was £14.5m (up from £13.9m in H1 last year) - remember these are just half year figures. The full year net cashflow in 2016 was £27.0m (before £0.9m exceptional costs). This is a fabulously cash generative business.
I'm not sure how much of the capex is for new sites, and how much is maintenance capex on existing sites. It would be good to find out the split. The narrative does mention a 5-year refit cycle.
Dividends - are negligible at the moment, but when the business matures, it will have the capacity to pay generous divis. So something to bear in mind for the future.
Valuation - I think we've established that this is an attractive business, which is trading well. As a self-funding roll-out, it's not going to be cheap. Here are the Stockopedia stats;
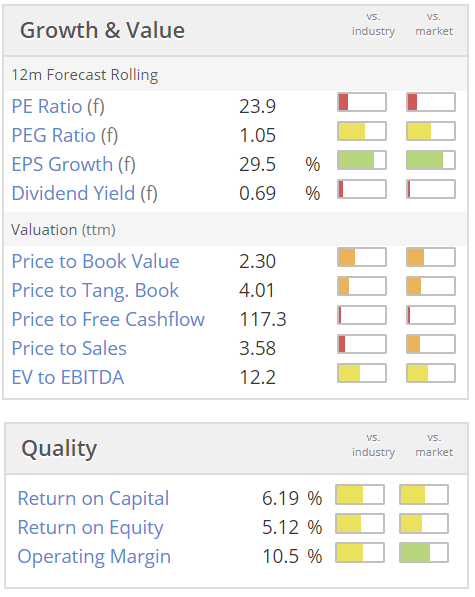
I think that valuation, a forward PER of 23.9, looks about right. It's justified by the strong earnings growth, and the roll-out working well, in my opinion.
My opinion - I like it. This seems a high quality company, which is performing well. It has a sound balance sheet, and is self-funding its own roll-out. Customers obviously like the format, and I've tried it out myself, and can confirm that the facilities are good, and excellent value for money.
I reckon that the revenues might be a lot more sticky than some people think. The worry is that, in times of recession, gym memberships are often cancelled, as one of the few discretionary items of spending that we can cut when times are hard. However, at just £14 a month, it wouldn't surprise me if GYM customers keep their membership going, even when they're feeling the pinch. It's such a small monthly outgoing, for considerable health benefits.
I must admit to being tempted to buy some shares in this company. I'm pretty certain that, on a buy and forget basis, this would probably be a good investment over say a 5-year period.
My main reservation is that it's difficult to see much short-term upside on a valuation which is already quite high. So on balance, I think it might be best to go on my watchlist, as the type of share I would buy at a lower price, if markets generally have a wobble.
EDIT: Many thanks to reader "bestace" who has kindly flagged up the investor presentation on GYM (LON:GYM) website.
HSS Hire (LON:HSS)
Share price: 47.35p (down 14.7% today)
No. shares: 170.2m
Market cap: £80.6m
Interim results - covering the 26 weeks ended 1 Jul 2017.
HSS is a tool & equipment hire business, in the UK & Ireland.
Graham reported on a poor Q1 update in his report here on 24 May 2017, so I've just read that to refresh my memory.
The company seems to be undergoing a restructuring, which the company describes as "substantial operating model changes".
The highlights section looks awful to me - an adjusted loss before tax of -£14.2m in H1. This compares with a £2.2m equivalent profit in H1 last year. That's really bad, especially as the company has a very strained balance sheet, with tons of debt.
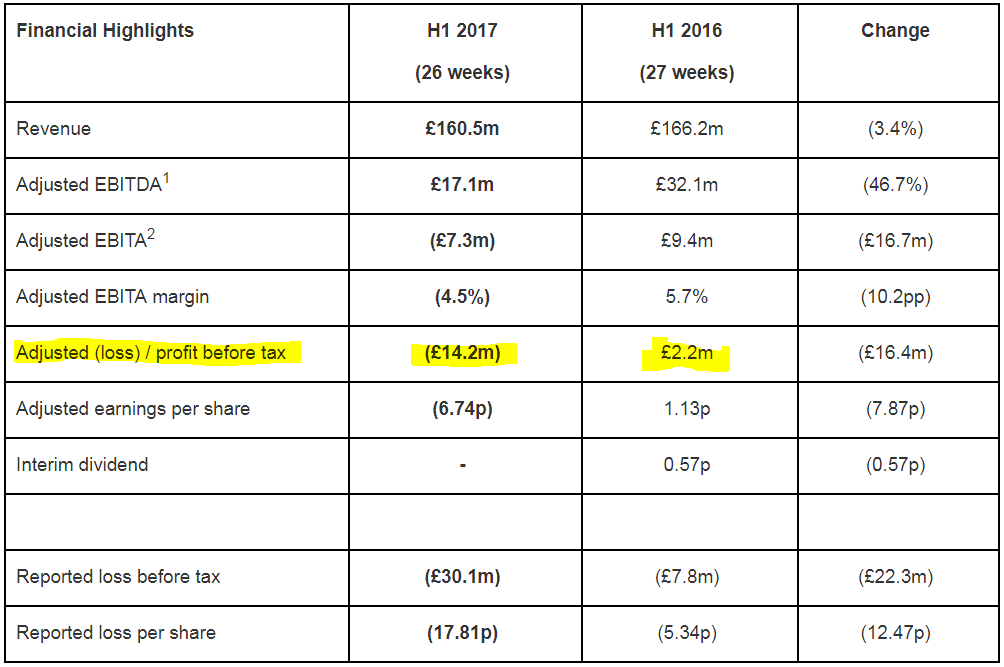
Debt interest is a highly material cost, therefore I would ignore the 3 items above my highlighting, as they're meaningless (due to them ignoring interest costs).
Note that the divi has been passed.
The company says that the trends improved in Q2 compared with Q1. So this share is really a punt on the company being able to turn itself around before it goes bust. Looking back to Q1, the adjusted EBITA loss was -£4.5m. In the table above, H1 on the same basis is -£7.3m. Therefore, by deduction this means Q2 was -£2.8m. That's still bad, although it is at least a smaller loss than in Q1.
Cost savings - of £13m have been targeted, compared to the Q1 run rate.
Outlook comments;
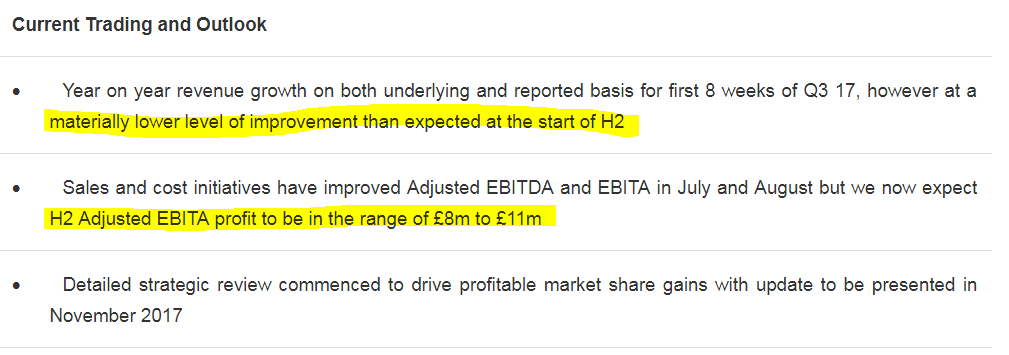
So it's a profit warning for Q3.
With a -£7.3m EBITA loss for H1, the £8-11m profit range for H2 means that the company seems likely to report a small adjusted EBITA profit for the whole year, of c. £1-4m. That's all very well, but bear in mind that the interest cost last year was £14.7m. So assuming something similar this year, a small EBITA profit would turn into a hefty loss before tax for the full year of £10-13m.
Net debt - this is the elephant in the room, at a gigantic £230.6m.
I would be worried about possible covenant breaches, given the very poor performance year to date. Nothing is said about this in today's announcement.
Unless performance drastically improves, I cannot see how the company would be able to renew its debt facilities. Its revolving credit facility expires in Feb 2019, and the Senior Secured Notes expire in 1 Aug 2019.
This looks a very similar situation to Johnston Press (LON:JPR) - where the company looks unlikely to be able to refinance its loan notes when they fall due. In the worst case scenario, that means the equity could end up being worth nothing.
The hire fleet has a book value of £125.6m (see note 9 in today's announcement). So to have net debt which is £105m greater than the book value of the hire fleet, looks an extremely imprudent state of affairs.
The bank and the loan note holders must be praying that the company's performance improves in time for them to get their money back in 2019. If not, then a hefty, dilutive equity fundraising could be the only option to refinance the company next year, in advance of debt facilities expiring.
My opinion - I've repeatedly warned about this company's awful balance sheet, right from the moment it floated in Feb 2015. Net tangible assets were negative, at -£54.1m at 1 Jul 2017.
The balance sheet would need to be strengthened by at least £100m in fresh equity before I would consider this share investable.
Tool hire businesses can be good investments when the cycle is turning up. They then see leveraged increases in profits. However, in the good times, capacity tends to increase until there is a glut. Then weaker players end up going bust in recessions, when over-supply meets sharply reduced demand. So a classic cyclical business model. The UK economy is showing some worrying signs of a slowdown possibly on the horizon, so I'm not currently amenable to the idea of buying into very cyclical shares like this.
Given poor trading, and a train wreck balance sheet, I have no idea why anyone would want to hold this share. Risk:reward looks pretty bad. I suppose an optimist might imagine that the company's turnaround plan could make it much more profitable. That has actually happened at competitor Speedy Hire (LON:SDY) so it's a possibility.
The trouble is that cashflow generated would really just be servicing the debt interest. It doesn't look in a position to pay divis for the time being.
Trouble is, the downside risk is very considerable here. Laden with so much debt, I wouldn't be at all surprised if HSS goes bust in the next recession. Therefore, for me it remains uninvestable due to its financial weakness. If risk:reward is poor, then it's best just to steer clear, in my view.
OptiBiotix Health (LON:OPTI)
Share price: 68.5p (down 2.8% today)
No. shares: 78.5m
Market cap: £53.8m
Half yearly report - for the 6 months ended 31 May 2017.
This company describes itself as;
OptiBiotix Health plc (AIM: OPTI), a life sciences business developing compounds to tackle obesity, high cholesterol and diabetes
I note that it has produced negligible turnover to date, and is loss-making. So that's normally the type of thing that I would ignore - as they nearly always go wrong as investments/punts, in the long run. There can be huge speculative moves up during bull markets though, for this type of story stock.
Anyway, I just thought it might be useful to do a quick review of today's numbers, so that we have something in the archive to refer back to in future.
Reading through the results statement, there's not really any point in me analysing the numbers, because again revenues were negligible at £75k. The company's valuation clearly hinges entirely on future expectations of revenues & profit from new products that are in the pipeline.
There was an operating loss of £981k in H1.
An exceptional profit of £4.1m was booked from OPTI spinning off one of its subsidiaries, with a separate AIM listing, SkinBioTherapeutics (LON:SBTX) . That is shown as an investment on OPTI's balance sheet.
Cash - cash is king at jam tomorrow stocks. In this case, it reports £1.9m in cash, and there are negligible creditors. That looks enough to last about a year, assuming no meaningful revenues appear. So possibly looking a little tight? The company reckons it has enough cash though, but blue sky companies always say that, then do more Placings!
Contracts/agreements - the company has an impressive-sounding list of deals underway, with named partners. So this gives some confidence that it's not just all hot air.
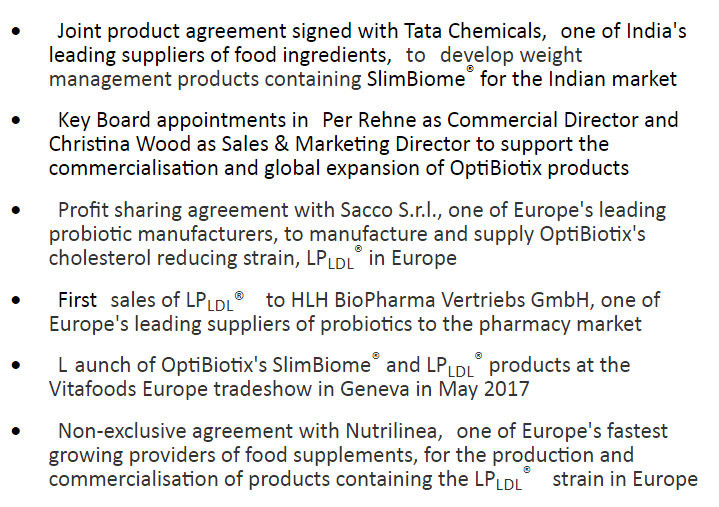
Although personally I'd want to see some of these agreements actually generating some real cash inflows before considering investing here.
My opinion - I don't touch companies like this, as practically all of them go wrong, after all the hype dies down. Maybe there's something good here, it's impossible for me to tell at this stage.
Although I do like the newsflow, which sounds credible. Also management seemed credible in a video I watched online.
Overall, it's too speculative for me at this stage, but I'll monitor future results to see if there's any commercial substance to the company. The danger is that people chase up the share price on promising-sounding newsflow, but then hard cashflows fail to materialise. That's the outcome with most jam tomorrow companies on AIM - things tend to take far longer, and cost far more, than originally anticipated.
I've got an open mind though, so will keep an eye on this company for signs of genuine commercial progress.
That's it from me today! See you tomorrow.
Regards, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

24 comments
Some very good contributions here on GYM, shows the quality of the Stockopedia membership. I write notes on companies that interest me as it is useful for monitoring performance and improving my returns. Given that growth shares have done very well over the last few years I thought it might be worth sharing some thoughts on valuing them using GYM as an example. Sorry if it's a bit long.
How to think about valuing growth –using GYM as an example
Investors are often faced with the type of situation where a company’s current profitability and returns are depressed by an aggressive re-investment of cash flows into growth. How should one go about assessing the potential and risks? My preferred method is to break down the opportunity into 2 parts, firstly, looking at the company as if it had no growth opportunities, and only then looking at the growth part.
Zero-Growth analysis
GYM very handily splits out maintenance capex, so we can estimate the underlying profitability. At the recent half year, free cash flow was £12.8m, (before growth spending, but including tax, financing and exceptionals, which are real employee expenses) and while we know that more sites will be opened in H2, for our purposes we can double the H1 number to get £25.6m full year. Taking average Net Assets from June 16 and June 17 of £112.8m, this gives a return of 22.7%. The underlying zero growth P.E is £264m/25.6m= 10.3x. It is clear that the underlying return on equity is high, and the no growth P.E. is low as it should be (zero growth should be priced at the inverse of the cost of capital). Let’s take a closer look at returns.
Management has indicated that new sites cost between £1.3 and £1.4m. A glance at the balance sheet shows PPE before depreciation is £155m and the number of sites at H1 is 95, giving a cost of c£1.63m per site. Maybe the trend is declining as scale and expertise reduce costs. Let’s take management’s word at £1.35m and we know the average revenue per site is £42.8m*2 / average sites (92) = £930.4k. So, the asset to revenue ratio is £1.35m/£.934= 1.44x. The implied return on investment is Return on sales divided by 1.44= £25.6m profit/£42.8*2= 29.9%/ 1.44= 20.77%.
How much should we pay for this mix of growth and return? Below I will describe a common sense approach. But, first, there is a useful model, which will help, called the Franchise Factor model, developed by Marty Liebowitz and Stanley Kogelman and I used this as a check on the numbers below. It essentially splits the P.E. ratio into a growth factor (the NPV of all future growth) and return on equity above COE. The resulting P.E. for GYM is 15.3x (7.2% growth for 10 years and 23% ROE)
The current rolling P.E. of 24x implies a growth rate of 15% for 10 years. (385 sites)
Growth analysis
We know the cost and returns expected by management, but we don’t know the size of the opportunity. We do know that low priced flexible gyms are taking market share form a stagnant total market and that share is c10%. It seems reasonable that this might reach say, 20%. It can be seen almost like a land- grab, with those best positioned to build out their estate quickest will reap the rewards. We also know that GYM is self- financing, and this is a big advantage. So, it might be reasonable to target a doubling of the estate from 95 to 190, over say, 10 years. That is slower than the current expansion rate, but seems more prudent. We can also factor in a small say, 2% inflation rate in price levels, from £14.28 to (1.02^10)= 1.21*£14.28 = £17.4 in year 10.
In this scenario, Sales in year 10 reach c£211m, and if the growth opportunity is non -existent by then, reinvestment needs will be low and the free cash flow return on revenues will be similar to the 29.9% we calculated earlier, or c£63m in profit. Put that on a low growth 12x P.E. and we get £756m market cap. If there is residual growth available, that multiple will rise a couple of points, so we might want to pin a £756m-£890m target range in year 10. The high end will give investors a 13% annualized return over 10 years or 3.3x return on capital invested.
Conclusions
I have deliberately kept the finer details of valuation models out of the discussion, because they can give the impression of precision, and this is a very imprecise exercise. Investing is all about laying out cash today, in order to reap a future return, which MORE THAN compensates for the risks. The worst case scenario for equity is always zero, but with some work and informed knowledge it is possible to find situations which offer a low probability of a permanent loss of capital and a high probability of a better than average return. Where does GYM fit within this wide spectrum? That is for each individual investor to judge. I have shown that the implied growth is 15% p.a., but I arbitrarily chose a 10 year time frame, whereas maybe 385 sites is achievable over say 15 years (a 10% growth rate). The durability of returns is just as important as the growth, because a falling ROE will impact valuation and investor returns. We have to remember that this type of product is completely discretionary and demand could disappear quickly; also while debt-free, the lease obligations are a form of long- term debt. All in all, GYM is an interesting situation. The current P.E. looks optically high, but as I have shown, even if the site expansion is only 7.2% for 10 years (half the implied growth), the potential investor returns are quite respectable
.
For those interested, here is the link to a prior GYM (LON:GYM) presentation, which contains a lot of useful information:
http://www.tggplc.com/media/83680/capital-markets-day-presentation-130617.pdf
For what it's worth, here are some of my own notes for GYM (LON:GYM), in which I hold a long position:
I may even be understating long-term profit as there is a note in the presentation I've included above that states the £0.5 EBITDA per mature site already includes maintenance costs.
EDIT:
Plus everything Bestace just said
I've looked at a lot of the gym businesses over the years and whilst the mid market has been smashed (la fitness, fitness first, esporta), it is clear there's been move towards budget and premium (such as Virgin) / racket clubs (David Lloyd). The budget gym model has grown explosively and performed well over the past 5 years but I do have question marks over the long-term profitability of the sector.,.
Some questions you may want to consider before investing:
- do they mention LFL growth of the core estate? Rollout potentially masks falling member numbers / profitability of the core business. Attention is diverted to the growth in turnover which is itself a byproduct of rolling out new sites and ramp up of those sites still maturing.
- budget chains grew fast during the last recession when rents were cheap. Many leases were signed on good deals which will be subject to upward rent reviews after 5 years.
- As rent and other cost pressures (rates, wage inflation) come through to impact the business, the only lever you have to pull (assuming membership numbers are fairly stable) to maintain margin is an increase in membership fees. Ok, the fees are cheap but over 40% of those using the budget gym sector are NEW to gym-ing (I.e. Were not regular gym goers beforehand). They are going as it is Cheap! Once prices start rising and if wage inflation does not keep pace, are you so sure these members will keep going ?! It will be interesting to see how these businesses survive a recession.
- finally, there is the high member churn in the sector. Marketing budgets are increasing to keep the established sites membership numbers stable (again, impacts margin). Also, when a competitor opens in close proximity with newer equipment, you can expect to lose a third of your membership base. Due to the operational leverage within these businesses, this can have a large impact on profitability.
In summary, this model was very attractive coming out of the last recession with budget chains rolling out sites with no competition and plenty of white space to grow into. As the sector matures, I can see it suffering from the problems as the mid-market did where investors lost their shirts. It could have a fair way to run yet though..just not one to hold 'forever' imho.
Great post nicobos
I agree with all that you've said, I'd add that as 'first mover advantage' (insomuch that they've already grabbed a big slice) in the budget sector, this should provide somewhat of a moat.
As Paul says, yes, it can be replicated for less, but how many people swap gyms to attend an unknown quantity for the sake of a couple of quid?
I'd like to see how many lapsed/terminated memberships were renewed and the length of those lapses (i.e. had they tried the competition and reverted back).
As an aside I was in David Lloyd last week as a guest. I was amazed at how busy it was, given it was the middle of the day on a weekday. But the prices. If you were really into fitness and had to tighten your belt, I know my host would ditch the David Lloyd membership for a GYM membership as DL is more of a 'social club'.
A lot of the budget gyms cluster in an area (near a key transport hub for example) so the location differential is not so apparent. The problem with new openings is that they work a bit like the airlines where the first 1,000 members or so can sign up for a year for half price, as they mature and reach capacity the prices do then begin to rise.
In this initial promotional period, the savings over 12 months can be substantial so that the existing gyms in the area do lose members. Combine this with shiny new equipment and it not being busy (I.e. No waiting for machines) when you need to use it, and the appeal can be quite attractive !
Then you have the 40% of newbies and churn to contend with. When there was only one gym in an area, you could pick up these members easily but say there are now 3, you have to work a lot harder to keep your membership base stable !
David Lloyd is a great business and competes mainly against independent 'racket' clubs. Whilst there was a dip in the recession, it did not fall as far as you may think as people are reluctant to give up their 'social club'. Quite often it's a place for families to spend time at weekends (kids having tennis lessons whilst parents use the gym etc); a safe and friendly environment.
It doesn't compete for the same demographic as low cost gyms and DL's members would rather give up one of their expensive family holidays per year than their annual membership.
Good points, well made. I should note I have a small position in the kids isas for a longer term view.
Given the rates the ability to open new sites pretty quickly, one would hope that if they cannot retain members in the manner you describe that they can ease up on opening sites and divert cash flow together with looking at closing any sites that aren't performing as well.
I'd finally note that the DL I went to in Beckenham seemed a bit tired but that's an aside.
nicobos,
Brilliant points, very well made! (re GYM (LON:GYM) ), post no.15 above.
I think you may have hit the nail on the head there.
So I won't be investing in GYM now.
Regards, Paul.
Plenty of food for thought there nicobos. I have no position here (yet), but here are some counterpoints as I see it:
Bottom line is that I think there is a long enough runway for growth opportunities (and by extension share price appreciation) before the downside effects of maturation and competition kick in.
One final point I thought worth mentioning from today's interims is the S-curve profile of how new sites mature:
So EBITDA tops out at around £0.5m per site after 2 years. Compare that to today's actual average site EBITDA of £187k, the difference being due to the estate being so young that many sites are still early on the S-curve. That implies if they stopped opening new sites today and sat on their hands for a couple of years, their overall EBITDA would increase to around £50m, which compares to today's enterprise value of £267m.
I might be talking myself into opening a position here!
In case anyone holding OPG, they are down around 25% due to a warning on 2018 results due to an unexpected increase in coal prices. I don't believe that this is the first time that coal prices have "unexpectedly risen"; have dumped mine :-/
Well, I'm actually looking for both investment ideas, and a new gym...so very timely article on both fronts.
Looks like a sensible little investment. On to the watchlist it goes.
(Monthly fee is £22.99 in my neck of the woods - do they have regional pricing?)
What region are you in - China ?
Re. GYM (LON:GYM) What impressed me about their presentation is the fact that low cost gyms only account for around 10% of the overall UK health & fitness market. (£0.5bn out of £4.7bn in 2017).
So there is plenty of headroom to capture market share as long as their operating model remains solid and execution of current estate and expanding roll-out remains tightly controlled.
The weakening in the depreciation rates at GYM is a massive red flag for me.
Gym equipment tends to get intensive use and needs to be regularly replaced to keep the membership happy and attract new members. There is a huge fixed asset base and assumptions on depreciation rates are critical to the level of profits reported. Depreciate too slowly and profits and EBITA are overstated, although it can take a few years for this to become apparent.
I view the reduction in the depreciation rates this period with great suspicion.
As an aside, I would add that the focus on EBITDA in the investor presentation bestace linked to above is entirely inappropriate, given the criticality of depreciation to this business.
The FD added some additional colour in the webcast on the change in depreciation rate.
He said that as a very young business, they were still evaluating how much life they can get out of certain assets and he cited their portals (entry systems) which they had been depreciating over 10 years, but they have now reached that point at some of their sites and found that the systems are still fit for purpose. They are therefore now depreciating those items over the life of the lease.
It's possible the changes are therefore unrelated to gym equipment, where if they are sticking to 5-year replacement cycles I don't think they could reasonably justify increasing the useful lifespan beyond that point and nor would I expect their auditors to allow that.
I had a look at a few of their competitors' accounts on Companies House and they are all indicating similar asset lives for gym equipment (typically around 6 years).
There was also an analyst question on the webcast about pricing for gym equipment and the response was that given they were rapidly increasing in size, there were economies of scale that should allow the replacement cost of gym equipment to be lower than the cost of assets that are being replaced.
Particularly well explained analysis of the Gym figures today Paul. Much appreciated.
GYM (LON:GYM) - it's worth also looking at the accompanying presentation on their website.
Among other things, this confirms:
Interesting slide, not sure how they've missed one of their biggest competitors off the list;
https://www.lifestylefitness.co.uk/find-a-club?gclid=COHesa-N_9UCFYW37QodmQUABw
50 gyms c£18 pcm, only different in 12 monthly contract which is no biggie imho
"Interesting slide, not sure how they've missed one of their biggest competitors off the list;"
If you look at the slide you can see that they are referencing a report by Leisure Database Company. So, it's not The Gym's data as such. I expect that Leisure Database Company either had problems obtaining the data, perhaps Lifestyle Fitness were not willing to co-operate, or it was human error to leave it off the slide.
As I mentioned, there are plenty of competitors, so it is really a case of who can execute the low-cost model most effectively. Right now, the numbers that GYM (LON:GYM) are achieving show that they are one of the best. (They've had the Paul Scott fine tooth comb treatment and were found to be sound).
As regards being locked into a 12 month contract, there are often complaints about the Ts&Cs with contract gyms in the papers and on-line. Just try googling gym membership renewal complaint. So, while being locked in a 12 monthly contract is no issue for some people there are many who have difficulty with it.
A couple of extra points on GYM (LON:GYM) . They have a very good facility whereby members can suspend their membership online, if e.g. you're ill, or away from home for a long period, and won't be able to use your usual Gym. You just pay £5 p.m. to keep your membership dormant. When I was a member, I did that, and it gives GYM a nice opportunity to tempt you back in. Plus of course I was still paying them £5 p.m. for nothing.
As regards competition, my view is that for just £14 p.m., it's going to be convenience and closeness to home that are likely to be the main factors. So if a competitor opened nearby and charged £12 p.m., would customers really give up their GYM membership to join the competitor? I doubt it personally. The price differentials are just too small at this budget level, so people are more likely to stick with the gym they are used to, and happy with.
So I remain of the view that GYM should continue to do quite well. The fears some here have expressed about depreciation policy seem overdone, in my view.
I got the feeling that GYM seem quite sensible with their accounting. Note that they didn't highlight the higher, pre-opening costs profit figure. That's just included in a table, but is not highlighted. Compare that with some other expanding retailers, who make a huge song & dance about higher profit which has adjusted out pre-opening costs.
The competition which would worry me, is free, or nearly free competition from local authority sports sites. Remember that this type of thing hurt Goals Soccer Centres (LON:GOAL) some time ago.
Regards, Paul.
Hi bestace,
Excellent contribution (as always!), thanks very much.
I'll put a link to the GYM (LON:GYM) results presentation in the main article.
Regards, Paul.
I like GYM (LON:GYM) as a potential investment but what stops me investing is they have no discernible moat, as an example I belong to 2 gyms , one David Lloyd has a pool , tennis, squash, that makes it the only one in the area with those benefits and they charge 5 times as much as GYM (LON:GYM) and are v busy. The other gym is nearer and better equipped as a gym, it competes on cost & proposition directly withGYM (LON:GYM), the only discernible difference is that's 10m nearer me than the GYM (LON:GYM) equivalent, they spend an inordinate amount of time & money trying to attract new members but they have 3 within 1 mile..all doing similar things. That looks like a margin killing situation to me so it suggests LT as open points are (over)filled the model will lose momentum fast. Imho
Thank Paul for the detailed analysis of GYM (LON:GYM). (I have a small long position).
It sounds to me like the numbers are well presented with pretty much all the detail necessary to evaluate how the company is doing. It is good to see them still growing successfully (profitably) despite the increases in business rates, minimum wage and so on. Seems like a very well run business. When you consider that a full service gym often charges north of £70 per month for membership, the offer of a well equipped gym for £15 per month (and not paying for the pool and sauna that you rarely use and the salesperson who persuaded you to sign up) seems like an attractive proposition for those on a budget. The use of IT to also take out cost seems well done. So to me the business model seems good.
There's plenty of competition out there (as there is for all retail) so it is execution excellence that counts for a lot I believe GYM seem to be executing very well. The Feefo rating published on their website gives 4.3 out of 5 on 8327 reviews and their Facebook page 4.2 on 2.3k reviews. That's pretty good for a budget operation.
One potential weakness and strength depending on how you look at it is that as far as I am aware they don't tie people into long contracts. That's attractive to those who are unsure about joining and also means that they know they have got to have satisfied customers to avoid them leaving. The downside is that it is easy for members to walk away when they need to economise or fancy a change. However, the proof of the concept is in the numbers.