Small Cap Value Report (Wed 30 Dec 2020) - M&A

Good morning! It's Paul here with the SCVR for Wednesday.
I had a lie in today, so the first section won't be up until about 11am.
There isn't any company news of interest today, so I've just had a think about M&A instead.
Today's report is now finished.
Mergers & Acquisitions
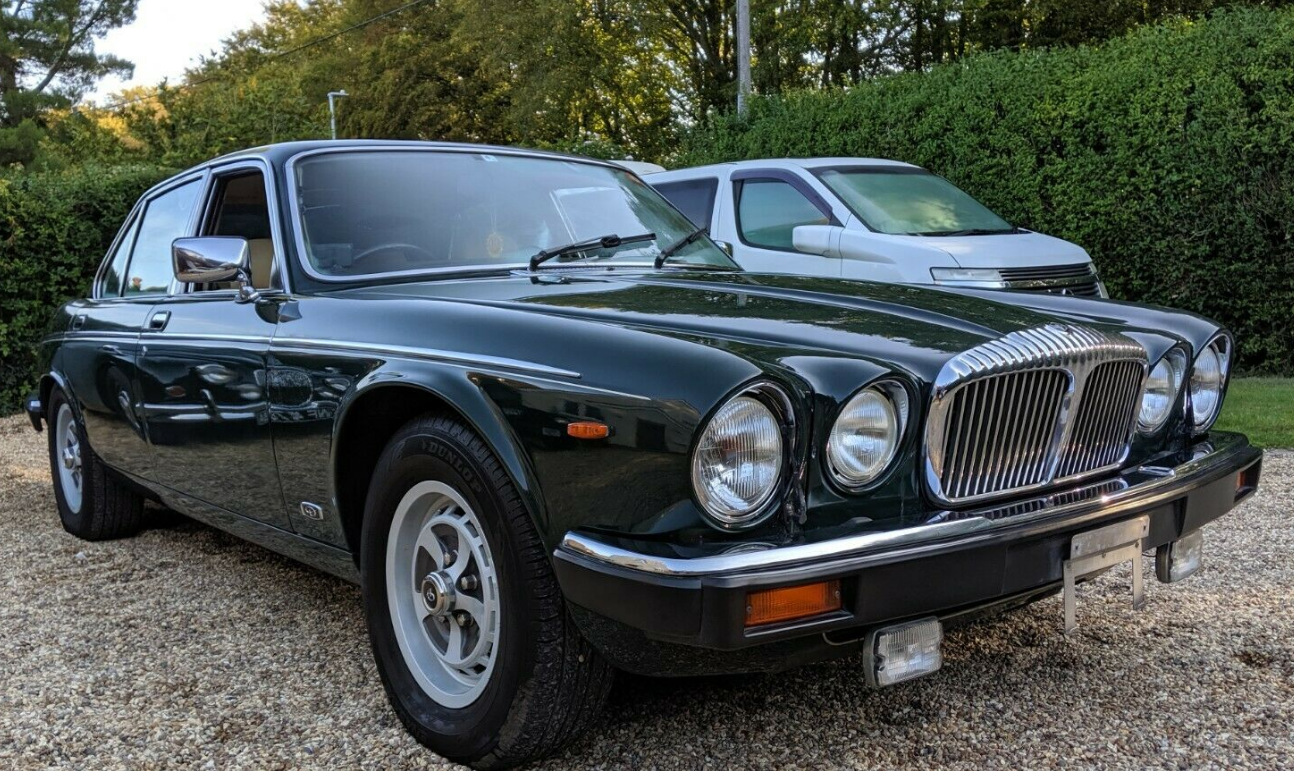
I was a bit bored over Xmas, so started clicking on cars for sale, always enjoyable but dangerous. Anyway, I've agreed to buy a classic Daimler Double-Six (1990) - in my view the most beautiful saloon car ever made. It will be lovely to just enjoy owning it, to me it's art. I justify the V12 engine on the basis that I'll probably drive it less than 500 miles p.a. therefore the environmental damage is minimal, and offset by my using entirely renewable electricity in my flat.
Here she is - a Japanese import, so in mint condition, only 35k miles from new. The service history is all there, but in Japanese script, so I had to take it largely on trust!
.
.
Anyway, the chap selling it works in the city, for a large overseas bank, doing leveraged buyouts with private equity firms. We were chatting about it, and he told me something interesting. Namely that banks & private equity generally think that they were too cautious in 2008-9, and missed a lot of stunning opportunities to pick up great assets on the cheap. They're determined not to make the same mistake this time, and the deal pipeline is incredibly busy he said.
Particularly with the main Brexit uncertainty now removed (although plenty of loose ends still to be tied up), he reckons there is likely to be a large wave of takeover bids in 2021. A fund manager said something similar in a recent newspaper article, but I can't remember which one.
People sometimes ask me how to identify takeover targets. A good place to start is obviously undervalued shares like Redde Northgate (LON:REDD) (I hold). Even though it's gone up a lot in the last 2 months, it's still irrationally cheap in my view - fwd PER of 8.5 (we can rely on forecasts because it's recently confirmed trading in line), and a divi yield of 6.0%. Combined with a strong balance sheet - what's not to like about that? It's historically been a very cash generative business, paying large divis, which is attractive to private equity. There are existing plans to reduce gearing, by leasing vehicles from manufacturers, instead of buying them. That would free up room on the balance sheet for a private equity acquirer to load it up with debt, which could be gradually paid down from cashflows.
Cloudcall (LON:CALL) (I hold) is another one that might attract interest from a US buyer. It's already got several US investors on the major shareholder list, and does about 40% of its business there. As a reader pointed out yesterday, tech valuations in America are incredibly high, so it makes sense for them to buy in growth from cheaper UK companies.
Boohoo (LON:BOO) (I hold) is growing its sales in America very rapidly, so it would make obvious sense for it to list on NASDAQ or the main market in New York, where it would probably get a much higher rating than here.
Intercede (LON:IGP) (I hold) is a tiddler, but does nearly all its business in the USA, with huge clients, like branches of US Govt, and major aerospace companies. A house broker note did suggest earlier this year that private equity might come sniffing around, who knows?
Victoria (LON:VCP) is another one where the Chairman has made it clear that the business would be sold once it reaches sufficient scale. A huge US private conglomerate recently made a strategic investment in Victoria, and that can often be a precursor to a full takeover bid later on.
French Connection (LON:FCCN) (I hold) is on the pending list. Hopefully at some point we'll be taken out, since the founder probably wants to retire & get the best price he can for it.
Best Of The Best (LON:BOTB) (I hold) - the takeover talks are still ongoing, but as Leon Boros said in a recent interview, when talks drag on this long, it usually falls through. I'm hoping the bid talks do fail, as I want to buy more BOTB shares, and there could be a spike down on a bid falling through.
I can't think of any others off the top of my head, but basically everything is potentially up for sale, if it doesn't have a controlling shareholder to block it.
I normally get 2 or 3 takeover bids in my portfolio each year. Sometimes they can be very lucrative, if the premium is high, and the position size is large. Mccarthy & Stone (LON:MCS) was a cracker - the price was irrationally cheap (way below NTAV, for no reason), and I had a fairly chunky position in it. Unfortunately, I got a margin call and sold a third of them a couple of days before the takeover bid was announced, so I threw away tens of thousands of pounds. However, I'm very much a glass two thirds full type of person, so I was just grateful for the profit on my remaining holding, and tried to block out the lost opportunity from my thoughts. We just have to accept that we'll get some investments right, and others wrong. Learn from each experience, then move on, is my approach.
Any ideas on possible takeover candidates from readers? It would be good to bounce more ideas around. Any sectors that are worth focusing on in particular?
.
No company news today, other than a rambling update from £pos which reads like a sales brochure, telling us why its wellhead gripping system is the best thing since sliced bread walked through the door. It concludes;
While the ongoing COVID-19 pandemic may continue to impact energy consumption levels and timings into 2021, we are confident that the best days for Plexus' proprietary technology lie ahead. Our confidence is based on the combination of the momentum behind the energy transition, the higher level of scrutiny operators are under to avoid and tackle emissions, and the growing pressure to manage costs in the current volatile oil and gas price environment where margins are under pressure. POS-GRIP delivers on all counts. With a capital-light licensing model, a debt-free balance sheet and a proven track record, Plexus is well placed to succeed for the benefit of all stakeholders in the energy transition."
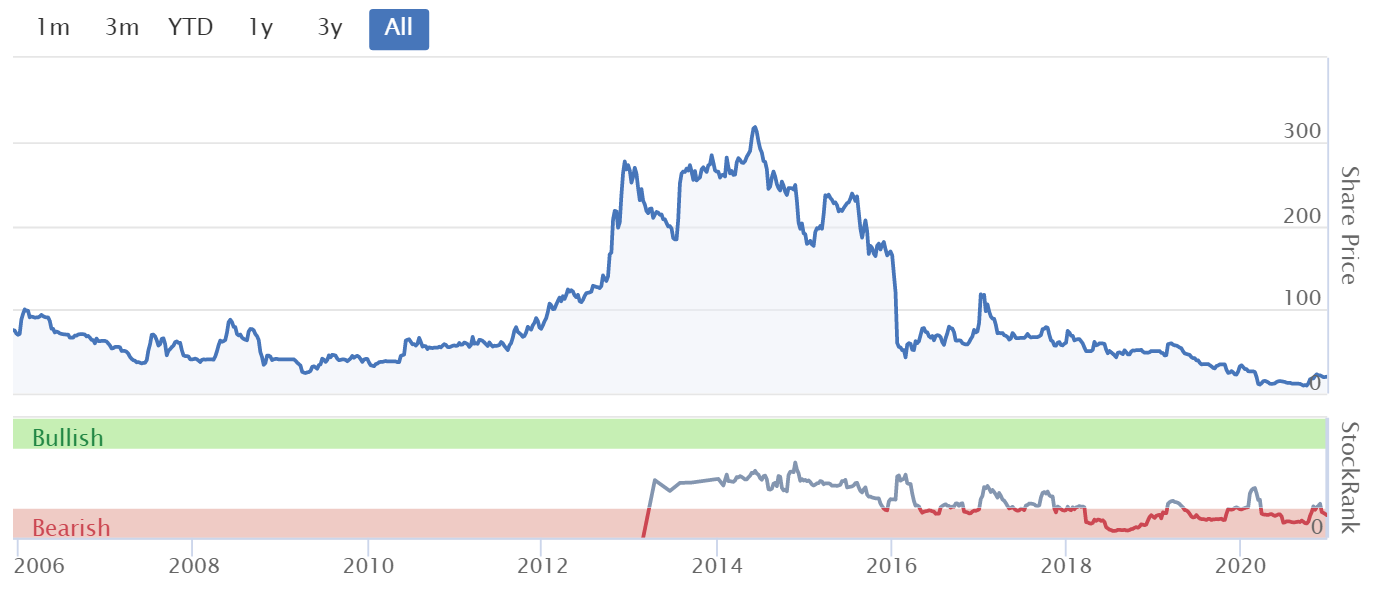
Plexus has been listed for 15 years now, and performance has been poor, as you can see;
.
It would take a lot to convince me that future performance is suddenly going to be good, given this track record.
All done for today, sorry there wasn't anything more interesting to cover.
Obviously it's wonderful news that, as expected, the Oxford/Astrazeneca vaccine has now been approved & will be rapidly rolled out.
Regards, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

147 comments
Excellent article!
However I'm surprised no one appears to be talking about Studio Retail Group (STU) seeing as it is trading a strangely low valuation for an online retailer with 199% growth (as confirmed in their HY Results) and has effectively been put up for sale !
Would highly recommend looking into this.
Agree that REDD is too cheap not to be considered as a target. Similarly I believe the same must be true of NAR also seeing as it's trading well below its NAV.
Agree with others re SLP and JLP being too cheap. Especially the latter given how it is now focusing on copper as well, and will start producing copper using Rio Tinto's old copper refinery in Q1 2021.
Would also say that Bushveld Minerals (BMN) is far too cheap. It's a vertically integrated vanadium play, evidently trying to emulate what Ganfeng has done with lithium, except it trades well below its sum-of-all-parts valuation. It's primarily one of the largest vanadium producers in the world, and also has stakes in 2 VRFB manufacturers (AIM: IES and Enerox), it's building an electrolyte production factory, has set up an electrolyte rental company recently (which has a deal with EDF's Pivot Power), and owns other assets including a huge iron mining resource.
HUM might also be a target, because that also appears to be too cheap.
Also, sticking my neck out here, I believe TEK might be taken over as well.
Lastly, on the subject of takeovers, I believe the attempted KAZ takeover will fail, and a higher bid (800p+) will be needed if the Chairman wants to take it private.
All in my honest opinion. Would be curious to hear others thoughts.
Fantastic Daimler. I have a 2003 Jaguar XJ8 4.2 SE that I bought in 2013 with 22,000 miles on it, one owner who sold it to me aged 82. The first of the 'Ford' cars, all aluminum body with a V8. It's still perfect today and in a light metallic blue there is nothing like it in the school car park at pick up time - plenty of black Range Rovers all looking the same , however. The children will not allow me to sell it.
This year four companies have been acquired. A record for me, but I hate l9sing talent and techbology abroad.
Back in 2002 The Daily Mail said , PERs below 10 were for cos in decline. A PER for 10 % earnlngs growth as about 18. Now so many growing cos are below 10, or attractive ones at 15. A target rich environment. plus whatever Pricate Equity is sitting on....
I am speechless.
Gorgeous car, always loved that shape.
M&A
My reading suggests positive tailwinds for PMG metals (essentially Platinum and Palladium).
There are three processors of tailings from chrome on the LSE I'm aware of - Sylvania Platinum (LON:SLP) , Jubilee Metals (LON:JLP) and Tharisa (LON:THS) . Removes the mining risk.
Currently these are massive cash cows and will probably attract PE interest due to their cashflows - unfortunately they are all in S Africa - but fwd PER's of 4 would seem to be far too low and leave them vunerable.
I'm in Sylvania Platinum (LON:SLP) and would rather it was not taken over but I've personal experience of what has happened to Kaz Minerals (LON:KAZ) - nothing which historically been at low PER's (mainly due to location - often at a harsh discount) is safe.
Phil
Edit: HAPPY NEW YEAR ALL....... BUT STAY SAFE
Great news on the car - what a beaut! Even with that V12 you're doing a big service to the environment by buying a 30 year old car and keeping it alive - much more environmentally friendly than buying a new one!
Even with that V12 you're doing a big service to the environment by buying a 30 year old car and keeping it alive - much more environmentally friendly than buying a new one!
Genius! I shall use that line with my niece & nephew!
I'd like an English Electric Class 37 please.
SPACtastic!
https://news.sky.com/story/sof...
Just saw that Quiz (LON:QUIZ) held its AGM today?
Talk about not being investor friendly! Anyone attend? It didn't seem to be virtual hosted either.
Quiz (LON:QUIZ) - My top candidate for an insider-led takeover. The owner made a fortune at IPO of this and still dominates (with family/LT associates). The 1 month delay in results announcement to the max 31st Jan (H1 ended in Sept !!) another indication of shareholder disregard
I expect will go private in due course - but I am hoping at >14p vs current 7p to move it through swiftly and without fuss in the next few months. The brand should bounce back when parties restart in the summer. It has shed all onerous leases and been forced from Dept store concessions so remaining largely online brand should do OK but no need to be listed..
Great article - how about LON:SOM as a potential buy out?
I agree. SOM is highly cash generative, so could attract a bid maybe?
On M&A there's a whole ton already underway - 25 at last glance:
https://www.thetakeoverpanel.o...
The government is also planning to increase its powers to block takeovers in industries it deems of national importance on national security grounds, so there's likely to be some pressure to get deals done before that comes into force:
https://www.cityam.com/ministe...
In terms of takeovers my number one choice is Itv (LON:ITV) but as my record of picking M&A targets is abysmal I would probably recommend looking elsewhere. But I think its back catalogue plus ITV Studios make it an attractive proposition at the current price even with the pain of advertising revenue falls.
I also think M&g (LON:MNG) is a sitting duck, despite the price having doubled since lockdown and all of the gaming companies must be potential targets - the bid war for Codemasters Group (LON:CDM) may only be just starting if the current price is anything to go by. Burberry (LON:BRBY) also looks like a bargain at current levels compared to its peers in the luxury goods industry.
But if you reckon UK equities are cheap by global standards and think sterling is likely to recover through 2021 then right now there isn't very much that isn't in play. There's an enormous amount of capital flapping around looking for a home.
timarr
Hi Timarr
I presume that’s Burberry that you are referring to rather than Burford Capital ;-)
Martin
I presume that’s Burberry that you are referring to rather than Burford Capital ;-)
Hi Martin
D'oh! :-)
timarr
Hi Timarr
I am with you on £ITV. I have been banging the drum about the intrinsic value in the back catalogue and ITV Studios for as long as I can remember. The free to air advertising revenues although declining are still valuable and you also have the nascent digital part of the business, both in the price for free at the current price, from my viewpoint.
I added close to the bottom during the market melt down so am nearly back to breakeven. However as an initial investment it has been 'educational'. I failed to recognise the impact of streaming and digital advertising on the business. It has therefore been carried by the rest of the portfolio, but my view of the intrinsic value has kept me invested. A salutary lesson, but as has been said failure is life's greatest teacher.
Will it be acquired, I don't know, but wouldn't be surprised. No doubt the bid or merger will be announced once I have sold out!
All the best
Hi jonno
I am with you on Itv (LON:ITV)
One of the drawbacks around ITV for potential purchasers has been its regulated public service broadcasting requirement which would need to be maintained in the face of falling interest in younger demographics. However, some of the changes outlined by Ofcom - forcing streaming services to give PSBs prominance and potentially widening the PSB obligation for other streaming services might actually make ITV even more attractive to a purchaser.
Overall the PSB obligations aren't that onerous, although they are currently required to be free-to-air (that may change in future):
Anyway, I'd expect something to change in this area. The BBC has been a target for sections of the Tory party for years, and weakening PSB obligations would be key to any changes to its charter. Against that will need to be weighed the potential issue of losing control over broadcasters - it'll be far harder to influence Netflix than ITV, for instance.
It's also worth noting that the Brexit deal excludes audiovisual services - the French blocked any deal in that area - which means that companies broadcasting out of the UK into the EU may find their transmissions blocked. As with most of the implications around services I have no idea what impact that will have but presumably it will force some companies to set up and get licensed in the EU and consequently increase costs and decrease profits.
More generally, I expect to see some quite interesting and inventive profit warnings from services companies over the next 18 months or so.
timarr
Classy wheels Paul! If you ever go into the minicab trade, I would hire you for my next rural pub crawl. ;-)
An interesting update regarding Naked Wines (LON:WINE) (please note this is from an investor in Naked Wines rather than from Naked Wines):
https://twitter.com/Symmetry_Invest/status/1344206957557800961?s=09
For anyone who owns Fevertree Drinks (LON:FEVR) this is an interesting picture which someone just told me about (I'm not a fan of the Kardashians but they certainly sell a product):
https://metro.co.uk/2020/12/30...
It's not what you say, it's the way you say it.
I can pretty much work out which ones of my posts will be down voted before I hit the "add comment". Doesn't worry me much, seeking validation from others isn't worth chasing.
Oh, and the ad hominem attacks don't do your reputation as a poster worth reading any good either.
When I started posting I got a lot of negative votes. It appeared that it was because I was asking questions rather than passing on opinions. Admittedly, I was a bit repetitive about Naked Wines which I had bought at 220p. I bet those that cast their negative votes wished they had taken a bit more notice. It is now at 668p.
People need to be more accepting of those with differing opinions.
Hi Paul
You probably remember my mentioning XAR on PI World. I think these are a classic takeover target tho I haven't bought them for that reason and sincerely hope they do not get approached for some time until they have re rated. But consider this. They have £25m net cash approx, no debt and are likely to get that again and more from the sale of the remaining 3D business to Stratasys who have a 2 year call option on the remaining 55% XAR own. That would be just what a private equity co would like to take out of the co, load it with debt and refloat it imo. You may also remember UK's Linx Printing and Domino Printing (several directors of which now run XAR) being taken over by Danaher and Brother respectively.
XAR is now the last remaining independent inkjet printhead co in the world. HP, Xerox and the like have taken them all over. Yet XAR has world beating tech, their 3D printheads could well become a thorn in the side for HP as 'powder bed' 3D printing stars to eat into their tech - powderbed fusion can print 3D products in production run size volumes and will require Xaar printheads even when the 3D business is sold off. Just coming back into profit too and cash generative which is when these bidders often like to pounce.
So they would be my prime bid target in my portfolio but I haven't bought them for that, I have bought for recovery, I am sure at some point they have to get taken out tho, the whole industry has gone to the big co's and XAR is the last remaining private trophy out there imo. I just hope XAR is further down the line and investors get the true value of the co in a few years time than now tho, but that choice isn't in my gift.
All the best
CR
Anyone any ideas whats going on at Petards Petards (LON:PEG) today - almost 25% up Tiny, I appreciate but against the Mkt ? (I'm still suffering a small 80% ish loss!)
Hi Paul - Picking up your comments above re Boohoo (LON:BOO) potentially considering listing in NY - Wonder if that is why the British fashion company FARFETCH which is based in London is listed - soley - in NY ? Appreciate they are in quite different ends of the Mkt - but its fashion nevertheless!
Think I might advise Plexus to change their ticker!
LOL, I know POS (piece of shit) does amuse me every time I report on Plexus!
The boss could also be called BOWB (boring old wind bag!)
Stop talking, and deliver some results, I would say.
Ive given up buying classic cars. Visits to the garage are scary
Hi Paul,
I'm with you on the beauty of your new acquisition. I have a 4.0 XJ8 circa 2001 - it puts a smile on my face every time I drive it. Only thing I would say is give it one or two decent (100 mile) journeys every few months - it takes a while for the XJ12 Oil to fully heat up and then driving it is an absolute dream.
Thanks to you and all your team for your sage words this year - and the other contributors too for that matter.
Hi Paul,
My sense is that there might be more consolidation coming in the property services sector. The one that got away is Countrywide (LON:CWD) that currently trades at 350p (up from 53p in May) on the back of the takeover approach by Connells.
Allow me to wish you and yours good heath, joy and happiness in 2021.
Jannie
I learnt a long time ago with an e Mail that humour can often be misinterpreted in print alone. No one knows your mood or disposition at the time you write. I now always put a smiley face :-) when I am joking. Hope it helps. I highly offended an old friend who didn't know I was joking. So easily done.
agreed. Wish actually the site had some emojis. At least smiley ones
well done getting that car - it popped up on my twitter feed just prior to Xmas and it did look very nice.......
Paul asks for any take over candidates from members? Here are a few I hold which I think may potentially go this year (a very mixed bag!)
Foxtons (LON:FOXT) ...almost the last listed High Street estate agent left. Been buying up specialist renting companies partly (I think) to ward off a bid. Countrywide has gone up significantly with two competitive bidders fighting over it. Will the loser have a go at Foxtons?
Webis Holding (LON:WEB) ....a micro company majority owned by a billionaire investor. Owns a trotting track in California and a number of sports licenses worth millions. Sports betting is booming in the USA and this company is perfect and cheap for those that want to expand there.
4d Pharma (LON:DDDD) ....listing on the Nasdaq soon and has some great drug candidates.
Galliford Try Holdings (LON:GFRD) .... sold their housebuilding arm and the remaining construction company is perhaps too small to compete. Lots of handy cash. No debt or pension liabilities. Ideal fit for one of the major companies in this field.
Petards (LON:PEG) ....small company that specialises in advanced security and surveillance systems. Bombardier is a key customer. Moving up in price quietly at the moment and many a medium engineering company would like their technology.
In addition to Paul’s suggestions and others posted today, here are 3 more:-
OPG Power Ventures (LON:OPG) 17p but up 22% today. Another being pumped? Or news (e.g bid or going private) leaking today? PE (according to Stockopedia) 6. 98 for value and 91 quality.
Micro Focus International (LON:MCRO) 431p. Note it’s a tech Company and with US quote. Nearly ruined by disastrous Hewlett Packard buy BUT their last update suggested the worst is over and share has recovered since that update. Note that share was £10.50 at start of this year and 5 year high was £25.
Saga (LON:SAGA) 257p. PE7. No need for comment as Paul’s superb updates have said it all. If anyone reading this hasn’t read any of them then it’s well worth checking them out. PE7. Share was £7 at start of the year and 5 year peak was £30. Saga apparently turned down a potential bid ahead of the fund raising, but without reporting it at the time!
Also mining sector is on a roll with commodity prices at multi year highs but shares well below previous peaks. Both Sylvania Platinum (LON:SLP) 87p and Central Asia Metals (LON:CAML) 241p (Their 2 low cost copper mines must be throwing out oddles of cash!) look possible targets.
I hold all of these.
Second £boo and £mcro. So believe both have potential - growth story for the former and recovery play at really cheap valuations on the latter. Anybody else have thoughts on £mcro ? £boo has been covered extensively by Paul (Ty!).
Disclosure: Don't hold either but considering a position in both.
Boohoo (LON:BOO) and Micro Focus International (LON:MCRO) .. hopefully that works!!
Boku Inc (LON:BOKU) is another possible takeover target. "BOKU is a leading global provider of mobile payment and identity solutions. Boku technology is integrated into over 220 mobile wallets and network operators worldwide powering mobile user authentication and mobile payments. Boku processes over 800 million transactions worth more than $7 billion annually in nearly 70 countries. Global leaders that rely on Boku to acquire, monetise, and protect digital consumer transactions include Apple, Discover, Experian, Facebook, FIS, Fiserv, Google, Microsoft, Netflix, Paypal, Sony, Spotify and Western Union." Quote extracted from latest trading update.
Bango (LON:BGO) too
Sylvania Platinum (LON:SLP) would be my takeover target. Appreciate not on Pauls radar.
All the figures are outstanding, 228M Cap, money making machine with 55M in the bank. Potential huge special dividend on its way early next year, PER < 5, ROCE > 35%.
Whichever car you drive, you need one of its metals and they are pushing ever higher on rarity issues.
On a bit of a spurt recently, but can see a larger miner coming in and getting it for song.
Today it became my second multi-bagger, the first being Revolution Bars (LON:RBG) (thanks Paul). Now in a dilemma, do I top slice and shove the money into Redde Northgate (LON:REDD), or leave it alone as believe its got a long way to go.
All these excellent tips and frustrating not having an unlimited well to dip into, but not complaining.
I did a write up recently on my takeover target for 2021/22 Rps (LON:RPS) and expect to at least triple my money on this one even if it doesn’t get taken over:
https://cube.investments/rps-g...
My guess at takeover material for 2021 Paul is Reach. Valuable database, Execs linked to bigger data companies and hard to replicate easily.
Hi Paul,
Love the car.-when that baby kicks in wow..
Totally agree on your comments. I think it was Mark Slater talking about UK being cheap relative to its peers-"normally he sees 3-4 takeover targets in his portfolio and this year seen 11".(P I World interview) . Another characteristic that came out in another one of these interview was how China loads up many of the companies they hold a stake in with debt -something the UK has been avoiding, by and large and maybe could be a catalyst for redirection of cashflow for PE players..
Mark
Hi Paul, would be useful if the Helpful Tip saying to use the £ sign in front of the ticker also mentioned that you need to click on the link tab as well. Took me a while to work out and I see a few others are also making the mistake of just typing, for example, Saga (LON:SAGA) and not Saga (LON:SAGA)
not sure how both the above ended up with a link!
They both worked because your original statement was wrong - I have never need to click "on the link tab as well" and it has always worked except:
1) if you don't leave a space after £saga's cruise ships
2) if a numeral is involved £d4t4
Thanks sharw, but I'm still confused as that doesn't seem to always work. There seems to be a Boohoo (LON:BOO) below posted at 3.26 that hasn't worked.
Roger Baron - I see the one you mean at 3.26. If I simply cut and paste it we get:
Hi FREng, Re Boohoo (LON:BOO) there have been
I think someone said it didn't work on the mobile app but I may be wrong (I've never used it).
Don't place a period or comma directly after your attempt or it will fail.
Love the new wheels Paul, enjoy!
In terms of takeover prospects, I hold Emis (LON:EMIS) and recently topped up due to attractive PE, low gearing and decent divi yield. I’ve always felt it could be a great acquisition for one of the bigger healthcare boys looking for growth into healthcare tech market.
I recently came across this from a technical point of view, it looks like there was some volume coming into the stock around 980, so maybe some accumulation going on here? Interesting, I don't know much about the company, but I certainly like the quality metrics and its net cash position.
£SAGA. I have just put up some comments o the Discussion Board for £SAGA. I would be interested in comments form Paul (my guru) and anyone else interested in this stock. I am not currently a holder, hence my research in between Christmas and now. Hope it provokes some additional valuable comments.
There you go, placing a period (or a comma) after Saga (LON:SAGA) costs you the link.
Abject apologies. Thanks for the reminder. HNY.
Hi Paul! Safe driving and it’s always nice to treat oneself, it’s a beautiful car although the Morse jag does it for me! Re takeovers I wonder how the new rules will work? We wouldn’t want to become Fortress Britain in terms of losing our free market principles although we do lose a lot of our good companies to overseas predators! Regarding Intercede Intercede (LON:IGP) , although an attractive business I would have thought a takeover there would be very difficult with US govt contacts involved.
Hi PeterM,
Regarding Intercede Intercede (LON:IGP) , although an attractive business I would have thought a takeover there would be very difficult with US govt contacts involved.
Good point, I was wondering about that too. Probably safe to say that the Chinese would not be allowed to buy Intercede. They shouldn't be allowed to buy anything in my view - a nasty dictatorship that despises western liberal values. Ignore it at your peril.
Regards, Paul.
What about Tribal? It is a sound but boring business providing admin IT services to universities and schools. It has an almost guaranteed income stream.
There is a private American company, Jenzabar, in more or less the same business that has built up a 20.1% holding and I have wondered if they might take it over at some point. As far as I know, they haven't yet shown any inclination to put in a bid.
I have held in the past but don't at the moment.
If Boohoo did ever list on the Nasdaq, it would have a double listing. The shares would also still be listed on the UK market so our holdings would see no difference other than hopefully a price rise "if" the company is awarded a higher rating on the Nasdaq. Another example of a company listed in both the UK and US is Hutchision China Meditech
Paul, enjoy your “Double six”. As a child my Dad had a Mk1 XJ6 in Tudor white with red leather.
My jobs were to change over to the other fuel tank on the toggle switches and if I was lucky to change over to James last on the 8 track stereo from Herb Albert. If I wasn’t lucky I got to empty the twin chrome ashtrays full of his Park Drive cigarettes....
We use to drive to South of France fairly regularly. It must of cost a fortune as there was a fuel crisis. I always wondered what that Nimrod overhead was for on those long journeys....
Enjoy wafting in silence
If you look on YouTube Jeremy Clarkson did a video on Topgear and said it was the most comfortable car ever made.
Evocative memories, Nigel! "The most elegant four-door saloon ever" Clarkson also says in the intro - here is the link, he looks so young...
Great choice, Paul, I am sure you will get a lot of pleasure from it. 35,000 miles from new is incredible, it must be one of the best in the country. I agree with you, it is a work of art.
Hi Whitbourne, Many Thanks for posting.
Ha ha, He does indeed. I bumped into his Mother many years ago. She was as mad as a box of frogs. Totally barking in a charming way.
Super cars Jags. Any self respecting criminal (of the time) wouldn't be seen driving anything else allegedly.... (not a slur on your character Paul btw)
Probably an ex-yakuza's car - so Paul may have to get a few Tatoos!
Thanks Whitbourne!
I didn't like the downbeat tone of Clarksons report on the Daimler Double-Six
These magnificent beasts are not dying, they're coming alive again!
Once I take delivery, expected in mid January, will post some pictures.
Stunning is not the word!
Best wishes, Paul.
Hi Paul, if Boohoo (LON:BOO) were to list on the NASDAQ, what affect would this have on current shareholders? would shares automatically move across? Thank you
Boohoo (LON:BOO) I don't think so, it would probably be a dual listing, such as Burford Capital (LON:BUR), you can buy and sell shares both in London and New York.
If Boohoo (LON:BOO) were to list on Nasdaq their shares would no longer qualify for UK inheritance tax relief because they would be trading on a recognised exchange.
Paul, with reference your invitation to suggest potential takeover candidates, I would suggest Tremor International (LON:TRMR) might be a candidate for either a take-over or US listing.
They hosted a "Tech lockdown demo" in the first half of December, which their house broker followed up with a quite extraordinary broker note (available via Research Tree or direct from finnCap's free to access research portal) which emphasised the valuation gap vs US peers & noted that, "As Tremor continues to deliver and exceed expectations, we do not expect that its current valuation will be sustainable due to market or external interest...".
I understand the company has a growing share of its business in the US and I believe the executives are now based out of the US (I think).
I did ask the question in their InvestorMeetCompany session in September whether they would consider and pursue a US listing, which was answered noncommittally as something which they were thinking of, but no current plans. The question did not appear though on the post meeting published Q&A, although I will not read too much into that!
£wine could be a target for one of the big beverage/distribution firms. It’s a growth area for them. A similar smaller competitor in the US (empathy wines) was taken over not that long ago.
Like the Jag, Paul, it might just be me, but I seem to think Jag has become very trendy in the past year or so - more so than usual. I also bought an XE R-sport this year. I don't think the boot is big enough for golf clubs - think Jaguar did that on purpose because of the old Jeremy Clarkson Top Gear stereotype! :))))
Interesting story too, there does seem to be a lot of talk of deal making in the new year, I've heard very similar things anecdotally. There is of course a lot of talk around loosening rules and restrictions on IPO listings too.
People down voting my comment, obviously don't have a sense of humour here.
Surprise surprise, the usual who come along and just down vote anything without reading it.
I made two comments yesterday that were identical to other people and mine were voted down and theirs up.
Guess people just want someone to agree with them on everything and tell them how amazing they are and don't like when someone breaks the norms.
Forbid we should have an opinion or make a joke!
Stockopedia should probably do away with the voting anyway, it doesn't add anything.
I am not sure I would want it removed, for me its a great reminder how the markets can be influenced by heard mentality. I have seen many times on here where comments are getting waves of down votes over absolute trivial comments.
Completely agree, I've seen that a lot. There is one below where I said it is high risk to buy a failed brand and it has plenty of down votes. Is that not an obvious statement, failed brands failed for a reason and therefore would be higher risk than a non-failed brand? :))) As Sir Desmond Swayne puts it "Herd Stupidity".
Another point just came up, yesterday I said schools are key spreaders of covid and would be closed for longer until testing weekly is ready and received net -8 votes, and then subsequently -35 net votes because I said the economy was shut to keep some school years open.
The government has just announced they are putting off opening most school years until 18th Jan because they are a spreader and until they have weekly testing ready - confirming what I said.
On top of that, the London School of Hygiene and Tropical Medicine said a lockdown with schools open would not work to reduce the R rate to below one.
It doesn't bother me at all if people vote down my comments but people just want confirmation bias so it makes votes redundant.
You are all good with me Sir Thornabian. You keep up your good work.
Thanks! :)
Hi Thornabian
I think the research rather disputes that Lockdown reduce the Virus in any case, schools or no schools. Even Prof Whitty confirmed to Parliamentary committee that the peak of Covid infections happened prior to the first Lockdown.
I do think it unhelpful to vote down views one doesn’t agree with. The sense of dialogue is what makes this Board valuable to me.
On a separate note, isn’t it incredible how after 5 years of sound and fury re Brexit, that this Board has been so quiet and relaxed on the subject. A bit of unity can make for a pleasant change after so much bitter dispute.
Martin
hi Martin,
Completely agree. I said that mobility increased over 10% between the second lockdown being announced and implemented. That also got a lot of down votes for some reason but anyone can view Google mobility data.
I imagine the next big argument will be about all the taxes we have to pay for the covid relief spending..... :)
Thornabian.
Hi Thornbian,
Stop taking yourself so seriously, and take a chill pill. It's XmAS ffs;
People down voting my comment, obviously don't have a sense of humour here.
Surprise surprise, the usual who come along and just down vote anything without reading it.
I made two comments yesterday that were identical to other people and mine were voted down and theirs up.
nOBODY CARES!
pAUL.
Who is the one taking things seriously? The one telling the joke or the ones complaining about it?
Interesting point from the MHRA in their presentation today, they recommended the two full doses of the Oxford vaccine, rather than the half dose-full dose, because they said there was not enough evidence that the half-dose was as effective as stated.
Likely because it was only tested on 18-55 year olds, so effectiveness is always likely to be higher due to the age of participants.
This means it will have a 62% stated effectiveness from the two full dose, stage three trials. Should still be high enough as influenza vaccinations are normally 40-60% effective but just introduces a small amount of caution on the vaccine effectiveness news.
Good point. Although with trials current data it’s 100% effective at stopping serious C19 cases. So far nobody vaccinated & infected during the trial was hospitalised. (yet)
Let's hope so.
Will be interesting to see now with cases flying back up after the Xmas mingling, it should give them a better idea on effectiveness of all vaccines as the one drawback for getting an exact effectiveness number is the virus being prevalent enough to either infect or not infect, seriously or not seriously.
Thanks Tamzin. As Mark highlighted, be greedy when others are fearful. The old Buffet investor maxim.
I wonder how many who look at these boards took advantage of the markets.
I increased my exposure.
Boohoo (LON:BOO) was one of those that crept into my portfolio. This was aided by Paul's commentary on the subject.
I took advantage of some lower pricing to invest more in Property Franchise (LON:TPFG) though this due to the fears of Covid restraining the market hasn't bounced as yet. However, I believe it is a strong and well run business, and has itself taken advantage of the market by acquiring another business in the meantime.
An investment of mine that hasn't done well, though were climbing before Covid is Everyman Media (LON:EMAN) a small cinema group that provides a more intimate cinema experience with dining and drinks. That is 40% down and the CEO who attracted me to the share has left the business. Through inertia I haven't done anything, and I hope to see some recovery later in 2021.
I sold Card Factory (LON:CARD) before Covid just on the basis I was tired of its relative underperformance and was increasingly unconvinced by the CEO. It will be an interesting one to watch. Maybe a takeover prospect, but is probably not a fashionable buy for M&A merchants, though PE could be tempted by its cash characteristics? I wonder if I should go back in?
I don't look at my portfolio on an annual performance basis, as a I don't baseline my stock annually, as I am not a huge buyer and seller, but tend to look at its performance relative to original cost. So I never particularly know how my portfolio in a calendar year. I suspect I am up against the FTSE all share, due to the performance of stocks like Up Global Sourcing Holdings (LON:UPGS), but frankly don't know. This probably makes me a very poor analyzer of portfolio performance!
Trident, your " look at its performance relative to original cost" defines my view of my portfolio. This morning I checked the best Stocko-rated shares I hold, 13 were Super Stocks or High Flyers, mostly Super Stocks. 11 were in profit, no multi-baggers, and 2 below water. The chances are that I will double-down on those 2 as at the end of the day it is the buying price that matters, along with dividends, to me.
I believe M&S could be a takeover target.....
Always thought that would be a good one for Amazon. They bought Whole foods in the US which from a food perspective is quite similar to M&S.
Paul, I hope the XJS is staying? You can't have too many Jags
Tamzin,
I would like to add my thanks to for all 8 of the interviews. Some interesting investment ideas and rationale on what often have been slow news days.
The final piworld 2020 round up interview with Mark Slater, here. What went well, and as expected, Codemasters Group (LON:CDM). Learnings: stay calm in a crises and buy aggressively! Outlook for 2021: positive. (Podcast).
We hope you've enjoyed this series, catch up on all 8 interviews here. (Paul's interview was the third, published 19th December.)
We'll be back in the New Year with more interviews, and more company presentations, etc.
Wishing you a very happy 2021.
I have enjoyed listening to them all Tamzin and appreciate what you are trying to do there.
Thanks Tamzin for some amazing insightful interviews- the questions you ask get right to the core of investing and provide for the amateur investor a window on what to do, and more importantly what not to do.
Best wishes for 2021
Mark
Thoroughly enjoyed them Tamzin as a new investor in my first 12 months, they have been invaluable. Keep up the great work!
Tamzin, please perform the same exercise next year. Every single one of the shares that your interviewees nominated as their favourite for 2021 rocketed. Next year I will be ready with my spread betting account.
I always enjoy your reports Paul - keep them going! I know you are keen on Boohoo and was looking at the company - can you tell me why they don't pay a dividend when they have so much cash? It would broaden their shareholder base.
They use the cash for expansion (warehouses etc) and purchasing brands. There is speculation they're going to get bits of Arcadia
They spend roughly 10% of sales on marketing of the brands each year.
Once it is established in the US and more mainstream, it may give them the room for dividends.
The equity raise they did earlier this year was sold as for purchasing brands but so far they have only bought the remainder of Pretty Little Thing for £198m. Although I also own Boohoo (LON:BOO) , that is the one thing which concerns me because I would like to also see a brand a bit more 'upmarket' - shall we say - brought in to diversify the brand appeal; but that's just my opinion if it was my company.
Like Warehouse and Karen Millen?
Are you saying Warehouse is upmarket? I don't see it as any better in quality than Topshop. Most of the clothes are Nylon or Polyester with poor sizing standards because it is mass produced - and it is meant to be for price leadership, not quality leadership as that is the main selling point.
Karen Millen was yes but they completely downgraded the quality which ruined the whole brand appeal of Karen Millen.
Karen Millen, Ted Baker, LK Bennett and Reiss etc. all have/had very distinctive brands of high quality clothes for office working people (women were the highest market).
This of course became crowded with competition pre-covid and has been hit hard by covid but it is still an important segment of retail, particularly for higher margins going forward.
I don't see any need for Boohoo (LON:BOO) to go and buy a brand of low quality clothes (e.g. polyester clothes from Topshop) when they already service that segment and have no use for stores - which is a segment of mainly teenagers who don't want to pay a lot but wear it casually or to socialise. I'm not saying that flippantly because that is perfectly fine, before people get uppity about it here as they always do - that is just the market they are currently having most success with.
Maybe if they get the brand for peanuts to bring in some 'attached' customers to the Topshop brand but I just don't see the synergy or diversification reasons for it.
You said “a brand ‘a bit’ more ‘upmarket’”.
Now what you’re saying is a luxury brand. Make your mind up.
And yes. Warehouse is “a bit” more upmarket than Pretty Little Thing and Boohoo.
Also, Topshop is an established brand in many geographies and would help grow the business through brand recognition in countries that have never heard of “Boohoo” or “PLT” which need heavy advertising to establish the brand. Its basically it’s a shortcut to increase sales faster.
We must have different definitions of luxury brands. I would put Channel, LV, Burberry, Gucci, Patek Philip, Dior etc. as luxury brands.
I'm talking about them buying a brand which sells clothes for £50-400 due to quality leading, not £500-£20,000 discretionary luxury brands.
Ah, we’re back to Karen Millen.
Nice going round in circles with you. I have to stop now though, I’m getting dizzy from all the spinning.
However, Topshop is also known as a failed bankrupt brand, that speaks volumes in and of itself, it is a huge risk to buy a failed brand.
Risk / reward.
How much will it cost? What are the possible benefits?
In other geographies, if the stores have a sign in the window saying "we're closing the shop, we've moved online", how does this make your average punter aware they're a "failed bankrupt brand"?
Like all business decisions the execs need to do a cost/benefit analysis. They managed this a few times already, especially Nasty Gal and proved they're no mugs at this game.
Long Boohoo (LON:BOO)
I wasn't disputing that it could be made at least moderately successful as a brand. My point was more, if it has failed once, there must be a reason for that and it would, therefore, be a gamble that they can somehow revive it by doing little new with it.
If I put myself as a fly on the wall in any internal meeting in Boohoo (LON:BOO) to justify buying another horizontal brand acquisition would be a difficult one to reason out.
They wouldn't do little new with it.
They'd close the shops, give it a shiny new website and slash costs in markets that Boo group doesn't have a significant presence. How many of these countries do you think Boo has significant coverage in?
https://www.topshop.com/store-...
True although the fruits of Karen Millen in particular remain to be seen. I think Topman/ Topman offer a nice middle ground which will perhaps attract a segment of the market that Boohoo (LON:BOO) currently doesn't cater for. Though given their solvency and rev growh it should be emphasized that boohoo and boohooman are much better businesses than them currently and boohoo group should be given huge credit for that.
On another point I'm holding my breath on the upcoming January update as the trends data across the brands doesn't seem to paint a pretty picture with Boohoo, Nasty Gal and PLT (significantly ex BF) trending down year over year since September? If you contrast this with previous yoy rates it always seems to trend up and to the right. This could indicate a slowing in topline expansion? The caveat I have is that asos seems to be trending down in Google search since 2015 but revenues have increased massively in that period?
Sure more people will be using the app and also going direct to the site but I can't find any reliable data indicators of these and I can't envision there being such a sizable switch away from Google search to undermine the Google trends data?
I can't seem to work it out but I think trends data is relevant to rev growth look -for example- at the bumper sales period in the first half of the year: trends data peaked at all time highs across several of the brands.
Also it makes perfect sense that the target markets didn't shop as much in the last quarter, few to no xmas parties, less nights out with mates, less date nights, freshers week cancelled, Halloween cancelled etc less need for new clothes. Why wasn't the case in the first half? Perhaps because we didn't expect restrictions to extend until next spring.
Long term I'm bullish and there is little doubt that in this year as a whole the boohoogroup will post substantial revenue growth. I suppose this is the issue with quarterly updates it leads to over analysis. When companies like this have performed unbelievably well over the year given the covid-19 backdrop. Half yearly would suit me down to the ground.
That is a good point, the £1 sales they did for Black Friday are a little bit of a concern too possibly. They claimed it was for publicity but intuitively the only real reason for selling for so far below cost is because storage costs are much higher than the margin cost on selling them slower at cost price.
Maybe we can take it at face value as they say, who knows, but I don't think it would be a crazy thing to sell going in to the next update and take some risk off the table.
A few points to reply and add some of my thoughts to your well thought out and constructed post.
Karen Millen cost a little over £18M quid. Risk reward seems positive, even if it stays small it should be good margin, uses existing infrastructure so low fixed costs relatively, and worth the effort.
There's only so much you can grow a brand in a geography. The marketing costs of starting a brand from scratch are enormous - getting an existing brand that has recognition and a customer base could, on a case-by-case basis, work out cheaper than starting from scratch.
I should imagine the UK market it pretty saturated at the bottom end now, growth not impossible but a lot harder and more expensive - cheaper low hanging fruit elsewhere. Plus, as you state, most of the target market will have the various apps and won't need to use search engines. Additionally I would state (speculation) that using the free tools to work out which sites are popular isn't that useful, certainly not from my experience of using them - data is a valuable commodity and good data is a paid for service. If you have access to these tools, my apologies, I am making an assumption :)
US, EU and RoW are where any new growth is going to come from. Buying existing brands in these geographies would be where I would put my land and expand energy, but I work in IT not corporate leadership, so I will, as I do regularly on here, admit I am a bit of an idiot in this field.
A horizontal brand acquisition in new geographies would be good move I think. Particularly in the US, something like Century21 (Not sure what happened to that brand) and I'm sure there are a few others.
Century 21 is a chain of estate agents!
It was a US retail chain and moved online actually:
https://www.c21stores.com/
Amazon never have paid dividends. Some investors like a dividend but that is just reducing the money in the business.
I'm not concerned about a dividend in growth companies.
Many of my income shares have cut or not paid a dividend this year.
I am always interested in the views of Terry Smith. He never buys on the basis of dividends. Some of the companies in his fund pay dividends, but his measure is share capital growth, founded amongst other things on a strong ROC (Return on Capital).
He says if you want to mimic the effect of a dividend, you can sell some of the shares that have risen on capital growth.
Whenever I have bought in the past on the basis of dividends alone, it never goes well!
I agree happy for earnings to be retained for good use. What am I going to do with it? Pay tax then buy more whisky and shares? No thanks.
Hear Hear , its always TOTAL RETURN that counts !
The power to strip shareholders of their voting rights lies with the Boards of Ryanair/WizzAir as set out in their Articles of Association give t. So either from day1 or at a later stage their Articles of Association were designed specifically to anticipate such a possible scenario.
If it was a change to the Articles at some point after the company was first incorporated then that change would have been approved by shareholders at one of their AGMs. I guess not many shareholders would be bothered to read through changes to a company's Constitution and these kind of changes often go through 'on the nod' - this shows it pays to read through AGM material and exercise your vote.
Having said that, for private investors the information is not readily made available by one's broker so you'd have to go to the trouble to find out..
I commented on this topic a few years back. The replies were to the effect I was a scaremongering Remoaner. So I doubt many paid attention to the Articles or, if they did, thought they would ever be invoked.
Thanks for the info. Your reply suggests that any company can do this and that perhaps any company I buy may have the power to do this. I wonder how many do? I confess I've never checked before. I can think of many circumstances where a company would like to disenfranchise a selected group of shareholders.
I also wonder what this means for institutional investors. Many fund mandates would probably require them to sell. Or they may decide they cant protect their investment and sell anyway. This must all be in the price for these companies already, but I confess I find the wider implications surprising.
So now is the time to leave Wizz Air Holdings (LON:WIZZ) and find something else (I held and sold at a pound less than now early in December), as I did.
Silver
On £EZY / Ryanair Holdings (LON:RYA) / Wizz Air Holdings (LON:WIZZ) and loss of vote:
For the average PI, not much different probably.
However, under self-imposed ESG rules, some institutions may be forced sellers (if they have not exited already) ?
If the board had not had these powers or rather shareholders had decided not to grant them these powers. I wonder what would have happened to RyanAir, EasyJet and Wizz. Would they have had to cease trading from January 1st 2021 or would finding a solution have been given a higher priority in the negotiations?
Ienergizer (LON:IBPO) new debt facility and what sounds like a possible special dividend. Any thoughts, Paul?
New debt facility will enable div payment. That’s the big takeaway here.
IMO ienegizer £ibpo is a t/o target. PER 18
div c5%
Margin over 20%
It provides content and other new media type services which are on the up as advertising goes from old school to new school
I see that Wizz air, Ryanair and easyjet are stripping shareholders of their voting rights as a result of Brexit. For Wizz Air, about 60% of its shareholders will be sent restricted share notices to stop them from attending future meetings.
Does anyone here understand the legality of this? As I understand it there has been no vote, only board decisions. Does this mean that any company can strip any pesky shareholders of their rights as it wishes? Surely not, but if this is allowed, I can't see why not. Anyone know?
Morning cmpeckham, Interesting - May I ask where you have seen this news?
What I have seen follows the exit from transition rules in that UK Shareholders are no longer qualifying Nationals POST the Brexit exit Deal. So its part of Boris's oven ready deal
Geneva, 29 December 2020: Wizz Air Holdings Plc (the "Company") announces its decision to treat as Restricted Shares certain Ordinary Shares held by Non-Qualifying Nationals and to issue to such shareholders Restricted Share Notices on the basis set out below (the "Disenfranchisement"). This is because from 1 January 2021 UK nationals will no longer be treated as Qualifying Nationals with regards to ongoing European airline ownership requirements, notwithstanding the UK-EU Trade and Cooperation Agreement.
I saw it on HL news.
The BBC have it here: https://www.bbc.co.uk/news/bus...
Perhaps Mr O'Leary's large share sale on the 15th was done in the anticipation of a sudden rush for the exit by UK shareholders when they realized what would happen to their votes. If the restricted shares become a second class of share, I would expect them be worth much less than the shares with voting rights.
You may be right but as I understand it, the restricted share designation belongs to the owner (if they are a non EU national) not the share. So the shares are still fungible, but perhaps worth less on average than they were before.
sounds like a typical bucket airline move, separate everything so you can then charge for each item. So share costs one price, want to upgrade to vote, certainly sir that will be £££ more please.
Slow news day....Just a vote in Parliament on the EU U.K. trade deal, and announcement of Oxford vaccine which is far easier to distribute. Santa rally may continue ;-)
agreed totally. to be honest, i feel a sense of guilt - i am her in London with my laptop and excess cash.. and now a vaccine.. while billions are starving and unlikley to get the vaccine soon - my biggest problem - breakeven or increase earnings. the time is now here that humanity realises we re all in this together - look at the social capital website. I started a food charity in Turkey for displaced hospitality workers from eastern Europe .. and hoses a homeless guy her in London for 4 months to help out. These tiny micro experiences shows me, i know now that Covid cost to humanity is beyond comprehension, I can feel it. I am a Zambian nw in London - very interested in Wildlife preservation in Africa. Agreed we are all in this together take care and stay safe
Apologies Martin I posted in the wrong feed!
Great post news.. re vaccine!
I'd have thought the answer would be to make it locally in S.A. under license, thereby providing some jobs too. Don't know how the funding would work but guess that issue is the same however the poorer countries get the vaccine (at least it's not for profit) .
RA International may be of interest to you given its business model
On a slow/no news day.........
I have to admit, if it wasn't for this report, I would never have known what Boohoo (LON:BOO) was, never heard of them before and certainly never seen an advert, even to this day.
However, courtesy of twitter, I have now seen one, I assume sales must be going well, as advertising in this location cannot come cheap.
https://twitter.com/SimeonPand...
You akshually saw two, the PrettyLittleThing advert that started at the end of the BooHooMan one is a Boo brand too :)
Morgan Stanley have just announced an increase in their holding in Boohoo (LON:BOO) https://www.stockopedia.com/sh...
It'll be either short interest or positions held for clients as contract for difference
Hi FREng, Re £BOO there have been vague rumours about the actual owner of that stake...and they’re not American despite MS being the broker....
New Comment
Hi FREng, Re Boohoo (LON:BOO) there have been vague rumours about the actual owner of that stake...and they’re not American despite MS being the broker....
Great news re the new vaccine. A BIG plus for U.K. scientific research and obviously the world in due course . Just hope we in South Africa won’t have to wait until July to get the vaccine as forecast by the President here a few days ago. The challenge will be to get the Oxford vaccine distributed world wide ASAP and not just to the richer countries
Agreed totally. to be honest, I feel a sense of guilt and also responsibility now to help - I am here in London with my laptop and excess cash.. and now a vaccine.. while billions are starving and unlikely to get the vaccine soon - My biggest problem - breakeven or increase earnings.
The time is now here that humanity realises we re all in this together - look at the social capital website. I started a food charity in Turkey for displaced hospitality workers from eastern Europe .. and hoses a homeless guy her in London for 4 months to help out. These tiny micro experiences shows me, i know now that Covid cost to humanity is beyond comprehension, I can feel it.
I am a Zambian now in London - very interested in Wildlife preservation in Africa. Agreed we are all in this together take care invest for gains and help others with the proceeds as best you can ! Stay safe
If the ANC have promised it in July I would check which year. They will be planning some back handers to get rich.
;) cynical perhaps but unfortunately there is some truth in this. As you may know SA played an important part in the successful testing of the Oxford vaccine with many people here being involved in the trial programme. Hopefully that will have earned them some priority in obtaining supplies but no one here is holding their breath !!
My morning smallcap tweet:
Argo Blockchain (LON:ARB)
Argo Blockchain (ARB) to co-lead an investment in Luxor Technologies, a hashrate management platform. ARB will invest $100k. [SP=33 Cap=97m]
Oxford COVID Vaccine approval announced just now!