Small Cap Value Report (Wed 30 Sept 2020) - BOO, AIR, TAST, TPT, BWNG, PRES, STU

Good morning, it's Paul here with the SCVR for Weds.
Many thanks to Jack for covering yesterday.
There are loads of results out today, presumably to meet the 6 month deadline for 31 March period ends?
Timings - mostly done by 1pm official finish time.
Update at 14:18 - there's lots more to cover, so I'll probably be carrying on until about 6pm.
Update at 17:39 - today's report is now finished.
Agenda
Boohoo (LON:BOO) - interim results - my favourite share, and one which many readers hold, so despite not being a small cap, I'll look at this, as usual. I think we can do a victory lap, and push the noses of the shorters into their mess! :-)
Topps Tiles (LON:TPT) - trading update
N Brown (LON:BWNG) - trading update
Air Partner (LON:AIR) - half year results to 31 July 2020
Pressure Technologies (LON:PRES) - Major contracts & trading update
Plus anything else that there's time for & looks interesting. Please remember I cannot cover everything, and dull things like in line with expectations updates, don't really add any value. I'm looking for unusually good or bad things, where we can make some money, or avoid losses.
.
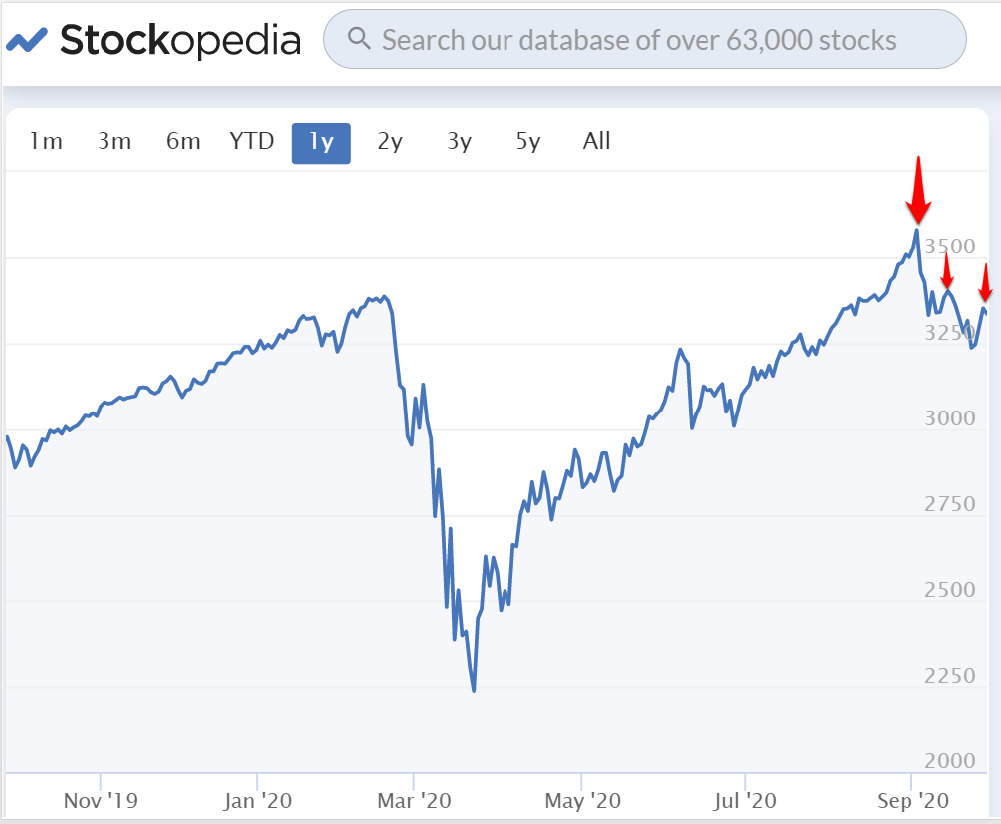
Buy the dip, or sell the rally?
A strategy of buying the dip, has worked incredibly well for many years now. I think it's one of the reasons that the market rally from the March lows this year seemed to get out of hand in the USA. As we know, the US market tends to set the tone & the direction for UK markets too.
As mentioned at the time, I hedged my portfolio back in Jan 2020 with some large shorts on US indices. It was a bumpy ride, but thankfully that worked very well, with profits from the shorts more than offsetting the heavy losses on my UK small cap shares. Sometimes people asked me why I blindly held onto things like Revolution Bars (LON:RBG) and French Connection (LON:FCCN) whilst they dropped 90% or more. The answer is because I'd hedged the positions, and that was the strategy I planned. Although, with hindsight, I didn't realise how bad the losses would be, and obviously it would have made sense to ditch them, but never mind. Both are actually very interesting special situations now though.
Unfortunately, over the late spring, and summer, I got it into my head that the US markets had overshot on the upside, and I lost tons of money shorting the US indices. I think sometimes hedging can morph into punting, without you necessarily being aware at the time!
It seemed crazy that US markets had recovered pretty much all the covid losses, despite covid being out of control in a second wave, and the economy recovering, but still on life support. So I've been waiting for a pullback, and it seems to be happening now.
Looking at the chart, I do wonder if "buy the dip" has possibly ended, and maybe the algorithms and hedge funds could now be switching to "sell the rallies?". For what it's worth, that's what I'm doing now, on the US indices, and it's made a few quid in the last few weeks. It's also nice to have a short hedge against my long portfolio.
What do readers think? Are we in a bear market now, I wonder, after a period of (at least in pockets) irrational exuberance, and out of control momentum? Or maybe it's too early to say? I find that charts are great at showing patterns after the event, but not so good at predicting what's going to happen next.
.
.
Boohoo (LON:BOO)
Share price: 384p (down 1.5% today, at 08:29)
No. shares: 1,226.6m
Market cap: £4,710m
(I hold)
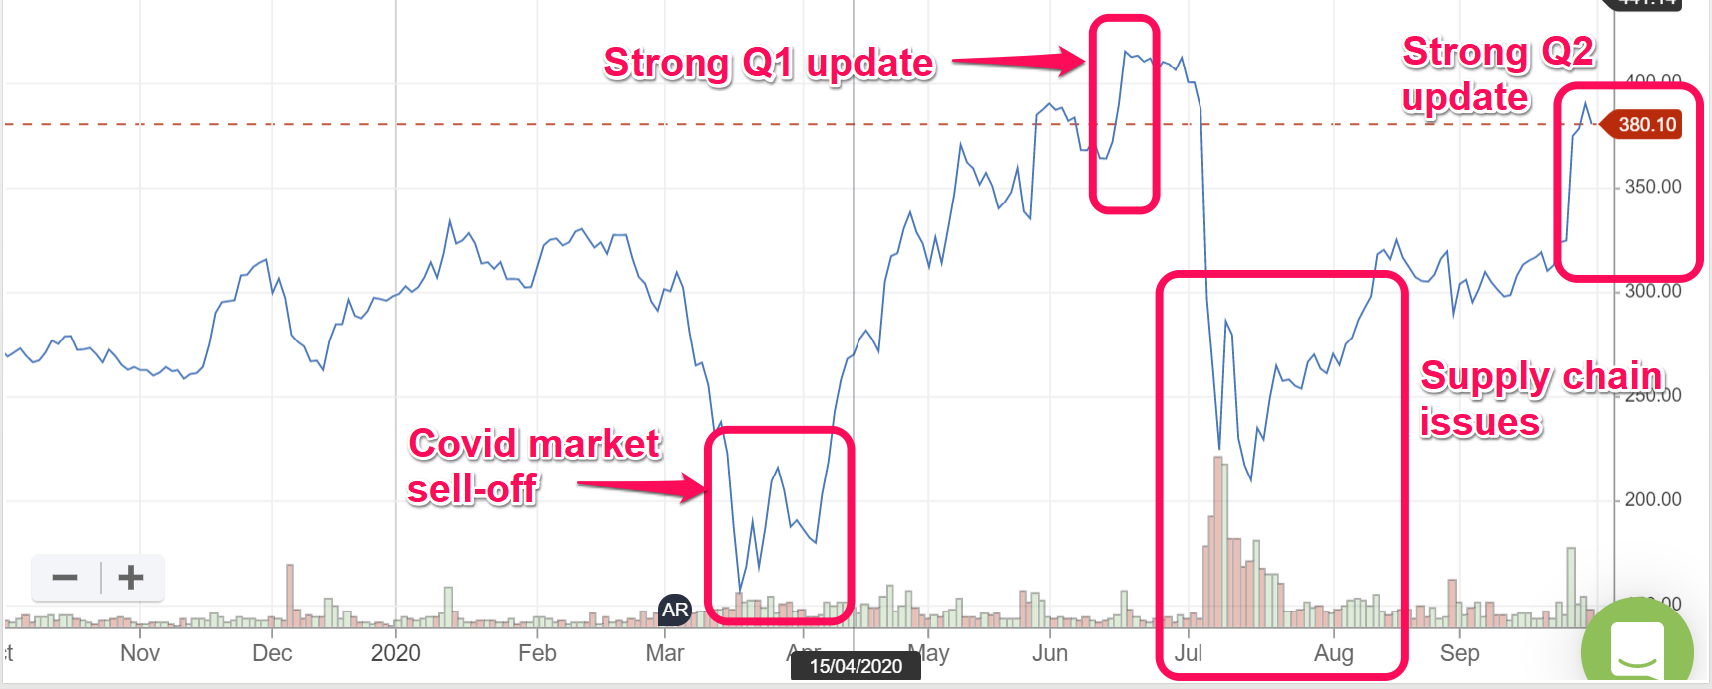
Sparkling results today, from this multi-brand (9 at the last count) fashion eCommerce business. The share price anticipated these numbers, as well as brushing aside the supply chain review published recently. That particular teacup has now recovered from storm conditions, despite some journalists' attempts to stir it up as much as possible.
Note that the allure of cheap fast fashion has clearly overwhelmed customers worrying too much about where or how the product is made. Rightly so, as practically the whole sector uses cheap labour from abroad, Bangladesh, etc. Arguably machinists allegedly working in Leicester for low wages because they're simultaneously claiming benefits, is a far more ethical setup than a sweatshop with fire exits chained shut in Bangladesh, and machinists being paid 50p per hour there. But we could discuss that ad infinitum, let's get back to the figures.
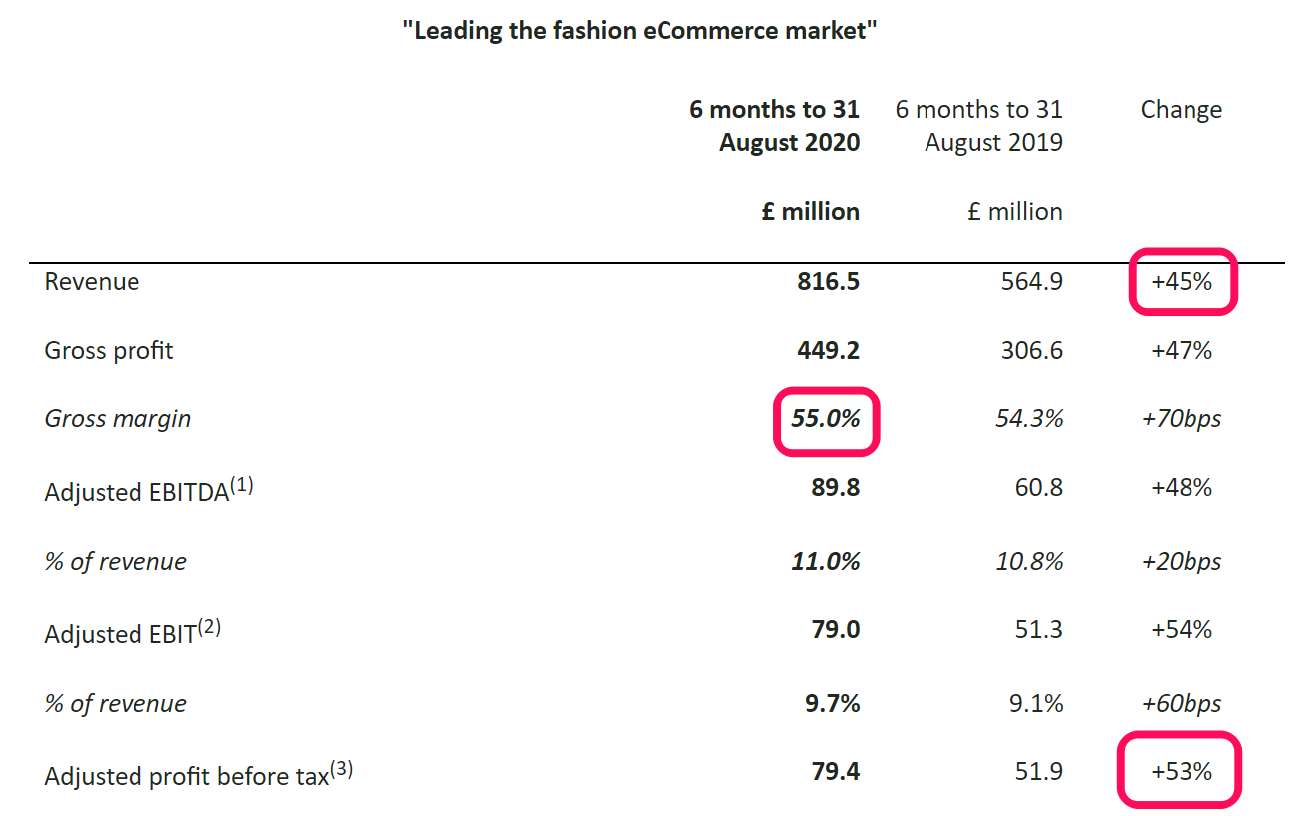
As you can see, the growth is highly impressive, given that this is now a sizeable group;
.
.
A couple of comments from me;
Note the gross margin is strong, and has gone up a bit. There's some wholesaling activity, which is lower margin, so the retail only margin will be higher still than the reported 55% total.
Looking back at the Q1 (Mar-May) trading update published on 17 June 2020, it also reported +45% revenue growth. That was during lockdown though. Hence there was a question mark over whether Q2 would see growth slowing, given that physical shops re-opened. That BOO maintained +45% growth, despite its competitors coming back, is really impressive. BOO seems to have generated its own momentum, and doesn't seem to be affected by what the High Street does.
Guidance is raised for the full year, FY 02/2021;
Group revenue growth for the year to 28 February 2021 is expected to be 28% to 32%, up from approximately 25% as previously guided, with adjusted EBITDA margin for the year at around 10%, increased from the 9.5% to 10% as previously guided. The group has made a good start to the second half of the year, with momentum continuing into September...
That bar looks set low, because H1 revenue is up 45%, hence 28-32% full year implies a big slowdown in growth in H2. History shows that BOO tends to under-promise, and over-deliver.
Its test & repeat model means that supply can be quickly adjusted not just to fashion trends, and repeat orders for bestsellers, but also can be quickly adjusted according to overall macro conditions. Compare that with the big problems physical retailers have with planning product deliveries months in advance.
Downside risks mentioned are;
- Possible downturn in consumer demand in H2
- Returns rate going back to normal levels
- Carriage costs increasing in some overseas markets
- Higher marketing costs in H2 (although that is what drives higher sales, so isn't necessarily a negative)
- Higher capex, to continue automating warehouses, and other IT spend
Medium term guidance unchanged;
Our medium term guidance for 25% sales growth per annum and a 10% adjusted EBITDA margin remains unchanged.
Webinar - I'm going to watch/listen to the analyst/investor webinar at 09:30, if you want to join here are the details;
boohoo group plc will today host a video webcast for analysts and investors at 9.30am (UK time) via the following link:
https://webcasting.buchanan.uk.com/broadcast/5f60844783507b593b4677e3
A replay will subsequently be available from 12 noon via the same link.
EDIT: the webinar has now finished, and it was really excellent, covering a lot of stuff about the new brands acquired, supply chain & margins, etc. Basically what I've been saying here all along is correct - that margins in Leicester are worse than from overseas factories, but it's used for speed & convenience. It's obvious management are very serious about fixing the supply chain problems in Leicester. So that's a dead issue now in my view. The recording is now up - click on the same link above, which will now take you to a recording of the webinar. End of edit.
My opinion - super-bullish, as I've been constantly saying here in recent months. I see this as a unique business, with unstoppable momentum in trading, and expansion. The multi-brand approach, and soaring international sales (now nearly half the total, and growing faster than the UK), mean that this is an almost unique growth proposition.
I think this is a hold forever position for me now, irrespective of valuation. Even if the valuation does become stretched (which it isn't now, in my view), then the group grows into it so fast, that pullbacks are just pauses in the bigger picture.
There's a lesson from the chart below - ignore the background noise, and focus on the company's strong fundamentals.
.
.
The rest of the accounts look clean to me.
My opinion - I think it's heading for 10p per share EPS, and probably double that within another 2-3 years. Hence I reiterate my view that this share could be worth 800-1000p in the medium term.
.
Air Partner (LON:AIR)
Share price: 73p (down c.5% at 11:37)
No. shares: 63.6m
Market cap: £46.4m
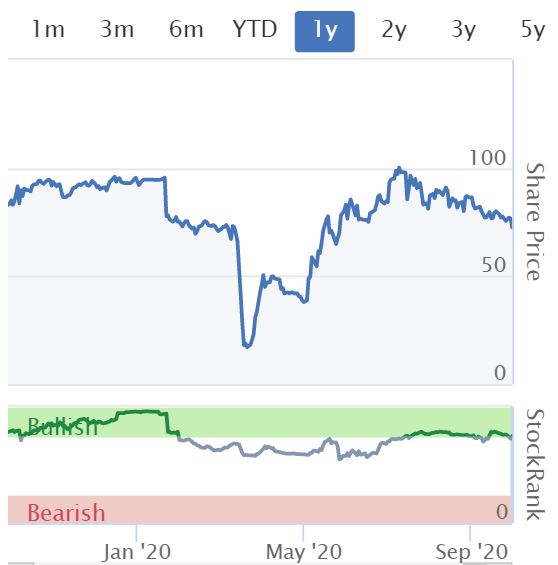
This air services group has updated the market frequently this year, flagging up that H1 would be exceptionally strong, with the outlook for H2 more hesitant.
As I reported here on 2 July, the company indicated it had made at least £10m profit in the first 5 months of the year.
Another update I covered here on 15 July, said that July trading was normalising, and the outlook uncertain, and costs having been cut.
Well done to the company & its advisers for being very open about the one-off nature of its H1 trading boom, and thereby keeping investor expectations grounded. The key boost seems to have come from repatriation flights due to covid, and air freight of medical PPE.
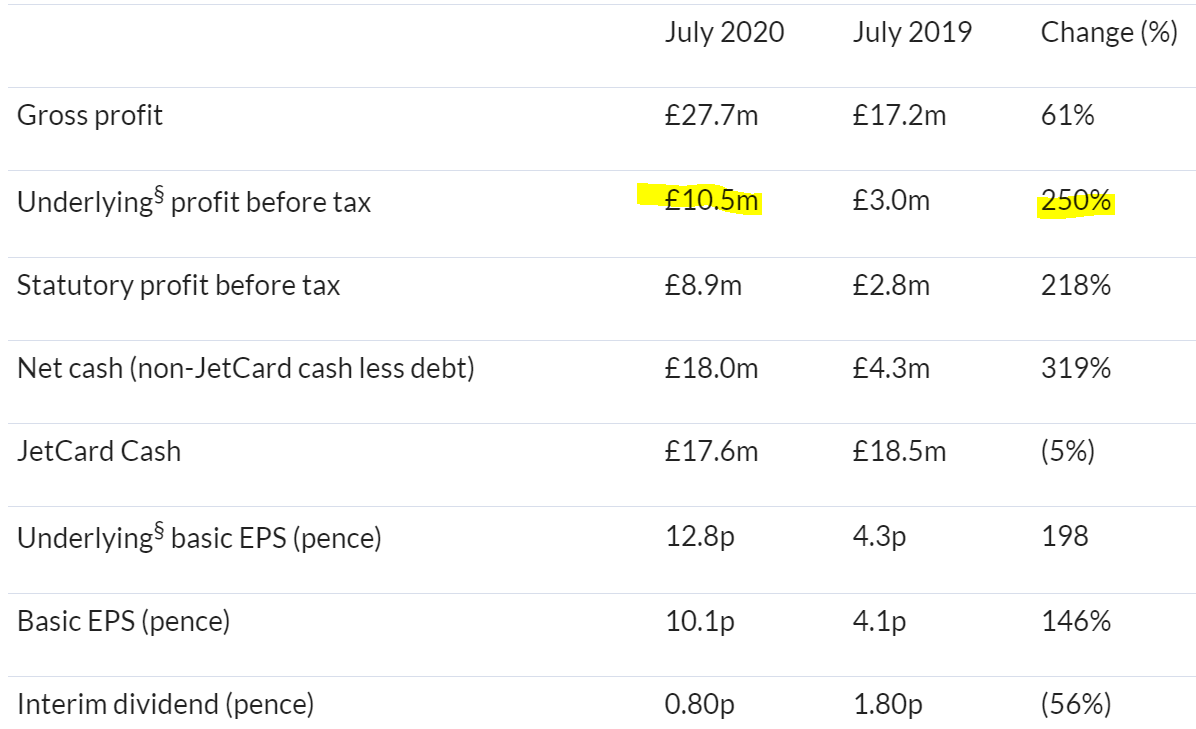
The H1 figures do indeed look marvellous as expected;
.
However, since this a clearly one-off blowout performance, we should not be valuing the company on any multiple of these numbers. That said, my view is that the company was able to profit from the crisis so significantly, is impressive. Clearly there must be some entrepreneurial people at AIR, able to fix up shrewd deals, which are the type of people I like to back.
Also we could see a similar crisis in the autumn/winter, if covid once again worsens, which is looking increasingly likely of late. Other parts of AIR have struggled though, so it's not a case that all divisions are doing well.
Current trading sounds nothing like the H1 boom time;
· Gross profit for the first two months of Q3 is down year-on-year, although this has been offset by a reduced cost base and governmental support across our various markets, where available
· Private Jet enquiries continue to increase from the low levels seen in Q2
· COVID-19 related activity in Group Charter and Freight has now stabilised, albeit against a rapidly changing market environment
· Visibility in Charter remains limited, however we are seeing some green shoots of recovery within the Safety & Security division
Outlook - only a "modest profit" in H2;
...although the continual, and often sudden, changes in the COVID-19 operating environment make it very difficult to predict the remainder of the financial year with any degree of certainty. As a result, we will not be reinstating market guidance beyond the end of this financial year, although we do expect to report a modest profit for the second half of the year.
Dividends - resumed, but lower, which doesn't send a great signal;
interim dividend of 0.80p per share, down 55.6% from last year's 1.80p. The Board's objective is to establish a level of dividends that is sustainable, well covered by the Group's earnings, and that can be increased over time. The level of this interim dividend is consistent with this policy.
Balance sheet - is not actually that strong overall, NAV: £21.8m, deduct £19.3m of intangibles & goodwill, gives us NTAV of only £2.5m. And remember that is after £7.05m (from cashflow statement) from issue of new shares. Without that, NTAV would have been negative.
The balance sheet is flattered by favourable working capital. But remember that all the cash is spoken for, either belonging to other people (see deferred income) or will be needed to pay other creditors.
Current assets: £46.3m
Current liabilities: £(45.8)m
Net current assets: £0.5m
The above figures demonstrate that the cash piles are spoken for, and are not surplus assets.
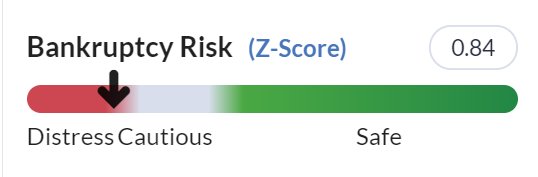
Altman agrees, with a weak reading on the Z-score. Although this will probably not include the most recent placing, which is likely to have moved it out of the distress, and into the cautious zone, at a guess.
.
My opinion - a fantastic H1 performance, but very much one-off in nature it seems. I think the best way of looking at it, is that H1 was a bonus for the company, has helped strengthen its finances, but shouldn't be used to value the shares.
Given the above, I reckon the valuation is currently probably about right.
If you're gloomy about covid, then AIR could be a beneficiary again from one-offs. Although do bear in mind that its other divisions could suffer from reduced travel if covid worsens in future. So it's not a one-way bet re covid, something that is explained in the commentary today from the company.
The forward looking metrics don't look realistic to me, in terms of the 2021/22 earnings forecast, so caution is urged there.
.
.
** BREAKING NEWS **
Tasty (LON:TAST)
2p - mkt cap £2.8m
Update
With such a tiny market cap, it's not worth mentioning for itself, but rather for the interesting read-across for other struggling hospitality & retailing companies.
My view is that restructuring though a CVA or the more risky pre-pack administration, is not just desirable, it's essential, for struggling companies with leases that tie them to now uneconomic rents.
If TAST can ditch its historic leases, and reset the viable sites onto lower rents, then it could be a long-term survivor. I wouldn't buy the shares personally unless/until that step is taken, as mentioned before. Even then, with a market cap this low, there's a significant risk that, as part of a restructuring, management might also decide to cut costs/hassle, by de-listing.
Anyway, this is what the company has said today;
In light of the continued economic uncertainty and the impact of COVID-19 related restrictions, the Company has secured a £1.25 million, four year term loan from its existing bankers, Barclays Bank plc (the "Facility"), in order to strengthen its balance sheet and provide additional working capital support.
The Facility is available to be drawn down until 7 February 2021, however, draw down is restricted until the future of the Company is assured through restaurant closures and creditor arrangements. The Facility has a capital repayment holiday of 12 months and carries interest at a rate of 4.5% per annum over the Bank of England Base Rate, following draw down.
The Board of Tasty confirms that, whilst no decision has yet been made, it is continuing to work with its advisers, KPMG, to assess the potential impact of COVID-19 on the business and the various strategic options available to the Company, including a potential company voluntary arrangement.
The Company will commence consensual negotiations with landlords and other creditors shortly and anticipates that this process will be completed by the end of November 2020. The Board believes that given the recently announced additional COVID-19 related regulations and the probability of future tighter restrictions in the near future, all potential options should continue to be explored but, with creditor assistance, a more formal procedure may be avoided.
Cleverly worded but to my mind, that is as clear as day, that Tasty is saying to landlords, that we need you to agree to rent cuts, or we'll do a CVA.
The problem generally, is that whilst many landlords are being co-operative, there are enough who aren't to make a consensual, informal process very unlikely to succeed. I mean generally, as obviously I don't have any inside knowledge re Tasty.
Therefore, I think we should work on the assumption that Tasty is very likely to do a CVA in Dec 2020, or maybe earlier. This would enable it to ditch non-viable units, and secure viable rents on the remainder. At that point, it would look like an investable business to me again, providing there is some assurance that it's going to remain listed.
Key point - CVAs or pre-packs are now the only viable option for struggling multi-site operators in hospitality & retailing.
So far we have;
Quiz (LON:QUIZ) (I hold) - already done a pre-pack, and has got remaining shops onto turnover rents, ditched shops that were not viable.
Revolution Bars (LON:RBG) - considering a CVA (very likely to happen, in my opinion)
Tasty (LON:TAST) - as above, sounds like a CVA is on the way.
What's particularly interesting with TAST, is that the bank is making drawdown of the loan dependent on getting some kind of restructuring done. Very sensible on the part of the bank! It suggests that banks are seeing the sense in their clients doing CVAs, and are supportive of this being done.
New Look was an interesting recent example of a CVA that succeeded, despite several big name landlords publicly condemning it & voting against. When push came to shove, the landlords backed down and voted for it, because they didn't want empty units, even if the terms of the CVA were unpalatable.
So many private companies are doing CVAs at the moment, that it's difficult to see how listed companies that are struggling can avoid following suit. I wish French Connection (LON:FCCN) (I hold) would get on it with it, and restructure, it's long overdue. With Hilco (a restructuring expert) having recently extended a new asset backed loan to FCCN, I hope very much that it is trying to persuade the CEO to ditch the problem leases through a CVA. Then the company/shares could have a much better future.
We'll see a lot more of these restructurings, I reckon. There could be some excellent investment opportunities, so I'll be watching closely & assessing them as they arise.
.
Topps Tiles (LON:TPT)
Share price: 49p (down 6%, at 14:53)
No. shares: 195.0m
Market cap: £95.6m
Strong finish to the year, modest pre-tax profits expected
Topps Tiles Plc (the "Group"), the UK's leading tile specialist, announces a trading update for the 52 week period ended 26 September 2020.
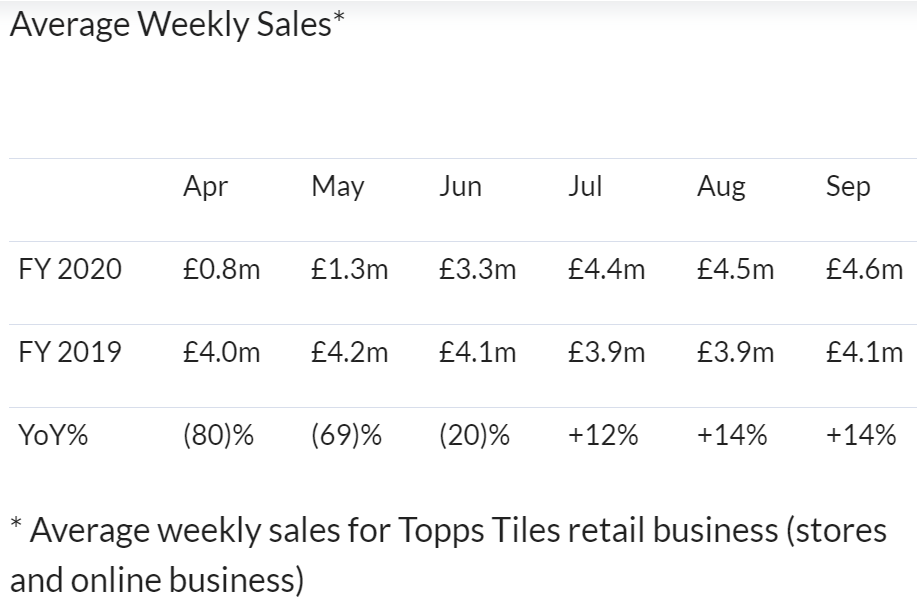
There's a very clear table given, so we can see the monthly trend of retail + online sale over the last 6 months. Top marks for clarity here;
.
As you can see, sales were badly impacted in lockdown, and since re-opening the company is recouping some lost sales, although nowhere near as much as was lost previously during lockdown.
Current trading sounds OK for retail (the main business);
Our order bay2 at period end was significantly ahead of the prior year level, providing a positive outlook as we start the new financial year.
2 Orders received from customers which are in process but not yet fulfilled
The commercial business is rebuilding more slowly, but it's immaterial at just under 4% of total revenues for the year.
Liquidity sounds fine, and it's great to see the company quantifying the short term benefits from Govt support - all companies must do this, as it's key information we need to know;
At period end the Group had c.£25 million of net cash and available cash headroom of c.£74 million within its financing facilities. This includes around c.£7 million relating to year end working capital timing and c.£6 million relating to VAT deferrals, both of which will represent cash outflows in the new financial year.
Outlook - most companies are including words of caution, to cover themselves in case covid conditions worsen, so I don't see anything company-specific to worry about below;
"I remain very positive about the longer term outlook for the Group but also recognise that the continuing impact of the Covid-19 pandemic may lead to more difficult trading conditions over the short to medium term. As market leader, and with our strong balance sheet, the business is well positioned to navigate these conditions and to meet future challenges."
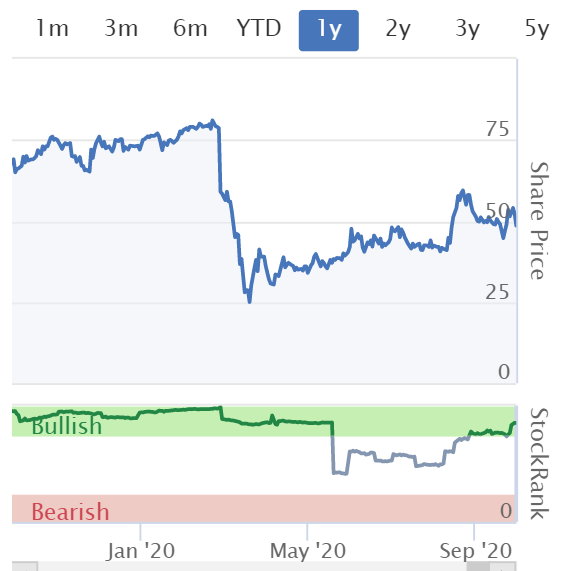
My opinion - I don't see anything in this update to justify a 6% fall in share price. Maybe some punters just decided to bank profits after a reasonable run of late?
Maybe it's the reminder (already known) that FY 09/2020 is only likely to be slightly above breakeven, that triggered profit taking? I don't know.
The last balance sheet was OK, not strong particularly. The sale & leaseback of property has helped liquidity since then.
I tend to blow hot & cold on this share. I imagine it should produce better results in FY 09/2021, and we know that it can withstand lockdown without serious damage. So I can see the merits of the share, but it doesn't excite me at all, so would rather keep my money in other things with perhaps more upside? Not that there's anything wrong with TPT. There's also the issue of the leases. It's trading too well to be able to restructure them probably. Whereas weaker competition might be able to do a CVA and thereby gain a competitive advantage?
.
.
N Brown (LON:BWNG)
55p (up 8%) - mkt cap £156m
This has been slowly ticking up in price on my screen today, so thought I'd better take a look at its trading update.
To save me re-typing it, here's a picture of the highlights;
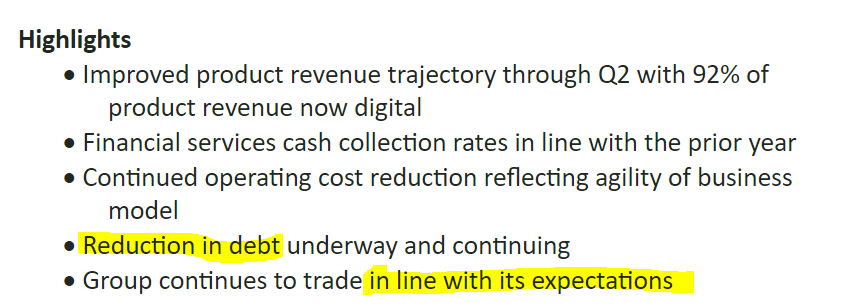
.
This share was being shorted a fair bit earlier this year, and it was a nice little trade, buying for a short squeeze, which paid off. Maybe the same thing could be happening again?
My opinion - neutral. I find it too difficult to come to a firm view on this company. The problem is that, whilst product sales are now 92% online, it doesn't really make any money from product sales. Instead, the highly regulated and expensive consumer credit offering is what generates the profit.
It looks cheap on a low earnings multiple, but are those earnings sustainable? Who knows?
The balance sheet has a very large consumer receivables book, mostly funded with bank debt. So maybe you need experience of the financial services sector to properly understand the risk:reward of BWNG's business model? Not my specialist area.
On balance, I'd be more inclined to be long, rather than short, but overall just think I'll focus on other things I understand better. Today's update sounds mildly reassuring., but doesn't particularly change the investment case either way.
.
Pressure Technologies (LON:PRES)
64.5p (unch) - mkt cap £12m
I hadn't realised how small the market cap had got when I put this on the list.
Today's update seems to be a profit warning, disguised as a contract win announcement!
... a loss-making performance at Group level is expected for the current financial year.
I don't think I'll cover this company again, as its performance seems too erratic, since it's dealing with quite big, specialised engineering contracts.
.
Studio Retail (LON:STU)
248p (up 6%) - mkt cap £214m
I've had a very quick look at the trading update from this unusual group, which shares some similarities to BWNG's business model - selling products online, but profits coming from offering consumers credit on them. It used to be Findel. There's been a long-standing disposal which has been held up for ages by regulatory issues. Also I can't remember what the £20m covid bad debt is, but it's material, so I'm flagging it.
I'm not going to look any deeper into this, but readers might want to, because this sounds encouraging;
... we currently expect the adjusted profit before tax from continuing operations* (including the impact of IFRS 16) for FY21 to be ahead of our previous internal expectations.
.
That's me done for today, see you in the morning!
Best wishes, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

140 comments
I see it got a bit fraught about Orangeman in here today with a covert Russian operative shutdown. Well he's going to win the election...all that happened last night was that Biden didn't blow it all at once. The positive reception for Biden is a lot that he wasn't as weak as feared. But his head is now above the parapet and has got to stay there with The Donald on a relentless Biden hunt with his magic 47. Time for us in the UK to pucker up...
https://medium.com/@mojomogoz/...
I know you'll disagree with me...but hey...I was feeling discordant as wanted to post re a stock that reported today and got very low attention so on to the main thing...
What if I said you can have 14% 3yr sales cagr, mid 40s op margin, p/e less than 7 and dividend yield above 7....high quality, with good growth and very low valuation. Jeez-Louise! Too good to be true?...
Well yes it is...if you believe that being in the financial sector doing something fairly traditional rather than whizzbang is a reason to shun something. Clearly a lot of people think this.
S&u (LON:SUS) reported interims today. Its primary business is hire purchase on used car purchases for non prime borrowers (up to £15k loan with c.£6k typical, typical c.17% flat rate or c.35% APR). It also has an organically developing property bridging loan business too (retail and typically c.£450k I believe from memory). Both types of lending are asset backed providing useful recourse.
Today's interims show that business stayed 100% operational during covid and traded successfully (although clearly there was a big reduction in new business for period).
Dividend continues to be paid but was cut by a 1/3 at moment (I guess that will be temporary). EPS for half year are down 2/3 but that is entirely driven by prospective provisioning for any loan problems coming out of Covid...this is much much worse than performance to date but is prudent. Cash flows were strong although there was a £9m reduction due to payment holidays granted (FCA mandated that these be offered so at peak they had 25% of clients on them).
Loan performance continues to be good. Lending is back to 80% of what it was pre Covid. It could have exceeded 100% based on demand but the company has tightened lending standards and move closer to prime being cautious to assess ongoing conditions. Collateral for loans has effectively strengthened with second hand car values up c.14% as supply struggles to keep with demand. Perhaps, most interestingly is that demand is particularly strong for sub £5k vehicles and over 7 years old (supposedly some people looking for 2nd and 3rd vehicles to avoid public transport and lower income people looking for a personal travel option too). This reduces some risk from lowest quality borrowers particularly where their loans have aged a couple of years (NB a new loan is higher risk as depreciation of vehicle will initially be quicker than the recoup from flat interest rate but then the latter years of the loan become very profitable as principal is worked down and the collateral value of vehicle remains...which now has a stronger market for it too).
And the future is much brighter. Some less well run lenders (there's always a lot of them) will either close or wind back business. High St banks and mainstream dealer finance will narrow its definition of prime customer so pushing higher quality than normal customer to S&U.
What about their debt? Well if you look at it correctly for this type of business you see that debt level is really low. They have retained and growing cash that they effectively continuously recycle into more loans (after paying fairly chunky dividends too). Its hard to exactly pin down due to the way that principal runs down but interest payment stay flat but gross receivables (which is an amount inc discounted interest payments minus adjustment for expected credit losses) are c.£280m with £108m of debt against that figure. Off balance sheet there is effectively an asset which is all the cars they have lent against (ownership transfers at end of hire purchase upon payment of transfer fee...c.£200 I think)...in last 3 years they've advance c.£420m (they'll have loans up to 5 years but using 3 as a proxy for some short term loans and/or early payback etc to be conservative about 'off balance sheet collateral')....anyway, its a long winded way to say that S&U are running a considerable float that provides both risk buffer and increases margin (plus ensures their funding is at low interest too).
This is what high quality durable franchise looks like...but everyone just hates it right now. S&U is perhaps one of the easiest high return options in the market right now...unless you think we are headed for a depression (....but then you should worry about ratings on some more glamorous names and S&U probably carves out solid business in harder times too and takes market share). You get a non distressed and high quality company at distressed type pricing. TBH it struggled to get above 12x earnings in past 5 years despite performing well...I think that's clearly sector dislike. Capital cycles turn and the love moves...
You're welcome.
I’ve looked at this share previously and the only thing that put me off investing was the 17% free float. The rest is owned by the directors and a Jewish faith charity. You might be entirely happy with this and I am all in favour of the directors having aligned interests with private investors, but I felt in this instance, the balance of alignment was far too skewed in favour of the directors.
Free float is a bit higher but yes a Jewish charity is biggest outside holder at near 20% and then the Coombs family own north of 40% so I make it getting into the high 30s in terms of other shareholders. But it tends to be a very steady and loyal base it seems.
Coombs family have owned the antecedent businesses since 1938 - started as store in Midlands, expanded into a bit of related manufacturing, listed LSE 1961, move into home credit in 1975 (around the time of liberalisation of credit which actually started with Labour govts before Thatcher), founded Advantage Finance in 1999 (now main business non prime car finance), sold home credit in 2015 to Non-standard Finance (LON:NSF) for £82.5m (NSF have been writing off goodwill since) and started Aspen Bridging Finance in 2017 (growing it slowly but successfully).
This looks like v good long duration stewardship that benefits from the family's oversight, strategic abilities and steadiness of leadership. They have made a few but very good shifts over time. Don't sprint, stay on focus, look for high margin business. The move out of home credit was particularly adept as it seemed to see the regulatory stresses coming. That said home credit is the highest quality part of the NSF business (and probably no coincidence that the new CFO who has been busy tidying up the balance sheet comes from that part of the business) and has buy and large avoided regulatory opprobrium.
The twins that run it now are 67 so there will be some transition at some point in future and this may loosen up some shares.
What do you reckon? If S&U were a tech business or niche manufacturer people would look on the founder involvement and stewardship more positively...alignment etc...
The price for this stable very high quality biz is silly. The future has just got brighter for it to (harder times create growth opp).
PS the company have certaintly been very accommodating in answering my questions. Some of them were reasonably involved and they gave quite specific answers rather than generalised handwaving that comes from others (looking at you PCF...see comment in 1 Oct SCVR). They seem to value shareholders...
thanks for this; one of my bigger holdings and has been a great source of dividends for me over recent years. Reinvested them.
They are doing a presentation on investormeetcompany on Friday morning and I personally find a good sense of alignment with the director - shareholders. Listed and run by the same people for many years. Sleep at night investment for me because they run a tight and focussed ship.
This is one which Maynard Paton follows on his excellent blogs; difficult for me to add much over what he and you have said
Agreed. I'm a johnny come lately shareholder though only building my position in the last few months so I missed out on the good stuff earlier on...but today it seems Mr Market wants to give me a chance at redemption...
Boohoo
What is your view of the impending court case in California?
A few days ago you said you were going to join a PMP webinar and report but I don't remember seeing your subsequent comment Paul. Is it too late to share your views now?
Hi brownrigg,
(I hold PMP shares personally)
There was nothing particularly of note in the Portmeirion (LON:PMP) webinar, but it was interesting, and useful for better understanding the business.
You can see the recording here on InvestorMeetCompany. The new CEO seemed a bit on edge to start, but soon got into his stride. I thought he was fluent & strightforward.
Incidentally, I'm recording an audio interview with him on Friday this week.
Regards, Paul.
Paul, FYI, I wrote in 3 questions for Portmeirion (LON:PMP) before for the InvestorMeetCompany webinar and heard all 3 asked - even my tetchy plea for why they did not simply use some simple tables in the trading release instead of or to accompany words that I'd only hoped would be read!!
InvestorMeetCompany looks a great free service for private investors to connect with companies and I promised to say so on here!
FWIW, I also hold PMP and thought the strategy update useful and more focused than in the past eg focus on online sales and 2-3 new 'big markets' from ROW to add to US/UK and Korea. Not rocket science but then again selling crockery isn't either. I also liked the simple pictures showing where the CAPEX was going reassuring. I hasd worried they were being sucked into a hand sanitiser bubble.
I think the business is tailor made for personalised sales and online collections in the long term and could easily double in next 2-3 years (where it would still be below its peak,
Boohoo (LON:BOO) (I hold)
Does anyone know why AP has increased so much?
I'm a little confused by the massive jump.
Does anyone know if this was asked on the call?
Hi abtan,
I cannot remember this being discussed on the Boohoo (LON:BOO) webinar.
I've had a look on the balance sheet, and I think the increase in Accruals could be linked to the big increase in inventories, perhaps? Inventories rose £74.1m comparing H1 with 12 months earlier.
Whereas if we add together Accruals & Trade Payables, the totals are £213.7m this year, and £132.8m a year earlier, an increase of £80.9m, which is close to the increase in inventories. Also remember that trade payables would include VAT, whereas inventories doesn't.
Carol Kane did mention today in her section of the presentation, that the new brands added (e.g. Warehouse & Oasis) involve a huge expansion in product lines, from a couple of hundred, to over 1,000, if I remember correctly. Given that sales increases would lag inventories increases, and that sales increases would only show for part of the year in the P&L, but the balance sheet shows the full year end position, then there could be a mismatch there.
Also, I think accruals is a catch-all term for other business costs, e.g. accrued holiday pay not taken by employees, anything (e.g. capex) that been incurred but not yet billed by the supplier, gift vouchers unredeemed, and all sorts of things like that.
It would be nice if we had more granularity on numbers generally from listed companies.
Overall, I can't see anything that jumps out at me as looking suspicious or wrong in the Boohoo (LON:BOO) accounts.
Regards, Paul.
Boohoo (LON:BOO)
Thanks for taking the time to respond Paul.
I agree, there doesn't seem to be anything untoward in today's accounts (other than the lack of splitting out by brands, which I liked).
I'll hopefully get a chance to listen to the call later.
Cheers
A
Boohoo (LON:BOO)
Abtan
Provision for Liabilities is presumably for returns (longer returns policy)
Per the last annual report provisions for liabilities was primarily returns but alos included dilapidations provision (£4mill last annual report)
It was explicitly confirmed in announcement today that returns provisons are higher
Returns provisions are higher due to the longer time we are giving customers to return product and the longer time it is taking to receive returns, especially from overseas.
Accruals is for....inventory?
they confirmed the following in the announcment today.
with high levels of trading activity driving increases in returns provisions and payables and accruals for inventory and goods in transit.
Accruals will likely also have other random odds and sods inluded.
In some respects an increase in provisions and accruals is somewhat pleasing - these provisions reduce profits so the fact that they are in at a high "warts and all" total suggests they are not pimping the numbers to flatter the profits. It tends to be the provisions entries on the accounts that are most easily manipulated if they were wanting to flatter the numbers for whatever reason. a bit of expalined natural variability is fine by me. Thats total idle speculation on my part in that regard.
Trade payables is for factory owners?
i would guess its primarily for stock.
From memory (its a while since i sold out of boohoo sighhhhh) i always thought that the Boohoo accounts and balance sheet were much more pleasant reading than ASOS reports - that suggested that they had nice tight ship. I know asos have materially higher sales but there stock is over £500 mill per last annual report - so guessing comparatives will still be favourable for boohoo.
Boohoo (LON:BOO)
Thanks for taking the time to respond.
I guess my main question is what's the difference between Trade Payables and Accruals here? I did check the report today and the last annual report and I didn't think it was very clear.
I think Trade Payables are invoices that Boohoo (LON:BOO) has received, but not yet paid, whereas accruals are (mainly) invoices that haven't been received yet, but which the company is, well , accruing for. They are essentially for the same thing, but are confusingly separated for clarity.
Does that sound right?
If others agree, then that's fine I guess, but it seems an overly complicated way to split out inventory costs on the balance.
A
Boohoo (LON:BOO)
Abtan
I think Trade Payables are invoices that Boohoo (LON:BOO) has received, but not yet paid, whereas accruals are (mainly) invoices that haven't been received yet, but which the company is, well , accruing for. They are essentially for the same thing, but are confusingly separated for clarity.
Yes you are 100% correct in your assumption - I don't think there is anything particularly confusing here - other than the fact its the sum of the two parts that matters so as you need to add the two together an extra calculation is there that you probably feel is more harm than good. It's very standard procedure though to have payables per billed invoice and separate accruals total being expenses that relate to the year but not billed (eg accountancy fees - last months energy bills if paid month in arrears etc etc) . It's certainly not a boohoo oddity that they have payables and accruals having both is the norm - albeit their accruals total is higher than the average bear booboo.
I certainly don't remember splitting out accruals from invoiced payables when I was making postings, especially when they related to the same thing - the liabilities just went into the same pot.
In any case, I think we agree that it's probably no big deal.
Thanks for your assistance.
A
Given that a bear market is defined as a 20% or greater correction then the FTSE 100, 250 and All-Share are still in bear markets.
AIM has recovered well YTD having sold-off the worst: it's flat on the year
The NASDAQ is up 30% YTD with the S&P up 3% while the DOW is lagging as it is weighed-on the industrial, oilers and transport components.
Market breadth in the US is incredibly narrow with a small number of now huge stocks flattering the indices. 303 of the S&P 500 have lost money YTD of which 156 are down 20% or more so in a bear market .
By contrast in the S&P $AMZN up 66%, $AAPL, $NFLX up over 50% .. Definitely a market of stocks rather than a stock market.
As an addendum, here's a sector view of the UK for 2020: of 1900 stocks, 1360 have lost money in 2020. Again, big winners have won big with the likes of £NYCT, Synairgen (LON:SNG) and £7DIG up over 1000% YTD
Hi Paul and by extension Graham, Jack. A big thank you for your valuable insights , energy for the daily SCVR - you're collectively a great catalyst for healthy insight and debate to this community. Very much appreciated! A good coffee and the SCVR - always something to learn and ponder (on). Phil
How kind, thank you Phil!
It's just me & Jack now, as Graham moved on to concentrate on his own website, after several years sterling service here!
Hi Paul, with you asking for readers opinions, "What do readers think? Are we in a bear market now, I wonder," my opinion is that so long as there isn't another national lockdown then I believe the market will continue to drift sideways or dip slightly over the next 6 months or so, until either the warmer weather arrives and cases drop or hopefully a vaccine is announced but I could equally be wrong because nobody can predict the future. Every year when asked what I would like for my birthday, I always asked for a bottle of hindsight!
Regards "Buying the dip" or "Sell the rallies", my plan is to ride things out. The majority of shares which I hold pay dividends and have heathy balance sheets. Hence, I plan to ride out the up & down fluctuations in the market and collect my dividends each month.
A while ago, I remember hearing an interesting piece of information (please correct me if I am wrong), that since the end of WW2 there have been something like 38 corrections in the stock market (a correction is defined as a drop or 10% or more). Out of those 38 corrections, the stock market has made a full recovery 38 times out of 38 and then gone on to set new highs. Hence, the reason why I plan to ride things out and collect my dividends.
For what it is worth given the well known challenges of predicting the markets direction my view is if the Democrats win the election there will be a drop back as their agenda will involve higher taxes and the risk of moving to a greener business model, be it environment or care. But I don't believe it will be significant given the alternative places for money to go. If Trump win s the feeding frenzy continues although I have to say he seems to claim a lot credit for what is an ongoing cycle.
Saw this chart on Fintwit last week, quite interesting!
Trump win, it's a rally. Biden wins it's a decline.
I don't think they'll find any useful precedents for a situation where the incumbent loses despite having tried their best to pervert the electoral process and refuses to give up office.
I read at the weekend that if Trump does lose and does refuse to give up office he will be escorted from his office by a number of military generals. That I would love to see.
- and the enemies of the western democratic model would love to see it as well.
Hi Forbsy,
I heard something similar at the very beginning of the USA elections, which was along the lines of... over the past 30 years or so, if the USA markets rose from the start of the electioneering in September until the voting in November then 88% of the time the existing President (Trump) would be re-elected. Also, if the markets fell between September and the elections in November then 88% of the time the opposition (Biden) would be elected. Lets see if this continues to be case.
Que? The generals would be upholding the western democratic model.
Mexican generals could be cool with plumed hats? - bit camp. Take him to a door in a big wall and leave him outside..anyway I digress. apologies
Biden did say that but the generals said they would have nothing to do with it and would leave the situation to the politicians to sort out.
Paul, re market thoughts,
I have taken great heed of Mark Dampier's market forecasts through the years in relation to the markets, he's been generally spot on in my view historically. He's written an update in the HL half yearly magazine with his forecast on the market this decade and sees it thus:- in the short term he sees the markets going up led by the US, followed by a period of deflation and a heavy stock market fall possibly even as early as this year, central banks and governments will do all they can to stop it but in his words this will sow the seeds of double digit inflation later in the decade, let's face it inflation is the obvious way of bring into proportion the huge debt deficit the world carries, gold I guess would be a good long term investment then
I notice both he (Mark Dampier) and another of my favoured fund managers Giles Hargreave are both retiring, whilst they give different reasons for their move I wonder if they are being visionary and insightful in sensing that we will at last be seeing the end of the 40 year bull market
You wouldn't know from reading the HL magazine piece that Dampier's decision to retire follows the debacle where HL were over enthusiastic cheerleaders for Woodford's funds.
Would appreciate any thoughts from more experienced chartists than myself but as I see it at the moment, with the SP500 now sitting below the 50 day SMA, downside is more likely in the short/medium term. However, until it closes below the 200 day SMA (currently around the 3120 level), it is not a bear market.
I'm watching to see if price level around the 100 day SMA holds in the first instance, as this level appears to have prompted the 'buy the dippers' previously, before taking a grimmer view on general market outlook.
Short term MA's also suggesting downside risk following the crossover in early Sep.
Hi Forbsy,
My take on it is that it will not be a Down Trend until the 3000 level is clearly breached.
Thanks for AIR update. So tempted to jump back in on the fall this morning, but the trend has been falling against a lot of positive noises since the summer. To be fair they have indeed been pretty open keeping the market updated about the business. Too easy to focus on the good news sometimes. I think your assessment is spot on and where else can we get some unbiased forensic financial investigation! Invaluable .
Even if there is a resurgence in Covid, I struggle to see Air Partner (LON:AIR) having a second bonanza. Its main source of super-profits in H1, as far as I understand, was delivering PPE and repatriation flights. It is difficult to see a second surge lead to such a worldwide hand-to-mouth situation for PPE. Also, in the event of a second surge, there are likely to be far fewer people caught unawares abroad needing repatriation - and those that do will probably garner less sympathy from governments, as their situation could have been said to have been predictable.
Hi Paul,
Interested whether you have any comment on the M&c Saatchi (LON:SAA) RNS today:
Update on 2019 audit & preliminary results
...I know you mentioned this looked potentially interesting recently. It reports new business doing well, particularly Australia - US business down. That said results are still delayed and shares will be suspended tomorrow until publication.
The news media find it difficult to assess the significance of COVID developments, perhaps not surprisingly as there are so many of them, but today might be regarded as quite a positive day in the pandemic as the results from Regeneron Pharmaceuticals' REGN-COV2 antibody cocktail drug are positive. This drug specifically targets SARS-CoV-2 and, importantly, showed strong results in patients who appeared unable to mount an effective immune response themselves. I am invested in a number of biotech shares including Regeneron but I am pointing this out owing to its significance for the pandemic as a whole rather than any investment opinion. Eli Lilly also recently had positive results for a similar (in principle) drug which I believe is at an earlier stage so this approach seems to work. The next stage is for Regeneron to interact with the regulator but I anticipate that the eventual problem may be not with approval, but rather the inability to produce large enough quantities of the drug to make a difference. I note that the Novartis CEO said today that it will take more than vaccines to fight the pandemic and that "treatments will play a crucial role". He reckons significant supplies of highly effective vaccines probably will not be available until the end of 2021 and he is in quite a good position to judge this.
Boohoo (LON:BOO)
Connected to Boo is a piece by Aswath Damodaran, September 21, 2020.:
“Companies have come under pressure to adopt reforms in the areas of environmental, social justice, and corporate governance, known collectively as "ESG". Professor Damodaran takes a look at this movement and notes that while ESG may make money for consultants and bankers, there is too much hype surrounding what it can be expected to produce for businesses and for our overall society. (Musings on Markets)“
http://aswathdamodaran.blogspo...
It is a very good piece but very long!
He concludes:
“Much of the ESG literature starts with an almost perfunctory dismissal of Milton Friedman’s thesis that companies should focus on delivering profits and value to their shareholders, rather than play the role of social policy makers. The more that I examine the arguments that advocates for ESG make for why companies should expand mission statements, and the evidence that they offer for the proposition, the more I am inclined to side with Friedman. After all, if ESG proponents are right, and being good makes companies more profitable and valuable, they are on the same page as Friedman. If, on the other hand, adopting ESG practices makes companies less valuable, the onus is on ESG’s proponents to show that societal benefits exceed that lost value.”
The company I work for makes the ridiculous claim that companies that are diversifying the workforce makes 10x the profit. They never give any sources or links to the “research” though.
on a similar note, this clip from The Week magazine.
Excellent post R--G. It corresponds with Trumps claim that he is clever because he doesn't pay much tax? It shows he really has no understanding of society or responsibility. As we used to say on the Stock Exchange "always give a little back to the other guy."
Is this what you do? Do your tax return and then say you know what I'm going to pay a bit more this year and maybe I won't open an ISA? Bet you don't.
Thx R—G. The Week often sums things up very pithily.
Michael I am aware that like poor old DVB99 that the slightest negative comment about £Boo gets jumped on and frankly that’s silly. I’m not interested in buying the shares as I have question marks about its valuation and I hope that’s Ok with everyone!
But the ESG thing that keeps being mentioned is of interest. I wonder how many have actually read the last published accounts? There is page after page about it in there written by a Director of Sustainability. I’m sure Boo’s investor relations team were courting ESG funds and one large one did and then divested.
A company as large as Boo which could be FTSE 100 has to comply with the Modern Slavery Act. Boos business model is simple - buy to sell. They will pay as much attention to their supply chain as they do to selling. They aren’t a market stall. They are buying with contracts £15m of products a week. I think they probably had close relationships with some local suppliers. Maybe they relied too much on the relationship and too little on the sort of auditing practices other retailers of a similar size carry out.
By all means buy the shares but let’s not jump on those who think ESG is important.
You won’t get jumped on by me over Boohoo (LON:BOO) or any others stock. Or on ESG though we might well disagree. One of things on my check list is “what is the bear case (if there is one)”. I think a contrary opinion is useful. (Paul’s bear case on Globo saved a lot of people, certainly me, money.
IMO ESG has to be personal I think though of course certain things are off limits but if tobacco was off limits to everybody, as it is to me (I used smoke 60 a day BTW) then all the tobacco companies would have gone to zero.
But for when it comes to funds it is the hypocrisy that does my head in. When SLA very publicly dumped Boohoo (LON:BOO) I am fairly certain they were courting publicity and investors. Their ethical fund at the time held investments in BAT loan notes and BP.
Your criticism of Boohoo is not unreasonable but I am going to take it at face value when they say they are going to mend their ways.
They have grown Boo from a turnover in 2013 of £67m to £1.5b in 2021. That takes phenomenal amounts of management time, which is a finite resource. (I took my own business from a t/o of £37k to £1.3m in about 15 years it is a killer and things slip/are ignored). Maybe I making excuses but I am trying to give my perspective
I might be being naive or deliberately forgiving so that my conscious will allow me to invest in this superbly profitable company.
Anyway hope the reply seems reasonable.
Regards
Michael.
Thanks Michael (and Paul for your comments earlier on this). Clearly this is a divisive topic and I understand the dismissal of ESG when crassly or cynically undertaken, but in one form or another (e.g. responsible investing/impact investing) it is not going away as a factor in how the world will shift deployment of capital. One of the challenges of empirical studies currently is that the definitions and values are diverse and sometimes done in an apples and pears way.
For anyone interested in a counterpoint to Professor Damodaran have a look at Professor Edmans at London Business School who interestingly, whilst taking a very different view, starts one of his courses by getting students to read Friedman in order to ensure they don't knock down straw dolls.
BTW none of this is specifically targeted at BooHoo since I don't know the details there in particular other than how endemic the issues are in the fashion especially fast fashion industry as a whole.
Finally I would just like to say how much I appreciate the SCR Paul and especially upholding a forum for sensible discussion allowing for a range of opinions in a respectful way. I believe investing opinions should be strongly held but easily changed - I know I make investing mistakes so welcome alternative views to try and catch them earlier.
Thanks Dogon. I have a lot of respect for Damodaran but have not heard of Edmans. Do you have a link anything he has written in the subject. Thx.
Hi Michael,
There's a small TED talk here: https://www.youtube.com/watch?v=Z5KZhm19EO0
He's also written a book - Grow The Pie - see a couple of sample reviews here:
the only problem with BOO for me is its corporate governance, and the issue about its suppliers - i have a distaste for it - similar to those door step lenders etc..
there's just a horrible "smell" around it
Possibly mildly true, but as they’ve grown they’ve recognised their original ways of working aren’t going to grow the company and it is in their own interest to hire professional management. Hence the appointment of Lyttle as CEO. They’re now, successfully imo, distancing themselves from the small company ethos and culture and growing into a monster with all the expectations that other monster apparel retailers have to face.
hopefully, this has spurred them into action, and will improve things. I wouldnt rule out investing in them in the future
Why not put the ticker so we know what you are referring to?
Thank you for your take on Boohoo (LON:BOO) which I agree with. A couple of things to remember:
The new distribution centre in Burnley was designed to handle £3bils worth of sales alone. I assume that is for the UK.
Secondly while as you say "As you can see, the growth is highly impressive, given that this is now a sizeable group;" one thing I am trying to grapple with is the size of markets for many products when you get outside of the UK. Often these figures are so large I struggle to get my head around them.
The size of the apparel market is enormous (2018):
https://www.statista.com/stati...
Western Europe $394.51bils
China $379.95bils
US $367.93bils
So that is well north of a trillion dollars. I think Boohoo has a huge runway for growth before growth starts to tail off.
Additionally upside from here is, when we truly come out of the Covid enviroment I would have thought that it would be reasonable to anticpate an upsurge in buying clothes for "going out", whether that be just out, partying, the office etc.
Of course if people can go back to shopping in the high street this mighty impact Boo on the other hand having experienced the ease of shopping online, perhaps people won't go back to shopping on the high street?
I hold. As you say I cannot imagine what would induce me to sell the stock in the next five years as a minimum.
Kind regards
Michael
Good points. I remember saying many years ago that I didn't think on-line would take off for fashion as women wanted to try things on! I can't see now why people will not continue to shop for clothes on-line.
very impressive presentation by Boohoo. Thanks for the link Paul
I agree. I did that deadliest of investing sins - enjoying the presentation so much, that I bought some more shares during it!
so did I
I've just bought a few more too. Glad I am in good company
Boohoo (LON:BOO) is already a 12% holding for me at an average Price of 277p, so I have to resist. I have learnt my lesson of what can happen with seriously over-weight positions through my holdings in Rockrose Energy (LON:RRE) and £AAZ.
That said any serious pullback 15%+ and i don’t think I would be able to resist.
Interesting point Michael.
I bought a fairly sizeable chunk of £BOO on the large dip and it is now (rather suddenly) 30% of my portfolio. I recall Graham noting in a SCVR earlier this year that Volvere (LON:VLE) had expanded from an initial 10% to 25% of his portfolio, simply by him not selling.
I’m not about sell boohoo either.
I did worse...top sliced on recent spike (@372p) than listened to the online results and had to buy back in. Forgive me for pruning the flower, Peter Lynch.
Hi Paul. Look forward to your brief on Air. Strange market reaction. Initially climbing on results and then dropping 12%. Seems to be stabilising now . Quite indicative of the wider market, confused .com. Rather glad I heeded your caution on Air earlier in the summer. I think it is understandable that companies are finding it extremely difficult and understandably reluctant, or terrified even, to give meaningful earnings guidance in the current circumstances. Sentiment is not surprisingly rather low with so much confusion on the 'science of Covid". Only a month ago two CO's were on the radio saying they thought we were very much in a V shaped recovery. Sentiment can turn on a pin, or needle should I say, and I think it it will when a vaccine is finally confirmed. As usual its all about stock selection as they blindingly obviously say.
Does anyone know why Tekmar (LON:TGP) has fallen 30% in the last month? Reasonably positive results, high growth sector, Covid weathered.
I think they have results tomorrow. Not sure if someone knows something?
Spent a bit of time this morning having a look at this one. decided to add it to my portfolio, so thanks for flagging the dramatic price drop! The main negative I can see is the market anticipating is another profit warning. obviously, that wouldn't be good. However, for me, this risk is outweighed by their fairly positive results and the fact China hasn't had to go in to another major lockdown (so hopefully they havent had any more delays). Again, thanks for flagging this one, i'd not previously looked in to it! :)
OK. Warning. This is a whinge!
Can anyone explain why some Stockreports are SO out of date. Nearly every time I've been doing research the past couple of weeks I've found one or two that still haven't been updated several weeks after results have been announced. Yesterday I noticed that Medica (LON:MGP) had not been updated, the interims were on 14th September. I've heard this argument that it's because the data provider is rubbish and doesn't update small caps in a timely manner as they are low priority (yeah, right) but what about Man (LON:EMG) ? A FTSE 250 company with market cap of £1.7bn? Interims were released on 30th July and the SR has still not been updated.
BTW this whinge is on behalf of readers here. I've already made my mind up on the quality of the data and quality of the new site and have voted with my boots.
All the best, Si
Hi Simoan! I can't explain it, but I agree that it can be very frustrating when it happens that the Stockreport does not yet take into account results released over a week ago. For me it means that I cannot analyse the company until the Stockreport is updated. To be fair, it does not happen to me that frequently, but it does happen. If it is indeed the data provider's fault, then, to my mind, Stockopedia should take it up with the data provider that they themselves have chosen, and that presumably they are paying for! Is there a service level agreement in place between Stockopedia and the data provider? My opinion is that there should be a service level agreement with a penalty for the late provision of information.
The board of DX (Group) (LON:DX.) have been active in the markets again, following publication of the full year results on 17 September. The latest purchases bring their total spend on shares to over £505k since the new management was installed a couple of years ago. With an average price paid of 11.2p per share (including the recent purchases), they have proved to be prescient in the past.
I've been noticing this too, been a bit put off by the % of shareholding they have invested, after a brief period of my selling out too low, probably the opposite ofconfirmation bias in my case though (denial bias ?) !
£SUMO (Why does the ticker thing not work??)
I hold a few of these and was pleased with the market response to the interim results and the optimistic outlook statement. The acquisition of Pipeworks seems a reasonable deal to me but comments on this would be welcome.
Revenue increased by 26.7%
Adjusted EBITDA increased by 15.2%
Reported profit before taxation more than doubled from H1 19
Virtually all the growth is organic
Strong underlying profit margins
Strong balance sheet maintained with £15.2m net cash at the period end
Sumo (LON:SUMO). This one you mean? It did for me. Not trying to be clever; just testing!
Yes, that's the one! Let me try again... Sumo (LON:SUMO)
Edited to add that it works in this reply. I wonder what I did wrong in the original post?
Sumo (LON:SUMO) (Why does the ticker thing not work??)
Well, that was cut and pasted from your original. The wonders of Stocko!
Anyway this is a reminder that there is a PIWorld webinar on Oct. 8th. register here:
https://register.gotowebinar.com/register/7385155030851262223
Boohoo (LON:BOO) seems to be a battle over the bears and bulls on the intra-day trading chart today. I wonder who will get tired first...
Studio Retail (LON:STU) "In the last 6 weeks since the Group's FY20 results announcement on 24 August, product sales have grown by 30% against the equivalent period from the prior year. This brings the total products sales growth for H1 to 39%".
This stock seems to be under the radar a bit I think.....yet seems to have taken the right steps e.g "online sales now represent over 90% of total orders".
Has anyone got any insights into M&c Saatchi (LON:SAA) ? Their accounts are in a mess and the shares will be suspended for a few weeks, but I think that they are saying that they are trading profitably. If so, is this a good buying opportunity? (I don't hold)
There an update from Bigdish (LON:DISH) this morning. Had a quick skim and couldn't really see anything new in there (was a really quick skim).
Paul, on your question about which direction the US stock market will go, it is difficult to believe that after the intemperate presidential debate yesterday they are going anywhere except down. Hopefully the knock on effect here wont be too severe.
BTW, does anyone have a view as to why Paypoint (LON:PAY) is some 14% off the boil..assuming market is not liking the EPS Rolling 1y (-6.9%) and flattish sales growth in an increasing cashless trend ..so is this share becoming more of a Income/Value play?
OFGEM announced this morning they were looking into them for unfair practices - trying to decide whether this is a good buying opportunity or not.
Yes OFGEM allege a monopoly of sorts on energy contracts and retail. Would a similar probe into schools (ParentPay) be next? Maybe they've had this backlash before..
I'm positive that OFGEM is the biggest unfair practice going.. My example is Centrica (LON:CNA), one of my worst investments ever but mind you, the stream of greedy directors haven't helped matters either.
Boohoo (LON:BOO) after a great set of results the shares are down??!!
exactly. Why ??! Any comments from readers?
perhaps the comments made by CEO regarding uncertainty in second half and return rates probably increasing??
In the questions to the presentation this morning, this uncertain guidance for second half was described as 'being prudent', in view of the unknown future of Covid. So personally I am not too worried by this.
Boohoo (LON:BOO) Outlook as stated in the announcement.
Group revenue growth for the year to 28 February 2021 is expected to be 28% to 32%, up from approximately 25% as previously guided, with adjusted EBITDA margin for the year at around 10%, increased from the 9.5% to 10% as previously guided.
My take on the two measures as below.
Revenue growth - Taking 30% revenue growth as average between the two guidance values (28% -32%), considering the growth in the first 6 months has been 45%, back of a fag pack calcs suggest growth for the next 6 months ahead to be a paltry 15%. That seems unrealistic. Am I missing something?
EBITDA margin – taking 10% for the year, considering 9.7% achieved in the first 6 months, this gives 10.3% expected EBITDA margin for the next 6 months.
(I hold)
They usually set expectations low and revise as targets are achieved.
Seems prudent, especially as we don’t know the scale of economic damage that’s in store.
I agree their forecast seems very prudent. Given we have Xmas and that will be huge online then I can see a similar 2nd half to the first.
And there is Black Friday before Xmas, which can actually generate the largest amount of sales for the year
Better buy some more then...! :-)
Interesting update from Topps Tiles (LON:TPT) - revenue down about 12% year-on-year which must count as pretty good. Current trading seems to reflect catch up spending. If they can get back to previous year's profits they look cheap. I don't hold - very poor Altman Z score - I don't know what you think Paul but stock turn looks weak.
A fine set of interims from Minds Machines (LON:MMX) this morning. They own and operate top level internet domain names
Billings grew by 7% but total revenue fell by 5%. This reflected the progress they are making in their transition to a recurring revenue business model, with 67% of revenues now recurring. There is strong visibility on revenues too, as much of their income is "earned" over the period of a licence, hence the balance sheet shows deferred revenue of $13m (equivalent to about 9 months sales).
Repeated licence renewal generates an annuity-like revenue stream for MMX. Now current management have completed the painful process of fixing the business after previous management messed it up, they are looking to use this predictable cash flow for the benefit of shareholders. Hence:
"Given the highly predictable cash generative nature of our core channel business, we are pleased to announce that a tender offer of £3m will take place in November. This will be supplemented by an ongoing buyback and an intention to target further distributions of approximately 50% of free cashflow from operations each subsequent financial year".
Further, they have announced a cost-savings initiative that should flow straight to the bottom line:
"In parallel, we are also pleased to report that we have initiated a series of steps that are expected to reduce costs in aggregate across OPEX, COGs and partner payment by over $1m in 2021 when compared to their expected amounts in 2020".
To put that into perspective, $1m is about 1/3 of forecast pre-tax profit. These savings, combined with continued recurring revenue growth, should bring substantial operational gearing benefits.
Minds Machines (LON:MMX) (I hold)
Thanks for your thoughts on this Effortless Cool.
I agree with everything you have said; this is a simple, highly cash generative business, with what appears to be relatively stable recurring revenues.
If there was any downside, it looks as thought revenue/domain is slightly lower this year ($6.18 H1 FY20 vs $6.53 FY FY19), but I find that hard to believe this is correct given the majority of revenue is from renewals, where the company can presumably charge slightly higher amounts.
It might perhaps be all the funnies in the accounts last year skewing my workings, but this is only a minor issue and it is clear that risk in this tiddler looks quite low, with reasonable upside through the acquisition of more TLDs and new products.
Cheers
A
Shadowfall started tweeting (7 tweets) just before market open with 'questions' for BooHoo (mud slinging). Not giving up on their short - or maybe giving the appearance they are not giving up their short
I’m all for shorting, but given they’ve (Boo) just released an independent report, announced a raft of measures and a £10m budget to improve the supply chain, at what point does this become harrassment rather than legitimate “concern”?
Great results from Air Partner (LON:AIR) this morning which I held from about 57p earlier in the pandemic. Well done to anyone who had the guts to buy even lower. It's trading at a PE of 7 based on its adjusted EPS for H1 results alone with net cash, and no debt (excluding some current liabilities), representing about 35% of the market cap providing a good platform for acquisitions and growth. It has recently moved into South Africa.
People new to this share might be wondering why it looks like such a bargain? It benefited massively from charter and freight related to the pandemic, and profitability is now coming down as freight becomes more normalised although the company notes still that they 'do expect to report a modest profit for the second half of the year.'
While a lot of countries should now have more stable supply chains, as another commentator below notes it could be a good hedge on another large second wave and perhaps it could benefit from COVID vaccine delivery if a vaccine ever arrives. Set against that, it seems unlikely chartered private flights for individuals will particularly pickup before next summer although one can imagine risk averse high net worth individuals may be particularly keen to use its services!
Using the figures today we can work out what the company made in profit before tax in July, as they previous gave us the figures for the first five months of the half year. Perhaps the July figure gives an indication of more 'normal' trading?
It's quite difficult to value this share given the exceptional H1 performance but I am planning to hold for the time being as my working assumption is there will be a second wave which will put pressure on healthcare systems once again.
down 10% today
Statement seems to suggest all profits gained during Covid were one off due to repatriation. States modest profit for remainder of year which I read as breakeven. I doubt they will benefit from a second wave and their other divisions will be probably loss making for the foreseeable future while air travel remains low.
Also worth noting while they were trading well up to June 2020 they were issuing monthly trading updates. These stopped once normal more subdued trading resumed from July onwards. They made hay while the sun shone and informed the market but the quietness since July tells its own story.
How did you reach your view that "I doubt they will benefit from a second wave"? My own view is that developed countries will have more stable supply chains but a) there will still be pressures on various supplies where there is a finite supply (e.g. drugs) and b) there may be new problems in the second wave because you've got the flu season, possible COVID vaccine deliveries, and hospitals trying to maintain usual services to a greater degree.
Agree about the quietness since July point but they've said today they still expect to be profitable in the second half so even at breakeven we're on a full year p/e of 6-7!!
Hi Patrick,
I doubt in the event of a second wave there will be the big repatriation event like during the initial panic situation caused by the first wave. As you suggest Governments will be better prepared and I would expect a more controlled situation. Maybe they would benefit to a degree but unlikely in my view to the level previously experienced.
The PER of 6-7 will be correct for the current year but this includes the bumper period so should not be referred to going forward.
They do seem a well run outfit but would expect eps to return to mid single digits in the coming years. This will have suffered some dilution following the placing which will depress eps somewhat.
Balance sheet will be stronger following the placing and I would be interested as a play at lower levels as they definitely have a niche in the market place.
Cheers
paraic84
Air Partner (LON:AIR)
and well earned it is too.
Paul has pointed out above the House of Cards balance sheet and the share is currently trading below the 12 June fundraising. On a historical note it is also trading below what it would fetch in July 1998 - a long and deserved record of mediocrity.
Only two directors participated in the June fund raising, pumping in 1% - £76K of the £7.5M raised.
The direstors saw no bargain to be had here and have been proven right.
Bonitabeach
No position
Thanks for the useful analysis of Air Partner (LON:AIR) ,Patrick. It's another Lord Lee investment.
Air Partner (LON:AIR) benefits when the world falls apart (COVID, Ebola, wars, etc.--when is it not falling apart somewhere?) and when the world is doing well (charter flights, etc.). In the days when I was working, I would sometimes arrange transport for 10 to 50 temporary workers. I imagine that it would be easier to find willing people if they were not asked to use public flights.
The share price is below the 5 year average, there have been acquisitions, there is plenty of cash, directors have bought recently, and AIR is an excellent hedge against disruption.
disclosure: I hold and have just bought a little bit more.
Air Partner (LON:AIR) (I hold)
Thanks for your thoughts Patrick.
FY21 THOUGHTS
This has grown into one of my largest positions and a part of me is actually torn on what to do next.
H1 was undoubtedly good, but I was expecting a much bigger recovery from Private Jet.
I did note that JetCard cash is actually up vs Jan 31st 2020, so perhaps there is more upside here than we realise.
FUTURE
There will be big sporting events in the next 2 years (Olympics + Euros + World Cup) and I'm one of those who believe that things will return to "normal" in the next couple of years.
I do also think that the Private Jet business will grow.
And sadly, natural disasters don't know about Covid, so that disaster-induced revenue will continue.
I was happy to hold before Covid when the company was generating +£5m cash a year, and given the current very low Enterprise Value of £35m* this still looks a bargain to me so I will likely hold.
QUESTION TO INVESTOR RELATIONS
For reference I did send the following question to IR just now, but they didn't respond to my last email so I'm not holding my breath waiting for a reply.
"Corporate costs increased in H1 to £1.3m,
vs £0.9m in H2 FY20, and
vs £1.2m in H1 FY20.
With management taking pay cuts, the company making use of Government support schemes and any incremental segmental costs accounted for separately, I'm quite surprised to see this increase.
Can you provide more colour on what was behind this increase?"
NEGATIVES
Cheers
A
*the company very helpfully provided a normalised cash balance of £15.2m, which I am using to calculate my own EV + I am assuming this will drop by at least £5m due to the cash outgoings expected in H2
Really helpful commentary from Paul and others today on Air Partner (LON:AIR) - thank you. I was probably overly bullish on the balance sheet and going through the numbers too fast this morning so really helpful commentary on that. I'm probably still going to hold in the short-term because of my working assumption of a difficult second wave and the potential benefit to freight, but it is tricky to value this share.
Would it be possible to hear your thoughts on Quinetic (QQ.)?. positive trading update, although growth over the next two years expected to be modest (low single digit%). cheers paul!
Agreed. Great update from Qinetiq (LON:QQ.) the analysts will surely give this one a boost on the back of this. Massive barriers to entry in evidence and I think single digit growth this year is a very credible result. Reinstatement of divi and guidance is a huge sign of confidence and visibility, I'm amazed how some of these businesses have been able to trade right through the lockdown - introduced a few to the list today. Well worth a look.
zeus upgraded £BOO numbers.
2021/2022 now looking at eps 8.22/11.37p
put 2022 on P/E of 45 and you get over £5.00
fantastic looking growth in US, big pot of cash.
Paul could you clarify for me what index you are using for the chart in your opening section. I am a fairly new subscriber and would also add that I find your reports extremely useful and a great help in making suitable investments.
That would be the S&P500 Martin. Paul was discussing how the UK market follows the lead of the USA.
888 Holdings (LON:888)
Very nice results and trading update from 888 with trading significantly ahead of expectations , i do think that the lockdown conditions over the last 6 months may have created the perfect conditions for them to deliver as they have so i don’t really expect the barnstorming numbers to be repeated this time next year. Stocky shows pe off17 at present and with upgrades to be expected this may perhaps drop around/below 15 ish perhaps? So despite the shareprice increase the price doesn’t look particularly expensive at present. Some vey nice us growth too (64% revenue growth) albeit from low base level - us only accounting for 11% of h1 revenue.
888 Holdings (LON:888)
I also hold. Results are pretty much as I expected, but it's the +56% Q3 QTD result that really looks good.
One point on the US revenue growth. With William Hill (LON:WMH) looking increasingly likely to be taken over by Caesars, I can't imagine that Caesars will continue to use 888 in the long term, so as far as I'm concerned a lot of the US revenue is simply waiting to disappear.
Fingers crossed they can sign other deals in the US to get things back on track.
A
My morning smallcap tweet:
M&C Saatchi (LON:SAA) AFH Financial (LON:AFHP) Altitude (LON:ALT) Pressure Technologies (LON:PRES) Studio Retail (LON:STU) Genedrive (LON:GDR) Integumen (LON:SKIN) Topps Tiles (LON:TPT) Symphony International Holdings (LON:SIHL) AdEPT Technology (LON:ADT), N Brown (LON:BWNG)
M&C Saatchi (SAA) FY(Dec) audit will miss Sept deadline so shares suspended from Oct 1. Unaudited results: rev up 2%, pretax -£8.6m (-£6.3m). Trading: co has continued to trade well and profitably since Aug update. [SP=57.6 Cap=66m]
AFH Financial (AFHP) guides FY EBITDA to be slightly below its previous expectations.. Co continued to be profitable and cash generative throughout the summer. Ongoing management fees returned to anticipated levels but recovery in new business written by the wealth management division and the associated inflow of new funds has been slower than anticipated [SP=326 Cap=140m]
Altitude (ALT) delays FY(Mar) to Oct. Guides 15 month rev £8m (prev 12 months £2.9m). Aug cash £1.6m in line. Trading: Aug: market transactional vol down 26%, only 300bp better than July. "The slower rate of improvement in August has tempered industry expectations for a V shaped recovery and whilst August may be indicative of a longer and slower climb" [SP=14 Cap=10m]
Pressure Technologies (PRES) wins contact for over £3m frm EDF Energy. Dreadnought submarine order - rev for 2nd boat delayed into next FY. Now guides FY loss. [SP=65 Cap=12m]
Studio Retail (STU) guides FY adj op profit (cont) ahead of mgmt expectations. "Primary business, Studio, has seen a continuation of its strong retail trading performance in the early weeks of its new Autumn/Winter season, with kidswear, gifting and early Christmas ranges performing particularly strongly." [SP=232 Cap=201m]
Genedrive (GDR) gets South Africa approval for its 96 SARS-CoV-2 Kit. [SP=104.5 Cap=54m]
Integumen (SKIN) wins first US detection agreement. $500k 3-year Great Lakes water contamination detection Project. [SP=34 Cap=38m]
Topps Tiles (TPT) Q3 retail rev up 16.5% but commercial sector has been rebuilding more slowly. Ups guidance to modest FY adjusted pretax. [SP=52.2 Cap=102m]
Symphony (SIHL) June NAV per share $0.6216 (Mar: $0.6043). SP was 51% below NAV in June. [SP=0.29 Cap=150m]
AdEPT Technology (ADT) AGM stmt: new order intake, project delivery, cash collection and operational effectiveness provide encouragement but no interim div. [SP=235 Cap=59m]
In line: N Brown (LON:BWNG)
I know that Boohoo (LON:BOO) (I hold) will be top of the pops this morning, but can you spare a glance for Air Partner (LON:AIR) today? Profit before tax up 250%, net cash up 319% (placing driven mind), and Basic EPS up 146%.
It looks fantastic, but... I was hoping for a transformational change in private jet use, whereas there appears to be a decline in JetCard Cash (pre-bookings effectively).
I still think Air Partner (LON:AIR) is a great second wave hedge, but I'd love to know what Paul thinks.
Yes, I've added Air Partner (LON:AIR) to the list of things to cover. It did well in the initial covid wave, as the wealthy chose to use private jets, and some one-offs like repatriation flights proved lucrative. So it will be interesting to see if trading has continued to be good, or normalised? Quite an interesting company I think.
I can understand why many might be focussed on Boohoo (LON:BOO) this morning, but interesting results also from Air Partner (LON:AIR), and Open Orphan (LON:ORPH) (both of which I hold), which are worthy of a look.
yes open orphan is worthy of consideration.
game of two halves. The first one in the interims was about joining two businesses and cutting costs dramatically, 2 expensive CEOs let go, offices shut and businesses rationalised. They have a beneficiary of Covid as they are a world leader of vaccine testing using human Challenge studies. Business is booming with large contracts signed on a monthly basis. These contracts include a large up front cash element and cash by Xmas is estimated to be £30m. Its 24 bed quarantine facility was previous only booked 25% is now fully booked for the next 18 months. Recently in the news regarding Covid Human Challenge Model that it is developing and it looks like the government want to work with them to use it to test the up and coming vaccines. Reports in press are that they might use the royal free hospital in London for the first human Challenge trial in January. Open Orphan are the only company that is nearing completion of a covid challenge model and government are in discussion with them as reported in FT.
They also have a universal flu vaccine stage 3 ready and a vaccine against mosquito borne diseases which they are looking to sell as non core.
Hence given current focus on viruses there is potential for £100m dividend.
they have also gathered a large amount of Genomic data and have been approached by 2 of the large wearables who want this data to help detect disease like the flu and covid in the future. Deal expected before Xmas. Note they will be collecting covid data during the forthcoming covid human Challenge trials.
as you can see there is a lot going on in open orphan and the transformation has been remarkable by its dynamic executive chairman Cathal Friel who has shown previous form in turning around companies. He has invested £2m of his own money locked in for 3 years ( 2 still to go) so is fully aligned.
check out any of his previous presentations and you will get a sense of hard working and genuine this guy is.
in short open orphan are World leader in human Challenge studies for a wide range of diseases so can charge premium prices. COVID-19 has highlighted the need for this service so they will be busy as governments and pharma will not want to get caught out again
Just off the analyst call for OO
Not officially confirmed but government have help secure a second site solely for human challenge studies (no lease liabilities as suspect it is a government hospital) .
Government have taken 3 slots , there is a £2-3m reservation cost for a COVID challenge study and they are talking to other vaccine pharmas. They are the only game in town so can charge premium prices. Their conventional challenge study for RSV has gone up from £3.2m to £4.3m (25% to 30% up front) and COVID challenge studies will be £7-10m . At least 10 in the pipeline. There will lots of work in COVID space as vaccine will only last for a year and also work in doing head to head COVID vaccine studies.
This company is operating in a niche with no current competitors so will throw off cash. There will definitely be a rerate
Great summary of Open Orphan (LON:ORPH) newstart, far better than I could do.
I hold.
The Early Morning News - Wednesday 30 September 2020 (OLD SITE)
The Early Morning News - Wednesday 30 September 2020 (NEW SITE)
Boohoo (LON:BOO) - very few companies can guide to 25% sales growth and 10% adj EBITDA margin continuing for the medium term. Its so impressive
Boohoo (LON:BOO) results highlights below.
FANTASTIC RESULTS BEATING CONSENSUS EXPECTATIONS AGAIN. Much better than even what I had expected too.
Paul,
would appreciate your detailed analysis of Boohoo (LON:BOO) today given we have tangible numbers now, especially your thoughts on next 6 months performance and impact on share price?
Cheers.
Great, thanks for flagging, I hadn't spotted the BOO numbers yet.
As readers here know, I've been super-bullish on this share, after the misguided shorting attack, & supply chain worries, presented us with a wonderful buying opportunity.
I hope readers have made a few quid! (I have!!)
Yes indeed. Many thanks Paul. It now represents 22% of my portfolio which I know is too much but I just see no point in selling yet and have increased my position on each dip.
Perhaps not that surprising that the BOO share price is a tad down today? The share had a great run up ahead of results, including that 55p gain (which bemused some ill informed Financial Press commentators who had assumed a big fall would result) after the Independent Report was published by BOO in full. So perhaps excellent results were mostly priced in.
Also this section from the comment might also explain why:-
Guidance and current trading
“The group has made a good start to the second half of the year, with momentum continuing into September. At this stage we feel it is prudent to continue to plan for a period of economic uncertainty in the second half of the financial year, including possible reduced consumer spending. It is also prudent to plan for return rates returning to normal levels, continued near-term carriage inflation in some of our overseas markets and increased marketing spend likely in the second half. Capital expenditure is expected to be higher than previously anticipated, in the region of £80 million to £100 million, reflecting the step-up of investments into automation at our Sheffield facility, further expansion of existing automation at the Burnley facility and significant IT projects to support the growth of the business and improve efficiency.”
So some increased capital expenditure along with the other cost pressures. If Press commentators/potential shooters focus on that one small negative part of their update, perhaps a chance of another temporary share price dip and top up opportunity? Imo Boo were sensible in including that paragraph.
I’m another very happy holder of BOO shares and would not have bought years ago at 35p but for Paul’s superb high quality updates here. Recent Press and other comment was often ill informed. There was even their failure to realise that this is a sector wide issue here and abroad, yet The Sunday Times and others thought they had unearthed new scandalous information which in reality had been going on across the sector for many years. Yes it’s wrong. But more wrong was just singling out BOO.
The share price fall after these exposures along with Paul’s brilliant coverage of this episode and also excellent reader comments too gave that chance to buy back at a bargain 215p.
"Leading the fashion eCommerce market"
6 months to 31 August 2020
6 months to 31 August 2019
Change
£ million
£ million
Revenue
816.5
564.9
+45%
Gross profit
449.2
306.6
+47%
Gross margin
55.0%
54.3%
+70bps
Adjusted EBITDA(1)
89.8
60.8
+48%
% of revenue
11.0%
10.8%
+20bps
Adjusted EBIT(2)
79.0
51.3
+54%
% of revenue
9.7%
9.1%
+60bps
Adjusted profit before tax(3)
79.4
51.9
+53%
Profit before tax
68.1
45.2
+51%
Adjusted diluted earnings per share(4)
4.53p
2.91p
+56%
Diluted earnings per share (2019 restated(5))
3.99p
2.80p
+43%
Net cash(6) at period end
344.9
207.3
+137.6m
Highlights
· Revenue £816.5 million, up 45% (44% CER(7))
· Strong revenue growth across all geographies and brands (UK: +37%; international: +55%, including US +83%). International now 47% of group revenue (2019: 44%)
· New customer acquisition in Q1 driven by pandemic's impact on consumer behaviour
· Healthy customer KPIs with a continued improvement in share of wallet
· Acquisition of the remaining 34% minority shareholding in PrettyLittleThing
· Acquisition and integration of the Oasis and Warehouse brands, complementary additions to the group's scalable, multi-brand platform
· Robust balance sheet with net cash of £344.9 million (2019: £207.3 million), healthy operating cash flow of £147.2 million (2019: £55.9 million) and net cash flow of £99.5 million (2019: £15.5 million)
· Non-participation in UK Government's financial support schemes to support jobs and businesses
· Successful £198 million share placing to support future acquisitions
· Independent Review ("Independent Review") of working conditions of supply chain in Leicester published. All recommendations accepted, improvements in supply chain governance to be robustly implemented in full
good news Boohoo
Yep. +45% revenue.
If we assume they can manage 40% eps growth for the year, and that the market will tolerate a P/E of 60 (low by Boo's standards), eps becomes 8p and an implied share price of ~480p.
I'd like to thank all the shorts for allowing me to buy a significant (for me) holding at <250p.
Also a big thanks to the short sighted institutions that offloaded at any price. You can have them back someday, but not for at least 3 years.
I agree! After listening to a fund manager the other day, talking about how ESG considerations meant that he wouldn't touch Boohoo (LON:BOO) it made me think that the ESG trend could be a wonderful way for us to make money - by buying shares in the best companies that fund managers aren't touching because of ESG fashion considerations. It's certainly worked a treat with BOO this year anyway.
You may well be right about the specific claims in relation to Boohoo in Leicester - I don't know the details - but I would be wary betting against ESG as a structural rather than short term trend.
I also believe that if done well, rather than as green washing, ESG considerations are very important (and potentially alpha generating). Don't forget that this covers situations such as the 1132 people who died in a fast fashion factory in Bangladesh in 2013 not to mention the toxic loads borne by child workers spraying cotton with pesticides.
I don't mean to suggest that you would condone any of this Paul, but just wanted to emphasise a broader point about how the world is changing, and needs to.
ESG is here to stay. The thing is where do Fund managers draw the line? How many genuinely 100% ESG compliant large corporations are there? I would be interested to hear a few that are
ESG will mean different things to different people. In some ways it is about trends rather than compliance.
Consider, which is better a company that sets a target for reducing its emissions of volatile organic carbons by 20% per unit of production in five years’ time and achieves a 17% reduction, or one that set a target of 10% reduction but achieved 12%? The first did not comply because it missed its targets but it achieved a greater reduction than the second. But then again perhaps the second company had already made big reductions when it set the lower target.
Then of course you have have to consider the various different aspects of sustainability - carbon footprint, water footprint, waste production, use of plastics, VOCs and so it goes on.
If you want to see which companies are generally considered to be heading in the right direction then look to the members of the Dow Jones Sustainability Index and the FTSE4Good Index.
These indexes are far from perfect but they do go some way towards being a standard for quoted companies.
However, many people seem to confuse sustainability in terms of a company’s own performance with the world of companies that deliver products that have a positive impact on the environment in the sense of renewable energy production and so on, which is a different kettle of fish altogether.
Obviously we're all aware of the issues. My main gripe with ESG is that it latches onto specific companies as being supposedly bad in some way. But as with BOO, if you look at the bigger picture, it's probably more ethical than most competitors.
And fund managers seem to be making rather poorly informed decisions as to which companies are, or aren't ESG compliant. Hence why I think it's a bit of a fad, being implemented poorly & inconsistently, hence throwing up opportunities for investors.
I bet if you dug into the supply chains of every large company, in every sector, you would find unethical things going on, which companies might or might not know about. How can they possibly police the working conditions of every component, and every factory supplying them?
So it's not that I think ESG is nonsense, it's more that I don't believe things can be properly monitored.
As for corporate governance, where is the evidence that companies which strictly follow all the multitude of rules & guidelines, actually perform any better? Some highly successful companies have had maverick leaders/founders, who have sometimes flouted generally accepted principles - e.g. Mike Ashley at Sports Direct, Tim Martin at Wetherspoons, Mahmud Kamani at BooHoo. Yet their passion, strong leadership, entrepreneurship, and work ethic, often brings far better results for everyone than a box-ticking, regulatory-compliant hired hand CEO.
Regards, Paul.
Aswath Damodaran analysis of the data does not support this.
Yes indeed. See my later comment about Aswath Damodaran on ESG.