Small Cap Value Report (Wed 4 Mar 2020) - PHD, INTU, NANO, MPAC

Good morning, it's Paul here with the SCVR for Weds.
This is a placeholder post, to enable readers to add your comments from 7am. I'll be writing the main report throughout the morning, adding each section as it's written. Official finish time is 1pm each weekday.
Estimated timings today - I'm running a bit late, so will keep writing until 4pm.
Edit at 16:09 - today's report is now finished.
Let's start with the three biggest % fallers today, which are all struggling to find buyers or refinancing;
Proactis Holdings (LON:PHD)
Share price: 32.5p (down 31%, at 10:26)
No. shares: 95.5m
Market cap: £31.0m
Conclusion of Formal Sale Process (FSP)
Proactis Holdings PLC ("Proactis", the "Group" or the "Company"), the global spend management solution provider, announces the conclusion of the formal sale process ("FSP") announced on 29 July 2019.
No firm proposals have been received. That's clearly bad news - I tend to stay away from any share where the company has conducted a lengthy sale process and nothing has come of it. What does that tell us? That potential buyers have had a look, and don't think much of it. There's no other possible conclusion, in my view.
I last reviewed its accounts here in Oct 2019, which I found very poor - in particular the weak balance sheet, loaded up with too much debt, from poor acquisition(s).
Today's update tries to sound positive, with some figures on new business wins. However, there is no clear statement about performance versus market expectations. It does say this though, which some people might think is positive (I don't, because it side-steps the key issue, of how they're trading versus market expectations)
As communicated within our recent trading update, we have delivered a significant improvement in new business and dramatically improved retention rates and we expect a return to revenue growth in the second half of this financial year. Our progress in the short-term has been encouraging and we are confident that the long-term prospects are significant."
My opinion - nothing's really changed. It's still an over-indebted software group, with patchy performance. The fact that nobody wants to buy it, confirms my negative view of this one. Maybe it might recover, who knows? There are some positive noises made today. The strategy of abandoning the sale process, and concentrating on cost-cutting, and driving sales up, sound sensible.
Given the wording used in today's update, I imagine that the risk is very much to the downside, as regards existing forecasts.
I'll have another look when the results come out, but this is likely to be a difficult year for many/most companies (as we discussed yesterday), so highly indebted companies like this are really best avoided in my view.
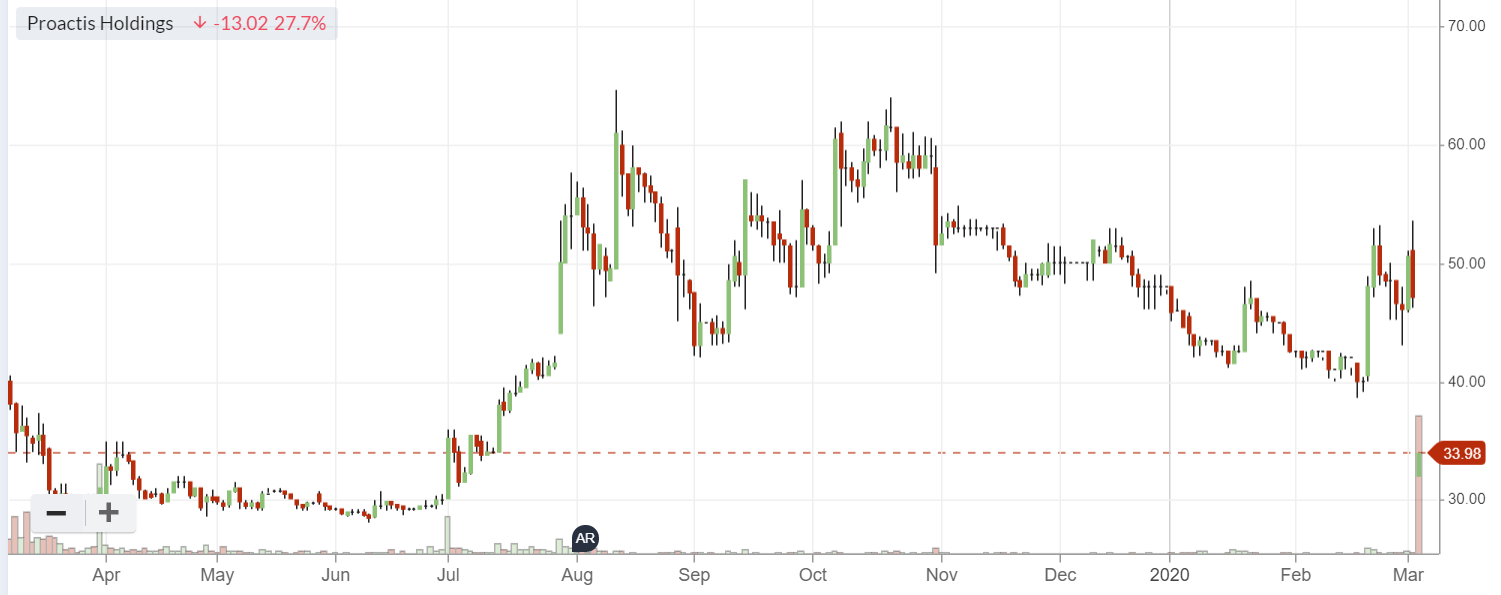
As you can see, the speculative takeover surge that started when it put itself up for sale in July 2019, has now evaporated completely;
.
Intu Properties (LON:INTU)
Share price: 7.7p (down 28% today, at 11:51)
No. shares: 1,355.0m
Market cap: £104.3m
Update on strategy to fix the balance sheet
This is a large, complex business, which owns some of the best retail shopping centres in the UK.
The problem is that it has been overwhelmed by debt, with asset values reducing due to some of its tenants struggling to pay rents which are now unaffordable.
Today's update is blunt;
intu has, over the past several months, engaged in extensive discussions with its shareholders and potential new investors regarding a possible equity raise of between
£1 billion and £1.5 billion. Following these discussions intu has concluded it is unable to proceed with an equity raise at this point.
Therefore, I think we have to (continue to) work on the basis that existing equity is probably worth nothing.
Alternatives are being looked at, but this sounds to me like people wanting to cherry-pick the best bits, and probably at fire-sale prices now that coronavirus is likely to further hit retailers;
However, during this process, intu received several expressions of interest to explore alternative capital structures and asset disposals.
My opinion - reading through all the detail, it seems that the crunch point re covenants could come in July 2020.
The debt to assets ratio of 68% mentioned today (after a £2bn valuation markdown in 2019) doesn't sound so bad, if the banks were prepared to maintain support, and equity holders prepared to stump up more cash. The trouble is, that does anyone actually believe the valuations? With retail conditions getting worse each year, and more tenants going under, then it seems likely that more large asset write-downs are in the pipeline. Coronavirus couldn't have come at a worse time for intu.
It looks far too risky to catch this falling knife. I think we have to work on the basis that the most likely outcome would be for a refinancing that largely, or completely, wipes out existing equity.
Nanoco (LON:NANO)
Share price: 13.45p (down 46% today, at 13:36)
No. shares: 286.2m
Market cap: £38.5m
This company makes tiny dots, which apparently can be used to make display monitors. It's a rather stale story, having been around for years, and not really getting very far, despite burning through a lot of cash.
Today it says -
On 20 December 2019, Nanoco announced that it had engaged with multiple interested parties as part of a formal sale process, as referred to in Note 2 on Rule 6 of the City Code on Takeovers and Mergers (the "Code"), and that certain of those parties were being invited to enter into further due diligence and detailed discussions about the sale of the Company.
Nanoco confirms that it has not to date received any firm proposals that, in light of the current market environment, it believes would lead to an offer for the Company from such parties and discussions with certain of them have now been terminated.
The Company is continuing to engage with a number of parties to establish whether they are prepared to make such a proposal.
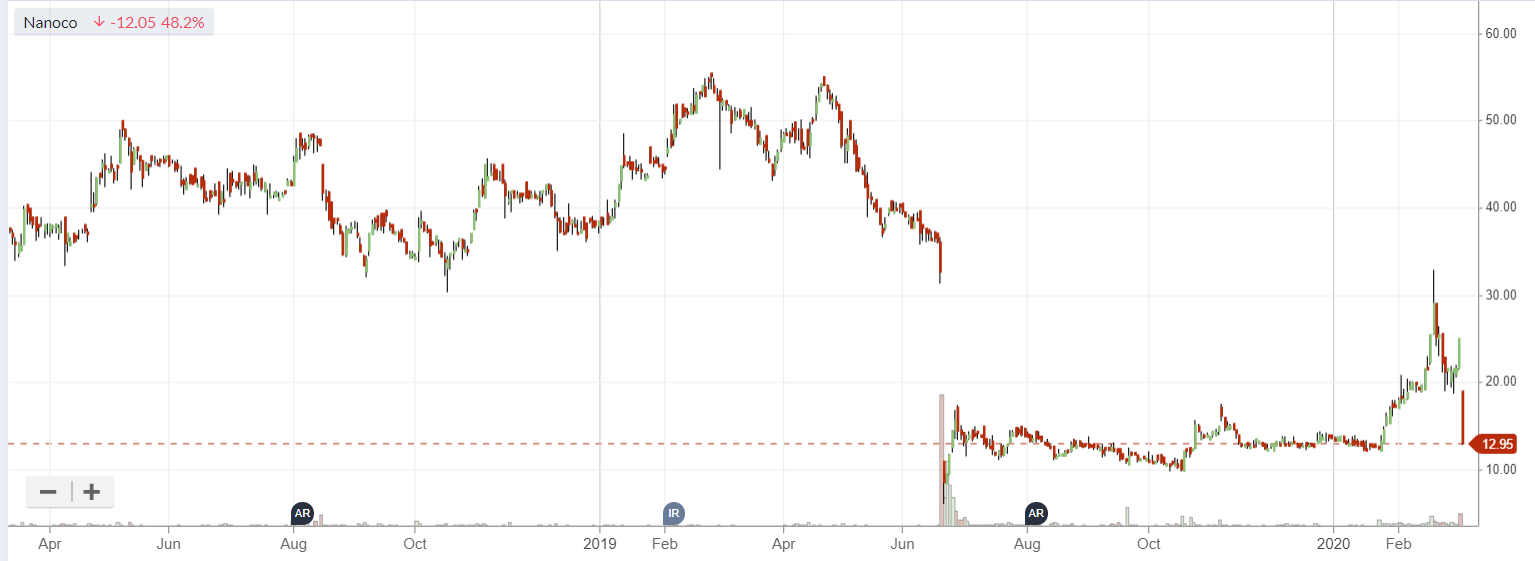
Which doesn't sound very promising to me. Similar to Proactis above, it looks as if potential buyers have looked over the books, and walked away. Although in this case, there are still parties involved, but as time goes on the likelihood of a deal tends to reduce. Potential buyers have had 2 months to do their due diligence, so I think anyone with a serious interest would have expressed it by now.
Strategy update -
As announced in February, Nanoco is pursuing a patent infringement lawsuit against Samsung. In addition, the Board continues to review all the strategic options available to the Company as part of the Group's strategic review, including possible sources of additional funding for the Company which include some short term commercial opportunities, with contingency plans in place if needed.
That all sounds a little scary - an expensive lawsuit, and by the sounds of it, a need for more funding (discounted placing, possibly?).
I've had a look at the last published accounts FY 07/2019, and to be fair, the company does seem to have made some commercial progress. Revenues more than doubled to £7.123m, at very high gross margins of almost 91%, achieving £6.458m gross profit. Costs were still very high, so the loss before tax was £5.5m. On the basis of these numbers, if the company is able to increase revenues, and reduce costs, then profitability could be achieved.
Although the narrative talks about a single customer, and expiry date of end 2019, so more work would be needed to ascertain what future sales might be like?
The legal case against Samsung is obviously a worry. Maybe Samsung might bid for NANO, to shut down the problem? On the other hand, given that NANO's finances are weak, then it might not be able to continue funding the legal action, which being in USA, would presumably be very expensive. I wonder if they should contact Burford, to do a deal on funding for the case?!
My opinion - on a cursory glance, I was expecting to conclude that this would be a basket case. However, whilst clearly cash must be becoming a problem, if it's able to refinance again, then the shares might be worth a fun money punt. In current market conditions, it might struggle to not only find a buyer, but to refinance again. So it must be seen as high risk. Although speculative upside does seem possible. I haven't done enough research on it to be able to gauge risk:reward. It could go either way, so I'm neutral.
.
Mpac (LON:MPAC)
Share price: 307.5p (up 1% today, at 11:45)
No. shares: 20.2m
Market cap: £62.1m
I was bowled over by the trading update from this company a little while ago, here on 8 Jan 2020. The most striking thing was repeated, and very substantial upgrades to forecast earnings - tripling in one year! You don't see that very often. I've been looking forward to having a proper look at it, so today is my opportunity. This might take some time to prepare, so please bear with me.
Here are my notes from reviewing the results announcement -
- 2019 was clearly a very good year, as has been previously flagged by the company
- Revenues up 52% to £88.8m, of which 24% growth was organic
- Acquisition of Lambert is described as a "strategic milestone", in May 2019
- Healthcare-orientated customer base - sounds good, growing sectors
- Underlying EPS 39.5p (LY: 4.5p!) - adjustment for pension costs not necessarily justified, as it is an ongoing & repeat cost
- Statutory EPS 29.7p - more conservative measure that some people may be more comfortable with - which is still showing impressive growth
- Divis re-starting, with a modest 1.5p final divi - so not an income stock yet
- 2020 has started well, in line with expectations
- 2020 opening order book flat vs last year at £52.2m (not clear if this is LFL, or including Lambert) - possibly slightly disappointing? Has the growth surge paused for now I wonder?
- Coronavirus - currently doesn't expect delay to parts. China is small element of supply chain. But, could be knock on effect if other suppliers impacted by China.
- Huge pension schemes - £423.6m assets, £403.2m liabilities, on an accounting basis - technically a surplus, but since deficit overpayments are calculated on the actuarial numbers, then I would delete the £20.4m pension asset from the balance sheet. Investors here do need to properly understand the pension fund situation.
- Annual pension recovery payments of c.£3m - are material cash outflows, and help explain why divis are so small. Not to be ignored!
- Tax charge - NB note the P&L tax charge is negative at +£0.3m - this significantly boosts EPS, so needs to be adjusted to a normalised tax charge to properly value this share
- Balance sheet - overall looks fine, even after adjusting out the pension scheme asset, and intangible assets. Cash position is fine.
.
My opinion - the figures look good. Although I think it's important to adjust the EPS figures down by normalising the tax charge, and possibly reversing back in some of the adjustments (especially pension fund related costs).
My big question, is how did the company achieve such a surge in performance, and is it sustainable? It could have been a one-off surge in orders, or it could be the beginning of a run of strong performance. I don't feel able to judge that, given no knowledge of the sector, nor its competitors. I think finding out about that should be the key focus of investors research. Remember that, when competitors find out how a company is achieving strong results, then they copy it!
Overall though, I think this looks interesting & worth a closer look.
If we're going into a global recession, which strikes me as likely due to coronavirus, then orders could be delayed, or dry up. Therefore, I'm not sure this is necessarily a good time to buy the shares. But it's on my watchlist for a possible purchase later on, when the situation becomes clearer re coronavirus.
I have to leave it there for today. See you tomorrow.
Regards, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

53 comments
The Equity Development research note on Mpac (LON:MPAC) is worth a read. It is freely available.
On Coronavirus it notes 'Sure there is some supply-chain/demand exposure within AsiaPac (8% of 2019 revenues), but these can be managed. Moreover the vast majority of Mpac’stop line growth is coming from Healthcare(74%)within the US(58%). And besides, there may actually be a minisilver lining, given somecompetitors are located in NorthernItaly, where severaltowns are in lock-down, potentially affecting operations.'
No-one knows what the real impact of coronavirus/recession might be at this stage, but maybe Mpac (LON:MPAC) is more insulated given 75% of its revenue is from the healthcare sector. It'd be interesting to find out more about which companies in healthcare.
https://www.equitydevelopment....
MPAC The nature of the business is project based and, by definition, variable month on month in terms of order intake. A strong focus on our prospects pipeline together with strategic initiatives of operating as a single entity business, 'One Mpac' and driving growth in recurring Service revenue is being implemented to mitigate against variable project demand and deliver consistent financial performance.
This is the coronavirus risk
Can someone explain this anomaly - I have shares in ASLR yesterday stockopedia saw them rise and today crash but the share is suspended -what is happening - any ideas?
There were 2 announcements today which should explain what is happening. You can find them on the Stock report near the bottom under News announcement.
Stockopedia is showing MPAC as a bankruptcy risk
I really think that caution is required if one is considering buying MPAC. In addition to what smig78 has said, why would you want to buy shares in a company that Stockopedia is showing as having negative Net Profit, negative ROCE, negative ROE and negative Free Cashflow? Am I missing something?
I am neither long nor short.
a 7% drop today also, so results not well received to say the least.
I think you are missing something, Stockopedia won't update its figures for a few days, anyway the results are in and they are not all negative. Are you looking at the TTM figures? I don't know the full history but this used to be Molins which was a tobacco machinery company but that was sold off in 2017. I'm not a share holder in Molins or MPAC (LON:MPAC), I'm sure there are others on here that can give you more information. Stockopedia is backward looking so some of the more recent changes may nor be reflected in it's information yet.
I'm a long term holder. These are very decent results - divi reinstated and £19m+ of the Market Cap of £55m is in cash. The business - packaging in FMCG is not going away anytime soon. Cant too much on the pension side, but lots to like imo.
I invested in Nanoco (LON:NANO) years ago, on the suggestion of a high-profile investor. Needless to say it didn't work out, and I dumped it long ago. I'm pleased to report that Nanoco (LON:NANO) is now exactly the kind of company that I wouldn't invest in these days.
Engaging in litigation seems like a desperate ploy to me, a last-ditch attempt to salvage something. It reminds me a little of SCO (Santa Cruz Operation), which was once a highly-respected vendor of a UNIX OS (Operating System). SCO faltered due to the relentless rise of the freely available UNIX-like Linux OS (a system on which I'm typing this message!). Towards the end it resorted to patent trolling. The cause was hopeless, and it died an ignoable death. It took a long time, too! It's actually surprising how long the death throes of a once-great company can be. I don't recall specifics, but investors would have known about a decade prior that the game was basically over.
Not that Nanoco (LON:NANO) was ever in the same league as SCO; not only is it the wrong ballpark, but the wrong ballgame.
Tangentially, a company is still selling copies of the Amiga OS. It updates the OS and makes occasional new releases. The OS isn't compatible with the original Motorla chips. It works on quite expensive hardware, actually. Now, if only they were to get it working on a Raspberry Pi!
There is still a lot of interest in the Amiga, and even conventions! All this despite the fact that the original manufacturers, Commodore, have long been out of business, and the last Amiga produced was around the mid-90's.
Ah, nostalgia, it ain't what it used to be.
I use Linux and was also an Amiga owner :-)
Btw. New Amiga hardware at least was available a few years ago. Look up Amigaone.
For those interested, AROS is a free clone of the Amiga OS targeting Intel x86. Progress is, shall we say, slow. It is, naturally, a very light and nimble OS. I think it has an emulator that works, too, so you can probably run original binaries on it. AROS also runs on a Raspberry Pi using Linux as a host.
Running AROS is fun for awhile, and anyone familiar with the Amiga is apt to say "wow, that's really cool," before going back to whatever system they were using beforehand.
If anyone remembers Aminet, that's still going, too. It has over 80,000 packages, with new uploads every day. It's quite extraordinary that it's still going despite the demise of the Amiga.
I recall for some years Nanoco (LON:NANO) was ramped by that buffoon-like ex-Daily Mail hack, Michael Walters. He who'd pushed 3DM, EDEN and other micro-cap stinkers. An immediate red flag in my book!
To be fair although not the kind of stuff I would get involved in these days he did rec 3DM at 5p and it went to about £2 plus trick was trying to jump off before it crashed back down and went bust get it right and you would have made a packet.
Mpac (LON:MPAC) Hi Paul, very interested in your views. This is an example (for me anyway) of why stop losses don't always work. Bought @110 and then twice more in the 80s and stuck with it in the 40s. I always had faith in the basics. Would also be interested in your views on Devro (LON:DVO) - a similar story but without the glory yet - though for once some decent results and a very interesting comment about their Chinese Plant running as normal.
Re: Proactis Holdings (LON:PHD)
Overall I agree with Paul's analysis. However, I think that saying Proactis 'has conducted a lengthy sale process' implies they went out looking for buyers, when the opposite appears to be the case. In fact I suspect the CEO found the approaches a nuisance but was not in a position to rebuff them, and maintain credibility with shareholders, so I suspect this was rather out of his hands.
My suspicion was the buyers were Private Equity based, as they are always looking for recurring cash producing assets that are undervalued.
However, Proactis Holdings (LON:PHD) were in a structurally difficult position with the business, and I think the repair of the reverse takeover/merger will take some time to sort out. The previous USA based CEO was not up to the job, and I have greater faith in his successor, who is a details man. I suspect the potential buyers just thought the risks were too great for their appetite.
The current CEO has a tricky job however. He is going to have keep the banks onside for a couple of years. Hopefully, he will be successful, but Covid-19 might have been the last straw on the risk profile for the buyers.
Re Proactis Holdings (LON:PHD)
Good analysis Paul and Trident.
With regard the FSP, I think this line in the RNS indicates what might have started it:
The Board recognises that this decision will not have achieved the desired outcome for some shareholders and the Board is committed to working with those shareholders to facilitate their objectives, where possible.
To me this suggests a major shareholder, frustrated with their performance, encouraged one or more approaches. The RNS continues with some governance changes which also supports the argument that major shareholders have been agitating.
cheers
Francis
Good point fwyburd.
Re: Proactis Holdings (LON:PHD)
Wouldn't be the first time they had a poke from a material shareholder. See an old cutting about a previous occasion.
https://www.yorkshirepost.co.uk/business/proactis-slammed-major-shareholder-1876062
I think in the end a share price and a sell out of their interests, put an end to the argument,but I vaguely recall this was the first time I had seen a major investor using something equivalent to the RNS system to voice a disagreement with the Company.
Paul you say "I tend to stay away from any share where the company has conducted a lengthy sale process and nothing has come of it." It is a similar thought process as to why I quickly sold out of my small, speculative holding of French Connection (LON:FCCN) although I believe you still hold?
Yes the potential turnaround story is there but for Marks who believes in the potential not being able to convince a list of suitors of the future value indicates that either the potential is not as great as he thinks or his asking price valuation was higher than anyone else was willing to give.
I honestly don't want to scaremonger.
FT is reporting shipping volumes to China have dropped hugely.
Apparently, the Baltic Dry index — which tracks the cost of shipping bulk raw materials such as metallic ores, coal and grains and is therefore seen as a forward indicator of global economic activity — has fallen 80 per cent from a recent high last September.
China was more or less shut down for about 1 month so that is no surprise, Chinese New Year is a 2 week break which was then extended. China is now trying to get back to normal.
Just wondering how others are playing the virus outbreak? I have gone from 75/25 equities/cash to 50/50 and plan to hold off further trades until it is more clear exactly how much the authorities reaction to the spread will impact human freedoms and economic activity.
I'm going the same way, this could get far worse, the markets are ignoring again a lot of bad news.
I don't trust some of the figures reported for Coronavirus.
Or it might get better too. Always look on the bright side etc.
I can't see that yet.
I've bought more of UK focused companies that have no impact or may even benefit e.g. ITV. Tristel and Reckitt Bekiser may also benefit as they sell disinfectant - particularly Tristel as they are hospital focused but I'm just not keen on either of them long term at the current price but I have held them before.
Another potential beneficiary but possibly not so expensive is PZ Cussons (LON:PZC), makers of Carex handwash and gels. My wife, who has no interest ion shares, pointed out that it might be worth buying some shares after seeing their products out of stock everywhere when trying to buy hand sanitiser for a seriously ill, elderly relative. PZ Cussons have had problems in Nigeria but possibly putting those behind them.
Pz Cussons (LON:PZC) got shares in PZC and am under-water with them. My wife went out to buy some Carex on Monday. Lloyds were out and Boots said it was selling as soon as it was on the shelf! Topped up as a consequence. Also got shares in Tristel (LON:TSTL) - they have absolutely flown since the corona issue took off. They do"antiseptic" in hospitals.
Don’t agree and I am doing the opposite. Bought quite a lot of Hsbc Holdings (LON:HSBA) today and will continue to purchase quality companies with strong balance sheets and a history of paying good dividends . Of course it helps that I am taking a long term view and it does not worry me if I miss the lows as I am sure the price will be much higher when I wish to sell in a few years or so.
I am not really a short term trader although it is really interesting reading all the comments on this excellent site.
That what makes a market. I'm talking more about small caps though. I would not be buying banks, they tend not to do that well in recessions. I have some large caps which I hold mainly for income, yes I may top some of those up. But I want to have a fair proportion of cash so I can buy when this virus is sorted out. I see cases in the UK jumped to 85 today, up 34.
I am 45% cash and expecting substantial falls in indices in due course. I suspect it might be a slow car crash as the number of people falling ill outside China climbs. The central banks can obviously try to prop markets up but why? The real problem is businesses going under in such volume that it effects the banks viability, that is what they should keep their powder dry for rather than extending the good old Greenspan put. Anyway, sorry about the quick rant. I hope it all gets better soon but I don't see any evidence of that at the moment.
Central banks are always pro-active and they have a lot of room to maneuver, I think central banks and gov's everywhere will move to accommodate for this, if they all move in tandem, I would expect a quick rebound in markets. Remember the 10 biggest stock market gains have always followed within two weeks of the largest falls.
What can central banks do? Interest rates are already very low so not much room to manoeuvre there. I'm reading there is not much they can do. I would be interested in your opinion.
Trillions of dollars are held by commercial banks at central banks so the injection of liquidity and reduction in rates which is happening now will push banks into a hard place because they won't want to go long duration at these levels and will most likely push this out into the munis, mortgage backed securities market and corporate bond market.
This will force less regulated financial services like pension funds to push even more into equities.
When the whole world is doing this in tandem, there is little risk short-term, but the market ends up with so much money that it becomes immune to risk - like buying Tesla at 100 year payback period ROI !
Fed has done it, bank of Cad has done it, BofE and UK gov are talking about it, IMF put up $50 bn, ECB and EU govs are talking about it a lot. So seems like more money is coming....
Sounds quite risky to me. But how will that help companies that are going under such as airlines, hotels, travel companies, entertainment and no doubt many others? Some countries are closing schools down such as Japan and Italy that will have a knock effect as some workers will have to be at home. Quite a few large companies are having staff work from home already. The UK govt. are warning that 20% of staff maybe off work it this becomes an epidemic. $50bn does not sound very much to me.
This is from one article I read in the Guardian "However, following the financial crash, central banks have few tools at their disposal to soften economic shocks. Interest rates are close to their floor and central bank balance sheets are still swollen by post-crisis quantitative easing, and it is not clear whether further asset purchases would be effective or politically possible. The burden of responding to the macroeconomic effects of the virus is therefore going to have to fall mainly on governments, using tax and spending tools, and not on central banks."
There also seems to be a serious issue with ships and containers being in the wrong places for global supply chains to operate effectively. It might point to this mess lasting for longer than some anticipate.
I made this point yesterday. This is far from over in my view. Supply Chains are only as good as their weakest link.
Paul I would welcome your thoughts on the RNS from Gan (LON:GAN) yesterday on switching listing to Nasdaq. It will be a first for me delisting on AIM and listing in US.
Common sense from Howard Marks - nobody knows!
https://www.oaktreecapital.com/docs/default-source/memos/nobody-knows-ii.pdf
Thanks for posting this Mammyoko, a great read.
FWIW, fear is more contagious than this virus and whilst we should take it seriously, we should ignore much of the speculation that our politicians, health authorities and media are spreading at the moment. And shame on employers and schools and other bodies who deviate from the generally sensible advice we are being given.
I mentioned a few weeks ago here that my daughter was one of the first 20 UK cases diagnosed with N1NI (Swine Flu). The consequent impact on my family was extraordinary and made much more unpleasant by the fear that was being disseminated by the media. We seem to be repeating these same mistakes today.
Cheers
Francis
We all have to use public/or communal toilets, and it bugs me when you hear a tap being run for two seconds in a hand washing process, and sometimes not at all. So the basics have be dinned into folks, many of whom seem to lack civil or basic health awareness.
The problem is also getting out of the toilet without touching any infected surface, yes many people don't even wash their hands. I rarely use public toilets. A hand sanitiser is a good idea to use after leaving the toilet.
Excellent link mammyoko.
I really like how Howard Marks make the distinction between facts, inference and guesses, I wish everyone who posts would highlight which distinction their comments fell into.
For example a typical post over the last few weeks, could be rewritten as
[FACT] xxx cases of coronavirus in country xxx
[INFERENCE] number of cases are likely to increase over the next few weeks
[GUESS] SELL. SELL, SELL, the market is going to decline xxx% next week.
Yes, TT electronics (LON:TTG) looks interesting but it does have 3 facilities in China and one in Hong Kong. "In 2019, these facilities accounted for 25 per cent of the Group's revenues". In one of the most detailed commentaries I have yet seen on the virus it estimates ".... we currently anticipate that it could impact underlying operating profit by up to £3 million".
Hi Sharw
Thank you for the update. I am currently listening to a live webcast on the results available on Tt Electronics (LON:TTG) website in which it details the situation, which the company appears to have handled very well.
Morning all. Just to let you know that a few weeks ago I wrote an article looking in detail at Mpac (LON:MPAC) 's Stockreport and concluded that it was of higher quality than a mechanistic application of the rules implies. You can find the article on the Discuss tab of MPAC's StockReport.
Mpac (LON:MPAC) is looking like a good turnaround story. As most of its customers are in the food/drinks and healthcare sectors there should be less impact from Coronavirus on sales, but the concern may be more on sourcing various parts for its equipment. Their update today didn't sound overly concern about Covid-19 but it did feel like they were trying to side-step it deliberately in their update. I'm happy to carry on holding here for now.
These are my notes on MPAC written on 22nd February (before the CV outbreak). You'll have to forgive the shorthand as its from my notes.
1. Clear uptrend
2. Fails REM doubling test but its a turnaround. Last R jump was 42% and next is 18% on a PE of 10. So cheap. Also, R growth jumped from 11% to 62% (42% on an organic basis). And PBT turned positive from a loss before. So its a turnaround. REMS are accelerating.
Also order intake up 54% v 0% and service order intake up 75%. Very nice.
3. Very positive news. AOE in Jan which followed an AOE in Sept so AOE on upgraded expectations. Very positive indeed.
4. Debt. Net cash of £4.5m though the Altman Z score is showing slightly in red.
5. CF though not excellent is OK. Net income is very negative but CFFO is slightly negative. Also, very little CFFF (very little debt and equity).
6. Moat. I'd say it has a moat even though it operates in industrial machinery. Normally, they'd be a commodity and cyclical but by being in non-cyclical sectors they have some insulation from the economic cycle. These are healthcare, pharma and food and beverages. And what they do, few can do. Its quite difficult to make machines that do complex things. Barriers to entry are probably quite high.
7. Catalysts
1. £30 Net cash to fund acquisitions. The market is quite fragmented and it allows them to become another SDI or Judges potentially. The recent Lambert acquisition seems very good.
2. Potential to X-sell
3. Increase service income. Bit like lifts or elevators, once installed you can make a mint from the servicing.
4. Could benefit from the AI trend.
8. It's risen a lot and now needs careful price monitoring. Ordinarily i would say it needs to now consolidate at its 50 DMA which implies 300p. Coronavirus may take us there. But, even at these levels (350p), it's a good buy.
DeleteEdit22 Feb 2020
One thing to consider with Mpac (LON:MPAC) is the tax situation: they have recently been receiving credits/refunds and as a result this will boost EPS, but as they have reached profitability that situation may reverse. It will result in a decrease in EPS when they start paying Corporation Tax.
Good morning Paul
I have only read the first few paragraphs of this morning's prelims from Tt Electronics (LON:TTG), but my initial impression is positive. The re-invigoration of the company under CEO, Richard Tyson appears to be progressing well, operating profit margin, cash conversion and order book all heading in the right direction. There is a reference to Coranavirus in the CEO summary but all in all generally positive.
Your views would be appreciated, time permitting.
I wonder whether there might be a positive read across to Volex (LON:VLX), as it cites Tt Electronics (LON:TTG) as the company with which it most compares. However Volex (LON:VLX) has much greater exposure to China and south east Asia, having four factories in the former, whereas Tt Electronics (LON:TTG), although having to my knowledge one Chinese facility has greater exposure to America in terms of operating sites. Just a thought.
I hold both, although have recently reduced my holding in Volex (LON:VLX) due to the disruption in China.
All the best
My morning smallcap tweet: Intu nearly out of options
Intu Properties (LON:INTU) Proactis Holdings (LON:PHD) Nanoco (LON:NANO) PCI- PAL (LON:PCIP) Hostelworld (LON:HSW), MPAC (LON:MPAC), Cambria Automobiles (LON:CAMB), Fulcrum Utility Services (LON:FCRM), Batm Advanced Communications (LON:BVC)
Intu Properties (INTU) has insufficient support for its massive equity raise. Brave face: co has "received several expressions of interest to explore alternative capital structures and asset disposals...will discuss to demonstrate the equity value of the business and to utilise its assets to provide further liquidity". Trading is robust. Valuations of portfolio at 31 Dec gave valuation deficit of £2bn, down 22% for the year. Co could breach covenants in July 2020. I'm short.
PROACTIS (PHD) fomal sale process ends - "superior shareholder value will be achieved by focussing the Group's efforts on delivery of [our] strategy."
Nanoco (NANO) formal sale process: "no firm proposals that, in light of the current market environment, it believes would lead to an offer for the Company...discussions with certain these parties have now been terminated. The Company is continuing to engage with a number of parties to establish whether they are prepared to make such a proposal." Still seeking new funding. I'm short.
PCI Pal (PCIP) H1 rev up 74%. But "timing of large contract wins and delivery of contracts contributing to a delay in anticipated revenue against market expectations for the year". Guides pretax loss slightly higher than market expectations.
Hostelworld (HSW) FY: EBITDA in line. WHat about profit? Covir-19 causing a material reduction in bookings and an increase in marketing cost as a percentage of net revenue. If near term trends persist to end March guides EBITDA hit €3m to €4m for Q1'20.
In line: MPAC (LON:MPAC) Cambria Automobiles (LON:CAMB) Fulcrum Utility Services (LON:FCRM) Batm Advanced Communications (LON:BVC)
Video: Attraqt FY19 results overview by CEO, Luke McKeever.
https://www.piworld.co.uk/2020/03/04/attraqt-atqt-2019-full-year-results/
Attraqt FY results out today. This video covers: Performance, Early Birds, Growth Strategy and Outlook.