Small Cap Value Report (Wed 5 Dec 2018) - WATR, WYG, VNET, JOUL

Good morning, it's Paul here!
Apologies, I conked out after getting back home yesterday, so nothing more got done for the day. Pangs of guilt got me out of bed early today, so let's start with a few snippets of news left over from yesterday:
Water Intelligence (LON:WATR) - the share price rose 7% to 308p (mkt cap of £47m) on a
Positive trading update.
- The company mainly operates in USA, fixing water leaks, partly through franchisees.
- Sales for YTD (9 months to 30 Sep 2018) up an impressive 40%, to $18.5m.
- Profits also doing well;
Underlying profits before tax comfortably in-line with expectations, despite significant reinvestment expenses
There's lots more detail in the RNS - I'd say it's worth taking a look.
My opinion - The valuation looks high, at 35 times this year's forecast earnings, dropping to 28 times 2019 forecast, but I suppose bulls must be hoping these figures can be beaten. This looks quite an interesting growth company.
WYG (LON:WYG) - an "international project management and technical consultancy"
- In line with expectations interim results.
- Full year guidance unchanged
- Order books stable
- Expecting a stronger H2, as usual seasonality
- Divi maintained (yield is quite good, at 4.3%)
I'm not keen on the balance sheet, with a lot of working capital tied up in work-in-progress and receivables. NTAV is under £2m. Doesn't interest me.
Vianet (LON:VNET) - this group owns the "Brulines" beer flow monitoring business, and several vending machine telematics businesses.
- Interim results look OK, if unexciting - which sums up this share actually
- Revenue up a little
- Adjusted operating profit up 6% to £1.8m in H1
- Net debt of £1.0m (worse than net cash of £2.7m a year earlier)
- Interim divi held at 1.7p
Outlook - I can't find anything relating to market expectations for the full year.
My opinion - the PER of 10, and yield of 5.4% look about right to me.
New products seem to take years to develop commercially, and then only on a small scale. Meanwhile the Brulines business faces a continuous headwind of pub closures. So it's difficult to get excited about this share.
Now onto today's results/trading updates;
Joules (LON:JOUL)
Share price: 207p (pre market open)
No. shares: 87.8m
Market cap: £181.7m
Joules, the premium British lifestyle brand, today provides a trading update covering the 26-week period to 25 November 2018, the first half of the Group's 2019 financial year (the 'Period' or 'first half').
There always seems to be something in Joules' trading updates which is unsatisfactory, or ambiguous. Today it's this;
Strength of the Joules brand and flexible 'total retail' model deliver first half profits ahead of initial expectations
What are "initial expectations", and from when? It's not explained. It sounds like the company is trading ahead of expectations, exciting.
The above is then toned down to "slightly ahead of initial expectations, further down the statement (my bolding & italics);
Given this sales performance, the Board anticipates announcing a level of Underlying Profit Before Tax (PBT) that is slightly ahead of initial expectations for the Period.
The full year outlook is then toned down again, to just in line with expectations;
... These attributes, combined with the robust first half performance and a strong Spring/Summer 2019 wholesale order-book, give the Board confidence in the Group achieving full year 2019 PBT in line with its expectations.
The above gives me a feeling that the announcement has been over-PRed. It's much better if things are kept brief, and crystal clear.
Other points;
- Good H1 revenues growth of 17.6% to £113.1m
- International growth is good - is now 16% of total revenues (up from 11.3% in H1 FY 05/2018). USA & Germany are key target markets
- Ecommerce sales now 50% of total retail sales (so about £40m eCommerce, out of £80m total retail sales in H1)
- UK market conditions expected to remain challenging
Brexit planning - this is very interesting, and not something I've seen before from other small caps.
Contingency plans have been put in place to mitigate the expected disruption that could arise in the event of a 'hard Brexit'. These plans include establishing an EU based 3rd party distribution facility; scheduling earlier inbound product deliveries for our Spring/Summer 2019 ranges; preparation for expected increased administrative activities; and hedging US Dollar requirements more than 12 months forward.
That all sounds pretty sensible to me, and probably at minimal cost. If you're supplying goods into Germany, then why import them into the UK first? It makes a lot of sense to set up a German subsidiary company (which wouldn't need any staff at all), and then send imported food goods direct from the Far East, into the German equivalent of Clipper Logistics (LON:CLG) , thus by-passing the UK (and any potential customers bottlenecks) altogether.
Hedging the dollar more than 12 months forward could backfire, if everything turns out to be OK, and sterling recovers.
Bringing in Spring/Summer deliveries ahead of potential trouble in late March 2019, also makes a lot of sense to me. It wouldn't cost much, but could prove very smart, if the ports do clog up as some people expect.
Valuation - given the good growth, and a successful eCommerce operation, this looks an attractive valuation to me. Before the market correction, this share was on a PER over 20. Now it's 14.1, despite nothing much having changed, in terms of the company's performance. This could be a buying opportunity, but who's brave enough to buy right now?!
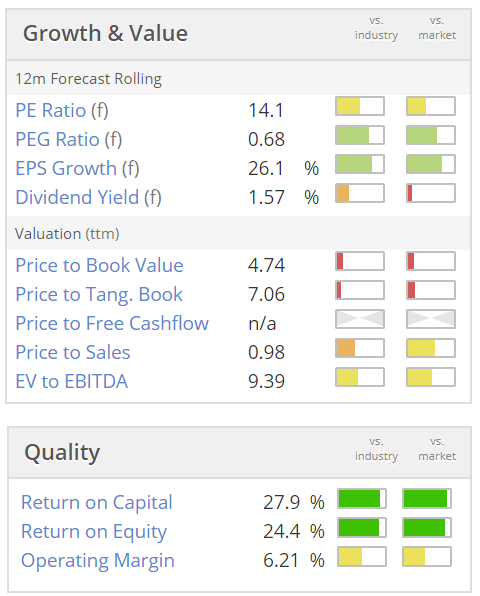
I was expecting to see a strong StockRank, however the Stockopedia computers take a fairly dim view of JOUL;
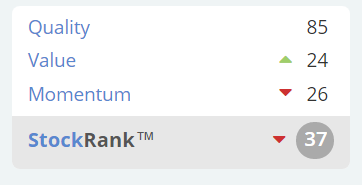
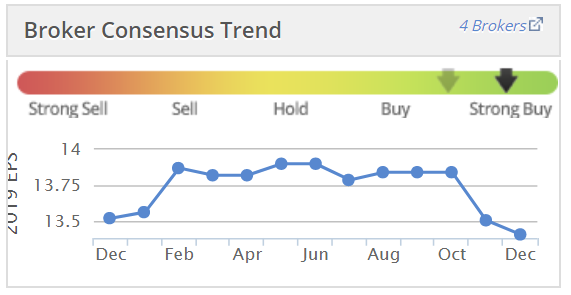
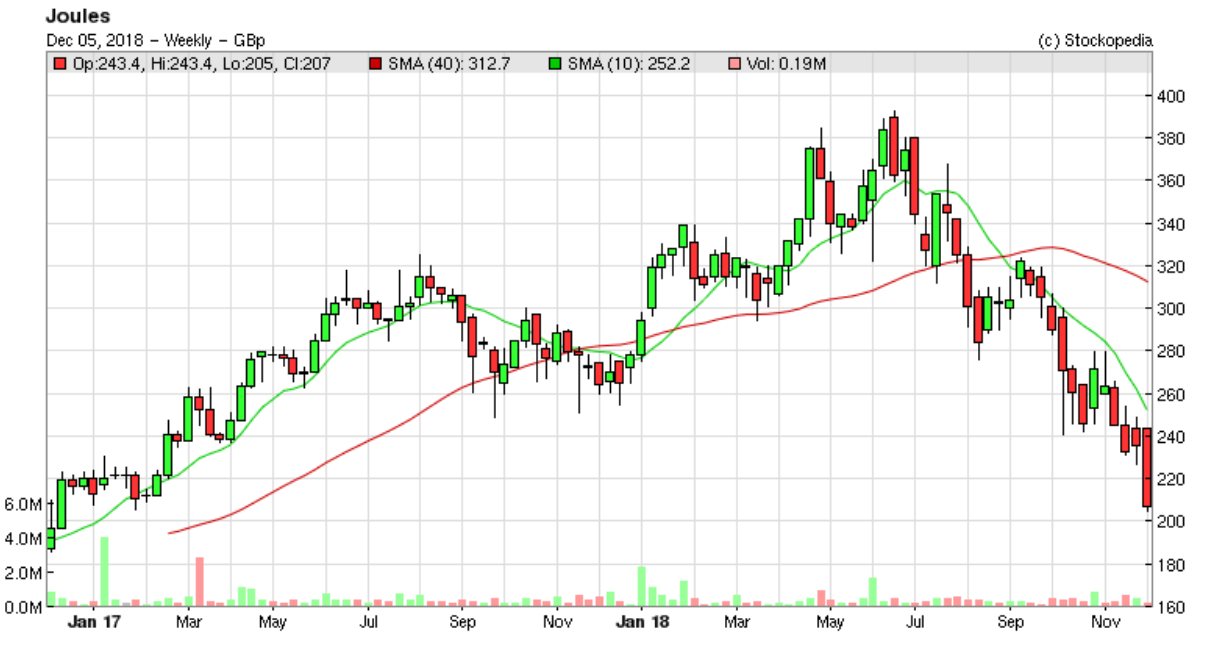
The share price almost halving since July will have pushed down the momentum rank, but also broker forecasts have wobbled, but only slightly;
My opinion - in this case, I'm minded to ignore the low StockRank, because it seems to me that unusual market conditions have pushed down the share price, rather than deteriorating fundamentals. So perhaps this is a time for us to be ignoring share price momentum, or even using it in a contrarian way? Since so many small price movements have really been indiscriminate, and often on low volume, they could be more opportunities than problems?
What I see here is a decent, lifestyle brand, which somehow manages to charge huge prices for (what to me) look fairly ordinary clothes! For example, a red men's gilet is £54.95 on JOUL's website. I've got something that looks identical hanging in my cloakroom, and it cost me £8 from Primark. Still, it doesn't matter what I think - if enough people love the Joules brand, are emotionally engaged with it (a very important point), and are happy to pay high prices for clothes, then that makes Joules a very good business.
Overall, if I had any spare cash, then this share would be high up on my list of possible purchases. Once all the Brexit uncertainty has been fixed, one way or another, then shares like this are likely to be more expensive.
How does this chart make sense, when the company is trading well?
I'll leave it there for today, as nothing else looks of interest to me.
I don't cover financials, Graham does, so if you ask him nicely, he might be persuaded to look at it tomorrow.
Best wishes, Paul
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

46 comments
Beware the Bear!
It might be of some cold comfort to know that as of today, AIM 100 has dropped over 20% from 2018 highs so is technically in bear territory. Probably a statement of the obvious given some of the savage price action of late.
AIM All-Share is down 18%.
FTSE 100 and 350 are more resilient down around 12%. That said only 80 of the 350 shares are above their 200 day moving averages . In the AIM All-Share only 164 of the 818 AIM shares are above 200MAs .
As is often the case, outperformers in 2018 are outperforming in this correction. The temptation to buy shares that have dropped the most is difficult to resist but the perception of value can often be the result of an anchoring bias. Shares that have remained resilient may offer better upside (avoiding defensives and very low liquidity non-movers that is)
The US scare-mongering over yield curve inversion seems to have added to the angst.
Much oversold and overdone in my book but price is truth. Well overdue some relief...where's that Santa man??? Failing a man in red then a man in orange with fat thumb might help
Revolution Bars (LON:RBG) now down 6p at 101p, this price is half of last year's takeover offer at 203p. Consensus pe for 2019 of less than 8. Does anyone have an explanation?
Revolution Bars (LON:RBG) was trading at the 105-110p level in the Summer of 2017.
In the last 12 months since Stonegate walked away:
If Stonegate hadn't bid last year the Revolution Bars (LON:RBG) would likely be trading nearer to 70p/share. It remains to be seen if Stonegate have any acquisitional firepower left to bid again.
At 70p it would be on a forward pe of 5.2 and a yield of 7.5%. Why should it be on such a low valuation?
Re Revolution Bars (LON:RBG)
Earnings per share fell in 2016, 2017 & 2018
The current FY1 forecasts suggests 47% growth in 2019. Does this seem likely in the current economic environment?
Analysts of Revolution Bars (LON:RBG) have no credibility. As mentioned in the previous post, they have already had to cut forecasts by 25% in the past twelve months.
Hence the current FY1 p/e (& hence dividend yield) will likely both prove to be illusory.
"The current FY1 forecasts suggests 47% growth in 2019. Does this seem likely in the current economic environment?"
This is where I fall out with Stocko because the % change figure they give does not compare like with like. The prior year figure is adjusted by Stocko according to its own rules but the brokers' forecasts tend to use the rules used by the company for its own 'adjusted' or 'headline' results. In this case Revolution Bars (LON:RBG) results give:
Adjusted*** Earnings per share 13.0p
*** Adjusted performance measures exclude exceptional items, bar pre-opening costs and share based payment (credits)/charges.
So if you look at somewhere like WebFG you will find forward eps 12.81 -1%.
Hi,
I thought it was interesting to see how much Joules had dropped from its 52w high and I recall Mark Minervini saying that when a market leader puts in a major top, there is a 80% chance it will drop 50% and and a 50% chance it will drop 80%. So I had a quick look at some recent high performers and quite a few are getting or hitting the 50% mark.
Share Drop from 52w High
IQE 56%
Xpediator 54%
Frontier Dev 53%
Learning Technologies 51%
Blue Prism 51%
And some other previous market leaders
Fevertree 41%
Keywords Studio 41%
So are these Black Friday bargain? Or is there worse to come.
You can also use the one-year volatility as a guide. There is about a 50% chance of a fall equal to the one-year volatility from a 52-week high in any given year. (The flip side is that they can be up by a similar amount from their 52-week low when things are going well of course.)
If we look at the volatility of these stocks we see they are very high (and they were fairly high even before the recent falls)
Hi Paul,
Thanks for given your views on Vianet (LON:VNET) , I had a ramble through in the comments on yesterday's SCVR (#64). I managed to get a bit more excited than yourself, but agree that it's difficult (or at least hard work).
Anyway I just wanted to note in terms of outlook, I did draw out the phrase “the overall prospects for the second half look increasingly assured” , I couldn't find that in the code book, but I took it to be equivalent to "comfortably in line" or thereabouts - first thing this morning the consensus eps seemed to be up c. 5%, which I though reinforced my view, but it seems to be marked back down again to 9.0p now so perhaps that reflects the ambiguity?
For newcomers to Water Intelligence (LON:WATR) you may want to read Effortless Cool's excellent post here: https://www.stockopedia.com/content/water-intelligence-the-long-story-195763/
I’m just an embittered ex holder ..I sold underwater at c.90p iirc
Effortless Cool has been spot on with his investment thesis ...I was just a little too paranoid about the way the company was structured/communicated and sold to go to more familiar waters
Thanks, rhomboid1.
We're all embittered ex-holders of something!
Or embittered current holders of something!
Having been burnt on Patisserie Holdings (LON:CAKE), I’m trying to take on board the learning point to be careful if a company looks a bit too good to be true.
So, I’m wondering if Water Intelligence (LON:WATR) falls into the too good to be true category.
They are a partly direct sell, partly franchise operator, so nothing hugely innovative about the business model. They operate in a sector (leak detection) which has been around for decades and where the same technology (acoustics etc.) is pretty much available to everyone and there are no doubt plenty of established small competitors. The pressure to reduce leaks for environmental and cost reasons has been around for a very long time so no change in the market there.
And yet Water Intelligence (LON:WATR) are growing revenues and earnings at a fast rate. I cannot see a clear reason for this or determine how it can be sustainable. If it is true, the competition will react and also want a piece of this lucrative pie (or new entrants will appear) and growth will stall. Or it is not true, as per Patisserie Holdings, then the truth will out in due course and it potentially will crash.
I hope for anyone holding it that I am wrong of course. But for now it is on the too good to be true pile for me.
Graham Ford, there are a number of red flags waving at Water Intelligence (LON:WATR) including:
1. The company has only two Exec Directors, DeSouza & Weigold. Weigold's employment background is in the recruitment industry, which doesn't seem overly relevant to leak detection.
2. It's not clear if who the Finance Director is. He/she makes no appearance in the Report & Accounts which unusually appear to be the work solely of one man (DeSouza).
3. DeSouza's salary $450K seems over-sized relative to the PBT of $1145K.
4. DeSouza is also CEO, President & Director of PlainSightSystems which has a series of Related Party Transactions with Water Intelligence (LON:WATR) , including technology licences & loan guarantees.
These red flags are individually insignificant but in aggregate raise concerns.
Thanks Howard. I had a vague recollection that someone had mentioned before that the management set up at Water Intelligence (LON:WATR) is very “unconventional”.
It’s definitely too problematic for me.
I seem to recall they recruited an Admiral as a non exec too ....presumably because of his familiarity with water
Hi Howard
Thanks for the posting.
I am reaching similar concerns as to who exactly is running Water Intelligence (LON:WATR) ?
According to Investors Chron., there are 10 Institutional Investors who collectively hold 19.43%. Would these have just bought to include Water Intelligence (LON:WATR) into their funds or would they have investigated the company in detail, I wonder?
I am not familiar enough with the first two to comment so I need to dig deeper. Other holders might have other insights to add maybe?
I hold a small position.
Regards
Howard
Hi Howard A,
Regarding the third Institutional investor on your list (Hargreave Hale), I know that Giles Hargreave (or his fellow fund managers) would not have bought just to add. They research their picks a lot.
Hi mmarkkj777
Thanks for that input.
I'm continuing to dig and re-reading Effortlessly Cool's postings and responses which are offering quite extensive insights and are indeed why I picked up on Water Intelligence (LON:WATR) in the first instance.
https://www.stockopedia.com/content/water-intelligence-the-long-story-195763/
Regards
Howard A
Hi, Paul Jourdan is the Amati guy. He comes across as considered and is well regarded in the VCT world I think, but I don't really know if his record reflects those statements!
Regards
Paul
Thanks Howard,
Really good points, and interesting food for thought, as Water Intelligence (LON:WATR) is on my watchlist.
Just one thing, perhaps Weigold looks after the Franchise growth side, which may be a bit more akin to his background. I don't know, just a thought.
Howard,
These are all legitimate concerns regarding Water Intelligence (LON:WATR), and ones that I share. My approach to them is to get a very good understanding of the business, watch it very carefully, and get to know the management. In my view, the risk-reward relationship remains favourable.
However, I will follow up on all of the issues you raise directly and post further in due course.
In the meantime, if I have got this wrong, I will just have to hope there’s a greater fool.
I don’t know Water Intelligence (LON:WATR) at all, but the fact that one of the board’s salary is nearly half of PBT would put me off immediately.
I’ve found through many years (of often costly!) trial and errors in investing that no matter how good a ‘story’ looks on paper, it’s often the small details that are often over looked, that come back to bite you.
For example:
- complex inter group transactions
- related party transactions
- being domiciled outside of the UK, I’m thinking places like the Caymans etc here
- large salaries of board members
- tiny board shareholdings in companies
- loud mouth CEOs, who often believe they can walk on water...
Not an exhaustive list by any means, and it’s not to say that companies who have any of the above are bad investments at some period in time, it’s just that ultimately I find that they unravel. So of course if you’re trading the share, it probably matters less, but if you like to buy and hold then it matters greatly, as one day you might find that you can only exit at a price that causes much indigestion to your wallet!
To be frank, I would say that ruling out investments based on the ratio of board salaries to profits is a clumsy and inefficient method for filtering potential winners. It effectively rules out any early stage opportunities.
A $450k salary is not excessive for the CEI of a quoted company, especially for a US business, and he has conceived what seems to be a winning strategy, and is executing successfully.
As my wife is fond of telling me: “you get what you pay for”.
Not sure I agree with this.
Early stage opportunities should be when salaries for management are low, with upside contained in share options/bonuses if targets are reached/exceeded (in my opinion).
Taking things to the extreme (though to be honest I would expect any small cap company where one person received 50% of all profits as already quite extreme) would you still invest if the MD took 100% of all the profits as a salary, simply because the top line was growing exceedingly fast?
Graham,
Is Water Intelligence (LON:WATR) too good to be true? Perhaps, but I think that there are good answers to the particular concerns that you raise in your post.
“And yet Water Intelligence (LON:WATR) are growing revenues and earnings at a fast rate. I cannot see a clear reason for this or determine how it can be sustainable. If it is true, the competition will react and also want a piece of this lucrative pie (or new entrants will appear) and growth will stall. Or it is not true, as per Patisserie Holdings, then the truth will out in due course and it potentially will crash”.
Revenues are growing rapidly for the following reasons.
Earnings are growing rapidly for the following reasons.
Sustainability is achievable for the following reasons.
Those are my views, anyway.
Thanks for your comments about Water Intelligence Effortless Cool. I would add that the two businesses on which the Water Intelligence is based (American Leak Detection and Qonnectis) were founded in 1974 and 1998 respectively which perhaps demonstrates a degree of resilience. I think the relationships with Thames Water and other utility companies also suggests a degree of credibility as these companies would presumably have done some due diligence on Water Intelligence. Others have suggested the company's performance looks too good to be true but I think you have explained that this is not the case. I must admit I have always thought that Fevertree's performance looked a bit too good to be true but I am glad I bought it a few years ago. I don't think it is a good idea to deliberately ignore the very best companies by linking good performance with risk of fraud - perhaps this amounts to jumping at shadows. However, I would agree that all companies, good or bad, are in trouble if the most senior staff are dishonest.
"these companies would presumably have done some due diligence on Water Intelligence"
A very dangerous phrase - as I've found to my cost more than once.
peterthegreat
"The two businesses on which the Water Intelligence is based... were founded in 1974 and 1998 respectively which perhaps demonstrates a degree of resilience."
Patisserie Holdings (LON:CAKE) was founded in 1926. But the management team that brought it crashing down joined a lot later. So for me it's as much a question of current management rather than the business per se.
Patrick DeSouza became Exec Chairman of Water Intelligence (LON:WATR) in 2010. The key question that shareholders must surely answer is "Is Mr DeSouza running this company for all shareholders or mainly himself & his Related Parties?". The Report & Accounts maybe suggest the latter.
"I think the relationships with Thames Water and other utility companies also suggests a degree of credibility as these companies would presumably have done some due diligence on Water Intelligence."
Small companies with 'blue chip' client bases often get into trouble, not least because the latter can dictate contractural terms. For example, the AA, Saint Gobain, EON, Iceland, Shell, Scottish Power, Direct Line Group are all clients of Trakm8 Holdings (LON:TRAK) , which has suffered a never-ending spiral of profit warnings in the last couple of years.
Joules (LON:JOUL) looks attractive on an earnings basis but historically it has generated little cash. It has lots of positive KPIs and impressive revenue growth - which management present very clearly - but minimal cash flow. This is partly down to the purchase and construction of a new head office which they are spending £16-£18m on over 2-3 years (according to FY18 accounts). 10% of market cap on an office looks punchy to me. You can make the case that once this work is completed and if growth continues it will generate attractive free cash flows but the lack of free cash flow today, despite several years of strong growth puts me off purchasing.
Hi Tristan,
That's not right. As you can see from the abbreviated cashflow statements below, JOUL generated strong operating cashflow in both the last 2 years. It then chose to spend that on expansion capex (i.e. opening new stores).
So it's a cash generative business in expansionary mode, not a business that generates little cash. That's a key difference!
It's an interesting point that your raise about the amount the company is spending on a new HQ as looking excessive. Mind you, I think Laura Ashley Holdings (LON:ALY) won the accolade for bonkers HQ spending some time ago, when they bought a (since sold) big office block in Singapore.
Regards, Paul.
Hi Paul,
Re Joules (LON:JOUL) cash flow. Yes they generated operating cash flow of £15m but they then spent £8.4m on fixtures and fittings and £4.2m on IT. As they don't break out growth capex and ongoing maintenance it is hard to know how cash generative the business really is. Depreciation and Amortisation was £7.8m so it is fair to assume that over half of operating cash flow is needed to maintain the business - before crazy head office expenditure!
Tristan
Tricorn (LON:TCN) Interim Results For the six months ended 30 September 2018
Tricorn Group plc (AIM: TCN.L) the AIM listed tube manipulation specialist,
announces its unaudited interim results for the six months ended 30 September
2018. Highlights (comparable six months ended 30 September 2017)
Earnings per share increased 52% to 1.52p
· Profit up 49.5% to £0.553m
· Gross margin up 0.5%
· Improved profitability of the Transportation division
· Continued growth in profits from the China Joint Venture
and yet down 17% as I write. Thoughts and analysis welcomed.
This may have done it for the share Tricorn (LON:TCN) price:
"Over the past two years, we have seen significant growth in our end markets. However, towards the end of the period, we witnessed signs of this growth slowing. Against this background, and after considering the impact of new business wins, the Board anticipates Group revenues in the second half to be similar to the first and full year underlying profit before tax to be in line with market expectations"
Thank you. It seems likely this was the trigger. SP recovering now, down 4 ish %.
All the best
It does seem like an overreaction given the PBT is still in line - as Tricorn (LON:TCN) said in October although they did not warn about flat revenue for H1 so we'd already been guided that revenue growth was flat.
The attraction with this share remains dramatically improved profits and eventually falling debt I hope. I was happy to hold still this morning although the timing of my buy last month at 25p was terrible!
Good morning mercury61
Re Tricorn (LON:TCN)
I think this statement probably caused the sharp share price drop. People are probably reading this a statement that growth is slowing and may even revers
"Over the past two years, we have seen significant growth in our end markets. However, towards the end of the period, we witnessed signs of this growth slowing. Against this background, and after considering the impact of new business wins, the Board anticipates Group revenues in the second half to be similar to the first and full year underlying profit before tax to be in line with market expectations."
All the best
Good afternoon. Thank you for your post and information.
All the best to you too
Numis (LON:NUM) reported today, revenue rose - slight beat against estimates and they say that Mifid II hasn't had too much of an impact on them from a revenue perspective, 6% higher than prior year in their equity division. However profits down 17% due to increased costs. Currently hold a long position but considering selling.
Paul, can you write up PCF. Thanks
Simon, please put a £ sign before the ticker symbol, then you won't necessarily get thumbs down. A reason why Paul should cover it would be nice too.....
.....so, Paul, please can you cover PCF (LON:PCF) today, who have announced excellent prelim results with eps 5% ahead of forecasts and progress a year ahead of internal expectations.
Paul does not cover financial shares.
Graham is a PCF (LON:PCF) holder, so perhaps he may comment. It is well worth reading his earlier posts here. He is both positive and critical.
My morning smallcap tweet:
Joules (LON:JOUL), Brave Bison (LON:BBSN), Taptica International (LON:TAP)
Joules Group (JOUL) H1 trading: profits ahead of 'initial expectations' but still guides FY in line with its expectations. H1 rev up 18%.
Brave Bison (BBSN) guides FY ahead of management expectations. Rev up at least 10%, adjusted EBITDA positive for the first time since IPO 5 years ago. Holders will have tears in their eyes as the end of value destruction dazzles and dances on the horizon..
Taptica (TAP) has accepted the resignation of Hagai Tal . A divisional CEO becomes interim CEO. I hold.
Taptica International (LON:TAP) confirms board’s acceptance of CEO Tal’s resignation and appoints an interim replacement from within the group (Rivi Bloch) pending recruitment of a permanent replacement.
https://www.investegate.co.uk/taptica-int--ltd--tap-/rns/director-update-and-appointment-of-interim-ceo/201812050700034516J/
Nice soothing noises about (low) impact of his departure on the business. Let’s see what the market thinks.
Gus.