Small Cap Value Report (Wed 5 July 2023) - CRN, SMV, SUP, REDD, EQLS, PAY

Good morning from Paul & Graham!
Today's report is now finished.
I've finally finished my half-year roundup of my 2023 top 20 watchlist of small cap ideas, so that article is here. I'm pleased with the performance, which is up 7% YTD (plus divis), in a market where the benchmark I use (AIM all-share) is down 10%. Not bad!
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £1bn. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk.
As usual, we'll focus first on the price sensitive announcements (above or below exps) -
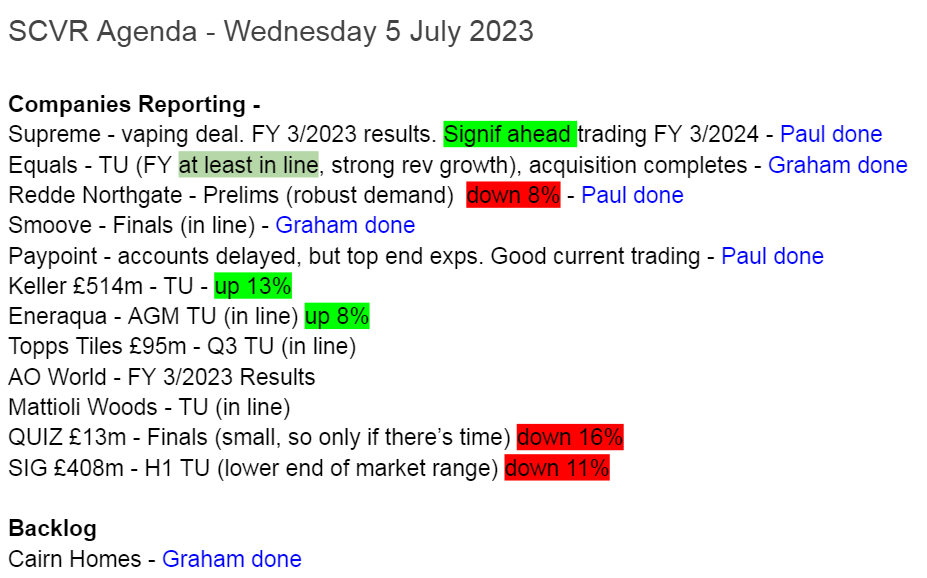
Summaries of main sections
Cairn Homes (LON:CRN) - down 1% yesterday to 99p (£684m) (€799m) - H1 2023 update - Graham - GREEN
This Irish house builder reaffirmed and updated guidance for 2023. There is slight pressure on margins due to cost inflation but overall it’s an encouraging update. I’m intrigued by the company’s buyback policy. With macro tailwinds supporting it, I’ll give it the green light.
Smoove (LON:SMV) - unchanged at 36.5p (£21m) - Final Results - Graham - AMBER
Losses have widened and cash has halved at this company that helps make home buying easier. Remortgage activity is huge but low-margin. It will be very risky to continue as a standalone company so I would accept a reasonable takeover offer (talks continue).
Supreme (LON:SUP) - Up 12% to 117p (£138m) - Final Results - Paul - GREEN
I review FY 3/2023 results, but focus more on the "significantly ahead" outlook for FY 3/2024. The result is a modest fwd PER of under 10. Bal sht is OK. The only downsides are ethical considerations over vaping (its main products), and founder mgt controlling too much, at 57%. Otherwise, looks very good, hence my GREEN view.
Redde Northgate (LON:REDD) - Down 8% to 347p (£866m) - Preliminary Results - Paul - GREEN
In line results for FY 4/2023, and a reasonable-sounding outlook. So I can't fathom why it has fallen 8% today. PER of 6.2 is now below the 6.9% divi yield, plus buybacks. Looks very cheap. Maybe profit on disposal of vehicles may not be sustainable? Cheap debt lasts for several more years, and the bal sht is rock solid. Overall, there's lots to like here for value/income investors.
Equals (LON:EQLS) - up 3% to 99p (£180m) - TU (at least in line) - Graham - AMBER
There is “upside risk” to forecasts as revenue momentum continues to build at this diversified fintech/payments group. They have also announced a small acquisition in Belgium, opening up Eurozone markets. This one may be worth investigating further.
PayPoint (LON:PAY) - Down 2% to 458p (£332m) - Postponement of FY 3/2023 Results - Paul - GREEN
Reconfirms previous guidance, whilst also saying the audited results are delayed due to a technical matter re recent acquisition. Doesn't sound serious, assuming mgt are being honest. We've been positive on this value share 3 times before in 2023, and it still looks attractive, especially for income, to me.
Paul’s Section:
Supreme (LON:SUP)
Up 12% to 117p (£138m) - Final Results - Paul - GREEN
Significant Vaping Distribution Agreement - says it has been appointed distributor for 2 other vaping brands. This is expected to add £25-30m revenues, and £2m incremental adj EBITDA for FY 3/2024 - that’s about 10% additional EBITDA (actual FY 3/2023: £19.4m), so useful extra business.
This is quite an interesting development, for third party brands to use SUP as a distributor. I wonder if that opens up further growth potential, for other additional products to be bolted on to SUP’s distribution network to many retailers of various sizes?
Management at Supreme are clearly entrepreneurial, and seem capable at spotting niches to grow into.
Strong headlines here -
- Robust trading across FY23 and a particularly strong second half, underpinned by an outstanding performance from the Vaping category and earnings-enhancing acquisitions
- Record levels of cash generated from operations
- Very positive outlook, supported by a significant profit upgrade for FY24
The outlook is more important than the historic figures, so let’s focus on that -
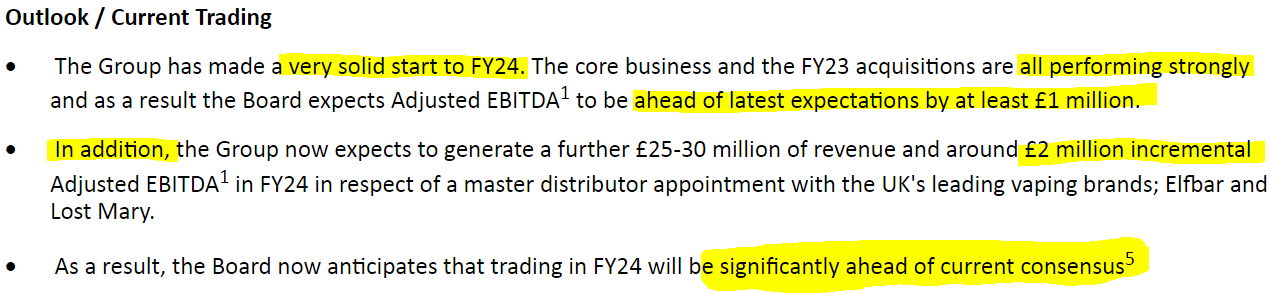
5Company compiled analyst consensus for the year ending 31 March 2024 prior to the release of this announcement and the vaping distribution opportunity announcement (dated 5 July 2023) was revenue of £159 million and Adjusted EBITDA1 of £22.6 million.
I’m not keen on the focus on adj EBITDA. I prefer adj PBT, and EPS, as more meaningful profit measures.
Equity Development produced a research note in April 2023, forecasting as follows -
FY 3/2023: £19.4m adj EBITDA, becomes £14.0m adj PBT, and 9.4p adj diluted EPS.
FY 3/2024: £22.6m adj EBITDA, becomes £16.2m adj PBT, and 10.6p adj diluted EPS.
(NB. these figures are before today’s upgrade)
I haven’t seen an update from ED yet, but expect there is likely to be raised forecasts shortly. At a guess maybe 12-13p EPS looks on the cards for FY 3/2024 now?
At today’s increased share price of 117p, that’s a forecast PER of 9 to 9.8x - still very reasonable, cheap even - providing profits are sustainable. There have been negative surprises before with this company - eg the lighting division seemed to suffer from lumpy orders in the past, and I’m not sure that part of the business is any good. The share price is still barely more than half the 200p-level where it settled in the year after floating.
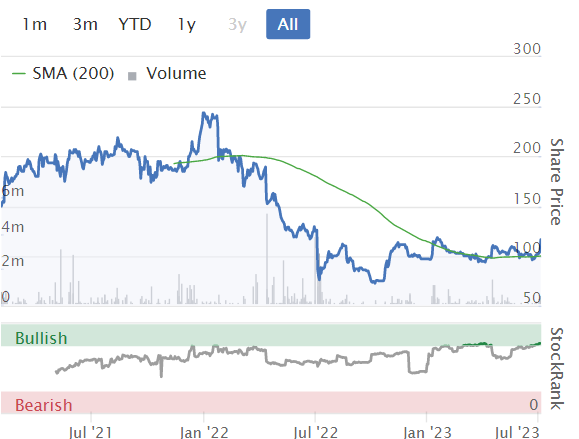
The bulk of revenues comes from vaping, which I personally wouldn’t invest in, as it’s doing so much damage to young people in particular, but that’s a choice for each investor to make, so it won’t affect my colour-coding of this share.
Bear in mind that FY 3/2023 adj profit did fall, to £15.2m, down 13% from £17.4m a year earlier. So the growth anticipated this year, FY 3/2024, is only getting profit back to where it was 2 years ago. Hence why I wouldn’t be inclined to chase this share too much higher.
Net debt has gone up, from £4.0m LY, to £11.8m at 3/2023. However, that includes £15.0m lease liabilities. So proper net (bank) debt is actually net cash of £3.2m, which looks fine. The cashflow is good, and has absorbed £11.6m capex & M&A costs this year.
Balance sheet - looks fairly healthy. NAV is £40m, less intangibles of £15m, gives NTAV of £25m, which is OK.
Paul’s opinion - a strong update today, combined with a reasonable valuation, means I have to see this as GREEN, consistent with our positive reviews of this share previously this year, in Jan, and April.
A negative is that management has too much skin in the game, at 57% shareholding.
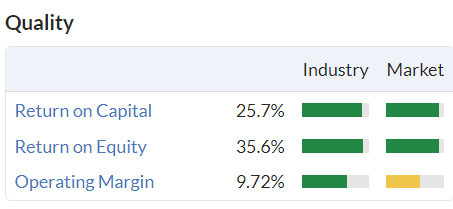
Note the quality measures are good, which is quite unusual for a low PER share -
Redde Northgate (LON:REDD)
Down 8% to 347p (£866m) - Preliminary Results - Paul - GREEN
After doing a quick review of the numbers & outlook, I’m struggling to understand why the market has reacted negatively, and pushed the price down 8% this morning?
This group is a substantial business, owning about 130k vehicles, which it leases out (vans), and operates credit hire replacement vehicles for insurance companies (cars).
Key numbers today, for FY 4/2023 -
Underlying EPS 55.6p (slightly ahead exps), up 10% - low PER 6.2
Dividends total 24p - good yield 6.9%
Buybacks of £60m also done in the year, so this business is clearly a big cash cow.
Profit on disposal of vehicles is large, at over a quarter of total profit - this may not be sustainable, as REDD has probably benefited from vehicle supply restrictions which have inflated used values.
Net debt looks high at £544m (+£157m leases), but this is funding for vehicles with a book value of about £1.3bn, so in that context, debt is actually fine, not a problem at all.
Note that of the £544m debt, £330m of it is super-cheap loan notes charging only 1.3% interest, and repayable between 2027-31. So REDD will enjoy highly competitive funding for several more years, helping boost its profits.
Outlook sounds fine, although it doesn’t say much -
We continue to enjoy robust demand as we start FY2024 and our recent signing of a further multi-service outsourcing contract for Redde reflects our healthy new business pipeline. With exciting opportunities across the platform, we expect to continue to make strategic progress; together with good momentum in the business we are confident and are well-placed to continue to create long-term value for shareholders.
InvestorMeetCompany webinar is on 13 July.
StockRank is very high, at 96.
Paul’s opinion - I don’t know why the market is so gloomy about the valuation here. Possibly it’s factoring in a gradual decline in used vehicle disposal profits? Although broker consensus for FY 4/2024 is little changed from actual earnings in FY 4/2023.
A dividend yield of 6.9% that is above the PER (of 6.2), combined with most of the share price being tangible asset backed (NTAV is £753m) has got to be very tempting for value investors.
So I have to view this share positively, GREEN.
It does have major contract risk though - I recall a few years ago, it lost a big insurance company to a competitor, and the shares took a plunge, but later recovered.
The dividend track record at REDD has been superb, over many years. So providing nothing fundamentally changes for the worse, then this could be a nice income share to buy & forget.
I’m not keen on the credit hire side of the business though. This has been problematic in the past, when unexpected regulations change, or insurers change their approach. For that reason, personally I wouldn’t want to hold an over-sized position in this share, but rather hold it as a basket of higher yielding shares, to spread the risk.
Ownership is fragmented, so it could become a takeover bid target maybe?
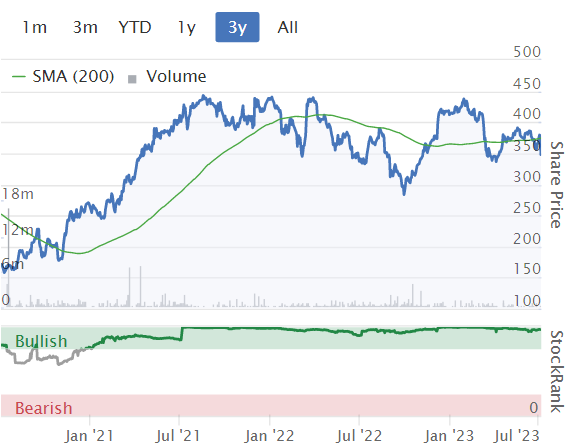
Stockopedia likes the numbers too -
PayPoint (LON:PAY)
Down 2% to 458p (£332m) - Postponement of FY 3/2023 Results - Paul - GREEN
Auditors KPMG need more time to review a “technical accounting treatment” re the acquisition of Appreciate Group. That doesn’t sound serious.
No date is given for when the results will be ready.
Guidance for the figures is provided, and sounds positive - although this is just repeating what it said on 2 June (also saying at top end of expectations), and on 20 April, so it’s not new news (hence use of the word “reconfirms” -
The Board reconfirms that Group net revenue, excluding Appreciate Group, is expected to be around £125m (FY22: £115.1m) with accelerated revenue growth across all three business divisions.
The Group anticipates that profit before tax for the financial year ended 31 March 2023 will be at the top end of the range of market expectations, excluding exceptional items and Appreciate impacts since completion of the acquisition, driven by the strong momentum across the business.
Current trading - sounds OK -
Trading early in the current financial year has been positive, continuing the performance seen in FY23. We have detailed execution plans in place to capitalise on the positive momentum built up in our key growth areas of card processing, Open Banking, parcels, integrated payments and the new Love2shop division (previously Appreciate), delivering profitable growth in our retail and card estates, further enhancements to our proposition and positive new business growth in key target sectors.
Valuation - very attractive yield in particular, at 8.6%, which is above the PER of 8.4 (coincidentally similar to REDD also reviewed today).
Paul’s opinion - this looks an attractive value share, that we’ve discussed here many times. The question that always comes up is over the longevity of its core product, payment cards for utility meters. Hence why it’s trying to diversify. The Appreciate acquisition looked canny, and a nice bolt-on.
We’ve reviewed PAY 3 times earlier this year, and been GREEN each time, due to the value. I’m not worried by today’s audit delay, so will remain GREEN. That’s obviously making an assumption that management are trustworthy, and that there are not any hidden, undisclosed audit problems.
Graham’s Section:
Cairn Homes (LON:CRN)
Share price: 99p (-1% yesterday)
Market cap: £684m (€799m)
As far as homebuilders go, this is a young company, founded only in 2014. We haven’t discussed it before in this report. It is based in Ireland.
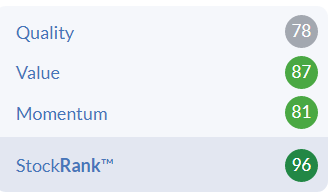
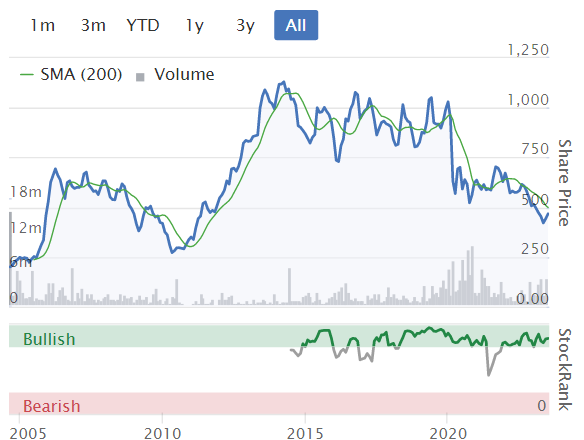
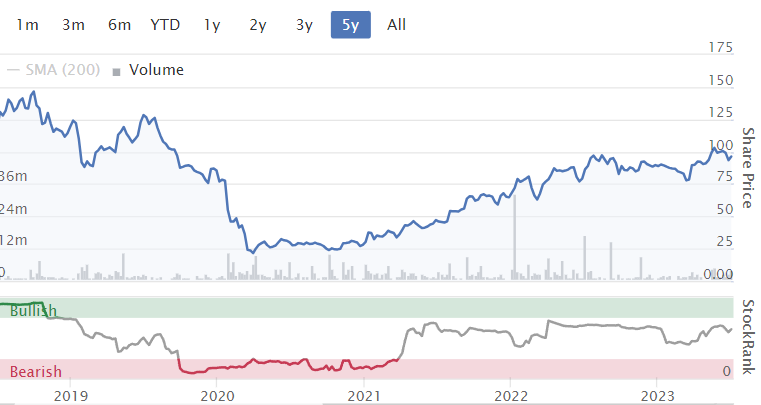
The stock started paying dividends in 2019, but capital appreciation has been limited:

Let’s catch up with their latest H1 trading update. The RNS does not include any of last year’s figures, so I’ve manually looked them up:
535 new home sales (last year: 547).
Total core revenue €215m (last year: €240m).
1100 homes went “sale agreed” (last year: 750)
Pipeline valued at €800 million (last year: €690m)
Pricing is “relatively flat in the period despite persistent, if moderating, build cost inflation” - should we be worried about margins?
Dividend: interim dividend will be set at 3.1 cents (2.65p).
Macro backdrop: housing is a controversial topic in Ireland, perhaps even more than in the UK, which is primarily due to a desperate situation in rentals (I cannot even bring myself to call it a rental market at this point!). Conditions for homebuyers are more reasonable and first-time buyers of new homes benefit from a range of policies including an extremely generous €30,000 tax refund (“Help to Buy”) - this in turn boosts the prices achieved by the likes of Cairn. However, the continued existence of Help to Buy is not guaranteed beyond 2024.
Here is what Cairn have to say about the macro backdrop:
Government surplus of €10 billion expected this year, with forecasts for large surplus until 2026
Housing policy is very supportive thanks to “Housing for All” strategy - includes various home builder rebates and a “cost rental subvention scheme” (GN note: this provides funding of up to €150k per unit to incentivise developers to produce cost rental housing).
Thanks to government support including Help to Buy and a shared equity scheme, 30k new homes have been completed for the first time in over a decade.
The mortgage market remains strong with first time buyer drawdowns up 7% in Q1 2023.
Guidance - full year guidance is “reaffirmed and updated”. Cairn expects “another year of growth across all key financial and operational metrics”.
Expected results:
Turnover in excess of €650m from 1750-1800 closed sales (total revenue last year: €617m).
Core gross margin c. 21 (gross margin last year: 21.7%).
Operating profit €105-110m (last year: €103m).
Their return on equity target is 15% - the StockReport suggests that they achieved 10.6% last year.
Graham’s view
My overall impression of Cairn is positive. Management seem to be credible and their developments are in prime locations or highly attractive commuter zones.
I also note the large buyback activity happening here. The company spent €75m buying back its shares last year, and is currently spending €40m on a new buyback. These are large numbers for a company of this size; the share count has reduced from a high of 771 million to a latest figure of 672 million.
The company is doing what I think most companies should probably do when they are on a humble single-digit P/E and they think their profits are sustainable: they should call the market’s bluff and start reducing their share count.
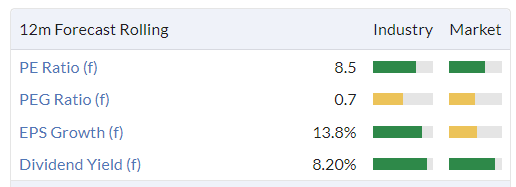
Are Cairn’s profits sustainable? It’s always just a matter of time until the housing market has its next hiccup, but I’m inclined to think that there is a growing consensus in Ireland that home construction needs to happen and that the government should not be standing in the way of it happening. It is remarkable to think that it has been a decade since 30,000 homes were built in a year - but at the same time, many people believe that the market could absorb 60,000 new homes annually. Bottlenecks around supply are the problem, not any shortage of demand.
This is not a buy-and-forget type of stock (I doubt that any house builder is), but I am willing to give it the green light primarily due to their aggressive reduction of the share count. Earnings per share could reach exciting levels if they can keep this up.
Smoove (LON:SMV)
Share price: 36.5p (unch.)
Market cap: £21m
As we learned in April, Smoove is the target of interest from a large Australian group providing similar property-related services.
We don’t yet have news of a firm offer, so Smoove shares remain in play. Here are the full-year results for FY March 2023:
Revenues +7% to £20.6m
Underlying EBITDA loss £4.8m
Statutory loss £5.8m
Cash falls by 50% to £10m (partly due to a return of capital to shareholders).
The loss reflects “investment in the core eConveyancer business and new product areas”. This service has a new user interface and “APIs deepening integration with introducers”.
I see that the company’s conveyancing completions grew by 44% for the year, but this was driven by a doubling of remortgages and a reduction of sales (reflecting broader issues in the housing market). As we have noted before, remortgages are low-margin work.
Post-period end, Smoove began a partnership with Mortgage Advice Bureau (Holdings) (LON:MAB1) and it does sound like a very useful bit of business: Smoove will “provide conveyancing comparison services to MAB's 2000+ Advisers through both Smoove's web platform and Connect APIs”.
Outlook - the current year starts “positively”; remortgages remain “buoyant” and sales are “stable”, thanks to contract wins with brokers.
Here’s an important bit:
The Board reaffirms the profit outlook announced in its trading update of 2 May 2023, which stated that the outlook for FY24 profit is in line with the Board's expectations, but with a different composition than previously expected. As previously announced, the Board expects the Company's cash burn to reduce significantly during the current financial year as a result of the initiatives it has put in place.
Discussions with PEXA around a possible takeover are ongoing. The current deadline for an offer (which may be extended) is 14 July.
Graham’s view
Management reassures us that cost reductions have been implemented and will be felt in the current year, so that cash burn can reduce.
I had high hopes for this stock when it popped up on my radar about a year ago, but the widening losses since then have dampened my expectations.
The company must be very confident that cash burn will reduce, as they were willing to send up to £5m back to shareholders in the tender offer. But it’s not hard for me to imagine that the company might end up wishing it had more cash in a few years - the forecast on Stockopedia is for a £4m loss in the current year (FY March 2024) and the current cash balance cannot survive three years at that rate. Hopefully conditions in the housing market can improve, and help to boost Smoove’s performance.
This is why I said that in the discussions with PEXA, it struck me that Smoove might currently be in a position of relative weakness. After all, if they don’t get taken out now, how confident can shareholders be that the company will make it to profitability as an independent company? I would not feel terribly confident about that.
If I were Smoove, I would bite PEXA’s hand off and take any reasonable offer.

Equals (LON:EQLS)
Share price: 99p (+3%)
Market cap: £180m
This “leading fintech payments group” provides an H1 2023 trading update:
Revenues +43% to £45m (or +21% if you compare to H2 2022).
Gross profit margin over 50% (last year: 47%)
Most of the growth is in the “SME” and “Solutions” segments.
Trading is “at least in line with expectations”, with adjusted EBITDA margins of c. 20%.
Separately announced, Equals buys Oonex for about £4m. Oonex is “a full service payment institution licensed in Belgium”, with regulatory licences, banking relationships, and the ability to issue IBANs in the Eurozone. The deal will “significantly expand the addressable market” for Equals, although it is likely to be loss-making in the short-term.
CEO comment:
"It is very pleasing to be able to report half-year revenues for 2023 that exceed those posted for the whole year in 2021. To have come so far in such a short period of time is testament to the incredible efforts of everyone who works for the Equals Group. Our trading performance clearly shows the success of our focus on the B2B customer segment and the continued growth of our Solutions business. With expanding distribution channels opening up increased addressable markets, we look forward with confidence."
Graham’s view
The growth here is impressive and hopefully it will translate to material profits in the current year: The StockReport suggests net income of £8m on revenues of £88m and that’s in line with the latest broker note from Canaccord Genuity, but revenues of over £90m look realistic. With the company expected to “at least” hit forecasts, I think it’s sensible for the market to start pricing in upgrades right away.
I’m not going to change my neutral view on this yet but if you like growth companies and the fintech/payments space then this one should be of interest.
Momentum has been building here for some time. They do have some B2C products which readers may be able to experiment with, to get a better feel for the company’s operations and any competitive advantages they may enjoy. The current valuation (PER c. 16x) may be justified and reasonable, given the growth prospects.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

85 comments
Top notch smallcp investor Simon Thompson at Investors Chronicle remains a BIG fan of Equals - rating the stock a BUY.
https://www.investorschronicle...
Supreme (LON:SUP) - detailed new note with audio summary - "Strong FY23 results backed by vaping acquisitions": https://www.equitydevelopment....
For the year to 31 March 23, Supreme reported revenue of £155.6m, +19%YoY (with H2 revenue rebounding 27%YoY versus H1 +6%YoY), and (adj.) EBITDA of £19.4m, -8%YoY (compared to H1 -19%YoY). Revenue was ahead of our estimate of £150m; (adj.) EBITDA matched our outlook. The Vaping product segment recorded revenue of £76.1m +75%YoY, 49% of total, with 40% of incremental revenue (c.£13m) generated by the acquired Liberty Flights, Cuts Ice and Flavour Core operations. Even excluding the contribution from acquisitions, we estimate that growth was an impressive 45%YoY. Batteries revenue grew 13%YoY to £39.5m, 25% of total. Lighting revenue declined 43%YoY (£15.4m) due to customer overstocking issues, but H2 recovered 50% on H1. Sports Nutrition & Wellness revenue grew 5%YoY (£16.8m), and the Branded Household Goods & Other segment contributed £7.8m of revenue (-17%YoY).
As of 31 March, the Group was (pre-IFRS 16) cash positive (£3.2m), having generated £19.3m in (net) cash from operations, in addition to which the disposal of TJuice yielded £4.0m. £30m in borrowing facilities offers the potential to grasp further suitable M&A opportunities. Consistent with Group policy of a 25% of net profit dividend policy, a dividend of 3p/share is payable for the year.
Supreme has announced a master distributor agreement in the UK for the popular Elf Bar and Lost Mary (QM600) range of disposable vapes across its retail network; we estimate that in FY24 this could add c.£25m in additional revenue and c.£2.0m in (adj.) EBITDA. The brands are owned by Shenzhen iMiracle Technology Co. Ltd., in China, and are some of the most popular disposable vape brands in the US (e.g. the Elf Bar BC5000).
Reflecting the potential impact of the Elf Bar distributor agreement, we have raised our FY24 revenue outlook by 20% to £194.5m, and (adj.) EBITDA outlook by 19% to £25.6m. Our Fair Value increases to 200p/share, indicative of a FY24 EV/EBITDA of 8.7x.
Have been a member of the Society for over 25 years but rarely buy wine from them . They have a good range at fair prices but I tend to use Wine-Searcher.com to find even better prices !!
my reply to any company who is not prepared to invest in uk...... is don't invest in them by buying their cars
my reply to any (car?) company who is not prepared to invest in uk...... is don't invest in them by buying their cars
I see where you're coming from although I would exclude Teslas on the the basis of their dull exterior styling and interiors that would flatter a Travelodge.
But that mercantilist approach leaves rather slim pickings and certainly nothing outside Tata, sorry JLR, in the premium sector that doesn't come with one compromise or another, eg Lotus, Caterham, Morgan. At least until you're paying Aston, Rolls and Bentley money, which I'm not.
I'm not sure I want to exclude patently superior options from the German premium triumvirate, Volvo, Alfa Romeo, et al based on nationalistic grounds. But each to their own.
Graham, on the subject of Cairn Homes (LON:CRN) do you think there is a danger of the Gov down south imposing some sort of surcharge on builders to help fund the compensation for those affected by the Mica scandal? Similar to the UK gov's stance on the cladding issue. I believe the bill is circa 2.7 billion Euro, far from insubstantial.
It's a subject I am only vaguely aware of, but thought you may be better placed to answer.
For those unfamiliar with it, thousands of homes in Ireland have been found to contain bricks with more than the maximum permitted amount of a substance called Mica, which has the minor draw back of absorbing water, something which has fairly obvious repercussions for bricks and houses. There are now homes all over Ireland, mainly County Donegal, that have cracked brick work that can not be repaired and that surveyors have said will need to be torn down and rebuilt.
More details, in case any one is interested...
https://en.wikipedia.org/wiki/...
It would be a huge injustice and very likely subject to legal action.
Sorry - should have specified a huge injustice on Cairn and Glenveagh
Hi Heron, I don't know enough about the ins and outs of the whole issue, it was just a thought that occured to me while I read Graham's write up.
Thinking out loud, would any potential levy on house builders be dependant on whether they have built houses using Mica, or would the gov just hit all builders (probably above a certain level) with a flat charge/percentage fee to cover the cost?
I hold PayPoint (LON:PAY) - they must be earning a fair amount on the cash balance at the moment. However, interestingly (and I suppose this is what makes a market) Keith Ashworth-Lord said the following in his July 2023 Buffettology factsheet:
Finally, we completed the exit of PayPoint during the month. We had held a number of concerns over this business but the final straw for us was the takeover of Appreciate Group, formerly known as Park Group. We judge management by how sensibly they allocate capital and, despite our efforts to get comfortable with the deal through engagement with management, it had all the hallmarks of an ill-thought out vanity project. Furthermore, we had real concerns the business was becoming over-geared at precisely the wrong point in the cycle, potentially putting the level of dividend – one of the saving graces of sticking with the position – at risk.
....
Thats a fair point re PayPoint (LON:PAY) debt. Its not huge at debt/EBITcrap around 1.5x, dropping to 1.1x March '24 according to Liberum, but it isnt coming down very fast so divi may come under pressure I suppose if business slows.
Id imagine Ashworth-Lord has been selling for a few months. Looking at RNS they started selling in August '22 (5.68% holding) and went below 3% January. Finally out in June?
Private investors have such an advantage over these large holders being able to sell out quickly. On a different note just had a quick look at Buffettology fund performance, have to say its pretty awful since 2020. Warren wouldn't be impressed.
PayPoint (LON:PAY) I can't see where he also said that his return over the last 5-years has been less than 1%. Might have conveniently left that bit out......................
Not all fund managers get their stock-picks right.
Simon Thompson at Investors Chronicle rates Supreme a BUY.
https://www.investorschronicle...
ST has started covering Supreme plc and suggesting it as a strong buy when it was 185p in one of his Alpha Small Company Research.
Mr Paul Hill life is easier when you are clear and honest with everyone and this is the only way you will be trusted by the investment community ( especially in these difficult investment times ).
Half stories are not welcomed here (certainly not by me).
Half stories are not welcomed here (certainly not by me).
Such as acknowledging your personal remuneration from your own business, but not your business’ remuneration from its client/interviewee? It’s just tediously and transparently misleading.
I doubt many of us mind that there’s a commercial relationship. We d just prefer not to be misled.
Yes Stockopedia obviously needs to improve the transparency about its contributors
Mattioli Woods (LON:MTW) and for those of you interested in a full analysis of the 'in line' update - full note published with optimism for future and Fair Value seen at £9 / share. Read it here: https://www.equitydevelopment....
REDD - the debt is up £100m on last year. Are the vehicles really worth the book value? What happens when they need to go over to electric - averave price of replacing the fleet will double. Profit up £50m, debt up £100m, is that sustainable? Has always looked like a carp business model to me due to the high cost of replacing vans and the temptation to not write them down enough. Can the divi be maintained like this? Wouldn't reducing the debt be better than paying such a large divi?
All questions they keep me from buying this one.
Debt is up mainly because of increased growth capex to meet demand so not too concerned about that. It's basically leasing debt so all backed up by assets, and largely long dated fixed at low cost. Interest rate coverage looks healthy (10x) so don't think dividend under threat - I'd imagine they'd stop the buyback before cutting the dividend.
They are still making healthy disposal profits so comfortable that vehicles more than worth the book value. For now, there still seems to be an under supply, so that should support pricing.
On EV transition, I think they look pretty well set up. They have a lot of the charging infrastructure in place and given the extra cost and complexity I'd imagine more companies will look to lease rather than buy.
The asset value of the vehicles swamps the net debt at Redde Northgate (LON:REDD) and are generally marked conservatively. The reality is that vehicles are traded. They buy in bulk from manufacturers to a certain spec so they don’t pay the new prices you’d see at a garage and they sell in bulk to specialist 2nd hand dealers who deal in the private market.
So in answer to your question yes the vehicles really are worth the NAV.
The main risk to NAV is falling second hand prices that then eat into margins. Certainly the company has tailwinds in this regard that will unwind at some point but vans tend to have a different second hand market dynamic than cars so don’t try and correlate your own 2nd hand car experiences to this business.
Specialist businesses like this know what they are doing. The have a model whereby they buy relatively cheaply in bulk, then lease the vans for a period (now algorithmically determined) and sell into private 2nd hand market. The model is by no means “Carp” as you describe it and has been proven over many years with the statistical models continuing to improve.
From an accounting perspective over a single year period p&l can appear volatile depending on how the second hand market is performing but you should really value the business over the asset lifecycle and not in a single period. I don’t think many investors appreciate that about the business.
Redde Northgate (LON:REDD)
As others have commented for higher sales you need more vehicles - debt up by much less than the extra vehicle additions. Note the debt only goes up if keep increasing the sales/vehicle count . The extra £190m million of vans will generate profits year over year.
Should they be paying a dividend whilst increasing debt? - presumably they take the pragmatic viewpoint that debt is less than 50% of the value of the fleet so its well under control - the majority of the debt is at very cheap rates - albeit the added debt looks like it is base rate plus so the marginal debt is preumably at 6% plus. The whole point is that on a tickover year the debt will come down quickly if they are not ramping up fleet size - they could in future chop the divi if needs be (or downsize fleet) . So overall the fact the debt is going up less than the value of the vans (size of the fleet) - on lfl adjusted basis debt per each van earnings its buck is probably down yoy. As a holder i am not unhappy with dividend and sharebuybacks - albeit if interest rates keep climbing who knows what may be the best option going forward. I must admit the market reaction today suggests you are not alone in worrying somewhat about the debt levels.
Supreme (LON:SUP) - you've all picked up on the 'ahead of' and Paul has written it up above. Management are presenting tomorrow at 11am. I suspect a number of you are already registered. The distribution deal is very interesting, with additional strong opportunities in the cross selling of all their other products. Anyway, join us tomorrow to hear more. https://www.equitydevelopment....
Redde Northgate (LON:REDD)
Paul
I’m not keen on the credit hire side of the business though. This has been problematic in the past, when unexpected regulations change, or insurers change their approach. For that reason, personally I wouldn’t want to hold an over-sized position in this share, but rather hold it as a basket of higher yielding shares, to spread the risk.
Interesting point i remember the whole sector used to be very spivvy - does anyone know if thats an unfair criticism now though? I get the impression now that there simply isnt the issue now that used to be present. Does anyone know if i am being over optimistic in that assumption or whether Paul is fimly stuck in the past with regard to his thoughts ref this beinga potantial banana skin? I am not saying they won't get into disputes i am just presuming its not the case now that theyt chuck in ridiculous claims that insurance compnies go to the trouble of actively not paying. Was trying to check debtors comparison for the old redd buisness but cant find an annual report. The receivables figure is high and is a danger somehwhat potentially but at under 1/3 of revenue the debtors book doesnt obviously strike me as being a material worry. Management here seem anything but spivvy with regard to the way the do business so i would be surprised if its anything like what it used to be.
The history of the credit hire sector was indeed spivvy, as you say. But years ago, REDD broke the mould, and started operating in co-operation with the insurance companies, on agreed pricing, and agreed payments. So it's been fine ever since then.
That wasn't really my point. The potential risk I fear, is if something unknown changes. Maybe a regulatory or legal change, or the insurers just decide they don't want to give REDD so much highly profitable, cash generative business any more?
It's not like a normal business model, where person or company A, buys something they want from company B. The Northgate van hire business side is like that, which is fine. But the Redde business is different, where it could be at the mercy of insurance companies deciding they want to do things differently, re providing hire cars to accident victims. So it will never get a high PER, because I think people (like me) are a little wary of that side of the business.
Redde Northgate (LON:REDD)
Thanks for your comments Paul - my viewpoint is that the need for replacement vehicles has always existed in the insurance work/credit side of things - as the need is there if Redd are a large honest player then i dont necessarily see why they need to be at loggerheads with insurance companies. Surely its in both parties interest to get stuff done at reasonable price with least hassle - if Redd do all the admin hassle surely thats worth at least the reasonable margin they are making. In that regard Redd should be better placed than most to provide good eficiency and customer service even to the somewhat variable insurance companies. I suspect its already like that with stuff being done via approved system that only dishes out the work to Redd if the isnurance companines are happy with what they deliver???. IMHO the facts its not really brought up anymore suggests there arent any real issues here - other than the normal risk of giving large credit to anyone. I do know though my thoughts are deffo under researched and may be wrong - so my lack of worry could be misplaced. When i originally purchased i was in for quick buck but i have been supper impressed with what mangement have delivered.
Redde Northgate (LON:REDD) down heavily on what looks good results. Seems to be driven by concerns over drop in free cash flow, as highlighted by one of the brokers. Closer inspection shows they ramped up growth capex in new fleet to meet demand so really don't see this as an issue.
Out of interest have you seen what the brokers have said about EPS estimates? I am wondering if someone has downgraded expectations? I can't see anything but I don't have access to any of their broker coverage
Not that I'm aware of. Outlook was confident so would see no reason for a downgrade. Might get more details once the analysts have gone through all the numbers.
Naked Wines (LON:WINE) i meant to comment on this yesterday but forgot!
very spicy news yesterday, with founder returning. i'm exceptionally interested in their annual report when it is released!
curious to see what their ad-spend is; IIRC it was £35-£40m last year (2022) which is very significant when you consider market cap of £75m-£100m, revenues of £350m~ and suppressed profits of £1m-2m as a result
fundamentally you have a (as of writing) £65m business that produced £20m~ of cashflow in 2020 and £31m of cashflow in 2021, all while recording a net loss (or tiny profit) due to ad-spend. for context, it took writing down a gigantic £60m in inventory in 2022 to make even make a dent in their cashflow (normalised write down is £8m-£15m)
if you consider their ad-spend as growth capex (as the company appears to), as a tap that can be turned on/off or up/down as required (as seems to be their plan), then these numbers are going to get quite silly. i mean really really silly
a £65m business producing £15m pre-tax? £30m+ in cashflow? that can be ran entirely off £1-2m of capital?!? (this is the real knockout blow)
but these are dog-shit numbers according to mr market, which is great banter since any business would kill for this level of capital efficiency and cashflow
incidentally, i noticed that their ex-board member john walden has now taken up a role at Motorpoint (LON:MOTR)
The problem with their ad spend in 20-22 is that it looks like it only generated short term sales. Otherwise, the huge spend should then be a tailwind for revenue growth in Q1-23? But it is not, because they dialed back the ad spend, and revenue followed. So really, they were doing the type of marketing that is just "buying sales". Thats a decent marketing strategy, but the trick there is to have such a great product that you then get customers sticking around and where you can nurture cross-sells and up-sells, generating strong Lifetime Value. This doesn't seem to be the case with Naked Wines (LON:WINE) . A massive rethink of Product, Business Model, and Marketing Strategy is required here...
Yes, I agree with Boon re Naked Wines (LON:WINE)
The huge ad spend is necessary just to stand still, let alone to grow, because of constant customer churn. It's like that with most of the eCommerce businesses I've looked at.
For this reason you can't ignore ad spending as discretionary, and pretend that the business is generating huge returns. It's essential to keep the business going, to replace the many customers that sign up just for the special offer discounted wine.
Virgin Wines UK (LON:VINO) said something similar - that a lot of people shop around with the wine subscription services, take up an opening offer deal (usually half price case of 12 wines), then close their accounts. Then they do it to all the other wine services.
The way I see it, Naked Wines (LON:WINE) hasn't worked as a business model, and it's rapidly running out of cash that has been provided by customers paying up-front. Also it's got into a horribly over-stocked balance sheet position, which could take a long while, and hefty write-downs, to resolve.
Looks very precarious to me. So why get involved? It's cheap relative to previous highs, but is the business actually worth anything, would be my key question? If it's going to fund production of wines, but then not make any profit or cashflow to pay divis, what's the point?
Happy to keep an open mind, and if the facts change, I'll change my mind, as always! The results will be interesting, so I'll spend some time going through those when they're published.
Regards, Paul.
Join The Wine Society - great wines at great prices. No dividends to shareholders. A fantastic organisation.
Re Wine Society dividends. Not entirely true. There are dividends, depending on your expenditure, which accumulate. They get returned to your heirs when you die. At least they did until 12 years ago. My father's lifetime drinking returned a useful, if not princely £300 or so.
I really like the management at Supreme (LON:SUP) but its difficult to value. Must be a risk the government, especially a future Labour government, will legislate in the future.
Scottish government recently were talking to Australian public health loons, with campaigners lobbying for vaping products to be prescription only. Maybe I'm wrong but think Scottish prisons use vapes from Supreme?
Australia are one of the only countries to make vaping illegal. They're also one of the only countries with soaring underage cigarette smoking. Why you'd take advice from Australia us beyond me, but that's politicians for you.
If you want to read quite how mad Australia has gone then this is hilarious. A GP giving his son cigarettes to get off vaping. The whole article has a "reefer madness" vibe.
https://www.theguardian.com/au...
My Granny was a lifelong smoker, due to her GP suggesting she took up smoking to help her deal with the stress of the WWII German bombers coming over her house in Grays, trying to bomb nearby Tilbury Docks, but often getting perilously close to Grandpa & Granny's house.
They had an eye for a bargain, and Grandpa was quite gung-ho about risk, so they bought a nice double-fronted Edwardian house, dirt cheap during the first Blitz, relocating from Cheshire to directly under the path of the Luftwaffe bombers in Grays!. Luckily, there were no direct hits, but the telephone exchange over the was obliterated one night.
Continuing the smoking theme, Granny's home-made cakes were legendary, and sometimes contained fag ash, which would drop into the mixture from the ciggie dangling off her bottom lip. It used to mesmerise us, how several inches of ash would remain dangling for so long.
She even smoked when putting us young children to bed at night, calling the lit end of the cigarette "tinkerbell".
It's obligatory to end stories like this by saying that she lived to a ripe old age, and actually she did, living healthily to 87. Mind you, I don't think she inhaled much of the smoke, she seemed to find it reassuring just to have one on the go a lot of the time.
I doubt she would have approved of vaping.
Excellent little story Paul
The Aussies may be bonkers, but I think that legislation is inevitable here. Vaping is endemic within schools - the kids are acquiring vapes from disreputable shops, and there is a huge market for onwards selling. They have no idea what they are doing, as the vapes are available in all flavours in very child friendly packaging.
Of course, this is no different from what schools were like in the 80s with cigarettes, and vaping is much safer than that, but we don't know if there are long term consequences, and given that these kids are likely to get hooked early on, I think some form of government will happen.
Not anti-vaping (I'm a medic, and see lots of the consequences of smoking cigarettes - vaping is a big part of the solution here), but very much anti the lack of regulation.
Dave
(Indirectly refence to Supreme (LON:SUP) )
We can only make educated guesses as to the direction of government legislation but IF there was appetite to impose further restriction, where might it fall? On the whole of the vaping market...or the market most popular with teens ie disposables. And IF disposables were banned...would supermarkets put refills and PODs on the shelves in their place? And who would they have an existing relationship with to provide such products? All hypothetical questions for now...
Supreme (LON:SUP) and future legislation.
In his Q&A with Paul Hill mentioned earlier Sandy Chadha said the first step should be to make vapes like alcohol - you need a licence to sell and if you are caught selling to those under age you lose your licence.
Beyond that is the matter of disposables being bad environmentally because of the battery sealed within. Supreme started with liquids and rechargeable devices and moved into disposables because of demand whereas Elfbar, synonymous with disposables a year ago, have moved up into also supplying rechargeables.
I asked a question on this at the last results presentation and here is the reply from the company - start 39min 30 sec in:
Most eyes looking at how things will develop are mainly concerned with COP10 at Panama in November. Worldwide views here:
https://www.ecigarettedirect.c...
I believe in regulation of cigarettes, vaping and alcohol. As the son of, brother of and husband of teachers, probably the bigger challenge in schools is social media and mobile phones. Even bigger for the planet is the ongoing climate crisis and hence the UK Governments's commitment to net zero. I genuinely hope that AI is not taught ecology because that could get really dangerous very quickly. I personally remain invested in Supreme (LON:SUP) (but no oil, tobacco or social media companies) but recognise that it is all rather complicated!
Alba Mineral Resources (LON:ALBA) is one of my more forgettable investments, it has raised more cash by way of a Placing to fund the de-watering of the Glogau gold mine and also talks about a Broker Option for shareholders who are seeing yet more dilution of their shares. I would like to know if any current holder of Alba Mineral Resources (LON:ALBA) shares thinks it a good idea to double-down and take up the Option. Or even bad of course.
Silver
Paul, thanks for the six month update. I really appreciate all the bolt-ons you provide like the various spreadsheets and definitely the podcasts - you are a natural broadcaster! Thanks again.
How kind, thanks Biogs! I'm listening to David Dimbleby's audiobook memoirs at the moment, hoping to pick up some tips!
Maybe I missed my calling as a local radio presenter?!
Nice update from Keller (LON:KLR) today.
They hinted at a beat with previous trading update in May so good to see it's come through (with earnings caveat) ...Contract at NEOM now could see this get on a nice earnings roll
Got to say a thank you to Paul who flagged this one up at previous update. I'd not have looked at it otherwise.
I thought Zoo Digital (LON:ZOO) Zoo should have reported yesterday. Anyone know what has happened as there is no RNS?
I think this chart shows just how badly the UK has lagged other developed markets this year. And AIM has been simply abysmal. We have certainly faced an uphill battle as UK small-cap investors!
(H1 returns in local currency terms)
With the changes to share capital gain tax lowered, new investors are not being attracted to shares?!
Hunt has got a lot to answer for and our day will come even if it is in the form of pre-general election sweeteners.
Don’t we in the UK have a very generous system with ISAs and SIPPS? I am not sure how CGT rates compare outside of those? £20k a year is a fair old chunk for most people and I would imagine a lot of people will never pay a penny of CGT on share sales.
Certainly suggests there could be value in small caps. My only worry is that we haven't seen a proper sell off in US stocks for a long time - this will surely come at some point, and don't think UK small caps would escape unscathed if and when this happens.
Not to start a whole hoo ha but Brexit must have had an impact on external investment into the UK. I'm not saying it's the reason but it does have an impact. Be interesting to hear from any International investors based outside of Europe if they think this is the case? Tesla has rescued my PF this year and even Elon Musk said the UK won't get a gigafactory due to Brexit as it's too difficult importing and exporting parts and cars, much easier to open a factory in the EU.
I think we need to base all comments on Brexit on facts & figures, not assumptions, hunches, individual cases, or partisan forecasters. There have been plenty of articles about inward investment into the UK being strong post-Brexit - particularly for services businesses, which don't need to worry about moving physical goods across borders. Equally, as you say, increased difficulties in moving physical goods might put off some investors from building factories in the UK.
It seems to me that Sunak was so short-sighted in hiking Corp Tax up to 25%, when the previous level of 19% was a fantastic attraction for companies wanting to set up in the UK. What an own goal, for not very much additional tax revenue.
UK has lagged for a number of years and it has got worse. My feeling is that the UK is better value and safer in a downturn, it is therefore a reasonable place to invest.
The difference between Aim and FTSE Smallcap x ITs stands out ....suggesting more problems with highly speculative, pre profit business models. Whilst the UK Vs US is frustrating, it is much less so over two years. You can't just look at this in isolation.
My ragbag of stocks is up about 5% ... which is ok. I think Pauls list of 20 shows you a solid return in sensible companies can be achieved... even with a cautious backdrop and everyone waiting for recession. The big Q really is how does it pan out from here? For now the shift to value remains somewhat illusive... and probably needs a cyclical upturn.... which I don't think anyone is expecting.
BUT the new orders to inventory component of ISM is suggesting things might turn up not down. Who knows, maybe, just not being as bad (recession postponed) allows the market to broaden out. Against my better judgement I find myself thinking about adding cyclical exposure ...for a slightly better US outcome helped by China stimulus ... the offset I would look for would be to reduce equities. It will be very interesting to see how the market receives the US CPI number this month....if $ ...bond yields ...and value all react well then maybe the UK can enjoy a better start to the second half. It's also worth noting that £ strength shaves about 5% off the US index returns for a £ investor.
I believe the UK index returns fit the situation actually... it's fairly arbitrary whether they are up or down at the moment since the numbers are small. Yet you shouldn't let this put you off... as they are just averages and under the surface you can uncover the gems...Pauls list has generated a very acceptable return ... in perfectly sensible companies. It annualises in double digit and is likely producing REAL gains...not just nominal.
I continue to fight my tendency to be cautious and wish everyone happy hunting in H2.
Supreme (LON:SUP)
I have seen this para from the Chair's statement pointed out in another place. You won't get every CEO doing this (my highlighting):
Supreme responded quickly to the cost-of-living issues faced by our colleagues and awarded an immediate 10% pay increase to more than half of our colleagues, regardless of location, role or length of service in September 2022. The scheme was directed towards those colleagues who were particularly impacted by the cost-of-living crisis. It is testament to the culture and values within our business that Sandy, our founder and CEO, volunteered to sacrifice his entire salary from then until the end of the financial year in order to finance this in FY23. We realise that our colleagues are one of our key assets, many of whom worked tirelessly through the Covid-19 pandemic and who continue to be pivotal to the future success of the Group.
Vaping ethics aside, Sandy Chadha (CEO of Supreme) appears to be a man of utmost integrity and competence. There's a story of him giving his Bentley away to a man who'd long forgotten he'd made a bet with Sandy 10 years earlier. He's definitely not a typical CEO but maybe that's a good thing. Happy to back him and it's easy to see Supreme being a much bigger business in 10 years time.
Made Tech (LON:MTEC) I know a few of you (myself included) may have had your fingers burnt on this one in the past BUT I see this morning the CEO has just bought another 900,000 shares taking his holding up to 28.5% and in the last couple of months Sarasin & Partners have declared a 5% holding as has Richard Penny of Crux Asset Management. I'm hoping they all have a better picture of what is developing there than I do as I am still annoyed at the last update from May but things can change very quickly and worth keeping an eye on. I hold.
I don't know which company is referred to in the last 3 posts (aero79, Nanotrader09 and greyster). Please remember half the options for reading this are not nested. As Paul says each day in the intro "please ... include the company name/ticker, otherwise people won't necessarily know what company you are referring to".
If you change the drop-down box under replies to 'threaded' you can see who/what ticker they are replying to.
Also, if you click the "in reply to" box at the top of the comment it puts both posts onto the screen
Supreme (LON:SUP)
Good results and even better outlook. Paul Hill interviews CEO and CFO (....and before mojo sets off I expect Paul H was paid by Vox to do this):
https://videos.voxmarkets.co.u...
Keller (LON:KLR) nice trading statement above revised expectations but does mention europe resession
My morning smallcap tweet: Supreme smoking, Quiz choking.
Supreme (LON:SUP) Equals (LON:EQLS) Tintra (LON:TNT) Mattioli Woods (LON:MTW) Bidstack (LON:BIDS) Arecor Therapeutics (LON:AREC) Zinc Media (LON:ZIN) Numis (LON:NUM) Graft Polymer (UK) (LON:GPL) PayPoint (LON:PAY) AO World (LON:AO.) Redde Northgate (LON:REDD) Quiz (LON:QUIZ), Eneraqua Technologies (LON:ETP), Topps Tiles (LON:TPT), Smoove (LON:SMV)
◄Supreme (SUP)► FY-Mar. Guides FY24 significantly ahead of current consensus of £159m rev and adj EBITDA £22.6m. Becomes master distributor for the UK's leading vaping brands, ElfBar and Lost Mary. Guides extra £25 -30m rev and c. £2m adj EBITDA in FY24. [edit] HT to Rhomboid1 on Twitter who notices that the ESG paragraph doesn’t mention their mainstay disposable vapes nor does the longer Vaping commentary. [SP=104.5 Cap=123m]
◄Equals (EQLS)► guiides H1-June rev up 43% and gross profit margins over 50% (47%). Guides FY at least in line. Completes acquisition of Oonex. [SP=96 Cap=175m]
◄Tintra (TNT)► will pay 3m in full repayment and termination of the Placement Facility (announced Dec) with Fintech Leaders Fund. [SP=93.3 Cap=15m]
◄Mattioli Woods (MTW)► guides FY-May rev up 3% and adj pretax in line with £30m f/c. Outlook - "Recent new business development and marketing initiatives, designed to assist clients in understanding the recent changes to pension and tax rules, such as movements in annual and lifetime allowances, have both generated increased levels of new business and resulted in a strong increase of +16% in new business enquiries versus the prior year." [SP=620 Cap=320m]
◄Bidstack (BIDS)► GM requisition to remove Glen Calvert and Lisa Hau as directors and appoint Nicholas Hargrave. [SP=0.9 Cap=12m]
◄Arecor Therapeutics (AREC)► additional agreement with a leading biopharmaceutical company to support the ongoing development of a biosimilar product. [SP=240 Cap=70m]
◄Zinc Media (ZIN)► rev end June won and due to be recognised in FY23 is £31m, more than all FY22. [SP=86.9 Cap=19m]
◄Numis (NUM)► Q3 total rev below H1 half run-rate "reflecting a deteriorating market backdrop across the investment banking industry". Expects difficult market conditions for erst of FY23. Acquisition by Deutsche Bank AG expected to complete during Q3 calendar 2023. [SP=332.75 Cap=366m]
◄Graft Polymer (GPL)► completion and commissioning of a production equipment site in Slovenia (due around the end of July), doubling production capacity. [SP=2.7 Cap=3m]
◄PayPoint (PAY)► FY23 prelims due tomorrow are delayed "due to a technical accounting treatment relating to the balance sheet of the Appreciate at acquisition". Confirms rev in line and pretax at the top end of market expectations, excluding exceptional items and Appreciate impacts. Current trading positive. [SP=467 Cap=339m]
◄AO World (AO.)► FY-Mar rev in line. Outlook - "confident in our ability to deliver on our 5% EBITDA ambition in the short term and returning to top line growth in the medium term". [SP=80.25 Cap=463m]
◄Redde Northgate (REDD)► FY-Apr. Outlook - "continue to enjoy robust demand as we start FY2024 and our recent signing of a further multi-service outsourcing contract for Redde reflects our healthy new business pipeline". [SP=378.22 Cap=867m]. I hold.
◄Quiz (QUIZ)► FY-Mar rev in line. Outlook - Q1 rev down 15% "reflecting the strong prior year comparatives in the first half as well as the impact of the macroeconomic uncertainty and inflationary pressures". Guides FY24 pretax flat as H2 trading environment is expected to remain challenging, [SP=11 Cap=14m]. I hold.
In line: ETP, TPT, SMV
The Quiz (LON:QUIZ) outlook comments make no sense: they say they expect a similar profit compared to last year but that Q1 revenue is down -15% at similar margins to last year and that the second half of the year will be 'challenging'. Their attempt at a positive spin that at least Q1 revenue is similar to pre-pandemic levels is laughable given the inflationary environment since then, so sales volumes must be awful. Also note that cash is down from £6.2m in March to £3.4m yesterday,
Regarding the cash, they say "The cash utilisation since 31 March partially reflects investment in three new stores and the commencement of works to expand our distribution centre".
With a market cap of only £13mn and sales of £90mn+ and PBT 2mn, I feel this is undervalued now. Wary of management lowball bid to take it private or PE buying it on the cheap. I would think 15-20p per share is fairer value, despite pedestrian outlook.
Greyster
Think your correct. Management have been talking this down for some time.
And Q1 was the biggest quarter for Quiz (LON:QUIZ) last year, surpassing even the quarter up to Xmas. So it’s one hell of a hill to climb for the rest of year to just stand still on profits. The release mentions cost increases on salaries and utilities, no surprise - although freight rates are supposedly tumbling. But as the share price drops, you get to the point where issues and risks are priced in, I think personally we’re near that point. Wary of delisting risk for a company this size so would only consider holding in my SIPP to avoid being forced seller.
Quiz (LON:QUIZ)
outlook comments make no sense: they say they expect a similar profit compared to last year but that Q1 revenue is down -15% at similar margins to last year and that the second half of the year will be 'challenging'.
Presuming we take the viewpoint they know more than Patrick L does ref projections - i would say it shows that they are well in control of the finances if they can drive savings elsewhere to clawback the difference elsewhere. As Paul has confirmed previously one plus point is that they have more flexible cost base than they used to.
Note i would say risk is on the downside now ref later profit warnings so you might be right to be skeptical that they can hit stated profit targets - at least we have some that can be fact checked later!!
Also note that cash is down from £6.2m in March to £3.4m yesterday,
Cash should be expected to be up and down - they had £11.2 mill of positive operating cashflow the last 2 years - you cant always have operating cashflow inflows above levels of profits being made. Rather unhelpfully they didnt quote the cash baalnce at this time last year it could simply be normal seasonal ups and downs. Retail is pretty simple if no execptionals cashflow should not really be an issue particularly.
I would agree with your comments ref positive spin - in their defence it is somewhat factual that finding lfl comaparatives since covid has been hard. I dont blame them for pointing out what they did albeit it does fail for the reasons you advise they are probably as wonky comparatives due to inflation in the meantime.
Good morning Paul and Graham
I wonder if one of you would have time to cast an eye over Redde Northgate (LON:REDD) preliminaries this morning.
They look to be a class act , rev up 22% and underlying eps and div up around 10% . With two acquisitions apparently performing well.
Thank you.
There was a one off depreciation gain they mention which flatters results a bit. I hold
Redde Northgate (LON:REDD)
Yep another one for Redde please they managed 100p eps last 2 years - compared to shareprice of 360p !. Must say i am very impressed by the board here - they seem to have done well with regard to widening the net with regard to income and profit sources -one needs to read results to get decent picture ref plans.
The obvious issue here is they have had massive tailwinds having large fleet of vehicles that are hardly depreciating and have probably more potential customers than they can supply. Its easy to make money in that sweetspot zone - the market has rightly not got ahead of itself in that regard though. Looking at core prospects they have probably never been better - so even if the easy profit on vehicle disposals goes and they end up in a place where demand doesnt exceed supply they look well placed to do ok. Its hard to know though what might happen if demand does ever dwindle but the board do seem to be higly competent here.
I don't really understand why Redde Northgate (LON:REDD) down 4% at present. Results looked excellent, divi up 10%, and outlook seemed promising too. Any ideas?
On the Redde Northgate (LON:REDD) price drop, my best guess is that the market thinks the favourable tailwind from high residuals is going to unwind and profits will fall accordingly. Even if that happens, this is a well-managed company with a strong market position. It's a long-term hold for me with an attractive dividend which has just increased. rmillare put it better than I just have... see his post.
One thing I think the market is missing is the significance of the switch to EVs. This is massive: no-one in the fleet sector has been through anything like it. Faced with such major upheaval, I think more and more companies will look to an industry expert like Redde Northgate (LON:REDD) to manage the transition for them, rather than going it alone. Hence good prospects for organic growth for years to come.
Agreed. Just bought more as this is such a well managed company with , in my view, a great future .
Debt up, cash generation down?
It would be great if Supreme (LON:SUP) could be covered today. FY23 was a difficult year for them, but they seem to be starting FY24 better. I hold.
The Quiz (LON:QUIZ) outlook statement in today’s results is downbeat. I look forward to Paul’s analysis of the figures.
Quiz (LON:QUIZ)
the Board currently anticipates that profit before tax for current year will be similar that generated in the past year.
Normally the bad news is hidden at the bottom of the outlook statement - i thought all things considered the fact they say they are on track to be similar to last years pre tax profit figure is pretty good. Ok i suspect the danger is they may miss targets if they a are struggling but to remain decently into posititve numbers is not a terrible result when its known to be tough out there . Obviously the lack of prospect of further positive progress ref sales and profits short term aint great and one should probably not be expecting shareprice to return to recent highs whilst this is the case - but at least on £1.5 mill pa profits they should be generating positive numbers ref buisness finances and keeping the lights on.
I reckon it's nonsense. It doesn't make any sense to be on level profits with last year if they're already down -15% on revenue (which will include inflation so sales volume presumably terrible) at similar margins and with a 'challenging' H2 ahead of them.
Quiz (LON:QUIZ)
As i said i don't blame you for being skeptical - i do applaud any company though that gives us a simple forecast of where they think bottom line will end up that can be fact checked later. Facts are though they know more than us and should be better positioned to forecats than us - if you dont believe them why not email them and ask the question of how - perhaps if Paul gets a chance he could ask that question - it does seem somewhat odd at face value that profits are expected to hold up so well - but they have said it so seems loginal they could expalin it. Perhaps its as simple as them investing in advertising coming out of lockdown and now they can roll that back and similar other things - could be they had high costs for a while whilst streamlining their store portfolio perhaps ?
Quiz (LON:QUIZ) Essentially they said that the H2 comparatives from last year are easier (presumably the postCV19 bounce had already softened). so last years profit levels are reachable. They may not be correct of course, but they are probably in good faith.
I think what people miss with Quiz (LON:QUIZ) is that their entire estate rent cost is pretty much revenue linked. So if revenues drop so do, what people might ordinarily assume, fixed costs. This protects margins and profitability. So whilst the market may be challenging that’s why they can maintain profitability. Plus they are getting a tailwind from dropping variable costs like freight offsetting some other cost inflation.
Management aren’t usually bad at forecasting but in todays market one can never be certain, particularly in the UK which seems to be a basket case of an economy atm and just full of doom.
On a 2 year forward view I think Quiz could do quite well but let’s see. Regarding cash they’ve opened 3 new stores so they clearly see expansion opportunities even in current conditions. Note cash does move up and down cyclically during the year anyway.
Morning! Just a heads-up on some online presentations all on the same registration link, at the bottom:
Tomorrow Tpximpact Holdings (LON:TPX) new management will give a FY23 online presentation at 1pm
- DSW Capital (LON:DSW) professional services company will give a FY23 results presentation on Monday 17th July, 11.45
- Wynnstay (LON:WYN) H123 Friday 7th July, 1pm
- Sosandar (LON:SOS) FY23 Tuesday 11th July, 12.30
Register for all/any of them here.
Morning all,
Supreme (LON:SUP) significantly ahead forecast for FY '24.
I hold.