Small Cap Value Report (Wed 6 Mar 2019) - HEAD, CAMB, ANP, RBG

Good morning, it's Paul here!
Please see above the companies which have caught my eye this morning.
Market conditions for small caps still feel very depressed. The UK small caps space seemed to have a nice bounce in January, but a lot have slid back again. Bad, even only slightly bad, news continues to be punished severely. I think that's mainly because there's a buyer's strike, until we know what's happening with Brexit. So some prices are falling too far, below what makes sense.
Selectively, I see some obvious & compelling value. Today's buyer's strike could well be tomorrow's buying stampede. It's market conditions like we have currently, which lay the groundwork for some big future profits, in my experience. I could trot out that Buffett quote about fear & greed, but everybody already knows it, I'm sure.
It all depends though, on where we are in the economic cycle? This recovery from 2008 looks very long in the tooth now. Is a global recession coming? The recent major recovery in the US stock market suggests otherwise.
We've had 10 years of ultra low interest rates, which has supported equities. What's to stop us having another 10 years of low rates? Will they ever normalise? It's really difficult to know where things are heading, which in turn makes it difficult to value shares.
EDIT: a friend has emailed me several articles, showing that housing enquiries in London are up, and that there is very positive data on construction of high rise buildings planned, especially in London. This is strengthening my growing conviction that we could, perhaps, be on the cusp of a post-Brexit boom. Even if it's a complete muddle (looking very likely), the removal of uncertainty could unleash a backlog of investment. Hence I'm back in buying mode, in terms of my small caps portfolio.
Headlam (LON:HEAD)
Share price: 420p (up 0.5% today, at 09:43)
No. shares: 84.6m
Market cap: £355.3m
Headlam Group plc (LSE: HEAD), Europe's leading distributor of floorcoverings, is pleased to announce its final results for the year ended 31 December 2018.
This looks a mature business (i.e. little growth in profit), and is priced accordingly, so it's a value share. It has grown historically by making lots of acquisitions, funded from cashflow - quite a nice business model.
Underlying profit before tax is basically flat at £43.4m (vs. £43.1m in 2017)
Gross margin was up, which together with growth from acquisitions, offset the LFL decline in revenues (worse in the UK than Europe).
Balance sheet - is excellent, and includes £36.7m in net cash
Dividends - up slightly, to 25p - giving an excellent yield of 6.0%
Current trading - looks good, but not quantified, so probably only slightly up;
Positive start to the year, with both the UK and Continental Europe up on a like-for-like revenue basis...
Outlook - I like that the group has already set up the market to have modest expectations for 2019. This reduces the likelihood of a plunge on a profit warning;
As advised in January 2019, we have taken a prudent view of 2019 and expect revenue to be in-line with 2018 due to the anticipated further general weakness in the UK market, and as a consequence it is anticipated that underlying profit before tax will be lower than 2018 due to a number of factors. These include the anticipated movement in revenue mix and associated margin, the year-on-year inflationary pressure on distribution costs and administrative expenses, and the efficiency initiatives being predominately at an early stage and not yet sufficiently material in their contribution to offset the current weak market backdrop and increases in overheads.
Valuation - as you can see below, this looks a classic value share - a reasonable PER, very good divi yield (and the strong balance sheet makes this look sustainable), plus decent asset backing.
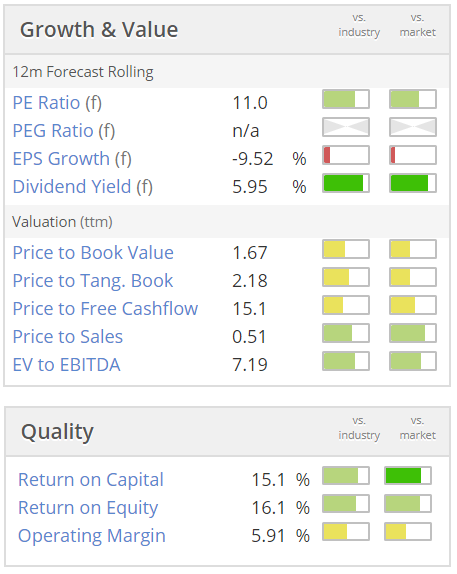
My opinion - this share looks worthy of consideration for a long-term income portfolio, e.g. a SIPP. The divis seem safe, and the company is prudently financed.
Given very wobbly market conditions, and Brexit uncertainty, I'm not convinced this is the right time to rush out and buy it though. I'd probably want a PER of around 8, to tempt me in.
Cambria Automobiles (LON:CAMB)
Share price: 64.5p (down 0.8% today, at 10:41)
No. shares: 100.0m
Market cap: £64.5m
This is a chain of car dealerships.
The Board of Cambria provides the following update on its franchising developments and trading for the five months to 31 January 2019...
Perhaps surprisingly, performance has been good;
The Group's trading performance in the first five months of the current financial year to January 2019 has been ahead of the corresponding period in 2018, both on a total and like-for-like basis.
Quite steep falls in new car registrations seem to have been offset by improved margins. Cambrian seems to be focusing more on high end brands these days.
Aftersales (an important part of profits) are doing well.
Outlook - reasonably upbeat;
Whilst challenges remain given the ongoing uncertainty around Brexit and the terms of the UK's departure from the EU, the Group's ongoing franchising and property development activities have enhanced Cambria's excellent dealership portfolio mix and the changes made in the prior year have further benefitted the Group. These new businesses are still in their infancy, though as they mature, their potential is exciting.
My opinion - I continue to see good value in this sector. It seems to me that any supply difficulties re Brexit are probably being exaggerated, and would only be temporary anyway, which could provide nice opportunities for a post-Brexit bounce, which is the theme of today's report. There again, I am a glass half full person, so some readers may think I'm being too sanguine?
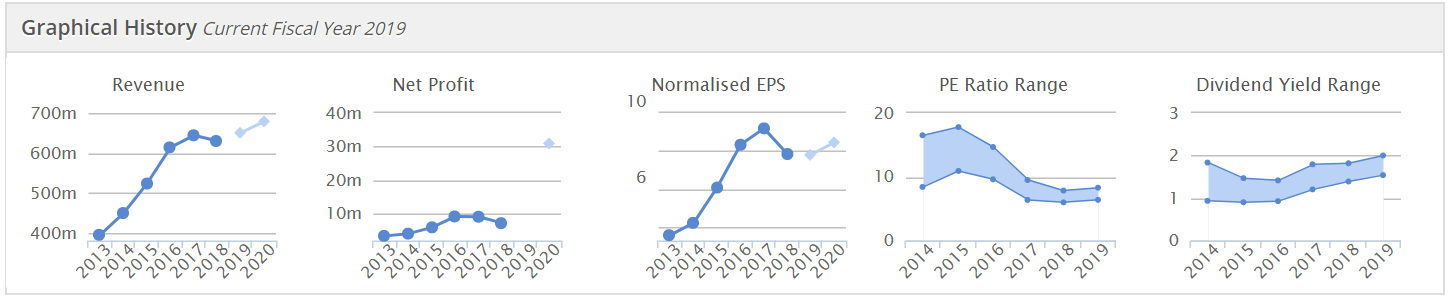
Cambrian's move up-market seems to be working well. See how the rating has come down considerably in recent years. This sector is not only cheap on an earnings basis, but most also have excellent balance sheets with loads of freehold property.
For value investors then, this is an interesting sector to investigate.
One area to look into is the possibility of mis-selling of finance. I read somewhere yesterday that the FCA is investigating car finance. Apparently some dealers or brokers have been given flexibility to change interest rates charged to different customers. That sounds potentially ominous, given the possibility of fines being levied. I'm just flagging this as a risk which readers would need to consider, if buying shares in this sector.
Anpario (LON:ANP)
Share price: 330p (down 2.9% today, at 11:39)
No. shares: 23.2m
Market cap: £76.6m
Anpario plc (AIM:ANP), the international producer and distributor of natural animal feed additives for animal health, nutrition and biosecurity is pleased to announce its full year results for the twelve months to 31 December 2018.
The financial highlights bullet points seem rather misleading. The first two points trumpet profit & EPS growth of over 30%. However, when you adjust for the fact that 2017 included £627k of exceptional costs, and 2018 had none, then the more meaningful adjusted EPS rose from 16.74p in 2017, to 18.9p in 2018, a rise of 12.9%.
This is the figure that should have been presented in the highlights section. I don't like it when companies cherry-pick favourable figures, and gloss over the more meaningful numbers.
Broker forecasts - the 18.9p adj EPS announced today for 2018 seems to be usefully ahead of the 16.9p broker consensus forecast shown on Stockopedia. Although with very limited broker coverage, Peel Hunt, and N+1 Singer, it's difficult to tell exactly. Peel Hunt is closed to private investors, unless you're prepared to pay them about £20k per year to get their superb research (and even then I expect they would say no!).
I note from Research Tree that N+1 withdrew its Anpario forecasts last autumn, due to a change in analyst. Hopefully there might be an update from N+1 fairly soon. So I'm in the dark as to what the future holders, unfortunately.
The PER is 17.5, based on 18.9p EPS
Revenues - actually fell, from £29.2m in 2017 to £28.3m in 2018. I'm not usually interested in companies where revenues are going backwards, even if profit has risen.
Outlook - not madly exciting;
Trading in the current year is ahead of the same point in 2018. However, we remain vigilant as there may be obstacles ahead due to Brexit and African Swine Fever, in particular. Our strong balance sheet and cash generation capability provide Anpario with a firm platform from which to invest in new products and to develop the exciting Anpario Direct opportunity.
Expanding profitable sales and distribution channels around the world remains our priority and the initiatives already implemented are gaining traction. This gives me confidence that we will return to sales growth as 2019 progresses.
Is that positive enough to justify a PER of 17.5? Probably not, in my view, given that we're in a sceptical stock market right now.
Cashflow - deteriorated in 2018, due to adverse working capital movements - although these can be swings & roundabouts. Net cashflow from operating activities fell from £5.6m in 2017, to £3.2m in 2018.
Also, note that capitalised intangibles rose from £624k in 2017, to £1.1m in 2018, flattering profitability in 2018.
Balance sheet - outstandingly good, with a bulletproof working capital position. There is cash of £12.9m, and no interest-bearing debt. Therefore this group has the firepower, if it wanted to, to make acquisition(s) up to about, say £20m - assuming it would be prepared to use all its cash, and take on a bit of debt. That could provide an important boost to future profits (and hence the share price), if thee cash pile is spent wisely.
I'm not keen on profitable companies sitting on cash piles which are far larger than needed, as in this case. Much better to put it to use with a decent acquisition, or give it to shareholders in a special divi or tender offer.
My opinion - I can't make a judgement about the company's future prospects, as it's not a sector I understand. Therefore, it's almost impossible to value the share (for me). This historical track record is not madly exciting;
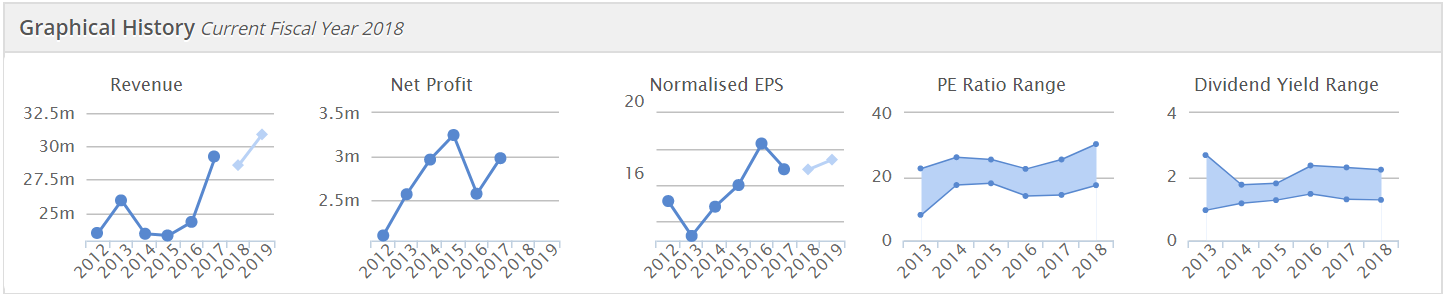
Growth appears rather pedestrian, which raises the question of why the stock is still on a growth company rating?
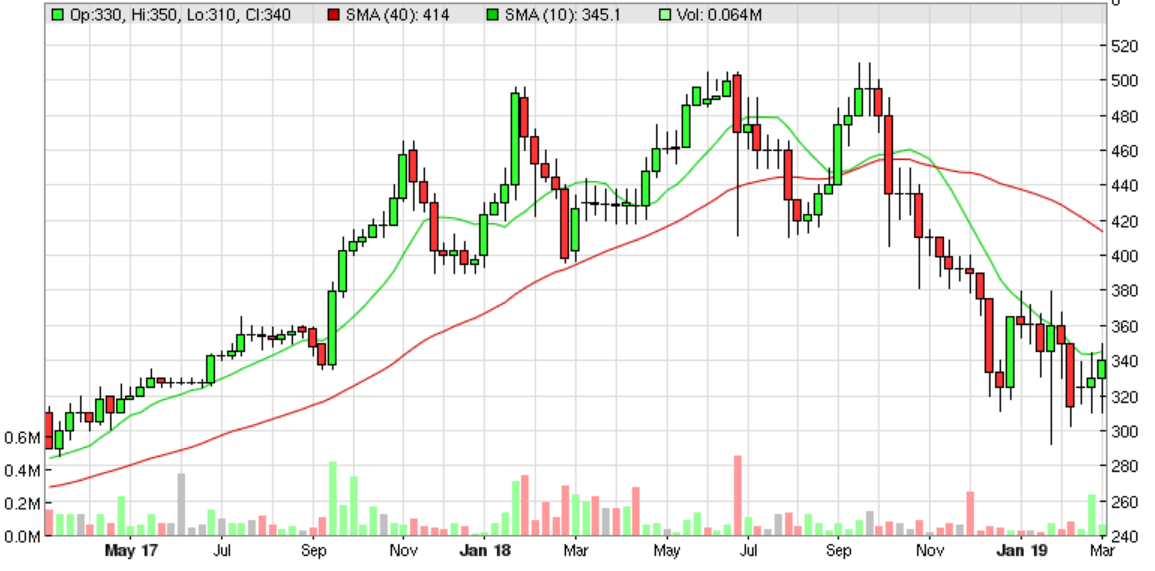
As you can see from the 2-year chart below, this share has de-rated considerably, in the indiscriminate market sell-off. Maybe there is scope for a bounce? Although it doesn't look compelling value to me, it's possible that improved market sentiment could add perhaps 10-30% to the current price? Who knows?
To interest me, I'd want to see better growth prospects, and/or the cash pile being put to good use in a decent quality acquisition. Also I would need to understand what its products are like. Are they any good? How are they better than the competition? Is there any moat surrounding its products, etc? If they're good, then why are revenues so small?
Revolution Bars (LON:RBG)
Share price: 63.5p (up 2.4% today, at 14:23)
No. shares: 50.0m
Market cap: £31.8m
(at the time of writing, I hold a long position in this share)
Interim results - meeting with management
I met with the new CEO, Rob Pitcher, and the CFO, Mike Foster, on Monday this week, in London.
... we'll have to come back to this another time, I got side-tracked talking to a supporter about what we could do about the situation in Zimbabwe
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

34 comments
Sosandar (LON:SOS)
I am reasonably confident the apparently excessive remuneration is not as bad as it seems at first glance.
What is relevant is what is the policy going forward in this regard with regard to remuneration and options.
what he have to remember here is that the company floated in the year in question - so the quoted remuneration includes practicably speaking a payment that relates to the floating of the company and that has inflated the yearly total massively. There is nothing wrong here and its all in the listing document so no one should be surprised we are where where are after doing proper research.
Looking at the numbers in question the listing document makes clear that there is a 500k fee in this regard. It is probably to the benefit of all involved that the directors took what they could in shares so there was the maximum cash flow left to invest in the business.
Also with regard to the salary levels they are massively higher in the period pre-float so i would kinda guess that Pauls 120k quoted figures will probably be closer to the mark albeit they could have any number of extras on top that we would need to directly ask the company about.
Note my assumptions my be wrong - i have just filled in the blanks guess wise by looking at the listing document and annual report.
For the record, on the subject of the Sosandar (LON:SOS) executive remuneration, the 2018 annual report (page 53) shows the joint CEOs are indeed paid a salary of £118k each (Paul’s correct) and the total board expenses (7 people) were £1.235 million) (Cleese is correct). This includes £500k paid as “Fee Shares” to three members of the board (not including the two CEOs) so possibly one time payments as part of the corporate reorganisation rather than an ongoing annual expense.
http://www.sosandar-ir.com/archive/reports/Annual-Report-2018.pdf
15 all, although perhaps Paul loses the moral high ground for posting after Pironi-o’clock. Been there, done that myself many times ....
Gus.
For value investors then, this is an interesting sector to investigate.
One area to look into is the possibility of mis-selling of finance. I read somewhere yesterday that the FCA is investigating car finance. Apparently some dealers or brokers have been given flexibility to change interest rates charged to different customers. That sounds potentially ominous, given the possibility of fines being levied. I'm just flagging this as a risk which readers would need to consider, if buying shares in this sector.
I agree. I've been closely monitoring car dealers of late as they are seriously in contrarian value territory. It looks like the FCA are going to clamp down on the dealers who have been making out like bandits by overcharging interest on PCP finance deals. I read the FCA report yesterday and it is all part of their "treating customers fairly" drive. It seems customers are being charged interest rates that bare no relation to their credit scores. So not only could there be fines but it could also remove a source of easy profit.
In addition, if you read the recent Vertu Motors (LON:VTU) trading update there is the concern that the car manufacturers will start to take back in house the spare parts business and use the dealers as little more than warehouses which will remove one of the higher margin revenue streams. Ford have already initiated this and it is likely others will follow.
All the best, Si
When my sister bought her car (from a BMW dealer), the salesman asked us what we would be able to pay per month.
Effectively the negotiation was on the finance rate, not the price of the car.
Certainly seems ripe for "adjustment".
When I bought my car from Toyota about two years later, they only had one person in the store who could talk you through the finance, presumably because the gentleman had received relevant training.
With respect to finance charges, I am not sure if it would be the finance company or the dealer that would be hit hardest.
Banks have to ensure their products are marketed correctly and need to monitor their agents, and presumably would have provided guidelines on the interest rate. My finance agreement states that Toyota acted as a representative of the finance provider, and for appointed representatives, the compliance responsibility is with the company being represented, not those representing.
Further, credit rating cannot be the only factor when pricing a car loan, since the amount of finance / term / re-sale value would all be subject to the pricing calculation?
Have a small holding in £VTU
All the best
Si
You would seem to be correct. See link below for further detail
https://www.petrolprices.com/news/britons-overcharged-300-million-year-financing-cars/
Disclosure - held Vertu, but no longer
Si
You would seem to be correct.
Well I would hope so because I read the full FCA report rather than the Daily Mail :-) I am finding the cheap metrics of the car retailers difficult to resist currently. I have made seriously good money on them over the years but I'm slightly more cautious these days and I find it difficult to get my head around investing in any kind of cyclical distributor type business with such low margins. The accepted wisdom is to buy such businesses when earnings have collapsed and recovery is imminent so the PER is high not low.
And in common with many other distributors they are squeezed on both sides i.e. the debt laden consumer on the one hand and the car manufacturers on the other. The fact they need to use such dubious practices as outlined by the FCA tells you everything you need to know about the quality of the business. And these days I am more interested in investing in quality businesses.
All the best, Si
Ten Entertainment (LON:TEG)
On the heroic assumption that City Financial might be finished this looked very good value after the fall with a fwd PER of 10, PEG of 0.58 and yield of 6%, so took a punt at 212 p . Looks very good value in comparison to Hollywood Bowl (LON:BOWL) especially as its LfL sales increase seems to be better.
Actually not sure if I'm too bothered if it falls further.
Phil
Interesting Phil. My only note of caution would be some of the difference in valuation must be down to working capital. Hollywood has more cash than current liabilities whereas with Ten thats not the case.
I had a nibble of Ten Entertainment (LON:TEG) in the afternoon too.
They do seem to have a high level of payables, but given the rather large increase at interim, I feel this may be more of a timing issue.
Hollywood Bowl (LON:BOWL) also have better margins, but Ten Entertainment (LON:TEG) growing top line quicker, and I would think that they would achieve the same margins if they get revenue to the same level as Hollywood Bowl (LON:BOWL).
Better growth runway too, although from what I can tell, Hollywood Bowl (LON:BOWL) are better at generating sales / profits per centre.
Would be surprised if Woodford is not having to fund more redemptions - if I understood that transaction correctly, his investors have had to retain poor performing investments at a 40% post tax premium. New Patient Capital issue would have received VCT rebate I think?
re Ten Entertainment (LON:TEG) City Financial only had 3.2m shares. 10.7m sold today. Somebody else bailing? Woodford?
Ten Entertainment (LON:TEG)
City out, Woodford increases stake (?!).
Lot more shares not covered by these two notices.
Phil
Where do I find Paul’s comments on RBG please?
Paul's article concludes:
I'm popping our for lunch now, then will return to write up (finally!) my notes on my meeting with Revolution Bars (LON:RBG) management. Sorry for the delay.
Paul, A bit outside of SCVR range now but but links to your comments on (London) construction prospects - excellent results IMHO from Ibstock (LON:IBST) yesterday .
Old school IPO in 2016 to fund expansion projects now starting to deliver. Looks a structurally safe(r) bet on UK construction given brick industry dynamics - see table below - and cross party support for building more new homes without the political risk arising from housebuilders' excess profits.
So good each way bet: if Brexit goes well, post-leaving boom; if it all goes bad, housebuilding an obvious govt make work/economic multiplier/balance of payments/make-the-young-love-me political play
* Financially, offers good dividend (9.5p/3.7%) well covered by free cash flow and very low debt plus special dividend opportunity (6.5p in 2018) .
* Revenue up 7.9% to £391.4 and EPS up 17.5% to 18.8p as investments/upgrades come on line
* Main brick business is 3/4 of turnover and leads an oligopoly where top 3 control 90% UK supply
* Record brick imports in 2018 - same year as their massive new brick factory (0.1Bn bricks pa) opens.
* 2018 also saw extra CAPEX/time invested in maintenance to underpin volumes going forward
* Sold off US business to focus only on UK - so very simple and focused now
* Conservatively used cash from sale to reduce debt. Debt: EBITDA now only 0.4
* Strongly placed to make further investments (another brick plant?) or related acquisitions
* Political support for more new builds (54% of brick use) plus signs digital/automation/product innovation starting to come to traditional construction industry
* Hiding in plain sight on Stockopedia computer (SR91 Q75, V61, M86)
(Disc: I own and will be topping up)
https://citywire.co.uk/funds-i...
For those that have missed it, CF are apparently selling up many or all their holdings (mostly held in small and micro caps) having filed notice to appoint administrators.
Unfortunately the link to the holdings list does not seem to work on here...see below.
I mentioned yesterday Miri; it appears CF took just over 4p for a stock that was around 12p at the start. It appears they also sold their entire stake in MNO...this was floated a few months ago at 15p and was below 3p today. There are other holding rns appearing on other small cap stocks too.
I should emphasize that I know absolutely nothing about these companies (although both appear to be trading well below cash and I bought Miri yesterday on that basis) or this fund. There seems to be a lot of dross in this list but that's just my opinion. However this seems to be an extraordinary special situation and if one of your holdings suddenly falls into a heap you might want to check the holding list to see if CF are trying to sell out well below normal bid. Clearly the market makers are aware of the position and are not exactly being generous.
I see this as an excellent opportunity and obviously your own research here is key. All very strange!
The attachment seems to be encrypted Barnetpeter.
It worked for me if I cut and paste the whole lot into a browser window as a URL. It being split over a couple of lines seems to have broken it as a clickable link for Stocko.
yes trying to get the link up....see if this works. The link is too long I think so the full link below needs to be copied and posted in your browser to get it to open.
City Financial Investment Fund Series IV - Reports and accounts (interim)
https://www.cityfinancial.co.uk/assets/download/15013/City%20Financial%20Investment%20Fund%20Series%20IV%20-%20Reports%20and%20accounts%20(interim)%20-%202018%2010.pdf
Ten Entertainment (LON:TEG)
1.6m shares of Ten Entertainment (LON:TEG) seems to have been sold this morning. City Finance holding per the above is 3m.
Another big shareholding I notice is Ramsdens Holdings (LON:RFX) .
Phil
City Financial Investment Fund Series IV - Reports and accounts (interim)
This should get you there (rather than having to C&P):
https://preview.tinyurl.com/y3mmyt22
Thanks. Whilst I wasn't exactly looking for it, you will never guess who their auditors were......
Upbeat results from TT electronics (LON:TTG). Improved margins and ROIC. Positive outlook and good cash conversion. The shares remain inexpensive in my view.
Paul just wanted to present heads up for Airea tomorrow morning. I have now given up trying to value them (as advised by Rhomboid) and he is right far too much guessing at numbers. As you point out bad news or not good news is being punished (as we saw in particular with BKS)!! In this environment part of me is yelling sell before the news as noone ever went bust taking a profit. BUT there is that thing called greed banging away so I will deter my decision until after a jolly good lunch.
Hi Camtab,
Yes I like Airea (LON:AIEA) - but have top-sliced my holding into recent strength. It's still a mid-sized position in my real world portfolio, so let's hope we have some good news tomorrow. A rare spot of positive performance, in an otherwise fairly dismal time for me.
Such is life - drawdowns (sometimes quite savage) are just part of the process, if you specialise in smaller, more speculative shares, in a concentrated portfolio, as I do.
Regards, Paul.
Quick question Paul on SOS I understand that 17.8% of the company is under option to management at a lot less than todays price and the board cost £ 1.2 m to run last year - do you feel that these options should be aligned with share holders more rather than deeply in the money freebies?
To be fair the options granted in Sosandar (LON:SOS) were granted with an exercise price that was in line with the underlying share price at the time (as far as I can see from the accounts with respect to the 15.1p options and the 29p ones recently disclosed). It's a fair point, though, to question whether directors are suitably incentivised, and in line with ordinary share holders.
An exercise price, particularly with an option expiry date of as long as 10 years, could have been set higher than the underlying to "encourage" directors to try and ensure the price was to rise over time. It is misleading though to suggest the options were granted at a price "a lot less than todays (sic) price"
For now it can be argued it is an expensive board, but by remunerating its constituents with equity (and options), this is at least cashflow beneficial. However, like with much to do with this company, it is about the future, not the here and now, and that will be the test of whether they are overpaid or not. I would like to think that future director benefits could be incentivised more than the present ones have been.
Thanks for clearing it up re option price and strike prices etc however it is a volatile share price and so surely this should be taken into account when granting options but maybe it was done as an average for several weeks I would like to see options granted at higher prices rather than in line with the price of the share when they were issued - I am all for incentives but they need to be aligned to a moving SharePrice so that share holders and directors interests are one and the same. My wife feels the clothes look low end, she liked only 2 items but having said that there is money in mass market products but they may be aiming at a different segments to what they feel they are actually hitting. I do think it is a stock that you can trade it seems to sell off at high 30’s and a floor around today’s price.
Hi Paul
Re "Market conditions for small caps still feel very depressed...."
Can't resist saying, not if one holds Bioventix (LON:BVXP) which is up 20% in the last 30 days.
But I know what you mean. It is not soi much depressed as cautious with so many uncertainties out there: China/US trade deal, slow down in the world economy, Brexit.
Whether 30th March will bring relief for our little of the investing world only time will tell.
Best wishes
Michael
Good morning, Paul. Have you managed to write up your discussions with £RBG? I'm looking forward to it!