Small Cap Value Report (Wed 6 March 2024) - CPI, PFD, IMM, LSL, QLT, NICL

Good morning!
It's B-day (no, nothing to do with bathrooms!) today, the last Budget before the next general election, widely expected to be focused on popular giveaways. This is despite the fact that the Govt is already running substantial annual spending deficits already. NI cuts cost less than Income tax cuts, because pensioners and many self-employed (if operating through a limited company) pay little to no NI.
Keelan will be reporting on the Budget on Stockopedia, and has already started with an article here - Spring Budget 2024: What to look out for.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps (usually) between £10m and £1bn. We usually avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
What does our colour-coding mean? Will it guarantee instant, easy riches? Sadly not! Share prices move up or down for many reasons, and can often detach from the company fundamentals. So we're not making any predictions about what share prices will do.
Green (thumbs up) - means in our opinion, a company is well-financed (so low risk of dilution/insolvency), is trading well, and has a reasonably good outlook, with the shares reasonably priced. OR it's such deep value that we see a good chance of a turnaround, and think that the share price might have overshot on the downside.
Amber - means we don't have a strong view either way, and can see some positives, and some negatives. Often companies like this are good, but expensive.
Red (thumbs down) - means we see significant, or serious problems, so anyone looking at the share needs to be aware of the high risk. Sometimes risky shares can produce high returns, if they survive/recover. So again, we're not saying the share price will necessarily under-perform, we're just flagging the high risk.
Links:
Paul & Graham's 2024 share ideas - live price-tracking spreadsheet (2 separate tabs at bottom),
Paul's 2023 share ideas, with live prices.
New SCVR summary spreadsheet from July 2023 to date, updated at weekends (very useful quick reference tool, search for ticker using CTRL+F). Hover over cell for pop-up notes.
Frozen SCVR summary spreadsheet for calendar 2023.
Paul's podcasts (weekly summary of SCVRs & macro views) - or search on any podcast provider for "Paul Scott small caps" - eg Apple, Spotify.
Companies Reporting
We collate a list of all companies reporting each day, but please bear in mind we cannot cover everything. So we'll pick the items that are ahead/below expectations as a first priority, then shares which have moved in price. Plus we consult the widget on the home page that shows what subscribers are most looking at, and we try to cover those too, within the timescale available (report out by 1pm).
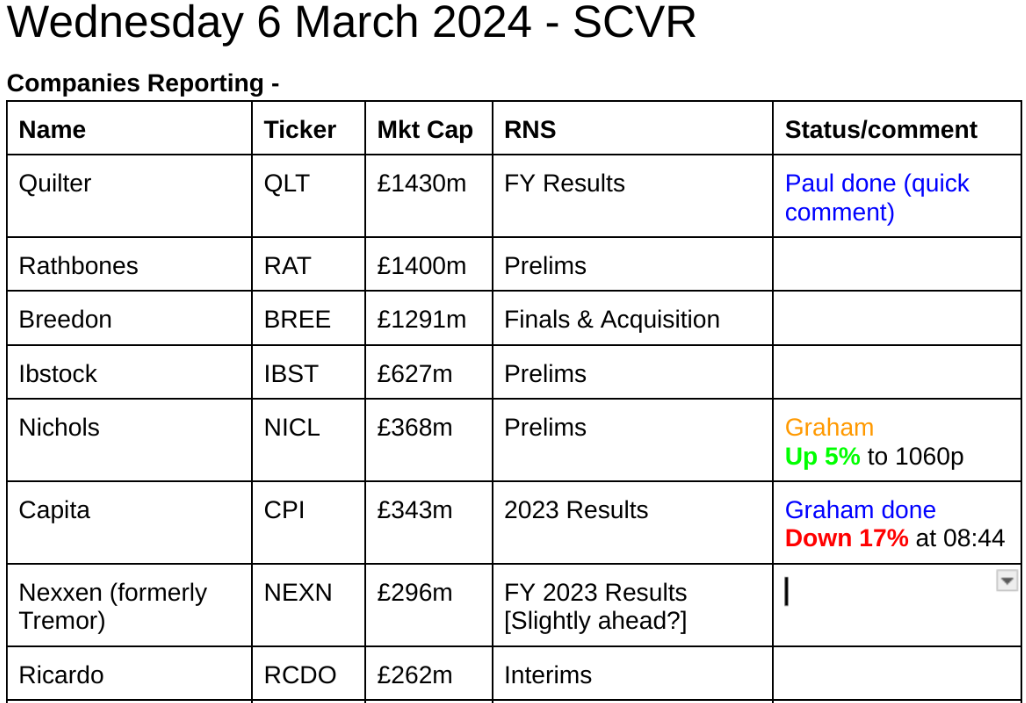
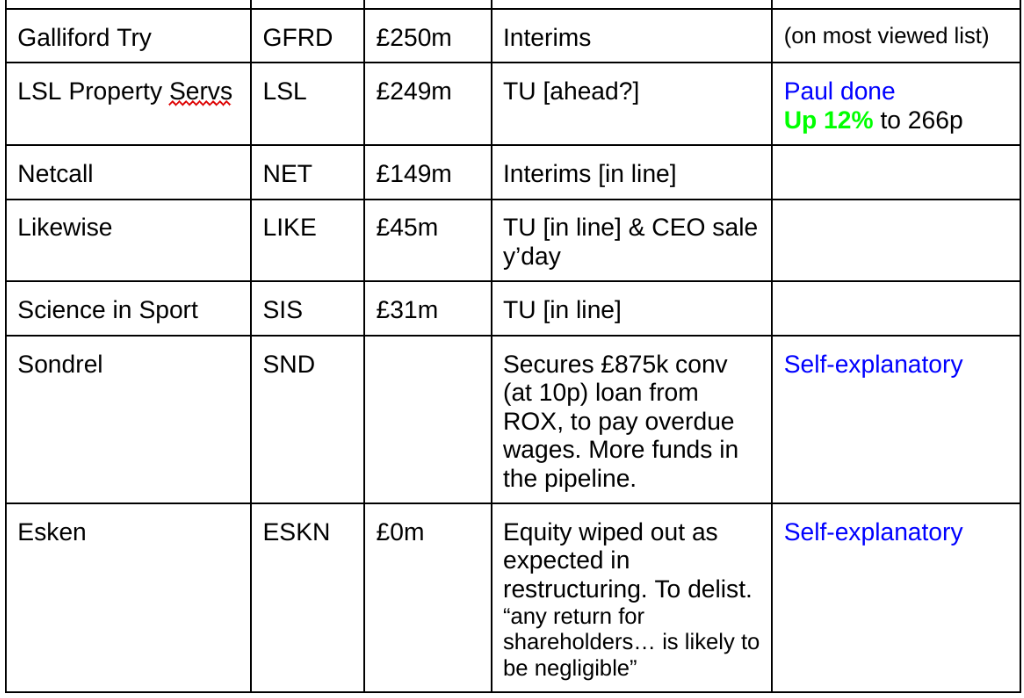
Other mid-morning movers (with news) -
Premier Foods (LON:PFD) - up 13% to 157p (£1.37bn) - Suspension of pension deficit payments - PAUL - AMBER/GREEN
“£33m increased free cash flow for the financial year ending 29 March 2025, and subject to the results of the next triennial valuation, the Group anticipates no further contributions to be payable after this date.2 Administration costs associated with running the pension scheme of c.£5m per annum and the dividend match6 mechanism are currently unchanged. “
Paul’s view - this share looks quite interesting. EPS forecasts have been rising, and the shares have made a decisive move upwards, quadrupling from the sideways range 2014-19. Good profit margins for a food company. Fwd PER c.11x, but miserly divi yield of 1.5%. Could this good news on pension funding lay the ground for more generous divis in future maybe? Worth a closer look. I’ve only done a very quick review today.
ImmuPharma (LON:IMM) - up 64% to 1.54p (£7m) - Update - PAUL
I normally run a mile from speculative, cash burning jam tomorrow shares. However this one caught my eye as a top mover today, and I quite like aspects of its rambling update today. In particular this bit -
“ImmuPharma would firstly like to confirm that the financing position of the Company is sufficient for its immediate requirements and it has no current plans to raise equity through the capital markets.”
Although you could argue that wording above gives wiggle room to do an equity raise later this year! The business model has been changed to reduce cash burn, and seek licensing deals.
“Future cash requirements are fully expected to be met through non-dilutive income derived from the Company's portfolio of assets”
Paul's view - It’s still very much jam tomorrow, but I’m tempted to have a little flutter with my speculative money. With so many discounted placings going on for poorly financed micro caps, destroying shareholder value, it's a powerful & positive message telling the market that you don't need to raise any more cash. Although whether IMM sticks to that in reality, is still open to question. It raised money last autumn, and is burning through it as we speak. So if no licensing deals raise money, then inevitably it will have to come back to investors for more cash. So I'm not entirely convinced by today's update!
Summaries of main sections below
Capita (LON:CPI) - down 21% to 15.9p (£271m) - Full Year Results - Graham - AMBER
This sprawling support services group reports a nasty loss if you don’t exclude its adjusting items. Each individual adjusting item might be a one-off but in aggregate they point to a company with structural problems. Further cost cuts now needed to improve performance.
LSL Property Services (LON:LSL) - up 11% to 265p (08:17) £263m - Trading Update [ahead] - Paul - AMBER/GREEN
A smashing update for the first 2 months of 2024 - ahead of expectations, but bear in mind last year's comparatives are weak. Healthy cash position. Valuation is probably up with events, but I imagine there could be further upside as the property market recovers, so I'm moderately positive on this share now.
Quilter (LON:QLT) - down 1% to 101p (£1.42bn) - FY 12/2023 Results - Paul - AMBER
A quick review of its results below, showing a nice rise in profits, an OK outlook for 2024. However, it also mentions a review of historical advice, which is the issue that clobbered STJ shares recently. That uncertainty puts me off wanting to delve any deeper here. Nice 4.9% yield though, and AuM are rising.
Nichols (LON:NICL) - up 5% to £10.60 (£387m) - Preliminary Results - Graham - GREEN
The Vimto maker reports that 2024 has started well; brokers have left forecasts unchanged. The company is successfully restructuring to boost profitability but still reports very clean accounts with few adjustments needed. At a PER of 17x I continue to view this as attractive.
Paul’s Section:
LSL Property Services (LON:LSL)
Up 11% to 265p (08:17) £263m - Trading Update [ahead] - Paul - AMBER/GREEN
LSL is one of the largest providers of services to mortgage intermediaries and estate agent franchisees.
It switched to a franchise model in estate agency last year, which I like, as it should in theory mean earnings are less cyclical, and might attract a higher rating from investors, possibly?
In advance of the 2023 Preliminary results, LSL issues a trading update for the first two months of 2024.
This is confusing, what do they mean by “previous”? It’s ambiguous -
At the end of February 2024, Group Underlying Operating Profit1 was materially ahead of the Board's previous expectations and around £7.5m ahead of the same period in 2023 and around £2.5m above 2022, reflecting in particular very strong trading in the Surveying & Valuation Division.
1. Group Underlying Operating Profit is including discontinued operations, before exceptional costs, contingent consideration assets & liabilities, amortisation of intangible assets and share-based payments
Profit being £7.5m ahead of prior year in just 2 months sounds great, but we don’t have sight of last year’s first 2 months management accounts, so we can’t put this into context.
Last year comparatives are no doubt soft, since early 2023 was the aftermath of the mini budget debacle, and rapid increases in interest rates which clobbered the housing market.
Cash position sounds fine -
Net Cash at 29 February 2024 was c.£28m (31 December 2023: £34.9m) with the reduction reflecting the acquisition of the TenetLime mortgage network which completed at the beginning of February.
Outlook - I imagine shareholders will be happy with this -
Whilst commentators have pointed to improving conditions in the mortgage and housing markets, it remains difficult to predict the future path of these with confidence. However, early trading reaffirms the Board's confidence that profits in 2024 will be materially ahead of 2023. The earlier than expected recovery means that even at this stage of the year, the Board's expectations for the full year have increased.
Broker update - thanks to Zeus for crunching the numbers, which is especially helpful when company updates are unclear.
Zeus today raises profit & EPS for FY 12/2024 by +15% - the share price reaction this morning is similar, which makes sense to me.
Adj EPS forecast is now 16.3p, coincidentally also making the PER 16.3x at 265p/share - I’d say that looks priced about right. Although Zeus makes the point that net cash of £28m could be viewed separately for valuation purposes, I calculate that stripping it out (104m shares in issue) is 27p per share. Although now companies earn interest on cash, this would be included within earnings, so I don’t think we should strip out cash for that reason. It was different when cash didn’t earn any interest between 2008 and 2022.
Paul’s opinion - this looks very good, and once earnings recover sharply like this, it often starts a trend of upgrades.
The 4.8% yield is an attractive reason to hold this share.
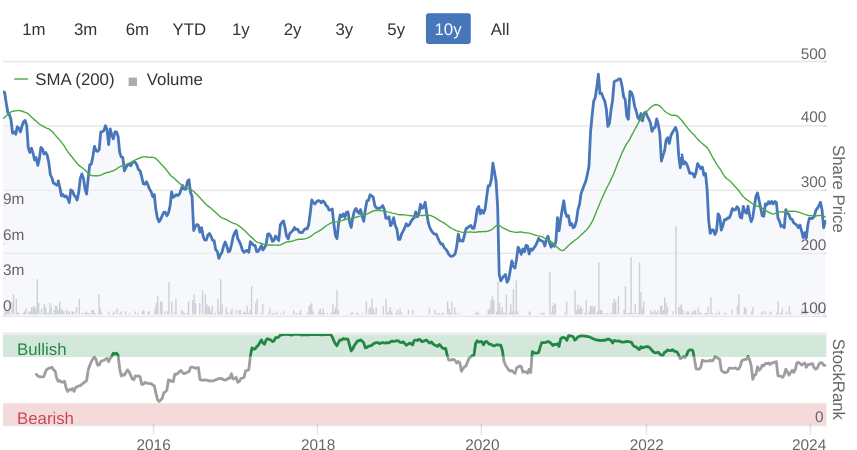
Overall, as property markets recover, I think LSL could be an obvious beneficiary. That said, its long-term track record is unimpressive (10-year chart below). For that reason, I’d probably only be interested in trying to play the economic cycle with this share, and then selling it once it’s done a sizeable increase. There seems a pretty firm floor under this share at about 200p, and there’s not been any change in the share count over the last 6 years, so I can see more upside than downside on LSL. For that reason, I’ll move up from amber/red (7/8/2023 profit warning), to AMBER/GREEN, to reflect very much improved performance now coming through in 2024.
Quilter (LON:QLT)
Down 1% to 101p (£1.42bn) - FY 12/2023 Results - Paul - AMBER
Decent rise in profit & margin (it’s targeting a 30% operating margin in future) -
Quilter delivers a 25% increase in adjusted profit to £167 million and a five percentage point improvement in the operating margin to 27%
This bit below puts me off, and is increasingly making me wary of the whole sector after the recent problems at St James's Place (LON:STJ) -
Subsequent to the year-end, on 15 February 2024, the FCA wrote to around 20 advice firms, including Quilter, requesting information regarding ongoing servicing. Consistent with our focus on delivering good customer outcomes, we are commencing a review of historical data and practices across our network to determine what, if any, further action may be required. This may lead to remedial costs but it is too early to quantify.
Outlook for 2024 it is expecting -
…modest year-on-year increase in Adjusted Profit, excluding any potential costs associated with the aforementioned review of historical advice.
Paul’s quick view - my first time looking at this company, and unfortunately it doesn’t interest me. The accounts look complicated, and I wouldn’t want to be worrying about the outcome of its review of historical things, given what happened recently to STJ. The 4.9% dividend yield is pretty good though.
Graham’s Section:
Capita (LON:CPI)
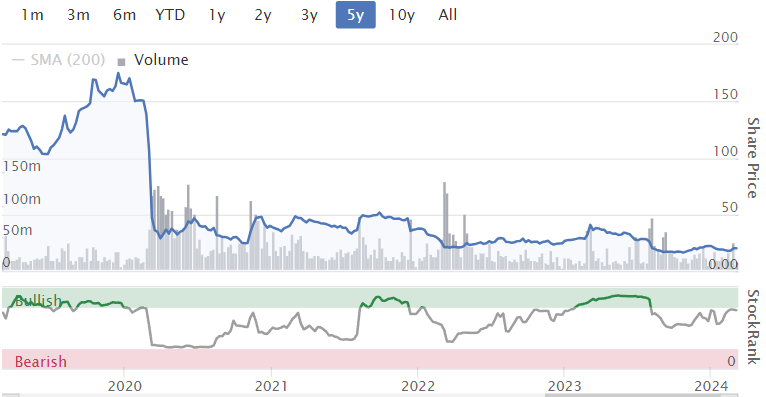
- Share price: 15.9p (-21%)
- Market cap: £271m
I still find it odd that Capita is a small-cap. I always think of it as a FTSE-100 member, but those days are long ago!
Today’s full-year results headline is designed to inspire confidence:
Stable revenue underpinned by strong contract wins, further accelerated efficiency measures to drive growth and improve cash flow
The company has a new CEO (started in January) who says:
Our 2023 financial results have demonstrated some progress. However, we have yet to deliver the operational excellence that will enable us to create the right platform for future growth or achieve our full potential for the benefit of shareholders…
"We need to deliver a rapid reduction in our cost base and are on track to deliver the net £60m annualised cost savings, from Q1 2024 as announced in November. Today we are announcing further material efficiency improvements of £100m to improve our competitive position.
“Efficiency improvements” of £100m sounds very large for a company with a market cap of £340m! And that’s on top of £60m of savings already announced.
Here are the financial highlights for 2023:
Adjusted revenue +1.3% to £2.6 billion
Adjusted PBT +14% to £56.5m, but this includes a one-off £20m “commercial settlement”
Pre-tax loss £107m “reflecting business exits, cost reduction programme expenses and 2023 cyber incident costs”.
The fact that the company makes over £150m of adjustments, but does not adjust out the one-off £20m gain that is in its favour, instantly stands out to me!
Adjustments
With over £150m of adjustments - more than half the current market cap - I need to take a closer look, to see what is going on.
£54m cost reduction programme costs - it seems reasonable to adjust these out as one-off costs with future benefits.
£36m loss from business exits - also reasonable in my view.
£42m goodwill impairment - arguably reasonable, but we should check to see how vulnerable the balance sheet might be to more impairments.
£25m cost of cyber incident - presumably a one-off event.
So looking at each of the adjustments in isolation, they all seem reasonable.
The previous year (2022), the company adjusted out a goodwill impairment of £169m, and that was the main adjustment to the 2022 results.
So I’m comfortable with the adjustments, but I would presume that any remaining goodwill is highly vulnerable to impairment.
Balance sheet
The December 2023 balance sheet shows total assets of £2 billion, and total liabilities nearly £1.9 billion.
Unfortunately there is still nearly half a billion pounds of goodwill on the balance sheet, along with other intangible assets of £90m.
Strip them out and the company is firmly in the red, with negative tangible asset value.
Outlook
2024 revenue to be “broadly in line” with 2023.
“Modest improvement in operating margin”
Free cash outflow £70m to £90m which includes £50m expected cost of efficiency programmes.
The cash performance has really been dire, with a free cash outflow of £115m already seen in 2023. That follows an outflow of £42m in 2022.
Net debt has risen to £545m, double the current market cap. But this does include property leases which many investors would be happy to leave out of the calculation.
Without leases, net debt is £182m, which is up £100m year-on-year.
The leverage multiple (net debt to EBITDA) is 1.2x, which would normally be considered manageable, and would only be 0.9x if one of Capita’s disposals had completed before the end of the year.
The company’s long-term target is for net debt to EBITDA of less than 1.0x, so perhaps it has already achieved this goal?
But remember that EBITDA is only a proxy for operating cash flow and doesn’t measure a company’s actual cash performance. With another large free cash outflow expected in 2024, I am not too optimistic about the company’s future debt profile.
Graham’s view
These results are even more complicated than I expected, with lots of moving parts.
My overall impression of Capita is that it’s a large, sprawling group of mostly low-margin support services businesses. Many of the revenues are likely to be “sticky” (think of long-term government contracts) but at the same time the prospects for growth are limited.
The shares are “cheap” but the true enterprise value is probably around £450m (adding £180m net debt to £270m market cap). With another large free cash outflow expected this year, I expect debt to rise again.
So then it becomes a bet on what the company will look like in 2025, with the hope that performance will be transformed by all of the business disposals and cost cuts.
I’m taking a neutral stance on this share.
I can’t take a bullish stance because the hole in the balance sheet (in terms of negative tangible value of minus nearly £500m) suggests to me that it could take several years of good performance before the company is on a truly sound footing.
I don’t want to take a bearish stance because the leverage multiple of 0.9x or 1.2x, depending on how you look at it, is not currently distressed. Although it could become distressed this year, depending on how bad the outflows are.
I also don’t want to take a bearish stance because I’d like to think that the £160m of total planned efficiency savings will transform the company’s financial performance, and that the new CEO will simplify and improve the overall structure of the group. Given these possibilities, this is not a stock that I would want to short.
Overall, therefore, neutral seems to be the safest and most sensible option.
Nichols (LON:NICL)
- Share price: £10.60 (+5%)
- Market cap: £387m
I left this soft drinks group on my top ideas list for 2024, so I’m eager to see progress in today’s full-year results!
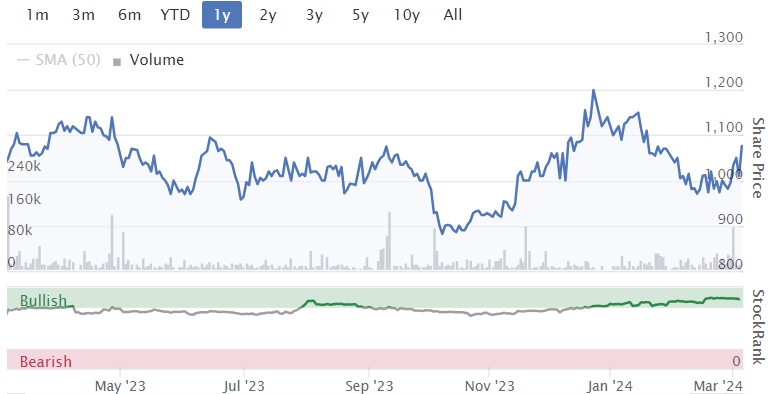
The Nichols share price didn’t make much progress last year:
We did already cover the full-year trading update in January.
Here are the results highlights:
Revenue +3.5% to £171m (GN note: this reflects inflationary price increases, volumes are falling)
Adjusted PBT +8.7% to £27m
Actual PBT +75% to £24m
My investment thesis here has been for margin improvement as inflation feeds through the system, rather than fast revenue growth. In that regard we have the following trend:
Adjusted PBT margin increases from 15.1% to 15.9%
Actual PBT margin increases from 8.4% to 14.2%
Clean accounts: in the previous year (2022), Nichols recognised a £9m impairment charge, and total exceptional items for the year were £11m.
For 2023, exceptional items are only £3m. This reduction in exceptional items has enabled the significant increase in the company’s PBT margin.
I’d also observe that for a company of this size (and note that its market cap is larger than Capita’s), these are very clean results.
Return on Capital Employed: the company calculates and reports its ROCE for investors as a KPI, a practice which I view as a green flag.
It also doesn’t hurt that the ROCE is very good. Adjusted ROCE falls slightly to 26%, while actual ROCE improves to 23%.
Cash balance rises to £67m, covering a chunk of the market cap.
Performance breakdown
Nichols is divided into a “Packaged” segment and an “Out of Home” (OoH) segment.
The OoH segment has been a problem in recent years with unprofitable contracts dragging on performance.
Today’s results show a 3.4% decline in OoH revenue (to £43.6m) as the company has been restructuring this segment following a strategic review. This restructuring of the OoH segment has also fed through to overhead cost savings that have helped to boost profitability.
Overall, OoH contributed an adjusted operating profit for 2023 of £5.1m, up from £3.5m in 2022. More progress should be seen this year.
The larger Packaged business sees 6% overall revenue growth (to £127m), with a remarkable divergence between international (+17%) and UK (+1%) growth trends. Adjusted operating profit for this segment grew to £36m.
There’s some useful commentary on the company’s strategy:
We raised prices to recover significantly higher material input costs early in the year where we were unable to mitigate these costs, with the expectation that we would lose some volume in the UK as a result of our decision to protect our gross margins. The price increase was designed to recover higher costs rather than to increase profitability and was consistent with our long-term strategic positioning.
Gross margin fell from 43.1% to 42.3%, reflecting “a change in sales mix within our operating units and our decision to pass on cost inflation only”.
Outlook: 2024 has started well, in line with expectations.
Estimates from Singer are virtually unchanged. They see modest revenue growth feeding through to adjusted PBT of £28.7m in 2024, and then £30.3m in 2025.
CEO comment:
2023 was a year of strong progress and execution for Nichols, as the Packaged business delivered another year of growth underpinned by the Vimto brand, and benefits from the newly streamlined OoH business were delivered earlier than anticipated. The Group delivered a very strong performance in international markets driven by strong market penetration across existing and new territories in Africa and the Middle East. Innovation remained a critical growth driver and we have an exciting pipeline of new products planned for 2024.
Graham’s view
Of course I’d love to see the adjusted profit margin increase even faster, but I can’t complain about the progress made so far.
The unsatisfactory performance of OoH is being addressed and has already yielded an improvement in profitability.
Long-term, I’d love to see volumes picking up again. For now investors must make do with inflation-driven revenue growth.
Stockopedia’s systems share my appreciation for Nichols:
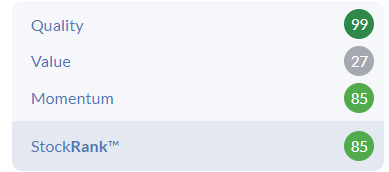
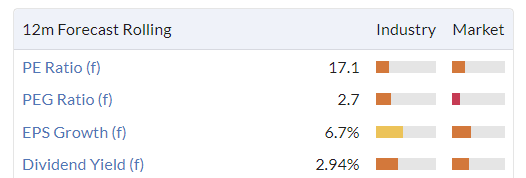
It continues to trade at a premium earnings multiple (in the context of today’s small-cap market) but I view this as justified for a high-quality family business.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

102 comments
Capita (LON:CPI) is just a low quality business imo.It reminds me of Carillion (LON:CLLN), which i held into bankruptcy back when, and the other Carillion type competing on low margin business that went bankrupt soon after, Interserve (LON:IRV^C19) .A jack of all trades and master of none, which can only compete on price, and has to try make their low margins up somewhere.. probably through paying employees little and giving them little training and incentive probably recruiting from people who just need any job to pay the bills.I'm just assuming as i'd think their human capital cost would be fairly large.Maybe i'm biased due to my previous Carillion (LON:CLLN) holdings though and don't know enough about the business in detail, just not a fan of the business model.I know deferred revenues did get Carillion (LON:CLLN) in real trouble in the end.
Capita differs in so far as it is primarily office based services rather than physical services.
Capita (LON:CPI) I dipped my toe in at 20 when the last cost cutting programme was announced. Initially the shares did pretty well but were hit hard when a broker with a strong following turned negative at the start of the year. Taking this, with todays announcement, its pretty clear to me that the new CEO wanted to further reset numbers with another cost programme .... and as seen in guidance this is negative for short term FCF. This explains the market reaction to guidance today I think. It looks like another year of transition with little revenue growth, negative FCF, higher debt and therefore less equity value. I could sell and move on but .....
The contrary view would be that the exceptional guidance for the year incorporated in the FCF guidance and little revenue guidance sets a floor from which the company can now beat. Experience book to bill is nothing to shout about at 0.9x but Public Service much better at 1.3x. The amount of cost coming out and the exceptional guidance gives a decent head room to beat.... the key of course is the swing to revenue growth and POSITIVE FCF. I am inclined to give the new CEO the benefit of the doubt for now. The purchase of 325,000 shares at 16.2p from him today helps. Im listening to the webcast now and find his presentation short on corporate waffle and rather simple which I like.... take some cost and pain now so we are in a better position to bid on contracts in the future.
The hit today is partially explained by an unwillingness to wait for better news in H2. Contract news can always be both positive and negative.... but for now I am happy to run my toe dip... even add a little and see how things develop. A capital markets day in June will likely focus on medium term margins and growth so hopefully the new CEO is in a better position then. The valuation upside is massive and in the past both Compass (LON:CPG) and Serco (LON:SRP) have gone on to make successful turnarounds once a platform for growth and positive FCF is established. These should be rather stable defence businesses in normal times that command better valuations.
Do you know what the best Stockopedia screen is to scan for recent earnings surprises and/or analyst EPS upgrades please?
This is what I use Edward. Can setup 2yr eps and eps downgrades also
The British ISA announcement in today's Budget was the only real positive for investors that I observed. However, ultimately it still left you with a lingering feeling of disappointment as there is no detail or timescale. Consultation to follow. Anyone have any ideas on whether this is for FY25 tax year or not? It's not been costed in the budget policy change impacts, so its not obvious.
EDIT - Consultation here https://assets.publishing.serv...
Responses to this consultation should be sent to HM Treasury by 6th June 2024.
Still no real detail on timing. Might get announced in Autumn Budget I suspect.
My takeaways
"This consultation does not ask for views on the principle of
introducing a UK ISA or alternative options for achieving the policy
objectives."
"At Autumn Statement 2023, the government announced it would
digitalise the ISA reporting system. HMRC is establishing stakeholder
forums . . . to ensure the pace and sequencing of the move to a digital
system reflects the needs of ISA providers and investors, as well as the
requirement to upgrade HMRC’s own infrastructure." - Given that we're still waiting for the pensions dashboard, probably best not to expect this any time soon.
So, if I've got it right, I'll be able to invest in international miners, oil companies and the likes of Windward (LON:WNWD) or M P Evans (LON:MPE) but not Arm Holdings (NSQ:ARM)
I always thought an ISA was a tax free wrapper. By implication a taxable profit needs to be made in order for said tax to be paid. Since being in the UK market since post-covid I would really like to be able to pay tax on winnings lol.
I was new back then so did not put all in on BAE Systems (LON:BA.) and gone back to sleep.
My worry is they will ‘encourage’ our hard earned (and taxed on withdrawal (crime)) legacy in pension funds into investing in hot (or politically supported industries - omg). Where winners are taxed offshore, or some green ideologies - I t’s about trust.
Call it Brit/UK whatever there must be a big sweetener - and sure they will ramp up advertising prior to catch the proles.
Likewise with Natwest (LON:NWG) although that is a different discussion and look forward for the sweetener (at taxpayer expense).
Harry if I was Chancellor I'd have made all tax advantage/protected investments UK listed only. Overseas listed investments are fine but why should they be subsidised by other UK taxpayers?
I was surprised how few ISA millionaires there are here in the UK.Only 4,000 so far but improving.Too many property investors i guess .The government does need to explain investing better to the average person.Although, share dealing platforms are doing better at that imo.
Aug 4 2023
'The latest figures come 20 years after Liberal Democrat peer Lord Lee of
Trafford became the first publicly declared ISA millionaire in 2003.'
'There are now almost ten times more millionaires, who have benefitted from maxing out their allowance, since 2016.'
https://www.ftadviser.com/inve...
Rich Pickings ?
Think this illiquid market with wild swings on no volume or few sellers has been spitting out sone consistent “daily deals”
Anyone with funds to invest in their core holdings shoukd be staring down the illogical “mr market” and holding their nerve .
I’ve seen half of my holdings have significant 20% bounces for no real reason other than light positive liquidity
And 3/4 ones sold off to what I considered illogical .
Managed to buy a big chunk of SDG at 102 last week .
Avingtrabs at 334
Now MSI down to a top up point .
Quite interesting times, I’m actually selling very little just increasing strong holds if they drop on no news by say 20% (or news that is neutral ..
I’m only able to do this on circa 20 companies that I follow inside out and day to day where you get the ebb and flow
Having had to deal with Capita (LON:CPI) for years in my job I will never be able to invest in this company. The staff don't have enough knowledge/education to do the job and their response times are absolutely appalling. Frustrating for everyone involved, and I'm not sure why so many councils use them. Seemed like a good idea at the time I guess and then you are locked in to a multi year contract...
A group that graces the pages of Private Eye with alarming regularity so like you would never consider investing in it.
It's the Public Sector! Lowest price wins, always. They waffle on about value for money as being the principal factor in their decision making, but from the Treasury down there is no recognised method of evaluating that. and when you want to cover your rear when it all goes wrong, as it invariably does, then one cannot get the bullet for going for the lowest price option. Not that anyone in the Public Sector gets the bullet for incompetence anyway. Kafkaesque.
Councils are generally in the midst of a long term process of re insourcing many functions previously performed by Capita (LON:CPI)
Which is definitely the right decision. Councils that don't use Capita are far more efficient than the ones who do (at least from my experience). Not sure how much of Capita's revenue is generated from councils, but I would assume it's a lot...
Hunting (LON:HTG) - "Guidance beaten in FY23 and unchanged for FY24" (new research report here: https://www.equitydevelopment....)
Hunting delivered EBITDA of US$103m, ahead of revised guidance and the inferred year-end expectation, representing a 98% y-o-y uplift (and 11.1% margin, +380bp). Significant contract awards boosted Subsea and OCTG activities in particular, but top line progress was also accompanied by good cost control to deliver the full year outturn. A record year-end order book position leaves the company well-placed to deliver further progress in FY24, where guidance is unchanged.
At the headline level, Hunting delivered group revenue growth of 28% and margin progress (ie gross +90bp to 24.5% and EBITDA +390bp to 11.1%), feeding into a fivefold increase in pre-tax profit with EPS up over four times in FY23. The full year dividend rose by 11% to 10c per share, covered twice by earnings.
Against our selected peer group average, Hunting’s P/E and EV/EBITDA multiples sit on discounts of 25-30% and 20-25% respectively. Taking a simple average of our P/E and DCF based analyses generates an unchanged fair value per share of 407p.
Supreme (LON:SUP) surprised to see this one up after the budget speech given that there will be a vape tax on importing the fluids? Certainly 6 years ago they were bringing barrels of the stuff in from China for their bottling line. Anyone know if that’s still the case or are they mixing it here now?
The can has been kicked down a very long road. Vaping tax now sometime in 2026. I bought a load more Supreme (LON:SUP) as he announced this. Read all the recent company announcements. Dyor
And tobacco duty will be increased to preserve the retail price differential. The price has been hammered recently simply because of fear about the vape tax. Supreme (LON:SUP) is a wonderful "trader's stock" at the moment. It's very volatile but he company is not going bust so bad timing will not result in a 100% loss, the primary trend is up, and it usually has pretty clear tops and bottoms. The most recent top formation lasted 7 trading days which is almost as good as ringing a bell.
I'd be careful buying into any vaping companies - I think it's only a matter of time before the health ramifications of vaping properly surface - full disclosure I work in the life science / healthcare industry. What Does Vaping Do to Your Lungs? | Johns Hopkins Medicine
BUDGET - Keelan set up a specific report for this so please post there:
https://www.stockopedia.com/co...
From the bbc
The chancellor says he will reform the ISA system to encourage more people to invest in UK assets.
The government will create a “British” ISA in the form of an extra £5,000 tax-free allowance for the public to invest exclusively in UK.
"This will be on top of the existing ISA allowances and ensure that British savers can benefit from the growth of the most promising UK businesses as well as supporting them with the capital to help them expand," he says.
Afternoon.
How many people here, like me, think that in long run the budget is irrelevant to the long term value in quoted stocks (or U.K. plc) and what would make a lot of difference is if government simply got out the way and allowed us (business) to get on and create wealth.
Ok rant over.
Regards
Michael.
the main thing is to encourage large companies to be based in the uk - at present if they are based overseas they can avoid a wad of vat (services) presumably coproration tax and the upping of the copr tax rate to 25% isnt exactly saying have your business base here rather than ireland. Dont think they could get it much more wrong if they tried - starter for 10 would be taxing heavily overseas companies who simply extract funds from the uk abroad paying minimal to no corp tax/vat - like google/facebook/uber/indeed - ie give them an incentive to have proper base here on which they pay corp tax and vat like uk based companies.
But businesses need state input to generate wealth. They need a healthy educated workforce, they need transport links, then need cross border trade arrangements. Businesses can't work in a vacuum.
Just announced a New ISA £5000 for British firms.
That makes more sense!
''it will come in the form of an extra £5,000 tax-free allowance for the public to invest exclusively in UK.''
Also mention of plans to unlock pension fund investment into UK equities - that could be a real game changer although very little detail so far.
Yes - only 4% of pensions are invested in the UK. That’s poor. Forcing public pension schemes to publish how much the pension invests in the UK is good as it will force managers to think about allocation and public perception. Won’t make a huge diff immediately but I suspect will channel increased investment over time which is kind of what you want.
The British ISA is what I was advocating the other week. That’s good but I would have gone further and provided additional tax benefits to the BISA to encourage use over a normal ISA.
And probably more pension deficits in future……..
Interesting that Journeo (LON:JNEO) now back to a cash adjusted PER of just 8* as impatient investors dribble out a little stock.
Similar with MS International (LON:MSI) - tiny trades dragging the shares down
Looks like there could be some interesting top up opportunities of high quality and growing businesses starting to arise.
Interesting that Journeo (LON:JNEO) now back to a cash adjusted PER of just 8* as impatient investors dribble out a little stock.
Seems very reasonable for a nice little niche business. I've been buying into the weakness.
Yes I agree. Journeo (LON:JNEO) is interesting for a couple of reasons I think.
1) They are emerging as a global leader in a niche area - but a market size that can support well in excess of current market cap
2) The SaaS side of the business is becoming larger and larger as a %age of revenue. That visibility is usually rated at more than twice what the market is currently attributing.
So as long as the company continues to deliver to plan and the Nordic / European expansion bears fruit I reckon it could end up a multi-bagger from here. I like the management - relatively understated, good track record, put own money into the business, so ticks my qualitative test.
It’s a reasonable holding for me now but I may top up - certainly any more weakness and I will be looking to add.
Journeo (LON:JNEO) (no position)
I don't know much about Journeo's products, but I thought I'd throw out a recent announcement made between Init Innovation In Traffic Systems SE (ETR:IXX) and TFL that may be of interest:
https://www.initse.com/ende/in...
I'm a big fan of this German-listed company as they expand across Europe and the US, but do not hold (yet) although I do have a position in Ivu Traffic Technologies AG (ETR:IVU) .
A
Thanks abtan,
Different products/market segment. Journeo (LON:JNEO) do cameras on transport systems, surveillance and digital displays (think airport screens) etc.
You could see though how industry consolidation might bring these horizontals together at some point as companies start to diversify product strategy around other complementary services.
Thanks to Judith McKenzie at Downing. Her selling into the market has killed the JNEO SP and created a buying opportunity. If I were, however, to be invested in her fund I would be manifestly unhappy.
I know this board is not the usual place for discussing O & G shares but I thought today's news from Challenger Energy (LON:CEG) was worth a mention. I don't hold but I've been following co for a while. They've farmed out 60% of one of their blocks offshore Uruguay to Chevron. Terms are very good & better than your average farm out deals, reflecting excellent prospectivity of their block. Offshore Uruguay is a geological mirror of offshore Namibia, which is arguably THE global oil explo hotspot at moment. To get a partner of the quality of Chevron is a real feather in their cap, which suggests that Chevron are serious and work will progress quickly on block (3d seismic & potential explo drilling). High risk punt but upside is potential billions of barrels discovery. There aren't many shares on AIM that have a company of the quality of Chevron as lead partner, with the aim of discovering billions of barrels of oil. Challenger were first mover into offshore Uruguay and that's why they were able to pick up blocks there, all of the other blocks are held by majors. They've still got another block offshore Uruguay and, after today's news, it's highly likely they'll farm out that as well, probably to Chevron or another major, so that's another near term catalyst. Just my opinion, but I think this is one of best, high risk, speculative shares at moment and worth a follow.
Reach (LON:RCH) - Edison have put a note out.
https://www.edisongroup.com/re...
Kitwave (LON:KITW)
Excellent presentation on 'investor meet company'. Ben Maxted current Chief Operating Officer and soon to succeed Paul Young as CEO knows the business very well as one would expect, and came across as cogent, credible and competent.
I am a happy shareholder.
Not a holder of Kitwave (LON:KITW) nevertheless I did tune into today's presentation. What I actually did after that was sell our MJ GLEESON (LON:GLE) at quite a capital loss and placed the proceeds in Stelrad (LON:SRAD) which seems to me to be a step forward whilst looking forward to buying Kitwave on a dip.
What I actually did after that was sell our MJ GLEESON (LON:GLE) at quite a capital loss and placed the proceeds in Stelrad (LON:SRAD) which seems to me to be a step forward whilst looking forward to buying Kitwave on a dip.
What happened to precipitate a 10% fall in Stelrad on 14th Feb? There's no RNS and earnings were in line only a fortnight previously. Was there so much Valentines-related frottage amongst couples that the resultant heat caused the market to re-price radiator supply for good? Is it read across from a competitor warning? Or something else?
There should be a decent Stelrad dividend on the way, Gleeson's has been and gone, I do like dividends and hate dogs. But you know the real money is in day-trading now. I do have long-term holdings in some good companies and compounding is producing some worthy dividends so keep two strings for my bow.
Marks and Spencer (LON:MKS) won Fashion Retailer of the Year last night. Inconceivable only a few years ago. Well done to Machin & team, (I hold).
Marks and Spencer (LON:MKS) won Fashion Retailer of the Year last night. Inconceivable only a few years ago. Well done to Machin & team, (I hold).
I was quite cheered by the colours and feel of the store when my wife dragged me in for her to buy some pyjamas. And the nightwear selection was great. Food hall meanwhile looks like it belongs in Europe - it's that good.
The fashion is nice, good quality and very well priced now imo.They have the new click and collect and returns big touch screens fully functional in my local M&S now.Very quick compared with the usual click and collect queuing up process at the main checkout desk.Now they just need Ocado type trollies to bring out the parcels in a cage and verify who you are with an app QR code or something.The lady doing the handover was very pleasant though.
This is a really good read I think, full of nuggets. Thankfully im blessed with not being troubled by the last point.
https://citywire.com/funds-ins...
"Given the impressive returns, it’s slightly disarming to discover how simple the Behavioral Small Cap Growth strategy is at its heart. But this is, as they say, a case of simple, not easy.............The things that really matter in Stanske’s quest to identify underreaction are earnings surprises and analysts’ upgrades to forecast earnings per share (EPS)."
"The psychological urge to underreact means analysts and investors get stuck playing catchup to events. One upgrade follows another and the share price responds accordingly."
"One of the big practical lessons from behavioural finance............is that the complexity of the real world creates confusion that results in worse decision-making. Clever people are especially vulnerable to overthinking."
Wolf, Yes I spotted this article too, which closely resembles my preferred (but not only) style of investing.
The behavioural bias mentioned is particularly true with shares at our near their 52 Wk High. Worth Goggling Frog in the Pan Momentum, for anyone who is further interested.
Well, I was interested. According to Google, Frog in the Pan Momentum means "investors are inattentive to information arriving continuously in small amounts" but Goggling Frog in the Pan Momentum sounds much more intriguing.
Headlam (LON:HEAD) (I hold)
Further to my note on here yesterday, Sharepad have reduced broker PBT forecast FY'24 by 40% from £12.7m to £7.72m. Also f/c EPS savagely cut to 7.18p.
This is far more severe than indicated by Management at yesterdays results presentation and is effectively yet another underhand profit warning without an accompanying RNS.
A dividend cut, based on these new forecasts, looks a near certainty.
This further underlines the lack of transparancy and effectiveness of the CEO who appears to be another example of a former CFO lacking the necessary CEO skills.
House broker Peel Hunt reduced their target price from 250p to 225p. No broker research available to the 'plebs'.
Headlam was on yesterday's SCVR list but on a busy day wasn't covered. Perhaps Paul or Graham could cover this as a backlog item please.
Given that 2024 looks like being another grim trading year for Headlam (LON:HEAD) it's looking like investors' money would be better deployed elsewhere for the time being, especially if it represents more than a small % of your portfolio.
Snazzy
Hi Snazzytime,
Thanks for an excellent summary of Headlam (LON:HEAD) - that's really helpful, and has caught my attention. Funnily enough, I had written HEAD down on my notepad this morning as something I'd like to revisit, as we got swamped with company news yesterday and I saw the share price was a little soft, so it went down the list of priorities.
I like the asset backing, and good historical track record of HEAD, but am becoming increasingly concerned that its deterioration in profitability might be something more structural than cyclical? Competitive pressures, from Likewise (LON:LIKE) in particular, which we've mentioned here before, and coincidentally is reporting today. Maybe I'll do a carpet special, and cover both together?!
I'll do my best to fit it in, but probably won't be today, maybe this Friday if it's quiet?
Thanks again, Paul.
Headlam (LON:HEAD)
Thanks Paul - that would be most welcome.
I'm not sure if you saw my post on here yesterday so I've taken the liberty of copying it below.
Snazzy
Some thoughts regarding todays FY'23 (to 31/12/23) results and PIWorld webcast.
That's enough random thought emptying for now.
My gut instinct tells me I've seen enough and should sell. I don't have sufficient confidence in management, no likelihood of SP recovery in short term plus risk of further profit warnings and dividend cuts. The only saving grace is the strong asset backed balance sheet (but a weakened cash position).
Snazzy
HEAD - Heres a couple of 30 year charts with EPS, EBIT margin, NTAV if anyone finds it useful.
Seems a gulf between Headlam (LON:HEAD) update yesterday and Likewise (LON:LIKE) today. HEAD '24 EPS cut almost 40% by the looks of things. LIKE showing good momentum in comparison.
Seems a gulf between Headlam (LON:HEAD) update yesterday and Likewise (LON:LIKE) today. HEAD '24 EPS cut almost 40% by the looks of things. LIKE showing good momentum in comparison.
Agreed. But it's a lot easier to rack up growth when you're young, small and nimble. I don't think anyone's looking for knockout growth from HEAD. It's just a recovery play.
Netcall (LON:NET) is well worth a further look. Interims in line with expectations, the company has 75% recurring revenues in the business transformation area, with AI, RPA and cloud offerings. What's more its profitable with £28.6m of cash in the bank.
Agreed. Netcall (LON:NET) is one of my largest holdings. Their main product is the Liberty platform which combines Customer Engagement and Intelligent Automation (Low code/RPA/AI). It enables digital transformation in large organisations (89% revs are Fin services/health/public sector) to be performed by companies themselves rather than external software engineers who are not familiar with the business. In particular, it works with all the disparate legacy systems their clients are saddled with.
The reason I have such a large holding is that like Intercede (LON:IGP) , their customer base is to die for because of their historical roots in contact centre software and it's so much easier to upsell to existing clients. They're in 75% of the NHS, many councils, large financial services groups like Nationwide/Lloyds, National Grid, National Rail, TFL etc.. 23% (up from 16% last year) of their Customer Engagement clients now take the IA solutions as well which results in an average uplift of 3 x annual contract value (ACV). They're also moving a lot of their CE clients to the Cloud which results in an uplift of 60% ACV.
They offer pre-populated hubs to help resource constrained public sector institutions get started - Patient Hub for NHS Trusts (10.2mm patient notifications last year with 2.3mm appointments managed), Citizen Hub (large take up by cash strapped councils as the payback is usually a matter of a 2-3 months) and Tenant Hub for housing associations. Many of these organisations have teams working on new Liberty solutions which they're then encouraged to app share which means word of mouth does the marketing for them. e.g. TFL have adopted a product acceptance solution for equipment on the underground which was shared by Network Rail who built it.
So why doesn't it show up in the numbers yet? Three reasons - 50% revenues are the legacy on prem customer engagement subscriptions which are mature. Cloud Services are now 50% with ACV growing consistently at 25-30% which will obviously have a greater impact on total revs as that weighting increases. Also this year was impacted by a contract renegotiation by an S&P 500 global financial services firm who had to slash their IT budget meaning Netcall swapped a $7mm pa 2 year contract for a $4mm pa 5 year contract. It was their largest contract and they don't have any others anywhere near that size. Next year's profits are also static due to substantially increased investment (>20% revs is R&D) in cloud contact solutions and adding Gen AI to their pre-exisiting Liberty AI modules.
What was interesting in today's results, is that new client adoption is actually accelerating with 33% of H1 bookings from new clients, up from 22% last year. Combine that with consistent Net Revenue Retention (NRR) of around 120% gives a long runway. The more Liberty is used across an institution, the deeper the moat.
Valuation wise, it's not obviously cheap, with a PE of 28x but 20% of the market cap is net cash and they're generating 5mm FCF pa. However, look past the static profits and you'll see the path to an ACV close to 100mm in 5 years with a commensurate increase in margins which could make it a 3-5 bagger pretty much just on the existing client base.
If you're looking for a UK business where Gen AI is going to have the widest take up among their clients, then IMHO Netcall should be near the top of the list.
That was a really good summation of the Netcall opportunities, and I'm very grateful for that!
Thanks Gerard.
And just to add, the Chancellor is fully funding the NHS IT modernisation of 3.4bn and will prioritise proposals that deliver 5 year payback in local government. AFAIK Netcall (LON:NET) don't do the internal hospital productivity (operating theatres, EPRs etc) but Liberty is used for everything to do with external patient engagement (appointments, waiting list management, NHS app integration etc.) . Likewise, their take up of Citizen Hub by local councils has a much shorter payback - usually less than 6 months.
With Healthcare making up 29% of revenues and Public Sector 38%, I suspect there will be an acceleration in their demand following this budget.
Thanks for this .... quality post. I don't hold, but had a quick look. SP has not gone anywhere for 5 years, but the underlying business metrics have improved immeasurably. The business seems to have grown into a previously very high PE. So the SP has remained static as the business has grown and the PE has declined to almost respectable ratio as EPS has grown. Looks an interesting business with lots of runway for further steady growth.
Yes, the market still thinks of Netcall (LON:NET) as a legacy contact centre software business but that's now only 50% of the business with the other 50% being the cloud services growing at 30% with a very long runway.
It's a good example of management seeing what their customers were going to need, in this case low code, then RPA and then AI (launched in 2022) and making an astute acquisition (Matsoft in 2017) to kick off expansion into this area.
There are several global Intelligent Automation providers but Liberty is the only platform to combine Customer Engagement and IA to provide a one stop shop. Combine this with the fact that most of their prospective IA clients are CE clients already and their specialism in public sector/health, makes a very attractive business IMHO.
I guess the market is just looking at a static EPS line and thinking meh, but at some point it will cotton on to what's going on underneath the bonnet . It's also nice having a fast growing tech company that's throwing off FCF.
There are several global Intelligent Automation providers but Liberty is the only platform to combine Customer Engagement and IA to provide a one stop shop - Netcall (LON:NET)
Ahem, ServiceNow (NYQ:NOW) mkt cap USD152 Bn and rated by analysts as the very best of breed software company anywhere. They offer everything that NET does, and much more besides. Look at that stunning long term revenue chart! Coming to a Netcall client tomorrow.
Now the above is a little tongue in cheek because I understand and respect the stickiness of NET's moat and its niche positioning. But either one of us could be underestimating the other's holding!
ServiceNow (NYQ:NOW) is a great company and they of course compete with Netcall (LON:NET) on the Intelligent Automation side of things but I can't find any site mentioning them as a competitor to Liberty Converse in the UK even though they do a CSM solution.
It also appears ServiceNow is used more as an enterprise platform rather than for external customer engagement at the frontline . So, NHS Scotland and NHS England use ServiceNow for their internal processes and staff management but 475 NHS Trusts and Boards use Netcall for customer engagement. There were 24 implementations of Patient Hub last year and NHS Devon adopted it in H1 to manage their waiting lists.
Likewise with Local Government, I can find several councils which use ServiceNow but it's mainly for streamlining internal processes. Since the hubs were introduced less than two years ago, there are now 70 customers using them with new customer adoption accelerating.
As investors, we're always looking in from the outside, but from what I can see, whereas the two companies clearly overlap in certain areas, they don't appear to be in direct competition for most of what Netcall (LON:NET) do.
Happy to be corrected if I've missed something.
You are 100% correct that Netcall (LON:NET) and ServiceNow (NYQ:NOW) are converging from different starting points. NOW was originally an ITSM platform only. But, by a land and expand strategy akin to that followed by NET, NOW has diversified right across the enterprise, initially in simple add-ons like staff onboarding, more recently and aggressively, into AI-driven automation. Customer engagement is less of a strength, as you correctly point out, but it’s a growing part of the offering and they have big pockets. Perhaps they will buy NET? Better that than a powerful alternative maybe?
It’s sobering to reflect that NET has delivered c60% total return to shareholders in the last decade while NOW has 13 bagged. Yet both are on the same multiple of revenues as 10 years ago. I’m inclined to the view that NET will do well, owing to its entrenched relationships combined with the pressing need to improve government IT. We saw this in today’s budget with the extra capital made available for NHS automation, some of which is probably coming your way. But the current trend of vendor consolidation argues for the more comprehensive - and doubtless more aggressively marketed - offering from the US.
I found your analysis very interesting and wish you good luck with your investment
Thanks BnB. Likewise with yours.
Luckily I started buying NET at 31p in 2019 when the first signs of the transformation were coming through and I see that NET and NOW have similar returns over that time period so I'm just about hanging on to your coat tails.
I recall Paul mentioning recently that he was thinking about buying a basket of building suppliers to capture any future upturn in the housing market. I thought this was a great idea as it's quite difficult to differentiate between the various names and would take a long time to analyse them individually.
I did a quick screen within the construction materials and construction suppliers sectors and then filtered by the following
PE ratio below 10
Dividend yield above 4%
Stock rank above 90
Came back with the following 8 names, some of which I know quite well and think all pretty good companies - Brickability (LON:BRCK) Michelmersh Brick Holdings (LON:MBH) Alumasc (LON:ALU) Severfield (LON:SFR) Keller (LON:KLR) Eurocell (LON:ECEL) Epwin (LON:EPWN) Norcros (LON:NXR)
Epwin (LON:EPWN) Norcros (LON:NXR)
I hold epwin and norcros - very overwight in norcros already - note is does get wad of its profits from south africa and does have chunky pension scheme (thankfully pretty mature compared to most others) - so invariably it does seem to be cheap most of the time even when its on a roll (cant remember pe ever having been much over 10)
Epwin (LON:EPWN) - tempted to top up here - they updated quite recently on 25th January and that update was pretty confident bearing in mind the poor market conditions that exist at present in the sector - compared to eurocell they are expected to deliver more profit 2024 and have 10% lower market cap - although Eurocell have historically had higher profits so perhaps its easier for them to bounce back up in profits when tehjn good times return
all 3 are making decent money in times that arent exactly favourable.
Brickability (LON:BRCK)
i very briefly held here - their recent trading hasnt been as good - and they have just splashed £100 mill on acquisitions in the last 9 months that have made good money recently (and are expected to do well) but werent making a forture before the recent "cladding boom" started. So slightly less confident about the that particular company - thats not to say shareholders wont be rewarded well if the new acquisitiojns deliver long term value.
I must admit that Alumasc (LON:ALU) is my preferred pick of the above given its focus on environmental products - 80% of revenues are linked to specification and regulation, and this has helped support revenue growth during challenging markets.
In addition Alumasc (LON:ALU) has recently taken over ARP, a competitor of the water management division, which will bring both cost synergies and product rationalisation, but these benefits don't seem to be in the price.
Wolf there should be significant benefit coming from converting the Estate Agency businesses from Managed to Franchise LSL Property Services (LON:LSL) . Frees up a lot of Capital, increases Operating Margin. And their Financial Services should build as and when the housing market recovers, imo. Haven't checked on them recently but see them transitioning to be more like Property Franchise (LON:TPFG) than say Foxtons (LON:FOXT) who I believe still managed rather than franchise their branch network.
Premier Foods (LON:PFD) (I hold) has shot up over 10% today on news I don’t fully understand on suspending pension deficit payments.
“This suspension of pension payments substantially increases the free cash flow available to us and presents us with enhanced capital allocation options to deliver on our growth ambitions.”
Congratulations Indie, that's very bullish news for Premier Foods (LON:PFD) .
£33m a year saving that can be redirected towards reducing their debt. With the interest savings over the next few years I would imagine this would have a very rewarding compounding effect on the balance sheet.
Thanks, Burnt Onions, compounding is indeed the eighth wonder of the world!
Any clue as to why Premier Foods (LON:PFD) can stop making these pension deficit payments?
(Full quote is: ”Compound interest is the eighth wonder of the world. He who understands it, earns it ... he who doesn't ... pays it.“ Einstein)
But is the Pension Scheme in deficit? If not then the Company certainly can take a Pensions Holiday - Unions hate them!
Premier Foods (LON:PFD)
I think there is additional good news here is the confirmation of the following.
"The further significant progress in the funding position of the pension scheme has enabled us to take another important step to expected full resolution of the Scheme by the end of 2026.
i dont follow this share so perhaps this isnt excatly new news (as they say expected) - but this is how you provide confidence to the market that hopefully the pension issue will be gone for good soon simplyifying everything else - presumably its in such well funded position that they can farm out to one of the specialists in that field to take control. checking the annual report here they reported a combined surplus of £765 million at 1/4/2023 - so its a very well funded scheme by the looks of it compared to that of nearly other listed company i have looked at.
Note scheme liabilities here are large at £2.3 billion
Perhaps somewhat odd that they have had to carry on paying as long as they have but as % of scheme assets surplus is only 25% so the pension scheme trustees have probably argued that they should have that comfort blanket just in case.
would be interesting to see if £765 mill surplus is enough for third party to pay them something to take it off their hands?
Premier Foods (LON:PFD). I still don't understand the announcement. Why is it "suspension" and not "cessation"? If this is because the total liability is in fact very large, why is the suspension of payments treated as good news?
Premier Foods (LON:PFD)
Note i am by no means a pension oracle my view are very lay in nature so i could easily get it wrong on anything pension related.
The way i look at it and company with the pension scheme liability on the balance sheet is potentially on thne hook for unkown future payments in that regard. All that ever happens with these schemes whilst they are still on the balance sheet is that they and the pension trustees sit down and decide whether the company will "need" to fund the pension or not over the short term and if they do how much they need to stump up each year. That situation is reviewed periodically and assessed say 3 years in the future and the same procvess is repeated.
This is where some peeps default to saying - ah well pension deficit is gone and/or no payments are needed ove the next 3 years so the problem has gone away. Thats anything but the truth the reality is its a temporary "holiday". What is important is to get handle on whether what is left may be an issue or not in the future.
So its 100% correct to say its a suspension of payments whilst the company is still on the hook - the investments could suffer catastphropic unexpected loss and te company would be on te hook again in the future.
The saving grace for premier foods is that they appear to somehow by £760 million to the good on the measure being used in the acocunts - its probably that surplus that is tehn only thing giving them confidence the whole pension can be syphoned off to an expert. I would expect the company to predict the end if they had any seriuous doubts so i have to presume the surplus will be enough that they can get shot in timeframe indicated.
Obvious compared to reach this company seems in a much less risky position than reach. If it needs the full £700 mill surplus If thats a real surplus to get shot - that would evidence how much of a noose reach's pension might be around their neck. In that regard though i dont have any predictive powers as to how much premier might pay / receive to get shot and similarly for reach what their similar bill would be. So if someone says pension scheme is no longer an issue they might be right and i could very well be flagging up a potential item that is not material or low chance. In that regard though if you aint heard it directly from the company in plain english i wouldnt be minded to believe an bb poster who goes you dont need to worry about that govenor.
there was a very good article by Maynard Patton a few years back - that is well worth reading it will certainly make more sesne than my ramblings - note it looked at norcros oplc which i have big holding in - despite this being a very mature scheme - the payments out needed carry for for a damn long time at elevated levels - so most of these schemes may take a decade or two or more before the level of outging payments start to materially reduce - thats a long time for something to wrong with returns on sheme assets.
https://maynardpaton.com/2018/...
Premier Foods (LON:PFD) thanks rmillaree suspension it is then and the share price reaction looks generous!
Premier Foods (LON:PFD)
I dont know if the share price reaction is generous - i kinda took the somewhat opposite viewpoint - if they will avoid having to pay out wads of cash they had previously agreed to pay and they now have more clarity ref exiting from pension issue completely thats fantastic news that may warrant a material uptick. as i know nowt about the company i dont know how much of this news was previously predicted and or flagged up though?
hi rmillaree
Obvious compared to reach this company seems in a much less risky position than reach
re Premier Foods (LON:PFD) and pension liabilities generally.
Guess you just couldn't resist raising the Reach (LON:RCH) pension deficit again?
Hope you haven't stirred up davidjhill for another 10 round bout as per we were all (entertained by?) yesterday, with both contestants determined to have the last word.
Sometimes it's best to just let go.
Just saying.
Snazzy
Guess you just couldn't resist raising the Reach (LON:RCH) pension deficit again?
it seemed to be highly relevant comparison - imho - so seemed silly not to compare the two - particulalry as randomly pfd came out with a pretty clear and concise explanation of the position ref their pension compared to reach's much more uinclear position - i would say its probably pretty easy for them to update if they know there is next to nil future risk - not so easy for reach board.
Its not really about point scoring from my perspective and i also presume from that of BnB - i am happy to be educated and corrected as when i get it wrong = and no harm in a bit of back and forth from time to time from my perspective easy to scroll past if you dont like it - apologies to those fed up reading the same thing 10 times - oopsies.
Its not really about point scoring from my perspective and i also presume from that of BnB
This is certainly true for me - I like to challenge in order to be educated. But I’m not clear where I come into a discussion of pension deficits. That’s not in my wheelhouse at all. Have I been mistakenly co-opted? Or is this a broader point?
hi BnB
Have I been mistakenly co-opted?
Yes you have.
rmillaree should have said davidjhill not BnB.
Snazzy
Thanks Snazzy
yes many apologies memory failure here
No problem at all
When I saw this, I thought of yesterday's comments on Reach (LON:RCH) and their pension funding tailing off. (I don't hold either)
I was wondering if we will see other companies in a similar position also be rerated. Anyone have suggestions on identifying these potential companies for DYOR?
Ibstock (LON:IBST) results and commentary today provide an interesting case study on short vs long term accountancy and strategy.
Reported statutory revenue (-21%) and profit (-71%) is way down - and that's only after it is supported by a major inventory build back to 'normal' levels. Apparently a disaster.
However, under the hood, big increase in debt to fund new cost (and carbon) efficient factories now starting to sell products (so de-risked as projects), with new products (like brick slips), 2 site closures and redundancies from restructuring plus bolt on acquisitions.
The company explicitly says it is incurring short term excessive fixed costs to keep skills, capacity and capability it does not need in still difficult 2024 to meet a medium term recovery. Already the UK market leader, it is betting big on UK housing and infrastructure growth
I am a patient optimist and think this is a good way - much better than more politically exposed housebuilders - to be involved in the next UK building boom whenever it comes.
Zipmanpeter, I was interested in your thoughts because I recently sold my holding in Forterra (LON:FORT) which I had bought in early Covid days, so a fairly long holding period. I think it is a good company and well run, but like Ibstock (LON:IBST) they have used 2023 to build stock and continue to absorb manufacturing costs, which has lead to a substantial cash outflow.
My concern is that on lower volumes in 2024, it's very difficult to understand how that will impact the cost price per brick and therefore margins going forward. Also Brickability (LON:BRCK) recently published some industry stock figures which show high brick stock currently. It's going to be interesting to see what happens around pricing, when the house builders start building again.
Finally these brick companies have had a little share price bounce over the last 6 months, while their profit forecasts have reduced, so I may have the opportunity to get back in at a lower price.
Galliford Try Holdings (LON:GFRD) interims. I hold.
Continued progress under CEO, Bill Hocking. Operating margins are always low in construction and related industries, but they continue to progress towards the current 3% target. Exceptional revenue visibility of 98% for 2024 and 83% for 2025, with order book standing at £3.7billion previously £3.5 billion. Improving operating margins, even at 2.5% on revenue of £3.7billion is a positive scenario.
The company is focused on regulated activities in construction and infrastructure, schools, prisons, water etc. I especially like the specialisms it is developing in water industry infrastructure given the forthcoming AMP 8 and the well publicised debacle over the pollution of water courses.
It has also developed a nascent but successful business in private rented and affordable housing.
Galliford Try Holdings (LON:GFRD) and its peer group have learned the lessons from the likes of Carillion and and have a controlled risk based approach to bidding. Most contracts, which are normally restricted to a maximum value of £25m are on a cost plus basis.
Galliford Try Holdings (LON:GFRD) is my preferred pick of its peer group. I was fortunate to buy initially at 167p and have since added based on the above appraisal. Hopefully the market will react positively to this morning's interims?
I hold Galliford Try Holdings (LON:GFRD) . I have read the interim report this morning showing what I would regard as good results beating consensus forecasts , a market cap of £247m and an EV of £66.3 m indicating that they have £180 m in cash yet the share price has dropped just under 3% from 241 p to 234.5 . Being a retail investor is hard work - can someone explain the logic for me because I must be missing something.
Galliford Try Holdings (LON:GFRD) I think you will find that much of the cash held consists of advances from clients and not their own. Having said that Galliford will earn reasonable interest on the cash, whether it is theirs or their clients.
Margins remain v low at Galliford Try Holdings (LON:GFRD) 2.5% margin doesn’t look great…especially as they continue to report some IT spend as exceptional. The history of one off substantial hits from contract snaffoos would suggest a fatter margin is required…notwithstanding what they’ve said/done to reduce risk in their business by better bidding discipline, still looks cheap though
It looks like the market perception of low margin contractors is starting to change (and I suppose this is important part in order for the share to re rate upwards)
The recent share price performance of Kier (LON:KIE) , Costain (LON:COST) , Galliford Try Holdings (LON:GFRD) , Serco (LON:SRP) , MITIE (LON:MTO) and Morgan Sindall (LON:MGNS) is really quite impressive.
We've also had the takeovers of Homeserve and Sureserve and rumours surrounding Serco (LON:SRP) - probably quite easy to construct a deal for an asset backed player (such as GFRD) at a modest premium?
So i'm starting to wonder, do they deserve a fresh look (having previously been put off by the wafer thin margins)......maybe this time its different :)
Decent looking update from LSL Property Services (LON:LSL) broker upgrade EPS 15%, scope for upgrades as the year progresses.
Shares have done nothing for 13 years but may be worth a look
LSL Property Services (LON:LSL) Last director to buy shares (£400k, Dec 23) left the board with immediate effect 27th Feb 24. He wasn't thanked.
Telecom Plus (LON:TEP) puts out an RNS saying it has reached 1 million customers. Within the announcement is statement that trading is strongly in line with expectations. I read that as towards the top end of expectations.
Capita tried to buy one of my businesses once. I can best describe the experience as akin to being corporate raided by a local authority. Uninvestable for me, but I guess there’s a cyclical gain to be had when the economy eventually recovers.
Capita (LON:CPI) looks a real mixed bag. Adjusted results ok, and trying to address cost base. New CEO could make this a turnaround story. Non-adjusted results show they are a little accident prone and have negative FCF. I will give the new CEO time to present (in June I believe), and see if I believe the story. Enough there to hold in meantime, but look forward to Graham's review.
Greyster
My morning smallcap tweet: The Value Destruction Olympics
Esken (LON:ESKN) MicroSalt (LON:SALT) Sondrel (Holdings) (LON:SND) ImmuPharma (LON:IMM) Harland & Wolff group (LON:HARL) Digital 9 Infrastructure (LON:DGI9) Active Energy (LON:AEG) Science in Sport (LON:SIS) LSL Property Services (LON:LSL) React (LON:REAT), Likewise (LON:LIKE), Netcall (LON:NET)
◄Esken (ESKN)► big d4e as it caves to Cyrus Capital Partners demand for immediate Southend Airport bond repayment. Will de-list. Holders probably get nothing. [SP=0.15 Cap=2m]. I hold.
◄MicroSalt (SALT)► US Patent Office says the claims are patentable in co's application for a patent for the production of MicroSalt. Expects patent grant shortly. [SP=90 Cap=39m]
◄Sondrel (SND)► issues £875k convert to ROX Equity Partners at 15% PA to pay Feb payroll and other creditors. Strike is 10p and converts immediately on equity raise of £6.5m min. [SP=10.1 Cap=9m]
◄ImmuPharma (IMM)► financial and biz update. Says it has no current plans to raise equity. Updates on drug dev. Multi-billion mkt natch'. [SP=0.89 Cap=4m]
◄Harland & Wolff (HARL)► wins five-year Master Services Agreement for the fabrication of large structures. First order is £3m over 18 months. [SP=12.2 Cap=21m]
◄Digital 9 Infrastructure (DGI9)► gets Icelandic approval for sale of Verne Global. "Change of Control Consent is still conditional, the Company is confident that all conditions which will need to be met have either already been satisfied or will be satisfied shortly before completion." [SP=18.95 Cap=164m]. I hold.
◄Active Energy (AEG)► receives $1.65m cash from the PDI Parties that pulled out of CoalSwitch plant project. [SP=1.11 Cap=2m]
◄Science in Sport (SIS)► guides FY-Dec EBITDA £2m, in-line with market expectations despite rev down 1.6%. Guides FY24 rev broadly flat and a doubling of underlying EBITDA. [SP=16.51 Cap=30m]
◄LSL Property Services (LSL)► Jan-Feb U/P op profit up by £7.5m, materially ahead of mgmt exp. Has seen a material and sustained increase in valuation instructions. Mortgage completions in line. [SP=238 Cap=247m]
◄React (REAT)► proposes 50:1 consolidation. [SP=1.36 Cap=14m]
In line: LIKE, NET
Purgatory or Paradise?
Usually the stock market usually leads the economy. However today, I suspect GDP is probably not quite as buoyant as the US lead #AI / #GPL1 drug frenzy suggests. Or as dreadful as UK smallcap valuations imply (re PEG ratios).
Meaning, the trick for alpha-seeking investors is to find & invest wisely in a basket of undervalued assets.
No prizes for guessing where I'm currently heading.