Small Cap Value Report (Wed 8 August 2018) - SHRE, TTG, IDP, SCS, STCK

Morning folks!
A couple of interesting RNS announcements to cover today.
In the US last night, we had further entertainment from Elon Musk at Tesla ($TSLA), who tweeted: "Am considering taking Tesla private at $420. Funding secured."
It looked like it was probably a joke to me (and to others), but Musk went on to write a blog post on Tesla's website about it. From a legal point of view, it can be expensive to joke about these things.
Tesla's share price increased by 11% to close at $380 last night, not far off its all-time highs. Stormy weather in Shortville.
Today we have:
- Share (LON:SHRE) - interim results. I'm conducting an interview with the company shortly.
- TT electronics (LON:TTG) - half-year report
- Innovaderma (LON:IDP) - appointment of CEO. Roots haircare brand to be ranged in Tesco.
- SCS (LON:SCS) - trading in line with expectations
- Stock Spirits (LON:STCK) - H1 results
Share (LON:SHRE)
- Share price: 26p (unch.)
- No. of shares: 144 million
- Market cap: £37 million
This is a stockbroker many of you will be familiar with as clients. It trades as The Share Centre.
I've just finished an interview with Richard Stone (CEO) and Mike Birkett (CFO).
My impression of the company hasn't changed. It seems to be providing clients with a very nice service, and is one of the safer brokers.
Beaufort clients will be keen to study their new service provider, as Share won the transfer of 15,000 Beaufort accounts in what must have been a competitive process.
Combining the Beaufort transfer with two other agreements, Share will soon be welcoming 38,000 new customers for a total of £1.5 billion in new assets under administration (AuM).
AuM is making serious headway. From £4.3 billion a year ago, it now stands at £5 billion and that is with the additional £1.5 billion still to arrive. This should translate to significantly greater revenues.
The Share Centre is not the cheapest out there when it comes to execution-only dealing, but it does have an excellent net promoter score (better than all other execution-only dealers) and has picked up a couple of awards for customer service and client satisfaction. So I suppose in some sense you must get what you pay for!
Share also offers ways for clients to access a preferential dealing commission of £7.50 per trade, which is competitive with the no-frills brokers. I would have no problem paying that sort of rate myself. On the other hand, its standard rate (1% of trade value) strikes me as expensive in today's environment.
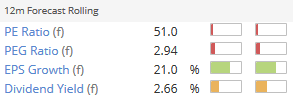
As an investment proposition, Share's balance sheet is rock solid, but margins and earnings are weak.
The company's profitability has been held back for several years by low interest rates and also by its cost base.
I've put together a table comparing some KPIs from Share's performance last year with Jarvis Securities (LON:JIM), a stockbroker where I am a client:
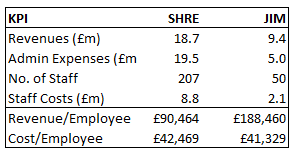
As you can hopefully see, SHRE and JIM's cost per employee is approximately the same at £41k/£42k.
On the other hand, JIM's revenue per employee is more than double that of SHRE.
To put it another way, JIM achieved half of SHRE's revenue using only one quarter of the staff numbers.
And speaking from experience as a client, I've never had the impression that JIM is under-staffed.
Today's results show a continuation of the theme of heavy costs at SHRE, not helped by the regulatory burdens that have been a pain for everyone in the sector. 15% growth in revenues is overpowered by an 18% increase in costs.
This leads to an operating loss of £520k, offset by investment gains from the company's strategic holdings in London Stock Exchange (LON:LSE) and Euroclear.
The outlook is more positive, management having plans in place "to substantially increase the scale of the business", both organically and through more acquisitions and partnerships.
Immediate growth in client numbers can be anticipated with 38,000 clients and £1.5 billion in fresh AuM already locked in, as I mentioned earlier.
We can also hope for improved interest income in the years ahead. Share's H1 interest increased by more than 150% thanks to the BoE rate hike last year, more relaxed rules around how long money can be lent out for, and bigger customer deposits.
The recent BoE hike should improve this source of income again, at no additional cost to Share. Even 25bps makes a big difference when we are talking about >£400 million of client deposits.
Some may feel that this is a sneaky way for stockbrokers to generate revenue, but in fact it is completely standard. And Share is probably more conservative than its peer group in the manner in which it does it.
Putting it all together, I'm happy to leave this on my watchlist. I have no qualms whatsoever about Share's ethos or mission, but it needs to deliver on profitability to become an interesting investment proposition. Hopefully we can start to see this as AuM and client numbers continue to grow. As things stand at the moment, there is not much earnings support for the current market cap.
TT electronics (LON:TTG)
- Share price: 256.5p (+17%)
- No. of shares: 163 million
- Market cap: £418 million
We've covered this electronics equipment provider several times previously in the SCVR.
This includes coverage of last year's interim report.
Last year, TT reported organic revenue growth of 5% for the six months.
This year, organic growth has slowed to just 3%. Thanks to acquisitions, total revenue is up 12%.
Quality
Admirably, the company uses ROIC (return on invested capital) as a KPI and this creeps up to 11.2% from 10.6% (and 9.2% the previous year). Not huge, but acceptable and moving in the right direction.
Similarly, margins are improving. The underlying operating margin is not super high-quality at 7.5%, but it's good that management are highlighting it.
The very large 45% jump in underlying operating profit has been "largely driven by operational leverage and better efficiency". Excellent.
Cash flow
Last year, there was a big and favourable working capital movement that produced an extraordinary cash conversion rate of 128%.
This year, we again see that underlying operating profit is more than fully converted to cash in the first six months of the year (105% conversion rate).
Outlook for the full year is ahead of prior expectations.
The strategy is working:
Our strategy to position ourselves in structural growth markets benefitting from increasing electrification is resulting in a much stronger business with higher growth and higher margins.
It made two important acquisitions during the six-month period, and has a history of acquisition activity, and this will necessarily complicate the accounts somewhat.
The underlying profit is £14.6 million, after making a series of adjustments to the actual operating profit of £7.7 million.
As is often the case, I would personally be inclined to take a stricter view than the company does and therefore would not allow all of these adjustments when it comes to making my own valuation.
Maybe something in the region of £10 million+ is a good, conservative estimate of underlying operating profit.
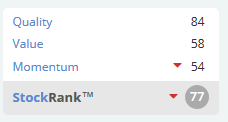
Summary - still looks and feels like a solid business that is performing well and successfully executing its acquisition strategy. Not much organic growth to shout about lately so it's more of a bet on management's deal-making and integration ability, and the overall strategic vision.
Momentum might pick up after today, and Quality should also be on the rise with improving ROIC. Perhaps the StockRank can grow in enthusiasm:
Innovaderma (LON:IDP)
- Share price: 131.5p (+18.5%)
- No. of shares: 14 million
- Market cap: £19 million
Appointment of CEO and Roots to be ranged in Tesco
I covered this stock in some detail at its trading statement in July, so won't repeat what I said then.
We have a double-barrelled piece of good news. The search for a CEO has culminated in one of the company's non-exec Directors being hired for the role.
Separately, the Roots haircare brand (for hair loss reduction) has gained access to over 400 Tesco stores.
This would appear to confirm suspicions that Roots is the most exciting brand right now among IDP's portfolio, after IDP's core brand Skinny Tan missed order expectations in H2 of FY 2018.
I like this sector and have previously considered investing in IDP. It might be worth looking at this again.
SCS (LON:SCS)
- Share price: 212.5p (-1%)
- No. of shares: 40 million
- Market cap: £85 million
ScS, one of the UK's largest retailers of upholstered furniture and floorings, today issues the following trading update for the 52 weeks ended 28 July 2018 (the "Year") ahead of announcing its preliminary results on 2 October 2018.
Trading is in line with expectations.
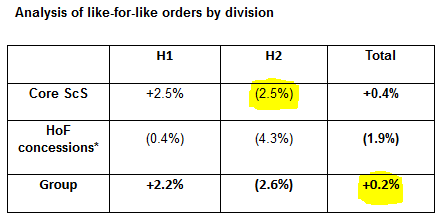
The "softer trading environment", and the weather, made for a weak H2. This means that full-year like-for-like orders are approximately unchanged, as expected:
CEO comment:
"I am pleased to announce that the Group has traded in line with the Board's expectations for the year, an encouraging result given the challenging retail environment. We believe this demonstrates the increasingly resilient nature of our business and the success of our value proposition.
This is another very cheap retailer. The Value Rank is 95 and the overall StockRank is 99.
Some value stats:
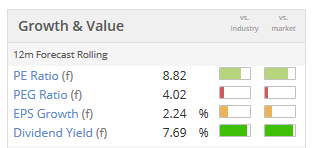
I already have a share in this category in my portfolio (United Carpets (LON:UCG) ), and I don't particularly want to own another one.
The market is pricing many traditional retailers for disaster, and the contrarian in me is happy to bet against that view with a certain, limited portion of my portfolio.
But if I did not already have sufficient exposure to the sector, SCS (LON:SCS) would make for an interesting candidate. It has generated superb free cash flow and reported a cash balance of £52 million (>60% of its market cap), with no borrowings, at its most recent interim results.
Stock Spirits (LON:STCK)
- Share price: 211.75p (+2%)
- No. of shares: 200 million
- Market cap: £423 million
Results for the six months ended 30 June 2018
Stock Spirits Group PLC ("Stock Spirits" or the "Company" or the "Group"), a leading owner and producer of premium branded spirits and liqueurs that are principally sold in Central and Eastern Europe, announces its results for the six months ended 30 June 2018.
I've never covered this one before. Might take a quick look at it before signing off for the day.
- reporting in Euros, revenues are up 5.3% to €124 million
- operating margin is ok at 14%, and operating profit is growing faster than revenues - good. Operating profit up by nearly 10% to €18 million
- modest debt load of < €39 million, low net debt/EBITDA multiple
Competitive positioning appears strong:
At the end of June our total market volume share YTD was 26.8% versus 24.7% last year, and YTD value share was 27.2% versus 25.7% last year. We have started to outperform our main competitor in this period, whilst the third main player in the market has increased its downward trend.Outlook: the group is "on track" with its results.
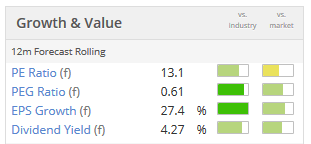
My view: interested to learn more about this. Looks too cheap for a branded spirits company with the percentage market share mentioned above.
All done! See you next time.
Graham
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

44 comments
View from arch Tesla bear Simon Cawkwell/Evil Knievel in his morning blog.
“I’ve been here before. Back in 1990, Polly Peck’s Asil Nadir, clearly all too well informed that the scam was coming to an end, declared that he would arrange a buy-out. The trouble was that no bankers could be identified who shared his optimism. The share price kept slip-sliding away until, eventually, it could no longer be propped up. Thereafter it imploded, and suspension followed a few hours later.
I suspect that Elon Musk is in the same position with Tesla (NASDAQ:TSLA). Yesterday’s shenanigans as the great con artist tweeted out his intention to take TSLA private at $420 a share (or $82 billion all told) obviously hit the shorts pretty hard. But gravity being what it is and the improbability of bankers putting up the necessary for a company marching to insolvency surely means that the only way is down. TSLA has been trading this morning before the opening at $376.
If these bankers are as ready as Musk claims they’ll write puts. And then they may not be….”
No position held, but in reference to DJCP’s post above, I’d suggest that while Tesla shares might be “priced” at something like $380 a pop, I’m not sure they’re necessarily “worth” that. Time will tell ....
Gus.
I have been a happy customer of Share Centre for many years. Provided you take out the Frequent Dealing Option, and have a holding in them, online dealing cost comes to £5.25 per transaction (unsure the discount still applies if you now take a holding). During couple of peak times (when Brexit referendum result was announced for example), their website functioned whilst a major stockbroker's crashed. They seem to put extra staff when anticipated demand was going to be high. More importantly the ISA Annual charge is capped at £60 per annum, whilst the percentage rate charged by some would cost a lot more for a reasonable size holding. If you transfer to them they also pay up to £300 of your costs.
Kind regards.
Graham Re SCS (LON:SCS) any views on the potential impact of the House of Fraser store closures on SCS? It was not mentioned in the RNS.
Hi andy, re: SCS (LON:SCS) no special insight into the HoF issue but it looks like SCS HoF concessions are a small part of the overall business and are doing badly, so it might be ok if they were shut down. G
Share (LON:SHRE) - Headline dealing costs are crazy high, but for £24/quarter extra deals are a fixed £7.50 online (£20 telephone). According to the letter of their T&C's, this can be further reduced to £5.25 for if you own 500 shares in them (which is only £125 worth). For frequent dealing on a medium-large account this is right up there with the cheapest. They also provide superior access to shareholder perks and other shareholder rights. Finally, in my opinion, there is less risk in dealing with a quoted company, or at least a better chance you will get to hear about problems before they become critical.
Caveats: I am not currently a shareholder or a customer. £SHR 's pricing structure seems pretty silly to me. AJ Bell are cheaper still for large accounts and will be quoted soon. Hargreaves Lansdown (LON:HL.) provide good value for both small, medium and large accounts, plus provide access to shareholder perks.
Re SCS (LON:SCS) cash pile...£24.9m is customer deposits as per their excellent presentation ;
https://www.scsplc.co.uk/~/media/Files/S/ScS/pdf/scs-hy18-results-presentation.pdf?pdfdata=1
I’ve held before & rate it highly but it doesn’t feel terribly defensive if the wider economy weakens
Opinions seem to be polarized as to whether the Tesla bid is genuine.What's your best guess,Graham ? :-]
Seems the Tesla/Musk tweet wasn't off-the-cuff, but I'd have thought the way it was done may come under scrutiny (i.e. no official announcement?)
Quick guestimate - at a $60b valuation, the 10% price news rise ($6b) and 10% of stock shorted, meaning that shorters took a $600m hit ? ... But maybe I'm getting confused ;o)
https://www.bbc.co.uk/news/business-45118393
The board had "met several times over the last week" to discuss going private, the statement said.
https://www.cnbc.com/2018/08/08/if-you-invested-1000-dollars-in-tesla-in-2010-heres-what-youd-have-now.html
Tesla stock is currently more than 2,000 percent higher than its IPO price of $17. That means a $1,000 investment in the company then would be worth $22,327
Don't think it is a breach unless proven inaccurate. Tesla have said that musk Twitter is an official source for company information on Tesla.
We don't have proof of "funding secured" yet :) G
Tesla...HUGE short interest in the market and I know many commentators in the UK have said it was a sell (Inc Paul Scott at one time if I remember?).
Must have all taken a huge hit yesterday. I wonder if Wall Street will sell off a bit as positions are sold to try to balance the debt.
Charging 1% on trades is gouging - can't see why anyone would want to pay those rates.
In a release this morning in association with the Beaufort administration, The Share Centre said that larger clients and frequent traders might be able to pay £24 per quarter and then be charged £7.50 for every trade. Not entirely transparent, and I am much happier with Jarvis's lower fees and better transparency.
I've used JIM and SHRE as brokers and holders of assets for some years (+15?) and finally sacked SHRE as part of a cost cutting exercise, I've never had a problem with either broker and I like the old fashioned JIM customer interface. I've also had some experience with transfers of assets as a broker joins or moves names/software/ownership and frankly it is very frustrating as data is lost, software tools evaporate etc, as a client I hate it and much prefer JIM's organic growth strategy where my money is my money and it is easy to access, recently Sharetrade's transfer was a disaster.
Re Share (SHRE)
Charging 1% on trades is unbeliuevable in today's climate. That leads them to deal for only the very smallest portfolios.
May be worth mentioning that Share Centre discount their fees to anyone with a shareholding, including those who have the flat-rate £7.50 dealing commission.
I'd be interested in Graham / Paul's view on Clipper Logistics (LON:CLG).
They came on to my radar back in April, when Paul gave them a favourable mention at, I think, The Investopedia event.
At that time they were standing at £4.58, but they've since dropped substantially, and as of today they're trading at around £2.97. This is despite announcing new orders recently, and generally looking well-positioned to succeed from the growth in mail order shopping.
I'm increasingly tempted to take the plunge at what looks increasingly like a bargain price, but I'm wondering if there's something that I'm missing.
I was thinking the same thing today. Numis has a target of 500 a share (cut from 520p). Singer however say results were disappointing which might account for some or most of the fall...their target is 395p
https://www.research-tree.com/companies/uk/transport-logistics/clipper-logistics/research/n-1-singer/share-price-reaction-overdone/694bc37f-05ee-46b0-9cb4-e27123f19247
Hello CK, very good to see you here.
Just a little 'protocol' tip here, Graham and Paul normally only comment on companies in this column when there is news / announcements.
As luck would have it though, Clipper Logistics (LON:CLG) announced their results a few days ago and Graham covered it at the time here
Thanks Gromley, I'd obviously missed that update, and protocol tip duly noted!
I will second the "good to see you here" sentiments CK. Lots of refugees from TMF here.
Jon
Thanks Gromley! G
Not strictly a small cap but any thoughts on Hill and Smith, previously regarded as a highly reliable compounder?
Re Hill & Smith Hill & Smith Holdings (LON:HILS) - I've held for a few years and had a similarly positive opinion. Aways found their updates transparent and open. A few alarm bells started ringing (a bit too quietly) in May though when that update blamed project delays/a weather impacted start to the year (though they said things had improved since mid march). So i was surprised 1) I couldn't find either issue mentioned in the FY results from March when all was v positive and 2) although they were confident in May of improved orders/meeting FY expecs, things seem to have actually got worse.. All feels v 'un-hill and smith like' to me..
Is Paul Scott no longer doing these reports? Have not seen him do one in weeks.
Secondly, to Graham, if he is talking to Share (LON:SHRE) management, I would like him to ask the question regarding their technology spend. I understand the expenditure is necessary, but it is worrying to see the constant dribble of cash out the door year after year. For the past 5 years, the cash balance has been in decline. Do they have a timeframe for when the cash bleed stops and they go into positive territory?
"Is Paul Scott no longer doing these reports? Have not seen him do one in weeks."
As I understand it Paul is taking a (well earned) sabbatical this summer, which is why Graham has been doing all the reports. Paul mentions it in the most recent report he did (when covering for Graham).
https://www.stockopedia.com/content/small-cap-value-report-mon-18-jun-2018-ptsg-vlx-ang-koov-opti-375614/
Hi. re: Share (LON:SHRE), broker forecasts are for it to generate positive adjusted net income during the current financial year (ending December) and for this to make further improvement in FY 2019. Obviously it depends on the adjustments involved and actual performance relative to expectations in terms of whether we get a reported profit or not. We'll have to wait and see. G
Re $TSLA
He probably got a perverse delight by trying to burn shorters, but its a dangerous game to be playing if just a joke.
Its not as if the USA is short of litigants!
A third for TT Electronics please Graham.
Hi, can you look at SECURE TRUST BANK (STB)
Interim results, Rev £72.5m v £61.1m, PBT £15.1m v £11.5m, EPS 74.7p v 53p. Re positioning of the business has lead to be income growth. With strong performance seen throughout the business. The board are cautiously optimistic of further growth through the second half. Shares down from £21 to £16.50 recently.
A second vote for TT electronics (LON:TTG) Graham that you have covered previously. Impressive interims with outlook for the full year "ahead of our prior expectations". I hold.
All the best
Jonno
Hi Jonno, TT electronics (LON:TTG) is in there now. All the best. G
Morning all! Morgan Sindall (LON:MGNS) might be too big to cover here now but I'd like to hear views on it - EPS up 28%, price up 4% last time I checked. However forward order book down 6% & Brexit fears mean I haven't bought any. They're building a new Poetry Library up here in Manchester so local interest too really!
Innovaderma (LON:IDP) - their baldy cream 'Roots' is to be sold in Tescos and they have a new CEO, previously a NED. I'd forgotten I still held this, up 22% this morning, wonder if it will hold into results
PS Vertu Motors (LON:VTU) - can anyone work out if Directors have bought or sold?
Thanks!
Why doesn't the ticker show?
Do you mean £G4M John Stone?
Could you do £GFM from yesterday?
Graham commented yesterday that he won't be covering that stock.
https://www.stockopedia.com/content/small-cap-value-report-tue-7-august-2018-peb-hvn-pdg-cto-dom-388579/?comment=23#23
Great.
I find out whats happening to my Beaufort assets from Share's accounts rather than the Administrator.
Phil
Me too, Phil. Doesn’t say much for PWC.
Richard
Richard
Certainly doesn't, howerver, I'd better second a request for Graham to look at Share as it's now going to be one of my providers.
All the best.
Phil
My morning smallcap tweet:
Share (LON:SHRE)
Share (SHRE) H1 rev up 15% but EPS -0.2p (0.0p) due to new regulations, principally MiFID II and GDPR. Did not find warning about this in previous RNSs this year. MiFID II has lengthened many offline interactions. Has taken steps to mitigate this. Underlying profit after tax £50k (£250k). Has grabbed 38k ex-Beaufort clients. Outlook: "Benefits of these new acquisitions are expected to be felt from Q4 2018, and the Bank of England's recent increase in the base rate will assist in raising interest income." They have some work to do to hit F/C of 0.47p EPS.
I will second Share (LON:SHRE) and hope you revisit TT electronics (LON:TTG), which you covered positively in March. It's been a fantasstic long term hold for me.
Jon
Yes, I'm studying Share (LON:SHRE) and TT electronics (LON:TTG) today. Cheers! G
Graham, Could you take a look at Share (LON:SHRE) the leading independent retail stockbroker, which operates as The Share Centre? Interims are out this morning here. Appears the near term future is going to be very strong " have plans to substantially increase the scale of the business, both organically and through acquisitions and partnerships."