Small Cap Value Report (Tue 19 June 2018) - CTP, TAP, IDP, FOOT, BON

Morning!
Updates I've noticed today (with your help in the comments!) are as follows:
- Castleton Technology (LON:CTP) - final results
- Taptica International (LON:TAP) - trading update
- Innovaderma (LON:IDP) - trading statement
- Footasylum (LON:FOOT) - full year results
- Bonmarche Holdings (LON:BON) - preliminary results
I will be writing through the afternoon, due to other demands on my time this morning - please check back soon.
Best,
Graham
Castleton Technology (LON:CTP)
- Share price: 82.75p (unch.)
- No. of shares: 79 million
- Market cap: £65 million
Acquisition of Financial Modelling Platform IP
This is a new one for me.
Checking the archives, Paul has covered it twice previously.
Most recently, in November 2017, he was not overly excited by it.
Having a listen to the management interview published at PIworld this morning, the CEO describes the company as "a complete one stop shop when it comes to providing basically all the key solutions that a housing association would require to deliver business functions to the tenants".
In the UK, its target market is the 700 housing associations with over one thousand properties. It also has a small Australian business.
Nearly all of the large UK housing associations are already customers. So for growth, it is looking to cross-sell to these HAs its entire range of software and services products. 40% of its customers used more than one product in the latest financial year, up from 35% last year.
The government is looking to reduce the net rents charged by HAs to their tenants every year. While that should motivate some HAs to increase efficiency using Castleton's products, doesn't it also negatively affect their budgets for spending on support services?
In general, you want your company's customers to be getting richer and having more money to spend, not the opposite! So I can't see why rent reductions are necessarily positive for the investment case.
The positive features of this stock on my initial view are:
- Strong cash conversion, enabling settlement of defcon (deferred consideration) and debt reduction
- Very well positioned among its customer base.
- Good forward visibility on sales with mostly recurring revenues and £8 million of deferred income (cash paid before revenue recognised)
Negative features are:
- B2B, selling to the public and non-profit sector. (Dependent to some extent on government spending & government policy. Customers quite price-conscious.)
- Few opportunities to find new housing association customers in the UK.
- Professional services / consulting work. Likely to be labour-intensive.
- No balance sheet cushion as the equity is dwarfed by intangibles
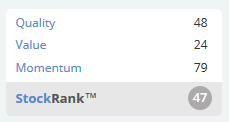
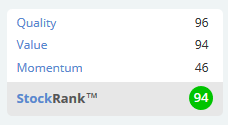
It has a very average StockRank and a forward P/E ratio of 14.6, according to Stocko data. Perhaps I've missed something, but I can't see any compelling reason to get involved at this point.
Taptica International (LON:TAP)
- Share price: 345p (+24%)
- No. of shares: 67.6 million
- Market cap: £233 million
A powerful relief rally today from this online marketing company.
A relief rally occurs when there is a positive surprise due to a lack of bad news. The market has been expecting Taptica to take a hit from the GDPR, but today's update doesn't even mention it.
To the contrary, we get a positive earnings beat instead:
...the Company expects to report adjusted EBITDA for FY 2018 moderately ahead of market expectations and revenue growth in line with market expectations demonstrating a moderately higher-than-expected EBITDA margin.
Operational and cost efficiencies improved the gross margin at its video brand advertising business (this one), so perhaps this is what fed through and boosted the EBITDA margin beyond expectations?
Either way, it's clearly a huge relief for shareholders to hear that everything continues to go smoothly. It has been nearly a month since GDPR implementation. If it was hurting the business model, today would have been a good day to announce that.
The valuation at Taptica has reflected foreign-stock risk (it is headquartered in Israel) and also regulatory risk (as acquiring customer data may prove more difficult in future). It has particular expertise in Facebook advertising, and of course Facebook has itself has been under pressure in recent months over how customer data is collected on its platform.
Taptica bears much in common with XLMedia (LON:XLM) and Plus500 (LON:PLUS), who share prices have exhibited similar discounts (for geographical and regulatory reasons).
It's not the absolute correct thing to do, but I am avoiding all of these stocks, virtually as a rule, when it comes to my own portfolio.
Note how the XLM share price collapsed by over 30% in a single day last week when it acknowledged uncertainty over the regulatory status of its European markets.
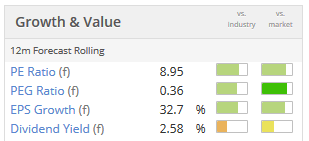
Taptica doesn't appear to be suffering from this problem, so perhaps it's the safest play among the three stocks I've mentioned. I would never feel comfortable enough to hold it in any size, and people with attitudes like mine probably explain why it is so cheap:
Price Monitoring Extension - a reader has asked what the price monitoring extension RNS is all about. I might not be the best person to ask, but I can try to answer this. Please do correct me if there are any mistakes in what follows.
My understanding is that price monitoring extensions allow additional time for the stock exchange to complete an auction.
Auctions take place at the market open, at mid-day and at the market close, and they sometimes take place at other times of the day, when trading is irregular. A very large share price movement with volume is the sort of thing that commonly triggers an auction. The closing auction is how we get the official price at the end of the day.
During an auction, the stock exchange takes in all of the bids and offers and analyses them, and meanwhile prevents trading so as to allow things to cool down. Then an uncrossing trade takes place at the price which best matches all of the bids and offers. If it needs more time to complete this process, we get a price monitoring extension RNS, to explain why normal trading has been suspended.
Innovaderma (LON:IDP)
- Share price: 111.5p (-7%)
- No. of shares: 14.4 million
- Market cap: £16 million
More share price weakness and disappointment at Innovaderma, owner of a range of consumer brands (mostly hair care and skincare).
This is a stock I really want to like, but was turned off it (as I explained at the previous trading update) by its expansion into so many sectors, many of them unrelated. If it had executed a small number of brands really well, then I would have been happy to see it add a few more brands via acquisition. But the pace of expansion was too much, too fast, by my estimation.
The company has been unable to predict its profitability this year. PBT was originally forecast at £2.3 million, according to my records. This was then halved at the profit warning in March. It is now significantly reduced again:
Revenue for the period increased strongly by 23.5% on a constant currency basis to approximately £11m (FY2017: £8.9m). However, partly owing to the significant one-off investments made across the business in launching new brands in the last quarter including the launch of Prolong, stock availability issues for Roots, and lower than expected revenue out of the US in June, profit before tax will be approximately £0.65m, lower than previously expected.
"Stock availability issues for Roots" - that's the sort of excuse that can sometimes make for a "good" profit warning.
Roots has been unable to meet consumer demand, and is about to be launched in Boots. Sounds promising.
The company is looking for a new CEO to manage hair care and skincare. This also sounds like a good move. Execution hasn't been terribly good so far, so a new CEO focused on these products would be welcome.
Meanwhile, the Exec Chairman will focus on the Life Science division.
The mere existence of a life science division is the main thing which has prevented me from buying the stock up to this point. It just seems too ambitious for a small company at such an early stage of its development.
A wide range of new distribution deals are announced in today's update. The incoming CEO will be busy.
Forecasts are as follows:
The Board expects 2019 to be a year of substantial revenue and profit growth as its key brands continue to flourish alongside new product launches, all underpinned by the strength of the DTC platform. The Company is still finalising budgets for 2019 and 2020, but expects FY19 revenues to be in excess of £14m with profit before tax in excess of £1.6m.
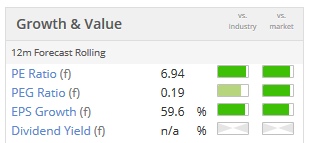
Hitting forecasts has not been its strong point recently, but the shares would certainly be on the cheap end of the spectrum if it did:
I think the key points of uncertainty are:
- New CEO - will they be any good?
- Are the recent sales blips really due to one-off issues? is Skinny Tan going to make it as a recognised brand?
- Is there any chance that the life sciences division could be sold off, to simplify matters? Or will it prove to be valuable component of the overall group?
- Is the company going to run out of working capital?
On the final point, the company is very clear on that matter today:
The Company's balance sheet remains strong with sufficient working capital to fund the anticipated growth of the business.
But do note that IDP raised money in November 2016, December 2016 and October 2017 (all the way up at 276p).
The most recent placing was for £4.4 million so you might think that the company does not need further capital, but it can't be ruled out.
Overall, I am tempted by this share at the current level. The uncertainties are plain to see, but maybe they are fully priced in now?
Footasylum (LON:FOOT)
- Share price: 80p (-52%)
- No. of shares: 104.5 million
- Market cap: £84 million
Wow - I did not expect to see a 50% reduction in share price with this one! Commiserations to any readers holding this stock.
It may turn out to be an over-reaction, after all. But for now, it's the classic tale of an IPO pumping up expectations rather high before flotation, and then disappointing shortly afterwards.
It has only been listed for about seven months, originally priced at 164p.
These were the financials presented to investors prior to IPO:
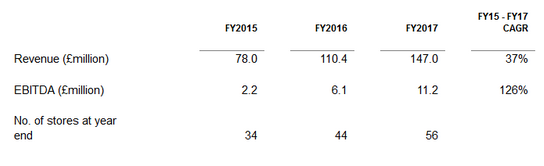
As you can see, both revenue and EBITDA were making dramatic progress higher, along with the number of stores. An expectation of this trend continuing is what helped to generate a P/E ratio of about 28x (as of yesterday).
At the trading update in January, the company presented sales growth of 35% for the first 44 weeks of FY 2018 (ending in February). It made no mention of EBITDA, but said that trading was in line with expectations.
These are the actual results today:
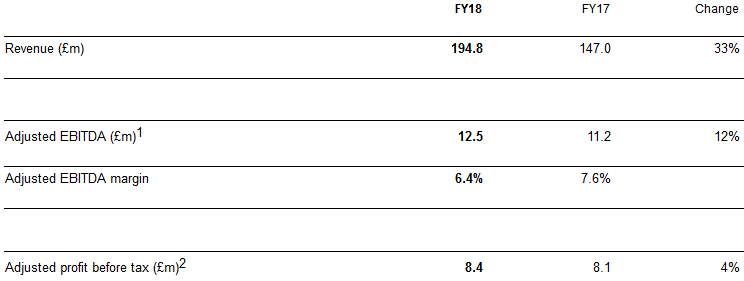
As you can hopefully see, EBITDA growth has slowed to just 12%, far below the exponential growing trend in the pre-IPO financials.
Revenue growth is also a bit softer, and there is only modest growth in adjusted PBT.
Worse, we are told to expect that FY 2019 will see lower growth, compared to FY 2018.
The weak High Street is culpable:
While our core target market of the 16 to 24-year-old consumer has proved to be comparatively resilient in a downturn, our trading since the beginning of the new financial year has undoubtedly been impacted by the widely documented weak consumer sentiment on the high street.
The company says that FY 2019 revenue will be in line with expectations, but the costs of "investment in our consumer offering" and store capex will result in "more modest growth" in FY 2019 adjusted EBITDA.
Does that, in itself, warrant a 50% share price reduction? Probably not, but I imagine that some shareholders were left feeling mugged by the IPO when they saw today's announcement.
The big question now is whether the shares have fallen to a level where even the miserly value investors among us would want to get involved.
Personally, I do think it is getting into interesting territory, at about 10x adjusted PBT.
From the £8.4 million adjusted PBT figure, I would deduct the £0.4 million share-based payment charge. The exceptional items - £4.1 million of IPO costs and £1.9 million of VAT provision - look like reasonable adjustments to make, so I wouldn't deduct them.
Therefore, I would use an adjusted PBT figure of £8 million. We can assume this converts to adjusted net income in the region of £6.5 million (after tax).
How to value it? My understanding of Footasylum is that it's primarily a warehouse for the big footwear brands, and its own brands have limited pricing power. This inevitably limits the valuation I would consider to be fair value for it. Maybe around a £60 million market cap?
The stock market has an awful lot of cheap retailers at the moment. Today, Footasylum joined their ranks after discovering that it hasn't bucked the trend on the High Street. Unfortunate that this was only discovered after IPO.
Bonmarche Holdings (LON:BON)
- Share price: 110p (+7%)
- No. of shares: 50 million
- Market cap: £55 million
Talking about cheap retailers, we have the likes of Bonmarche Holdings (LON:BON) and also N Brown (LON:BWNG) (covered here last week), each trading below 8x earnings.
These results confirm the online sales growth mentioned in the April trading update.
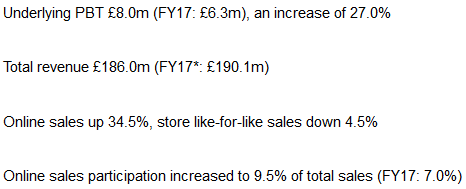
It's just a shame that online sales aren't already a bigger slice of the pie. Despite rapid growth, online sales aren't yet big enough to take up the slack from declining store growth.
The all-important outlook statement is as follows. Trading is in line with expectations:
The financial position of the business continues to be sound, with no net debt, and the robust balance sheet provides a stable platform for the future.
We will continue to improve our proposition, through the implementation of a series of self-help initiatives. Whilst we anticipate that the market will remain difficult, we expect these ongoing improvements to make a real difference to customers, and we look forward, with confidence, to delivering further progress in the coming financial year.
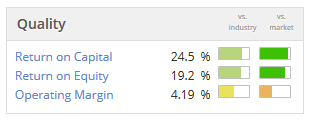
As Paul has noted previously, it's not a particularly high-margin business. The gross margin is 58.4%, and the operating margin is a lowly 4.4% (using today's figures).
Despite this, it has generated very nice return on capital stats, thanks to the very efficient conversion of its asset base into sales:
Conditions are tough out there (see Footasylum) and this might never deserve a premium rating on the merit of its own brands. But I think there are signs at this company of competent and shareholder-oriented management who haven't taken an undue amount of risk. One of the more interesting retail stocks at the moment, I think.
All done for today! Sorry again for the slow start. Hopefully I managed to write up a decent report in the end.
Cheers,
Graham
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

44 comments
Re Thalassa Holdings (LON:THAL) ..are they still leasing at vast expense a stately home owned by Mr Soukup?
Thanks for the write-ups as always Graham. Some interesting thoughts on Taptica International (LON:TAP) and Bonmarche Holdings (LON:BON) - two opposite ends of an interesting spectrum but both struggling to increase their share price.
Any chance of a comment on FLYBE who released Full Year Results today.
Hi folks.
I'm not sure it has been widely reported yet but there is a world wide shortage of CO2.
I know this sounds ridiculous as we are trying to cut CO2 emissions but food grade CO2 is in very
short supply just now.
I am a publican and when placing my order today with Heineken was told that they are unable to supply
John Smiths or Amstel for this very reason.
My brother is a large scale brewer and has confirmed that the shortage is starting to bite. He is worried.
This will not only affect the beer industry but also the soft drinks market.
When this becomes publicised I would expect the relevant shares may take a downwards blip.
You may wish to check your portfolios or maybe open a couple of shorts?
https://www.gasworld.com/breaking-news-co2-supply-crisis-hits-europe/2014944.article
Kind regards
Douglas
A short on Fevertree Drinks (LON:FEVR) springs to mind as a good candidate!
Hi Graham,
When you look at Taptica International (LON:TAP) could you explain the RNS notifications for the Price Monitoring please?
Thanks,
Hi - I did that re: Price Monitoring Extensions. I hope it makes sense now! G
re Footasylum (LON:FOOT) : the under-performance in years 1 to 2 of IPOs is almost a predicable pattern and presumably is linked to some extent with large equity holders exiting within that period. even Boohoo.Com (LON:BOO) suffered a similar fate after an IPO in the high 60s it tanked to 24p within a year on a profit warning...of course the rest is history. $FB IPO'd around $46 and then dropped to $18 within Year 1 ..the rest is again history
Here's an article from the FT in 2015 based on research on IPOs: there may well be a tradeable/investable edge in catching good growth stocks in the the early nadir of their developing "story": I guess the trick is to have sufficient domain/sector/market expertise in that area to understand their offerings and longer term GARPishness: or maybe to just watch and wait and then take a position on the emergence following the doldrums
The structural destruction of retail by technology and shifting consumer habits doesn't help as omni-channel is still nearly as unintelligent as it sounds.
Good chart DS !
I'm not surprised by the AIM line which would include a lot of blue sky 'story stocks', heavy loss-makers, Chinese frauds and speculative resource stocks taking a cheap listing on the junior market.
It would be interesting to see what the chart looks like with only profitable and growing businesses included and how many end up doing a Footasylum (LON:FOOT) or Accrol Group (LON:ACRL) by issuing a profit warning in their first set of results.
My gut feeling is that IPOs which are used for growth (i.e. not to cash out existing shareholders), have a decent track record of growing revenues, are profitable and get through their first set of results with a clean bill of health, can be decent hunting ground for overlooked opportunities.
It's the bad 'uns that people remember. But £WKG and Rathbone Brothers (LON:RAT) among others have done very well recently. Long established businesses with good track records and managements that retain a decent stake are good signs, as is having one of the better nomads.
None of that is rocket science - a good track record shows that that there's a real business, presumably one that's making money, and a good advisor can help a company through the culture shock that comes with the relative transparency of listing. And committed managements are obviously a generally positive thing, although if the CEO is proprietorial about "his" company then that can be an issue.
There's actually some (now quite old) research into AIM stocks that shows this. If I remember correctly about a third of stocks delist within 5 years, although a few of those through getting taken over or moving to the main market. It's a bit of a casino, frankly, but you can weight the odds in your favour if you're careful.
timarr
Bonmarche Holdings (LON:BON) -
Ageing people pottering around secondary and tertiary metro centres is a secular growth area. What does Bonmarche need to do to become a glamour GARP stock? By all means have a bit of online going on but the growth market is defo old biddies pottering.
I've looked but don't hold as can't see the picture from them...they ain't grasping the oppo well enough and playing it too safe which means they might get outplayed by someone else. Plus I own SCS (LON:SCS) which was brought to market by same PE company (Sun Partners) a few years back which retains large stake in both so don't want to double up plus SCS is the much better managed business with clear strategy/identity and upside of at least 1x from current share price over coming years with high divi
Not suggesting it merits a write-up (unless people see it as a recovery play finally turning the corner) but Hornby (LON:HRN) final results today include an unusually frank Exec Chairman strategic report highlighting the challenges facing the business, especially manufacturing logistics and discounting policy https://www.investegate.co.uk/hornby-plc--hrn-/rns/final-results/201806190700027571R/ Possibly there's some read across to others in the niche hobby market?
Hi Graham,
InnovaDerma looks interesting if they can keep their marketing costs under control. Gross margins seem high enough and there are plenty of warm words about their progress on product placement in retailers. I would be interested in your thoughts. I am not a holder.
Thanks,
Peter
Comment on Innovaderma (LON:IDP) - https://www.stockopedia.com/content/innovaderma-figures-disappoint-but-laid-groundwork-for-growth-376214/?comment=1#1
Interested in views why I'm wrong.
Great comment re: Innovaderma (LON:IDP). All to play for. I'm intrigued by the possibility it could still come good..
Hi Peter
re: Innovaderma (LON:IDP). It's include in the report. Feedback always welcome! G
Bonmarche Holdings (LON:BON) has a £20 m online business (growing in FY18 at >30%). Standalone (I don’t know if it is viable standalone) could be worth a large part of the market value. The CEO seems to have done a good job at reinvigorating the online offering.
Not a holder, but struggling to reconcile this statement from the Footasylum (LON:FOOT) results announcement with a 46% fall in the share price this morning. The “gloomy” expectations commentary seems pretty generic to U.K. high street retail in general so not quite sure why Footasylum (LON:FOOT) is getting caned so hard. Hopefully Graham or others can enlighten us .....
Gus.
Clare Nesbitt, Chief Executive of Footasylum, commented:
"We are pleased to report a strong performance for the financial year, our first as a quoted company following our successful IPO last November. We have delivered broad-based growth across all of our channels and product categories, while also continuing to invest in our infrastructure and talent in order to support further long-term expansion.
While our core target market of the 16 to 24-year-old consumer has proved to be comparatively resilient in a downturn, our trading since the beginning of the new financial year has undoubtedly been impacted by the widely documented weak consumer sentiment on the high street.
Despite this, we are confident that continued investment in digital and in our stores will allow the Company to deliver strong revenue growth for the full year in line with market expectations. This includes increased investment in our consumer offering ahead of our usual peak trading period in the second half and delivering additional store upsizes alongside new store openings. However, this will have an associated increase in both expected capital expenditure and property costs for the current year and as a result, we now anticipate that, adjusted EBITDA for FY19 is likely to show more modest growth than in FY18.
In the longer-term, we remain confident that the Company's differentiated, product-led, multi-channel proposition, combined with strong partnerships with core suppliers, will underpin its continued progress."
The clue to Footasylum (LON:FOOT) 's drop seems to be here:
https://www.stockopedia.com/sh...
Footasylum (LON:FOOT)
Broker Peel Hunt says the guidance is "a major surprise
for a company so recently floated"; downgrades to "reduce" from
"hold"
Lol a broker majorly surprised that IPO float projections are based on glass 100% full type forecasts that don't materialise.
Are any of the bods here surprised that a "recently floated" retailer is struggling in the current climate - i doubt it.
YET ANOTHER IPO that has disappointed within a year of listing!
It's becoming almost a farce how often this is happening. It makes me think that a primary investment rule should be to avoid all IPOs until a full 12 months of confidence and delivery against pre-float promises have been shown.
Why the big fall?
"increased investment in our consumer offering" = cut prices.
I hate this PR nonsense.
Graham, I think we have decided Debenhams is a risk too far, but interested to hear your thoughts on todays announcement, which isn't very good. Interesting that internet sales up 16%. I wonder if this isn't one of those times one might regret not buying a few in 5 years time. A Next in the 1990s?
Hi Camtab. Which announcement? G
Bonmarche Holdings (LON:BON) please, seems like a Strong Buy
Morning Graham,
Taptica International (LON:TAP) Please. The company has recently got caught in the general GDPR headwinds despite reassurances from the CEO (definitely worth a read if you have a minute) recently that they were unlikely to be affected by this.
Unusual client base in that it isn’t overly exposed to a few high value deals and quotes in excess of 300 clients. Very compelling product, mkt leading and seen as an innovative organisation ( I hold). I wonder how much of the market sentiment to this company is dictated by the fact they listed in the UK and operate out of Tel Aviv?
it hasn't disappeared ...second button in , choose quote
Ah yes, there it is - thank you dscollard!
Hi Graham,
Paul covered 3 RNS's on companies intending to list, is this something you'd consider including ?
I dont know if other readers would find this interesting/useful?
Hi john - I do cover intention to float notices when I have time and when I spot something interesting. Was there one in particular you wanted coverage of? G
Hi Graham, no specific RNS, more that a quick overview of what’s been released/coming up is useful. If you already filter out what looks interesting and update on that, ideal. Thanks
I thought I'd try to calculate the EPS of Bonmarche Holdings (LON:BON) on a cash-free basis. Assume that:
* They have £15m spare cash (the average monthly balance)
* They could pay it out as a special dividend and rely on their revolving credit facility
* Average debt would be £5m a year (the average would really be zero, but of course interest received on cash will be negligible compare to interest paid)
* Interest rate of 7% (they are already paying the facility fee)
* EPS due to grow 20% next year.
Interest costs would £0.35m, £0.28m after tax, 0.6p a share. Diluted earnings per share would therefore be 12.8 * 1.20 - 0.6 = 14.76p on an adjusted current share price of 105p - 30 = 75p. A forward PE of 5.1.
Compare with Next (LON:NXT) who have significant net debt (although some of this may well be seasonal) on a PE of 14.
Hi - Next (LON:NXT) have no effective net debt. They are cash positive. The net debt numbers in the balance sheet all relates to their financing book (ie. where they finance a customers purchases at an apt APR), which is both highly profitable and more than covered by customers debt balances owed to the company.
Graham,
Could you have a look at Castleton Technology (LON:CTP) which I hold. Not watched todays video release at time of posting.
I like the growth story in a relatively secure sector but over half the profits are a tax rebate (R & D) and NTAV is a concern although with good cash flow they are paying down debt at a decent rate and have bought in the software platform they use, also announced today.
Dave
Hi Dave, thanks for that - Castleton Technology (LON:CTP) done. G
Hi Graham,
Second for Footasylum (LON:FOOT) I believe these guys are the original founders of JD Sports and looking to replicate that model, but with trainers.
Hi Graham,
Benchmark please, Benchmark Holdings (LON:BMK), full results today look promising and finally a profit although looks mostly driven by a £9m tax credit. They have a new chairman who looks like he is to try and focus on 'shareholder returns'. I am hoping this means leveraging what they have built over the years and reining in the strategic plans. The CEO is the founder but he seems too focused on building the ideal product set than profit & cash - just my opinion having followed them for a few years and watched his PI presentations.
Financial summary
Revenue +9%
EBITDA +21%
Adjusted EBITDA2 +91%
Profit £3.6 (-£8.2)
Thankyou...
Bonmarche Holdings (LON:BON) - Following on from my comment on Friday (https://www.stockopedia.com/content/small-cap-value-report-fri-15-june-2018-rec-nxr-bpm-gym-bwng-374429/?comment=21#21), here are my thoughts on the results:
* Revenues had already been disclosed, profits are in line hints and with my expectations (I don't know what the market's expectations were)
* Cash levels are disappointing. I was aware that it would be significantly lower than reported at the interims, as it is every year, but after the prior years exceptional investment I had expected an increase. This is recognised in the report which (under the heading "Cash flow and cash position") explains this is partly due to timing issues. It reminds us that the average balance is much higher, giving a figure of £15m and that they have an unused (but paid for) revolving credit facility. This raises the question of how much the market cap should be adjusted to get an enterprise value.
* The recent cash-in-bank trend at year-end worries me: 2016: £13m, 2017: £7m, 2018: £5.3m. I have not looked into this in detail.
* They confirm lease cost deflation of 0.3%. I found this is disappointing.
* The update on current trading is downbeat and I was hoping for better. This should be put in the context of a general conservatism in the current management's outlook statements and a virtual refusal to discuss the weather after the previous CEO repeatedly blamed it for bad results.
* They warn an ongoing drag from exchange rates offset by ongoing benefits of cost cutting and price increases / product mix changes.
* The big news is the dividend increase of 8.5% to yield 7.5% at yesterday's prices. Although this implicitly and explicitly expresses confidence in the future, this is more about deliberately lowering dividend cover rather than reflecting an expectation of an imminent large jump in profits.
* Net margins are 4.3% (6.9% at FY2015 peak). This makes them much lower quality than say Next (at 18%) and gives them higher operational gearing for good or bad.
I think that they are undervalued and that market will like this. The dividend increase may draw attention to them and result in a re-rating. However as you have probably gathered, I am mildly disappointed.
I agree with leoleo73 about the Bonmarche Holdings (LON:BON) dividend that
Although this implicitly and explicitly expresses confidence in the future, this is more about deliberately lowering dividend cover rather than reflecting an expectation of an imminent large jump in profits.
If a share is already yielding 7%, that usually says the market is doubtful the divi can be maintained. Personally I would have preferred to see Bonmarche Holdings (LON:BON) keep the money and either bolster their balance sheet or invest in further improving their online offer, or staff training, or building the brand. Inflation is running at 2% or so and in that context I don't think dividend increases of 8.5% are sustainable, unless as leoleo73 says they reflect an expected increase in profitability.
I wonder if Paul's view is still "Why buy Bonmarche Holdings (LON:BON) when you could buy Next (LON:NXT) and get a much higher quality business, at a fair price?"
By the way, there used to be a formatting option to show a quote from another post with special formatting. Has it disappeared or am I being thick?
My morning smallcap tweet: IDP's 2017 droops but toots Roots in Boots.
Taptica International (LON:TAP), Alliance Pharma (LON:APH), H C Slingsby (LON:SLNG), Innovaderma (LON:IDP), Ubisense (LON:UBI)
Taptica (TAP) guides FY EBITDA moderately ahead of market expectations, revenue in line with market expectations.
Alliance Pharma (APH) £34m placng at 91, an 8% discount, to help fund £60m 'material earnings enhancing' acquisition.
Slingsby H C (SLNG) Recent trading improved. First 5 months of FY LFL -1%. Q1 was -6%. "However, disappointing levels of order intake across the Group so far during June 2018 lead the Directors to remain cautious."
InnovaDerma (IDP) Guides FY pretax £0.65m, lower than previously expected. Blames significant one-off investments made across the business in launching new brands, stock availability issues for Roots, and lower than expected revenue out of the US in June. Roots will be ranged initially in 359 of the largest of Boots' 2,500 stores from August. Guides FY19 revenues over £14m, pretax over £1.6m.
Ubisense Group (UBI) wins SmartSpace sale in North America. Initial revenues > £4m expected in 2018 with a framework agreement for similar sized follow-on orders expected in 2019.
Alliance Pharma (LON:APH) has announced a £60m acquisition and placement this morning, acquiring rights to a medicated shampoo brand, Nizoral, in the Asia Pacific region. Funded through a combination of debt and new equity book build being placed at c. 91p/share.
https://www.investegate.co.uk/alliance-pharma-plc--aph-/rns/nizoral-acquisition-in-apac-and-proposed-placing/201806190700108203R/
Represents about 13% of current Alliance Pharma (LON:APH) market cap. Looks a decent add on although 10% placement discount seems quite steep.
Gus.
Interesting update from Iofina (LON:IOF) this morning who make iodine out of fracking waste water. Production up '575-605 metric tonnes ("MT") of crystalline iodine in the full year 2018 from its four currently operating IOsorb® plants. This compares with last year's total production of 503MT', due to another plant (1 of 7) but due to take a small hit of £100k revenue due to China deciding they have been 'dumping'. (No position, but the main advfn Versarien (LON:VRS) bod 'superg1' is underwater there, so must see something in it.
runthejoules, not sure what you mean re your comment on VRS of which I am a holder. Why is 'superg1' "main bod" in VRS and what does "underwater" mean in this context? I also note in your ADVFN comments you say you have bought for your Mum, which is in terms of share holding a position in which you are involved and therefore technically you do hold a position.
Camtab
What runthejoules means is that the ADVFN poster 'superg1' is a leading authority on both Iofina (LON:IOF) & Versarien (LON:VRS) . His book cost on Iofina (LON:IOF) is higher than the current price ('underwater'), yet he contines to hold.
The comment has no direct implication regarding Versarien (LON:VRS) .
Camtab, for more information please re-read.
Versarien (LON:VRS) is simply the new Iofina (LON:IOF) - expertly and persuasively ramped despite having no tangible business. It will be labelled a sucker stock by Stockopedia until it can show at a minimum compounding revenue growth. How the business develops is at this time a coin toss, though statistics, for example the graph posted elsewhere in these comments, tell us most small listed companies fail. We don't recognise that because share listings have a structural survivorship bias. That doesn't mean it is guaranteed to go the same way; I have the same insight into the medium term future as everyone else, which is to say none at all.
Hi Graham if you get a chance to look at Ethernity Networks (LON:ENET) that would be great. Thanks.
Castleton Technology (LON:CTP) FY results today in line with expectations.
CEO Dean Dickinson and CFO Haywood Chapman give an overview of results:
http://www.piworld.co.uk/2018/06/19/castleton-technology-ctp-full-year-results-2018/
60% recurring revenue. High margin. Seems pretty predictable.
Yes I second the Bonmarche Holdings (LON:BON) request as it look like potentially an interesting contrarian recovery play on 7x & 7% 95 Stock Rank super stock, albeit a bit small.
Paul / Graham - could you comment on Footasylum results please, the first after IPO
Could you take a look at Bonmarche Holdings (LON:BON) if you have time.
Results are today.
Highlights :-
· PBT £8.0m (FY17: £5.8m), an increase of 38.1%
· Underlying PBT £8.0m (FY17: £6.3m), an increase of 27.0%
· Total revenue £186.0m (FY17*: £190.1m)
· Online sales up 34.5%, store like-for-like sales down 4.5%
· Online sales participation increased to 9.5% of total sales (FY17:
7.0%)
· Basic EPS 13.1p (FY17: 9.2p), an increase of 42.4%
· Inventory levels reduced by 4.8% to £23.9m
· Cash generated from operations £10.6m (FY17: £9.5m)
· Recommended final dividend increased to 5.25p per share, bringing
the total for FY18 to 7.75p, an increase of 8.5% (FY17 total dividend: 7.14p)
Operational Highlights:
Many thanks
Lloyd