Small Cap Value Report (Weds 10 Nov 2021) - TRCS, GYG, RNO, ZOO

Good morning, it's Paul & Jack here with the SCVR for Weds.
Agenda -
Paul's Section:
Gyg (LON:GYG) - profit warning yesterday, but not enough information is provided to properly assess the situation, now a large customer seems to have gone bust.
Renold (LON:RNO) (I hold) - strong interim results, and Finncap reinstates full year forecasts. Looks cheap, but remember to adjust for the large pension deficit. I'm very pleased with progress here, the turnaround seems to have worked well.
Jack's Section:
Tracsis (LON:TRCS) - growing software company focused on Rail and Traffic data. Notes from call with management now included. Worth investigating.
Zoo Digital (LON:ZOO) - strong revenue growth and the group continues to invest for the future, although there's a loss after tax, and cash burn is a consideration. Progressive ups its FY22 and FY23 forecasts, but the valuation looks high given that Zoo still has to prove the profitability of its business model.
Explanatory notes -
A quick reminder that we don’t recommend any stocks. We aim to review trading updates & results of the day and offer our opinions on them as possible candidates for further research if they interest you. Our opinions will sometimes turn out to be right, and sometimes wrong, because it's anybody's guess what direction market sentiment will take & nobody can predict the future with certainty. We are analysing the company fundamentals, not trying to predict market sentiment.
We stick to companies that have issued news on the day, with market caps up to about £700m. We avoid the smallest, and most speculative companies, and also avoid a few specialist sectors (e.g. natural resources, pharma/biotech).
A key assumption is that readers DYOR (do your own research), and make your own investment decisions. Reader comments are welcomed - please be civil, rational, and include the company name/ticker, otherwise people won't necessarily know what company you are referring to.
Paul’s Section
Gyg (LON:GYG)
50p (down 14%) - mkt cap £23m
Trading Update (profit warning)
We already knew that there were uncertainties over contracts at this superyacht painting company. Major shareholder, Harwood Capital, pulled out of a takeover bid recently, over contract uncertainties, which we reported about here on 29 Oct 2021.
I’d like to be able to report that the fog is lifting, but today’s update doesn’t give us enough information to work out properly what’s going on.
This is what the company says today, which sounds a can of worms to me. Note the conditionality of its reassurance below, which I’ve bolded -
As a direct result of the significant operational and financial disruption
caused by Nobiksrug, GYG will now deliver a financial outturn for 2021 much lower than the Board's previous expectations. Importantly, the Board is confident that the Group will remain profitable at the EBITDA level in the current year. The Board also reiterates that, after further thorough review, it is confident that the Group can meet its working capital requirements and repay its borrowings as they fall due providing that the Nobiskrug situation is resolved before 31 December 2021, which the Board fully expects.
On this basis, the Board does not believe that the Company will need to seek additional funding from shareholders in the foreseeable future to maintain operations or to meet its obligations.
In this type of situation, investors need to know chapter & verse - how much money is owed (if any) by the customer that has gone bust? What impact on profit, cashflow, and cash, will there be? This latest update from GYG is far too vague. To be fair, there are probably good commercial reasons for that. You don’t want to publicly disclose sensitive commercial information on the RNS, that the other side will read and take advantage of. Therefore I can see why investors are being kept partially in the dark.
However, our job at the SCVR is to attempt to unpick and make sense of company updates. In this case it’s just not possible at this stage, and we don’t like guesswork, so we can only watch & wait.
The trouble with Harwood Capital, Christopher Mills operation, is that they’re incredibly shrewd investors who have been known to take their best ideas private, whipping away the upside from small shareholders. So why would I want to follow them, knowing that they’ll take GYG private if the upside case looks likely? They’ll pay the minimum premium necessary, that’s the problem. So Harwood’s involvement caps the upside to a level that doesn’t excite me. They did this with Essenden a few years ago, and I have a long memory. Hence why I admire, but tend to steer clear of, anything with a big Harwood Capital shareholding. They shift risk:reward too much in their own favour, the way I see it. Whereas personally, I want open-ended upside, not a major shareholder poised to grab the upside for itself & leave me with some crumbs.
.

.
Renold (LON:RNO) (I hold)
33.5p (up 8% at 10:09) - mkt cap £75m
Renold (AIM: RNO), a leading international supplier of industrial chains and related power transmission products, announces its interim results for the six month period ended 30 September 2021.
Significant revenue growth…Record orderbook…Strong cash generation
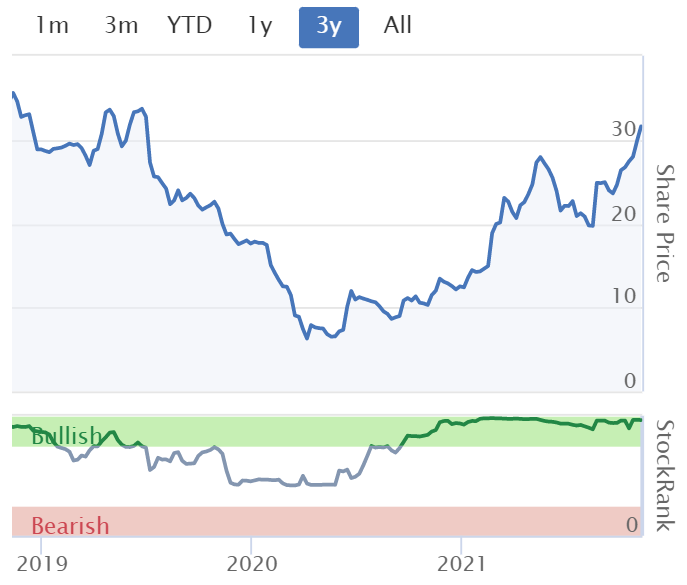
I’ve had a quick skim through these interim results, and am very pleased with the company’s progress. The company was overly-indebted in the past, and has a huge pension deficit, so many investors ignored this share. Under the surface though, a decent turnaround has been underway, something we spotted and have been flagging up to SCVR readers for quite a while.
It’s now financially secure, and performing well.
Revenues up 17% to £95.3m, which is back to almost pre-pandemic levels
H1 adj operating profit of £8.2m
Adj EPS very good at 2.3p (H1 LY: 1.1p)
Strong order intake of £113m, which is more than H1 revenues, so the closing order book has risen to a record high of £72.1m
One-offs boosted profit by £1.2m, mainly US Govt support (loan forgiveness)
Net debt of £13.9m is now quite modest, at only 0.6x adj EBITDA, so I don’t have any solvency concerns at all, the finances have been fixed.
Balance sheet overall has NAV of £3.3m, less intangible assets of £28.5m, so NTAV is negative at £25.2m - not ideal, but it’s the £77.8m (after tax) pension deficit which is the big drag on the balance sheet - it’s a manageable long-term liability, so annoying rather than dangerous.
The pension scheme is an annual cash drain of about £5.5m, and the company has been able to pay this without diluting shareholders, although it obviously does absorb cash that could otherwise be used to pay divis.
No interim divi, due to uncertainties over costs, supply chain risk, etc.
Outlook - no specific outlook section. The company expects continuing pressure on materials, energy & transport costs in H2 - no surprises there.
Price rises - encouragingly, Renold says it has successfully passed on increased costs to customers. That’s a key positive. The strong order book is encouraging in this regard - it’s easier to pass on price rises when capacity is already booked up with existing work. Renold’s products are best in class, and sell for premium prices.
Broker forecasts - thanks to Finncap for reinstating forecasts today. It has pencilled in 3.3p EPS for FY 3/2022 which looks beatable, given 2.3p has already been done in H1. That means the share is on a high single digit PER - cheap, although remember the big pension scheme deficit is part of the reason for the PER being low.
Acquisitions are mooted, which would be a great way to gradually dilute the pension scheme into a larger group. Norcros (LON:NXR) has done that very successfully, as an example.
My opinion - so far, so good! I’m very happy to continue holding for another 6 months, and then review it again. This is a decent business, which has been restructured over a number of years, and is now beginning to shine. Factories have been modernised with heavy capex, the pension scheme burden has been managed. Therefore we should see divis resume at some stage, plus there’s scope for bolt on acquisitions too.
It’s going well, I’m happy with progress so far. We could receive a takeover bid at some stage too, possibly?
Note below that the StockRank system seems to have got wind of the turnaround early on.
.
.
Jack’s section
Tracsis (LON:TRCS)
Share price: 970p (+3.74%)
Shares in issue: 29,350,067
Market cap: £284.7m
Tracsis is a leading provider of software, hardware, data analytics/GIS and services for the rail, traffic data and wider transport industries
Half of the business is software for the railway industry, which is expected to grow double digits over the long term with plenty of opportunities. The other half is transport-related data analysis to do with traffic etc. Obviously business here dried up over lockdowns.
The new management team is focused on better integration across the group (which was formed by a series of acquisitions) complemented by a couple of additional purchases.
Shares have more or less doubled over the past year and are now well above pre-Covid highs, so the investment case rests firmly on the group’s growth prospects.

Highlights:
- Revenue +4.6% to £50.2m with growth in the higher margin Rail Technology & Services Division and in Data Analytics/GIS,
- Revenue grew by £3m (+12.7%) in Rail Technology & Services Division
- Revenue -3% in Covid-impacted Data, Analytics, Consultancy & Events Division,
- Adjusted EBITDA +23.8% to £13m driven by software revenue growth and cost reductions,
- Profit before tax +12.2% to £4.6m,
- Diluted earnings per share are down from 9.67p to 7.82p as a result of a larger tax bill,
- Cash balance up from £17.9m to £25.4m,
- Dividends to be reinstated in the upcoming financial year.
The business has performed well despite Covid challenges and should bounce back as lockdowns ease. A large, multi-year RailHub enterprise software contract win in the UK will double the user base to over 30,000 individuals, and Tracsis has continued to implement various TRACS Enterprise rail contracts that were won in previous years.
The pipeline has grown, with additional multi-year rail contract opportunities, the recent acquisition of Flash Forward Consulting (FFC) strengthens Tracsis’ transport insight offering, and the group continues to invest in integration, management, processes, and systems.
This business was acquired in February for up to £2m.
Post year-end, Tracsis has seen a rebound in Events and Traffic Data ‘with both markets expected to recover to full activity levels through the course of the coming year’. There has also been another acquisition - Icon - which will enhance the group’s Data Analytics/GIS capabilities. Q1 trading is in line with board expectations.
Rail Technology and Services - the biggest segment, with revenue up from £23.4m to £26.4m, adjusted EBITDA up from £8.6m to £9.1m, and PBT up from £8.1m to £8.3m. Annual recurring and routinely repeating revenue was c70% of the segment total. Underlying organic revenue growth excluding acquisitions grew by 10.9%.
Revenue for Rail Operations & Planning increased from £10.5m to £10.9m; Digital Railway & Infrastructure sales rose from £11m to £13m; and Customer experience revenue increased from £2m to £2.5m.
Data, Analytics, Consultancy & Events - Revenue down slightly from £24.6m to £23.8m, with adjusted EBITDA of £3.9m (2020: £1.8m) and PBT of £3m (2020: £0.5m) thanks to cost reductions. Activity levels have been progressively recovering here as restrictions have been lifted.
Data Analytics/GIS revenue was up from £5.4m to £5.7m; Transport Insights was more or less flat at £3.5m (2020: £3.4m); Traffic Data revenue was £1m lower at £7.7m; and Event Transport Planning & Management was stable at £6.9m (2020: £7m).
Outlook -
The Group has a clear growth strategy and has a strong balance sheet to support its delivery. We continue to implement a number of large multi year enterprise software contracts and have a record pipeline of future opportunities. Whilst the timing of these remains difficult to predict, the Directors believe they establish a strong foundation for future growth. In addition to delivering organic growth, M&A remains a core part of our strategy. We also recognise the need to continue to enhance integration and collaboration across our businesses, increase senior management bandwidth and talent, and improve our systems and processes as we prepare for scalable growth. We have made good progress in the year and will continue to invest in this area.
The Board believes that the Group is well positioned to deliver further growth in the coming financial year and beyond.
Balance sheet - as a software company, perhaps it’s to be expected but more than 60% of £93.5m in total assets comes from intangibles. Cash is the second largest line, up from £17.9m to £25.4m. This covers the £23.4m of current liabilities and there’s no debt.
Tracisis is reliably cash generative. Free cash flow of around £9m is notably higher than the reported profit after tax of £2.5m.
Conclusion
The valuation is quite high here, to be expected from a growing software company. Tracsis also looks to be recovering in its Data business, so if everything plays out well then the momentum could end up quite strong here.
This looks like a good company to me, worth a closer look - in fact I’m going to publish what I’ve written up so far as I’m about to hop on a call with management. I’ll post the notes once that’s finished.
Notes from call with management:
Scuppered slightly by a poor connection, but still enough positives to invest some time into considering whether or not there's enough growth potential for the company to kick on from its current valuation.
Spin out from Leeds uni in 2004, listed in 2007. It originated from the Computer Science department as a solution to complex optimisation capability. That’s things like shift scheduling and work patterns, which can become surprisingly complex in industries such as Rail.
After listing, the group operated an impressive buy and build strategy. A total of sixteen acquisitions have been made, with five of those falling under the current CEO’s tenure. The focus has shifted slightly more recently towards a more complete integration of previously acquired businesses.
Half the business is in rail tech, which is higher margin (c35% EBITDA) and preferred by investors. The other half is more data and services, which is 12-13% EBITDA margin, but there’s an opportunity to make more of this side of the company. It’s essentially two quite different models and the group is currently working on integrating them.
Loads of white space to go for, confident of taking market share. There’s not many (if any) companies out there doing what Tracsis does.
They have looked at more than 200 companies in the US to analyse the competitive landscape there. Nobody is doing what Tracsis does. That’s good as it’s a market share opp but means they can’t buy like for like. Instead they will look to acquire someone with a different product but the right routes to market. This is perhaps the kind of acquisition we can expect - not another Tracsis, but something that opens the door in a new geography.
The US was the only international company discussed, but management says there is plenty of remaining opportunity in the UK as well. Total addressable market is about £100m for Tracsis in UK Rail - but this is a tailored figure and very much represents what the company can go after now as opposed to simply saying ‘the UK Rail market is worth so many billions of pounds’. The company would be happy if, in five years time, they had £50m-£75m of UK Rail revenue and can’t see why this couldn’t happen.
The UK rail market is very political with a lot of apathy. It’s not like the car market for example, which is much more commercial. That means procurement cycles are longer but, on the flip side, there are switching costs once you’re in. Some of the group’s products are things like Enterprise Resource Planning, which require onboarding, but again, once the customer is won that creates switching costs. Sticky revenue and recurring business. So there are some attractive characteristics.
Zoo Digital (LON:ZOO)
Share price: 130.84p (+1.04%)
Shares in issue: 87,651,594
Market cap: £114.7m
ZOO Digital supports Hollywood studios and streaming services to globalise their content by providing localisation and media services. Anyone who has watched Squid Games recently (which is referenced in today’s update) will be aware of the increasing demand and ability to consume content from around the world.
The company was founded in 2001 and operates from hubs in LA, London, and Dubai, with a development and production centre in Sheffield, UK.
Its media services include: ZOOsubs, ZOOdubs, ZOOstudio, and the group has invested to create an end-to-end suite of services to prepare both original and catalogue content for digital distribution. Customers include Disney, NBCUniversal, HBO and ViacomCBS.
It’s been a strange period in terms of share price performance, with the group just about approaching the multi-year highs of 2018.

Flicking back through the SCVR write ups, I note that I’ve been described as a ‘Yorkshire sceptic’ on this company in the past due to volatile profitability and cash generation, but the StockRank has been improving since 2019 or so.
Companies do change and evolve, so it pays to keep an open mind and periodically reassess prospects. But Zoo is not yet dependably self-funding, which makes it riskier than other software companies that have already proven their profitability.
In August, it was reported that new projects were back to pre-pandemic levels and that TV production continues to surge. This, combined with the on-going migration of catalogue content to streaming platforms and the launch of those platforms in new territories has driven very strong sales growth in H1 of 64% over the prior year period, a trend that we expect to continue.
Highlights:
- Revenue +64% to $26.9m driven by strong growth for subtitling and media services,
- Gross profit +68% to $8.6m,
- Adjusted EBITDA +82% to $2.4m,
- Operating profit of $0.4m, up from a loss of $0.1m,
- Cash balance up from $2.1m to $8.2m following $10m placing,
- Conversion of convertible loan stock into shares, reducing borrowings and interest payments.
Media services grew by some 142% due to a high volume of work in preparing catalogue titles for release on streaming platforms. Localisation grew 30% as new productions resumed in Q2, and a global growth initiative has been launched.
Further investments have been made in the key content sourcing and distribution locations of Turkey, Korea, Thailand, India, Japan, and Malaysia. Zoo’s R&D team has also been expanded in order to increase the pace of innovation into things like AI research in speech technologies. It’s hoped that these initiatives will increase the group’s competitive advantages in future.
Outlook
- Strong order book across all service lines with good visibility for H2,
- New mastering initiative and international expansion provide two additional revenue streams,
- The board will continue to invest in expanding capacity to support an increase in market share in H2 and into FY23, which is expected to generate increased profitability in future periods.
Stuart Green, CEO declares:
This is our time. We are but one of a handful of players that can meet client needs through our market leading approach. We are confident of strong growth for the foreseeable future. We are currently building increased capacity to accelerate sales and making great strides toward our medium term target of $100 million.
Conclusion
The ‘Over-the-Top’ (OTT: film and television content platforms provided via high-speed internet connections) market was worth around $122bn in 2019 and is forecast to reach $1tn by 2027, which is a huge CAGR.
It is worth noting that Zoo is still loss-making to the tune of $1.7m over six months. Revenue has jumped by some 64%, but COGS have risen pretty much in line. Perhaps it is correctly investing in order to seize a substantial global opportunity but at some point, profits are required. Zoo is not yet reliably cash generative, so I’d want a stronger balance sheet and more of a financial cushion here, particularly given the ongoing investments for growth.
The group generated a negative $913k in net operating cash flow in the period, and then spent a further $1.3m on the purchase of PPE and intangibles. Excluding the $10m fund raise, it looks like the group would have burnt through $4.8m of cash. So with $8.2m of cash remaining, further dilution could be on the cards if the group struggles to translate revenue growth into cash generation.
On the other hand, management does say it is expecting increased profitability going forward.
The group seems confident of delivering long term growth and Progressive Equity (Zoo’s commissioned broker), is upgrading its FY22 and FY23 estimates. Interestingly, Progressive also says it expects that ‘significant investment for growth’ should be largely completed by FY23 at which point the profitability of the underlying enterprise might become clearer.
The projected revenue trajectory is impressive and the medium term target is for $100m, which the group may well be able to reach.

Ultimately though, I’m not clear what kind of profit margins a more mature Zoo might be able to command. It’s a growing market but what kind of pricing power does the company have in five years’ time, and might competition become more of a concern?
It’s an interesting space to operate in, with clear structural growth as content becomes more globally distributed. But there’s also a fair bit of good news priced in at current levels, so I’m happy to wait and watch the expansion play out a little further.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

45 comments
Late in the day RNS from Angling Direct (LON:ANG) giving an update on the recent cyber hack. Restating that it’s now under control and the various websites and social media platforms are coming back on stream. Reconfirms that they don’t expect any material impact on the business (hope or expectation?). Must confess to having had a small nibble at just over 60p.
https://www.investegate.co.uk/...
Good that they’ve tackled it head on and got on top of things so quickly. Hopefully won’t get caught with their pants down again in delicto flagrante ….. etc., etc.
Gus.
£TPG
anyone else thinking that at these prices might be worth a contrarian / turnaround play? Am tempted to buy some on the basis that I could see a 2nd bid around the 6.5p mark within 12 months or that the new board starts the turnaround.
Downsides - do we think a fundraise is likely to top up balance sheet? or continuing management disruption.....anything else?
RE: Tp (LON:TPG)
anyone else thinking that at these prices might be worth a contrarian / turnaround play? Am tempted to buy some on the basis that I could see a 2nd bid around the 6.5p mark within 12 months or that the new board starts the turnaround.
Personally I wouldn't but my record in these things isn't great. For someone more comfortable with risk than me there may be an opportunity here.
However, Science (LON:SAG) have previous in not overpaying and with effective management control of TPG they have a number of ways of making things difficult for existing shareholders - a massive profit warning and/or a rights issue at a price above the market value, for instance. A lot may depend on what M&G decide to do - with their near 19% stake it will be difficult for Science to get above the 75% control mark.
But I think it's stretching credibility to believe that Science sees TPG as having an independent future. The real value will come from taking them over and merging the business.timarr
DFS -Gatemore Capital Management stakebuilding.
Sorry for being off-topic, but I have just seen that it's been reported recently on Sky News that the above activist group are stakebuilding in DFS, (although not publicly disclosed yet)believing their share price to be significantly under-valued and susceptible to a Private Equity bid. Surely this must also read across to SCS, baring in mind their cash situation at the last update? Trading update for SCS at end of November probably. Any thoughts Paul/anyone?
Perhaps but Scs (LON:SCS) possibly a bit small to get any private equity interest?
Tracsis (LON:TRCS) (I hold)
Thanks for the write-up Jack and for the extra comments from your call with management - greatly appreciated and very insightful.
Geographical Opportunity
To add to your notes on the market opportunity in the US, note the jump in North America revenues in H2 FY21:
*(I would ignore the H2 FY20 negative number - it's correct, but immaterial, and it was from the Jan-June 2020 period, so I'm happy to take no notice of it given the extreme volatility around that time.)
It's still tiny of course, but it's a start and hopefully they can build on the remote condition monitoring contract won last year, especially in light of the Biden infrastructure plans.
Valuation
By my estimates underlying cash generation was closer to £10m in FY21 (this is after capex and leases) and I expect this to jump to £13m in the current ahead, and £14/£15m next year as normality returns and the full year impact of many acquisitions feeds through.
Also, as you pointed out, a lot of revenues are highly recurring, so combined with the above comment on cash generation, I think a high multiple is warranted.
I personally apply a minimum x20 multiple of cash generation, which I would increase if I see more progress in North America.
So by own personal metrics this is valued quite fairly right now.
Cash
Given the:
I can't help but think that the company will return something to shareholders at some point. Does it really need so much cash sitting on its balance sheet?
My preference is that they buy back shares (and cancel them) if they have too much cash sitting around. It seems like a nice position for the company, and shareholders, to be in.
---
There's really very little to like here and I remain a happy holder.
Cheers
A
Hi abtan.
Well thought through comments on Tracsis (LON:TRCS) (as always). I think there is a “not” missing in your final sentence. Hopefully after the “little”.
Gus.
Haha
Yes, a minor omission there :)
How much read across in Marks And Spencer (LON:MKS) results is there for Joules (LON:JOUL) and Boohoo (LON:BOO) ?
I thought the Wetherspoons one had more read across for Boohoo. Whenever I go to my local ‘Spoons at the weekend it’s rammed with yoof drinking cheap drinks and wearing cheap clothes.
MKS one reads well for Joules and SOS imo. Definitely starting to align with Paul in thinking SOS might have a decent beat on forecast, been here before though!
Renold (LON:RNO) - at face value the interim results look very good this morning, citing EPS of 2.3p but I think the results are being flattered by maybe a slightly cheeky EPS figure and comparison to the COVID hit last year - unlike a lot of other companies they aren't using pre-COVID comparisons. The positives are:
However, they note that they had a significant one-off benefit from the US Govt waiving a COVID loan (plus a smaller one-off cost impact). This reduces adjusted operating profit down to £7m but they haven't provided the equivalent EPS figure. By my calculations, if you take the £7m figure and then take off net financing costs and taxation you get to £3.8m profit after tax which translates to diluted adjusted EPS of 1.6p (note I am using the diluted share count figure). 1.6p EPS is still good but slightly less good than the headline figures used by the company. My general understanding of balance sheets and income statements is not very good so please do correct me if I am wrong.
I can't quite tell whether there is a second half weighting generally with Renold (LON:RNO) but, using my figure, given the positive order book maybe this points towards full-year EPS of 3.2p-4p? Given this has often traded at 8-9x P/E historically reflecting the low growth and pension deficit, but now with a bit of growth thrown in for H2, then maybe a share price of 40-44p is a reasonable target?
Would love to hear Paul or Jack's expert take.
Note I sold out at 27p as I didn't project results this good and was concerned about possible supply chain issues. I might buy back in though as there's still 20-33% upside by my calculations (at time of writing share price is 33.3p)
Not small caps so no comments expected or requested, but as a general overview positive announcements from Itv (LON:ITV) and Marks And Spencer (LON:MKS), which has been in short supply over the last few years. Carolyn McCall and Steve Rowe appear at last to be turning round their "tankers", albeit slowly. Slightly surprised that both remain independent. As to how the market reacts, well that is another matter.
Hi jonno.
Yes, good reports from both Itv (LON:ITV) and Marks And Spencer (LON:MKS) after several years in the doldrums. I agree Itv (LON:ITV) is a clear bid candidate (although a bit like Godot, it never seems to arrive) but I think the Marks And Spencer (LON:MKS) brand is now pretty diminished and the substantial debt pile is a pretty big poison pill for any potential suitor to swallow, especially since they cannibalised their freehold property dowry several years ago.
Gus.
Morning Gus
As many contributors will know I have been a patient and frustrated holder of Itv (LON:ITV) for a number of years, having misjudged my original purchase. My reasoning for continuing to hold is the value in the back catalogue and ITV studios, which has produced some excellent programmes, Line of duty, the Bodyguard and more recently Vigil. I find it difficult to believe that some of the big media conglomerates have not or are not running the rule over the company. Take out price £2 plus, but that is speculation, at least for the time being.
I am still slightly adrift on my entry price, but with dividends received fairly close to breakeven.
As for Marks And Spencer (LON:MKS), I missed the boat, but as you say debt is an issue and likely to deter potential suitors.
I hope members will excuse my one time foray into large caps on the £SCVR.
Fingers crossed Paul does have a look, he is particularly good when he does retail and Marks results this morning are interesting
I think the Marks And Spencer (LON:MKS) update is fantastic given this period is still impacted by COVID and it is looking very decent value in my opinion (I hold). Food is a growth driver here (+10% on 19/20), plus Ocado income, plus the dark horse might be international online which is starting from a lower base but is +142% up on 19/20 pre-COVID. Clothing and home is flat with 19/20 which I think is very good and remember that before COVID clothing and home was declining year-on-year so that has now been halted (AND during a period when there were store closures at the start of the period and when some sites will have been affected by lower footfall).
Re net debt, the headline figure includes lease liabilities which I personally wouldn't use. Excluding lease liabilities it's £0.8bn - still high compared to market cap but that's come down quite a lot and the company is continuing to repair its balance sheet.
I think the market has not been recognising how Marks And Spencer (LON:MKS) is transforming and is ignoring some of the growth drivers in the business. In the next financial year or the one after I think this can return to EPS figures in the 30s because food is higher, now you have Ocado, a much better UK online presence, and stronger online international clothing and home, and clothing and home may start to grow. I am therefore targeting 300-400p in 12 months having bought at 90p and topped up today at 230p.
And don't forget there was no dilution during the pandemic.
EDIT: Also don't forget Marks And Spencer (LON:MKS) is H2 weighted. So I think Shore Capital's projected EPS for this financial year of 21p looks pessimistic and I would expect closer to 25p EPS maybe?
I have to give my thanks to abtan who picked up on my developing interest in Itv (LON:ITV) back in July and left me a very encouraging comment on the merits of it, on my BBB Fund post.
This led me to doing a deeper research into ITV. I never bought since July, but last week saw some encouraging Q4 industry outlook, which caused me to take a medium sized stake yesterday (at 109.5p) just before the Q3 results came out today.
I think 140p is definitely achievable based on revised broker forecasts that will drip in over the next few days.
The key threat was advertisers pulling spend in Q4 because of stock issues. This doesn't seem to be the case, not flagged in today's outlook.
(I hold)
Itv (LON:ITV)
I bought in the depths of the pandemic induced panic. ITV is clearly a takeover candidate, but a lot may rest on the outcome of the Public Service Broadcasting review. ITV has threatened to wak away from its PSB committments if the new arrangements aren't fairer - i.e. don't address the rise of the streaming platforms and spread the PSB requirements.
Once that's sorted - which could take until 2024 - then I'd expect an offer sooner rather than later. Whether the government would allow it through is another matter.
timarr
Hi Timarr
If there were to be an offer for Itv (LON:ITV) it would at least provide a benchmark for the share price. Also I would expect that an initial offer would 'flush out' other potential suitors.
Whether the Government would allow it through is as you say another matter. Having said that if a bid were to create a conundrum for the Government so be it as it previously spurned the opportunity to level the playing field with the likes of Amazon, Netflix et al.
Like you I added significantly in the early days of the pandemic.
All the best
RE: Itv (LON:ITV)
Hi jonno
The price was - and is - way out of kilter with global valuations for media content and production. Everyone focuses on advertising revenue - which I get - but that misses the enormous underlying value. I know intangibles are ... well ... intangible, but some of this is obvious.
In a bidding war even double the current price is too cheap. I do wonder whether the government would intervene - but if they extend PSB requirements to streaming platforms then the issue becomes moot, I suspect.
timarr
That's also why I bought, the content value and the value of the production studio. When you look at the valuations paid for studios in the USA...
I wonder if Itv (LON:ITV) were to spin off their studios into a separate listing. Whether that would unlock some of the hidden value.
Angle (LON:AGL)
New research paper published from St Barts regarding the use of CTCs for enhanced, non-invasive, treatment of prostate cancer. It has been picked up (and translated) in the Times and Daily Mail.
hTTps://abstracts.ncri.org.uk/abstract/circulating-tumour-cell-analysis-to-evaluate-docetaxel-treatment-response-and-resistance-markers-in-prostate-cancer/
hTTPs://www.thetimes.co.uk/article/blood-test-help-treating-prostate-cancer-risks-t5qdtkln5
Thanks I had missed that. My biggest small cap position. Asleep at the wheel but happy.
£AGL Also my biggest position – by a very long way. Hoping for a merry xmas courtesy of the FDA.
Renold (LON:RNO) HY results out today, they look pretty good to me, shares are up 8%.
Key stat for me in these Renold (LON:RNO) numbers is that order book is up from £46.5m at 9/2020 to £72m at end Sept this year.
£PROC (ProCook) IPO priced at 145p, towards the lower end of the indicated price range of 137-185p. About 25% of the company/£40m of shares being placed so not a huge amount of paper for the market to digest. Not sure if this tells us something about investor reaction to this particular company or a degree of satiety/fatigue creeping in after a lot of new issues/ secondary placements in recent months.
https://www.investegate.co.uk/...
Gus.
I think ProCook is quite an attractive proposition and have placed an order to participate in the IPO.
Rubix Group pulled its float recently (link here), referencing poor IPO conditions. There have been so many listings that I think an element of fatigue is setting in.
Tracsis (LON:TRCS) overview of results for the full year 2021 by Chris Barnes, CEO and Andrew Kelly, CFO. They outline the achievements of the year, where the Rail Technology and Services Division grew revenue by 12.7%. Group PTP increased 12.1%. The cash balance is £25.4m. Q1 trading is in line with expectations, and Data Analytics, Consultancy and events is expected to fully recover in the coming year. Video and podcast. It all sounds positive. There is a results webinar on Friday (12th) at 13.30 register to attend here.
Separately, Tpximpact Holdings (LON:TPX) (formerly The Panoply) will publish interim results on 1st December, there's a management results webinar with Q&A on Thursday 2nd December, at 11am. Register to attend here.
Finally, Ig Design (LON:IGR) will publish interim results on 23rd November, there is a management webinar with Q&A on 23rd at 1pm, register to attend here.
Fevertree Drinks (LON:FEVR) & Revolution Bars (LON:RBG) :
Copied below is an extract from Wetherspoons’ trading update today; bodes well for the drinks industry.
“In the last 15 weeks, there has been a considerable increase in sales of the range of drinks often consumed by younger customers, for example ****tails (+45%), vodka (+17%) and rum (+26%).
In contrast, draught products, more often consumed by older customers, have been under pressure, with traditional ales down by 30% and stout down by 20%, for example.”
Cheers (as they say)
[deleted]
Interesting on £JWD, means older drinkers are not going out so much, 30% drop on ales sales is huge, the only good thing is the profit margin on spirits is far higher. I don’t think bodes well for pubs and breweries but not unexpected.
Have we really come to the point where we can’t even print the word COCKTAILS in full?
Have we really come to the point where we can’t even print the word COCKTAILS in full?
How about Scunthorpe?
Have we really come to the point where we can’t even print the word COCKTAILS in full?
Perhaps it depends on the type of cocktail?
Sex on TheBeach cocktails
Pornstar Martini COCKTAILS
Scunthorpe Cocktails
Blue Balls Cocktails
Edit - it sems to be fine for me whatever the variety - perhaps ihalliwell is being targetted by the censors ?
Hi ihalliwell
Looks like others agree with you Revolution Bars (LON:RBG) opened positively this morning. Cheers.
Looks like this is particularly good for the next Revolution Bars (LON:RBG) trading update, which I think will be throwing off prodigious amounts of cash over the next few quarters. Certainly my experience is that younger people are out all the time at the moment and anywhere "buzzy" is jam packed. The Weatherspoon notes on the cocktail market certainly chimes with that. Revolution Bars (LON:RBG) just look like the wrong price to me, I expect profit upgrades but I guess most probably post Xmas period as management will inevitably be highly conservative until then.
It wasn't just the product mix that chimes well - the J D Wetherspoon (LON:JDW) update seems to say:
younger consumers are going out, older consumers aren't - great for Revolution Bars (LON:RBG)
pubs with music trading better than those who don't have - ok for Revolution Bars (LON:RBG)
trade positive in center of larger cities and towns, poor in suburbs - great for Revolution Bars (LON:RBG)
breakfasts and coffee down due to WFH - no effect on Revolution Bars (LON:RBG)
Also says any stocking issues have been manageable with replacement products - if this is true for J D Wetherspoon (LON:JDW) which has a wide range and customers who know their alcohol, it must be doubly true for Revolution Bars (LON:RBG) - do their customers really care which rum is used in their cocktails?
Most surprisingly, says staffing issues aren't a major problem. This doesn't match with either Tim Martin's recent complaining to government on the issue or my experience trying to recruit front of house staff over past few months - might just be a reflection on the quality of staff required in a typical 'spoons.
£RGB are due with preliminary results and an update on 16th Nov (next Tuesday) - briefly considered a trade this morning but with a 10% bump today it's too small and illiquid for a short term play I think - might regret it.
Morning all, £HFD - Halfords - profits above expectations, and supply chain issues seem to be going away. I bought in at the wrong time, and hold a loss, but this morning's update seems positive overall.
Tracsis (LON:TRCS) had its final results, worth have a look at it. They had a good run this year, more growth coming?
Renold (LON:RNO) - Interims look good - revenue, profit and EPS up and debt down. Pension costs are 'stable' and 'sustainable'
Thoughts on Vesuvius (LSE:VSVS) please. Unicorn Bay at
https://unicornbay.com/t/VSVS....
are positive.Looks a good long term investment, but am I missing anything?
Last discussed here in 2017.
No news and your link is for Vistry.
Corrected, thanks