Small Cap Value Report (Weds 12 May 2021) - REDD, VTU, RBG, JOUL, MACF, MER

Good morning! It's Paul & Jack here with the SCVR for Wednesday.
Timing - we're hoping to be finished by 1pm official finish time today, and I'll be catching up on a couple of overdue items from yesterday (e.g. Revolution Bars (LON:RBG) (I hold)).
Update at 11:48 - let's extend that to 14:30, as I've got 3 more companies to cover.
Update at 15:23 - punctual as ever (!!) - today's report is now finished.
ZANE Zoom
The team at ZANE (my favourite charity) have been absolutely thrilled with the £22,766 we've raised, with more in the pipeline from Mello Monday's charity pledge fundraising too. ZANE has doubled up our donations, with a release from its reserves, so that's over £45k in total - remarkable! Thankyou to everyone who contributed, large and small, all are greatly appreciated.
Anyway, the team at ZANE thought that, with so much interest being shown in the charity, that they would set up a Zoom for us, to meet some of the team, including case workers from Zimbabwe, who want to tell us about the current situation there, and the type of work they do. This should be a fascinating insight into ZANE's work, and I urge you to try to find the time to join the Zoom, even if only for a little while. Every time I hear about how dreadful life is in Zimbabwe, it makes me seriously thankful for my life here in the UK, and I stop moaning about my own trivial problems (for a day or two anyway!)
It is this Friday, 14 May, at 2pm
There are security issues operating in a difficult country, so I can't put up a public link.
ZANE has asked me to collate the email addresses of people who would like to attend, which I will vet & then pass on to ZANE, who will invite people individually. The audience will I suppose be in listen-only mode, so there's nothing required from us. Although I do think it's polite to put your camera on when Zooming, as it helps the speakers visualise who they're talking to, and get some body language feedback, or just a reassuring smile, but that's a personal choice.
To book your place on the Zoom (all readers here are very welcome!) just email me at: ZaneMeeting@gmail.com
Agenda
Paul:
Redde Northgate (LON:REDD) (I hold) - ahead of expectations update. Still looks good value, despite having doubled in price in the last 6 months. I can't see any reason to bank profits, when the PER is only 12, and divi yield close to 5%.
Vertu Motors (LON:VTU) (I hold) - strong results & very good outlook. This share looks remarkable cheap to me, and is more than 100% asset backed with NTAV. Very appealing for value investors, in my view.
Revolution Bars (LON:RBG) (I hold) - trading update from yesterday. Trading very strongly in first stage of re-opening, so expect a bonanza once its 66 bars can fully open. Liquidity sounds OK. I've decided to bank some of my profits, as it hit the lower range of my 40-50p target price. This has been a painful journey, but it's actually worked out alright in the end, for those of us who averaged down heavily at the lows.
Joules (LON:JOUL) (I hold) - positive trading update, ahead of expectations. More importantly, broker forecasts have been substantially raised for this future years, which makes the valuation a lot more palatable. This is one of my coffee can holdings (hold forever).
Macfarlane (LON:MACF) (I hold) - a slightly vague update, but it sounds OK. Mentions raw materials price increases. Worth a look for value investors.
Jack:
Mears (LON:MER) - disposals are making for a more focused company and the shares could prove in time to be cheap, but there are execution and financial risks to consider.
.
Paul’s Section
Redde Northgate (LON:REDD)
(I hold)
365p - mkt cap £898m
Looking back through our archive, readers nagged me to look at REDD in Oct 2020, and after crunching the numbers, I found an exceptionally good value share, rated at 6.5 times earnings, and with a prospective yield of over 7%. At just 178p this share was stupidly cheap at the time, a completely irrational market price, given that it had just put out an in line with expectations update. Thankfully I took a medium-sized portfolio position, and it’s done very well, doubling in price by now. Although lots of shares have doubled in that timeframe too, so there’s also an element of right place, right time. We’re not necessarily great stock-pickers, since lots of speculative junk has also doubled (or more) in price, so you could have picked anything at random and done well in the last 6 months.
Although the market cap has now risen well above my usual top end, I’ll be scrutinising today’s update anyway (as I still hold), and it’s a shame to stop covering our winners here.
Redde Northgate plc (LSE:REDD), the leading integrated mobility solutions platform providing services across the vehicle lifecycle, today announces a pre-close trading update for the year ended 30 April 2021, ahead of its results for the year scheduled for 7 July 2021.
This looks good -
Stronger than expected performance with PBT ahead of consensus; entering new financial year in a position of strength
The announcement is peppered with TLAs (three letter abbreviations) with no key as to what they mean. It’s so annoying when companies do this. Companies & advisers need to remember that investors look at hundreds of companies, in various sectors, and don’t necessarily know what your abbreviations mean, so it wastes time having to work them out.
In this case, I think -
LCV probably means light commercial vehicles, and
VOH probably means vehicles on hire. But does that mean just for Northgate (which leases white vans), or including Redde (hire cars for accident victims)?
Anyway, I can forgive them for a poorly worded RNS, because the outcome is positive -
As a consequence of the stronger than expected performance in H2, the Board now expects underlying PBT for FY2021 to be moderately above the top end of the current range of analyst estimates 1 and not less than £92m.
Footnote: 1 Current range of analyst estimates for FY2021 underlying PBT £83.3m to £88.0m
Very useful to include this footnote, thanks for that.
It’s a nice beat, current consensus is 27.4p, so we might be looking at c.30p for FY 04/2021. At 365p per share, that’s a PER of about 12 - seems good value in a market that is generally attributing higher PERs than 12 for many companies.
Bear in mind that the Redde part of the business has seen volumes suppressed by lockdowns, so earnings should rise in future as road traffic volumes increase. Forecast is for 33.78p in the new financial year, FY 04/2022.
The forecast yield is c.4.7% - very attractive.
My opinion - although the share has doubled in price, I don’t see any reason to sell - it’s still cheap, and rewards holders by paying generous divis. There’s more detail in today’s update, which all sounds fine - e.g. integration going well, cost savings being achieved as planned from integrating the 2 businesses, liquidity is fine, etc.
Overall then, this gets a thumbs up from me, it’s still an attractive value share in my view.
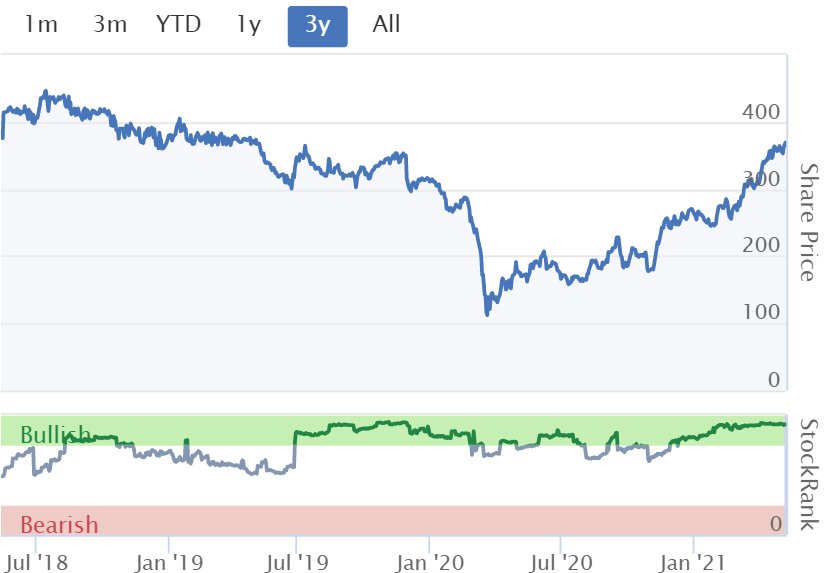
Note the high StockRank, giving me additional reassurance.
.
.
Vertu Motors (LON:VTU)
(I hold)
45.2p (flat, at 08:53) - mkt cap £166m
Vertu Motors plc, the automotive retailer with a network of 149 sales and aftersales outlets across the UK, announces its final results for the year ended 28 February 2021 ("Year").
"Leadership in online retailing contributes to above expectation results for FY21 and a strong start to FY22"
The CEO commentary sounds very upbeat -
"These results, which are ahead of expectations, are outstanding in the Covid interrupted circumstances. I am proud of the entire Vertu team for their adaptability and effort to deliver these remarkable results.
The Group has significantly evolved during the year, with accelerated delivery of its strategy in achieving enhanced online sales capability via its inhouse developed Click2Drive technology platform, reduced cost base due to productivity gains and significantly grown the number of sales outlets.
We have started the new financial year very strongly, have generated record levels of cash and have a very strong balance sheet. We have now re-instated guidance. Brexit uncertainty is now behind us, and we are exceedingly well placed to benefit from the changes and opportunities which are ahead of us."
There’s a short video presentation on the company’s website which I’ve just watched, so save time ploughing through all the numbers. Key points -
- Strong asset backing of 50.2p NTAV (below share price of 45p), so financially strong. This is something I’ve repeatedly mentioned here when reviewing previous figures from VTU. You’re effectively getting a hybrid car dealer/ property company, with loads of freeholds. Therefore it’s copper-bottomed, and under-performing sites can be sold off, and turned into supermarkets, etc.
- Adj EPS of 4.44p (PER of just over 10) - it’s important to note that taxpayer support of £27.8m from the JRS (furlough) and £8.7m in business rates relief, accounted for more than the entire year’s profits. The company says it will not be repaying it, because it covered substantial losses, during enforced shutdown, particularly in the first lockdown. That’s a questionable decision.
- Emphasis on online strategy, including having its own IT developers, with bespoke IT platform for doing business online, including when showrooms are shut.
- Pent-up demand - lots of people skipped a service last year, expected to be a backlog of demand to benefit this year.
- Supply problems - particularly due to semiconductor shortages (lots of companies mentioning this at the moment). However, supply problems benefit Vertu, as margins increase when supply is tight, and fewer new cars means better prices for secondhand cars.
Outlook - seems very strong, actually I’m surprised the share price hasn’t risen today yet -
OUTLOOK HIGHLIGHTS
· Strong start to new financial year with trading profits at a record level in the two months to April 2021. Adjusted profit before tax in the two months of £19.2m compared to £14.8m in the same months in 2019
· The Board expect the Group will deliver an adjusted profit before tax for the year ending 28 February 2022 in the range of £24.0m to £28.0m
· The Board is confident that, dependent on the financial performance of the Group, dividends can recommence in January 2022
Broker updates - many thanks to Liberum and Zeus, who both update today with big increases in the forecast profits for FY 02/2022 - e.g. Liberum upgrades to 5.7p EPS, so at 45.2p that’s a current year PER of only 7.9 - seems extremely cheap to me, given that the share is also fully asset backed.
My opinion - I’ve seen enough to believe that this share looks too cheap. Car dealers don’t seem to attract high valuations, but even so, the combination of very low valuation, strong asset backing, and improving fundamentals, looks very attractive to me. Especially as Vertu is also embracing online transactions.
I don’t believe that online startups like Cazoo have any competitive advantage at all, yet apparently are going for sky-high valuations. Vertu seems a much better setup, as it’s established, doesn’t need to spend a fortune on advertising, and can justify physical sites with lucrative after-sales revenue.
Lovely high StockRank too.

.
Revolution Bars (LON:RBG)
(I hold)
40.5p - mkt cap £50.6m
This update is from yesterday, when I had an unplanned outage, so apologies for this being a little late. In a nutshell though, it’s working out as I hoped - the company did indeed have enough liquidity to survive until re-opening, and the signs are now very positive about a bonanza in trading beginning, from pent-up demand. None of us know how long this bonanza is likely to last, but personally my hunch is that it has some legs.
Imagine how young people must feel. If you’re in RBG’s target customer base, aged say 21, then lockdowns have destroyed your social life for a third of your adult life! Therefore it’s a seriously big deal. Whereas shopping has not been interrupted as such, because there was a perfectly good alternative - buying online.
Also, I reckon that for the target male customers (about 40% of total) at RBG, going clubbing is a lot more enjoyable than going shopping!
Anyway, this is the latest from RBG, summarised by me into bullet points -
- 25 bars have re-opened (out of 66 total), with outside space - trading “extremely strongly”
- Only 15% capacity available (outside areas only), shorter hours, and cold weather - despite this, these sites delivered 48% of pre-covid 2019 equivalent sales - very good indeed
- Liquidity looks fine -
- Net bank debt at 10 May 2021 stood at £28.5m, with total available facilities of £40.2m.
Outlook - strong
Following the customer reaction we have seen over the last four weeks, the Board is confident that significant further pent up demand exists and therefore further strong trading is anticipated in the months to come as restrictions fall away and we fully open up the estate.
Ahead of expectations -
Taking the above into account, together with continued tight cost control and better than anticipated support from third parties, we now expect that our full year performance for the year ending 30 June 2021 will be ahead of previous management expectations…
... huge pent up demand and a rapid recovery across the nation in the bars with outside space that we have been able to open to date.
Re-opening - bars will still be restricted to 50% of usual capacity, from 17 May 2021.
Mid-June - expected that all restrictions will be lifted.
My opinion - management has done a really good job in restructuring the business during the pandemic. All problem sites were either disposed of in the CVA, or had consensual lease restructurings to make them financially viable.
I think the newsflow from RBG is likely to be outstandingly good for the rest of 2021, assuming no further resurgence in covid.
Some time ago, I indicated here that this was not a share I want to hold forever, and that my target exit price was 40-50p, at which point I’m happy to pass the baton to someone else, playing for the continuing momentum.
Accordingly, I’ve halved my position size now, and am probably looking to exit completely if it does reach 50p-ish later this year.
Remember that there are now 125m shares in issue, due to the emergency fundraise last year. Prior to that, there were 50m shares in issue. That limits the upside on this share, so people looking at the chart and imagining it could get back to 150p+ have perhaps not taken the increased share count into account?
By instinct I’m a value/GARP (growth at reasonable price) investor, so it’s entirely possibly I might end up kicking myself for selling out too soon, but that’s a risk I’m happy to take.
It’s worked out far better than many people thought likely, and people who had the balls to buy more in the 20p placing & the plunge to c.10p at the lows, have been nicely rewarded. As I mentioned at the time, insolvency didn't seem likely, because it was fairly easy to calculate the weekly cash burn, which meant there was enough headroom under the extended bank facilities.
Now that survival seems assured, a big bounce in share price looks logical, which we’ve already had.
Will it need to do another placing? Possibly, but I think the cash generation for the rest of 2021 could be astoundingly good, and of course there won’t be any corporation tax to pay for a while, so I reckon it could organically reduce net debt strongly, which hopefully might prevent any further dilution. The other point to consider, is that cashflow improves once sites open - because cash comes in instantly from customers, but bills are paid monthly in arrears.
.

.
Joules (LON:JOUL)
(I hold)
269p - mkt cap £300m
Again, this was left over from yesterday, so apologies for my tardiness.
Joules, the premium British lifestyle brand, today provides a business and trading update for the 11 months to 2 May 2021 (the "Period"). This follows the UK Government's announcement yesterday confirming the timetable for the easing of restrictions across the hospitality and leisure sectors over the coming weeks.
This looks like an unscheduled trading update, issued because the company is trading ahead of expectations - the best type of trading updates!
Summary -
Positive performance across retail channels resulting in anticipated FY21 revenue and PBT ahead of expectations
* As at 10 May 2021, FY21 company compiled analyst consensus was for: Revenue £187 million and PBT pre- exceptional items £4.1 million
Reasons given -
- continued strong sales on the Group's digital platform
- encouraging initial contribution from the acquisition of Garden Trading
- performance of the Group's stores since their reopening from mid-April.
Broker upgrades - thanks to a friend for flagging up an update from Liberum, which you can see on Research Tree. What’s notable is that analyst Wayne Brown has put through some hefty increases for future years. We know how cautious analysts are generally being at the moment, due to macro uncertainty, so it’s worth taking note when a credible analyst upgrades numbers substantially.
We’re now looking at 4.3p for the current year FY 05/2021 - a PER of a rather scary 63 times! This is a red herring in my opinion, as it’s the future (post pandemic, we hope) that matters more. In any case, JOUL has proven itself highly resilient, because it’s now an eCommerce-led business, with a digital marketplace for complementary brands. Digital marketplaces are the way of the future, in my view, hence why I like Joules so much.
The current year FY 05/2022 goes up to 12.5p forecast, then 18.0p for FY 05/2023 (an increase of 67% on previous forecast). If achieved (or beaten?!) the 18.0p EPS forecast brings the PER down to only 14.9 - now the valuation makes sense.
My opinion - I really like this share, it’s a coffee can holding for me - i.e. I’m largely ignoring short term valuation & price movements, to focus on the bigger picture long term.
JOUL is difficult to value, because nobody knows if forecasts 2 years out are likely to be missed, hit, or beaten. So there’s clearly risk in adopting that valuation approach.
The business model strikes me as really excellent - selling mainly online (showing rapid growth), selling complementary brands alongside "Friends of Joules", buying the best performing brands after seeing exactly how they perform on the FoJ marketplace, plus a relatively modest store portfolio. The branding of Joules is incredibly strong, and very distinctive, with customers prepared to pay high prices. There’s a lot to like there. The product's great too, I'm very happy with my research-driven purchases - including an exterior mirror which I managed to smash within 5 minutes of unpacking it (my 4th floor terrace is rather windy). Hopefully not the harbinger of 7 years bad luck!
I’m more comfortable now that forecasts have been greatly increased, which reinforces that my research is probably correct, and that the valuation is actually looking quite sensible, and not as stretched as it looked on the old, super-cautious forecasts.
As my investing education continues, I’m gradually learning that sometimes you have to look through the figures, and see the bigger picture.
The StockRank could rise, once the greatly increased forecasts flow through, which should improve the momentum and value scores.
.

.
Macfarlane (LON:MACF)
(I hold)
121p (up 6% today, at 15:02) - mkt cap £191m
This is a packaging products company, with a calender year end.
Yesterday, it said-
"Macfarlane Group has made a positive start to 2021, with sales in the first quarter 15% ahead of the same period in 2020. Group profit for the year to date is also well ahead of that achieved in 2020.
Two recent acquisitions are going well
Net debt has increased due to acquisitions, but is still modest at £6.0m, hence bags of room on £30m bank facility
Outlook -
Covid-19, supply shortages and raw material price increases will continue to have an impact on the markets we serve for the remainder of 2021. However, we have consistently demonstrated our ability to address such challenges and effectively support our customers. We are therefore confident that the resilience of our business model, together with the skill and commitment of our people, will ensure 2021 will be another year of good progress for Macfarlane Group."
I wonder if that means price increases can be passed on to customers?
Lots of companies are reporting raw materials price increases at the moment, so the risk of inflation does seem to be a genuine risk.
My opinion - this is a decent business, and it’s actually cheaper than it looks. Why? Because very conservative accounting means it doesn’t adjust out amortisation of acquired goodwill.
Supplying packaging materials to eCommerce businesses looks a good space to operate in. Other markets should recover over time.
Overall I think it’s quite good, and worth considering for value investors. Bolt on acquisitions seem to be well executed, at reasonable prices.
Jack’s section
Mears Group (LON:MER)
Share price: 193p (+3.76%)
Shares in issue: 110,836,888
Market cap: £213.9m
Mears (LON:MER) is a housing and care provider to both the public and private sector. With its focus on local communities and care to people, it hopes to ‘tackle the deep rooted challenges to the NHS and Social Care’.
Sometimes the companies you want to do well aren’t necessarily the strongest investment cases. And on that note, Mears Group has poor trailing twelve month (TTM) return on capital and operating profit scores.

These have been stronger in the past but the trend over the past two years has been poor and the group has struggled to grow profitably over time despite decent revenue expansion.

But the company is changing shape.
Its revamped strategy revolves around transitioning to a ‘focussed, low capital intensity, housing services provider, specialising in the affordable sector’ and this transition is now largely complete following the disposals of Terraquest and Domiciliary Care businesses for up to £70.0m and £7.5m respectively.
Highlights:
- Revenue -9% to £805.5m on a continuing basis; Maintenance revenues -19% to £536.9m (Covid disrupted), Management-led revenues +40% (due in part to full year impact of the Asylum Accommodation and Support Contract ('AASC'), mobilised in September 2019),
- H1 adjusted loss before tax of £8.2m; H2 profit before tax of £4.8m,
- FY adjusted LBT on continuing items of £3.4m (FY19: £32.4m profit); statutory LBT of £15.2m (FY19: profit £20.3m),
- ‘Significant transformation in indebtedness driven by disposals’ - net cash of £56.9m at year end; average daily net debt for FY20 of £97.3m (FY19: £114.4m) and now more like average daily net debt of c£65m.
The group has a pension fund and £229m of capital lease obligations too. It has also struggled to remain consistently cash generative. So even though progress is being made, this looks like a high risk stock.
I like the reporting of average daily net debt (more companies should do this in my opinion, in order to prevent window dressing).
It expects an H2 weighting of results in the upcoming year due to lockdowns easing.
FY21 guidance reinstated:
- Revenue of £770m-£820m
- Normalised PBT of £21.3m-£25.5m
- 100% cash conversion targeted
- Capex at 1.25% of revenue
- Targeting average net debt reduction and resumption of dividends ‘as soon as prudent’
Conclusion
Following the disposal of the Domiciliary Care and Planning Solution activities, Mears looks like a smaller and simpler business with a clearer strategic focus on becoming a leading provider of housing solutions.
FY21 guidance suggests the group is targeting around 15-20p of earnings per share depending on tax rate. With today’s share price, that makes for a forecast PE ratio of around 9.7-13x.
And the group does generate a lot of revenue - £831m of annualised revenue from a £206m market cap company. When you get that sort of profile, small percentage changes in revenue growth and cost base reduction can quickly translate into a jump in earnings per share.
Share dilution has been minimal, so shareholders would hopefully capture quite a lot of that upside. The disposals could be an important step on the path to recovery but it’s early days yet.
There’s a path forward for Mears here and you can argue that the shares are cheap. But it is not executing this turnaround from a position of financial strength, and it’s a complicated situation with a number of important variables at play.
You’ll need a high risk tolerance to consider it and further due diligence is required. All things considered there are probably better, simpler opportunities out there.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

72 comments
Macfarlane (LON:MACF) Thanks for the update. Actually hard to find much information. I brought at 80p so its a share that is doing well for me
Hi MrBeak,
Lot's of information on Macfarlane (LON:MACF) here:
https://www.stockopedia.com/content/macfarlane-the-long-story-451513/
I'm glad to hear you have made money on them. I think there is a way to go yet, however, and have added 20% to my shareholding since the AGM trading statement. I'll post more on this at the weekend.
Interesting announcement from On The Beach (LON:OTB) today. They've decided not to sell any holidays starting before 31st August at this time, until there is more "clarity".
They took this decision based on:
Not a good read to other Europe travel exposed companies. But really strong signal for staycation, local tourism companies.
I also note that TUI reported today that their "order book" for summer has actually decreased from Feb! Many people opting to push to autumn or next summer. Summer order book 69% down from same time 2019. Not sure if UK only or UK+DE or DE only.
Just wanted to add my thanks for the excellent quality coverage you guys provide.
There's no way I would have looked into Redde Northgate (LON:REDD) if it weren't for both the quant approach of the site and forensic deep dives in your write ups. There is far too much spivvy ramping out there (actually puts me off some stocks that might be OK). In contrast, the approach here very measured and goes way beyond what I could do myself.
I really appreciate it.
Sorry you have had such a painful time with Revolution Bars (LON:RBG) Paul, but on behalf of those of us like me who first bought in April last year when you were suggesting it might be a 5 bagger (if things went as planned and it didn't go bust), a big thank you. Sadly I only topped up at 16p rather than 10p and plenty at the Rights Issue. Also thanks for the useful reminder about dilution this morning. I noticed the unusually high volume of trading this morning - presumably quite a lot of those were yours. Cheers and thanks again - and also for Vertu "tip" last year!
I hold Vertu Motors (LON:VTU) but I do have doubts about how much the freehold of auto retailers is really worth. An example from the VTU figures is that they paid £19.3m to buy a number of dealerships with a freehold value of £16m and annual revenue in 2019 of £305m from an Inchcape subsidiary. Just seems strange that a company would sell £305m in revenue for an effective price of £3.3m. OK, it made a loss of £6m in 2019, but had they really given up all hope of turning it around.
Here are my SCVR heat maps for today (prices as at ~11:30am).
I share these heatmaps with the intention of giving a visual indication of what is going on in the SCVR world: who’s reporting (and it's impact on the share price); and what’s moving more than 'normal'. There are no associated recommendations, implied or otherwise, just information. How, or indeed if, you choose to use that information is up to you. Please feel free to ignore them if you don't find them useful.
Please read my heat map thread for a great deal of explanation of how the heat maps are formed and how I use them to guide me with my research, and for a full key to the contents.
I very much welcome feedback so if you do have any feedback, not already covered in the heat map thread, it would be very helpful if you could post your comment in the heat map thread rather than the SCVR thread. The more specific and constructive the feed back is, the more that likely it is that I will be able to act upon it. Thank you all for the feedback so far.
Small / Micro Caps reporting today:
Big movers today in the SCVR world (moving more than a 20d EMA of the ATR against either yesterdays close, or today's open):
Warm regards, stay safe, and best of luck!
greensiax
Re Redde Northgate (LON:REDD)
I too dislike Three Letter Abbreviations, but WTF is an 'integrated mobility solutions platform'? :-)
Gostevie
I think it was Paul who deciphered this to mean "Van Rental Company"!
Thanks for the write ups this morning Paul & Jack.
Vertu Motors is one i picked up when i read about it in the Feb SCVR and has become one of my favorite shares due to its freehold ownership.
Re the non-repayment of taxpayer support - i have no problems with this in this case. They've confirmed dividends wont be paid to shareholders due to receiving this support and this is a company which has had its normal course of business heavily impeded (justifying their use of GVT schemes in my view). I'm actually impressed with their results and ability to utilise its online capacity so well. I also have an old school friend who works at one of the dealerships who has posted on Facebook about how busy hes been at work since coming off furlough
However, i don't think this share is going to get carried away with itself. I think it'll be a slow climb and will be undervalued for some time, but a solid long term hold for me. Happily averaged up this morning... only 2% rise? bargain!
Anybody have an opposing view on this share? i like to write these down so my confirmation bias doesn't get the better of me.
RE: Vertu Motors (LON:VTU)
Re the non-repayment of taxpayer support - i have no problems with this in this case. They've confirmed dividends wont be paid to shareholders due to receiving this support and this is a company which has had its normal course of business heavily impeded (justifying their use of GVT schemes in my view).
They were justified in using the schemes and in not repaying the funds, as they met the legitimate purpose. However, I really don't think companies should be accepting government funding on one hand and then paying them out to executives on the other.
"In light of the performance and the significant progress made by the Group during the year, the Remuneration Committee have elected to award one-off bonuses to the executives. These bonuses will be paid 50% in cash and 50% in shares in the Company, with the shares required to be held for three years from the date of issue."
Entirely reasonable to award some shares with a lock-in period if the performance merits it, but paying out cash seems wrong. To be fair - especially compared what's happening at companies like Foxtons (LON:FOXT) - it's not life changing amounts, but it feels inappropriate.
timarr
Vertu Motors (LON:VTU) interests me. Just wandering what the long term implications of electric vehicles are on servicing revenue.
Hi Paul
Regarding Redde Northgate, I am having a problem with buying this share. The problem is I can't reconcile buying this share with such a large nett debt of 531m and an Operating Profit of only 26.7m., with my calculation, that means it will that nearly 20 years to pay the Debt back.
Am I doing the calculation correctly? or am I missing something here? I would appreciate your comment if you have enough time.
Hello Terry. Yes - I share the same concerns. The nett debt figure of 531m doesn't tally with the write up in today's SCVR regarding REDD. Maybe we're missing something but it is precisely that amount of debt that made me shy away from buying into this stock.
Hi Terry,
Redde Northgate (LON:REDD) - forget the debt, it's not important. Why? Because it's asset funding debt (for buying a huge fleet of vehicles) and the value of the vehicles greatly exceeds the debt used to fund them - I've checked all this out in detail, see the archive for my posts on REDD.
Also, REDD has stated that in future, it will be looking to bulk lease vehicles (instead of buying them). That means the debt should disappear, or become non-recourse lease type of debt, which is not subject to any covenants, and cannot be withdrawn.
So in a nutshell, don't worry about it! But obviously you might want to confirm this by DYOR (although I've already done the work, and it's all fine).
Regards, Paul.
Thanks Paul you are a star. I will now go ahead and purchase the said share.
Rebirth do you agree?
I agree. Thanks Paul for clarifying this for us.
White vans are a currency in themselves
Some say they are better than Bitcoin!
They said they would start bulk leasing vehicles, yet they announced today the acquisition of a rental fleet in Scotland for £25m. 2000 vehicles so £1,250 each, give or take, sounds like an excellent deal in fairness. (I hold)
Hi barnakles,
Not such a great deal for Redde Northgate (LON:REDD) (I hold) bulk purchase of 2,000 vehicles. You might want to check on the floor, because I think you'll find you dropped a decimal point ;-)
It's actually £12,500 per vehicle, not £1,250!
Regards, Paul.
Ouch! Thanks for the clarification Paul, that does put a different shade on it alright. They mention the deal will "bring significant benefits from ongoing customer relationships" - are they suggesting the customers of the seller will now use £redd? I guess it's a possibility if the seller is getting out of van rentals. Hopefully, sounds pricey for such a large order otherwise, although as other commenters have noted, very high residual values at the moment.
Redde Northgate (LON:REDD) Barnakles - £25m for 2,000 vehicles is more like £12,500 per vehicle.
Paul ... a few things I don't think you are factoring in;
1. residuals in the used van market place are sky high at the moment, so Redd would have benefited from this in it's latest accounts.
2. When they switch to a contract hire format, they won't benefit from inflated residuals, the finance company taking the risk will. Although they are protected from any losses, the liklihood of this happening is small in this economy.
3. Why contract hire when money is so cheap; the finance company will be making a healthy margin that Redd would normally have benefited from.
Any thoughts?
Redde Northgate (LON:REDD)
Those are great comments 55555 - i was thinking along the same lines. I suspect at the moment covid has created a mismatch between suply and demand if new vans are not being built or imported at the rate they were previously - i would suspect as ever this supply shortage won't last too long and as ever it may be that as everyone ramps up production things could easily go the other way at that time could leasing benefit them perhaps?- its often the case with certain items that there can be surplus /defecit situation more than there is an even keel. I own redd and was thinking could this be the peak of good news? but the good numbers today and forecasts for 2022 sort of give me confidence that i have no reason not to believe that the people who do know the situation inside out are confident. No guarantees as often companies may factor in this year will be like last year - i also do take confidence from the volume of business they do - there is enough sales being done that £1 billion of revenue income should be enough to generate some decent profits come what may - looking at the old pre merger numbers on stocky the net profit generated seemed very resiliant over multiple years which is a good sign in that regard. So on the run your winners basis aligned with the modest valuation i am staying put - thats bad news for holders as when i move on the good news from the company isn't far behind(i sold down some sdg on monday).
I even managed to accidentally sell my somero shares last week after the good trading update as i either hadn't fully cancelled my limit sell order (was on my tablet and in a hurry to go to work) or my cancelled subject to confirmation limit order was sold before it was cancelled by my broker - be careful with those limit orders peeps ! - i was gonna sell the prior day but the trading update was enough to make me have an about turn.
Hi ... thanks for your response. I still think Redd will miss an income stream ie. residual value profit, by contract hiring their vehicles. The contract hire companies will always set their residual value with a good degree of safety built in and are known to make healthy profits; profits that Redd would have been making. Most companies use contract hire as it's tax efficient and to access fleet discounts, but for vans it makes little difference and Redde will already have massive buying power. Also isn't one of their directors from BCA auctions, so they will have an easy access too mass disposals to the trade. Anyway, I'm sure they have their reasons ...
Redde Northgate (LON:REDD)
Hi ... thanks for your response. I still think Redd will miss an income stream ie. residual value profit, by contract hiring their vehicles.
I think you could very well be right here , if that is the case lets hope the current market forecasts have factored this fact into the pie - it should be if the amounts are material - perhaps that's where some of the very impressive merger savings have bene eaten up or the other numbers factored in would have been higher. In summary lets hope overall broker forecasts have the bottom line numbers on track in that regard.
What they should have done is rather than contract hire their vehicles they should Finance Lease them. It's the same money from the same source, but Redd would take the residual value risk / profit and would be responsible for selling them. They've made a mistake using contract hire on this occasion :(
Lisa Montague and her team at Sanderson Design (LON:SDG) are certainly proving adept at monetising the company's brands as demonstrated by this morning's announcement of a comprehensive licensing agreement for its Morris & Company brand across south eat Asia. I think that Richard Crow, aka Cockney Rebel is right when he said that Sanderson Design (LON:SDG) is becoming a brand orientated company rather that being regarded as a 'decorating' concern and will hopefully be re-rated accordingly.
I hold Sanderson Design (LON:SDG) and £REDD so a good morning so far.
Gromley if you still read the SCVR, which I believe you can, I hope that you also continue to hold £SDG.
All the best
Hi jonno,
Indeed, we like Sanderson Design (LON:SDG) (I hold) here at the SCVR too.
I've mentioned many times here, that the portfolio of classic designs, must have considerable value, and licensing deals happen from time to time.
The announcement today sounds good, but contains no financial details. That's a bit annoying, as we have no way of knowing the materiality (haha!) of the deal. I've emailed the PR company to ask for more colour! ;-)
My next thing to check was Research Tree, as brokers might have been told some financial details, but there's nothing available there. Hence I drew a blank, and don't have enough information to do a write-up in today's article.
Regards, Paul.
I've had a reply to my query about the materiality of the Sanderson Design (LON:SDG) licensing deal as follows;
Today's update was issued on RNS Reach, therefore it's a topic that shareholders might find interesting, but is not financially material at this stage.
Licensing deals take time to kick in, because there's a cycle to go through, of coming up with product designs, them being approved, arranging manufacture, then selling, etc.
So it looks like a nice to have thing, rather than something immediately share price enhancing.
Fair point regarding the absence of financial details Paul, but the prelims are next week so we should get an indication then. Hopefully they will be positive and mirror the recent share price movement.
If they can get Carrie to endorse I'm throwing in the farm :)
I note Sanderson Design (LON:SDG) is up today on news of a licensing deal in Japan and East Asia for its William Morris designs.
Can you imagine, I used to sell materials in those designs whilst at my Saturday job in Debenhams in the 1970s. Now own shares in both companies...so it goes.
Well for what it is worth I used to have a Saturday job in Hamleys in the late 60s/early 70s and had the privilege of starting the large model railway that circumnavigated the first floor. Great place to work as a 15 year old, especially at Christmas when it was absolutely manic.
UK SMall Caps being added to the MSCI Global Small Cap Index - https://twitter.com/imueslibro...
VLX, SAGA, ARB, RANK, REACH, TRMR, KAPE etc
Air services logistics provider John Menzies (LON:MNZS) (is it just me or did anyone else think it was a newsagents?) raised £22m in equity via a placing and PrimaryBid offer last night. Paul flagged it (the company and it’s need for a fund raise) in January SCVR.
https://www.stockopedia.com/co...
I looked at the offer but at about 10% of the issued share capital being raised it seems little more than a sticking plaster given the state of the balance sheet. I don’t hold - I think there may be more fundraising to come.
Gus.
For some reason the FD et al has bought shares heavily before and including this raise. I'm following the money.
I tried to subscribe via PrimaryBid and received a message this morning to say "Due to subscription levels, the Company has decided to allocate to existing shareholders only on this occasion".
Quite frustrating as PB's payments processor is rubbish and took me about half an hour to get the order in successfully.
Hi gus 1065, not only do I remember shopping there when they still had the newsagents side, I also remember being told in no uncertain terms that it's pronounced 'Mingis' - hence 'Ming' Campbell for Menzies Campbell. The original Scottish 'y'-consonant corresponded to an Anglo Saxon 'g' character which looked like a Roman 'z' and was mis-written as such in lots of Scottish names. But not relevant to investment...
No not relevant but these snippets are very interesting nevertheless !
My morning smallcap tweet:
RM Secured Direct Lending (LON:RMDL) Chesnara (LON:CSN) Nanoco (LON:NANO) Xeros Technology (LON:XSG) Eden Research (LON:EDEN) React (LON:REAT) Nightcap (LON:NGHT) VR Education Holdings (LON:VRE) Vertu Motors (LON:VTU), TP ICAP (LON:TCAP), Gresham House (LON:GHE), Cenkos Securities (LON:CNKS), FBD Holdings (LON:FBH)
RM Secured Direct Lending (RMDL) Update on refreshed investment focus: "good progress in growing the portfolio in line with its focus on all new lending being allocated to Social & Environmental Infrastructure". Confirms name change to name to RM Social & Environmental Infrastructure Income. [SP=92.37 Cap=107m]
Chesnara (CSN) CEO to retire at year end. He is thanked. [SP=274 Cap=411m]
Nanoco (NANO) in the patent infringement lawsuit against Samsung the court has largely confirmed NANO's case in so far as the meaning of words. Trial set of Oct. [SP=25.9 Cap=79m]
Xeros Technology (XSG) Chinese license partner launches Hydrology brand of commercial washing machines incorporating Xeros' tech. Xeros will receive a mid to high single digit % royalty for machine sales and royalties for XOrbs. [SP=243 Cap=58m]
Eden Research (EDEN) signs exclusive Commercialisation, Supply and Distribution Agreement with Corteva Agriscience for Eden's first seed treatment product after successful evaluations. Covers EU, UK and Serbia. "The agreement with Corteva is a defining moment for Eden and clearly demonstrates the next major step in the development of a new product in the significant seed treatment market, whilst also expanding our product coverage to broad acre crops." [SP=15.14 Cap=58m]. I'm short.
React (REAT) recent acquisition Fidelis Fidelis FY rev £4.87m up 48% and gross profit up 45%. REAT "delighted with the smooth integration of the business". [SP=3.49 Cap=3m]
Nightcap (NGHT) £10m (significantly more than originally indicated in RNS of 4 May) placing at 23p (22% discount) to fund purchase of 9 bars. [SP=28.2 Cap=38m]
VR Education (VRE) China co HTC says VRE's VIVE Sessions will be included in the software bundle of the HTC's new headset. Also HTC partnership with HP to roll out VIVE Sessions on new HP ProBook laptops sold inside China. CEO hails 'fantastic news'. [SP=15.25 Cap=39m]
Vertu Motors (VTU) FY(Feb) LFL rev down 21.6%. Adj pretax £24.6m up 7%, ahead of mkt exp. Guides FY22 adj pretax £24m to £28m. [SP=44.4 Cap=164m]. I hold.
In line: TP ICAP (LON:TCAP) Gresham House (LON:GHE) Cenkos Securities (LON:CNKS) FBD Holdings (LON:FBH)
Vertu Motors (LON:VTU) numbers ahead this morning, seems like they have slashed costs and are set to have a bumper year based upon the first quarter this year. numbers ahead
Agree that the numbers look good for Vertu Motors (LON:VTU) , especially considering the lockdowns they have had to contend with. They mention "Strong start to new financial year with trading profits at a record level in the two months to April 2021. Adjusted profit before tax in the two months of £19.2m" and then guide "adjusted profit before tax for the year ending 28 February 2022 in the range of £24.0m to £28.0m". So if Im reading right they've already done 69-80% of their full year target for 2022 in the first 2 months of the year.
NAV of 50p here too, above the current share price.
I hold and have added to my holding this morning.
I noticed the strange difference between there estimate for the year and the first two months.
Does anyone know if they are just being overly cautious or if there's just some peaks and troughs in this business?
Haven't read in fine detail but just did a scan and ctrl+f on Vertu Motors (LON:VTU)
"Semi-conductor shortages are also likely to limit new vehicle supply in the months ahead as several plant closures and curtailments of production have been announced across the globe. Manufacturers are also having to balance the emission levels of their sales, which may impact production and availability. In contrast, the renewed strength of Sterling against the Euro and Yen makes the UK a more profitable market for Manufacturers to export cars into and this tends to increase supply levels. Overall, the Board believes constrained new vehicle supply is a key uncertainty in the near term which may impact the business."
New vehicle volumes were 33% of FY21 total, and 50% of FY20. So quite a substantial chunk of total sales. So far they're not crystalising the chip shortage risk, as manufacturers themselves haven't confirmed CY Q3 and Q4 supply crunch. A key risk to keep an eye on for any holders of Vertu.
Looking for a turnaround story? Then come along to the Dialight (LON:DIA) webinar today at 5pm. The chair and CEO will talk through the recently released results (30/3) and the strategy to improve profitability.
Register: https://us02web.zoom.us/webinar/register/5816170860545/WN_GytV-Z6wRaaVa9wBGEVoPg
Many may have missed the q1 update from Macfarlane (LON:MACF) [I hold] at their AGM yesterday. Oddly, they always delay publication of the AGM statement to the time of the start of the meeting, so miss out on both the 07:00 news flow and the Mr Contrarian summary.
https://www.investegate.co.uk/macfarlane-group-plc--macf-/rns/agm-statement/202105111200012510Y/
Packaging revenues were 10% up on q1 2020 and manufacturing revenues 45% up (the latter substantially boosted by an acquisition). The overall increase was 15% and its should be remembered that the comparative period was largely pre-COVID, This seemingly represents a substantial jump in the underlying rate of growth of the business, with the equivalent q1 2020 statement being only 2% ahead of 2019.
Broker consensus for 2021 revenue (per Stockopedia) is £248m, versus £230m in 2020. That is an increase of just 8%, so broker upgrades now look inevitable. My own forecast was £257.1m, up 12%, so I also expect to improve my projections.
Net debt of just £6m at q1 2021 compares favourably against my existing HY forecast of £14.6m, so it looks like cash flow over the period has been very favourable.
All-in-all, I believe things continue to look very positive for Macfarlane.
Morning Paul & Jack,
Is Redde Northgate (LON:REDD) on your radar today, after their trading update??
Regards,
Paul
Was about to post myself. Although Redde Northgate (LON:REDD) are not strictly in the SVCR league (Mkt Cap £800m+) I know a lot of people are invested/following after Richard Leonon highlighted them at some point last year. Todays update of being slightly ahead of forecast is excellent news and I would hope that with their prime markets opening up again after lockdown this will bode well for the future.
I am very happy holding them, although I did take a small top-slice recently due to them becoming overweight in my PF, but extremely happy to keep hold of the rest.
This is one of the reasons I will always continue to subscribe here. I'd never heard of them until it was posted here back in Oct. Having done my own review I put in a bit and like others have come off with an 108% gain so far and have paid for my subscription for the next 20 years :-)
Whilst I have top sliced some companies like Water Intelligence (LON:WATR) which to me has clearly got toppy I have not done so here as I think it's still got some legs to go yet when they have a full year without lockdown.
The thing I love about this site is that we act as a disjointed team lead by Paul and Jack. That enables us to be really pleased when people make money rather than some of these BBs which involve so much unpleasantness. So well done!!
On Redde Northgate (LON:REDD) : a while back Roland Head published a really helpful article about the merger of Redde and Northgate which I recommend reading for anyone looking to invest here. He had helpfully combined the group's accounts but unfortunately on that page the image showing those calculations isn't working now (for me anyway) but luckily I saved it so I am reposting below. It provides a helpful comparison for today's figures but obviously note the Redde part of the business performance has been suppressed during the FY21 reporting period so it was always likely to be worse than 2019.
I make the revenue today about £1113.97m for FY21 which is good given the COVID impact on Redde but note the PBT figure of £92m compares less favourably with FY17 when a similar revenue was achieved.
As you can see from the table, a key issue with this business is the combined entities were having to run to stand still: increase revenues to get the same profit. It sounds like from today's update that margins are starting to improve again, at least at Northgate, which is a key opportunity for this share and could drive a further re-rating here. However, it does sound like there might be some one-off gains from used vehicle sales boosted by a (temporary?) market price rises which presumably will continue at least partly in FY22.
I am slightly unclear what today's PBT figures mean for EPS but Paul's suggestion of 30p sounds plausible. If anyone spots a broker note then do let me know :)
I hold. Despite my nervousness about flatlining PBT in previous years I think the share is still undervalued and could re-rate if margins improve and Redde activity increases, which it should do with lockdown restrictions easing.
EDIT: Apols I made a few edits to this after initially posting. Bit hungover from lockdown easing so made a couple of mistakes!!
The reducing margins were occurring from a time when the company had different management. New management came in who are much more dynamic with lots of ideas. The new Redde Northgate is only just getting going.
A good page for investors is found on Redde Northgate (LON:REDD) website.
https://reddenorthgate.co.uk/i...
It highlights the analyst consensus in a very clear manner. In spite of a few abbreviations in their RNS, there is some nice clear reporting here.
Redde Northgate (LON:REDD) (no position)
Hi Patrick
"However, it does sound like there might be some one-off gains from used vehicle sales boosted by a (temporary?) market price rises which presumably will continue at least partly in FY22."
I think there is some truth in this.
A few days ago ALD - which I hold and who operate in a similar space to Redde Northgate (LON:REDD) - posted their Q1 update which stated that used car sales had resulted in a unit profit of 439EUR.
https://www.aldautomotive.com/...
Note the huge increase in Q1 2021 Used Sales Income to 38.2m EUR from 3.2m/12.2m EUR last year.
(NB1: note that there was a 9m EUR impairment charge in Q1 2020, hence the 3.2m/12.2EUR I've noted above)
(NB2: For comparison Q1 2019 was 19m EUR)
This was a big surprise as during their Capital Markets Day last year they stated an expected 200EUR unit income on used car sales.
A few more snippets that may be of interest:
a) An illustration on how their business operates and makes money:
b) Link to that Capital Markets Day Presentation:
https://www.aldautomotive.com/...
Cheers
A
Morning chaps wondered if any thoughts on Stock Spirits (LON:STCK): profits and eps up over 90% debt down by 30% and tad over 3% yield any more upside or have they seen the best of it with the likes Rev Bars reopening and the trend moving away from home drinking possibly.
Solid update from Brazilian maritime services and investment company Ocean Wilsons Holdings (LON:OCN) this morning.
https://www.investegate.co.uk/...
A bit off the radar but Stocko metrics are strong and as highlighted in today’s update it is trading at a generous discount to NAV as per this extract:-
“At the close of markets on 30 April 2021, the market value of the Ocean Wilsons holding of Wilson Sons totalled approximately US$375.5 million which is the equivalent of US$10.62 (£7.69) per Ocean Wilsons share. The investment portfolio of US$332.7 million represents US$9.41(£6.81) per Ocean Wilsons share. Adding the market value per share of Wilsons Sons and the investment portfolio results in a net asset value per Ocean Wilsons share of US$20.03 (£14.50) per share. The Ocean Wilsons share price of £9.25 at 30 April 2021 represented an implied discount of 36.2%.”
Bear in mind as at yesterday’s close the share price was 985p so the discount would be about 32% (although likely the NAV will have moved since 30/4 too). Possibly one to put in the “deep value contrarian play” category given the sizeable discount and Latin American/COVID exposure. I hold.
Gus.
I agree, I too hold.
Couldn't agree with you more and I wonder if Paul and Jack have any thoughts on this - it appears to have similarities with SAGA with two distinct businesses and one of them supporting the other .
Anyone invested in Airtel Africa? The trading update today was stellar keeping in mind that the company is valued at 2.90B currently.
-- Constant currency underlying revenue growth was 19.4%, with Q4'21 growth of 21.7%. Growth was recorded across all regions: Nigeria up 21.9%, East Africa up 23.5% and Francophone Africa up 10%; and across key services, with revenues for voice up 11.0%, data up 31.2% and mobile money up 35.5%.
-- Underlying EBITDA was $1,792m, up 18.3% in reported currency, and growing 25.2% in constant currency.
-- Underlying EBITDA margin was 46.1%, adding 181 basis points (210 basis points higher in constant currency). Underlying EBITDA margin for Q4'21 was 47.7%, an increase of 389 basis points in constant currency.
-- Operating profit increased 24.2% to $1,119m in reported currency, and by 32.8% in constant currency.
-- Basic EPS was 9.0 cents, down 12.6%, largely due to prior year exceptional items and a one-off derivative gain. Excluding these, basic restated EPS rose 44.5%. EPS before exceptional items was 8.2 cents.
-- Our customer base grew by 6.9% to 118.2 million, with increased penetration across mobile data (customer base up 14.5%) and mobile money services (customer base up 18.5%). The recent slowdown in customer base growth has been due to new SIM registration regulations in Nigeria.
-- The Board has recommended a final dividend of 2.5 cents per share, making the total dividend for FY21 4.0 cents per share.
yes I hold Air Partner (LON:AIR) and was similarly impressed with today's results and I am kicking myself for not adding more last week. A bit too big for this thread though.
sorry wrong ticker I meant Airtel Africa (LON:AAF)
kevin101 - I suspect you have not yet discovered the edit button, which would have been more helpful on this occasion. It appears with Report/Link/Share at the bottom of your post for an hour after posting.
thanks I did look for it but I was in a hurry so might have missed it
I don't understand the stockopedia dividend %age.
Doesn't AAF pay a 4 cent divi, being around 3.6p? Or am I messing up my currency?
Stocko is showing a forecast dividend of 4.9c for Airtel Africa (LON:AAF) which google converter tells me equals 3.47p giving a yield of 4.45% @ 77.9p so Stocko look correct on this occasion.
Airtel Africa (LON:AAF)
Hi Luckstrike
I'm very bearish on Airtel Africa (LON:AAF) as I've mentioned on the dedicated thread for this company.
It's less to do with the top line growth and more to do with the cash generation.
Free Cash Flow is quoted today as $647m, but there are number of items excluded from this calculation, for example lease liabilities ($208m) and interest costs ($317m).
By my own calculation free cash flow is therefore closer to $160m. Not very much in my opinion vs $4.1b market cap + $3.5m of debt.
Note also that the company is funding itself through:
I do wonder if there will be an inflection point at some stage, but for now the financial metrics just don't appeal.
Cheers
A
EDIT: They're going to need that $160m cash generation to either pay down the $2b of debt or to pay a small dividend - I don't see how they can do both.
Airtel Africa (LON:AAF)
I think its unfair to criticise this company solely due to poor cashflow - although i do understand your reluctance to invest if cashflow doesnt meet your expectations - no better measure of reality than cashflow, there is likely alot of ongoing investment needed - seems like there is also alot of moving parts ref funds needing to go here there and everywhere!
looking at the sum of the parts though cash decreased £67 mill after paying £169 mill dividends spending £270 mill on intangibles - there was also £257 investment in term deposits (is this £257 mill excluded from cash balances presumably it must be?) - so if we add the 270+257+169 i do get back to a number over $600 mill positive that has then been spent on these 3 line items .
What does look interesting here is the likely spin off of the mobile money buisness arm and the valuation of that sub unit as being $2.65 billion - mention of mastercard as minority holder in that unit should give any separate listing a decent kudos value. That listing will likely make any cash concerns go away.
My question would be what % of the business profits vanish if the mobile money arm is spun off ? mobile money is only 10% of revenues - but i don't know if its ultra high margin stuff. If they can keep 75% of profits and bank 75% of $2.65 billion from a listing i suspect that may have a very positive result for shareholders if funds arent squandered on some vanity project.
Airtel Africa (LON:AAF)
Hi rmillaree
"I think its unfair to criticise this company solely due to poor cashflow "
To be honest I think poor cashflow is a very good way to criticise any company.
I'm not against low cash generation if there's evidence of a growing business, but when I look at the income statement I see revenue up by 20% ($3,422m --> $3,908m), but Profit After Tax level with prior year ($408m --> $415m).
There doesn't seem to be much operating leverage here, whereby a revenue increase will lead to increased profits, or even increased cash generation, but perhaps there will be at some point.
Just so it's clear where my numbers are coming from:
1 - Operating Cash Flow before working capital movements = +$1,785m
2 - Interest paid = -$195m
3 - Investing Cash Flow = -$901m
4 - Leases + Interest Costs = -$525m
1 + 2 + 3 + 4 = +$160m excess cash generation.
This $160m needs to be used to pay for dividends and/or debt reduction.
Given that the dividend payment was $169m in 2020, it looks like this is the focus, though I think we need to be wary that Net Debt has increased by just under $200m over the last 12 months too.
I haven't looked into the spin-off you mentioned, so there might be value there. From the very poor cash generation + increased debt though, it's not one for me.
A
Airtel Africa (LON:AAF)
Hello Abtan thanks for providing further detail ref your calcs.
"To be honest I think poor cashflow is a very good way to criticise any company."
I would agree that its great practice to red flag poor cashflow however it doesnt mean that your critisism has any merit , a business can genuinly go through negative working capital needs for extended periods of time and come out the other side with the obvious reversals or stabalisation that one would expect leaving long term cashflow being close to long term profits. If a business is in such a capital intensive phase for genuine reasons that do unwind later or do not repear later is it really fair to criticise per se ? I am not convinced it is - but thats just my opinion and that means didly squat apologies if my comment came across in the wrong manner - i can't argue with the fact you have dug through the detail and come up with some good probing questions - cashflow issues should probably be red flag number one for most investors so i applaud your approach here in digging into the dirty details fo what is a fairly complicated business.
Looking at the numbers quoted by yourself you seem to have included the 270 million paid for "intangible assets" within your calcs that make you arrive at the $160 mill total.
"despite investing $247m of intangible capex to renew licences in two of our largest markets, Nigeria and Uganda, and acquiring additional spectrum across a few of our markets.
Looking at the outlay here it seems more probably than not that this is upfront genince cash outlay for licences that presumably last a decent time into the fuuture - to criticise a company for spashing out for necessary capital investment that has preumably mostly future reward seems unfair.
Note i don't have the same issue with the purchase of property and plant adjusts as they are are matched by the depreciation charge for the year - albeit they seems to have mixed the two together when they say "depreciation and amortisation"
If we add 240 mill to the 160 mill figure you ended up at thats a decent dint in the shortfall between stated profits and cashflow.
Ok onto your second point
There doesn't seem to be much operating leverage here, whereby a revenue increase will lead to increased profits, or even increased cash generation, but perhaps there will be at some point.
I would beg to disagree here - the numbers ref operating profit are as follows.
Operating profit increased 24.2% to $1,119m in reported currency, and by 32.8% in constant currency.
Thats a decent result i would say at the operating level there are 3 main adjustments below that line that bring the final botom line figure much closer to prior year.
prior year had an extra 60 mill of finance income - thats not relevant to lfl trading calcs really
last year had 70 mill non operating income - thats not relevant to lfl trading calcs really
tax due this year is up 90 mill on prior year - taxes are what they are and hogher taxes dont necessarily reflect badly on the cpompanies operating performance this year.
if we look at pre tax profit adding back the non relevant 60+70 mill prior year items thats
profit pre tax this year 697 compared to "rmillaree comparible adjusted profit last year" of 470
On fair comparible trading metrics alone the company appears to grown pre tax profits by 48% that number seems fine and dandy to me if i havent got my maths wonky!!!
In some repects i was expecting for numbers to be much closer to flat with p/e of 10 being present - preumbaly they are a fairly household name where they are and i would ssupect thjeir customer base along would be woth a few bob to one of the big boys ?
Note i haven't really looked into this company in detail before today and i have been very time limited today so i could be slightly wonky in my thinking ref calcs used. If nothing else its certainly a fun set of accounts to dig beneath the hood to try and fathom what the reality is.
I am slightly wary of this type of sector if i am being honest it often seems to be a race to the bottom with costs - i was reasonably lucky to sell out of vodafone about 6-7 years ago at about 220p and i see they are now worth only 140p - ok they may have paid out the difference in dividends along the way but if the big boys struggle to increase profits by above inflation amounts then what hope for the like of Airtel Africa. Especially if everyone if will just be able to have everything sent via starlink in 5 years time. It is still an interesting prospect that may end up on my watch list for fun.
Airtel Africa (LON:AAF)
Hi rmillaree
No offence taken whatsoever, I enjoy a discussion, especially where it's quantitatively thought out.
As you've pointed out there's clearly a lot of moving parts.
A few points and then I think it's best for me to stop:
Intangible asset purchases have gone from $125m to $155m to $270m respectively over the last 3 financial years.
It might never stop growing and I personally would assume it's a regular annual cost, not a one-off.
There are too many adjustments that can be made - something I know from personal experience as I used to be one of the people posting accruals/releases/etc....and mistakes can be made too.
It's why I focus so much more on cash - it's much harder to falsify or make a mistake.
Right, I'll stop there as I need to work on holdings I actually own now :)
Thanks for continuing the discussion and good luck if you do continue to hold.
A