Small Cap Value Report (Weds 13 Jan 2021) - QTX, CHH, CARR, MNZS, ASC, SOS, WEY

Good morning, it's Paul here with the SCVR for Wednesday.
Timings - I have to be finished by c.1pm today. Today's report is now finished.
Agenda -
I wrote the first 3 sections last night, to clear up some of the backlog.
Quartix Holdings (LON:QTX) - Trading statement for 2020
Churchill China (LON:CHH) - Full year (2020) trading update
Carr's (LON:CARR) - Trading update (19 weeks to 9 Jan 2021)
John Menzies (LON:MNZS) - Trading update for 2020
Asos (LON:ASC) - Trading update - I've reviewed this because of read-across for BOO (I hold) update due out tomorrow.
Sosandar (LON:SOS) - Q3 (Oct-Dec 2020) trading update
Wey Education (LON:WEY) - Trading update for first 4 months (Sept-Dec 2020) of FY 08/2021
.
Quartix Holdings (LON:QTX)
403p - mkt cap £193m
Quartix Holdings plc, a leading supplier of subscription-based vehicle tracking systems, software and services, is pleased to provide an update on trading for the year ended 31 December 2020 (the "Period").
The Board is pleased to report that it expects revenue, profit and free cash flow to be in line with current market forecasts1
[1] The Board believes that consensus market expectations for 2020, prior to this announcement, were as follows: revenue: £25.9m; adjusted EBITDA £7.9m; free cash flow: £5.3m.
Actual results (pre audit) are very similar, at £0.1m below expectations for revenue & adj EBITDA, close enough to be a rounding error, so that’s fine.
Many thanks for the footnote, providing us with market expectations figures, but it would have been useful to also provide the EPS result in this RNS.
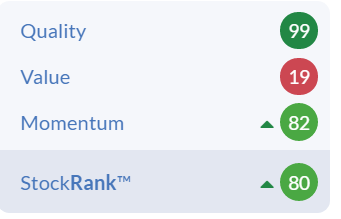
I’ve got a consensus forecast of 12.3p EPS for 2020, whereas Finncap’s latest note says 13.1p adj EPS for 2020. Using the latter, that gives a PER of 30.8 times FY 12/2020 earnings - quite pricey, given the lack of profit growth in recent years - this share is on a growth company rating, but isn’t really growing overall (decline in insurance business offsetting growth in fleet business) as you can see from the graphs below.
.

.
Quartix repaid the furlough monies to the Govt, and is up-to-date with VAT. Good stuff, that’s the right thing to do.
Customer churn (“attrition rate”) seems modest at 12.2%
Growth improved in H2
Insurance segment declining quite rapidly: 15% of total 2020 revenues, expected to reduce further to 10% of 2021 - not important, as this is low margin business
Intends to increase spending on sales & marketing in 2021, to accelerate growth - estimated at £1m extra costs, mainly in H2
US 3G network is being retired, which will involve Quartix spending £1.7m to replace equipment at its US customers - quite a nasty hit - I wonder if this issue could impact other territories too?
UK lockdown expected to have an impact on short term new subscriptions
Outlook - significant opportunity to accelerate growth, confident in 2021 and beyond.
My opinion - this is a good quality, high margin, recurring revenue business. It’s proven its resilience with decent 2020 results, actually slightly higher EPS achieved than the original, pre-covid forecasts.
Finncap has forecast a much bigger 2020 dividend, up from 5.4p previously forecast, to 20.5p.
The problem with Quartix, is that the decline of its insurance telematics business, combined with increased spending on sales & marketing in expanding overseas markets, completely masks the underlying growth. So the overall figures make it look like an ex-growth company, when you can dig below the surface and see it is actually growing the core business.
I feel that the valuation looks quite full at the moment. Lovely business, excellent management, but fully priced, is my opinion.
.
.
Churchill China (LON:CHH)
1275p - mkt cap £141m
Churchill China plc (AIM: CHH), the manufacturer of innovative performance ceramic products serving hospitality markets worldwide, is pleased to announce the following trading update for the year ended 31 December 2020.
- Traded around breakeven in H1, depending on which figure you use.
- Q4 impacted by covid restrictions
- Still profitable overall in H2 (no figures given).
- Comfortable liquidity (no figures given here either)
- Expecting 2021 to improve, but not in Q1 (due to lockdown)
- No dividends for now - will reassess in April 2021
My opinion - there’s inadequate information in this update to crunch any numbers.
Looking at the last balance sheet, as at 30 June 2020, Churchill is very well financed, e.g. a current ratio of 4.45 is very healthy indeed. This included £14.8m cash, with no interest-bearing debt. Note there is a small pension deficit.
Therefore there are no solvency worries at all - this company is very solid, and probably trading around breakeven currently, so it could survive current conditions indefinitely.
So it all boils down to what the future holds for the hospitality sector? It seems inevitable that many restaurants are likely to go bust. Also, I’ve seen many doing CVAs, which involve closing under-performing, over-rented sites. That’s bound to reduce the demand for new crockery.
Therefore, my best guess is that CHH could take several years to recover, and might not attain previous levels of profitability when the hospitality sector was booming. Sector over-capacity could take years to unwind.
If CHH shares were dirt cheap, then I would consider it, for a 2-3 year recovery in earnings. The trouble is, as you can see below from the 3-year chart, the share price now is actually higher than it was 3 years ago, when revenues & profits were growing consistently. Profit has collapsed this year, so why is the market cap so high still?
Valuation here doesn’t make any sense to me, it’s far too expensive given the sector woes & outlook, in my opinion. Why pay up-front for an uncertain recovery?
.

.
Carr's (LON:CARR)
126p - mkt cap £115m
Carr's (CARR.L), the Agriculture and Engineering Group, provides a trading update to coincide with its Annual General Meeting being held as a closed meeting in Carlisle today at 11:30am. This update relates to the 19-week period ended 9 January 2021.
Carrs has an unusual end August year end.
It’s trading in line;
The Group has made a positive start to the year with trading overall in line with the Board's expectations.
Agriculture is trading ahead, and Engineering trading below, netting off by the sounds of it.
Net debt has reduced by £6.3m to £20.4m, compared with a year earlier. It doesn’t say if any creditors have been stretched or not.
Brexit deal on 24 Dec 2020 provides clarity, and that customers (farmers) remain competitive across the EU. New system of agricultural support is pending.
Confident in the long-term prospects of both divisions (implies maybe not so confident in short & medium term possibly?!)
Points out resilience of business, due to essential nature of its supplies.
Outgoing CEO is thanked.
Diary date - Interim results to 27 Feb 2021 are scheduled for 21 April 2021
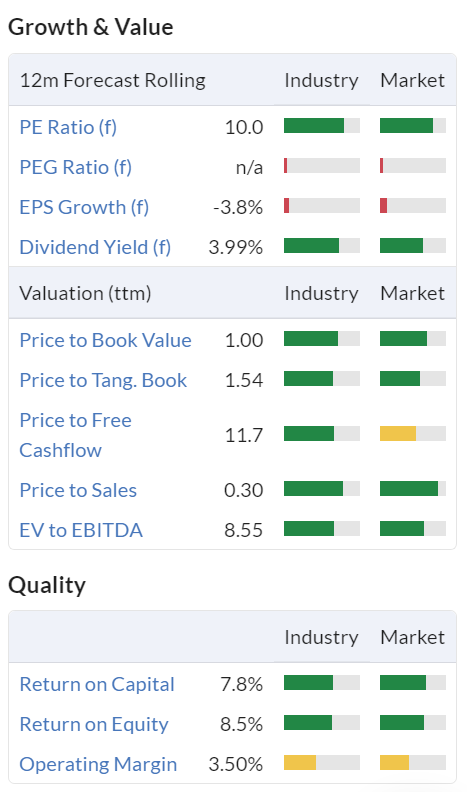
My opinion - forward PER of 10, and divi yield of 4.0% put this in the value share category. Here is my review of the last FY results. It’s a good solid company, with a strong balance sheet. The trouble is that the market isn’t really interested in value shares, so this one has just gone sideways for years on end. That might change of course, so there is the possibility of a one-off revaluation at some stage, once the tech shares bubble has burst, maybe?
Given the in line with expectations update, we can rely on the forward looking valuation metrics. This is noteworthy for being a sea of green:
.
John Menzies (LON:MNZS)
252p (up 7% yesterday) - mkt cap £212m
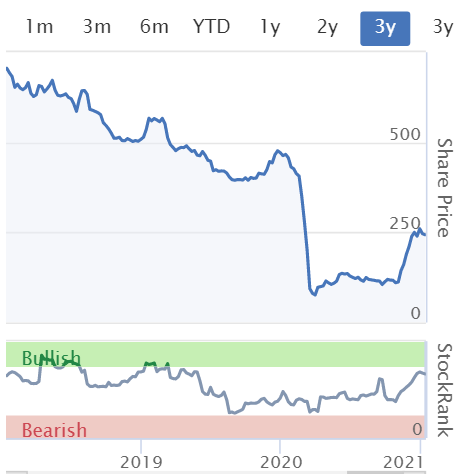
Given that it provides airport services, it’s having a grim time. Interim results to 30 June 2020 were ugly, with an underlying loss before tax of £(48.7)m. Plus an additional £(31.4)m of exceptional costs.
The balance sheet was bad before the covid crisis. Now it looks terrible. Altman warns on this too;
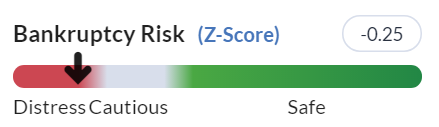
NAV is negative at £(8.3)m, then deducting £181.6m of intangible assets, takes NTAV to negative £(189.9)m. The whole thing is propped up with mammoth long term borrowings of £470m. Although it is also sitting on net cash of £137m within working capital (cash of £224.2m, less £87.2m in short term borrowings). Those figures do include lease liabilities though, of £177.6m, so it’s not quite so bad when you reverse those out.
However, bear in mind these figures are as at 30 June 2020. By June 2021 it could look worse still.
This balance sheet will need to be fixed in due course, hence I reckon a big placing is probably inevitable at some stage.
Revised bank covenants were agreed in Sept 2020. It makes sense for the banks to support it, until business is back to normal.
Trading update (issued 12 Jan 2021) -
John Menzies plc, the global aviation services business, today announces a trading update for the year ended 31 December 2020.
the Board is pleased to report that the Group has continued to trade in line with the expectations set out in the Group's interim results on 29 September 2020. Revenues for the second half were similar to those reported in the first half and for the full year were 37% below the prior year…
As anticipated, in the second half, the Group generated an underlying operating profit which was in line with the Board's expectations. As previously guided, this second half performance was driven by increased volume, a significant contribution from various government support programmes, the positive impact of continued effective cost management and a proactive flexible approach to operations.
Liquidity is good, but bear in mind this is due to very large bank facilities.
Outlook - continued difficulties in the early part of 2021 expected.
While there has recently been some renewed Covid-19 related disruption, the positive developments with regard to the roll out of vaccination programmes are encouraging and support assumptions of a gradual recovery in volumes from the second quarter of 2021.
Assuming a more stable, if still subdued, backdrop in 2021, the actions taken to structurally reduce costs, should show an increasing benefit in the current year, with government support schemes also continuing to provide a material benefit in the first quarter.
Over the medium to long term, the Board expects that the benefits of the reduced cost base, together with the ongoing good commercial momentum will contribute to structurally improved operating margins and consistent cash generation. This will enable the Group to both reduce its leverage and take advantage of selective strategic opportunities that may arise.
My opinion - I’m amazed the banks are being so supportive. Holders of the shares need to be aware that they’re totally reliant on the bank continuing to be supportive, which makes this share high risk.
Also I would expect to see equity diluted considerably (maybe as much as 1:1) in a placing in due course. The recent bounce looks considerably overdone to me, so personally I’d be taking advantage of that, and selling.
It's interesting to note that the company has stripped out costs. That should logically lead to higher profits once things are back to normal, than pre-crisis. So maybe I'm being too harsh, concentrating on the weak financial position?
.
.
Asos (LON:ASC)
5350 (up 3% at 08:05) - mkt cap £5.3bn
I was wondering why Boohoo (LON:BOO) (I hold) opened up this morning. It’s probably due to read-across from competitor Asos putting out a good update today. Asos has a 31 August year end, so updates us today on Sept-Dec 2020, 4 months. This covers the peak seasonal trading period.
Key points;
Revenue growth “surpassed our expectations”
Lower customer returns rate - a benefit from covid/lockdown (I suppose customers less likely to want to return packages to the post office, etc)
Net covid benefit of at least £40m extra profit in H1 (6m to end Feb 2021)
FY 08/2021 outlook unchanged, but expect to be at top end of mkt expectations - wonderful, there’s a footnote, very helpful, thanks;
2Company compiled PBT market expectations for FY21 as at 5th January 2021: Consensus: £141m, min: £115m, max: £170m
That’s quite a broad range of forecasts, so pretty significant to be at the top end.
Growth table is provided (see below) - what strikes me is that Asos is doing very well in the UK, but international growth is much lower. That’s a bit disappointing, given that overseas markets are huge in total.
Whereas the last update for BOO, showed stellar growth in USA (+83% in H1 to 31 Aug 2020), different period I know, but Asos is only reporting +13% in USA today. Therefore, I think BOO could be a stronger international growth proposition than Asos, we’ll have to see when it reports tomorrow.
Here’s Asos’s growth table from today’s update (remember this is only 4 months);
.

.
Brexit - this cost seems to have been absorbed by out-performance. It would annualise to a larger figure, if the company is not able to get round it somehow;
Brexit tariff costs of c.£15m in FY21 associated with country of origin rules
Capex - continued very heavy spending on warehouse automation;
FY21 capex guidance increased by £20m to around £190m reflecting investment into US automation
Strong net cash & balance sheet, but no figures provided.
Outlook - I would imagine BOO is likely to say something similar tomorrow. This is what Asos said today;
Looking forward, given the uncertainty associated with the virus and the impact on customers' lives, our cautious outlook for the second half of the year remains unchanged. However, the strength of our performance gives us confidence in our continued progress towards capturing the global opportunity ahead."
My opinion - it’s pretty obvious that online fashion is a strong structural, and lockdown-boosted growth area.
I much prefer BOO shares to ASOS, because BOO makes a much higher profit margin, generates stronger growth, and is delivering more impressive international growth. ASOS has never really generated any free cashflow to speak of - the cashflow seems to be sucked into building more & more warehouses.
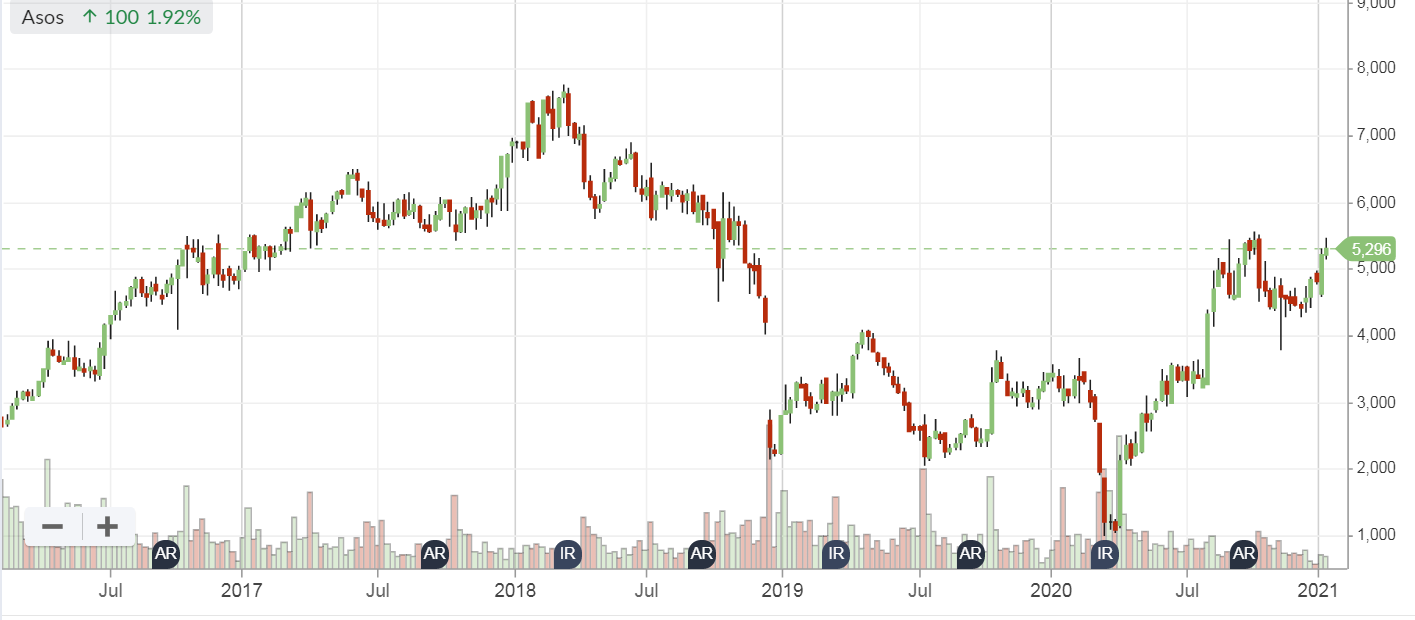
As you can see below, Asos badly disappointed in late 2018, and was a remarkable bargain in the covid panic in March 2020, but has since strongly recovered. 2017-18 is a warning that these highly-rated growth stocks can be a disaster in the short term, if high expectations are not met.
.
.
Sosandar (LON:SOS)
(I hold)
15.5p (down 16% at 10:10) - mkt cap £30m
The market has reacted negatively to this update today.
Sosandar, the online women's fashion brand, is pleased to provide the following trading update covering the three-month period ended 31 December 2020.
We’re now just over ¾ of the way through FY 03/2021.
Key points -
Revenue growth in Q3 only 6%, to £3.98m
However, this has been achieved despite a 66% or £1.61m reduction in marketing spend - NB the cost base is extremely flexible, with marketing spending being discretionary - a massive advantage over physical retailers.
Covid/lockdown means that the main focus on partywear didn’t happen (as expected)
Hence two very considerable headwinds there, which means reporting positive sales is actually not bad.
Profitability - EBITDA loss is down 60% on LY - but no figures given - this is more important to me that revenue growth. I want the company to conserve cash, and not do another placing. Although a top-up placing of £3m would only be 10% dilution, so not a disaster if it happens.
Returns rate has gone up from 42% in the interims, to 46% - so I don’t like the way this has been presented in the RNS as if it is a reduction! It is a reduction Y-on-Y (49% to 46%), but it’s a sequential increase from when last reported in the interims (46% vs 42%). Another example of Sosandar’s technically correct, but slightly misleading style of reporting, which investors here can see through, and don’t like (see the reader comments below). Cherry-picking or omission of important numbers is another example. Sosandar needs to ditch the previous era style of reporting (a bit rampy at times), and look to the transparency of Next (LON:NXT) as the model for its future reporting, in my view.
It’s a growth company, so it doesn’t cut the mustard telling us that sales are at a new record. They need to be, that’s the whole point.
John Lewis & Next new ventures are doing well. That’s encouraging, although bear in mind it started small, but should be good for future growth.
Net cash is £3.9m as at 31 Dec 2020 - this is the most important number to me, and I’m pleasantly surprised. I didn’t think SOS would get through 2020 without another placing, but it has done, and indeed still has a decent pot of cash. Well done to management. It hadn’t stretched creditors last time I enquired. So this is good news. I prefer the leaner, lower cash burn strategy at the moment.
Current trading - January 2021 has “already started well”
Brexit - no significant impact expected.
My opinion - I place more emphasis on keeping cash burn low, rather than chasing sales at a time when people were not buying partywear. This shows a flexible, and sensible approach in my view.
As things stand, the share price looks about right to me, for now.
Broker forecasts are still withdrawn, but who cares, because Shore Capital don’t let non-institutions see them anyway, so are irrelevant to the active part of the market, private investors.
Revenue for FY 03/2021 is going to be nowhere near the original forecasts of c.£20m. I calculate that we’re heading for about £10-11m revenues instead.
Far more importantly, the EBITDA loss is going to be drastically reduced on last year. It lost £1.0m in H1, and I reckon H2 should be less than that. Cash burn seems negligible at the moment, which is a huge improvement on where they were. Slower growth, with cash in the bank, is better than shooting for the stars, and running out of cash. Look at the mess that was Koovs, which eventually blew up, as I warned people it would, for years, because it targeted growth at any price. Sosandar has neatly avoided the same pitfall.
I’m happy to hold, given the sound cash position, and that cash burn seems to have been almost eliminated. To me that’s more important than chasing stellar revenue growth at a high cost.
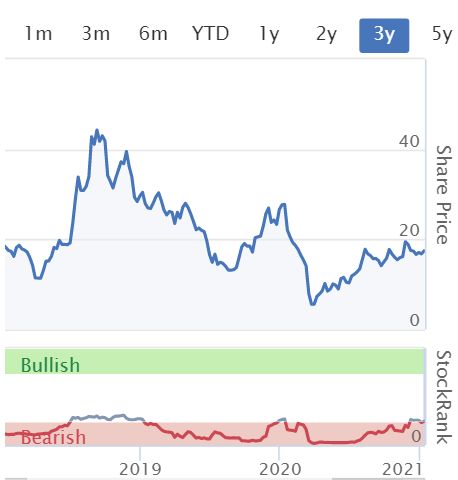
It's still (slightly) above the IPO price, which isn't bad at all for what was originally almost a blue sky startup at the time. I rate the management team here very highly. What they're trying to do is incredibly difficult. So to have got this far, is highly impressive.
.
.
Wey Education (LON:WEY)
36.5p (unchanged, at 11:41) - mkt cap £50.6m
This is a very interesting online education business. There's a good trading update today -
Wey Education announces that trading in the first four months of its financial year has been significantly ahead of budget and market expectations. The Company expects to exceed market forecasts in both turnover and profitability for the year ending 31 August 2021.
That's a strong statement to be making 4 months into the new financial year.
The share price initially surged this morning, but has come back down to flat now. I think that might be due to this statement about VAT -
Following a group structure and tax review, the Company also reports that InterHigh will henceforth charge VAT to its UK clients. This change will also allow the Company to recover VAT on UK expenditure and ensure that future InterHigh profits are distributable.
Part of the benefits from current trading will be used to smooth the transition in these charges for existing clients and notwithstanding this and a further targeted increase in marketing expenditure the Company expects profit before tax for 2021 to be ahead of market expectations.
I find that all a bit confusing, and the company clearly needs to give a more detailed explanation.
My questions;
- Why has the company decided to charge VAT now for UK customers? It seems likely to be adverse in its impact on profitability (20% extra cost of fees is likely to reduce net revenues as some customers are deterred). Also given that the big costs would be teachers salaries (non VATable), then I can't see how reclaiming input VAT would be a greater benefit than lost sales due to the price of the service going up 20% to the end customer.
- If the company is being forced by HMRC to start charging VAT, then surely that implies it should have been doing so in the past, in which case, is there a risk of a back-dated VAT claim? Revenues since 2015 have totalled about £23m, so back-dated VAT on that would be c.£4.6m, which couldn't be reclaimed from customers.
- Why would a change in VAT have any impact on distributable reserves to fund dividends?
My opinion - I'm not going to jump to conclusions about the above, but the company needs to issue a more detailed explanation of the VAT issue to the market.
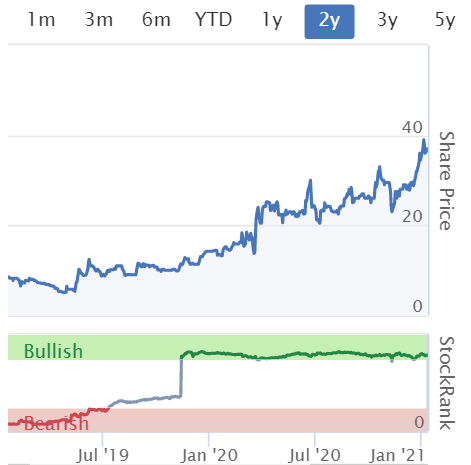
The share price has risen very strongly recently, on the back of considerable interest from investors. It got wide coverage in end of year investor reviews, for quite a few opinion leaders, successful investors. I'm a little worried that it might now be a rather crowded trade, so I'm not interested in buying back in at the current level, although I do like the company and think it has a good business model, and strong growth prospects.
Overall then, I'm positive about the company, feel the current valuation looks a bit rich for my taste, and need clarity on the questions asked above.
.
.
All done for today. See you tomorrow morning.
Regards, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

125 comments
Excellent reports for you this week Paul. I'm amazed how much ground you manage to cover in a day (and night) with your usual thoroughness and humour along with the occasional macro musings.
Thank you (and it's only Wednesday). Here's looking forward to what Boohoo (LON:BOO) has to say tomorrow. It looks like Lansdowne reduced their short yesterday so I'm hoping that's a good sign as I hold a shed load.
cheers
Francis
Wey Education (WEY:LON) I reckon you are spot on here Paul and there may be a big VAT bill to pay. At the end of the day its an online school and there is no VAT to recover on the largest budget item in any school which is teacher salaries! To now add 20% to fees for the parents of pupils at the school could be a disaster despite some scheme to alleviate the burden in the short term. The clients (parents) will not be able to reclaim that VAT back as they are not VAT registered business entities. Unless there is a better explanation to be found this looks like a disaster in the making, or made in the past and now they are facing the consequences. It is very difficult to make a profit from a school unless there is charitable trust or Foundation status and even there in UK private schools break-even points and margins for profit can be critical, and slender. Perhaps the business model is not so good after all?
In the review of the Stockopedia Top Stocks for 2021 I invested in most of the stocks on the list, for a 2021 Folio but not WEY. I classified that as too risky - and I'm a retired teacher - but cannot see how it can make a profit even by selling services to other schools. COVID has helped it sign up pupils for an online learning experience but "bricks and mortar" schools can offer that and so much more with their appreciation of the holistic needs of children and young people.
I think the VAT situation re Wey Education (LON:WEY) is not as complex as it seems.
If you refer to HMRC guidance on Education and VAT
Section 4
So long as Interhigh was ploughing all profits back into enhancing and expanding its offering, then its services were not subject to VAT.
However, if they are now making sufficient profit that Wey want to use in the rest of the group, or pay in dividends to shareholders, then they have to change the tax status.
This is a sign of the maturity of the business and must be a planned move not some shock revelation.
As such they will have considered what they will do with their pricing - whether they will pass on the impact to the customers or reduce their prices. For a business with little marginal incremental cost per student I would have thought it more likely they would take a margin hit, but I don't know.
I'm not a tax expert, but I don't see how this could create any historic tax liability. At the time of past sales, their services were exempt from tax and besides providers of goods and services do not pay VAT , they collect it from the customer.
Wey Education (LON:WEY) is another company of which I have been short in the past as it was significantly over-hyped on hope and expectation.
Some of that hope is seemingly becoming reality so I might have another look, although the valuation looks overly full to me even now it appears to have a profitable business.
No position currently.
Wey Education (LON:WEY)
I'm not a tax expert, but I don't see how this could create any historic tax liability. At the time of past sales, their services were exempt from tax and besides providers of goods and services do not pay VAT , they collect it from the customer.
Excellent spot gromley - Notice 701/30 is a bit of a quagmire for anyone at the best of times.
The bit you highlighted seems to tally exactly with the wording of the news today , i originally though wth (heck) has distributable profits got to do with vat treatment - there you go.
Note if we carry onto section 4.5 we get the following "warning"
4.5 The meaning of the term ‘does not distribute any profit’
Distributing profits does not just include paying a dividend to shareholders. It also includes making a payment or donation to another body, even where the recipient is a charity. Management charges or other fees paid to an associated company or individual may also be viewed as a distribution of profits.
It will be necessary to provide reasonable evidence that the profits cannot be distributed and that if the organisation’s activities do generate a profit that they will be recycled back into its education or training activities. For example, the Memorandum and Articles of Association, or some other constitutional document, containing a suitable reference or clause, may be acceptable as evidence of how profits are to be treated, although it’s what takes place in practice which will determine whether the exemption applies.
If we then jump straight to page 22 of the last set of accounts filed (always work backwards if you are looking for hidden info) the company confirmed that they have paid management fees to Wey education. Note i should probably highlight the use of the term MAY here so that doesn't mean there is necessarily any issue. I would suspect that not many shareholders would know that this entity was previously being run on a non profit making basis!
Great further find rmillaree.
I did start to respond on the two possible outcomes this might imply - but it was going to be too long and convoluted.
I'll just leave it that there is a potentially materially significant uncertainty over the impact until the company clarifies this.
My gut feel is that it is benign , but I would not want to stake any money on it at this time.
That was a very good spot, Gromley. I can't agree, however, that the result is entirely benign - either they will have to increase the price to their clients or they will have to take a hit to their profit margin. Neither is a good long-term result, surely? I have now sold, but I will continue to monitor their results with interest.
Hi Howard,
To be fair, I was only asking 3 questions about the VAT issue for Wey Education (LON:WEY) - I don't know the answers, so am not making a judgement on the company, we just need clarification from the company to those questions.
Regards, Paul.
I would voice a counter-point to your argument that private schools have low margins. That is true, but the private schools you're talking about are bricks & mortar schools.
Just like Online Retail is eating the lunch of Bricks & Mortar Retail, would the same logic not apply to Online Private Schools vs Offline Private Schools?
After all you strip out the physical costs - and then there's operational gearing of one teacher able to teach larger classes, as well as potentially cheaper teachers as you can source across the UK or even across the world.
However, I am also sceptical of the prospects of Wey Education (LON:WEY) as I think their market is too niche. Their strength is not better academics, better grades, Oxbridge entry, etc. They are often the last resort for parents who would prefer to send their kids to normal state/private schools, but have to send to an online school due to their child not being able to attend a normal school. The market for this is niche, and parents are stretching their budgets to pay for this - they're not the typical families that can afford private schooling.
MNZS - possibly worth taking into account that they cut 17,500 jobs in March - if they were all minimum wage then that would be £317m cost savings on top of other cost savings made. Say wages in other countries might not meet our minimum wage and halve it for safe measure that's still around £160m that goes right to the bottom line.
All imo
Hi Paul. Any thoughts on Renold’s update this morning? Thanks
Hi Gerryb,
Sorry I didn't get round to writing about Renold (LON:RNO) (I hold) but had a quick look at the update, and it seemed alright. I'll try to do something in tomorrow's report.
Best wishes, Paul.
Thank you Paul for responding. Your previous reports on Renold have been very helpful and informative.
Paul,
Completely off topic and definitely not a small cap but in the week when Next (LON:NXT) shares will exceed 8,000p I’d be really interested in your thoughts about what is an accurate valuation of the company is. Clearly it’s benefitted massively due to its online sales mix and site rental negotiations but based on this is a market place that has seen the entry of a number of highly valued competitors what can Next (LON:NXT) achieve?
M
Paul
Thanks for the remarks on Wey Education. The VAT issue raises questions for Management to answer. From the Mello Event discussion, I thought they were good communicators.
It was very useful for commentators to have picked this point up this morning. Shows the value of SCVR and its constructive chat.
I sold to bank profit. Still question whether growth is fuelled by Covid lockdowns and therefore may not last.
The sponsored WHI note on Wey Education (LON:WEY) says about the VAT issue "Price elasticity appears high, so we do not anticipate any significant issues around this". I think they mean that price elasticity appears "low" (i.e. that there would be a limited demand response to an increase in price). They don't refer to any evidence. And is that right? If customers would pay 20% more with limited loss of volume, WEY would presumably have charged 20% more even when it thought VAT was not payable. I suspect VAT has just eaten a significant chunk of the gross margin (as the biggest cost must be teachers who are either employed or, if providing services, under the VAT threshold).
I agree completely with your comments on Wey Education (LON:WEY) Paul. It does seem strange that they present themselves as having suddenly decided to charge VAT. I had not considered the possibility of a retrospective HMRC claim. Time to sell for a moderate profit I think.
Great write up as always
Wey Education (LON:WEY) VAT status
https://www.gov.uk/guidance/va...
HMRC guidance on VAT for education providers. Essentially can be VAT exempt if non profit making (like most private schools which are registered charities). Non profit making social enterprises (which can have shareholders) may also be exempt if offering education.
I’m wondering if this is a premature move by Wey Education (LON:WEY) as it would be easier to expand the customer base while charging lower fees. Maybe they had their hand forced by HMRC / accountants.
Another major risk to the company may come from more established private schools with strong brand value muscling in on the online education market. Most schools have now had nearly a year of experience in delivering online learning, some with great success. For those struggling to fill their expensive school places, online expansion may offer a lifeline. As registered charities they would also not be required to charge VAT.
£WEY Agreed. Going forward would most of the clients not be VAT registered themselves so not really increasing the cost to client?
No they will be parents of the pupils so even if one had a VAT registered business I cannot see the VATman permitting a VAT on child's school fees as being deductible.
I agree fully with your thoughts on the competition to Wey. If I remember correctly when Paul last reviewed it he thought on-line education was a sector with potential upside, but couldn't any moat that stopped many other players getting involved it. I believe he also thought there seemed a lack of management ambition to grow it in to large player.
Ben1,
I'm not sure about that. Probably better to put up a link to anything I've said previously, rather than putting words into my mouth, which may not be fully accurate.
Thanks, Paul.
Re Wey Education (LON:WEY) , if their intention was not to make profit, why were they listed? Sounds very strange. Another company in the same online learning space, Malvern International (LON:MLVN) , is on a much lower valuation and is beginning to move in the right direction.
Paul. A lot of quality commentary done very speedily in my opinion. Excellent job. Tks
Thought the trading update at Stv (LON:STVG) is worth a mention. Results "comfortably ahead" of market expectations, local advertising revenue down just 5% for the full year and up 8% in the second half and online advertising up 12% for the full year, net debt position significantly better than expected.
https://www.investegate.co.uk/...
Given some of the startlingly high valuations around STV and Itv (LON:ITV) continue to look cheap, I think.
timarr
Gigantic pension fund at STV I think. That's why it's cheap.
Gigantic pension fund at STV I think. That's why it's cheap.
Yep, they're forking out £9 million a year for the next decade or so to cover it. Supposedly that makes the pension fund self-sufficient, although I don't quite know how they guarantee that.
timarr
I know this newsletter does not cover miners etc but this news put out today by £ARCM is very interesting for those that are keen on this sector (disc: holding).
"Update on Exclusivity Agreement with Anglo American
Arc Minerals ("Arc") announces that it has received a formal notice from Anglo Exploration Zambia Ltd ("Anglo American") dated 6 January 2021 that, following due diligence, it is sufficiently satisfied to give notice to conduct negotiations in respect of a commercial transaction prior to the expiry of the extended exclusivity period of 180 days, commencing in January 2021.
Arc reminds shareholders that there can be no guarantee that the Company will enter into any commercial transaction with Anglo American".
Saga clients will be ‘among the first’ to start travelling again | Travel Weekly
Saga (LON:SAGA) This recent article might be of interest. I hold.
Carnival declined to give any visibility when they will start cruising again.
Royal Caribbean have pushed back first sailings to April 30.
If the two biggest cruise companies can't find a way to even have one cruise, before May, amongst all the ports/countries in the world at their disposal, that says something about viability of cruises. IMO we're looking at the first cruises only in H2 this year.
Couple of things on recent news. (LON:SAGA).Saga have put their office complex in Thanet up for sale. Taking the view that the enforced home working is proving successful and is here to stay.
(LON:KOMEK) Interims this morning. Any views? I like Dr Bassu, always very enthusiastic. Must be really frustrating to have come up with so many essential and amazing gadgets for medical diagnostics, bio war and pathogen detection. Clearly a big market out there when customers can get the products installed in between lockdowns. Seem to be bumping along on the cashflow which looks perilously low compared to what they might need to see the other side of this pandemic. More jam tomorrow if they have anything left to spread it on
I feel with Kromek (LON:KMK) they are too willing to take next year's cashflow for this year's development spend. And difficult to see the underlying performance through the Covid-caused problems. Maybe one of those cases where the founder scientist is not be best person to be running the business?
ST> I was a little disappointed with the figures this morning. Doesn't quite back up the 'normalising market. 'If COVID had such a big impact on business last year I can't see why he thinks its not having an impact now. I think they are a great small British business and possibly the government grants and funds will help them chug a long and see them through, but there is that nagging concern they may still need an additional raise.
Kromek (LON:KMK) I decided was not for me last summer - after this promotion https://www.proactiveinvestors... in April 2020.
"Kromek PLC's (LON:KMK) Dr Arnab Basu caught up with Proactive London's Andrew Scott after announcing they're turning its manufacturing efforts over to producing medical ventilators. Work will start before the end of the month and he's expecting to have 1,000 units available within eight weeks and 2,000 by 12 weeks."
I could not find any government contracts for their ventilators.
Why did my reply get deleted?
My post stated nothing that wasn't implied in the post it was replying to, contained no offensive language and was not harassing.
Just randomly taking down posts with no evidence they ever existed, and without explaining the reasons why / which rule it supposedly violated is just BS.
IGPJ was this in response to me on Bango (LON:BGO) ? I'd skimmed on phone and now at PC it seems to have gone.
Yeah. Who knows what was wrong with it.
I can't be bothered to retype it. In short, I don't agree with your analysis of the Korean deal, I think that getting a larger, more capable partner could only ever be good for Bango to effectively exploit the data.
I think the marketplace regulatory risks are there but aren't that significant as they don't, to the best of my knowledge, release the raw data in any form they sell access to targeted groups that are known to use their phones for purchases.
I mainly hold these on the top and bottom line growth trends.
If this one gets deleted, I'm finished here.
If posts are deleted the head is still there with a red "This post has been moderated". I don't understand what you are on about. I have only just opened this and it would appear to be about post 29 starting:
"I think your points are fair enough. I'll level with you, I've not dived that deep into it, however I've never seen Bango market themselves as being a "big data" company.
I also don't understand your points on the NHN deal. Bango ....."
which I can read perfectly.
Yeah it vanished for about an hour then came back. It appears I have jumped the gun in my frustration and I apologise to the team unreservedly for my tantrum.
If it was in a moderation queue or something perhaps they could've put a "this post is being moderated" placeholder up and that might have reduced the frustration.
Thanks David, as I said I hadn't been looking in detail I realised they had sold part of the analytics business I hadn't they had sold all of it.
So that's yet another substantial strategy change?
None of it makes sense to me - I think I'll leave it there.
Okay. I wrote a response to David Hill...its a bit messy...I'm sticky with Bango (LON:BGO) is fishy
Do you mean this one: "I think your points are fair enough. I'll level with you, I've not dived that deep into it, however I've never seen Bango market themselves as being a "big data" ........
." ?
SOSander (LON:SOS)
If I may paraphrase the Sosander trading update:
Good News: "We spent a whole lot less on marketing"
Not So Good News: "This stopped sales growth in its tracks"
I will leave holders to draw their own conclusions.
Bonitabeach
No position.
With regards to Churchill China (LON:CHH), as they are in a strong position with a strong balance sheet and plenty of cash, is the share price reflecting a pick up in market share? I have not looked into their competitors here but I imagine the hospitality industry could drag under plenty of suppliers with it, therefore £CHH benefitting due to its chances of surviving?
I was thinking something similar could happen in the hotel industry, plenty of the smaller hotels could go bust leaving the stronger participants picking up more market share.
Yes smatthews1, any competitors of Churchill China with weaker balance sheets are likely to be hit harder by the impact of COVID-19. One other point is that, despite some share sales, the Roper family still own over £23M worth of shares in Churchill so I think it would be fair to say they still have "skin in the game". The current shakeout in the hospitality sector is clearly hitting Churchill hard but I wonder if this is creating future demand as new restaurants will eventually open to cater for demand after the pandemic is over. This would not be true if the new restaurants take over the china from the old establishments, but I would have thought it more likely that they would buy new supplies of ceramics as the patterns on plates help owners create the character of their restaurants.
Completely agree with Paul's assessment that Churchill China (LON:CHH) is over valued. It is a great company which has been around for over 200 years with a strong family shareholding. No doubt it can survive the economic after-shocks of the current pandemic. However, its heavy dependence on the hospitality industry, in the UK and abroad, is a serious headwind, and steady share selling by key executives over the last few years suggests that they also share Paul's opinion.
Wey is one of the Stockopedia Staff picks. I am in any thoughts on the Trading Update and the introduction of VAT charging highlighted in the comments today.
I often read the Sosandar (LON:SOS) updates now trying to interpret what is not written as opposed to what is. Why not get some tables out there?
The update at this time last year had some more granular data including customer database, repeat orders. Are these not KPIs any more? If they are it may be interesting to know, especially as marketing costs went down.
I agree, Snoo. I am disappointed at the lack of numerical detail provided for Q/E 31/12/20 v 31/12/19 by £SOS.
What happened to Total Number of Orders, Average Value per Order, Conversion Rate, Customer database numbers, and Active customers numbers?
Every quarter the number of metrics either diminishes or is changed and the narrative become selective, as Paul above has pointed out. It becomes harder to evaluate and form a view.
At the last investor meeting I asked what the marketing spend was as a percentage of turnover. It wasn't answered. I have no doubt the founders are great managers and have in-depth knowledge of the market, but as an investor I do find the RNSs and presentations lacking detail.
Reacher:- re Sosandar (LON:SOS) and "I have no doubt the founders are great managers and have in-depth knowledge of the market, but as an investor I do find the RNSs and presentations lacking detail." - I'm of the view that if they thought it would be in "their", as opposed to "our" interest then they would let us know.
Disclosure: I do hold but becoming more disillusioned by their seeming determination to "not tell it how it really is". Oh, if only all companies were as up front as Next (LON:NXT) and Games Workshop (LON:GAW) (as just two examples)
Good Morning all,
Touchstar (LON:TST) momentum seems to be continuing (TA this morning). As Mr C said, not a lot of numbers but now "strongly" profitable, net cash and good cash generation. One has needed to be patient here, and the market may be over reacting (up strongly as I write), but as a recent holder of Triad (LON:TRD), this seems to be happening a fair bit and in my mind is a sign of possible general over exuberance.
Such was the rise in Triad (LON:TRD) I actually managed to sell at 135p, and shortly thereafter there was a "notes the recent movement in the SP" RNS, which has brought right it back down to earth.
Paul, you have been positive on Touchstar (LON:TST) lately. There's probably not much to comment on here but thought I would highlight it here for those who like a turnaround under newish leadership.
Hi fredericktug,
Touchstar (LON:TST) (I hold) is probably too small & illiquid to warrant a section in the main report. I've held since 2018 (not ideally timed, at 80p per share) because it looked cheap at the time. It's looked very cheap ever since! Hence why I couldn't see any reason to sell, despite the share price halving in the last couple of years. It's my assessment of the fundamentals of a company that drives my buy & sell decisions, not the share price movements, and I always thought Touchstar looked potentially interesting, and with good upside possible because the starting valuation of about £4m market cap previously was so tiny (it's only about £6m now after today's big rise). If it rises to £20m market cap (possible on some good news about growth), then that's a 5-bagger from the lows.
I think today's update is good, especially on cashflow. Although it is not stated whether creditors have been stretched or not.
Touchstar seems to have current, and relevant products & software (handheld computers for e.g. delivery drivers, etc).
It would be good to hear from anyone who has experience of using Touchstar's products, or had dealings with the company.
I seem to recall the head honcho was previously FD at Avesco, which was a cracking result for many of us here - multi-bagged on a turnaround, then was sold off at a large premium price. I can still remember my broker ringing me up to give me the good news on that!
Regards, Paul.
Maybe a takeover target for someone like Solid State (LON:SOLI) ? They've said they want to get into the logistics sector and recently announced their first win in this space IIRC.
I was a little surprised by the super positive performance by Touchstar (LON:TST)
Their last update / results were a bit worrying with a low order book, and warnings that the lead time from enquiry/prospect to order and delivery was long.
Clearly it seems there's been lots of demand for their products in the last 6 months. Maybe their products are really good - if companies are willing to shell out for new multi-month / multi-year license commitments, even during a time like this.
Morning, any thoughts on Tui rights issue? Apologies if already covered but couldn't see it from searching
Good Production and trading update today from Kenmare Resources (LON:KMR) - Kenmare which does not seem to register on the folio news section today. Worth reading for those who are into specialist mining sector. I hold but TBH I'm no mining expert.
re Kenmare Resources (LON:KMR), (I hold), this is a miner and not really one for this board. This is just a production report, with minimal guidance on profit outcome - there will be Covid related costs in the final outcome. However, they are entering a sunnier upland - less development spend, higher grades from the new mining area, and improving prices. I think it is still under-valued, but then I would.
Andy Sav take a look at Avacta, although known for its lateral flow COVID test, it has just started a clinical trial on one of its targeted chemotherapy drugs. It has signed up in some interesting JVs too. Avacta (LON:AVCT)
I’m surprised to learn that the covid vaccine is actually the result of a long running technological breakthrough. The new delivery mechanism “might” result in curing all sorts of hard to treat diseases. I’m admit I don’t understand Pharma, but I am wondering which stocks should warrant further research with this info in mind. Any ideas?
Snippets below from the following article: https://www.nature.com/articles/d41586-021-00019-w
“The idea of using RNA in vaccines has been around for nearly three decades. More streamlined than conventional approaches, the genetic technology allows researchers to fast-track many stages of vaccine research and development. The intense interest now could lead to solutions for particularly recalcitrant diseases, such as tuberculosis, HIV and malaria. And the speed at which they can be made could improve seasonal-flu vaccines.”
“RNA vaccines carry only the directions for producing these invaders’ proteins. The aim is that they can slip into a person’s cells and get them to produce the antigens, essentially turning the body into its own inoculation factory.”
You see, when I read “slip into a person’s cells” I start thinking of autoimmune responses. There’s been no long term study of the effects and I worry about developing rheumatism, lupus, etc.
I’m sure many doctors here can tell me why I’m being irrational, and my doctor wife has happily had the Pfizer vaccine.
If people want to guinea pig themselves they’re more than welcome. I’ll be sticking the Oxford vaccine.
Hi, interesting! I hadn't appreciated the Oxford vaccine uses a more conventional / proved method. I guess this explains why its slightly less effective (70% vs 90% but still really good) and doesn't need to be stored at -80% Thanks :)
https://www.theguardian.com/wo...
I wouldn't assume at this stage that the Oxford vaccine is actually less effective. The definitions of effectiveness were different across the two trials.
The Oxford vaccine was 100% effective in preventing hospitalisation, which will do for me.
The use different technologies (and M RNA is the more novel) but in both cases what they are doing is giving the body early sight of the what the spike protein looks like.
IGotPoesJacket - I have no medical knowledge but would happily go with the new technology. Perhaps if you are offered the Pfizer I can swop you my Oxford!
Hi Andy, I would suggest taking a look at Open Orphan (LON:ORPH) Open Orphan (I hold) worth taking a little time out to watch Cathal Friel interviews he is the CEO, so much potential upside, I won't list here in case I am accused of ramping, the main thing though for me is they don't manufacture vaccines, they run challenge studies and trials, so if one does fail, they still get paid, plus they have a nice Government contract being worked on.
I saw a presentation from the Open Orphan CEO, in which he was at pains to stress that at the end of the day they were are a services company, with a maximum level of business possible (due the size of the facility), and kept cautioning investors against chasing the price up. So after a bit more research I decided pass on it. Worth looking in to that I think, if you are interested in them.
Thanks Ben, appreciate your thoughts, maybe it was an older presentation as they have other facilities now they are using on behalf of the government and have work booked going out at least 12 months on trials not just Covid related, glad you made me question my investment though, always good to revisit where you money is, I wouldn't even mention wearables data from their genome database, and selling non core companies and giving cash back to shareholders as it would sound like I am ramping :-) and I have been known to be wrong on so many occasions
I am pretty sure it was on investormeetcompany if you want to look for it, but I can't remember the date of the presentation itself. There may have been other facilities opened since. I have to say I was pleasantly surprised to hear an exec chairman, warning investors not to chase the price up. Many I fear would have allowed it happen and sold shares themselves.
Thanks Ben, will go and find it as I like to know as much as I can about Open Orphan as it is one of my larger holdings, just for info, the CEO Cathal owns 6.88% of the company and is locked in for another couple of years I believe and is truly aligned with shareholders and keeps saying about handing cash back, and also says they are now profitable.
The only thing I can see keeping the price where it is would be Invesco reducing their holding, once that is done I am hopeful of another surge in price, but then again my crystal ball is broken.
Appreciate your feedback
They're looking to open up an additional two facilities and are in advanced stages of negotiations. this should add more incremental revenue to the business so their ceiling gets much higher. FY2021 revenue is already in the bank, and as you said the biggest upside is in Immutex sale and a licensing agreement on their database for wearables manufacturers (Google, Amazon and Apple), which should form as special divi . This will be game changing against the current SP and none of the valuations are factored in and all upside. I'm a big believer in ORPH and Cathal, as he seems to be really honest with shareholders and trying to manage the SP for controlled growth versus volatility which I don't mind. It's a significant portion of my portfolio and have no plans to sell or topslice until I know where we are on Immutex and data wearables. I don't invest in Pharma, but ORPH isnt a Pharma company, big contracts for their competitive moat which is hard to replicate is why I am invested here.
Of course DYOR as above is my opinion :)
Nice one Phil, you know them so well, I was reluctant to post too much in case I got accused of ramping, but I firmly believe this is going to be one of this years major winners for me,
I am with you, I don't invest in Pharma either, but this is so different and his interviews are well worth watching.
I want to add to my holding, but will wait until the next leg up (or at least the start of the next leg up)
Thanks for your post, spot on!
Open Orphan (LON:ORPH) on initial appearance , CF appears to be a "BS artist" who loves talking. After you see his presentations over a few months and then the results that he has already alluded to in previous presentations, you then start to change your perspective to CF. You start to realise that he is a top rated entrepreneur who is focused on the bottom line and says what he says he will do. My perspective on CF has changed from 100% scepticism to 100% confidence of his ability to steer Open Orphan (LON:ORPH) to achieve high growths. Genuinely, he talks the talk and walks the walk.
He loves to promote Open Orphan (LON:ORPH) because not only did he buy one of the businesses in Open Orphan (LON:ORPH) at a super bargain basement price from Woodford (so he's like a kid in a candy store), he now has top rated and highly valued contracts to go with them. Phil Dunphy - above - wrote of all the "goodies" that us shareholders are very much licking our lips and looking forward to.
In respect of his scientific background - he has got jack technical background but he was a founder of Amyrt Pharma. Most importantly, he has a world class scientific team who does all the technical day to day stuff. So excellent balance, he focuses on cutting costs, deal making and leaves the science to lab experts. To me, Open Orphan (LON:ORPH) right now, is like a coiled spring.
Spot on maxistaxis, Open Orphan (LON:ORPH) summed up very nicely
Cathal is one awesome entrepreneur, cuts costs, removes the fat, increases revenues and margins, leaves the scientific stuff to the experts I am more than happy to follow his lead and that's why I am slightly overweight with my current holding, and once the current opportunities come to fruition and we start to move up again, I will be adding, also because he is totally aligned with shareholder value
Quite an adventure, this will be my next Paysafe!
I don't think stuff like this is ramping, as long as it is backed up as to why you believe there is upside. I'm always on the lookout for new investment ideas and communities like this help steer me towards something I should research and not miss some great opps. ORPH is one of my two big bets this year. Fingers crossed it all goes well! GL
Thanks Phil, appreciate the reply, maybe I should post more on other investments and the reasons behind them, I do tend to get passionate about holdings and opportunities, my research is nowhere near that of Paul, Jack and others, but think it's good enough for me enhanced by others.
Good luck with Open Orphan (LON:ORPH) but I don't think it's luck, more right place, right time and right CEO!
Open Orphan (LON:ORPH) I listened to the presentation and remember the CEO saying their target is to double the share price each year. I was impressed and bought some mor but DYOR
Thanks Skier
It seems there are a few Open Orphan (LON:ORPH) fans on here, I thought it was a best kept secret :-) the CEO impressed me too which is why I bought them in the first place, and as you say DYOR
Maybe this is a Buffet "be greedy when others are fearful" moment. But Open Orphan (LON:ORPH) , PE(f) of less than 6 and a PEG of 0,1 according to the Stockreport, based on broker forecasts, and net cash around 5% of market cap just looks too good to be true!
If that is the case, how has the market got this one so wrong? One assume there must be a massive amount of execution risk or just straight up failure to meet expectations in the past that's carrying forward?
I might just throw £1k at this to keep an eye on it in the "punts" portfolio, feels like I should back up the truck though!
Open Orphan (LON:ORPH) I agree with you IGotPoesJacket, it does look too good to be true,
The potential having watched most of the CEO presentations is what swung it for me, as he brought the companies together, he slashed costs by shedding the top tier of executives, identified the opportunities, is divesting non-core assets.
Cathal Friel the CEO is the largest shareholder and it is in his interests to make as much as he can, not only for him but fellow shareholders
I have tried to find something not to like, because I really believe if it is too good to be true it usually is, but this (at least for me) is a gem of an opportunity, as always I stand to be corrected and listen to those that know more than me
I like his honesty, earning £150K per year, looking to move to London to be closer to the business and to reduce the travel from Ireland, to me this sounds like some committed CEO and he is also locked in for another couple of years.
Other things I really like which has been driven by Covid is for the last 20 years, massive investment has been made in other medical areas including gene therapy but little with Vaccines, which is now changing and plays right into Open Orphan (LON:ORPH) I also like the fact they have the worlds largest genome database and are talking to the main players regarding wearable tech and how they can monetise this, we have all seen fitness trackers on smart devices
Interview with Cathal here for those that are interested and any feedback would be welcomed
Good luck if you do, and it goes without saying DYOR
£ORPH - quite possibly the broker's forecasts could be out of date. As a holder only from 23p onwards (I was converted late after trading it at 13-14p), the news flow is unbelievable - new contracts, renewed contracts but once again as Phil Dunphy stated - existing shareholders are itching for the release of the news on the "wearables" incorporating Open Orphan (LON:ORPH) proprietary database , the disposal or Nasdaq listing of Immutex , a subsidiary ; significant re-rating due to increased facilities to carry out more challenge trials (= more venues = more rev) ; and John Eustace, below alluded to - peptide based univeral flu vaccine candidate in their portfolio in phase 3 (i believe) trials. It's no secret as well, CF being an entrepreneur, he would be very open to a big boy buying the company out in 12-18 months time. GL
Open Orphan (LON:ORPH) nice one maxistaxis nothing I can add to this, you clearly know all the known potential of this company.
I got in originally at £0.14 added on the way building my position and my average in one account is £0.20 now, but got caught in the other with a top up of £0.32, but I am certain it will well exceed that, just a timing issue with me I think.
I am looking forward to an update from their attendance at the J.P. Morgan Healthcare Conference this week.
Good luck
Cheers
Steve
I have quite good holdings in the US Biotech ETF's. To choose an individual share would for me be like sticking in a pin so best to go for good coverage. These companies can revolutionise medicine and the Covid situation is drawing attention to the fact.
Thanks all :)
I am somewhat surprised that all the discussions here (not only now but in the past) have tended to ignore the Moderna vaccine. particularly given the ongoing discussions concerning Covid 19. The Moderna vaccine uses the same technology as the Pfizer vaccine, has the same 95% efficacy, but it is much easier to handle, and appears to be one of three vaccines which is obtaining universal acceptability. I hold Moderna shares - $MRNA. DYOR.
The obvious candidates are Moderna and BioNTech. They seem to be being traded as mostly vaccine companies and now people are realising as you say that the vaccines could just be the first applications for RNA technology.
I also hold Open Orphan (LON:ORPH) but don't think of them as an RNA company. And I have the funds Biotech Growth Trust (LON:BIOG) and £ARIX. It's probably a mug's game for non experts to dabble in individual small biotechs (memo to myself really).
I agree on Open Orphan I believe they provide test facilities rather than develop tests or vaccines themselves. The vaccine developers hire their facilities and test expertise
Open Orphan (LON:ORPH) do have an interest in a peptide based univeral flu vaccine candidate in their portfolio. They say the technology could have possible use for coronavirus by swapping out the universal flu peptide with a peptide specific to COVID-19. They hold this through a 49% interest in Imutex
It's in the US but Moderna is basically the front-runner in the mRNA field. It has a huge platform across lots of different disease areas (not just vaccines). Now the technology has been validated it should be all systems go for the other indications too. It's basically a blueprint to get the body to make it's own medicines. That's what I'm hoping anyway! Re: the comment below, the mRNA only 'slips into the cells' to get transcribed into a protein. It doesn't hang around after that. The Oxford vaccine is DNA based and that too has to enter the cells and be transcribed into a protein (DNA to mRNA to protein). So there is no real difference in that respect
Sosandar (LON:SOS) Good news they are still managing to grow by modifying their range, however, given they are an internet only retailer I would have expected more frankly. They’ve slashed the marketing spend. It would have been completely stupid to continue with things like adverts on the tube when there’s not many people there these days so I can’t award them any marks for that. But I do wonder if they’ve missed a trick in not spending a bit more trying to get their name in front of customers who are browsing the net looking for somewhere alternative to buy quality stuff when the shops are shut.
Still loss making (will they ever break even?). Loss is substantially reduced; is this pretty much because they spent hugely less on marketing or has the underlying performance improved? Hard to tell. We’re not given a figure for the loss, just a percentage reduction. An oversight perhaps, or just omitted because it is embarrassingly large?
Overall a mixed bag. Seems like another business in semi-hibernation until Covid is under control. Generally though it feels like they are in the “survive” category rather than “thrive” category. So, it’s still on the avoid list for now for me.
If Sosandar (LON:SOS) has done badly over x-mas, I can't imagine how Quiz (LON:QUIZ) has done. Even more partywear, much worse eCommerce. And running on fumes in terms of cash and probably can't spend millions on digital marketing to drum up sales.
ASOS (LON:ASC)
It's had a good first 4 months with sales up 36% in UK (high teens RoW) . Bit of a read-across to other on-line fashion retailers.
This is interesting:-
"Our performance in P1 also benefited from the resumption of lower returns rates driven by renewed social restrictions in the period. With restrictions likely to be in place for the balance of the first half we expect a net COVID PBT benefit1 of at least £40m in H1."
Phil
all comforting for BOO (LON:BOO) tomorrow
Busy morning for my portfolio.
Sosandar (LON:SOS) - not sure what to make of this. Revenue up 6% despite significant cut in marketing budget. In short it’s a party wear retailer that managed to grow sales on reduced marketing budget when there are no parties to go to. As ever with this co. the bull and bear case are finely balanced IMO and I think when parties do start again (hopefully starting with a backlog of weddings later in the summer) business should boom here though there’s likely to another dilution.
Bango (LON:BGO) , revenues very slightly ahead of expectations (£12m vs 11.9 expected). Starting to generate significant amounts of cash. They’re valued at about 40x the cash added, but hopefully operational gearing is now kicking in and any additional revenues are dropping to the bottom line. As ever, I’m an idiot and may have misunderstood what’s going on.
Allergy Therapeutics (LON:AGY) , another one where I think operational gearing is kicking in. They spend a lot on R&D being a pharma. Sounds to me like they’re managing to fund ongoing trials from the revenues generated by previous product launches, potential exponential revenue increases as sales generate R&D which increases revenues. Hopefully won’t be a small cap long.
Tp (LON:TPG) , announcing possible sales of some assets. Seems to want to move from a stable engineering business to the “hot” sectors, alternative energy, space etc. No figures and I genuinely don’t know what to think of the recent developments.
IGPJ + other enthusiasts-> Bango (LON:BGO)
I confess I've been suspicious of this company since checking it out mid 2020...it probably me being grouchy/cynical. The TU looks good on glance (without detailed look and comparison).
I thought last nights update re other directorships was a bit of odd but announcement of change of broker and nomad explains timing...I still don't these were errors the company should have made (they knew better!)...which feeds my view that mgt are over promotional.
Anyway, the thing that caused me most unease was their activities away from direct carrier billing - Audiens related purchase and then sale and Marketplace.
With Audiens I found it odd that they bought then sold to Koreans NHN quite quickly after retaining a passive minority interest. Financially the transaction looks positive but why would this 'innovative' data company buy something to develop their data capability/monetisation and then sell on to someone else.
Also, it doesn't make sense that Bango remain passive minority owner. NHH will do all the investing and as a big, savvy and complex company I don't see how they will let value flow to passive Bango if they succeed in significant monetisation. So it seems to my jaundiced eye that Bango had something they didn't know what to do with and flogged it off to someone else who did...nice trade but not really what one wants management to do and hinting that Bango aren't that great at 'big data' stuff. Which takes me to Bango Marketplace...
My suspicion is that this is rather basic stuff rather than anything significant from data analytics perspective and its value and capability is that it evades regulatory environment that stops other payments services/processors (banks, credit cards, paypal, tech cos, etc) from selling direct or very proximate data on what their customers have been buying (ie very valuable data but highly prohibited in regulated environments). If so its quite desirable....but quite unstable and unpredictable as to when the loophole closes...also very hard to value a long duration of growth and cash flow from this.
My hunch is that Bango will seek to make a new acquisition quite soon. This is way of monetising the value in the share price created by the Bango Markekplace and Audiens buzz
Okay! So I'm probably just not getting it! I could be way off here...but I'm suspicious and do not trust what I've seen
I think your points are fair enough. I'll level with you, I've not dived that deep into it, however I've never seen Bango market themselves as being a "big data" company.
I also don't understand your points on the NHN deal. Bango were unlikely to maximally exploit the data for revenue purposes, even if NHN rip them off massively it's likely to be more revenue generative than Bango going it alone. Reasons for not being able to maximally exploit this data include, but are not limited to; not having a platform to process it, not having sufficient data analytics/machine learning/AI technical capability within the team (and it's hard to recruit), not having the customer base or relationships.
As for the point regarding about what customers have been buying, I don't think they do that. All they say is "these anonymous ids make in app purchases, would you like to send them an advert for your product" defined by things like "shopping app", "game app", "20 something female". I don't think (happy to be corrected) the person wishing to advertise gets any of the personal data, they just get to select a "bucket" of personas most likely to transact.
Anyway, I've pretty much given up spending too much time going right into the nitty gritty of companies. There's a couple of reasons for this - I've noticed that companies where I think I have a knowledge advantage over peers makes me look to hard at the bear case not the bull case, and secondly, you can't ever, really get enough data from the outside. So now I'm more interested in the trend, both for the general market the company operates in and for top line bottom line growth, remembering I only need to be right 60% of the time :)
I note a new competitor has listed recently, I forgot to make a note of the name. I haven't yet worked out if there's space for competitors because the market is growing so much and there's space for growth and competition or if Bango (and Boku - I don't hold Boku) are going to find things more difficult from here onwards with downward pressure on margins and increase cost of sales.
hey Mojo - I'm long Bango (LON:BGO) but have been since around 70p I think so I was always bullish on the core business. It's an interesting point on Audiens though. I would imagine they have an exit mechanism at fair value but I've seen too many instances of boards getting that sort of thing wrong to put any trust in that. I will ask management when I get chance. They made money on the purchase and sale irrespective and got a strategic investor into the business so shareholder value additive rather than destructive but I'd like to know how they ensure they derive the benefit of the value creation in the long run.
To be fair I don't think the Audiens deal has any "buzz" about it anymore. The share price is reflecting the near doubling of EUS to 1.9b and the fact that it is now cash generative and profitable and continuing to grow. They have operational gearing from here to 5bn+ of EUS so I expect very strong free cash flow so long as the EUS growth doesn't stall.
Marketplace is an interesting concept and idea. I don't really factor anything into my valuation for it personally but I'll be interested to see its revenue potential when we next get a management call.
I haven't looked properly at Bango (LON:BGO) for a while (used to be short).
Not sure what you are saying about Audiens there david - are you suggesting they might sell it? I thought Audiens WAS the business now and the EUS machine now existed just to harvest data?
As for 'now cash generative' - I'd have to be sceptical here - they have been claiming for a few years now to have broken through to cash flow positivity and profitability - it hasn't proven sustainably true so far.
Gromley - you are out of date :)
They sold Audiens to NHN Corp (Massive South Korean company) and retained a 40% minority interest. At the same time NHN took a circa 5% stake in £BGO.
The business is predominantly the EUS payment plus Marketplace. They have been cash generative consistently for a number of months now. check cash position.
Bango (LON:BGO)
Hi David
Bango has never been cash generate as far as I was aware, and looking back at the last cash flow statement published with their Interim Report, the only reason they ended up with more cash in the period was due to a £3.4m share issuance.
Take away the £3.4m and "it looks" like they actually lost cash in the period.
I say "it looks" because they unhelpfully don't seem to have provided a breakdown of operating cash flow so we have no idea if they truly are cash generative.
They may well be cash generative now, but as far as I can see nothing has been published to 100% confirm this.
No position.
A
Bango (LON:BGO) do seem to be cash generative for H2 2020 though waiting on annual report for that it could be a result of working capital.
I'd guess it may be that they cut investments with the sale of Audiens and with revenue growth that helped push through into positive cash. Nevertheless its marginal cash positive and would suggest that they are at best 50-60x earnings with a lot of prove re how revenue drops through to bottom line and/or whether they more development spend....or maybe make another hugely value destroying acquisition like Audiens.
It looks like they made a cash return in H2 2020....but I agree it feels more short than long
It sounds to me like you really should own Boku Inc (LON:BOKU) rather than Bango (LON:BGO) then as better relative value/potential particularly as Fortuma adds similar smaller client higher margin dynamic, and their ID business is real and truly scalable (tho they have been slow to monetise and not clear whether they need a lot more investment to make it work....which they might be withholding now to make EBITDA look good)
IMO the share price is discounting that they are doing something interesting with data. I believe investors should understand Marketplace as part of that pricing....and my hunch (tho not sure) is its 'reg arbitrage' in play. I'm not claiming great expertise or that I have my inshite correct but I've owned a business that touches some of this area (and was fully FCA authorised) and that knowledge and trying to put together pieces is why I think what I do re Marketplace.
Based on speaking to investors and looking at Tweets I do believe that selling Audiens to NHN was a buzz factor and that its likely it retains rosey afterglow still (even if its not front of mind). I stand by the view that the round trip from buy to sell on this doesn't make sense regardless of whether they made a buck on the turn (which is all in the shares issued to NHN...so not really for Audiens even but obvs the two are tied as as happened at same time). And what they have with NHN is likely to be nothing as there is no way that NHN let value flow back to Bango a now passive non capital or IP contributing investor as NHN pump $8m at least in. HNH will write down that $8m, report that Audiens is worthless and then use the IP/tech they have from it elsewhere in NHN biz that Bango gets no coin for. This is shell game by NHN to extract value and Bango to hide that they are getting nothing for Audiens.
Strange strategically re whole Audiens thing....and why didn't they develop the potential they had sought out and bought themselves? I find that fishy and in need of explanation. My suggestion is that they lack the ability plus they needed cash (which they got through equity transaction on the side...kind of obscuring the need for a raise to PIs).
An additional oddity is that new shares where issues to NHN (at discount I assume). Why? NHN probably don't have strategic interest in Bango so why the stake....well it looks like paying for Audiens but as its in equity they can get their money back out (lucky them with added return at moment). So NHN get 60% of Audiens without paying anything for it and the equity they took is a little bit of a shell game whereby they can get their 'purchase' back out...of course Bango get extra funding.
Then to repeat 1) They are very promotional and pump out any little bit of news, 2) last night's RNS was a bit dodgy....I note new broker/nomad probably caused need for it and that sounds like something capital market ish coming down the pipe.
I don't like feel of Bango at all. I think its an avoid.
Boku is better and merely very overvalued
"their ID business is real and truly scalable". You know who else does IDs? Facebook, Google, Microsoft. I wouldn't put much store in a tiny player gaining much traction in the ID business unless they have something really niche and unique.
I'm no expert in corporate law amongst my other failings, however I do know that in Europe it's illegal for business entities to cross subsidise each other. So I would've thought writing down a business unit to zero and then transferring it to another part of the business where it immediately generates profit would be highly questionable. Transferring / allowing the use of IP without cross charging licensing fee would also be dodgy.
Next, if they write the Audiens business down to zero, Bango can put a zero offer bid in for it which they would be duty bound to accept. As soon as they say "no we want x $" they've revalued the business.
Maybe I'm naive, but I would've thought that an effective asset theft in this way would be hard to get away with. Easier for them to just play nicely, share the profits, and if it's worth it, just buy out the whole thing at fair market value.
If it works out the way you say, there's no reason for any company ever to become a minority partner in another company.
Boku Inc (LON:BOKU) ID is fairly unique (I've worked with such data from credit reference agencies for prior business I owned)....I don't know if its scalable or desired...they've got lot to prove there and like I said before I think they will probably need to put in accelerated capital to get anywhere and likely underinvesting at the moment (so a bad acquisition so far)
I don't mean that Bango (LON:BGO) will write down JV. I mean that it will be written down overtime by the Korean owners. They'll put development capital into the vehicle but for monetisation the capability will somehow find itself outside the JV...its just what happens....wont be illegal and if it were a bit dodgy will be highly intractable and very costly to enforce some rights for Bango
See my further comments on the absolute mess Bango made with Audiens. Its been costly
...okay...more Bango (LON:BGO) ....as curious went digging...
Here's the acquisition RNS for Audiens : https://polaris.brighterir.com...
Note first that it was combined with a capital raise comfortably ahead of cash they were paying for Audiens.
So they paid £1.3 cash, 520k shares (at the time >200p, so that's £1.1m) and 740k 10yr warrants exercisable at placing price (so c.£1.5m at that time) plus some undisclosed success linked additional consideration payable to Marko Maras in exchange for the 1.55% of Audien shares he still owned.
Holy F! They sold that to NHN just over 1 year later for zero....or really less than zero!
NHN paid nothing for Audiens. They promised $8m investment into a company they now control. There is zero chance that any returns on that investment flow back to Bango as they are committing no further capital or IP for their 40% stake.
NHN got 4.7% stake in Bango for £3.2m (approx 20-25% discount to price at time, ie effectively a £0.7-1.1m payment to NHN), now worth £6.3m at today's market price.
To facilitate this deal they had to pay £1m to gain ownership of remaining shares of Audiens....this if effectively Mr Maras's earn out for his 1.55% stake in Audiens....unless they didn't previously disclose a significant other shareholder (that would be very naughty so assume it Maras).
So altogether Maras (and other prior owners of Audiens) seems to have got £1.3+1.1+1.5+1.0 = £4.9m (assuming the warrants are converted at 200p sometime before 2028)...
...and Bango got zero back! They got an equity stake from NHN but that comes with dilution for shareholders so that is a liability of the company.....it is not payment for Audiens.
They are sleeping partner in JV with big Korean tech firm. What they hell has happened here...and why are you guys hot for Bango?
I flag again:
1) Dodgy RNS last night - https://polaris.brighterir.com...
2) V promotional releases...they'll RNS anything
3) Is Bango Marketplace a likely unstable or unsustainable regulatory arbitrage of payment and data regs...see comments here https://www.stockopedia.com/co... and here https://www.stockopedia.com/co...
Bango looks nose bleed overvalued....and perhaps with some skeletons to come out of closet too....and my hunch (helped along by broker change) is that they will be in market to raise or buy and raise soon.
DYOR
mojo
I note you didn't actually address any of the points in my reply and then posted a load of FUD.
So NHN, pumped in $8m + took £4.9m, of outstanding liability so what's that value the company at the time? ~ £11m of which Bango own 40%, so 4.4m or so and they got a massive uplift in technical capability and marketing with a well funded partner at zero cost - it's all gravy. But you claim they got less than nothing,
You're welcome to your opinion, it's what makes a market :) I think you're wrong.
My apologies for FUDing you...it wasn’t really a message to you but general analysis .
But I have answered your questions. Fine you disagree. I’m right obvs ;)
FUD is Fear, Uncertainty, Doubt :) I know it wasn't aimed at me personally
I grew up in Aberdeen and it means something very different there...
https://www.urbandictionary.co...
Obvs I didn't take it like that.
On your points re JVs you are of course correct. Take explorer that partners with major to fund and/or develop resource find. Or a biz that provides service or tech to (usually) bigger partner that has flow and can be metered in some way. These are quite measurable and engaged relationships. But early stage IP and tech that has minimal traction that is entirely operationally passed over to new player to develop....this is what is wrong with the JV...why would NHN do anything other than have it as a 'sink' to put some form of accounting loss or R&D supplement into (whatever Korean rules are) and then make sure the IP pops out somewhere else in the NHN relative behemoth. Bango (LON:BGO) have 40% but its entirely passive with no ongoing contribution from them.
The rest of the deal around acquiring Audiens and selling it sits somewhere on spectrum of desperate->cover for 2 fund raises->incompetent->iffy....but hey earnings share delivered from NHN will prove me wrong. I bet they don't arise in next couple of years (heavy investment at moment) and the JV disappears into long grass over few years...
My interest in Bango was really as a reference to Boku Inc (LON:BOKU) and today is first time I've paid close attention to some of the details (previously looking more at the tech and biz model)
My morning smallcap tweet: WEY to go
Bango (LON:BGO) Hostelworld (LON:HSW) Renold (LON:RNO) Sosandar (LON:SOS) 1Spatial (LON:SPA) Nightcap (LON:NGHT) TP (LON:TPG) Wey Education (LON:WEY) Touchstar (LON:TST) STV (LON:STVG) M Winkworth (LON:WINK) Charles Stanley (LON:CAY) Octagonal (LON:OCT), Allergy Therapeutics (LON:AGY), Real Good Food (LON:RGD), Ab Dynamics (LON:ABDP)
Bango (BGO) guides FY(Dec) rev-cont £12.2m, up 70%, ahead of expectations (whose?). Adj EBITDA over £4m (£0.45m). [SP=166 Cap=124m]
Hostelworld (HSW) guides FY(Dec) net bookings in line. Looking at debt and equity options, to secure long-term financial position. Talks with lenders in relation to a new €30m debt facility at a mid-teens int rate. [SP=79 Cap=92m]
Renold (RNO) guides H2(Mar) adj op profit broadly similar to H1 as orders recover. [SP=12.65 Cap=29m]
Sosandar (SOS) Q to Dec rev up 6% with marketing down 66%. EBITDA loss down c.60%. Dec rev significantly better than anticipated given 90% cut in marketing. Returns rate 46% (49%) due to change in product mix. "Following growth in the customer database through autumn, the Company is well placed to successfully navigate the next few months." [SP=18.65 Cap=36m]
1Spatial (SPA) wins $0.6m two year US contract for the 1Integrate and 1Data Gateway SaaS service. [SP=27.35 Cap=30m]
Nightcap (NGHT) starts trading on AIM. IPO funds used to buy (rescue?) related-party London Cocktail Club. Aims to become the UK's leading bar group. Really? Might be the drink talking. [SP=NA Cap=NA]
TP Group (TPG) has received expressions of interest for the Maritime Engineering business. Disposal would be in-line with strategy. [SP=6.2 Cap=48m]
Wey Education (WEY) guides FY(Aug) rev and profit market forecasts as firs 4 months are significantly ahead of budget and market expectations. Co will now charge VAT to its UK InterHigh clients. Will smooth price rise for clients. [SP=35.8 Cap=50m]. I hold.
Touchstar (TST) guides a FY(Dec) profit with strong cashflow. Net cash £1.6m but no other numbers. [SP=50 Cap=4m]
STV (STVG) guides FY(Dec) op profit comfortably ahead of market expectations, driven by a stronger than expected regional and digital performance. Net debt significantly better than market expectations. [SP=300 Cap=140m]
Winkworth (WINK) guides FY(Dec) rev broadly flat, pretax down (to what?). FY div cut 15%. [SP=150 Cap=18m]
Charles Stanley (CAY) FuMA end Dec up 10% over the Q. Rev down 1% over Q. [SP=300 Cap=156m]
Octagonal (OCT) H1: "trading continues in line with the board's expectations, the result for the year may be impacted by any effect of the recently announced SEC complaint against GIS in the US, the outcome of which cannot yet be determined with any certainty. " [SP=0.84 Cap=6m]
In line: Allergy Therapeutics (LON:AGY) Real Good Food (LON:RGD) Ab Dynamics (LON:ABDP)
Frontier Developments (LON:FDEV) trading statement this morning is a confusing mash up which I interpret as inline for FY21 although it's billed as being ahead. It starts with this: "Trading in the current financial year to date is ahead of the Board's original expectations" which seems clear enough. Also clear is this: "Trading in the first six months of the current financial year ('H1 FY21' - 1 June 2020 to 30 November 2020) was in-line with expectations". So I'm thinking that H2 is ahead but wait.. "Sales across all our games in FY21 to date have been consistent with expectations after a strong close to FY20". So is it ahead or inline? It must be ahead because they say this: "Revenue in December, ... ahead of expectations" and then this: "As a result, trading in the current financial year to date is ahead of the Board's original expectations." OK good so that's all clear now - they are definitely ahead right? Not so fast, because then we have: "based on all currently available information the Board's projections for FY21 remain in-line with the previously guided revenue range of £90 million to £95 million". So it's inline after all. All clear now then. Oh and I make it a forward P/E of around 54 on FY22 estimates so my eyes are watering now. I hold but perhaps not for much longer.
I agree it seems poorly written. But the key word there is “original” expectations. So, I expect they’re beating what they forecast at the start of the FY but they’ve revised the expectations since.
But it absolutely highlights the point often made by Paul, if you’re going to be talking about “expectations” then you need to state clearly and simply what those expectations are. “Management expectations” with no numbers are just waffle. “Words are wind” as they say in Game of Thrones.
Re Quartix & 3G mobile networks. There is a general trend to switch off 3G networks at mobile operators now 4G is well established and 5G is starting to be rolled out in limited forms. You'll see if happening more and more over the next three to five years. 2G networks are expected to be kept for quite a bit longer.
Seemingly positive trading update from £WEY. But they've suddenly decided/realised that they need to charge clients VAT in the UK. I think this is bound to have a big effect on margins (if they have to lower their prices to make up some of the difference) or lose them customers if prices to clients go up significantly.
"Seemingly positive trading update from Wey Education (LON:WEY) . But they've suddenly decided/realised that they need to charge clients VAT in the UK. I think this is bound to have a big effect on margins (if they have to lower their prices to make up some of the difference) or lose them customers if prices to clients go up significantly."
Or pay retrospective VAT? Unfortuantely they don't detail why they suddenly belive they need to charge VAT or whether they now realise they should have been charging VAT historically. No idea how material this is to Wey Education (LON:WEY) as a whole, if at all, but Wey Education (LON:WEY) could certainly have been a lot clearer. This sort of RNS lack of clarity is why I sold... ...not a great decision given the subsequent SP rise.
I was turned off WEY when I watched a recent results presentation. The chairmen twice went on about the 'overhead' (or something similar), of being on AIM and said something about looking forward to being able to get back to running the business when the rounds of presentations of the results was over.
With an attitude like that to reporting results to shareholders, I was not interested further. It felt it was being run for the benefit of the mgt, and other shareholders were a nuisance.
Indeed. The y could have put a statement that reassured no historical Vat liability. But they didn't.
And digging around, I don't see any government change in Vat announced over the last few months, so it's not a new VAT policy driving this behaviour.
Charging 20% extra is a hit. Their clients aren't rich families looking for top end private education. Many are forced to go Interhigh because their kids can't fit into the state school system.
re Wey Education (LON:WEY), the report gives the impression that this is a voluntary choice on their part as otherwise they couldn't pay dividends. I am no tax expert but I thought that school fees were currently exempt from VAT, in which case the change is unlikely to be retrospective. The increase to customers would be a lot less than 20%, since changing from exempt to chargeable means they will reclaim their input VAT. Still, there must be a significant hike in fees. (I don't hold, and am neutral on Wey Education (LON:WEY).)
Good morning Paul, just a quick heads-up as I know you have a penchant for 'late night venue' businesses.
Have you seen the imminent listing to AIM of Nightcap £NGHT http://nightcapplc.com/
Consists mostly of the London Cocktail Club, albeit they are looking to raise capital to take advantage of the current environment, targeting 'millennials'. Either a strange or genius time to list imho.
I don't have time to read through the admission doc but it's here if you are interested...
http://nightcapplc.com/wp-content/uploads/2021/01/admission-document.pdf
If you want to know more, I suggest reaching out to the management team. I rate the CFO highly (and he's an amiable chap) and my interest has been peaked by the fact he's just come on board, so must rate the market opportunity highly. My starting assumption would be that they are putting a over-qualified management team in place vs the size of the business as a demonstration of their growth ambitions.
The video they put out as part of the offer was both compelling and entertaining:
https://primarybidassets.s3.eu...
but I decided not to take it up.
Dear Tom W. has some insightful and inciteful things to say about Nightcap. You will probably need to pay for it, but a month's subscription is a negligible cost, and I vaguely remember that he has a price for one day's access. https://www.shareprophets.com/... There are accusations of bankruptcy, related party deals, missing information, deception... Tom Winnifrith is very good on the sell side.
I wouldn’t give Mr W. the proverbial steam let alone actual cash.
Whether you like the guy or not (Tom W) some of the forensic examination of companies accounts has turned up some scary analysis. There were enough red flags in their analysis that I wouldn't touch it, but everyone needs to form their own opinion.
Nor would I. Remember tips.com?
I do - seriously awful
Just had a skim through of the Nightcap (LON:NGHT) admissions document.
- Lots of related party transactions
- CEO with over 30% of the overall shares at admission? For creating a shell company and coming up with the idea of acquiring London Cocktail Club?
- Very low free float at listing. Concert Parties holding 74%. Will make it difficult to buy/sell without a wide spread.
- £5.7m valuation for 10 bars...!
- No reduction in rents negotiated prior to acquisition. 3 sites have agreed to waive/reduce accumulated rent up until now. Another 3 sites negotiating waiving/reduction. 4 sites not playing ball at all.
- 9 million options granted to CEO and CFO already. Up to another 15m share options for management performance to be granted. That's a lot of options.
- Positive is that existing shareholders of London Cocktail Club getting their consideration entirely in shares of Nightcap, so they need it to work as well. But maybe LCC was worth almost nothing so shares in a new IPO is still better than nothing...