Small Cap Value Report (Weds 14 April 2021) - RNO, WJG, KOO, FOXT, TMG

Good morning, Paul & Jack here, with the SCVR for Wednesday.
In case you missed it, I added some additional sections to yesterday's SCVR in the afternoon. So here's yesterday's full report.
Timing - TBC - probably early to mid afternoon finish time today, as there's a fair bit to get through.
Agenda -
Paul -
Renold (LON:RNO) (I hold) - in line trading update for FY 03/2021. Order intake recovered, and has ended the year up. Renold has proven itself to be resilient in FY 03/2021, and net debt greatly reduced. Big pension deficit though, which sucks out £5m p.a., hence why market cap is so low. Too low, in my opinion.
Watkin Jones (LON:WJG) (I hold) - I go into quite a bit of detail on the business model (which I think is very good). An in line update for the half year to 31 March 2021. Judging from the company's previous results presentation slides, I think existing forecasts look far too conservative, because there's a big pipeline of Build To Rent projects for the next 3 years. One for long-term investors, not punters!
Kooth (LON:KOO) - readers have flagged this one, in the comments section below. It's speculative, and I don't think I can add any value by crunching the numbers in detail, as it's still loss-making. Hence I won't write up a full section on it, instead having replied in the comments below, and several subscribers have written up interesting posts about it below, so this note here is to draw your attention to the comments section below. I'll add a tag for KOO so that we can search and find this post easily in future. Thanks to all.
Foxtons (LON:FOXT) - upbeat Q1 trading update. (For the avoidance of doubt, I no longer hold this share personally).
Jack -
Mission (LON:TMG) - Improving results for this cyclical marketing small cap. Negative NTAV but net debt is down and the pipeline is strengthening.
.
Paul’s Section
Renold (LON:RNO)
(I hold)
21.8p (pre market open) - mkt cap £47m
Renold, a leading international supplier of industrial chains and related power transmission products, today issues a trading update covering the year ended 31 March 2021 (the "Year"), ahead of the preliminary results announcement for the Year on 8 June 2021, together with the completion of a small bolt on acquisition in the UK.
Acquisition - very small, but Renold is paying a maximum of £0.6m, to bolt on £0.2m p.a. additional operating profit. Small, but good! Apparently the industrial chains market is very fragmented, so Renold could become a consolidator (or a bid target itself).
Trading overall - is in line with expectations -
The recovery in both order intake and revenues has continued and trading for the Year has been in line with the Board's revised expectations, as announced in the Company's trading update on 13 January 2021.
Checking my notes here from 14 Jan 2021, Renold said that it expected H2 adj operating profit should be “broadly similar” to H1. H1 saw a £5.8m adj op profit, so double that, and we get £11.6m for the FY 03/2021.
Revenues - down 12.7% on last year, to £165.3m. This is split £81.5m in H1, and £83.8m in H2. Trading improved (a little) as the year went on. It mentions supply constraints today -
Trading improved in the latter part of the Year and Group revenue in Q4 was behind the prior year by 8.3% (5.6% at constant exchange rates), being held back in the short term by constraints on global supply chains emerging from the pandemic.
Last year’s supply constraints could be this year’s catch up sales, so I’m not bothered about this.
Order intake - as with so many companies, Renold took an initial hit from covid/lockdown, and has been gradually recovering. As results are in line with expectations, the only number that matters, is the closing order book -
... the order book at 31 March 2021 of £53.6m was 3.6% ahead of the prior year figure (9.3% at constant exchange rates).
Note that currency changes are having quite a big impact, we haven’t seen that for a while, so expect to see this at other companies trading internationally.
Order intake for the whole of FY 03/2021 was down 7.4% - not bad considering what a disrupted year everybody has experienced. An interesting point that management made when I spoke to them a while back, is that the industrial chains made by Renold are essential items, usually bought on a planned maintenance basis by clients. I.e. the chains have to be replaced, or the often large & expensive equipment using them, is at risk of failure. Renold is a very well regarded, high quality brand name, and can charge up to 5 times what competitors charge, due to the high quality & reliability of its products, often used in mission-critical machinery.
A large part of Renold’s business is repeating business, and hence it’s not as cyclical (hence vulnerable) as some other businesses in economic downturns.
I think the stock market has not recognised this resilience of Renold’s business model. Maybe it will in future?
Interim results to 30 Sept 2020, during the worst initial shock from covid, were also resilient, with adj operating profit of £5.8m for the 6 months, down 25%. Note that profit is stated after a large depreciation charge of £5.2m (for 6 months), so EBITDA was a hefty £11.0m in H1, and will be similar in H2. That’s a nicely cash generative business, which has been steadily modernising its fixed assets in recent years.
Net debt - greatly reduced -
During the Year, cash generation outperformed initial expectations, as a strong focus on cash management resulted in a c.50% reduction of net debt to £18.4m (2020: £36.6m).
Diary date - 8 June 2021 for the FY 03/2021 results.
My opinion - so far, so good. I’ve held this share for a while now, and added to my position after the solid trading update in Jan 2021. The reason this share is so cheap, is due to the large pension deficit, which sucks out c.£5m p.a. in cash recovery payments.
My hope is that higher bond yields might lead to a reduction in the deficit, but nobody really knows with pension deficits, because there are many moving parts.
A friend emailed me over the weekend, to say that, for the first time in ages, the (monthly reported) transfer value of his defined benefit pension scheme reduced sharply. This made him ponder whether there was a wider move afoot, for pension deficits to start falling (due to pension scheme liabilities being discounted more heavily with higher bond yields). Do we have any pensions experts in the house, who might be able to comment on that?
Renold shares are really a geared bet on two things -
- Continued efficiency improvements from a long-running turnaround plan - a previous broker note indicated that another round of restructuring in 2021 could deliver higher operating margins - if so that would feed through to equity, leaving the pension deficit unchanged (which accounts for most of the enterprise value effectively).
- Pension scheme cash outflows reducing over time, leaving more of the (hopefully increasing) profits for equity holders, in cluding a resumption of dividends.
In terms of valuation, the market cap of £47m is extremely low, for a business making over £20m p.a. EBITDA, with that forecast to increase further as more restructuring occurs this year.
The closing order book is now up on last year, after a good intake in Q4, suggesting that FY 03/2022 profits could increase on FY 03/2021.
We’re in the dark somewhat, because there’s no broker research available to private investors. I’ve mentioned to the company that they need to get the message out there to PIs, who are the people who create the liquidity & set the share price.
The two steps needed to raise awareness about what a decent business this is, are broker notes being made publicly available, and doing some results presentations. I’ve suggested that the company starts doing results webinars for PIs, and appoints a broker that publishes its research on Research Tree, where we can get hold of it.
There’s a lot to like about Renold, with a strong underlying business, obscured by a large pension deficit. If management can further improve the operating margin, which is their plan, then the payments into the pension scheme would become less onerous, which would lead to a re-rating of the shares.
I suspect Renold could be attractive to an overseas bidder, e.g. from America.
I appreciate that historically Renold has not covered itself in glory, hence why there seems a generally negative perception about the business with investors. In my view that's changing, and the company has an increasingly interesting investment proposition. It got through covid, and has service the pension deficit for years, all without any dilution for shareholders.
The StockRank sums it up nicely - a medium quality business, with good earnings & share price momentum, which is dirt cheap! (although the pension deficit is partly the cause of that cheapness).
.

.
Watkin Jones (LON:WJG)
(I hold)
230p (up <1%, at 08:50) - mkt cap £587m
Too big? - the market cap has been going up of late, but I really like this company, so it would be a pity to stop covering it. That’s the problem with a small caps report - if we stick to a market cap limit, then we stop covering the best companies as they grow too big, and keep reporting on the laggards, which doesn’t make a lot of sense, does it?! Hence why I like to continue covering good companies that grow in size, for a while anyway.
Preamble - What I like about WJG’s business model is that it’s a construction company with a difference - it pre-sells building projects (typically student accommodation blocks, but also a growing “build to let” housing division) to institutional investors (e.g. pension funds that want inflation-protected long-term future income streams, to match their liabilities). This locks in WJG’s profit margin on each build project, before it’s even built, and means there’s very little balance sheet risk. That’s a really nice business model.
The reason I jumped in and bought some shares personally a while back, was that, although I found the valuation a little warm, the last webinar showed that the contracted pipeline was already in place for a substantial increase in profitability over the next few years.
My last point, is that WJG has a great track record, and seems able to manage big construction projects on time, and on budget. The company seems to have a niche specialism, and great relationships with institutional investors. There’s limited competition in this space (hence good margins), and considerable barriers to entry - smaller building companies are effectively locked out of this sector, as institutions won’t take the risk of them going bust, or messing up the build. Whereas WJG has the reputation, track record, and balance sheet strength, to be a very credible partner to large institutions.
The student blocks that WJG builds look like office blocks. They’ve built a couple near where I live, and I was amazed at how fast they go up, with a steel frame, and quite high (one is about 14 stories).
The only bear case I can think of, is that founder/management made very large disposals of shares. Although they remain big shareholders.
Watkin Jones plc (AIM:WJG), the UK's leading developer and manager of residential for rent, with a focus on the build to rent ('BtR') and purpose built student accommodation ('PBSA') sectors, provides the following trading update for the half year ended 31 March 2021 (the 'period' or 'H1-2021').
'Maintaining momentum as the economy reopens'
H1 trading - this looks OK, it’s in line -
"We anticipate our profit for the first half of the year to be in line with our expectations and slightly below last year, which was before the onset of the disruption caused by the pandemic.
Other points mentioned -
- Covid curtailment is “beginning to restore some normality and confidence to the UK economy and our market sectors. “
- “Further good progress in securing new forward sales, adding to our development pipeline”
- “Construction activities all on track”
Outlook -
"The fundamentals supporting the markets for high quality build to rent and student accommodation assets remain strong and with the continued progress we have made in the first half of the year, gives us confidence in our future trading."
Liquidity - looks fine -
Good half year liquidity position, with gross cash of c.£88.0 million (H1-2020: £72.4 million) and net cash of c.£31.0 million (H1-2020: £37.5 million), after deducting site specific loans.
Director retirements - both the Chairman and CEO CFO are planning to retire which might introduce some risk possibly? Non-Exec Chairmen are not really important, so I’m not worried about that change.
EDIT: Thanks to Martin for pointing out an error, I incorrectly typed CEO above, instead of CFO. Sorry about that. I've corrected the error. End of edit.
Valuation - as we’ve just had an inline update, then we should be able to rely on the company achieving the broker consensus numbers. As you can see below, despite recent rises, this share remains good value, and there’s quite a good divi yield too. I think this share deserves a higher rating than, say a standard housebuilder, because it has a superior, less cyclical, lower risk business model in my opinion.
Also note the high return on capital & equity in the quality scores -
.

.
Note that WJG did not need to raise any new share capital in the pandemic, so it’s a resilient business. There’s hardly been any dilution in the last 6 years, one of the benefits of investing in a family owner-managed business - they tend to be very protective of existing shareholders, reluctant to issue new shares, and run the finances more conservatively than hired hands might do.
Broker forecasts, as you can see from the graph below, estimates have been reduced. This doesn’t seem to tie in with the more upbeat outlook I recall from the company’s last webinar, which seemed to show earnings poised to rise about 50%, from the existing pipeline. Maybe that was over a longer timeframe?
.

.
Pipeline - ah yes, I’ve found the presentation slides on the company’s website. These are a little old now, from Jan 2021, but show the pipeline graphically.
The full slide deck is here. Which gives a very nice detailed view of the company (45 slides). Well worth a look.
Slide 25 below, shows how the pipeline gradually progresses from being in negotiation, to legals, to requiring planning permission, to planning permission granted, to forward sold. It’s a nice visual summary of the purpose built student accommodation division (PBSA) - the biggest division.
.

.
Clearly there will always be a risk that one or more large projects could go wrong, or be delayed, so not an entirely risk-free business model.
That’s all good, and shows that c.£300m p.a. revenues look to be fairly secure.
What interests me more, and the reason I bought shares personally, is that strong growth is coming through (subject to planning) from the Build To Rent (BTR) division. Check out these numbers, from slide 26 below. It’s set to grow from only a small part of the business, to a similar size as the main division, by 2023.
That should drive a big increase in earnings, and hence share price. This is what’s particularly interesting about this share.
.

.
My opinion - there’s a lot more detail in the update today, about various projects, but I’m only really interested in the overview, which is: results in line, and confident outlook. So for my purposes, that’s enough.
It’s the rapid growth in pipeline, for the Build To Rent division, that makes this share interesting. It’s already good value, but there’s a clear, measurable, catalyst here to expect future earnings to rise strongly - if all goes well, of course nothing is ever guaranteed, nobody can predict the future with certainty, same with all shares.
We’re all making loads of money at the moment, because everything is going up. But are the foundations solid enough to last? I don’t think so. We’re seeing pockets of mania developing in lots of speculative areas, and the parallels with 1998-9 are vivid, in my view.
It’s great that people are making money, and I hope they manage to bank the profits before the most speculative shares crash, as they always do, eventually.
My preference is to focus on shares where I can see that the fundamentals fully support a higher share price. I’m not comfortable to rely on ever-increasing market euphoria to keep taking share prices up. There has to be a measurable reason why the share price is highly likely to keep going up, even if speculative shares do crash.
Hopefully I’ve demonstrated above, with the pipeline information, that it’s very easy to forecast that WJG should see a considerable rise in earnings over the next 3 years.
There’s no guesswork, or hope, involved (well apart from hoping they get planning permission).
For that reason, this share is in my coffee can portfolio. I think it’s a nice long-term hold, due to the earnings being likely to grow strongly, and it’s also paying out decent divis along the way because it has a capital-light business model.
As always, I have absolutely no idea what the short term share price is likely to do, I cannot predict that. I’m only interested in where the fundamentals are in 2-3 years time, and that should in theory drive a higher share price then, compared with now.
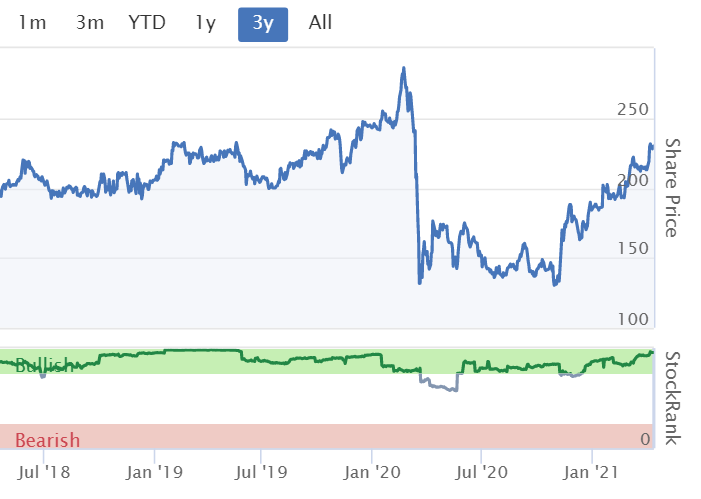
An encouraging chart below, I think the recovery from the covid crash is justified by the fundamentals & good pipeline. Note also the consistently strong StockRank, which I find a reassuring backup to my own research. Neither are infallible of course, because buying shares is all educated guesswork to a large extent!
.
.
Kooth (LON:KOO)
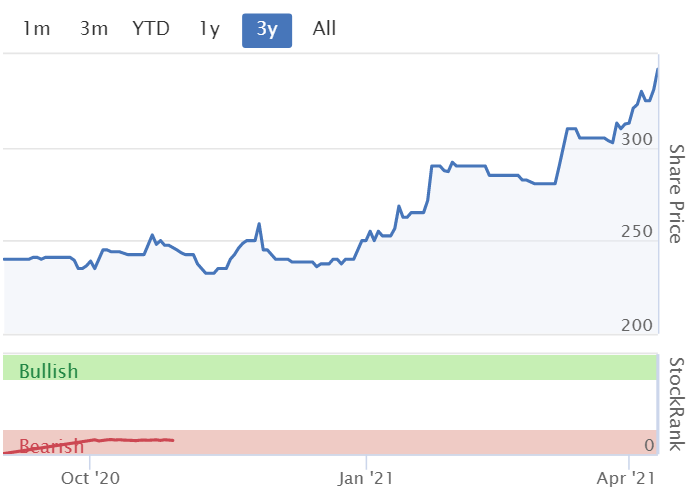
Please see the comment section below, for an interesting discussion about this mental health app company, which floated last year. Looks speculative, and difficult to value, but I like the concept. Potentially interesting as a bull market punt! It's got meaningful revenues too, recurring, so it's a proper company, and has contracts with the overloaded NHS. Just not profitable yet, and difficult to value.
.
.
Foxtons (LON:FOXT)
(I no longer hold)
66p (down 1%) - mkt cap £216m
For transparency, I sold my position in Foxtons recently, on a portfolio review, mainly on valuation grounds, as it no longer looks particularly cheap to me. Carefully looking through all my positions (there are about 50 in total), questioning whether the last 6 months price rises in many of them were justified by the fundamentals. Rightly or wrongly, my decision was to bank profits in both FOXT and GATC, both smallish positions, to free up cash for things where I see more upside potential.
Foxtons Group plc (LSE: FOXT), London's leading estate agency, issues the following trading update for the quarter ended 31 March 2021.
- Q1 2021 has started well
- Strong Q1 revenue growth - up 24% on LY, to £28.5m
- Rents in London have declined by about 12%, offset by increased volumes - so flat organic revenues
- Acquisition of Douglas & Gordon lettings business contributed £1m extra revenues, being all of the overall 6% rise in lettings revenues to £14.8m
- House sales commission revenues up 60% in total, 49% organic, 11% acquisition
- Materially higher level of properties exchanging contracts
- Sales pipeline has continued to grow
- Mortgage broking revenue up 20% to £2.3m
That all sounds pretty good. It’s must be, at least partly, driven by Govt stimulus, with the stamp duty holiday.
Liquidity - Foxtons remains in a healthy net cash position, having cleared its bank debt last year with a placing.
The Group's net cash position, excluding lease liabilities, at 31 March 2021 was £22.3m after the £14.25m acquisition of Douglas & Gordon.
Boomin - is the name of a property listings portal that FOXT has invested £3m into. I’ve had a quick look at it, and it’s not clear what the point of difference this has to other property portals, other than it looks nice. FOXT are experts in their field though, so they must see something good here, to have invested £3m in it. For what % stake I wonder? This could be an interesting wild card - not too much damage if it fails, big upside if it works maybe?
Outlook - this sounds good -
As we look forward, the strong trading momentum is expected to continue through the second quarter and together with tight cost control gives us confidence that operating profit for the first half will be significantly higher than last year".
My opinion - neutral. I can’t find any broker research, so it’s difficult to know how to value this share. I’m quite optimistic about London coming back to life, and hence people will always want to live & work there, in my view.
Foxtons should return to profitability, but at what level? It’s difficult to say, and with no broker research available to guide me, it would be mostly guesswork. For that reason, it’s difficult to work out if the £216m market cap is reasonable or not.
.
Jack’s section
Mission Group (LON:TMG)
Share price: 87.5p (pre-open)
Shares in issue: 89,028,484
Market cap: £77.9m
We’ve seen quite a lot of small cap cyclical share prices rallying ahead of lockdowns lifting, and it looks like Mission (LON:TMG) is no different as it is more or less back to all-time highs.

This is a UK-based marketing communications and advertising company, with segments including Branding, Advertising and Digital; Media; Events and Learning, and Public Relations. Subsidiaries include April Six Ltd, which is engaged in marketing communications and specializes in the technology sector; Big Dog Agency Ltd, which is engaged in Marketing communications, Speed Communications Agency Ltd, which is engaged in public relations, and Bray Leino Ltd, which is engaged in advertising, media buying, digital marketing, events and training, among others.
What’s interesting here is that Mission appears to still offer good value even at these levels, and the Ranks are quite strong across the board. So if you did think you’ve missed the rerating here, it’s worth quickly reexamining that.

Highlights:
- Revenue -24% to £61.5m,
- Operating profit -82% to £1.9m,
- Headline profit before tax -88% to £1.2m; reported loss of £2.1m
- Diluted earnings per share -89% to 1p
Results have been improving sequentially, with losses in the first half but notably better results in H2, and cash conservation measures mean the group ended the year with net bank debt down from £4.9m to £1.2m.
Client retention remained strong, with well over 50% of revenues generated from Clients of five years or more with a useful amount of business coming from more resilient sectors like healthcare and technology.
Mission also completed the acquisitions of Innovationbubble, the psychological insights and behavioural solutions consultancy, and brand activation consultancy, ALIVE.
And the outlook is positive, with trading in the first quarter of FY21 in line with the group’s expectations and a ‘robust and growing’ pipeline of new business opportunities. Removal of uncertainty around Brexit negotiations also opens up further opportunities across international markets.
Conclusion
To achieve profitability whilst at the same time reducing debt is good, all things considered. And this is a marketing agency, so caution is required in interpreting the commentary, but it does sound like things are picking up.
In the medium term, Mission is focussed on leveraging infrastructure by adding high margin, high engagement capabilities in data, analytics, and performance media. It has set a 14% margin target by 2022, which would be a big improvement on the historical average of between 4-5%.

At the height of uncertainty in Q2, the Group deferred roughly £6m of VAT, PAYE and National Insurance taxes. All deferred PAYE and National Insurance was repaid in Q3 and all deferred VAT has been repaid in Q1 2021.
However some 65% of total assets are composed of goodwill and this proportion has increased over the year. That means the group actually has negative net tangible assets of £6m.
The group is quite cash generative, at least.

The key balance sheet ratio measured and monitored by the board is the ratio of debt to headline EBITDA ("leverage ratio"). The group started the year in a strong financial position, with a bank debt leverage ratio of less than x0.5 and committed bank facilities of £15m.
I note the spate of director sells in February of this year... But even accounting for that it looks like management retains a decent stake in the business. Still something to be aware of though.

Mission looks worth investigating as a riskier cyclical small cap that could continue to rebound, although I’d like to see a further strengthening of the balance sheet.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

73 comments
Kooth (LON:KOO)
Few points:
Colour me sceptical that mental health as a service has very good scaling in economics. I think the costs will always run high relative to the revenue. I do not doubt that it can be a useful and innovative service that has medical scaling ability that is attractive.
This could work but I think I'll get the chance to see more at a price similar or less than quite racy current on a more mature business with a clearer reveal on underlying economics.
Saga (LON:SAGA) (I hold) - nice little update from Travel Week, saying that 4 out of 5 of Saga's inaugural round-UK cruises, sold out in c.2 weeks of being announced.
https://travelweekly.co.uk/new...
Here are my SCVR heat maps for today (prices as at ~12:45pm).
I share these heatmaps with the intention of giving a visual indication of what is going on in the SCVR world: who’s reporting (and it's impact on the share price); and what’s moving more than 'normal'. There are no associated recommendations, implied or otherwise, just information. How, or indeed if, you choose to use that information is up to you.
Please read my [heat map thread] for keys to the heat maps contents, more (non-SCVR specific) heat maps, and an explanation of how I use heatmaps to guide me with my research.
I have added a MarCap category to the heat maps, along with a high spread indicator. The key to the symbol heat maps is now:
As an experiment, I've sorted the heatmaps alphabetically by EPIC today. Which I'm hoping will make it easier to find a particular instrument in the heatmaps.
Small / Micro Caps reporting today:
Big movers today in the SCVR world (moving more than a 20d EMA of the ATR against either yesterdays close, or today's open):
Warm regards, stay safe, and best of luck!
greensiax
Paul writes "if we stick to a market cap limit, then we stop covering the best companies as they grow too big, and keep reporting on the laggards, which doesn’t make a lot of sense, does it?!"
Excellent point. Novices often grab a profit on a stock and keep the ones they are down on....so end up with a portfolio of losers. There are a number of tiny stocks a year ago that are now well over the limit.
Personally I don't care on the size. If a stock is cheap I want to hear about it. What is a "small cap" anyway? A previous large cap that has blown most of its investors cash? How about changing the idea to something like "value report" and letting the writers just report on any undervalued stock that they want to at their discretion?
Your comment on Watkin Jones (LON:WJG) hits the nail on the head. I've got a sizeable investment in #RMMC, a microcap fund, which has done very well. It's top 10 holdings include companies such as Science In Sport (LON:SIS), Joules (LON:JOUL), £AQY and £MXCT. But due to rebalancing all the time, it is a constant seller of MXCT. Had it simply held onto it, that would now be 30-40% of its market cap, and performance would have been (even) better.
RMMC has a very clever feature where it has a compulsory redemption so that its NAV doesn't exceed £100m by too much, so it can continually focus on the best microcap ideas. But as you say about WJG, an investment doesn't change just because the size of the company goes past an arbitrary level. That's a constant challenge for those of us with big winners, though the last few years have, at least, disproved the theory that elephants don't gallop.
Hi Jack, Paul and others
In the 8th October 2020 SCVR Jack covered Newriver Reit (LON:NRR) recoding the share price as 56p, market cap £35.3m (it has also been covered in several earlier SCVRs by Paul) .
As I write it's share price is 106.69. A rise of 50.69p, +90.52% in 7 months. Market cap now £316.71m.
Newriver Reit (LON:NRR) 's TU and strategy update today seems to me quite positive in that their rentals achieved seem quite strong given the circumstances they faced (as did all retail). They explain ......
'Our retail occupancy at 31 March 2021 remained high at 95.8% (March 2020: 94.8%) as a result of our sustained leasing momentum. In the fourth quarter we completed 360,500 sq ft of new lettings and renewals, representing £2.5 million of rent, exceeding the 188,100 sq ft completed in the fourth quarter of FY20. Long-term deals were signed at a 5.7% premium to ERV and a 3.7% premium to previous passing rent. These included two significant deals totalling over 32,000 sq ft with Instant Offices, a flexible office provider, in our shopping centres in Cardiff and Bexleyheath.
Our retail portfolio remains well-diversified, with our top five tenants, Poundland, Superdrug, B&M, Wilko and Boots representing 9% of our gross income at 31 March 2021. Our average rent remains affordable at £11.51 per sq ft (March 2020: £12.66 per sq ft).'
They are now planning an IPO of their Hawthorn pub chain (which achieved a few industry awards) which ought to add to their cash pile. They are then going to focus towards 'essential retail' (such as the example tenants above).
They write ....
'Reflecting our focus on essential retail, approximately 54% of our occupiers by gross income remained open and trading during the fourth quarter, despite the current lockdown restrictions across the UK. This includes eight of our top 10 occupiers by gross income. This figure has risen rapidly this week to 82% (89% in England), following the opening of non-essential stores in England from 12 April.'
Their yield on Stocko is over 9% (on HL over 15%).
Given the easing of Covid restrictions I think Newriver Reit (LON:NRR) could be quite attractive as a value play and/or an income play.
This is link to the TU for those interested.
https://www.investegate.co.uk/...
Their chart seems to be pretty good since the Covid fall, albeit with a bit of volatility which seems to be reducing.
Disclosure: I did short-term trades in June 20 but waited out until Dec 20 doing another rapid trade. Now I'm in for a longer term from 23/02/21 as the share now seems to be heading upwards.
Regards
Howard
Hi Paul. Maybe a little off the radar today but I've been watching Paypoint (LON:PAY) for some time. It looks like there was a significant seller in the market suppressing the share price until recently. However the share price is now rising steadily. If it reaches 675p then Paypoint (LON:PAY) will have completed a 9 month head and shoulders bottom stretching back to June 2020.
Paypoint (LON:PAY) should benefit from the UK opening up and indeed has said it is now focusing on the profitable UK market. On this basis I'm increasing my holding. I'd be interested to see if the team agree?
hi Revs8
I'm no witch doctor chartist but I hope you meant an 'inverse H&S' for paypoint £PAY as it usually indicates (reliably) a trend reversal. I hold.
Hi Revs8
Paypoint (LON:PAY) as an ex holder - it has this to contend with - hence the cheapish valuation
https://www.ofgem.gov.uk/publi...
Morning all,
"We’re all making loads of money at the moment, because everything is going up".
Most of my portfolio seems to be heading South this week , conversely!!
Regards.
Just wanted to say thanks to Paul for the brilliant WJG update, great detail from their recent presentations to provide more context around the trading update, cheers
Hi Lridly456,
Many thanks, much appreciated.
I do like to delve into more detail on the most interesting companies reporting each day, rather than doing superficial updates over lots of boring, ordinary updates. Hopefully it adds more value that way.
Best wishes, Paul.
How can Audioboom only score in the 60s for momentum? Seems to be
I notice that Paul states in his piece that the Chairman is planning to retire, but also the CEO, this is incorrect, it’s CFO who is (also) looking to retire.
Hi MartinVT,
Thanks for pointing out my error, I must have read the RNS incorrectly in haste. As you say, it does clearly state that the Chairman & the CFO are retiring, and not the CEO as I mistakenly said.
I'll correct my error straight away, and am grateful you pointed it out, as clearly a CFO retiring is far less of a worry than the CEO retiring!
Apologies to all for this error.
Best wishes, Paul.
A very strange update from Vianet (LON:VNET) this morning.
You have to read all the way down to the last sentence before they use the word exciting.
Also it was one of those annoying trading updates. Why do companies like to be coy and not just come out with some numbers, even a range?
In any case, Vianet (LON:VNET) has been on my watchlist for a while as a beneficiary from COVID reopening.
But for me I still have big questions on how much faster their Smart Zone install base decreased in FY21. It was already in decline pre-COVID, but obviously pub sector taking a big hit over the past year. How many more closed up, or can't afford now to upgrade?
Meanwhile Smart Machine install growth slowing, which was meant to replace the declining Smart Zone revenues. Will they recover, or the new flexible WFH means less viable vending sites going forwards?
Annoyingly, Cenkos the broker released a note. But it has nothing useful! No FY21 or FY22 estimates.
Too many unknowns for me. Valuation looks about right, and IMO chances of a 30%+ upside are almost nil at this point. Which is my minimum threshold for even considering buying a share. So back to the watchlist it goes.
Hi Paul, would love to read a write up of Kooth Kooth (LON:KOO) who released their final results today! they're a specialist mental health provider thats made great revenue progress from last year and have strong gross margin!
RE: Kooth (LON:KOO)
I've been holding for a while, after I noticed John Lee had bought a stake and noticed that none of the directors sold any shares at the IPO.
It's an extremely interesting proposition but it's way too early to draw any major conclusions. It's profitable (just) after reversing out exceptionals - I'm being generous on the share based compensation, but there are some decent underlying metrics:
The idea of a digital platform to support mental health, especially given the inevitable restrictions on the NHS and the rise in psychological issues due to the pandemic is extremely attractive. All the indicators are in the right direction.
However, this is still relatively early stage and is still a story stock. Most medtech companies utimately need a combination of skilled clinical staff (in short supply) and highly effective data analytic tools to deliver effectively. Kooth look like they have the right business model, and they appear to be pushing at an opend door but whether they can deliver will be the acid test.
Happy to hold a small stake to see what happens. Wouldn't want to bet the farm (or even a couple of barns) on it though.
timarr
Thanks for your thoughts Timarr! i stumbled across Kooth in November when a nurse friend of mine said they were worried about the impact of the constant lockdowns on people's mental health. there was very little info about the company financials at the time so i did only take a small position because i was esentially taking a punt on her thoughts (which do make a lot of sense)
they do have some fundamentally strong metrics as you've listed above but i was disappointed to see that it is hardly profitable - i wonder what they can do to boost this? i do feel like they're in a niche position, not only because of COVID, but mental health is at the forefront of many people's mind's now, and seeking help is being championed globally.
whether or not they can turn this in to real profits i don't know, but there is undoubtedly a demand/need for their services. i'm happy to continue holding - opposing views welcomed!
Hi andywillz94,
Thanks for flagging up Kooth (LON:KOO) - it looks an interesting company, and they're generating good growth. I like the recurring revenues, and that NHS is using it.
Whether it's likely to become a profitable business, who knows? As others have said in the comments here, it's still loss-making. I've had a quick look at the figures, and note that the £0.9m adj EBITDA is more than wiped out by £1.5m capitalised development spending. So it's making a small loss in reality. But that's fine, lots of small, rapidly growing businesses make losses early on, then hopefully move into profit once they've scaled up.
I like the concept, of a mental health app. There's a short video here explaining it, voiced by a youthful man, dropping all his letter "t"s as seems obligatory these days, in order to sound cool and appeal to yoof:
If that doesn't work, here is the link.
How on earth do we value it? It's gone up a lot recently, and is now valued at about £115m mkt cap - quite pricey, given that we don't know if it is going to be a viable, profitable, long-term business or not.
But we're in a bull market, so this could be quite a good thing to have a punt on.
Three's an obvious & growing need for support for mental health problems, many caused by covid/lockdown. My Mum has told me that she knows loads of people with serious mental health problems, who can't get any support at all from the NHS. They just don't have the resources. So I can see how farming it out to an app, especially for young people, could be a very valuable, and much cheaper alternative.
Do we know what the revenue model is, i.e. how much is charged per user, etc?
Overall, as a smallish, fun money punt, I like it! I might join you with a little flutter here. Thanks for flagging up.
I don't think there's any value I can add by dissecting the numbers reported today, so won't put up anything in the main report. I'll flag it in the summary above though.
Regards, Paul.
Cheers for taking a look Paul! After posting, I vaguely remembered the GVT said they planned on adding more funding to mental health services. they actually have a Mental Health Recovery Action Plan which was published by the Department of Health and Social Care on 27/03/21 (link https://www.gov.uk/government/...). maybe Kooth will benefit heavily from this £500m funding over the next couple of years considering the NHS is their main contract?
I also see an opportunity providing 'in-house' services to businesses with employees under constant high stress / target based working environments (the show on Sky Atlantic, Billions, comes to mind, albeit heavily dramatised). I would expect private sector work would provide much more lucrative revenue?
I agree, pretty much impossible to value the company at this stage but i can personally see the importance of its services in the future. The app is free to use -i'm going to have a play with it at lunch. from the video, it looks pretty clean and user-friendly.
Theres no solvency concerns with this one either so for me, im going to hang on to my small position and keep an eye out for any news about mental health/NHS funding.
A few months back, I bought a small holding in Kooth (LON:KOO) after the government announced £500mn to be spent on improving mental health services to the public. Sold out since. I could not stand how quiet they are with shareholders. Perhaps not a reason to sell out. Shhhhhhhhhhh!
I think Kooth (LON:KOO) were trying to teach you mindfulness.
LOL
Cheers Paul. I think the move to offer services to companies is very smart (KoothWork). Mental health/wellbeing is such a big part of life and perhaps even more so corporate life these days that I can imagine all FTSE350 companies needing this form of service. They offer 24x7 365 day a year appointments which does make me wonder about expertise though - I mean if you book a session for Midnight I can't help wondering if you end up with a chatbot followed by someone from a call centre in Bangalore - maybe that's a bit harsh. I found a freedom of information request that showed Jersey paid £52k for 14 months use of the service which is primarily a mental health redesign program enabled review of existing children and young people's mental and emotional wellbeing. Jersey isn't exactly huge with around 100k pop and about 16k children pop so you could apply a similar figure to a FTSE company for the service I would of thought? So back of a fag packet £50k x 350 is a potential revenue of £17.5m. If you are in charge of HR this type of service sounds lie a no brainer to get in - especially with the shift to home working? It is expensive but who knows!? I guess other private health care providers can muscle in on this if they aren't already but this service should I'm guessing be free to all employees as opposed to a BUPA type scheme for exec staff only.
I had a small punt some time back up nicely on my purchase, but difficult to value, I found this interesting see my notes below.
To date, the Company has provided these services entirely within the UK but is in active discussions to offer these services overseas working in partnership with local healthcare providers Discussions are underway in Canada and South Africa where partners would license the Kooth SaaS platform to operate in their region. In addition, the Directors believe that there is a significant potential to establish Kooth in the United States given Kooth’s expertise in supporting children and young people.
On the theme of outsourced medical services where the NHS are the client, this reminds me of Medica (LON:MGP) (I hold).
Kooth has £16m ARR and a £109m market cap, gross margins of around 60%
Medica have £58m rev pencilled in brokers for CY2021, £190m market cap, profitable, gross margins of 48%. And also growth potential via overseas expansion (US, AU, IE). And been listed for a while, so has a good track record.
Clearly mental health and B2C app is of course more hot/topical at the moment. Does go to show that the right story can add multiples to a valuation.
Property ex London (and suburbs) - I have a colleague who has just sold a 4 bed detached seaside town property in Suffolk [9 viewings in a week and 4 bidders bidding above the asking price SOLD in 10 days) Another has relocated from London and is selling an apartment [50 viewings over an extended period and 1 offer below asking price].
Herd / Fickle Fashion mentality? How to capitalise on such mood swings in my investing?
I have family trying to buy in Caversham across the river fom Reading and there are hardly any properties to view. They only hit the open market if the agent doesn't have a cash buyer lined up that wants it.
2 properties in my road sold before even getting on the website or the sign going up. One looks like it is a second or holiday home. The other was bought by a local who sold her flat within hours to a Londoner.
If I did need to work in London I would live there. I worked in London for years but never lived there.
If you can work from home, then makes sense to move if you lived where you do because of work location. If you can get a better house for less money, even better.
There's a nice looking and seemingly complimentary acquisition by Adept Technology (LON:ADT) this morning.
It pays £9m (plus up to £7m more (earn out) for Datrix, bringing in adjusted ebitda of £1.5m on sales of £10.7 . Earnings enhancing in Y1.
Downing continue to hold 10%. Market seems to like it.
Re PI's and ability to access new issues has anyone else had problems with PrimaryBid? They force you to use their App which they acknowledge has bugs and this morning I applied for shares in one new issue and was sent an email confirming my application to a totally different issue!
Hi Charles10
I've had problems with Primary Bid recently. Tried to apply for recent offer of Jarvis treasury shares without any luck. Using an Android 7 phone the app got stuck in a perpetual loop asking me to review my application and I was left not knowing whether I had applied for 750 shares or 15,000 (I tried about 20 times!). I have a fairly large position for me in JIM and would have been more than miffed if the dilution had been much greater than 2%! Can anyone tell me how to exit that loop?
That happened to me and I emailed primary bid with my displeasure. They replied with a link that allowed me to make a payment from my computer for my subscription. Great customer service. I think it was a tempoprary issue with their payment processors.
Anyone looked at Watkin Jones or Anglo Pacific today? APF looks like it's totally transforming from coal into battery metal royalities, downside looks limited given how lowly rated it is already and strong well supported dividend
Good morning Lridly
Progressive Equity Research has this morning published a note on Watkin Jones (I hold) and which you can find on its website www.progressive-research.com.
Kind regards
Phillip Arghebant
thanks for the paid link
I have a small holding in Anglo Pacific (LON:APF) and thought the results were a bit disappointing particularly as they were released the morning after a very positive presentation in the Shares event yesterday evening. Very odd - who does their presentation the evening before the results and can't talk about them because they are in a closed period.
I think a divestment of their remaining coal assets is needed to complete the turn round story here. I would add to my holding on that.
they do presentations all the time, watched that and thought the outlook was very good but this is obviously a transformational year, better than sticking with coal at least!
Anglo Pacific (LON:APF)
2021 looks like a stretch year. 2021 earnings perhaps at 15x and covering the dividend from net cash flows tight. I'm not a 100% sure and need to look at results more closely.
The Kestrel coal asset has been highly cash flow productive. The near 50% cut in carrying value seems to be entirely driven by the fact that their royalty is attached to only a portion of the mining area and the operator seems to be moving off it. There feels like more negative risk here. It doesn't happen all at once obvs but the dividend is highly dependent on this old cash productive asset. The newly acquired cobalt asset has production risk as ramping up. Its also quite a complex financial agreement that I need to work out a bit more as at times they need to pay more to get more (partly connected to commodity price moves). It feels like a deal to me with a decent element of speculation in the cobalt price to make it work. This may pan out...but its not a 'conservative' approach...particularly given need to pay back debt.
Debt is on favourable terms at libor +1.75% but note they sold 3/4 of their high yielding LIORC iron asset to finance too and overall their a c.£10m cost to the extra debt and the given up on iron related income stream. They get a net +£2m income approx (I've seen them forecast $15-16m cobalt related income this year).
APF are walking a tightrope. Optionality feels to downside rather than upside. They seem to need commodity bull market so as they can tread water rather than it being what makes hay for them. I need to look more...but I'm not feeling good about their capital allocations and decisions at present.
Views? (Mine are quick and maybe erroneous)
£APF
I held this prior to March 2020 then, when it dropped with everything else in the market, sold and rebought in summer 2020. Seeing the results today I decided to sell my position again as whilst they speak about diversifying away from Kestrel / coking coal it still seems to dominate their results. I feel there are better resource plays available (though this has the advantage of a solid dividend).
Last year's results were heavily impacted by lower royalties from Kestrel - these are going to run down further over the next few years, as mining moves outside the area for which Anglo Pacific (LON:APF) receives royalties. I can't see any point in their divesting Kestrel, which will drop off sharply over the next two years, or Narribri, which is small in the overall portfolio. I hold, but the valuation necessarily depends on how far the other royalty streams will make up for the loss of Kestrel. Anglo Pacific (LON:APF) is currently buying back its own shares, which suggests the current SP is reasonable.
£APF (ex-holder) I cant help thinking - you buy mines when no one wants them. You certainly try to avoid buying them when everyone is talking about commodity supercycles. IMO, APF forced themselves in a corner after repeated announcements of their transition to green resources.
Another random thought - I recall Justin (ceo) or Kevin (another director) mentioned that the longwall changeout may re-occur again this FY in Q3 or Q4 which may impact royalties in that Q.
The longwall changeout at Kestrel.
Also @SundayTrader - I thought they have stopped their buyback programme a few months back?
Renold. I am an actuary and it is my fellow actuaries responsible for the large pension fund deficit. Switching into bonds for liabilities that are income inflation related is a mistake. if pension funds were invested in UK equities a yield of 3.5% would eliminate most deficits. In Denmark they allow liabilities to be discounted at 4 % regardless of the yield on assets as they argue that this is the long term mean interest rate and the liabilities are long.
I Chair the trustees of a "small" (£100m) defined benefit pension scheme.
Rising bond yields will reduce the pension scheme liabilities - the discount rate goes up and the present value of the future pension payments comes down. Typically the discount rate used to calculate the accounting liabilities is higher than that used in the triennial valuation which is negotiated between the employer and the trustees.
The other part of the equation is the pension scheme assets. In both cases (accounting and triennial valuation) these are valued at market value although the effective dates may differ. Trustees have flexibility how the scheme assets are invested but the bulk are typically in equities or bonds. In more recent years, many trustees have shifted the balance more into bonds (or bond like investments) as these provide a good hedge against the liabilities. As DIWReynolds points out, bonds tend to yield less than equities. A pension fund that is heavily invested in bonds therefore will see its deficit remain more predictable as interest rates move around, In the current environment with equities performing strongly and interest rates increasing, a scheme with a heavy weighting to equities should see its deficit reduce over and above that caused by contributions.
The pension scheme deficit is the excess of the liabilities over the assets. Any triennial valuation deficit will lead to the agreement of payments by the company to the scheme to "repair" the deficit over a period typically not exceeding 10 years.
I have not looked at the Renolds scheme in detail, but to understand the impact of the current market movements, you will need to understand how the scheme assets have been invested. Their Annual Report, note 18 gives useful information including the sensitivity to interest rate moves. It shows that on an accounting basis there is a large deficit so the deficit repair payments are likely to be greater than this amount.
Investors should treat the pension fund liability as a creditor which reduces the overall value of the company to shareholders.
Thanks for sharing SurreySteve - it is really useful to get insight from someone quite intimately involved with the defined benefits issue.
Overall it is an issue that I find somewhat frustrating.
Trustees are IMHO by and large doing absolutely the right thing by protecting their members and putting the companies, who implicitly made "deferred salary" promises on the hook.
However, by switching to bonds during a period when they are arguably more over-priced than at any time in history, they are denying the sponsor companies any chance of recovering the shortfall from any future market moves.
I was trying to work out the winners and losers here :
Pensioners & deferred pensioners : Neutral - they will still get what they were promised.
Sponsor Companies : Losers - they are being forced to lock in losses, when those losses are potential at their max and been denied any opportunity to get any benefit from the next phase of this particular cycle,
One party losing and one party neutral - I was struggling to find the winning party, but I think I have worked it out :
Past shareholders of sponsor companies. In 1986 legislation was introduced by the Thatcher government forcing pension schemes to pay back any surpluses and ensuring that companies could not fund pension schemes that were in surplus.
The narrative we were all fed more recently was that Defined Benefits were unaffordable because investment returns are lower than the were in the past, but that seems questionable to me - DB pension funds were not allowed to keep (& grow) gains at the 'top' of the cycle which would have allowed them to survive the 'bottom' of the cycle.
I have hugely digressed here from the point I was working towards, which is that not all pension deficits are 'equal'(ly challenging) ; however I will post anyway, because if we can avoid too much polarisation, there might be an interesting discussion here.
Hi Gromley
You make some very interesting points that I think are worth exploring further. I have somewhat summarised your points - apologies!
Trustees are pushing for lower volatility in pension deficits
While trustees are not rewarded for taking additional risk, they do have the benefit in many cases of being able to take a long term view. It is often companies with the pressure imposed by regular reporting who are keen to "derisk" the pension scheme investments. Certainty is often seen to trump cost.
Interest rates are low
This has been broadly the case for the last c10 years. It is very difficult to time the turning point in the market. It may now have happened but we cannot yet be certain and Central Banks keep promising "lower for longer".
The movement from return generating investments (equities) into heading assets (bonds) is very much a one way street at the moment. This is in part driven by the regulatory environment.
Winners and Losers
Companies that have a high proportion of their pension scheme assets in return seeking assets are likely to see more volatility in their pension scheme deficit than those with a high proportion of hedging assets. Who the winners and losers are will depend on the performance of the investments and the direction of travel of interest rates.
If a company fails with a pension scheme deficit, pensioners will typically be protected by the Pension Protection Fund. Non-pensioner members who have higher pension entitlements will often experience a "haircut".
Legacy issues
Many, but not all schemes, are now closed both to new membership and to future accrual. In the majority of cases these changes happened nearly 20 and 10 years ago respectively. With normal levels of staff turnover this means that a minority of senior management are now members of the defined benefit pension scheme in such companies, if they are represented at all. This makes it something to be "managed away" rather than something that management want to actively participate in.
Immotion (LON:IMMO) have got the moves. As I've said before mgt are true ducking and diving scrambling do whatever it takes entrepreneurs. A good thing and darn lucky for IMMO shareholders. Covid was a bum deal for a business that was on the cusp of commerciality but relied on people gathering...
But couple of things re RNS. Still no guidance on what Uvisan is and will make. So still sounds like marginal. And I believe there's a mgt/board connection into Aardman.
Note 2020 and 2021 revenue expectations for IMMO and so earnings are fantasy. If they were hitting those numbers it would clearly be a screaming buy.
My guess is that between now and the fy20 results there's going to be a raise....one more to commerciality?
I suspect there will be a further raise in Immotion (LON:IMMO), but like previous placings, most recent end March, I reckon it will be at a premium which is OK by me.
Management own a heap so they don't want too much dilution.
And remember, when 400 sets are up and running in attractions... further sets drop to the bottom line.... so they may struggle on 29th but as things open up... the company is going to gradually take off.
They only floated in July 2018 don't forget so hopefully they are now hitting that sweet spot of maturity and cash generation.
Were you in MMX Mojo?
greenhat2
Yes I was in Immotion (LON:IMMO) as an early stage speculation early 2020. I felt that it had created a sustainable high margin model for their out of home VR product, would breakeven cash flow and had a rollout ahead of them...then covid. I did buy more when it plunged sub 2p but then sold out Q3ish 2020. All told for a moderate loss. So narrow esscape.
I think their product is good. I worry about the need to refinance, why these new products if the main one is good (Uvisan and the lets explore at home VR) and a pretty fulsome valuation that implicitly rewards them for a terrible 2020! (share price is down but market cap is up due to equity financing)
You answered the Uvisan question already Mojo - they are entrepreneurs..
Look in the post covid era, ppl are gonna want clean kit... I mean I'm not going to wear a VR headset after you or Jimmy Joe has just worn it...
In my mind their innovation of UV cleaning kit for VR sets and for rooms is sensational inventiveness... It just so happens that there is a lot of crossover utility for this kind of thing out there...
My dentist has a 'virus killer' on the wall... he's techie... I asked him how it worked... he said it sucked in air and put it under UV light... great he thought... he now can let it do it's job for 30 minutes between clients...
Imagine if the Uvisan could do that in 5 minutes, 2 minutes.... clean a room in 2-5 minutes...
That would be in demand my friend.
Necessity is the mother of invention and that has played out well here... they have sold some Uvisan kit to the NHS - if NHS start buying this kit en masse... that could be huge
Leaving this aside, the out of home VR has potential to be a big earner... At home VR and Uvisan kit is just the cherry in my opinion...
Covid has held back breakeven, so yes, another premium raise potentially but they did say at 400 sets of out of home VR, they would be profitable and self funding and everything over 400 dropping to bottom line... so as the world opens up, they should get 400 sets operating day in day out quite easily and getting that revenue share into the coffers
Maybe they might need to raise a small amount to fund the proper roll out of Uvisan, it rolls out at the end of this month...
Uvisan seems to be a software add on to existing UV technology so that is easily replicated... hoping they have the IP protected on the software...
I expect results on 29th to be poor, numbers wise... but look at the potentials:
the potential for more out of home sets
the potential for more out of home sets dropping down to bottom line
the potential for At Home along with results...
the potential for At home in the USA (maybe some figures from the recent launch there?)
the potential for Uvisan... maybe elaborate more on potential clients ? NHS?
There's a lot of potential here... under the radar
I agree there is potential ...I’m lacking the imagination to see it at current valuation. I feel I’ll get a look in again whether higher or lower price I dunno
Uvisan products listed here:https://www.uvisan.com/ And advise in their release today that they expect a full commercial launch by end April 2021.
And give further details of range of product uses in todays release saying:
'Uvisan's product range provides rapid, safe and effective disinfection using the power of UV light.
Aardman is using Uvisan's UV-C disinfection cabinets in its production studios in Bristol, UK. The cabinets will be used to disinfect delicate puppets, props and rigging kit, including puppets for the new 'Shaun the Sheep' movie.
Below is a link to further information on why Aardman chose Uvisan:
https://www.uvisan.com/aardman-animation/
Along with the sales to Aardman, the Company has now sold cabinets into a number of different sectors and high-profile clients including education (school and universities), healthcare (including NHS trusts) and a number of other corporate sectors.
The Uvisan disinfection cabinet has also been recommended by Hewlett Packard, after extensive testing, for safe disinfection of their VR headsets.
In addition, Uvisan has installed its first new UV room disinfection system, "Cleanroom by Uvisan" into Chichester University. This system uses fixed UV-C lights and a proprietary control and safety system to provide rapid disinfection of un-occupied rooms. This system allows disinfection, typically in less than 10 minutes, of an entire room, including all surfaces and the ambient environment itself.
Chichester University will use Uvisan's technology to cleanse its state-of-the-art recording studio (mixing desks etc.) and the other equipment used in it, as well as cameras and related equipment. The new installation will enable rapid and safe handover of the recording facilities and equipment between user groups.'
You know my thoughts on this Mojo. I discount the Uvisan product to zero though that’s harsh given the progress it’s made, but with the opening on the economy and pent up demand to pretty much go to any destination attraction operable I see them doing very well with their core product. the home AI launch in the US could be very interesting in the latter part of the year but I know you can’t quite share my enthusiasm on that.
Nonetheless I stand by my personal price targets but can see a raise if the share price gets to 7.5/8p but probably sub 10% of equity which is ok if it funds growth.
They will probably raise whether they get to 7.5p or not given all the projects they have going and needing funded. Plus they will want to fund further destinations. They may get some asset/revenue backed sort of financing for that but the best way to grow is if they can fund it without complex financial negotiations.
Yes they will have surge, that's beyond question. But they will have lower numbers due to restrictions and some extra costs.
>7.5p is seeing market cap at c.£32m. This seem heroic. What revenues are they going to print 2021? They are also a relatively capital intensive business that hasn't reached self-financing scale. What size is that? Its gone up a little due to new products to finance and volume restrictions on existing (eg Madalay Bay)
Mission (LON:TMG) James Clifton, CEO gives an overview of TMG’s full-year 2020 results released today. Trading recovered in H2, reversing the H1 Covid-19 hit to deliver a headline PBT ahead of market expectations. Q1 2021 is in line with expectations with a growing pipeline of new business opportunities. Focussed on 14% margin target by 2022. Video & podcast.
Quixant (LON:QXT) Jon Jayle, CEO & Andrew Jarvis, Interim CFO give an overview of QXT's full-year 2020 results released today. . On the gaming side, Q1 was strong but Q2 was marked by casino closures, this was followed by a very rapid recovery in H2. Densitron traded resiliently with double digit growth in broadcast and medical. Looking forward, the Q1 group order intake has been strong with 106% order coverage of the Group budget for H1 2021. Video & podcast.
Also, piworld webinars coming up shortly: Mercia Asset Management (LON:MERC): The Mercia Brief next Tuesday 20th April, 4pm. A good opportunity to grasp the different parts of Mercia, which was Reg Hoare's 2021 pick back in February 21. Register here.
And, Property Franchise (LON:TPFG) FY20 presentation followed by Q&A, with the CEO, Gareth Samples and CFO David Ragget: Wednesday 28th April, 11.30am. Following Belvoir's strong results I'm looking forward to this. Register here.
Also, yeseterday piworld published the Ra International (LON:RAI) FY20 results presentation, CV19 hit revenues, but positively impacted margins. Going forward they have a record order book and are winning larger contracts with higher margin work. Video & podcast.
And, Sumo (LON:SUMO) FY20 results presentation, who after adjustments came in ahead of expectations. Extraordinarily headcount has increased to 1,043 at December 20, from just 277 at December 19! Overall a very strong market backdrop and a very positive outlook for FY21. They are now working on more than 40 projects with 28 different clients, up from 21 projects with 12 different clients as at April 2020. Video & podcast.
Hi Paul. Encouraging news from Renold (LON:RNO) What do you think?
hi Paul would you be able to look into Renold (LON:RNO) please ? Thank you
Kooth (LON:KOO) results look interesting today Paul. Recently IPOd and mainly dealing with mental healthcare; plans to take it to workplaces and international.
My morning smallcap tweet: Will the Napster Phoenix sing or just die again?
Futura Medical (LON:FUM) Napster (LON:NAPS) Mission (LON:TMG) £K3C Palace Capital (LON:PCA) Iconic Labs (LON:ICON) Distil (LON:DIS) Newriver Reit (LON:NRR) Vianet (LON:VNET) Audioboom (LON:BOOM) Foxtons (LON:FOXT), Renold (LON:RNO)
Futura Medical PLC (FUM) FY. Pinky potion prospects perky. [SP=55 Cap=137m]
Napster (NAPS) cuts spending on growth of the MelodyVR platform, "both application updates and new content streams will be limited during these coming months as resources are now focused on the development and subsequent relaunch of Napster." Convertible loan inc to 8m and drawdown accelerated. Also MelodyVR launches exclusive 5G partnership with NOS in Portugal which has 5m users. [SP=2.65 Cap=68m]
Mission (TMG) CFO scarpers. He is thanked. [SP=89.25 Cap=81m]
K3 Capital (K3C) guides FY(May) rev £45m and adj EBITDA at least £13.25m, significantly ahead of consensus upped in March. [SP=312 Cap=215m]
Palace Capital (PCA) trading. Rent collection continues to be 'very strong'. 82% of March 2021 Q rents collected or are expected to be received under monthly payment plans. Hudson Quarter enquiries and reservations on the residential units have increased significantly. Sells 2 properties for £2.45m, above book. [SP=232 Cap=107m]
Iconic Labs (ICON) Greencastle Acquisition bust up escalates with demand for £59k from Greencastle. ICON alledges serious wrongdoings by Greencastle which is run by former directors and others. [SP=0.01 Cap=3m]
Distil (DIS) guides FY(Mar) rev up 48% to £3.6m and volume up 30%. Adj EBITDA like-for-like up c.55% to £302k. LFL EBITDA? [SP=3.1 Cap=16m]
NewRiver (NRR) valuation decline in H2 will be less than that reported in H1. Is that supposed to be good? Has 'increasing optimism'. Will sell community pub business, probably by IPO. WIll sell non-core retail assets and recycle the resultant capital into resilient retail. Outlook "consumer economy will perform better than expected but that the retail sector will continue to be influenced by market trends which existed pre-COVID". [SP=103.4 Cap=317m]. I hold.
Vianet (VNET) guides FY(Mar) adj op loss c. £0.7m and cash generation c £1.1m. In line? [SP=103 Cap=30m]
Audioboom (BOOM) Q1(Mar) rev up 49% and 12% on Q4. Adj EBITDA flat (-$0.5m). Guides FY (Dec) rev well ahead of market expectations. How long will the lockdown tailwind last? [SP=720 Cap=113m]
Foxtons (FOXT) Q1 strong with sales revenue up 60% and mortgage broking rev up 20%. CEO getting stick in press for taking £1m bonus while co took Gov't support. Shameless as ever. [SP=67 Cap=218m]
In line: Renold (LON:RNO)
You have such a way with words. Futura Medical (LON:FUM) “pinky potion prospects perky”. I love a literate alliterator.
Morning Paul, any thoughts on £foxt would be welcome (I hold)
I was encouraged by this from their update today, suggesting to me that they’re well resourced to scale up as demand returns, ‘Lettings revenue was up 6% to £14.8m (Q1 2020: £13.9m). Rents in London remained under pressure during the period, declining by around 12%, but were offset by increased volumes.’
I live in the centre of London and watch the local House (Flat) prices. From my local area and watching properties similar to mine using Rightmove, asking prices keep dropping and properties I watch don't seem to sell. I would like to move out of London but from what I can see I would take a 20% hit on what I thought my property was worth (based on asking price of a flat exactly like mine, now up for sale). It make me wonder how people are managing to sell up from inner cites and move out, are they taking the hit on asking prices or using bridging loans?
They can sell because where they are moving to is cheaper, around here (Suffolk) you can still get detached houses for around £300-400k, although prices have risen and properties are selling fast, mostly it seems to Londoners.
K3 Capital (LON:K3C) Trading update
"significantly ahead of revised consensus market expectations, with revenue expected to be in the region of £45 million and Adjusted EBITDA* of no less than £13.25 million."
Yes looks good, I have held for a few months now. Directors hold over 30% which I do like to see.
Yes Lefty 99, K3 Capital (LON:K3C) have a revised, revised situation in te last few months. All upwards, all good. Lets hope that the profile cntinues to improve. This was a featured Small Company Sharewatch feature earlier this year. Showing a nice 30% rise since I bought.
Good morning all
I see Immotion Immotion (LON:IMMO) (I hold) have announced that the makers of ‘Shaun the Sheep’ have done a deal to buy their anti-virus cleaning cabinets which Immotion (LON:IMMO) originally designed to clean their VR headsets.
They have a room cleaning solution too... let’s hope that takes off.
Immotion (LON:IMMO) supply VR experiences to visitor attractions... they are a young company focusing on the Aquarium market atm but will expand to Zoos etc shortly.
IMO £IMMO’s COVID recovery hasn’t hit SP yet.... unlike other leisure players most notably Accesso Technology (LON:ACSO) who have software geared towards visitor attractions... SP up over 30% in the last month
As aquariums reopen, revenue visibility will increase.
Looking forward to next update on 29th April - they placed at a premium recently so it’s looking promising :)
Actually, sorry I see Chichester Uni is taking the room cleaning kit for a recording studio.... interesting....
comment on Renold (LON:RNO) update (since you hold), please.
I would second the request for Paul or Jack to have a look at Kooth Kooth (LON:KOO), if possible. It seems under the radar but, as a digital mental health company, it is surely very relevant to the current times. I believe private equity still holds a sizeable stake. Not sure whether this is good, or bad.