Small Cap Value Report (Weds 14 Oct 2020) - BOO, CALL, WGB, SYS1, WATR, ANG

Good evening/morning. I'm posting this first section about BOO (I hold) early, on Tuesday night, while it's fresh on my mind, and so I can get this out of the way and concentrate on small caps in the morning.
Timings - I've got to attend to a meeting from 12:30 for about an hour maybe. Then lunch, then I'll carry on here- so estimated finish time of 5pm. Today's report is now finished.
Agenda (Weds morning) -
Walker Greenbank (LON:WGB) - Interim results
System1 (LON:SYS1) - Trading update
Water Intelligence (LON:WATR) - Trading update Q3
Angling Direct (LON:ANG) - Interim results
Ramsdens Holdings (LON:RFX) - Trading update - sorry. I ran out of time to look at this one, and am not familiar with the company, so it would have taken too long to look at it from scratch. I really don't like pawnbrokers anyway. The share price is up 11% today, so the market clearly likes its update.
.
BBC Radio 4 - "All Sewn Up"
This was a BBC investigative programme, aired on Radio 4 at 8pm on 13 Oct. A reader kindly flagged this up to me, so I listened to it & took notes, which follow below. It mentioned Boohoo (LON:BOO) (I hold), hence my interest. If BOO doesn't interest you, then please move on to the next section. I'm not entering into any discussion about why I cover BOO. I cover it, and always will. End of!
NB. As I hold shares in Boohoo (LON:BOO) I'm not impartial. I've formed a view on the Leicester supply chain issue, and obviously as I've bought more shares in BOO, then my view is that the recent share price weakness is a buying opportunity, and the supply chain issues do not in any way impact the value of the shares long-term. The company has recently reported record trading, despite the best efforts of the media to tarnish the brand.
My view remains this: BOO has admitted there are failings in its Leicester supply chain, and has already announced extensive ways to rectify the situation.
This is roughly what the Radio 4 programme said (main points I jotted down whilst listening to it, together with my comments). Apologies for any errors or omissions;
Leicester supply chain - allegations
- Separate investigations by journalists Paul Kenyon & Ashley McCartney, who narrated the programme.
- Evidence of money laundering & VAT evasion (systemic fraud, endemic) in the Leicester garment factories, which supply some of the UK's fast fashion retailers. NB all factories are independent companies, not owned by retailers. No evidence that retailers are aware of illegal practices.
- Spinney Hills district of Leicester LE5 is powerhouse of fast fashion manufacturing - supposedly 1,500 hidden "dark" factories operating in secret, with VAT fraud key to the "impossibly low prices" they charge.
Case study - Mr Nagra, Rose Fashions
A civil action which blew the lid on dodgy practices in Leicester garment manufacturing industry
Select (High Street retailer with 170 shops) was the customer. They did not know a VAT scam was operating, and they paid full price, including VAT, unaware that Rose Fashions Ltd was generating fake invoices at inflated prices, through shell companies.
Shell companies were set up, typically had a lifespan of about 2 years. Never filed accounts, and were struck off by Companies House for failing to file accounts. Left behind large VAT liabilities, unpaid.
This was not explained at all well, but the VAT fraud seemed to involve fake invoicing, with surplus, never to be paid VAT. being withdrawn in cash, by the crooks, and then disappearing.
Double accounting, by manufacturers, one set of books for the taxman, and different, secretly coded cash books, to keep track of reality.
Mr Nagra ripped off another businessman, hence how this came to light in civil court case.
Judge said Nagra was a liar, and made him bankrupt.
NB No suggestion that Select knew anything about the VAT fraud. Select refused to comment.
Another example given of TNS Fashions, which folded in 2017, owing £1.7m in unpaid VAT. Sole Director banned for 7 years. Had supplied BooHoo. When queried, BOO said they had never dealt with the company. BBC then told BOO it was an unauthorised subcontractor of another company. BOO recognised name of other company, and severed all dealings with it. BOO appointed a supply chain auditor in 2019.
HKU Trading Ltd provided as another example of a shell company with 2 year life.
Shell companies used for VAT fraud look odd, because they immediately commence trading on a meaningful level, but don't have any staff or premises costs. So clearly bogus (but how is anyone meant to know that, since they haven't filed any accounts?)
Rose Fashions supplies (ominous music starts) PrettyLittleThing, operated by, yes the same Kamani family which owns BOO. BOO then terminates relationship with Rose Fashions, when wrongdoing comes out.
Exploitation of employees in Leicester factories
NB, This is general to the Leicester factories, supplying fast fashion retailers.
Bulgarian woman interviewed via a translator. Says she & husband live in cramped living conditions. Is paid about £6 per hour, below minimum wage. Was paid £2.50/hr initially. Frightened to speak out. Came to UK for a better life.
HMRC
Supposed to be policing tax payments. Needs to ask tough questions. Under-resourced?
HMRC claims success, having done 25 VAT investigations in Leicester garment sector, recovering £2m. Suggestion this is only tip of iceberg?
Retailers
Auditing supply chains more. They say to suppliers, renegotiate if prices are too low, don't break the law.
My view
An interesting programme, but rather muddled, and poorly explained in parts.
No smoking gun re the retailers, in fact it seems they were paying in full, with full VAT, unaware that some suppliers may have then been using a web of shell companies to execute a VAT fraud.
Flaw in the logic of this programme, is that it claims retailers are getting artificially low supply prices of garments through suppliers almost being forced into committing VAT fraud. But then it later says that suppliers are spending their VAT fraud loot on £100k cars and lavish lifestyles for themselves.
What the programme failed to point out, is that retailers can get lower prices by sourcing from abroad, and air freighting into the UK. Because labour in places like Bangladesh is a fraction of Leicester, at only about 50p per hour. Leicester is used because it's convenient & quick, not because it's cheap.
VAT fraud occurs in many industries. It's a rubbish system, full of holes. You cannot blame the end customer, who has paid in full, if a supplier improperly accounts for their own VAT, unbeknown to the customer. Therefore the whole basis of this programme seems spurious to me.
I'm starting to wonder if deliberate, or maybe subconscious bias is starting to play a part in the hounding of the Kamanis at BooHoo. After all, they've built a fantastically successful business, becoming billionaires, being British-Asians, and flash with their cash, maybe there's a bit of jealousy creeping into some of the reporting?
We had a similar situation with Sir Philip Green. I went through 15 years of BHS filed accounts, and found no wrong-doing. But he's flashy, arrogant, so the press took great delight in presenting a largely false picture of his business dealings at BHS. For example, there was no pension deficit when he was legitimately paying out large divis from profits. The pension deficit arose due to UK Govt policy to slash interest rates in 2008-9, which made liabilities balloon. There were no divis after that, and he did everything possible to save the business, but BHS was overwhelmed by low cost retailers emerging, like Primark, and of course the internet.
Another example - look at the Telegraph article last weekend, hounding Mahmud Kamani, and contrasting his enjoying a birthday party in Istanbul, with low paid machinists in Leicester manufacturing items for BOO's websites. Why should't he enjoy a birthday party for goodness sake? You can almost hear the envy (or worse) dripping from the pen of the low paid journalist writing that piece - which again contained nothing new.
One of my readers here made a very good point in yesterday's SCVR comments - that re-hashing articles about BOO is a good way to get page impressions, hence ad revenues online. So perhaps this story will just run & run, as desperate journalists try to seek page views?
As for short sellers - remember that they are deliberately trying to provoke fear & panic selling, in order to trigger a short term spike down in share price, for their personal financial gain. I respect short sellers that expose frauds like Globo or Quindell, but I have little time for those who attack good companies, in order to trigger a brief spike down in price, for their own quick bucks.
.
Cloudcall (LON:CALL)
93.5p (up 3%) - mkt cap £36m
(I hold)
Trading on New York OTCQX Market
This is an interesting announcement. We've discussed here before that CALL has several disclosable shareholders based in the USA. A significant part of its operations & customers are also in the USA. Tech, growth companies are valued much more highly there, than in the UK, hence a potential opportunity for a re-rating, or takeover bid for this company? Although I noted that a recent RNS showed one of the US shareholders had reduced its stake.
In a webinar earlier this year, someone asked a question about whether CALL would move its listing to the US. The CEO said no plans to do so, but "never say never".
Today CALL says;
...announce that the Company's shares will cross-trade publicly on the OTCQX®Best Market ("OTCQX Market"), under the ticker "CLLLF", with trading commencing from today. CloudCall's ordinary shares of 20p each ("Ordinary Shares") will continue to trade on the London Stock Exchanges AIM market under the symbol "CALL".
I'm not familiar with US OTC markets, but the term "cross-trade publicly" sounds like a matched bargain type of arrangement, as opposed to a liquid market with market makers holding a float of shares to trade either way.
Commenting on this important step, Simon Cleaver, CloudCall CEO, said:
"I am delighted that CloudCall has now joined the OTCQX Market. We've been attracting the attention of U.S. investors and I hope to accelerate this trend by making it easier for them to find research and trade.
That sounds interesting.
One query though, maybe readers can help with this. I thought that AIM shares couldn't have a dual listing, or it impacted the tax benefits of AIM? I could be wrong there, but it's in the back of my mind, hence me querying it. Does anyone know the position on this? Does an OTC arrangement in the US count as a dual listing, or maybe not, I don't know?
EDIT - thanks to reader comments, confirming that it seems to be the case that an OTC listing in the USA might not qualify as a recognised exchange, hence that should not impact the AIM tax benefits. That sounds sensible to me. Hmmm, reading a couple of other reader comments, I'm not so sure now. Easiest thing is if I ask the company, I'll email them now & come back to you later.
Update at 13:51, I've spoken to the company, and they have helpfully clarified as follow;
This is not a dual listing. Whilst it’s an exchange and we have market makers etc, it’s a ‘cross listing’ or to be technically accurate it’s defined as a ‘Cross Trade’. As such, it should have no bearing on UK regulations or Tax. In short, it should not affect CALLs IHT status.
.
Walker Greenbank (LON:WGB)
Share price: 59p (down 6%, at 10:13)
No. shares: 71.0m
Market cap: £41.9m
Walker Greenbank PLC (AIM: WGB), the luxury interior design and furnishings group, announces its interim results for the six-month period ended 31 July 2020.
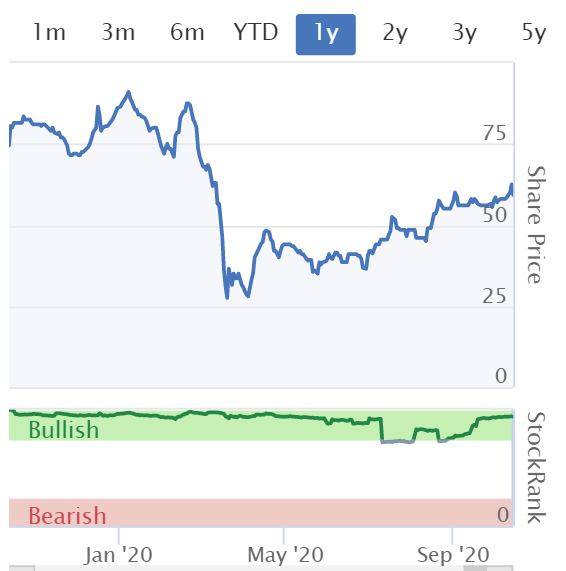
The share price is down 6% this morning, but as you can see from the 1 year chart below, it's still in a healthy up-trend since the March lows;
.
.
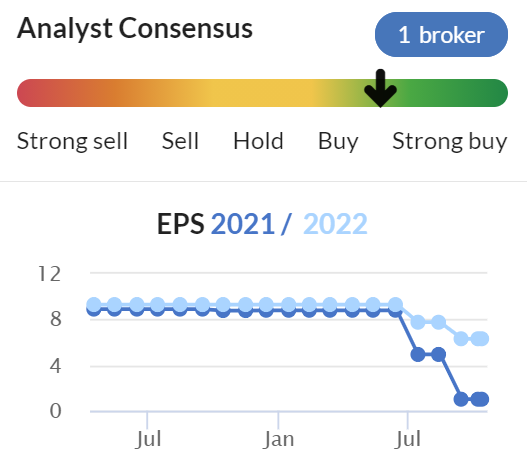
It looks as if a realistic broker forecast didn't come through until July 2020. Its caused a huge headache this year, given that companies and brokers withdrew forecasts & guidance for so long. This seems very bad to me. Just because things are uncertain, doesn't mean investors should be left in the dark. The missed opportunity for companies/brokers is that they should have given a range of forecasts: base case, then a downside, and an upside alternative. This approach is often taken when companies are seeking funding, and for going concern purposes. So why couldn't such estimates have been more widely published? It's not good enough, and I think the city has badly let investors down throughout this crisis, with poor, or non-existent information. In difficult times, guidance to investors is more important than ever, so shutting it down is the opposite of what's needed.
Anyway, given the extent of the forecast fall, it looks to me as if we can rely on these estimates as being realistic;
.
In terms of valuation then, I'm ignoring this year FY 01/2021 as an aberration, and would base my valuation on a multiple of earnings somewhere between 6-10p. On the basis that FY 01/2022 will probably be a partial recovery year, then hopefully the company might subsequently recover further back to levels anticipated pre-covid. I'm also making a general assumption that a severe or prolonged recession globally seems unlikely, given the vast amount of stimulus being injected by Govts. Why would then suddenly withdraw support, and allow the economy to slump, given that they've propped it up this far, and can continue to borrow for free (and print the money via QE)?
On that basis, WGB is probably still quite cheap. 12 times earnings, based on my 6-10p range of future earnings potential, gives a share price range of 72-120p, usefully above the current price of 59p.
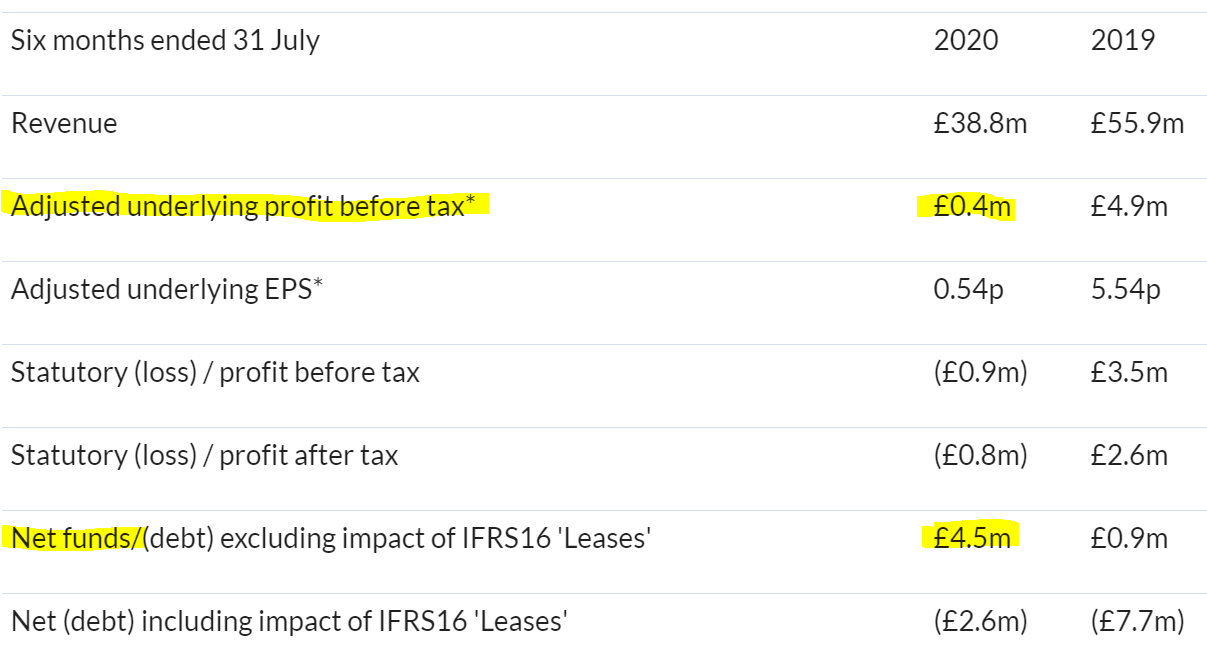
Interim results - this looks much better than I was expecting. A small profit, in a chaotic covid/lockdown period, strikes me as commendable. Also, it has net cash;
.
Although note that furlough grants of £3.2m helped considerably - which is what they were designed to do.
Liquidity looks ample;
Measures taken to improve liquidity resulted in cash headroom against available banking facilities of £19.5 million at 31 July 2020 compared with £13.8 million at 31 January 2020
Dividends - no interim divi, but committed to restoring divis when conditions allow. That's fine. I think companies which have benefited from taxpayer support, are honour bound not to pay divis for the time being.
Current trading - sounds OK;
Better than expected trading performance in July, August and September 2020; given the ongoing impact of Covid-19, the outlook remains cautious at the start of the autumn selling period
Name change - Dec 2020, Walker Greenbank plc will change to Sanderson Design Group plc - I quite like this idea, as Sanderson is probably its best known brand. I'm glad they're using a recognisable brand name, and not some silly invented word that means nothing to anyone (as name changes often are), or just using initials. A reminder from its website that WGB has a stable of lovely brands, and attractive products, some of which attract licensing revenues (valuable intangible assets).
Cost-savings - a useful benefit for future years. It's interesting how lots of companies are now saying that covid/lockdown has forced them to re-assess everything they do, bringing long-term benefits;
Year-to-date efficiency and cost-savings expected to deliver a saving of £1.2 million in the current financial year with annualised savings of £3.0 million
Outlook - sounds pretty decent to me, in the circumstances. Companies have to flag uncertainty, because things are particularly uncertain at the moment, due to covid Brexit, US politics, etc. So I don't see anything company-specific to worry about in this uncertain outlook;
Whilst our results for the six months ended 31 July 2020 have been impacted by Covid-19, we have come through the first wave of the coronavirus with a better performance than anticipated in our scenario planning, carried out at the onset of the pandemic.
Trading has been ahead of our expectations in July, August and September 2020, with the business both fulfilling delayed orders and demand returning more strongly than expected.
We are now at the start of our key autumn selling period and, owing to Covid-19, we remain cautious in our outlook for the remainder of the year. We have a clear strategy and, with the decisive action taken to improve liquidity and reduce costs, we are confident of emerging as a leaner and more agile business when the pandemic recedes.
That sounds good to me. I have no idea why the share price has fallen today.
Pension deficit - has gone up. We're getting mixed messages from different companies on this issue. Some are reporting pension deficits down, due to buoyant equity markets, others are saying deficits increased due to low bond yields;
The retirement obligation has increased from £5.7 million at the end of January 2020 to £9.2 million, reflecting the effects of reduced asset values and increasing liabilities due to lower bond yields.
I am worried that the Bank of England appears to be moving towards possible negative interest rates, which I assume would make pension deficits worse again?
Balance sheet - tremendously good. There is no insolvency risk here at all, in my view.
NAV: £61.2m, deduct £29.1m intangibles (even though WGB has considerable value in its designs & brands, so this is being super-conservative), giving NTAV: £ 32.1m. That's really strong, considering the market cap is only £41.9m
Note that working capital has shrunk somewhat, reflecting reduced activity levels in H1, so expect the hopefully improved future activity levels to suck in some of the excess liquidity. With net current assets of a whopping £26.1m, this business is in a very comfortable financial position. Shareholders should sleep soundly at night. I think management was overly cautious in its cash preservation measures, but that's with hindsight.
My opinion - I think the share price should have gone up today, not down.
As a shareholder myself, I'm pleased with these interim figures. The group has sailed through covid/lockdown, and remains in rude health. Current trading is good. Uncertain outlook is to be expected.
Overall, as with everything, I've no idea what the short term share price will do, but I reckon this is a nice share for the long term. I find today's numbers & commentary very reassuring, and better than I expected.
.
System1 (LON:SYS1)
Share price: 109.5p (down 5%, at 14:11)
No. shares: 12.7m
Market cap: £13.9m
System1, the marketing services group, issues the following update on trading for the six months to end-September 2020.
The Company will announce its interim results on 17 November 2020.
Given the sector it operates in, I would expect H1 to be bad, but in the circumstances this reads quite well;
H1 sales down 25%, due to covid
Costs 22% lower, thus largely protecting the bottom line - impressive that costs are so flexible (mainly people though, so not clear whether this is redundancies, or furloughed staff)
Reviewing leasehold property for impairment. Says this would be a non-cash charge, my view is yes and no. If locked into still paying rents, then it's future cash outflows for empty/under-utilised office space. We're starting to see the impact of work from home - I imagine this is likely to become a recurring investment theme
Profit before tax (before lease impairments) of £0.6m - still positive, seems to me a good outcome, down from £1.4m in H1 LY.
Net cash of £5.1m is up including a £0.5m R&D tax credit.
Guidance suspended & no divis.
My opinion - not too shabby at all, I'd say, given the terrible circumstances. Unfortunately there's not enough information for me to form an overall view. The danger is that H1 could include work that was contracted prior to covid, but may not now recur? With no forward guidance, I can't take this any further.
The market cap looks very low now, at some point the market might start to price in a recovery in marketing, perhaps? The cash position looks fine. Note that, in extremis, SYS1 could slash spending on its heavily loss-making startup subsidiary, so management does have more levers to pull if necessary.
Looks temptingly cheap, but at this stage, not knowing what the outlook is, then it's nothing more than a punt. Management has previously said that visibility is limited, even in the good times.
.
Water Intelligence (LON:WATR)
Share price: 465p (up 3%, at 16:13)
No. shares: 16.89m
Market cap: £78.5m
Water Intelligence plc (AIM: WATR.L) ("Water Intelligence" or "Company"), a leading multinational provider of precision, minimally-invasive leak detection and remediation solutions for both potable and non-potable water, is pleased to provide a trading update for year-to-date through the end of the third quarter.
[YTD is Jan-Sept 2020, Q3 being July-Sept 2020]
This sounds excellent;
The Company had a very strong third quarter building on its already strong 1H results.
Revenue accelerated and profit before taxes (statutory and adjusted) are on track to exceed expectations for full year 2020.
The Company also has a strong corporate development pipeline for 4Q and 2021.
Revenues by division are given, and are up 13% to $27.8m for the 9 months YTD. That's decent, but not spectacular growth. If we assume 13% growth in Q4 also, then FY 12/2020 revenues would be $36.6m, usefully above the $34.0m broker consensus shown on the StockReport.
There's plenty more detail in the trading update, see the RNS, the tone is very positive, it does look like a business on a roll.
WH Ireland has today upped its forecasts, but looks to be cautious, so I think we can probably work on the basis that EPS of US 20c is more likely than WHI's 18.4c. Convert my guess of 20c into sterling, and that's 15.4p - giving a valuation of a PER of just over 30.
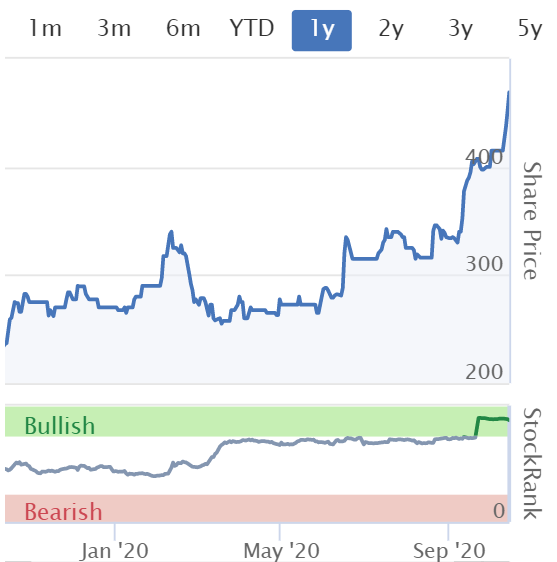
My opinion - the valuation is too rich for me now, but it looks a decent, but small, growth company, with good earnings momentum. It looks set to more than double EPS over 2 years, which is very impressive, so maybe the high rating is justified? That's for you to decide. Things are clearly going well, but well enough to justify the large price increase shown below?
.
.
Angling Direct (LON:ANG)
63.7p (down 7%) - market cap £49m
I'm out of time now, but will make a quick comment on interim results 6m to 31 July 2020, from this fishing equipment business, stores and online.
Considering that its stores were closed for a good part of H1, then these numbers look OK. It seems that a combination of pent-up demand after lockdown, and healthy online sales during lockdown, plus the £1.5m benefit from the furlough scheme, have offset the difficulties of covid.
- Revenues up 21% to £32.4m
- Profit before tax of £1.4m (up 250%)
- Net cash of £21.0m - seems very high, so why did they do a £5.5m fundraising?
- Balance sheet looks superb, with about £26m NTAV
The Board is now of the view that there is sufficient visibility to reinstate guidance for the current year outturn and confirms that the Group is trading in line with market expectations for the year ending 31 January 2021 ('FY21').
They forgot to include a footnote stating what market expectations are, which would have been useful.
Stockopedia figures show a small loss for the year, so this is nothing to get excited about.
My opinion - I've not got time to dig any deeper, but I'd say the H1 numbers look OK in the circumstances.
I like the very strong balance sheet. Also I like the growth of international websites - currently only small, but could provide good future growth maybe?
I'm not convinced that ANG's hybrid model of online, and physical stores, is a good idea or not. Time will tell, but at the moment it seems to tie up an awful lot of capital, and not generating a return from it.
Mind you, we saw with Gear4music Holdings (LON:G4M) (I don't currently hold) that a focus on improving margins, and large online sales, can suddenly become quite lucrative. I don't see ANG being anywhere close to that, so for me it's a no. Although I'll continue to monitor it, and if signs emerge of more profit potential, then I'll be happy to revise my view. Almost £50m market cap, for a business that hasn't really proven up its business model yet, seems dubious.
.
I have to leave it there for today, as time has run out.
See you tomorrow.
Regards, Paul.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

148 comments
An interesting perspective - so it’s good to use extremely low pay staff in other countries, rather than higher paid staff in the U.K.?
Follow through with that thought experiment and their is no U.K. business.
Bias can be conscious, subconscious and unconscious. Unconscious bias can be the most damaging because you don't even know you're doing it.
ANG last on the list and you ran out of time, but i think it would be worth investing more time on this one. It looked a good set of interims yet the price dropped.
This is a huge market and ANG are developing fast and as you say just like G4M, they may reward further investigation
Question.....do you look at AQSE STOCKS ?
ANG last on the list and you ran out of time, but i think it would be worth investing more time on this one.
I spent a lot of time on the report, and made time to cover the main points on ANG.
This is likely to be an unpopular comment, especially from a long time lurker, minimal poster, however I get the sense that recent complaints about Paul's Boohoo (LON:BOO) commentary on SCVR is akin to making a noise complaint to the council after they've just moved next door to Ministry of Sound!
Paul has been writing the SCVR for 7-8 years on stocko (give or take) and throughout this time has repeatedly reported on BOO's movements due to his background at Pilot and obvious passion for the share (and making money!). It was Paul's repeated coverage on SCVR back in 2014(ish) that got me interested in researching it further, leading to 2 entry points in 2015 at 23p and 25p. Needless to say I'm very appreciative of the content he covers on a frequent basis.
If you don't want to read about BOO, scroll down and move to the next company, simples!
Disclosure - still a holder after several further buy and sells along the way.
Couldn’t agree more with this comment Greg. I continually fail to understand why readers of this board would be annoyed with the author of the board posting his opinions. Add to that Boohoo (LON:BOO) (I don’t hold) is an interesting share with massive potential to move. Whether your opinion is positive or negative doesn’t really matter and adds to collective knowledge.
Saying you don’t want to hear anymore about the authors opinion is a bizarre opinion for someone reading the authors opinion.
Have just spent the past hour engrossed by Paul's analysis and the vast array of associated comments. I particularly enjoyed those from Tommy H as I stumble through my failures to buy/sell at the right time - but I am getting better, helped by the views expressed here. However today has been kind as sold some £NYCT (even tho' I missed the first big peak) to cover the losses on £RBG (as i don't think the SP is not coming back anytime soon). Discussion on (subconscious) racism reminded me strongly of Asil Nadir and Polly Peck in the 1980s. A similar rags to billion dollar empire story providing employment for thousands and then being hounded for an extravagant lifestyle and (allegedly) not being liked by the City! The empire duly collapsed and he was (eventually) imprisoned for taking £m out to fund his lifestyle.
Not sure the Kumanis would appreciate that comparison, what with convicted Nadir fleeing to northern Cyprus, thus avoiding prison until he returned years later for his porridge.
Top stuff as always, thank you Paul/SCVR team.
Slid into Boohoo (LON:BOO) @318.50 today - been on my watchlist for a while - taking a position in such a high P/E company makes my face squish up like I'm eating a lemon.
bargain!
My final comment for the day.
I just want to say that the SCVR and the comments there on just seems to get better and better on an almost daily basis.
Thank you.
I agree. Well said. And thanks Paul for a stimulating and informative report as always.
Well I am pleased with the results this morning from Walker Greenbank (LON:WGB) (I hold) I am not too surprised though by the small fall this morning. For one thing the price popped up yesterday in anticipation of the results (no - I'm not suggesting insider trading).
Also there is a lot of chatter around that the home improvements market is booming, so perhaps some had very high expectations here?
"Better than expected trading performance in July, August and September 2020" sounded very much too vague. However I am pleased to see they gave more granularity later
In their last few announcements they have given a fantastic amount of detail on their trajectory if you stitch all of them together.
So they are almost back to pre-pandemic levels of business (although some of this may still be catch-up). On this basis I see no reason that their 2022 forecast should not be back to where it was before, in fact probably higher given that they have (opportunistically) reduced headcount by around 10% as Paul notes.
Talking about the forecasts, they have actually been less helpful in this case than even Paul suggests.
Pre-pandemic there were two brokers covering WGB and during the summer one of the analysts (cannot remember who off the top of my head) reduced their 2021 forecast to a loss (My view was breakeven to a slight profit).
So the July "consensus" of around 5p was in fact an average of a small negative and a stale forecast of c. 10p. Somewhere along the line the stale forecast dropped out of Stocko's feed and the other broker updated their view to small profit.
Does that matter? Not a massive amount to be honest, except to note that broker's forecast is trending up and I would expect to see a further small upgrade. That's seen by many (including the Momentum Rank) as positive, but it is not yet reflected in the numbers as stated.
All looks good to me.
An acquaintance of mine once ran an interior design business and sold all the Walker Greenbank brands mentioned here. I would say that his clientele was more well-heeled than normal so probably not a brand that would have mass appeal.
The product quality seemed very good and the company reportedly gave retailers excellent support with marketing literature etc.
I would guess that if Covid and Brexit do not affect supply chains that this company could recover steadily.
Anyway, thumbs up for writing a lengthy post which manged to avoid mentioning BooHoo.
Thanks for that intuitive6191 re Walker Greenbank (LON:WGB) , a little bit of (in)direct experience is always valuable and I do agree that Walkers Greenbank Sanderson are probably not about to become mass market and grow their business ten fold over the next couple of years, but neither do they need to as you say,
They may well 'bag' from here and I'm reasonably confident they might 'double bag' from my recent purchase price, but I don't see a bigger bag multiple as likely.
Anyway, not your fault at all, but I'm about to break the hoodoo you mentioned ;-0
Walker Greenbank (LON:WGB) (again)
To mangle a phrase : Some may have found my lack of surprise at the share price fall disturbing,
You would have been right as the price rallied somewhat later in the day to close about 5% up.
It's probably a bit of a fools game to try to read too much into the movements of a relatively thinly traded share like this and looking at the trades of the day I would be pretty sure that there were only PIs playing today.
Slightly more relevant to anyone interested - the results presentation is now available online HERE
I'm going to have a bit of moan to them about the fact that they only provided the slide deck and not the audio/video of the the analysts call - there's really no excuse for that given how remote communications have become so mainstream in the last few months.
I cannot remember now which company it was, but one of the small caps I follow recently did a webcast and not only allowed PIs to watch it live also allowed them to ask questions - although I think this was limited to typed questions rather than audio (that's perhaps not an unreasonable stance as it allows them to screen out any irrational rantings of the kind that occasionally occur at face to face AGMs)
Anyway, just to further the point I made earlier about an almost running commentary on levels of demand - they provided this chart.
I can understand why the have not provided labels for the vertical access as this is an unusually detailed disclosure.
The chart title implies that this is total monthly revenue and I think it probably is as I don't think it quite fits the previous narrative (July was still quite short of recovering to pre crisis levels). I will see if I can get some clarity on this point.
It is certainly reassuringly V-Shaped anyway.
Paul,
Nothing can be closer to truth than the below that you said:
"As for short sellers - remember that they are deliberately trying to provoke fear & panic selling, in order to trigger a short term spike down in share price, for their personal financial gain. I respect short sellers that expose frauds like Globo or Quindell, but I have little time for those who attack good companies, in order to trigger a brief spike down in price, for their own quick bucks."
they SUCK THE MONIES OF MINOR RETAIL INVESTORS whose fault is they wish to invest in a growing company and make some money for their life. It's a SHAME.
Are you saying that short selling should be banned? If its a short term spike down and you believe in the investment how does it suck your money?
Burford is going to be listed on NYSE in a couple of days time. AIM listing since 2009. So I don't think that explanation is correct that AIM shares can't have a dual listing.
EDIT- just read down the page, and seen others have made a similar point.
They can have a dual listing but no longer qualify for IHT relief.
https://www.gov.uk/hmrc-intern...
In connection with Cloudcall (LON:CALL) Paul asked whether tax benefits ended with a dual listing. AFAICS the answer is yes if it is a recognised exchange. These are listed here and for the USA include:
BATs Exchange Inc
Boston Stock Exchange
Chicago Board Options Exchange
Chicage Stock Exchange
International Securities Exchange
National Stock Exchange
New York Stock Exchange
NYSE MKT
NYSE Arca
NASDAQ OMX PHLX
NASDAQ
__________________________________________________
Edit brucepackard having made the point that Burford Capital (LON:BUR) is about to dual list on NYSE I have double checked. The main tax benefit of AIM for PIs is for IHT purposes.
Which companies qualify?
—Must be an unquoted trading company (including those on AIM) at the date of disposal
—Must have qualified for a continuous period of six years ending on disposal or entire period of ownership if less
—Must carry on a qualifying business activity
from https://docs.londonstockexchan...
So although regarded as unquoted on AIM as soon as it is dual listed on NYSE it will be regarded as quoted and any IHT relief would, I assume, go (but I am not a tax expert!)
A nice trading update on Stock Spirits (STCK) this morning. i thought the price had fallen back quite a bit for no reason, so topped up a couple weeks ago. dont think i'll be holding long term though, the tax concerns noted are very real and i suspect it could impact the SP when the appeal hearing begins in a couple of years time.
Excellent QM Sotckranks so the algos like it. It came up in a screen I'm thinking of running.
agreed. I sold just now
Touchstone Exploration Inc (LON:TXP) is up sharply today on an RNS about a "significant natura gas" discovery.
Paul doesn't cover oil and gas but @Lord Gnome (of this parish) introduced me to Touchstone Exploration Inc (LON:TXP) through a comment in July's SCVR (https://www.stockopedia.com/co...) when the price was 57p. It's 114-116p today and I thank him for the introduction.
Thanks FREng. Glad you made some money. TXP has been a great ride so far, and a very rewarding one again today. I still think there is lots more to play for so I won't be cashing in just yet. I just wish all my investments paid off so handsomely.
My personal view on Boohoo (LON:BOO) is reputation matters - if the market doesn't like you and public don't like you that's ALL that matters. In BOOs case it's just that it hasn't filtered down to the end consumer....yet. It IS the retailers job to reasonably police their supply chain, ever heard of corporate governance? I can't believe for one minute they were completely in the dark on supply chain. Similar to your comments on Philip Green - he clearly did every single dodgy trick in the book in the past, didn't ask any questions on where stuff came from, plenty would have been off the back of a lorry at the start of his career and then went asset stripping where he could eventually offloading BHS to a serial bankrupt 'chaffeur' for £1. It'll come back to bite.
My worry on Boohoo (LON:BOO) is - if they can be that ignorant of correct business practice in buying then what other fraud/dodgy dealing could have gone on in the past that the market won't forgive them for when it surfaces?
(I don't hold a position, have been long and short a little over the last couple of months but feel it's about right at the £3 level for now given the risks)
Totally agree. They are far too big for AIM and to my mind have not applied for a full listing as they do not want the extra scrutiny that brings.
Hi Parsley,
They are far too big for AIM and to my mind have not applied for a full listing as they do not want the extra scrutiny that brings.
Where's your evidence for this please?
Note that Asos (LON:ASC) is also still listed on AIM, so are they dodgy too, by your logic?
There's an argument that, requiring a NOMAD, AIM involves closer scrutiny of announcements for example.
I think the main reason these companies remain on AIM is possibly for the IHT relief? Also, if it ain't broke, why fix it? AIM works fine for larger companies, so there's no reason to move to a full listing.
Regards, Paul.
Hi Paul, in regard to Aim listed companies being dual listed, Burford Capital will also be traded on the NYSE from Monday 19th October so it is possible. Not sure if this negates the tax advantages but haven’t been advised that it does.
It's not so much the dual listing as the stock being listed on a recognised exchange.
AIM has an exemption so the stocks count as unlisted companies, which were the original targets of the relief.
Under s.105(1ZA), with effect from 1 April 1996, the definition of “unquoted” is “not listed on a recognised stock exchange”. Shares dealt in on AIM are accordingly treated as “unquoted” for the purposes of business relief. If, however, shares dealt in on AIM are also listed on a recognised stock exchange overseas, they will not be “unquoted” and will not qualify for business relief. You should, therefore, check if AIM-listed shares have dual listing on a recognised stock exchange.
https://www.gov.uk/hmrc-intern...
Paul but why not? Its a £4bn market cap and according to your forecast could be a £10bn one in the near future. It would be a welcome addition to the FTSE 100 which has too many banks and natural resource companies.
I think a Chairman, independent of the founders, would have been the right response as well as a commitment to move to the main Board.
You can answer any legitimate question with "why not". The question should be, why - a sensible reason for going through the expense and pain needs to be articulated and "a welcome addition to the FTSE 100" isn't it. What's the benefit for Boo shareholders?
lots of investment funds don’t invest in Aim.
Hi kjb,
lots of investment funds don’t invest in Aim.
That's what I thought too, but recently a city mate of mine challenged me on this, and said it's not like that any more, or not to an extent that matters.
Plus of course, going the other way, IHT portfolio fund managers have had a lot of funds inflows in recent years, and they can only invest in IHT Qualifying AIM shares.
So possibly it evens out?
Looking at the list, I see there are 20 AIM companies with market cap over £1bn.
Regards, Paul.
kgb1953,
what do you say about £ASOS ?? Same industry, same sector, but much bigger !!! They are bigger than Boohoo (LON:BOO) too, and they do use a considerable portion of their supply from Leicester, for the same reasons that BooHoo use (speed and convenience). Has there been any scrutiny / probe on them?! If not why not?
I just want to find an impartial logic on recent attacks on £BOO.
Hi Mort, but it does look like Asos (LON:ASC) are on top of the supply chain issues in Leicester: https://www.standard.co.uk/business/asos-boohoo-quiz-fashion-leicester-a4498031.html
by what the journalists say only? Any proper report like what Boohoo (LON:BOO) did using a QC Barrister?!
Paul
"Being on AIM, boohoo can follow the Quoted Companies Alliance Governance Code, a code specifically tailored for small and mid-sized quoted companies. Boohoo’s much larger. The QCA code allowed boohoo to adopt a woeful Management “Incentive” Plan at the end of June. If the directors can crank up the share price to 600p on 17 June 2023, the two co-founders, Mr Kamani and Ms Kane, will receive £50 million each (on top of the uplift in value of their substantial shareholdings). Another of Mr Kamin’s sons, Samir, who heads up boohooMAN, will receive £25 million. If boohoo pays out these maximum amounts, it could create shares to dilute shareholders’ investments by 2 per cent. The UK Corporate Governance Code would have required a shareholder vote for this. Proxy voting advisers would have been all over it. But boohoo is a Jersey company (presumably for tax reasons) and, it says, a vote is neither required under the less stringent QCA code, nor under the AIM rules."
Investors Chronicle, No Free Lunch column, July 2020
Top turkey - I think the point isnt that they were ignorant but it was part of the business model to rely on local, personal relationships which were not monitored. This enabled them to have advantages in speed to market and cost which are part of their 'moat'. The question is whether the model now has to change and how that will impact on value. My view is that is why the share price has recently been falling. Not outrage at the practices themselves.
You can build up close relationships with factories anywhere in the world these days. Plus, I found that a lot of the overseas factories in the rag trade would have a UK front end company/people, that invoices, and manages the production with (often relatives) in India, Bangladesh, etc.
If you look at the recent BOO webinar, it covers these issues extensively. The CFO demonstrated with some slides, that it would be cheaper for BOO to move production to low cost overseas factories, and air freight it in (inexpensive on a per garment basis). Speed to market is hence very similar to UK production, but it's a lot more hassle to manage the process, and would definitely need more administrative staff at BOO HQ.
I remember direct importing being an absolute PITA, re paperwork, handling customs clearance, etc. So I completely understand why BOO would prefer to use a factory down the road in Leicester, even if it costs a bit more.
The important point being that switching the supply base to more overseas (which they said is inevitably going to happen, as they sever ties with dodgy suppliers in Leicester), will not hurt profits. It's probably going to improve them, if anything.
The test & repeat business model could mean that the initial production runs of 200-300 units might be done in the UK, if they start selling well, then a repeat order likely to be placed with an overseas factory, to do the higher volume production at lower cost, then air freight it in. Speed to market very similar.
Regards, Paul.
Further to my comments above, re share price, Because of shorters!! Causing panic selling for small retail individual investors and sucking their money to their BIG FINANCIAL advantage - it's a SHAME.
Hi kgb1953
Interesting take on it but I don’t think that is likely. Half the sales are overseas and growing faster than UK sales. So Leicester geography is not relevant in terms of margin.
I think it more likely to be investors (particularly institutions?) selling because they don’t like uncertainty and don't like to be seen holding stocks which media are trying to smear as being “non-ESG” even though the high profile exit from Boohoo (LON:BOO), SLA, also held oil stocks and BAT loan notes in its fund.
We will see. I am not buying any more because Boo it is already a 10% position and I have got caught before being heavily over-weight a particular stock (at one point I was 40%+ in Anglo Asian Mining (LON:AAZ) and Rockrose Energy (LON:RRE)) and getting severely burned but it is requiring all my self-control not increase my exposure from 10% of pf to 15%.
Like Buffett I am hoping this will go on sale even more and I can pick a lot mor stock up at say £2.20 as I did before.
Regards
Michael
BOOHOO (LON:BOO) aren't ignorant of correct business practice though, and the resulting independent review which they commissioned proves that when it comes to transparency, they are head, shoulders, in fact the whole darn garment ahead of Asos, Arcadia and other rivals. As the media spotlight grows, it will be interesting to see how much longer these worried rivals can resist scrutiny and maintain their own brand reputations. Boohoo are, once more, ahead of their fast fashion rivals.
Afternoon (just) Justin James1 - Topical choice of yours for comparison as ASOS have posted figures today - so I have looked up their published corporate responsibilities
A quoted company putting FWI (Fashion with Integrity) up on their web site
https://www.asosplc.com/corpor...
Doesn't mean they fully conform to what they publish I grant you - But they have made it an open policy. Like BOO - How accurate are their ideas compared to reality?
The bigger discussion point surely is with a large cap company - should they be seen to be looking after ALL their stakeholders?
No fraud/dodgy dealing has gone on at Boohoo (LON:BOO) - it was one of their suppliers and as far as I can see an unauthorised supplier to one of their suppliers. They did 'reasonably police' their supply chain but if investors want them to unreasonably police their supply chain how on earth will they make a profit. Also as far as filtering down to their customers is concerned that is most unlikely. I doubt whether many investors in BOO have a clue who their customer base is and will certainly never have engaged with them unless they have teenage daughters who probably don't watch the BBC or read the Guardian. I would like to see some acknowledgement that 40% of BOOs products are made in Britain whereas only 4% of £ASOS are. I hold both as they are the well managed and highly profitable leading players in a global trillion dollar market which is going to grow and grow.
I just wanted to ask what about £ASOS ?? They are bigger than Boohoo (LON:BOO) too, and they do use a considerable portion of their supply from Leicester, for the same reasons that BooHoo use (speed and convenience). Has there been any scrutiny / probe on them?! If not why not?
I also have to remind, as a person with law background, the QC barrister's report had, among other things, one key finding: that THERE WAS NO EVIDENCE TO SUGGEST BOOHOO's performance or margin was as a result of Leicester malfunctions, correct? And this is what it matters l, isn't it? If evidence was found that BooHoo was making (an)use of such malfunctions, then share price was irrelevant, and investment was not doable for me. But a top QC barrister's thorough investigation FOUND TO THE CONTRARY. So let's be impartial and let a growing British business grow!!
Re £BOO Could you expand further on: “ It IS the retailers job to reasonably police their supply chain,..”
How far are they supposed to go? Weekly/monthly/annual checks, external audit of supplier and suppliers sub contractors payslips/time sheets, interviews in confidence with employees of same? Do they also audit the fabric manufacturers who supplier their suppliers? The building contractors of their new facility in Burnley? Where does it stop/start?
I ran a small business for 30 years and no I cut some corners but in the process grew it’s sales 45 fold. Nothing on the scale of BOO (knock three naughts off) but I am proud of what I achieved. Does that make a bad person? I think what they (Kamani/Kane) have achieved is extraordinary and will back them with my money happily.
What would you have them do that they have not committed to doing in response to Alison Levitt’s report?
Regards
Michael
Boohoo (LON:BOO)
'Flaw in the logic of this programme, is that it claims retailers are getting artificially low supply prices of garments through suppliers almost being forced into committing VAT fraud. But then it later says that suppliers are spending their VAT fraud loot on £100k cars and lavish lifestyles for themselves.'
I think a combination of VAT fraud, paying substantially below the minimum wage, artificially low supply prices and lavish lifestyles of the participants are not at all mutually exclusive.
Could be an explanation of what the Asian girl was doing when stopped with 5 suitcases holding 1.9 million in GBP notes on the way to Dubai. To my mind, due VAT payments from the Midlands become gold in Dubai and travels onward to Pakistan.
Andrew Coaton
Where does it stop. So if i go and buy a car from a garage am i responsible if the garage didnt pay their VAT. How stupid are peoples views.
To answer your question no - please read the linked guidance its reasonably clear exactly what situations this rule applies too and your example scenario has nothing with these rules.
I think it will weather this because it is a sound business. I'm not sure that suggesting institutional racism will get you far. Tall poppies are always the target of the press whatever their race and in this instance some major fraud has clearly taken place. It's possible Boohoo closed their eyes............
Of more interest...Angling direct reported interims today , any assessment ?
Another firm to look at if you like cryto is Kr1 (OFEX:KR1)
They have released an RNS today. They have a market cap of £16m and nearly all covered by the holding in just one asset, see below. They are also being questioned over a US listing. Easy to dismiss crypto & the new blockchains but this is attracting $ billions of investment in the US. I wouldn't put a lot into these firms but as to Pauls ‘multibagger punts’ list you can add these two imo.
There are a couple of good threads on bitcoin/blockchain on here.
KR1 plc (AQSE:KR1), a leading digital asset investment company, is pleased to
announce that the Company has sold 202,297.55 DOT tokens in the Polkadot
(“DOT”) project at an average price of US$5.12 per DOT token, generating
proceeds of US$1,035,043.46.
This partial exit represents only a small part of the Company's Polkadot
position and, as previously announced, KR1 is actively staking a significant
majority of its Polkadot position to generate recurring revenue.
As at the date of this announcement, KR1’s total holding of Polkadot tokens
is 3,558,490.89 DOT,
Is this basically the BooHoo fan club thread nowadays?
Yes.
Paul - I welcome the commentary on £Boo as I think its a fascinating company.
It would also be interesting to get your thoughts on StitchFix. Which I think are another extremely interesting clothing retail company. £SFIX have managed to sell over 5 billion USD of clothing "sight unseen" and have essentially built the return rate into their offering.
I know everyone says "company x is the Uber of <insert Industry here>" but I see Stitch Fix as the major disruptor and a potential massive winner in the apparel retail industry.
I can't think of any company in the sector as interesting as £SFIX or anyone better qualified that you Paul to look into it and give us your opinion. Please consider it if you have time.
I listened to an interview with the founder on Patrick O'Shaghnessey' s Invest like the Best podcast recently which I recommend.
Hi Carey,
Thanks for the pointer. I had a quick look at SFIX - lovely revenue growth, but it doesn't seem to make any profit. I do sometimes wonder if I'm wasting my time looking at UK small caps, when US growth stocks do so well.
Interesting company though, so thx for flagging it.
Best wishes, Paul.
Hi Carey
Thanks for highlighting SFIX (StitchFix for those not in the know).
I have a lot of interest in companies not listed in the UK, so it's nice when there's a comment that aligns with my own interest.
This is the point where I'd offer to buy you a drink and say, "hey, maybe we can go some place quieter to talk about our favourite stocks?" but alas, I shall need to keep the commentary public, so apologies for those not interested.
I too really like SFIX and it's pretty close to the top of my buy list. I'm just waiting for some sort of vaccine-induced pullback for online stocks before opening a position.
I must admit I was a major sceptic as well - personalised online stylist? How on earth could that work?
But the numbers don't lie.
Revenues are growing fast, the company is cash flow positive (it might be neutral in the near future, but that's fine by me where there is growth), and it really does have a unique proposition.
More than the original service (set number of items being sent to you each month, you keep what you want and return the rest), it's actually the new "Direct Buy" option that has me interested.
Imagine going to a website or store where they know everything about your fashion interests, and have clothes they know you might like laid out for you? No time wasted browsing the 1,000's of SKUs, or looking for the right size. All you need to do is see what you like the look of, pick it up and buy.
I also saw the last quarter results and there was a rapid increase in first time users, which should lead to material increased in revenue over the next 1-2 quarters.
Amazon are muscling in on the space - a good sign in my opinion - but with not very good reviews (heard anecdotally, i haven't confirmed this), so there must be something there.
In summary, it ticks a lot of the right boxes, and I'm sure this year has sped up the growth story.
As mentioned, no position yet, but I imagine there will be one before the end of the year.
Do you hold?
A
ps there's a How I Built This episode with Katrina Lake, the founder, if that is of interest
Boohoo (LON:BOO) Yes but based on the facts, anticipated revenue and income growth and likely overseas expansion. And as we are all here to make money Boohoo (LON:BOO) probably more than most companies on the LSE is a good place to do that over the next five years!
I could be wrong but having made a 44% CAGR on my first foray into Boohoo (LON:BOO) between 2015 and 2020, I believe that while it might not quite equal that GAGR, I think it is distinctly possible. My current investment (started June 2020 and added to subsequently) is up 17% a CAGR of 62%.
Additionally the broker note put out at the time of the results was very downbeat and certainly did not seem to reflect the likely outcome next February (full year results). Revenue to Sept 2020 was £816m and Zeus (house broker) is projecting £1609 for the FY. So a weaker second half (which includes Christmas, and hopeully a less "Covidy" enviroment.
We will see but I will make a note to self as I don't want to re-write my memory when sales come in at £1609mil!
regards
Michael.
can you people stop attacking readers who like to read and know about Boohoo (LON:BOO)?! Why can't you simply move on to the next section if you don't like?! Come on.. it's easier than writing a comment, is it not????
Paul, I am afraid I don't agree on several levels. At a macro level it is important that journalists are seen to unearth scandals like this. We see globally (Russia,China and Mr Trump) trying to downgrade, kill, torture journalists who are essentially keeping the rest of us informed. Some very brave people there. I do agree the standard of journalism seems to have dropped but it would wouldn't it under constant threat and exploitation. The second issue I have is that whilst I am keen to defend my investment in Boo I also recognise it is working in a dirty sector which needs cleaning up. In this world of "self regulation" it is up to the companies to clean it up and this shows why that is so misguided (as it is expecting the City to self regulate!!) Boohoo are partly responsible, to say they didn't know isn't enough. Either they get to self regulate or we find tough people to regulate but one way or another dishonest people drawing from our society need to be stopped. Disappointingly I am a seller not because I think it is a good prospect but because I believe in our society more. Misguided I might be.
‘Trump) trying to downgrade, kill, torture journalists...’
I know ‘Orange Man Bad’, but you might be overstating your case.
Sorry Martin, I wasn't saying he was doing that, I was combining 3 leaders with 3 actions. He is more downgrading journalists "fake news". Clumsily put I will agree with you. Although I suspect if given a free rein he would go further. But politics does not enter this investment page, so I withdraw that one.
Dear Camtab what has BooHoo got to do with Donald Trump?
Jamal Khashoggi was living in the US and a columnist for the Washington Post. US Intelligence became aware of a Saudi plot to kill him and warned the White House. That warning was not passed on to Khashoggi. He was killed at the Saudi embassy in Istanbul.
https://en.wikipedia.org/wiki/...
And the link to Boo?
Quite clearly Trump is trying to downgrade journalists. And there are also plenty of recent examples of journalists being targeted by police at protests in the US. As yet torture and murder remain mainly the province of the other two leaders in the post, but I see nothing wrong with the original statement.
Re: Trump, I presume you are referring to Mr Assange, though the assassination attempt was aborted apparently.
I respect peoples view on Boohoo on here and every investor hasma choice of selling shares rather than buying more if they feel the business ethos doesnt sit right.
What is clear is Boohoo will be successful irrespective of where they but their in demand products from and it would be aa natural conclusion that they will use overseas suppliers to ne succesful if necessary
Great update from Kainos (LON:KNOS) and good bump in share price - not a small cap but I think Paul has looked at this before.
Yes I noticed that, Kainos (LON:KNOS) was up about 30%. Pity I haven't got a team so we can cover everything - that would have been interesting to look at, for someone who was primed by being familiar with the company. I think we looked at it here a couple of years ago. But as always, when you look at so many companies, about 500 I do personally, it's impossible to spot things. I just review the numbers, and my specialism is balance sheets of course.
Best wishes, Paul.
On US listing, if you like a punt, have a look at Argo Blockchain (LON:ARB) , UK bitcoin miner, without going into what the hell this actually means, on all KPIs they are better than almost identical US companies, but rated at about 1/4 of the US market caps. Shareholders have been pushing the management to list in US with the justification of ‘why wouldnt you’ , operations in US, nearly all bitcoin miners there & US markets understand BItCoin in the way UK just doesn't.
The BBC generally hate any form if success and project fear has infected every part so if attacking commerce & success & any form of positivity is racism then they are guilty.
However, journalism.... or government mouthpiece as i believe the definition is changing to, love a headline and Boohoo (LON:BOO) perfect to hang all this possible VAT fraud off. Massive fraud in the rag trade, no, surely not, well i never. However without Boohoo (LON:BOO) there I suspect this would be page 16 news at best.
Boohoo (LON:BOO)
It's not technically correct to presume or say that boohoo has zero obligations with regard to suppliers in their supplier chain commiting vat fraud. Missing trader vat fraud is a big issue (so big that hmrc are completely re-organising how vat works in construction and have already done similar with overseas transactions.
HMRC official advise is as follows in that regard
How can missing trader fraud affect your business?
If you knew or should have known that your transaction was connected with fraud then HMRC may refuse your VAT claim in respect of that transaction. In determining whether you knew or should have known HMRC will consider all of the circumstances relating to the transaction, including whether you took reasonable steps to verify the integrity of your supply chain.
https://assets.publishing.serv...
Note i am not saying that it is a problem for boohoo , i really doubt boohoo would get dragged into this area presuming their checks have been "reasonable". However if its flagged up as happening in their supplier base and it is their customers vat that has partly been stolen down the line they do at least need to pay enough lip service to keep the vat office happy.
Where does it stop. So if i go and buy a car from a garage am i responsible if the garage didnt pay their VAT. How stupid are peoples views.
Andrew even the biggest advocate of Boo would admit there is a difference between a garage and a listed company with a £4bn market cap.
I have largely tried to avoid joining in on the recent commentary on Boohoo (LON:BOO) . It is a company that falls outside of my risk threshold wrt corporate governance. I don't think they are dodgy, but neither can I be sufficiently comfortable that they are not, so they are just not in my potential investment pool.
I do though think that the whole supplier fraud is perhaps being to vehemently dismissed by some bulls.
There are quite a few comments I could have picked on, no offense to Andrew that this was the one I first happened upon when looking back.
Probably you are not responsible in this case. However if you get a mate of a mate to service your car cheaply but only if you pay in cash - you might be implicated in any underlying fraud; and if you get some bloke that knocked on your door to dispose of your building waste on the cheap you are absolutely liable if he then fly tips it in the local park.
At one level there is the question of whether took all 'reasonable' (whatever that means) steps to ensure that their supply chain is clean - the bull view is certainly that they did, I have no way of knowing.
On a somewhat more focussed note, I seem to recall that some of the earlier accusations suggested that might be quite a close relationship between Kamani and some of the alleged wrong-doers. I do not know if this is true, but I do not think I saw it rebuffed either.
I am sure that some will choose to pull the race card on this next comment (frankly I think I have earned my spurs over the years on the subject of equality, so I will roll with that) ; but there are some communities (by no means all of them 'ethnic minority') where personal relationships (without provable economic relationships) can be very significant.
I certainly do not mean to cast any mud in Mr Kamani's direction, but from a personal investment point of view I try not to give ANY circumstance the benefit of the doubt. There are so many available investments that I don't mind missing out on some.
FWIW I can immediately think of three (there may be more) stocks that fail my initial 'governance' sniff test . Each of them has soared in value since I rejected them, but each of them I still think could easily crash and burn.
So I will continue to watch from the side-lines with £BOO - good luck to all holders but it just falls outside of my risk tolerance.
Thanks for yet another good update but very disappointed you feel the need to mention your unfounded thoughts on possible racism. For you to suggest it may be deliberate or subconscious racism behind this journalism, without advising of any evidence to support your thinking is to put it politely....unhelpful.
Hi Arpe,
Re: Boohoo (LON:BOO)
I have to confess it has also crossed my mind over the last few months. And whilst institutional racism is hard to prove, I don't agree that Paul should be censured for saying this; indeed, I thought it rather a brave thing to say.
cheers
Francis
EXACTLY. Do you want us believe that journalists are not having racism ???? Wrong. Black people, people from third world countries, certain religions, women, these are still BEEING DISCRIMINATED. This is the bitter truth...
Mort
We’re just noting that no evidence has been produced that this is racism on this occasion. The notion that the media are only reporting on BooHoo’s potentially poor working practices and supply chain issues has been debunked in earlier comments.
Are we not allowed to ask for some evidence to support suggestions that this is racism at work?
I imagine all the thumbs down are from the white middle classes... Bravo Paul, Bravo mort
Probably as much because of the capital letters, overuse of exclamation marks and rotten spelling/grammar....
Hi arpe,
"Unhelpful" to whom? I don't accept your finger-wagging rebuke.
I think we should ask the question, why is it that the Kamanis are being hounded relentlessly by the press re-hashing the same story over & over, for failings of their suppliers, when all the other retailers are being ignored, despite the reality that many of them are also turning a blind eye to sweatshops abroad, with far worse pay & working conditions than factories in Leicester.
My niece has been educating me recently about subconscious racism, and there's a lot of it about. There's no doubt that the press love pulling down rich, successful, flashy people who are seen as having got above their station, especially if they're minorities - like the Kamanis, Philip Green, etc.
Paul.
Paul
On the one hand you’ve asked for evidence from another person here about an opinion regarding the AIM listing, but on the other you haven’t produced any evidence that the journalists involved in the reporting are racists either consciously or sub-consciously. (Is there evidence, for example that these journalists predominantly criticise ethnic minorities and ignore misdeeds by others on a regular basis?)
You may see it that there is a focus on BooHoo in this particular incident and others have not been criticised but it tends to always be the way that large companies get greater scrutiny. E.g. working conditions at Amazon and Sports Direct are scrutinised too.
Hi Paul,
Apologies it wasn't meant to be a finger wagging rebuke but reading it back I can understand your comment.
I think too many people today wrongly accuse or infer racism without just cause. My view is the press enjoy bringing down anyone that is successful (and many who aren't) regardless of ethnicity.
My comment on "unhelpful" was because I felt it detracted from what was otherwise a good update.
arpe
Hi arpe,
Classy reply, thanks. Points taken.
I just wanted to raise the possibility of unconscious racism maybe being a factor in the hounding of the Kamanis by the press, whilst they ignore everyone else in the sector. I don't have a particularly strong personal view on it, but think it's an important question to ask.
Take last night's Radio 4 show. It highlighted Select (170 store fashion retailer) as being a customer of the dodgy supplier case study. Yet there was no gloomy music added, no mention of who the people behind Select are or their lifestyles, and they were cheerfully glossed over as completely blameless. Then when PrettyLittleThing were mentioned as another customer of the same supplier (that was fiddling its VAT through shell companies), the tone was totally different, far more accusatory & implications of some kind of network of evil! Yet the positions of Select and PLT were identical viz the supplier concerned.
It's this that concerns me. It's clear that journalists are not being impartial, but are presenting information in a skewed way, which presents BOO as villains through guilt by association, simultaneously emphasising that other retailers caught up in the same thing, are completely blameless despite the circumstances being identical.
Regards, Paul.
Or the Issa brothers who the press were trying to dig the dirt on within 24 hours of the announcement of the deal to by Asda.
If it is not racism or envy/British dislike of success (and I believe it is likely to be one or the other or a combination of all three) then it is difficult to understand why Boohoo (LON:BOO) alone has been singled out. The can't, surely, be the only business selling cheap clothes in to the UK?
On Philip Green and his Monaco residency if you were able to pay your self a £1bil dividend because of the profits the business you operated or your share investments generated, would you happily pay the £400mil in tax or would you move to Monaco and pay nothing? I know what I would do but then I like Monaco.
Thank you Paul for the write up of the program. I wish you synopsis could be disseminated more widely.
One wider aspect of the current investing enviroment is that we are all told to think long term (I am talking about investors rather than traders), which I try to do but then shares like Novacyt Sa (LON:NCYT) (which I hold and have made a lot (for me) of money on) are bid up even though more than a couple of years out it is IMO prettty much impossible to value and companies like Boohoo (LON:BOO) and to a less exten Anglo Asian Mining (LON:AAZ) (both of which I hold) where one as reasonable long term visibility as to revenue and income, are bid down on short term stories.
Regards
Michael
Michael
It is just BooHoo that happen to be caught in the headlights this time. There was a big furore about Primark when a factory in Bangladesh where they sourced garments collapsed. Parliament and the press were on and on and on about the working conditions at Sports Direct for a long time. Amazon have been regular criticised for allegedly poor working conditions. Amazon have also been criticised around VAT issues.
Boohoo have not been singled out.
Can't share your view on aggressive tax avoidance on a massive scale. It is this sort of thing that gives capitalism a bad name. No, I would not move to Monaco.
I would not move to Monaco either but I see no harm in wishing to reduce tax. Monaco does not appeal to me as a place to live and very few tax havens do. Lived for 30 years in Hong Kong where I paid next to no tax other than tax on income from my property investments in the UK. It was great to be able to buy and sell UK property without paying CGT. Of course that is not possible any longer but no one surely can blame me for taking advantage of the situation ? I support my share of charities,mainly in Africa,so I have a clear conscience.
I would not move to Monaco either but I see no harm in wishing to reduce tax. Monaco does not appeal to me as a place to live and very few tax havens do.
You don't even need to move to monaco - just move your spouse there :) (from memory that's what green did?) - although i guess the downside is that shopping bills coming out of the "household" account may rise somewhat.
Hi Caper4,
Good for you! Monaco is a bit like Luxembourg, in my view - you almost die of boredom after 2 days! the selfish, vacuous people who live there are welcome to it!
Having done my due diligence on ZANE (small charity in Zimbabwe) in 2019, I cannot understand why anyone would buy eg jewellery, instead of giving small amounts of money to ZANE every month, to help keep people alive & pain free, with $15 per month drugs, per person.
On a small scale, my own reckless lifestyle has recently caught up with me - covid19 was a nasty illness back in Mar/Apr, but it seemed to linger. As it turns out, covid seems to have triggered type 2 diabetes in me, serves me right for being an idiot. But the point I'm making, is that the extreme tiredness, and shooting pains in toes & fingers, etc, are now receding due to me taking Metformin pills 3-5 times per day. I'm imagining what it must be like for pensioners in Zimbabwe, who cannot get the $15 per month Metformin tablets. Many can't. I went to 4 old folk homes in Harare, where those tablets were given out to old people. It's only now that I realise what a life-saver it is. Your feet go completely numb without the pills. You can't sleep. Imagine if there wasn't any medication to help at all?
I met the people in Zimbabwe that ZANE looks after. If you give $15 per month, that pays for the Metformin for one person, who otherwise would suffer terrible pain.
I know many of you have ur own charities, but please remember ZANE if you can.
Thanks, Paul.
I hasten to add I dont live in Monaco, just visit from time to time and wished I did!
Monaco is awful! Expensive hotels, and I am so angry about losing 5k Euros on some wheel of fortune thing c.2005. Plus my partner forced me to buy a Versace bedspread! If we'd stayed there another week, I'd have gone bust. Little did I know that 3 years later the GFC would screw things up for me!
Still, you can't look back in life. Let's look at these experiences as formative, and character building.
I got a horrible email today, from an old friend. Simon. Turns out that he blames me for his life being a disaster, despite the fact that he blew about £500k by being a complete idiot, punting on resource stocks I think.
But 8 years later, he blames me for accidentally blowing £7k on some shares I liked. That went wrong.
I really do despair.
What happened to personal responsibility? What happened to manning up?
Some shares work, some shares don't. Stop blaming other people for your own wild punting on shares. Don't get anywhere near that kitchen, unless you know what you're doing!
I've tried to help all readers who say they're upset. But when Simon waited 8 years, to tell me he is angry with me, for trying to help him make some money. you can imagine what I think of the little scrote. MAN. UP.
Paul.
Lol! Mike Ashley & Tim Wetherspoon have each just pulled up a chair...
Thanks for the write Paul much appreciated.
With regard to Boohoo (LON:BOO) and Philip Green (AKA Sir Philip Greed by one newspaper), I would not be so quick to cry racism.
Look at the opprobrium heaped on Fred the Shred. What about the brickbats being throw at Richard Branson? Oh, and then there’s the chap that bought BHS from Sir Philip. And of course there are many others who are rightly or wrongly vilified. Nothing at all to do with racism.
As far as the fast fashion sector is concerned, my impression is that it is an environmental disaster so I choose to avoid it entirely for that reason.
As far Philip Green is concerned, I think that the dislike of him generally also has a lot to do with the way he and his family use Monaco residency to reduce their tax bills here. All perfectly legal as far as I am aware, but pretty much what has become known as aggressive tax avoidance.
Graham To some extent I would agree but there is a bit of a difference in that Fred the Shred trashed a huge bank through an injudicious expansion policy and Branson while I am (or least was) a fan disappeared of to his island tax haven to spend his money on a slightly out there space program and when his airline got in to trouble through Covid, he asked to be bailed out by the UK government. So brickbats deserved IMO. See my other comment about Green.
Regards
Michael
re £BOO. I don't think this is racism. There is a genuine scandal here as both the journalists and the company review has highlighted.
The implication is that the relationship between Boo and its suppliers were very strong - maybe not in a truly legal way but more integrated than fully arms length. Similar to PLT when it was not fully owned. Also that BOO likely relied on these personal relationships to monitor supplier performance than supply chain auditing that other suppliers adopt. Correcting this will require new capabilities and there will be an impact on its business model potentially increasing either its costs or the prices of its products.
I doubt if any current shareholders of Boo will be selling the shares based on the story itself and estimating whether fixing these problems may impact on profits and cash flow.
The focus of BOO investors should be on whether the shares are likely to go up or down, and whether their own ethical selection criteria are satisfied. Raging at the media coverage is a distraction.
Better than expected interim results from Walker Greenbank (LON:WGB). I would have expected share price to move significantly higher. Profit higher than expected, balance sheet much stronger and cash flow well ahead of expectations. But this company seems well under-the-radar of most investors. Restructuring and reorientation of the company under relatively new (couple of years) CEO, Lisa Montague, is continuing apace. More licensing agreements, significant cost savings. New company name soon - Sanderson Design. By many accounts, UK spending of DIY and home improvements is going "gangbusters" as lockdown reduces other discretionary spending options (eg travel and eating out etc). This is both a value and a turnaround stock. Should be a lot higher!
Walker Greenbank (LON:WGB)
Half year results out this morning for Walker Greenbank (StockRank 93).
Better than expected but still cautious.
The new management seem to know what they are doing. I know the Chairman and have a great deal of confidence in her abilities and that of her team.
I like the change of name to "Sanderson Design Group plc" and the simplification of the structure and branding.
The restoration of salary levels back to 100% and almost all employees back at work is a good sign.
Holding back on the interim dividend is also sensible in the circumstances but might weaken the share price in the short term.
A cracking q3 update from Water Intelligence (LON:WATR) this morning.
Revenue growth of 13% over the 9-month period compares to the 6% broker consensus for the full year and my own estimate of 10%, so upgrades will be coming.
The core franchise business revenues grew by just 2%, but that is adversely affected by the ongoing reacquisition of franchises. I reckon the underlying growth rate here has been around 4% for some years now.
The three other segments are the growth engines for the business. US-owned franchises grew 15%, although the underlying is lower as this benefits from reacquisitions; insurance-related business grew 14%, having added another national insurer to the roster; and international franchises grew 21%, although again benefiting from reacquisitions.
Naturally, with revenues so buoyant, profit is also above expectations (although it is too early to quantify this) and the increasing scale of the business should bring material benefit from operational gearing.
All in all, Water Intelligence appears to have sailed through COVID-19 without issues and be very well placed to continue its growth trajectory without further recourse to the markets or to debt.
WH Ireland have indeed upgraded their revenue forecasts for Water Intelligence (LON:WATR). Both 2020 and 2021 have been increased by 3% to $35.0m and $36.9m, respectively. In both cases, I would suggest, they remain too low.
The WHI EPS estimates have increased by 6% for 2020 and 11% for 2021, illustrating the benefit to the bottom line from operational gearing. Of course, if their top line is indeed still too prudent ....
Thanks EC - great to get your take here - keep them coming please! Looks like I've missed the boat on this one as it looks a bit rich to me now, at around 32x 2020 earnings and 5x book value - but then thats what I thought before and it's turning out to be one of those ones that always seems a bit rich to me! I've put it on the watch list - I certainly like the growth market - leak detection.
cheers
Mark
Dowgate have also upped their forecasts for Water Intelligence (LON:WATR) today, by amounts similar to WHI.
Their distribution of investment recommendations is quite comical:
Buy : 142
Hold: 0
Sell : 0
A perfect illustration that, whilst broker notes can be useful, they should never be trusted, particularly with regard to valuation.
I came to the party late on this one only buying some 2 months ago. Overall its a good performing company in a growing market with seemingly market leading technology, what's not to like? For me this looks like a lock in the drawer and keep for a long time type company unless it gets snapped up.
Hi Brookeda,
In the interest of balance, I should be clear that the "what's not to like" column for Water Intelligence (LON:WATR) is not empty. Corporate governance is a genuine concern, with a dominant executive chairman and too many related party transactions. This alone has been enough to put off many Pis who might otherwise have been interested.
Fair point and I don't disagree with that
Cloudcall (LON:CALL) Cloudcall lists on the OTCQX market in US to provide US daytime trading in its shares in dollars. Main listing remains on AIM. Good news and logical as they have been attracting US investors recently: http://uk.advfn.com/stock-mark... Also sensibly holding a capital markets day on 22 October to help promotion. (I hold)
Hurray - finally! we've been saying this to management for a while now.The US is a much better market for this company and much of its business is done there.
Thats interesting on Cloudcall (LON:CALL) listing in US
After Gan (LON:GAN) success and if I was a CEO of a growing tech company, it would be high on the agenda.
I cant see Frontier Developments (LON:FDEV) £CODE Interceed Gvc Holdings (LON:GVC) Kape Technologies (LON:KAPE) EagleEye, not benefiting from a rerating or takeover.
Will be a sad state of affairs if this starts to happen but i have read recently of two other firms looking at a duel US listing- i cant remember which ones.
The optimists will say that the UK tech will catch up but the US markets view tech very differently & who can argue with the success of their approach in backing and paying up for ideas. Cloudcall (LON:CALL) and the other companies listing in US will be watched very carefully i’m sure. In this type of market, i could very easily imagine ‘US listing’ also being the next ramptastic headline. Come on Bigdish (LON:DISH) its obviously the next step to sweat that equity man.
Short term id like all my tech to relist, long term it will be terrible for the UK market.
I think £PTRC might have been one
Hi Sheeza
Couldn't figure out who you mean by PTRC - typo possibly? Thanks
I have recently taken a role within a Private Equity funded unicorn based in Europe. Like most there is a plan to float in a few years but the decision has already been made to go on the NASDAQ as the European markets just wouldn't rate it as highly.
Interesting development; I'm a bit ignorant of what the OTCQX market is so will have to do some research. I suspect, as someone else pointed out earlier, a number of UK tech stocks will at some point (if things continue) decide to make the jump given the disproportionately low valuations the UK seems to ascribe some of them. Loopup (LON:LOOP) would be a classic example that would be trading at many multiples higher with a proper U.S. listing (edit: I see the OTCQX market is what used to be the pink sheet market, so I am less enthused by that prospect, and would suggest a proper listing in the US i.e. NYSE/Nasdaq)
HI Fegger,
I am a little bit more circumspect when companies list in the USA from AIM after the painful experience with £VRP. Verona Pharma listed in the USA, and raise the funds need to take the business forward. Now it is delisting in the UK causing forced sellers and a decline in the share price. For example, holders in SIPP and ISA's become forced sellers if they want to continue holding cash in the wrapper.
BSV
Thanks for taking the time to write up Paul - really interesting comments. I too hold Boohoo (LON:BOO) and whilst the negative press is a bit uncomfortable in the short term, long term if the company is successful the share price will follow. The USA growth is particularly exciting. For our journalists, headlines containing Boohoo rather than "Rose Fashions" will definitely get more clicks as the reader pointed out, despite the offender being Rose Fashions.
Did Boohoo know and agree to turn a blind eye and meet the supplier in the middle price wise if they paid those invoices with VAT - only Boohoo will know for sure, of course they deny it, so we have to make our own judgement.
Thank you for the comments about Boohoo (LON:BOO), when I read the article yesterday I didn't understand why they were being dragged into the story. From the article it is the factories at fault, not the retailers.
It would be like a customer walking into a shop, buying an item then being criticised as the shop does not pay the correct tax.
Ramsdens Holdings (LON:RFX)
Fairly positive update today, guiding "anticipates reporting Profit Before Tax of approximately £9m in its next audited accounts covering the 18-month period from 1 April 2019 to 30 September 2020". Compared to 6m for the previous 12 month reporting period seems ok. Strong balance sheet, noted their loans are paying down returning cash, while good for the balance sheet is a headwind on future earnings.
I have a small holding. Was a bit dubious about their FX business (13.1m income in previous period) as in the long run this should surely move to pre-paid cards and online apps. However a quick look at their website gave a competitive Pound-Euro rate of 1.08400 which is not much more than Transferwise at 1.09896 at least for small holiday amounts. So this part of the business should survive a few years longer, until the govt eventually withdrawals paper money from circulation.
So for now happy to hold, in the expectation we are in the right part of the cycle to buy subprime businesses.
I hold RFX. They changed their year end accounting period earlier in the year. Correct me if wrong but 18 months trading to end Sept has produced £9million PBT but they advised in May that the year to end of March produced £8.5million. Does that mean the profit for the last six months was only £0.5million?
Awaiting Paul’s assessment.
£RFX I hold. The similar factors that affected H & T (LON:HAT), must have affected £RFX. Ramsdens Holdings (LON:RFX) also has forex or lack of to deal with ( forex biz obviously fell given all this messing about with quarantine for overseas travel).
On another note, Simon Thompson wrote a great piece on Ramsdens Holdings (LON:RFX) earlier this year citing that a large proportion of £RFX's sites are coming to an end. Thus highly negotiable for discounted rents. ST also mentions that, given the death of Thomsons holidays, there are fewer players in forex market for holidays etc. Ramsdens Holdings (LON:RFX) will be benefitting from this.
Best to view Ramsdens Holdings (LON:RFX) as a stock, like Easyjet (LON:EZJ) and H & T (LON:HAT), once C19 vaccine found, will rally big time, particularly because of its pawnbroking biz which is super relevant in today's economy and the high gold prices. So long run (2-3 years), it's a no brainer for me. DYOR
Morning Paul, I'd love to hear your thoughts on RFX, 35M Mcap, 16M in cash. Trading statement out today guiding of PBT of 9M for an extended 18 month accounting period. Circa 1M PBT for the last 6 Months March to September with Covid hitting hard. Seems like the team have weathered the storm particularly well if the can move back to circa 8M PBT in the next few years the shares appear terrific value. Stockopedia metrics are brilliant as well.
Best, Phil
Angling Direct H1. All looks very positive under new CEO, with sales and margins strong. Cash mountain?
Paul, could you please take a look at RQIH numbers out this morning? Narrative reads well, but the numbers need an interpreter. Distribution is being restored. Future positive but I dare say the devil is in the detail as always.
Another buying opportunity for £Boo then!
I have no problem with Boo being covered here, especially as I hold but in general, covering the occasional large cap that can give a picture of the economy is good in my opinion.
Interesting. BOO aside, could it be that Leicester will become the English Malmo where dog will eat dog?
My morning smallcap tweet:
Water Intelligence (LON:WATR) Ramsdens Holdings (LON:RFX) International Personal Finance (LON:IPF) SkinBioTherapeutics (LON:SBTX) Directa Plus (LON:DCTA) Petards (LON:PEG) SysGroup (LON:SYS)1 Arbuthnot Banking (LON:ARBB) STM (LON:STM) Audioboom (LON:BOOM) Stock Spirits (LON:STCK) Galliford Try Holdings (LON:GFRD), Angling Direct (LON:ANG)
Water Intelligence (WATR) guides FY pretax above expectations (mkt?) after very strong Q3. [SP=464 Cap=68m]
Ramsdens (RFX) guides FY(Sept - 18 month) pretax c. £9m. Is this in line? "We are pleased with the Group's robust performance." [SP=111.5 Cap=34m]. I hold.
International Personal Finance (IPF) Q3 returned to profit, collections effectiveness improved to 95% of pre-Covid expectations. "Prudent relaxation of credit settings resulted in a 55% increase in credit issued in Q3 compared to Q2." Still 49% down YoY. In line? [SP=53.2 Cap=119m]
SkinBioTherapeutics (SBTX) £4m placing and £0.5m OO at 16p , an 11% discount. Cash nneded to "to explore the use of the SkinBiotix® technology in areas such as, oral and hair indication...establishment of its own lab facilities...and explore both the launch of an own-label cosmetic product and partnering opportunities for cosmeceutical product lines." [SP=18.4 Cap=24m]
Directa Plus (DCTA) good performance at 51%-owned environmental remediation business Setcar. 9 month rev up 15%. Contracted order book is expected to generate revenue of €4.0m during 2021 and €3.0m during 2022. [SP=69.8 Cap=43m]
Petards (PEG) wins contract for over £1.3m to supply Porterbrook Maintenance Limited with eyeTrain systems. Deliveries are expected to be completed during the first quarter of 2021. [SP=6.75 Cap=4m]
System1 (SYS1) guides H1(Sept) rev and gross profit down 25%. "The downturn was particularly pronounced in the US, against a very strong H1 2019/20, while the UK and Asia Pacific produced double-digit revenue growth." Guides pretax £0.6m down 57%. [SP=112.5 Cap=14m]
Arbuthnot Banking (ARBB) recent Q profitable. Loan balances up 3% , deposits up 14%. AuM up 4%. "Resilient". [SP=745 Cap=112m]
STM (STM) business weak: "certain initiatives are not yet delivering the volumes of business that we had expected". "Options workplace pensions solution business currently achieving a 50% revenue uplift year-on-year, it is now expected to fall short of its overall revenue target by circa £0.32m." Also flexible annuity new business slow. [SP=35 Cap=21m]
Audioboom (BOOM) formal sale process end with no acceptable approaches. £3.15m subscription at 225p, a 27% premium. Q3 rev up 15%. YTD rev up 18%. YTD loss $1.6m, 32% down. [SP=177.5 Cap=25m]
Stock Spirits (STCK) guides FY(Sept) trading ahead of mgmt exp. [SP=225 Cap=450m]
Galliford Try (GFRD) gets two new lots in the Thames Water AMP7 framework worth up to £60m PA over 4 years. [SP=78.8 Cap=88m]
In line: Angling Direct (LON:ANG)
Thanks for your comments Paul. I think that the media should be exposing dodgy and illegal working practices in Leicester. No doubt about that. However Boohoo (LON:BOO) is now their shorthand for these problems and it's dead easy to keep bringing the company up as an example. The fact that it's not Boohoo's job to police their entire supply chain and ensure that nothing dodgy is going on is easily overlooked. Still it's clearly positive for the Boohoo brand to steer clear of these issues and the board appear to be moving in the right direction.
From an investment perspective the company is galloping along and appears to be picking up momentum rather than losing it. At some point the share price will respond to this underlying performance although any deflation in the high P/E rating will act against a significant rise. So I see share price volatility remaining while the current publicity rolls on and until it fades from view.
Sensible half year results out of RQIH today. I hold.
An incredibly difficult company to analyse, but after some years of switching around to find a solid strategy has now settled down - just, as in the last couple of months. For what it's worth, having historically held Beazley, Amlin, Catlin, Lancashire, I consider that this is currently the only insurer of this type to hold. The others are overpriced, for historic reasons, in my view.
This one has a good chance of running and running, I think.
Greyinvestor,
Randall & Quilter Investment Holdings (LON:RQIH)
After a brief look I completely agree.
Interest was completely killed off by seeing that since 2011 messrs. Randall & Quilter have sold down their holdings from 37% and 8% to 5% and 1% respectively - despite their generous share awards under various "management incentive schemes".
I think they know a lot more about the prospects for this business than I could ever discern.
Bonitabeach
No position.
Randall & Quilter Investment Holdings (LON:RQIH) - Not sure what you mean by 'only insurer of this type..' Hiscox and the others are mainstream Market insurers. R&Q are concentrated into a small specialist niche of the market and so yes they are difficult to analyse. Bonitabeach makes an interesting point about the founder shareholdings - but thats going back over so many years - Yes, some families never sell and the company becomes stale. Here at least you can point to over 60% now held by Institutions.
Paul, thank you very much for your research.
Well said Paul. One does start wondering why some in the media want to constantly high light issues that are not the fault of Boo and to be honest cannot be responsible for illegal activities of people of who are not directly connected to the company and impossible to police individually.
I hold from the days off 65p and intend to stay for the long run
Totally agree Paul. Bought more at 330 yesterday afternoon .It’s a share I shall keep for the long haul and continue to buy on dips.
Totally agree Paul.
Supermarkets like Tesco have many suppliers. Are they supposed to monitor all of them for VAT fraud or other possible breakages of the law? Surely not. They wouldn’t have time to run their own businesses if having to do that sort of thing.
BOO have had questions to answer, but why are the media so often singling out BOO alone? As you’ve pointed out sweat shop labour is rife in the retail sector supply chain. Those so critical of BOO seem to ignore it when it happens abroad but not when it happens in Leicester. In an ideal world it wouldn’t happen anywhere and people would be well paid with excellent working and living conditions whatever Country they lived in. Aside from anything else if only that could happen the migrant crisis would be solved!
How are the likes of Primark able to sell polo shirts for £5 or £6 and nearly all their clothes at incredibly cheap prices? It’s how and where they are sourced. Look at the “Made in” labels hidden away on big brand name clothes to see they too are made by cheap labour in Countries like Bangladesh.
It’s the same with cheap food. Some of that is produced here with slave labour in the FENS. Our supermarkets know this happens as surely the Government does too. But a blind eye is turned to it whenever a TV programme like Dispatches or a newspaper exposes it.
The effect of this on BOO share price? Short term negative (share was down 14p today) but longer term probably similar to Amazon. Scandalous Amazon working conditions have been exposed too and if there was any hit on their share price it didn’t last long!
And Leicester is a small part of their supply chain. If this continues presumably BOO could wash their hands of Leicester and source only from abroad? Not sure all the workers in the clothing supply trade who maybe are not getting the minimum wage but are using the pay to supplement benefit payments would welcome that! That would apply even more if other retailers fearing similar exposure also decide to quit Leicester.
Quick answer to the first question. While the supermarkets don't look for vat fraud they most certainly inspect factories and to my experience have looked at pay records, hours worked, holidays taken and many other things. The supplier, of course, has to pay for the inspection.
If you watch the latest press conference by BooHoo, that's exactly what they are doing with their suppliers. Maybe not in 2017 but they are now.
Do supermarkets look at the factories of subcontractors of their suppliers and the subcontractors to the subcontractors? This is the problem being discussed.
There are indications that HMRC and the local authorities have not been addressing the issues of tax fraud and low pay in Leicestershire over the last 10 years.
In the case of my client the supermarkets need to know in which of their factories the production will take place and the paperwork to prove what has been done on a day to day basis is considerable with everything that moves being recorded. Certainly they would not accept goods produced by a subcontractor without knowing the full background. They are, however, involved in food production where scrutiny is much more important.
It may be a brilliant company, but I suspect this story will resurface again and again.
Hi Chris,
I suspect this story will resurface again and again.
But, so what? Why does it matter what the press say? The company keeps beating forecasts, and the share price remains in a long term up-trend. The fundamentals are stunningly good. I think that hugely outweighs any supply chain stories are just blips down in a long term rising chart. So why should long-term investors be de-railed by any of this? We get a quarterly update that usually thrashes expectations. They've set the H2 expectations low too.
I think the journalists and shorters are misguiding people, and causing investors to lose money. Not a good thing to do.
Regards, Paul.
The canny will capitalize on this opportunity the press have given. I personally thank them for their short sightedness.
The press articles are affecting the short term share price movement but if you're a medium to long term holder they're irrelevant. Boohoo (LON:BOO) clearly have made mistakes and certainly have been naive, but extensive steps have been put in place to rectify that.
The most pertinent question is are customers put off by the current stories and the results show certainly not. Yes, some more ethics-conscious customers may be lost, but the vast majority of the demographic couldn't care less and certainly not those in the major growth areas like the US, who probably wouldn't have even heard of the issues going on.
if it was a brilliant company it would not be embroiled in this mess. It is a reasonably good company.